CoreMacro
Find out more
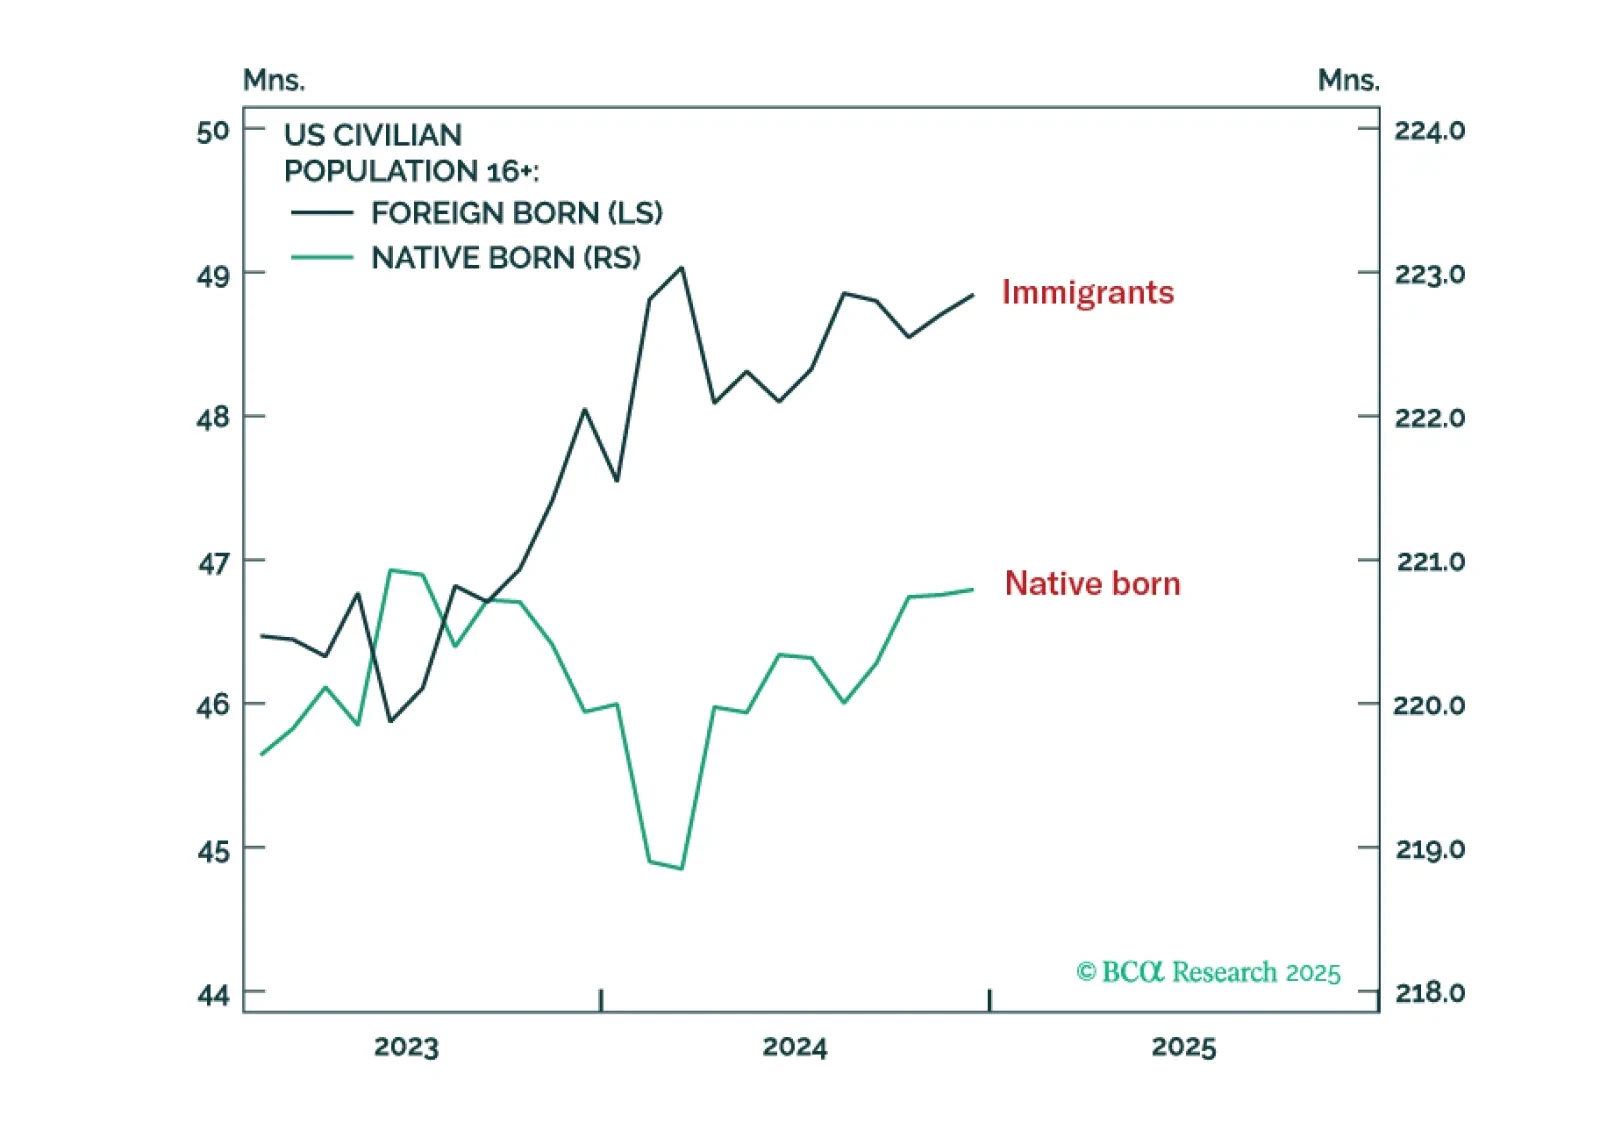
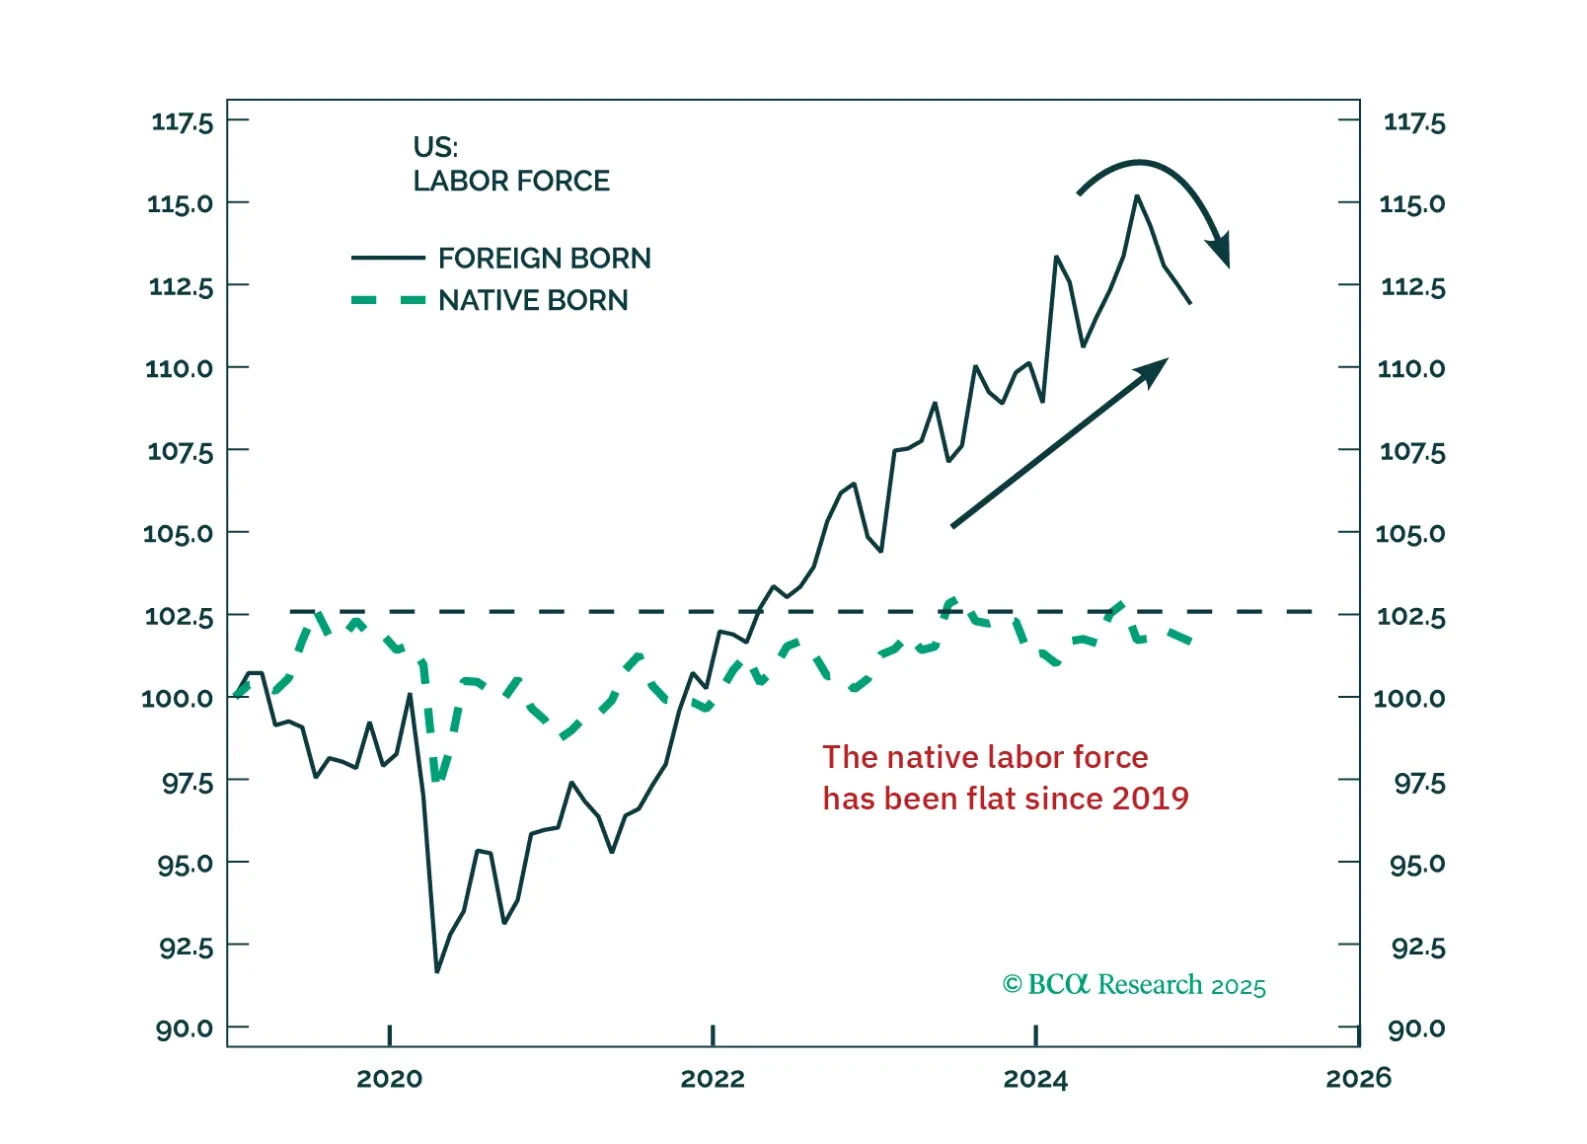
All the growth in the US labour supply since mid-2023 has come from immigration. This means if net immigration comes to a grinding halt, as Trump wants, it will hurt economic growth as well as keep the labour market supply-constrained. An increase in productivity growth could save the day, both to maintain growth and to kill inflation. Yet hopes that AI is about to usher an imminent and sustained boost to productivity growth are misplaced. Hence, expect a slowdown in US growth combined with inflation stuck close to 3 percent, a combination that I call a ‘mini stagflation’. We go through the investment implications. Plus: Tactically overweight Portugal versus Europe.
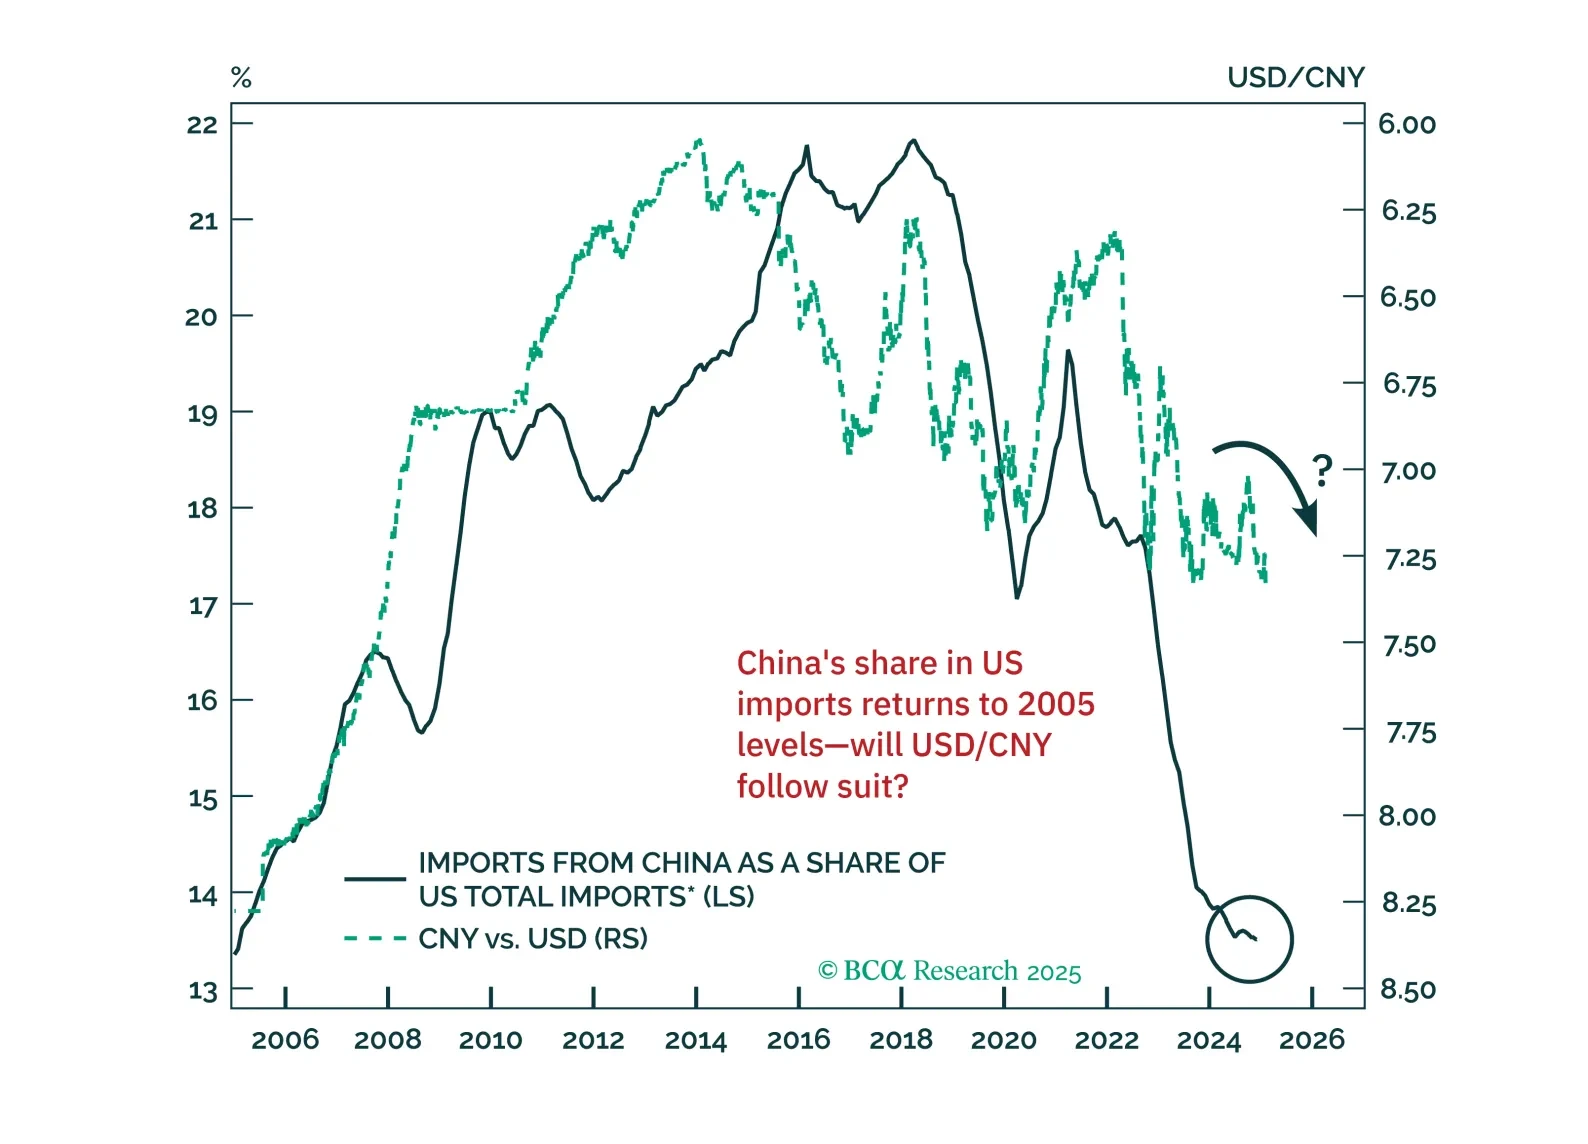
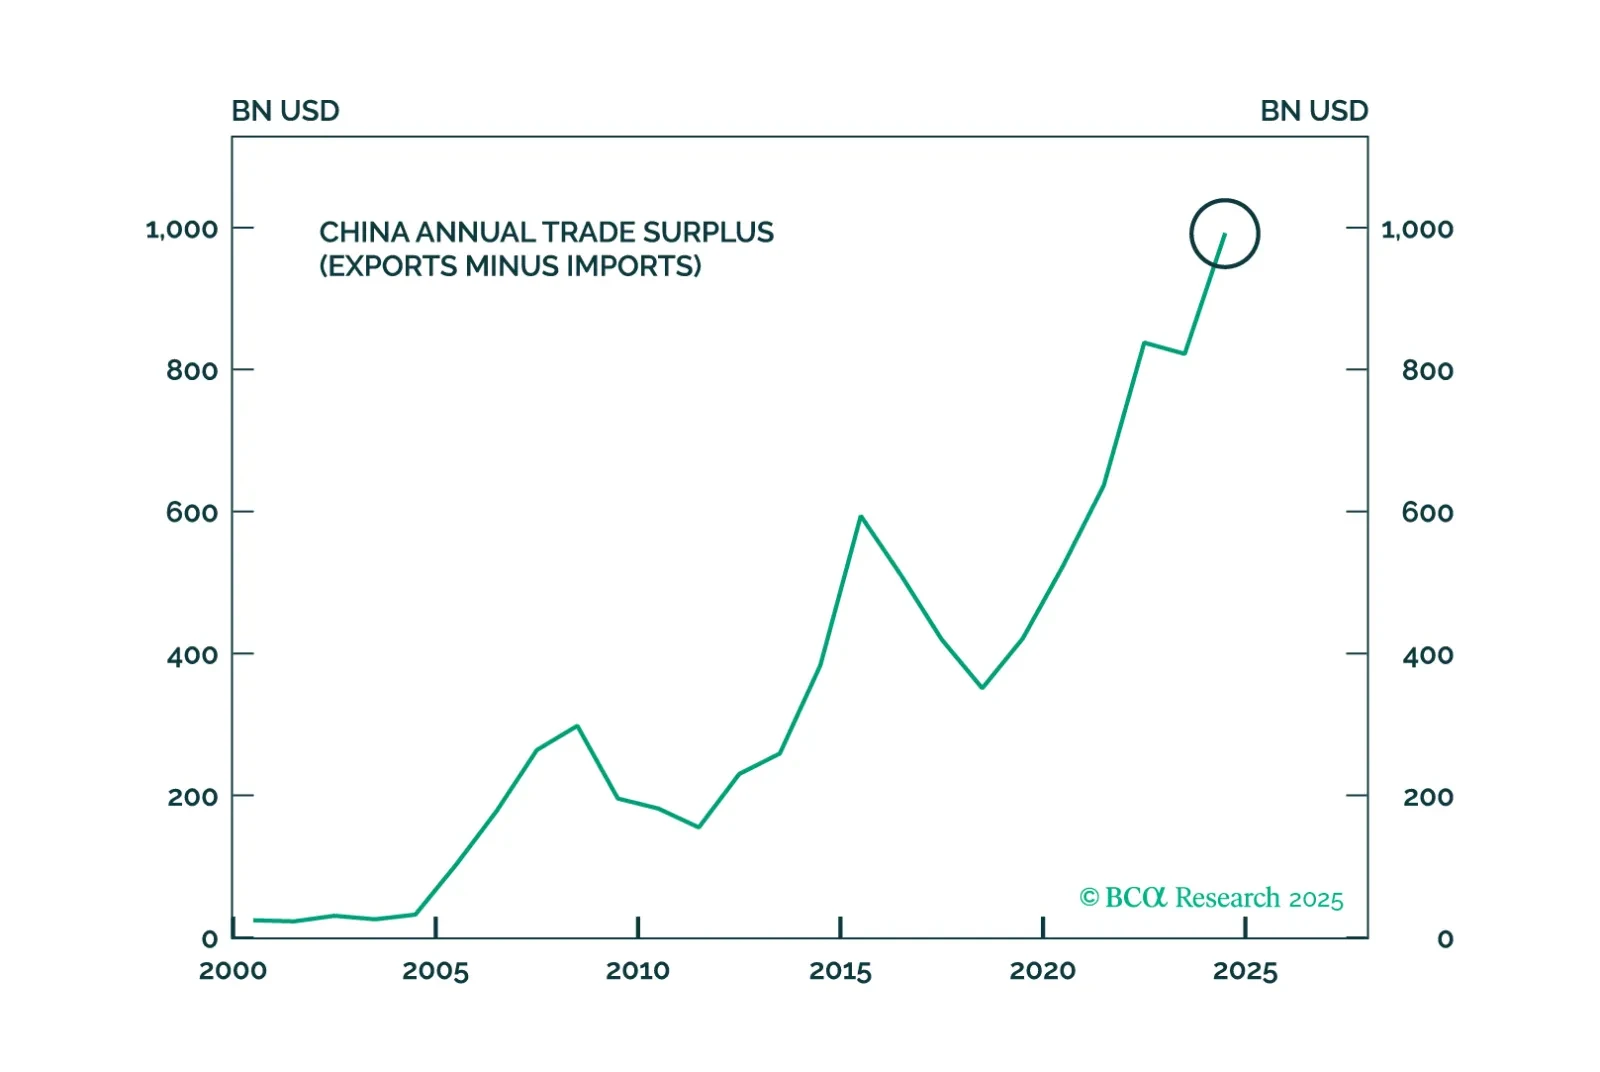
The 10% tariff hike announced on Saturday will likely serve as the opening salvo in a broader wave of protectionist measures. In this report, we assess the increase in US import tariffs on China. While the direct impact on China’s overall economy may be manageable, the country’s economy faces significant risks from potential disruptions in global trade.

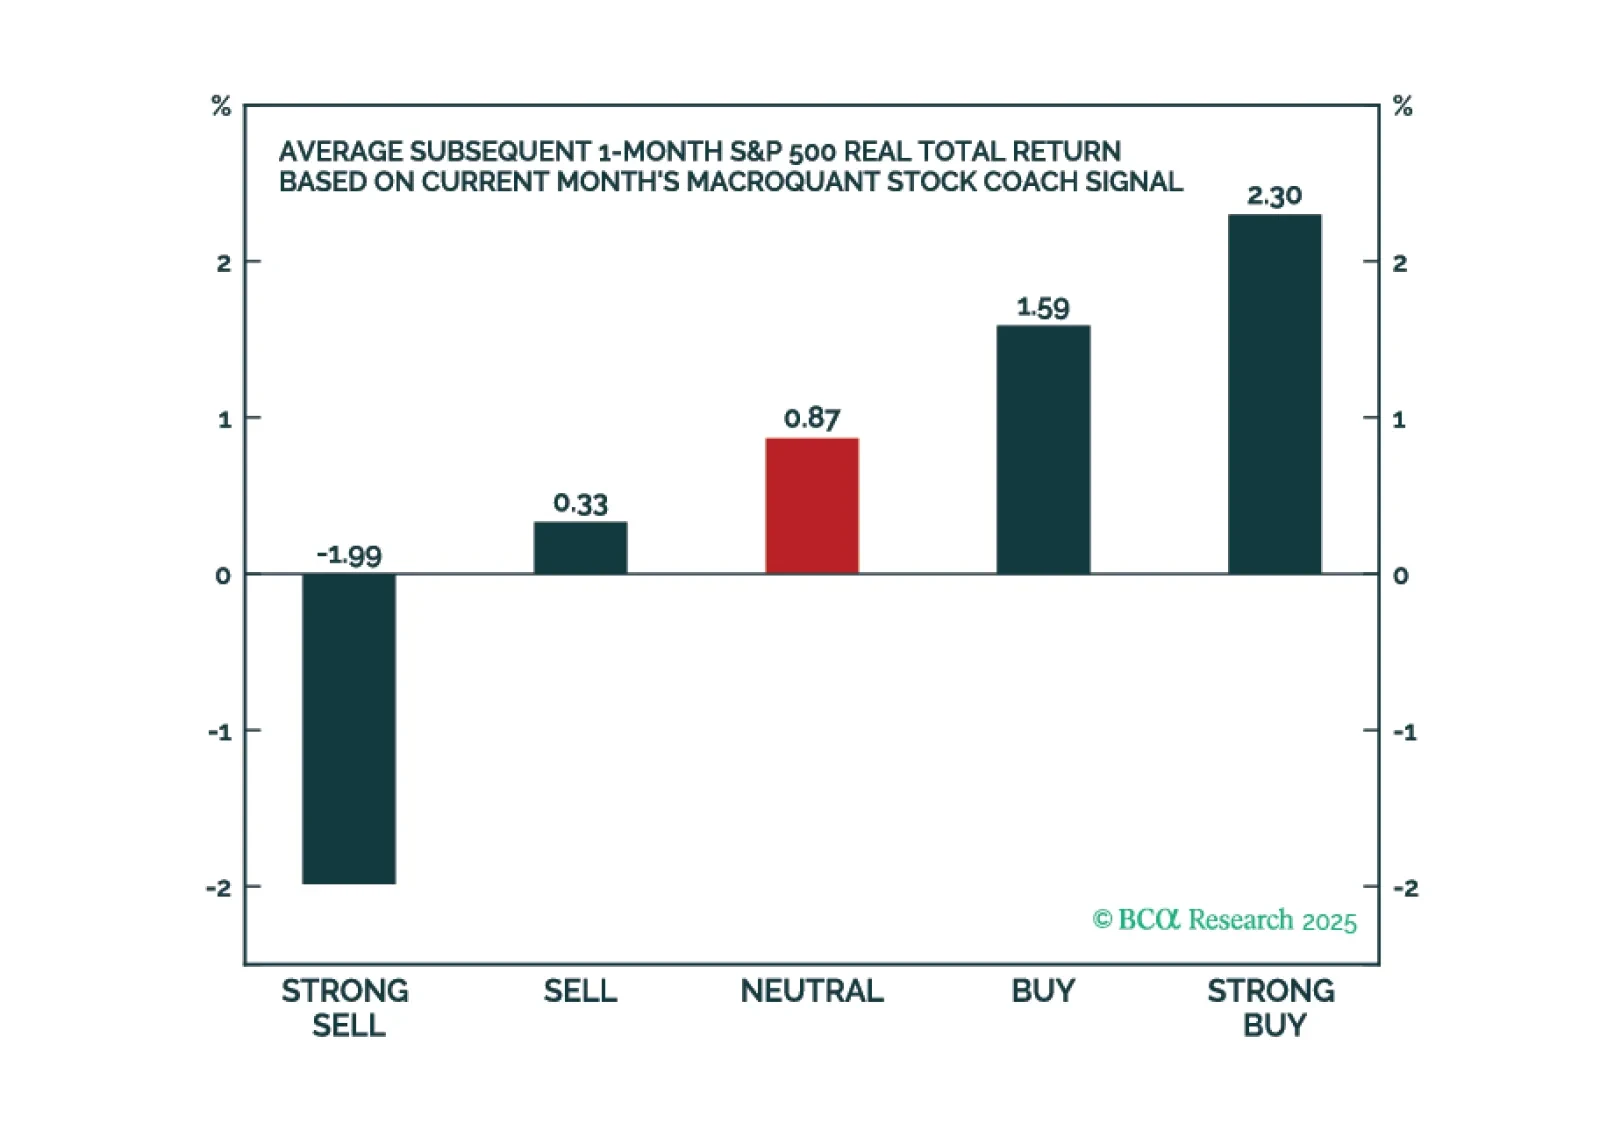
The latest version of the MacroQuant model suggests that the bull market in US stocks is winding down. The model expects Treasury yields to fall later this year but is not ready to go long duration just yet.
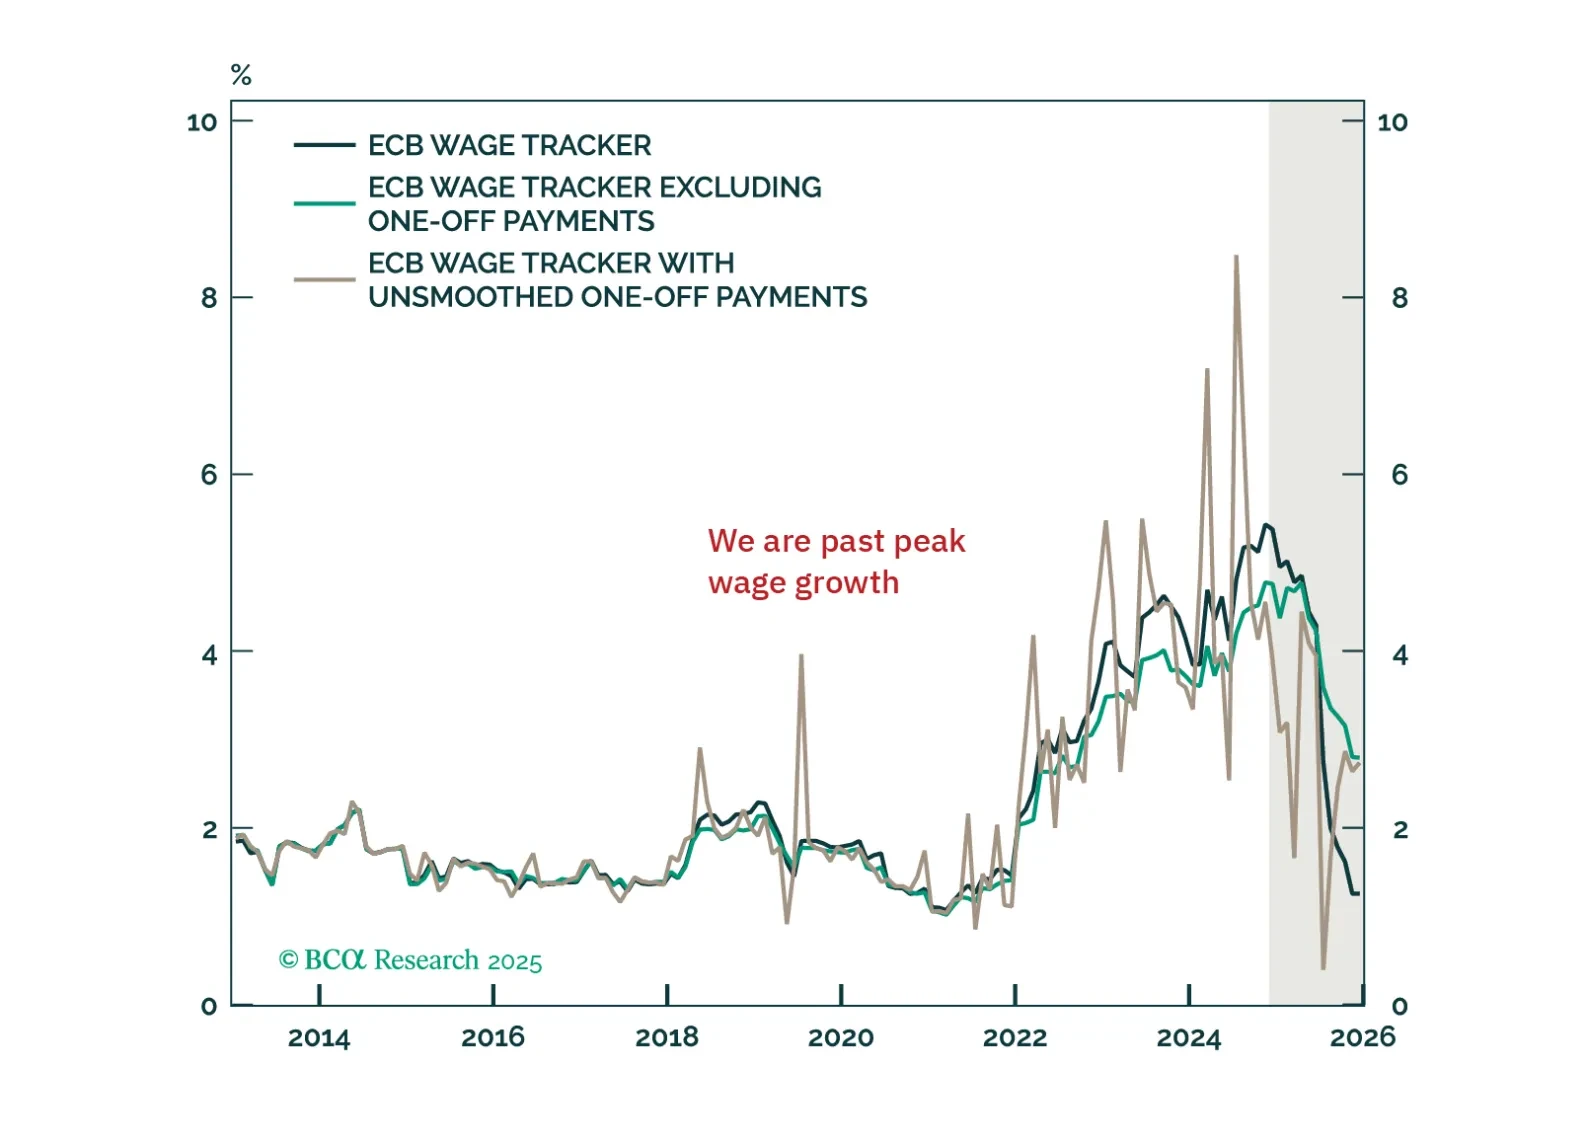
The ECB cut its deposit rate to 2.75%, as was widely anticipated. President Christine Lagarde did not provide any fireworks, but the Governing Council’s message was clear: Policy is restrictive, and inflation will fall further. As a result, if we combine our economic forecasts for the Eurozone with Frankfurt’s data dependency, we continue to expect the ECB’s deposit rate to settle below 2%. Consequently, German bond yields have downside, and the euro has yet to bottomed.
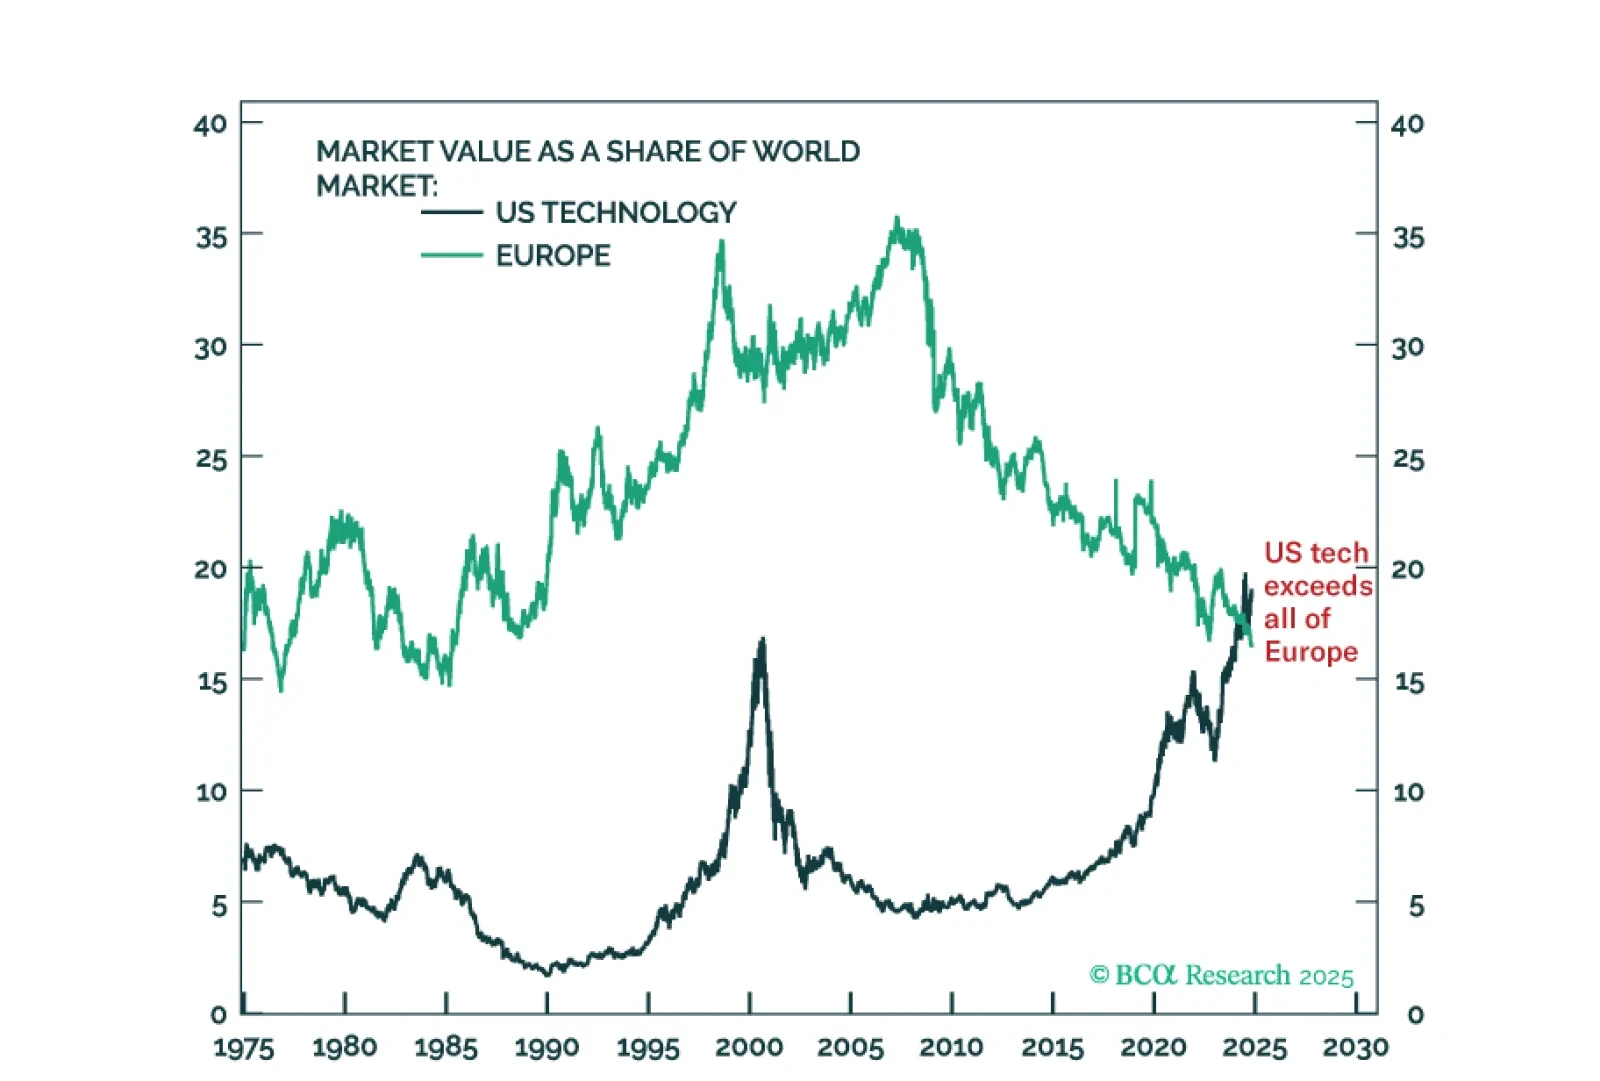
US tech stocks as a share of world stock market capitalisation is at an all-time high that exceeds even the peak of the dot com mania in 2000. At the other extreme, Europe’s share in the world stock market is at a 50-year low. While I am optimistic about the potential of generative-AI, I am not as manically optimistic as the market. And while I am concerned about the current malaise in Europe’s economy and politics, I am not as depressingly concerned as the market. For me, the AI mania combined with Europe’s current malaise is a 50-year mispricing… and opportunity. Plus: go tactically short coffee.