CoreMacro
Find out more
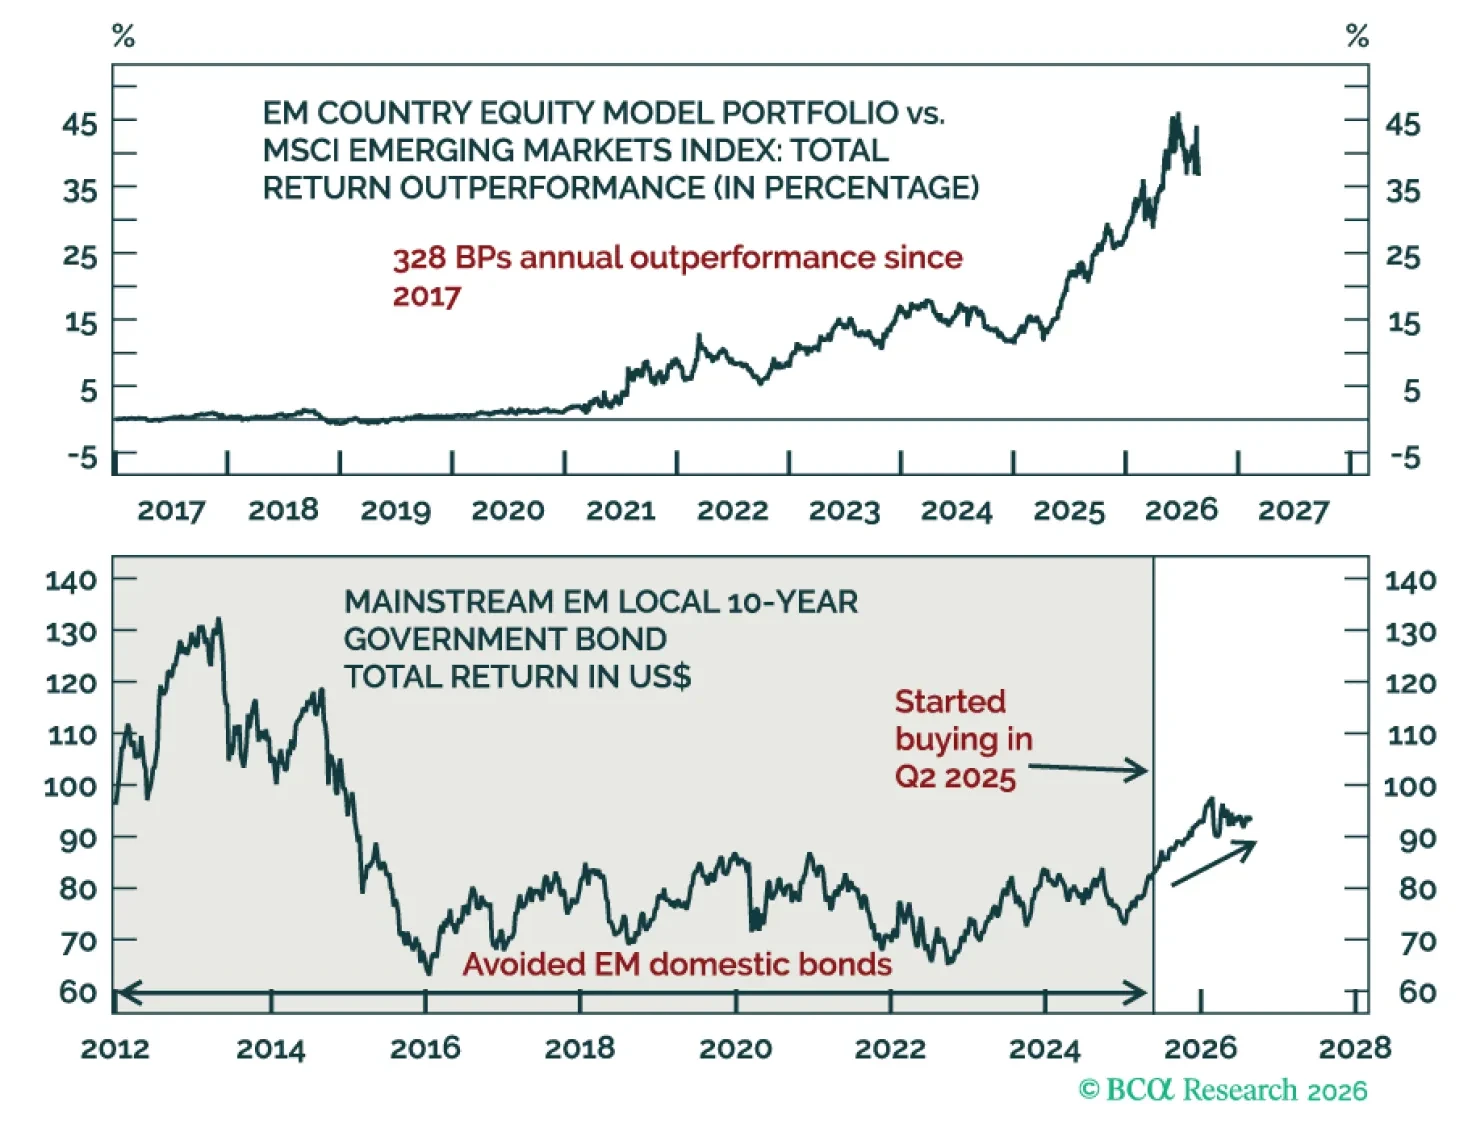
We review the track record of our broader investment strategy and individual calls. We also use this opportunity to close several positions that have become stale.
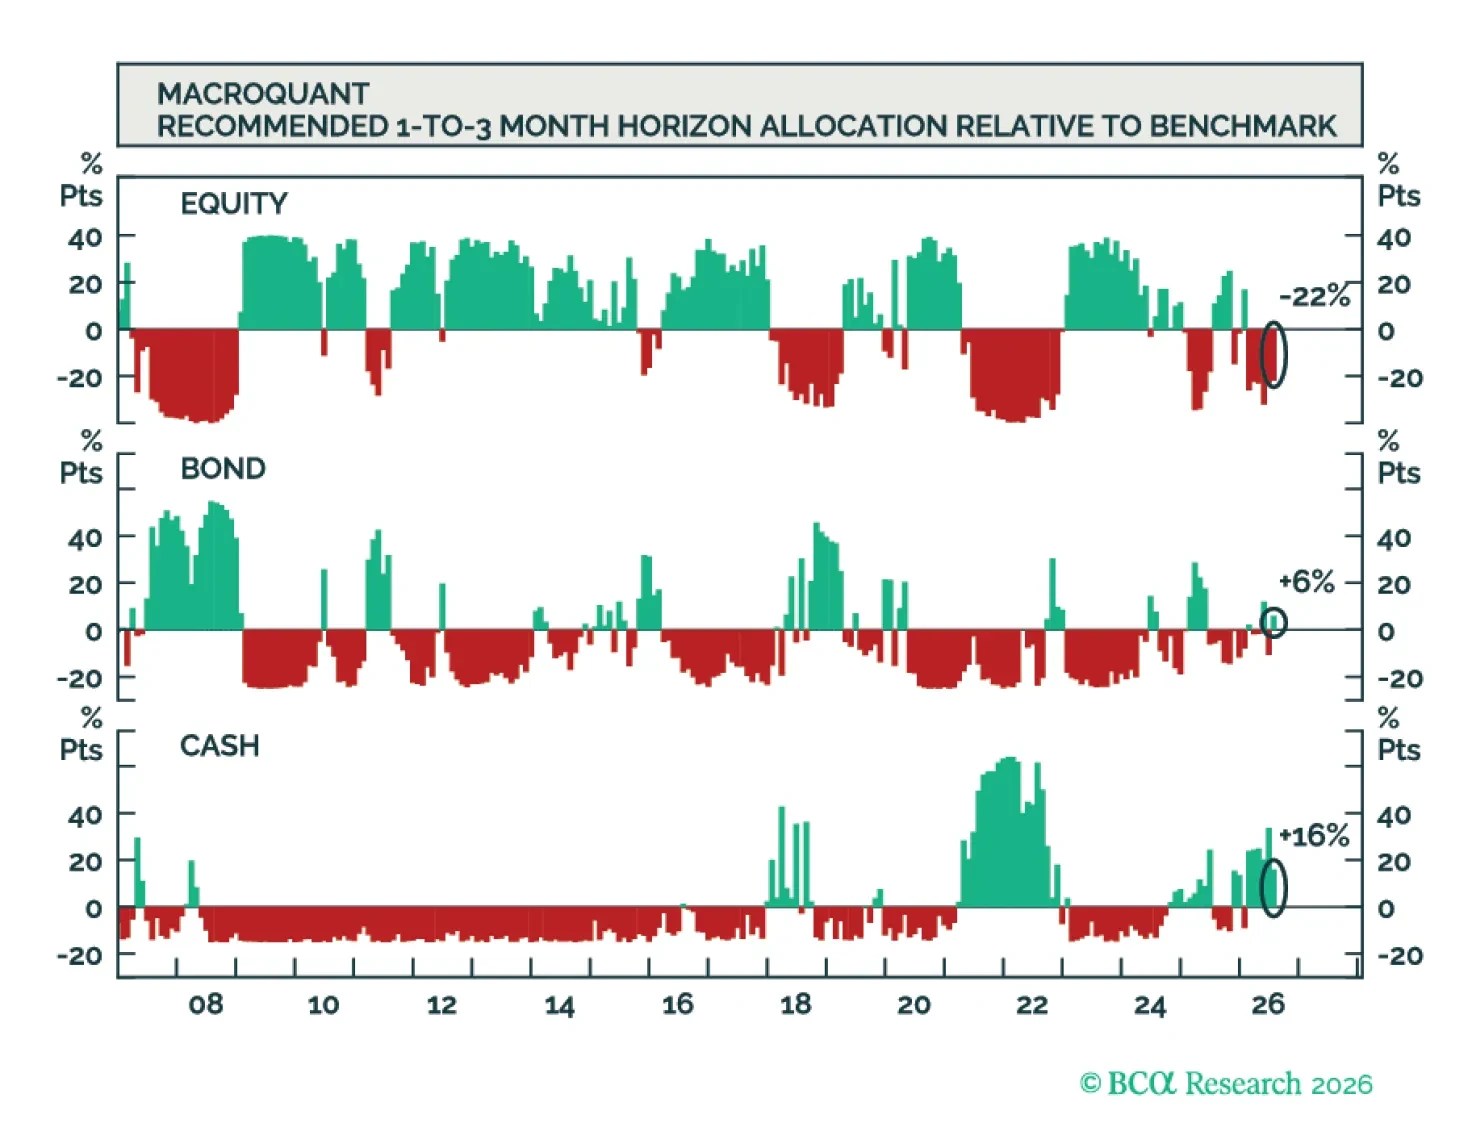
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
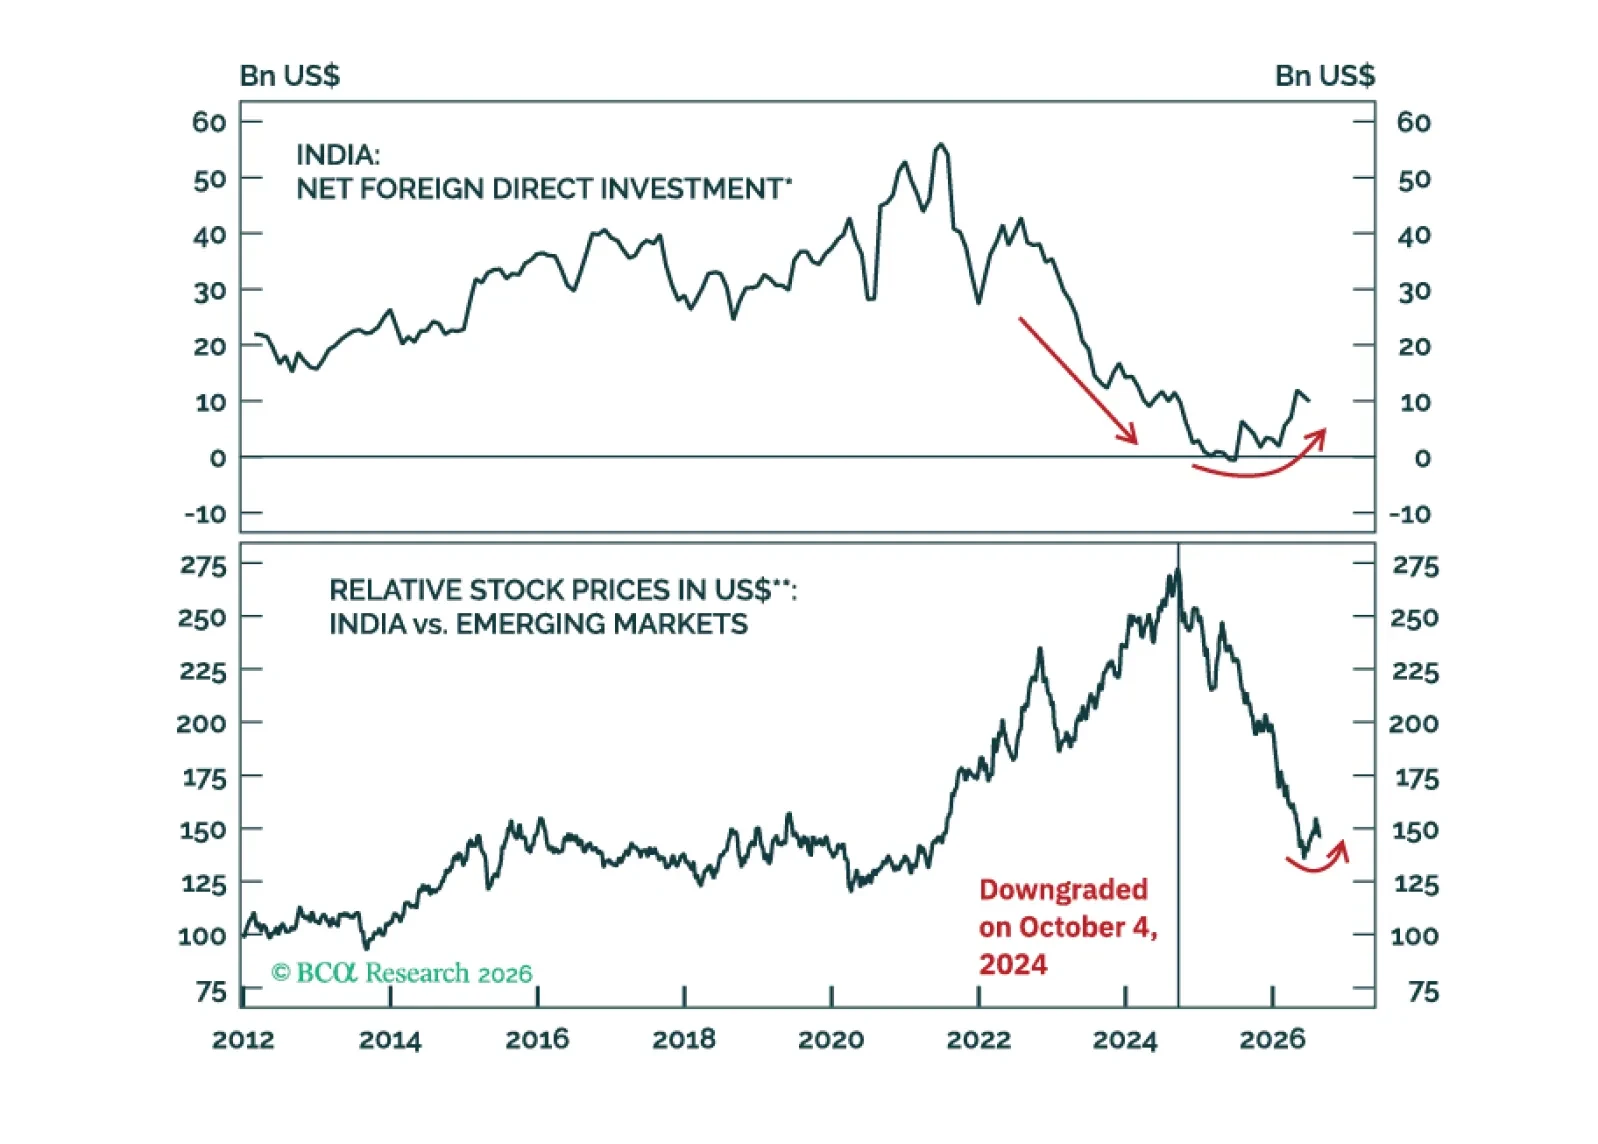
BCA's CoreMacro and Portfolio Construction teams combine two distinct but intersecting lenses to revisit a once heralded opportunity: India. We upgrade India across both public and private markets, but the conviction is not the same everywhere.
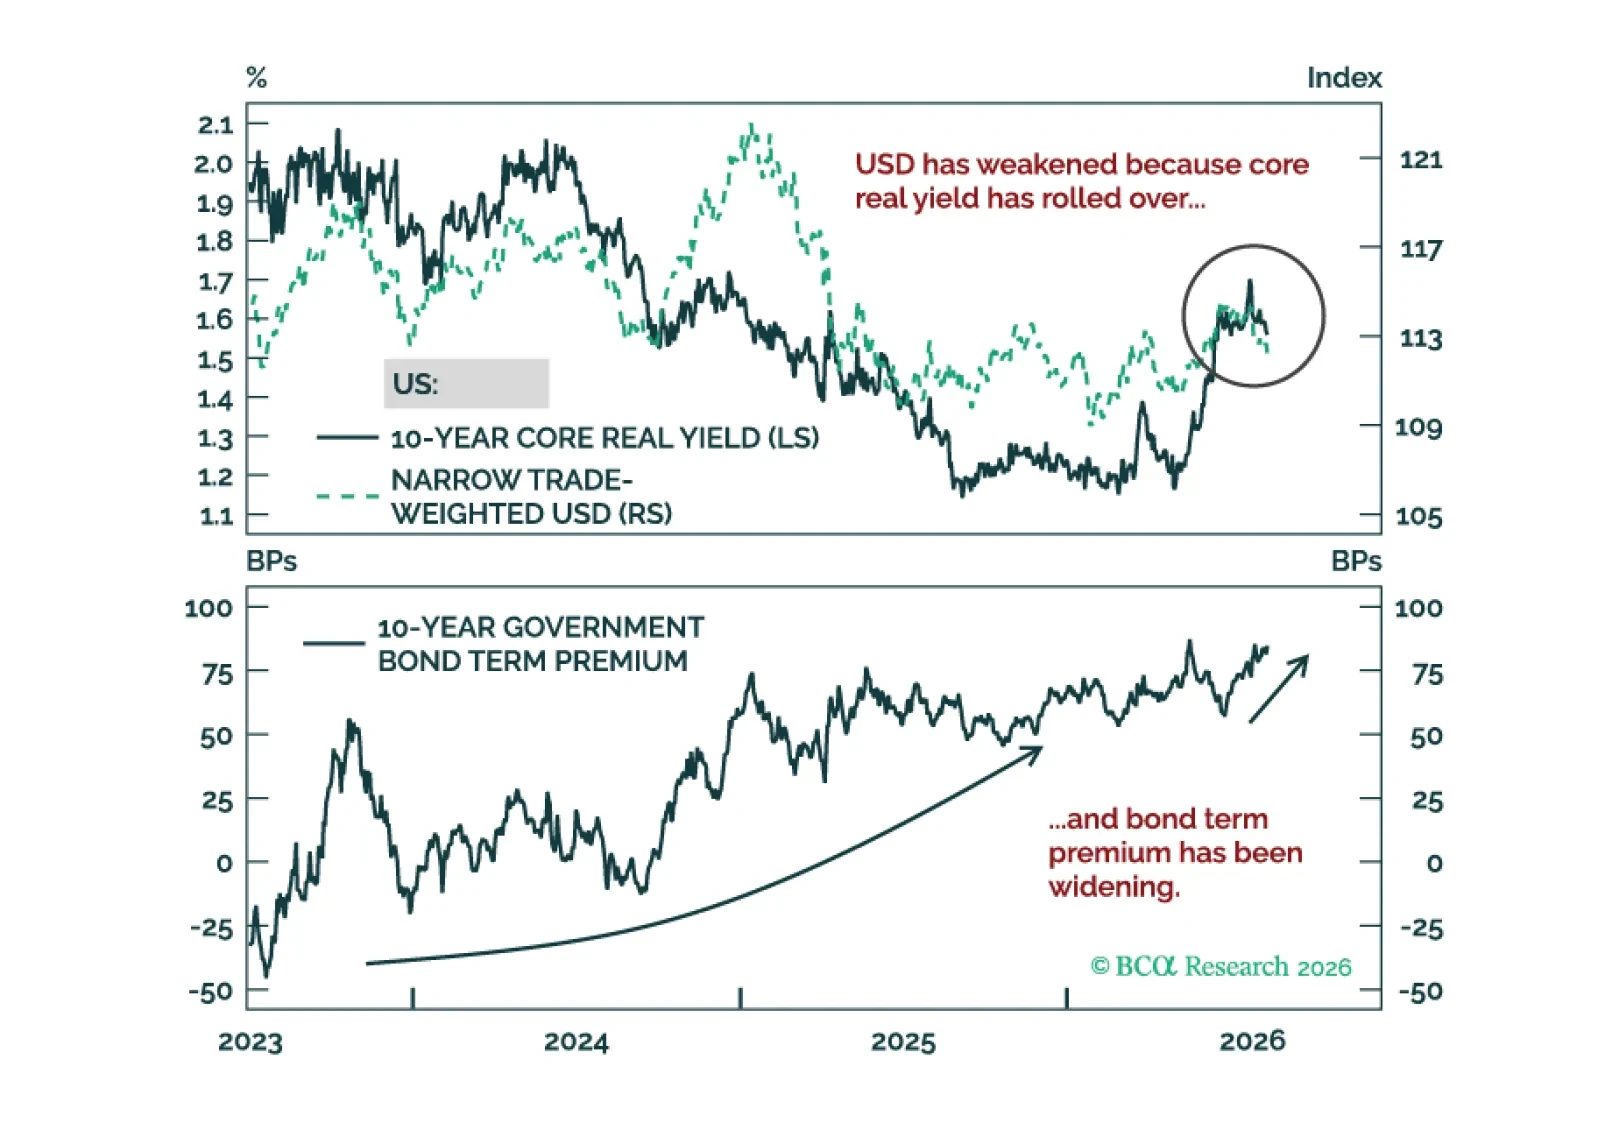
If bond yields rise due to widening bond term premiums or escalating inflation expectations, Bessenomics is unlikely to avert a stock-bond collision. Buy back gold mining stocks.
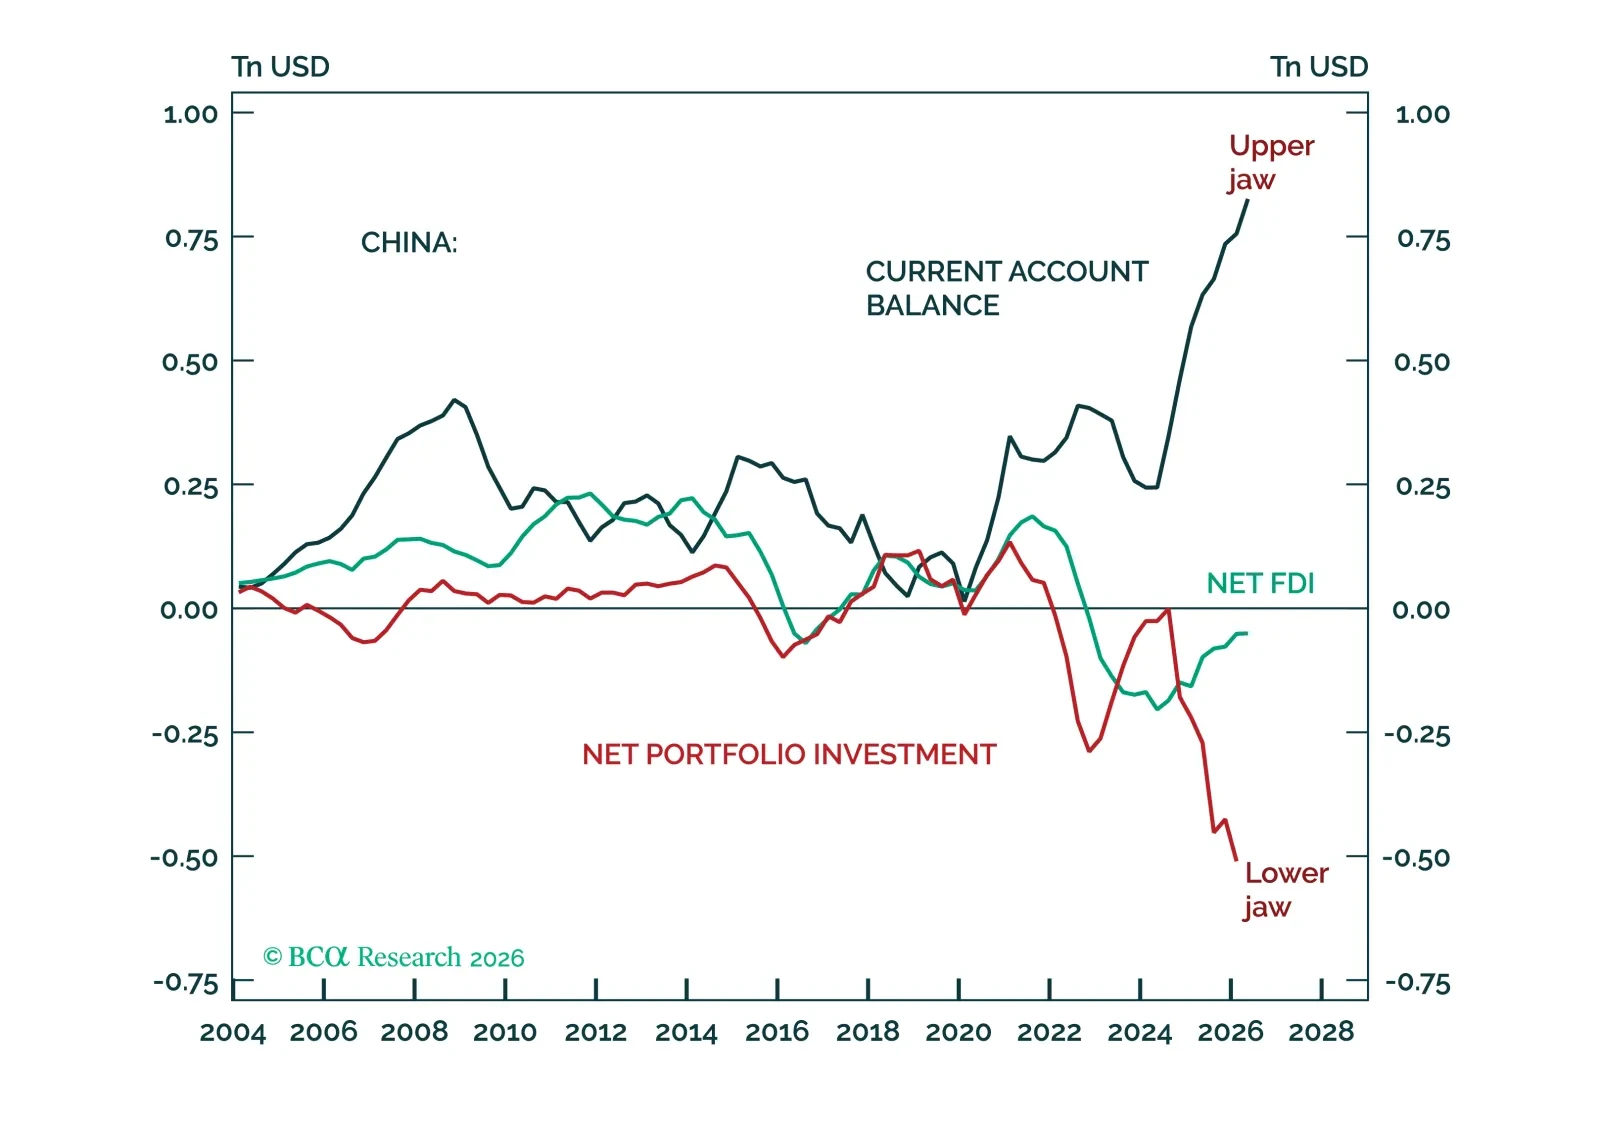
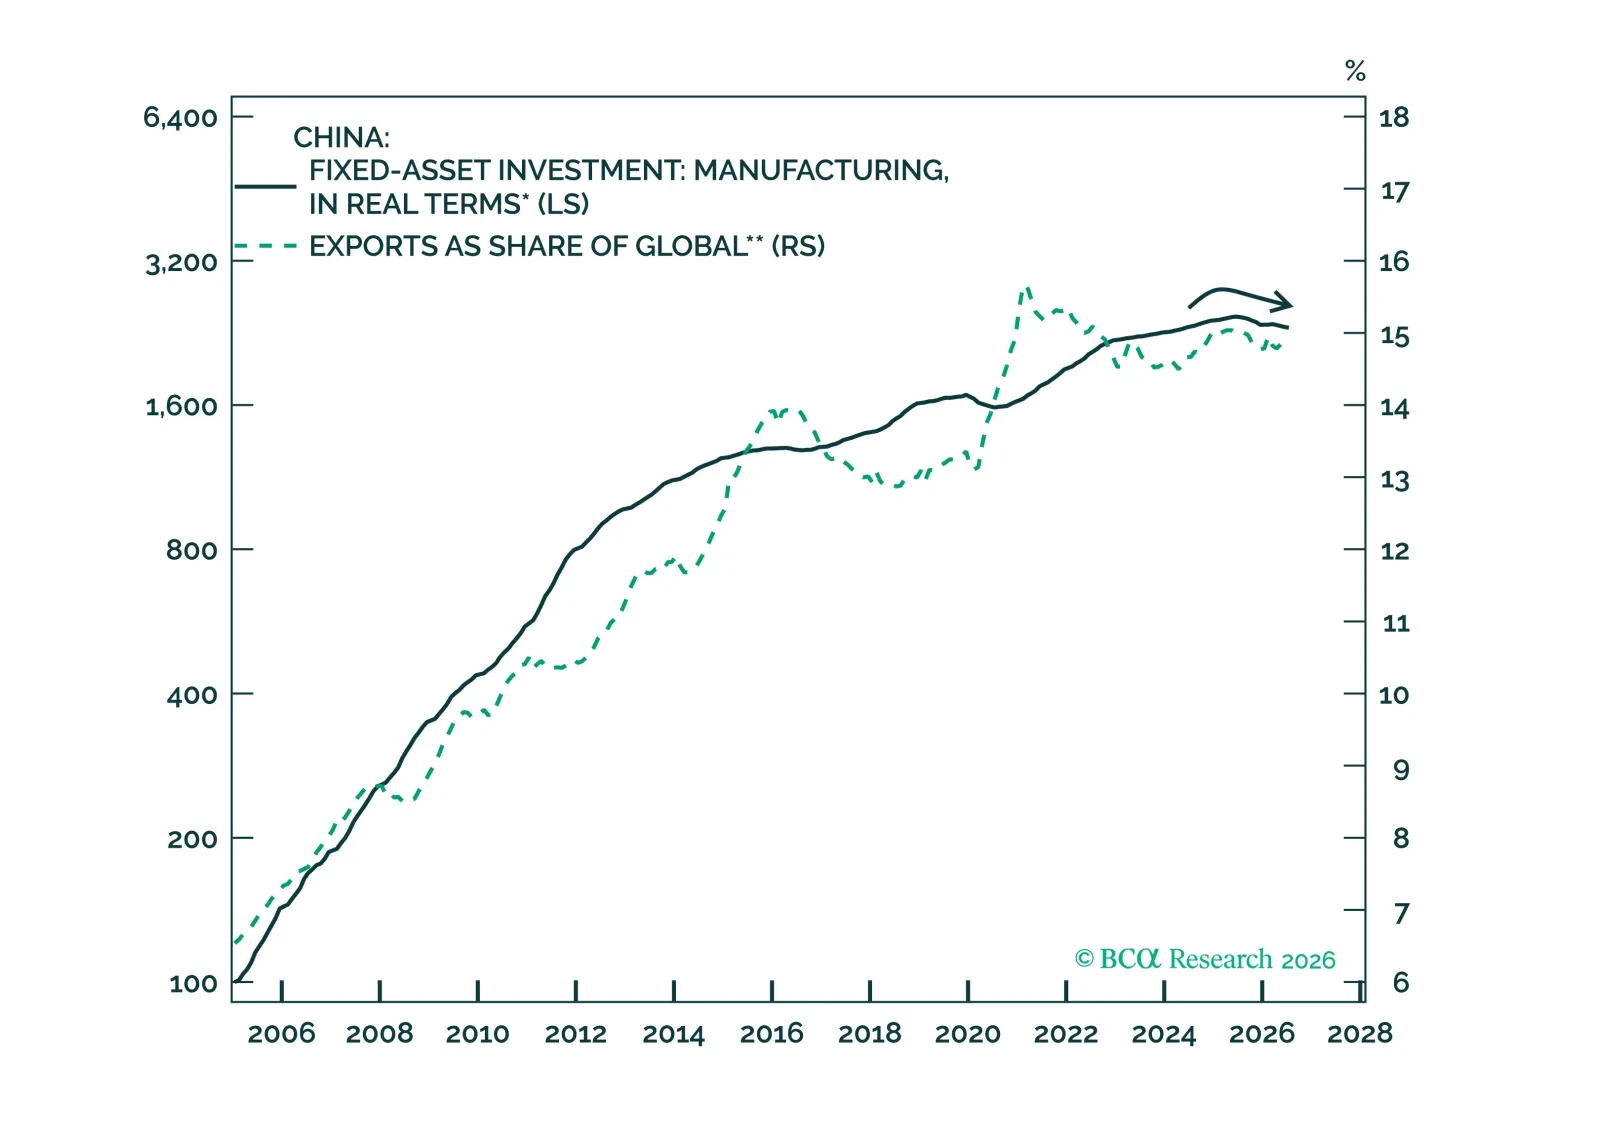
In this report, we highlight notable developments on both sides of China’s BoP: a widening external surplus on the current account side, and shifts in how that surplus is recycled abroad through BoP financial account.
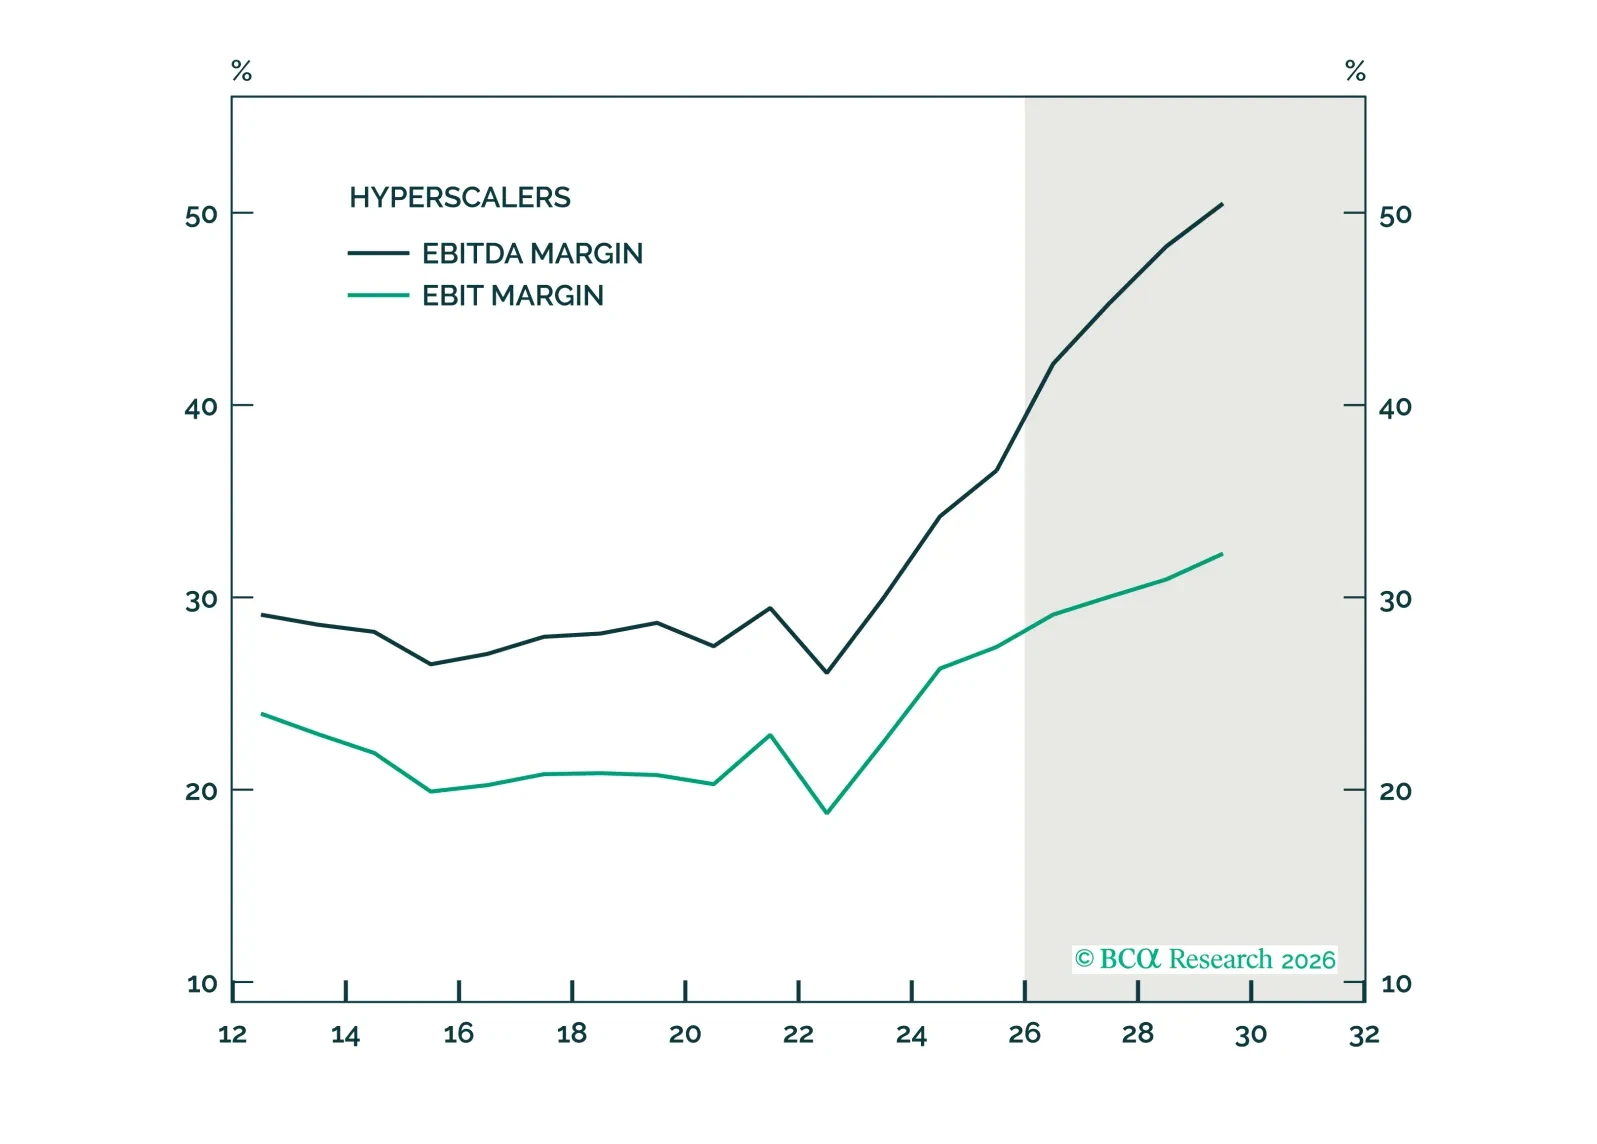
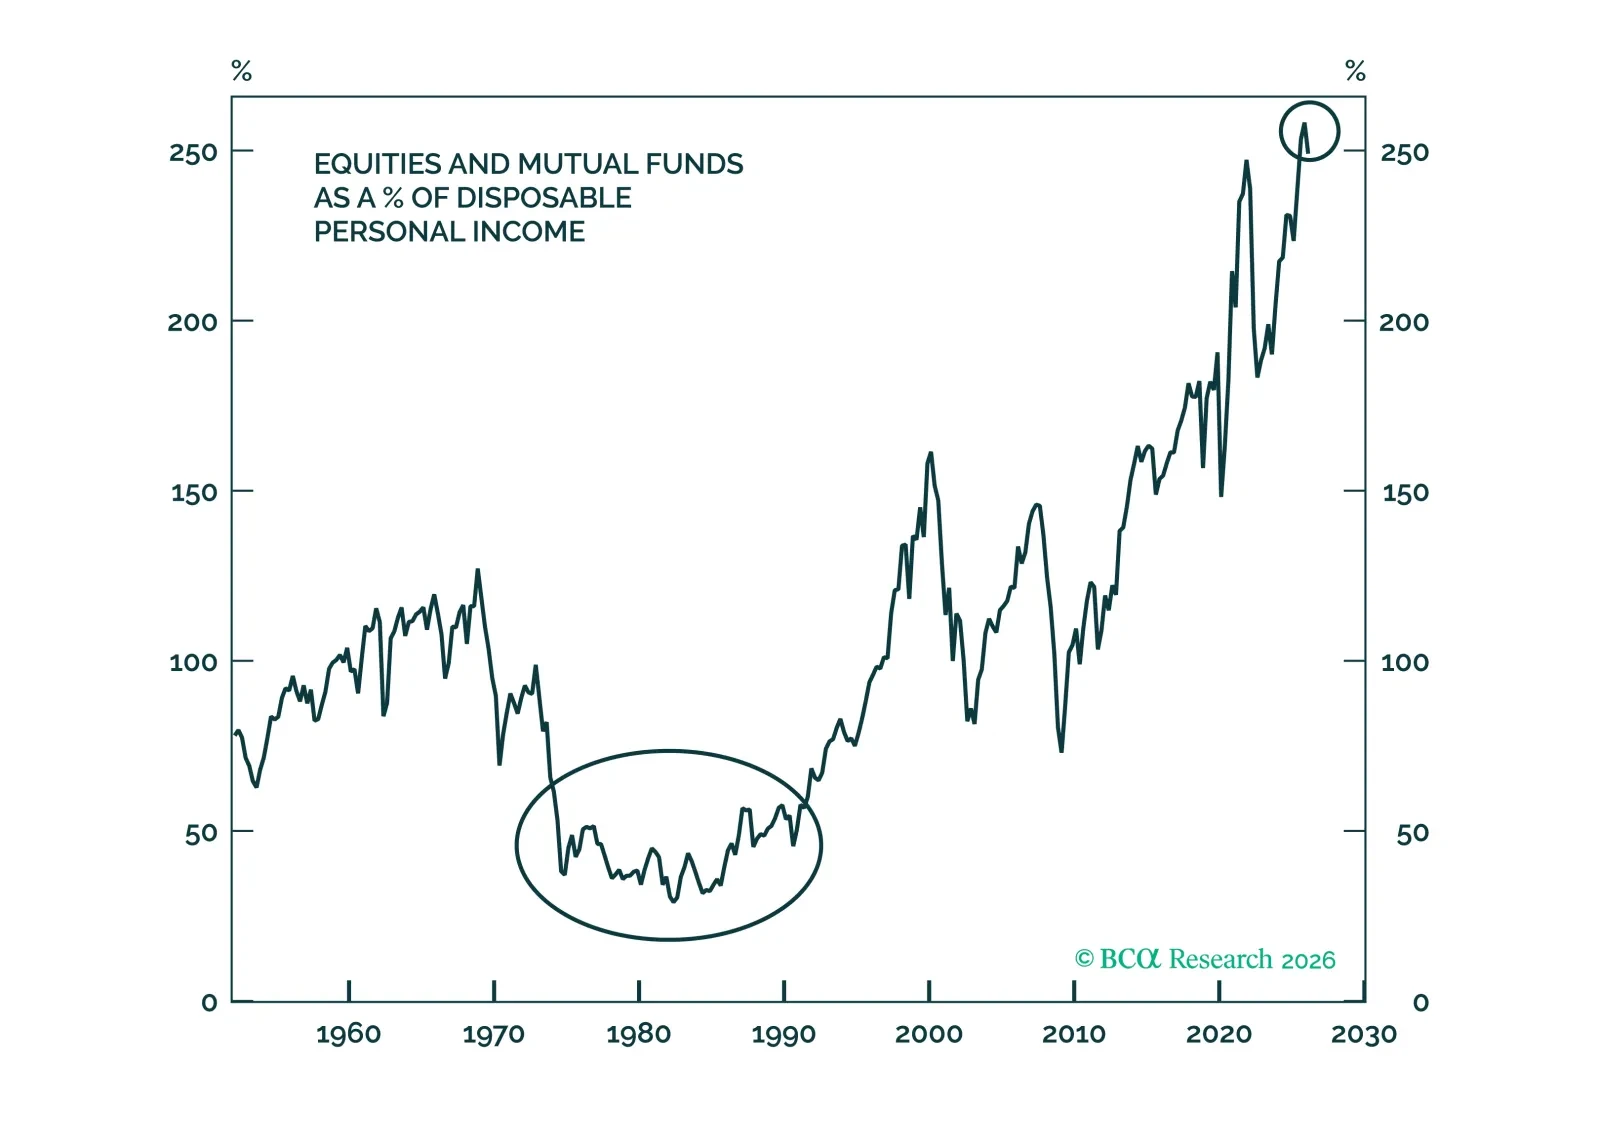
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
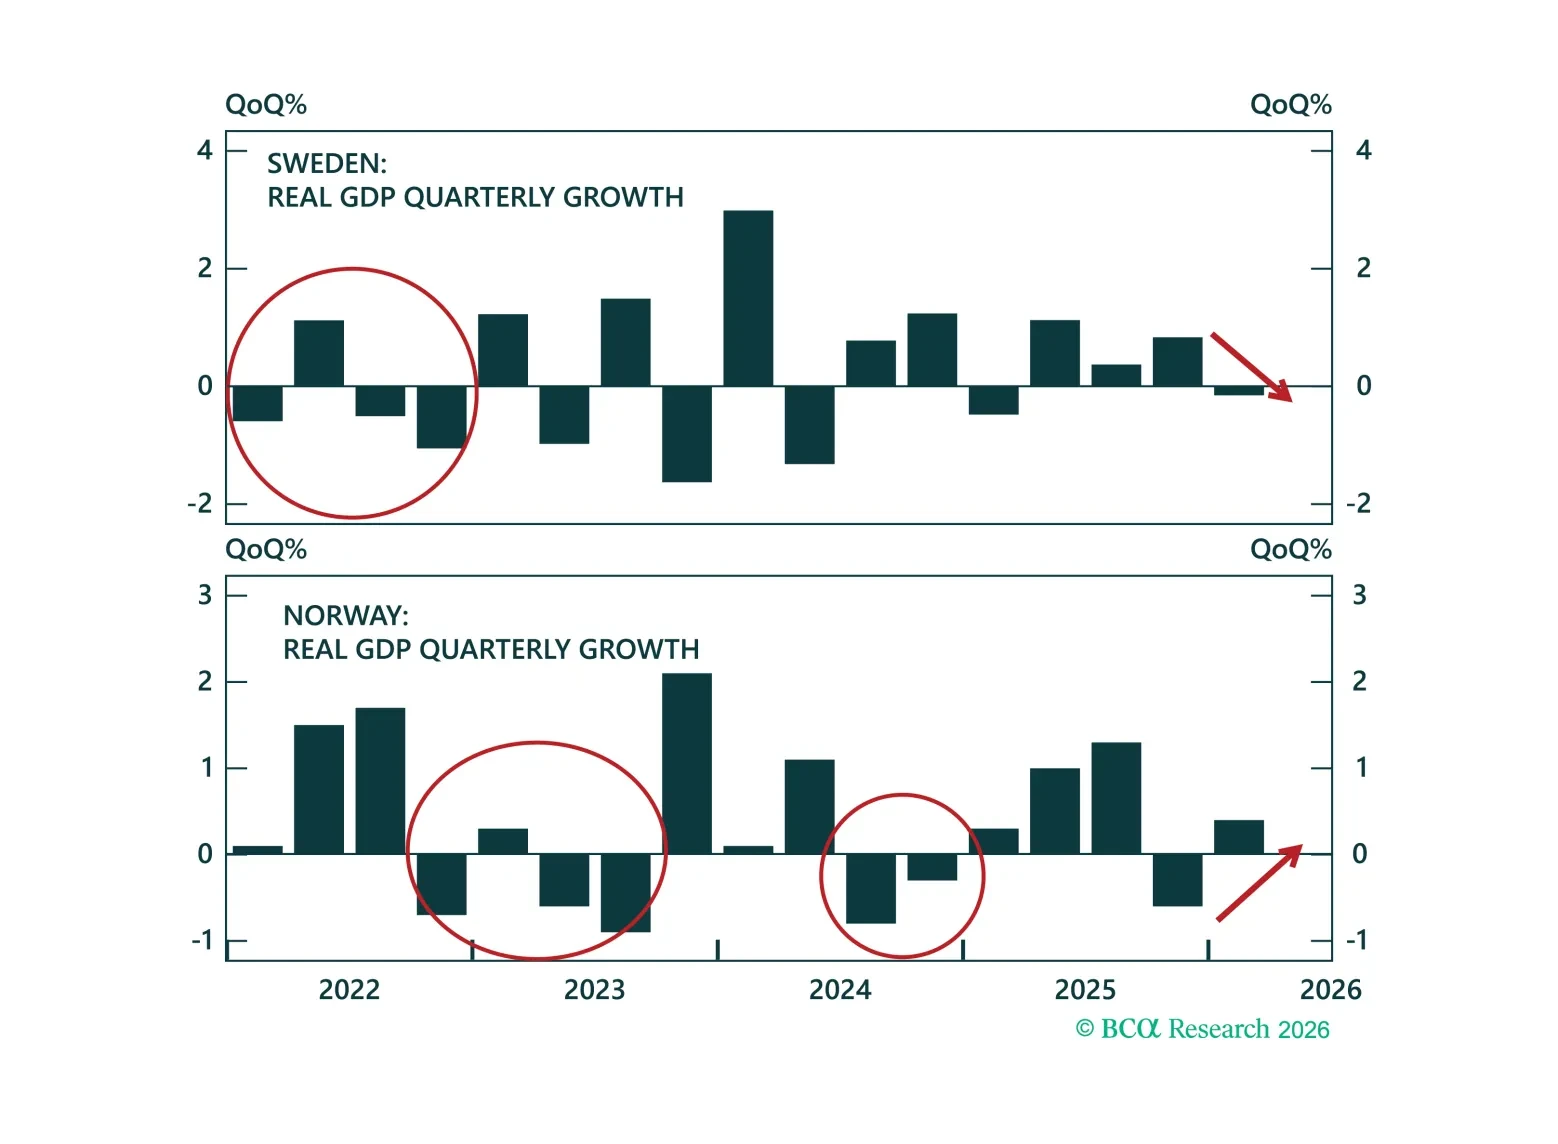
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.