 CoreMacro
Find out more
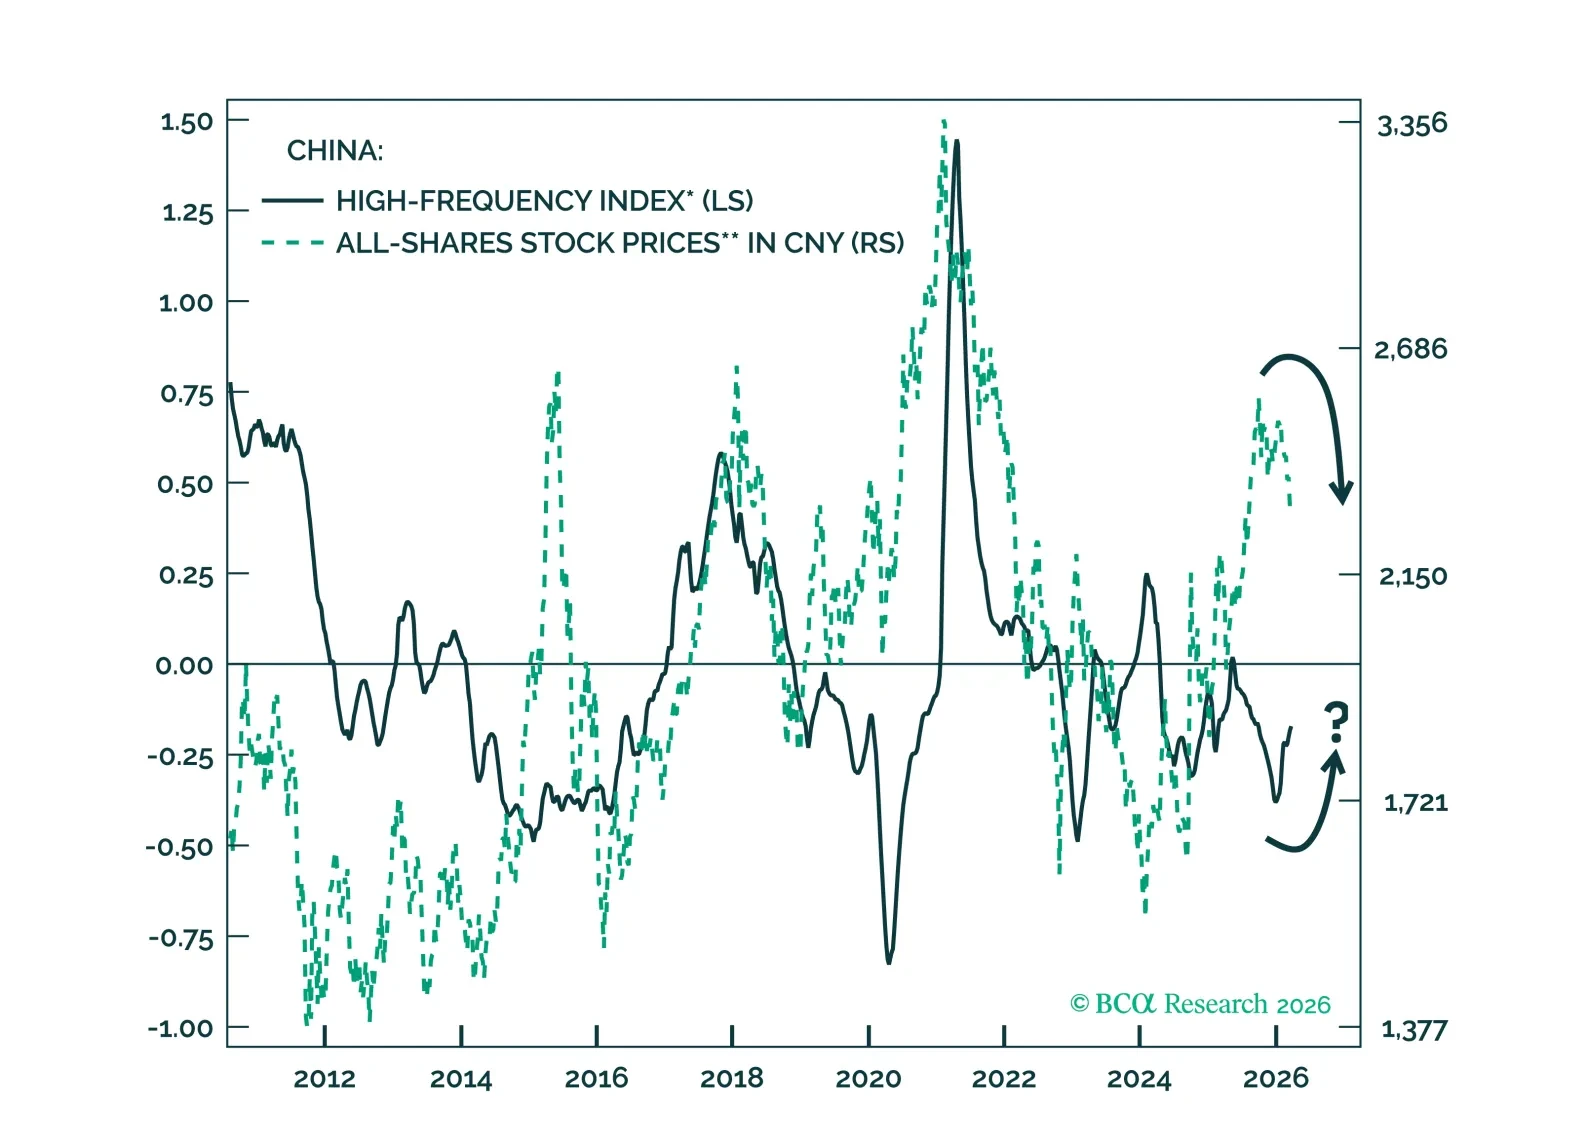
Chinese stock prices are converging with economic growth after a 2025 rally. While the country can endure a short-term oil price shock, it remains susceptible to extended supply disruptions and a global slowdown.
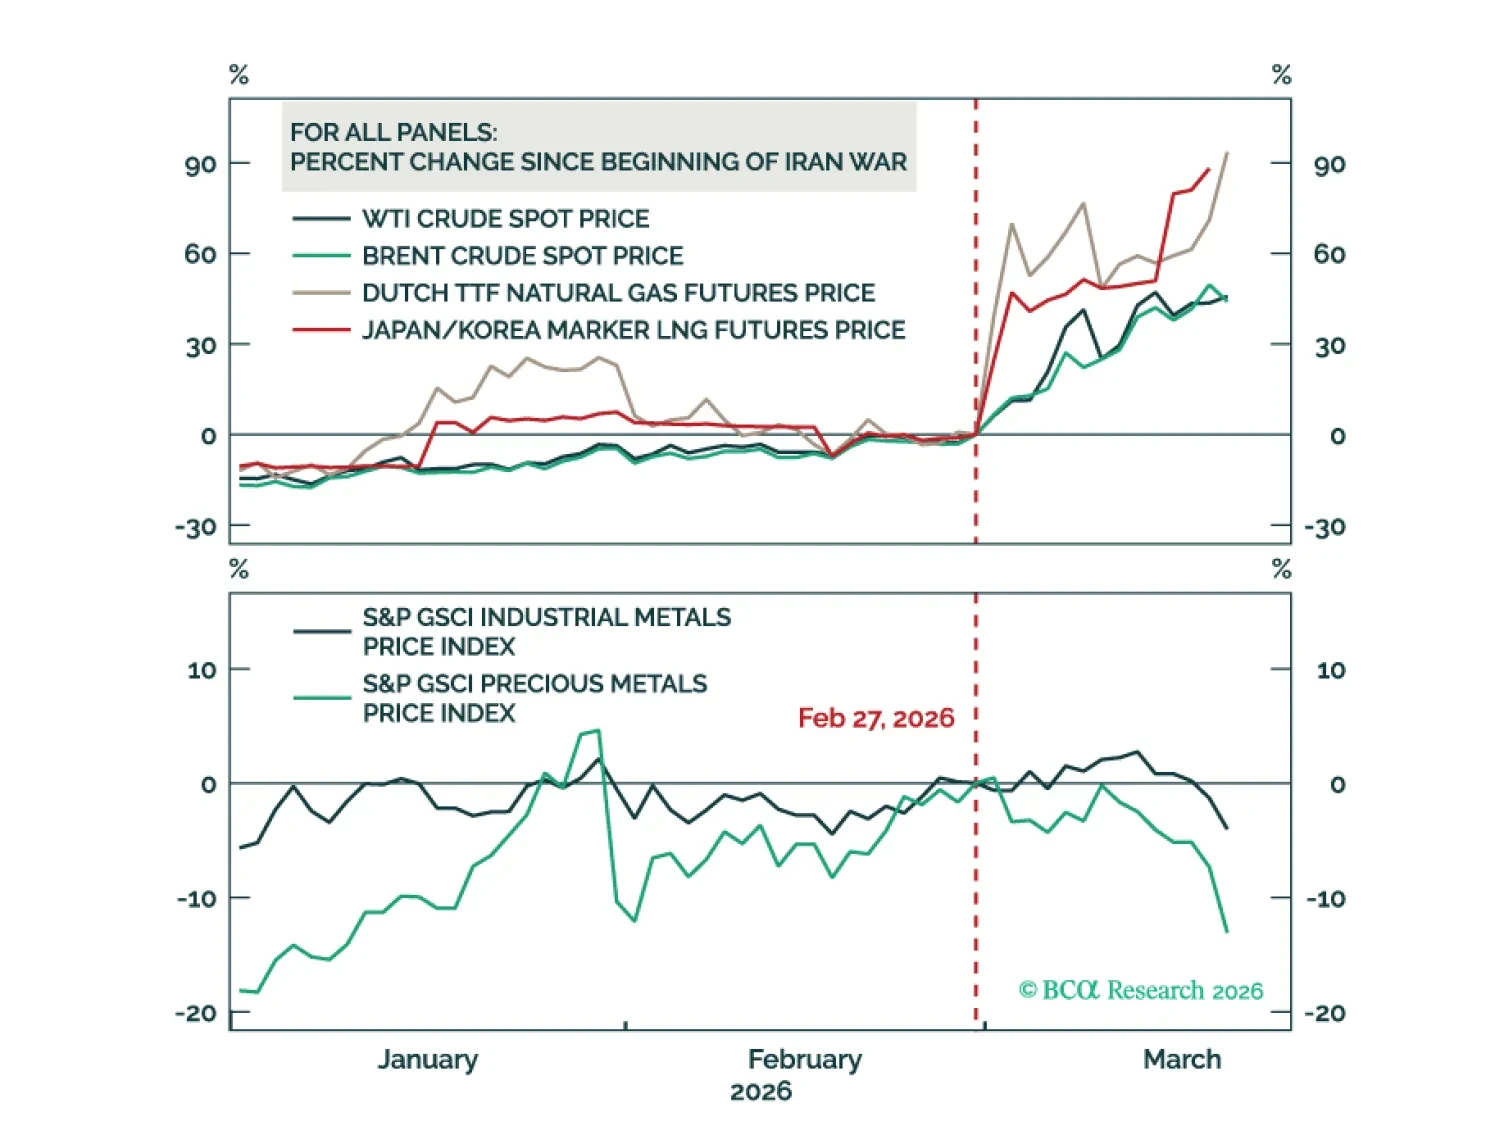
Higher oil prices threaten the global economy, warranting an underweight stance on equities. Over the long haul, industrial metals will fare better than crude.
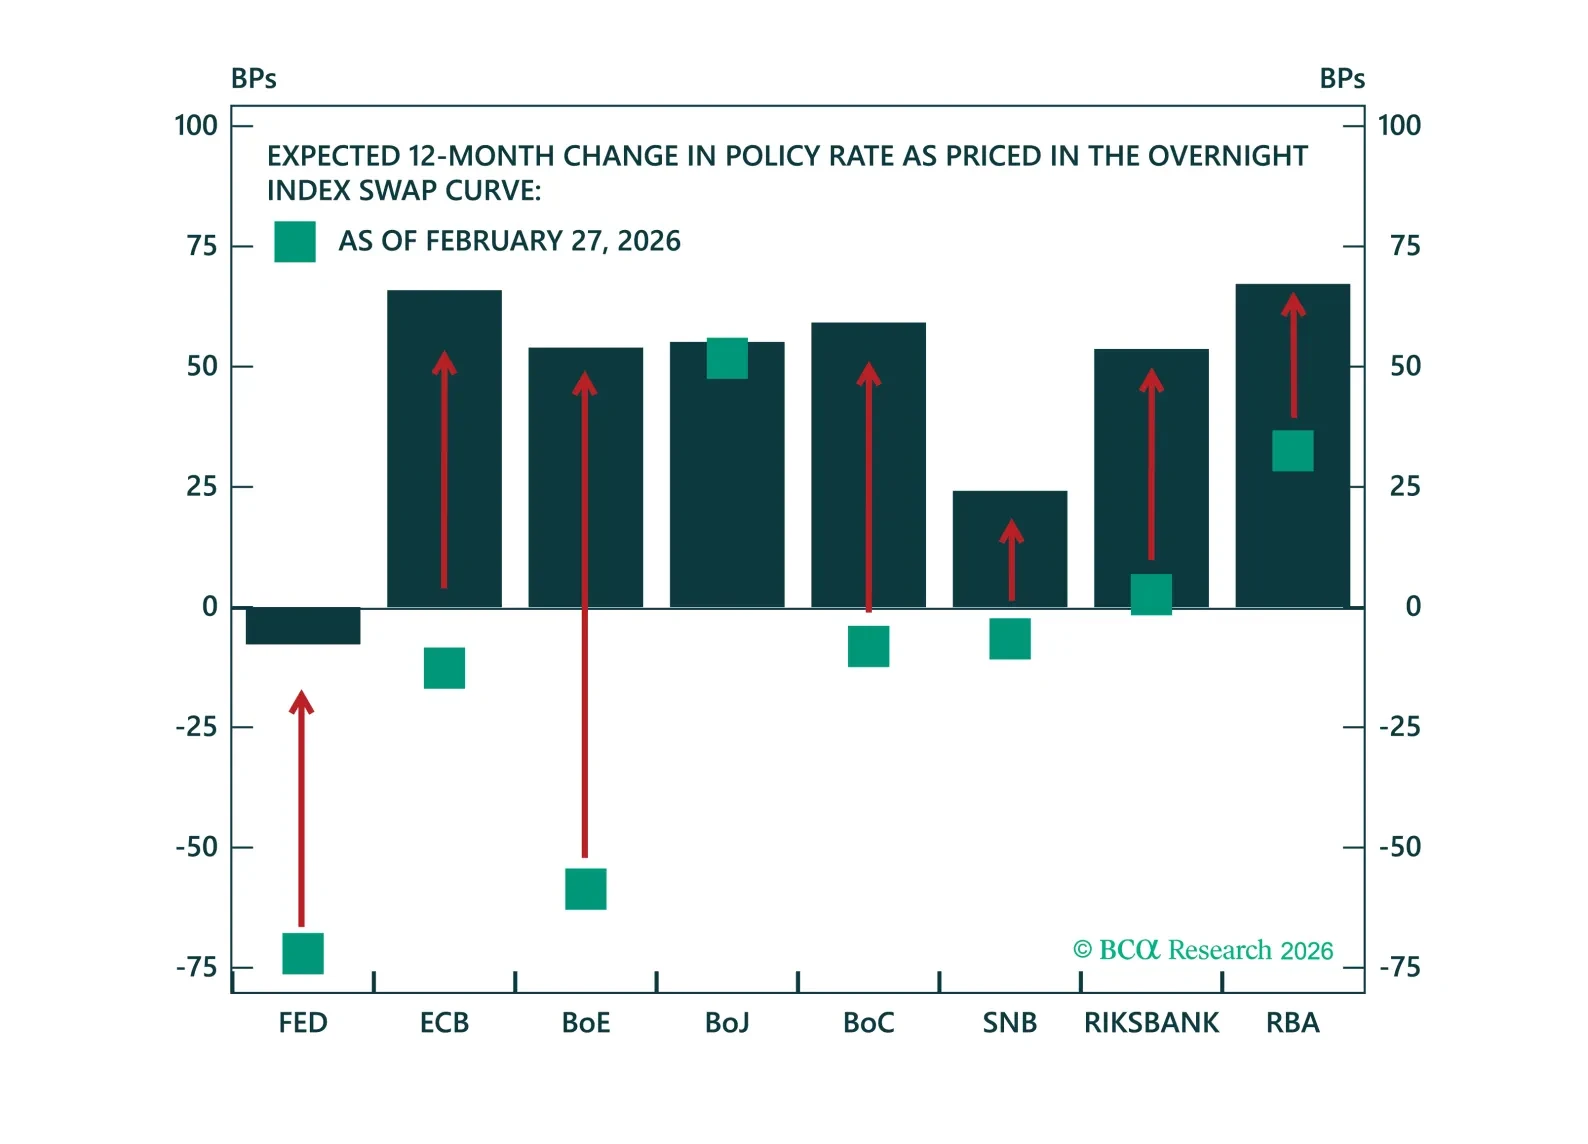
We discuss the takeaways from this week’s central bank meetings amidst the unfolding energy price shock.
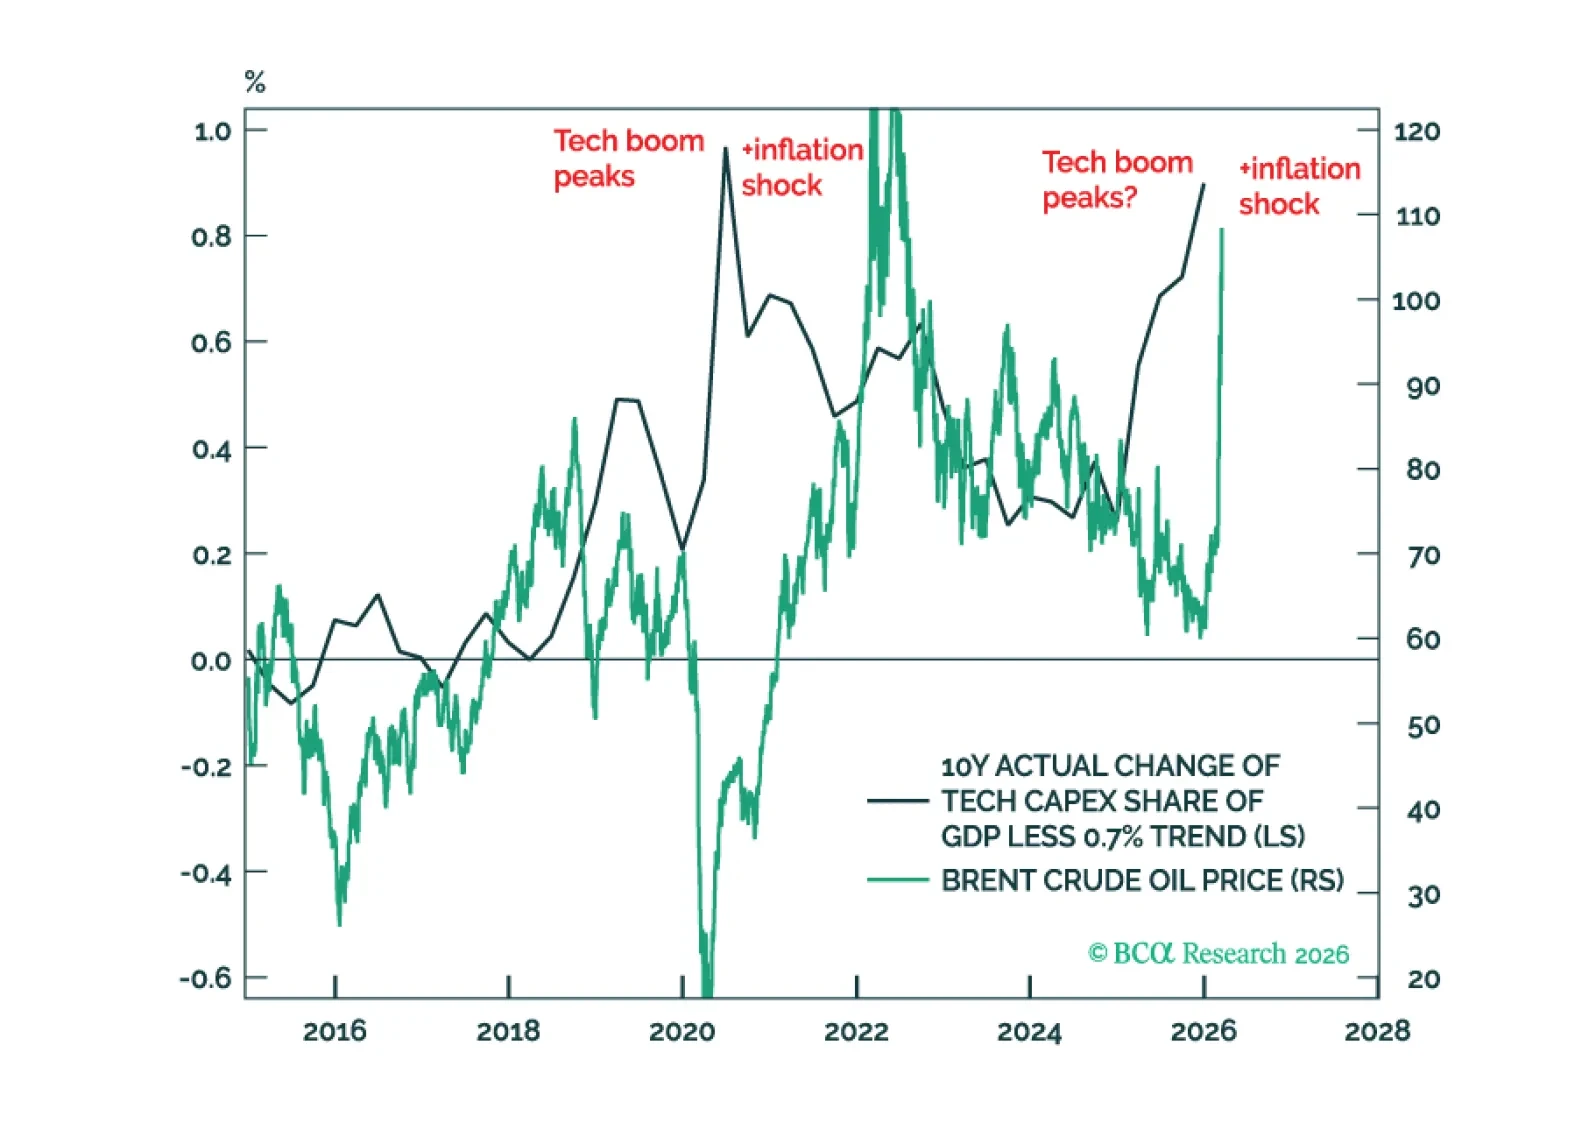
Forced to choose between growth and inflation, the Fed will save growth and the stock market rather than the 2 percent inflation target and the bond market.
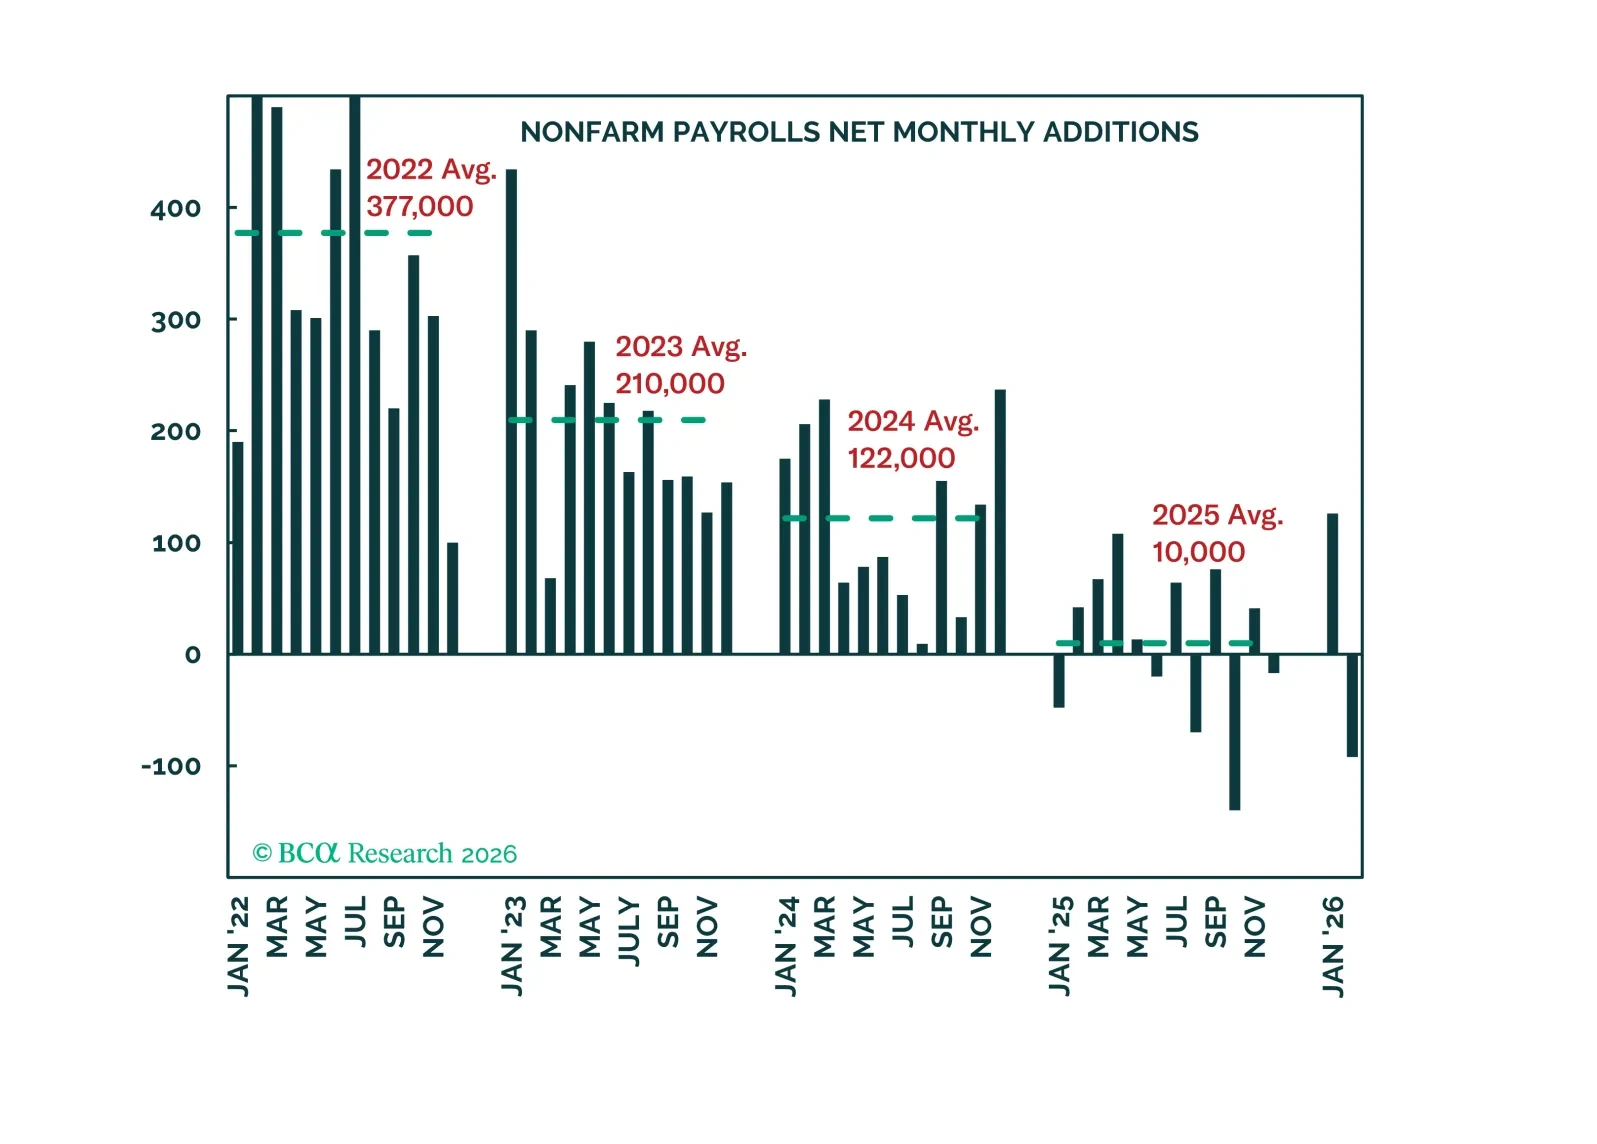
Job creation remains stalled, but consumers are carrying on and S&P 500 earnings have been growing by double digits. Although the repercussions from the war in the Middle East are not yet clear, the US economy was doing just fine before it began.
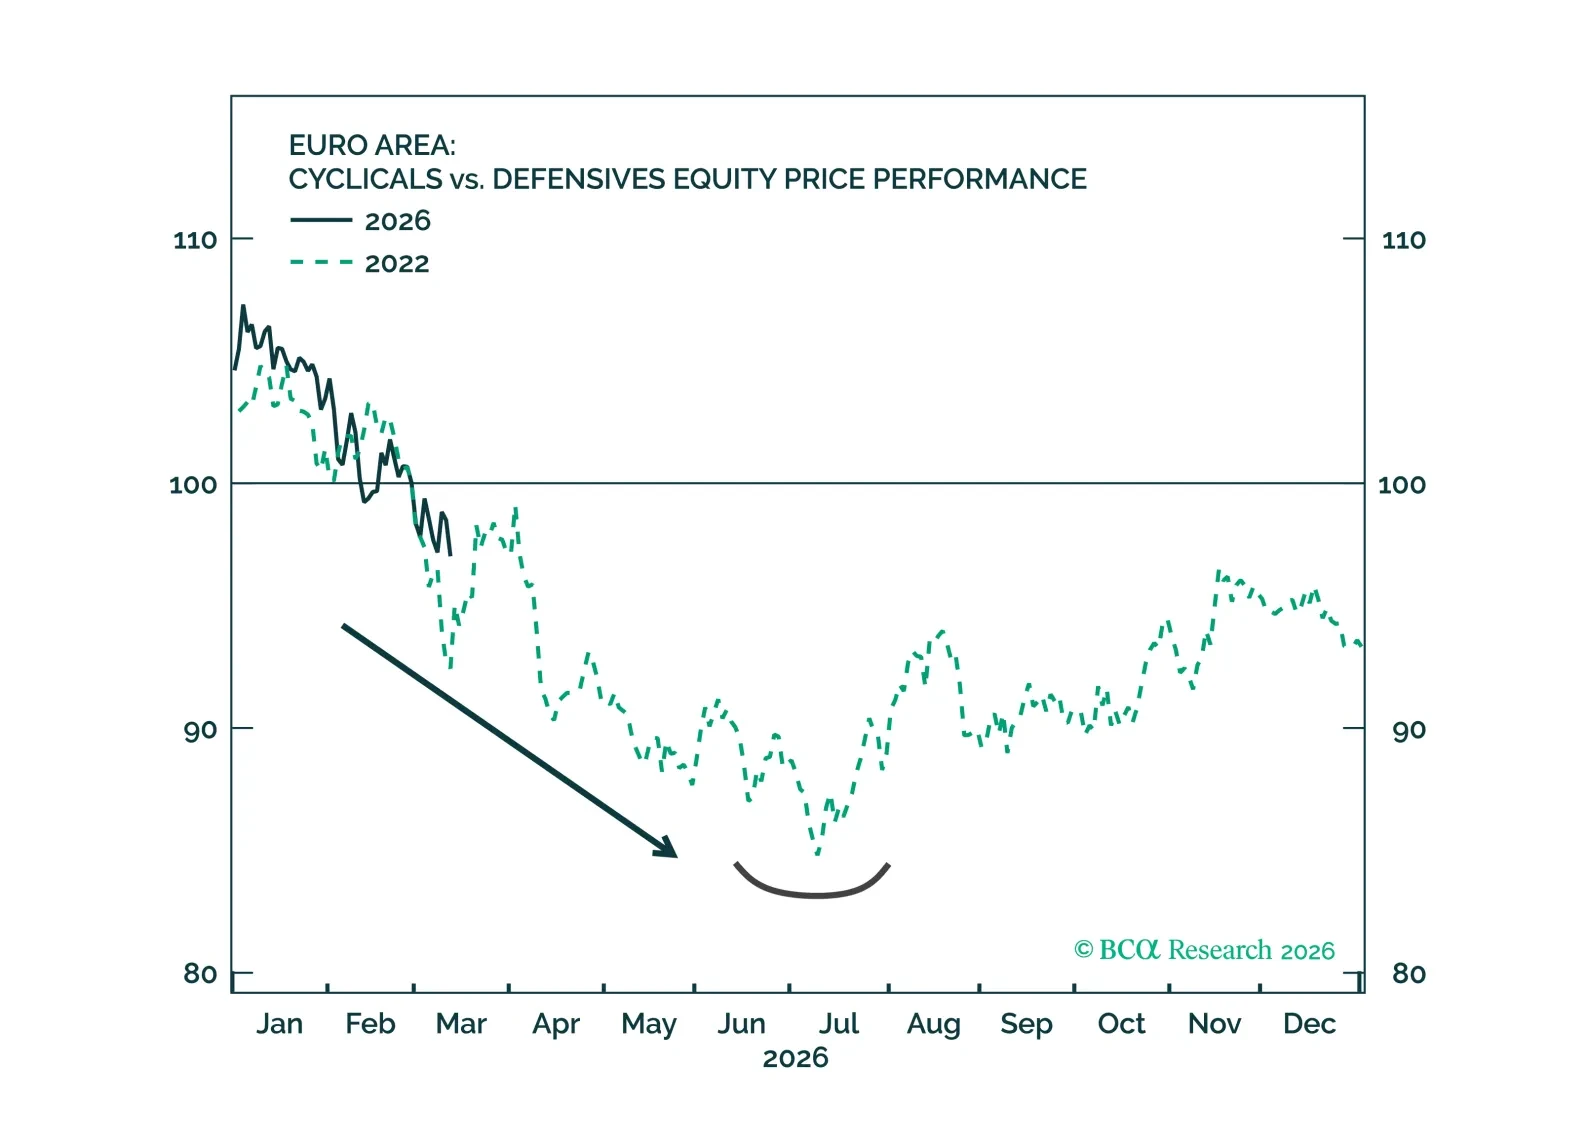
War momentum and escalating rhetoric around the Strait of Hormuz have pushed Brent above $100 and raised the risk of a broader supply shock. While parallels with 2022 offer a roadmap, today’s shock is likely shorter but more globally disruptive. Markets are repricing monetary tightening risks, though we see rate hikes as a mistake absent second-round inflation. Beyond oil, sulfur, helium, and fertilizer disruptions threaten food prices and the AI supply chain. Position defensively.
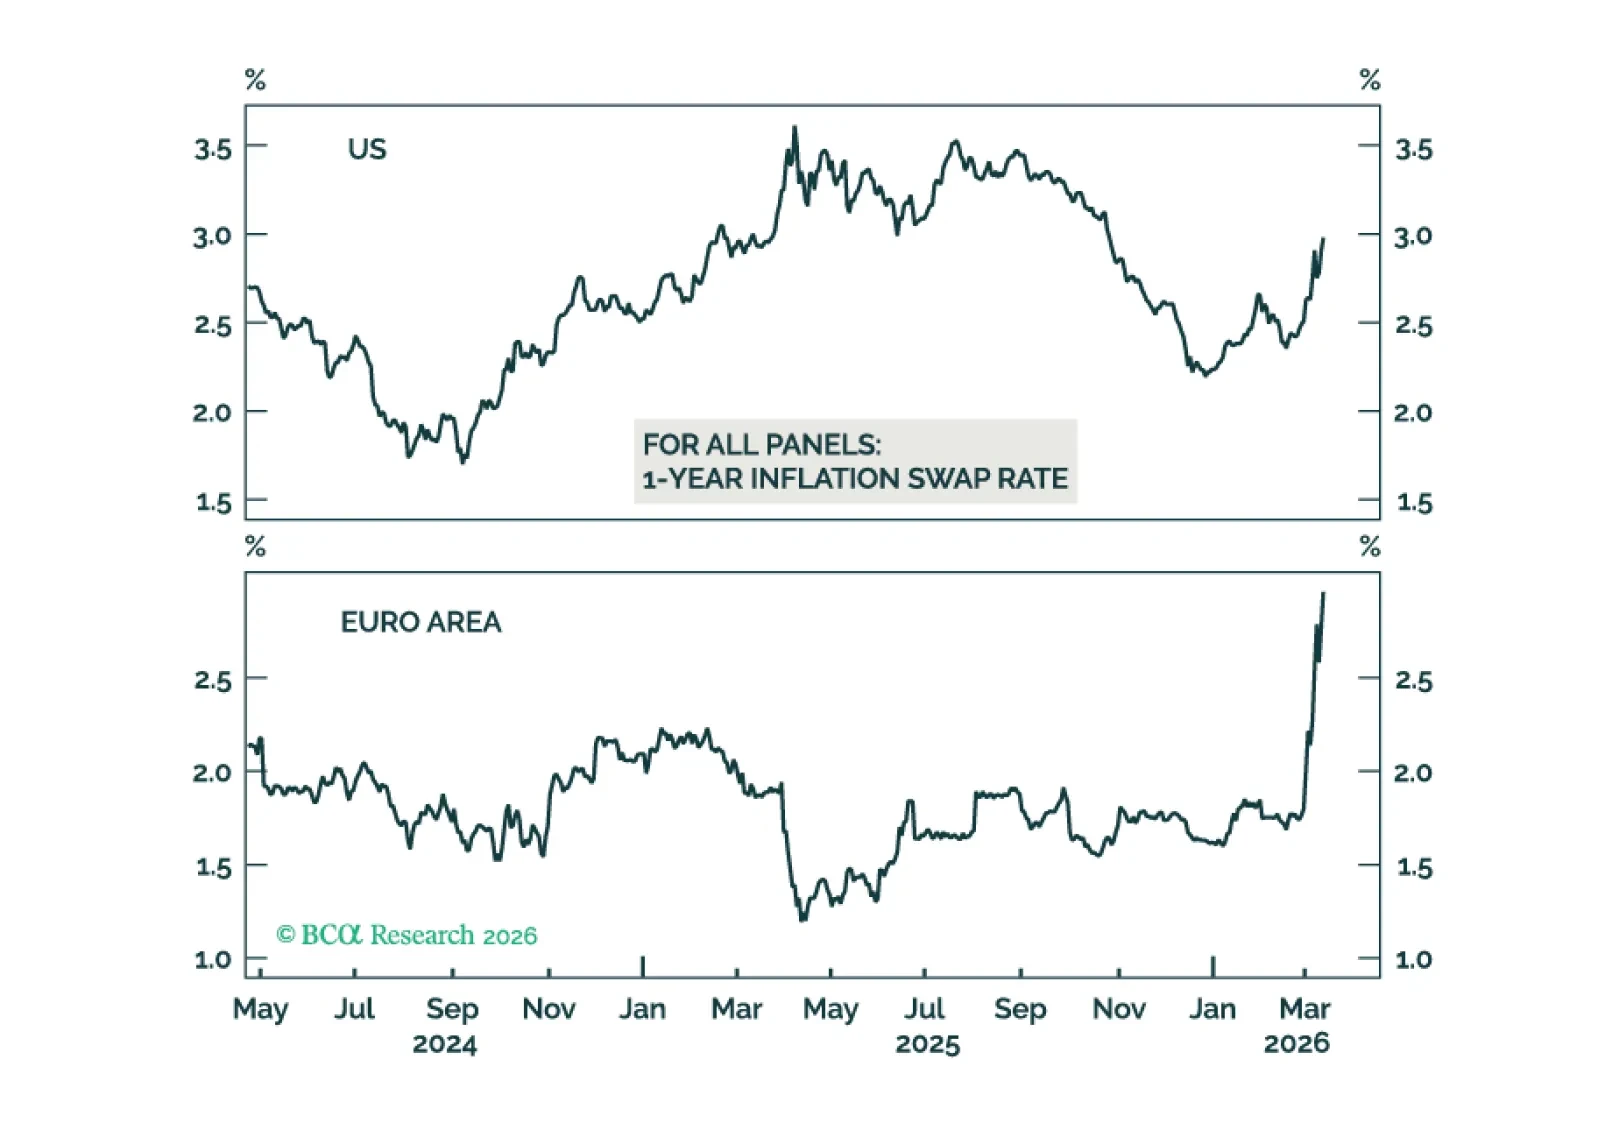
The spike in oil and gas prices has raised the odds of a global economic downturn. Combined with a more negative signal from our MacroQuant model, this warrants tactically downgrading stocks from neutral to underweight. Looking further ahead, the Iran war will lead to bigger defense budgets and a greater focus on energy self-sufficiency.
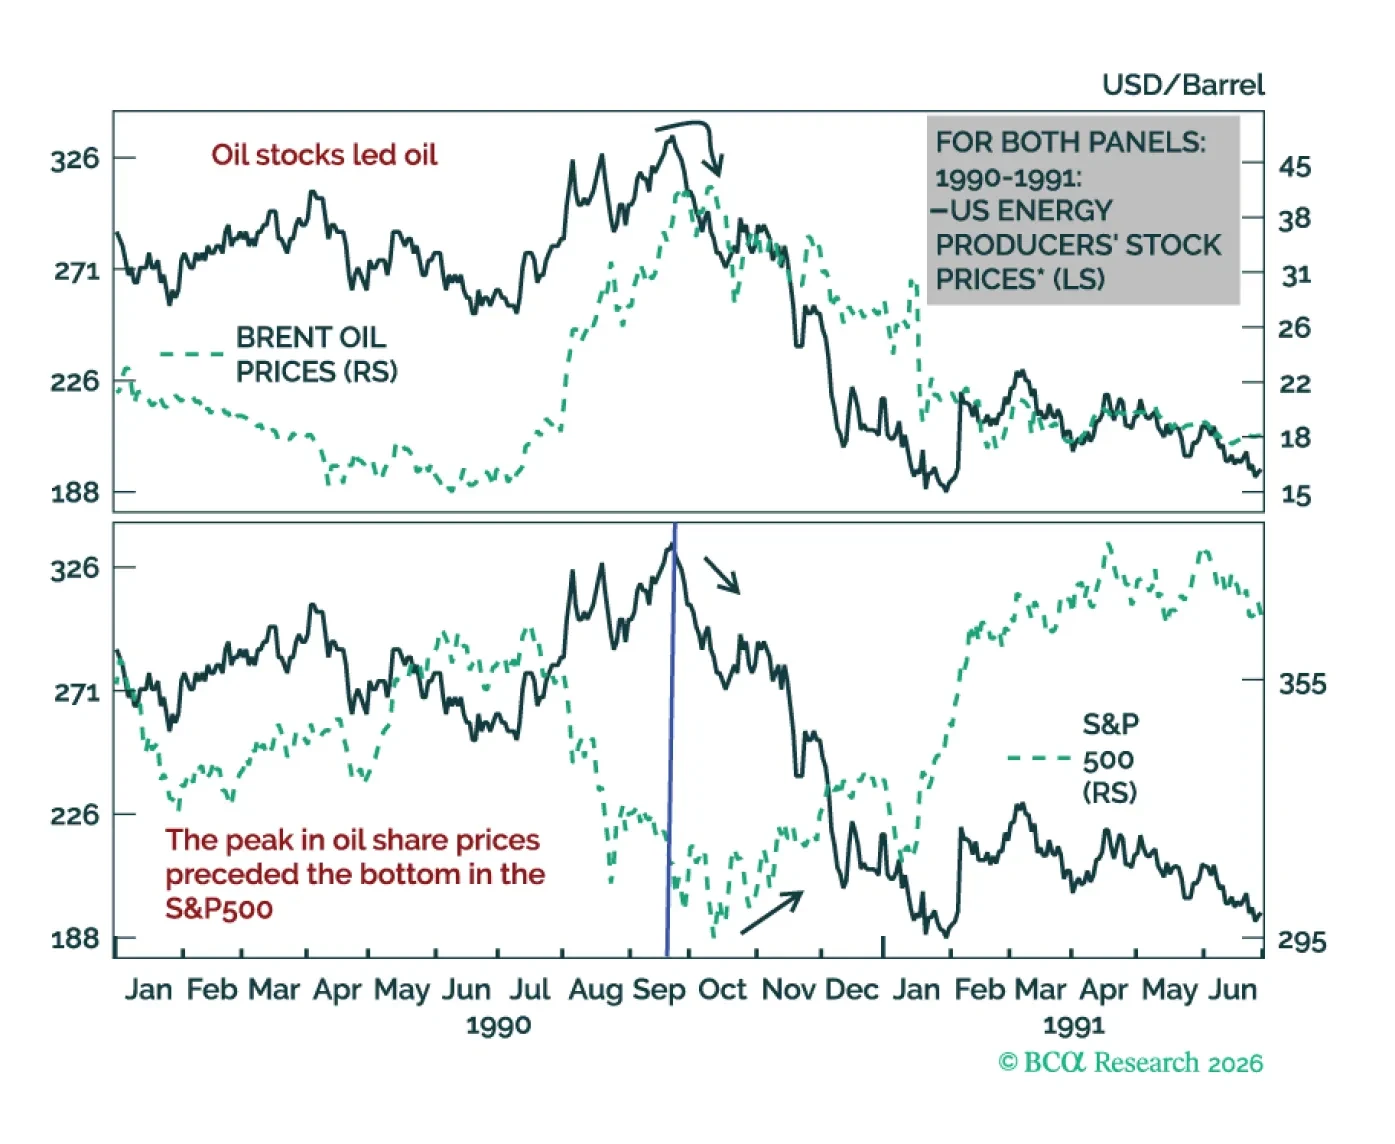
Oil prices will likely rise in the near term, irrespective of developments in the Strait of Hormuz. Given that global share prices have become correlated with crude prices, global stocks will continue selling off. Go short the EM equity index and take profits on our open trades that have benefited from the global risk-on environment.
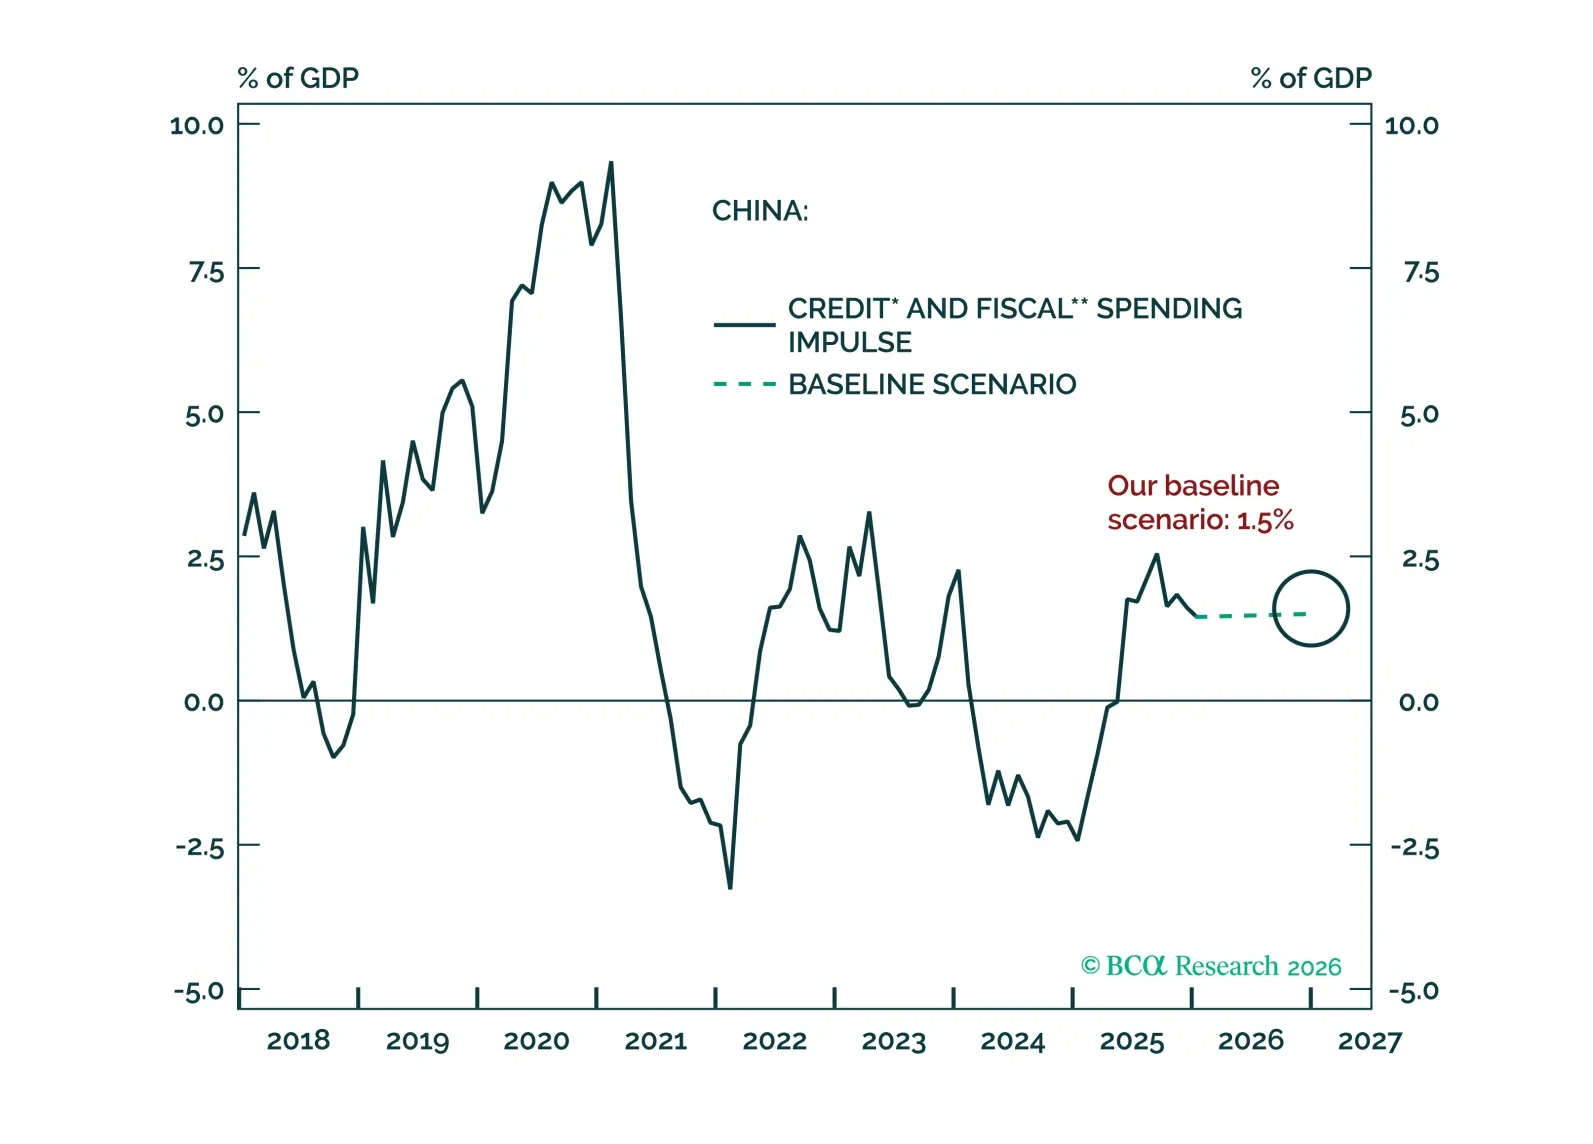
This report unpacks this year’s uneventful NPC, reading the tea leaves of key messages and offering insights on the impact of rising oil prices on China.
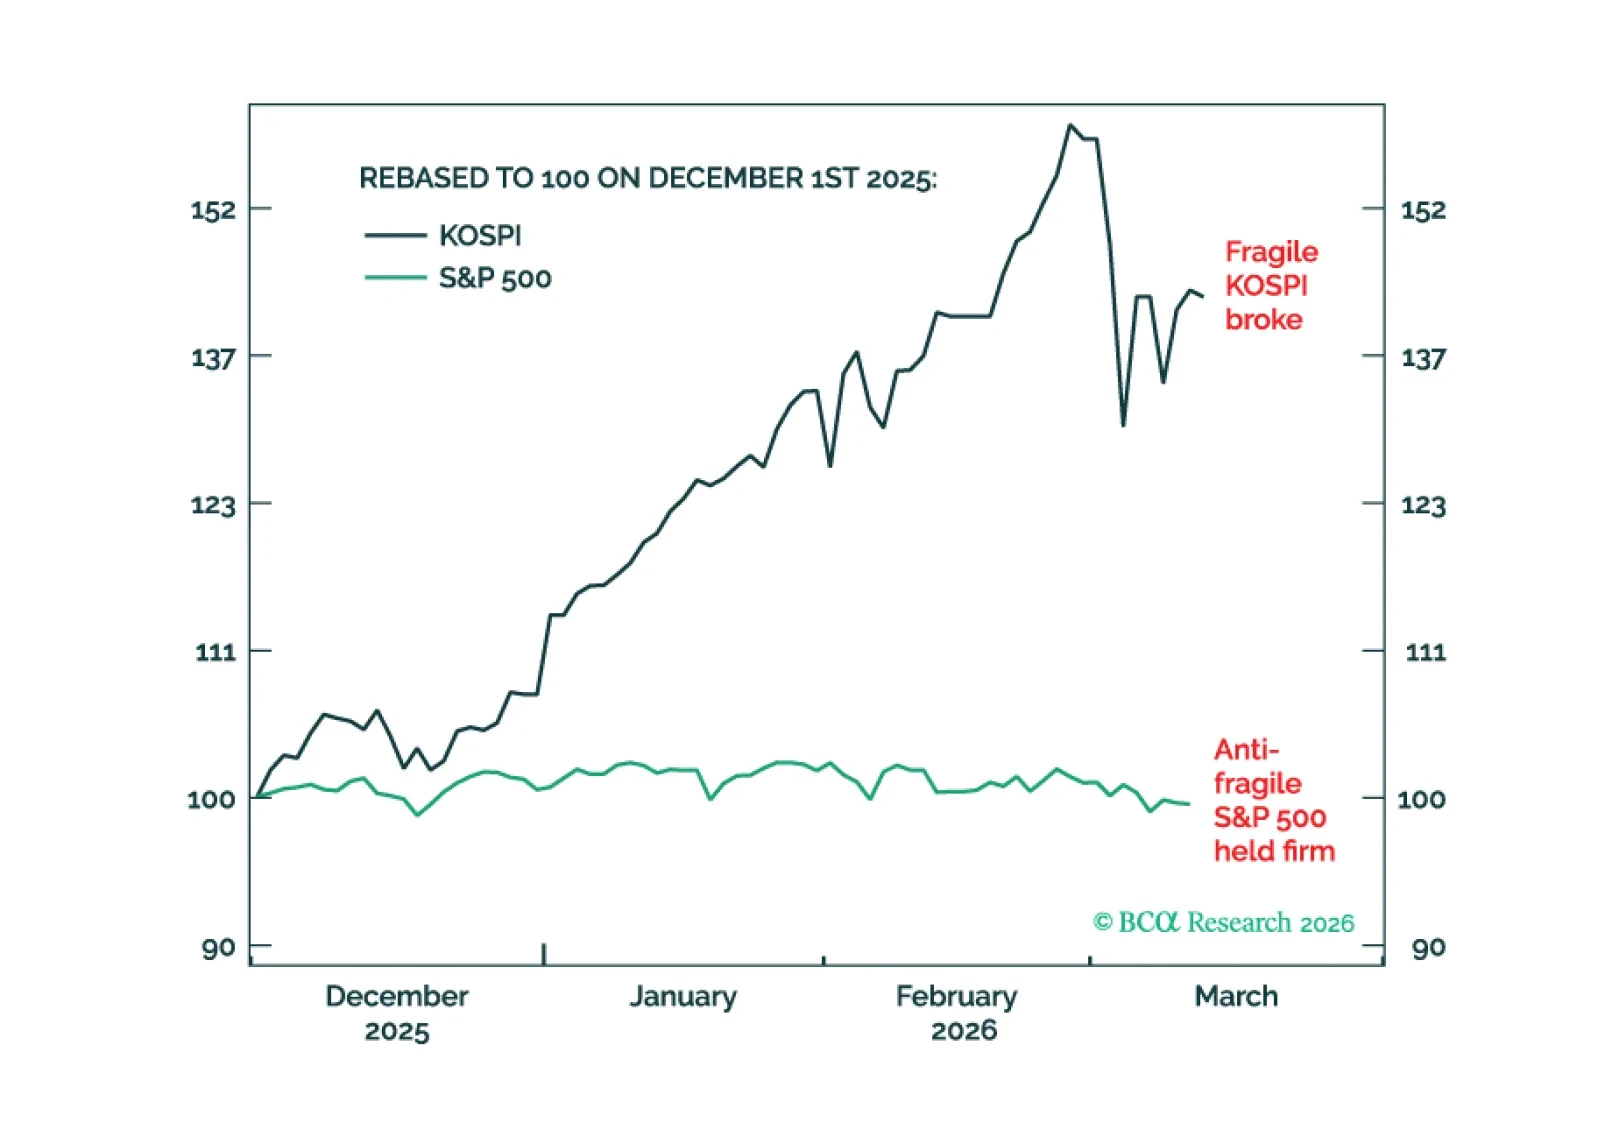
In the ongoing Middle East crisis, anti-fragile markets will remain relatively resilient while fragile markets will break. We describe how to draw the distinction. Plus, a new trade is a 50:50 combination of long USD/MXN and overweight Consumer Discretionary.