 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
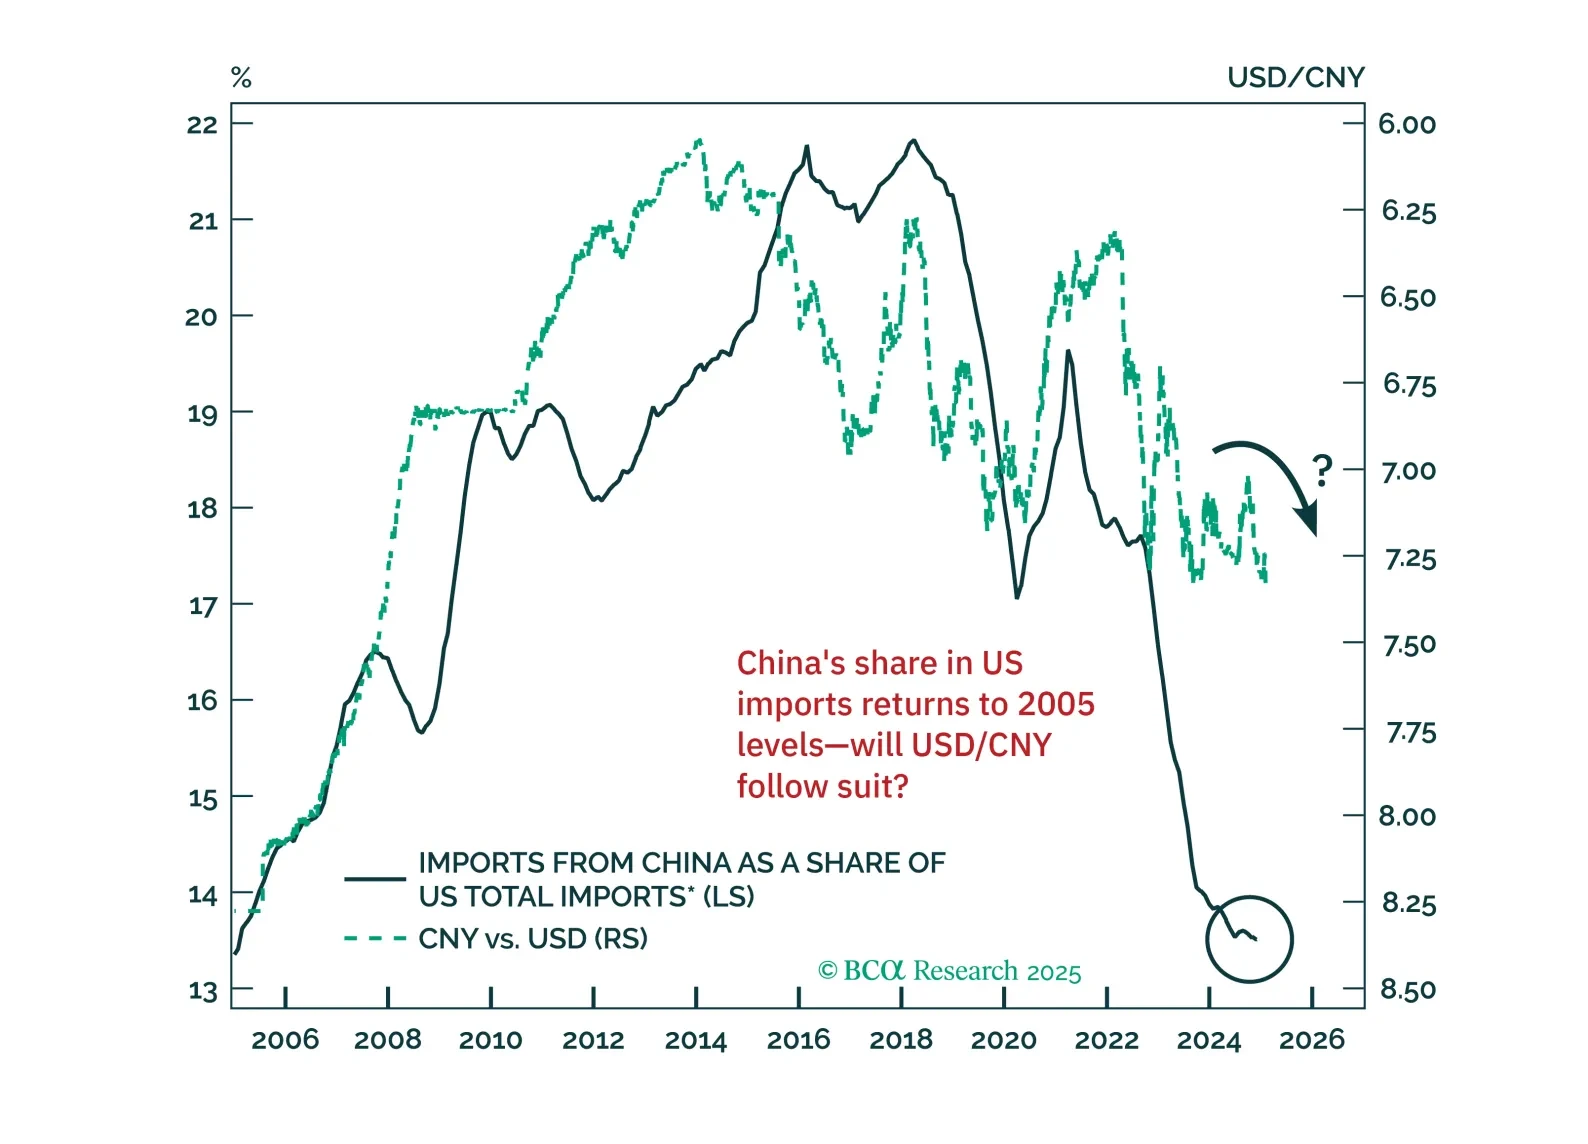
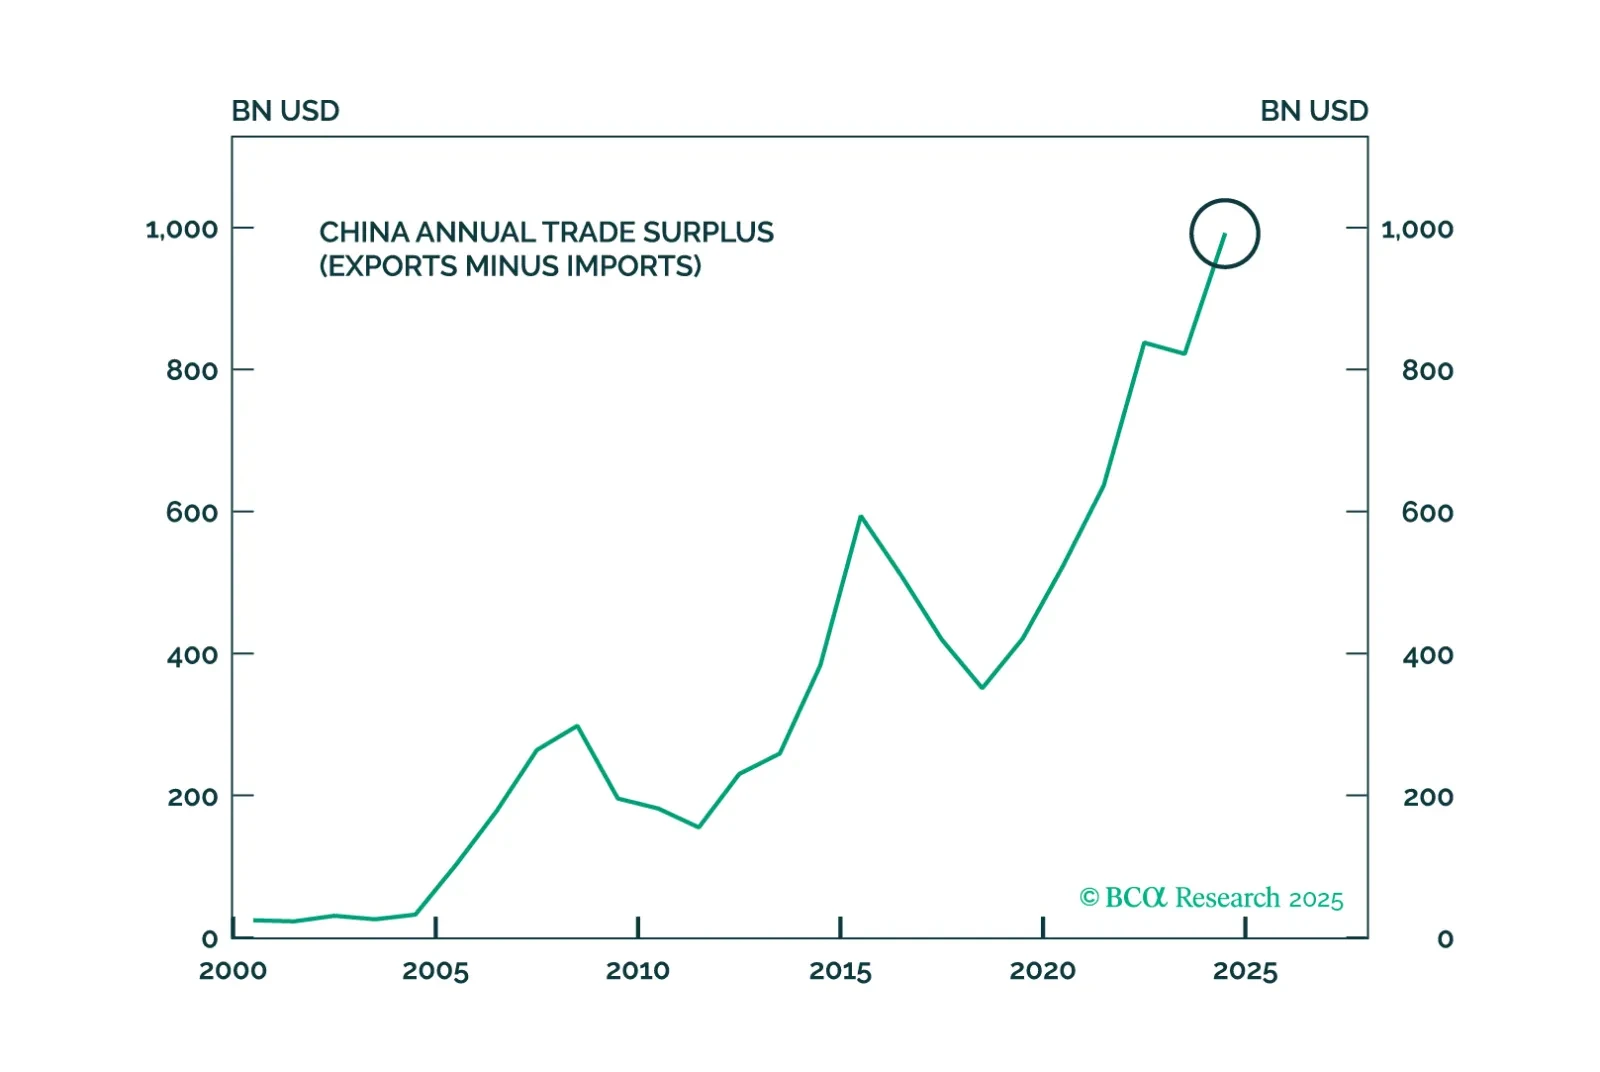
The 10% tariff hike announced on Saturday will likely serve as the opening salvo in a broader wave of protectionist measures. In this report, we assess the increase in US import tariffs on China. While the direct impact on China’s overall economy may be manageable, the country’s economy faces significant risks from potential disruptions in global trade.

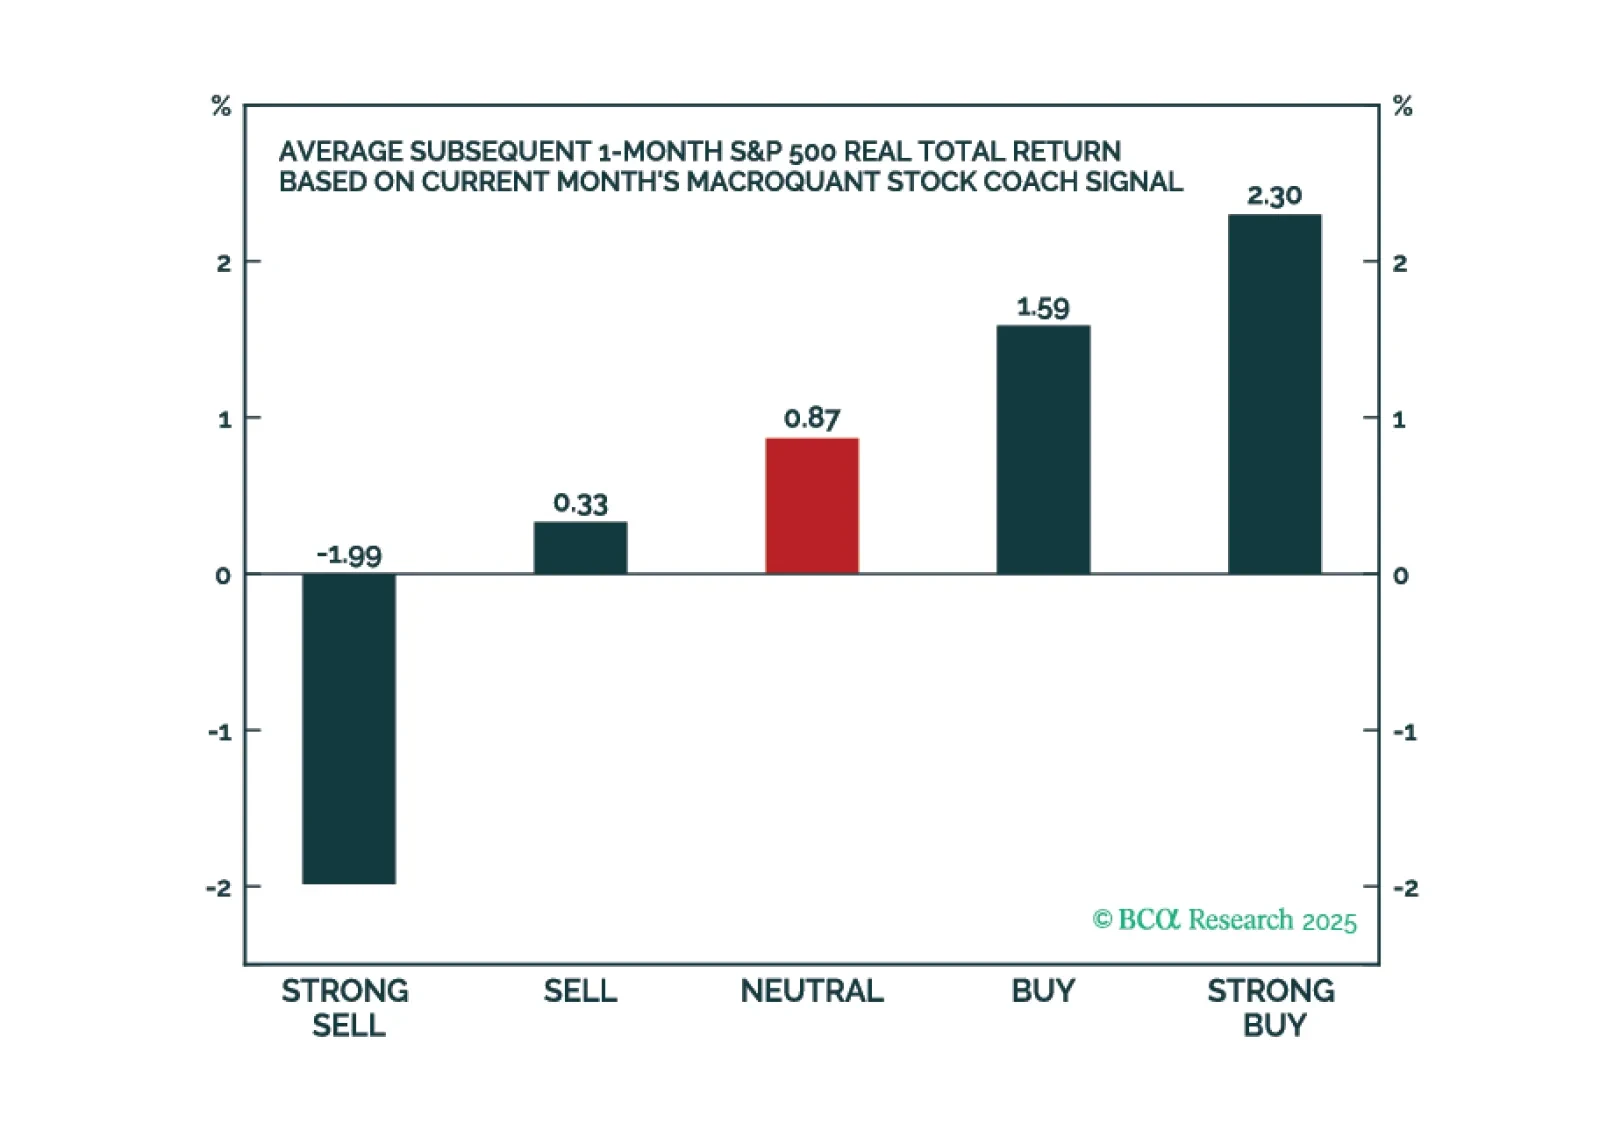
The latest version of the MacroQuant model suggests that the bull market in US stocks is winding down. The model expects Treasury yields to fall later this year but is not ready to go long duration just yet.
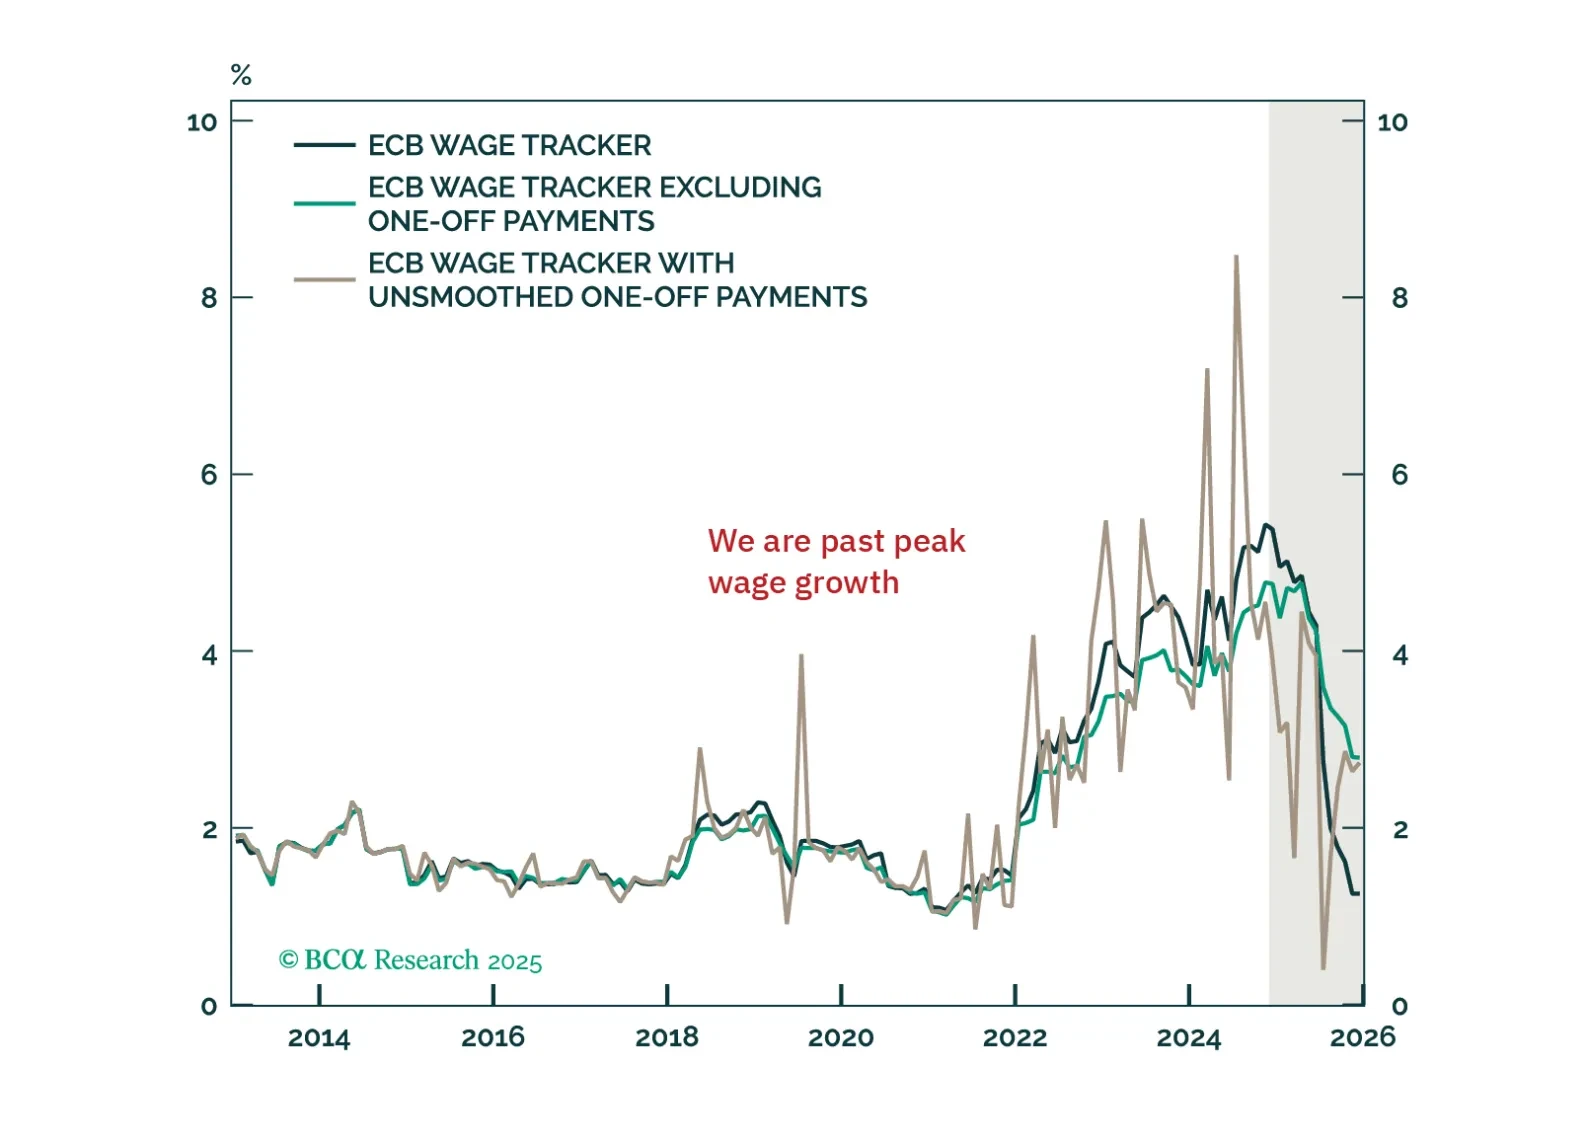
The ECB cut its deposit rate to 2.75%, as was widely anticipated. President Christine Lagarde did not provide any fireworks, but the Governing Council’s message was clear: Policy is restrictive, and inflation will fall further. As a result, if we combine our economic forecasts for the Eurozone with Frankfurt’s data dependency, we continue to expect the ECB’s deposit rate to settle below 2%. Consequently, German bond yields have downside, and the euro has yet to bottomed.
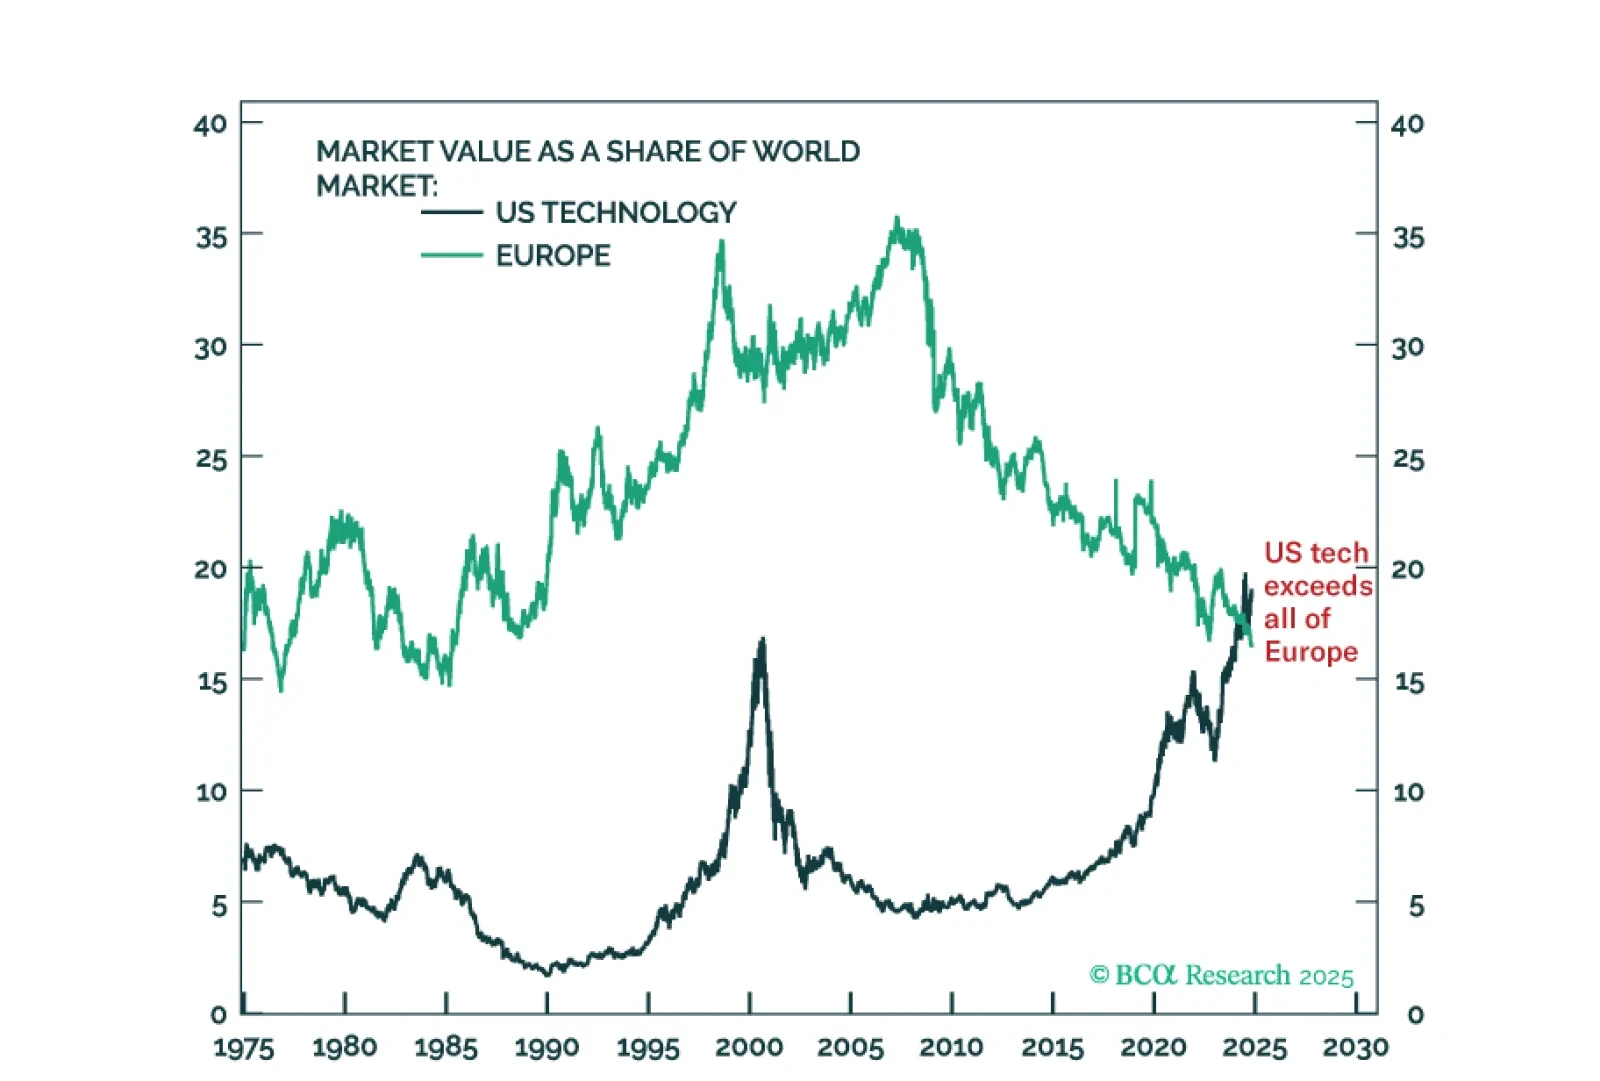
US tech stocks as a share of world stock market capitalisation is at an all-time high that exceeds even the peak of the dot com mania in 2000. At the other extreme, Europe’s share in the world stock market is at a 50-year low. While I am optimistic about the potential of generative-AI, I am not as manically optimistic as the market. And while I am concerned about the current malaise in Europe’s economy and politics, I am not as depressingly concerned as the market. For me, the AI mania combined with Europe’s current malaise is a 50-year mispricing… and opportunity. Plus: go tactically short coffee.
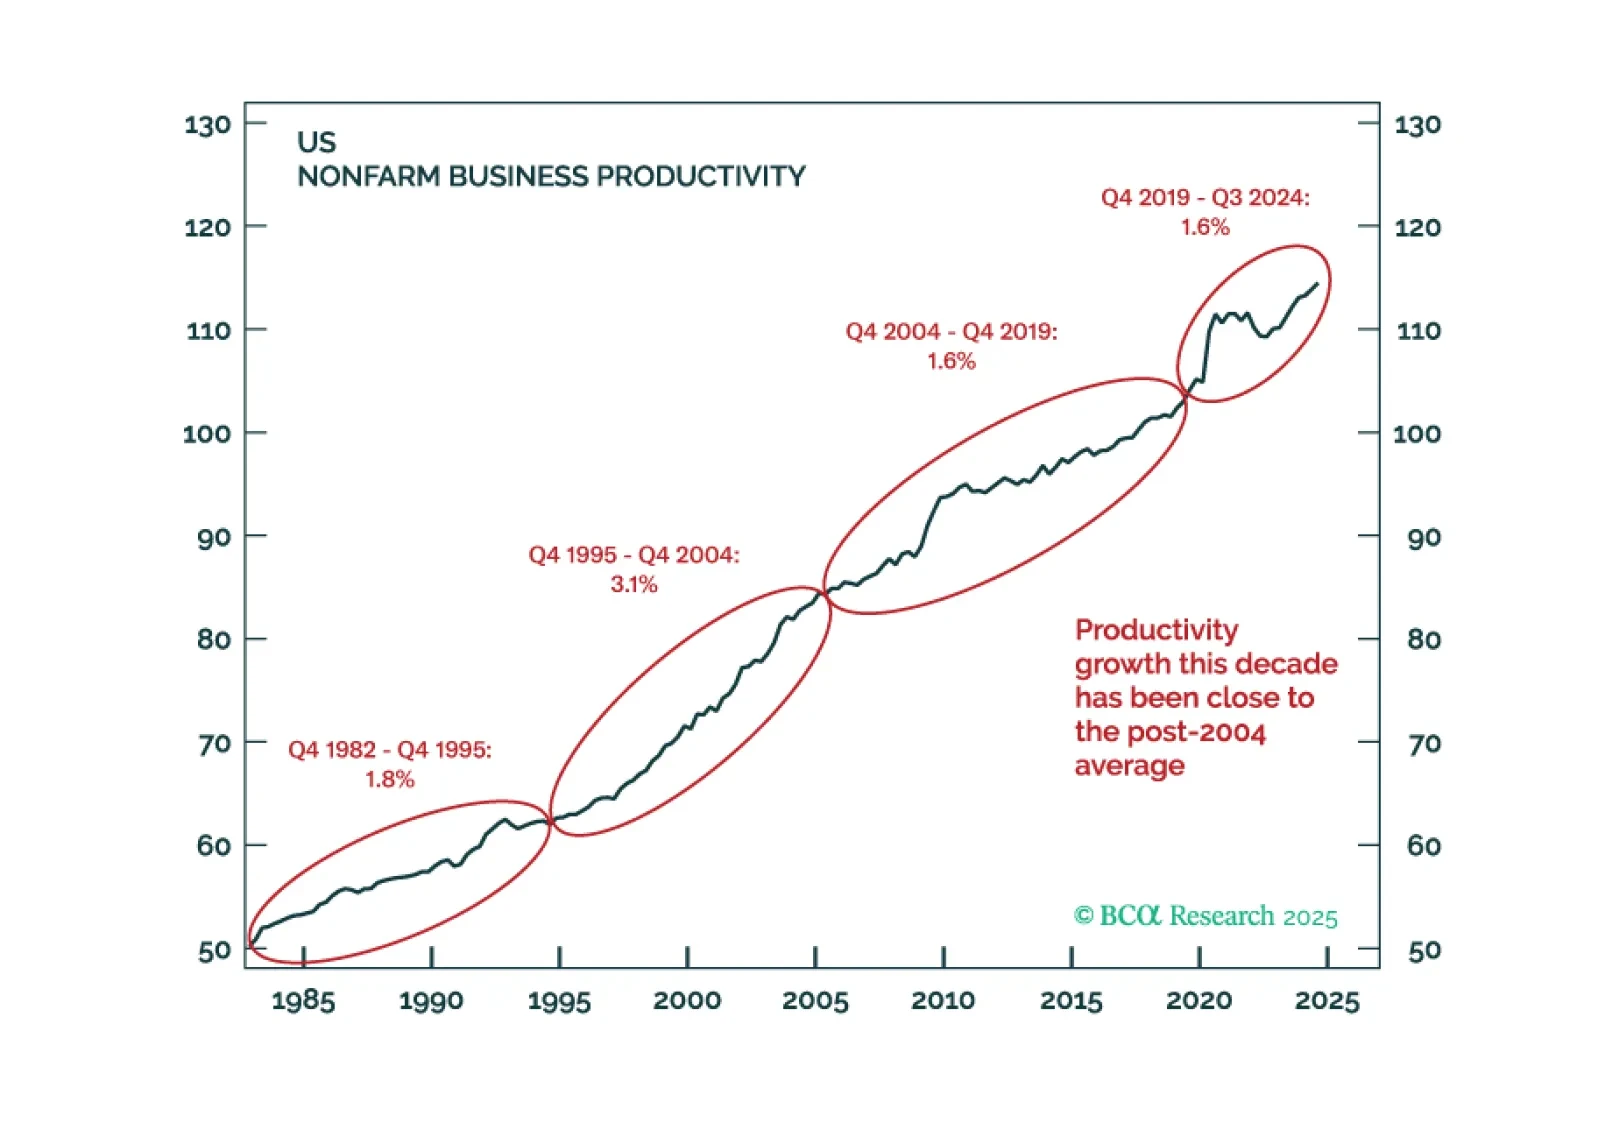
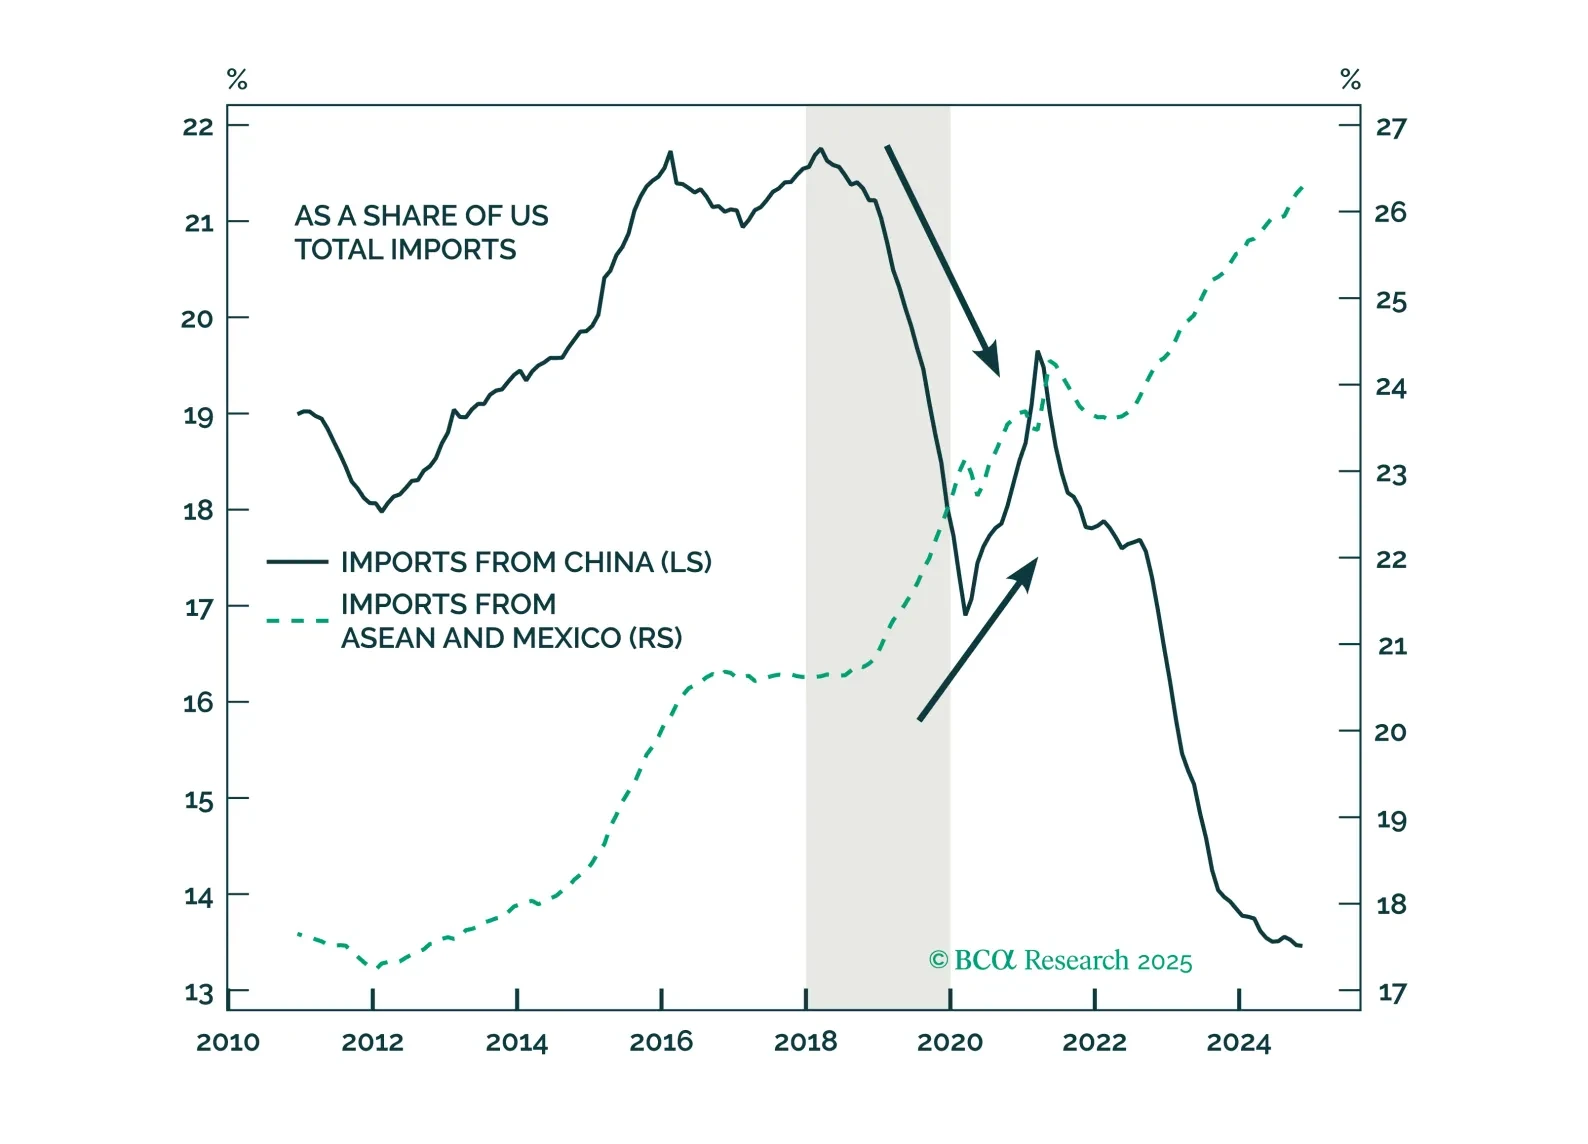
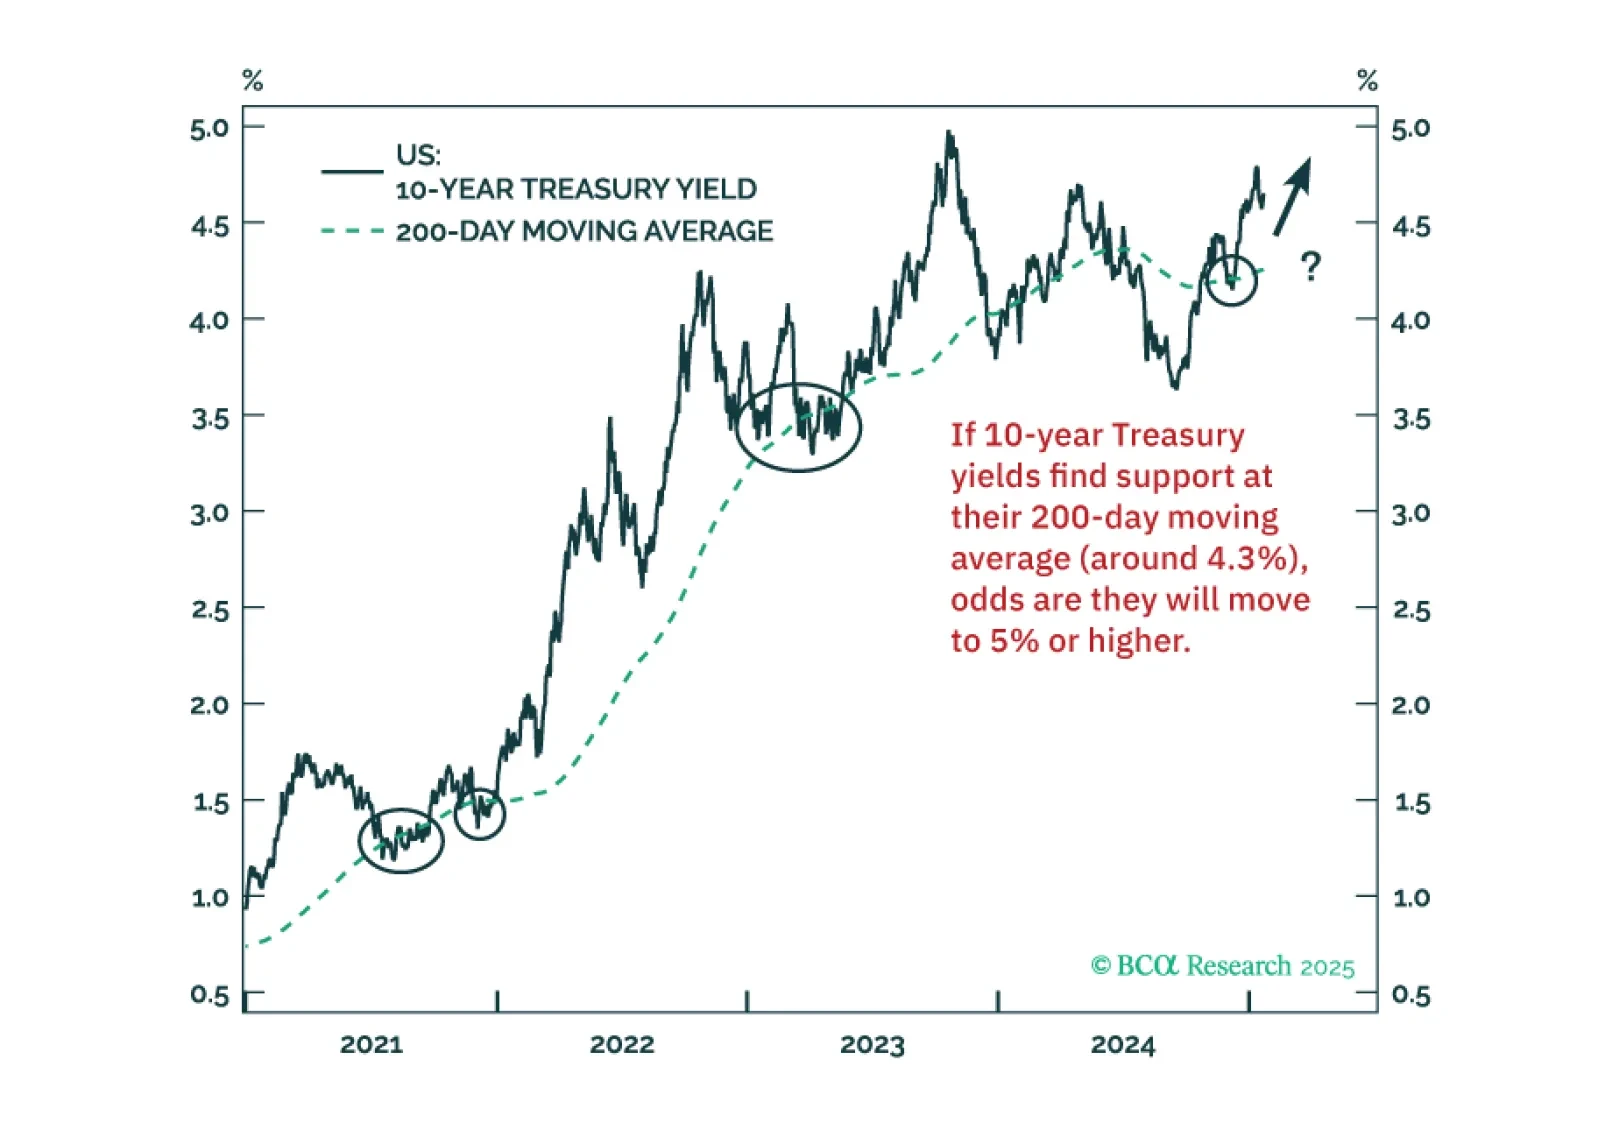
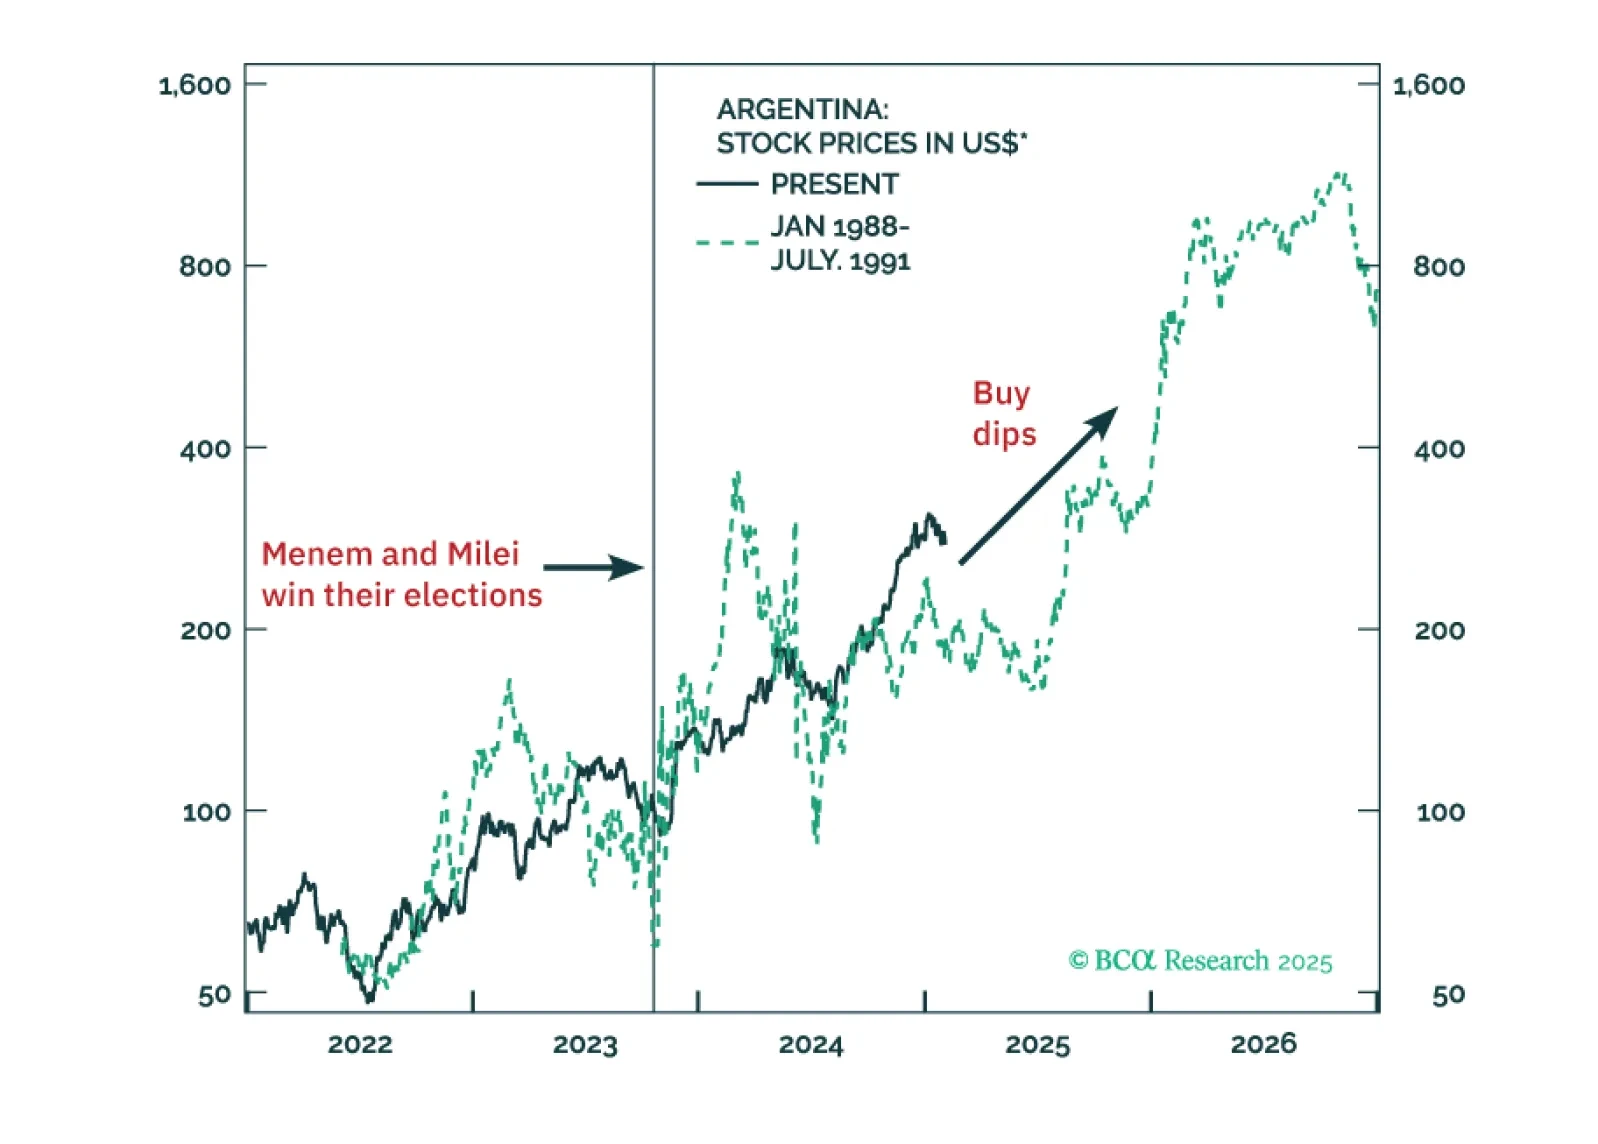
Last week, I visited clients in Europe. My recent report on Bessenomics – the name we gave to US Treasury Secretary Scott Bessent's policy mix – was often the focal point of the discussions. We will continue discussing Bessenomics, its progress, and its investment implications in forthcoming reports. In the meantime, we are sending my chart pack used during this trip as a Charts That Matter publication – a chart-based report. It covers the following areas: China, Bessenomics, US fixed income, global currencies, EM credit markets, the global ex-US business cycle, EM and US equities, and an EM local bond relative value matrix. In my opinion, the most important variable in global financial markets are US long-term Treasury yields. If they hold above their 200-day moving average, odds are that new highs lie ahead. My hunch is that 10-year yields will break above 5%. When and as this happens, global risk assets will sell off considerably.