Skip to main content

CoreMacro

BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
Explore CoreMacro
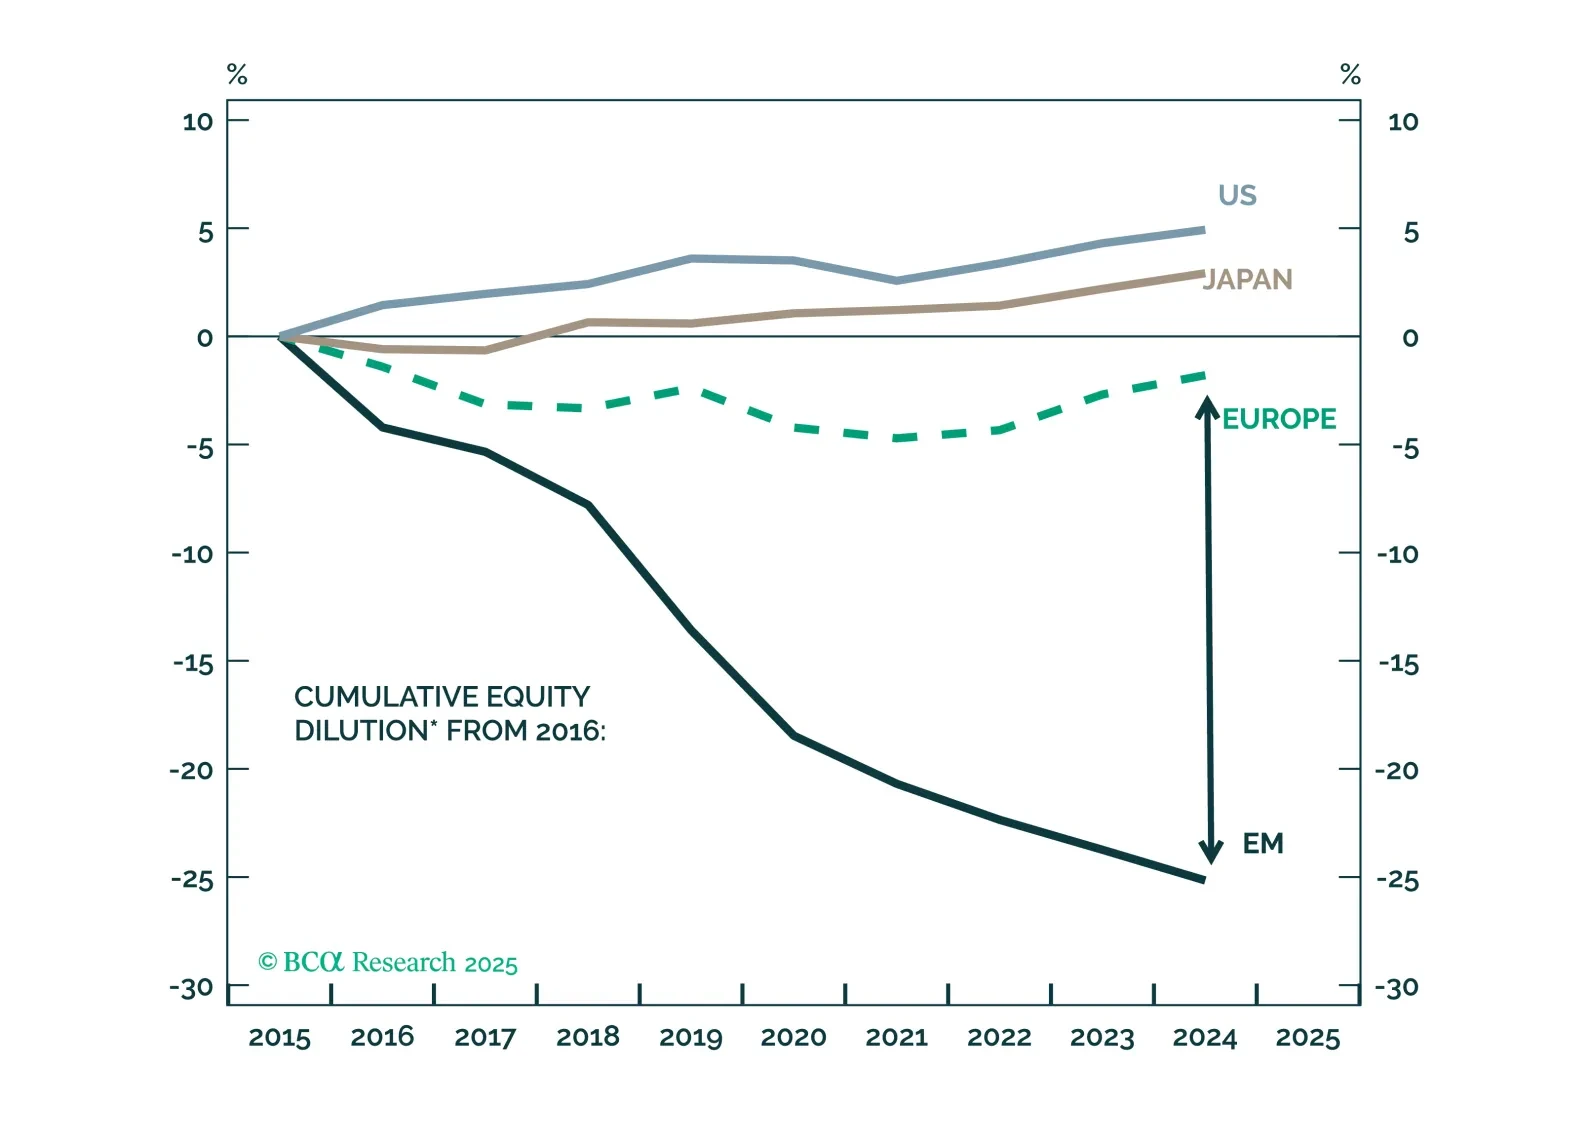
Special Report Dilution is one of the two main reasons why EM EPS has been much weaker than EM GDP and EM non-diluted profits. We calculate “pure” dilution – adjusted for companies’ inclusion and exclusion from the stock index – for various bourses around the world. To our knowledge, this is the first time this analysis has been conducted.
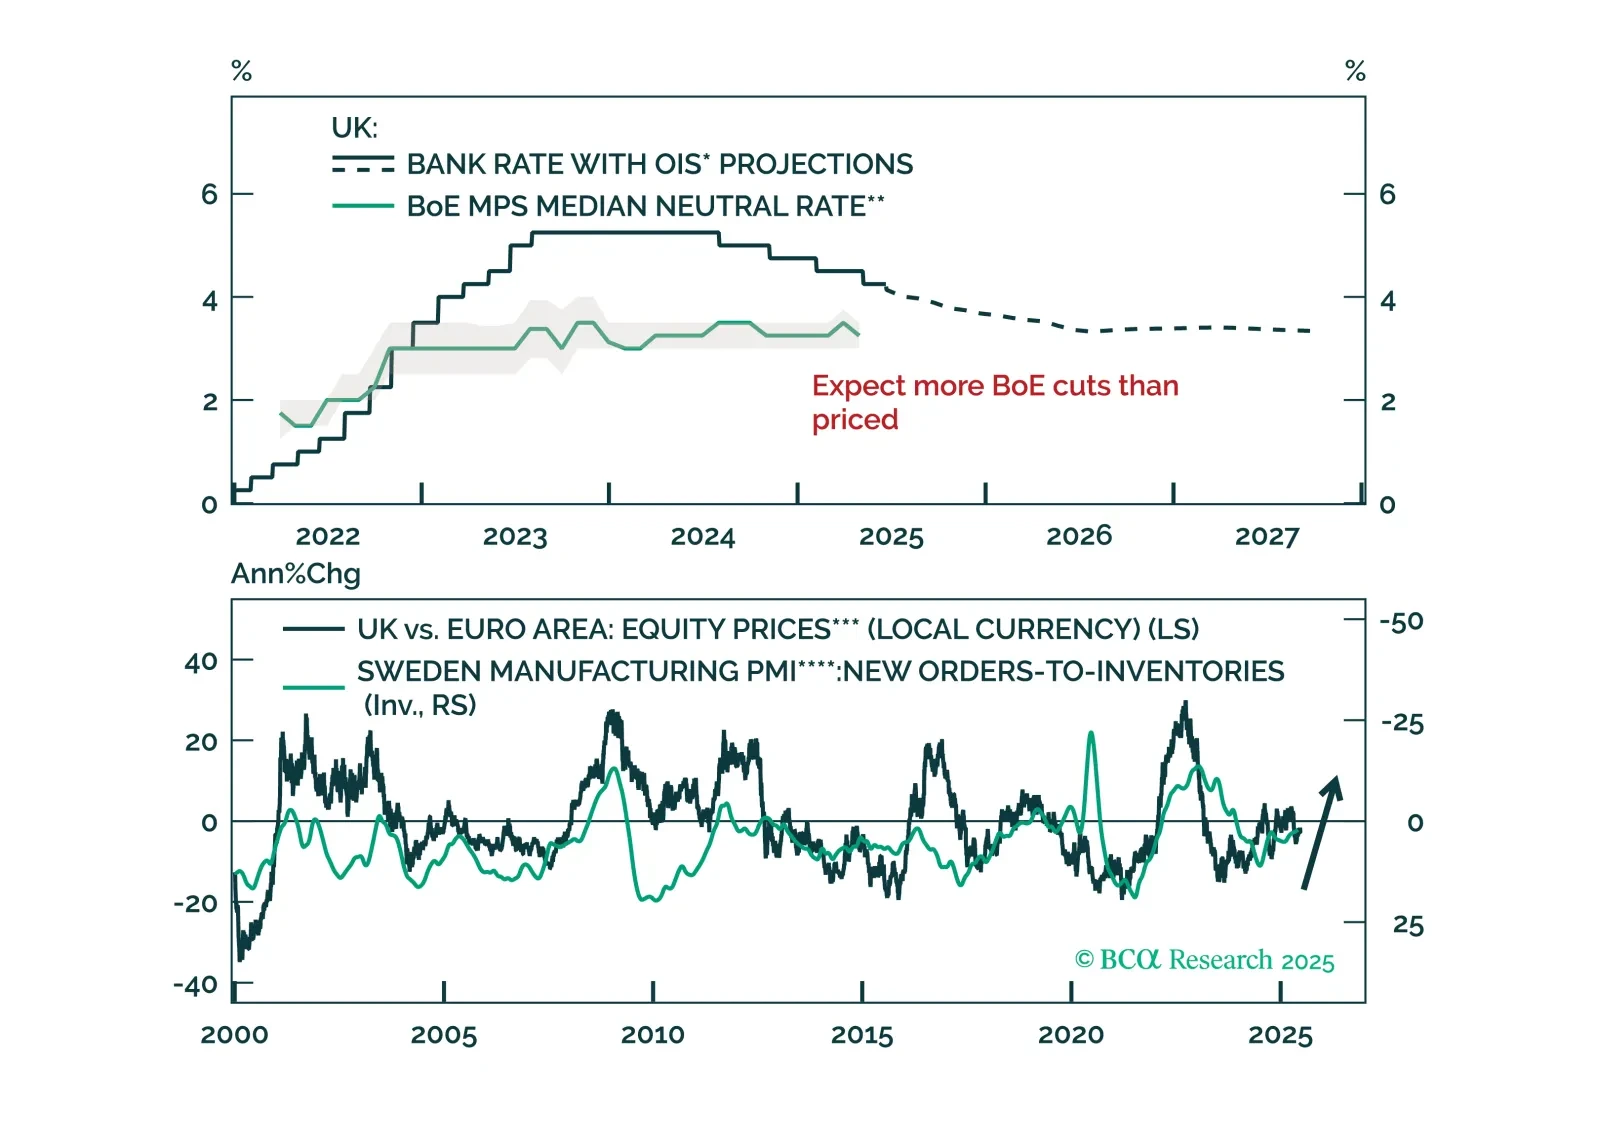
Special Report UK inflation risks are falling on the back of a weakening labor market. Read why Gilts and UK stocks are poised to outperform as BoE easing resumes.
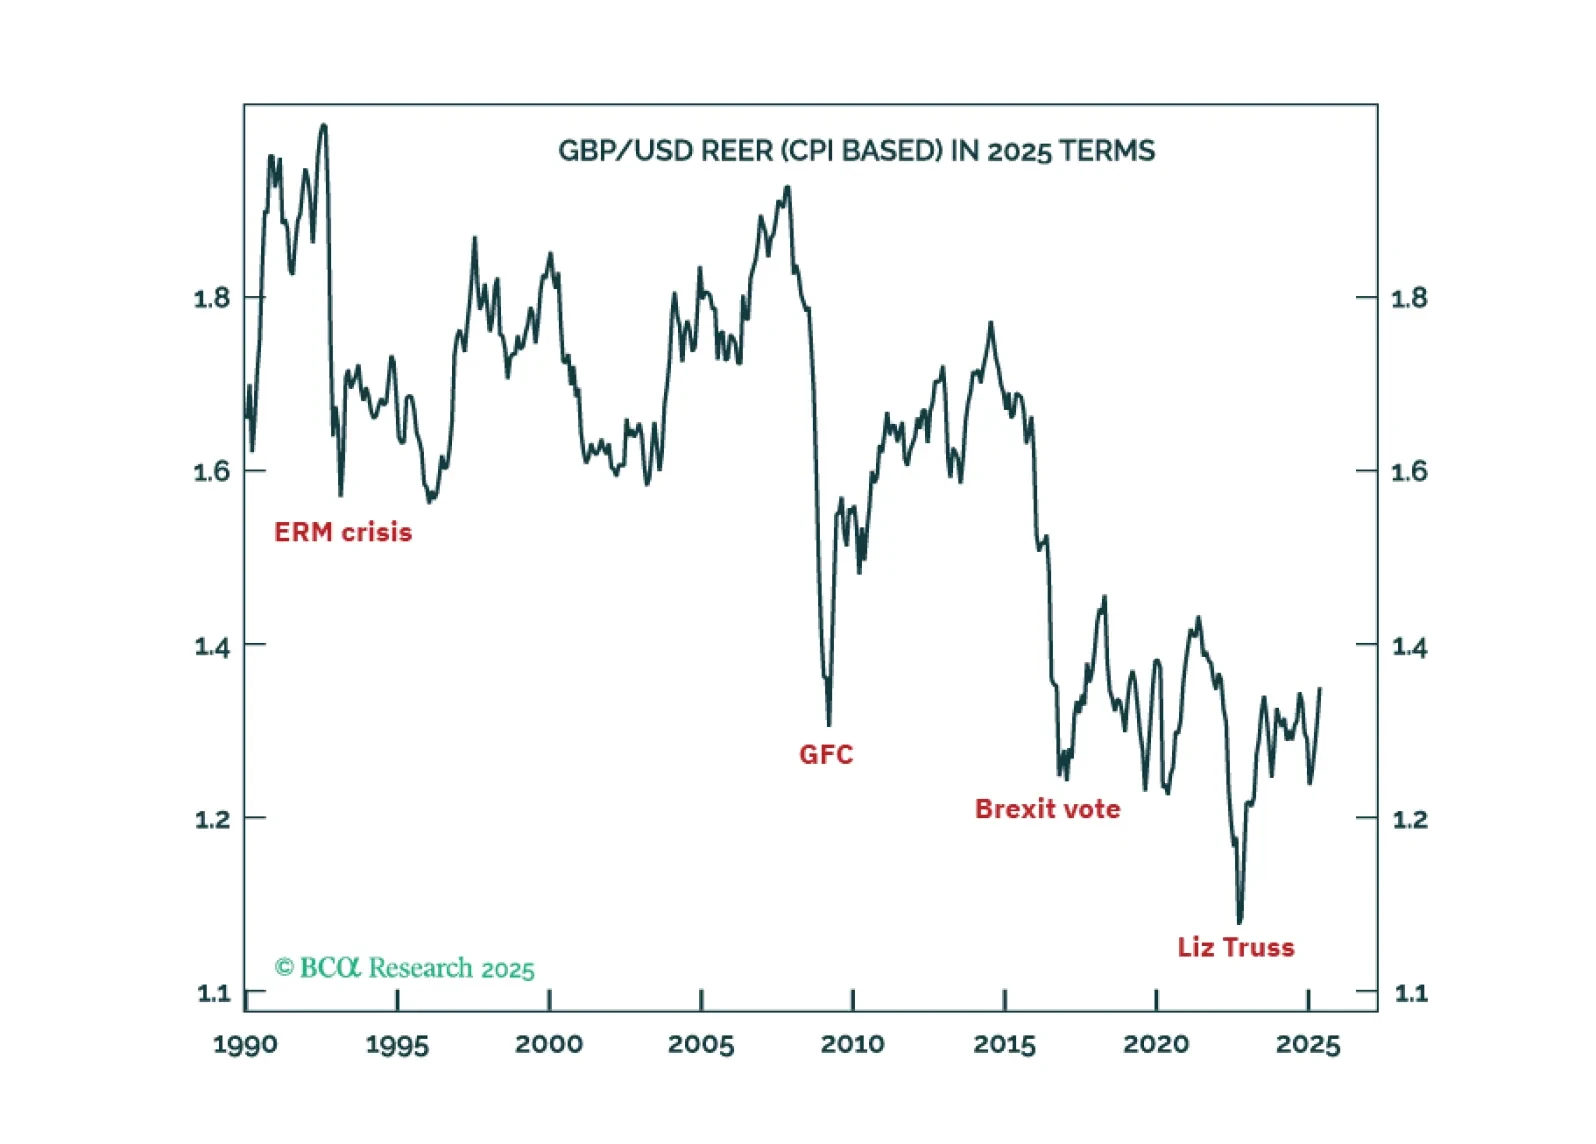
The pound will reach $1.60 if ‘America’s Brexit’ cancels out ‘Britain’s Brexit’. Meanwhile, the flight from the fiat dollar to non-fiat bitcoin will enable the preeminent cryptocurrency to reach $200,000+.
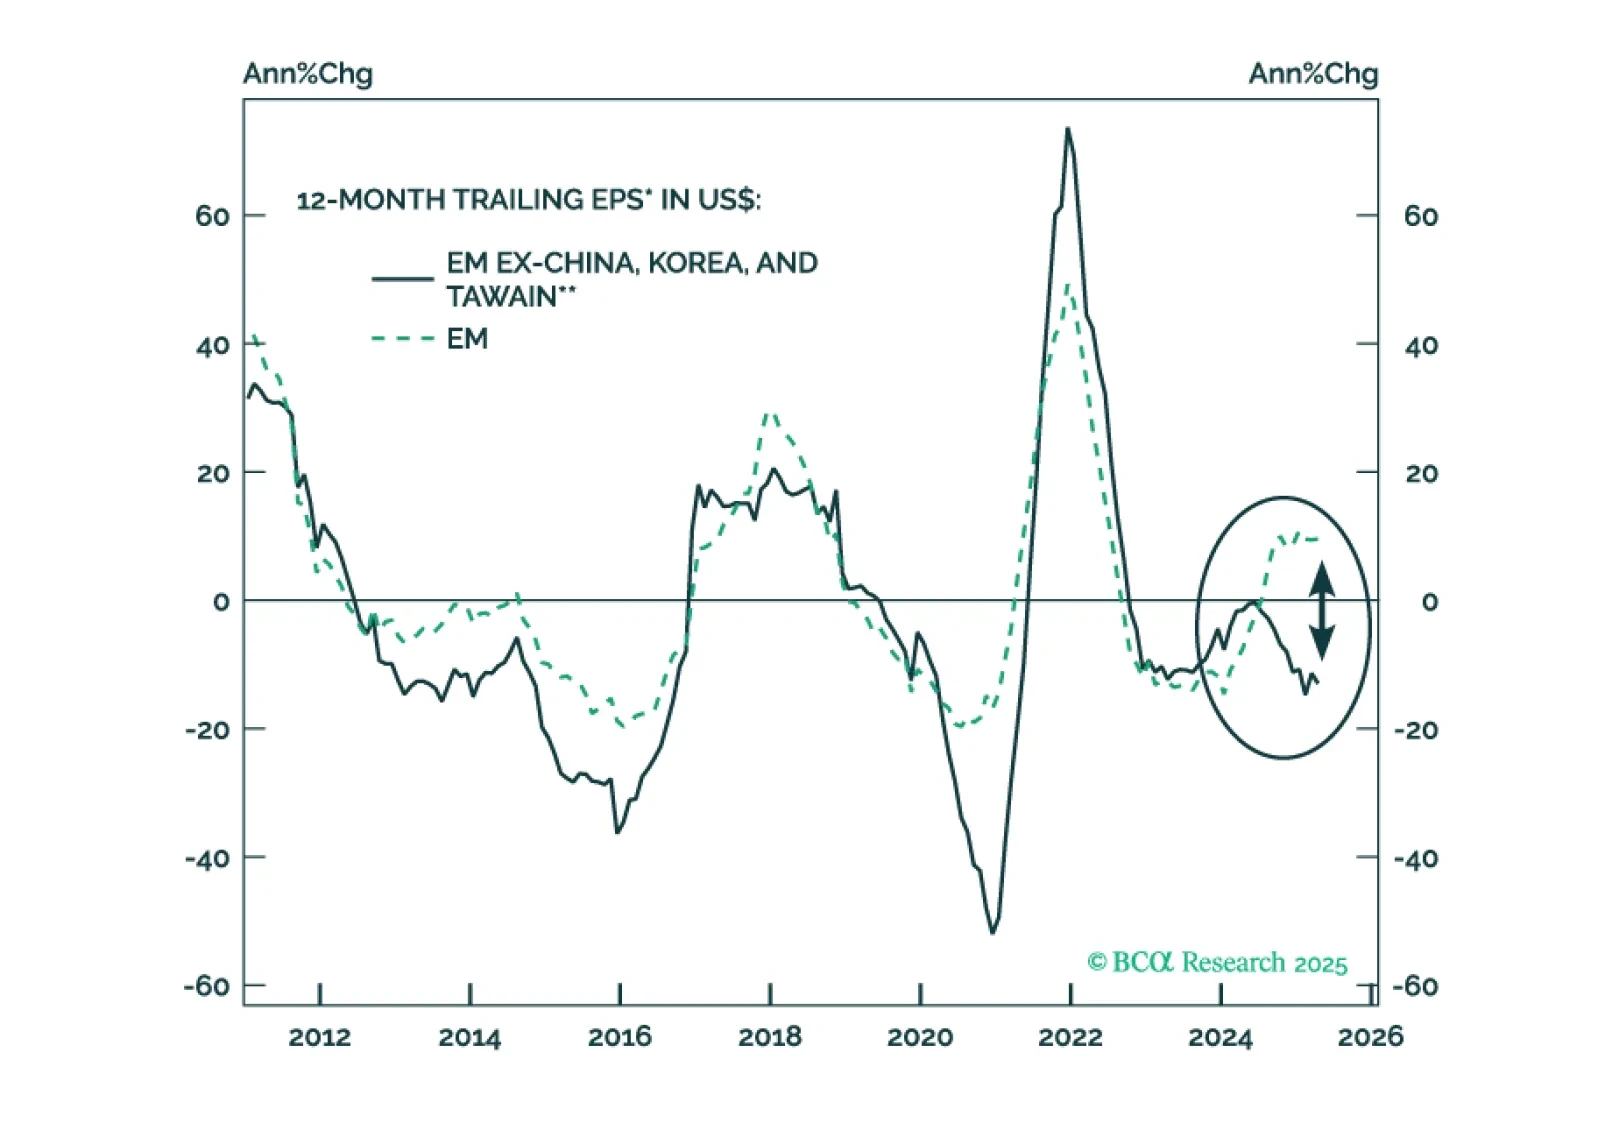
The EM EPS recovery has been narrow, solely driven by TMT stocks in China, Korea, and Taiwan. EM corporate profits are set to contract in the next six to nine months. Unlike in the past, US dollar weakness will be deflationary, not reflationary, for EM share prices.
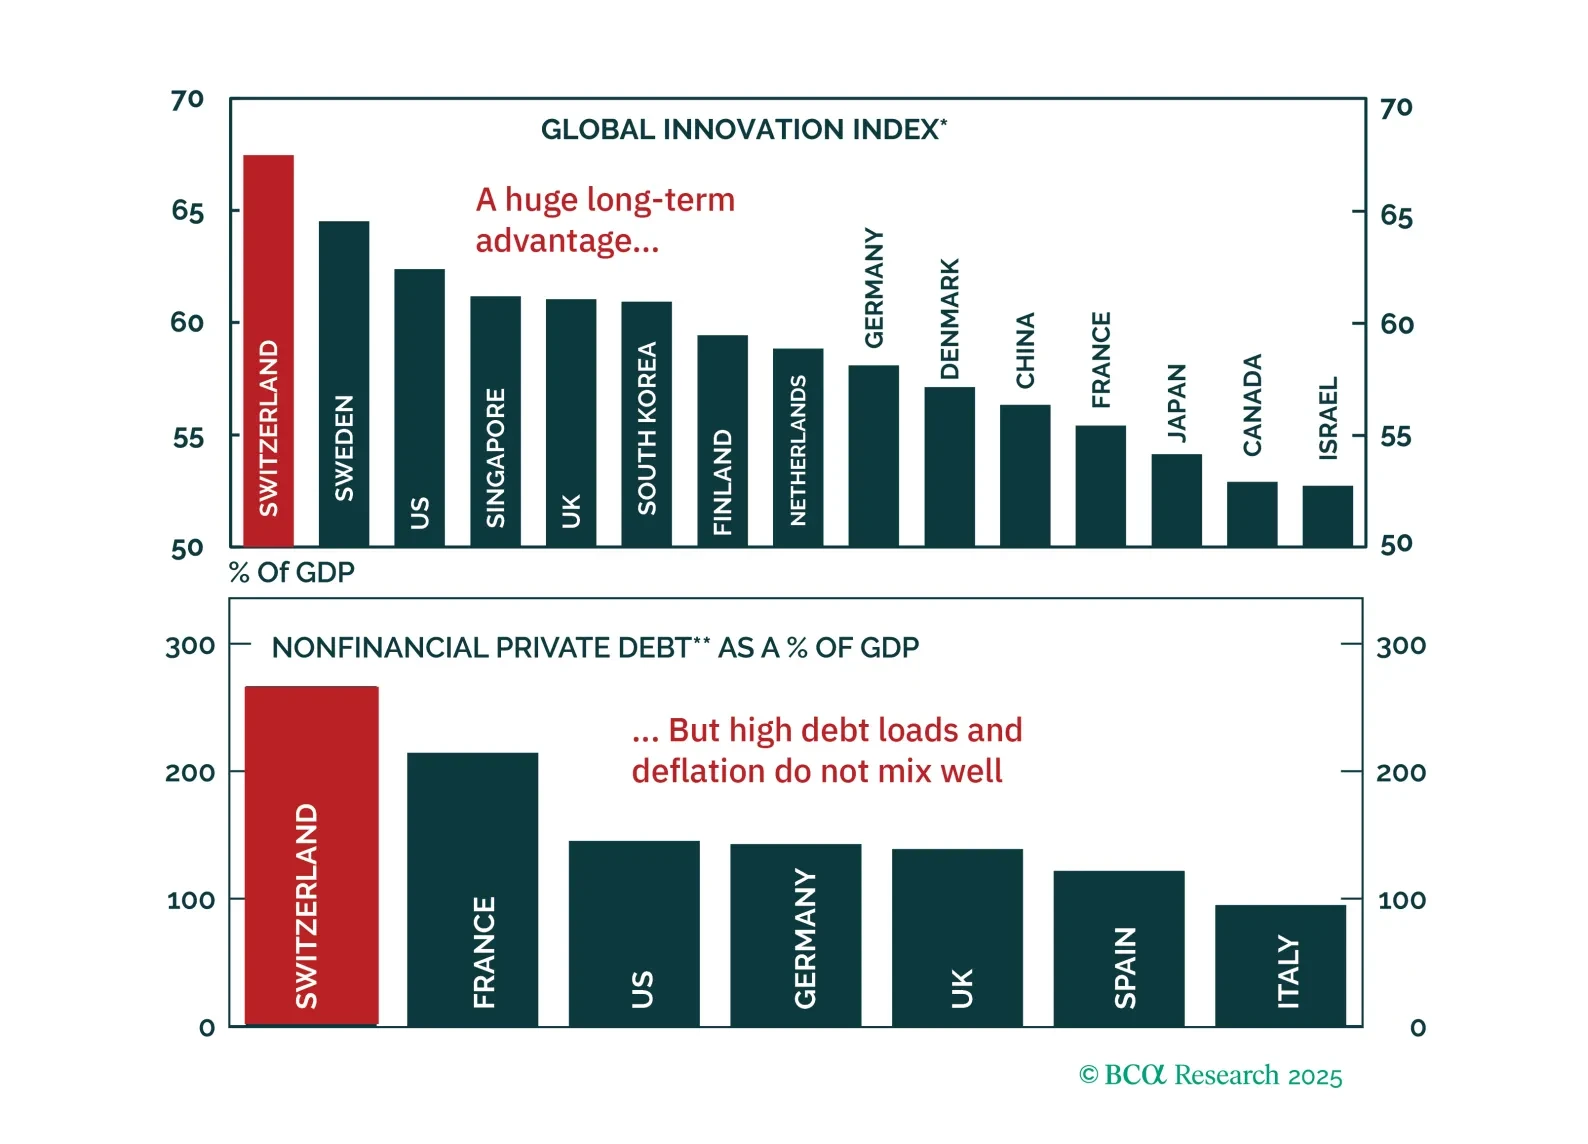
Special Report Switzerland looks pristine, but the near-term risks are mounting. Deflation pressures, overvalued assets, and a highly exposed export sector leave the economy vulnerable to a slowdown. This report explores why the SNB will ease more than markets expect, and how to position across CHF, equities, and bonds.
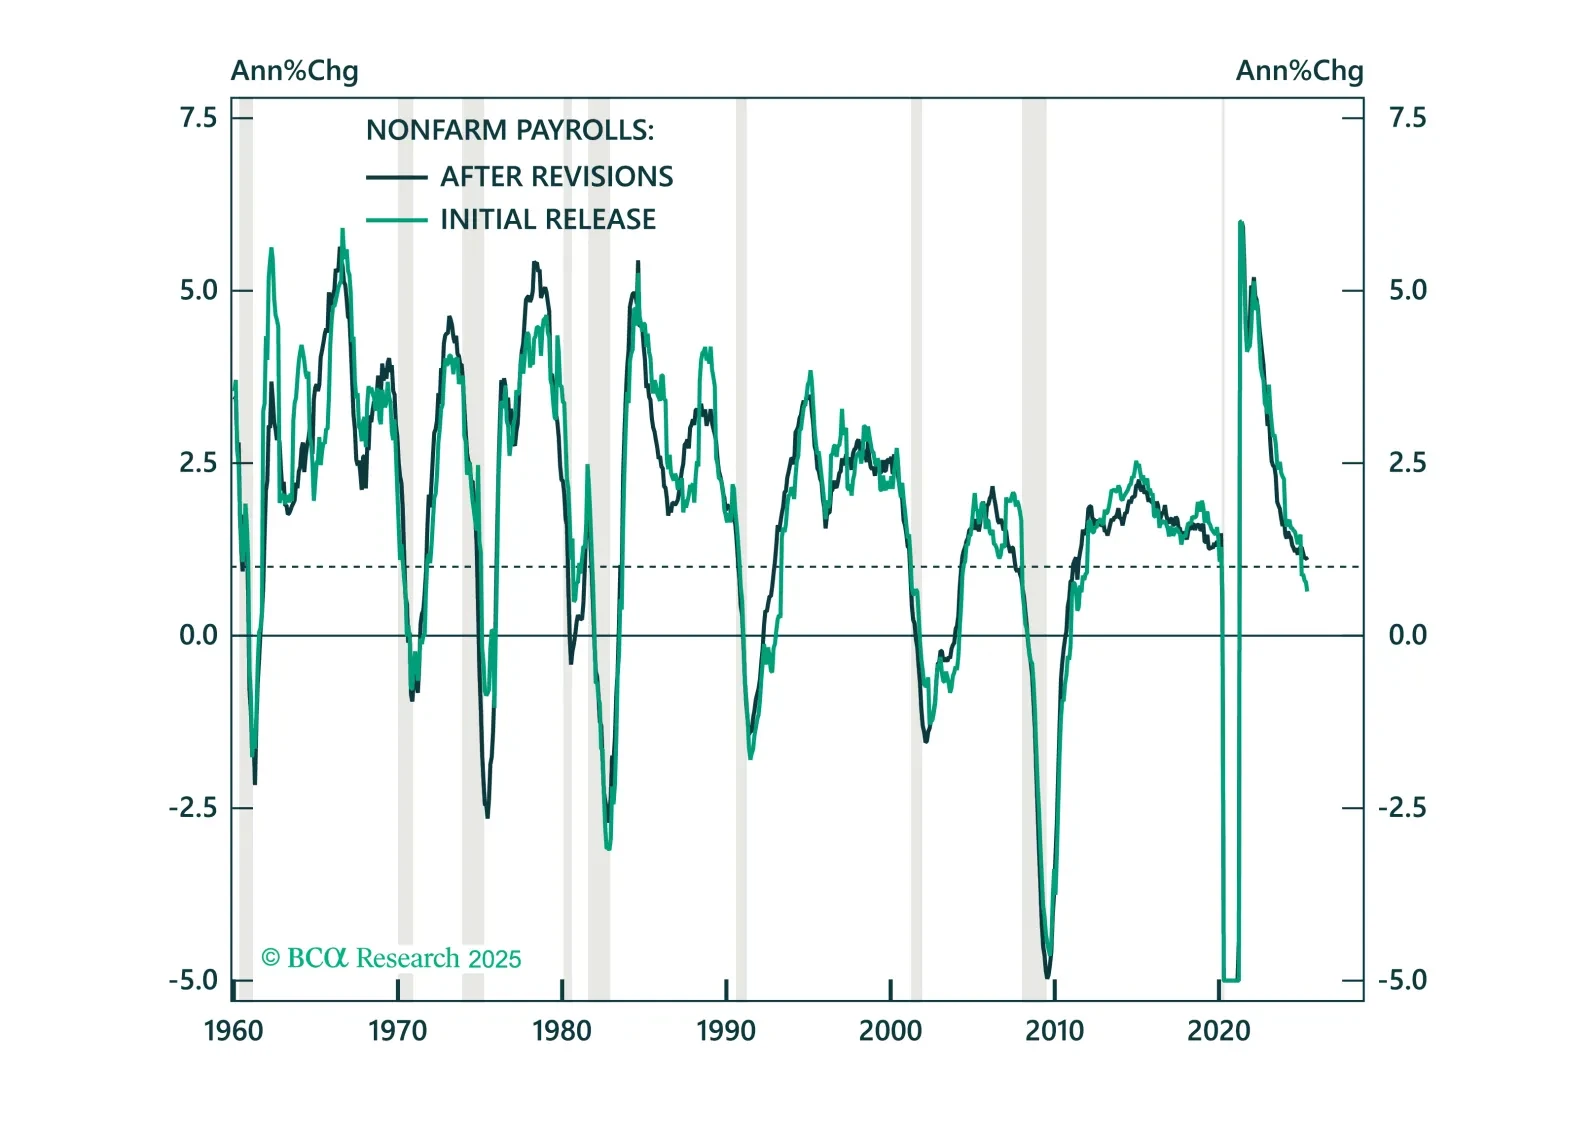
Following a rapid-fire review of issues related to household balance sheets, durable goods demand, the impact of tariffs, DOGE’s capacity to move the budget needle and the labor market’s ongoing cooling, we reiterate our defensive asset allocation recommendations.
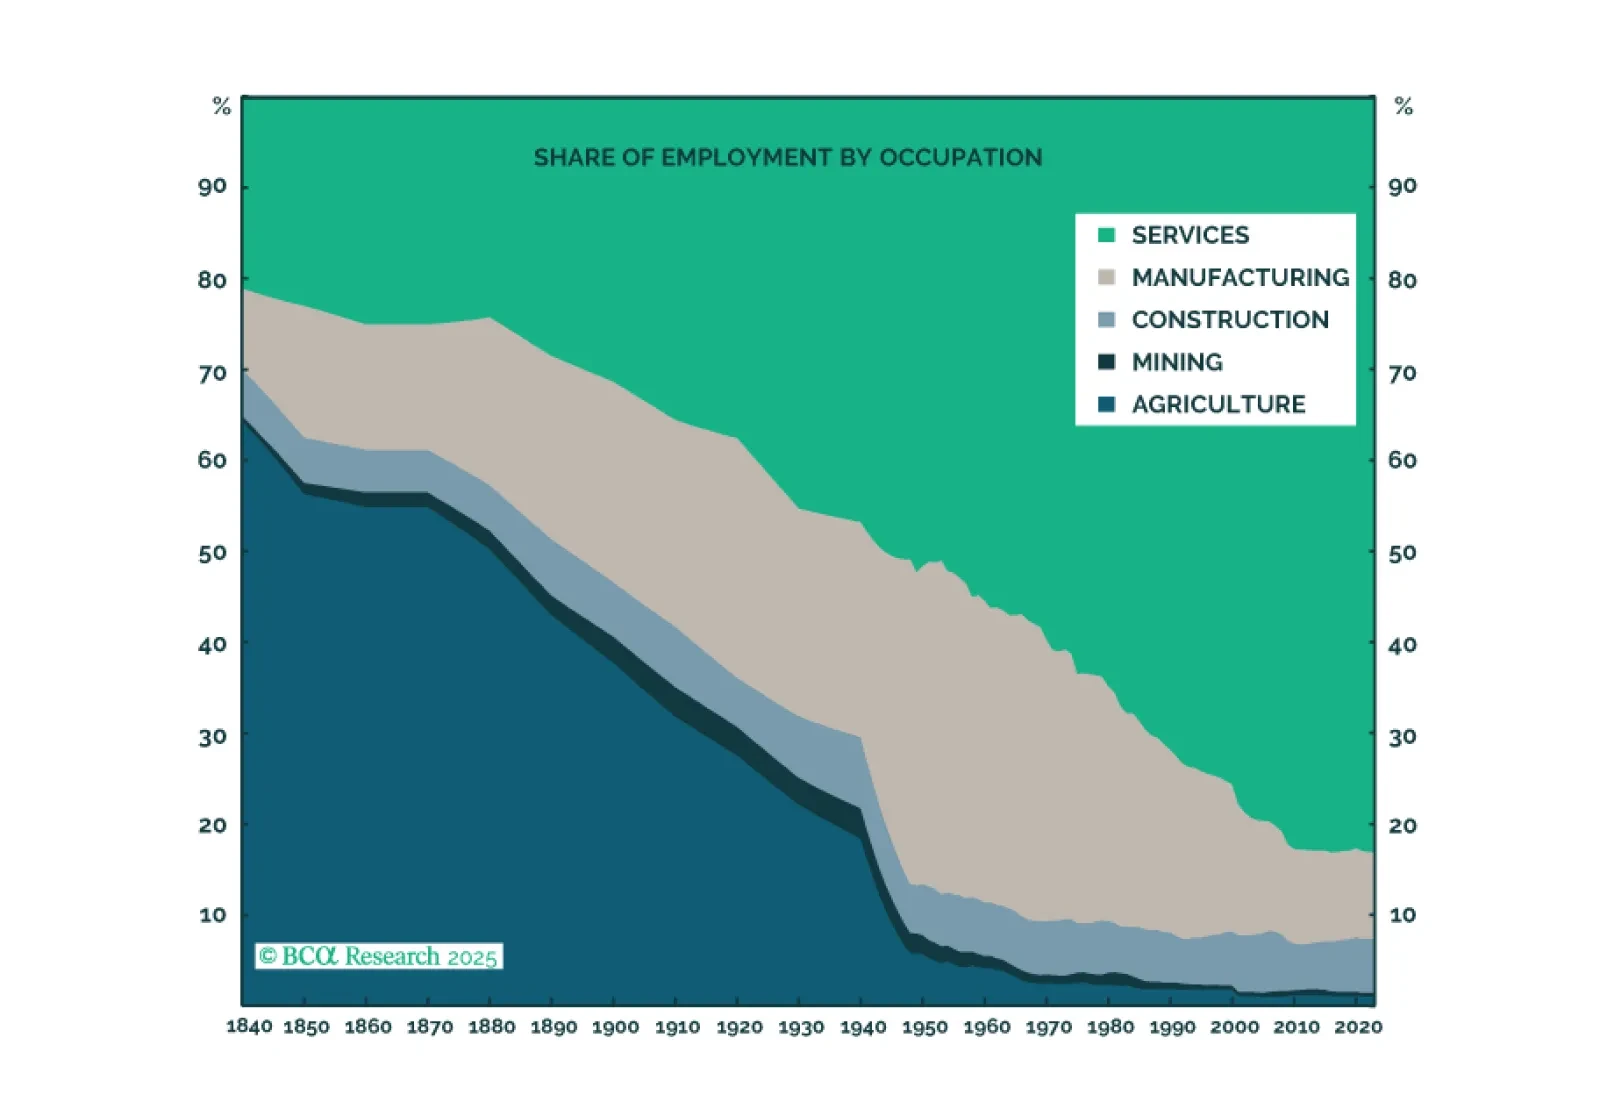
Special Report Provided that humanity can overcome the existential risks posed by AI, real incomes will rise. Although most workers will ultimately gain from the transition to an AI-dominated economy, the biggest winners will be those who control the land and the natural resources beneath it.
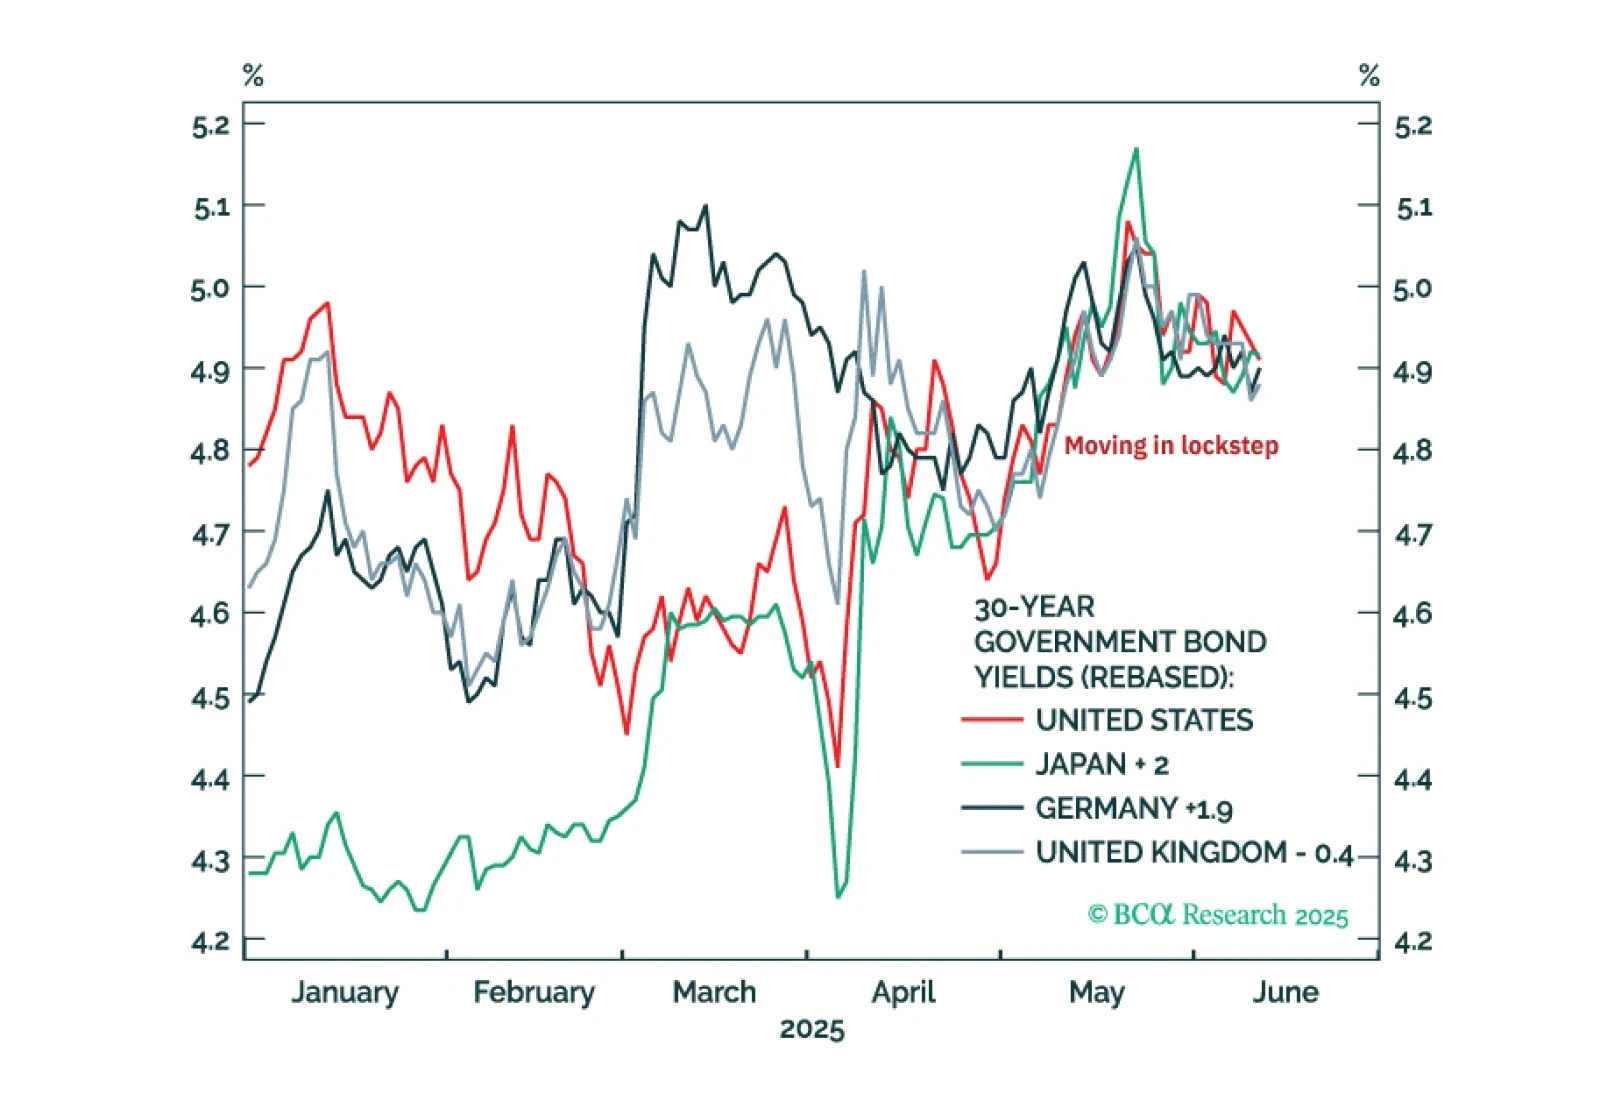
The perfectly synchronised moves in US, Japanese, German, and UK 30-year bond yields through the past two months are odd… and irrational. These irrational moves present compelling investment opportunities.
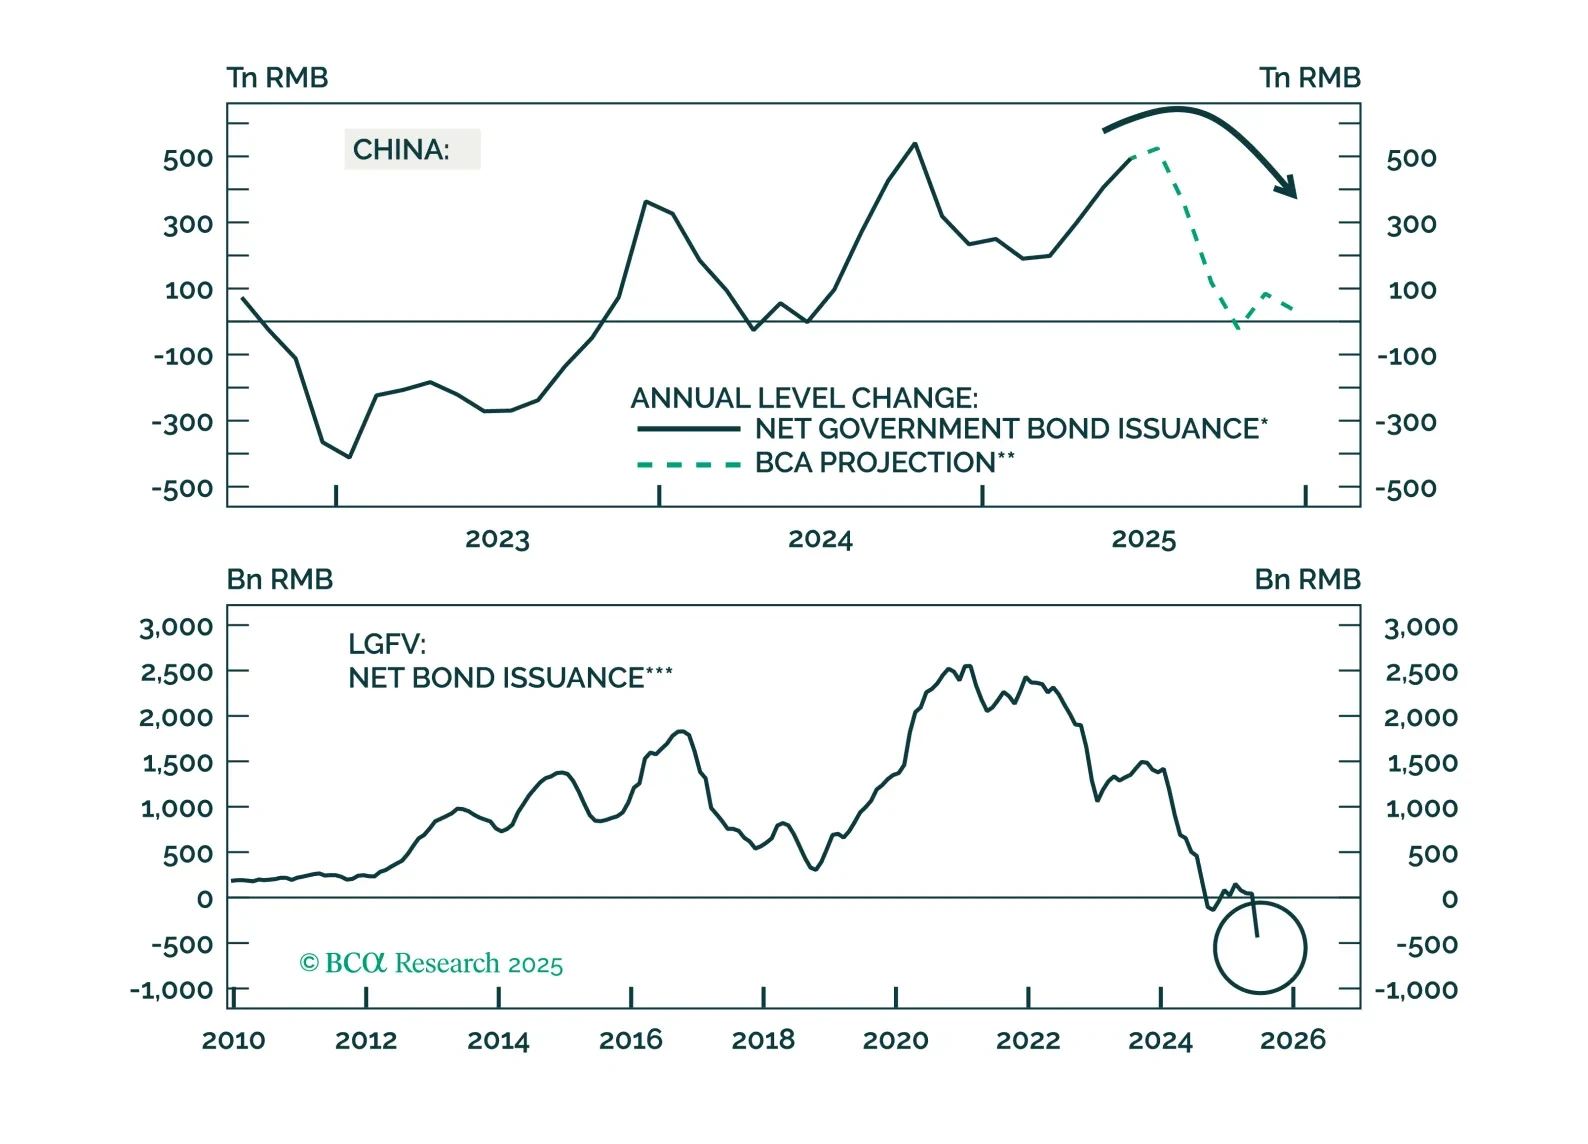
The London Sino-US trade talks offered hope of de-escalation, but Chinese equities remain under pressure from deflationary headwinds and lack a clear macro catalyst to trend higher.
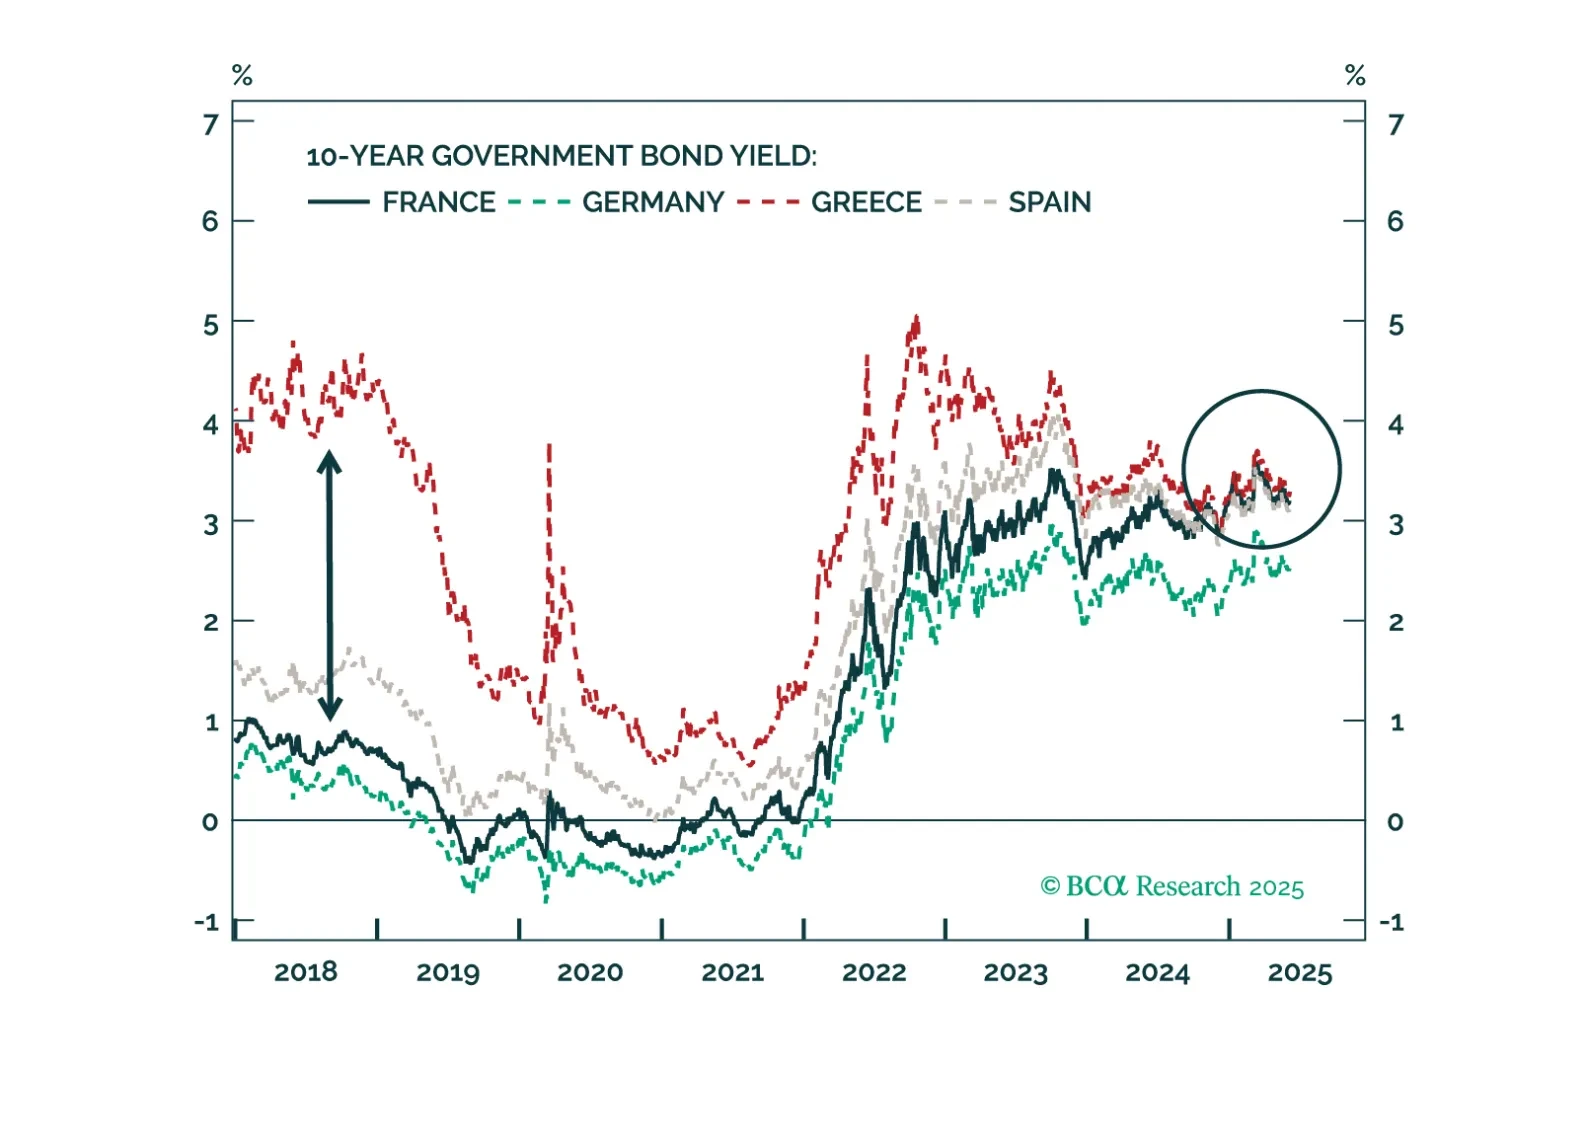
Special Report France’s political turmoil is far from over, and fiscal fears are growing. This is not a bond-friendly environment. In contrast, it is a good time to upgrade French equities. As the 2027 presidential race is about to begin in earnest, we make an early call on its outcome.