Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
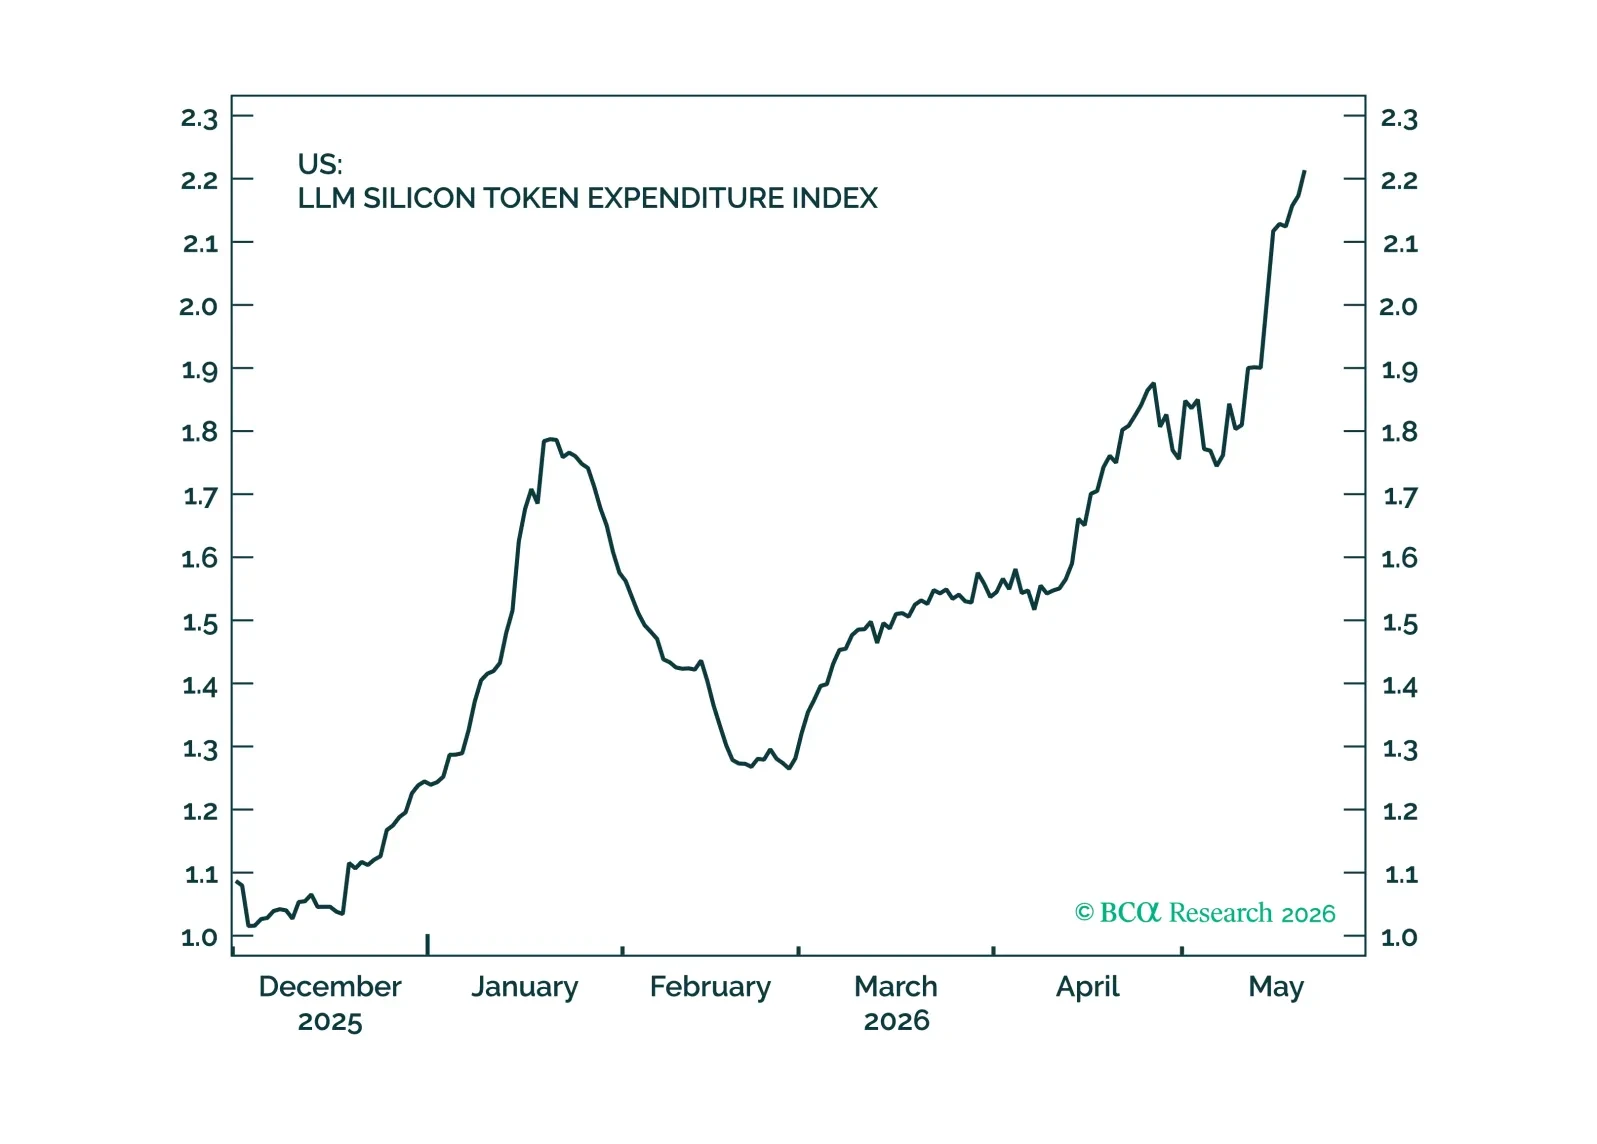
So far most of the value in the AI supply chain has been captured by hardware companies. However, as model providers shift to usage-based pricing, value will begin to accrue to models and applications. Communications Services and Software should benefit from this shift. This broadening of the AI story, along with solid economic momentum should keep the rally going for the rest of the year. Remain overweight equities. Downgrade Energy to Neutral. Buy Software.
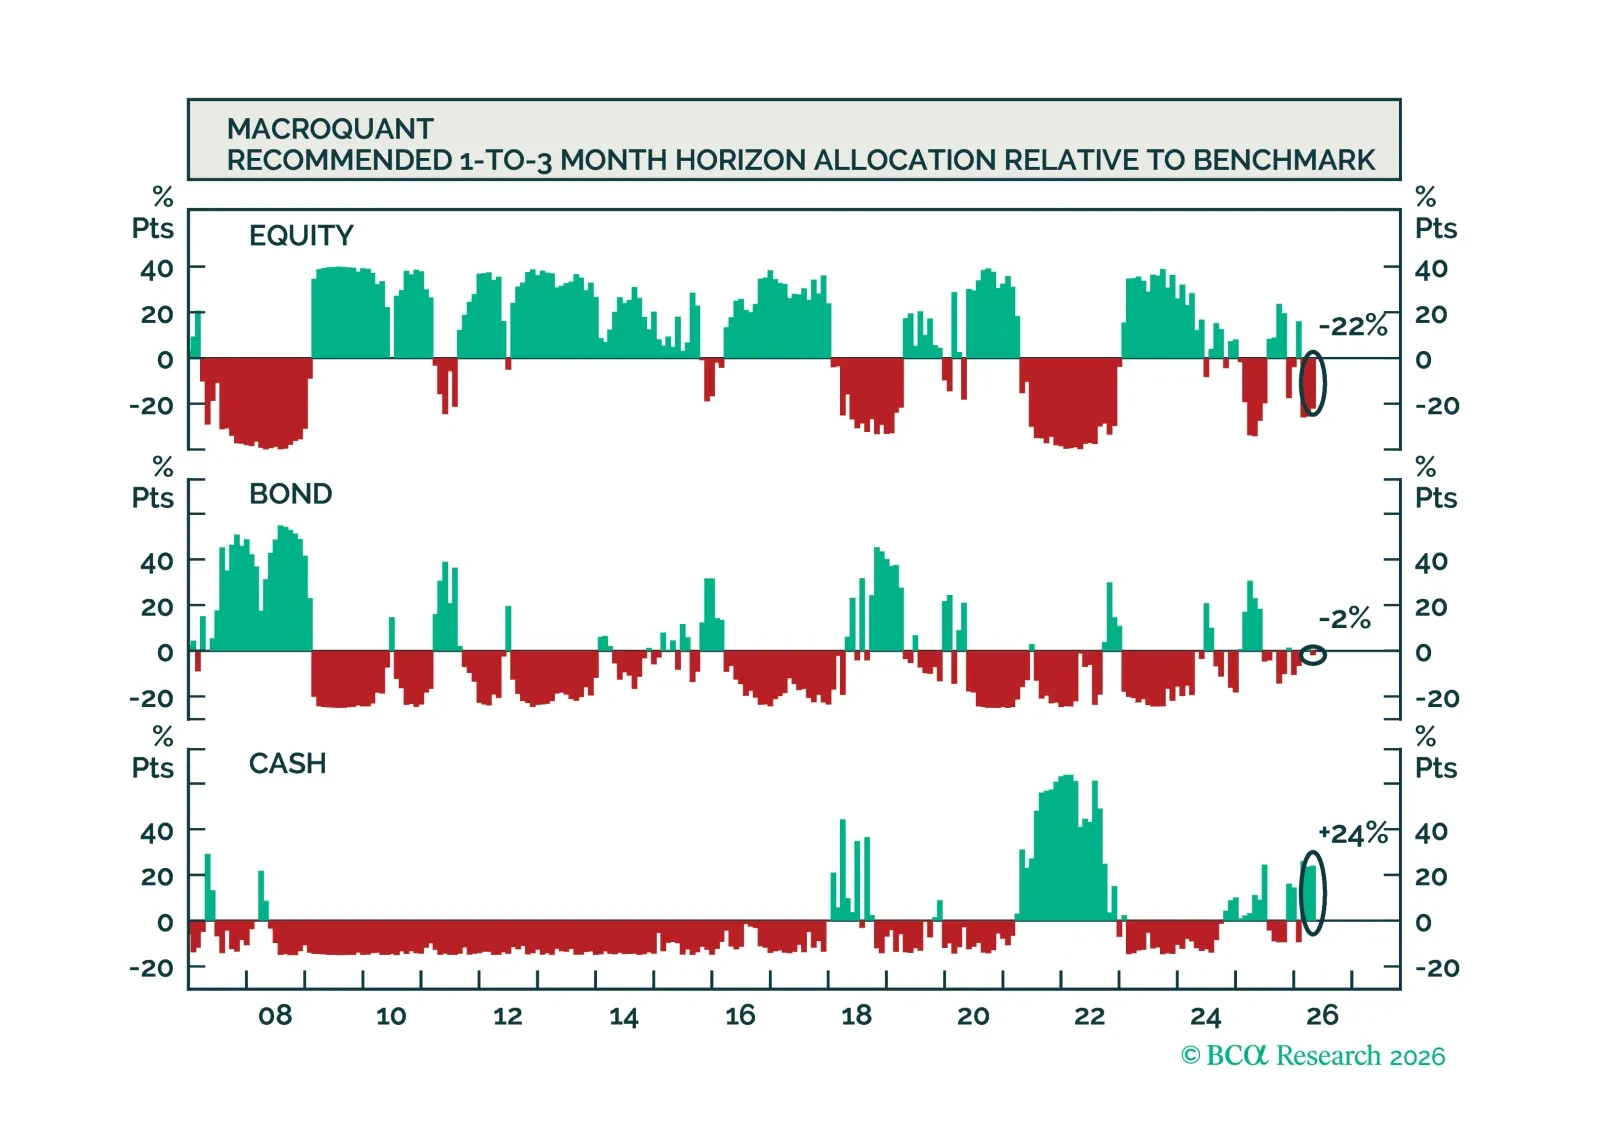
MacroQuant recommends a slight underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is very positive on the US dollar, downgrades gold to underweight, upgrades copper to overweight, and remains very bullish on oil.
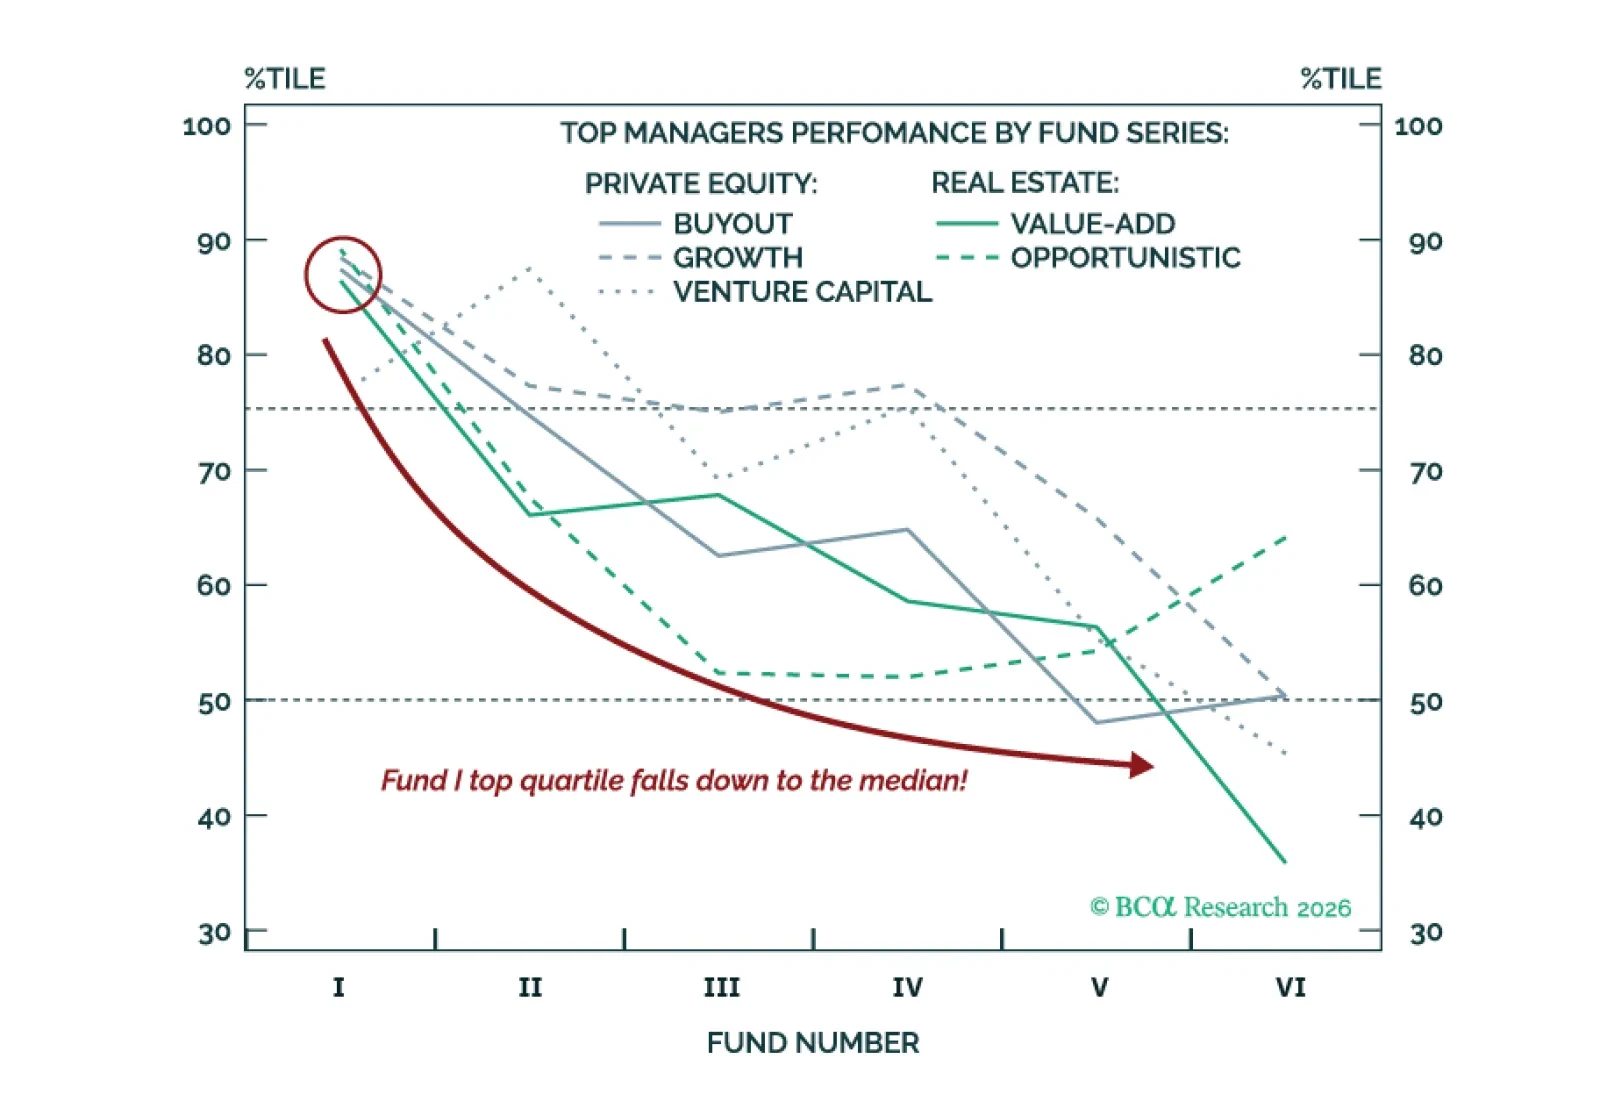
In Private Markets, yesterday’s winners often see outperformance fade. Top-quartile managers often regress toward the median as fund series mature. For investors evaluating the next Real Estate or Private Equity manager: Bias toward underweighting Funds V and beyond.

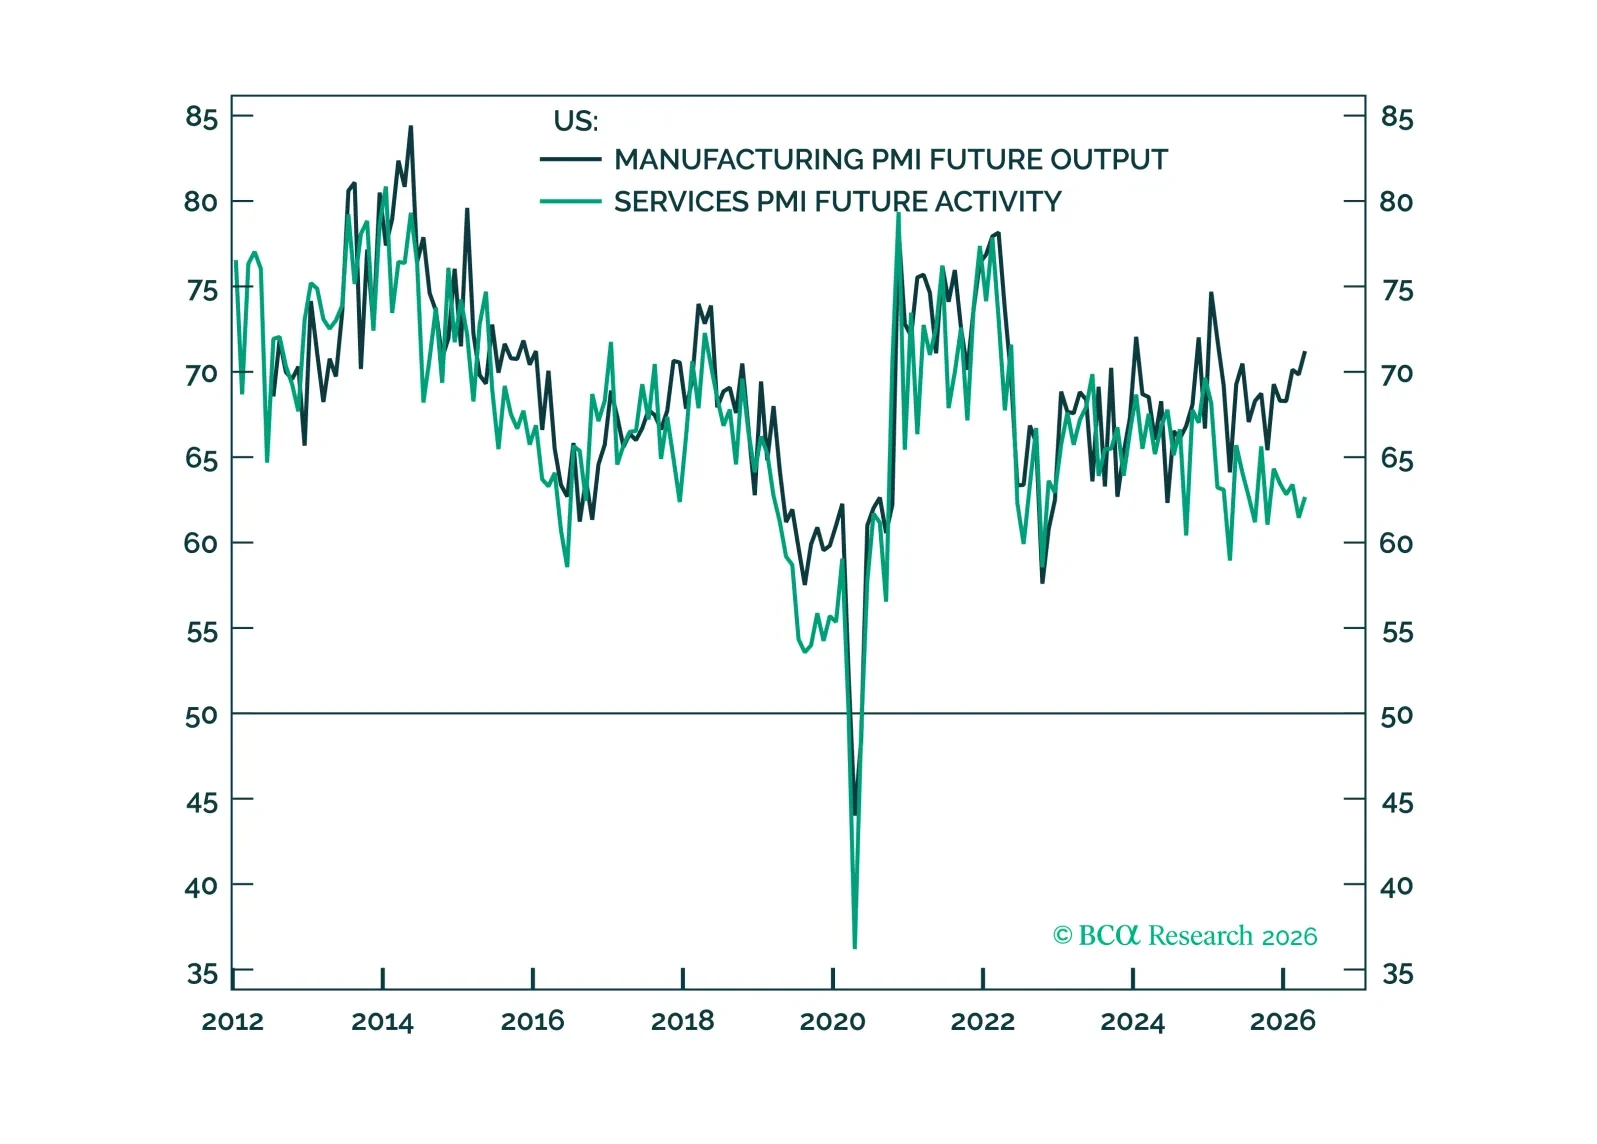
The Strait of Hormuz remains closed. Even if the Strait were to open tomorrow, global consumers will be squeezed for the rest of the year. However, AI capex is accelerating, and signs of ROI are emerging. This capex boom will keep the world from an economic downturn. Upgrade equities to overweight and downgrade cash to underweight. Upgrade the US and downgrade Europe and Australia. Upgrade Communication Services.
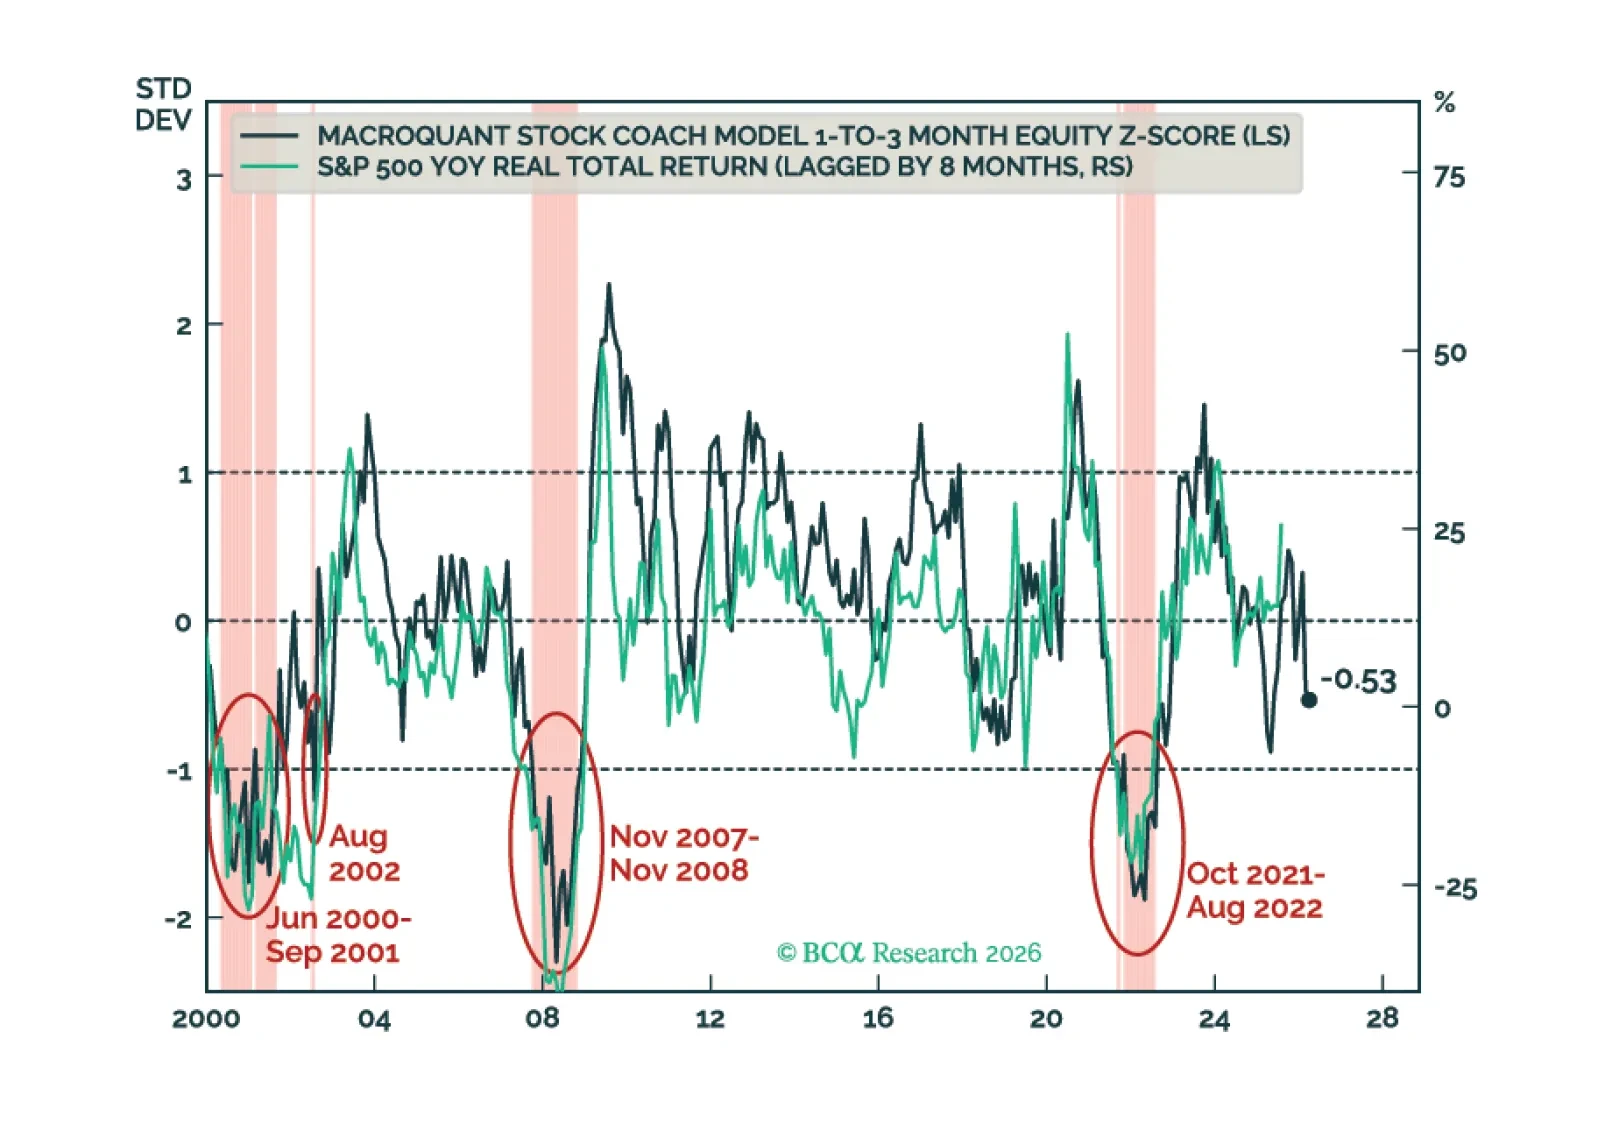
MacroQuant recommends an underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is neutral-to-slightly positive on the US dollar, remains neutral on gold, upgrades copper to neutral, and is very bullish on oil.
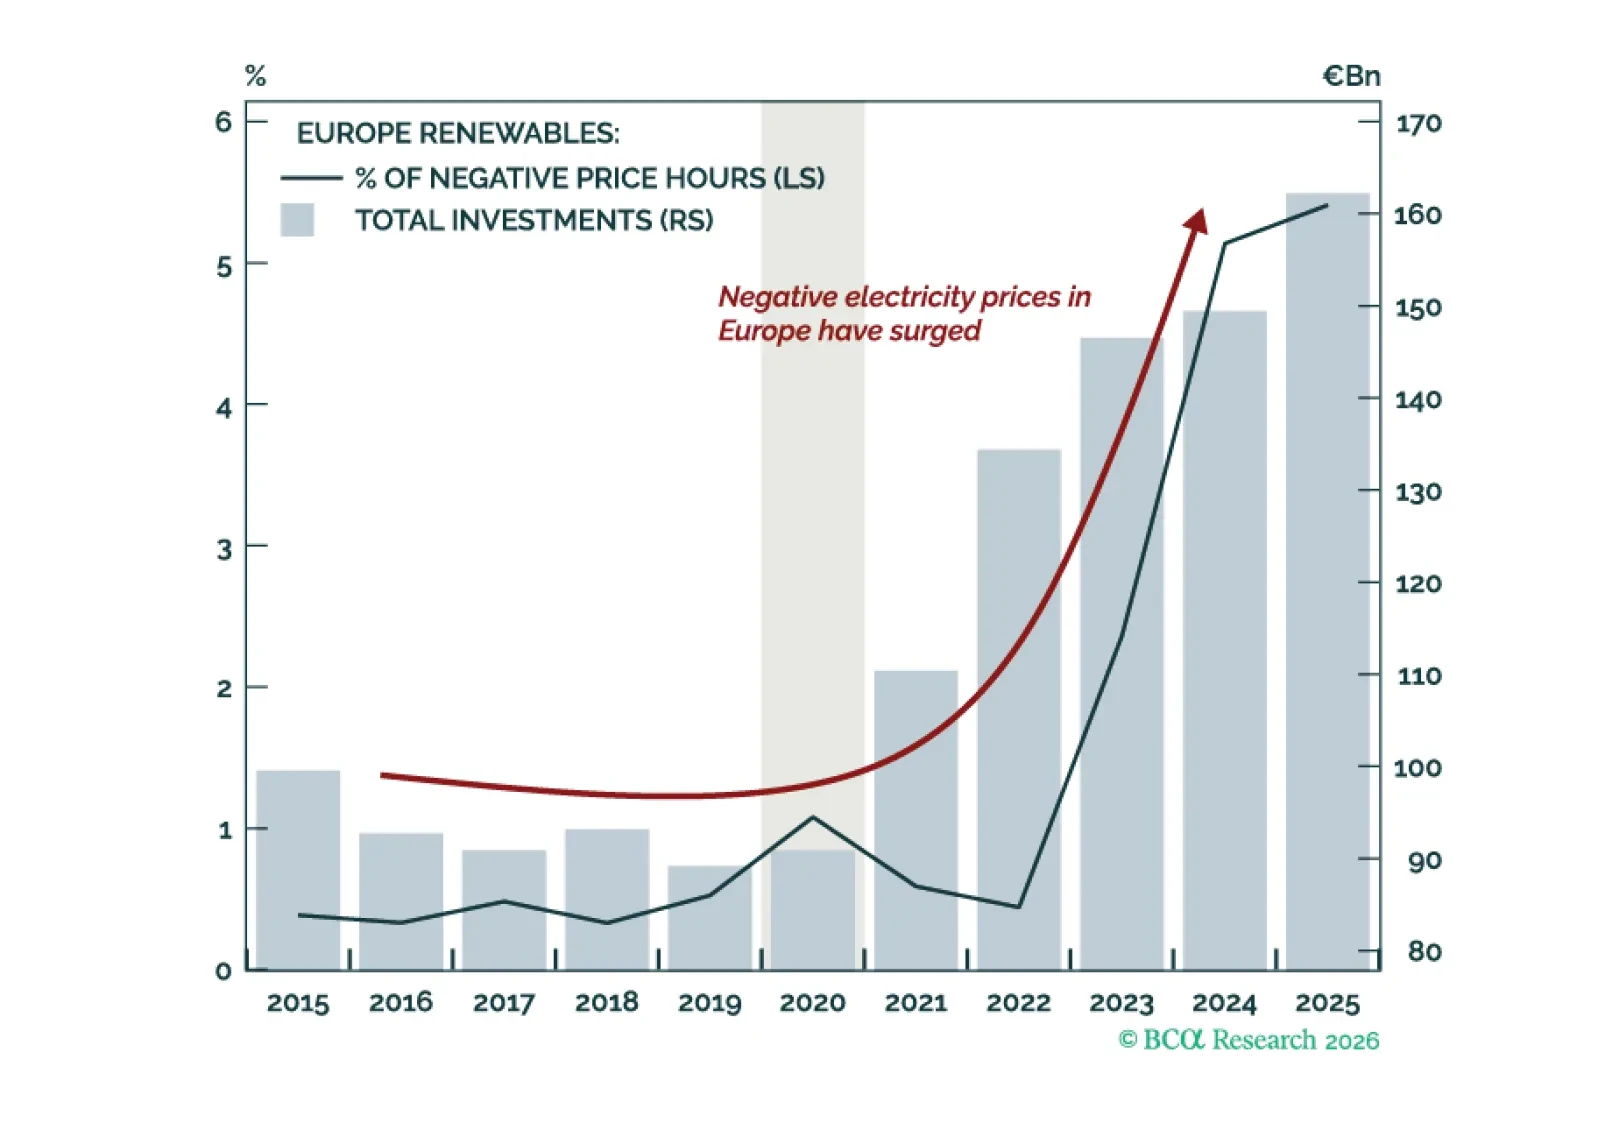
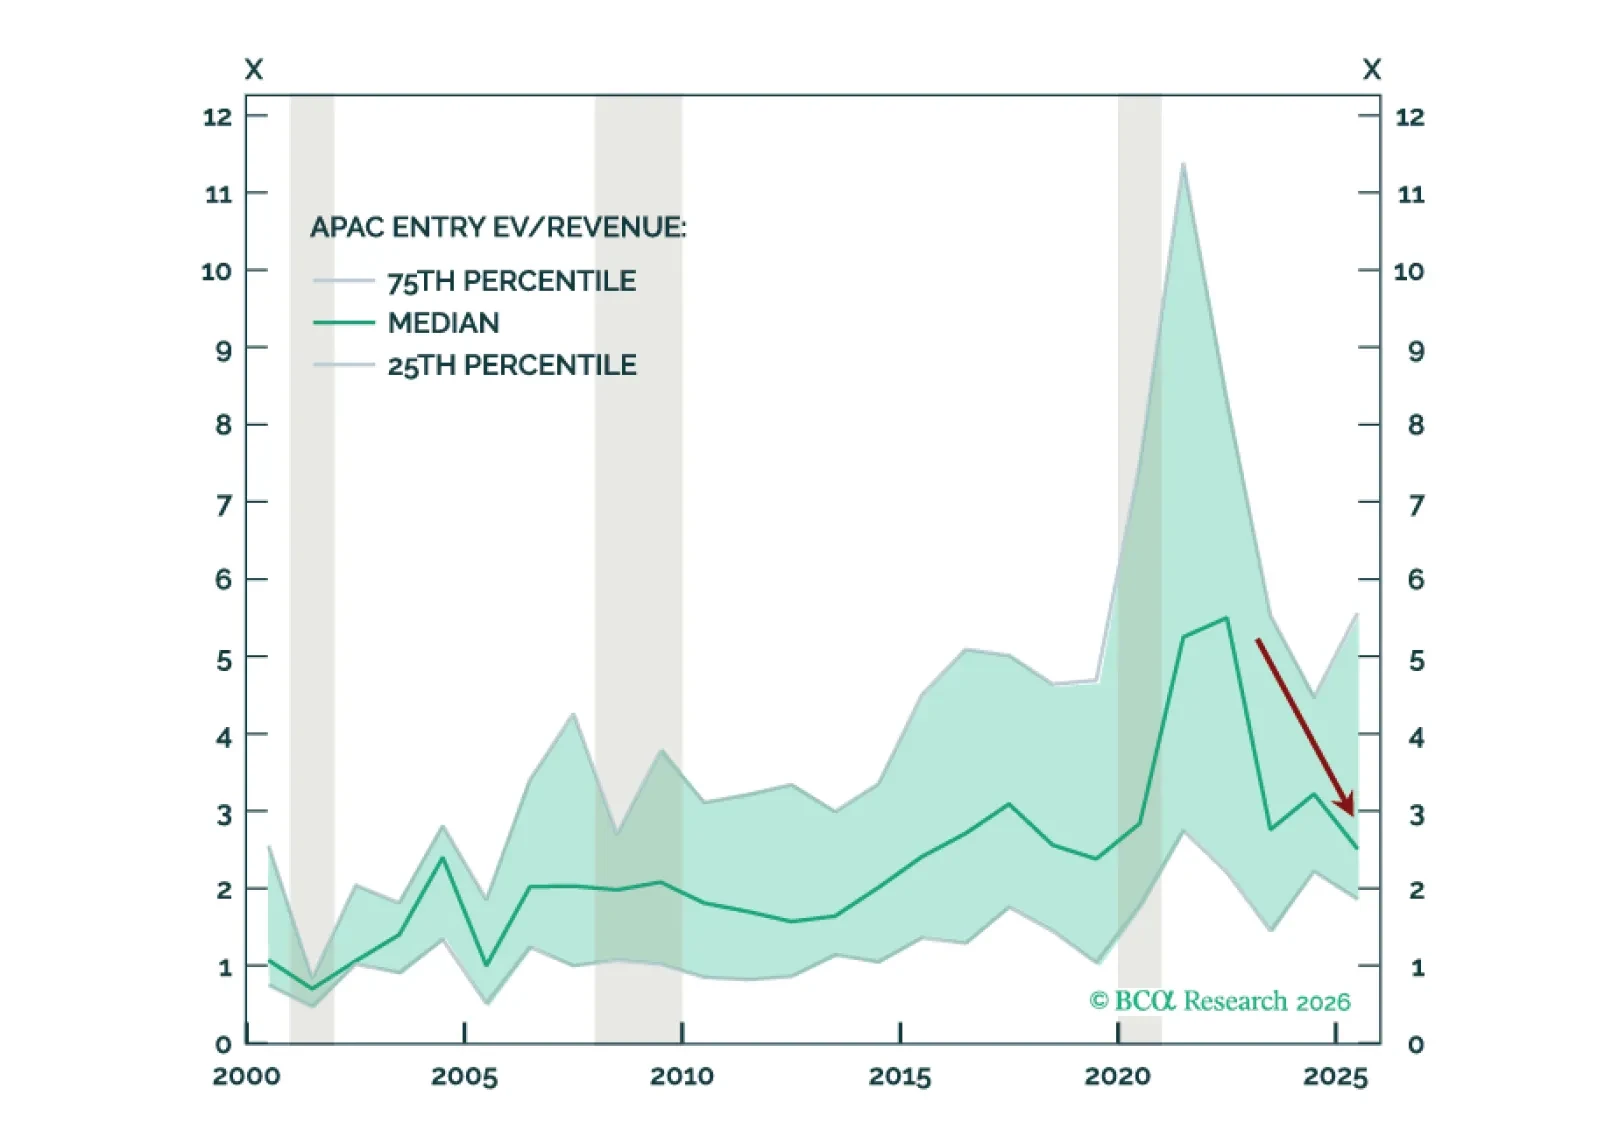
We remain overweight APAC in both Private Equity and Venture Capital, recognizing the region and its opportunities have evolved meaningfully. Buyouts are growing faster than many realize, driven by Japan, while a deeper reset in fundamentals versus global markets supports stronger upside potential.