 Portfolio
| Tactical Asset Allocation
Where to overweight and underweight over the next 6 to 12 months, across public and private asset classes.
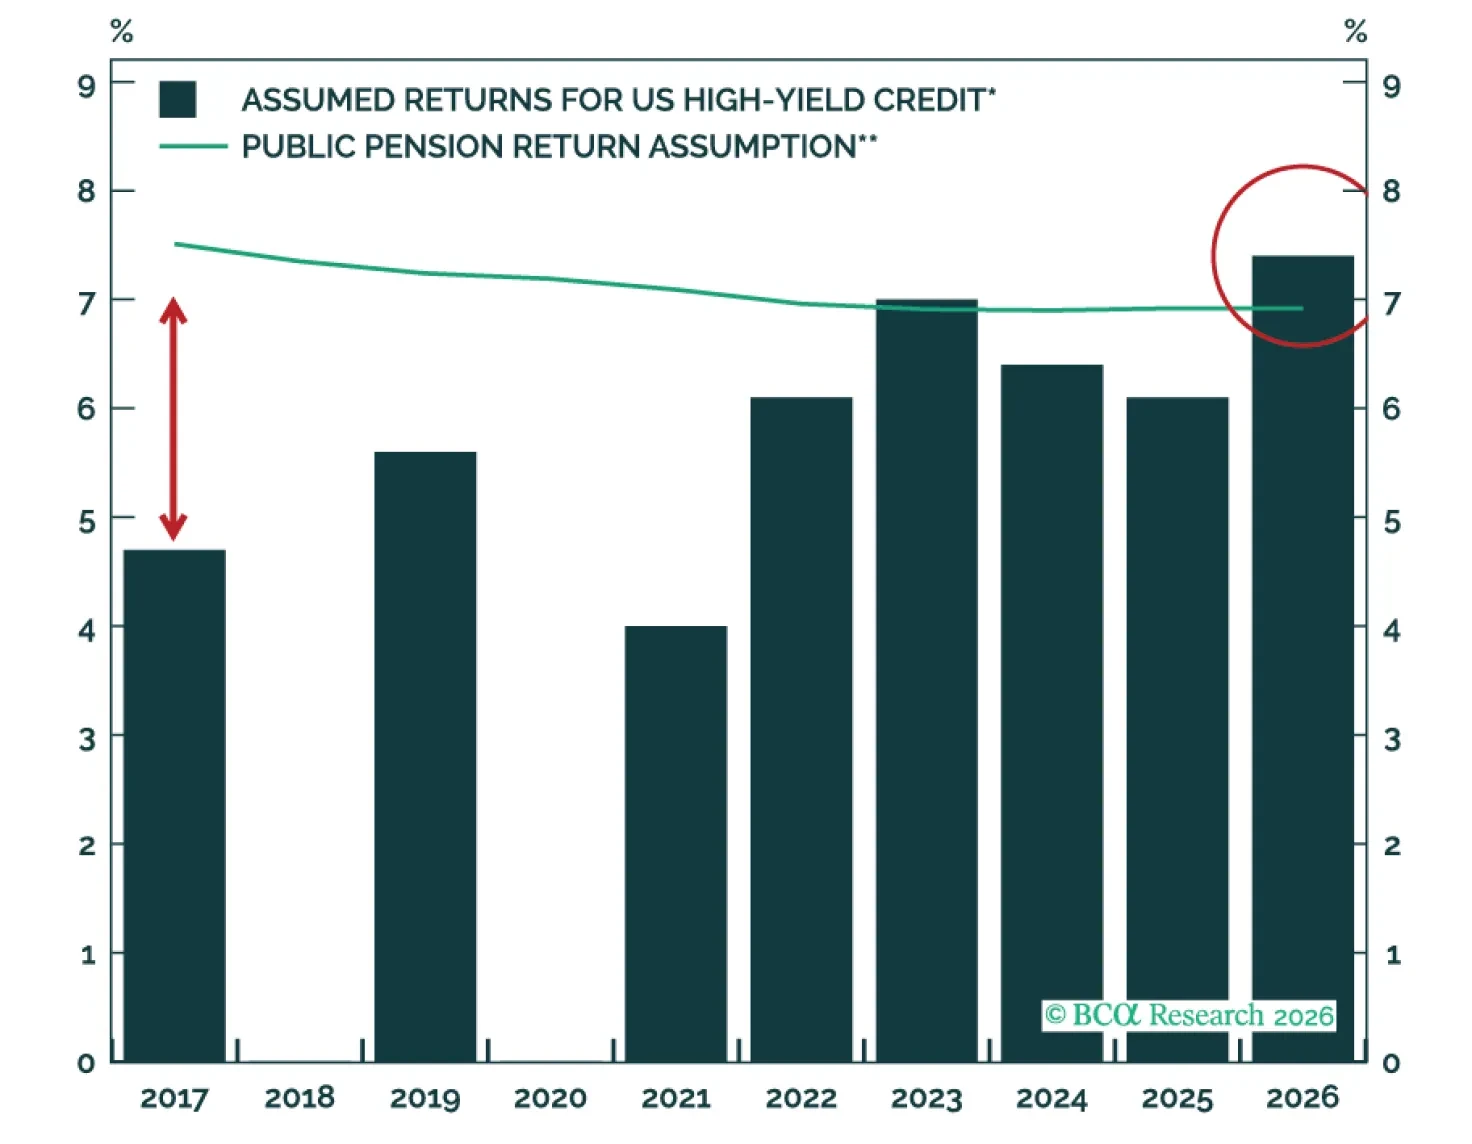
Higher rates have changed the opportunity set. Overweight High-Yield Credit, both within asset allocation and versus Private Credit. Investors are no longer picking up pennies in front of a steamroller.
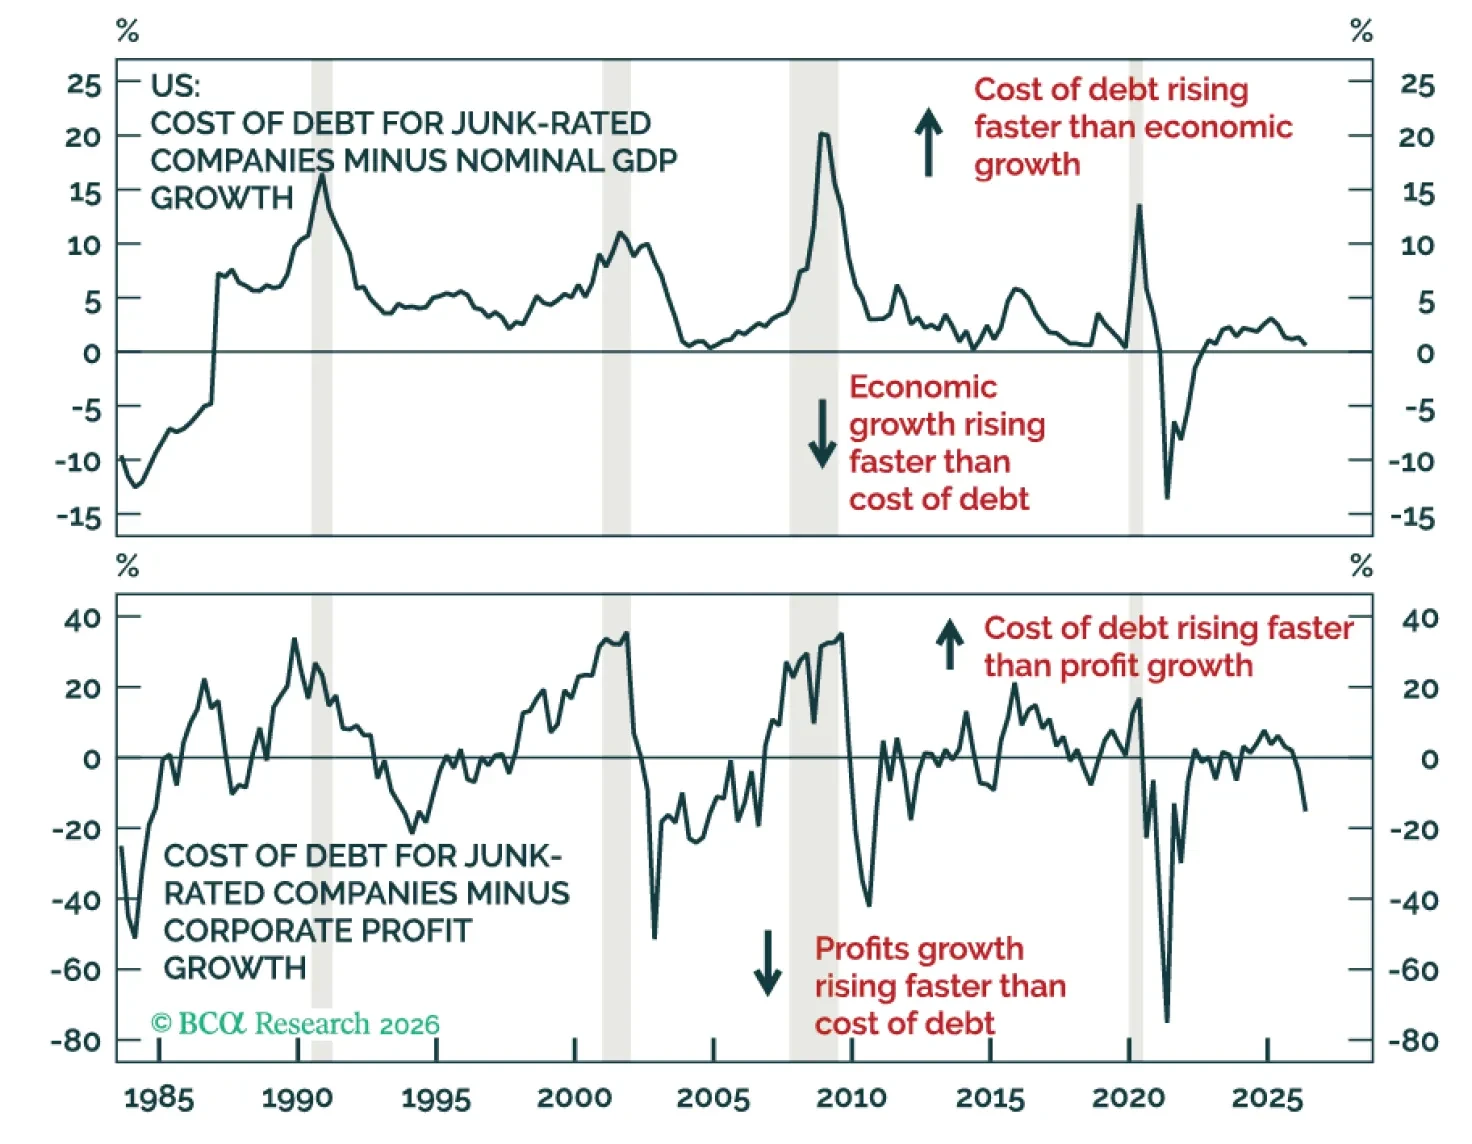
Investors overestimate the threat current interest rate levels pose to both equities and the economy. Despite a rising long end, the gap between high-yield borrowing costs and both nominal growth and corporate profits is at five-year lows and falling. Remain overweight equities. Within Fixed Income, Upgrade High Yield and Downgrade Government Bonds and EM Debt. Downgrade Chinese Equities to Neutral.
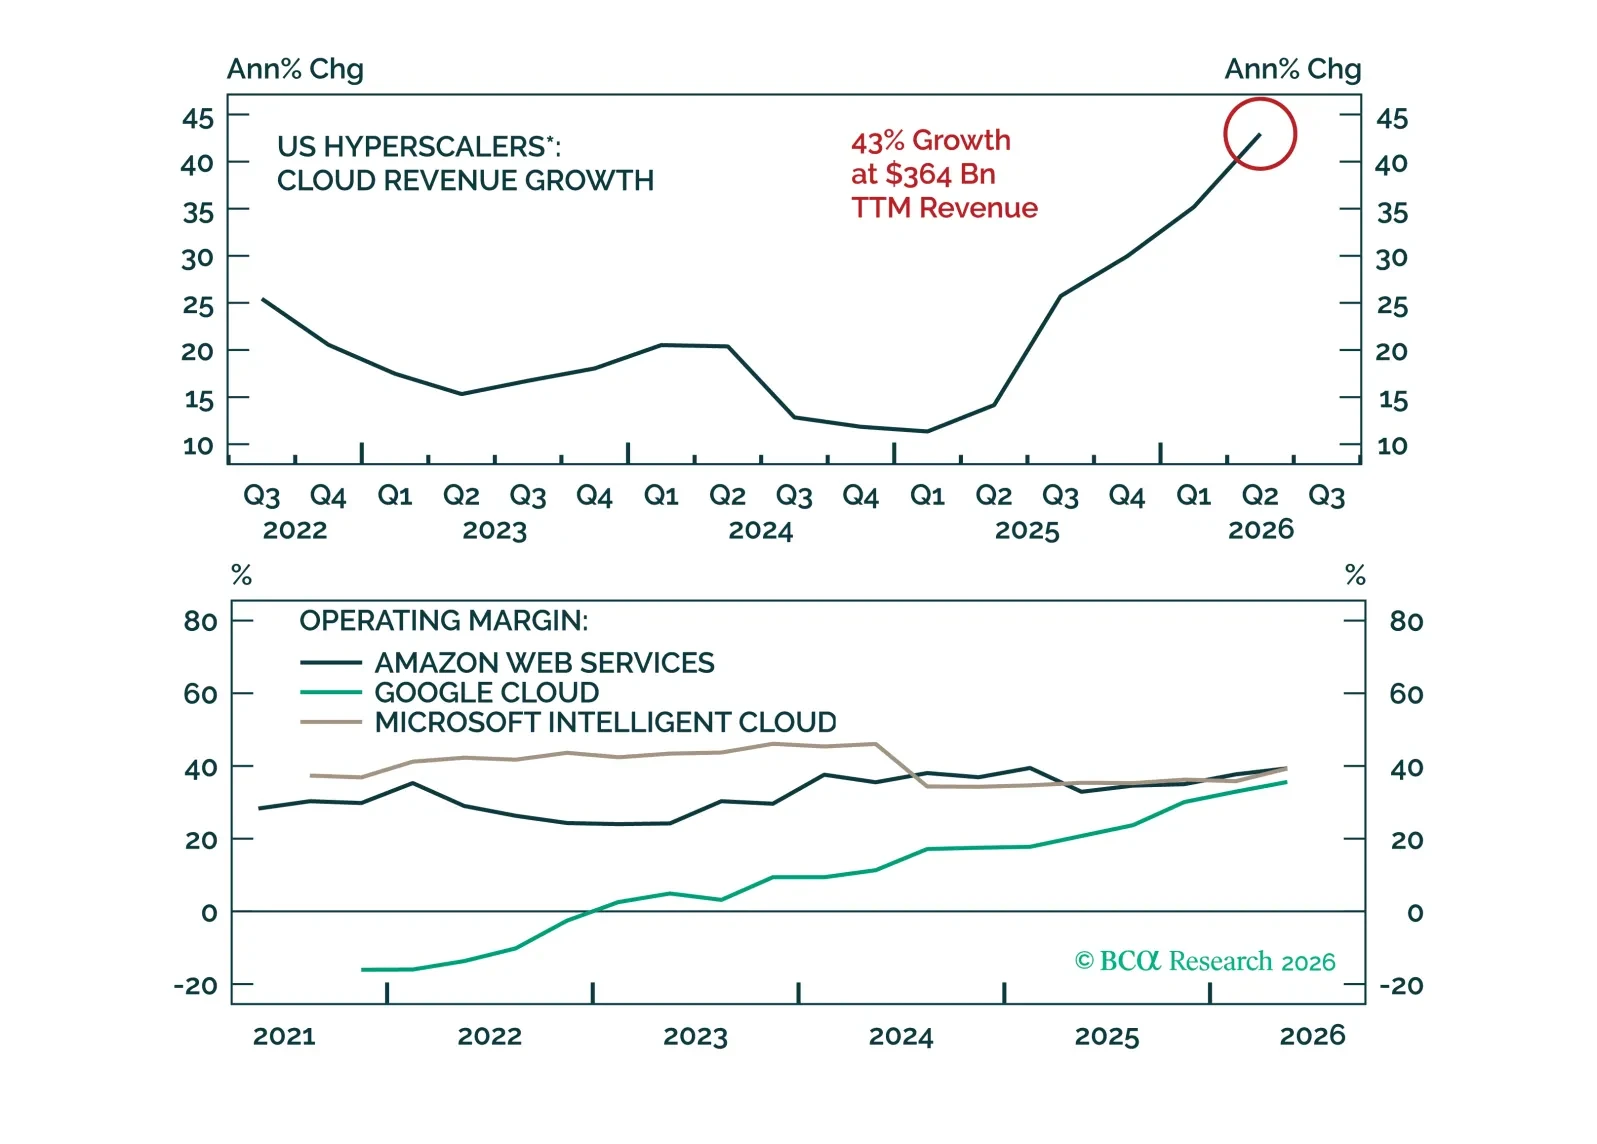
Investors have remained very skeptical about the profitability of the AI buildout. However, this earnings season the ROI has begun to show up, giving the bull market a green light to go higher. Remain overweight equities and continue to favor the hyperscalers.

Beginning with this Quarterly report, The Global Asset Allocation and Private Markets teams are combining our quarterly outlooks into a single, unified framework, reflecting a more integrated approach to portfolio construction. In this joint outlook we upgrade Private Equity to overweight. Sentiment has soured, LPs are starved of distributions, flows have collapsed, valuations are trending lower, Secondaries are outperforming Primaries, and GP stocks are experiencing their worst underperformance on record. All signs of a durable bottom.
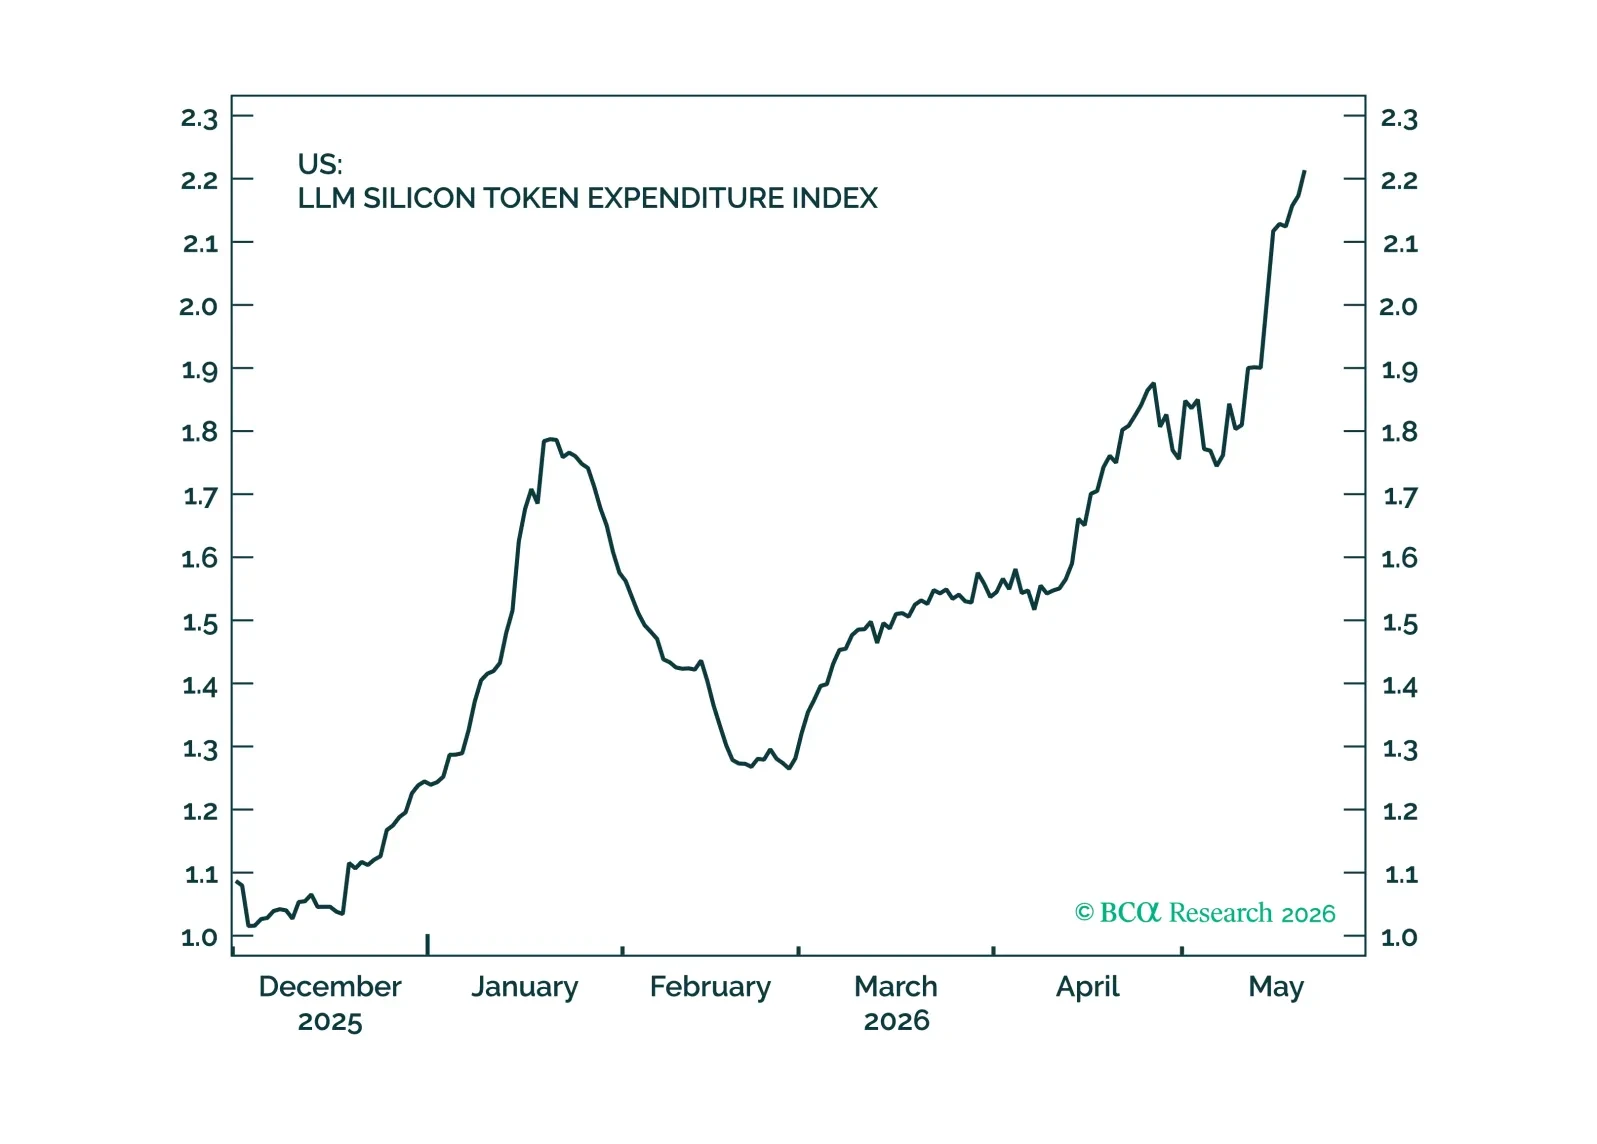
So far most of the value in the AI supply chain has been captured by hardware companies. However, as model providers shift to usage-based pricing, value will begin to accrue to models and applications. Communications Services and Software should benefit from this shift. This broadening of the AI story, along with solid economic momentum should keep the rally going for the rest of the year. Remain overweight equities. Downgrade Energy to Neutral. Buy Software.
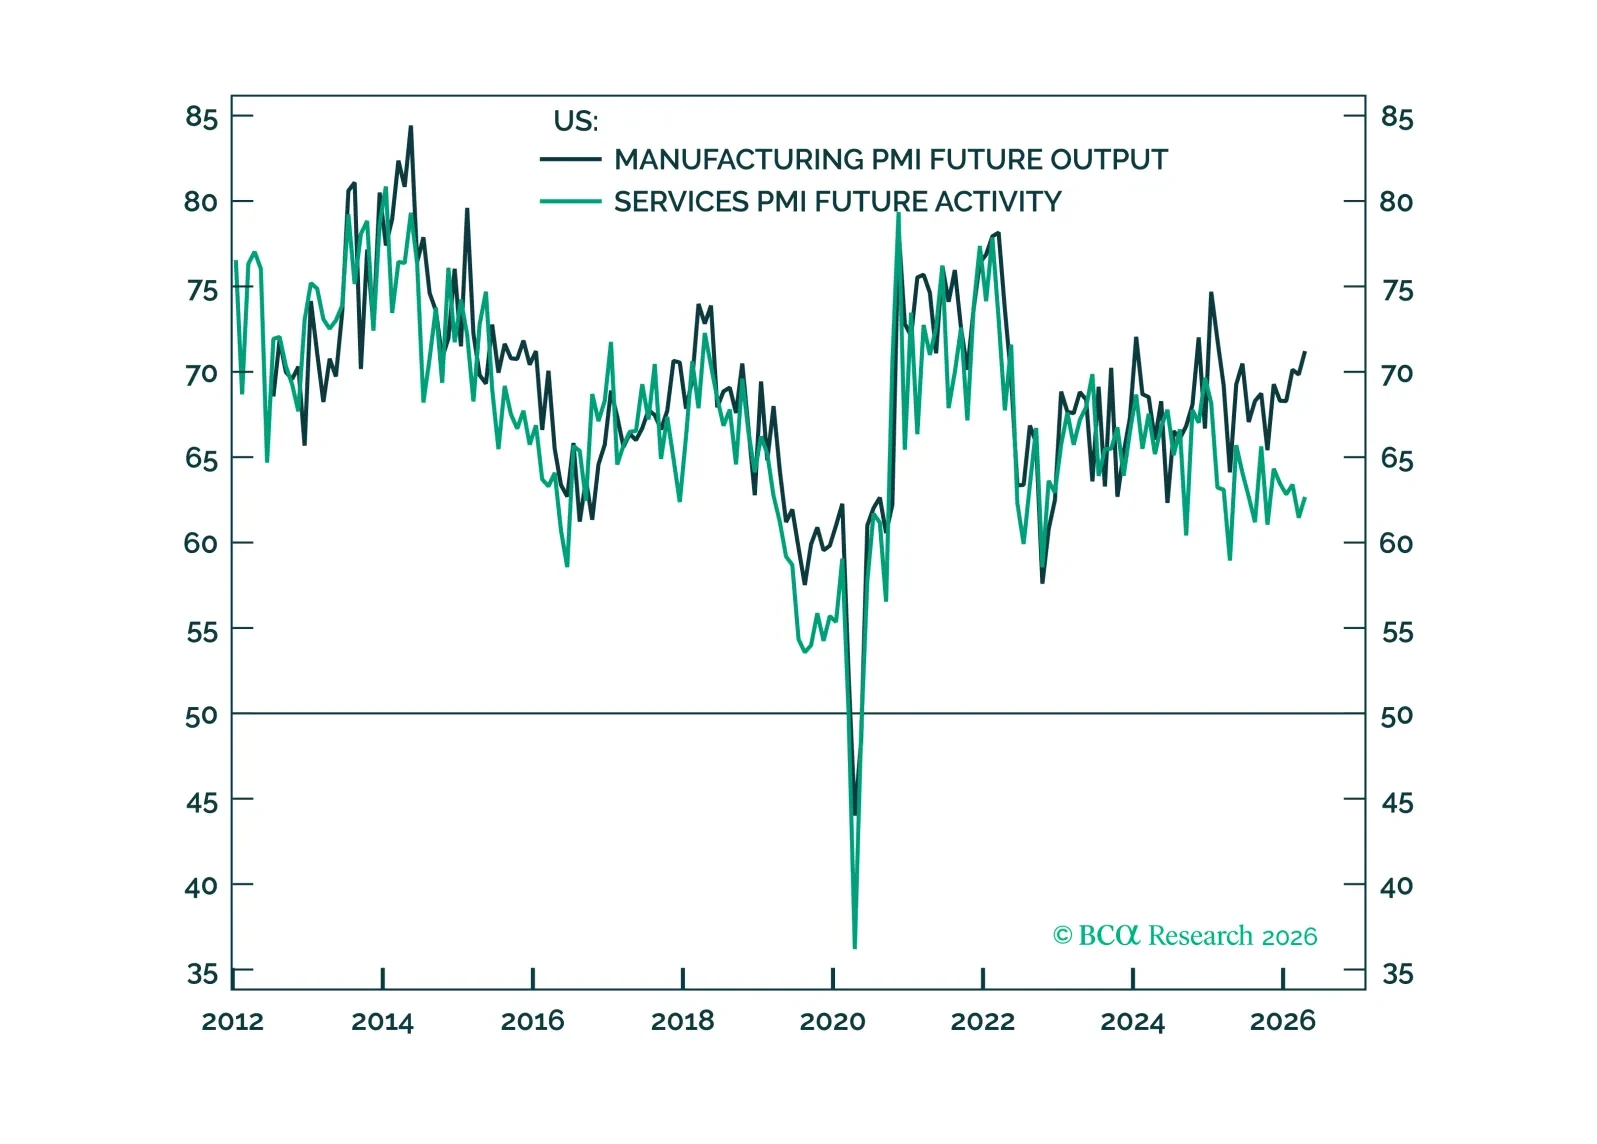
The Strait of Hormuz remains closed. Even if the Strait were to open tomorrow, global consumers will be squeezed for the rest of the year. However, AI capex is accelerating, and signs of ROI are emerging. This capex boom will keep the world from an economic downturn. Upgrade equities to overweight and downgrade cash to underweight. Upgrade the US and downgrade Europe and Australia. Upgrade Communication Services.

We explore how markets reacted to different oil supply shocks in the past, how conditions differ today, and provide a playbook for investors to navigate the current crisis. Remain neutral between equities, bonds, and cash. Downgrade Tail Risk Strategies from Max Overweight to Overweight.
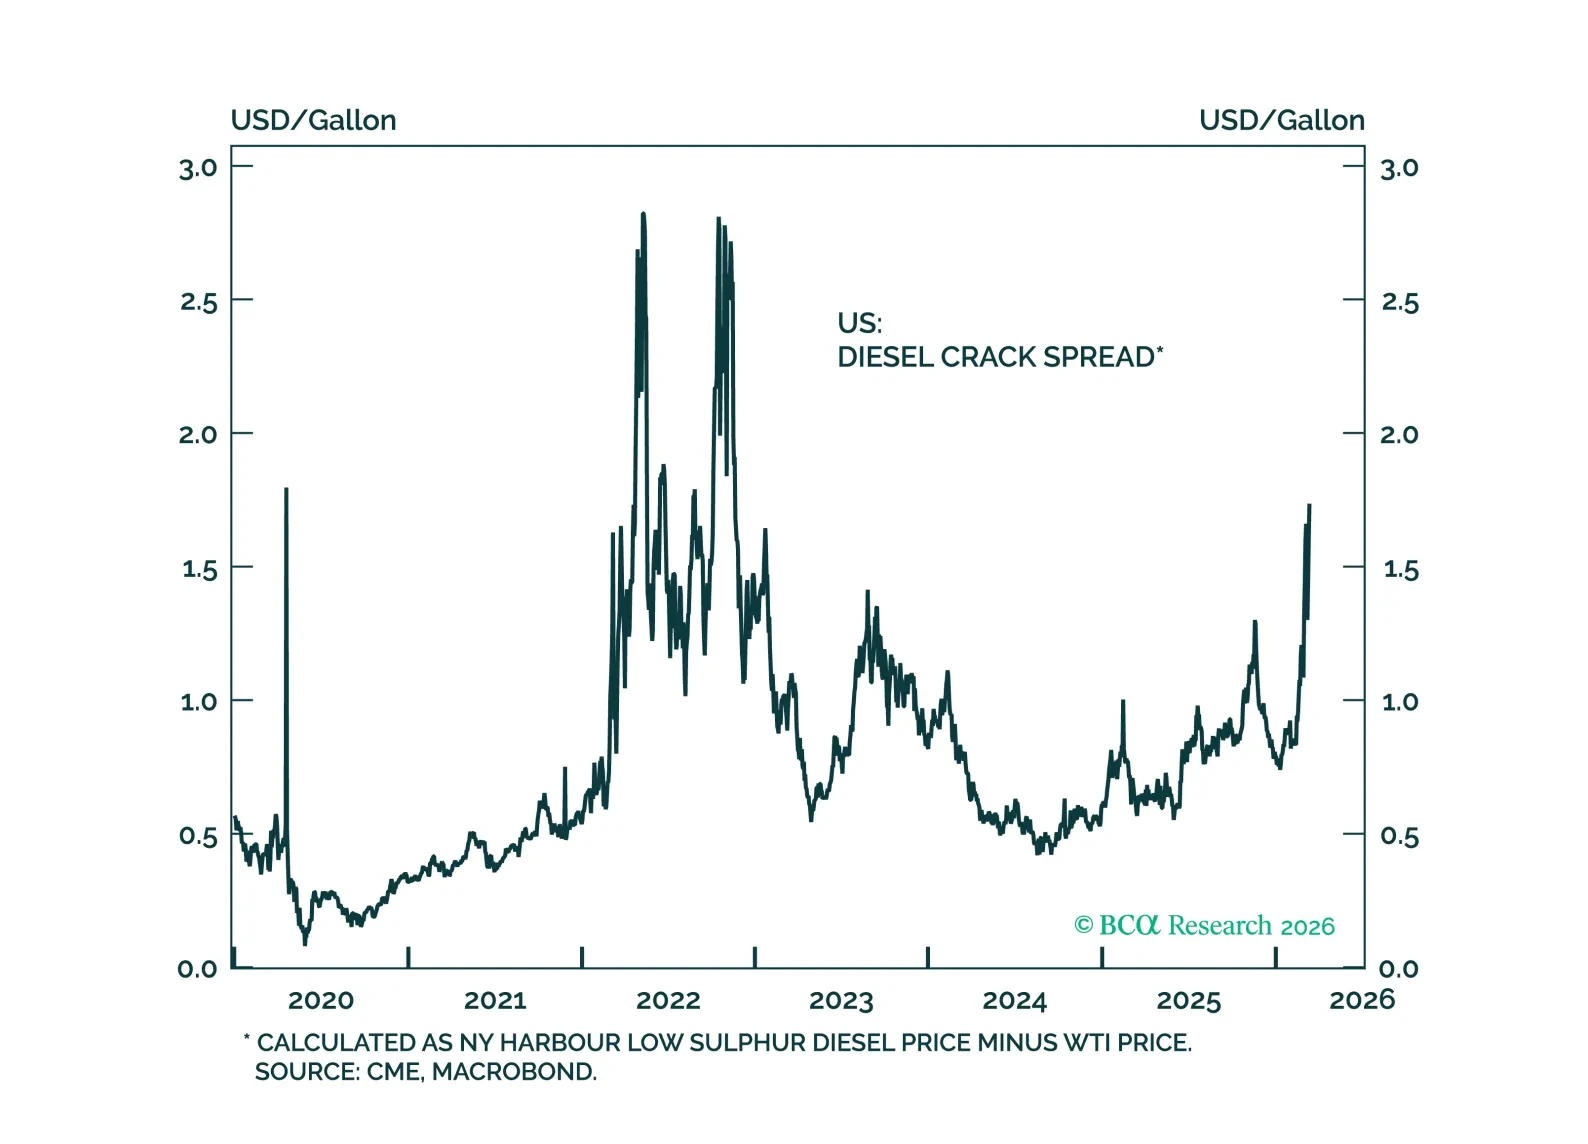
Investors are too complacent on the closure of the Strait of Hormuz. Upgrade cash and downgrade equities, both to neutral.
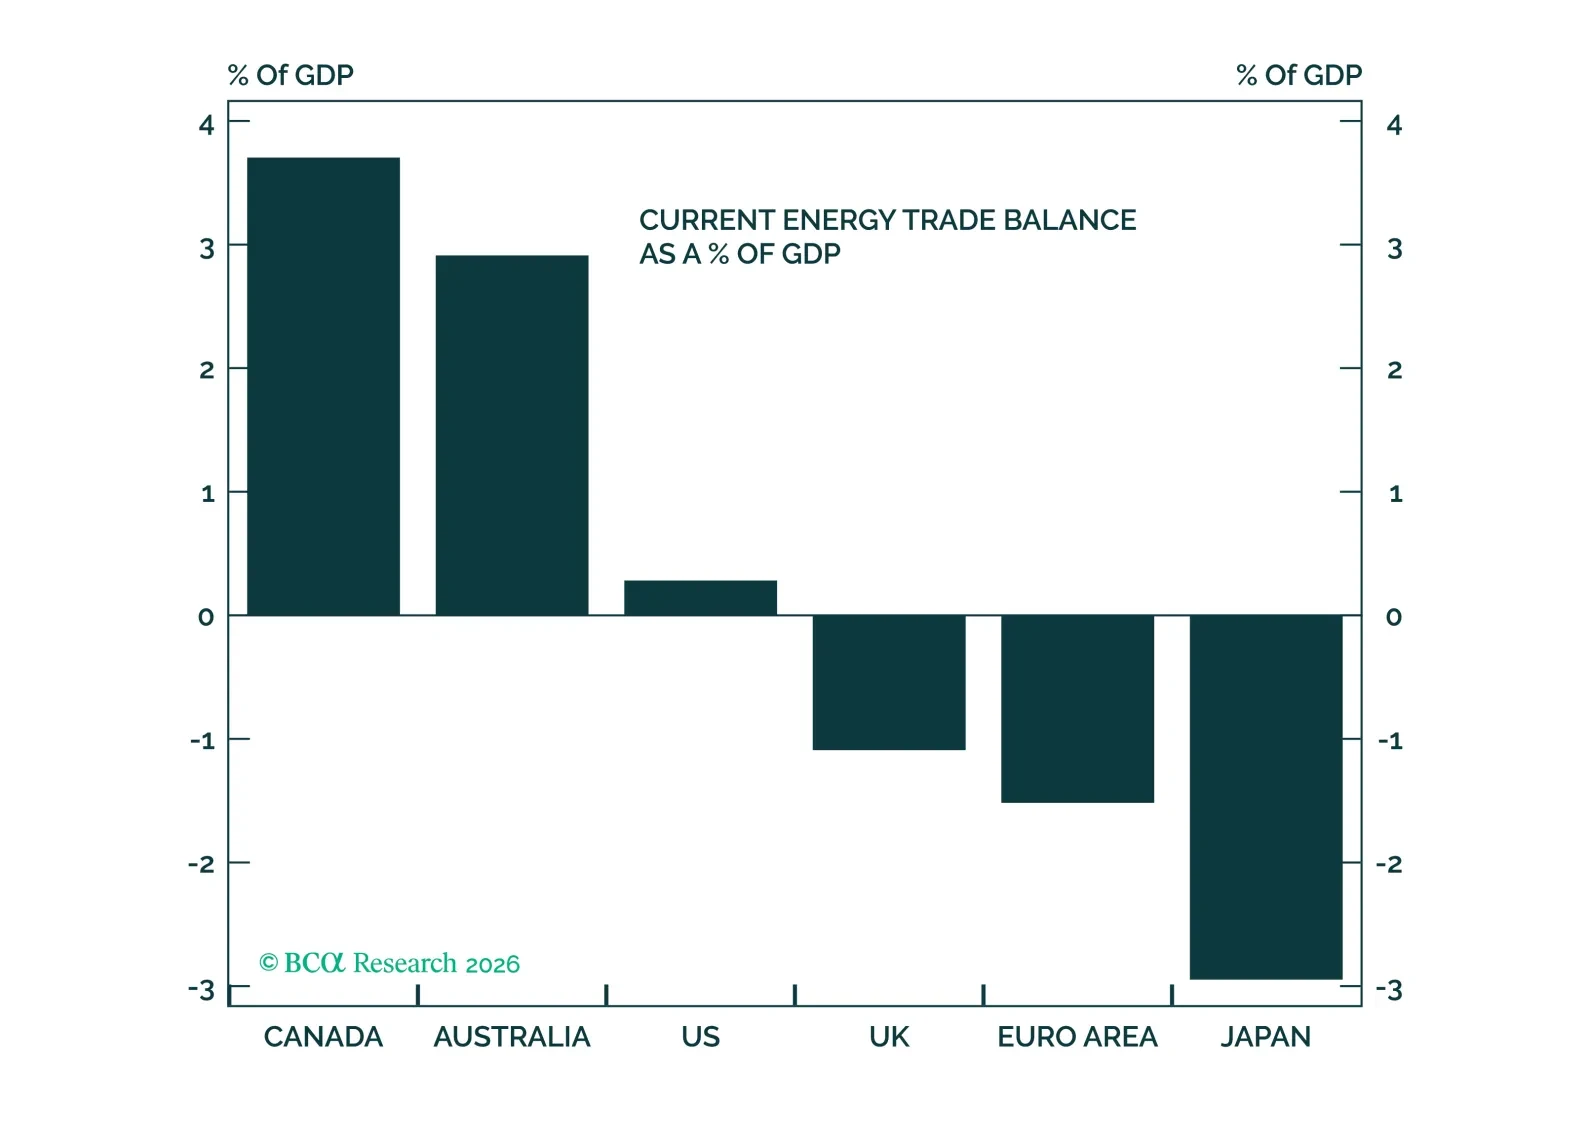
A key risk to our view has materialized. Our base case remains constructive, but risks have increased. Upgrade Tail Risk Strategies from overweight to max overweight. Upgrade Canadian equities and the Canadian dollar to overweight. Upgrade Australian equities and the Australian dollar to overweight.
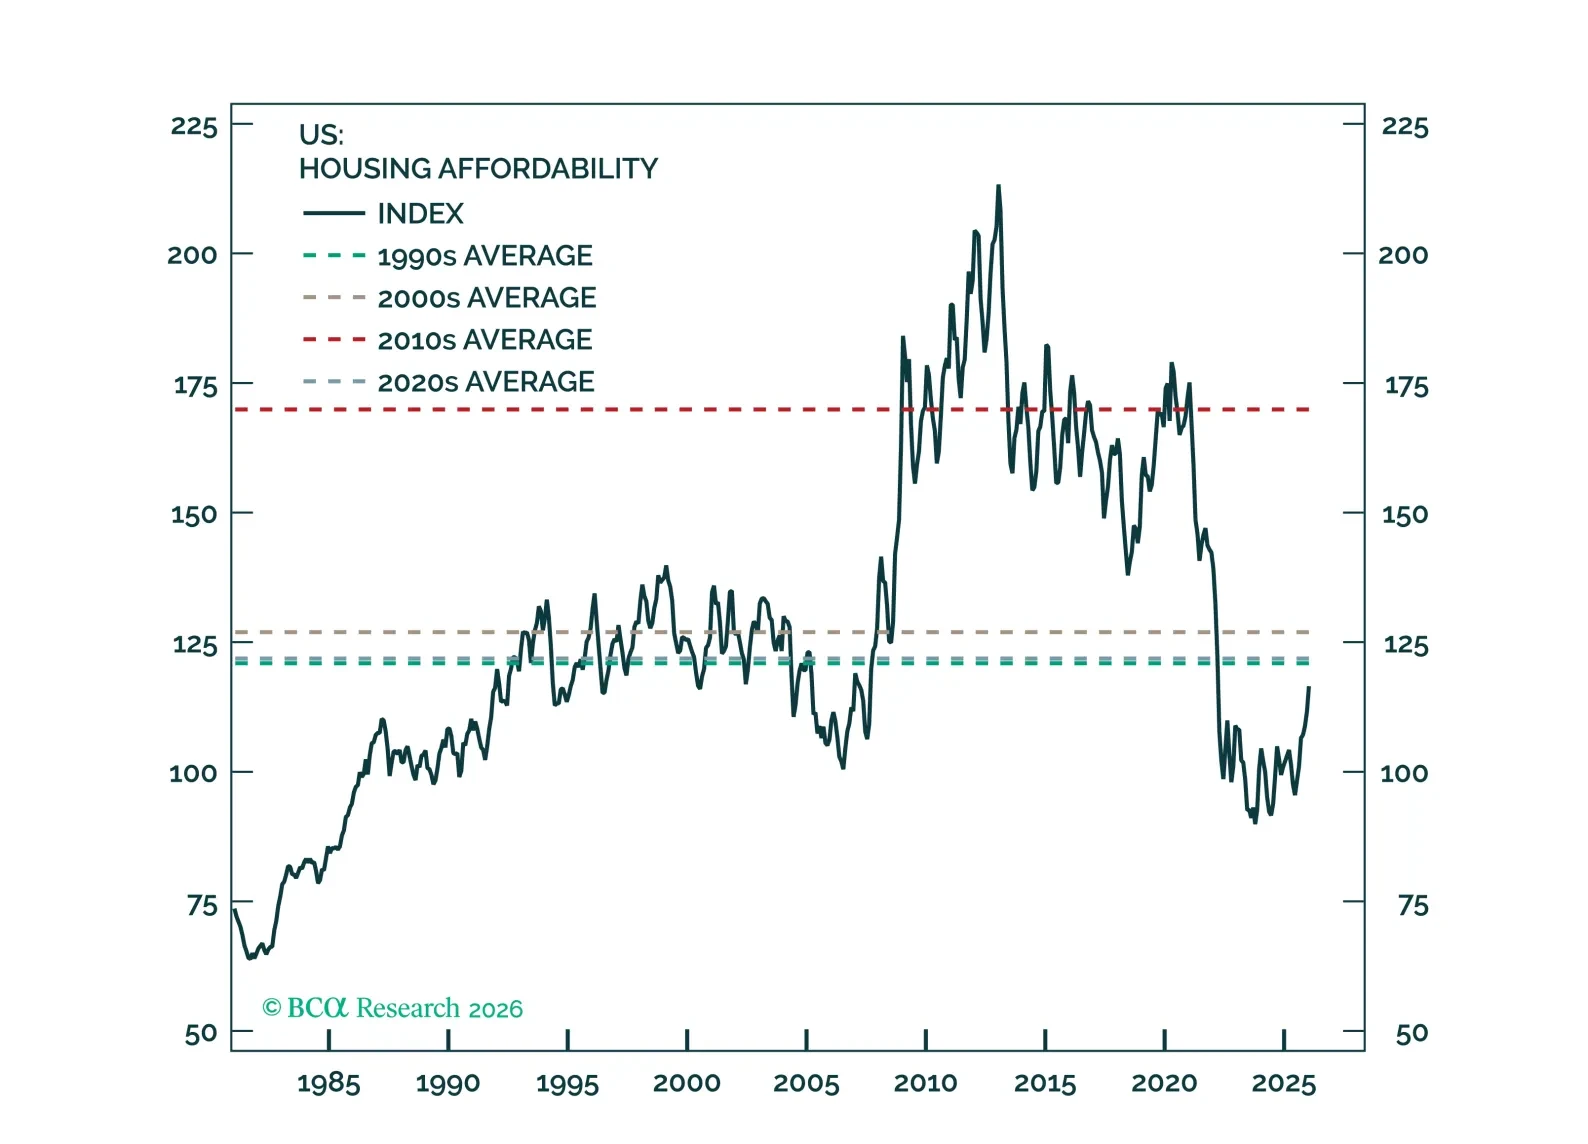
Fears of widespread job losses due to AI are overstated. For investors, the key is that white-collar anxiety is accelerating a red-hot blue-collar economy via lower yields. Upgrade Private Real Estate to overweight.