Skip to main content

Portfolio

| Private Markets

Private equity, credit, real estate, and infrastructure, analyzed with the same macro lens BCA brings to public markets.
Find out more
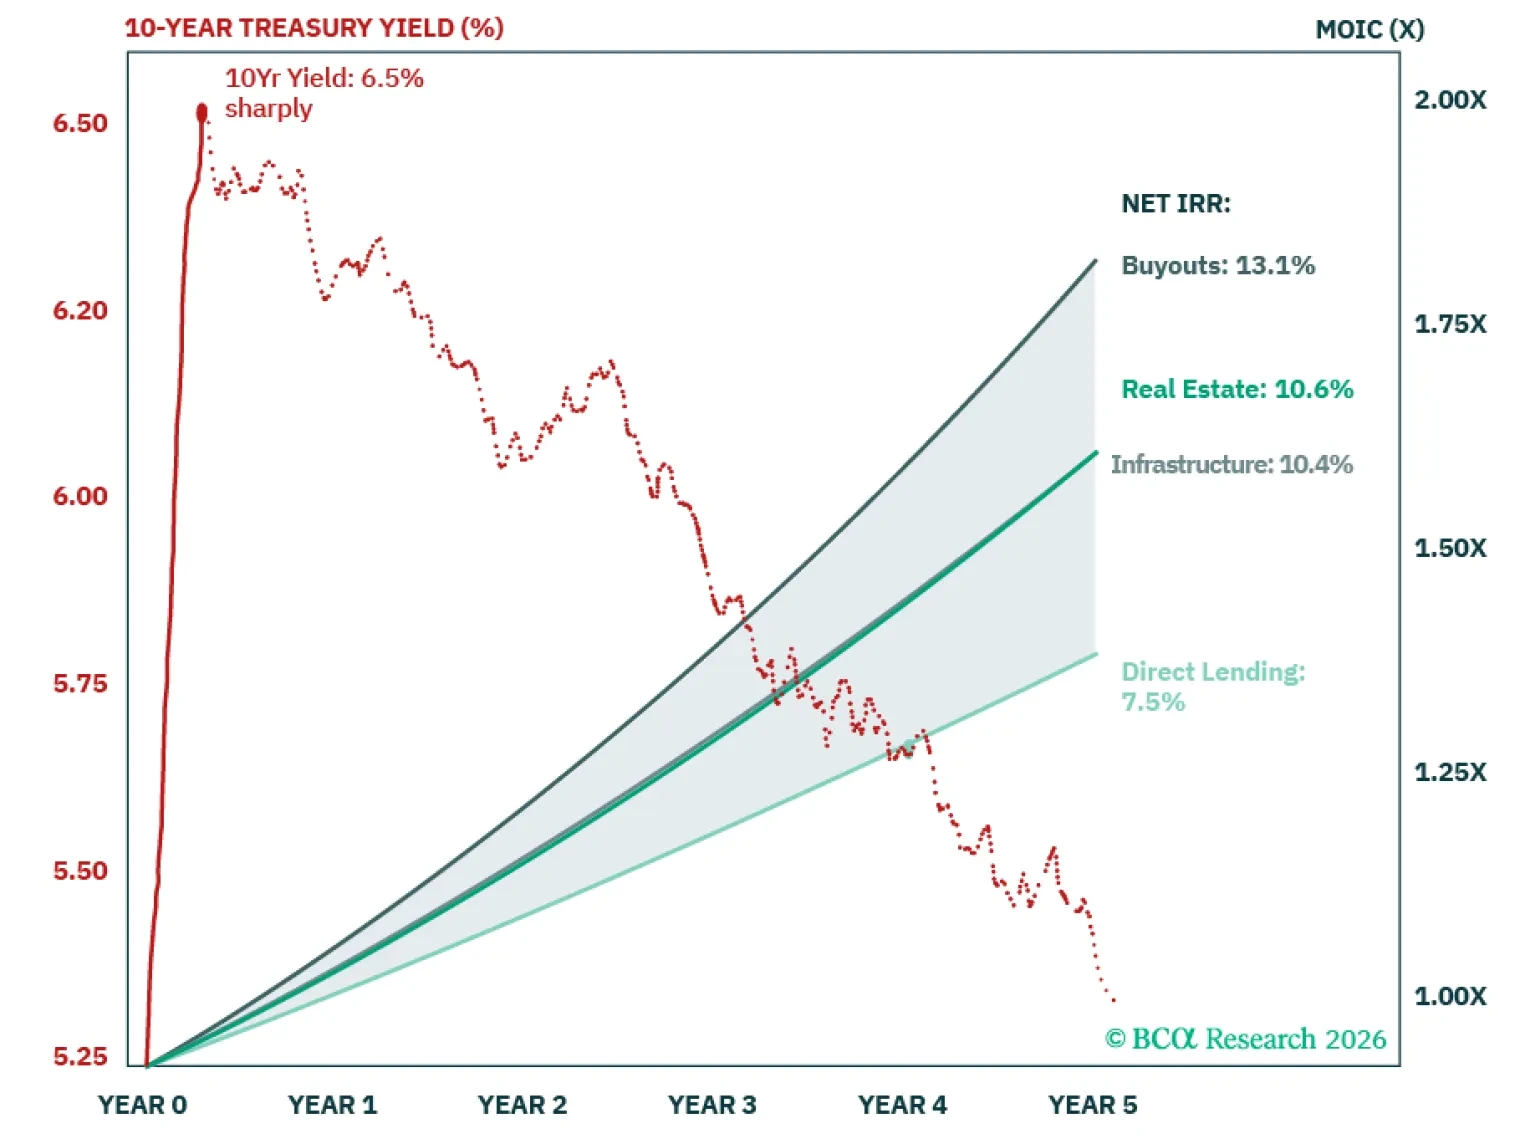
Special Report With capital locked up for years, scenario analysis is especially valuable for Private Market investors. We provide a framework for mapping returns on new investments if the US 10-year yield hits 6.5%, a level last seen in 2000. Just do not expect the risk premiums of that era.
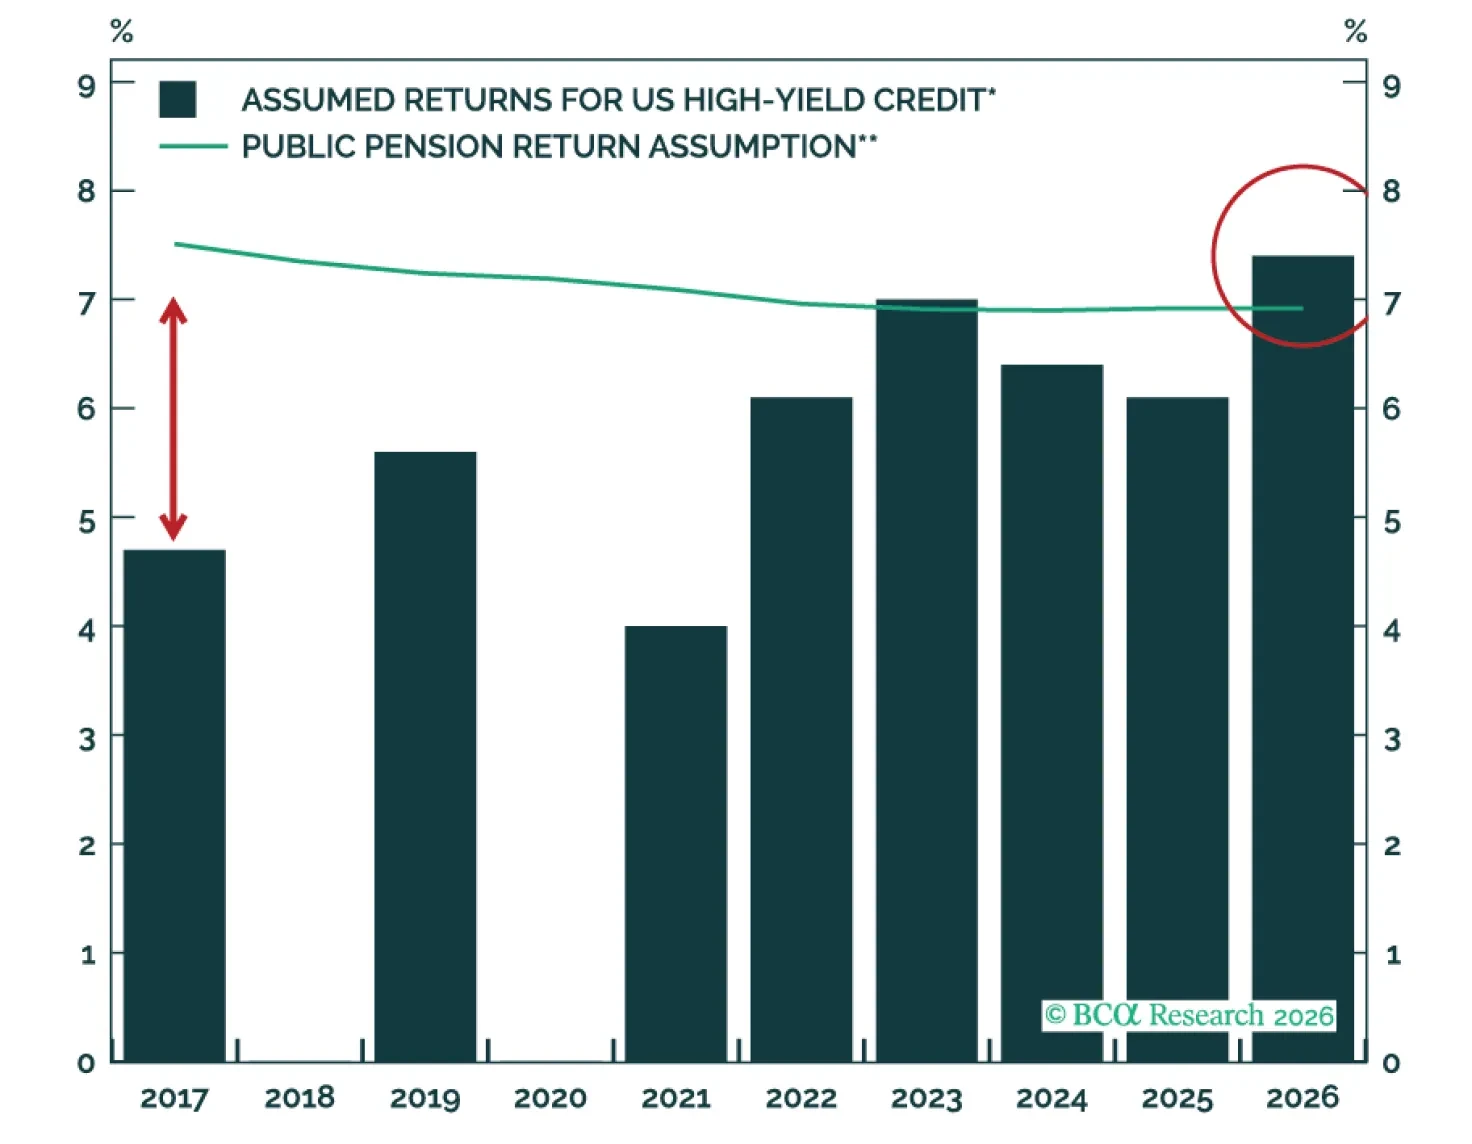
Higher rates have changed the opportunity set. Overweight High-Yield Credit, both within asset allocation and versus Private Credit. Investors are no longer picking up pennies in front of a steamroller.
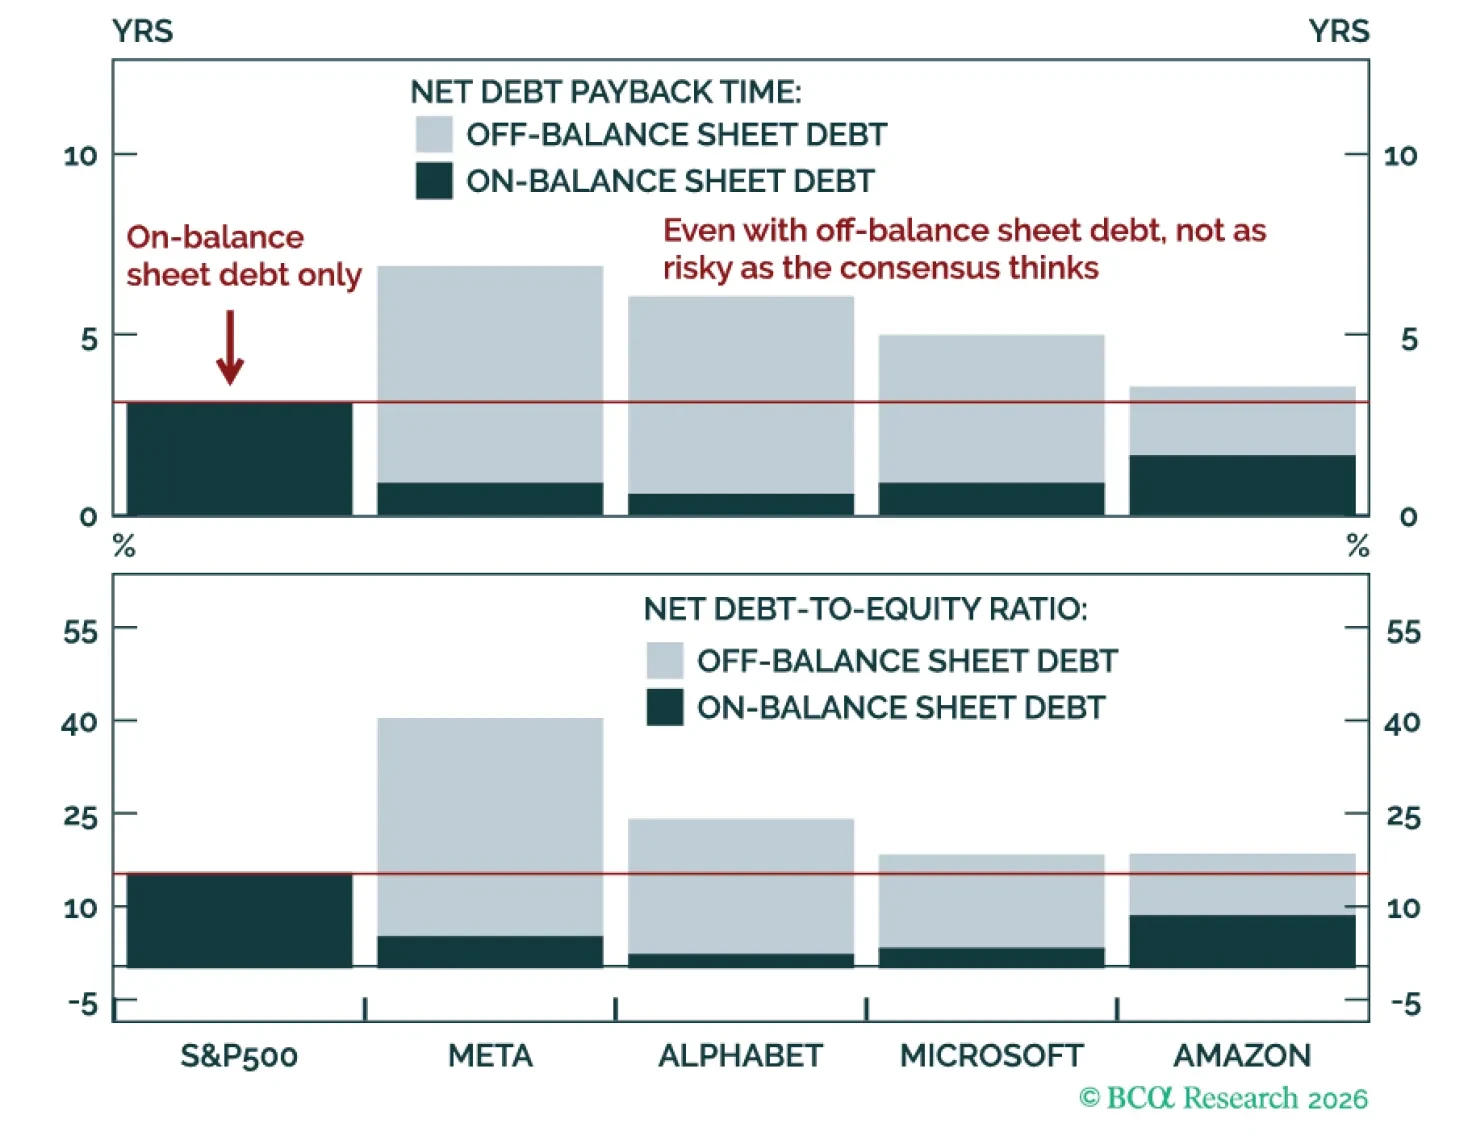
Nerves are rising around Data Center financing but most of the fear comes from GPU financing. GPUs are not Data Centers. Data Center collateral is solid, and so are the tenants.
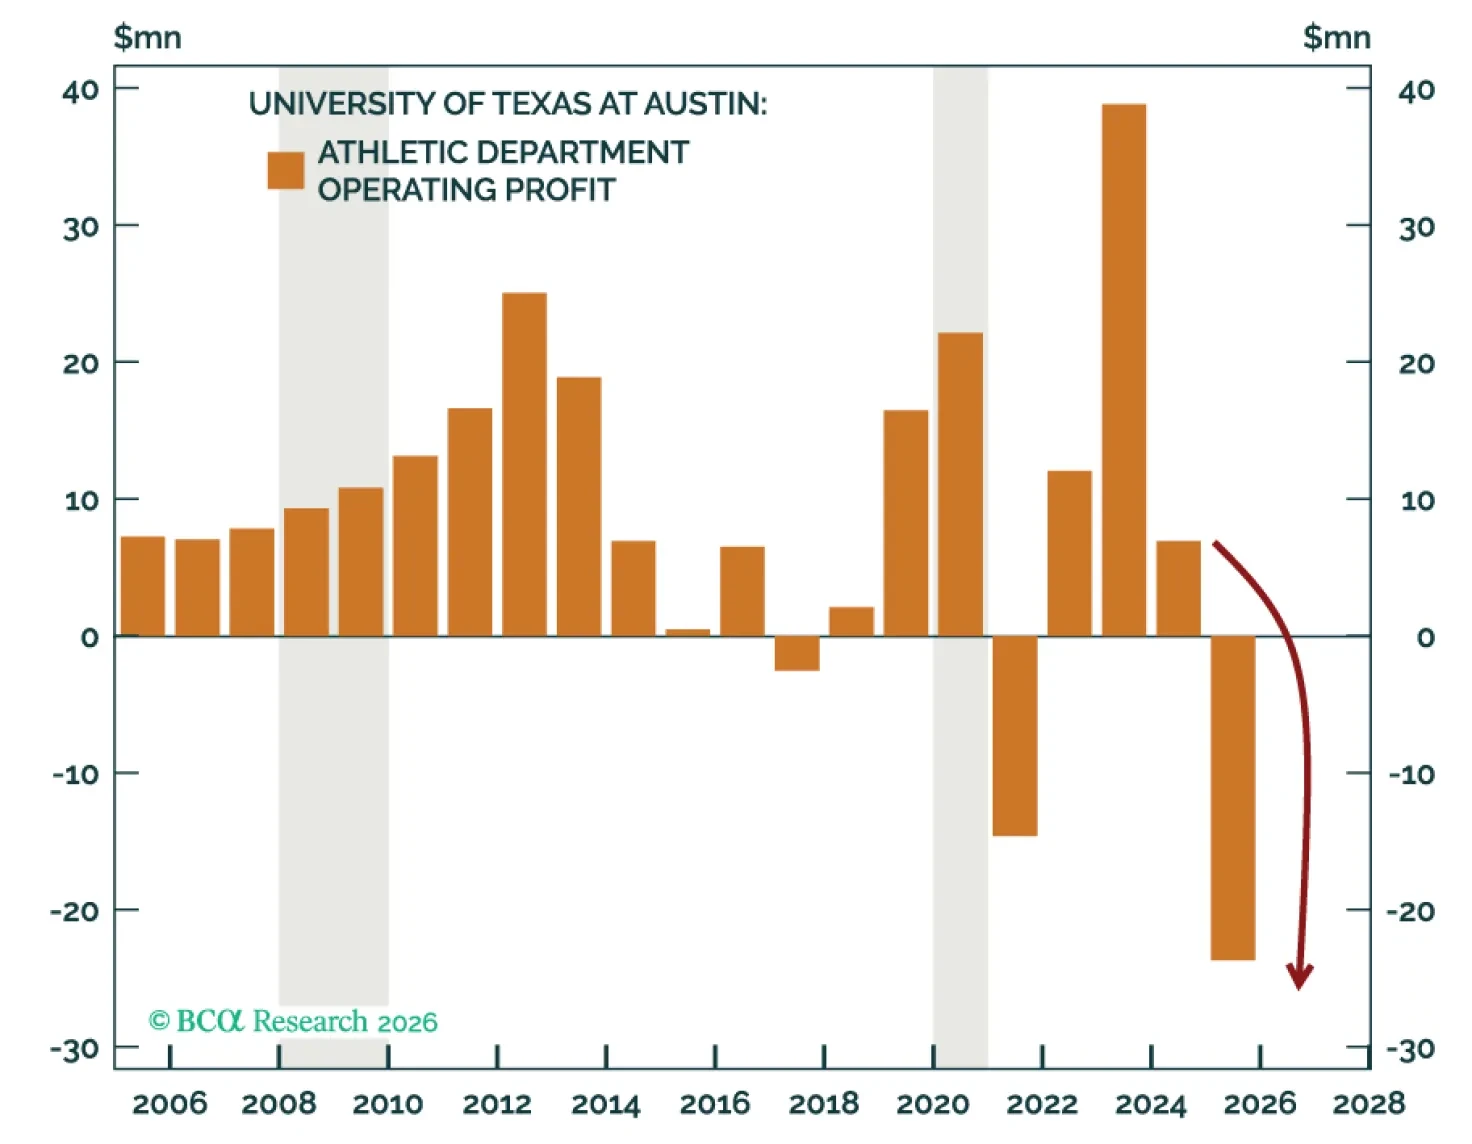
It is that time of year again for our annual Private Equity & Sports report. This year, we examine private capital's entry into college sports. Athletic departments generate significant revenue, but margins are under pressure. Colleges still hold untapped assets that private partners will help monetize.
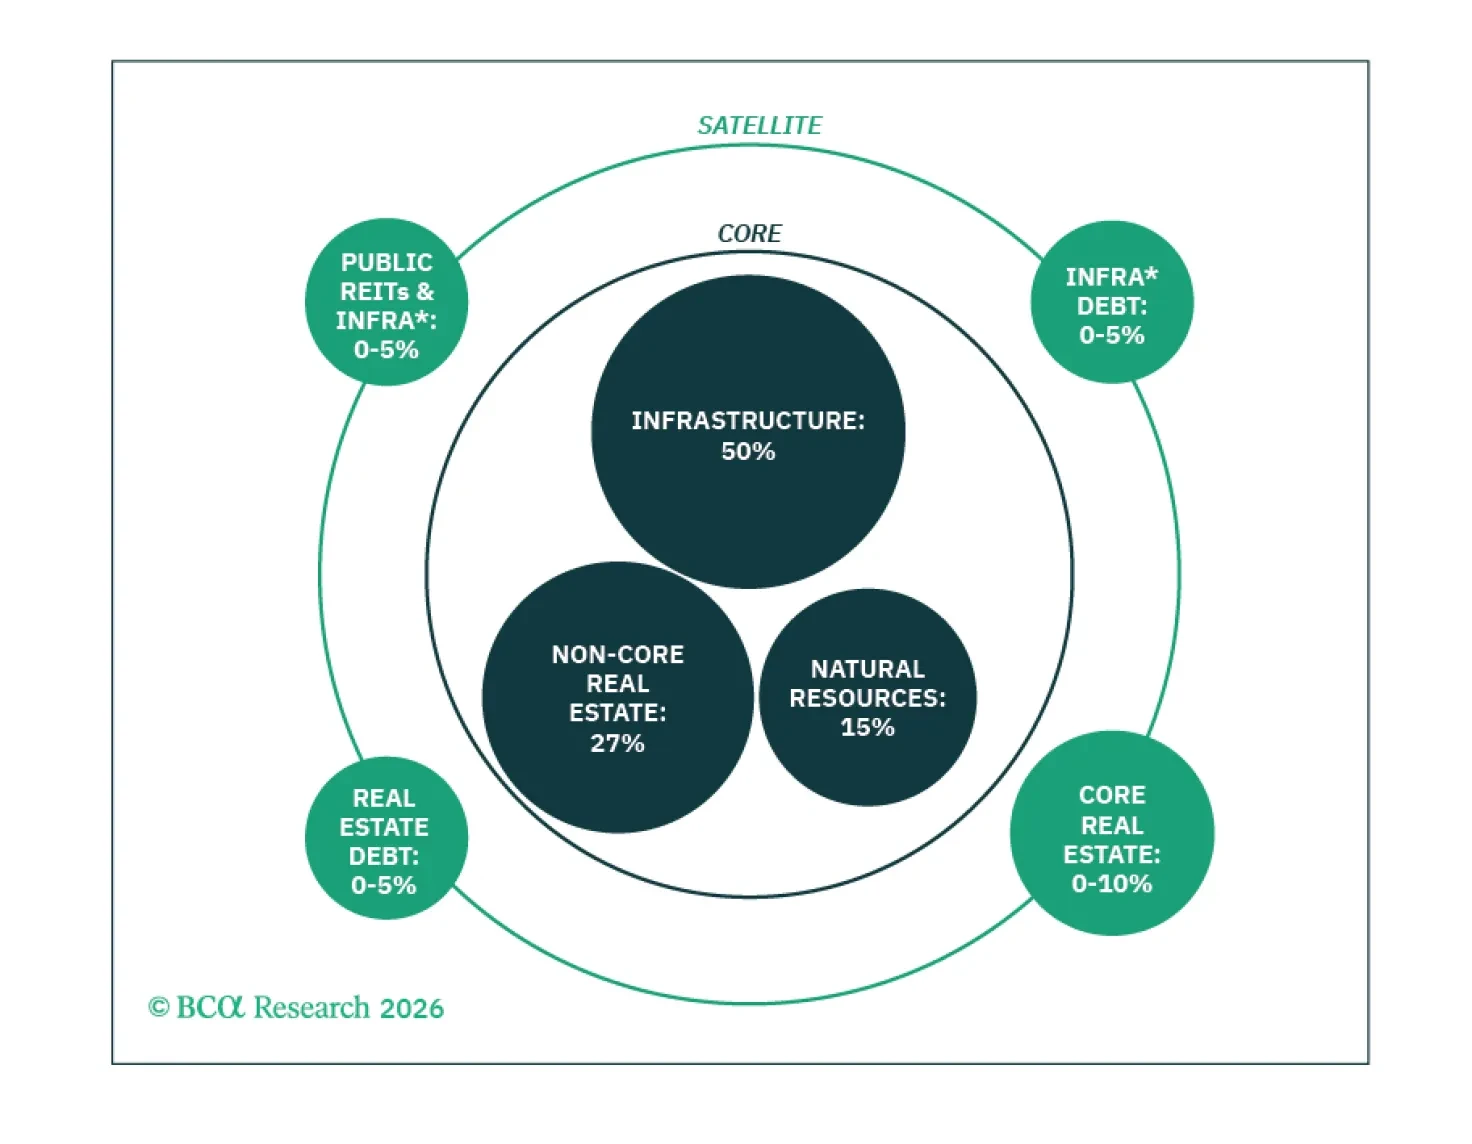
Special Report Real Assets remain underweight in investor portfolios, a gap the 2020s bond bear market has exposed. We provide specifics on constructing a portfolio that supplies more than diversification, it delivers return. The specific weightings may not fit every investor, but the three core principles behind them can.
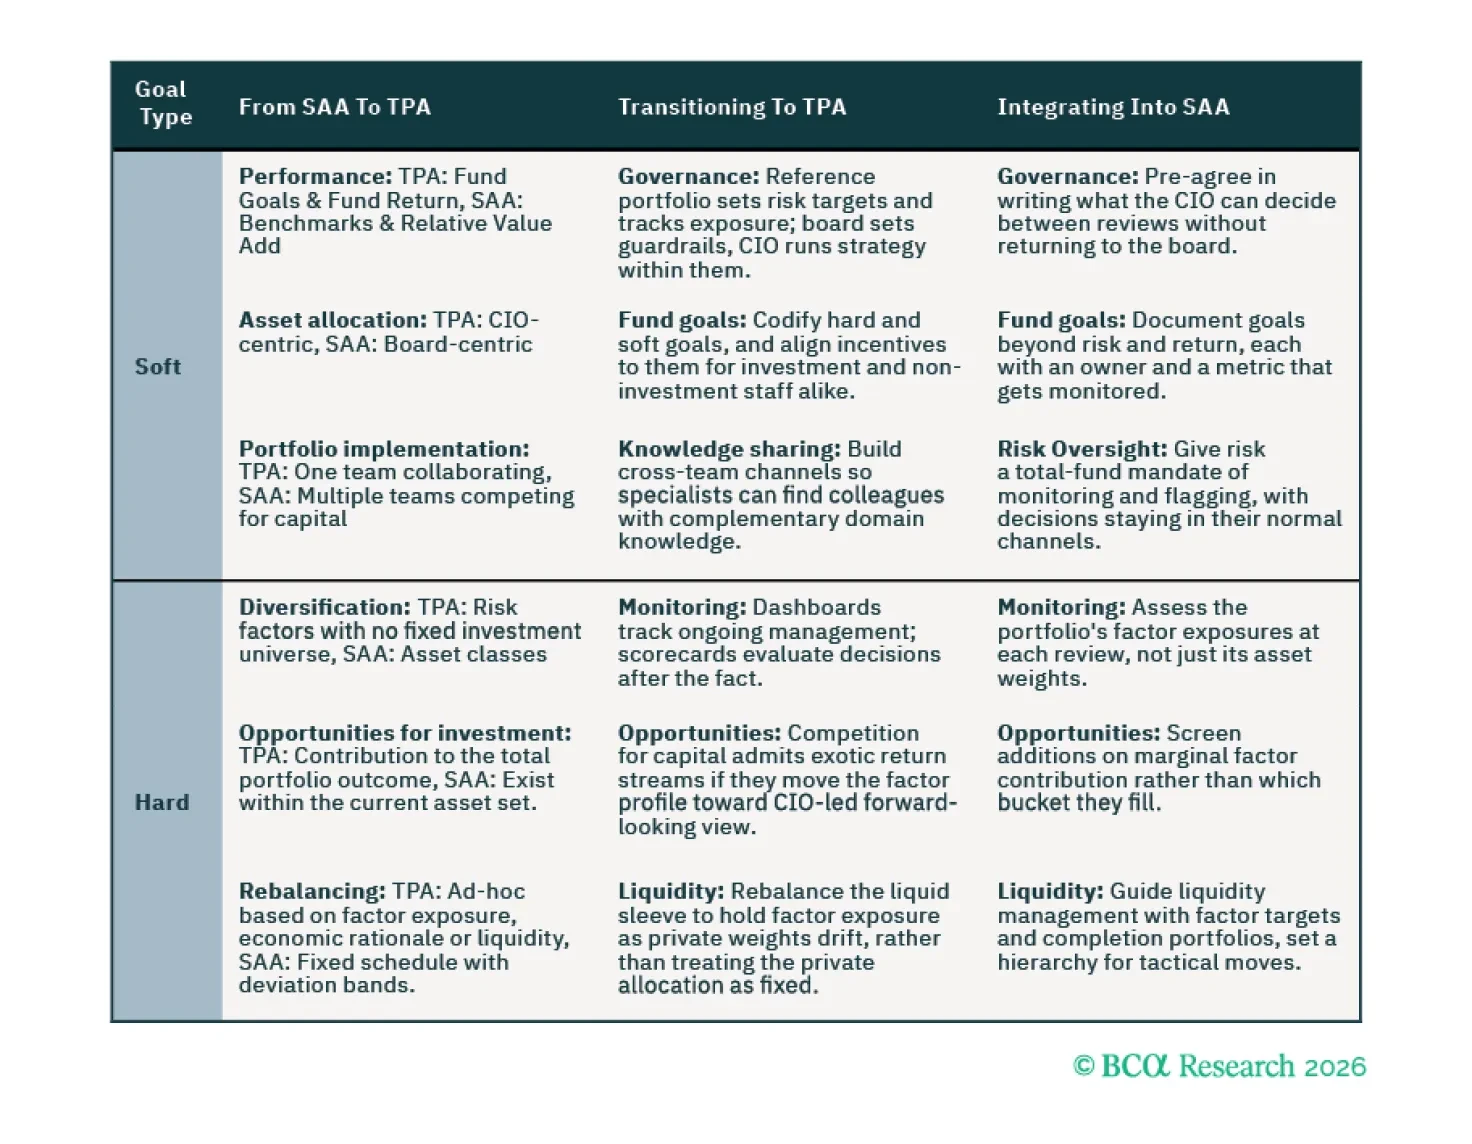
Special Report High-profile adoptions of the Total Portfolio Approach (TPA) and the often-cited outperformance of TPA funds have generated FOMO among funds following an SAA framework. Buzzwords and vague rulesets frustrate anyone trying to learn more. We combed through the TPA literature, built practical examples, and found that many components are just best practices, repackaged. Our suggestion: look past the hype, adopt what fits, ignore what doesn't.
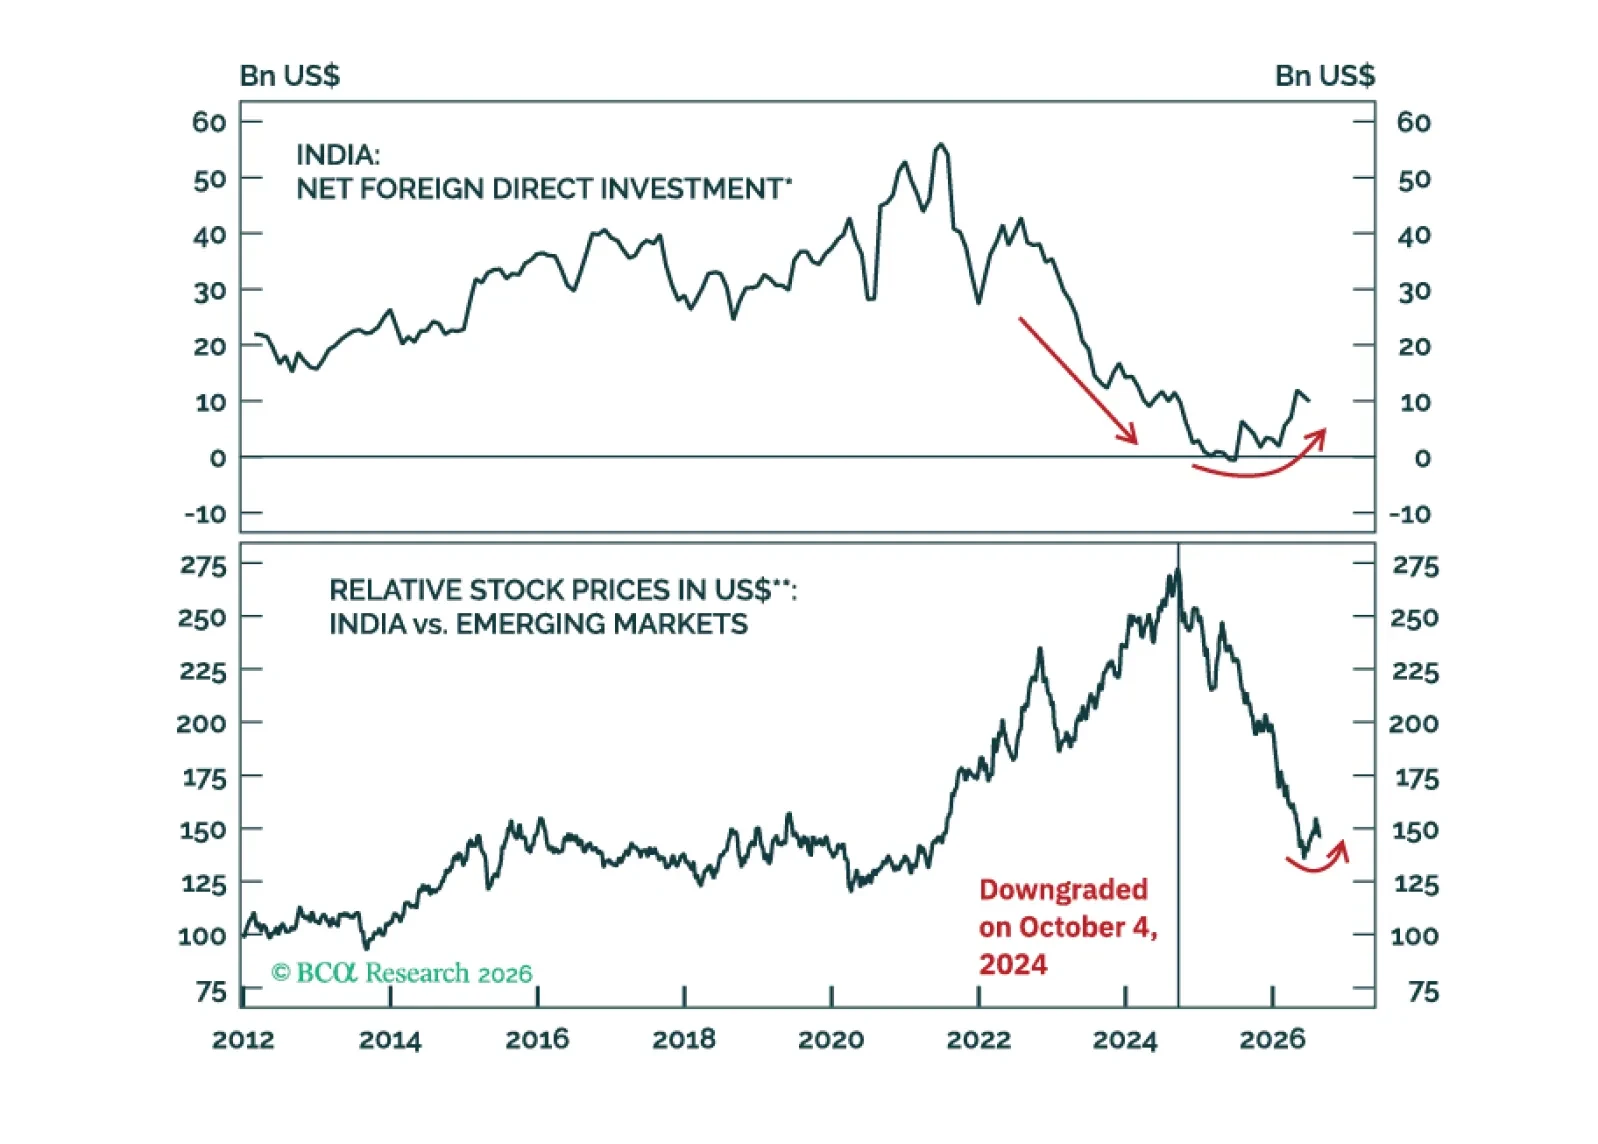
BCA's CoreMacro and Portfolio Construction teams combine two distinct but intersecting lenses to revisit a once heralded opportunity: India. We upgrade India across both public and private markets, but the conviction is not the same everywhere.
Special Report Today's concerns about Private Credit are overstated. We provide our three-criteria framework that investors can use to track Private Credit's doomsday risk. Systemic crises build over years and decades. In Private Credit, that build is happening now.
Beginning with this Quarterly report, The Global Asset Allocation and Private Markets teams are combining our quarterly outlooks into a single, unified framework, reflecting a more integrated approach to portfolio construction. In this joint outlook we upgrade Private Equity to overweight. Sentiment has soured, LPs are starved of distributions, flows have collapsed, valuations are trending lower, Secondaries are outperforming Primaries, and GP stocks are experiencing their worst underperformance on record. All signs of a durable bottom.
Special Report AI dominates markets, but concentration is risk. Real Estate is the diversifier. It outperformed during the Dot-Com bust and will do so again if the AI trade unwinds. Even Office, the sector arguably most exposed to AI disruption, will prove more resilient than bears expect.