 Portfolio
| Private Markets
Private equity, credit, real estate, and infrastructure, analyzed with the same macro lens BCA brings to public markets.
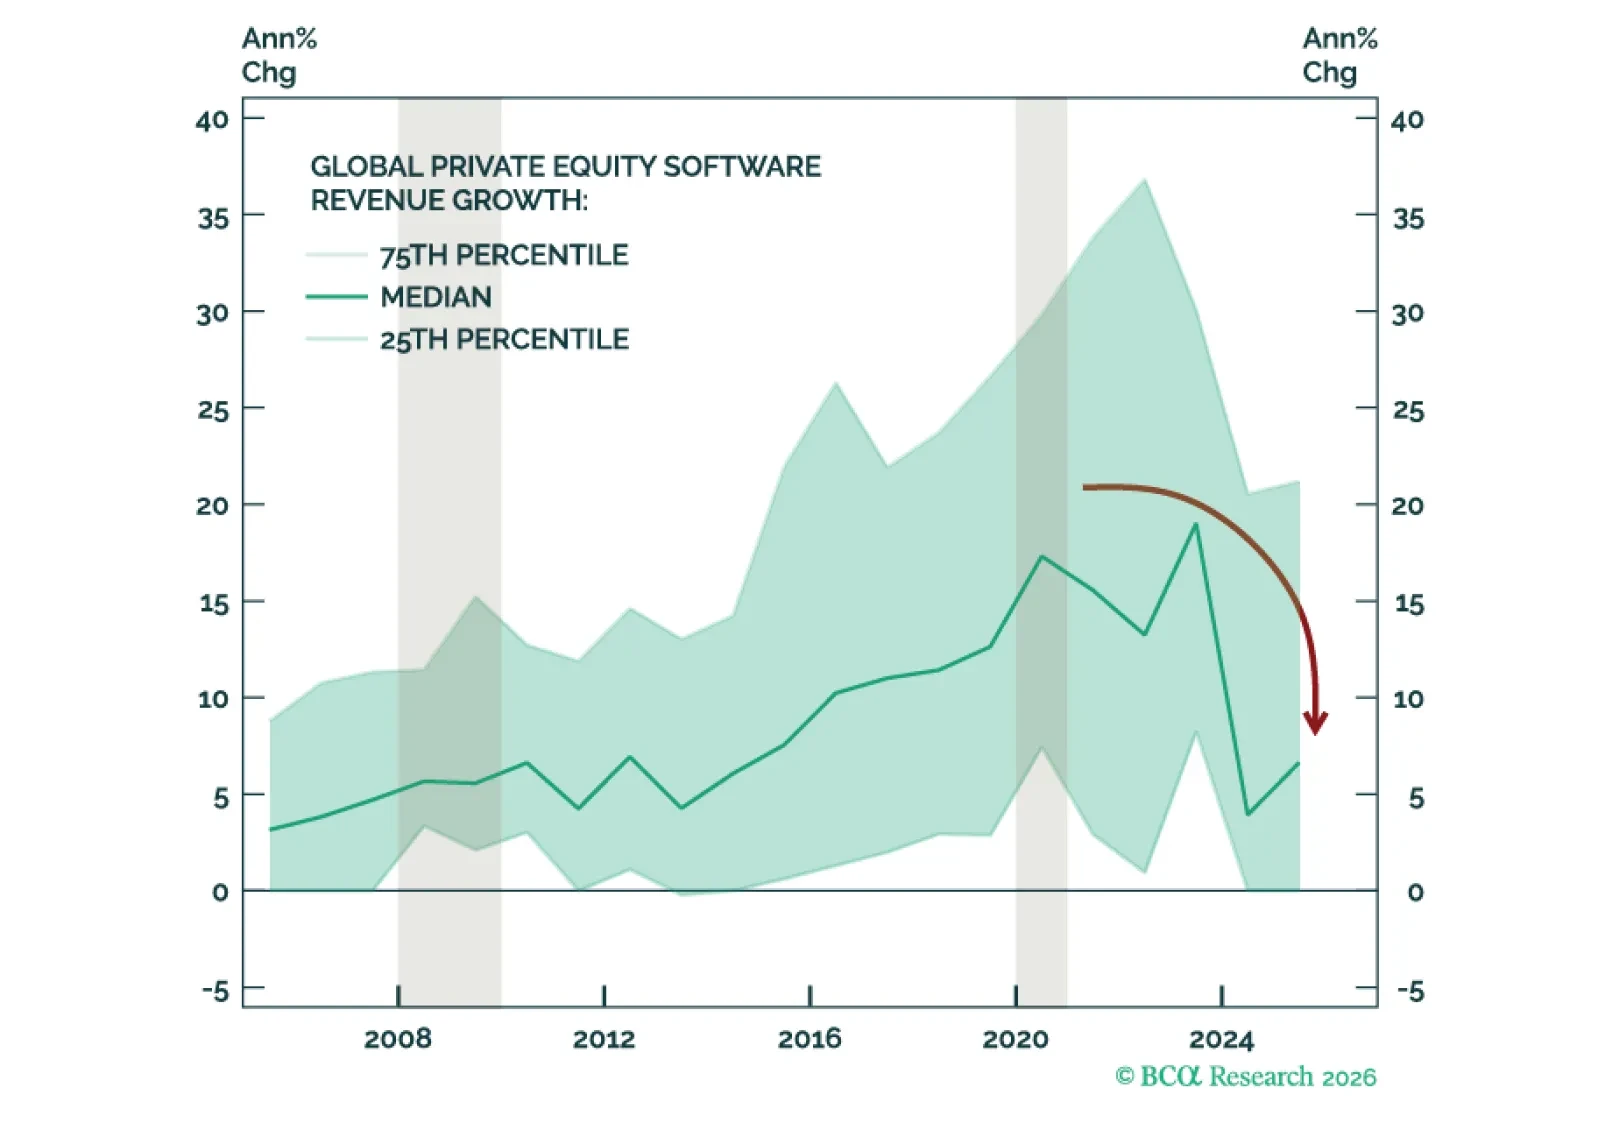
Software has rattled Public Stocks, BDCs, and Asset Managers. Exposure across Private Markets has raised more questions than answers. We size it up. Private Equity is under pressure, Venture Capital is racing ahead, and Credit is pricing in the risk.
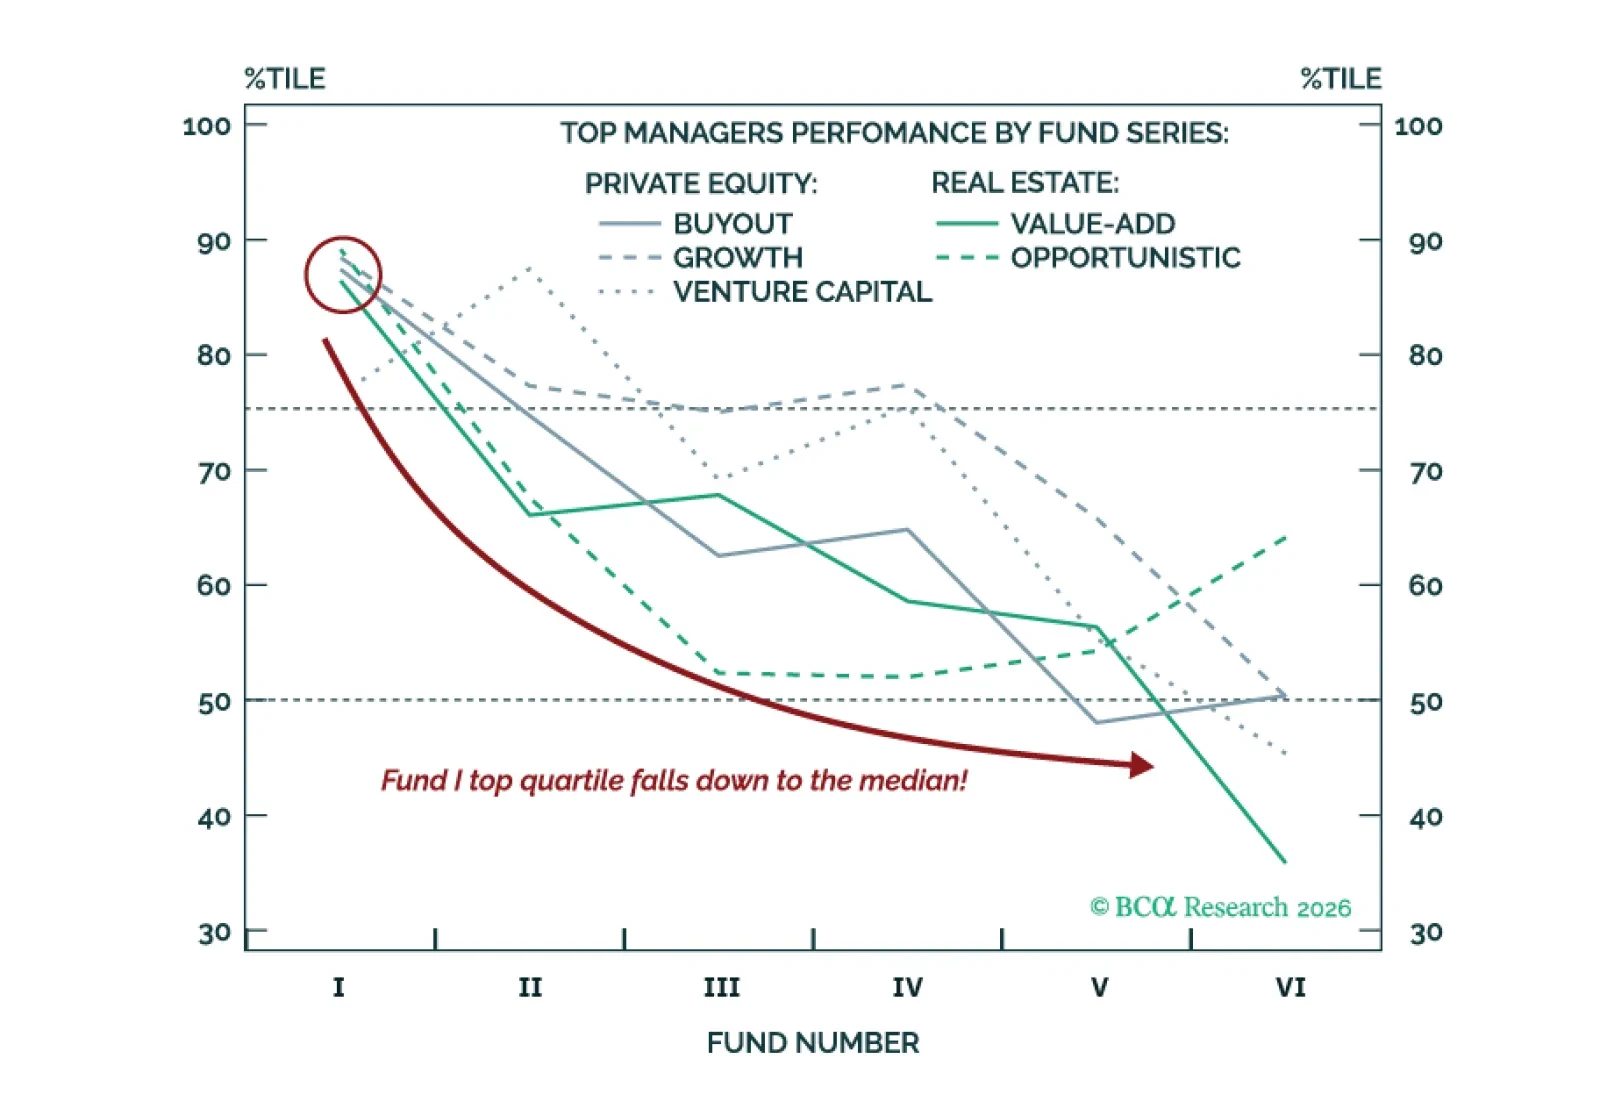
In Private Markets, yesterday’s winners often see outperformance fade. Top-quartile managers often regress toward the median as fund series mature. For investors evaluating the next Real Estate or Private Equity manager: Bias toward underweighting Funds V and beyond.

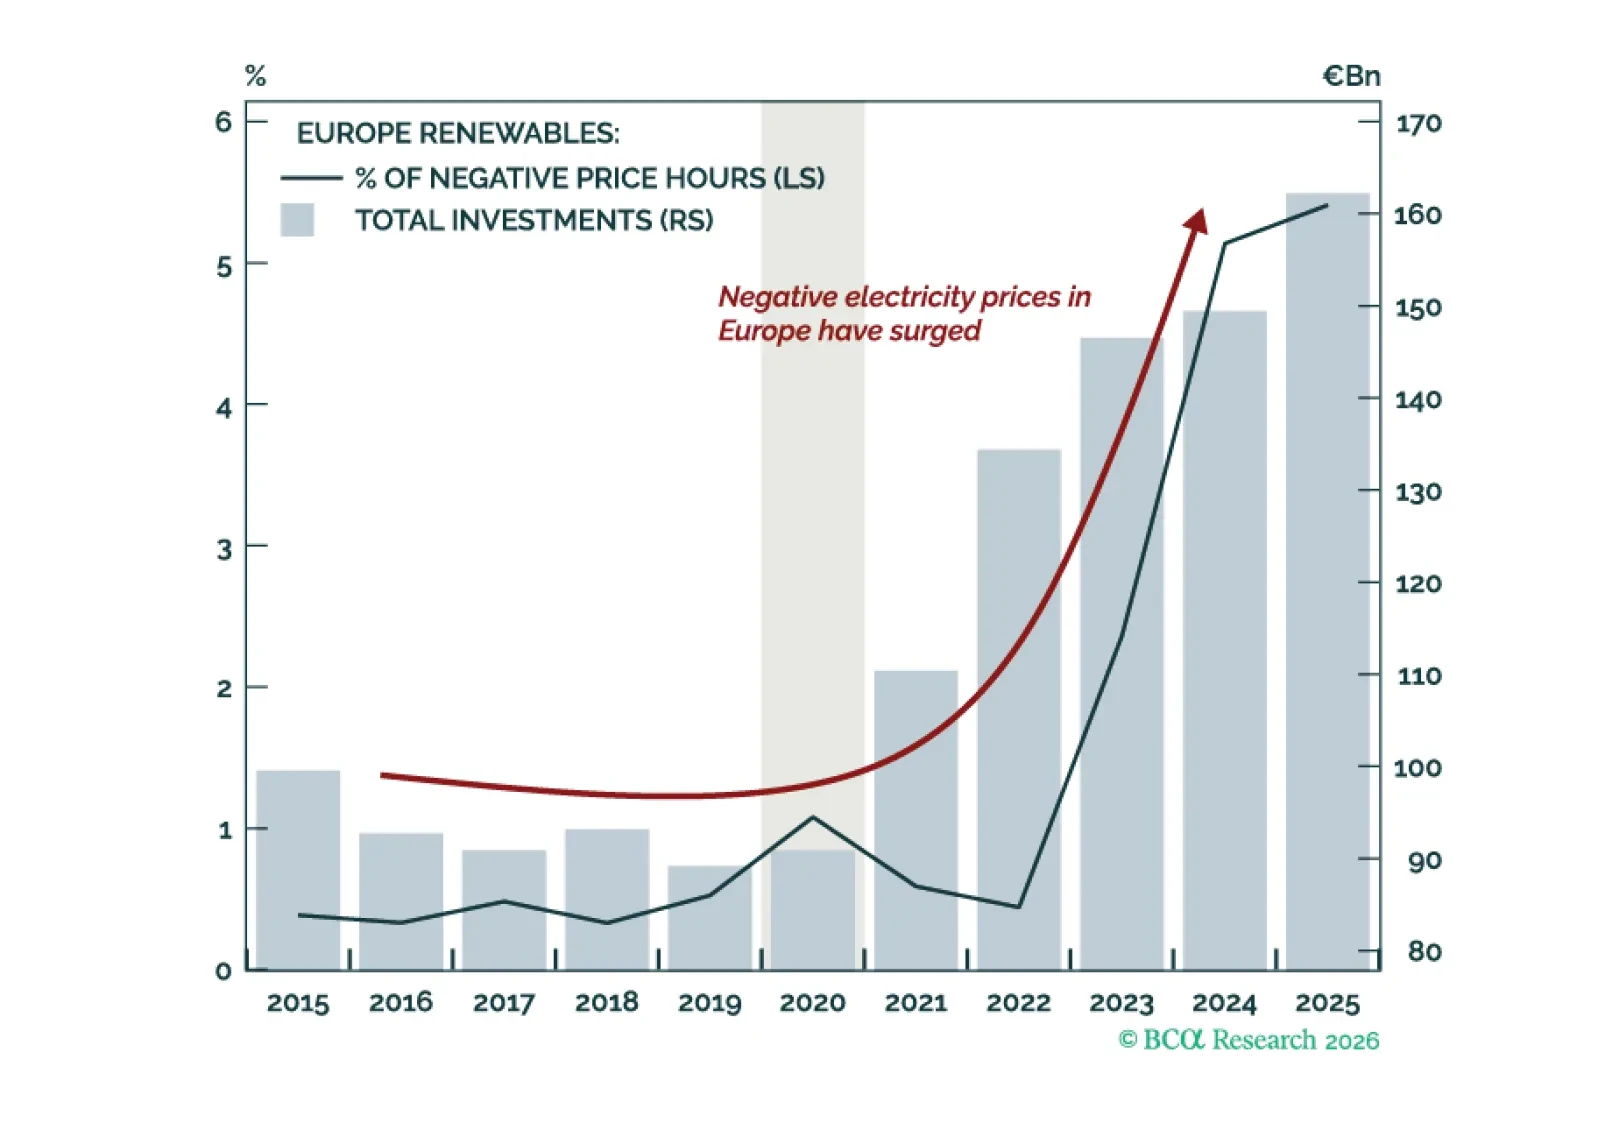
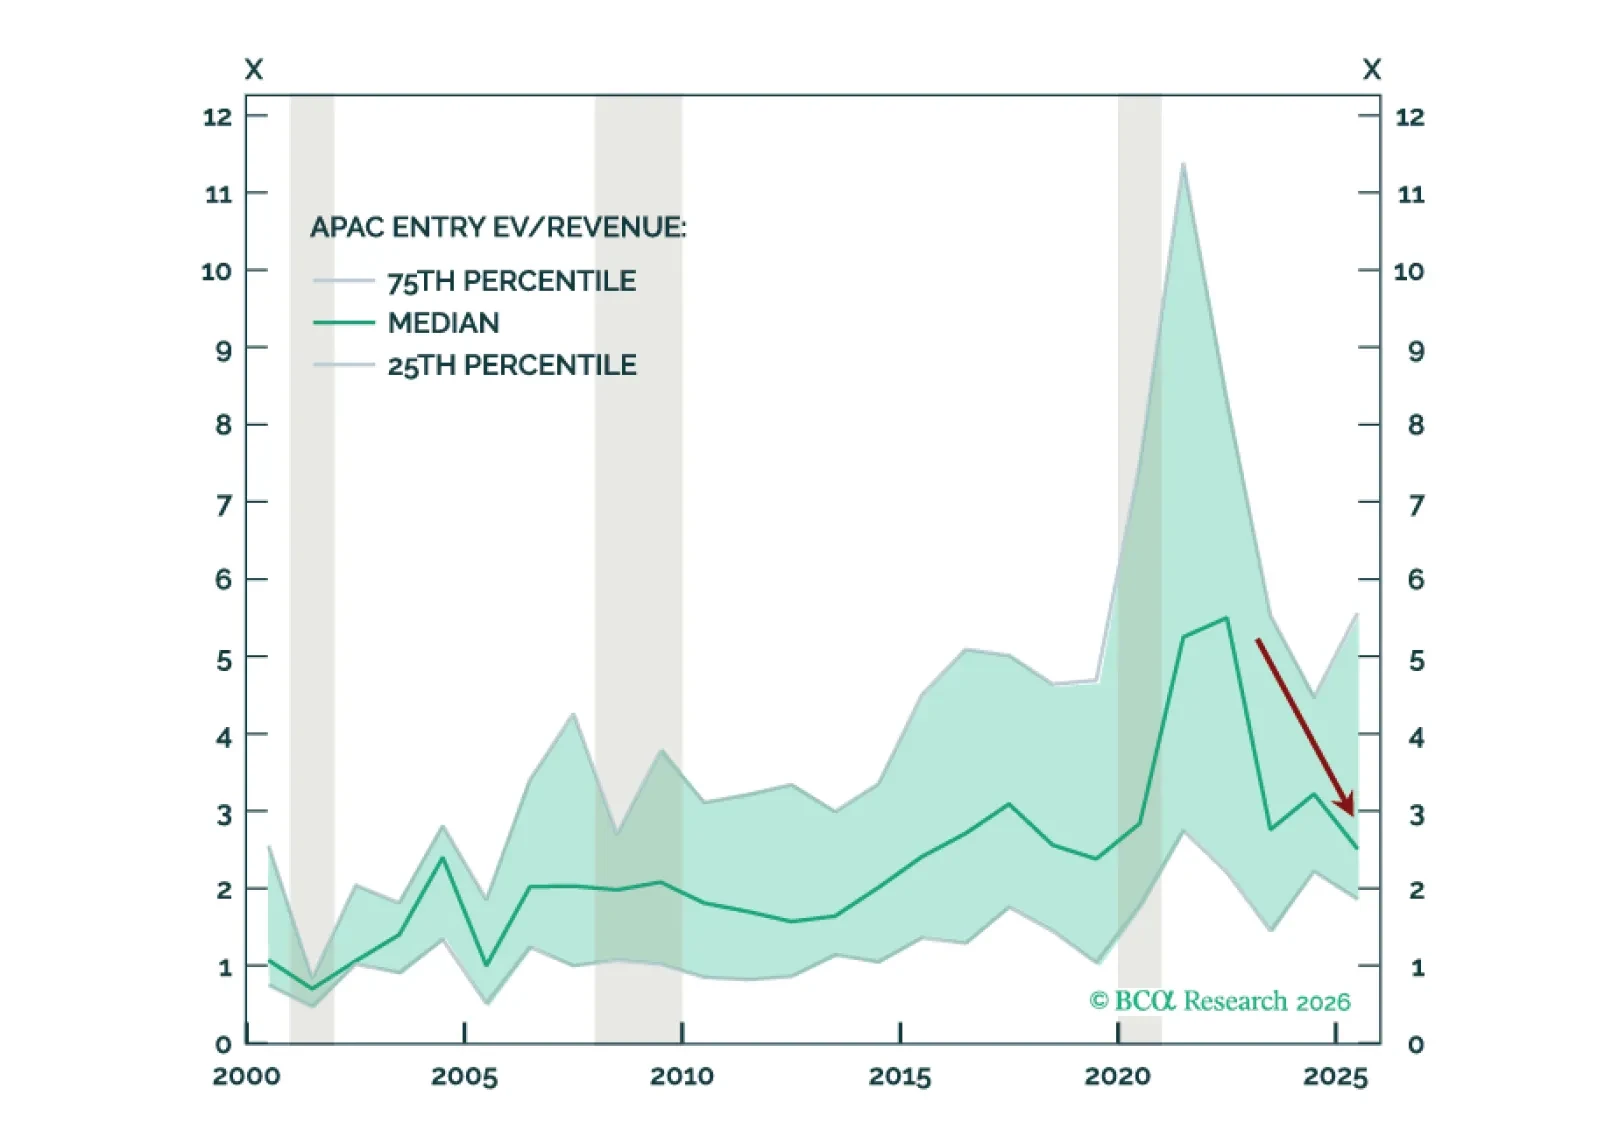
We remain overweight APAC in both Private Equity and Venture Capital, recognizing the region and its opportunities have evolved meaningfully. Buyouts are growing faster than many realize, driven by Japan, while a deeper reset in fundamentals versus global markets supports stronger upside potential.

Investment risk in Private Markets differs from that in Public Markets. It unfolds over time, with today’s issues coming from yesterday’s investments. We explain why, and more importantly, why the next dollar now faces lower risk across both macro and fundamental drivers. Just do not expect a discussion about standard deviations.
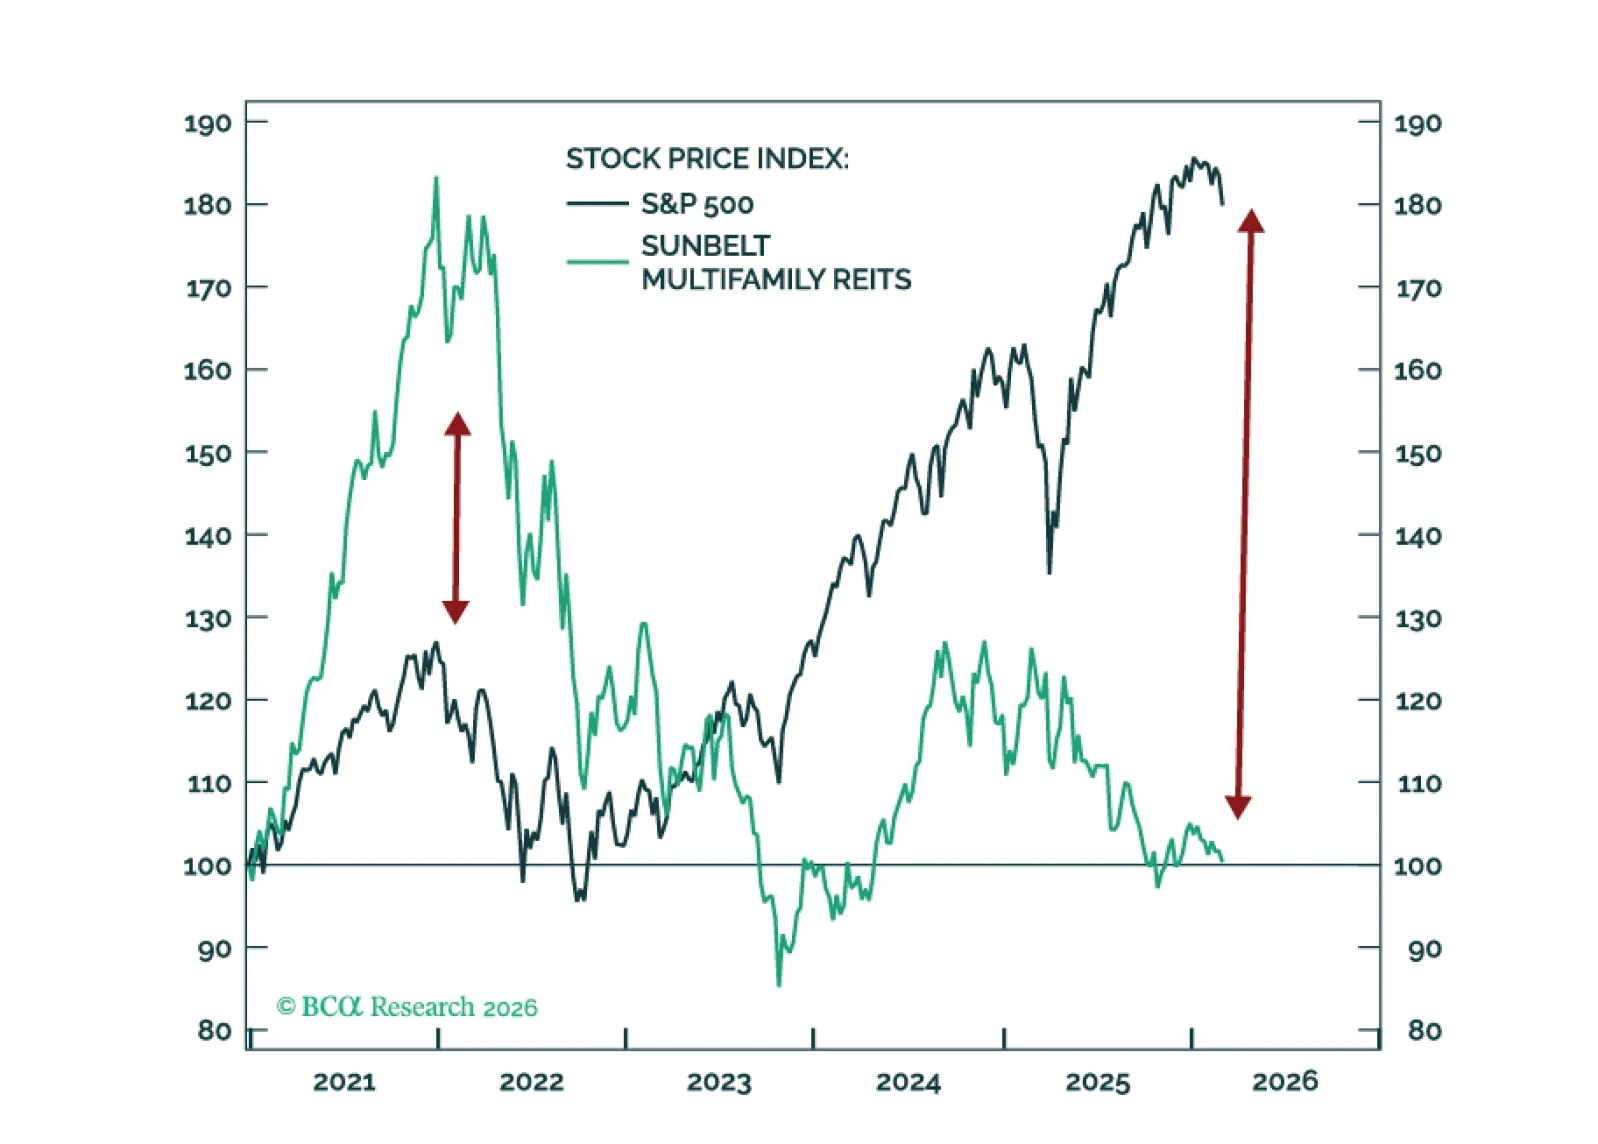

Everyone has opinions on Private Credit, but few have the data, and fewer have the objectivity. We give you both. In under 5 minutes, you will understand how we got here and, more importantly, how to allocate from here.
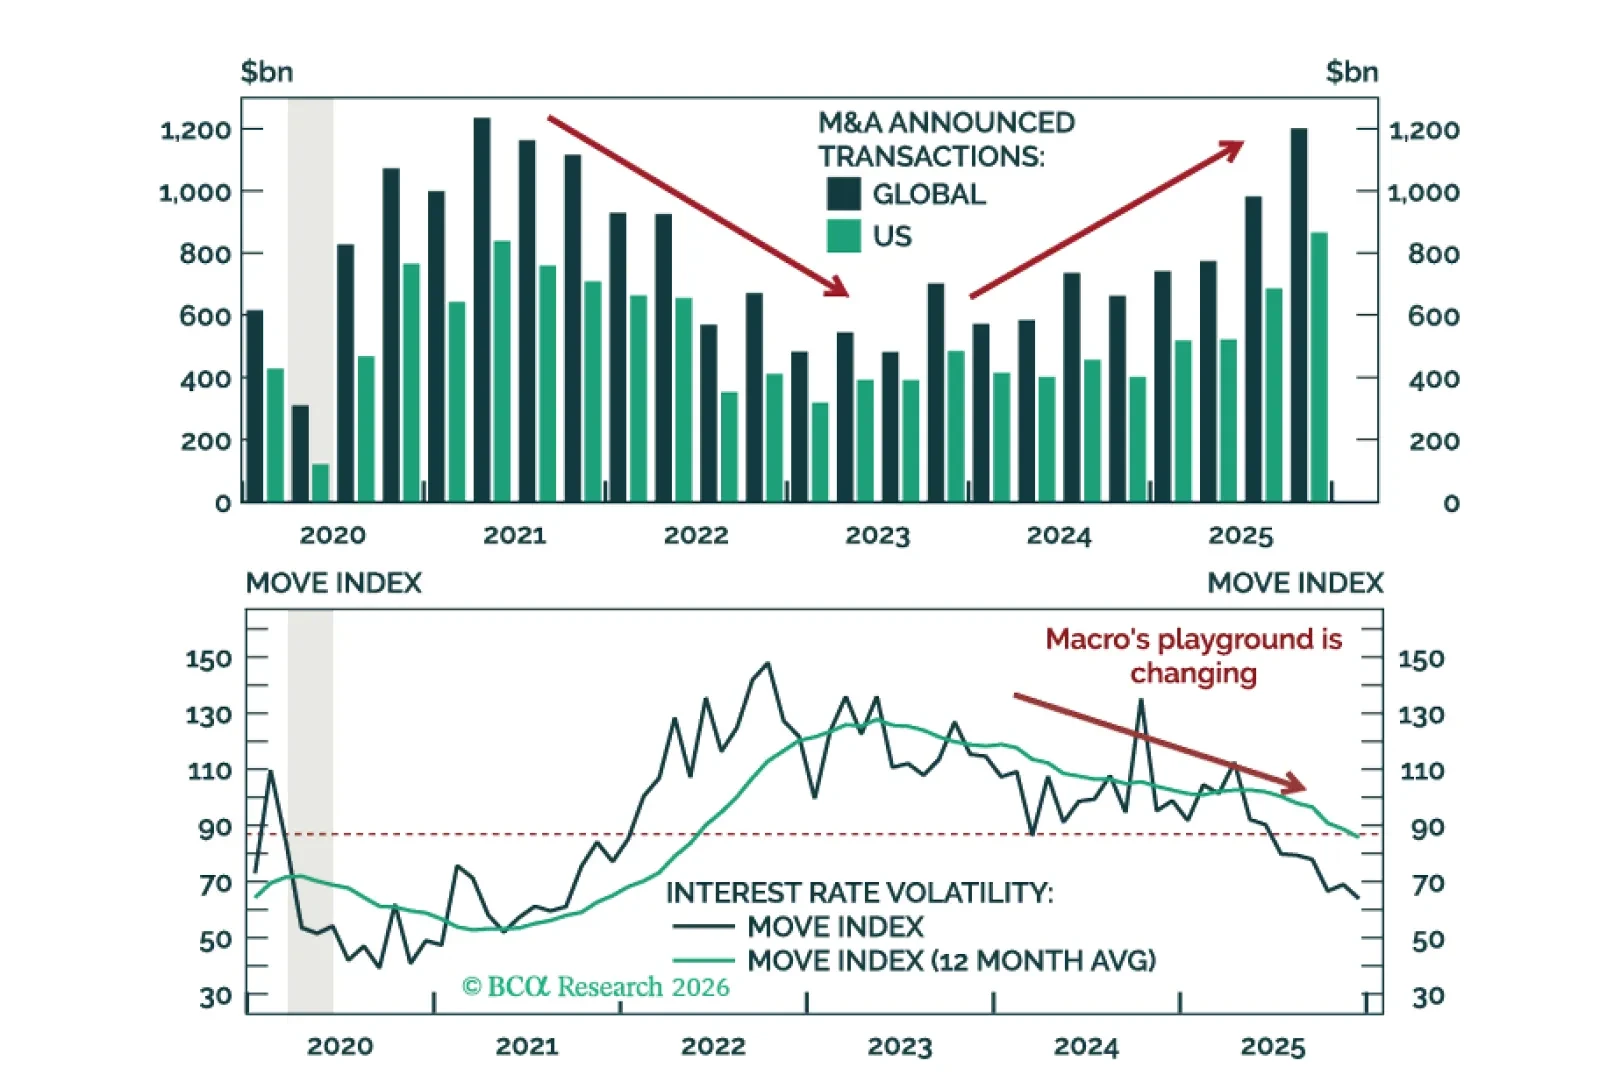
M&A activity finally reaccelerated in Q4 2025—it’s just the start. Macro Hedge Funds have outperformed with top-decile performance from Discretionary Macro—but that’s towards the end. We move Macro from overweight to underweight and Event Driven from neutral to overweight.
