 Portfolio
| Private Markets
Private equity, credit, real estate, and infrastructure, analyzed with the same macro lens BCA brings to public markets.
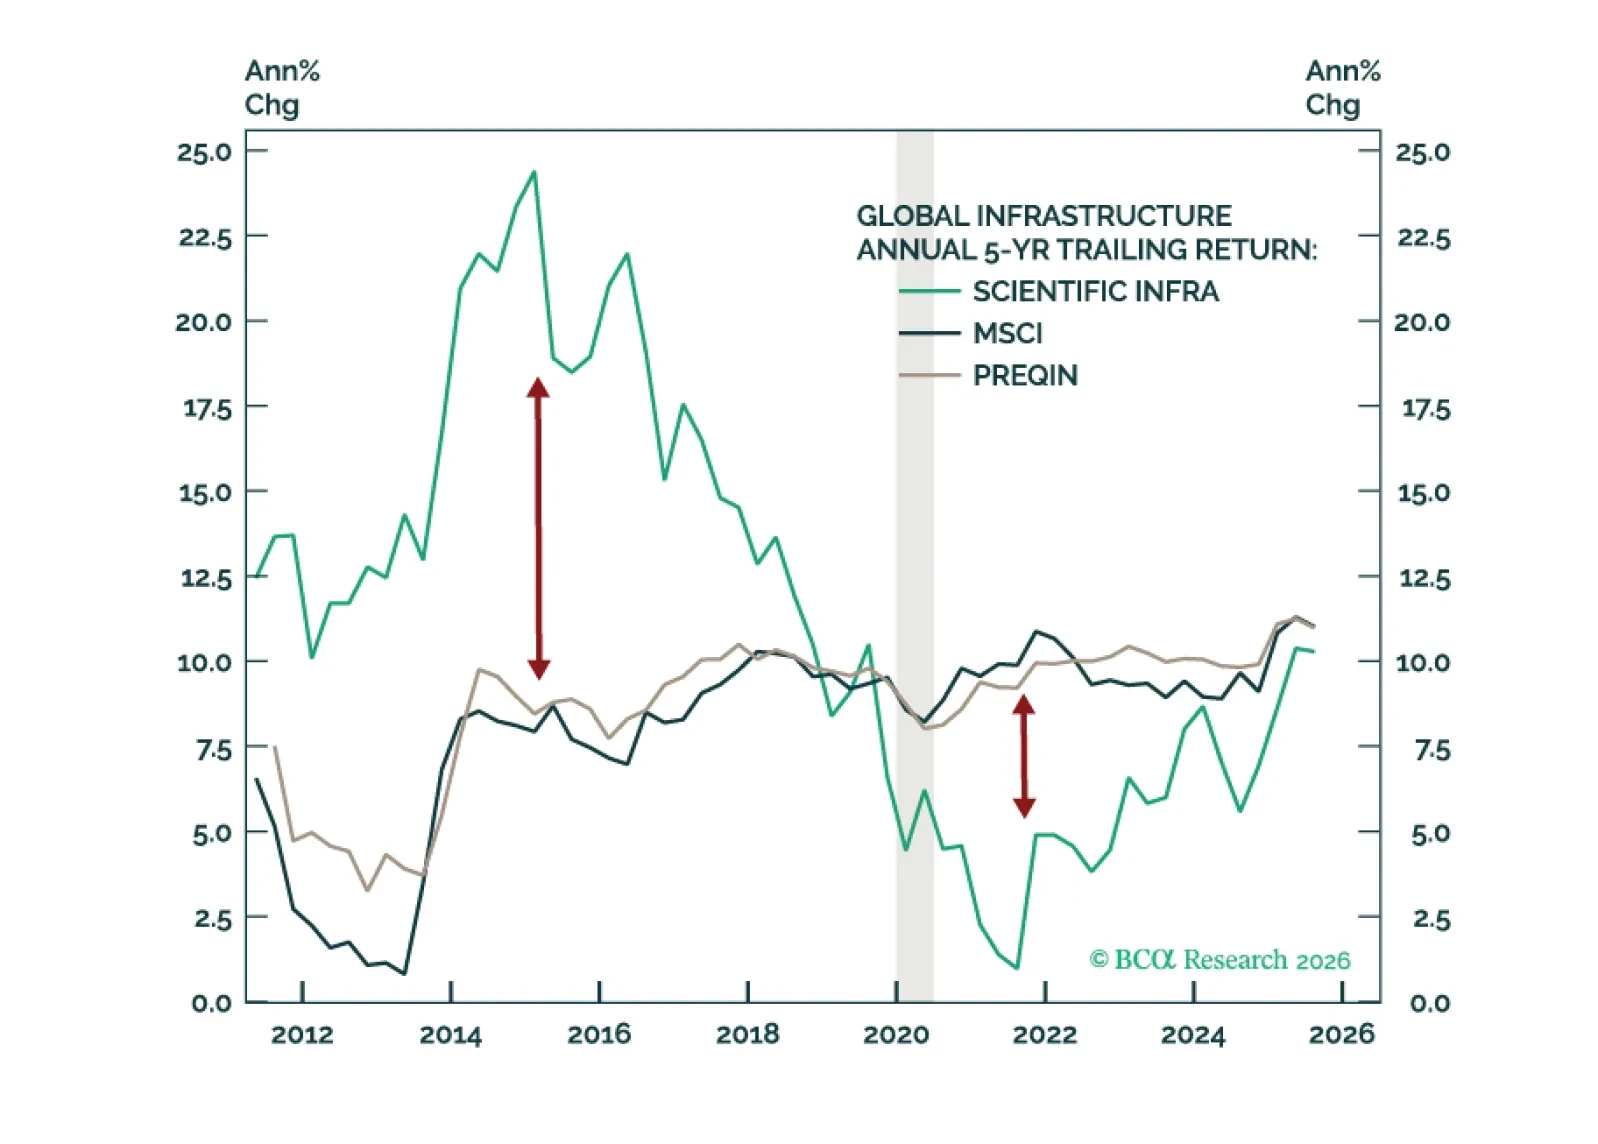
Private Infrastructure is the fastest growing alternative asset class. While metrics vary across data providers, differences largely reflect sector and regional mix. Core Infrastructure inflows have been strong, reversing declines seen in preceding years. Recent returns have been robust, and despite valuation dispersion, levels do not appear stretched.

The AI trade has broadened beyond Public Markets, pulling Private Credit deeper into the ecosystem. Investors are right to understand their overlapping exposures between Public Equities, Venture Capital, Data Centers, and now Private Credit. However, risks from rising Venture Capital Debt and Asset-Based Lending are going unnoticed.
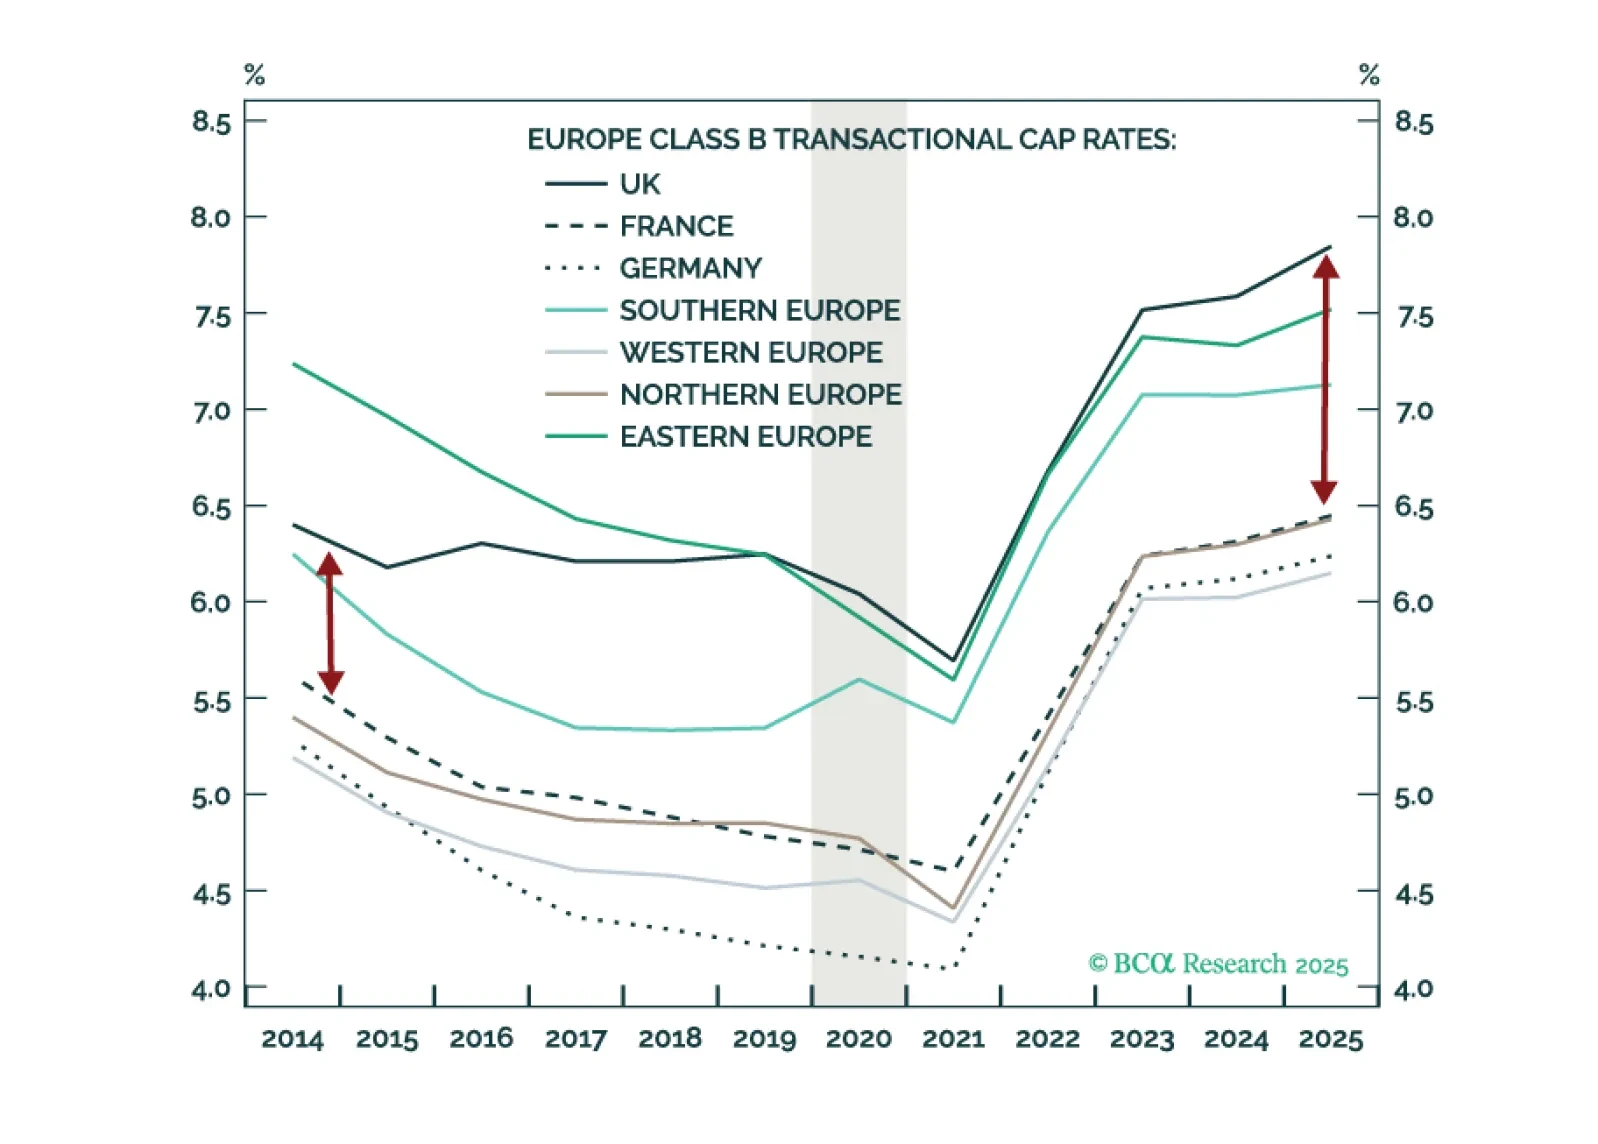
As in the US, Europe now offers compelling opportunities, albeit in different sectors and countries. Multifamily remains resilient amid structurally tight supply, while Industrial continues to cool. The most attractive opportunities are emerging in Office and Retail, where fundamentals are beginning to turn.
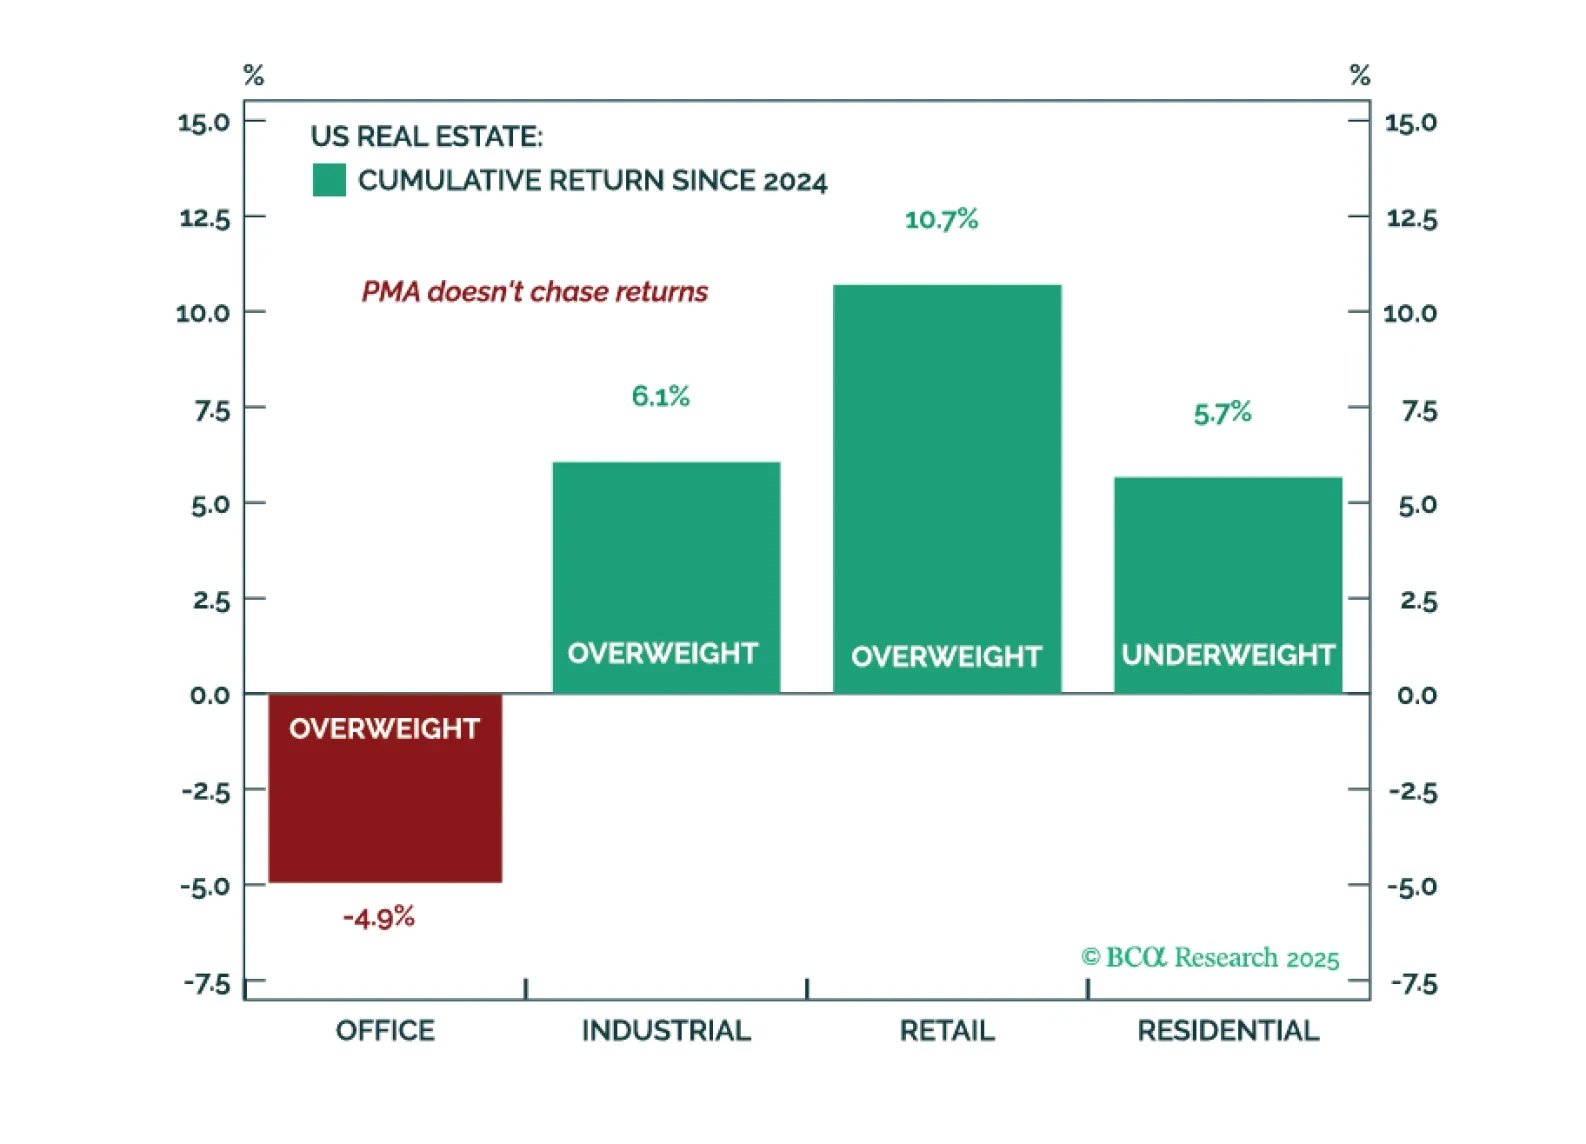
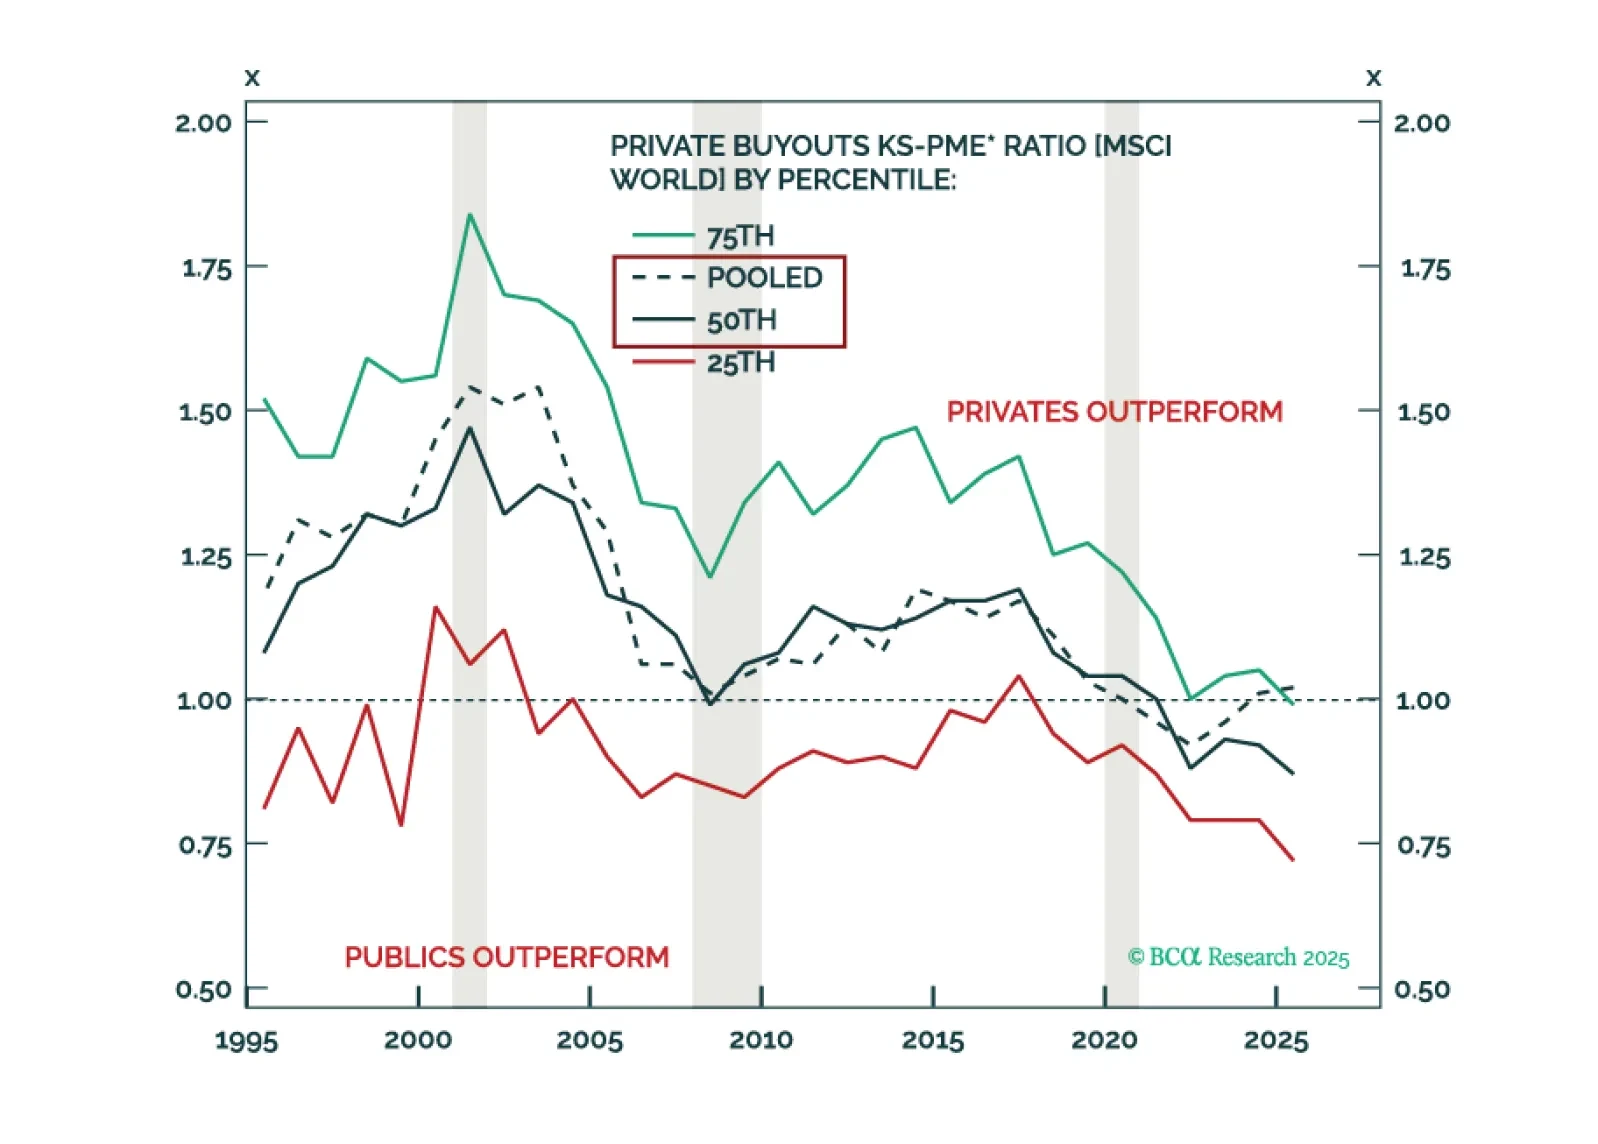
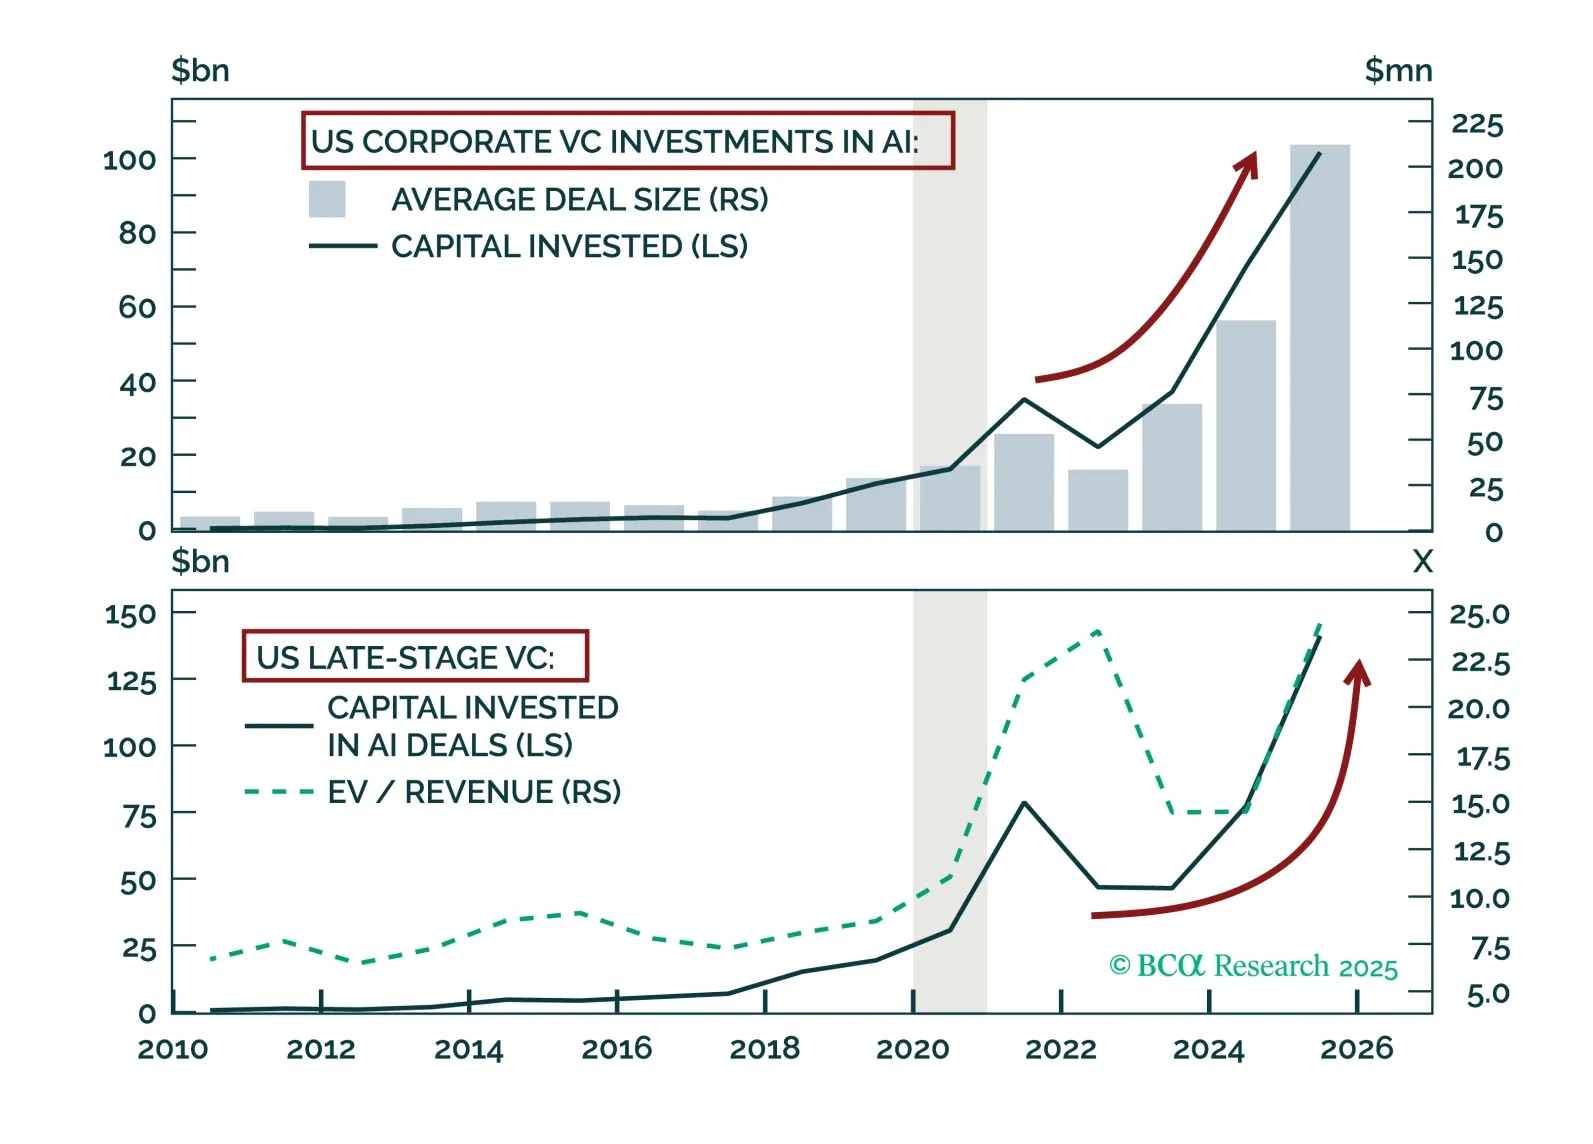
Our latest chartpack provides a comprehensive view across asset classes, highlighting current positioning, risks, and opportunities. Real Estate remains our highest conviction asset class. Private Credit will remain in the headlines amid stresses from 2020–2021 loan vintages. In Late-Stage Venture Capital, AI-related risks continue to build, while an improving US IPO market contends with a softening labor backdrop. Buyouts remain a key focus as the distribution bottleneck persists, setting the stage for improved entry opportunities.
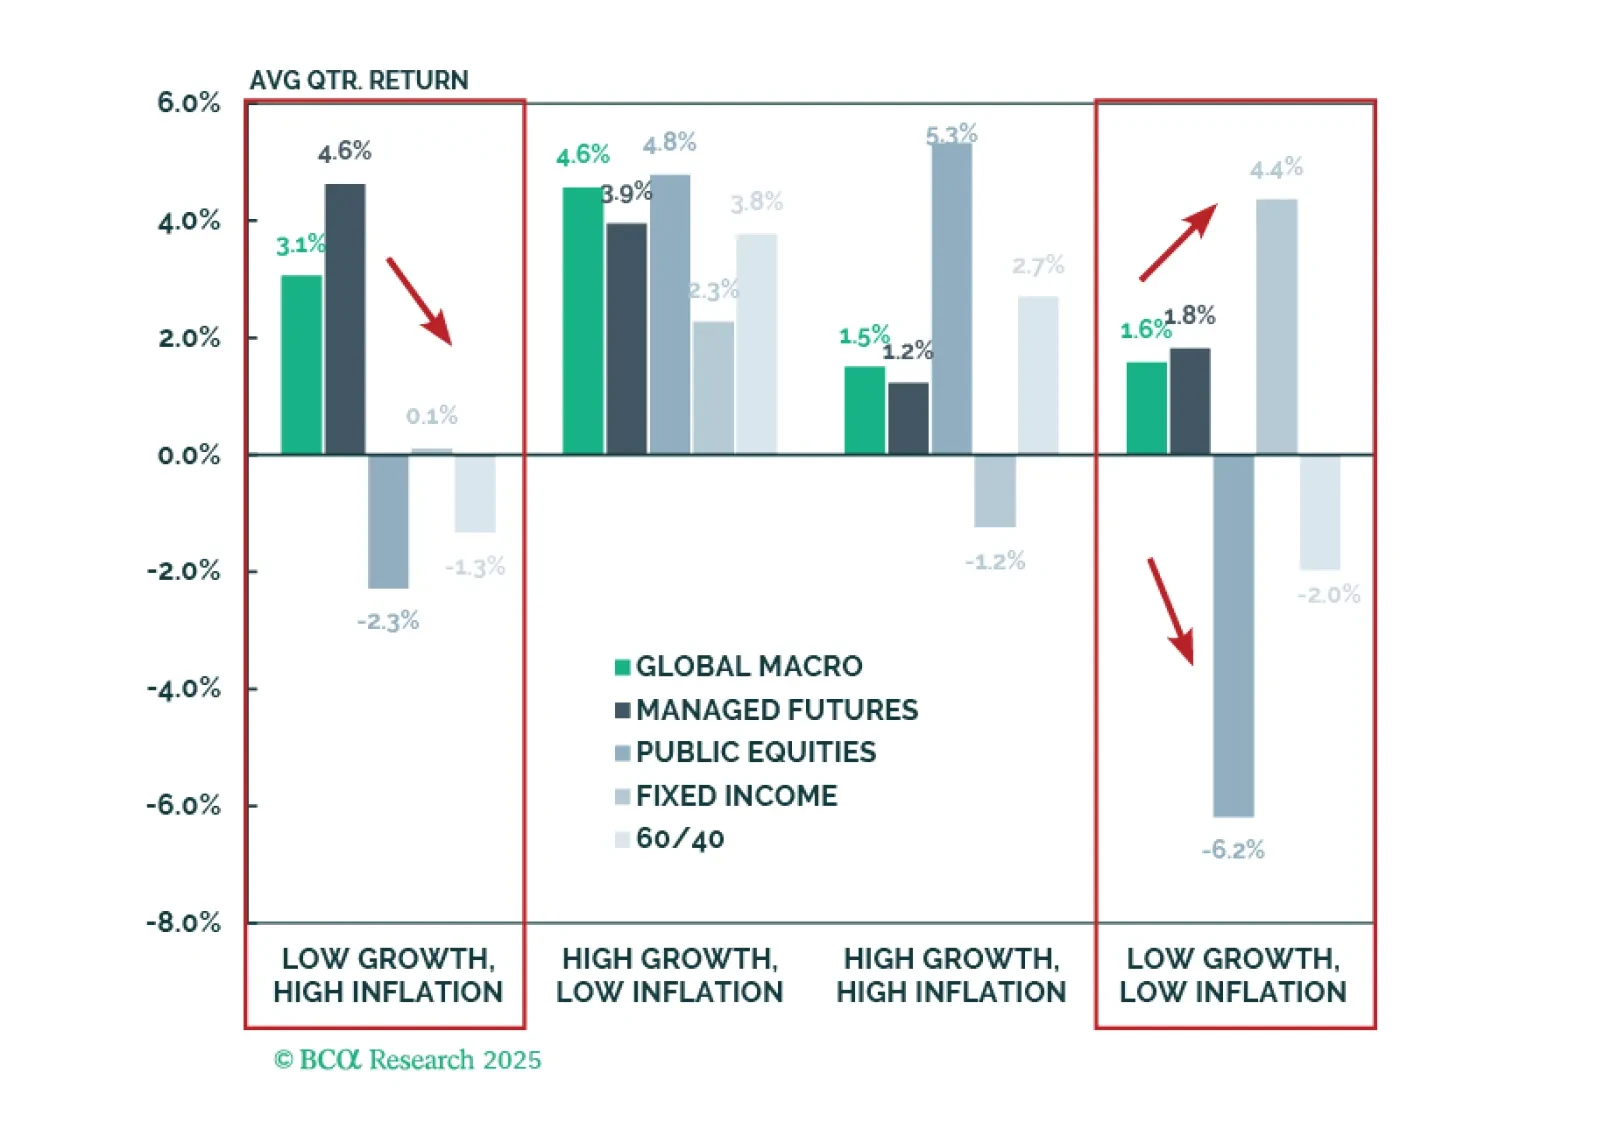
Understanding asset performance across Growth and Inflation regimes helps investors construct and manage balanced portfolios. Our first G&I Catalog report examines Hedge Fund strategies. Global Macro and Managed Futures offer the strongest protection in Stagflation-like periods, when traditional assets typically struggle. Since 1998, these regimes have occurred less than 10% of the time—but that may not hold true going forward.
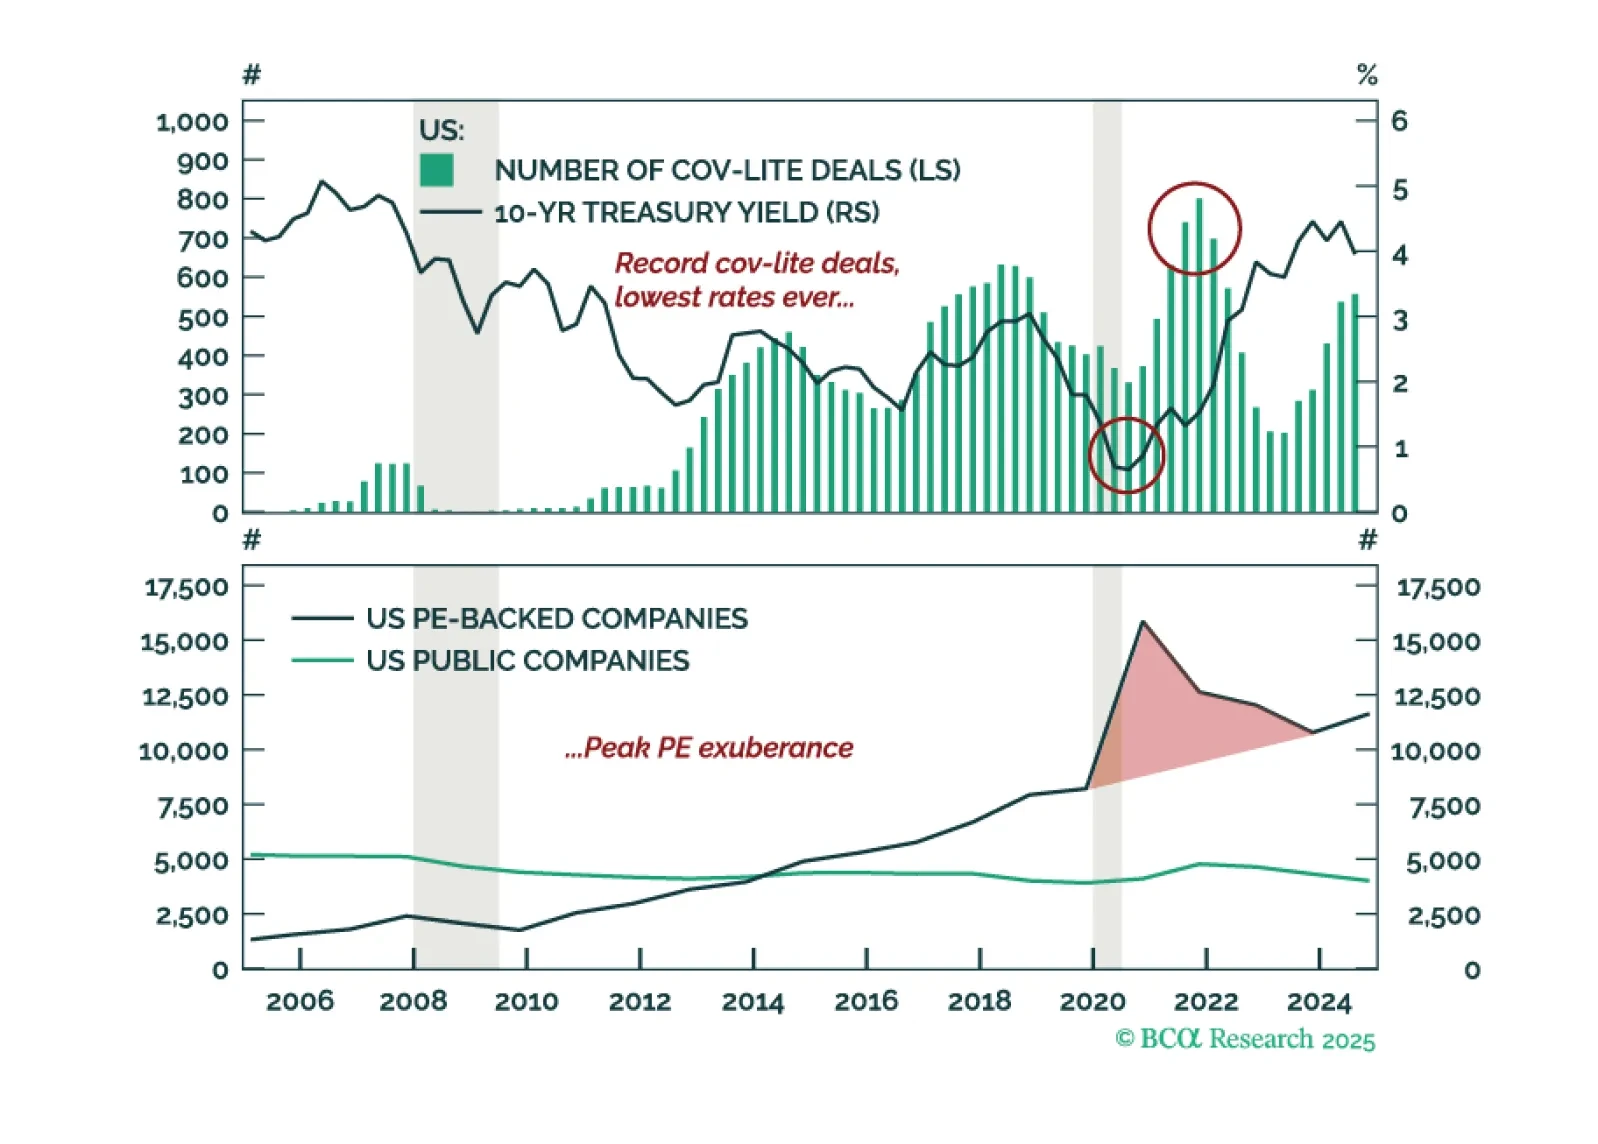
Private Credit outsiders are skeptical, insiders are believers—but are becoming nervous now. In the highlight of this Quarterly Report, we dig beneath the surface to uncover the buried bodies in Private AND Public Credit. The ghosts of 2020-2021 loan originations are catching up with investors.
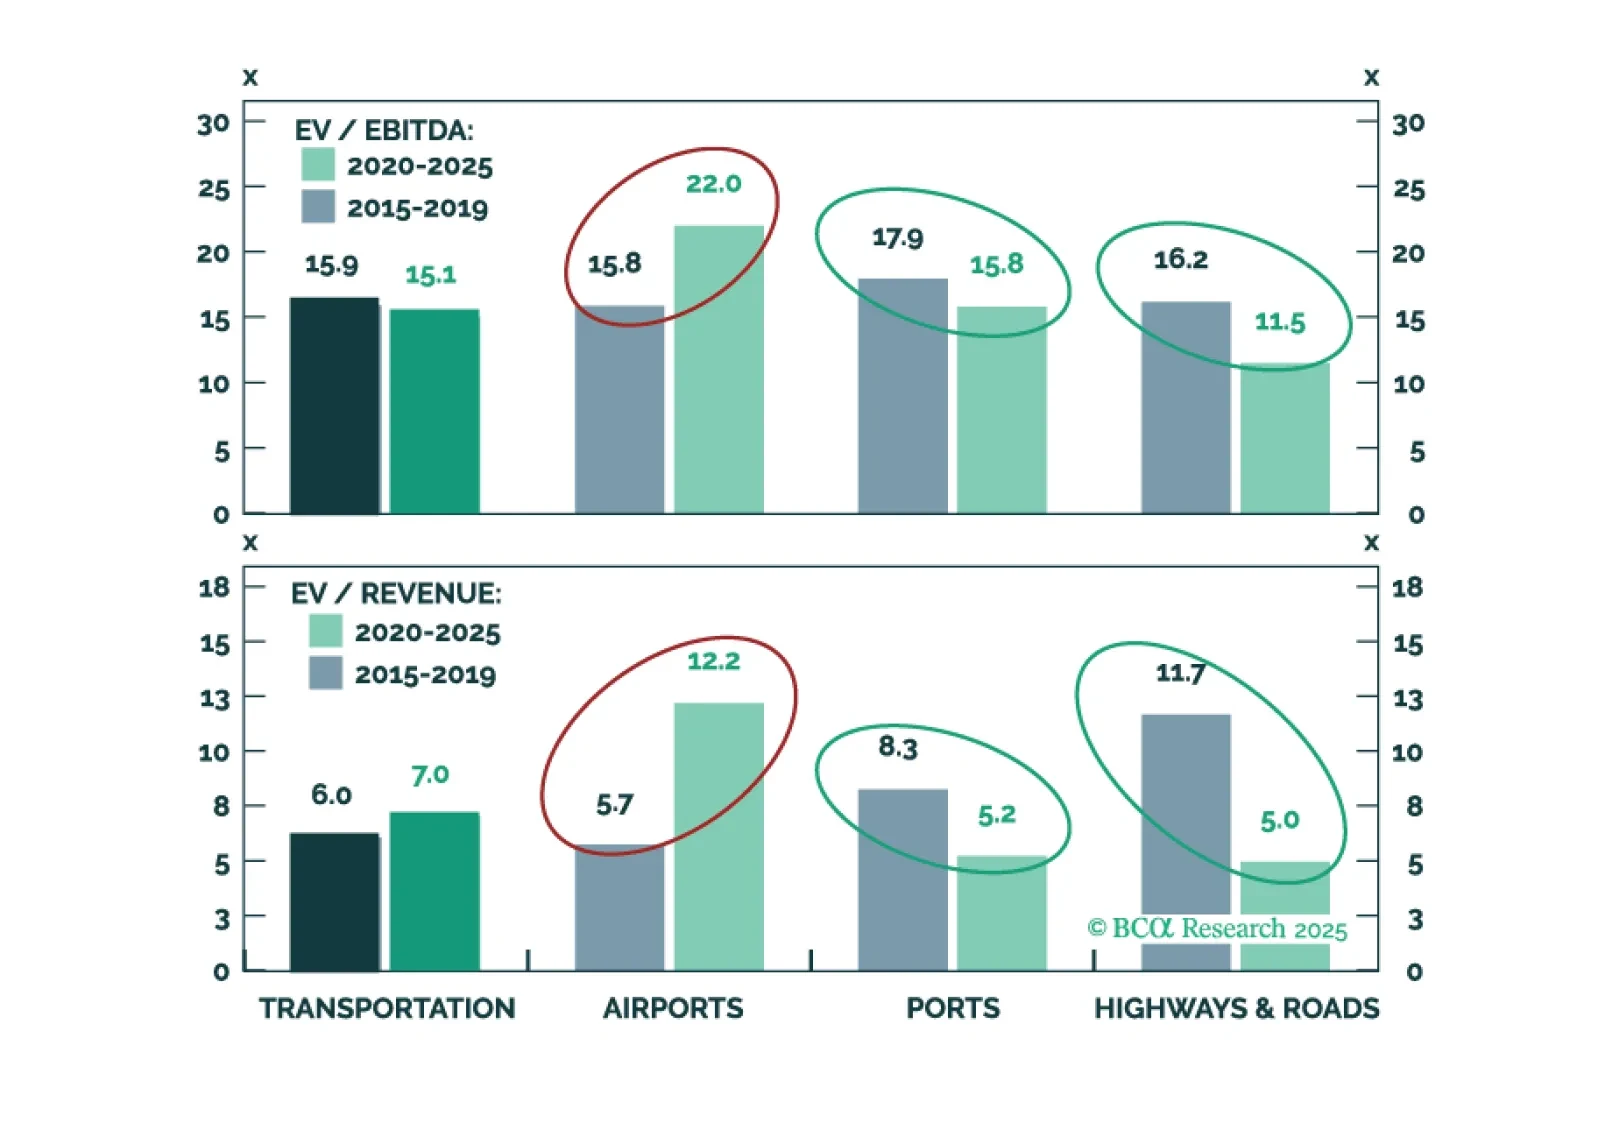
While Transportation Infrastructure is intuitive to grasp, its cash flow dynamics are often less understood. This educational report examines cash flow drivers across sectors, highlighting both macro and micro influences. Current opportunities are strongest in Ports and Highways & Roads over Airports.
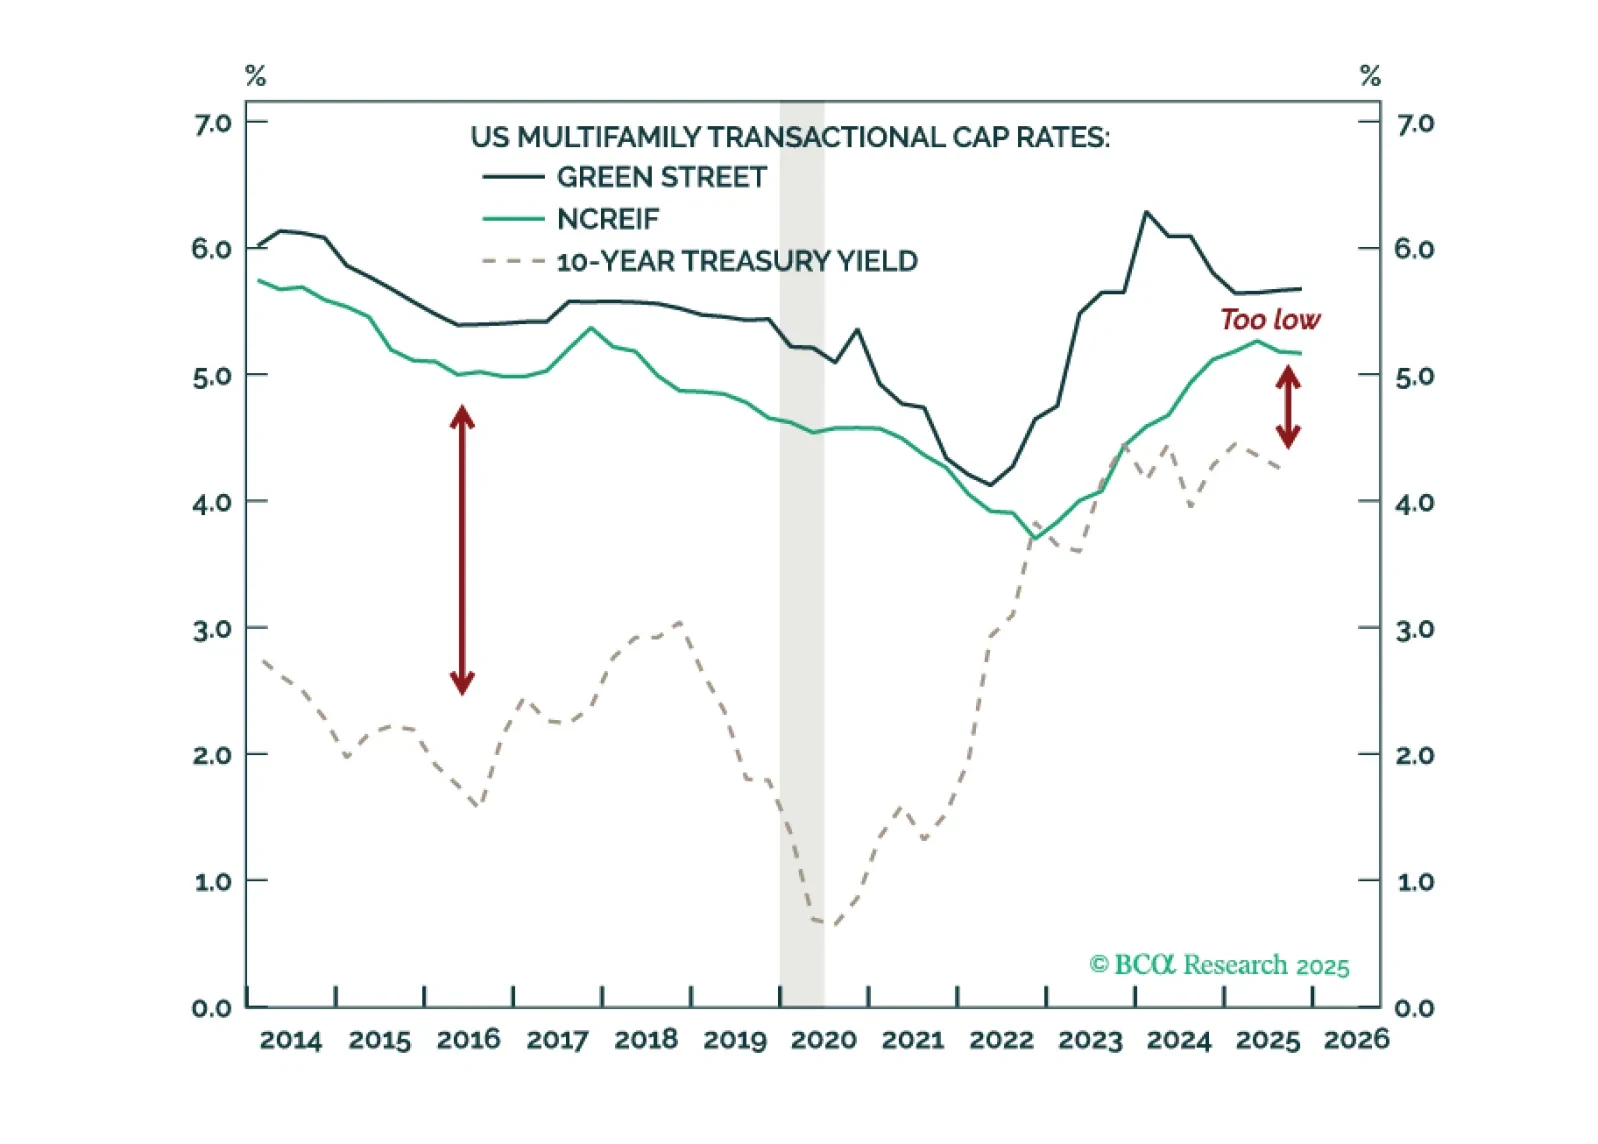
US Real Estate has been under pressure post-2022. This chartpack offers a snapshot of the cap rate cycle across measures, sectors, and cities. Industrial and Multifamily spreads remain tight while Office and Retail have peaked. Chicago and Houston differ as cities, but their Real Estate trends look increasingly alike.