 Portfolio
| Private Markets
Private equity, credit, real estate, and infrastructure, analyzed with the same macro lens BCA brings to public markets.
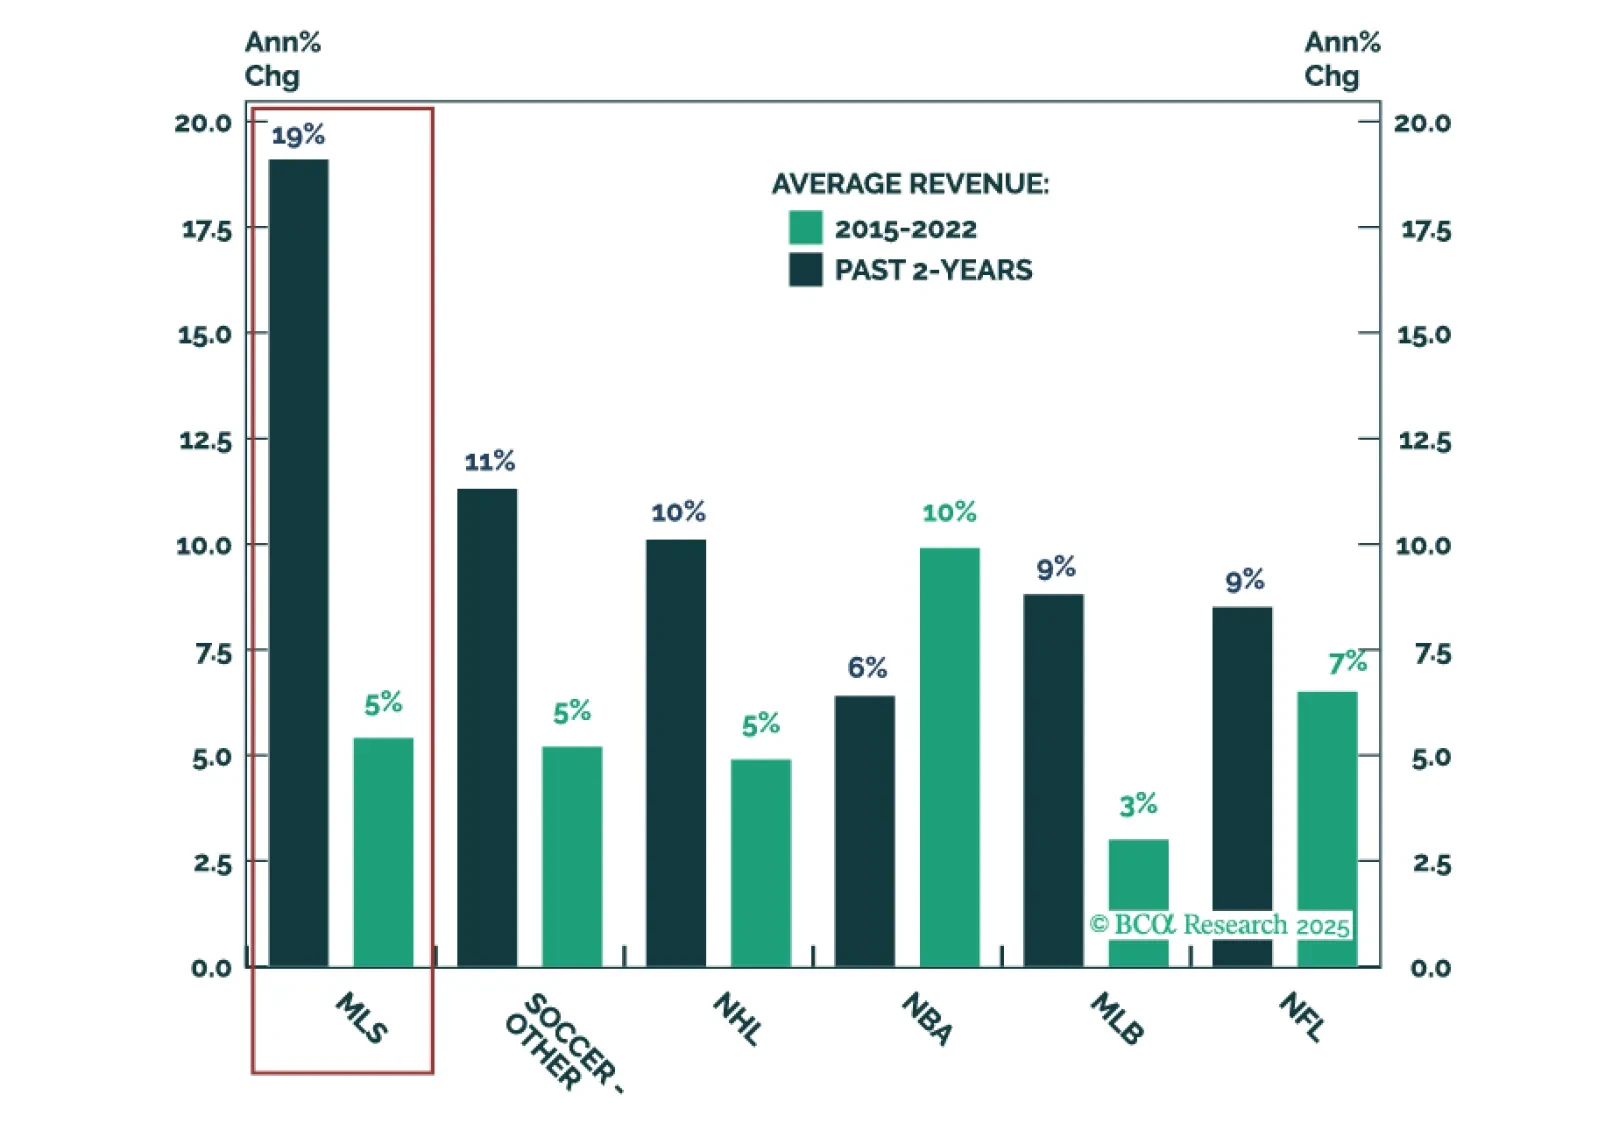
The NFL and NBA grab the headlines, but growth beats size. This report reveals the story behind Major League Soccer (MLS) growth. Valuations have jumped, yet plenty of upside remains—making the MLS relatively attractive compared to other US major leagues.
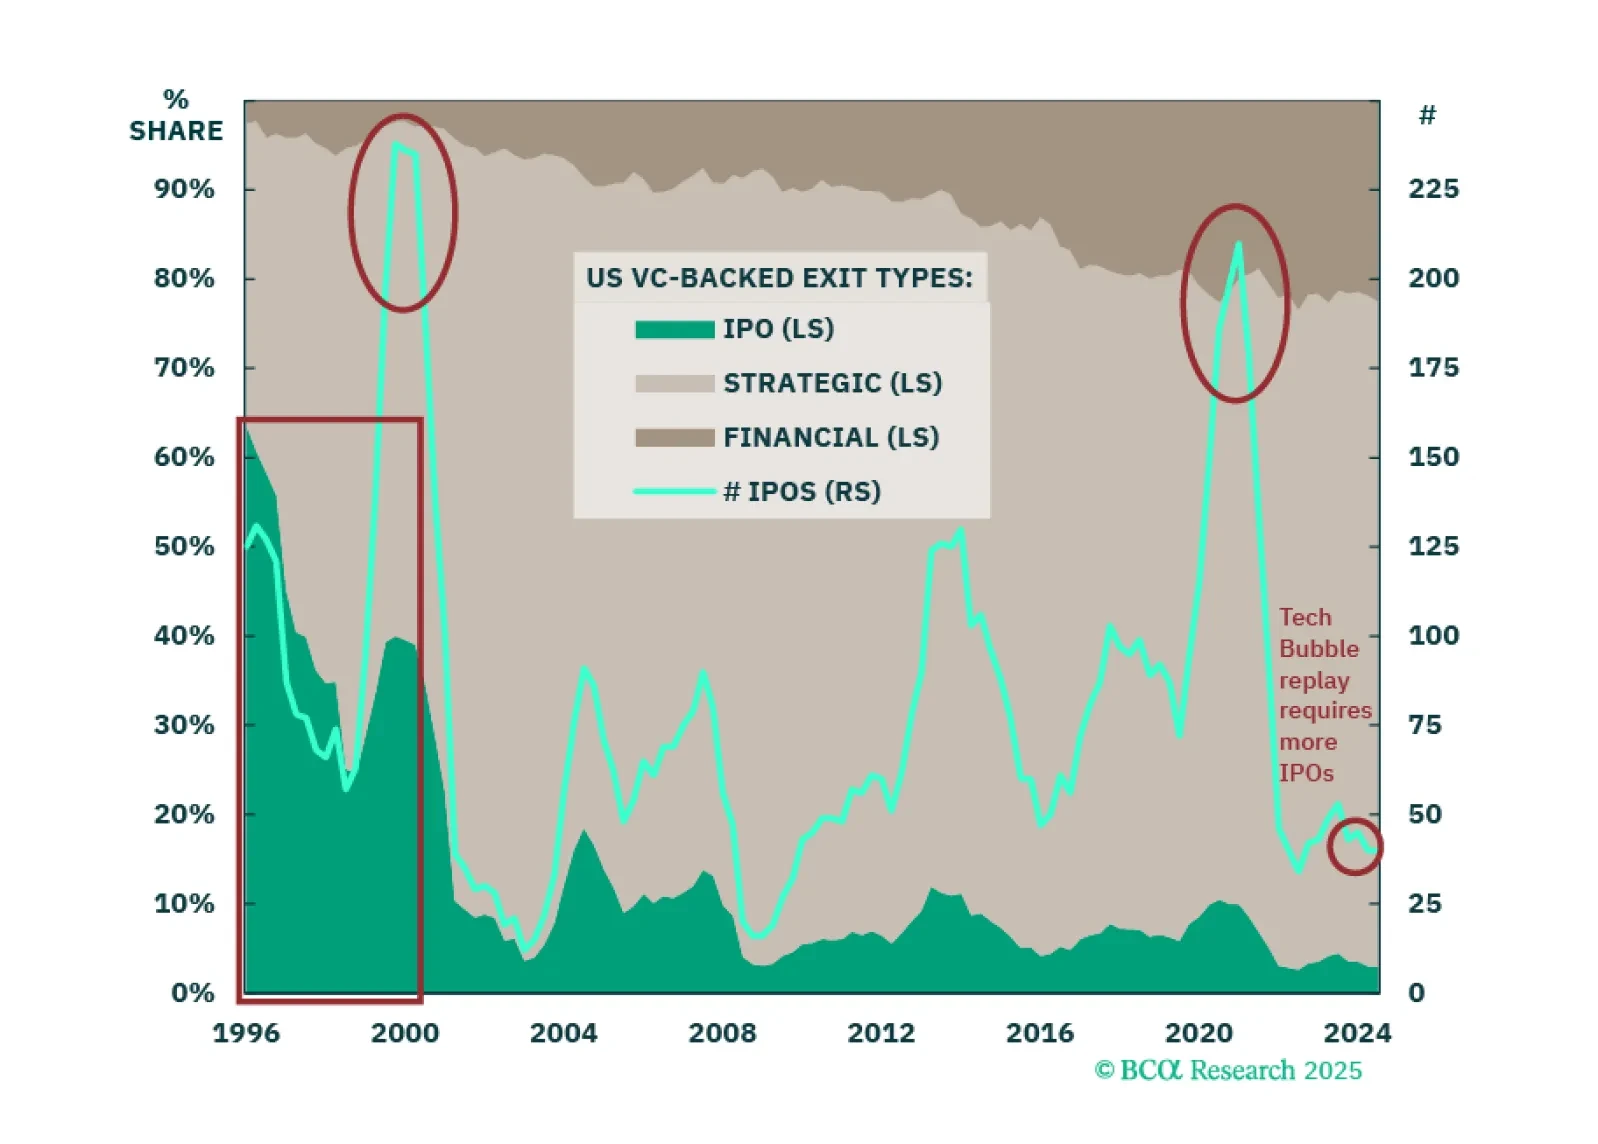
In 7 charts and under 1,000 words, we reveal the real story behind AI Venture Capital. Valuations are not at extremes and IPOs do not signal a replay of the 2000 Tech Bubble—yet.
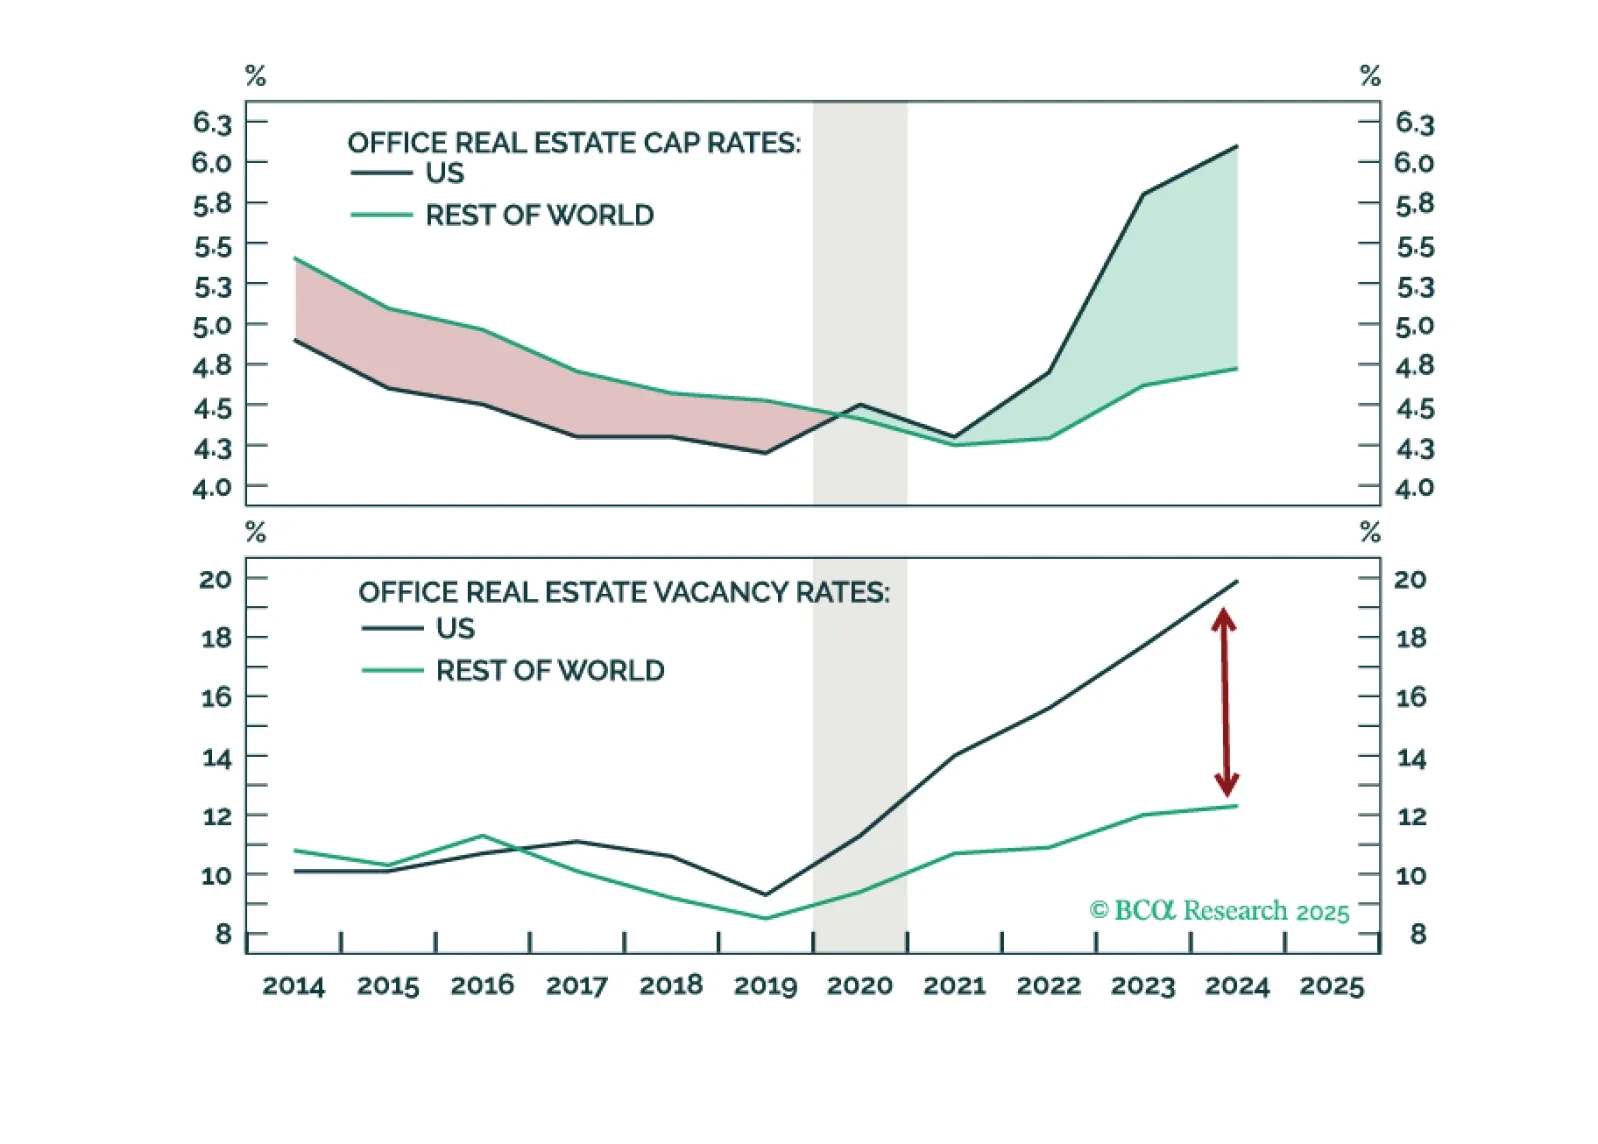

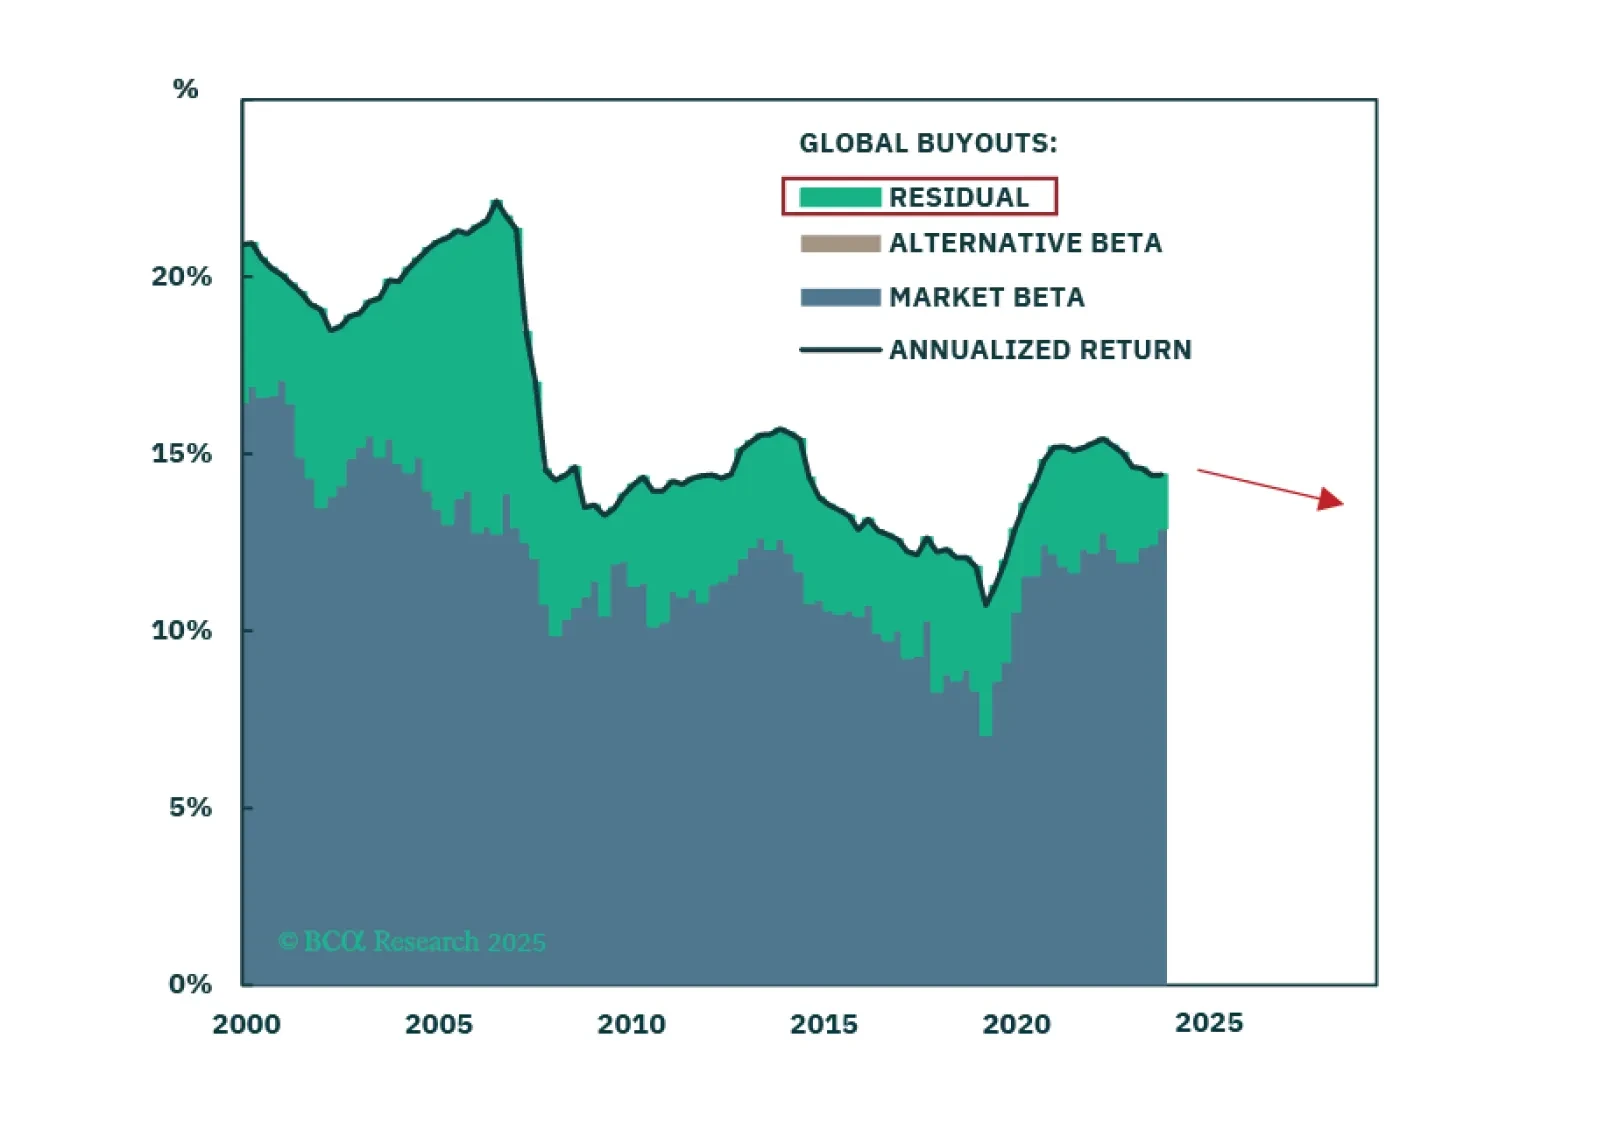
European euphoria is overdone. The most exceptional asset class in Europe is Infrastructure, but granular opportunities span other asset classes by sector and country. Venture Capital is a North America and Asia-Pacific play. We downgrade Private Credit, and upgrade Global Buyouts. Time to take profits on Long-Short Equity Hedge Funds.

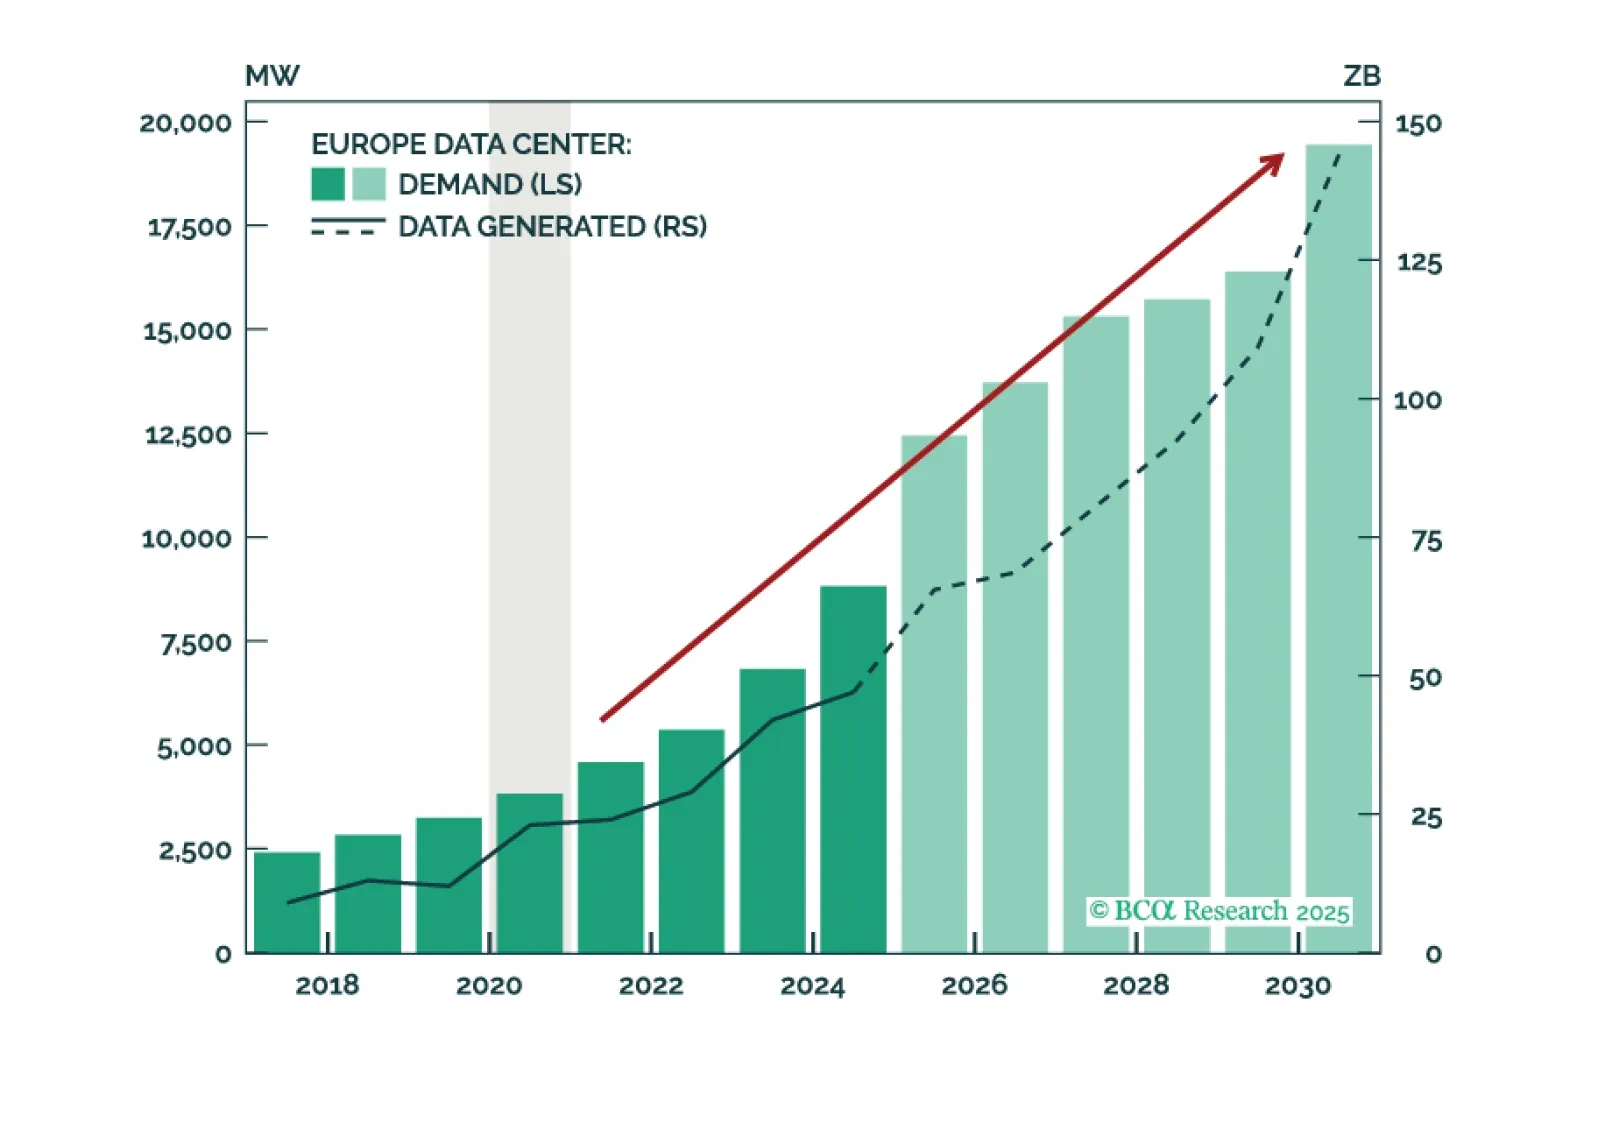
While the US is the pioneer, Europe will follow suit—more rapidly than expected. It is not a question of if GenAI will boom in Europe, but when. Europe’s Data Center growth is already strong today, but a US-style boom is just around the corner.

Private Credit return expectations edge lower. Middle Market Direct Lending remains attractive, rivaling Middle Market Buyouts.
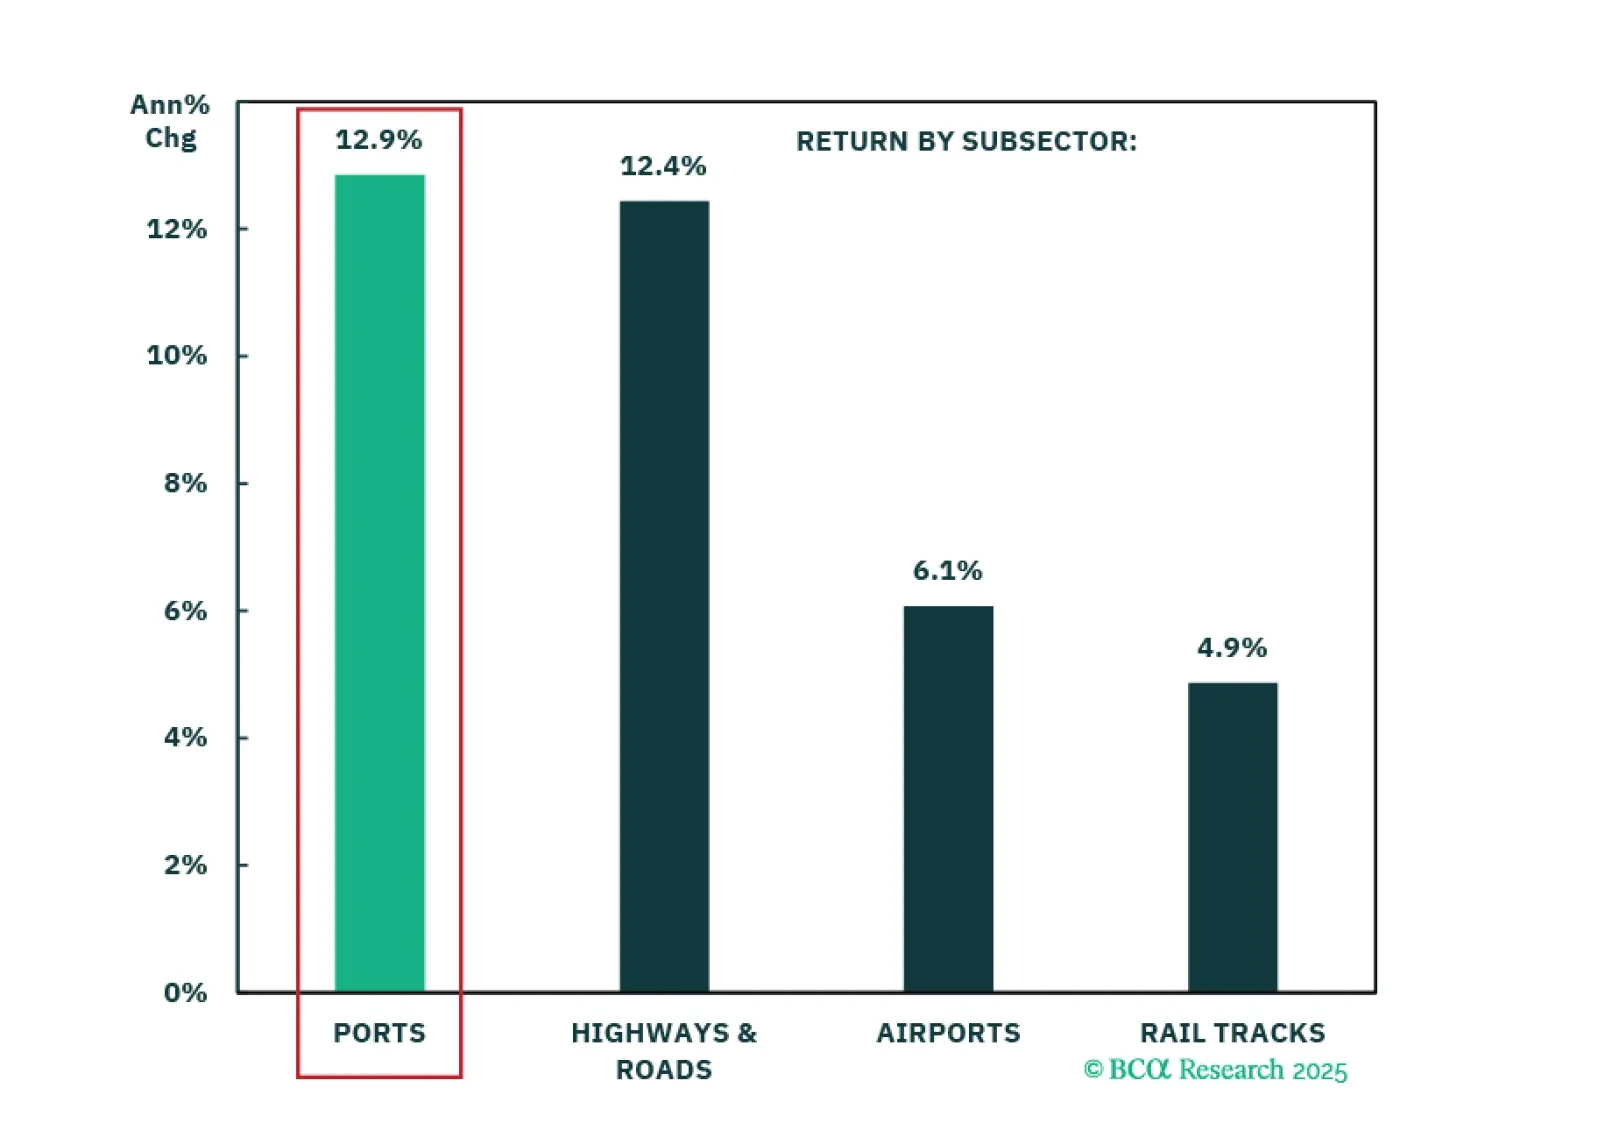
The US will continue to lead global trade, but the past winners from China-US tensions face decline. Reglobalization is underway. India Port Infrastructure will be a long-term winner.

Tariffs may trigger the recession, but the economy was already vulnerable from unsustainable growth and inflated expectations. Private Equity is most exposed, though this situation neither emerged suddenly nor will it unfold overnight. Our recommendations remain largely unchanged as market conditions increasingly align with our outlook.