 Portfolio
| Private Markets
Private equity, credit, real estate, and infrastructure, analyzed with the same macro lens BCA brings to public markets.
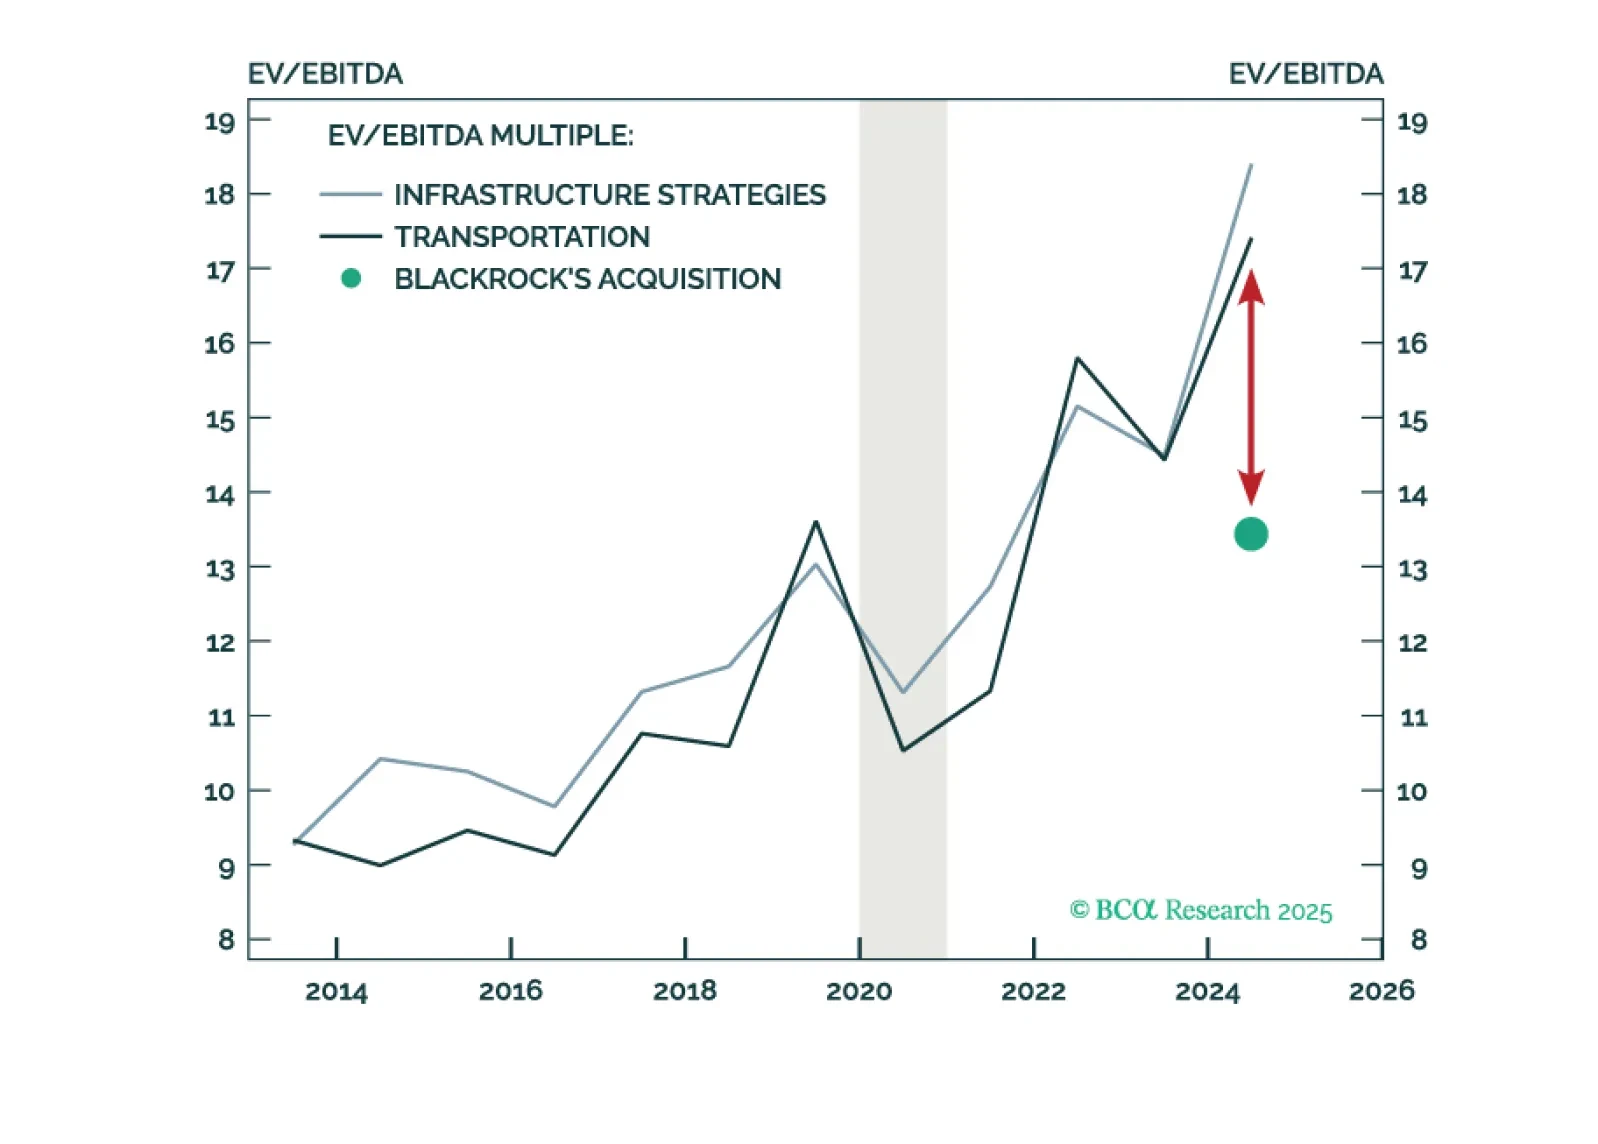
The ports that BlackRock acquired on both sides of the Panama Canal appear to be a bargain in terms of the entry valuation. But are the risks being appropriately compensated? In this prefatory report, we prepare investors for our upcoming Infrastructure reports, which will highlight geopolitical risk factors in this private asset class rarely encountered in others.
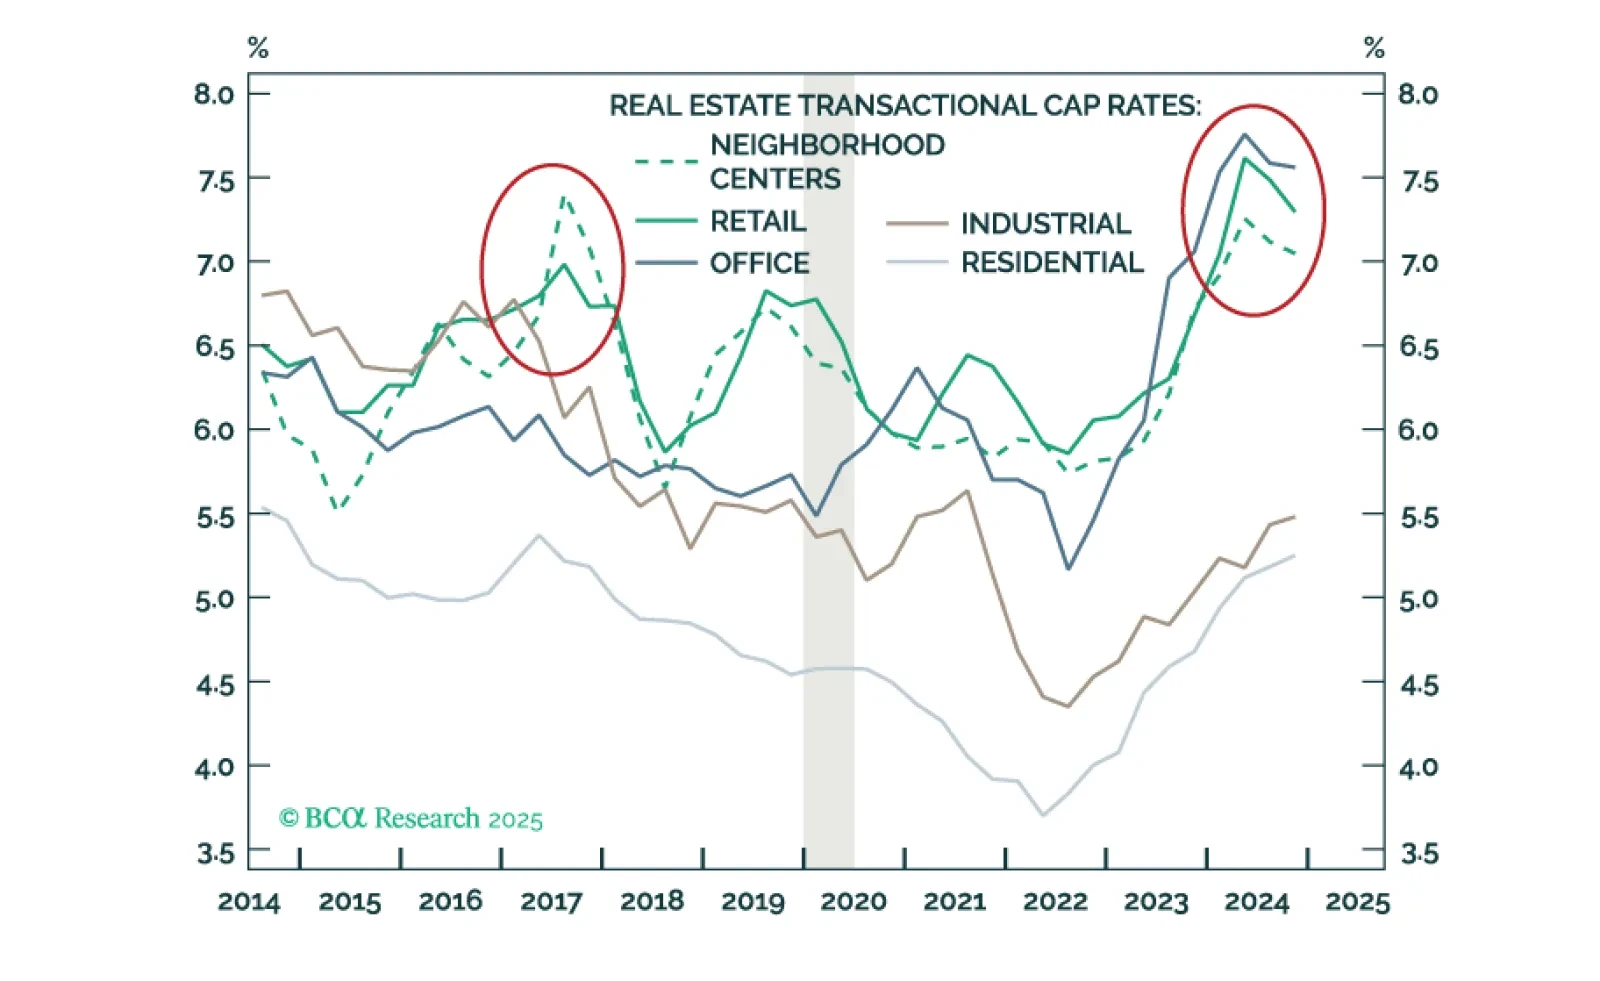
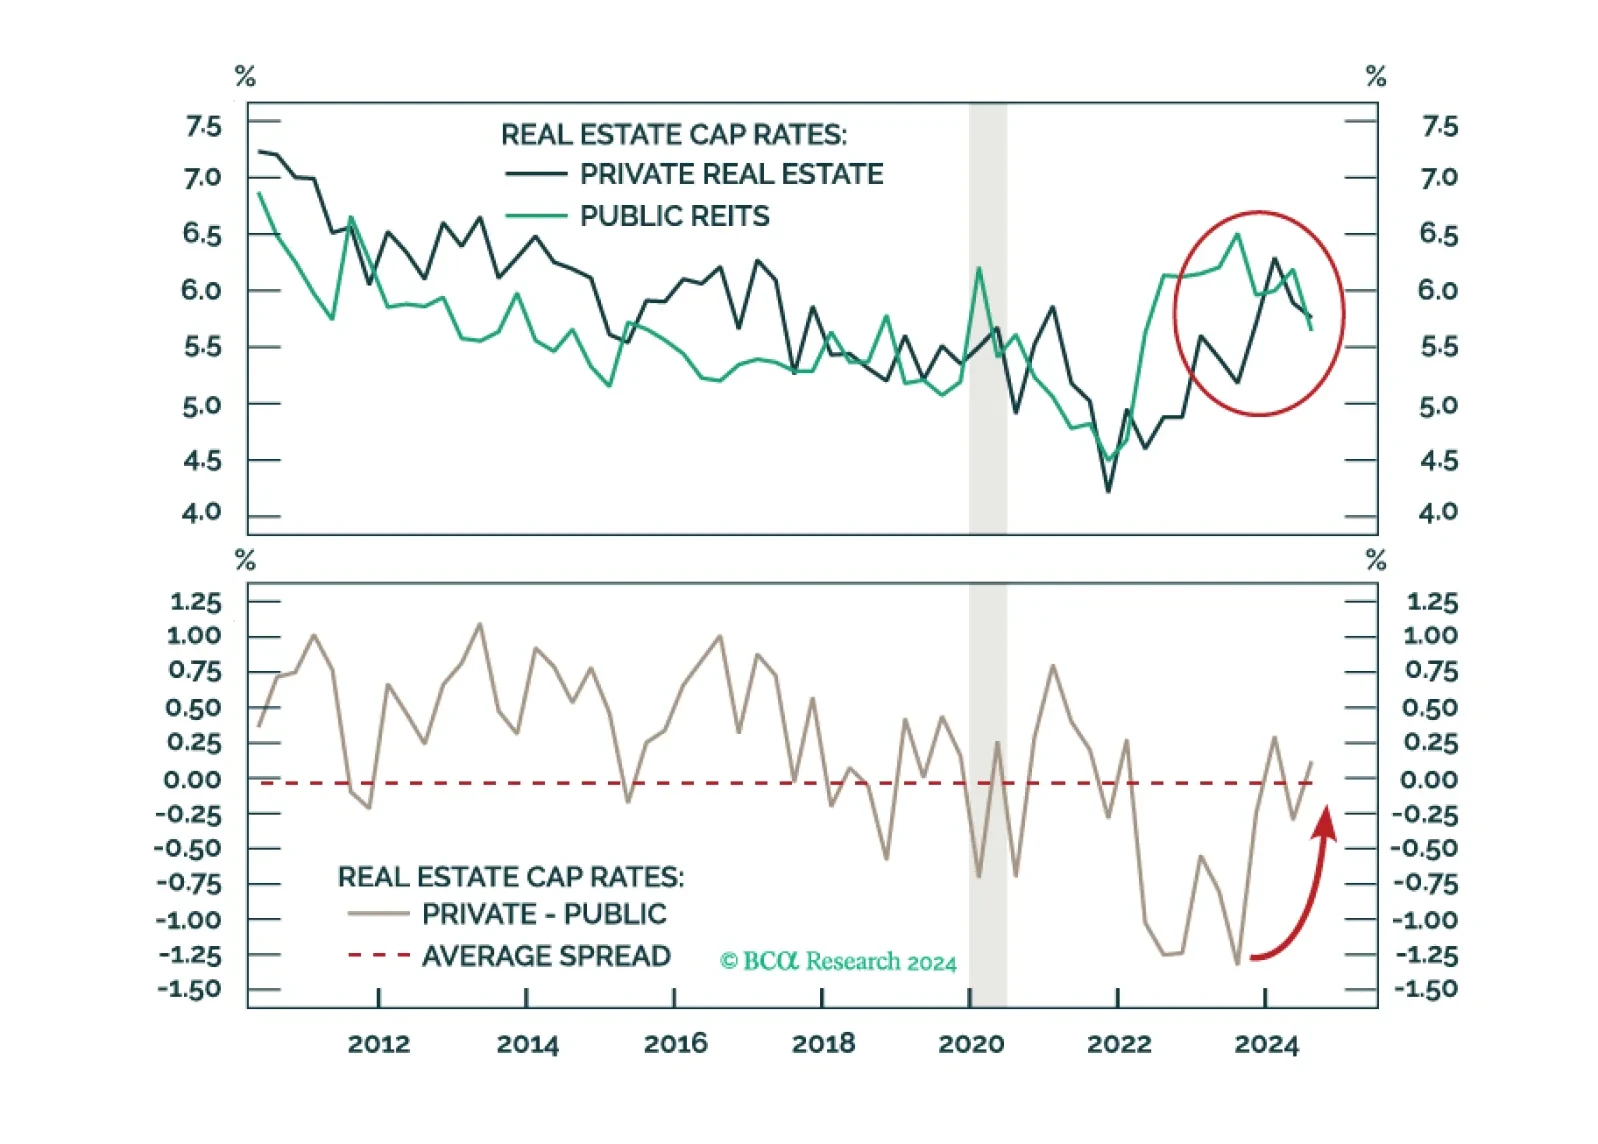
It is time to bet on brick-and-mortar again. The next time you step around your partner's Amazon package on your way to a physical store, consider this: Rock-bottom investor expectations, attractive initial fundamentals, and ongoing demographic shifts make Retail Real Estate a buy for the first time in a decade.
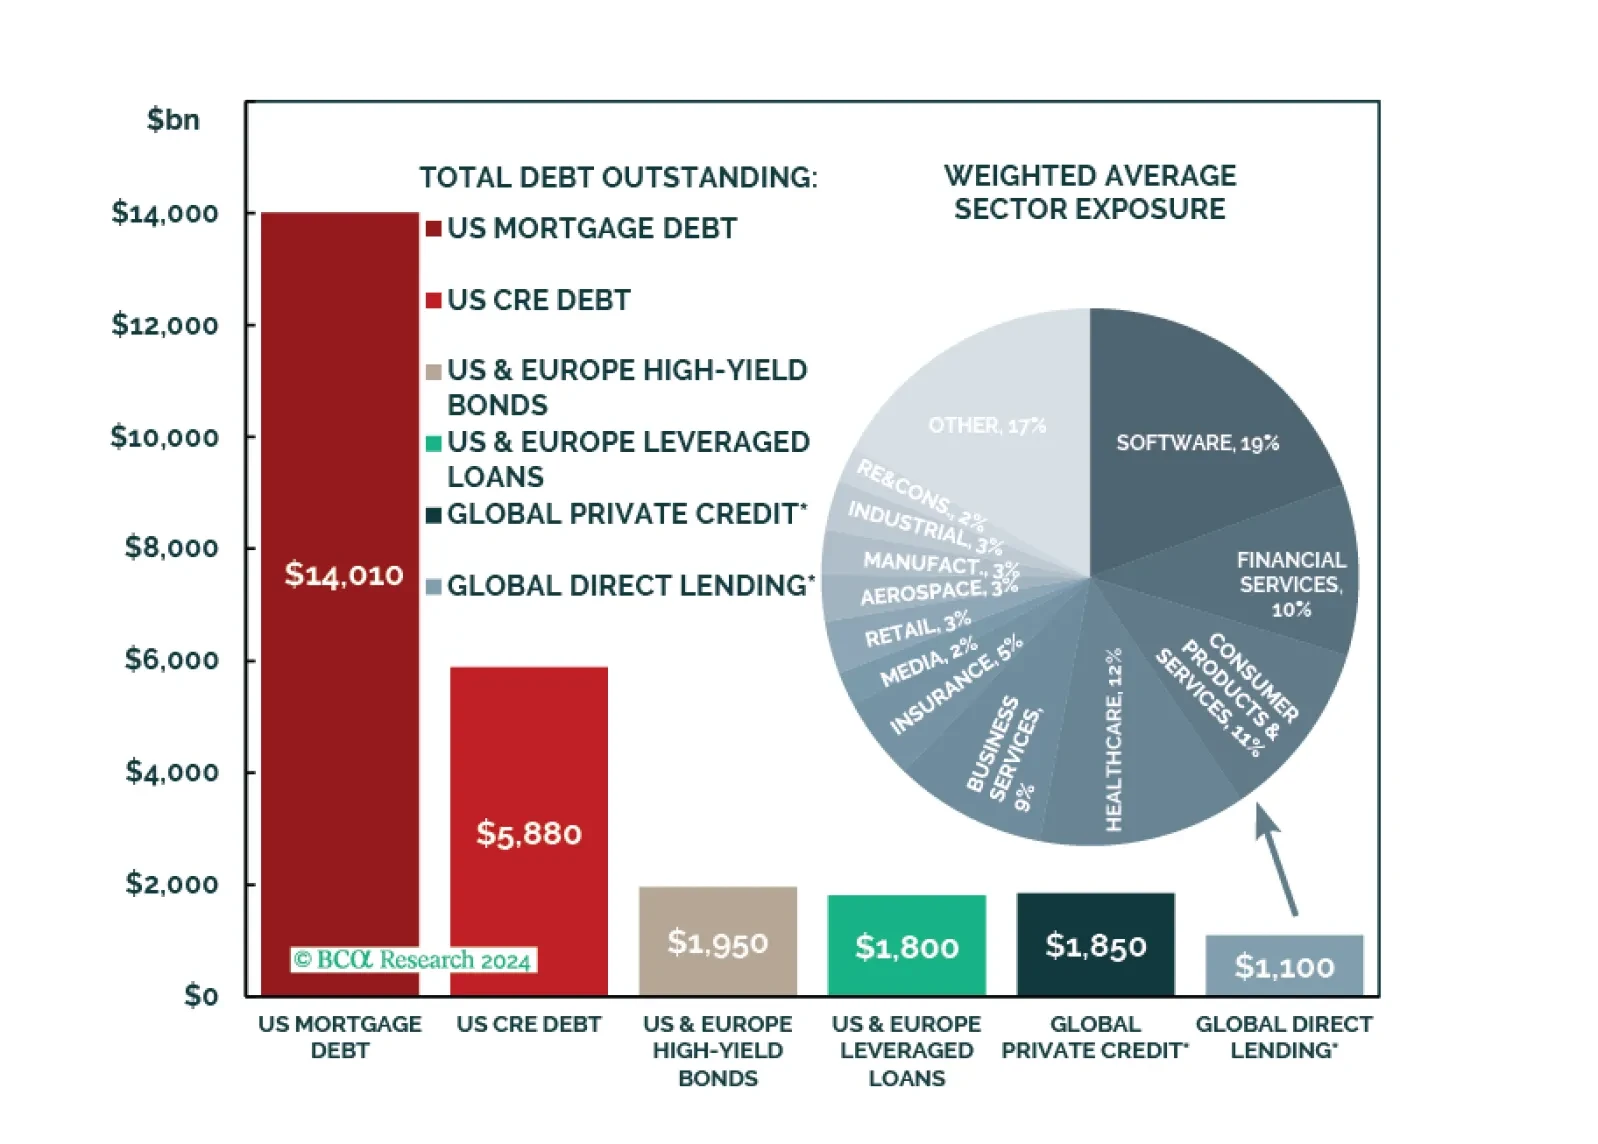
Understanding the risks across Private Credit will enable investors to be offensive, not just with sizing but across their total portfolio. Senior Direct Lending is not risk-free, Private Credit is not systemic, and a liquidity crisis will not be born in this asset class.
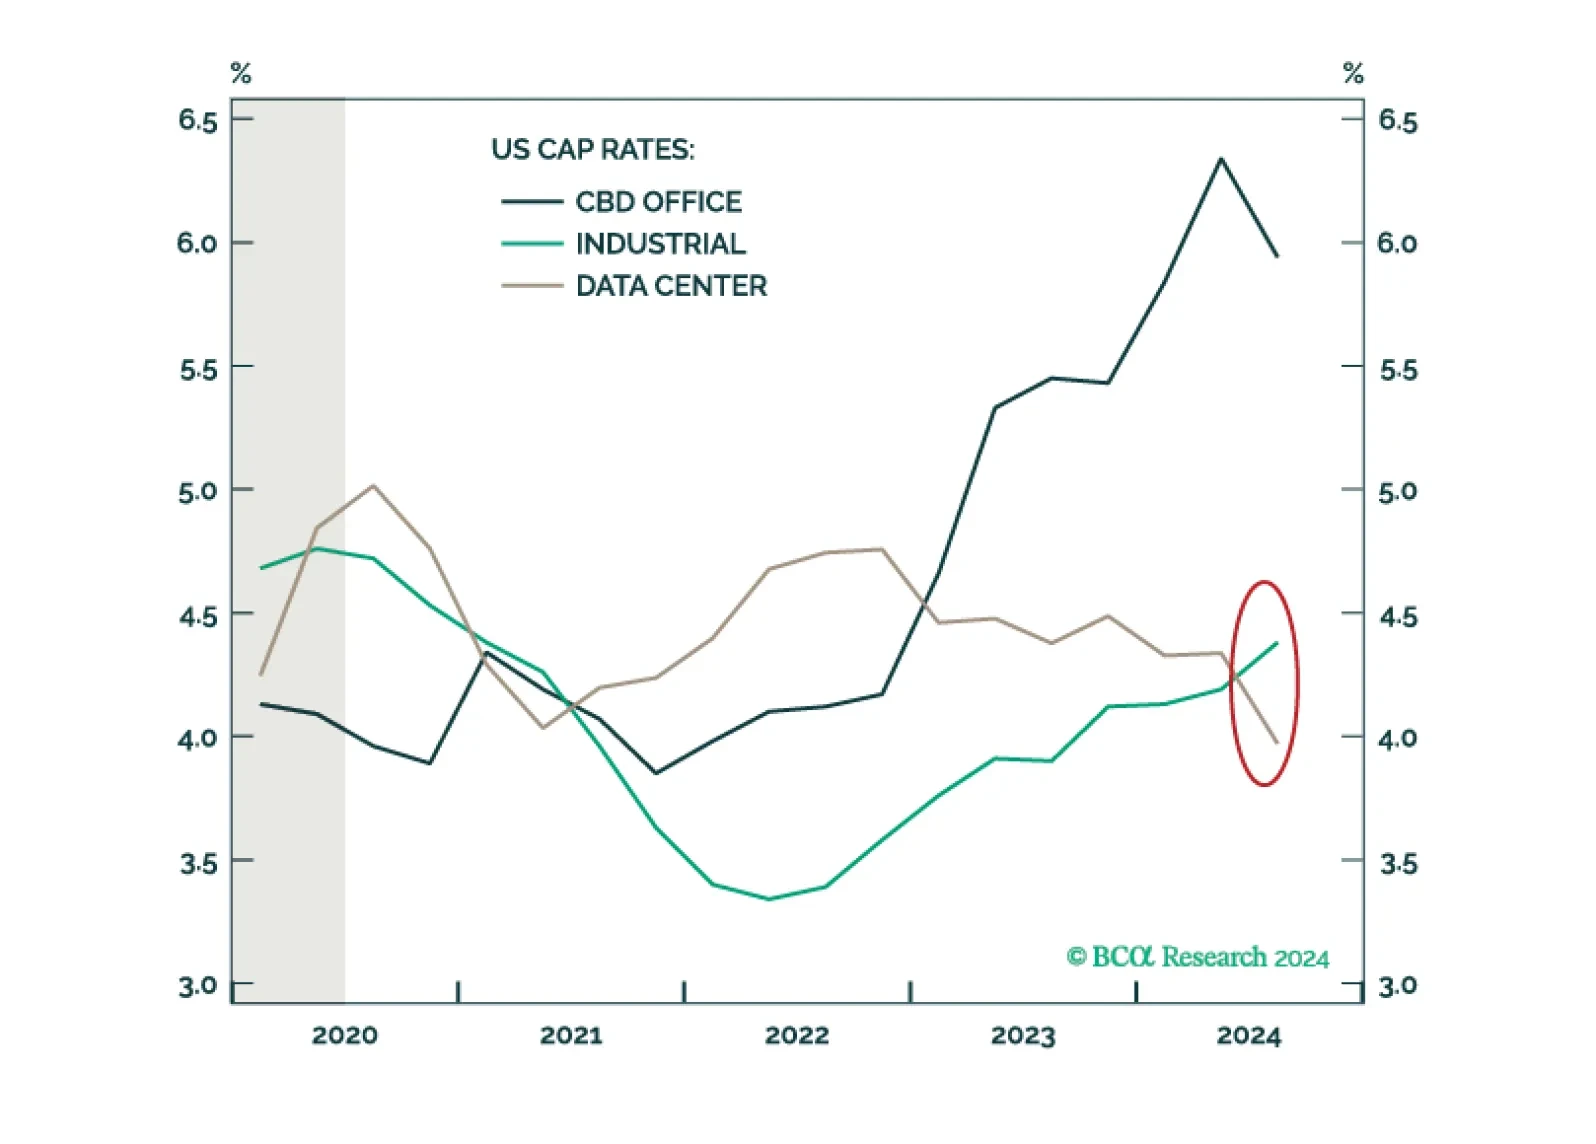
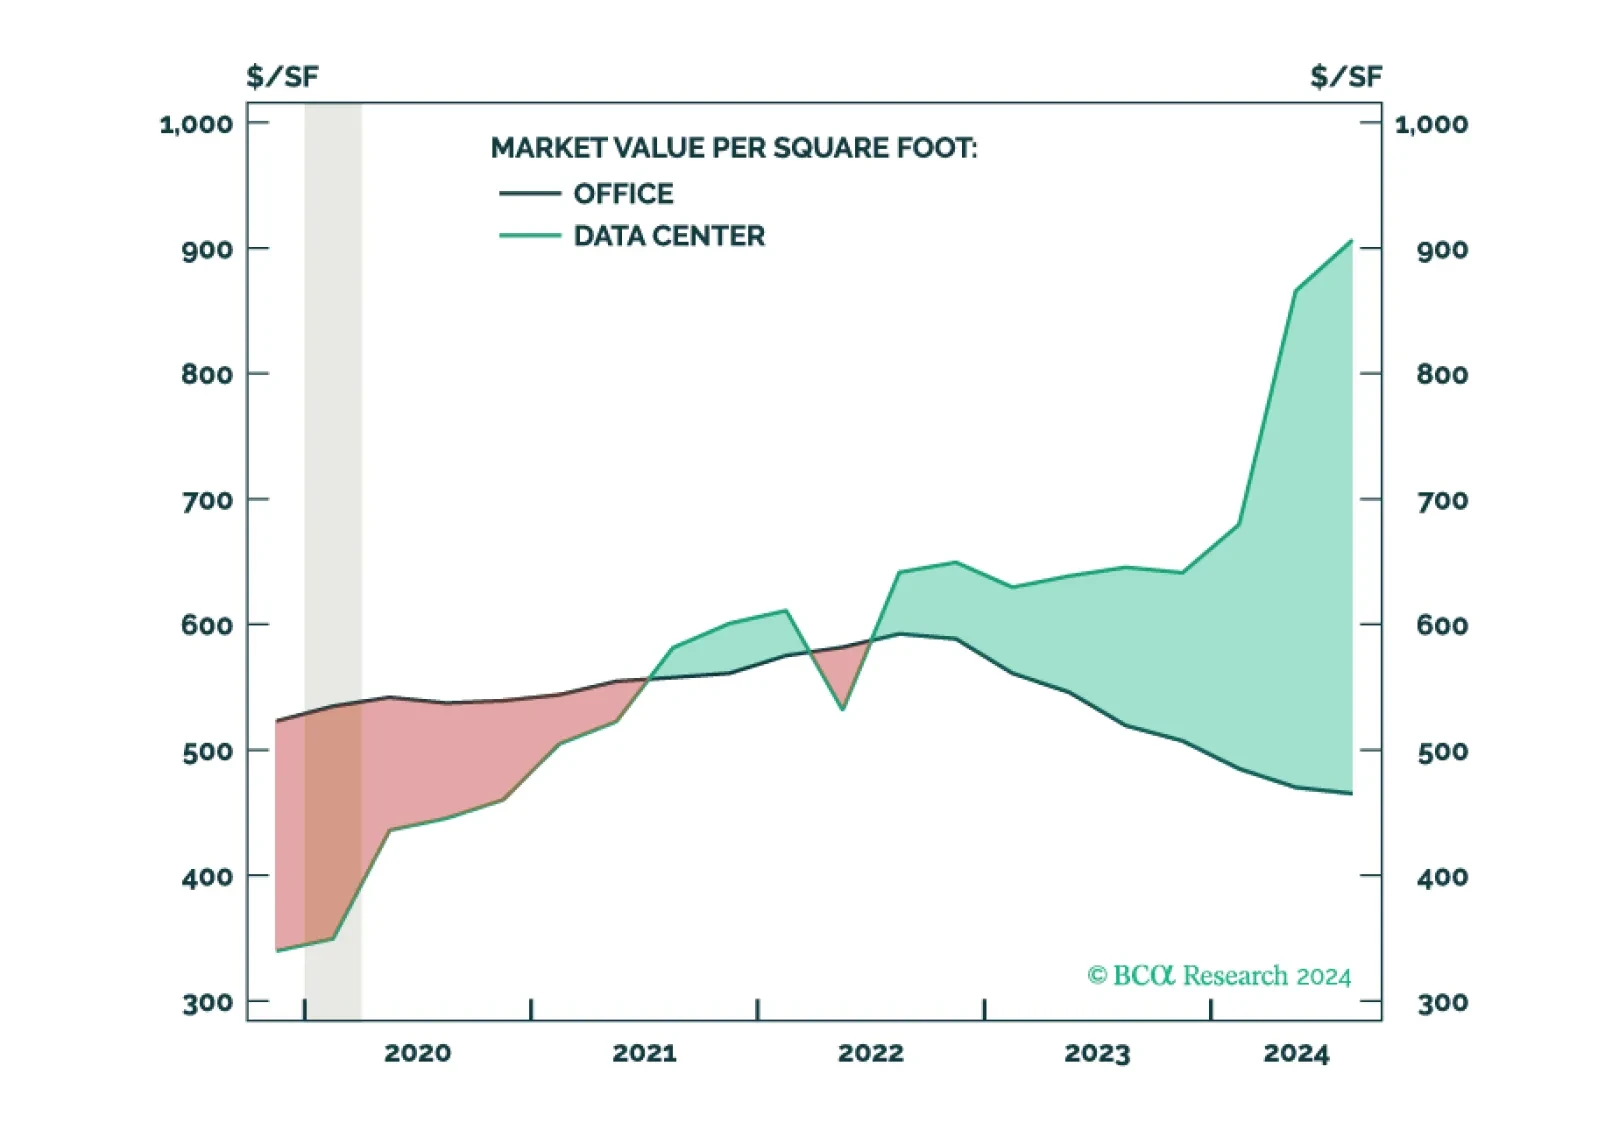
While AI deployment creates compelling investment opportunities, hyperscale facilities are not the only path forward. Investors should consider Office conversions into colocation Data Centers as the next dollar opportunity.
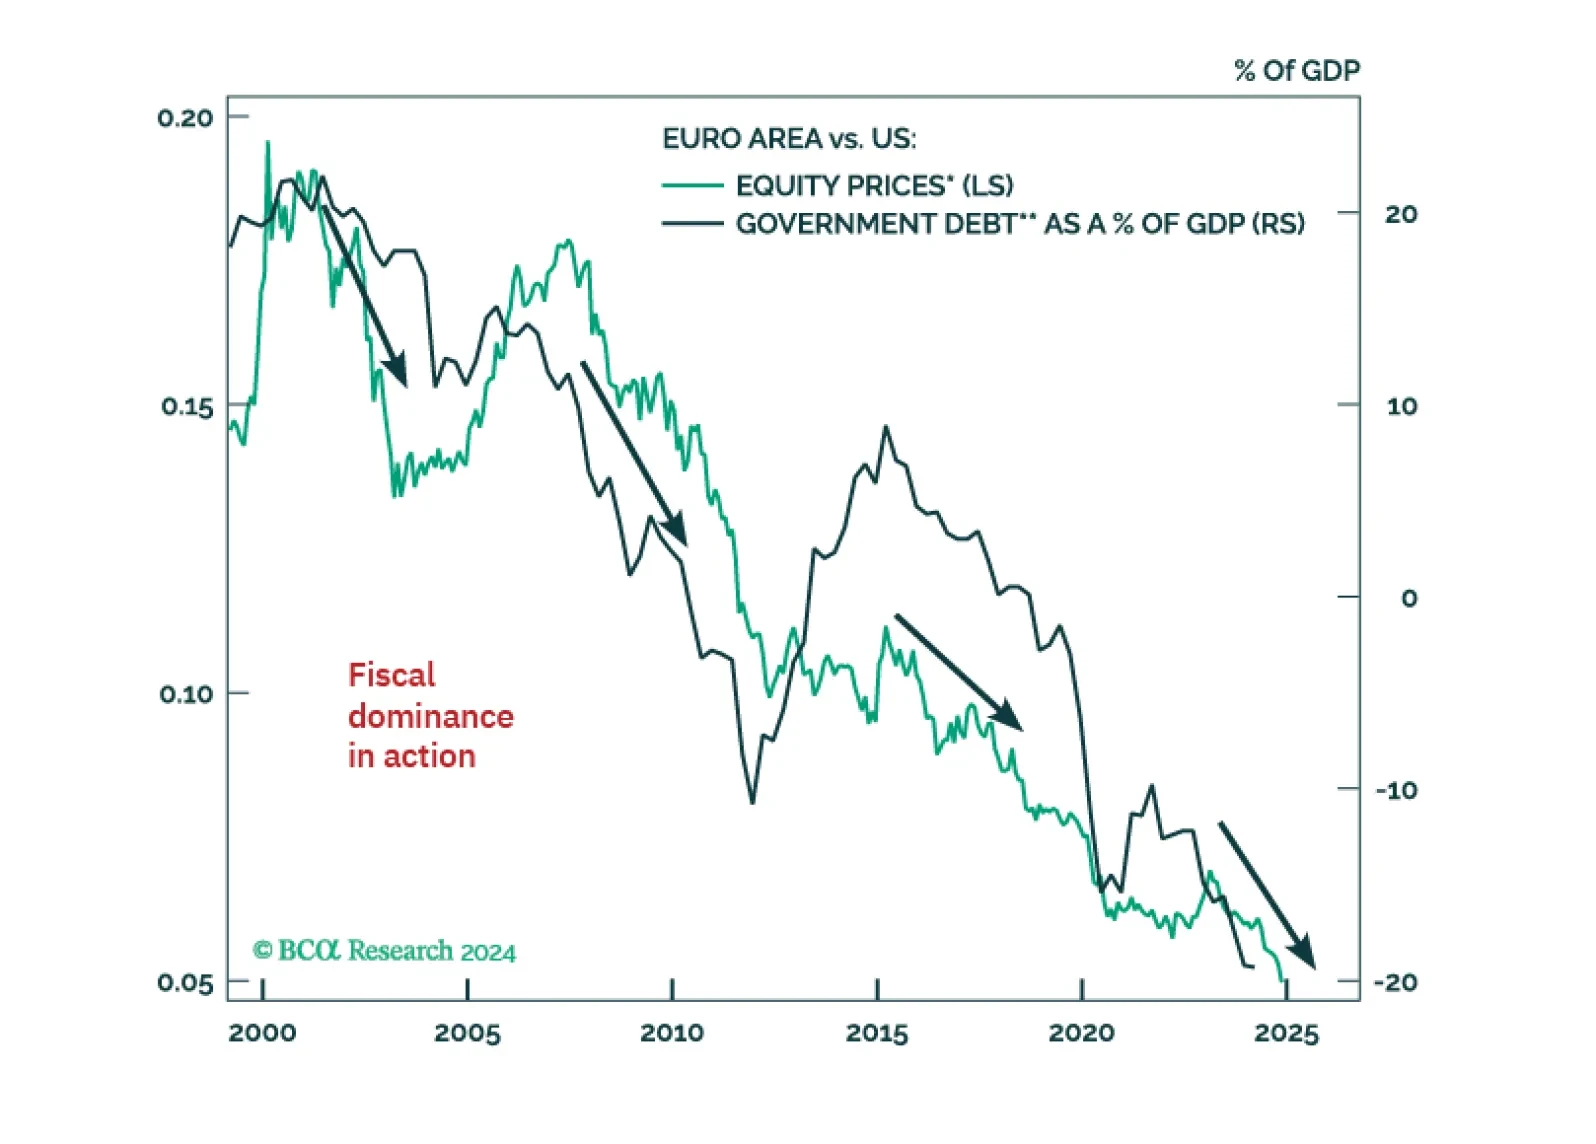
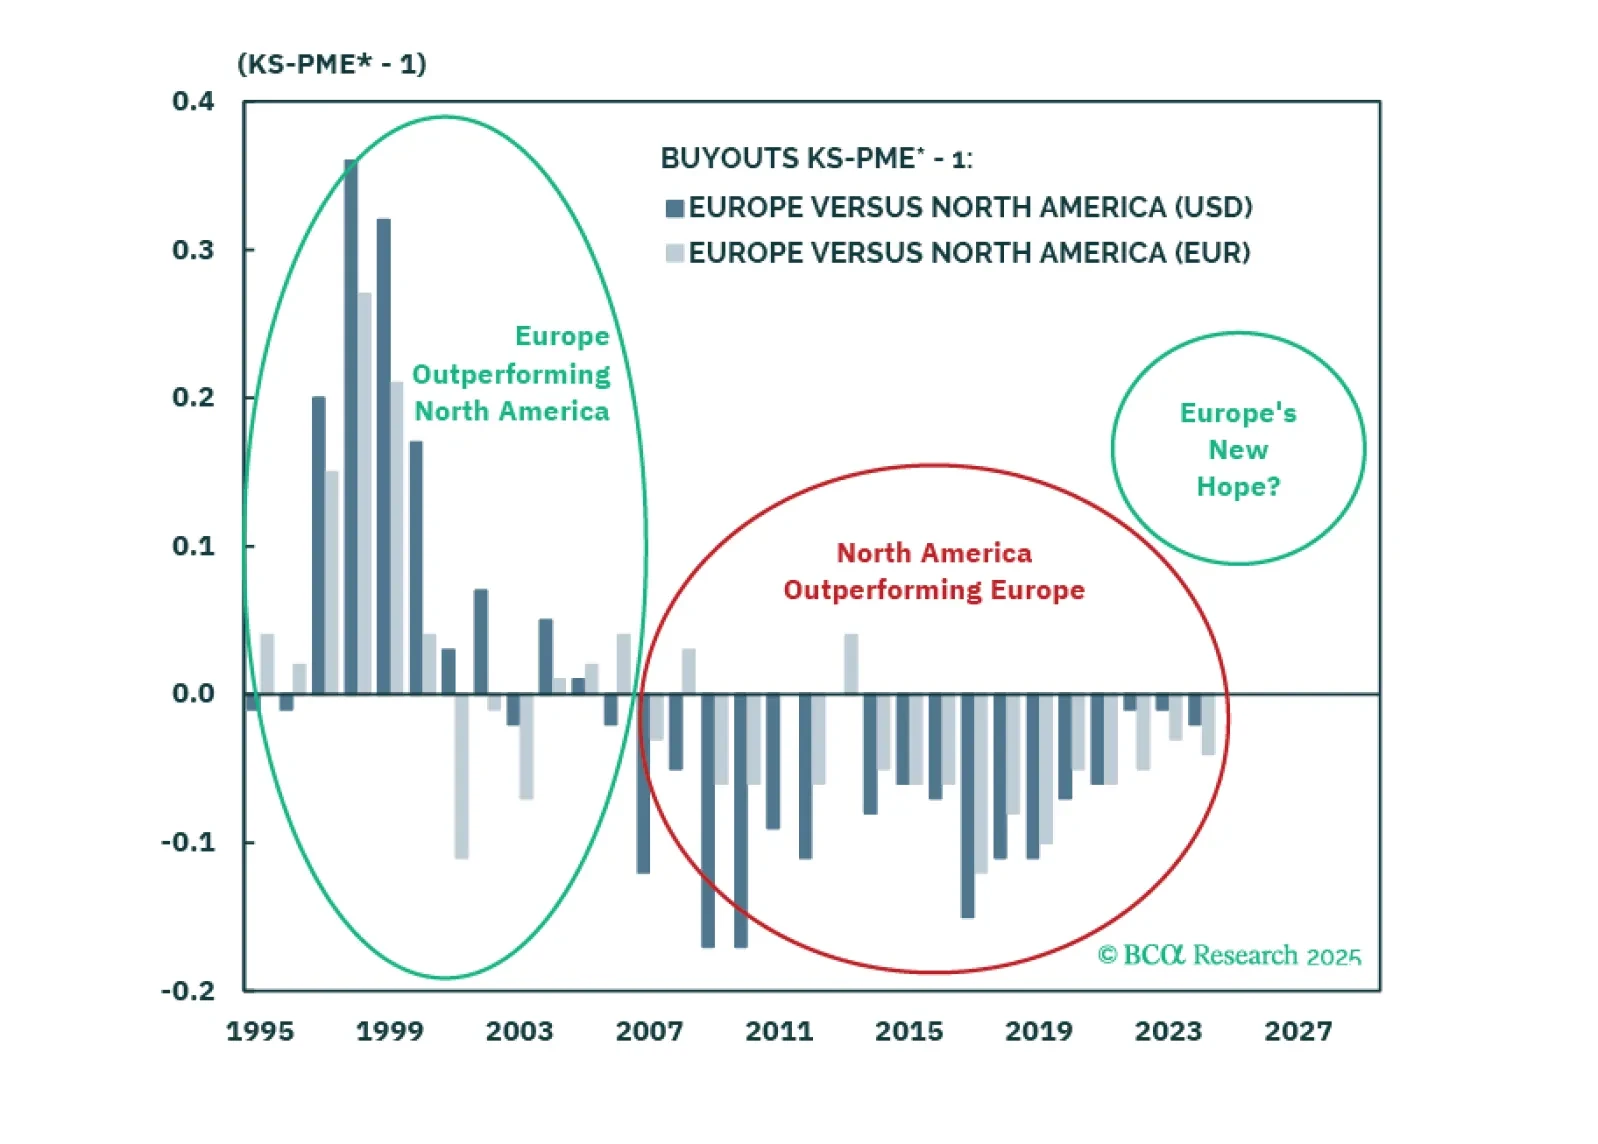
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
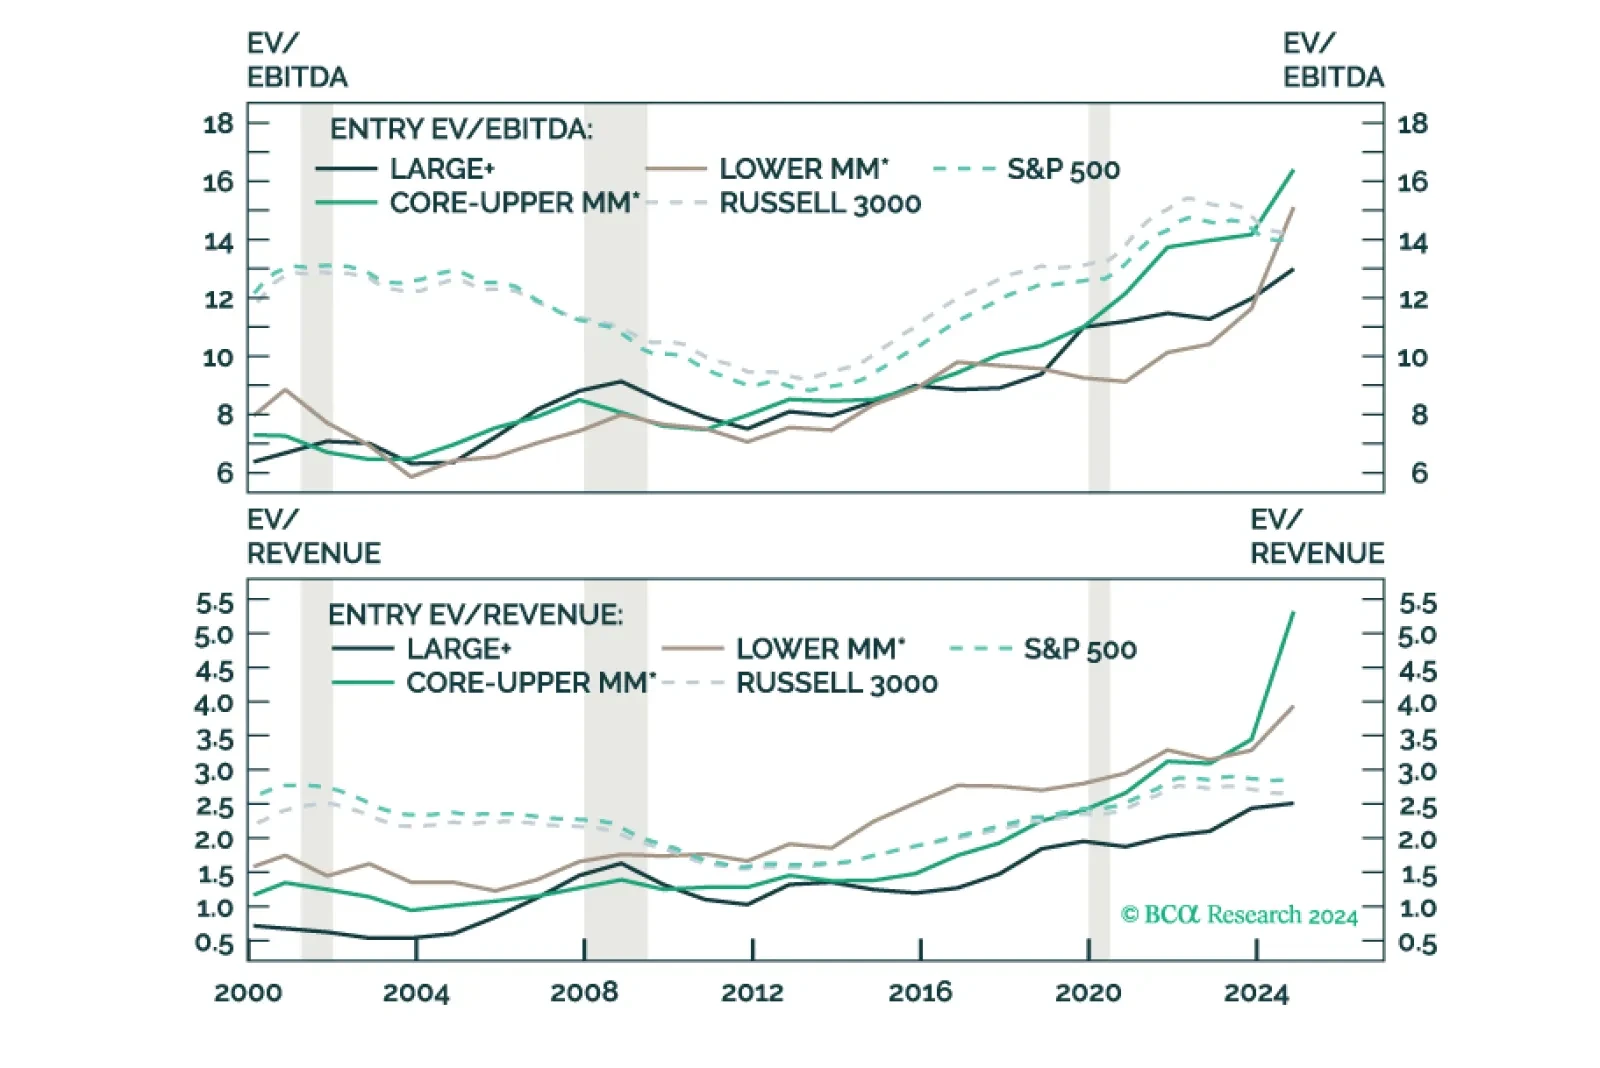
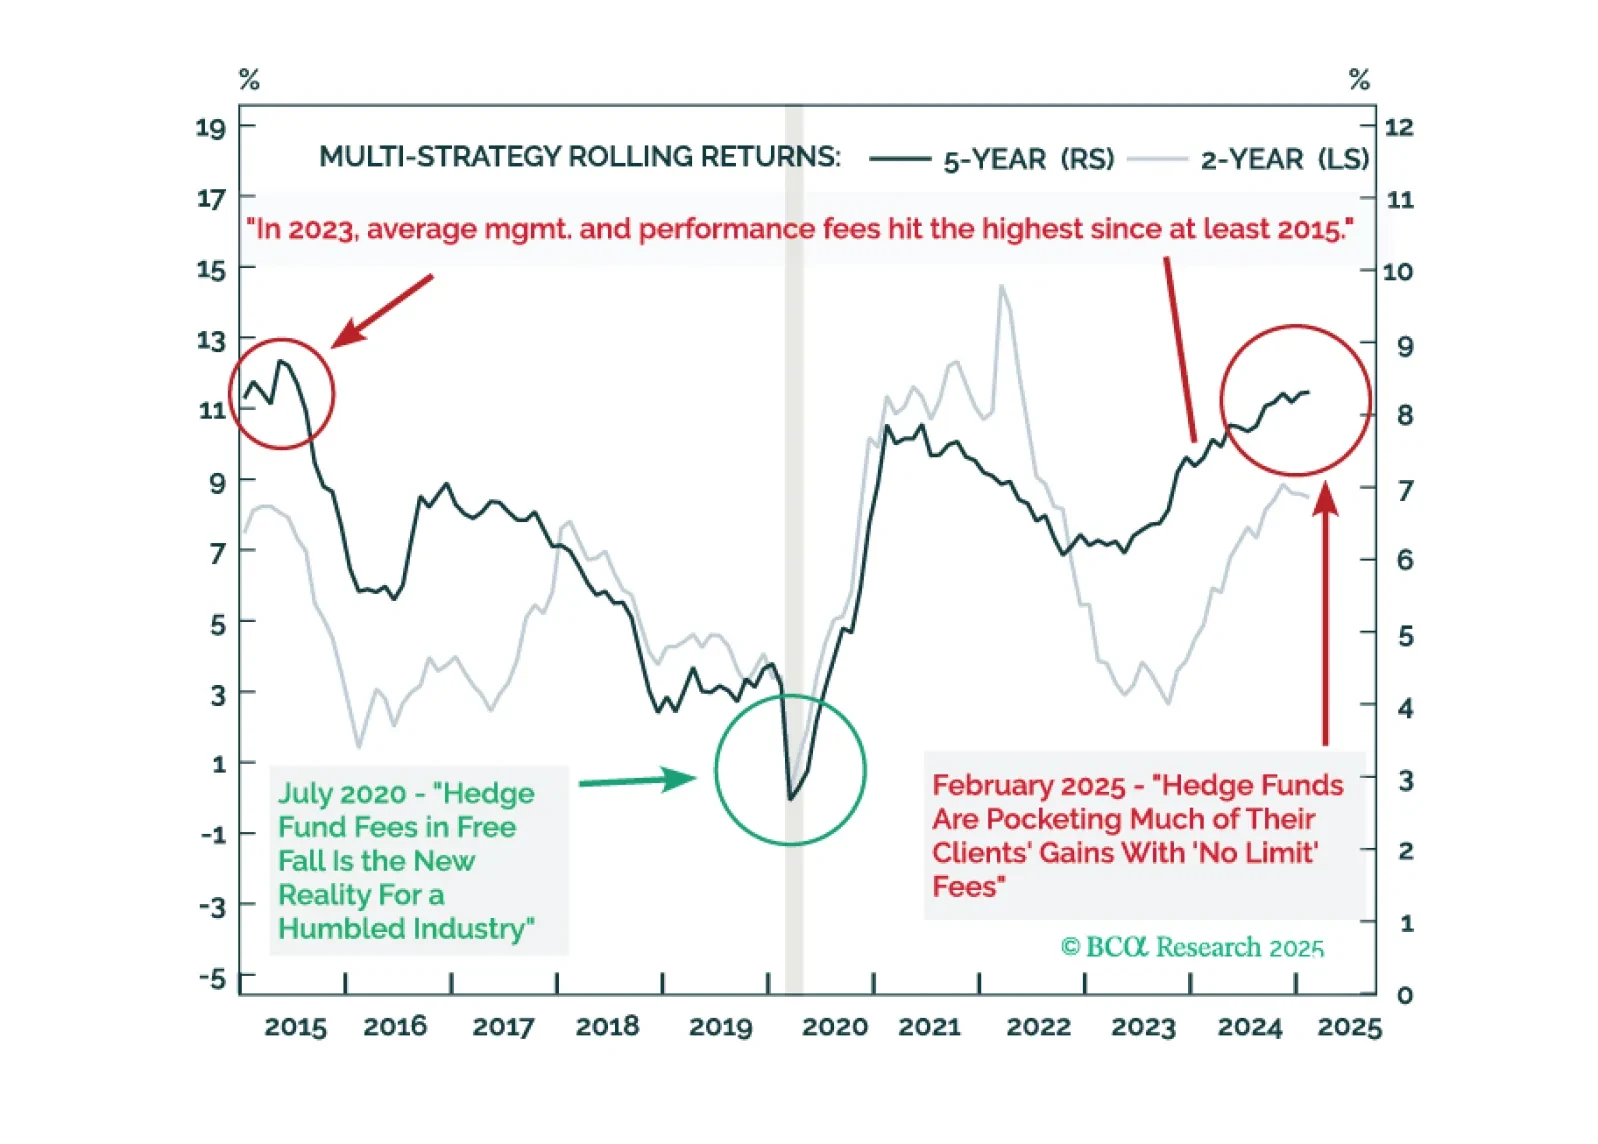
We prefer Non-Core Infrastructure and Venture Capital over Buyouts and Multi-Strategy Hedge Funds. We are now overweight Core/+ Real Estate. Investors need to recheck the bank regulation tailwind for their long-term assumptions on Private Credit.