Portfolio
| Private Markets
Private equity, credit, real estate, and infrastructure, analyzed with the same macro lens BCA brings to public markets.
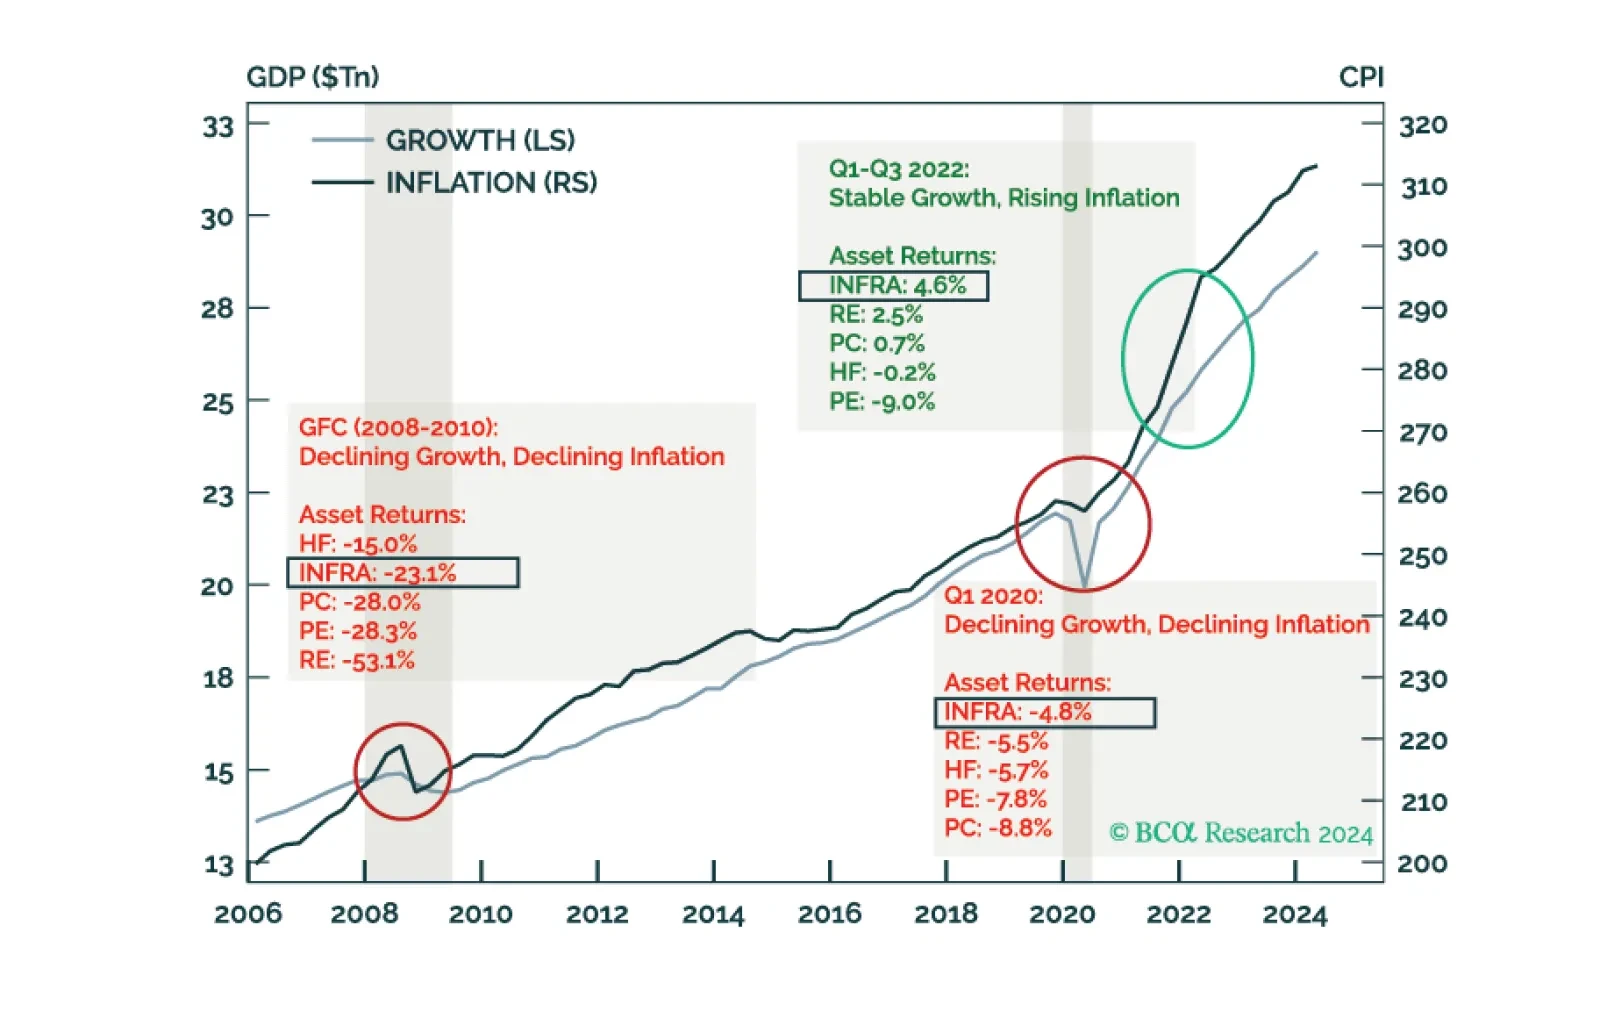
Institutional investing is not as straightforward as picking the fastest horse. Infrastructure’s attraction as an investment stems from its diversification, specifically its feature as an inflation-hedge, cash flow stability, and scalability. This Primer lays the groundwork for integrating Infrastructure into the PMA framework.
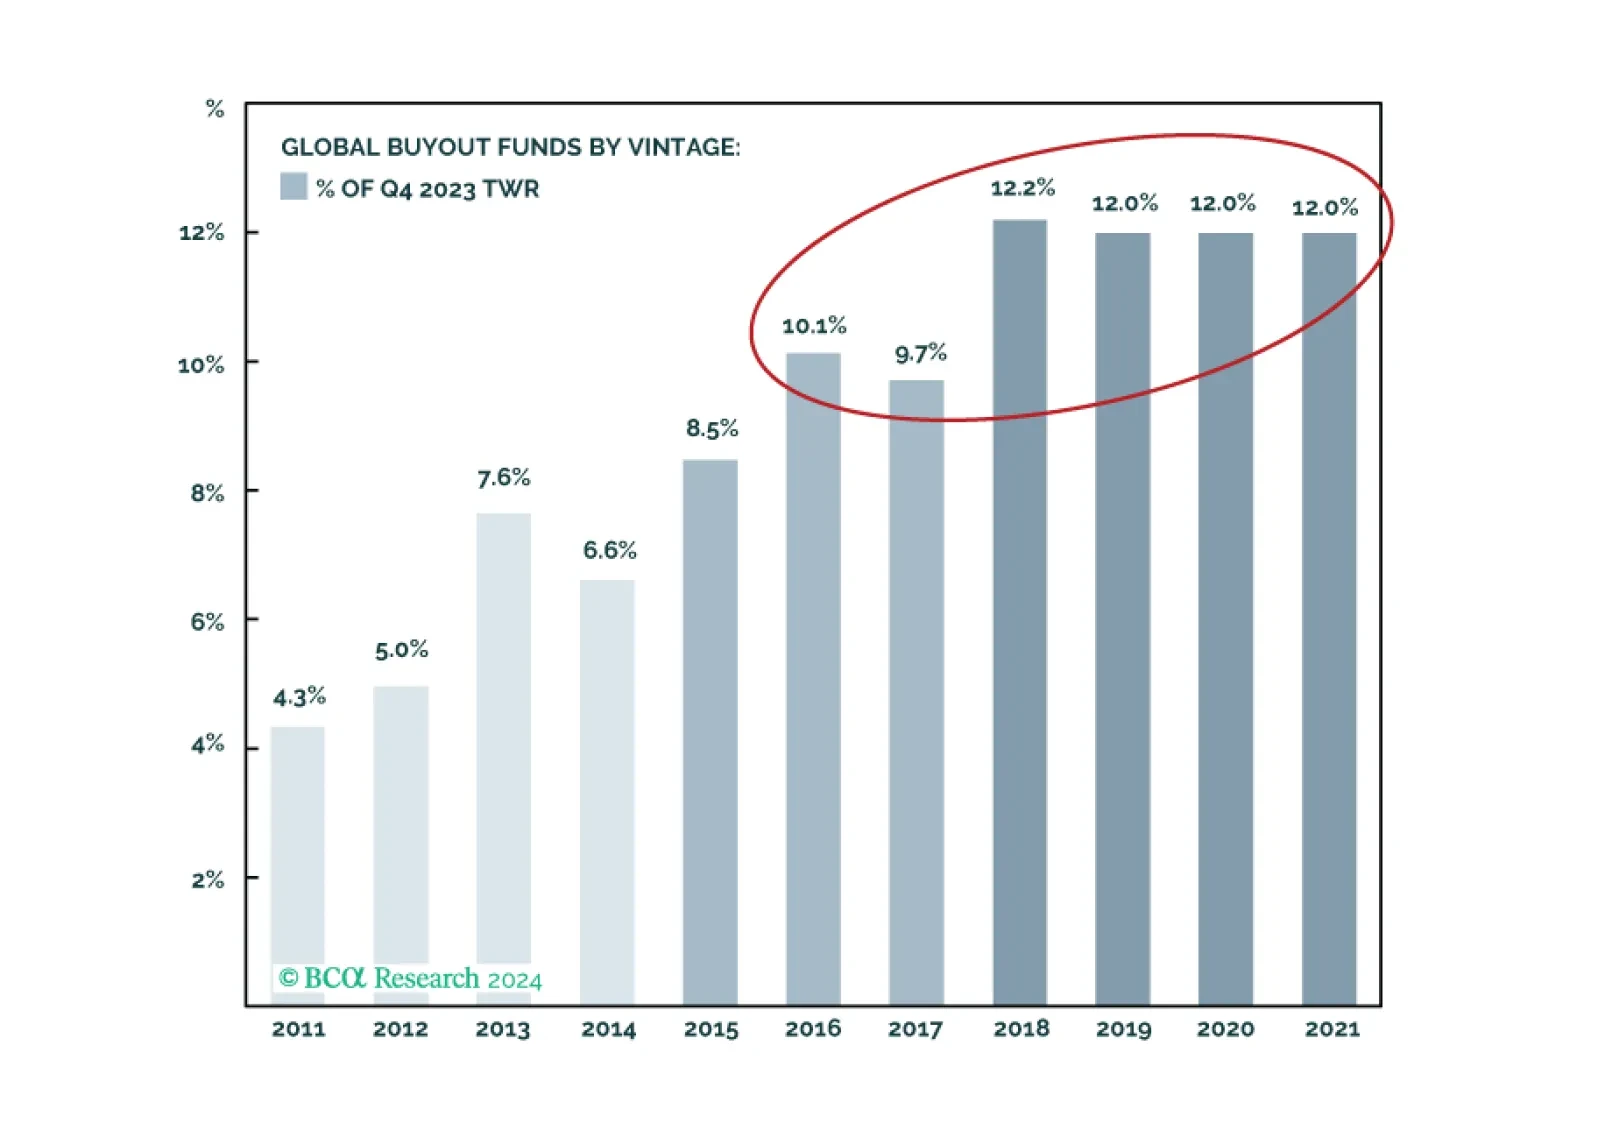
Unlike public markets, performance in private markets is complex and multifaceted. In this report we present multiple metrics across time and sources, offering investors a comprehensive range of benchmarks to assess their relative performance. Differences across sources will surprise.
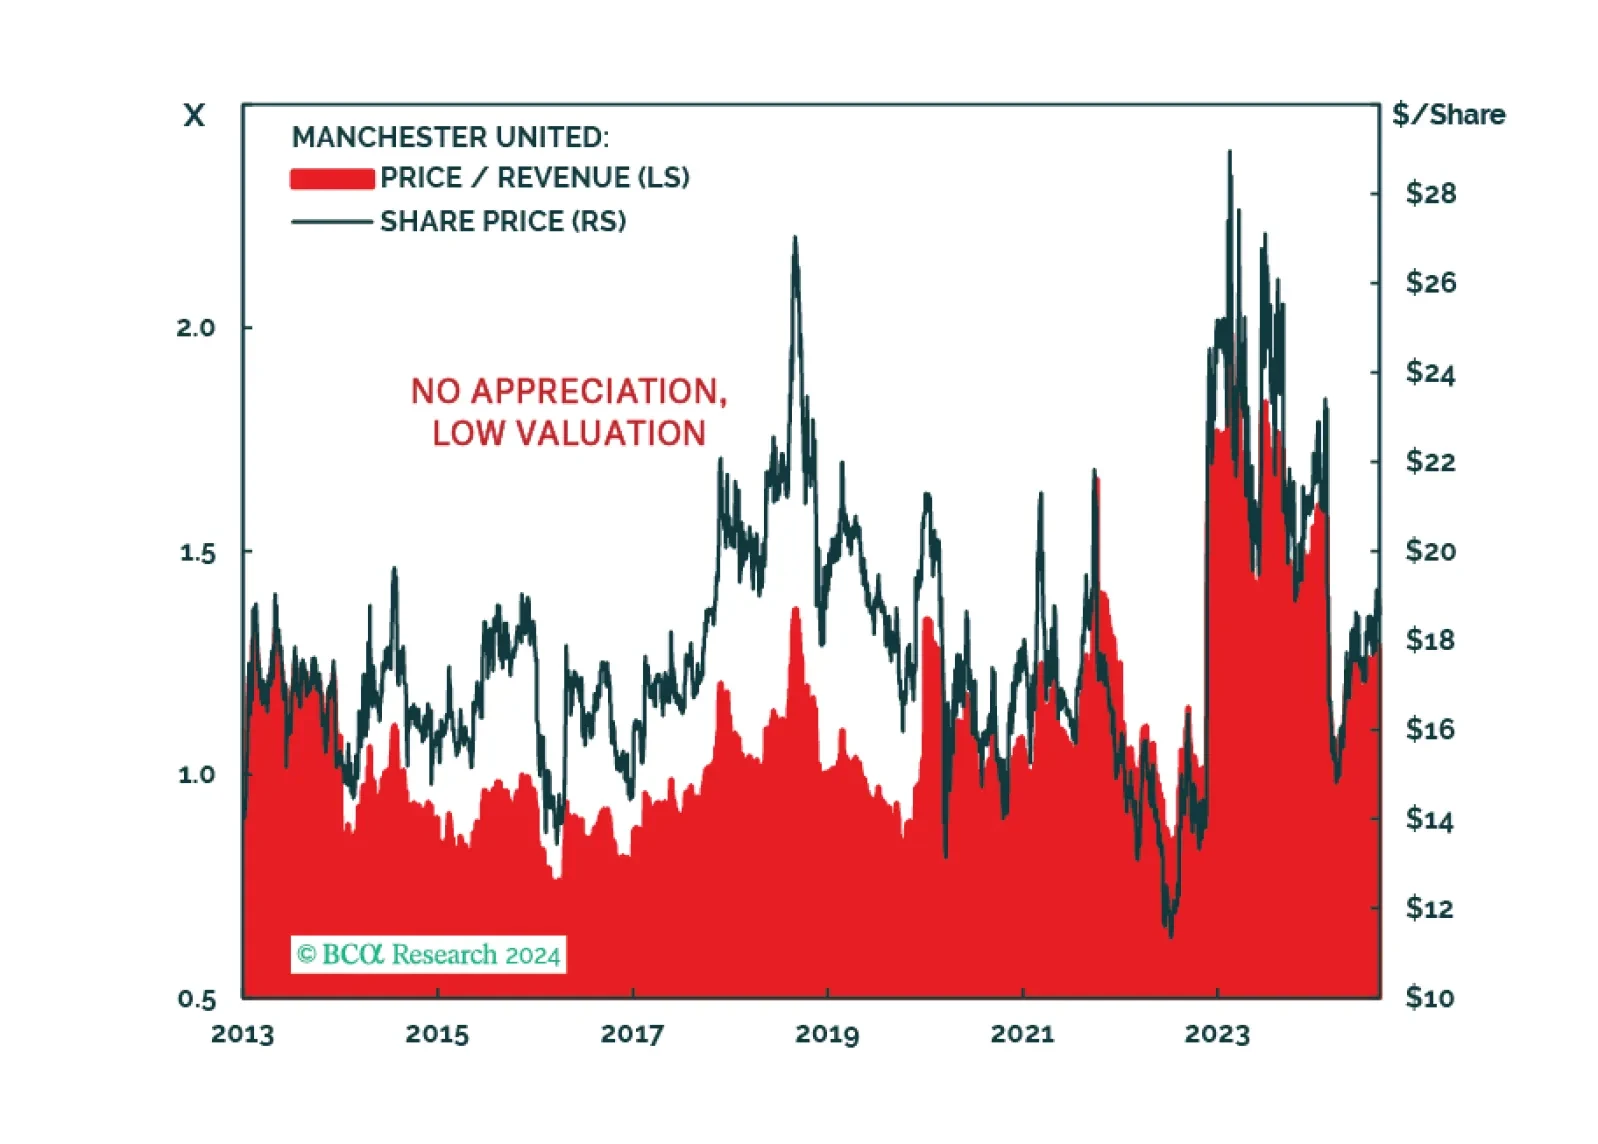
The NFL is opening the gates to the barbarians. No majority ownership is allowed...yet. However, that will not limit the upside in Growth Equity investments. Investors should cheer, so should fans.
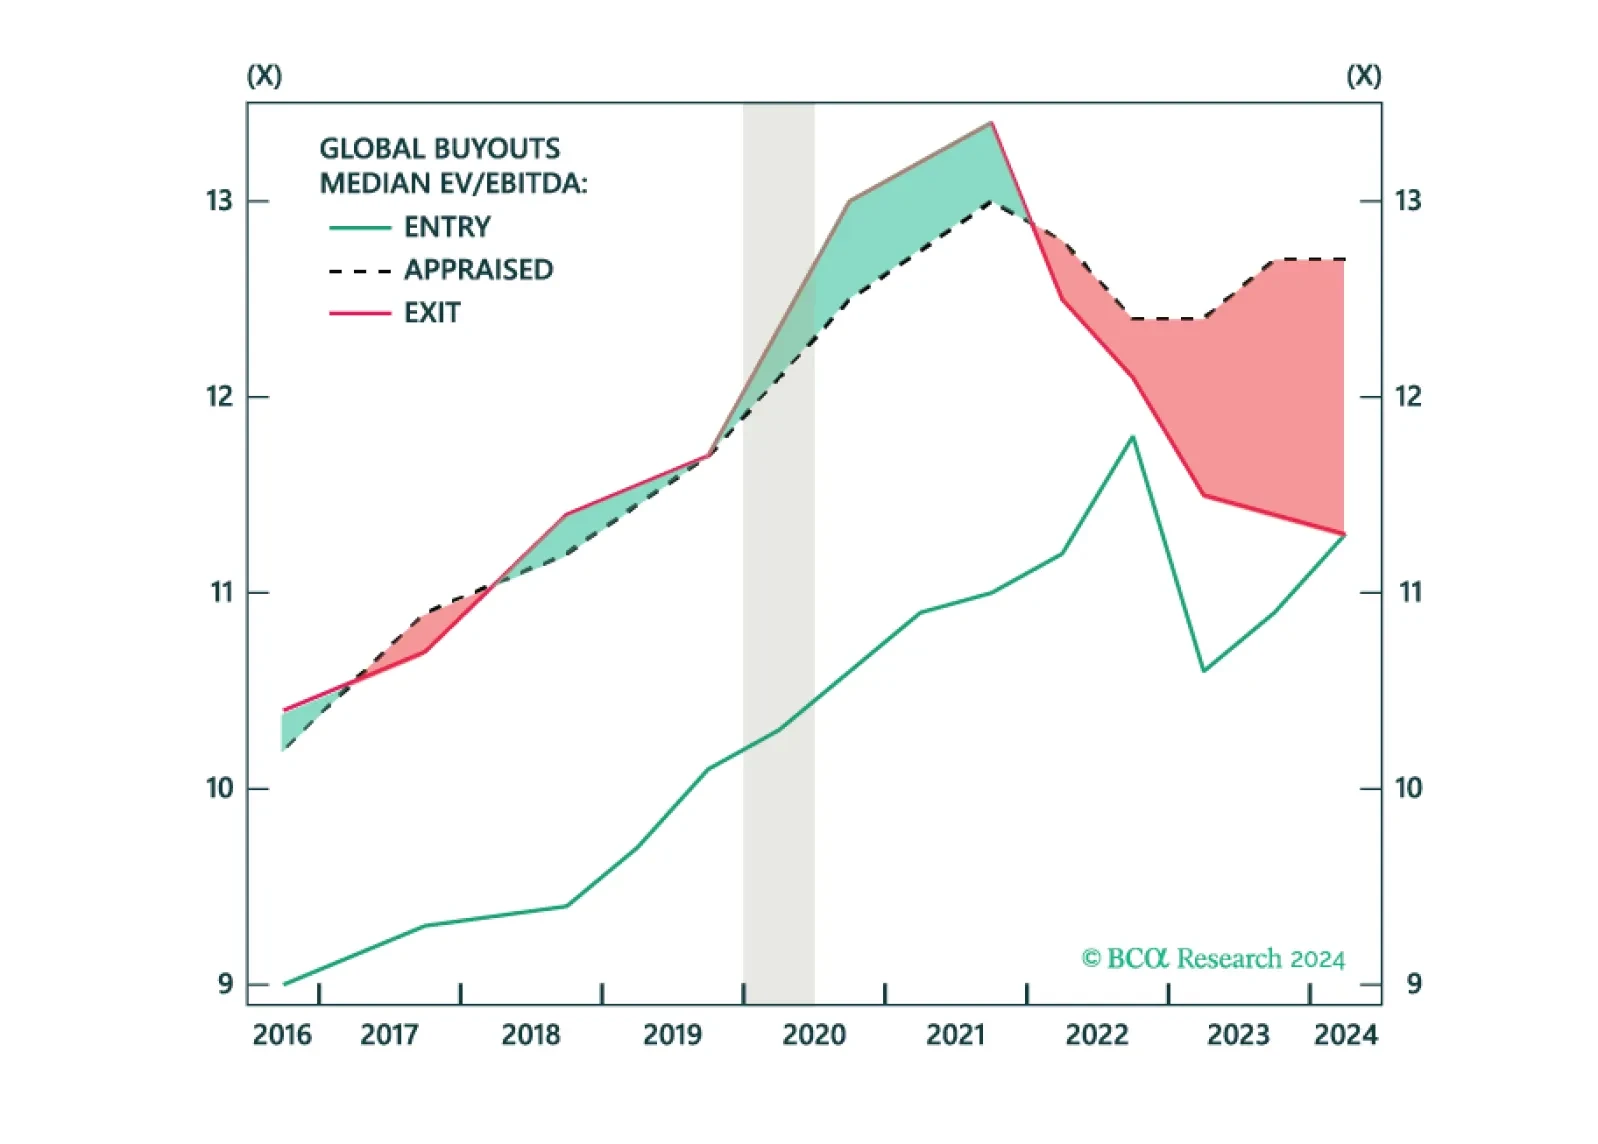
Private Equity Secondaries have grown but so have their opportunities. Near-term opportunities will be fertile while underlying trends will sustain the asset class in the long-term. Private Equity investors should be greedy.
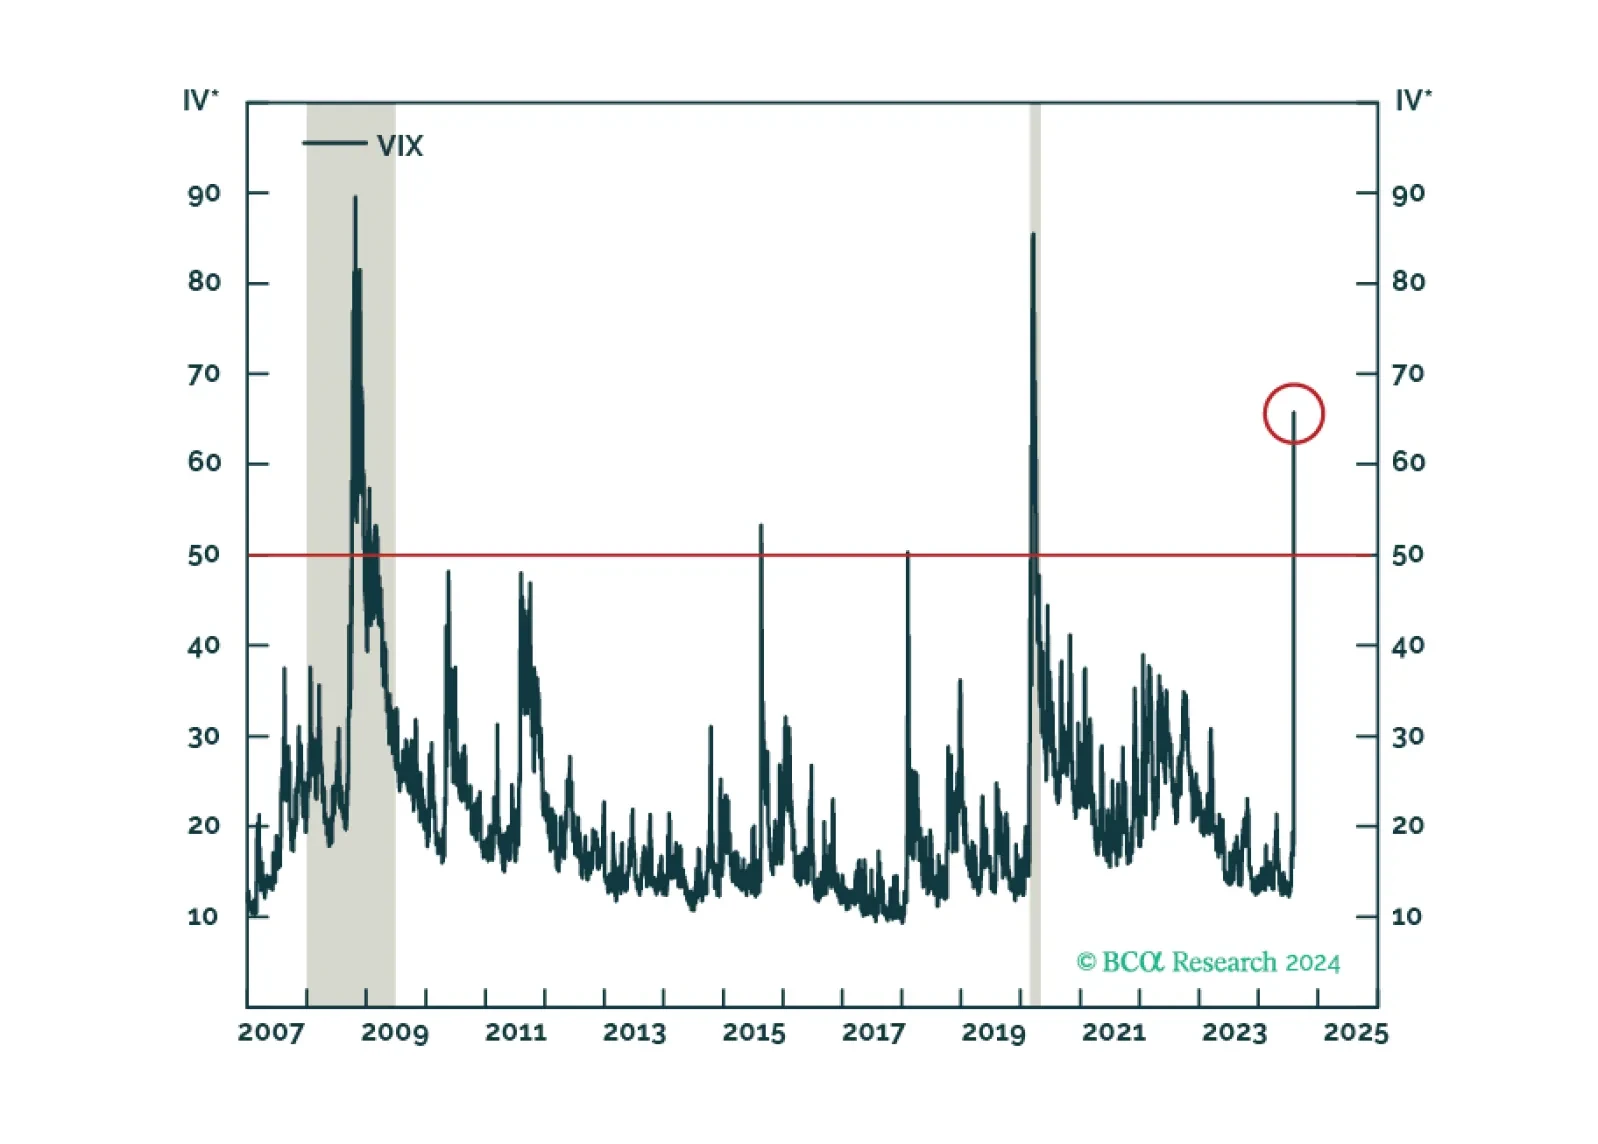
Market volatility has surged. Investors should no longer be allocating into Tail Risk structures. For those invested, start monetizing gains and let CTAs and Developed Market Fixed Income take the wheel from here.
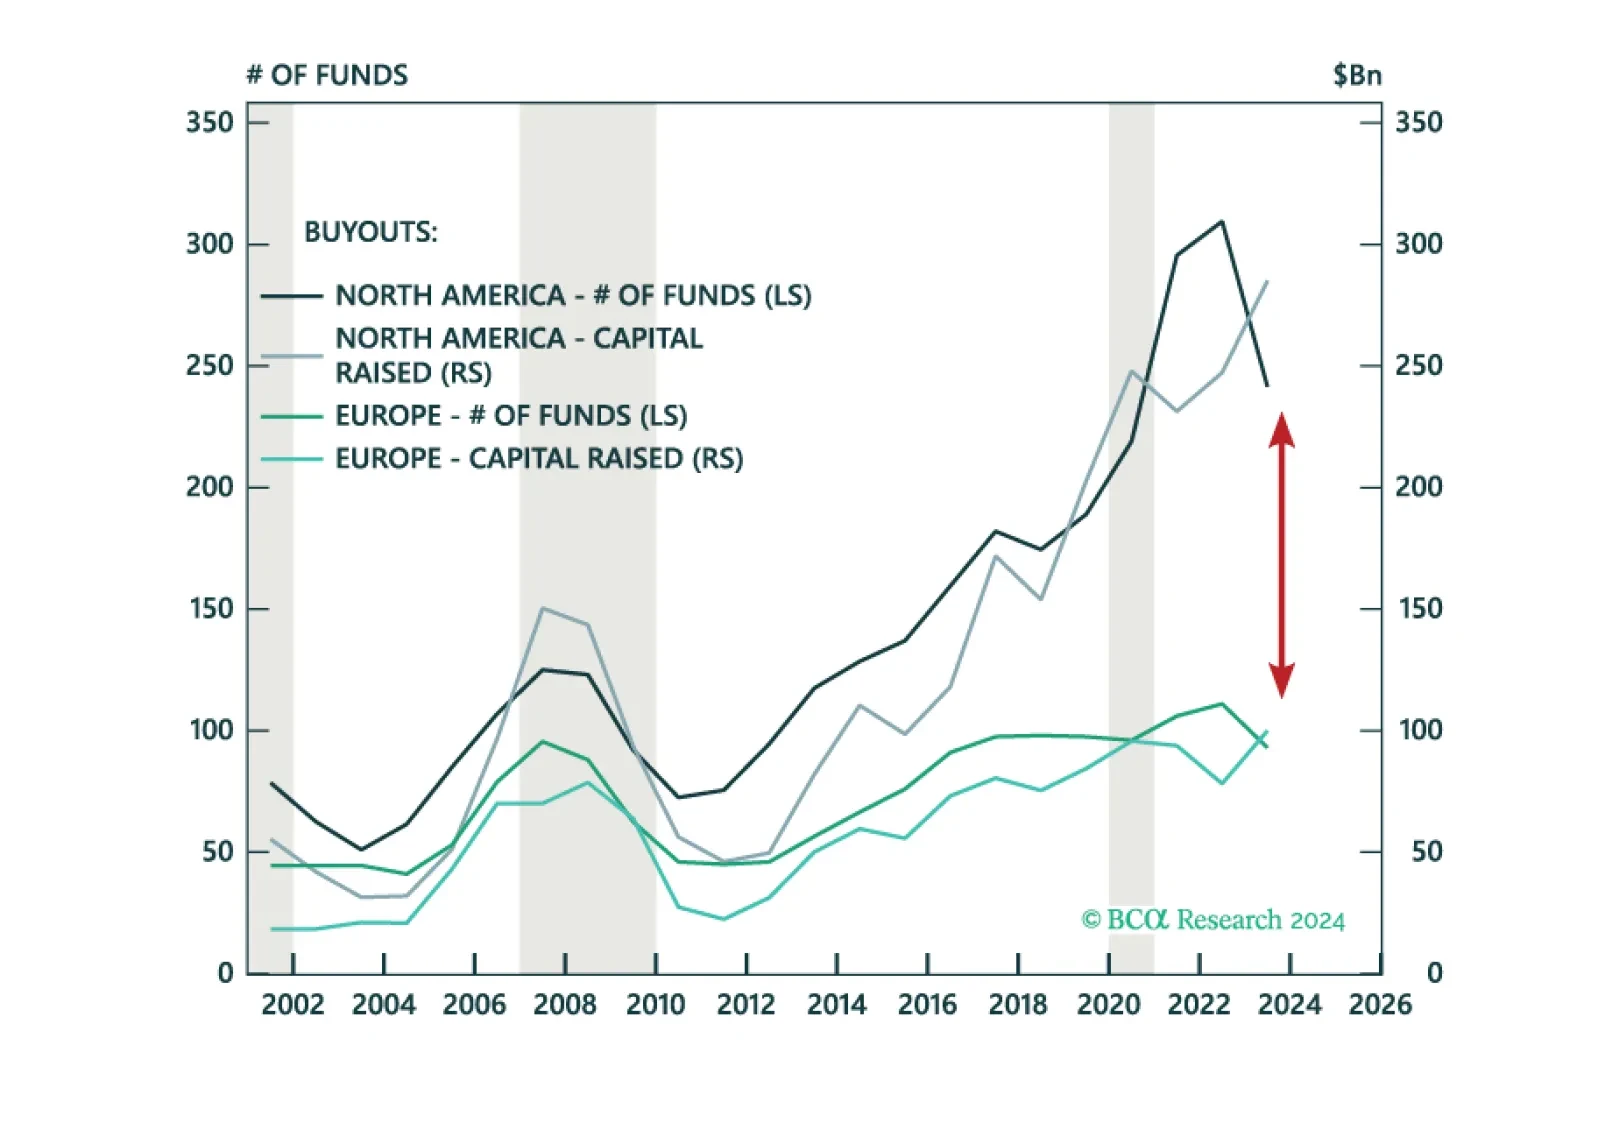
We are growing positive on Growth assets with recession expectations increasing our optimism on entry points. Equities are led by APAC Private Equity, North America Venture Capital, and Europe Buyouts. Our outlook continues to improve on CRE within the Inflation & Diversification bucket while we are underweight Multi-Strategy amongst Hedge Funds. We maintain an overweight to Senior Direct Lending for Income with a preference for North America.
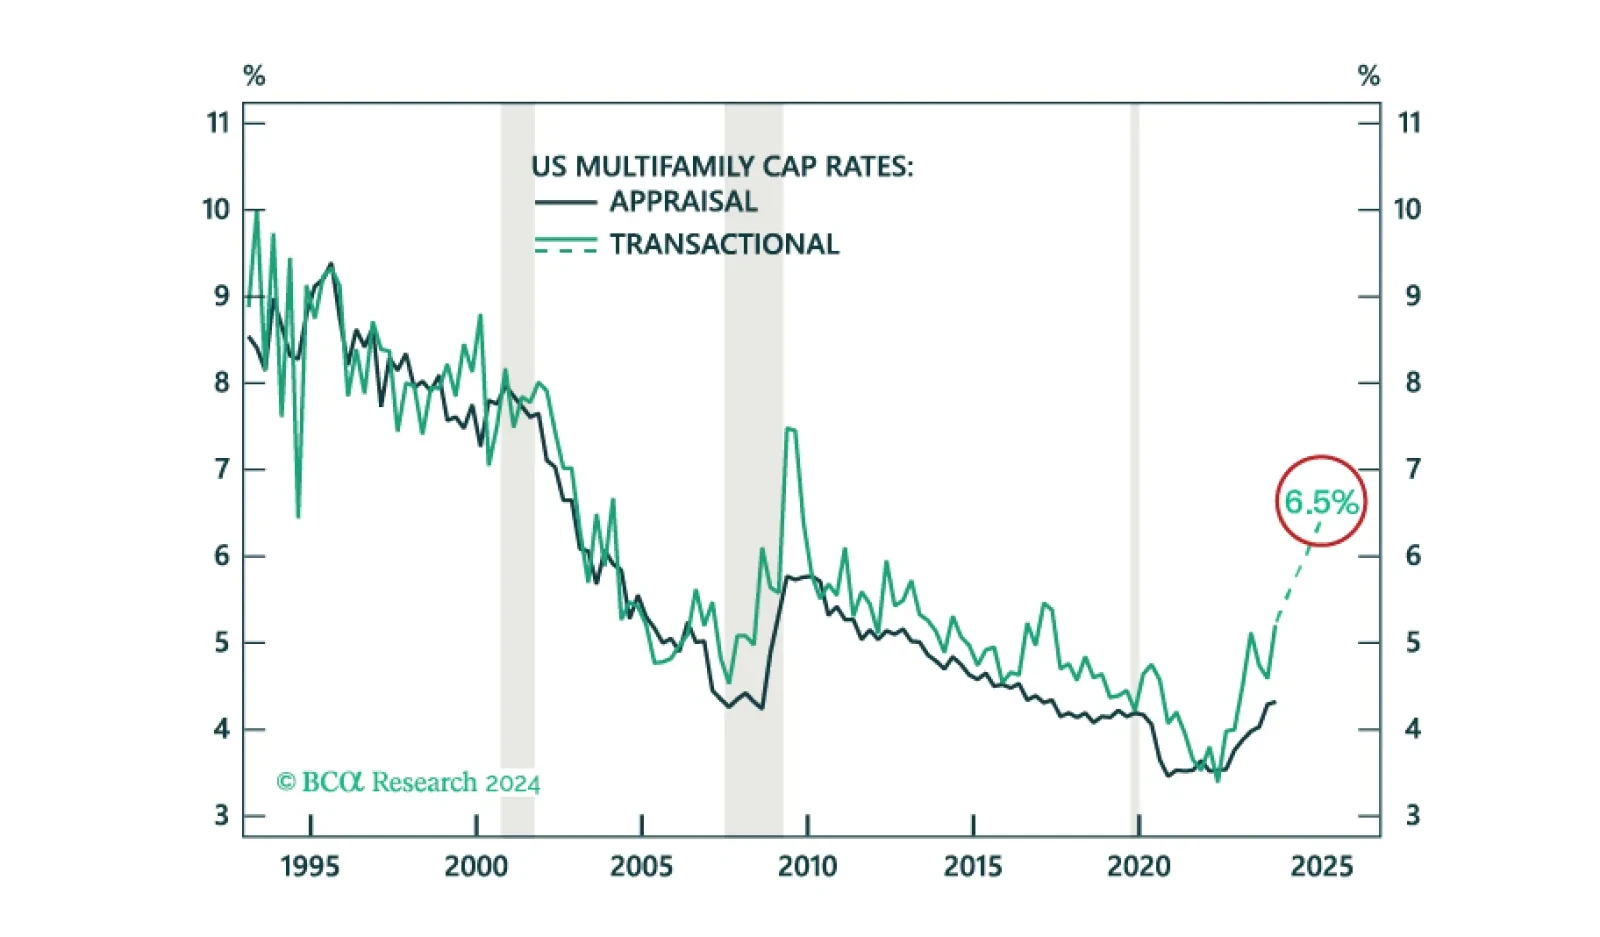
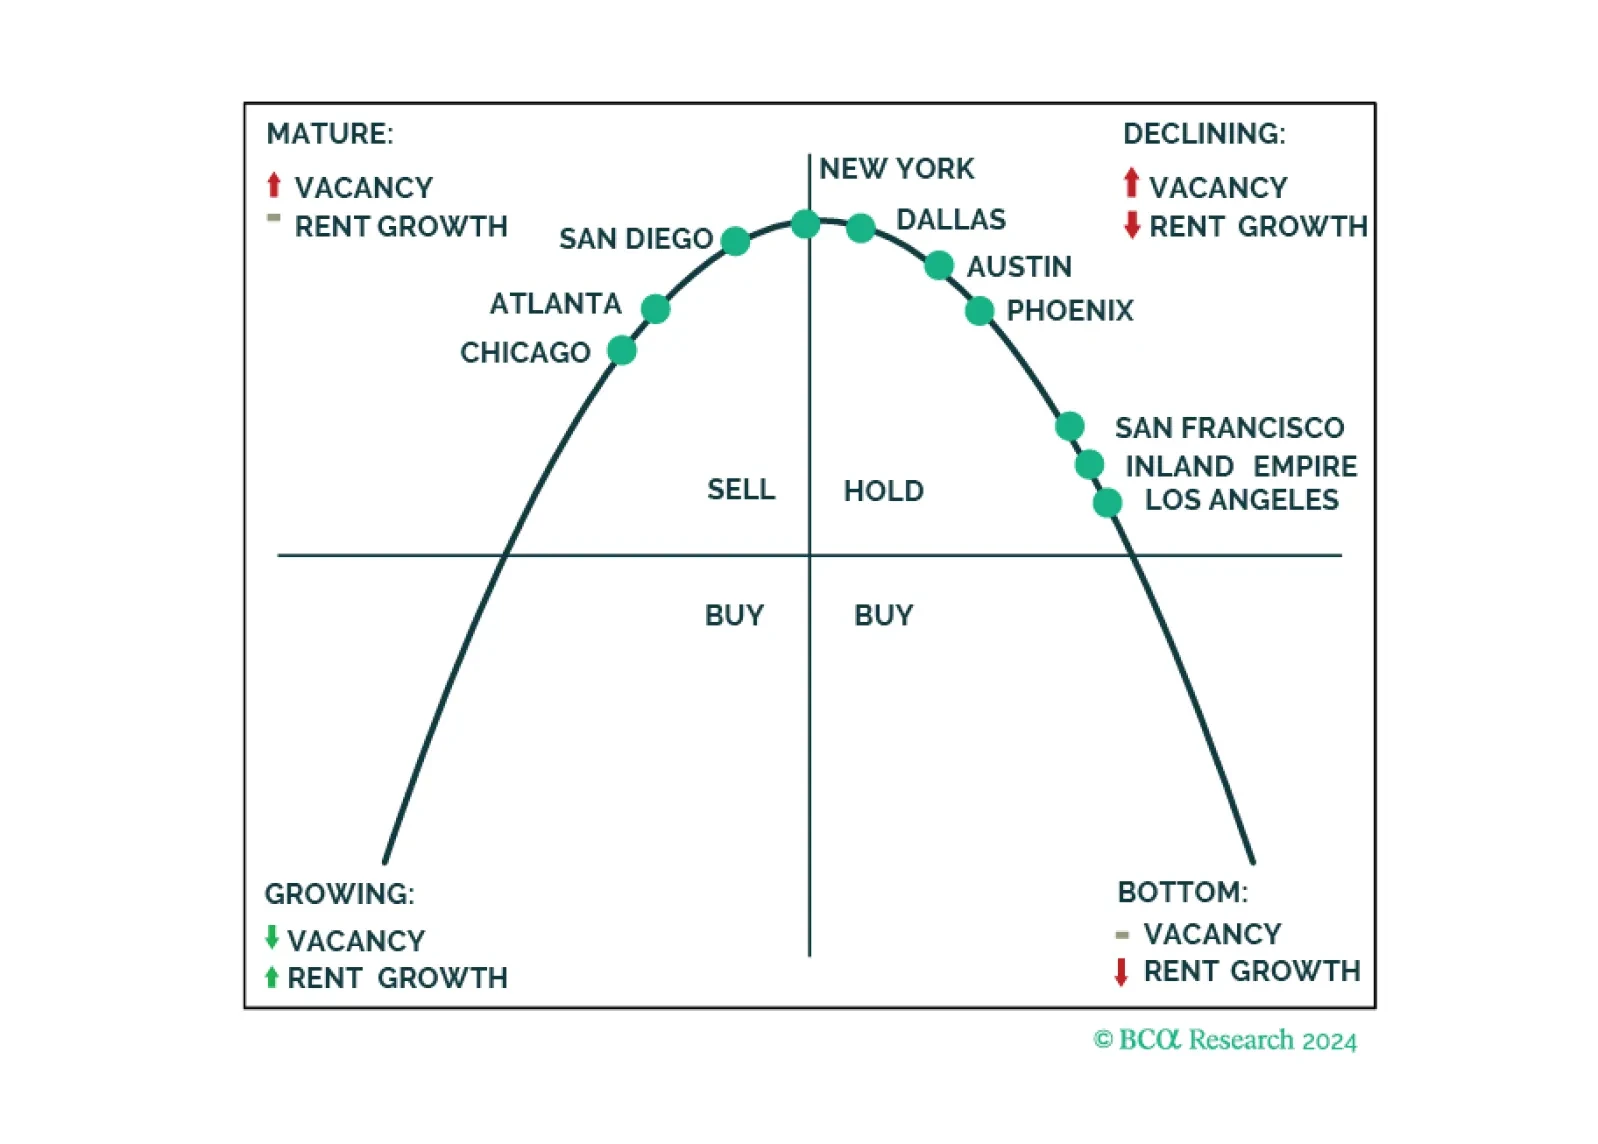
We project US Multifamily cap rates to increase from 5.2% to 6.5%. While we find an unfavorable risk-adjusted return on the asset, especially relative to other opportunities in CRE, cap rates are moving closer to peak.