 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
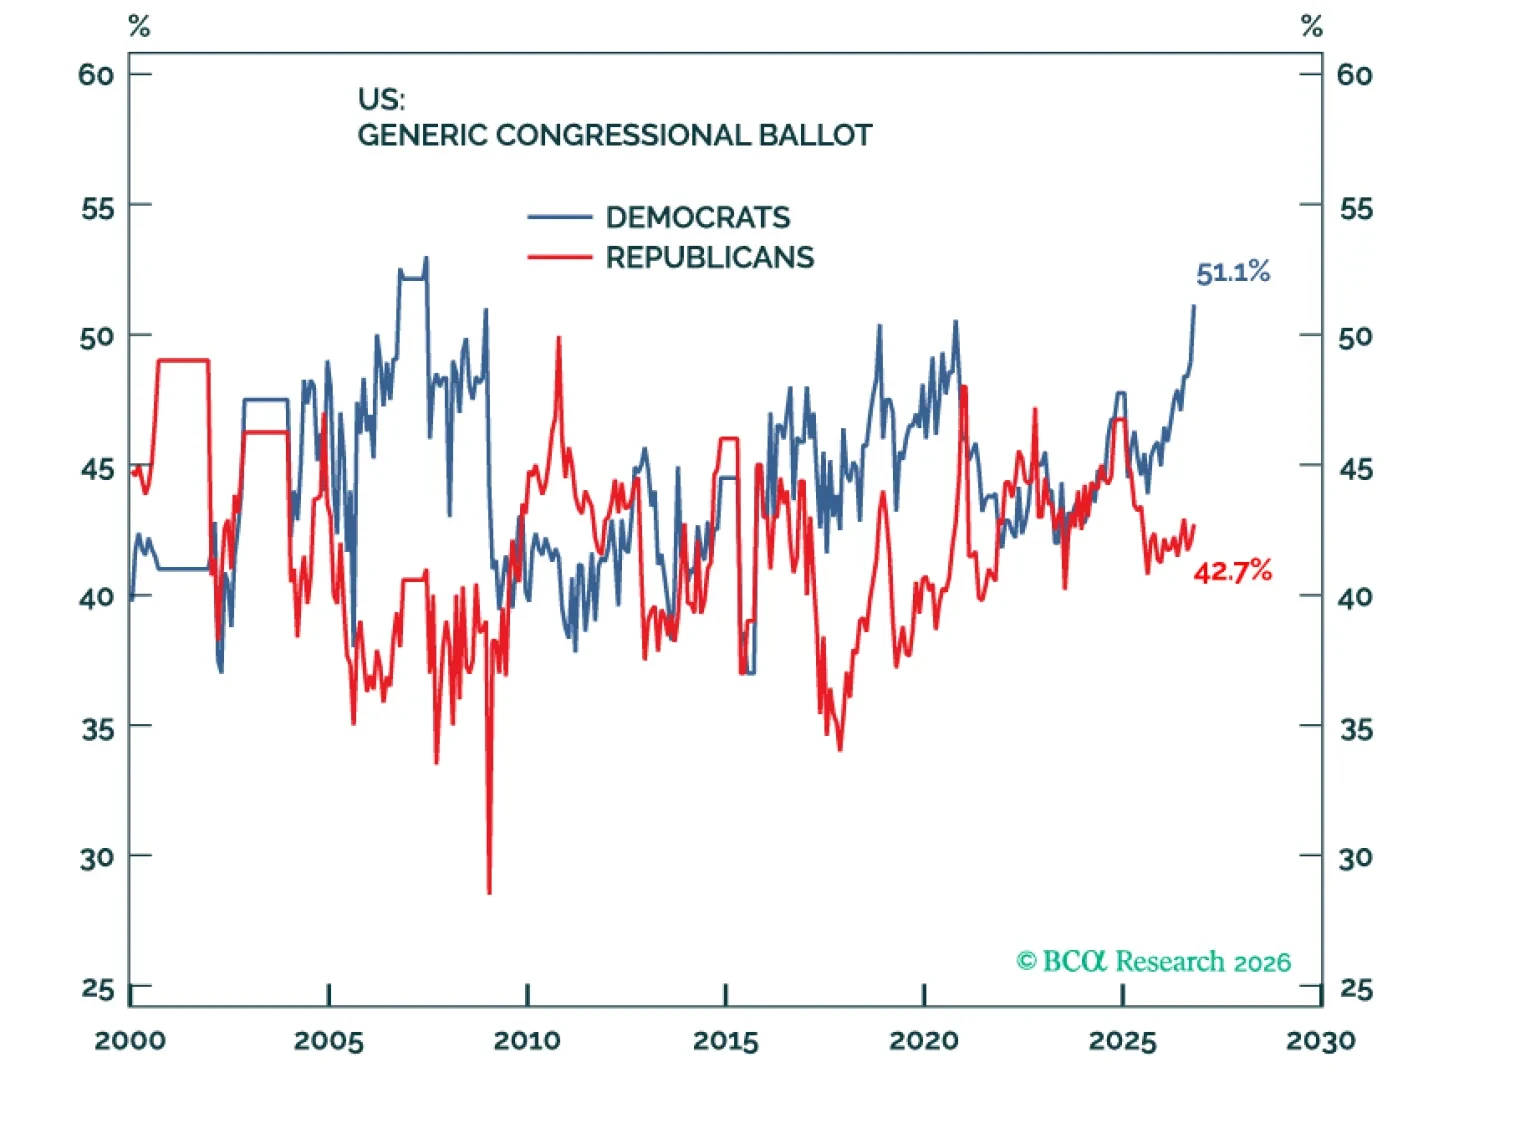
Democrats will win both houses in the midterm, but beyond near-term volatility, none of the outcomes pose a major market risk. The vote is more important as a signal of an anti-business turn in US policy in coming years, which markets could start to price in late 2027 or early 2028.
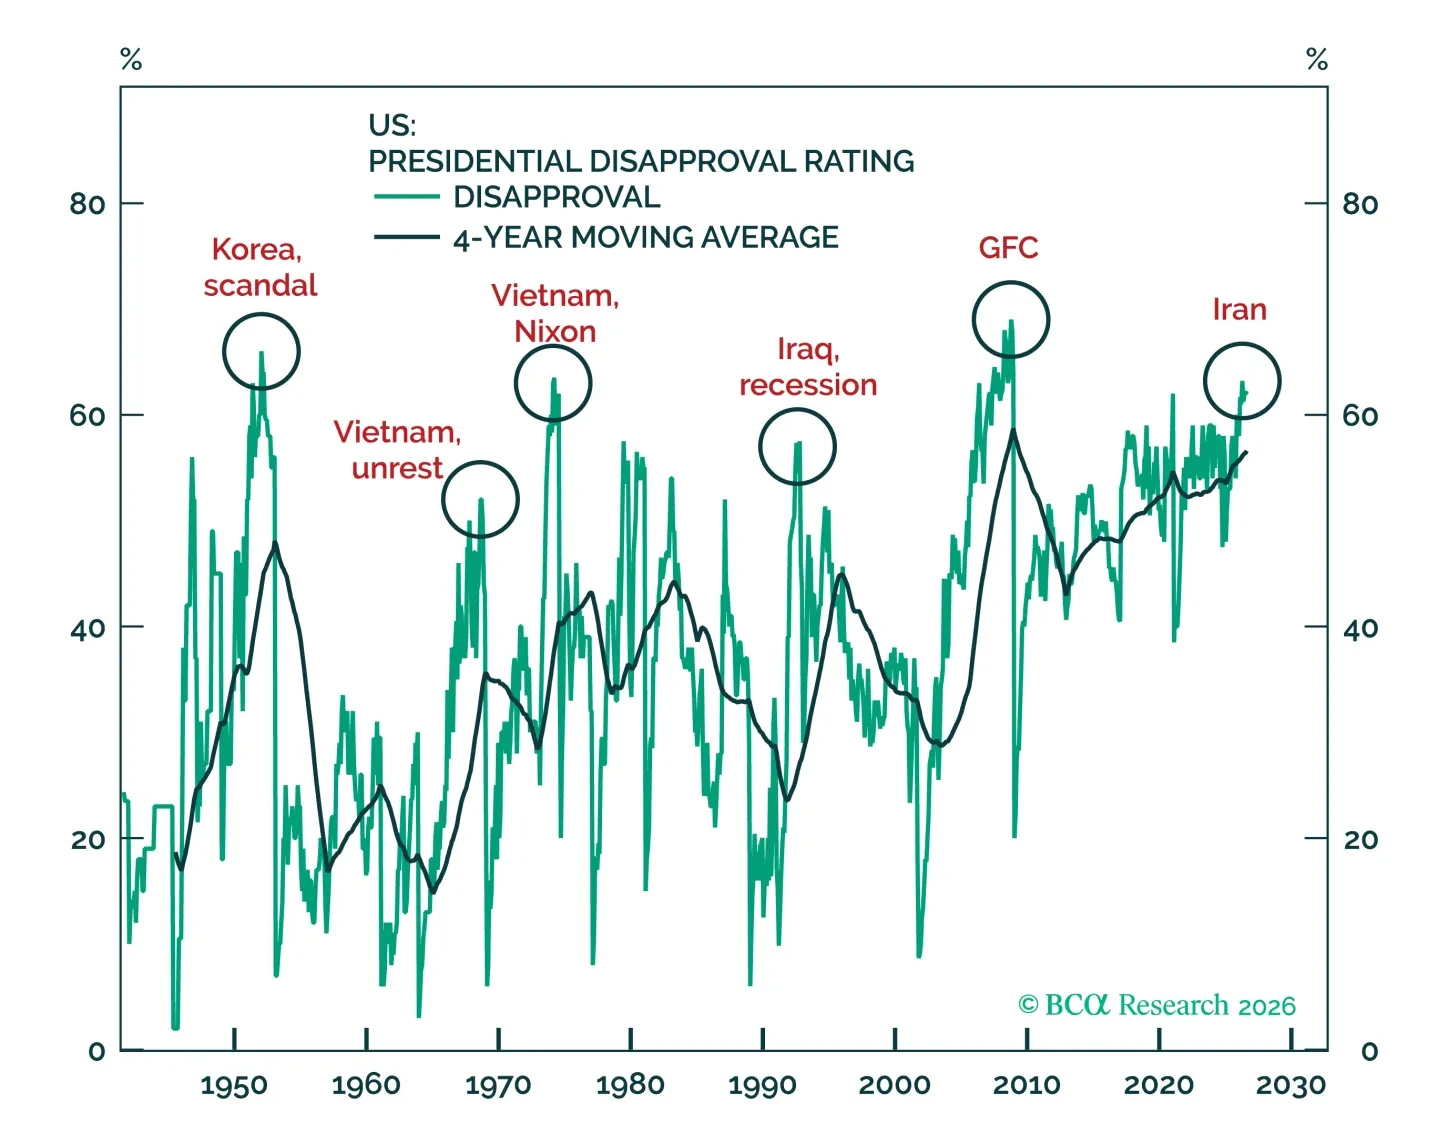
The big risk for the markets remains a flare up in the Middle East conflict. The Fed appears to be targeting geopolitics as much as inflation fundamentals. By the logic of transitive properties, therefore, more war means more hikes. That’s negative. So why are we not bearish on equities and bonds? Because President Trump holds his own faith in his hands. With his unfavourability near all-time highs (Chart of the Month), the conflict in Iran is at its end. Our worry? A Democratic Party sweep that surprises in its intensity and thus forces markets to start pricing in a leftward tilt in 2028.
Democratic candidate for the Texas Senate seat, James Talarico, has been leading his opponent, Republican Ken Paxton, for over a month in the betting markets. At the moment, Talarico’s probability of turning the Texas Senate seat blue is a whopping 65%. This is partly a result of Paxton’s flawed candidacy that builds on his dramatically flawed time as Texas’s attorney general. Remember, the staunchly Republican Texas House of Representatives voted to impeach Paxton in 2023!
Markets woke up to twin Houthi attacks on October 12. On October 9, the Yemen-based, Iran-allied, militant group attacked the King Khalid International Airport with a missile, killing 12 civilians and injuring over 300. Following that attack, President Trump suggested that the US “may” join Saudi Arabia’s fight against the Houthis. On October 11, the airport was struck again, with Saudi Arabia vowing to respond.
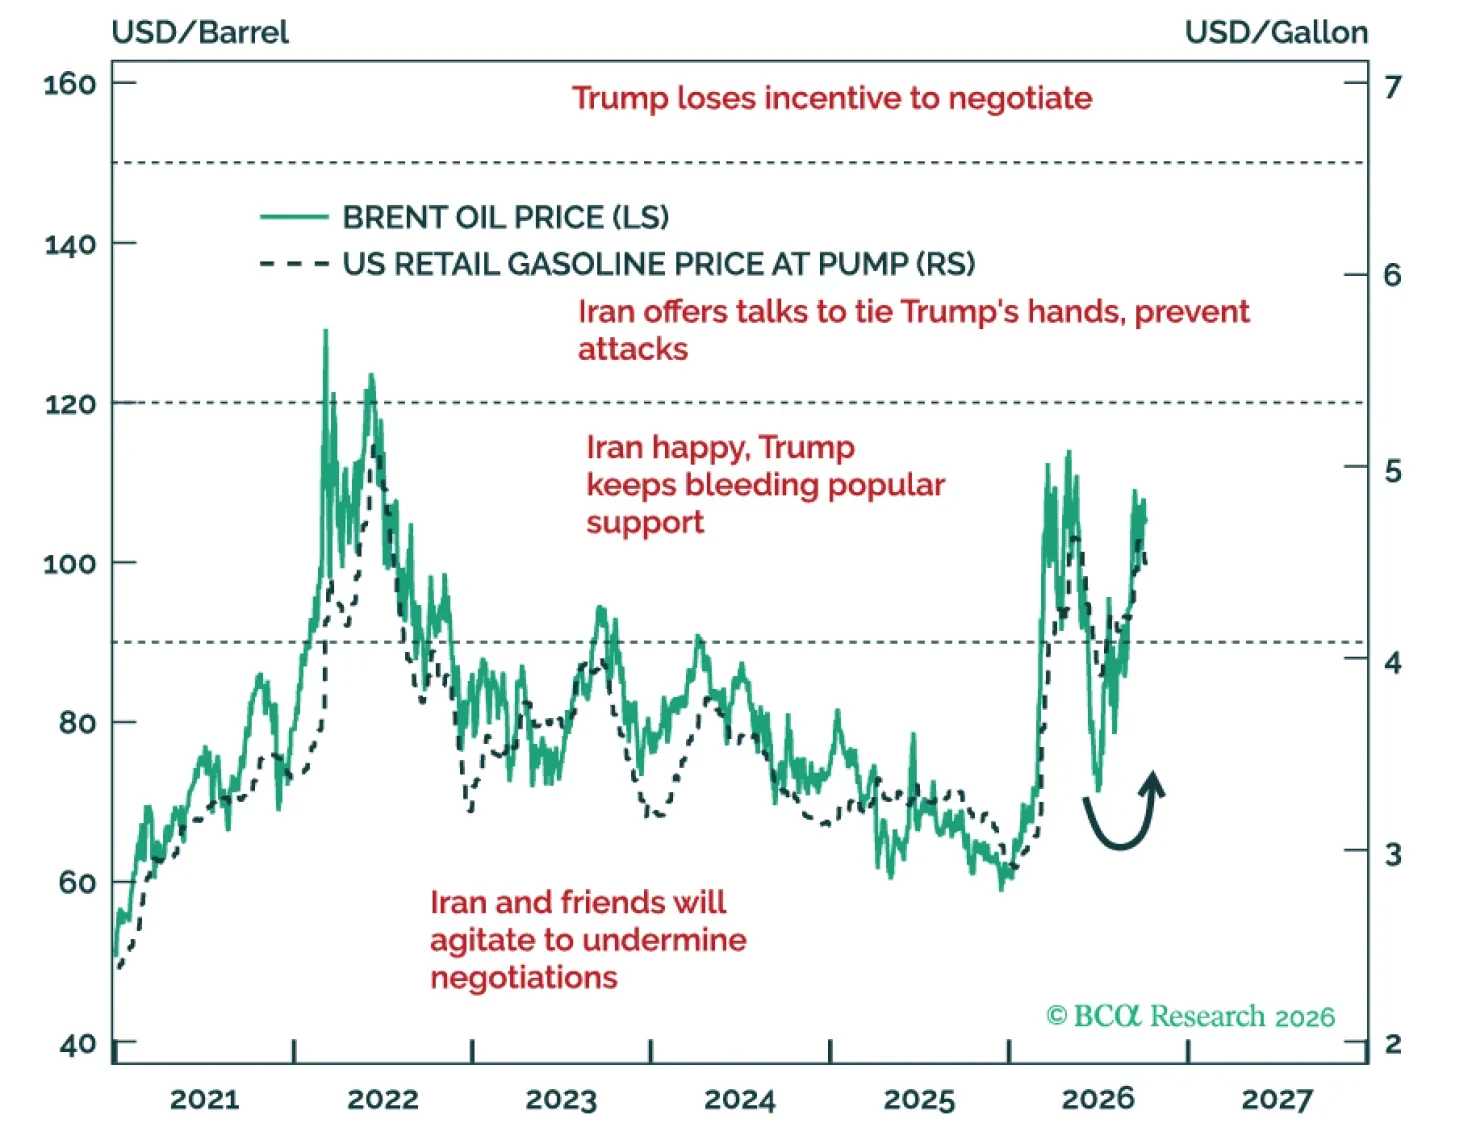
We keep the Global Geopolitical Risk Score at 8 because there are still no ceasefires in Europe or the Middle East. Russia is provoking NATO, which will need to push back. Iran, emboldened by the lack of definitive US success, pushes its luck, which could invite a destructive response from the US. The Chinese economy remains fragile, increasing the likelihood of foreign belligerence. After the US midterm, President Trump faces fewer political constraints, allowing him to pursue a maximalist foreign policy to cement his legacy during his lame-duck period.
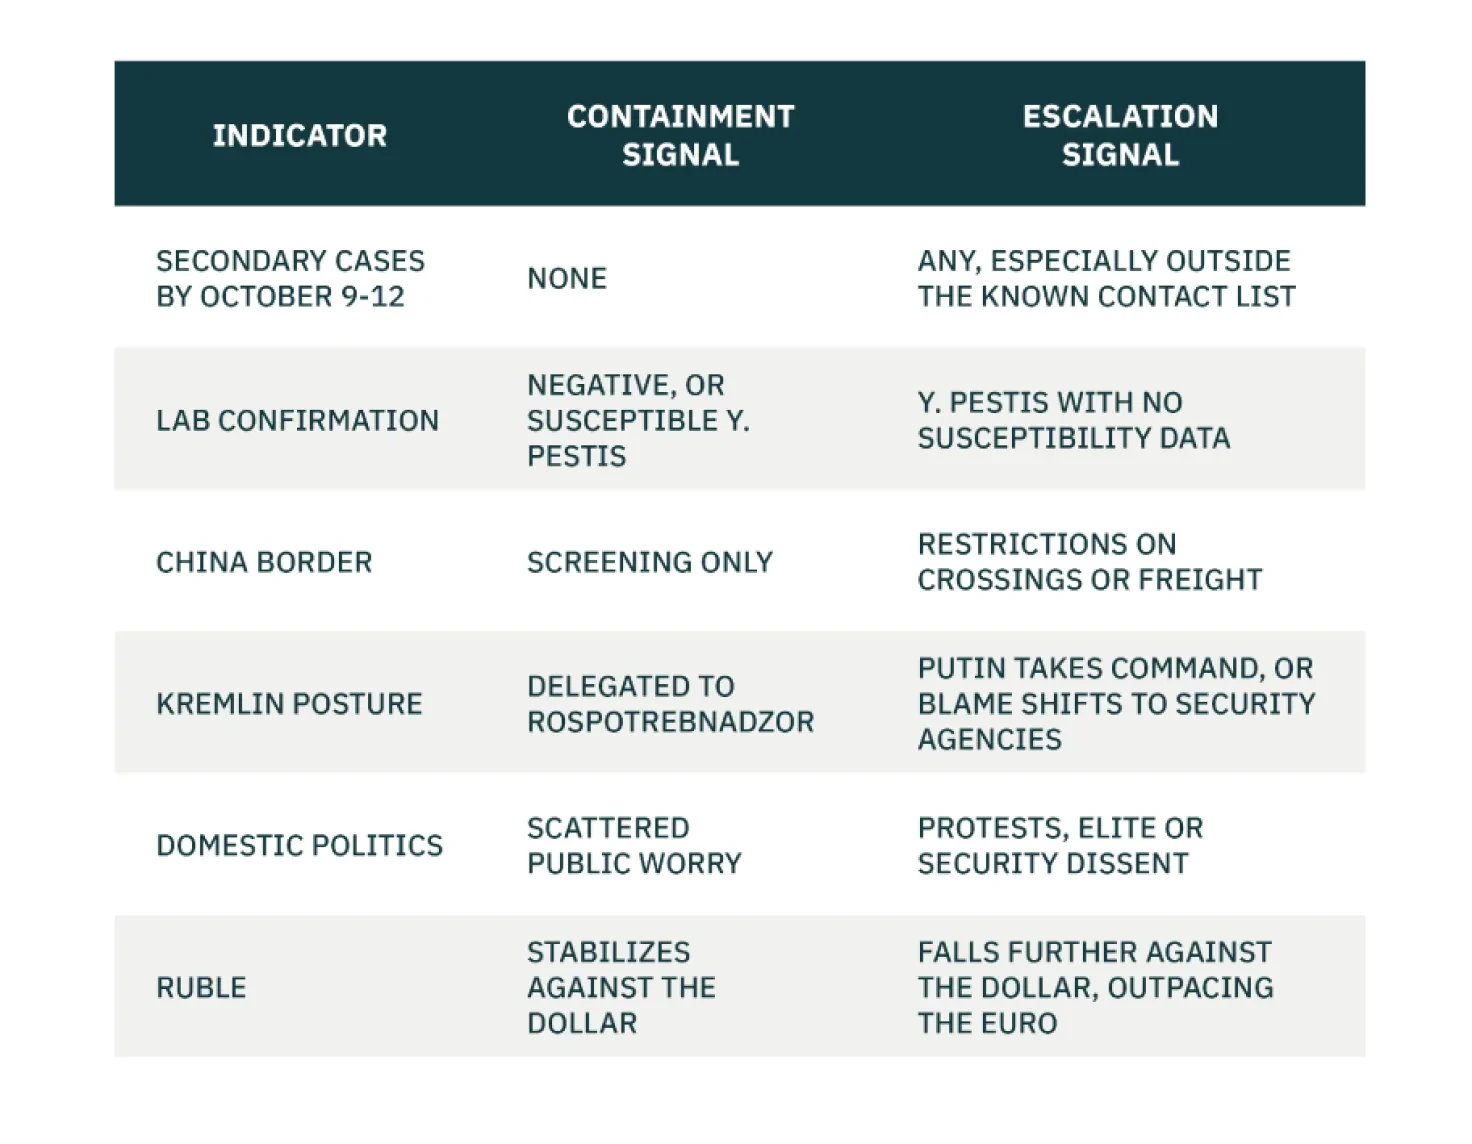
The Irkutsk plague scare is not yet a crisis, but if it becomes one, Russia is a bad place for it to happen.
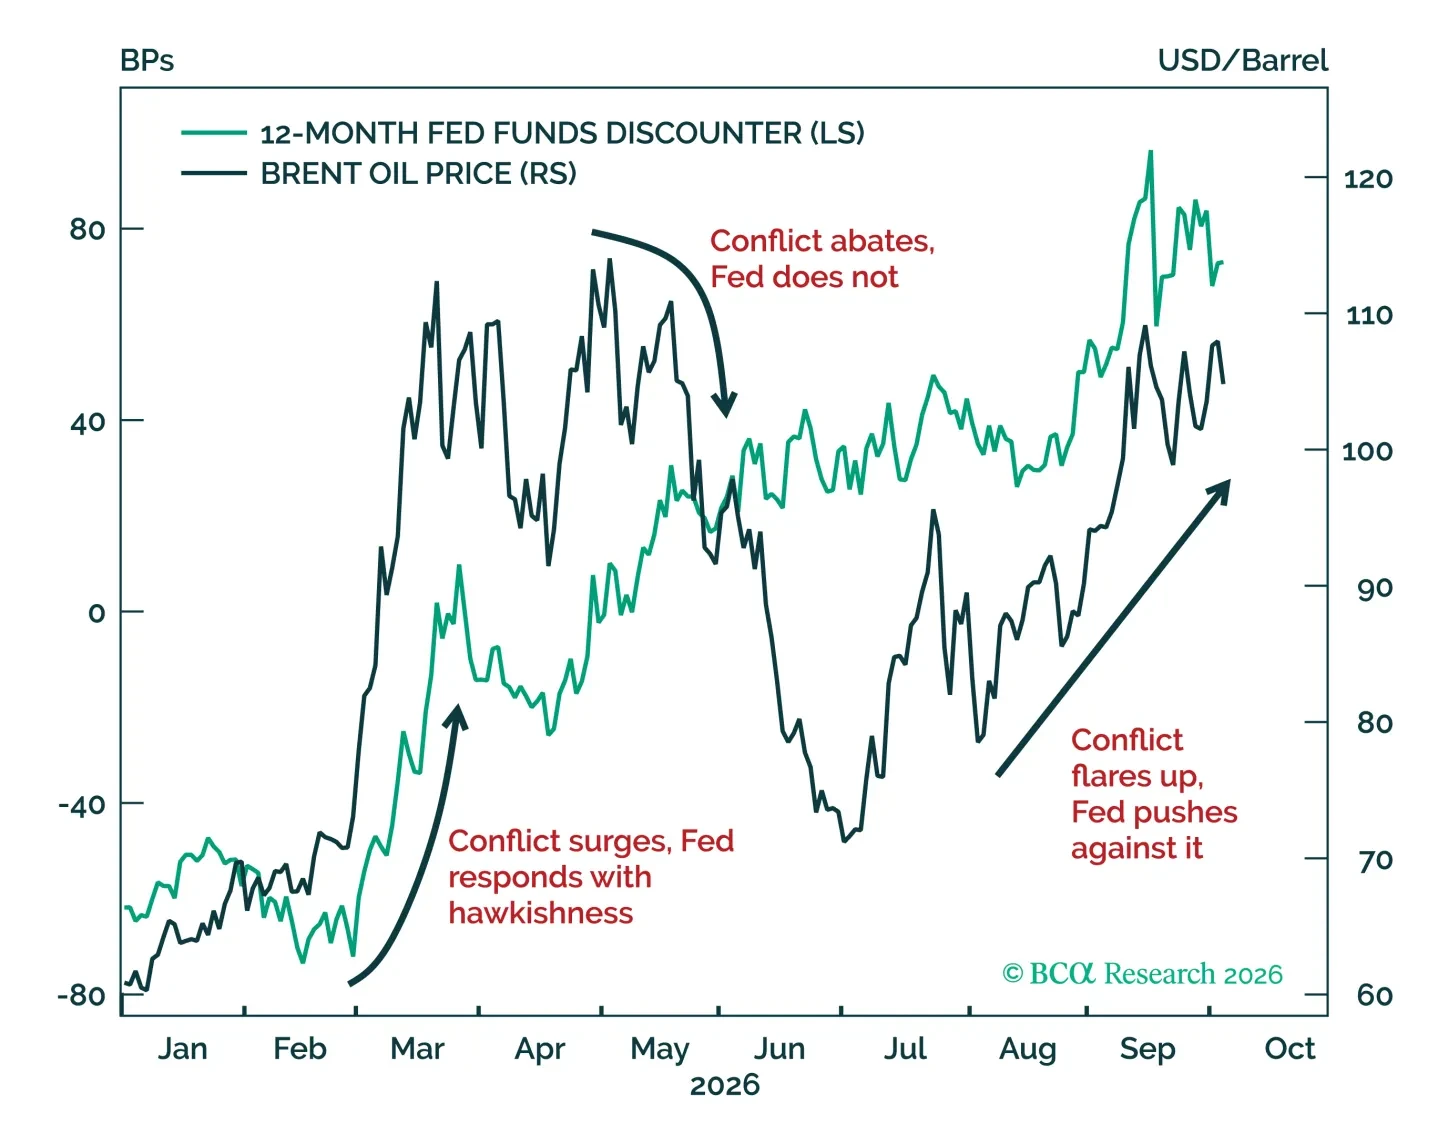
Long-dated bond yields rose another 48 bps since our last missive, quite a move in just a month. And yet, equities have remained resilient. This suggests that the move in bond yields is due to sanguine economic forces, not fiscal profligacy or inflation fears. In addition, the war in Iran is subsiding, partly because the Fed itself has conspired against it. Will President Trump restart the conflict regardless? Perhaps, however, the constraints are mounting against the White House foreign policy. We remain bullish on equities and reaffirm our view that investors with a long-term horizon should be nibbling at the current level of yields. To make sure that our bearish clients are happy, we pivot to the risk of higher tax rates in the US. Specifically, we try to answer the question of when markets price higher tax rates.
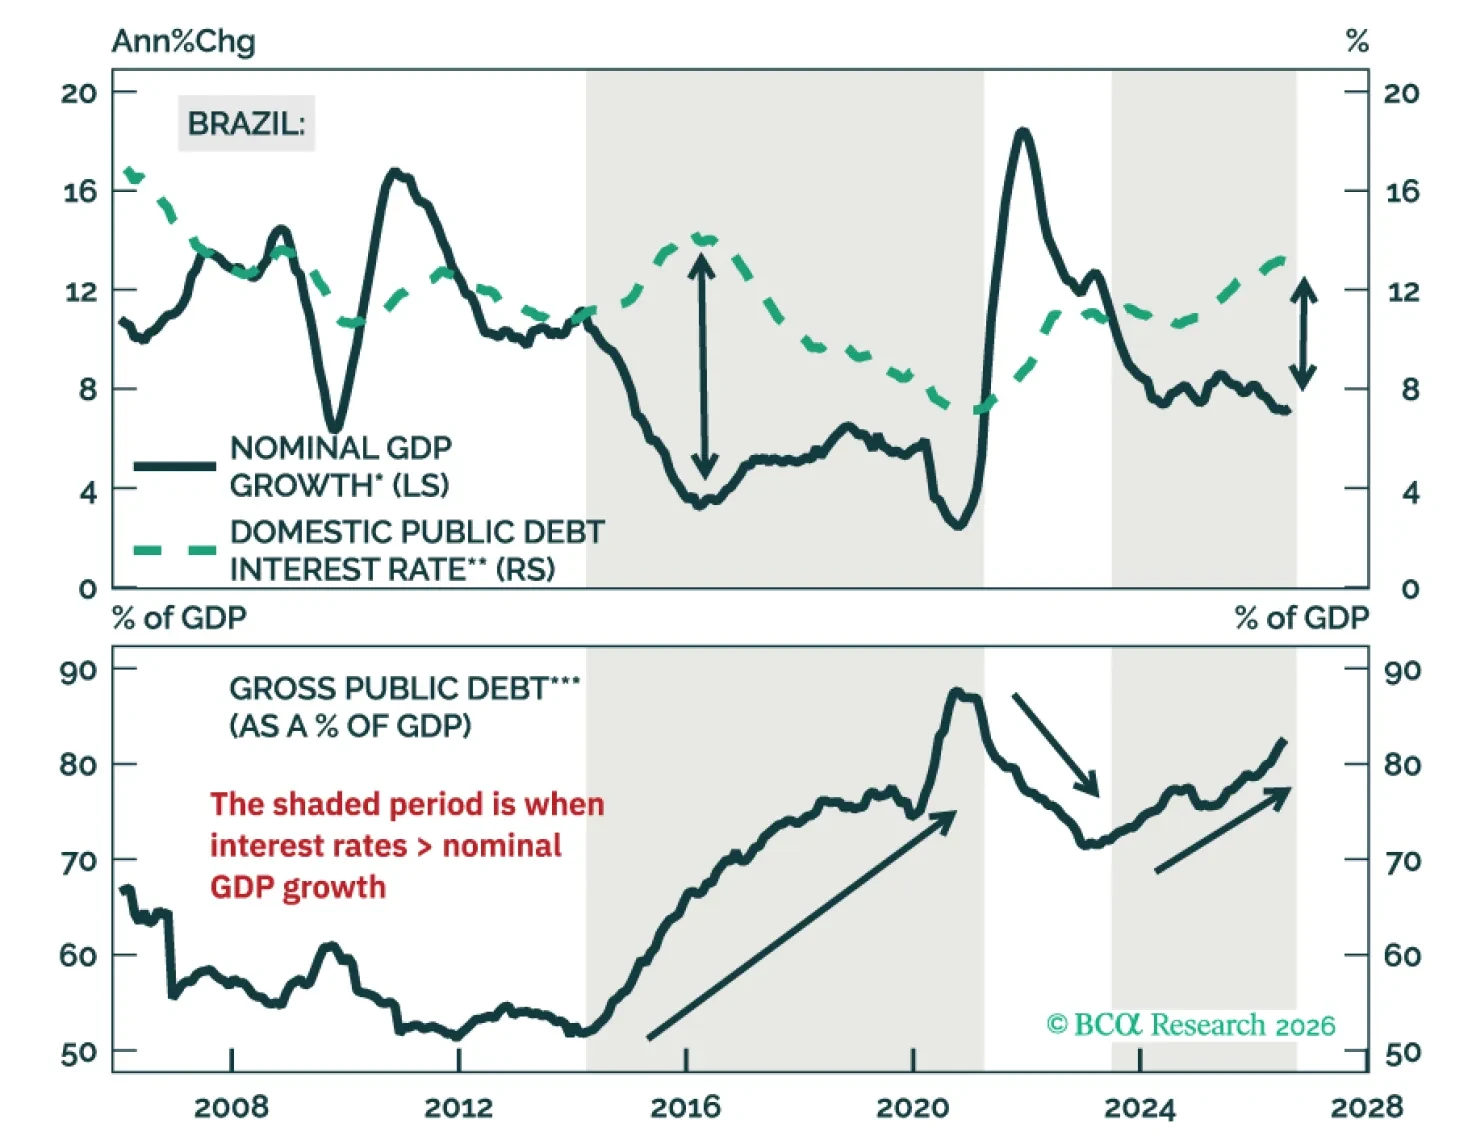
The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.
Most investors would argue that Europe overregulates relative to the US. However, that was not always the case. Political Scientist David Vogel of University of California, Berkeley, posited that the two economies shifted models in the 1990s. Prior to that decade, the US led health, safety, and environmental regulations, having far more stringent rules than Europe. As a prominent example of this, it was the US that quickly banned all non-essential CFCs, chemicals that harm the ozone layer, whereas European governments did not act initially, favoring their industries while awaiting evidence.