 Equities
| US Equities
US equity research, from the S&P 500 to sectors and factors, on where stocks are heading next.
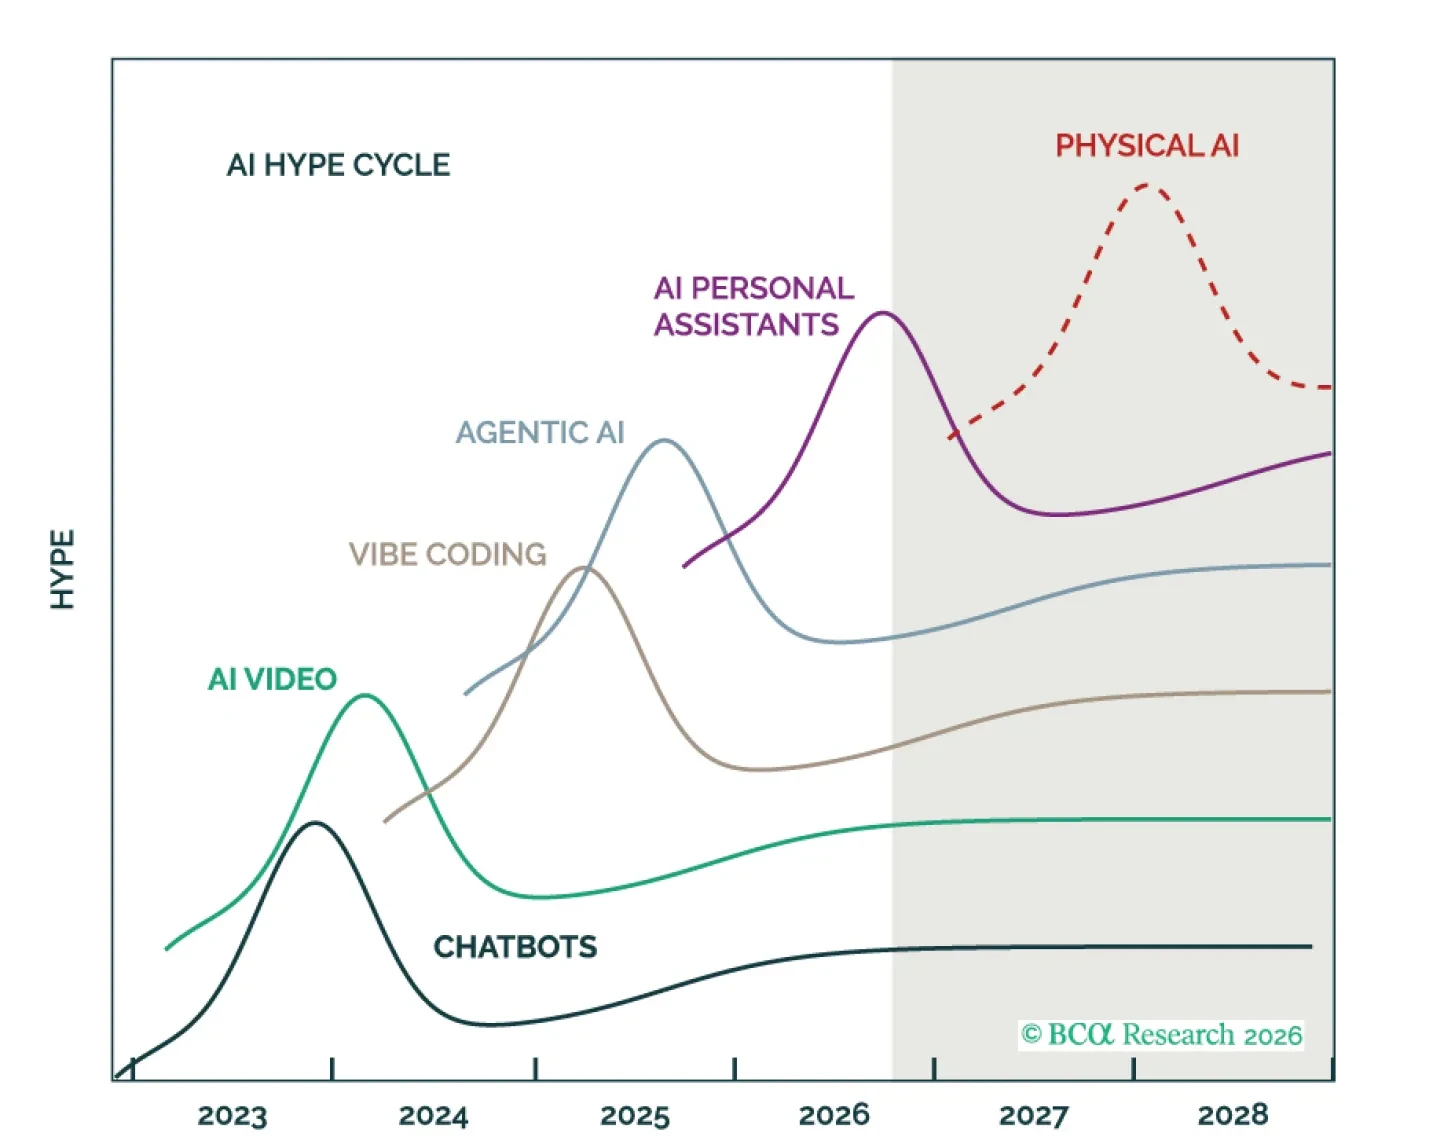
Since ChatGPT’s launch in late 2022, multiple waves of AI innovation have driven markets and dominated the conversation across the investment community. Drawing on an extensive set of questions from BCA clients and strategists, our new report tackles the uncertainties that remain: What beyond customer demand drives token consumption? Will open-weight models eventually dominate? And, perhaps most importantly, how worried should we be about AI-induced extinction?
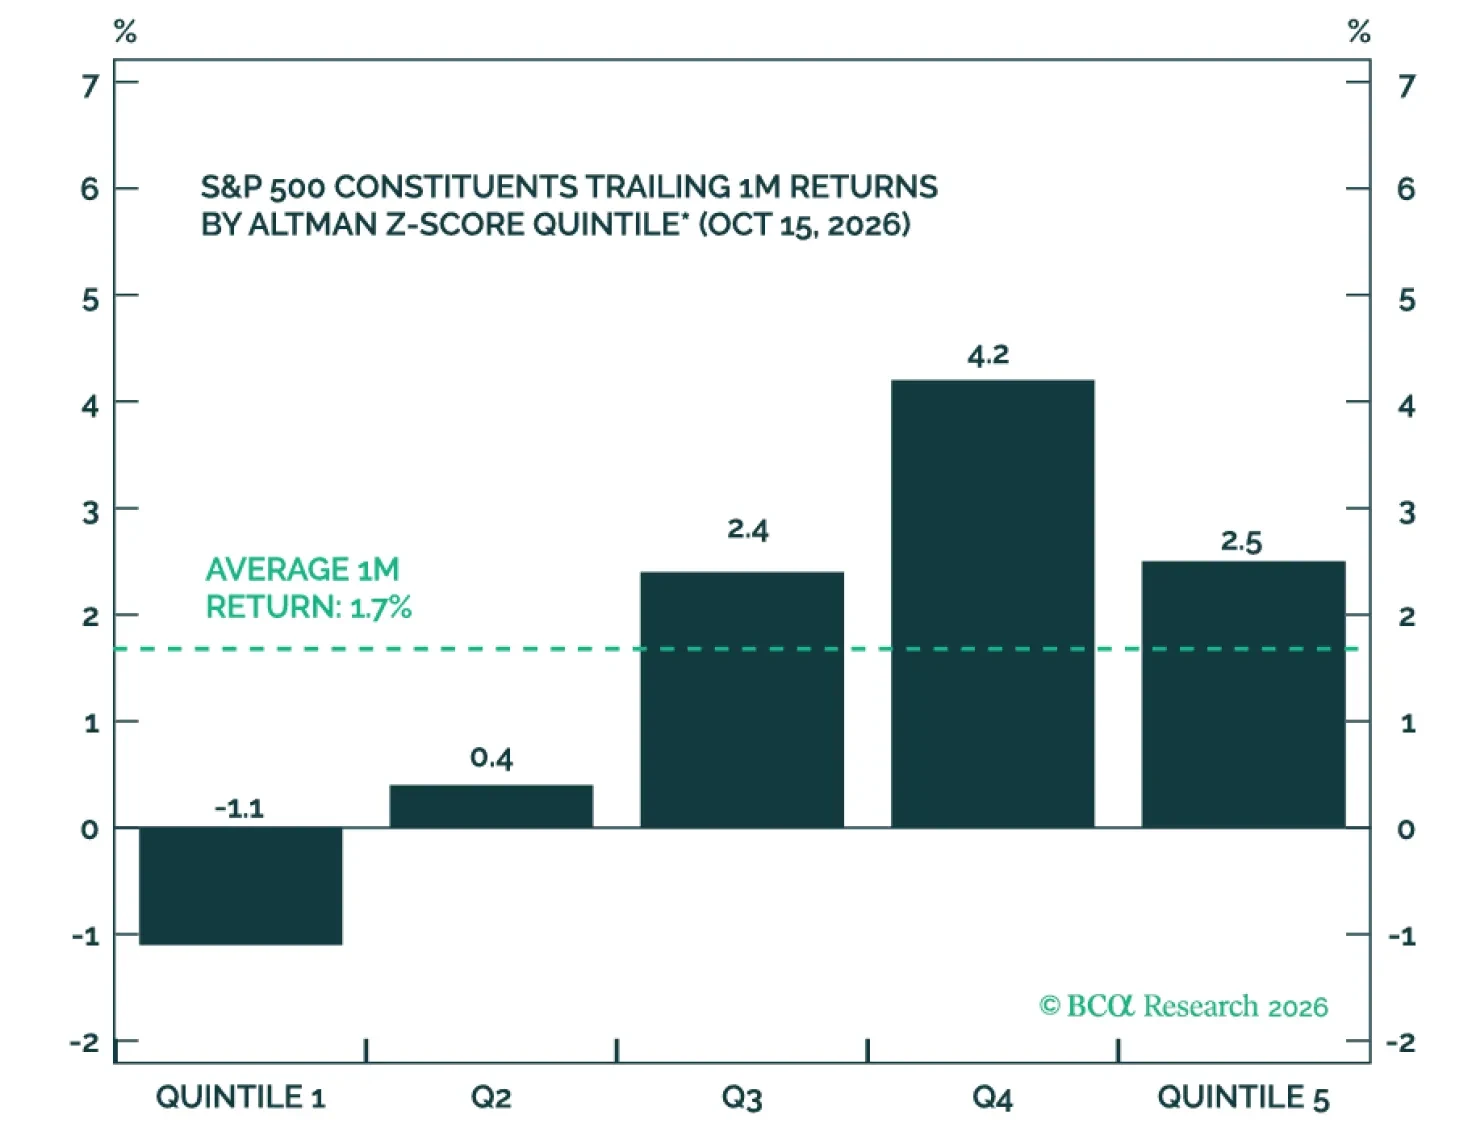
Credit spreads have widened as bond risks intensified, pressuring weak-balance-sheet companies. But the stress is narrow and valuations have already compressed, so equity risks look manageable. Rather than de-risk, we would lean into quality: large over small caps, quality capex, and defensible Tech margins, and look to Q3 earnings for confirmation.
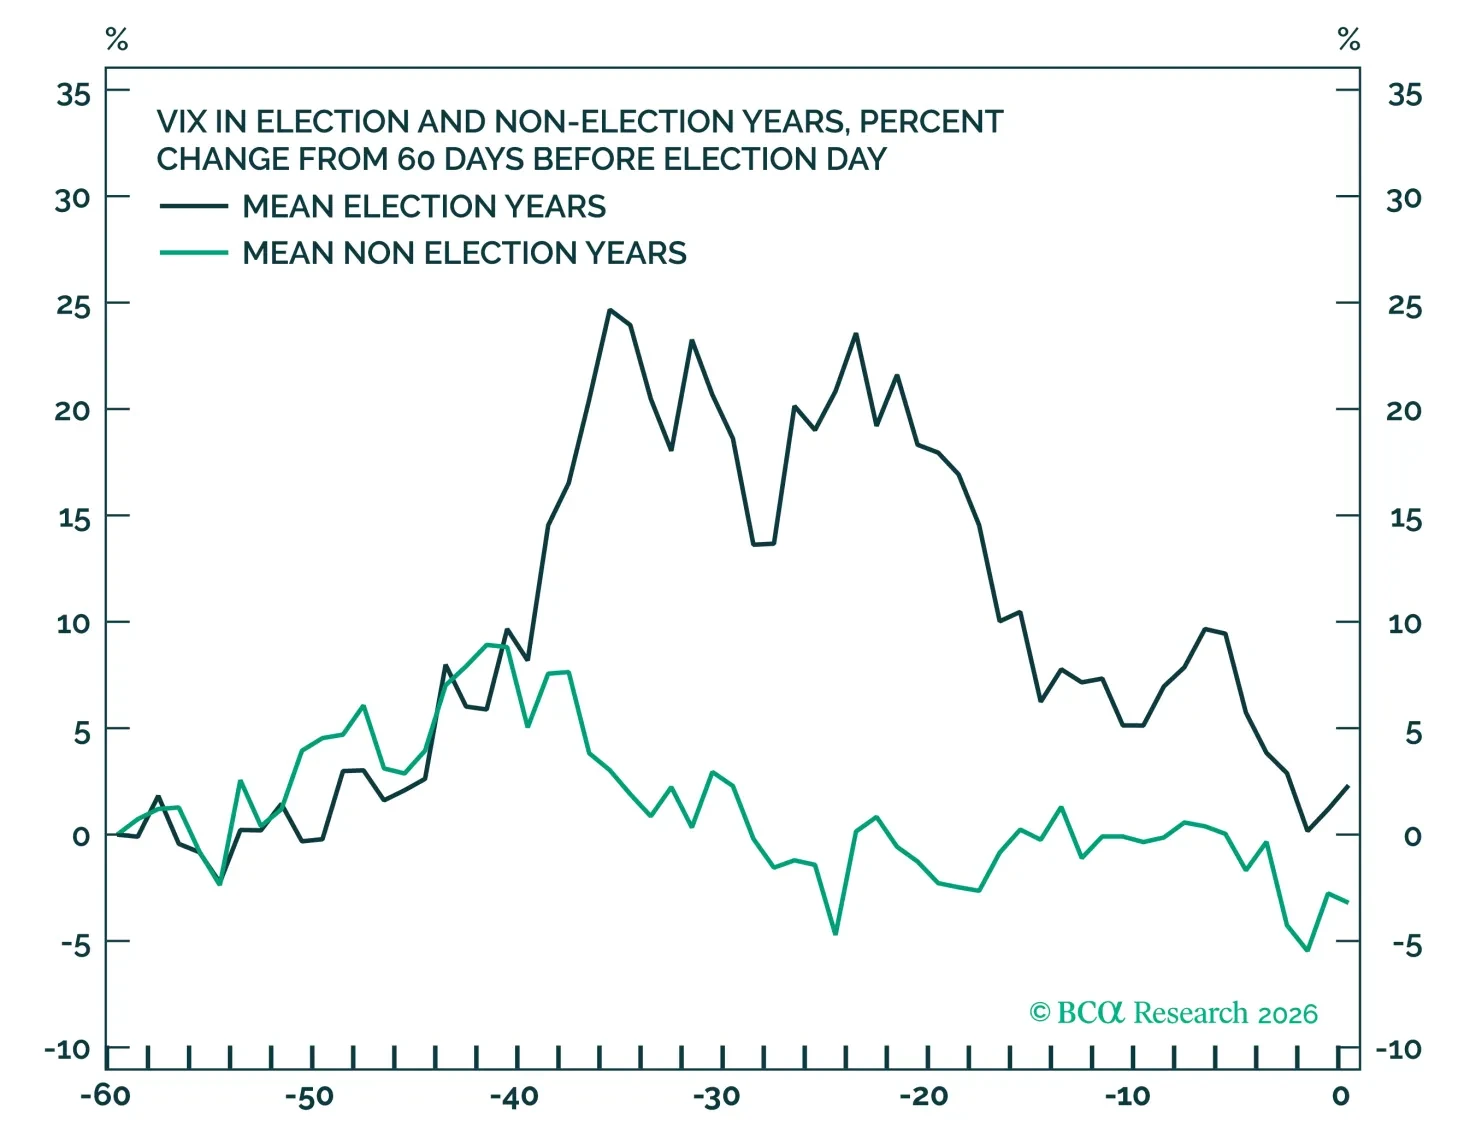
Betting markets give Democrats a 90%-plus chance of flipping the House, but history suggests a midterm flip is business as usual, not a signal for 2028. Volatility measures suggest little of the typical election risk is priced at the index level, but stock-level volatility is elevated, particularly in politically sensitive sectors, and politically exposed stocks are underperforming. Index protection looks inexpensive.
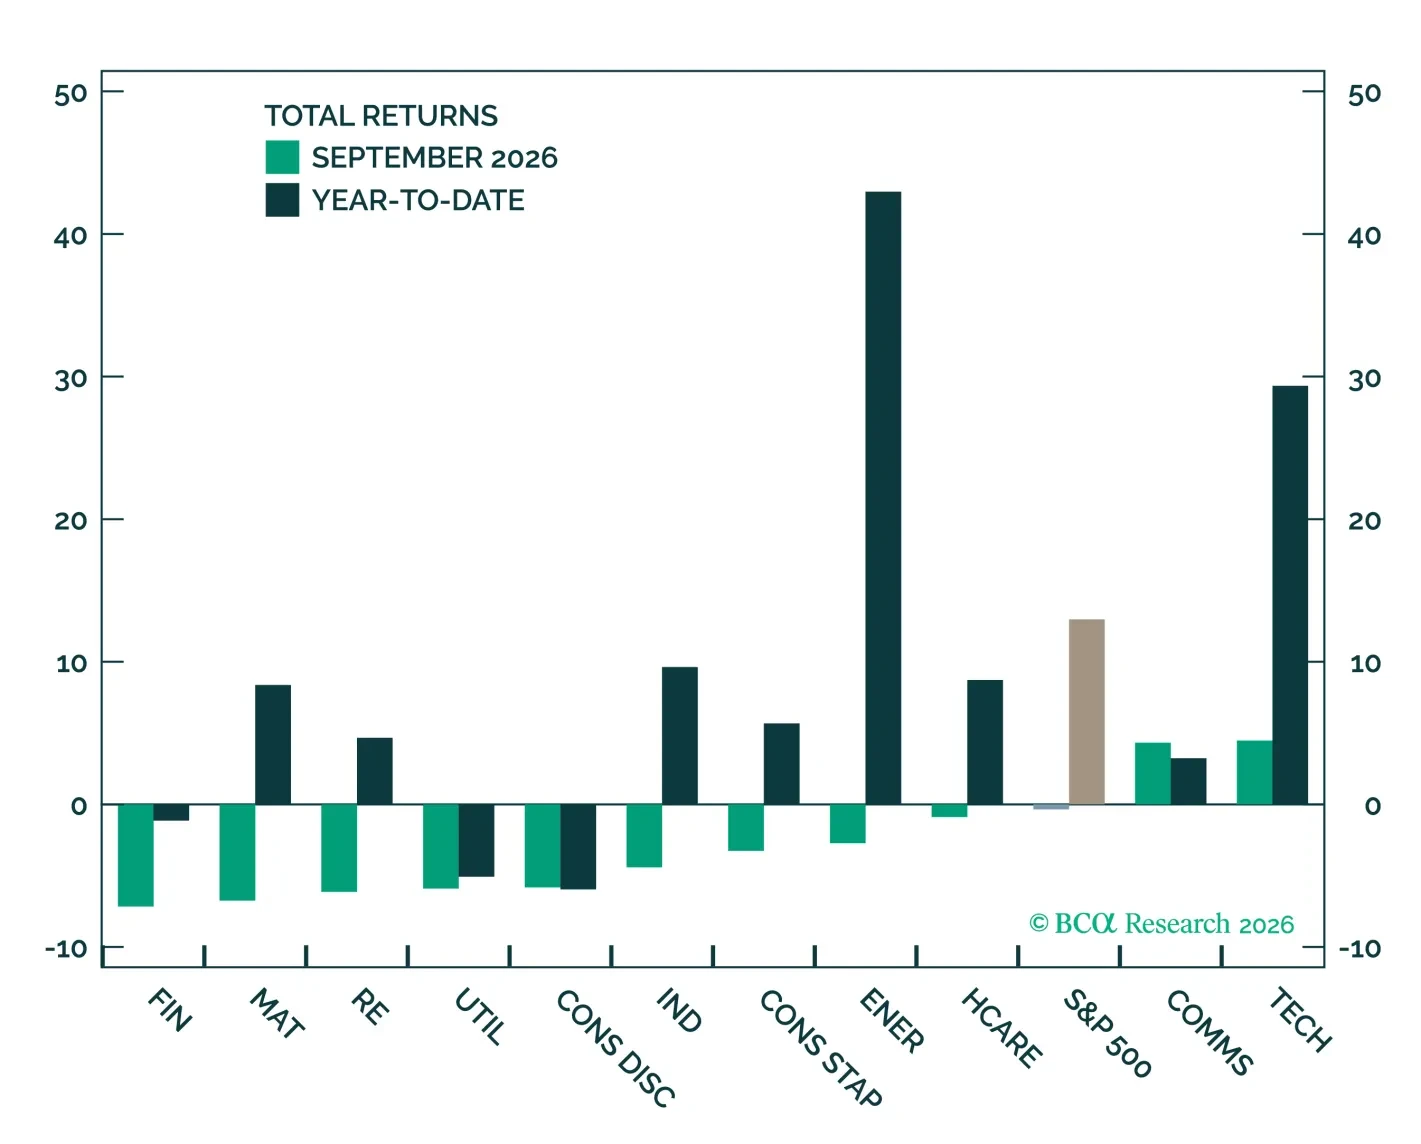
As the 10-year yield surged in September, the S&P 500 slipped but only by 0.3%, supported by Technology and Communication Services. We see upside into year end, with bond yields remaining the key risk.
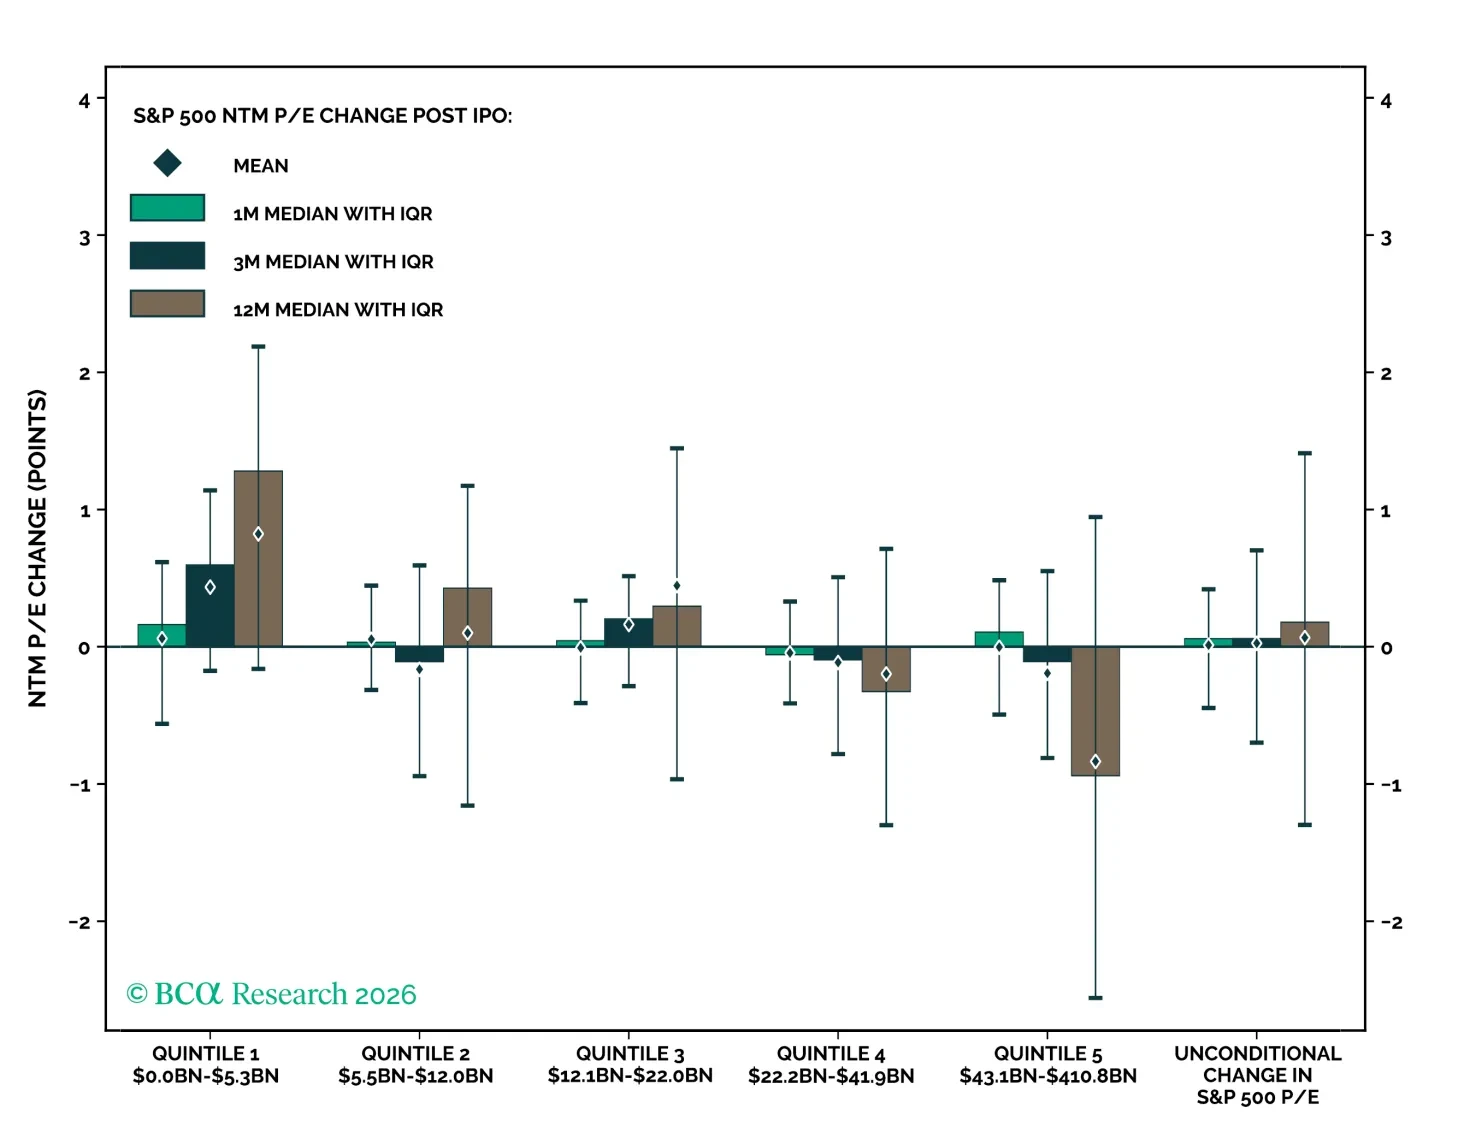
The IPO wave has arrived, dominated by SpaceX’s massive listing. Aftermarket performance has been weak, and elevated issuance is weighing on S&P 500 multiples, although some pressure is already priced. SpaceX remains only partly digested, while Anthropic and OpenAI will bring further supply and greater business model scrutiny.
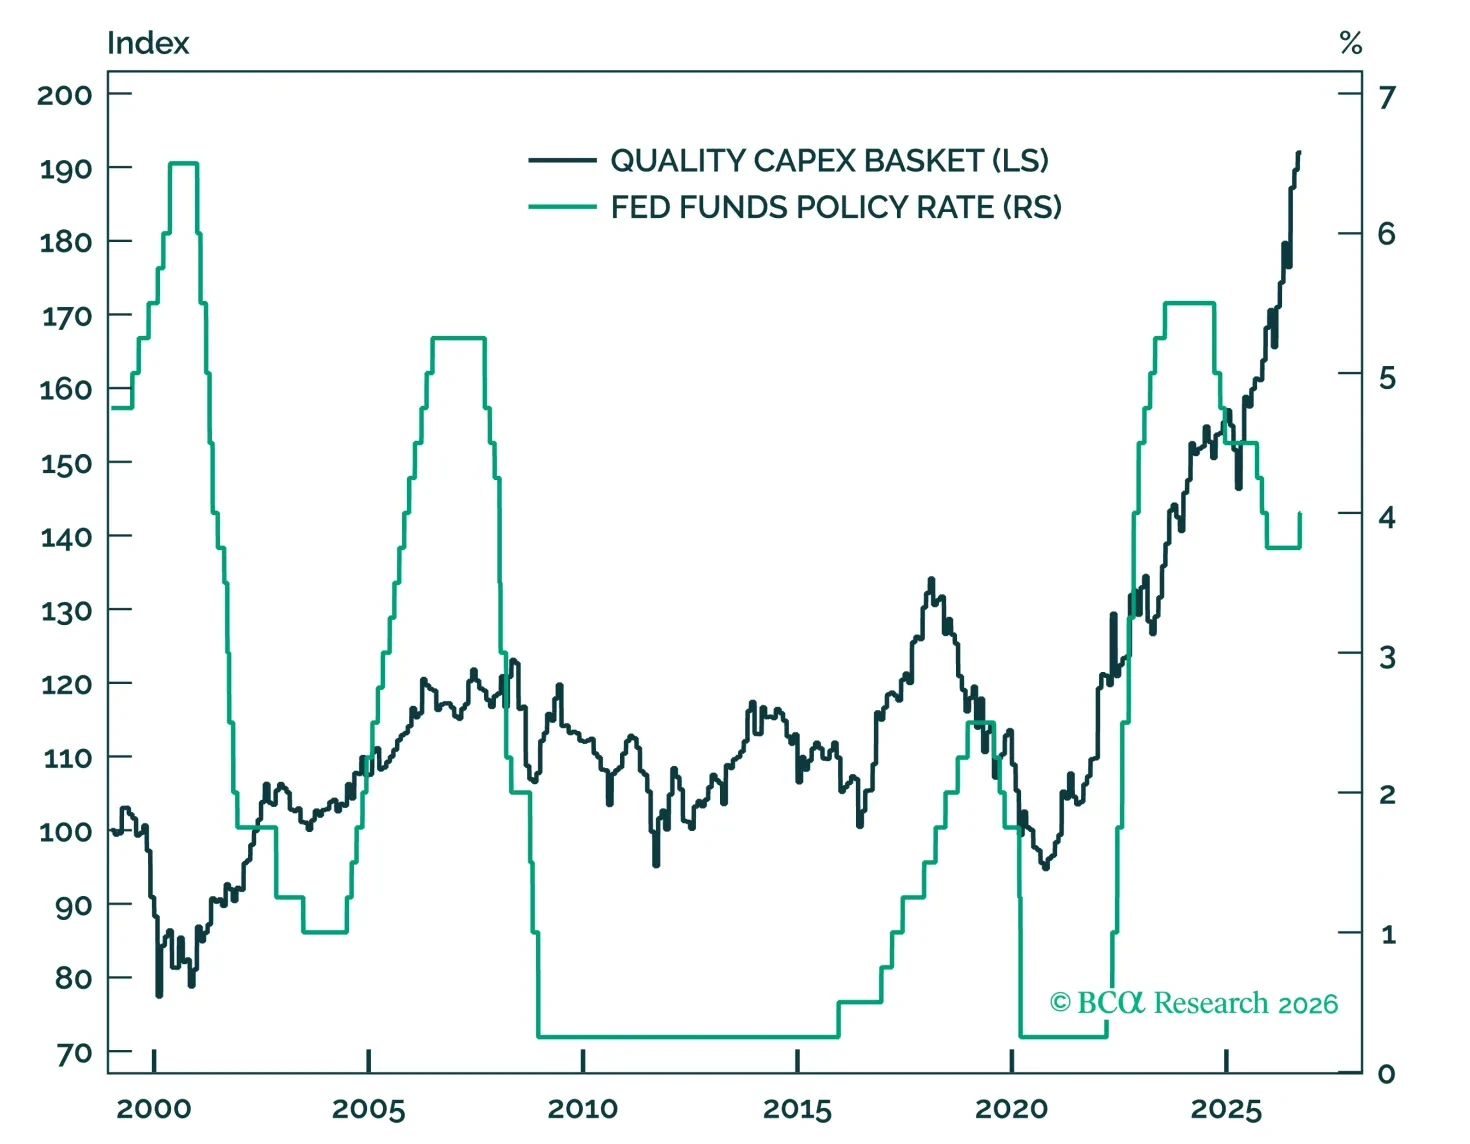
The Fed’s first hike is unlikely to be an equity-market cliff. Recent multiple compression has absorbed some of the rate shock, while bond risk premia, rate volatility, and inflation expectations remain contained. Stocks have typically climbed through hiking cycles, but we favor moving up in quality through our long/short Quality Capex Basket.
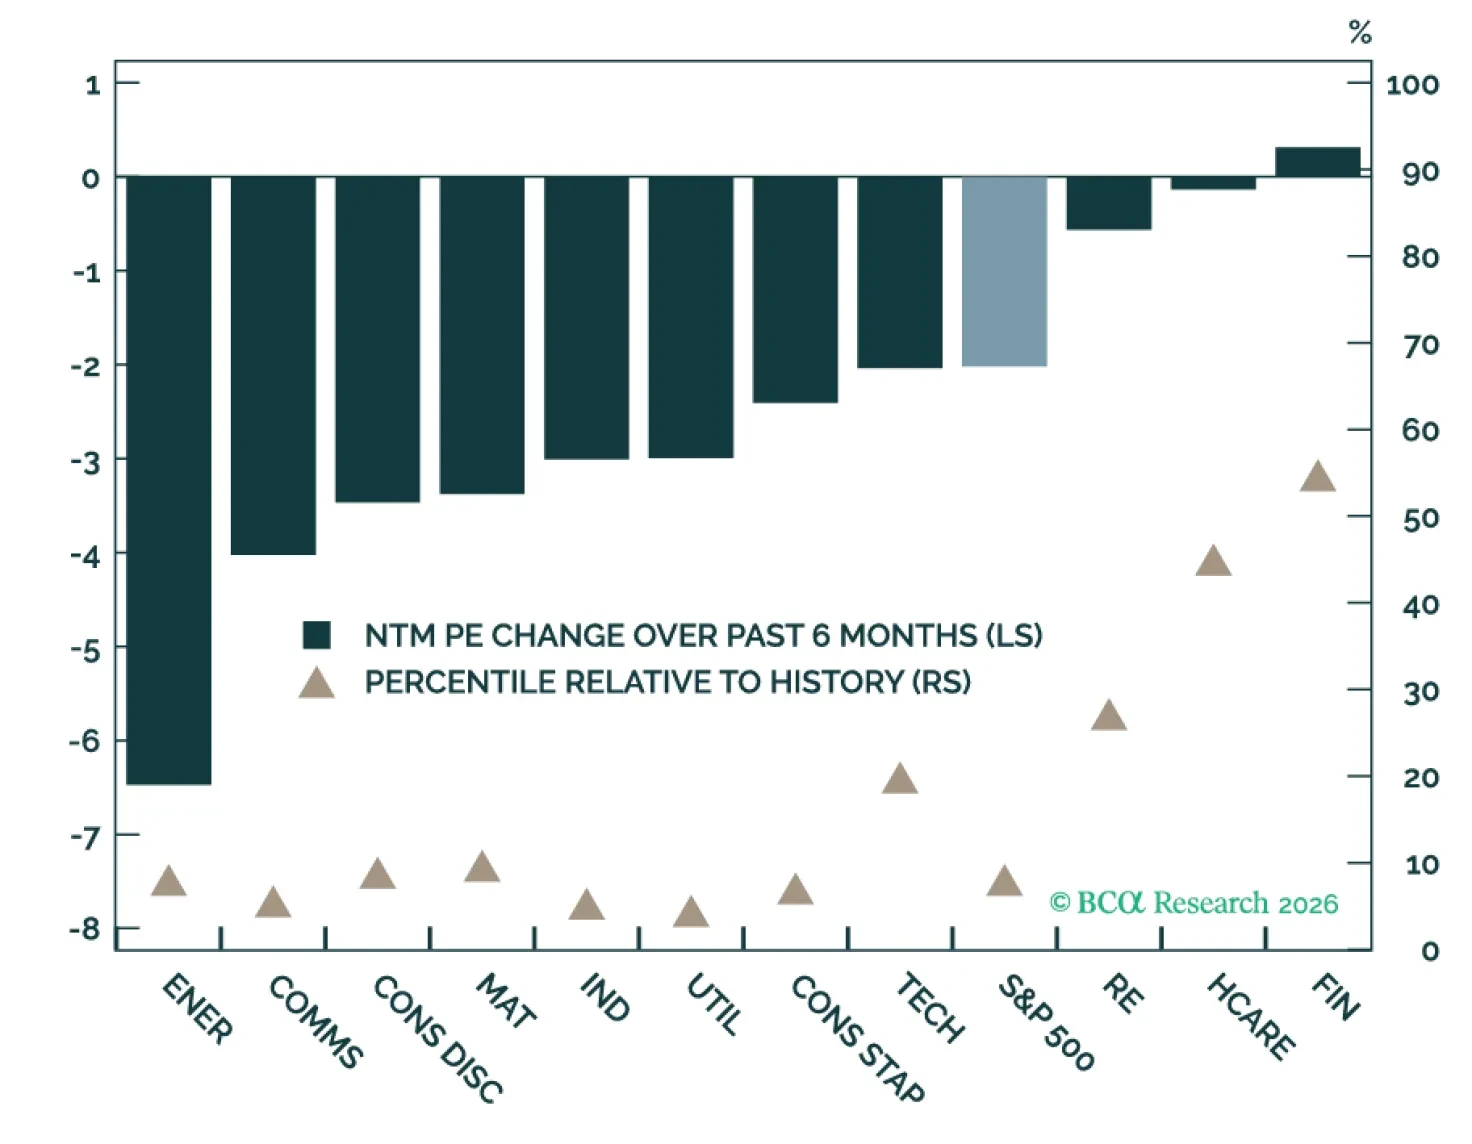
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
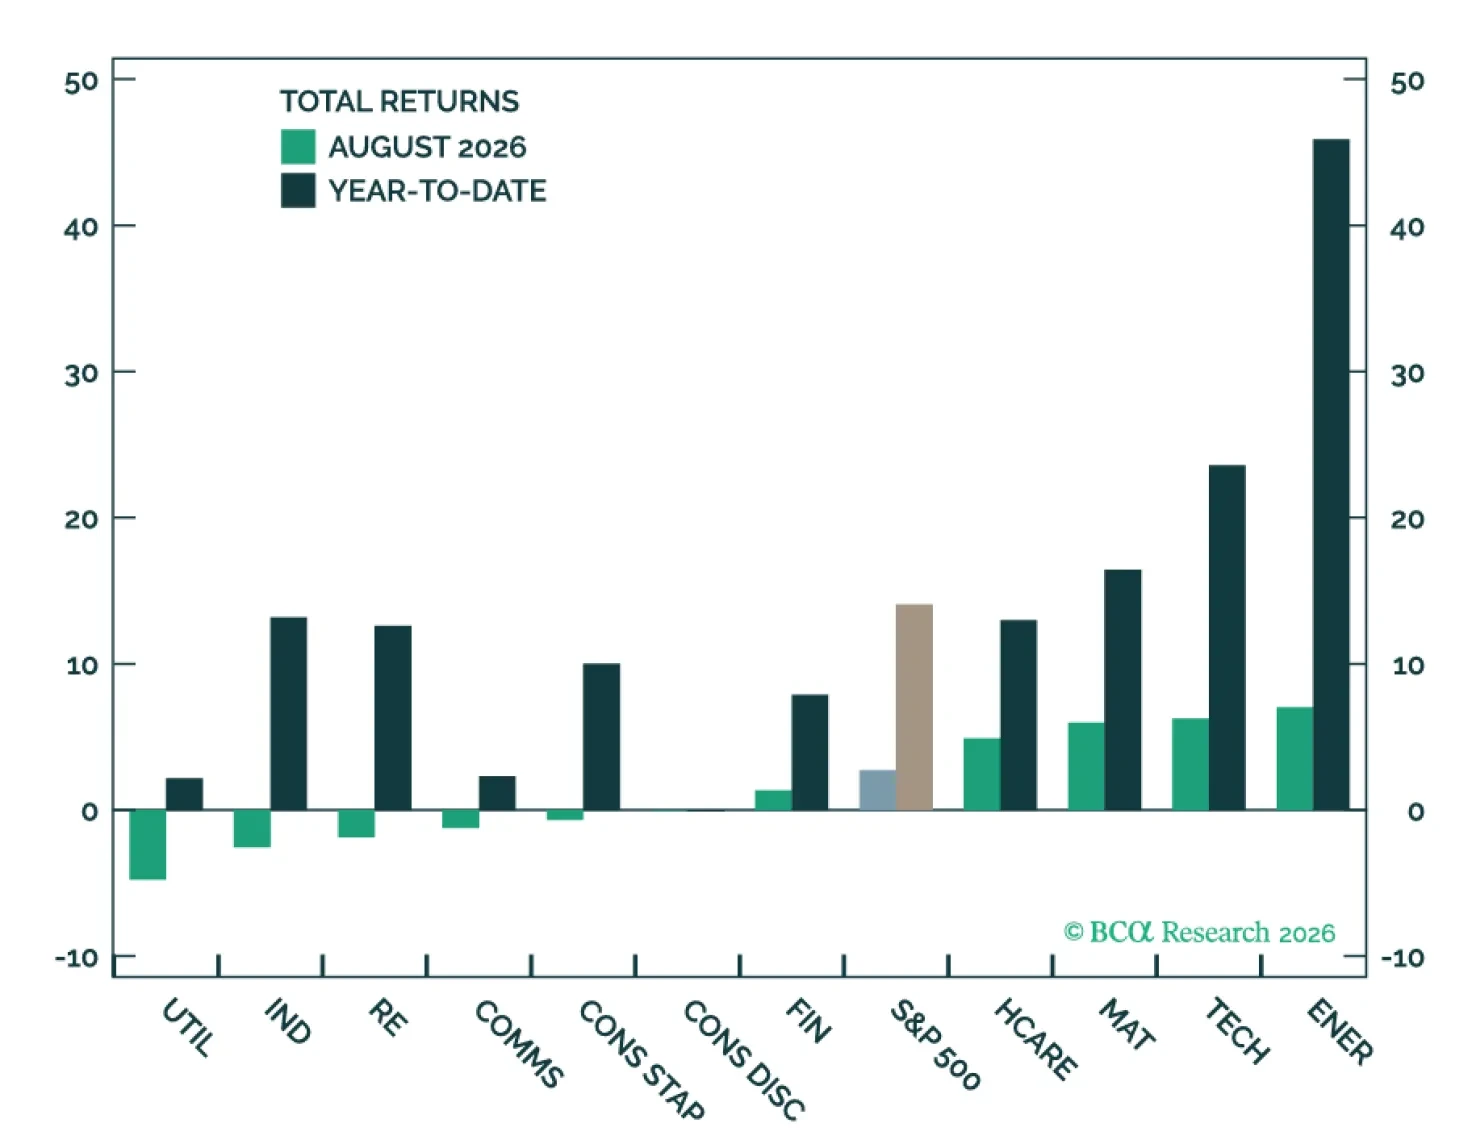
Strong second quarter earnings suggest that the AI story is intact. Buoyed in part by this strength, tech stocks have recoupled with healthy fundamentals after a late-July swoon, posting solid August gains. We continue to see upside for the S&P 500, favoring the cyclical and AI exposure of tech, materials, and industrials. But rising bond yields remain the dominant headwind.
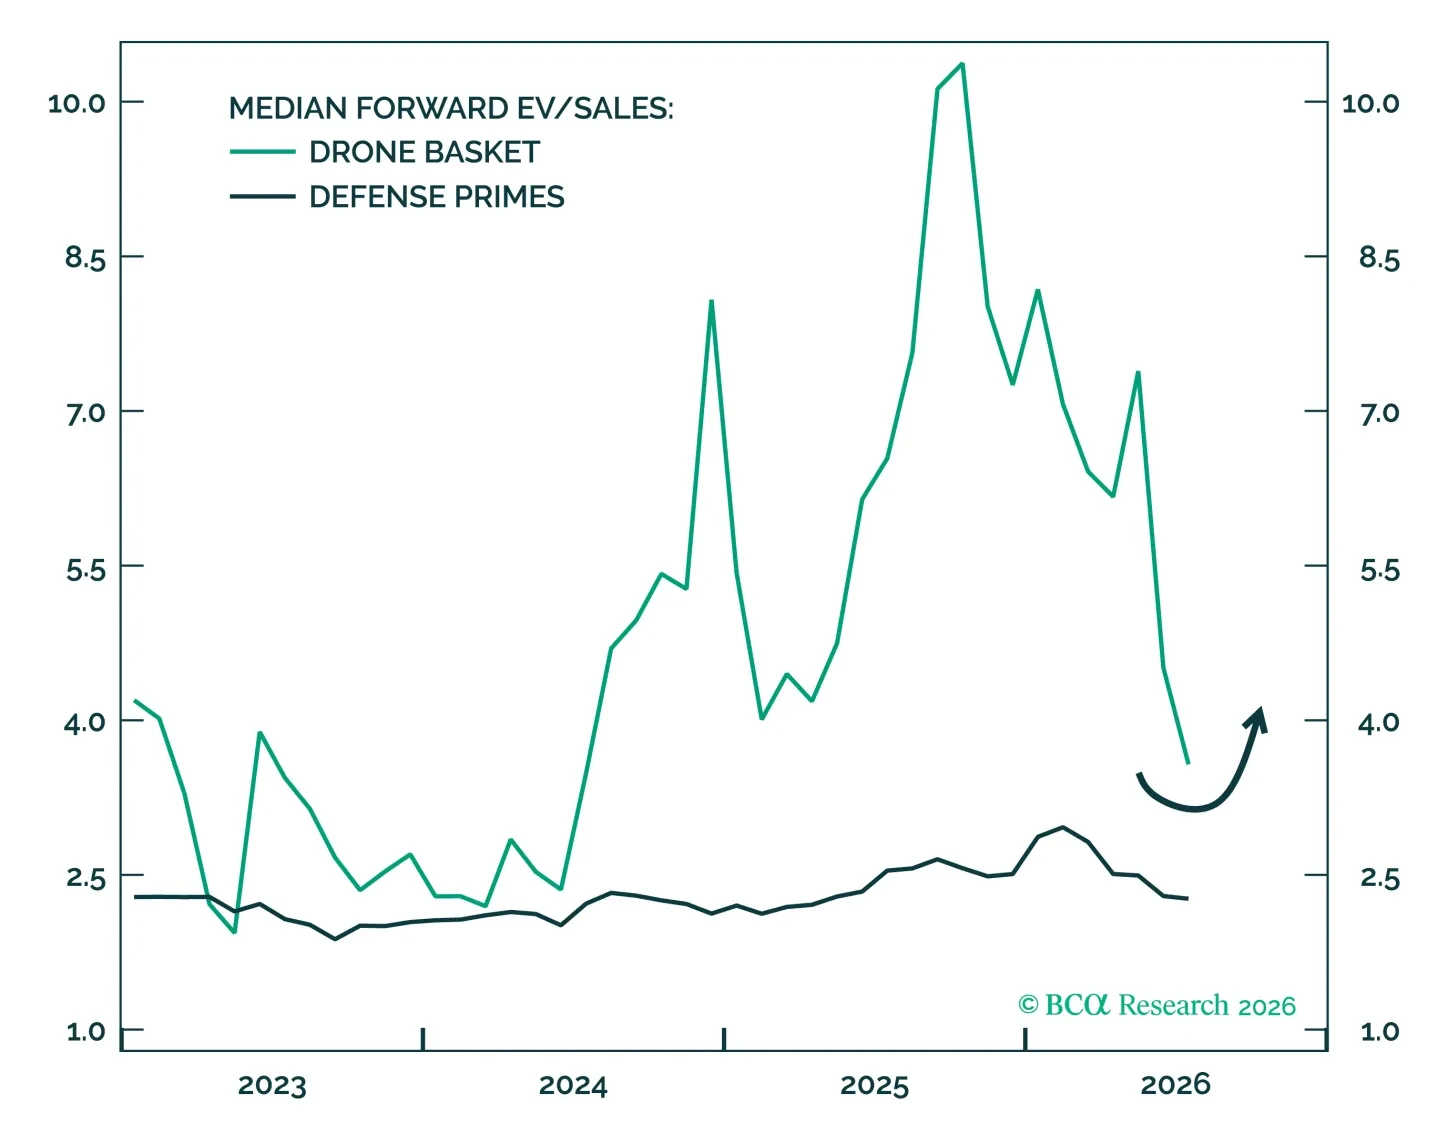
US aerospace and defense stocks still have a structural tailwind from geopolitics, but face rising cyclical challenges from macro and market fundamentals, as well as eventual Iran and Ukraine ceasefires and political change in the United States.
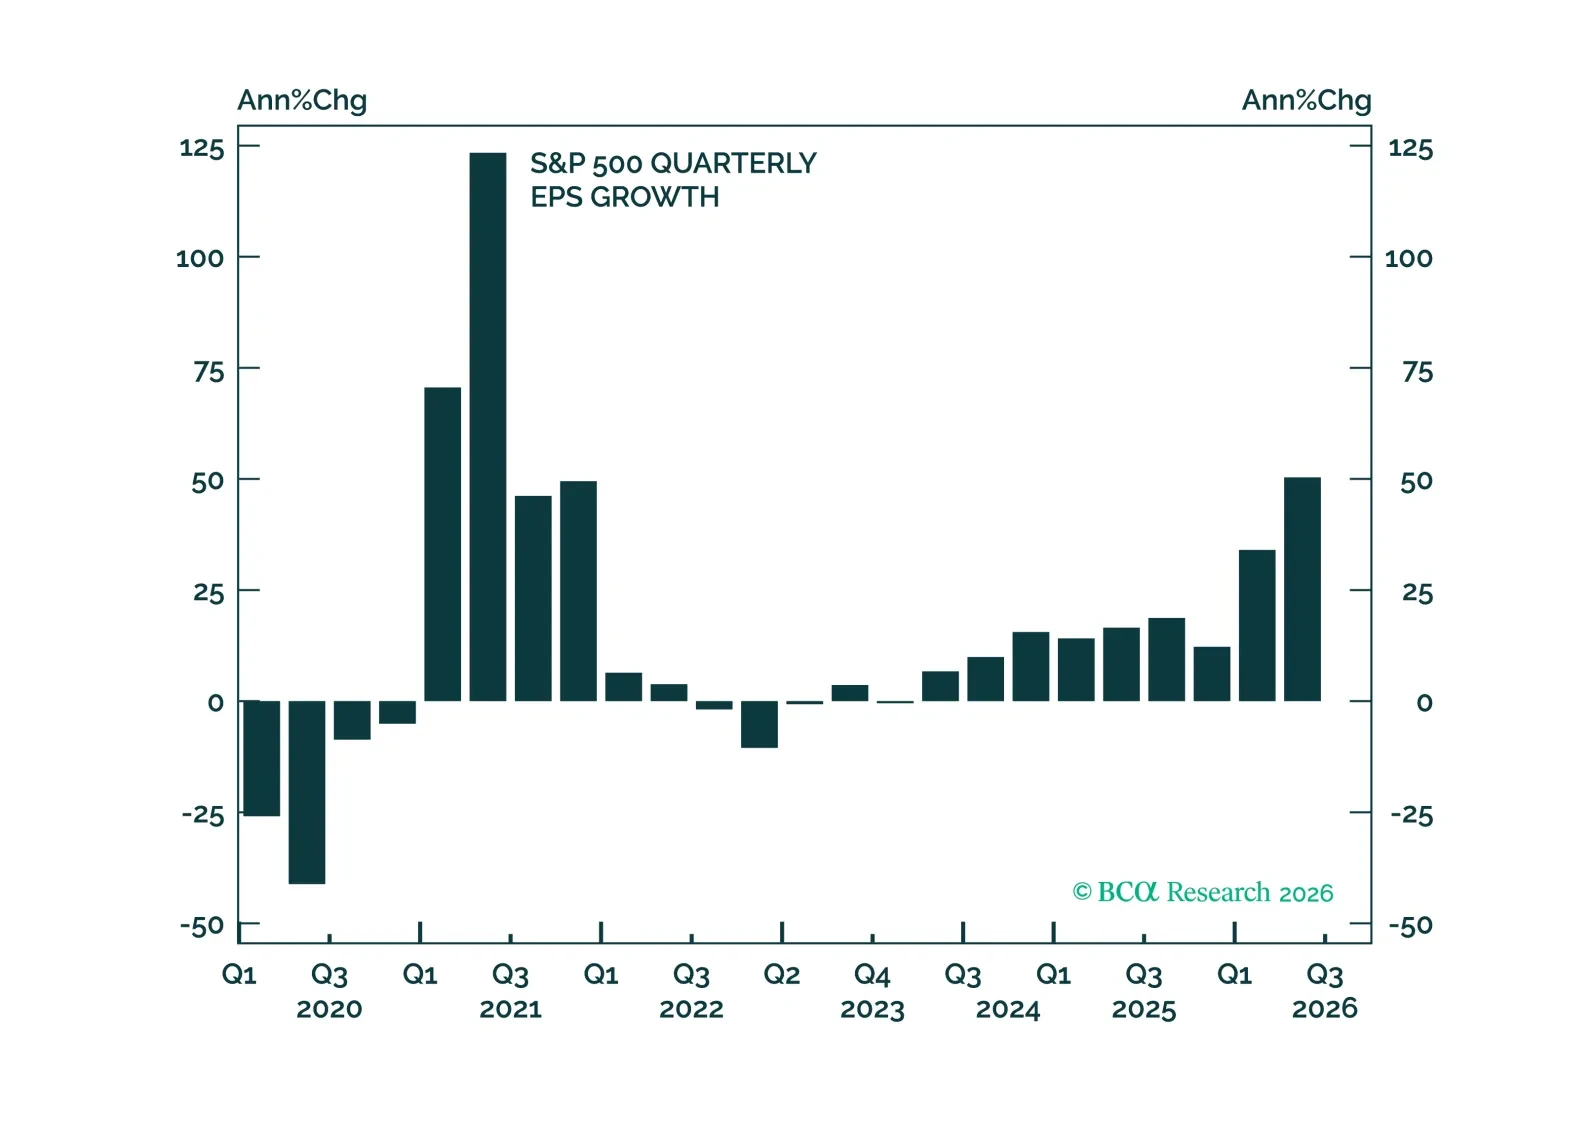
Q2 earnings confirm broad-based strength, but the bond market remains the key risk to equity multiples given today's positive stock/bond correlation regime. We close our tactical GDX long for a 16% gain, though we continue to view goldminers as a valuable structural hedge.