 CoreMacro
Find out more
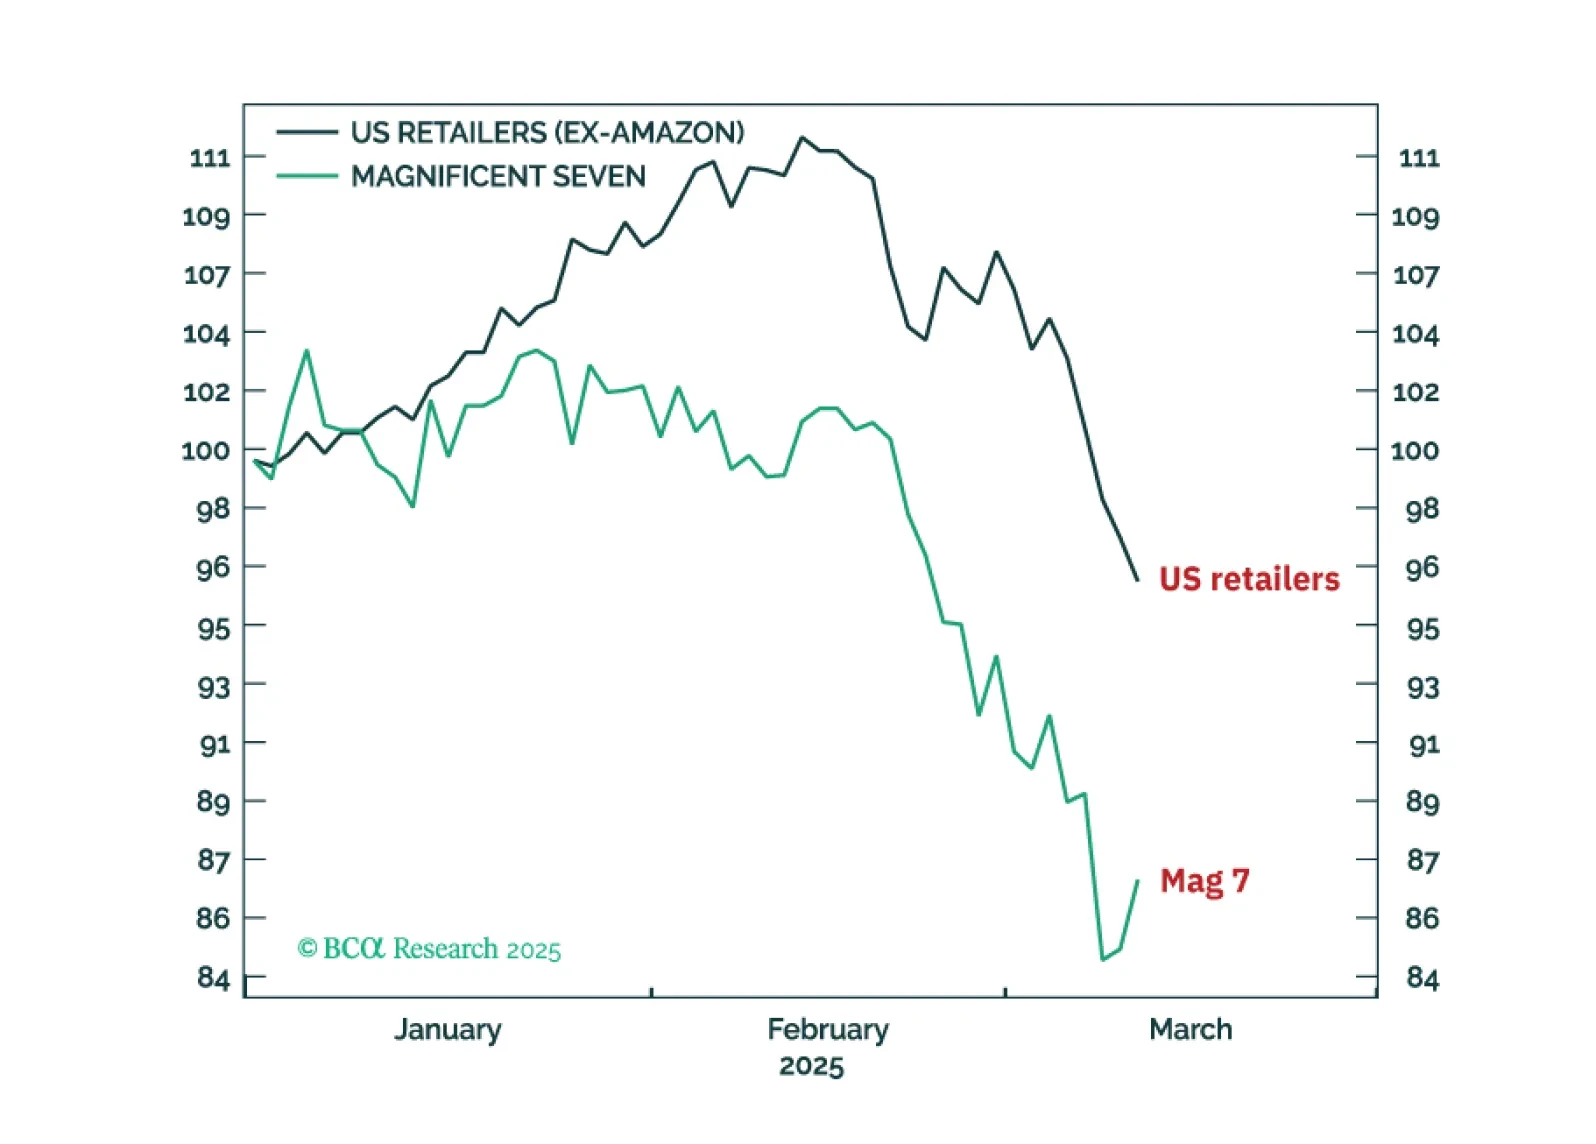
The Trump slump is nearing a temporary reprieve, with a playable countertrend rally in stocks and a tactical rebound in the dollar. Go tactically long USD/SEK. For long-term investors though, the AI bubble still has a lot of air to come out.
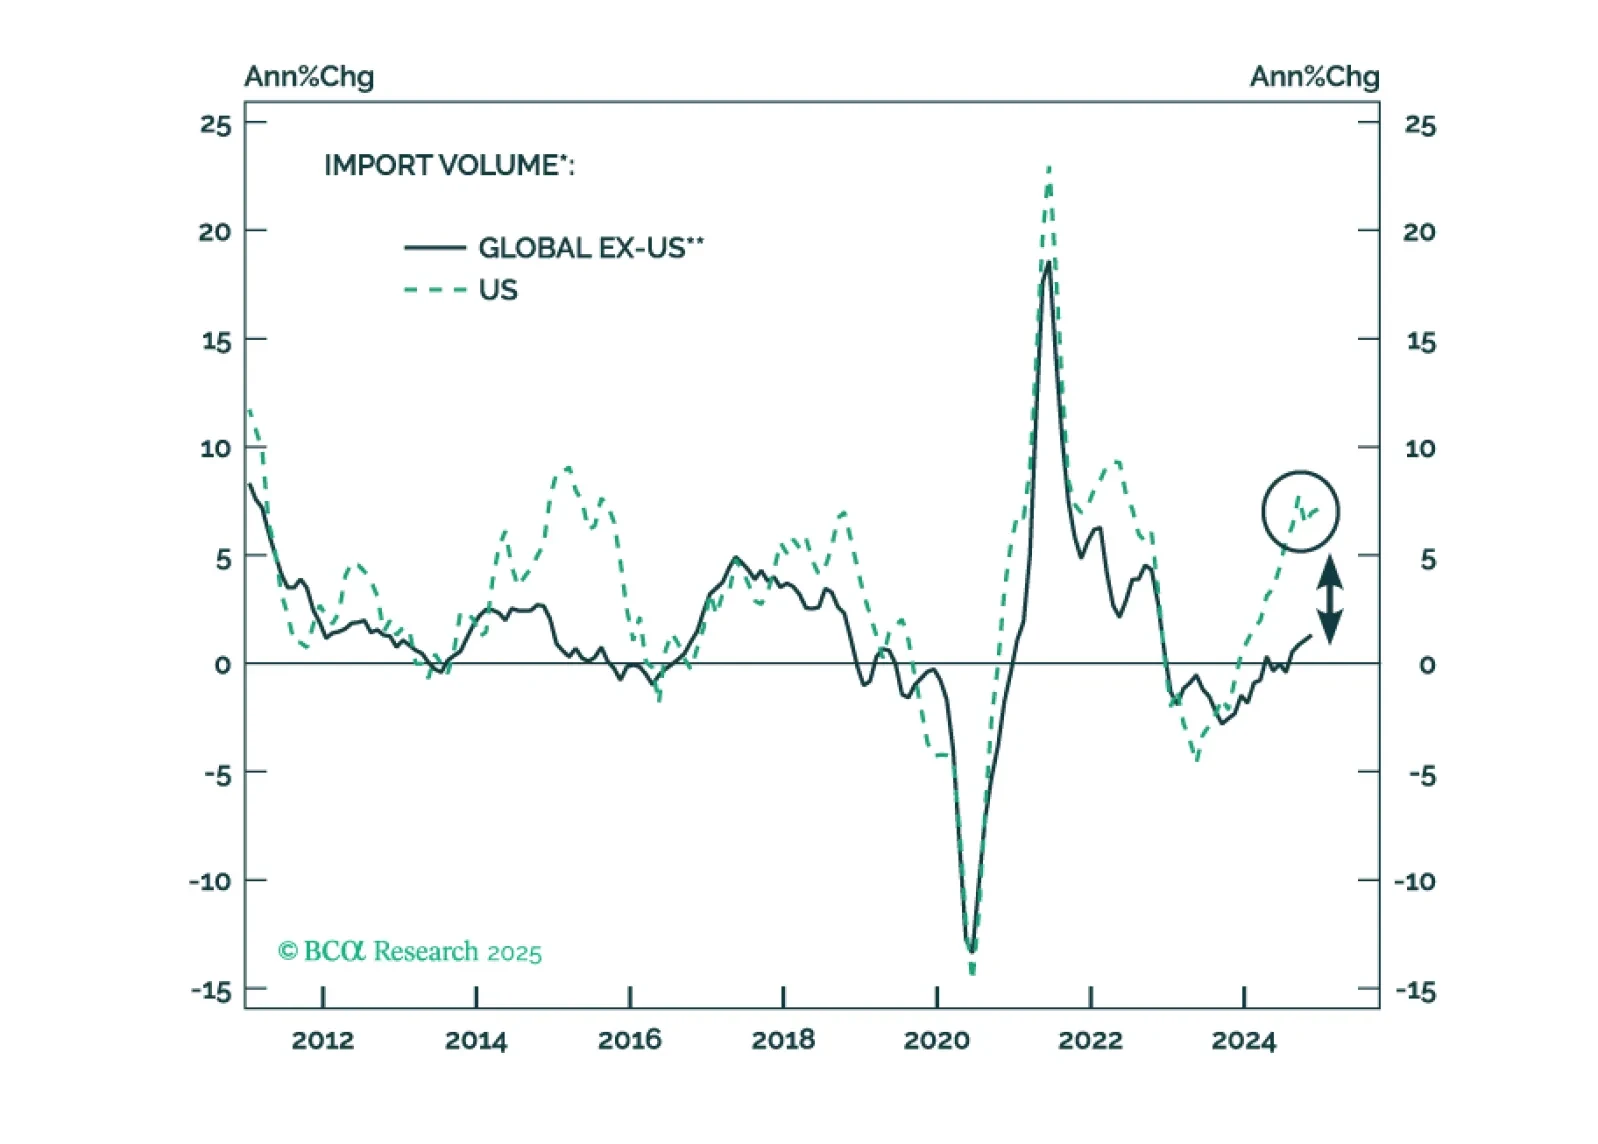
Notwithstanding periodic short-term rebounds, the path of least resistance for global share prices remains down. The resilience of European and Chinese stocks in the face of the US equity selloff is unsustainable. These economies will deteriorate as US demand – the sole pillar of global growth in the past two years – vanishes and tariffs bite. A new currency trade: go long MXN / short an equal-weighted basket of CAD and the euro.
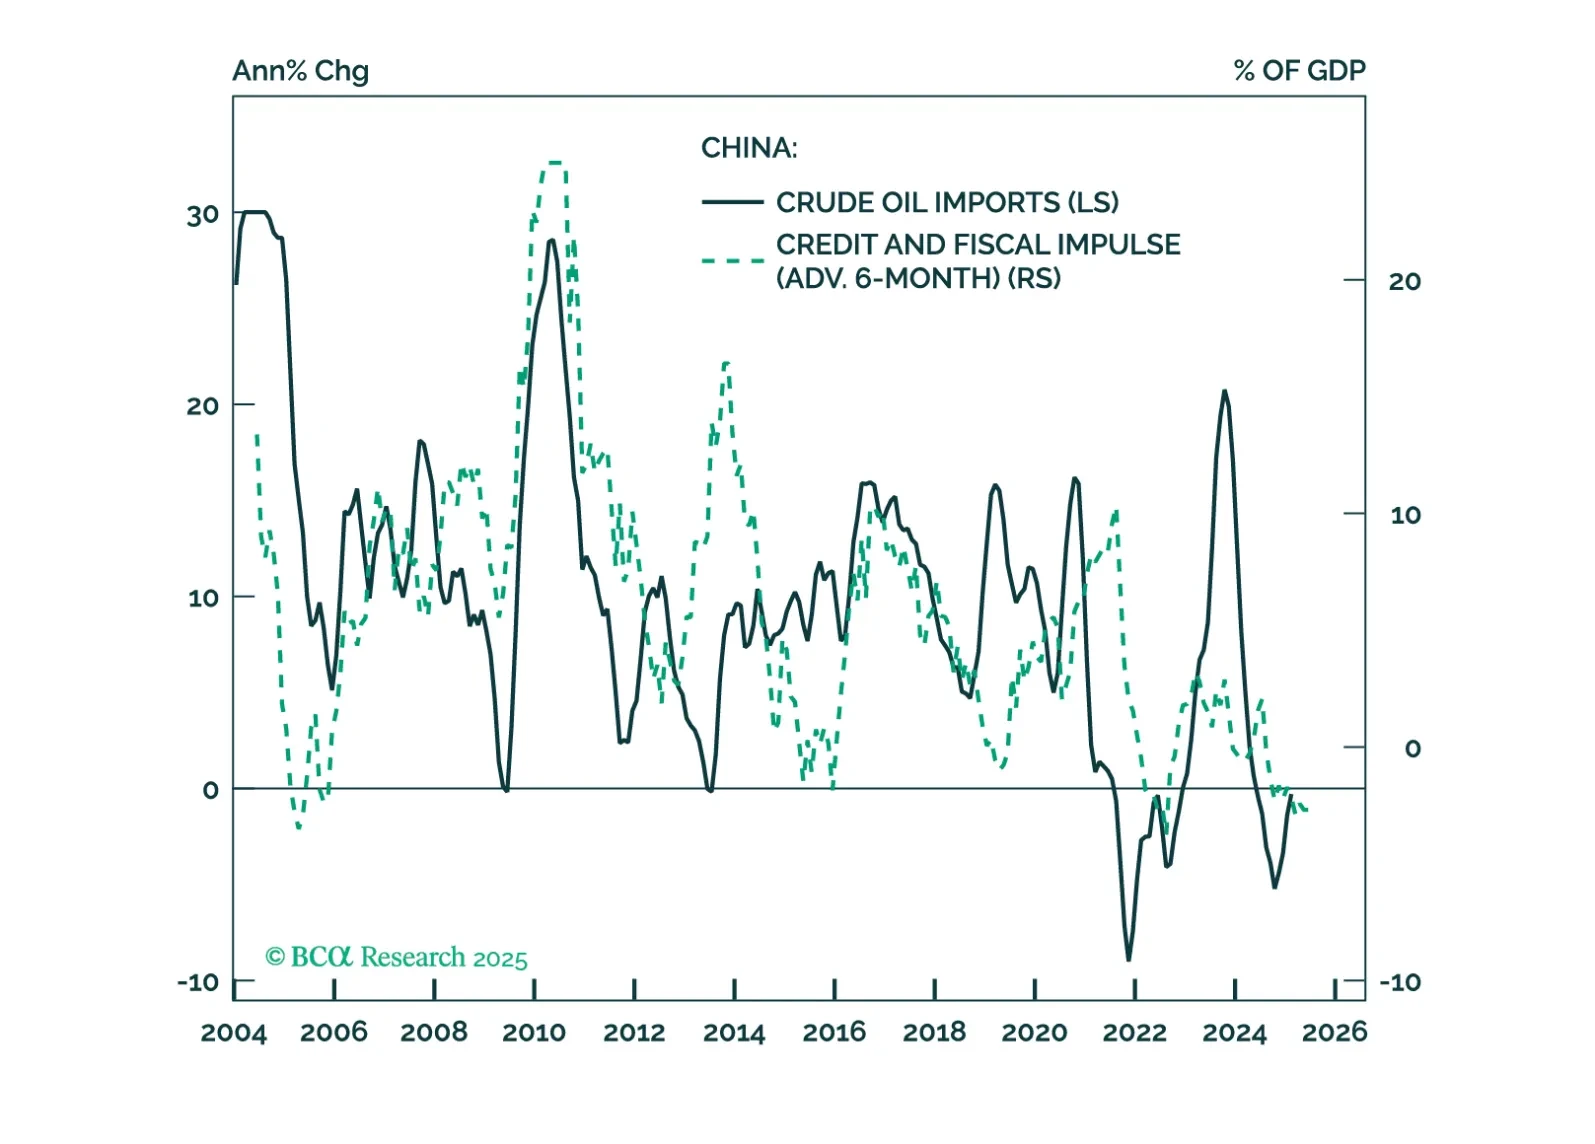
OPEC+ is planning to boost its crude oil output at a time of lingering demand weakness. What is driving this decision? And will Chinese oil consumption – historically a key contributor to global oil demand growth – reaccelerate and justify the coalition’s decision to bring back more supply to the market? This report answers these questions and more.
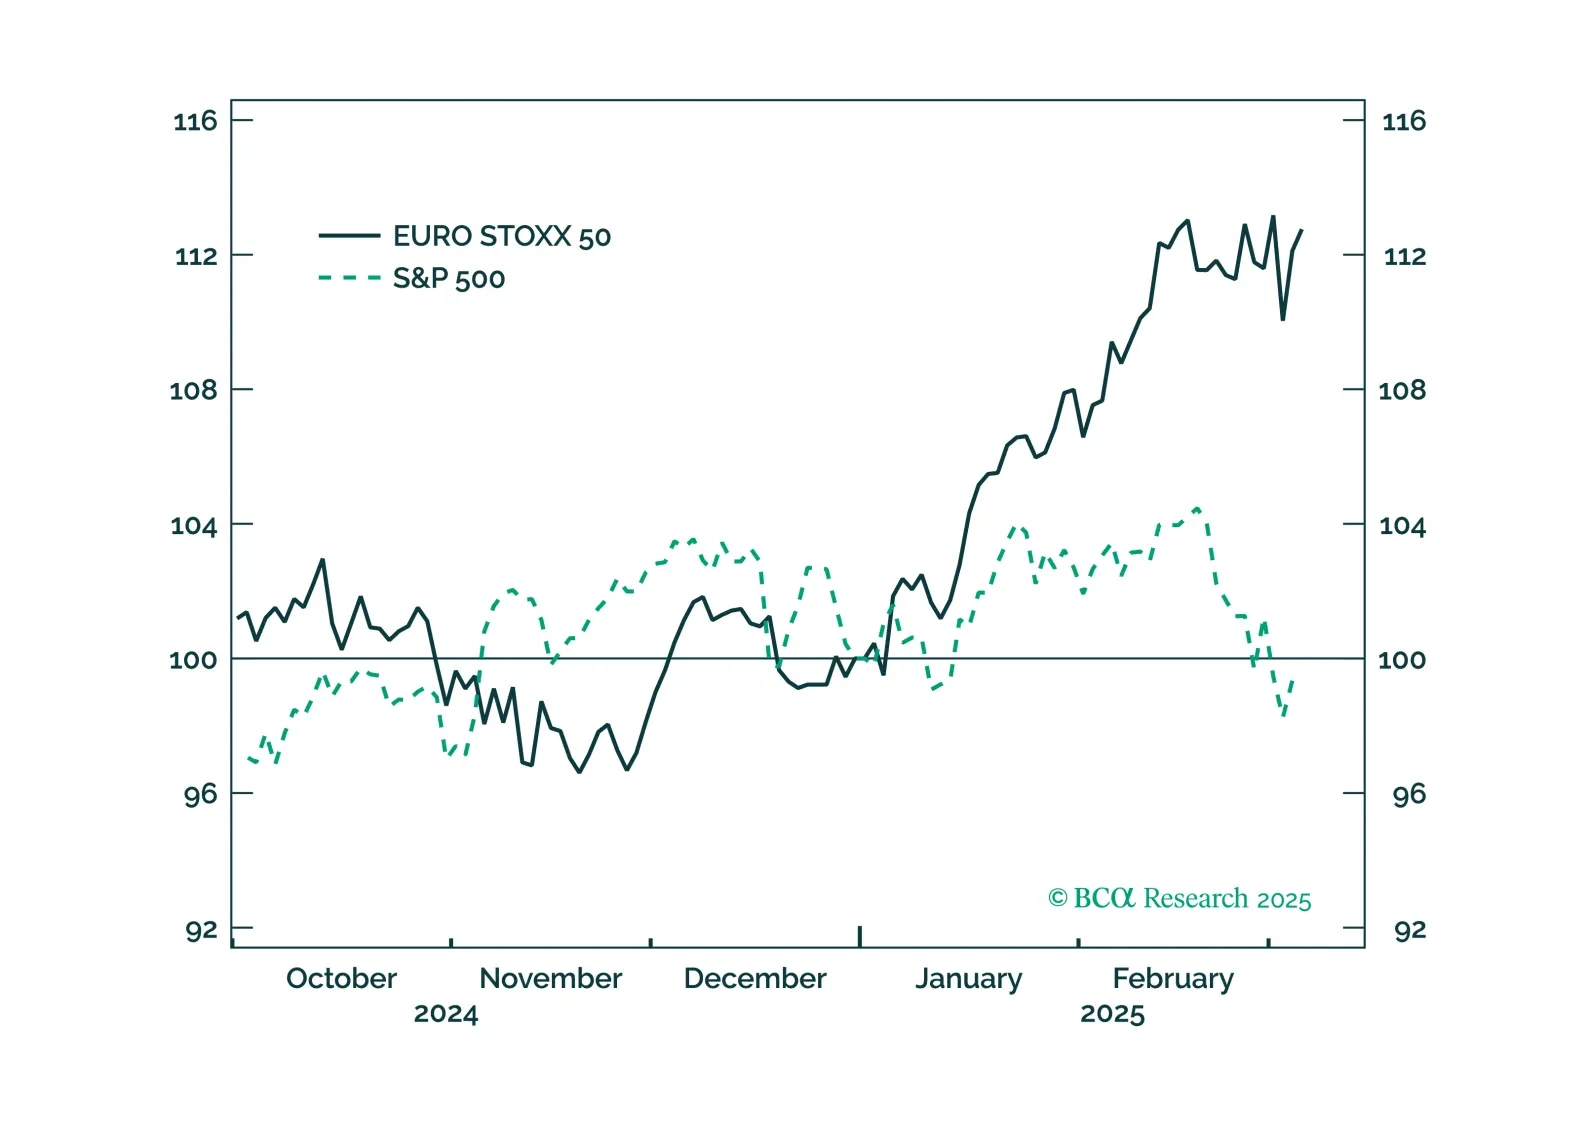
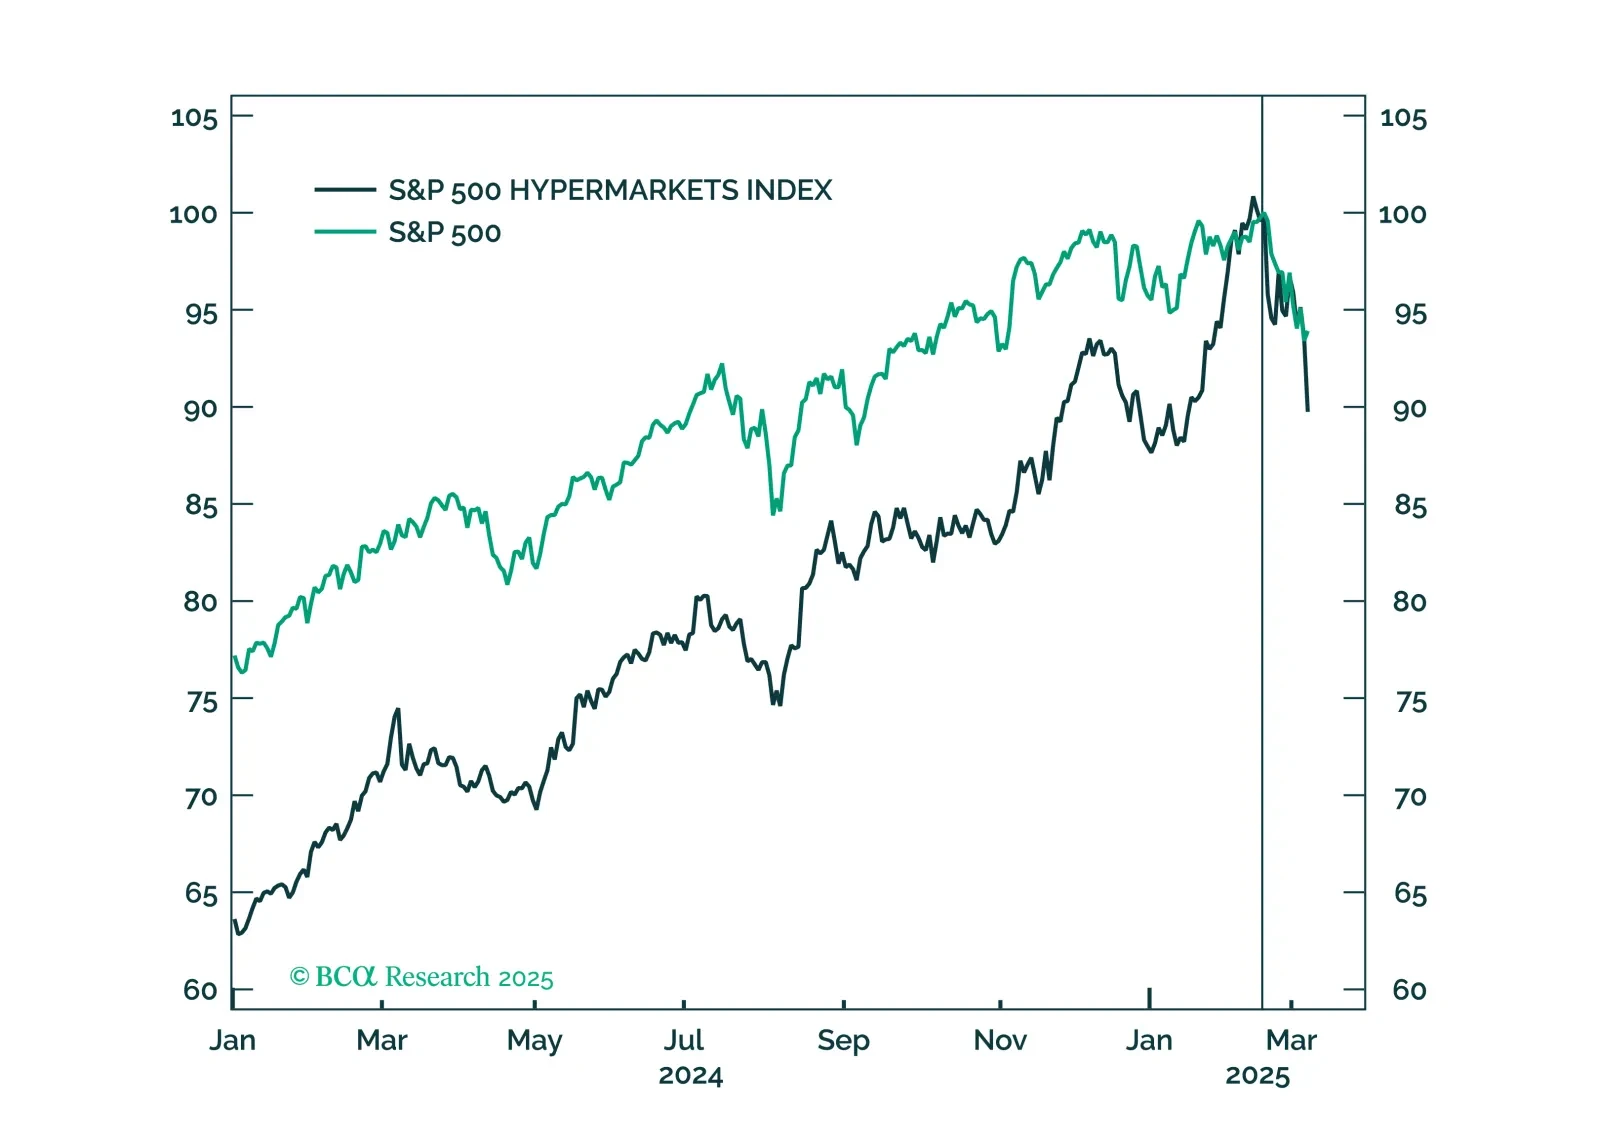
Although there may be a method to DOGE’s 100-mile-an-hour madness, we think the worries and uncertainty stoked by it and on-again, off-again tariff measures have increased the probability of a recession while bringing forward its start date. We are therefore tactically downgrading equities to underweight and upgrading fixed income and cash to overweight. Investors should pursue a defensive posture.
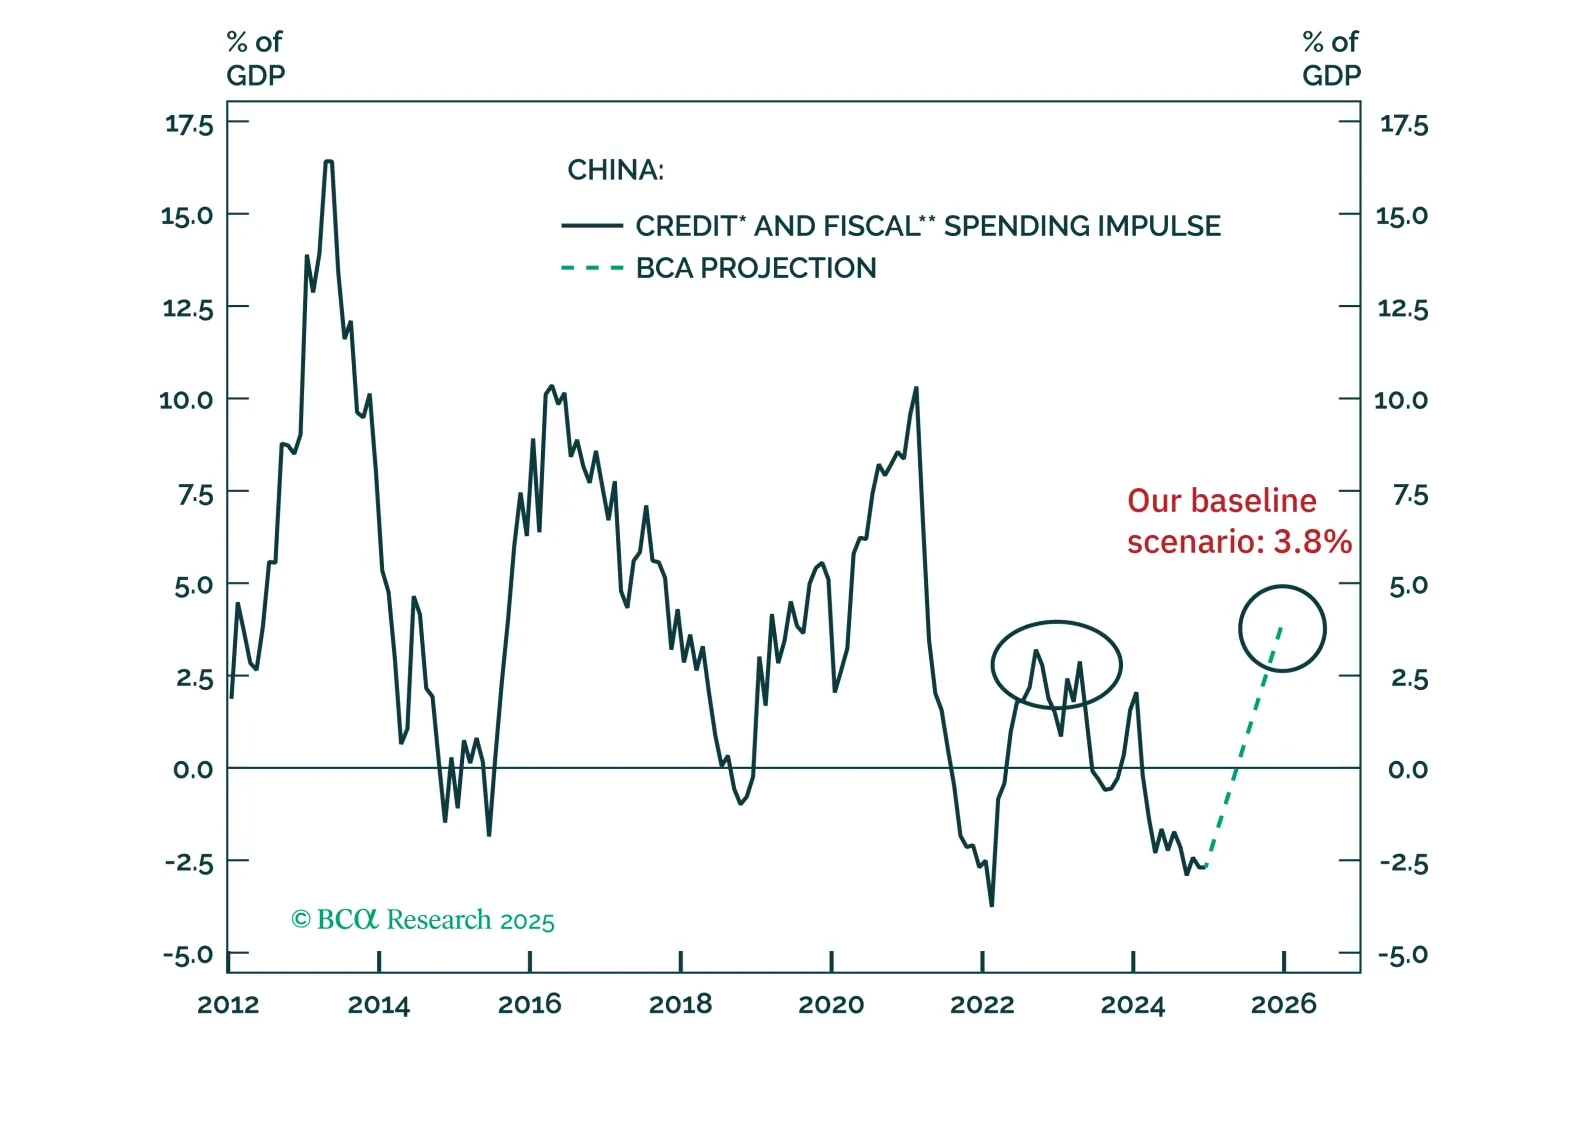
The fiscal stimulus announced at this year’s National People’s Congress is only slightly larger than last year’s. Notably, the details of the measures suggest that it will be challenging for fiscal stimulus to effectively counterbalance the country’s economic difficulties this year.
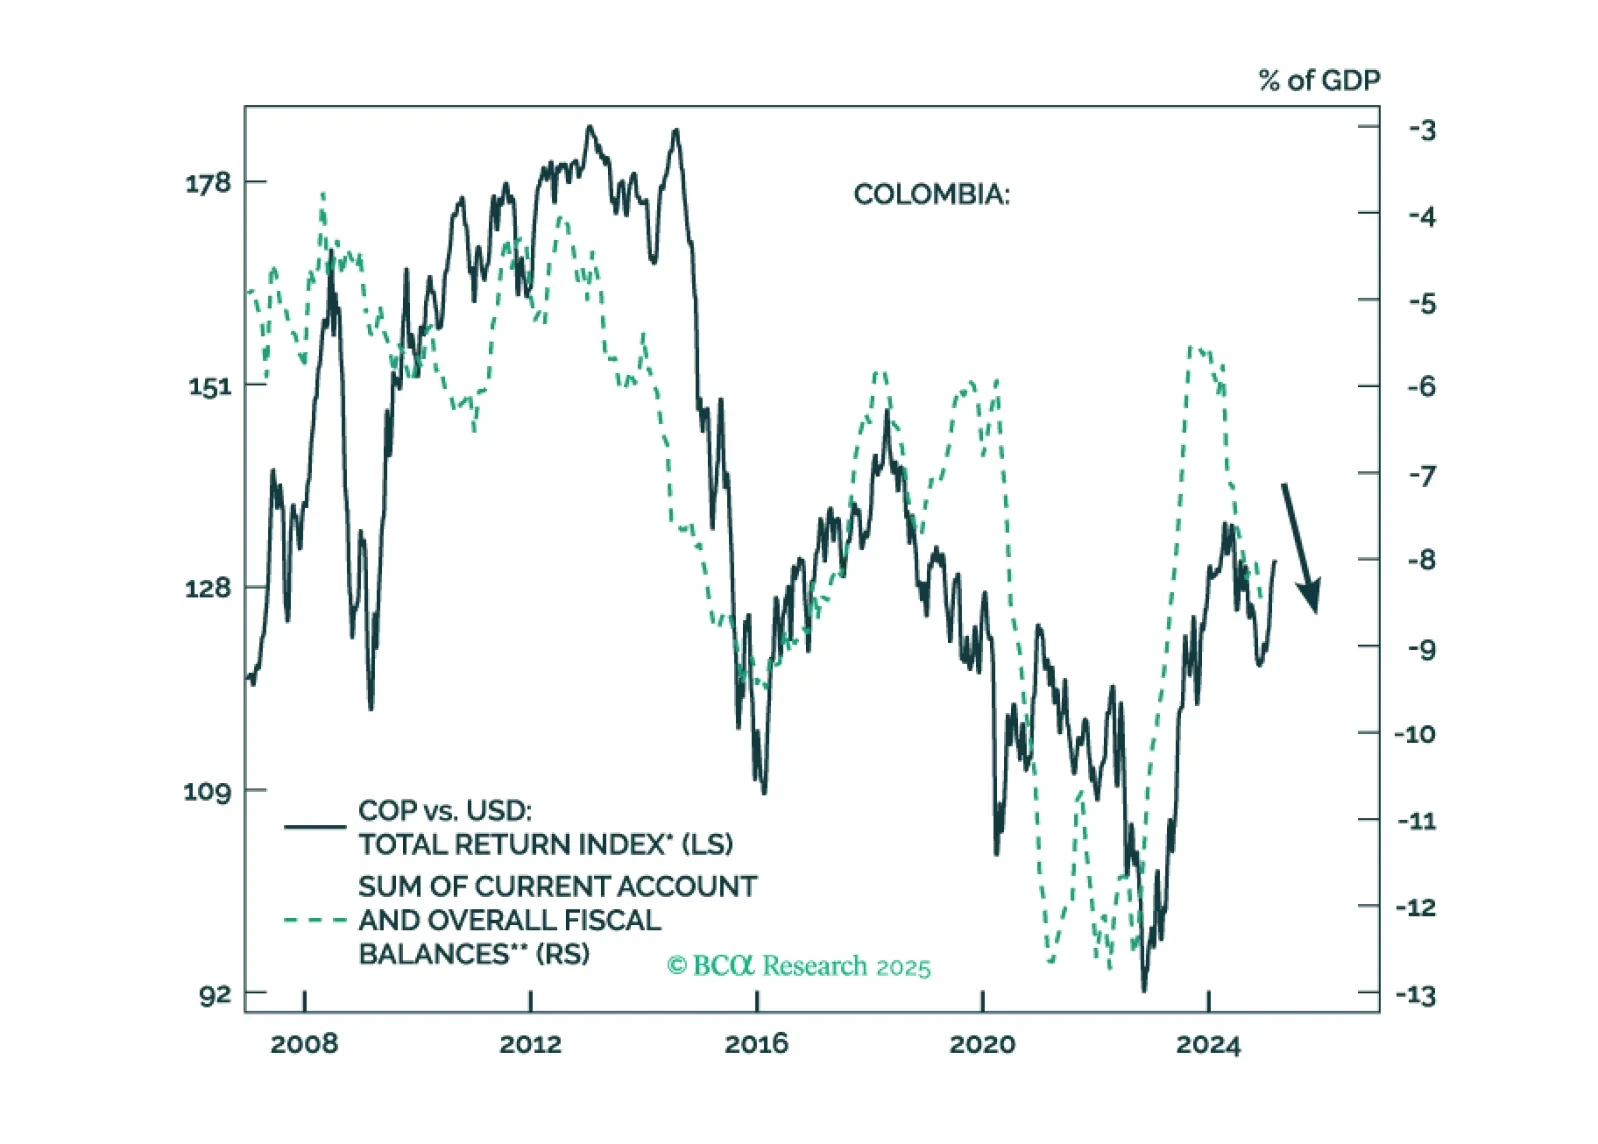
Colombian financial markets have rallied on the expectation that a right-wing government will be elected in 2026. We take a contrarian bearish stance on the nation's financial markets. Colombia is suffering from two structural macro issues – unsustainable public debt and plunging energy exports – that will not be easily solved by a conservative administration in 2026. Continue underweighting Colombia within EM equity and fixed-income portfolios, continue shorting the COP versus the USD and the CLP, and bet on yield curve steepening.
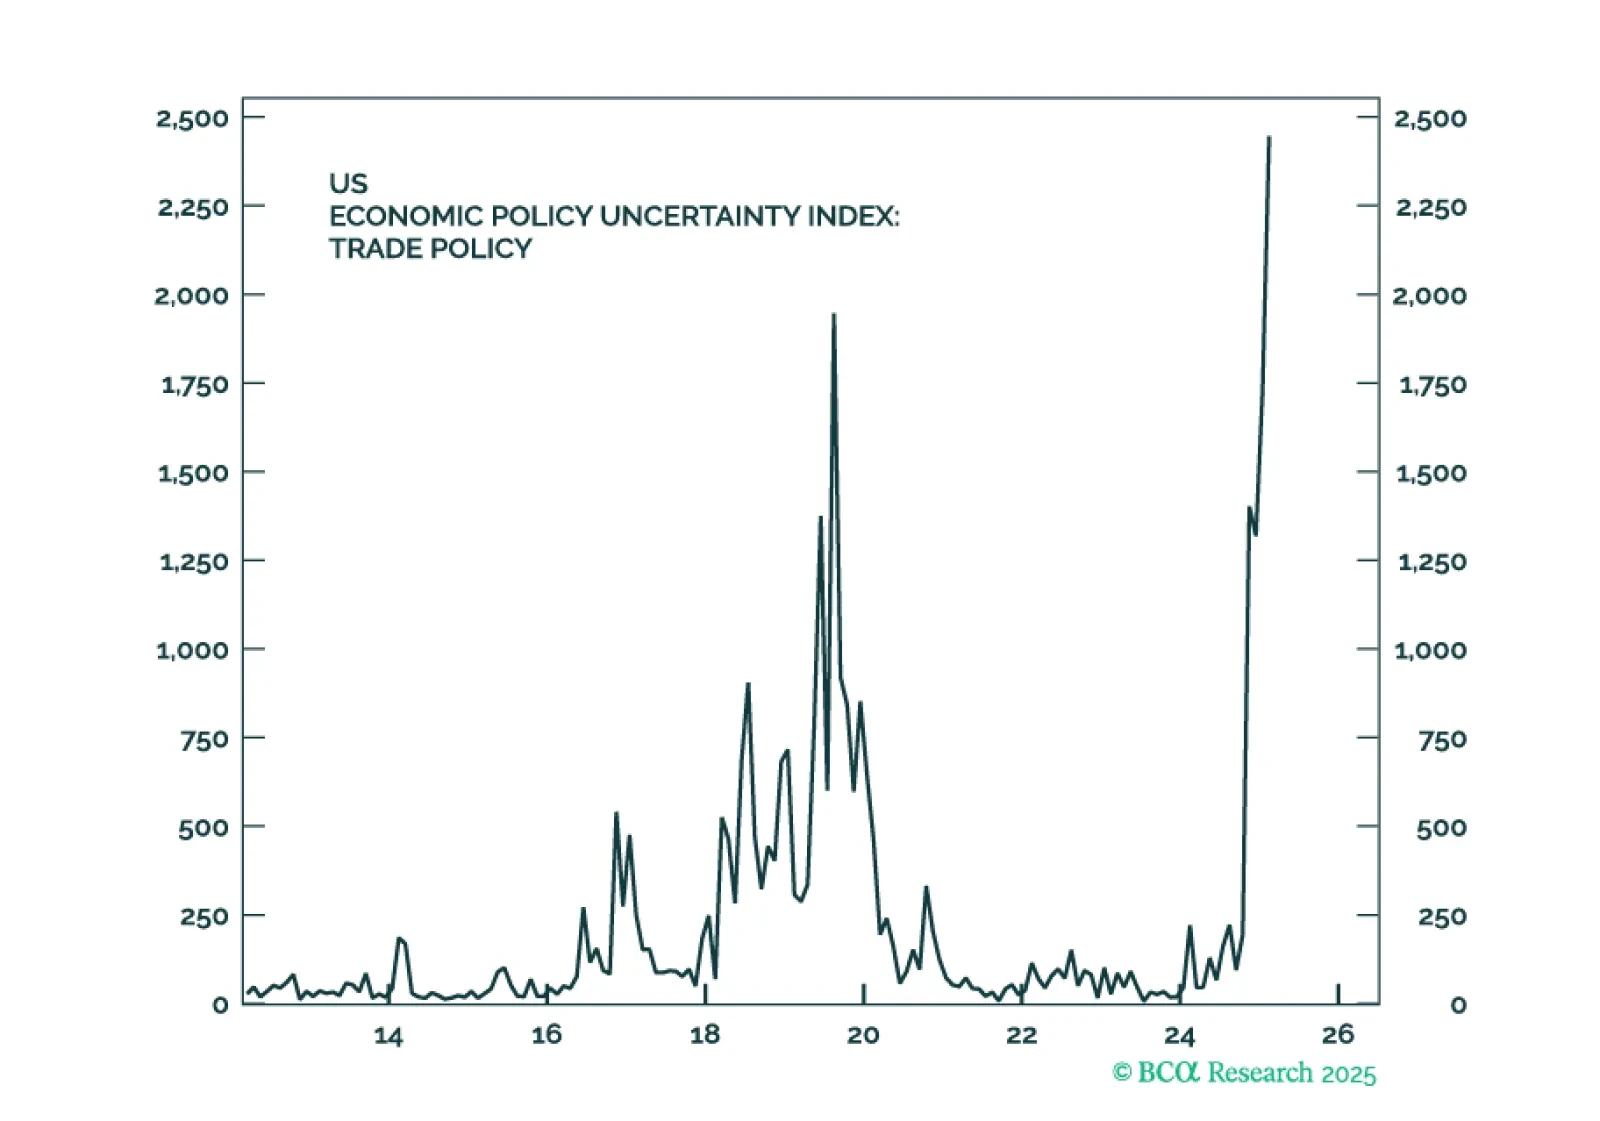
The US economy is set to enter a recession within the next few months. Stay underweight equities and overweight cash. Look to increase fixed-income duration exposure over the coming months. The euro is likely to strengthen and European stocks should outperform US stocks over the next month or so, but these trends will reverse by the middle of this year.
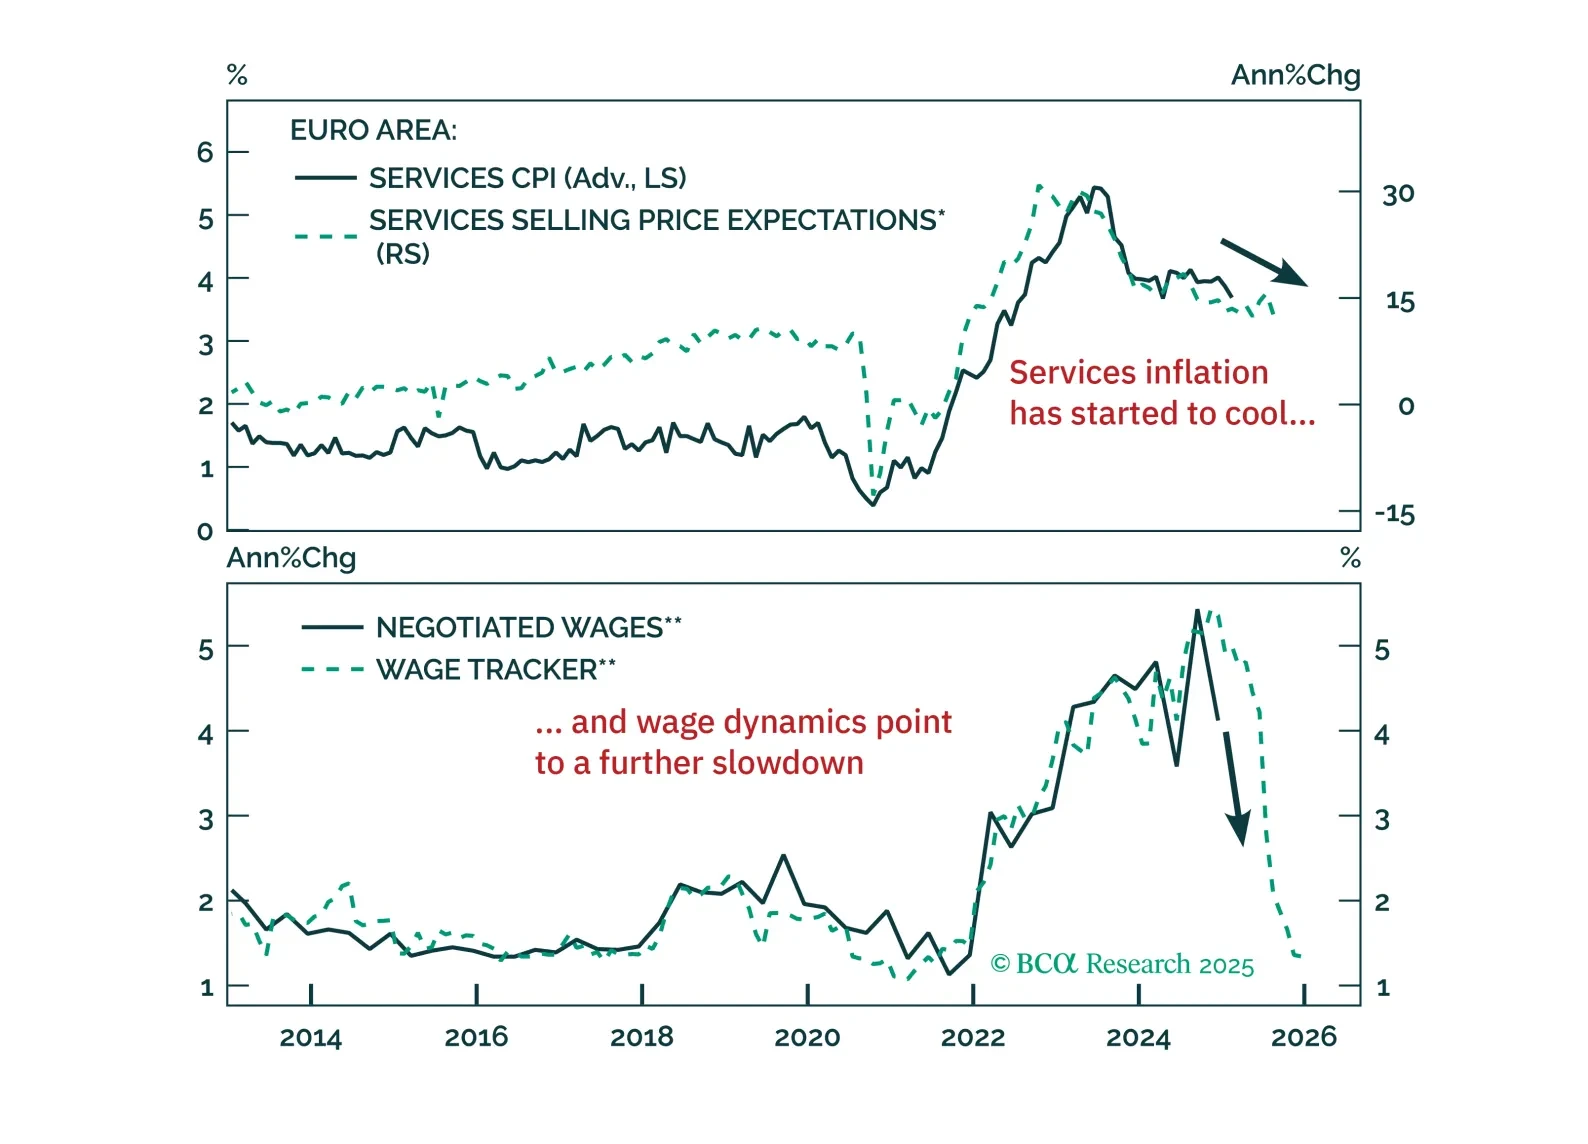
The ECB cut rates as expected, but rising yields and a stronger euro are tightening financial conditions just as fiscal policy shifts the macro landscape. With more rate cuts ahead and market positioning stretched, we outline the key risks, investment opportunities, and our updated call on the ECB’s terminal rate. Read our full report for actionable insights.
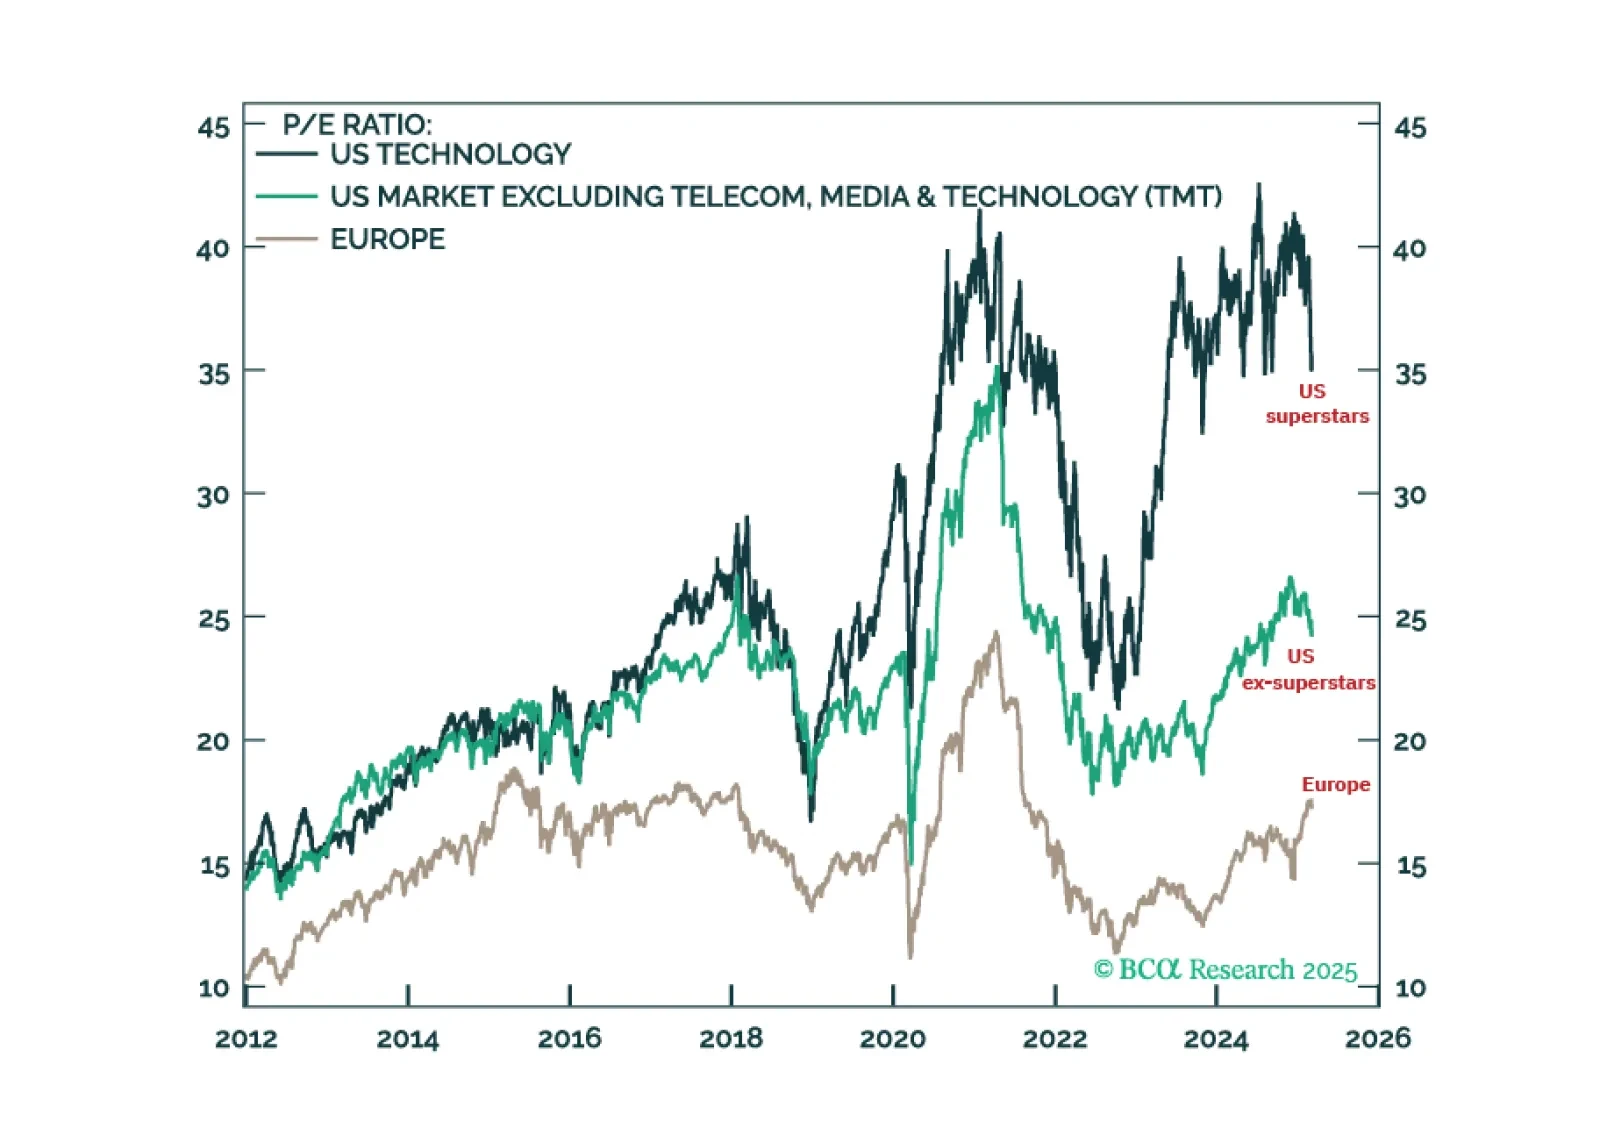
US stock market outperformance has been driven entirely by the 0.0002 percent of US superstar companies. But this superstar outperformance is based on two highly questionable assumptions: that all productivity gains from the generative-AI revolution will go into corporate profits; and specifically, into the profits of the Web 2.0 superstars which will morph into the generative-AI superstars. As these assumptions become undermined in the coming quarters, relative performance will reverse, starkly. On a structural horizon, stay maximum overweight Europe versus the US. Plus: time to go underweight global financials (IXG).