CoreMacro
Find out more
I am pleased to announce the launch of PowerTrades, an exclusive new service for Global Investment Strategy subscribers that delivers our top trading insights directly to your inbox.
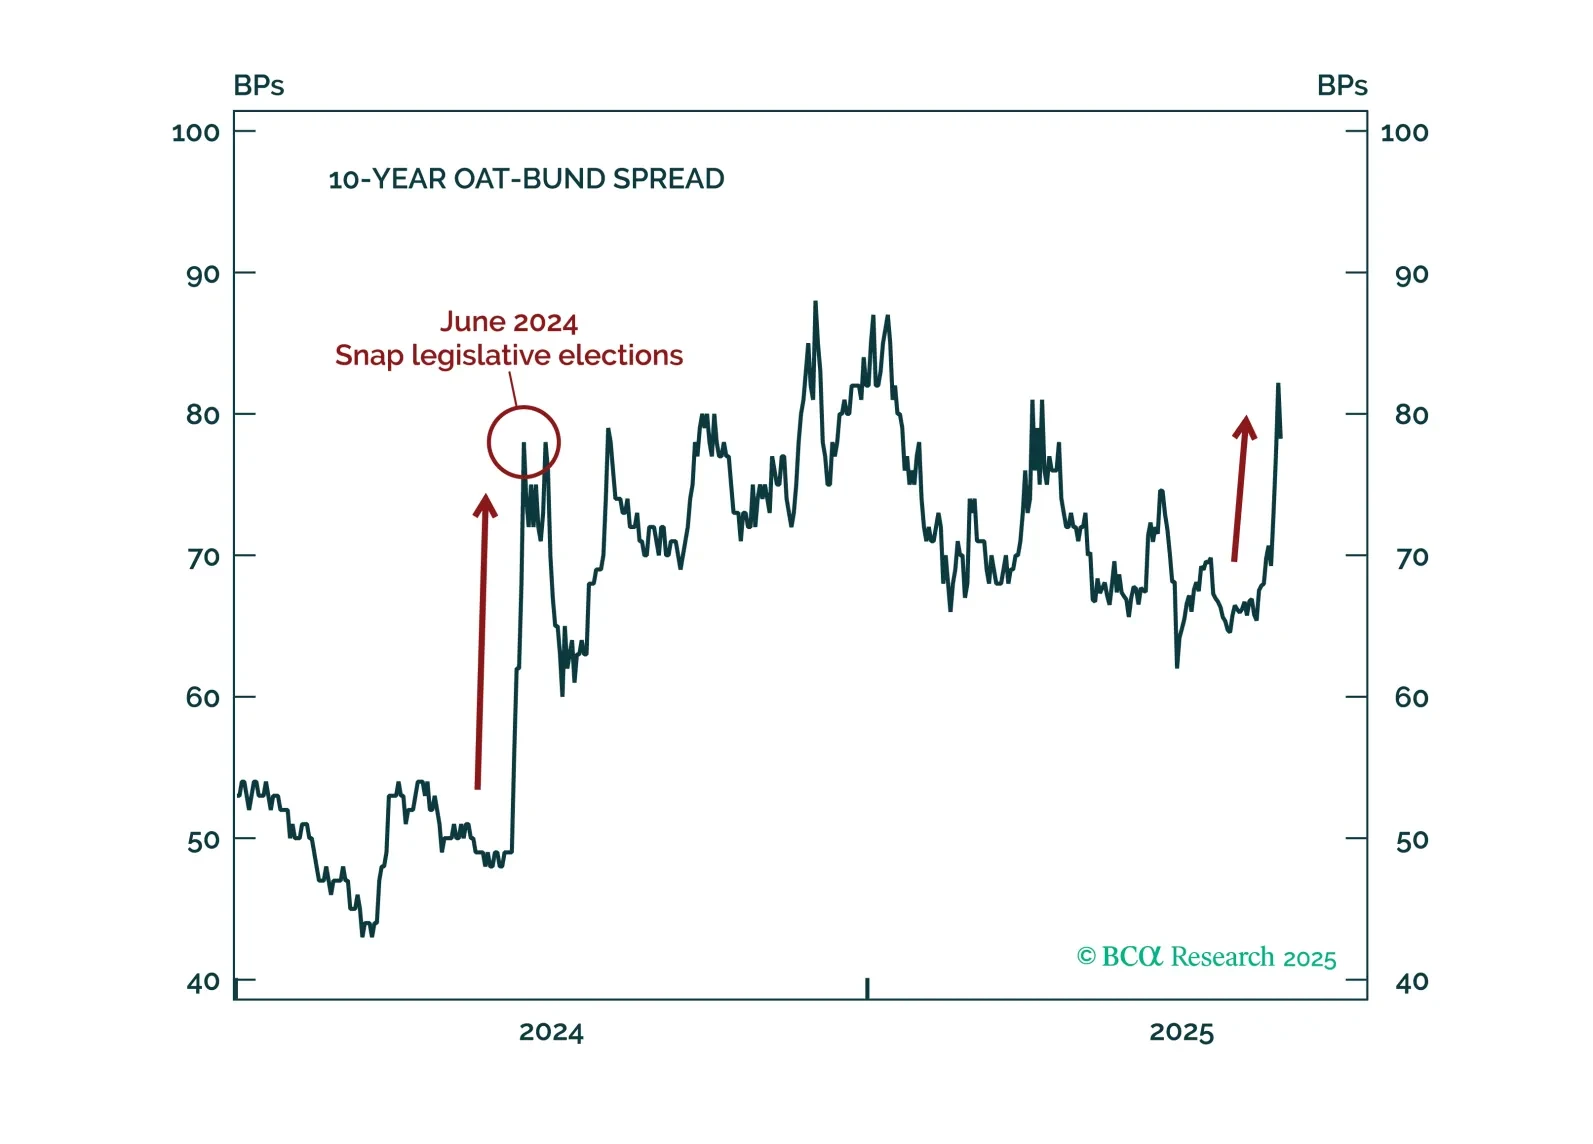
Political instability will persist in France as PM François Bayrou loses the confidence vote. The nomination of a new PM will not end the country’s political paralysis and will further fuel fiscal fears. Investors should remain underweight French OAT. French equities, especially French banks, should be bought on dips.
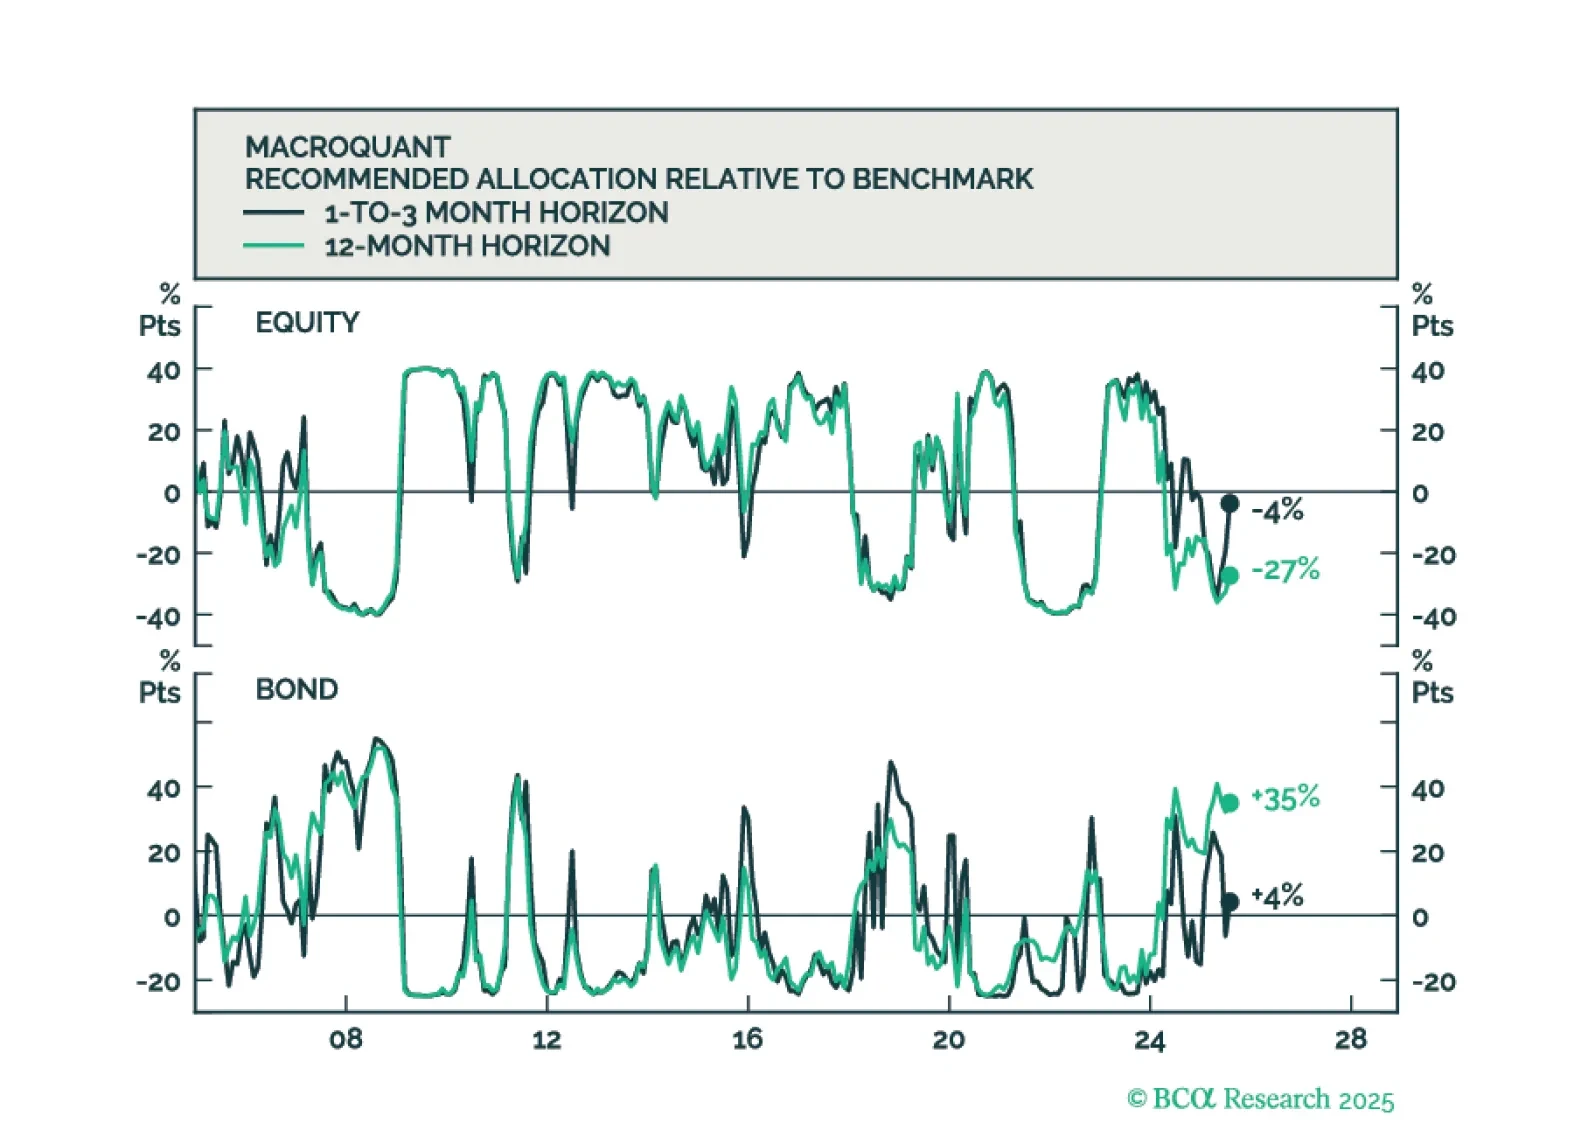
MacroQuant sees downside risks to stocks over a long-term horizon but is not yet saying that we are at imminent risk of an equity bear market.
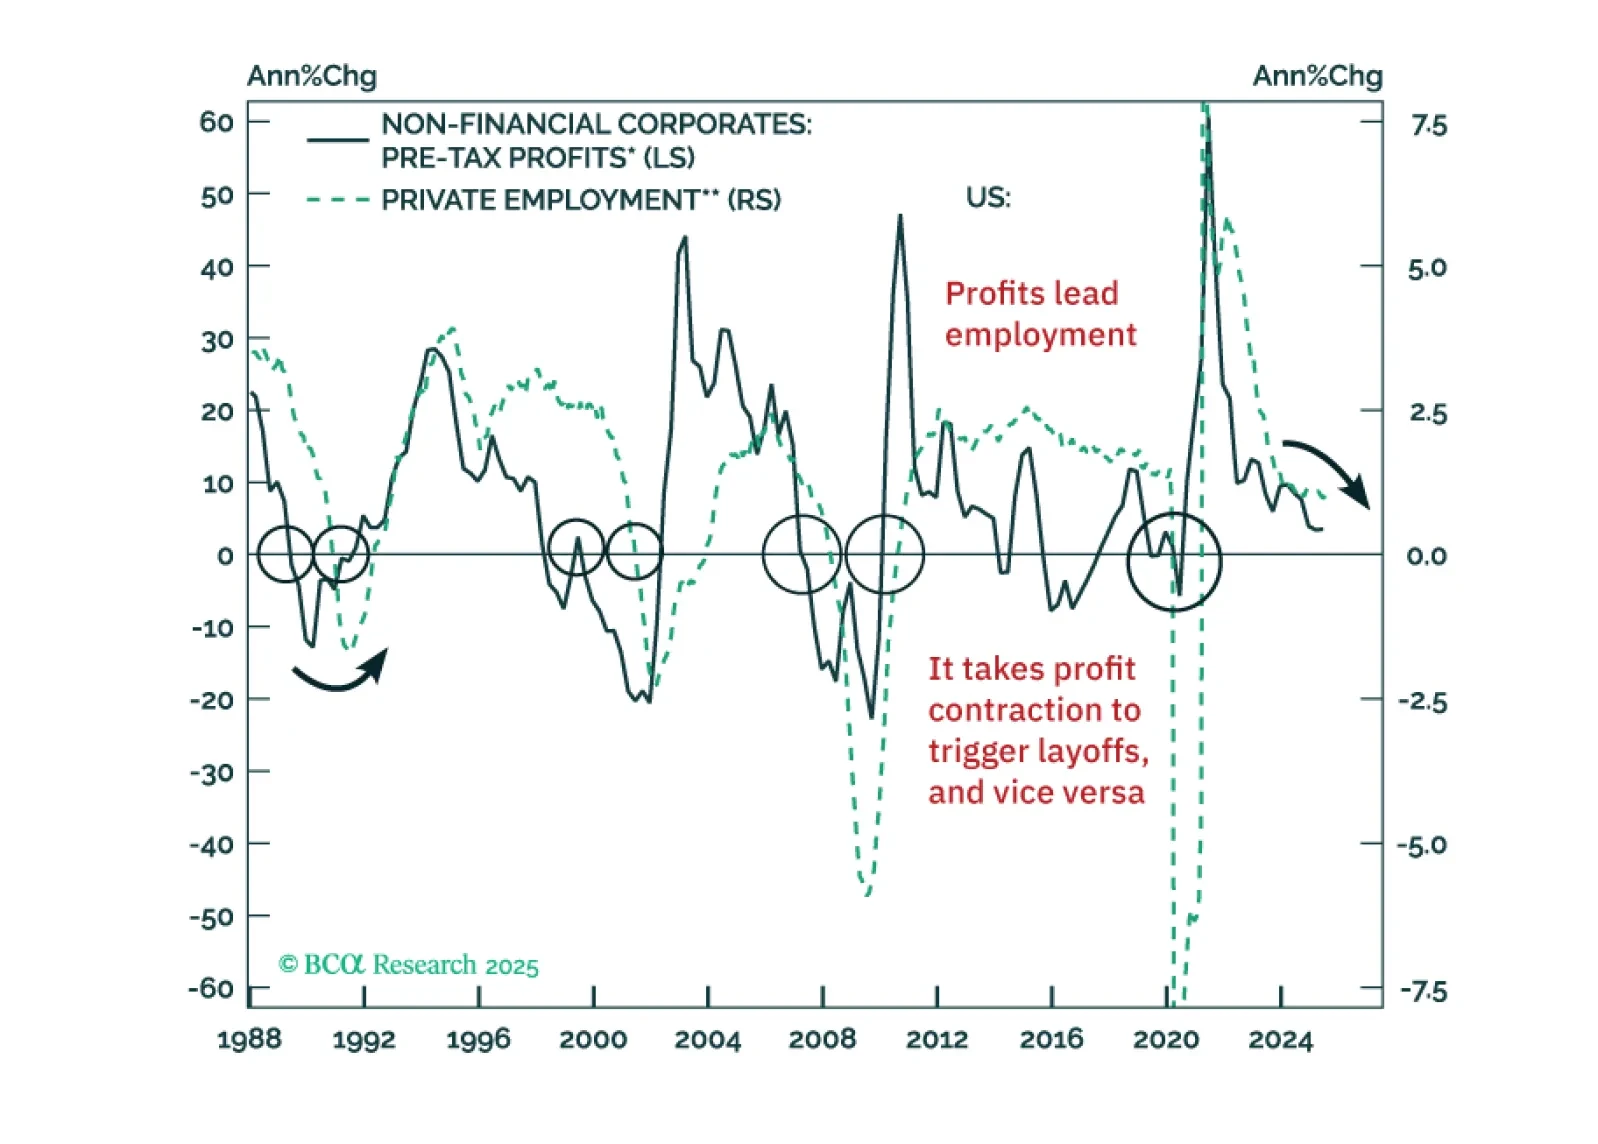
We see two risks that could spoil the rally in US risk assets: (1) a tariff-driven stagflation, and (2) a US Treasury tantrum. Our negative view on EM risk assets is primarily driven by the outlook for global trade, which is set to shrink in Q4 this year.
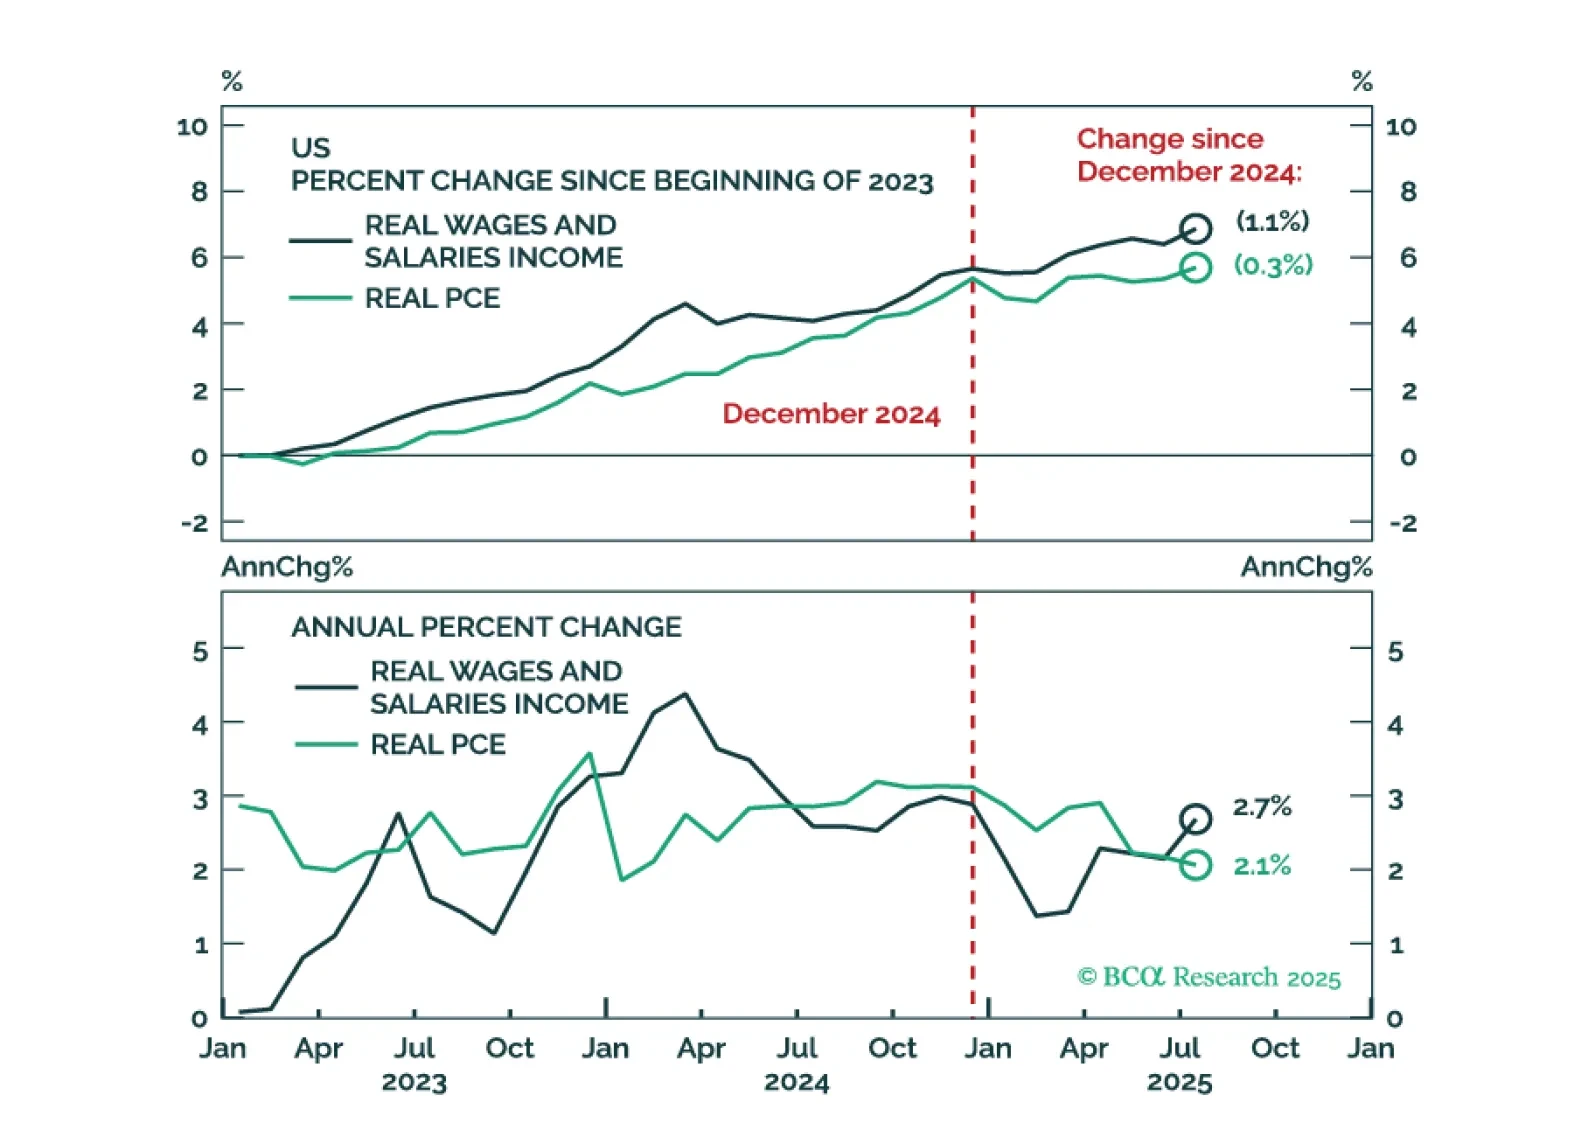
Today’s PCE report was broadly in line with expectations. Real consumer spending rebounded in July but remains only 0.3% above where it was in December.
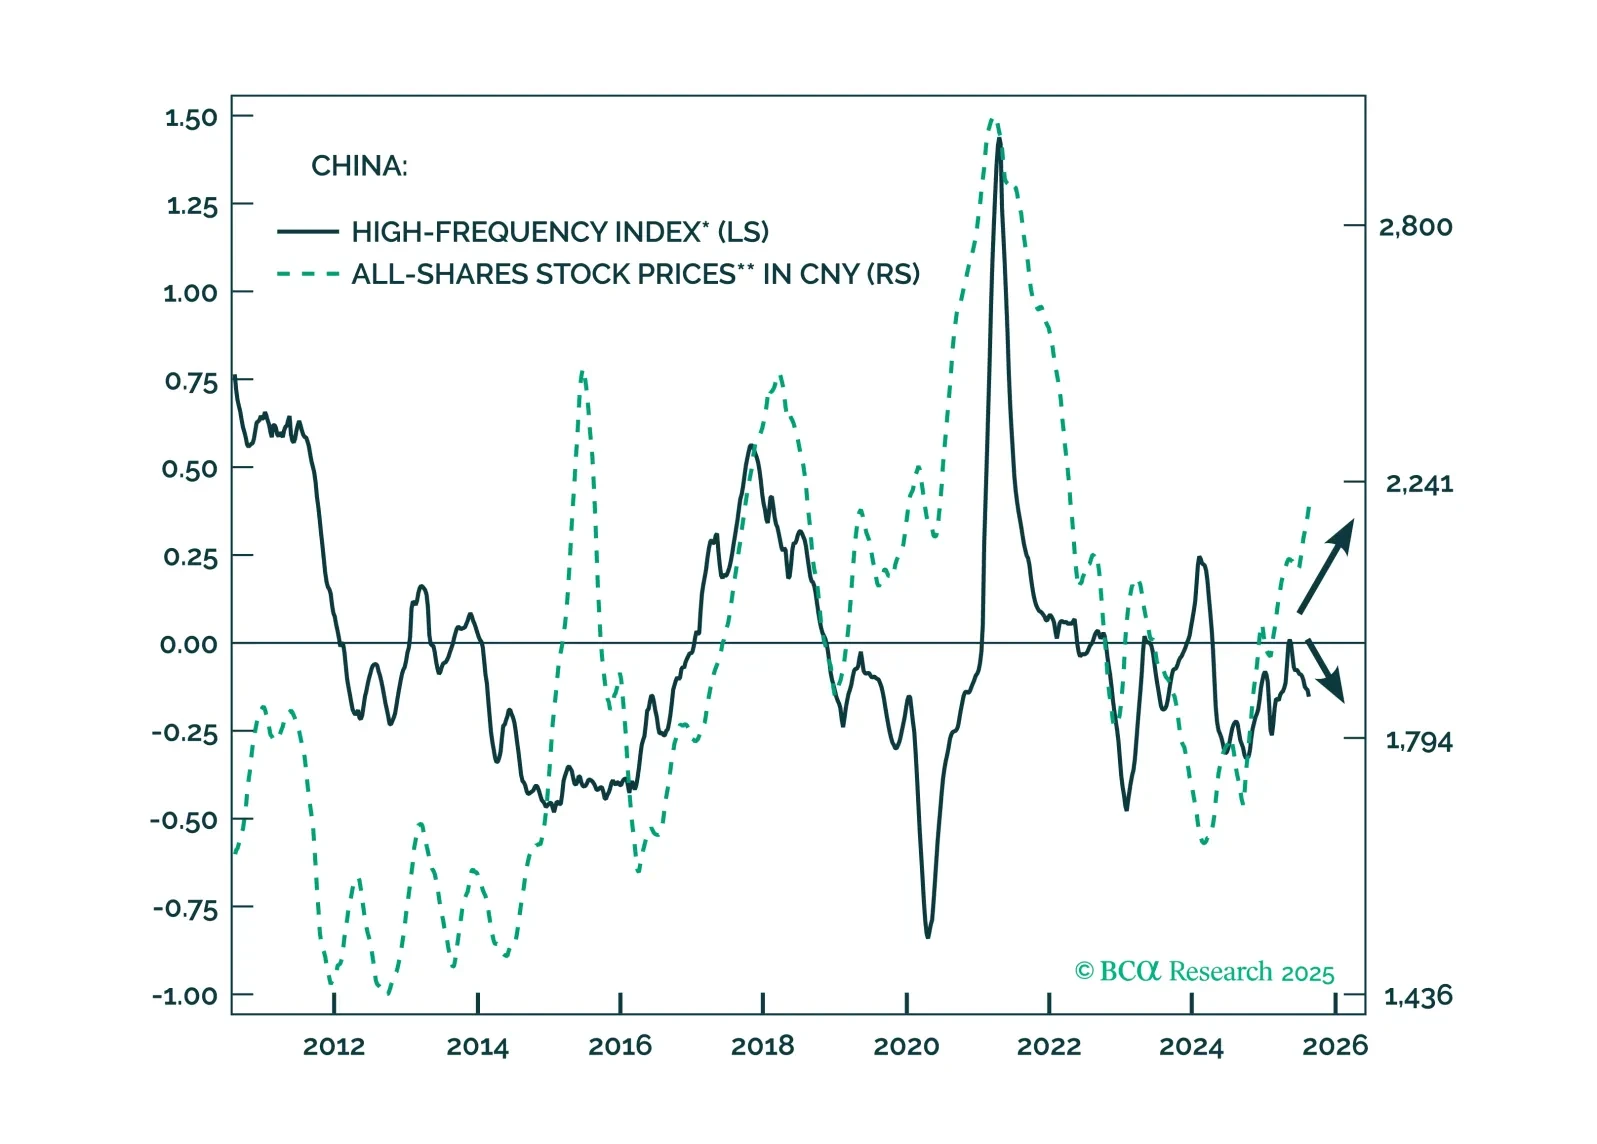
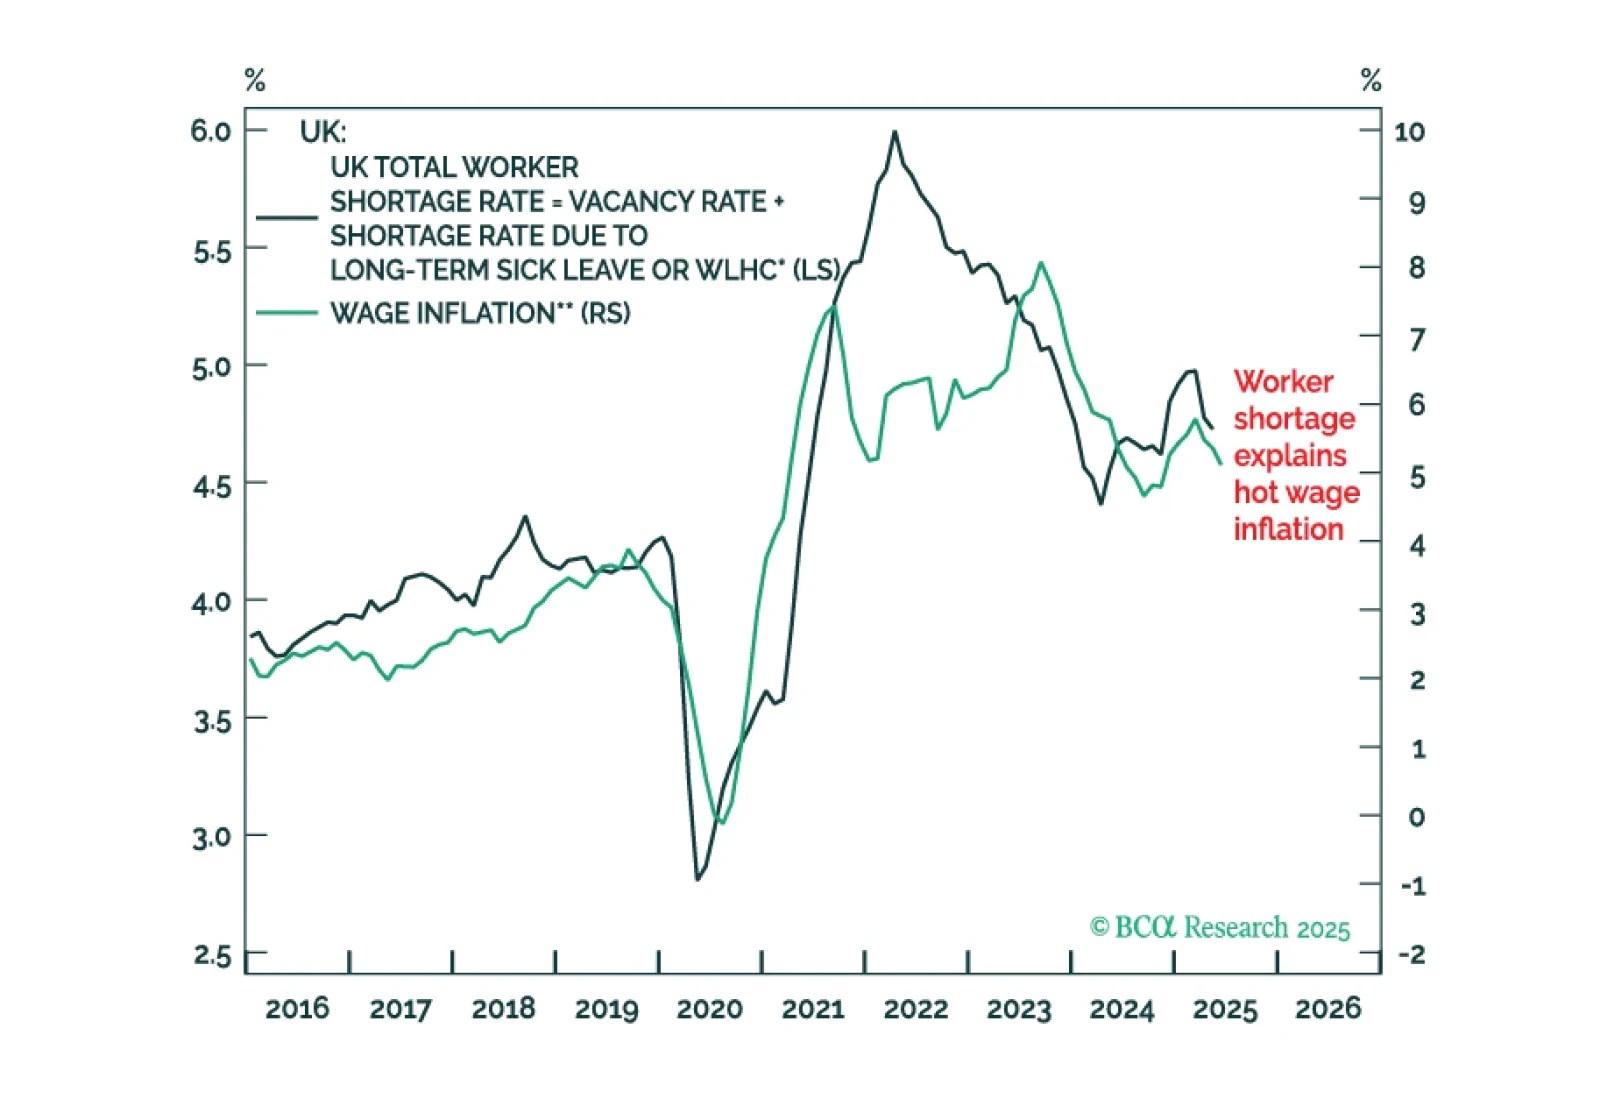
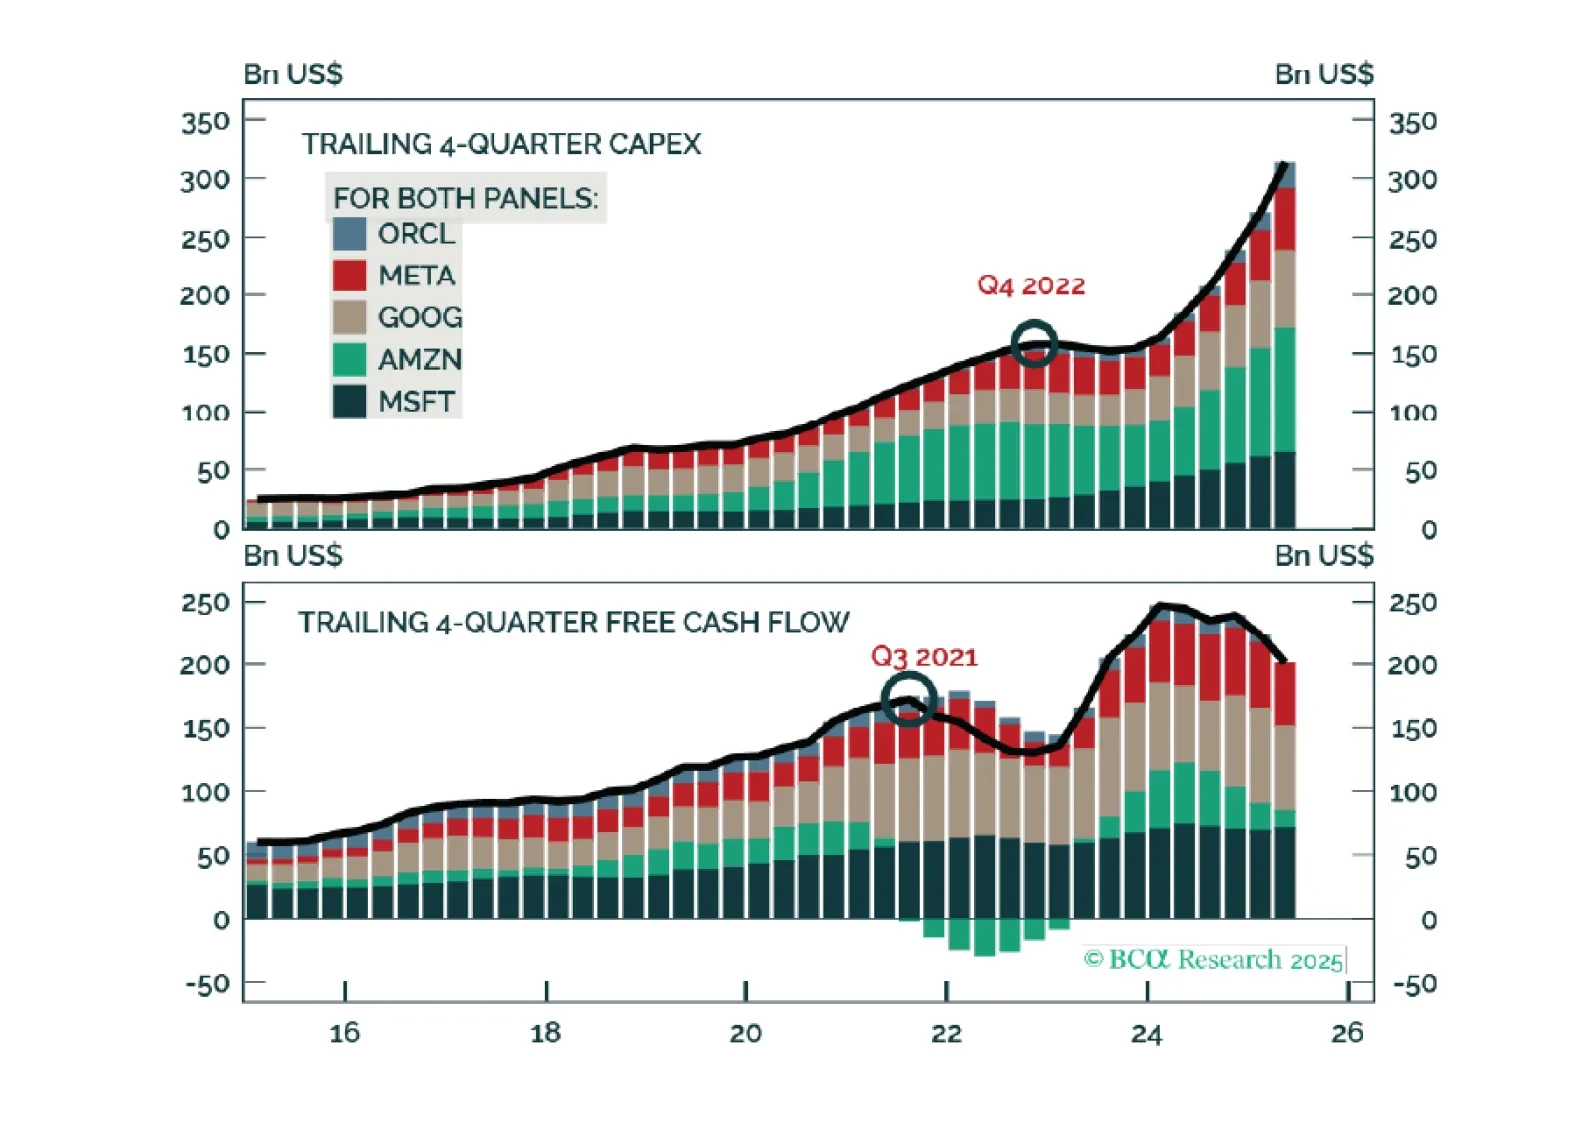
Investors will be scrutinizing Nvidia’s earnings report tonight for signs of cracks in the massive, ongoing AI capex boom. I understand the temptation to do so, but I am not certain that capex is the best metric to focus on.
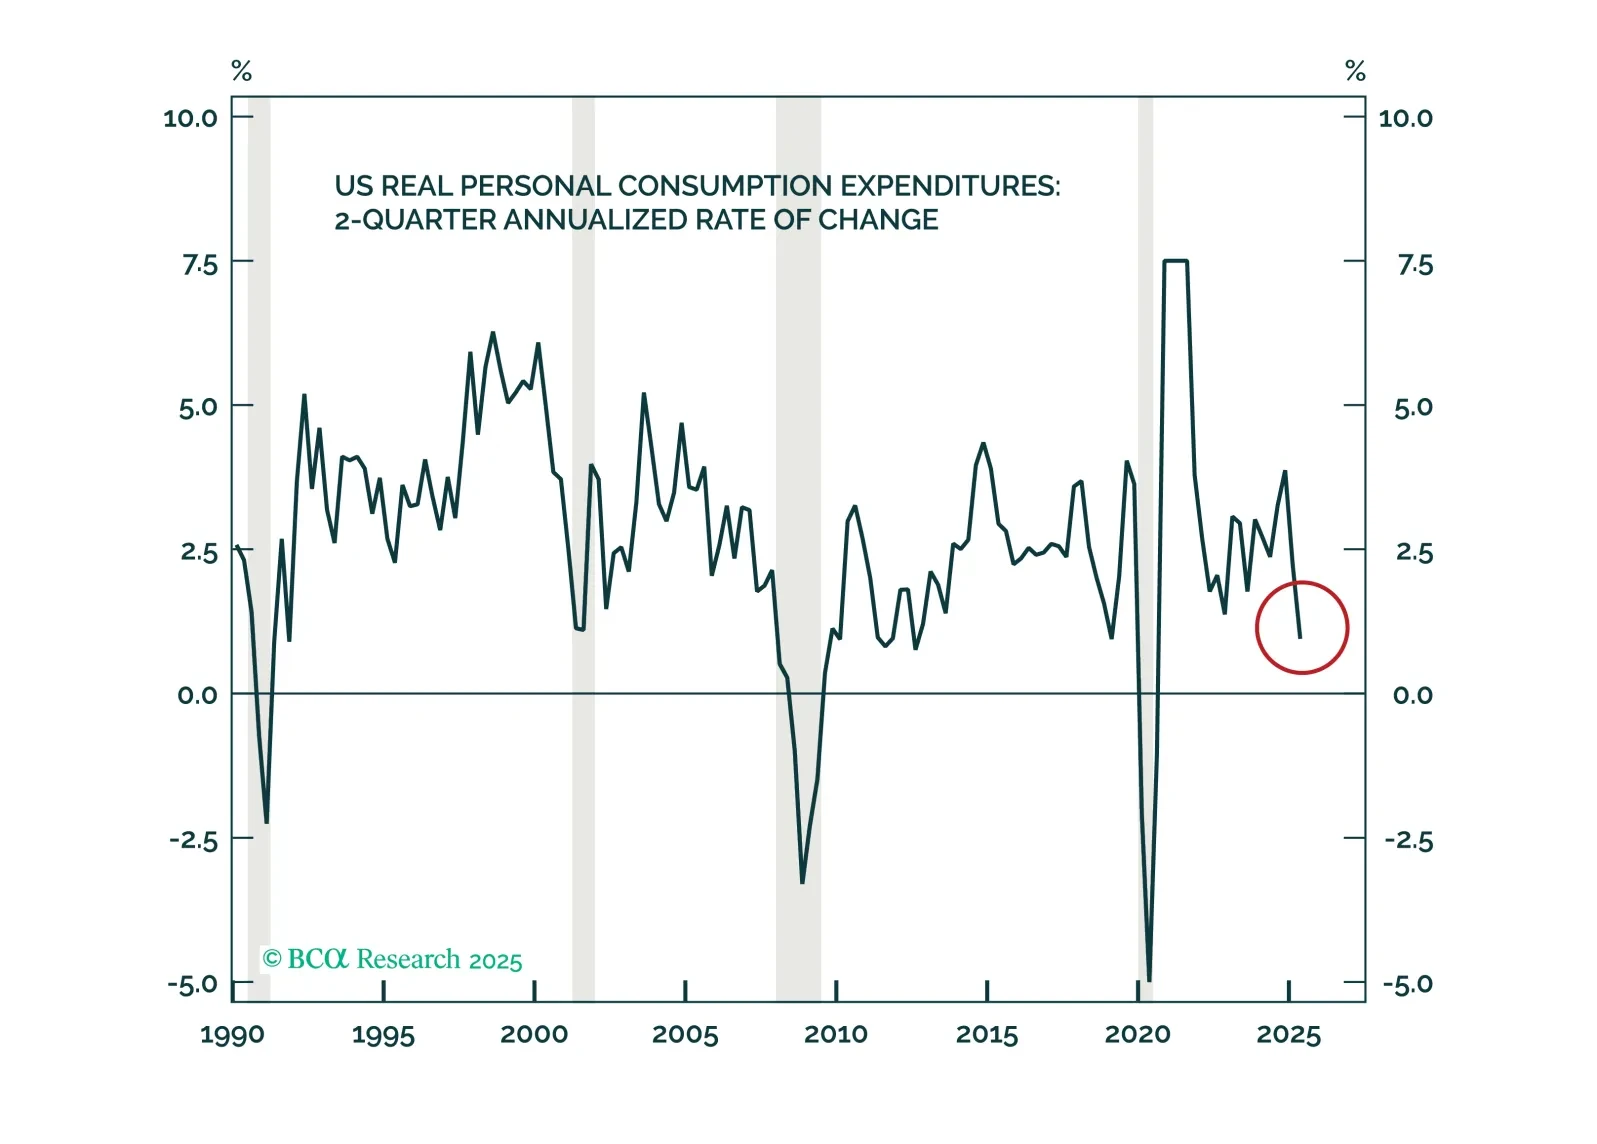
Economic activity plainly slowed in the first half, led by decelerating consumption and payrolls growth, but financial markets didn’t care. If the next two weeks of data don’t indicate that the May-June slowdown stretched into July and August, we will likely drop our defensive recommendations.