 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.

Central banks remain on hold amid heightened uncertainty. We rely on BCA’s Central Bank Monitors to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.
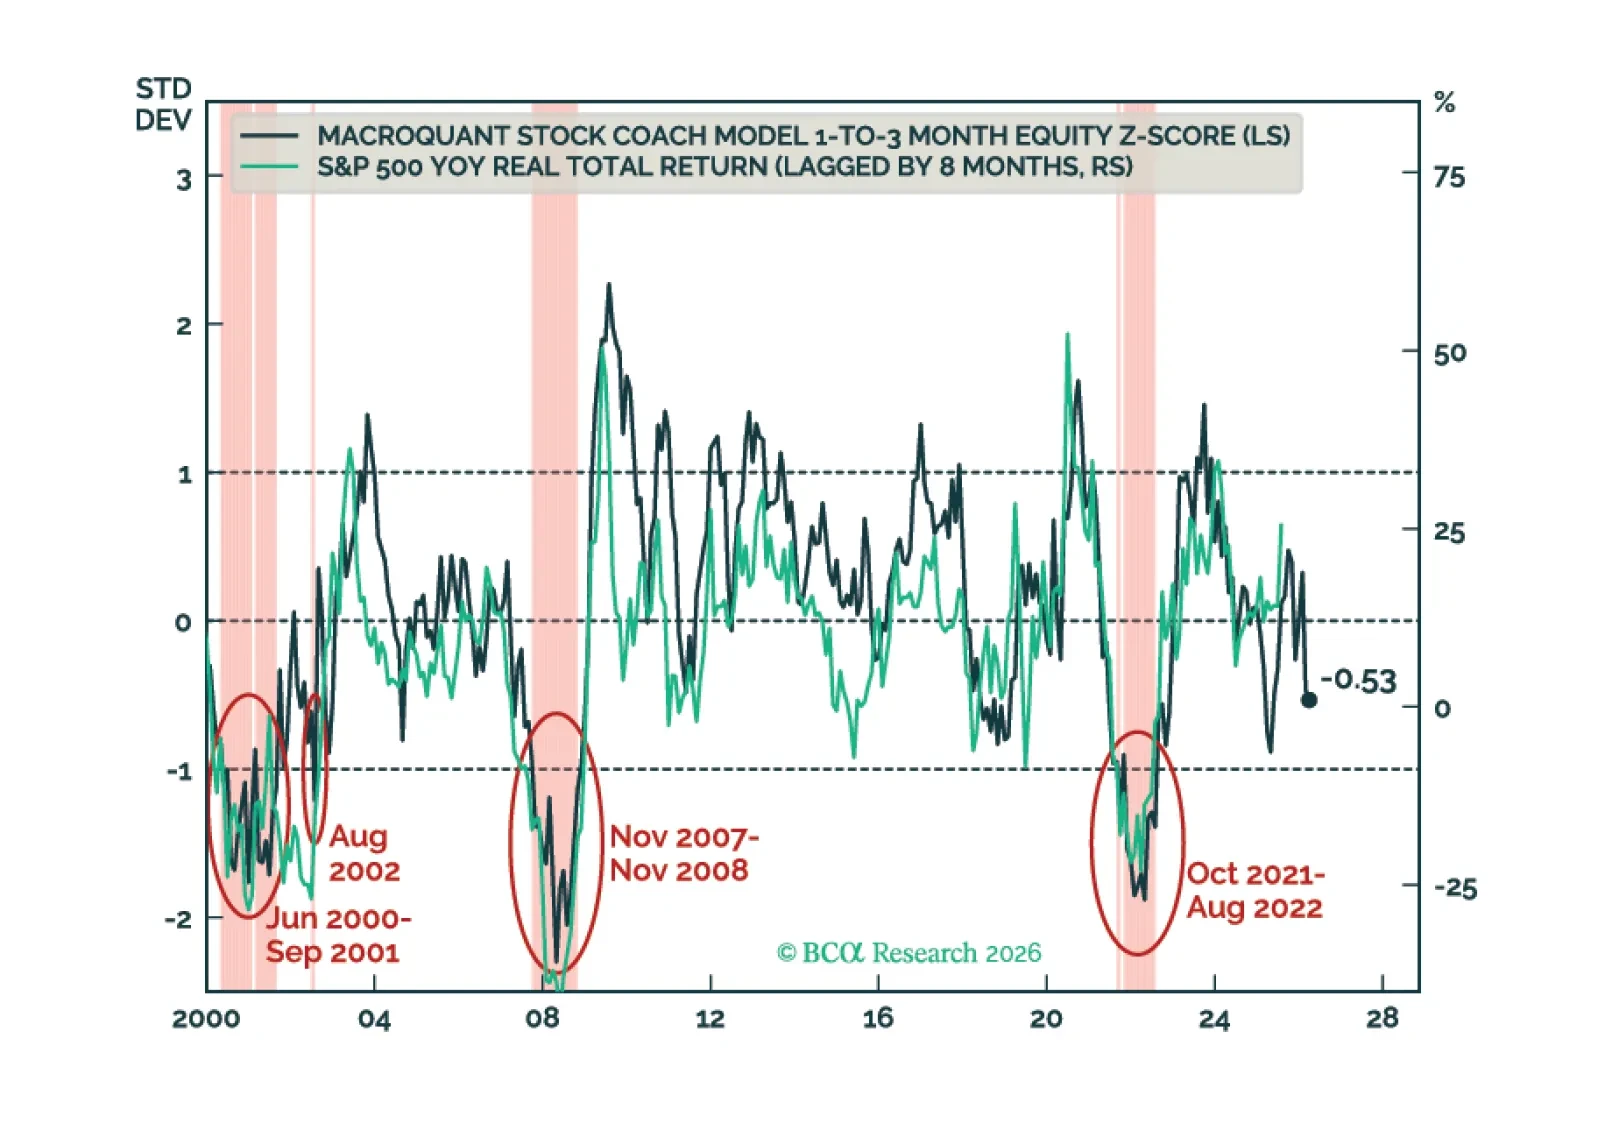
MacroQuant recommends an underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is neutral-to-slightly positive on the US dollar, remains neutral on gold, upgrades copper to neutral, and is very bullish on oil.
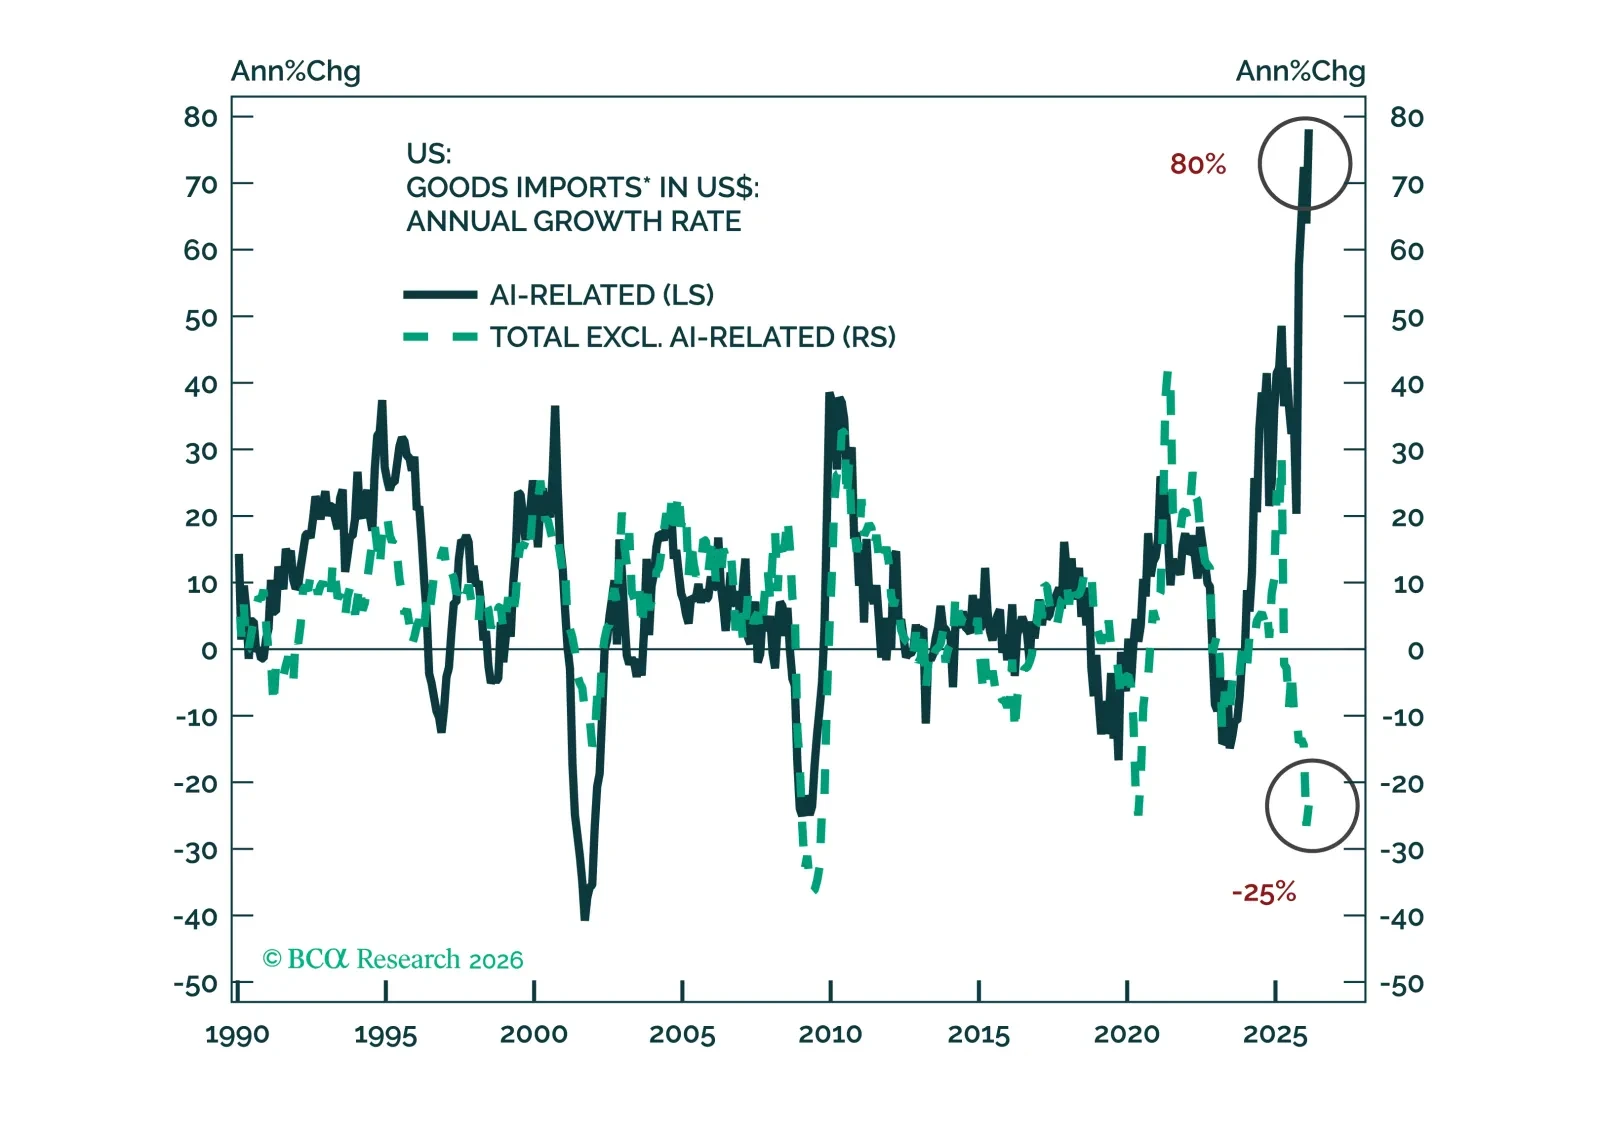
Global trade has held up despite US non-AI import volumes contracting by 25% over the past 12 months. The strength in global trade has concentrated in two areas: (1) imports of AI-related hardware and (2) developing countries’ imports, especially from China. Will these continue?
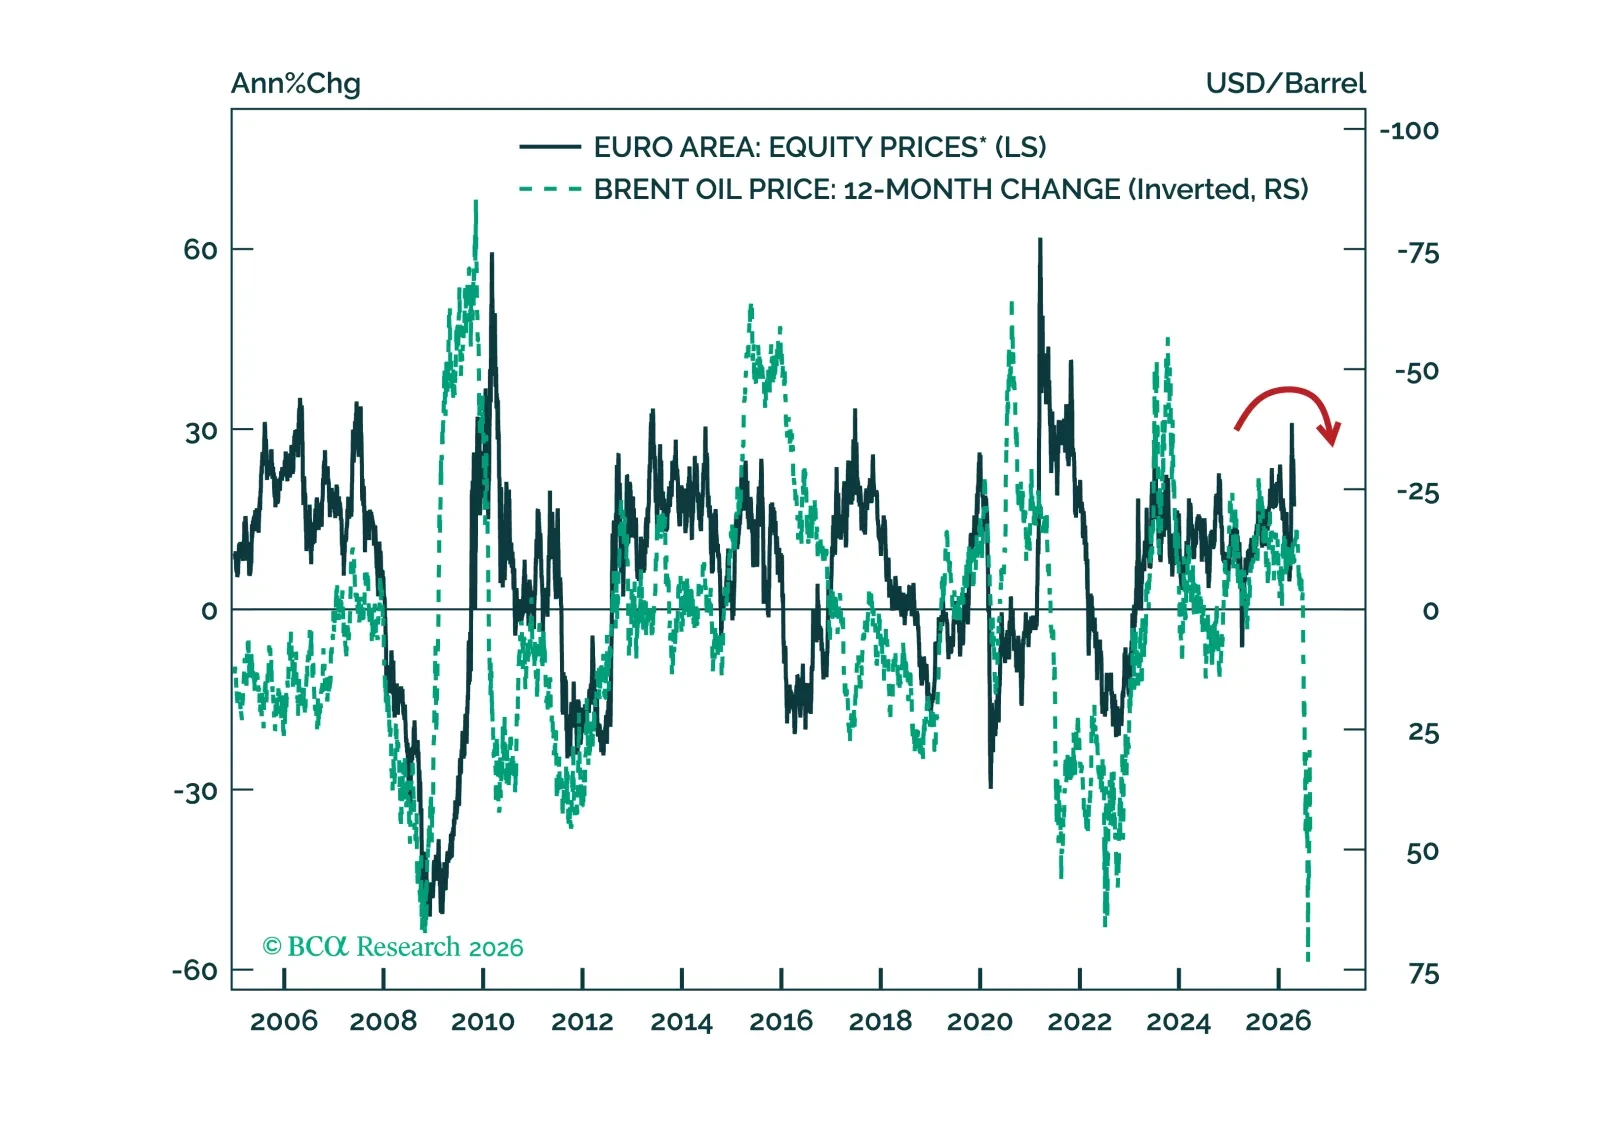
The longer the Strait of Hormuz remains closed, the more likely the Eurozone will experience an economic recession, as higher energy prices, supply chain disruptions, and weaker global demand slowly grind the European economy to a halt. The relief rally is running out of time. Investors should add exposure to the best-performing sectors following past oil supply shocks: Energy, pharma, and utilities.
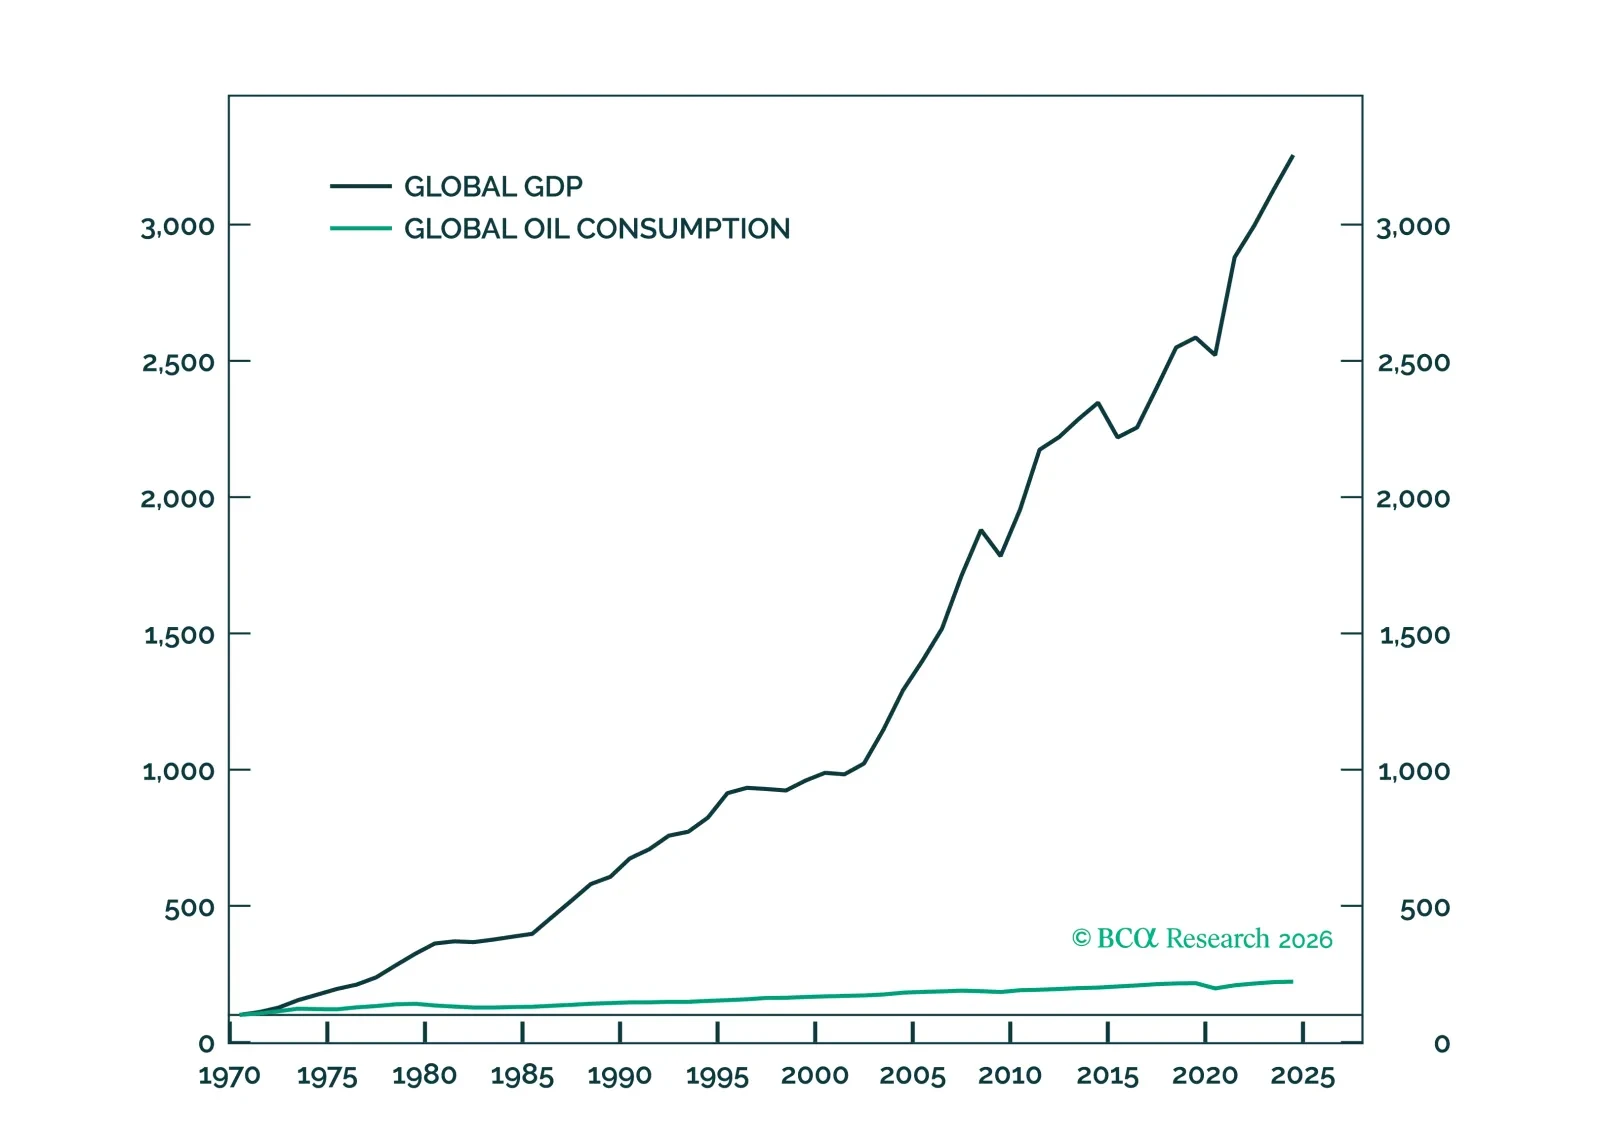
The S&P 500 finished last week at an all-time high as optimism over earnings has pushed the Iran conflict out of the spotlight. Despite uncertainty in the Strait of Hormuz, we do not think investors have enough evidence to justify underweighting equities and other risk assets.
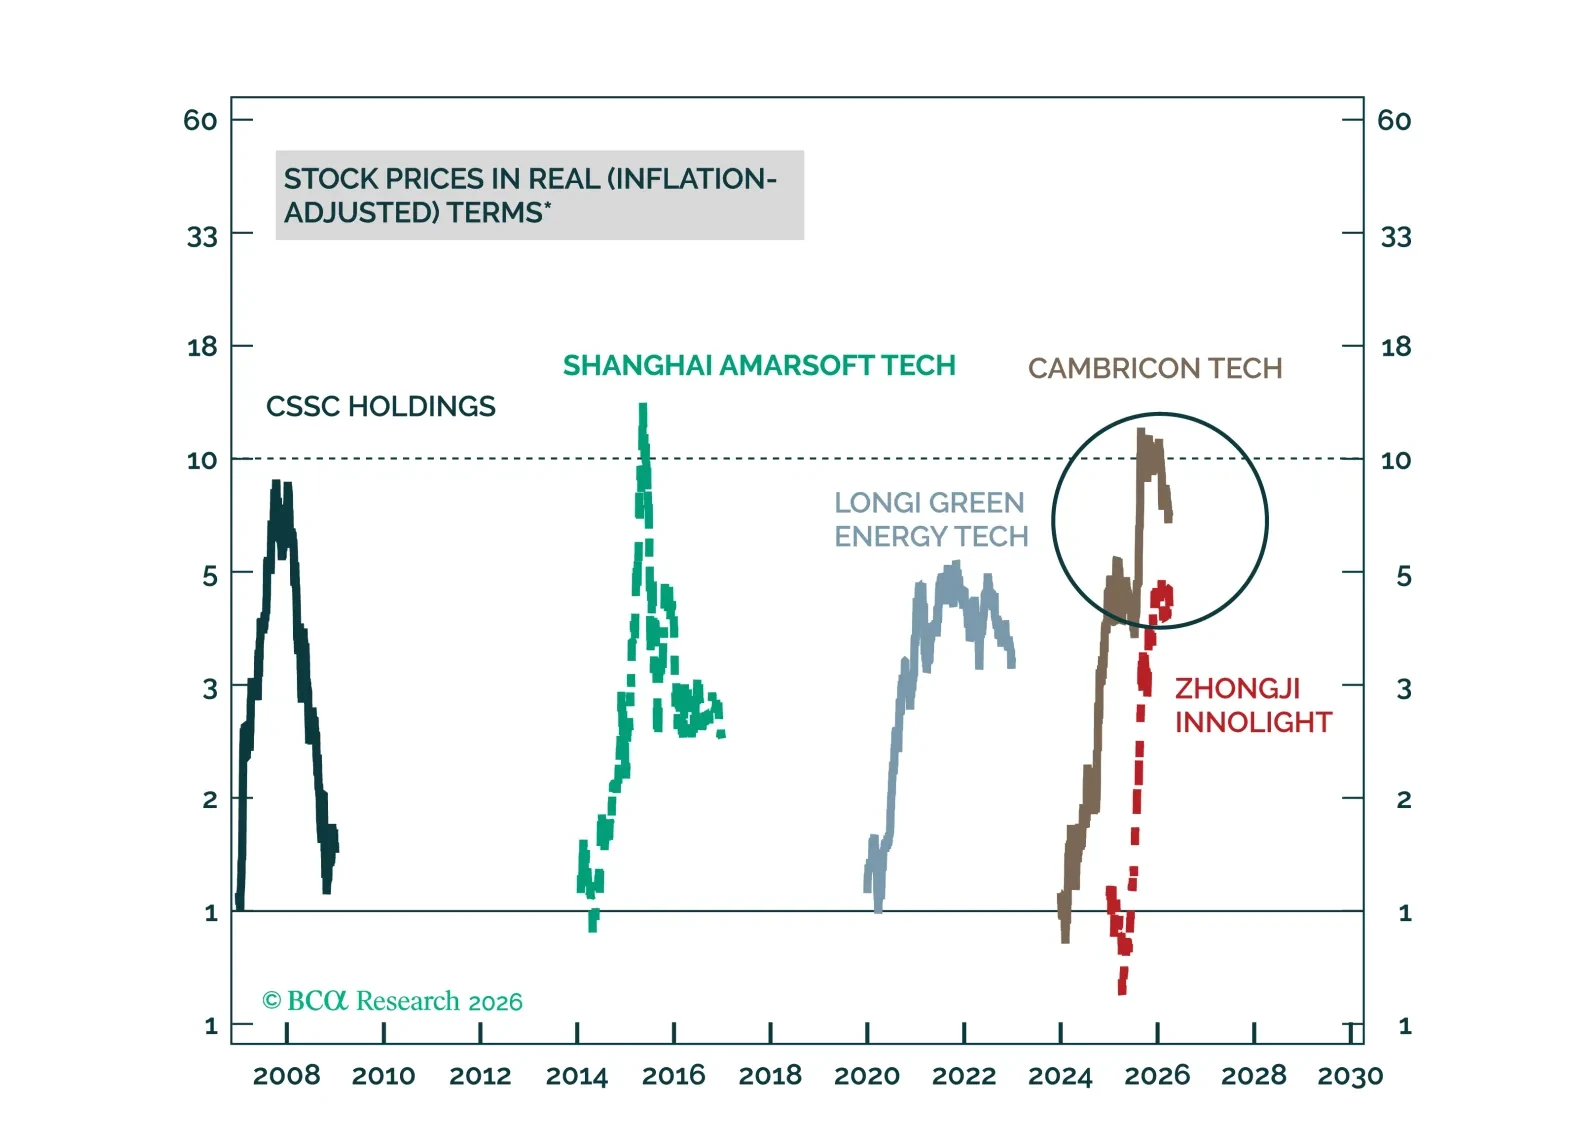
Chinese onshore equities are riding the global “scarcity trade,” powered by tight semi supply and surging alternative-energy demand. How should investors position in this environment?
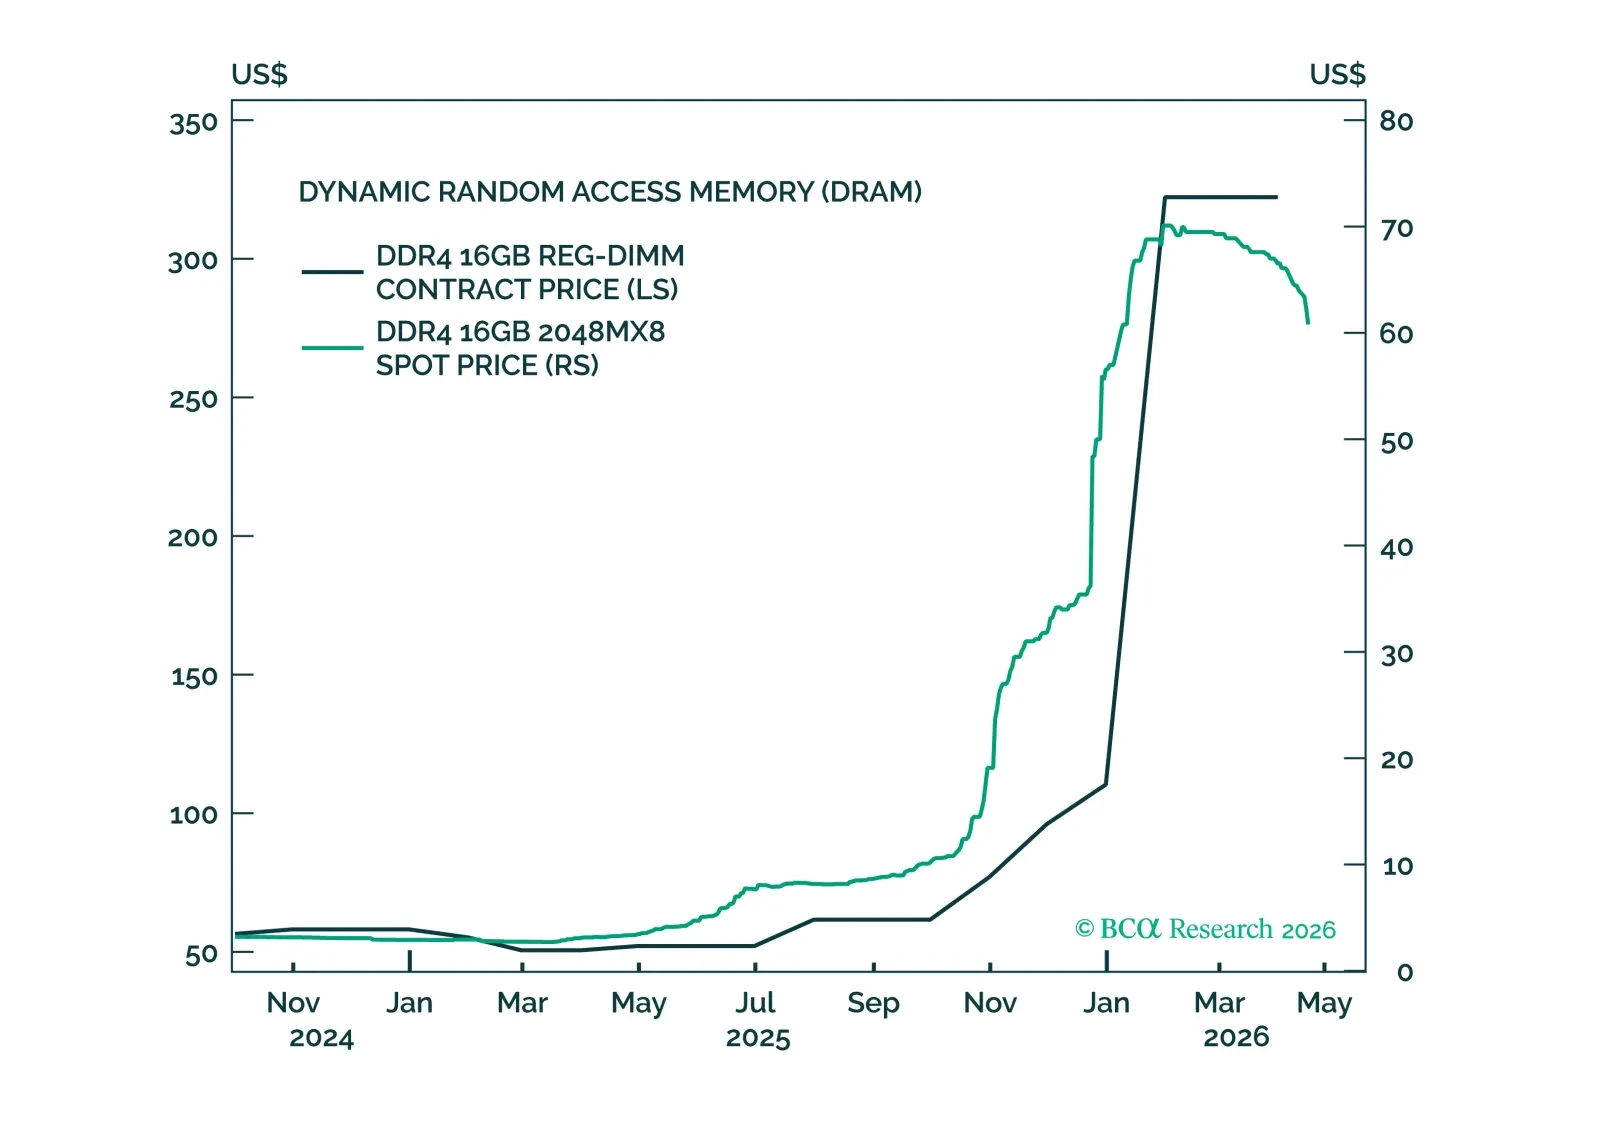
Most of the increase in S&P 500 earnings estimates this year has stemmed from shortages. The oil shortage, which has pushed up estimates for energy companies, will fade once the military conflict is resolved. However, the shortage of semiconductors and other AI paraphernalia could persist for a while longer. As such, we are moving our recommended 12-month equity allocation from a slight underweight to neutral. We are already neutral on a 3-month horizon.
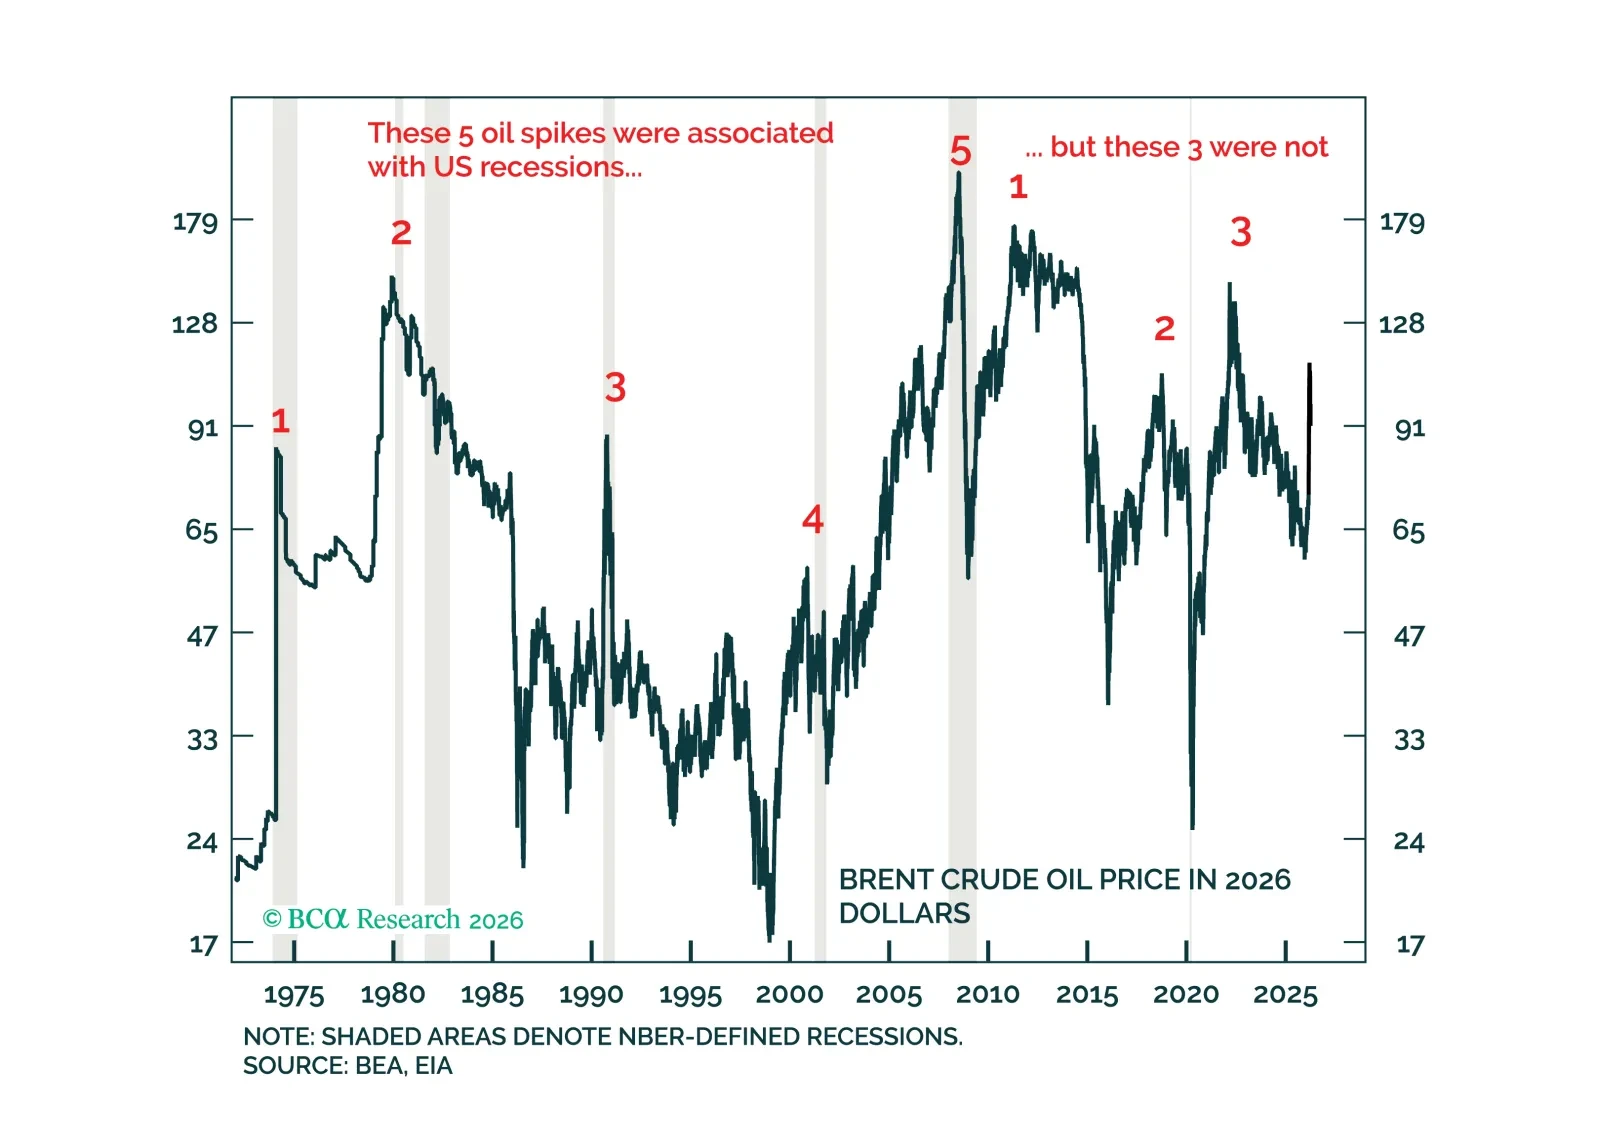
In the US, the oil shock’s impact is more inflationary than recessionary but in the other economies, like the UK, the impact is both inflationary and recessionary. This creates relative value opportunities for bond investors. Plus, we reiterate short AUD/JPY as a trade.
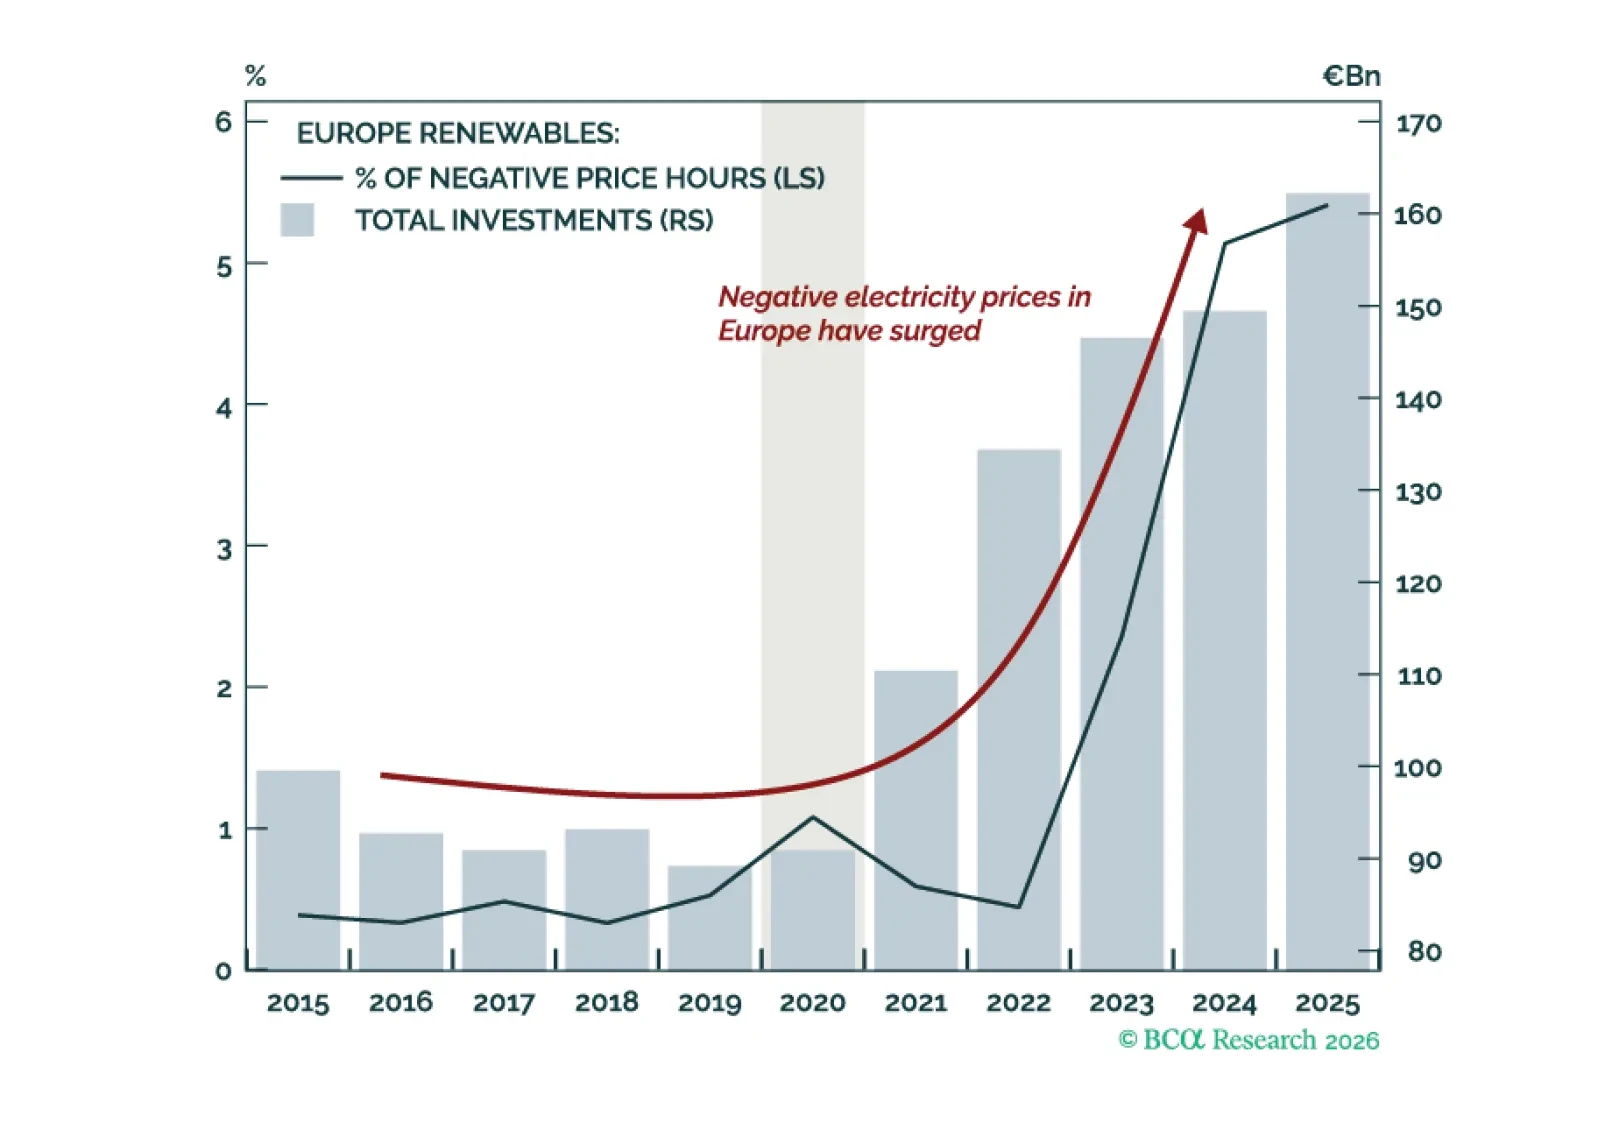
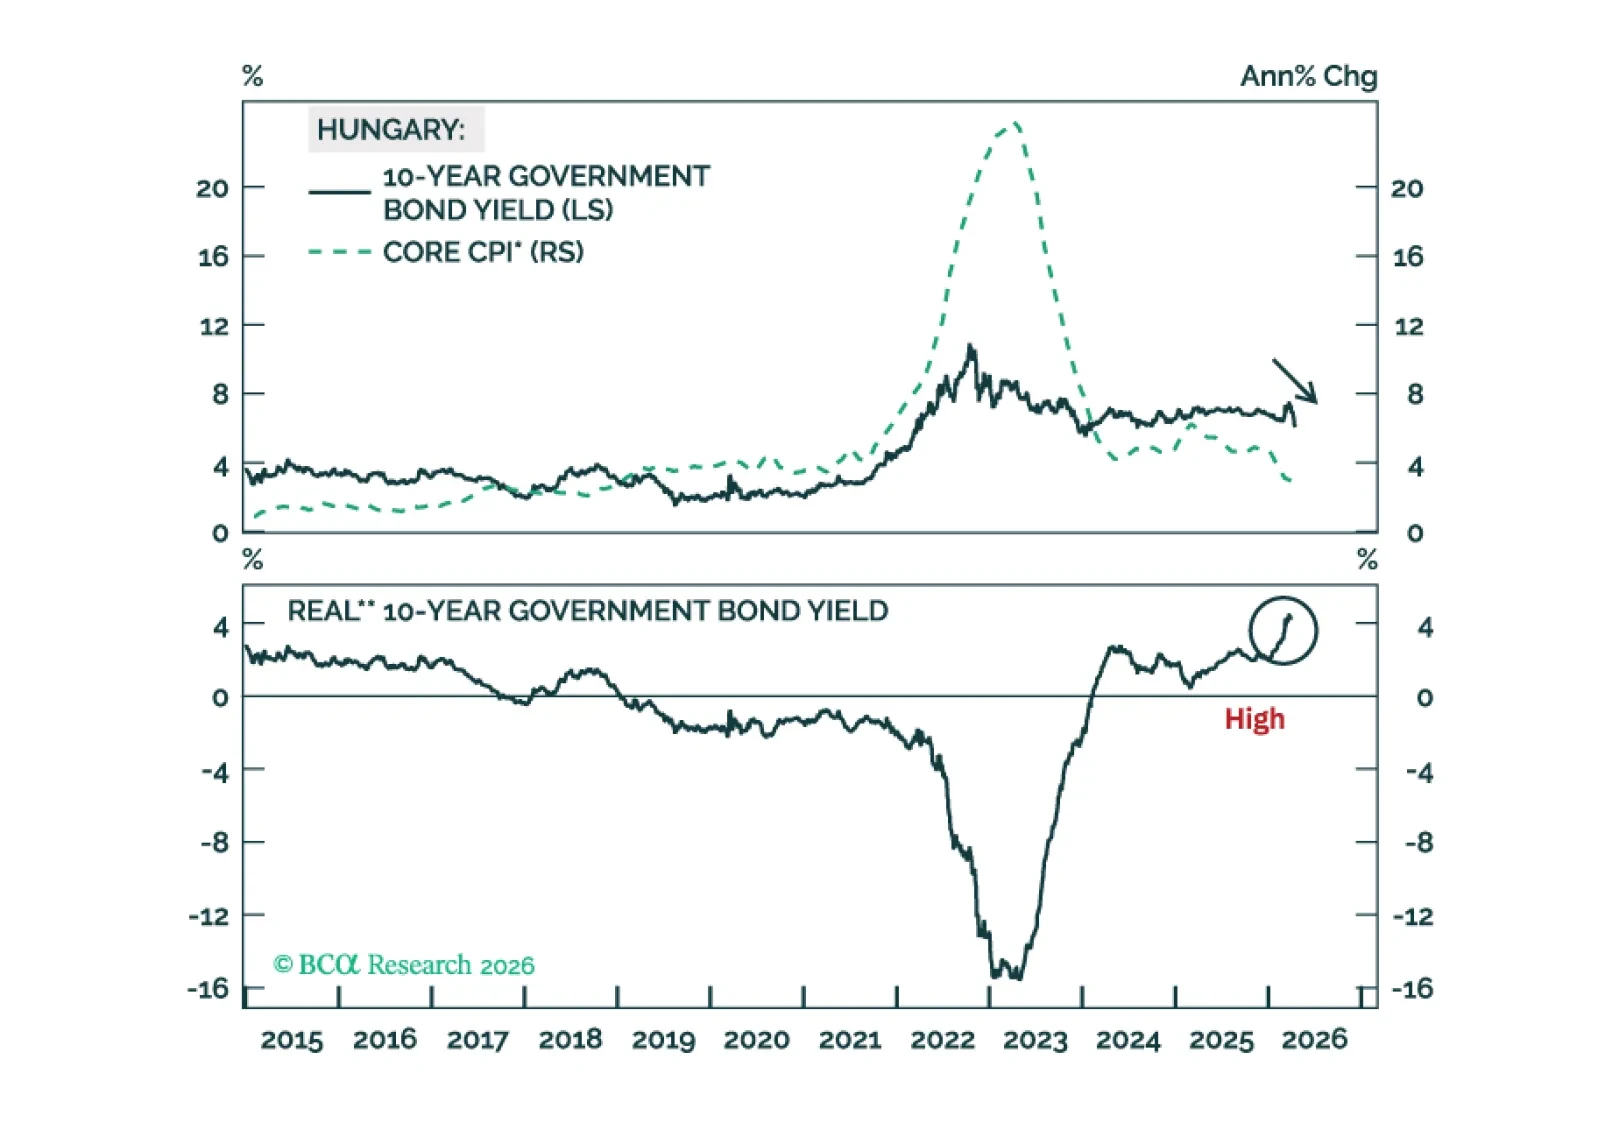
Hungary’s growth outlook has improved as the election of a new government will likely unlock significant EU funds for the country. Currency traders should go long the Hungarian forint / short US dollar.