CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
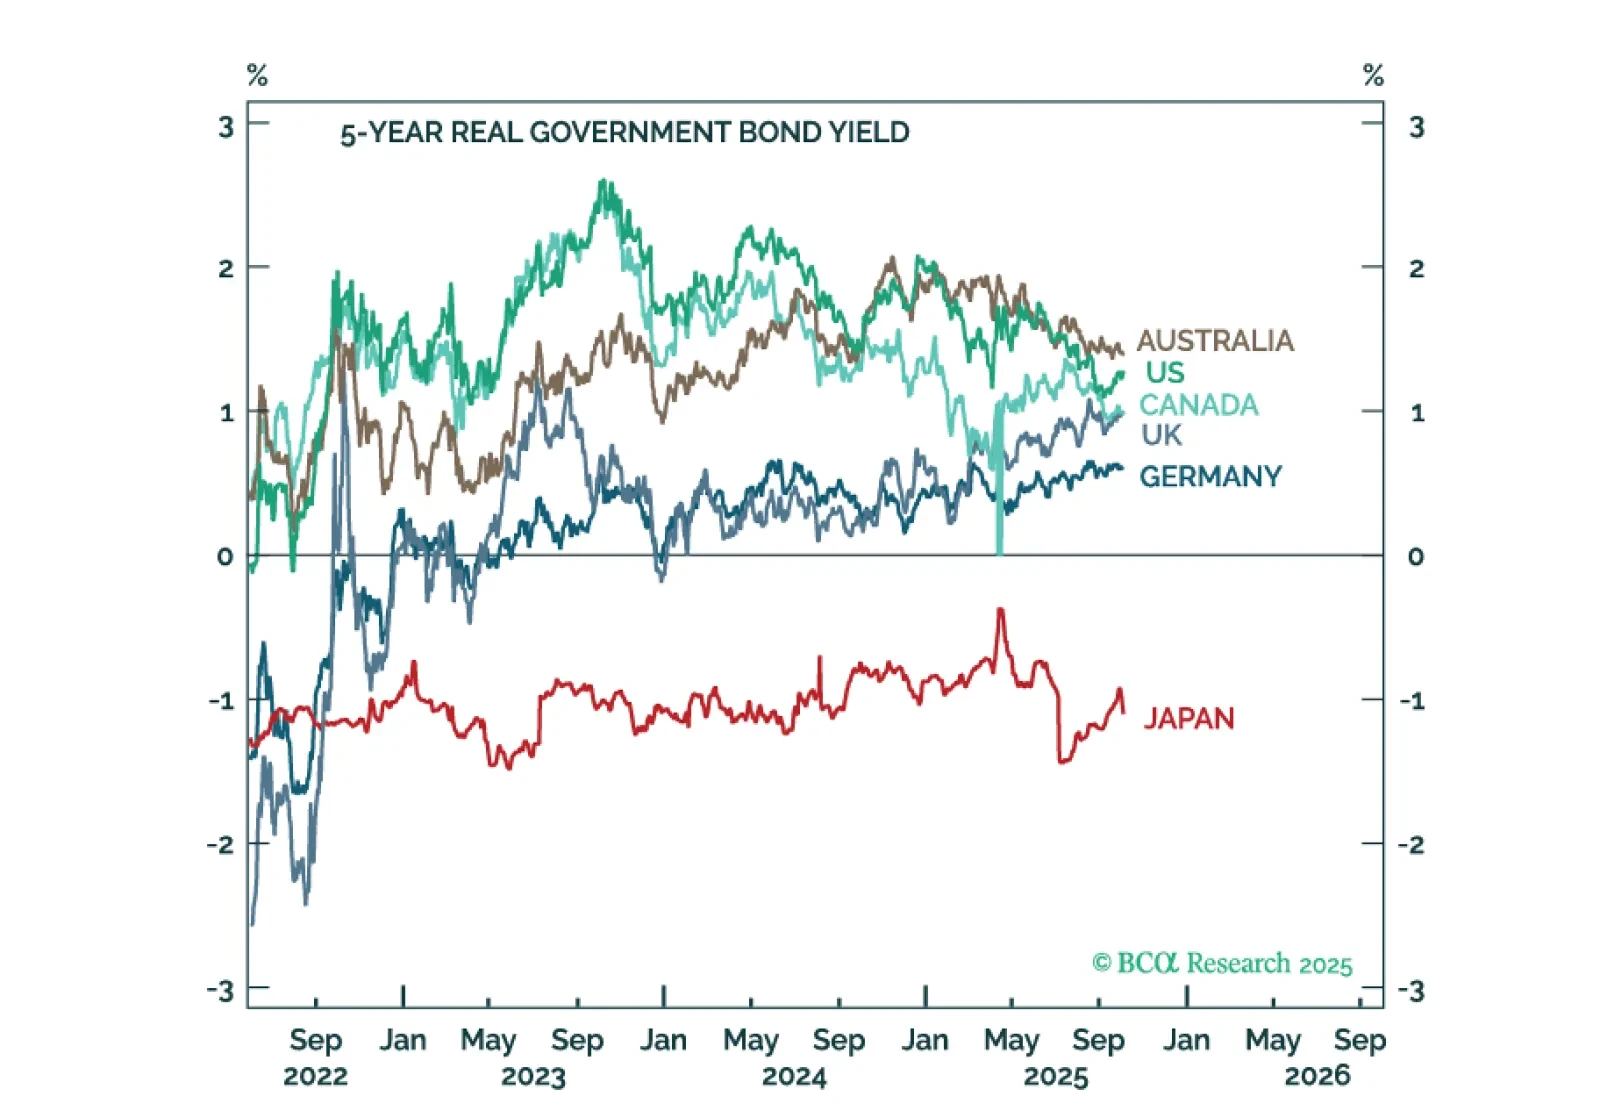
The surprise election of Sanae Takaichi as Japan’s ruling party new leader has delivered yet another blow to the beleaguered yen. Takaichi is widely expected to pursue the basic tenets of Abenomics – easier fiscal and monetary policy.
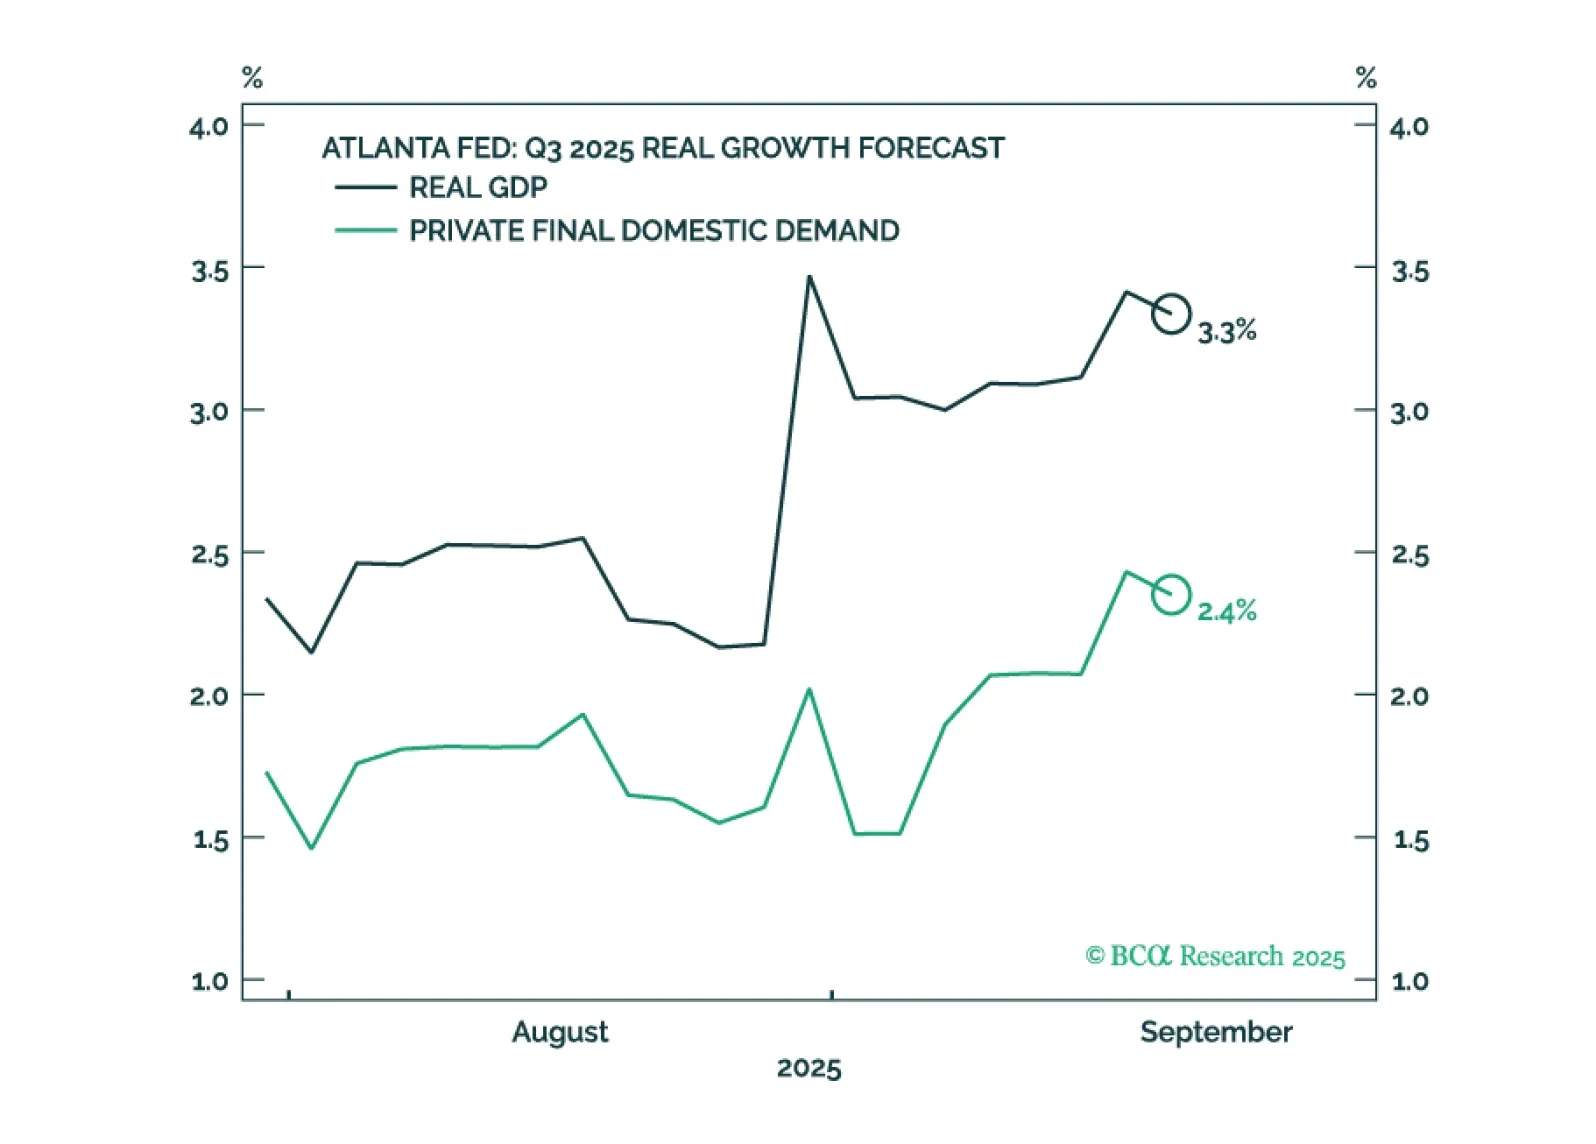
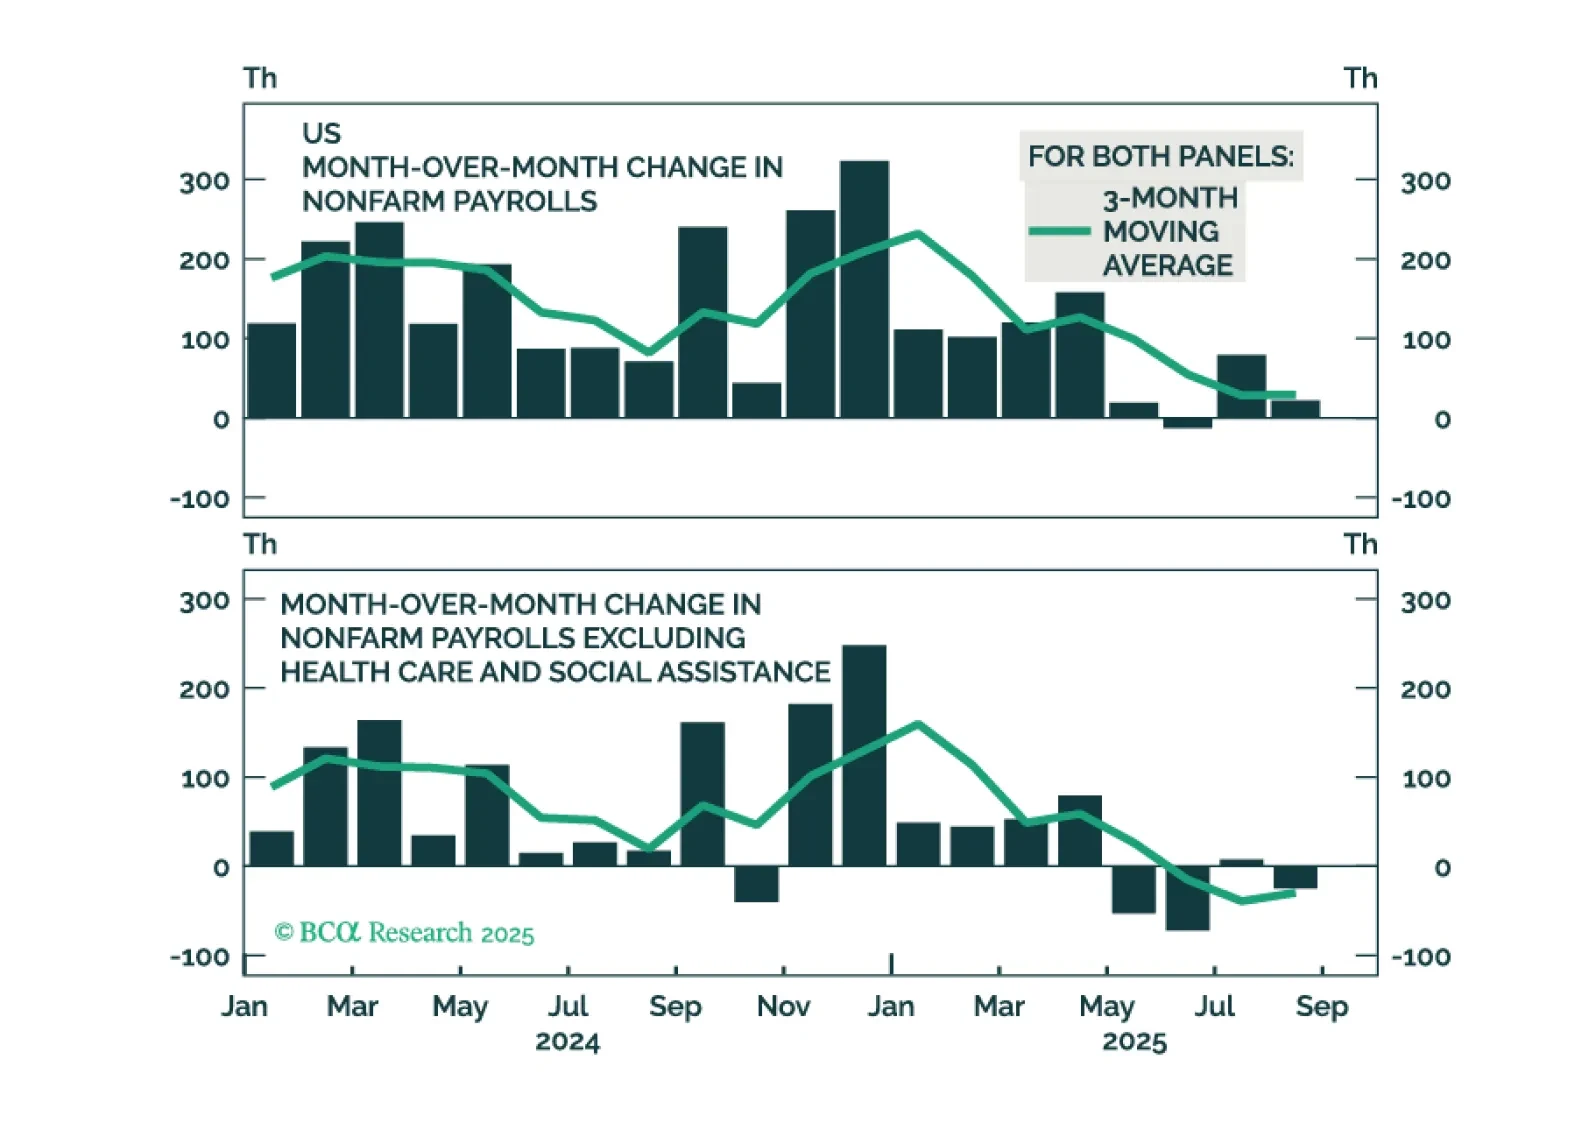
US GDP growth appears to have accelerated even as employment growth has faltered. We will make a final decision in early October when we publish our next Strategy Outlook, but most likely, we will cut our 12-month US recession probability to 40%-to-50% from 60% and turn tactically neutral on stocks, while still retaining a modest equity underweight over a 12-month horizon.
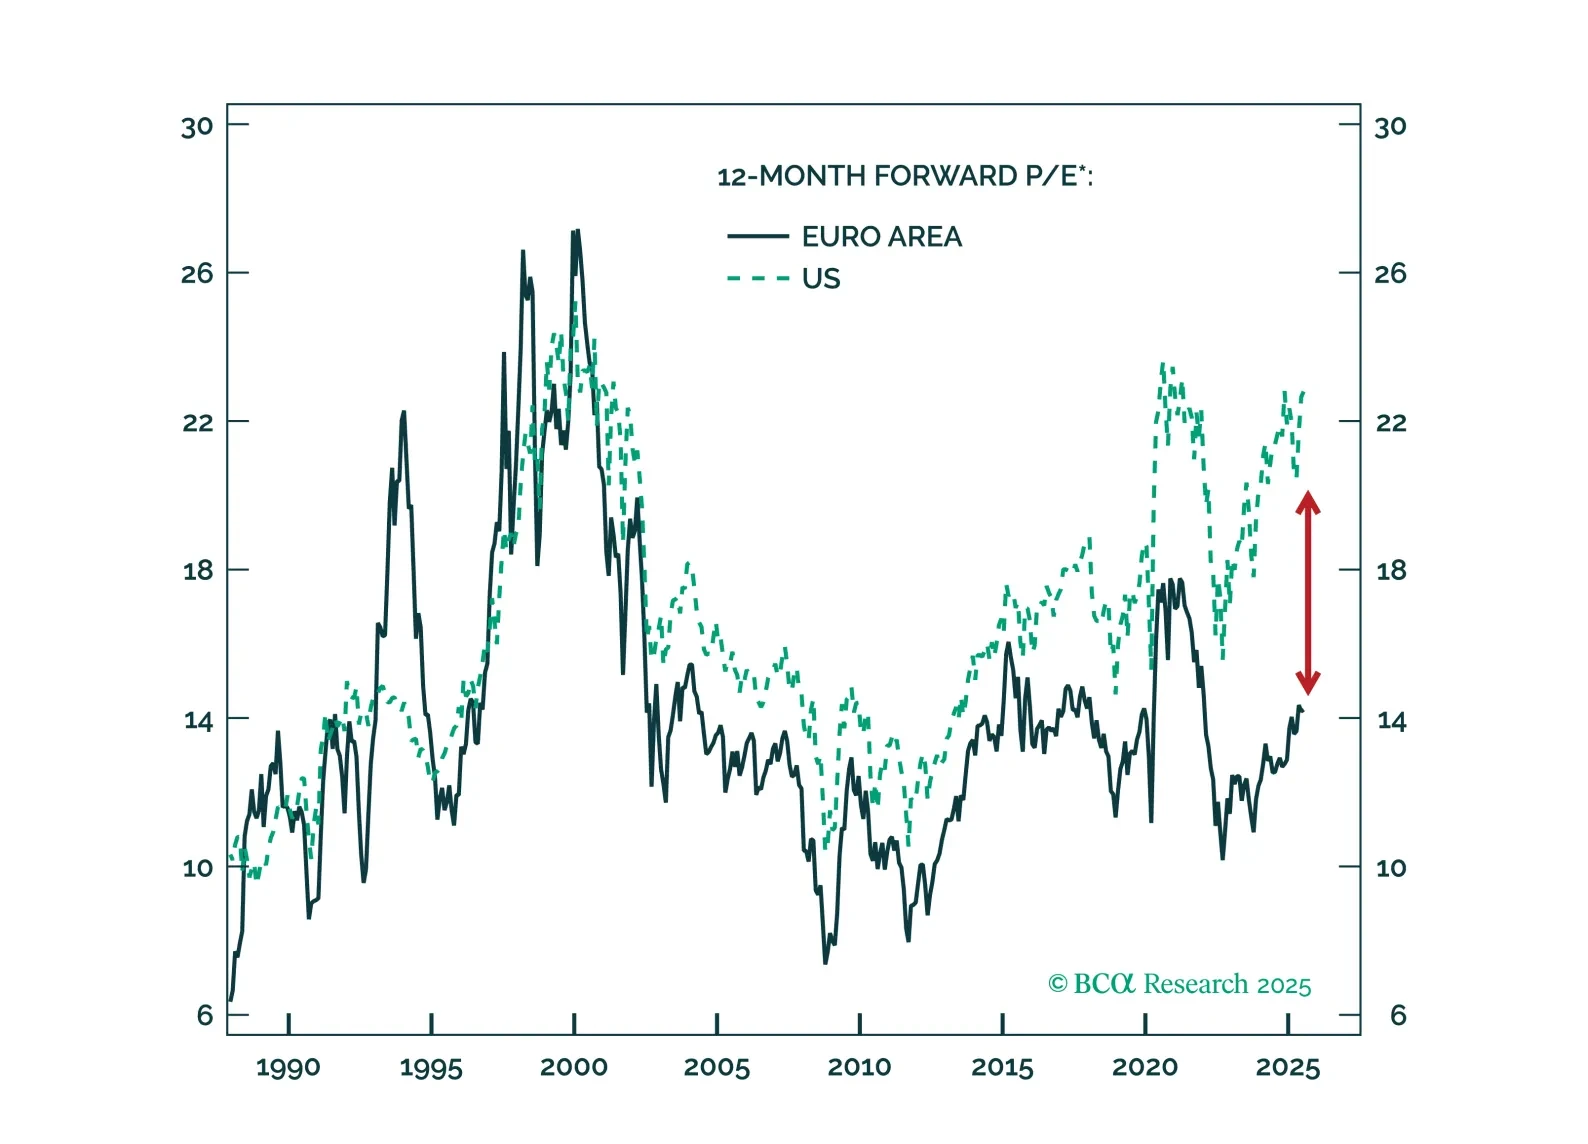
While it is impossible to know exactly when global equities will peak, there are now enough vulnerabilities to justify keeping one’s finger near the eject button.

Inflation expectations in the US remain reasonably well anchored and there are few signs of a brewing wage-price spiral. Thus, the near-term risks to growth outweigh the risks of higher inflation. Looking beyond the next year or two, however, we are worried about stagflation.
I am pleased to announce the launch of PowerTrades, an exclusive new service for Global Investment Strategy subscribers that delivers our top trading insights directly to your inbox.
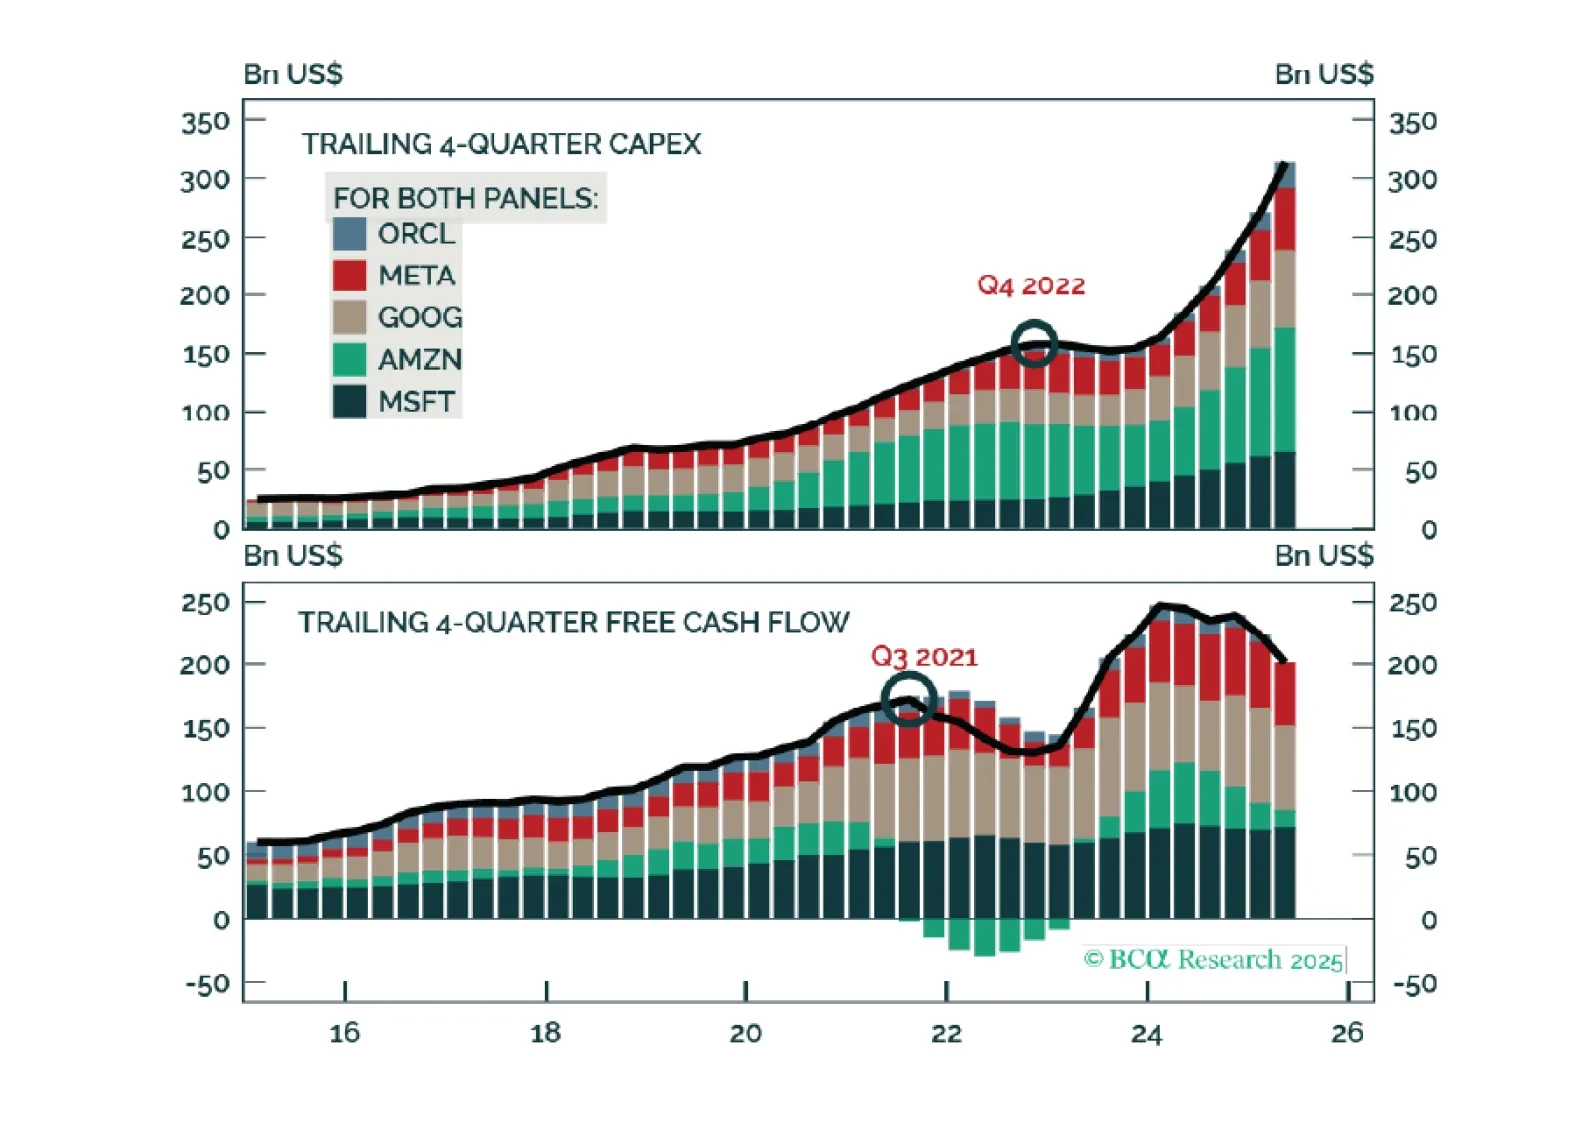
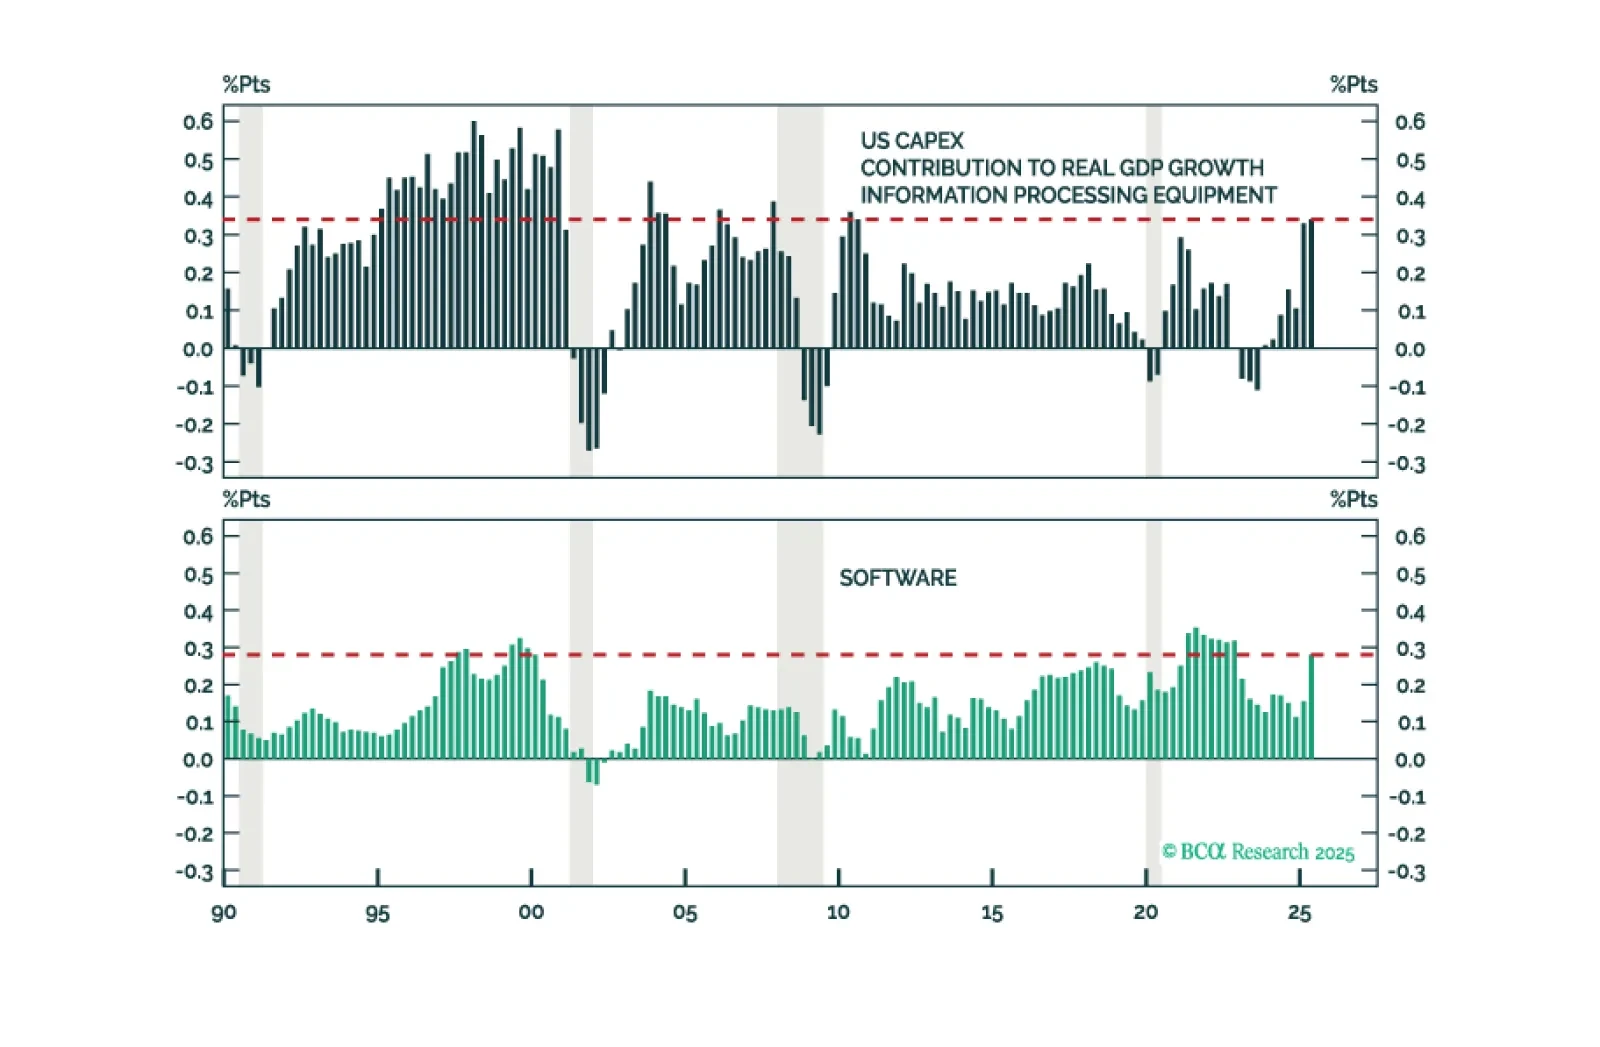
Investors will be scrutinizing Nvidia’s earnings report tonight for signs of cracks in the massive, ongoing AI capex boom. I understand the temptation to do so, but I am not certain that capex is the best metric to focus on.
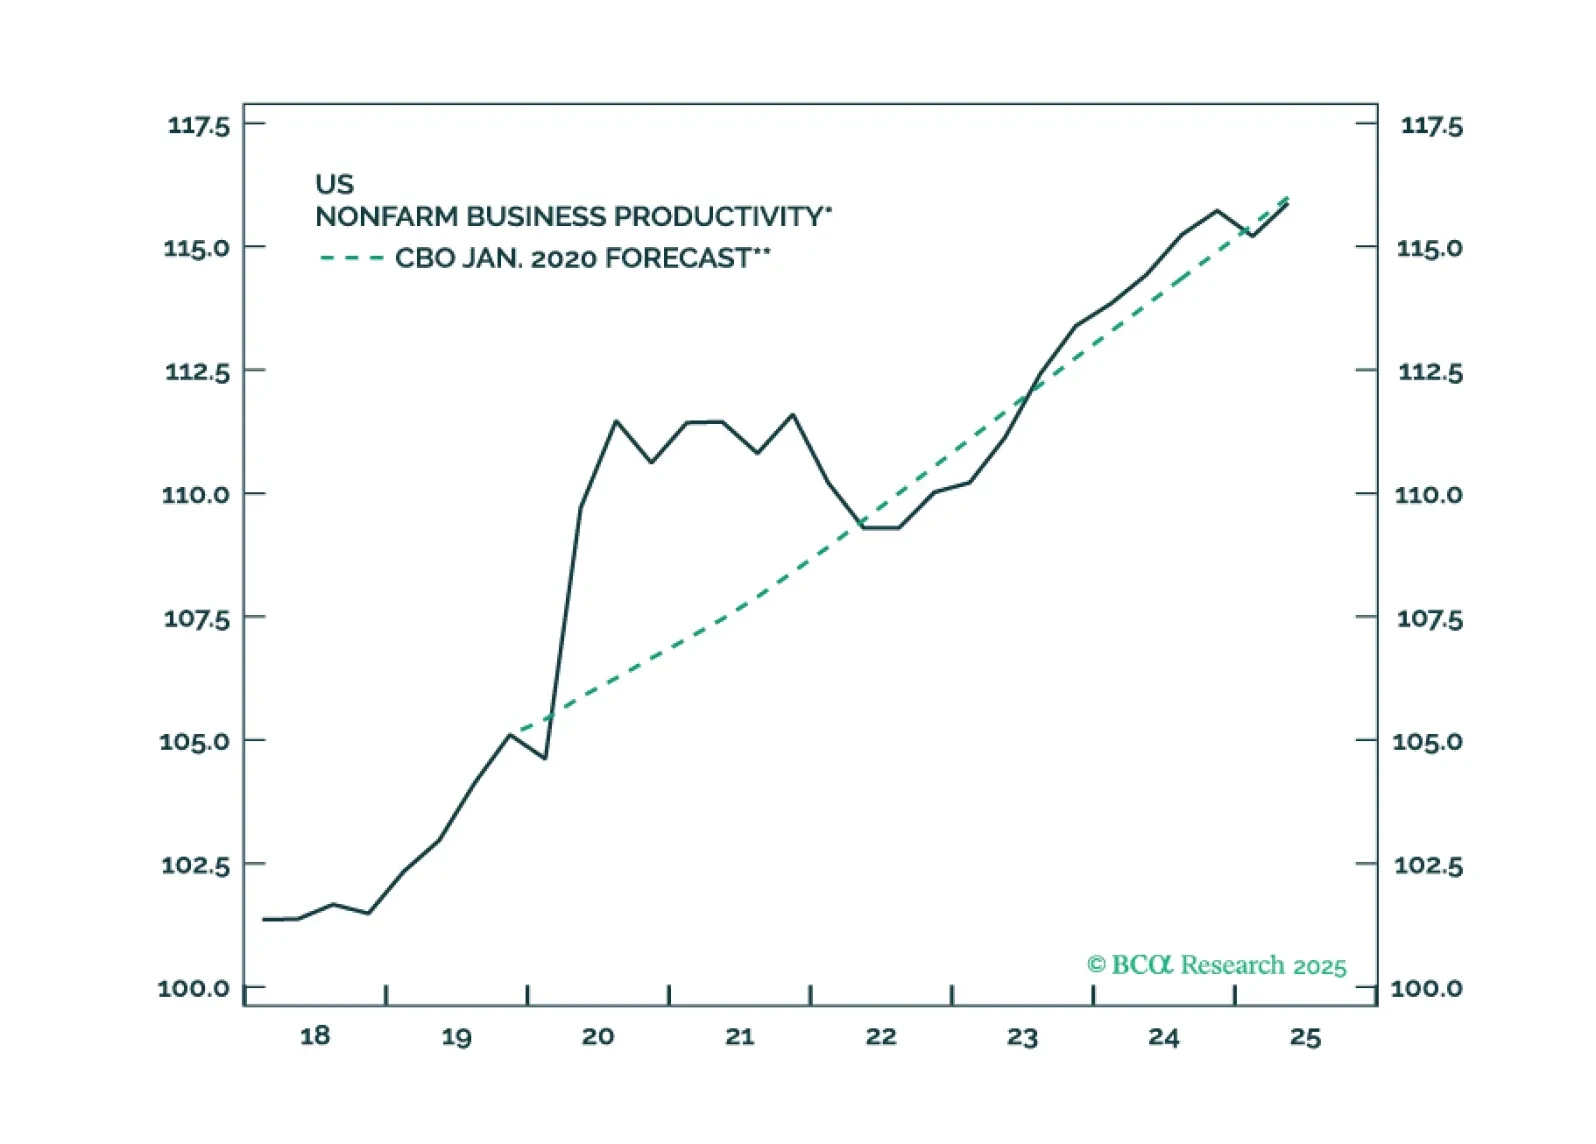
The AI boom has had less of an impact on the economy than widely believed. This may eventually change, but the risk is that investors grow impatient before it does.