 CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
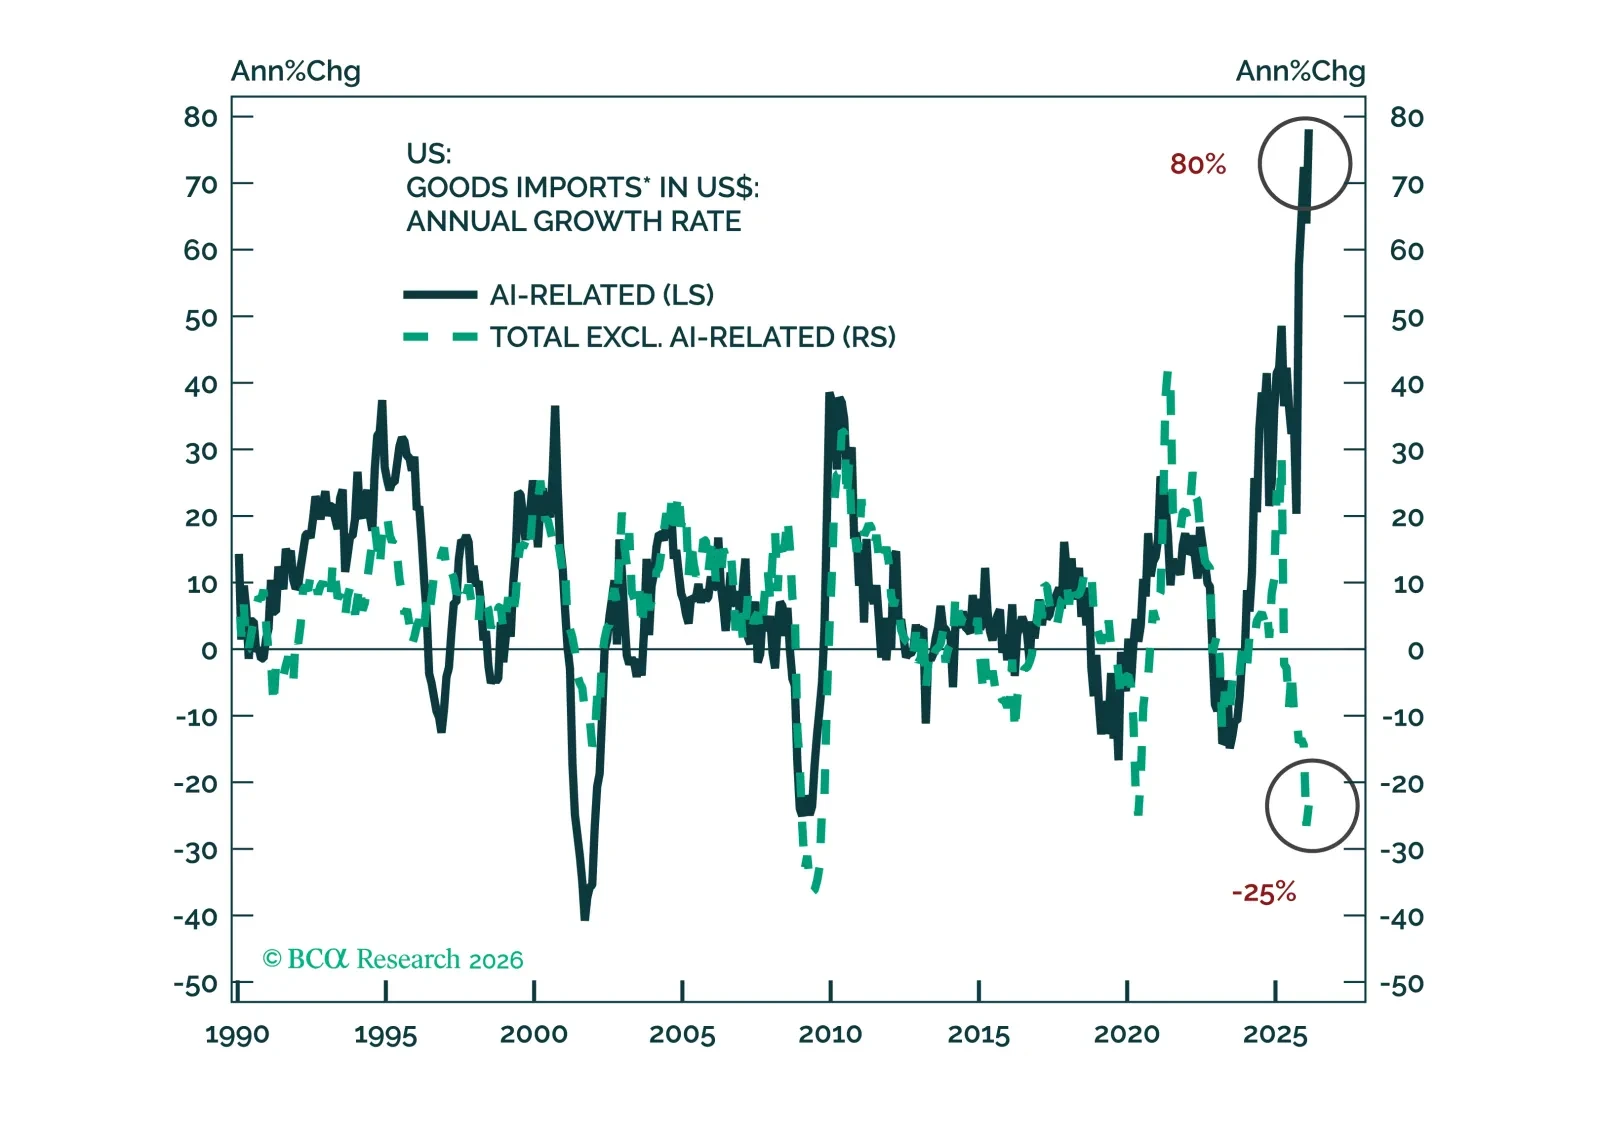
Global trade has held up despite US non-AI import volumes contracting by 25% over the past 12 months. The strength in global trade has concentrated in two areas: (1) imports of AI-related hardware and (2) developing countries’ imports, especially from China. Will these continue?
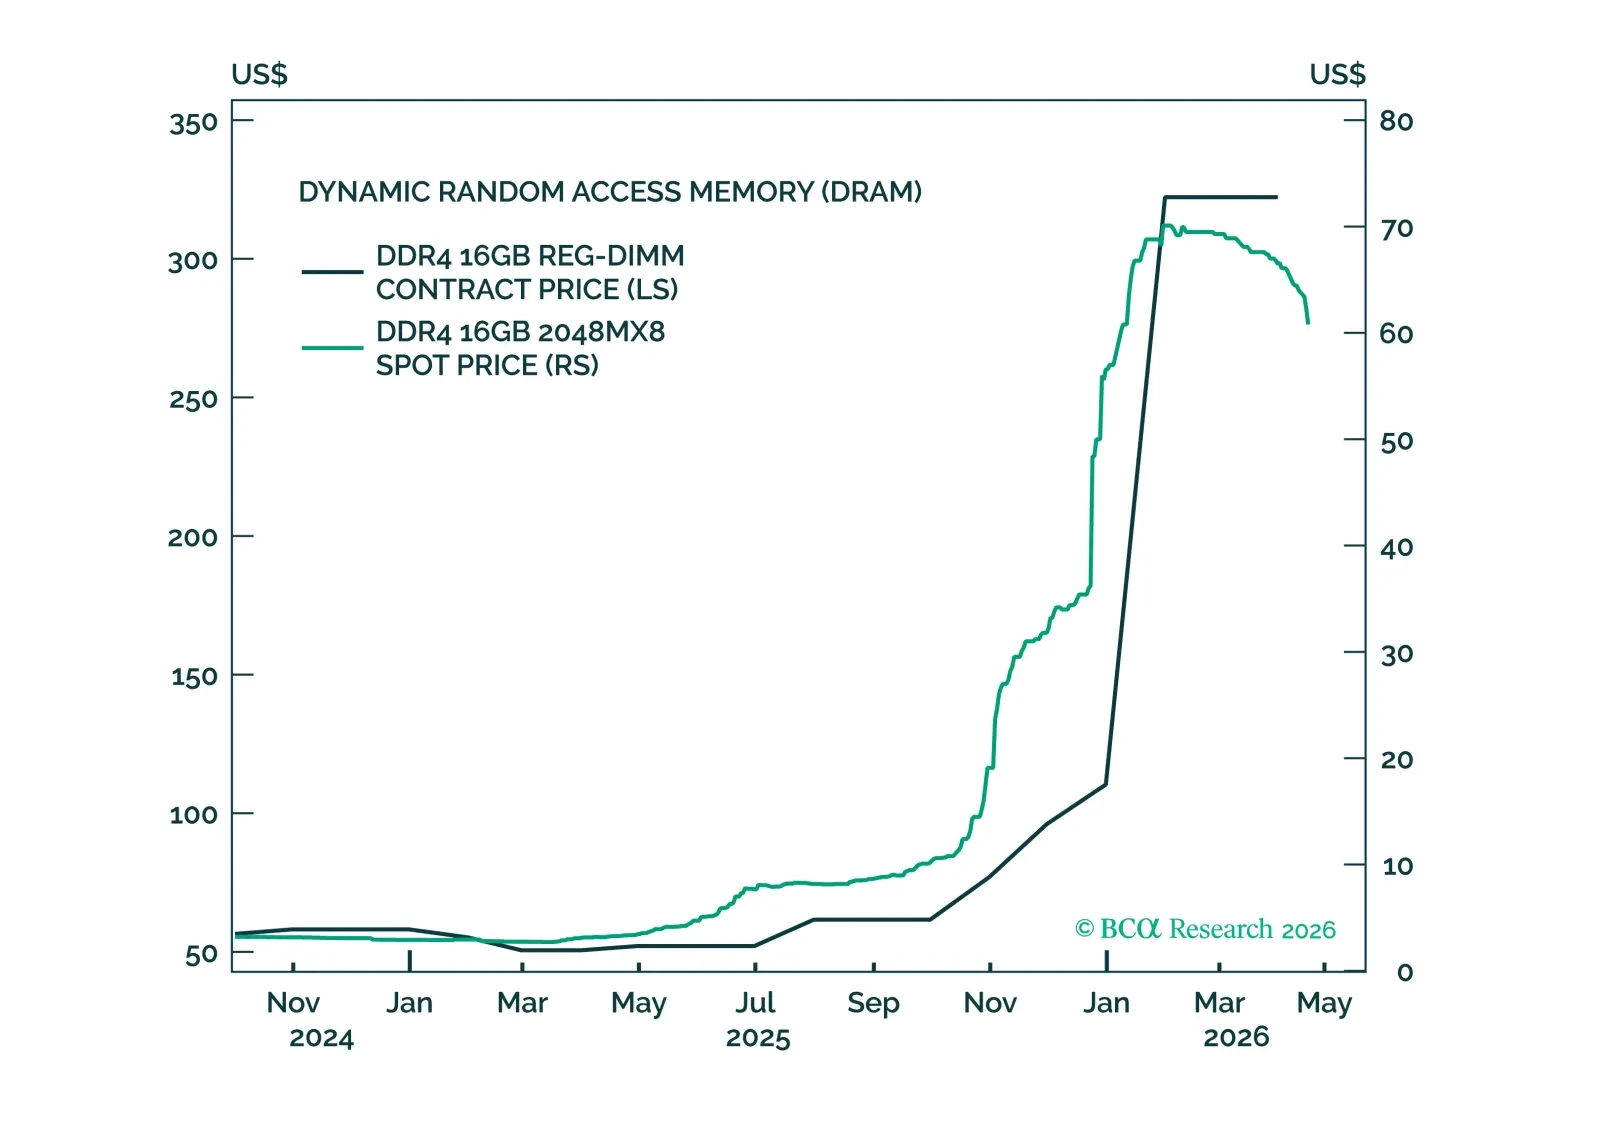
Most of the increase in S&P 500 earnings estimates this year has stemmed from shortages. The oil shortage, which has pushed up estimates for energy companies, will fade once the military conflict is resolved. However, the shortage of semiconductors and other AI paraphernalia could persist for a while longer. As such, we are moving our recommended 12-month equity allocation from a slight underweight to neutral. We are already neutral on a 3-month horizon.

We do not expect the oil shock to have a lasting effect on inflation. Looking further out, a variety of structural forces will influence inflation, including fiscal policy, globalization, demographics, and AI.
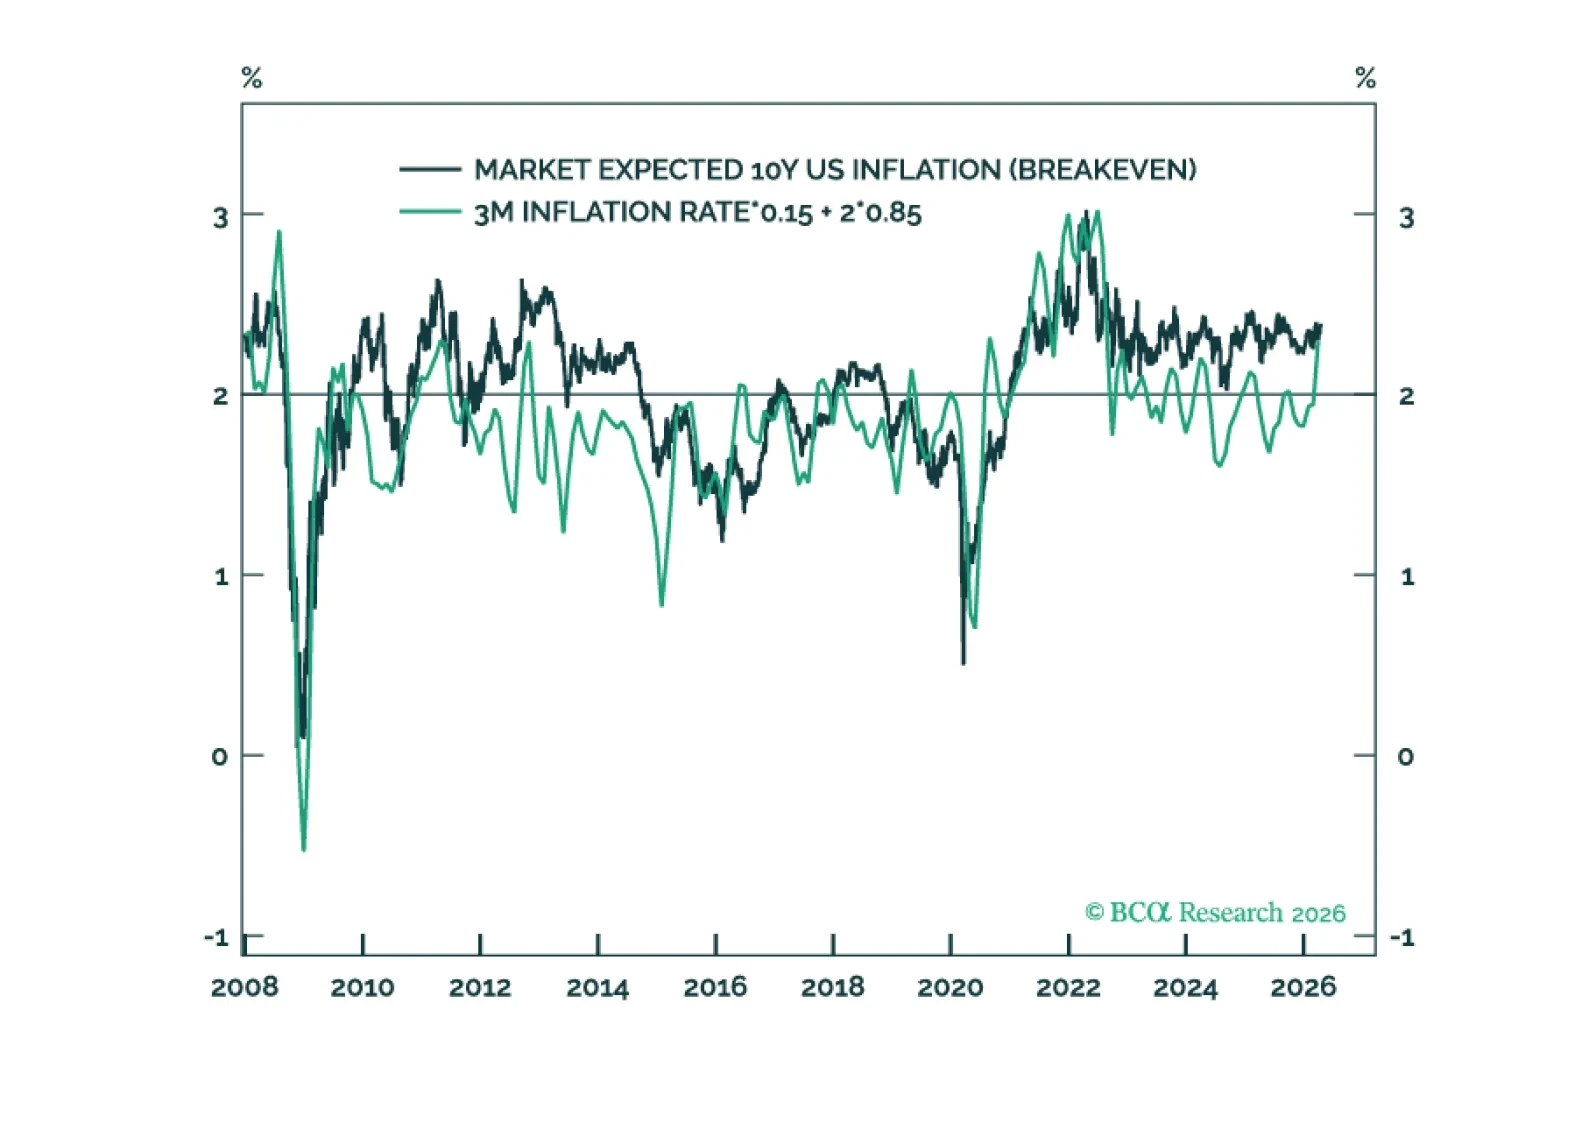
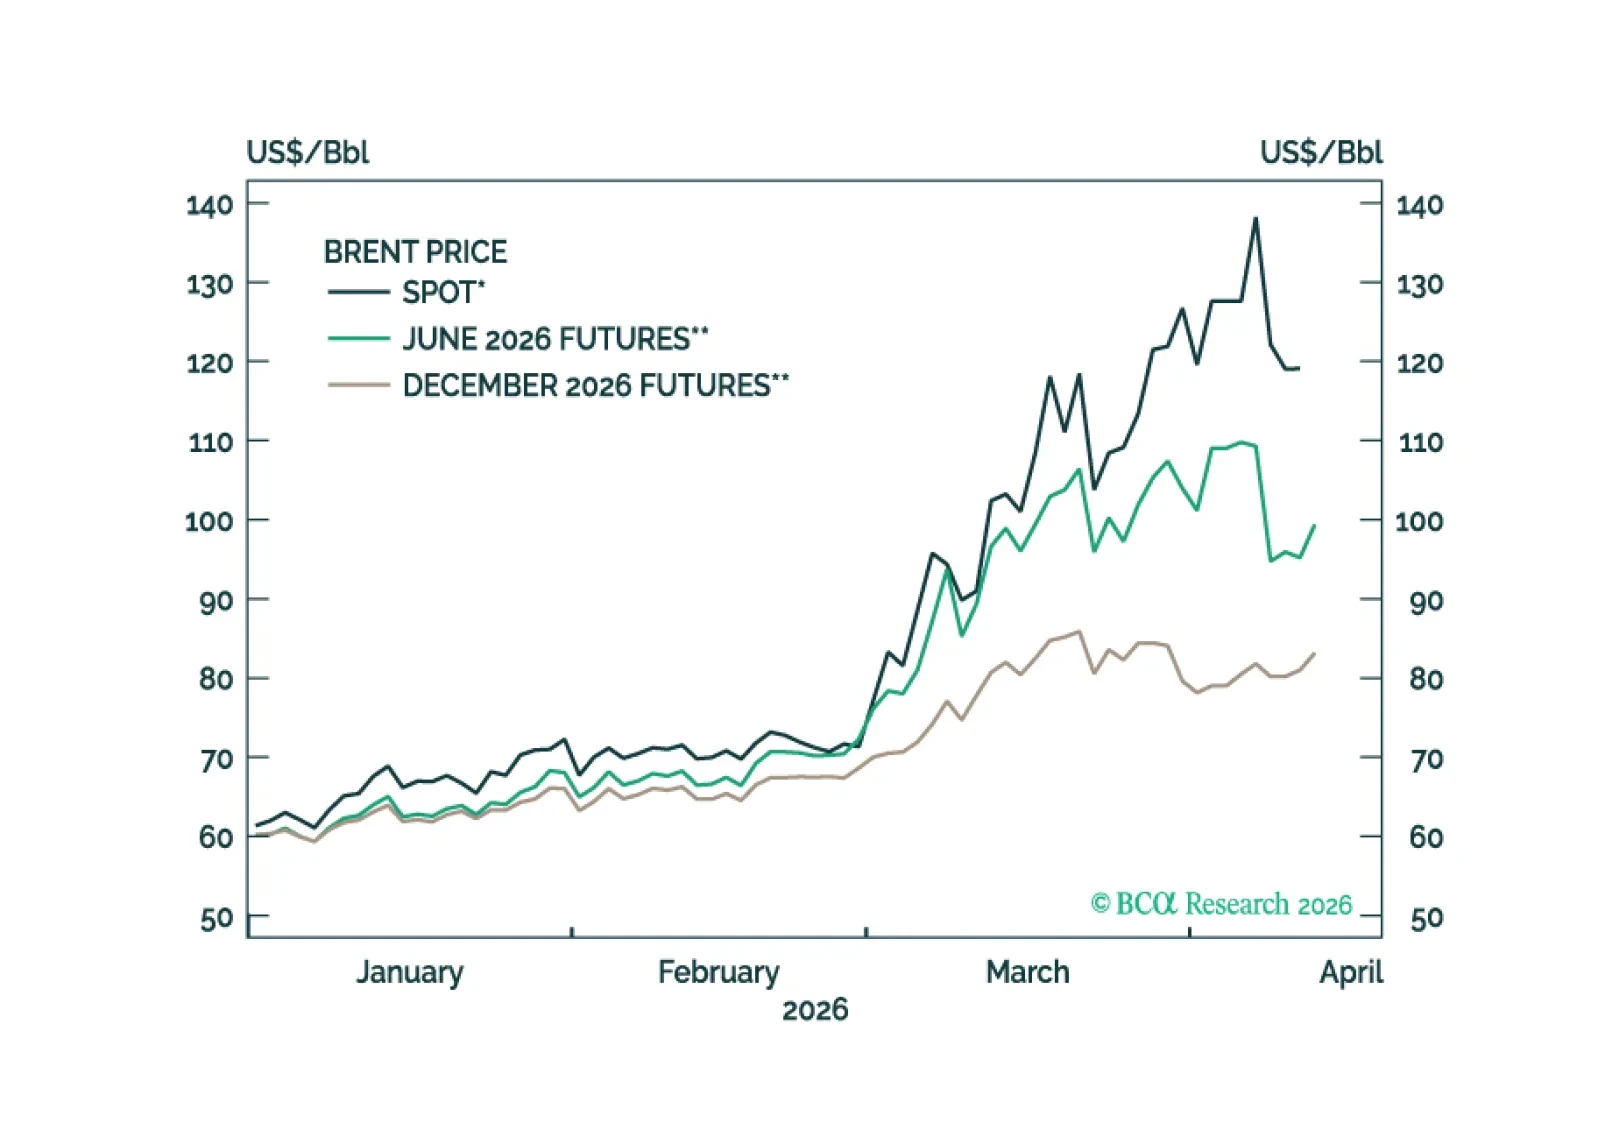
The main reason the oil shock has not caused stocks to crash is that investors do not expect the shock to last very long.
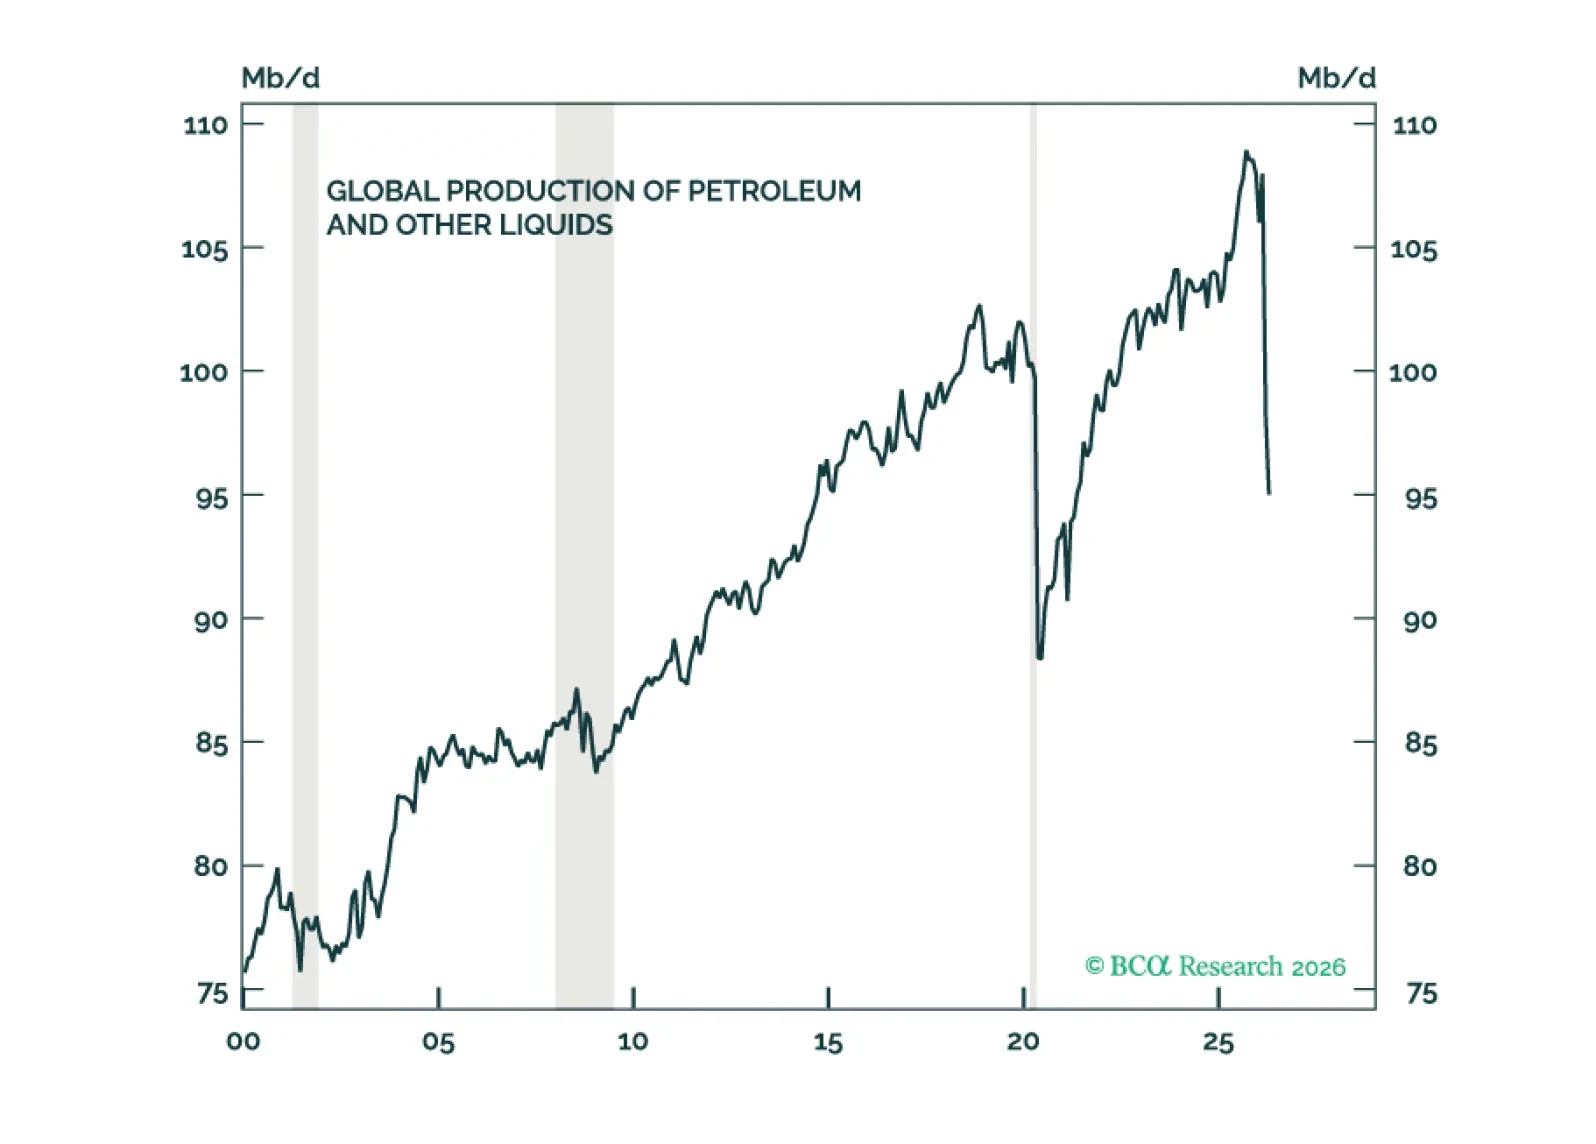
The relief rally in stocks can continue a while longer. However, much can still go wrong. As such, we are retaining a 12-month underweight to stocks but are moving to neutral on a short-term tactical horizon.
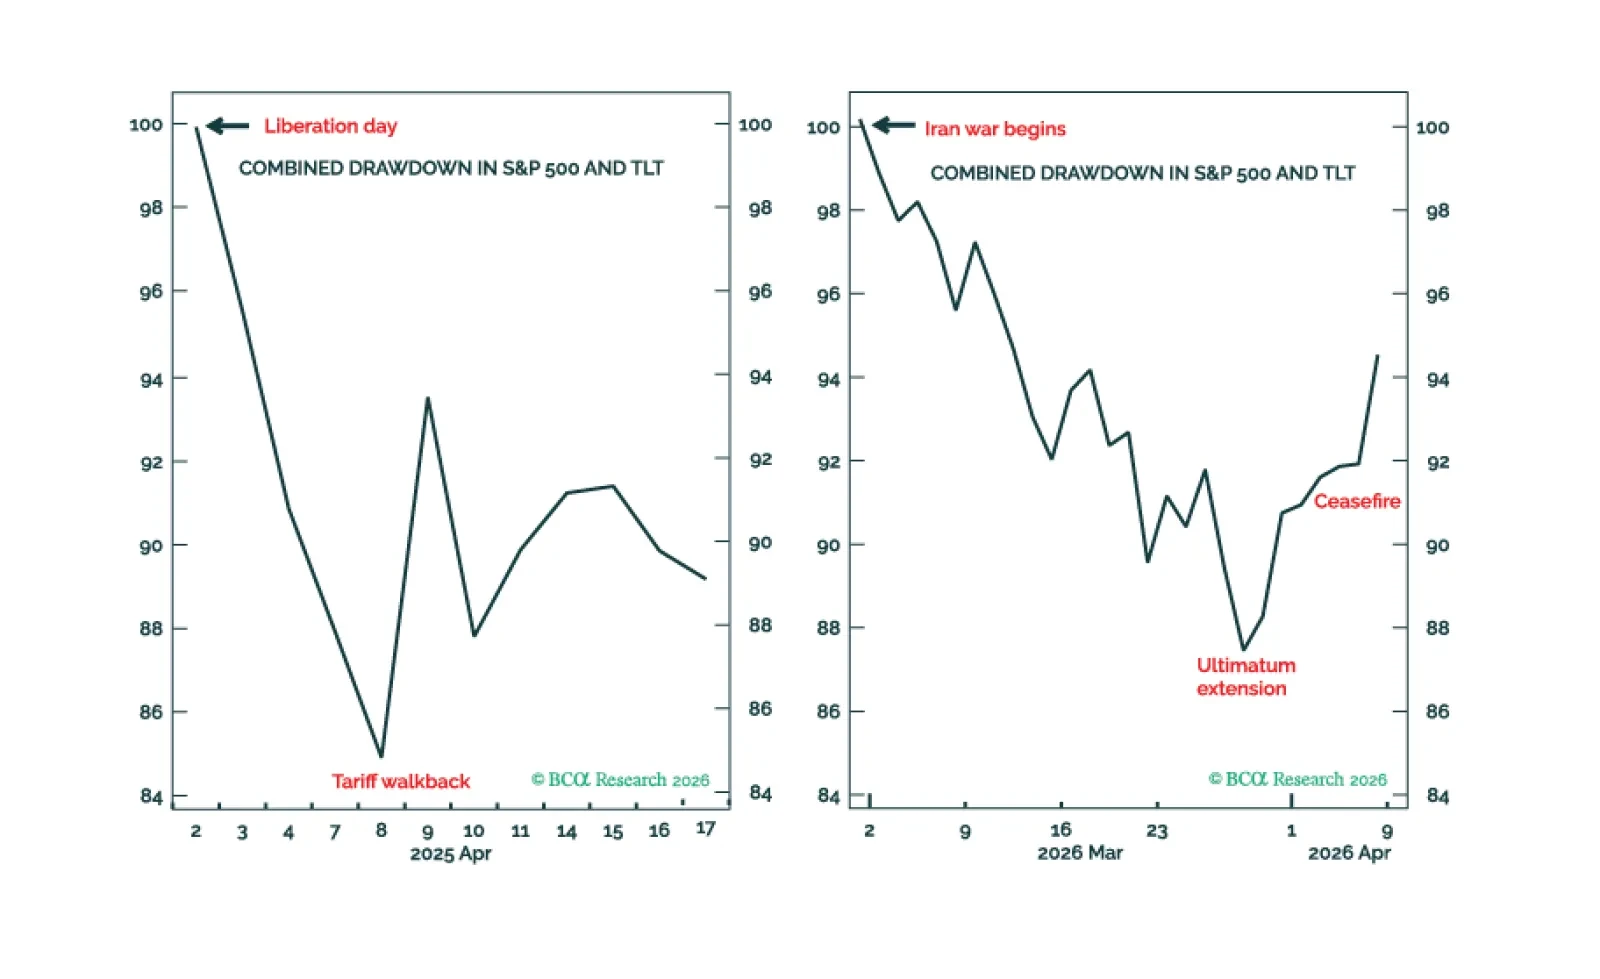
Trump’s breaking point is encapsulated by the combined drawdown in stocks plus bonds reaching 12-15 percent. On this basis, we describe how to ‘trade Trump’. Plus, we highlight three positions that should do well independent of Trump’s actions, including a new trade.
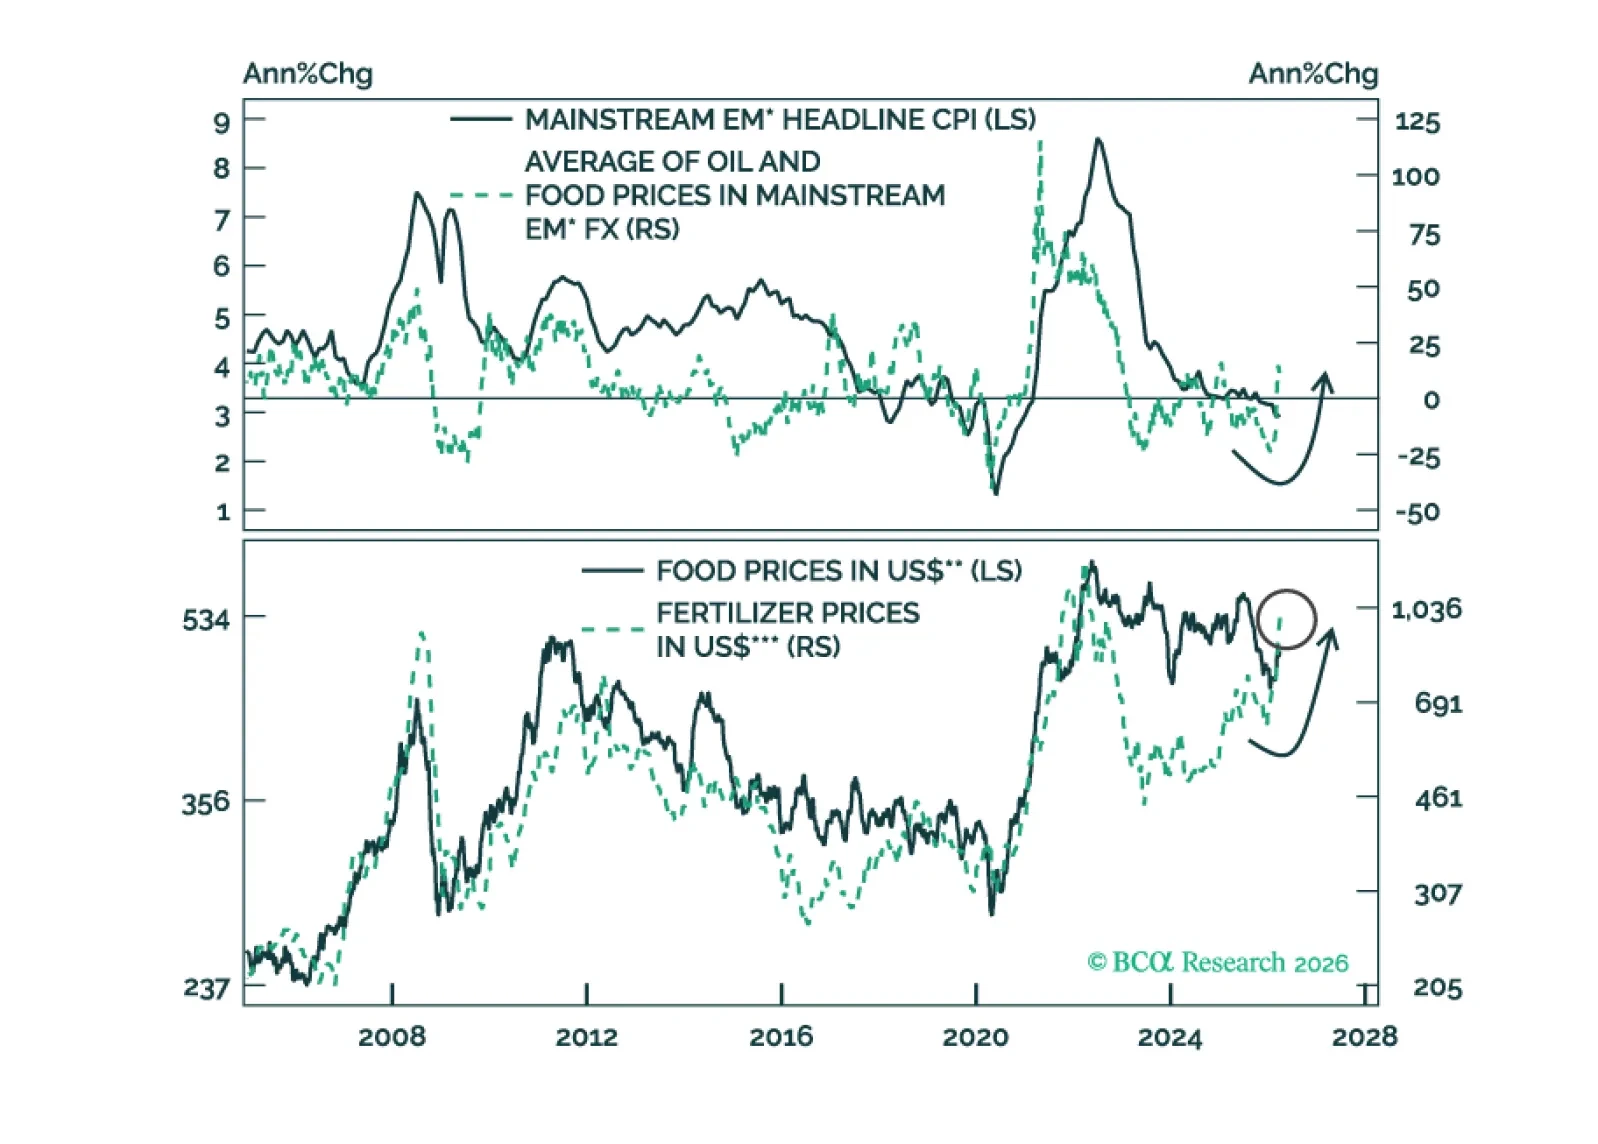
The global risk-off phase will persist. It is too early to buy local-currency bonds in Mainstream EM, but it is not too late to sell EM sovereign and corporate credit (USD bonds).
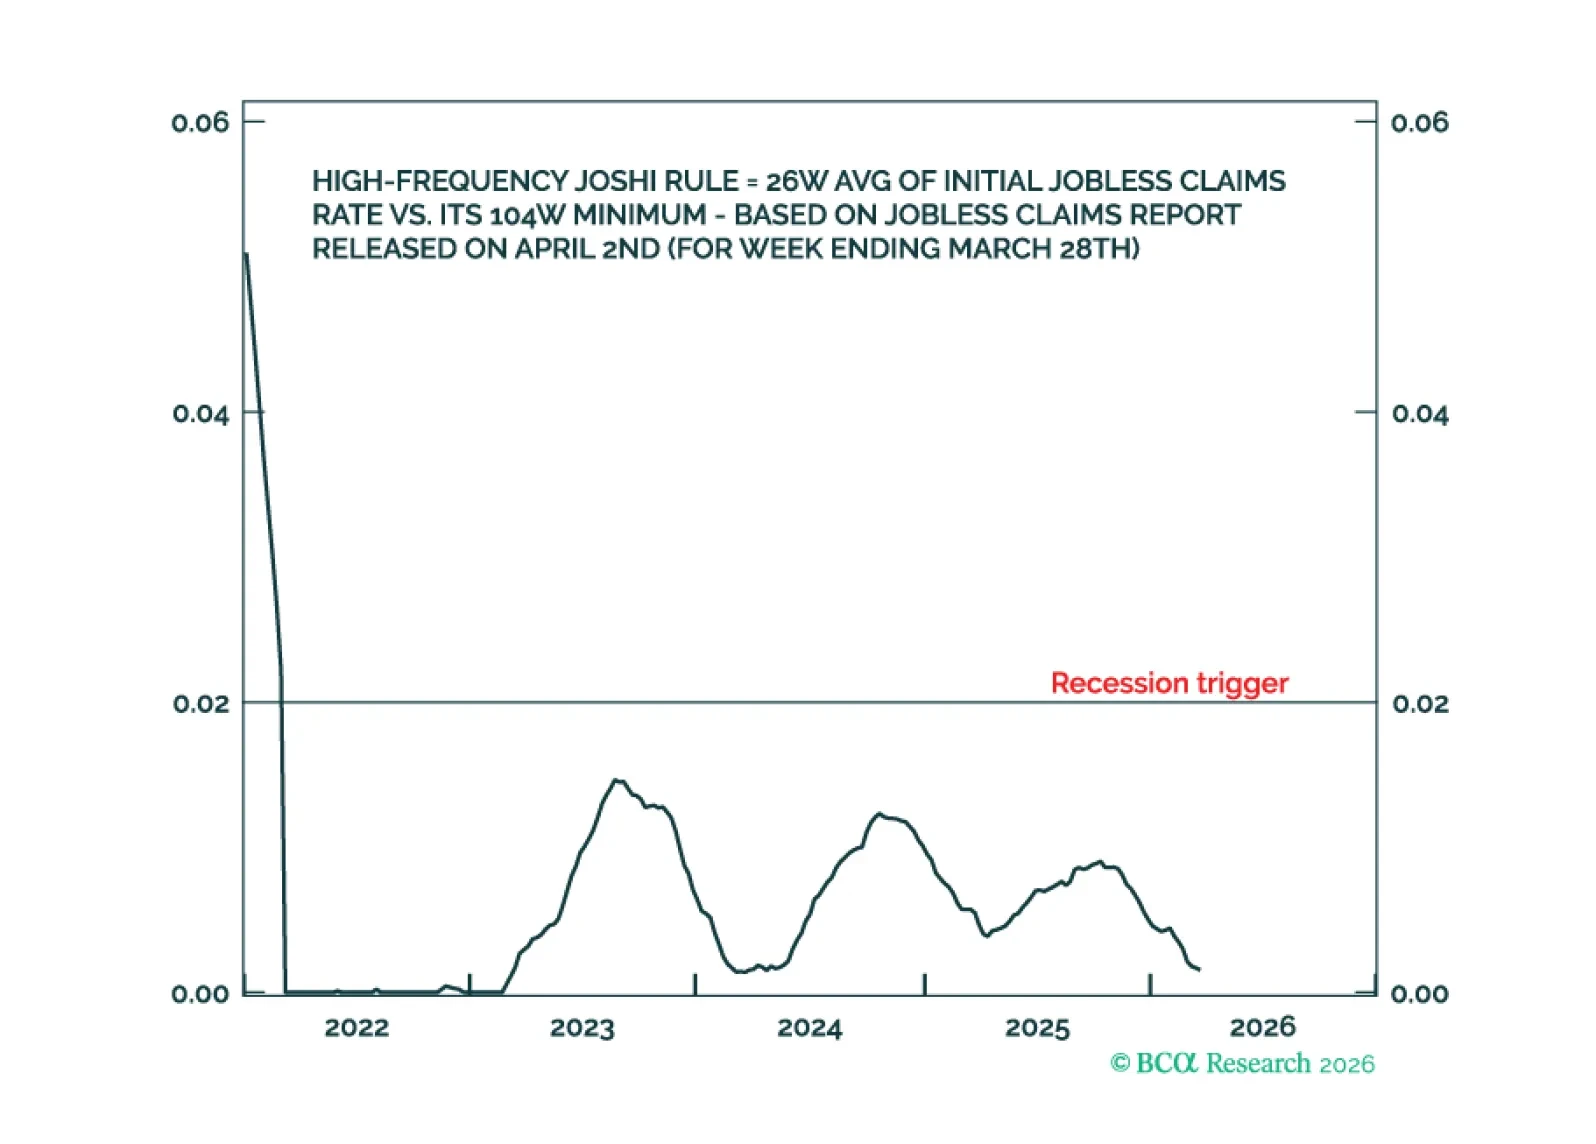
While the Middle East conflict’s inflationary impact is likely to persist, US recession risk is contained whereas non-US recession risk is more elevated. We discuss what this means for investment strategy. Plus, a new tactical trade is to underweight Utilities.
We are pleased to introduce our new Quarterly Investment Outlook, a joint publication bringing together the European Investment Strategy (EIS), Global Fixed Income Strategy (GFIS), and Foreign Exchange Strategy teams. The main takeaway of the current edition is that investors should not add risk. Markets are still focused on inflation, but the binding constraint is growth: if the energy shock persists into mid-April, a rapid shift toward recession pricing will follow.