 Explore CoreMacro
CoreMacro | Emerging Markets
Emerging Markets research - including in-depth country reports. Typically published four times a month.

President Javier Milei’s electoral win has massively outperformed expectations. Meaningful legislative support and renewed market confidence will revitalize his liberalizing economic program. Our recommendation not to sell Argentine assets following the post-Buenos Aires election carnage has been validated.
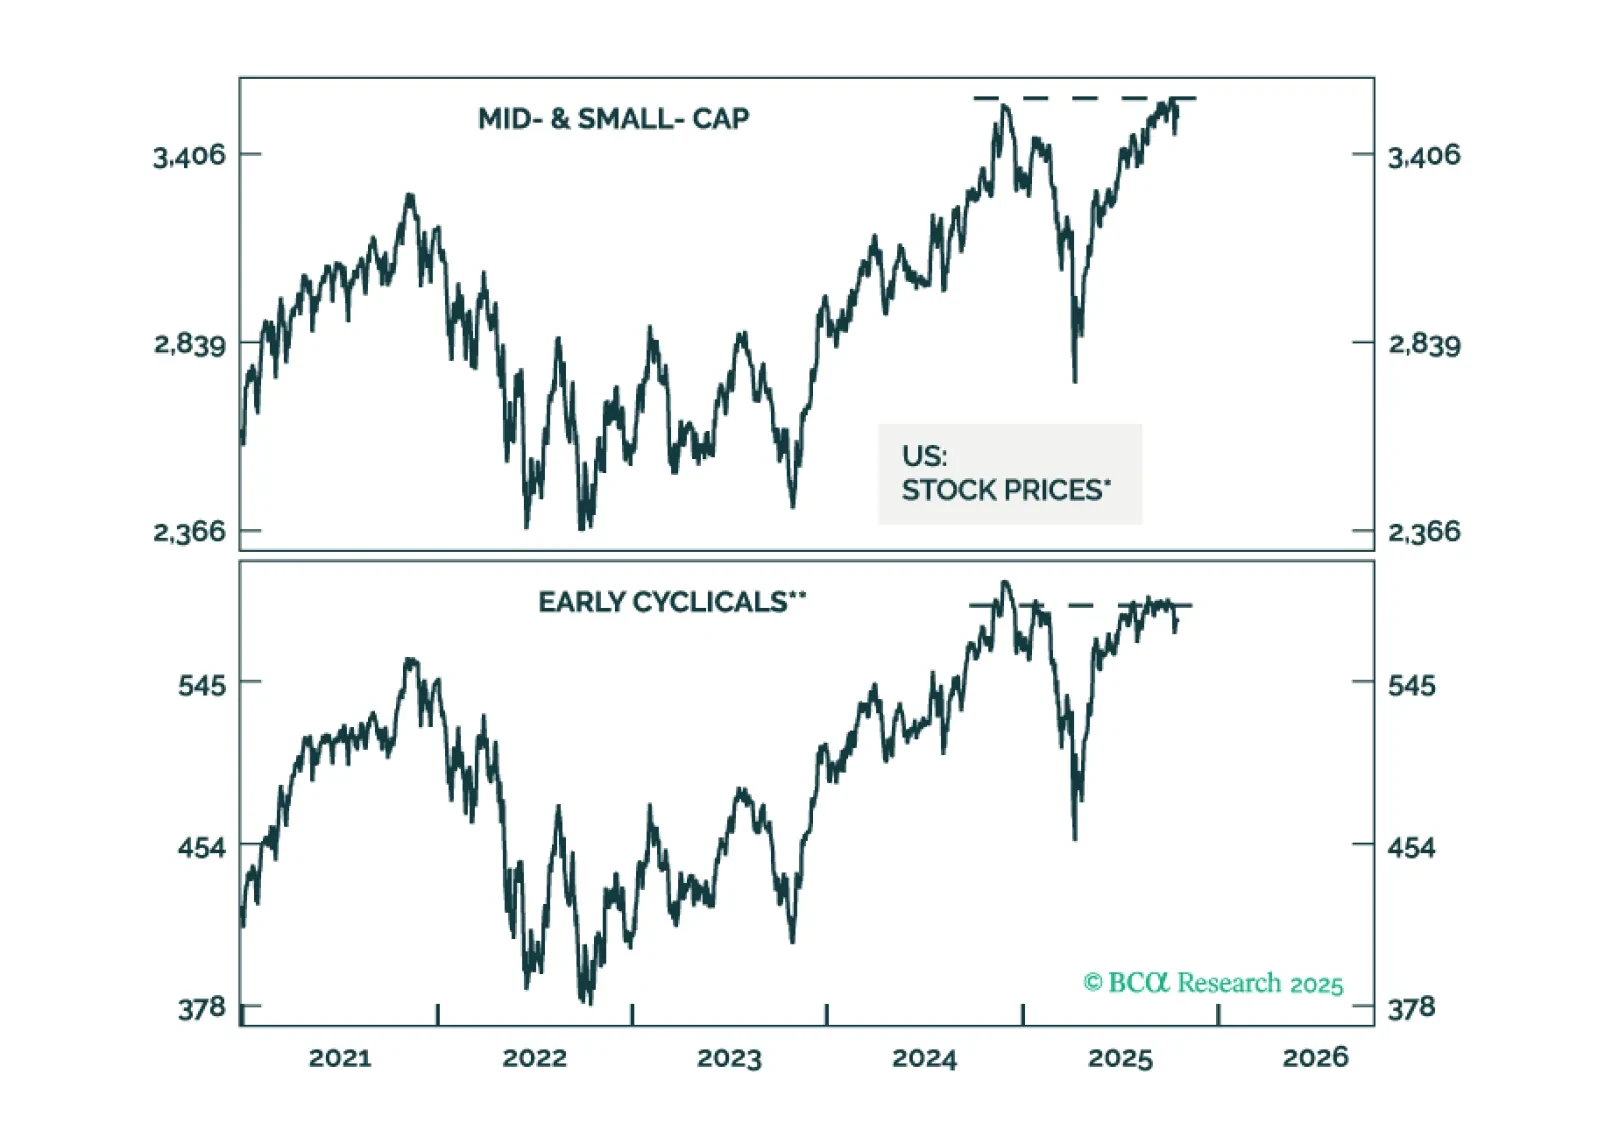
In global markets, speculative forces have intertwined with the sound fundamentals of specific equity segments, perplexing investors. This report aims to distinguish between excessive price run-ups and healthy fundamentals.
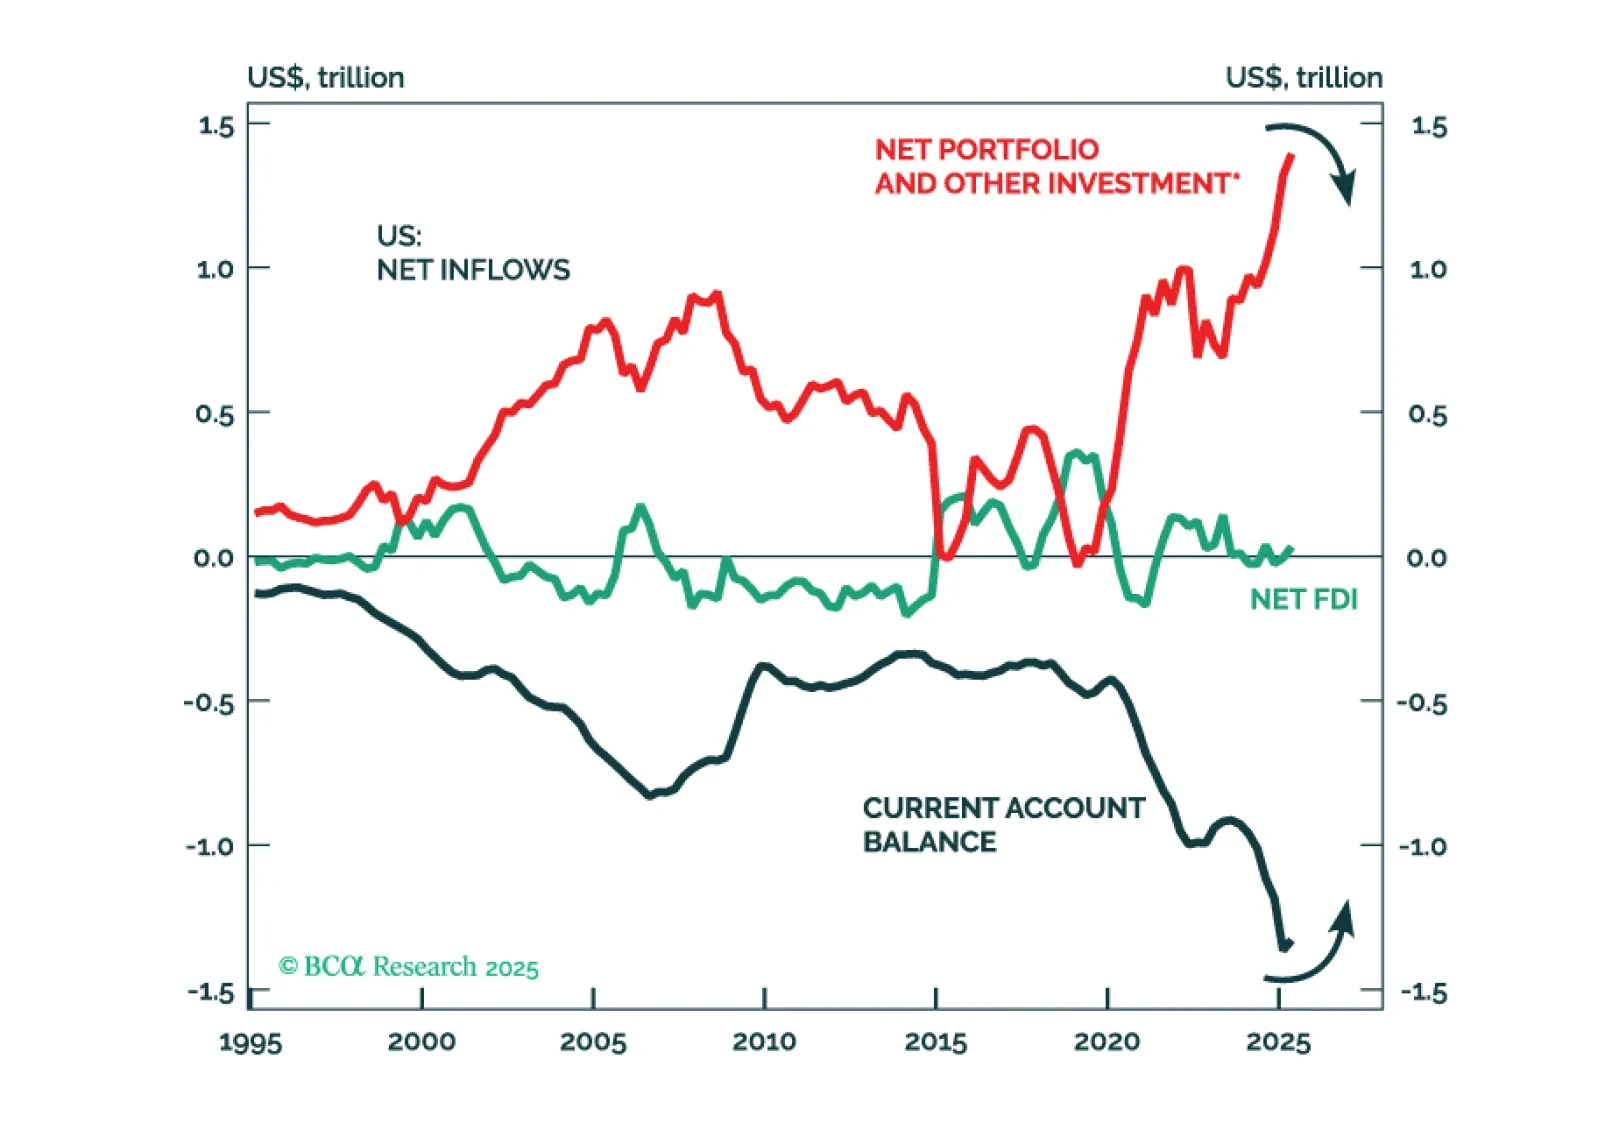
The belief that net portfolio outflows out of the US will fuel EM assets is a common but misguided narrative. If the US starts experiencing net capital outflows, it would need to run a current account surplus. A shift in the US current account from deficit to surplus would be devastating for the global economy in general and EM in particular.
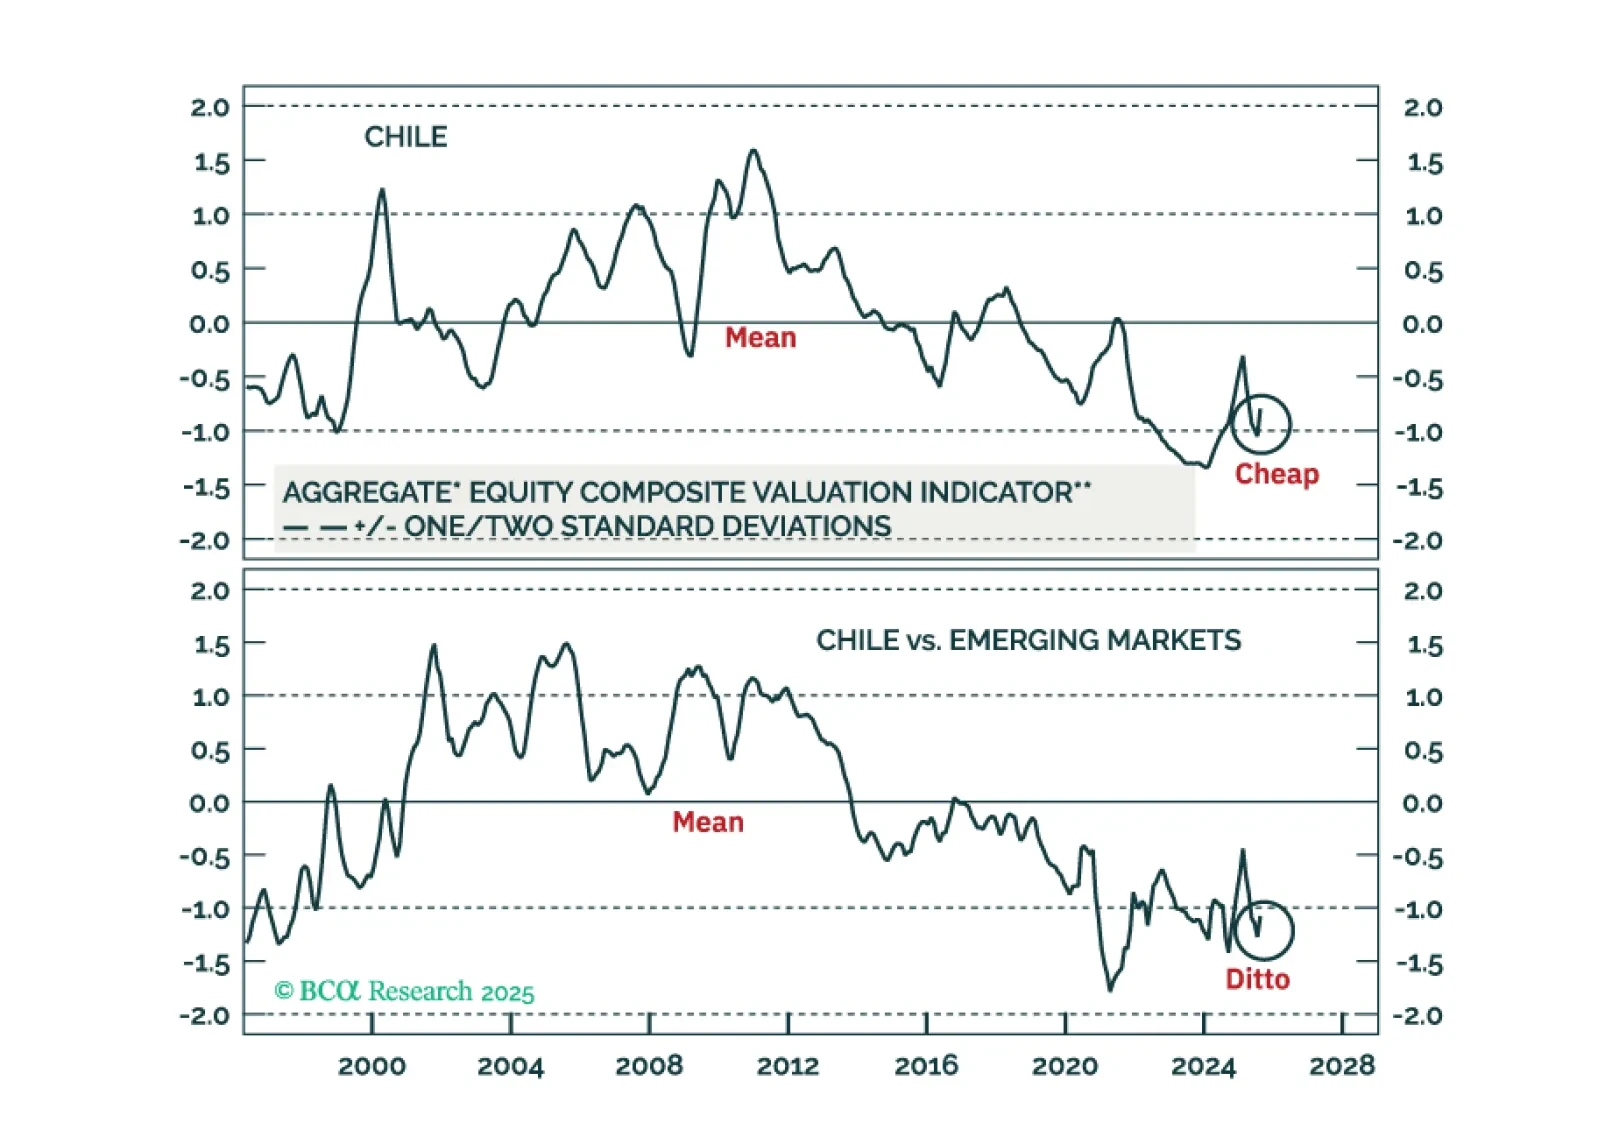
Chilean equities are undergoing a structural re-rating. A political swing back to a pro-business administration, a benign macro backdrop, and a resilient exchange rate will drive Chilean markets’ outperformance versus EM peers.

Indonesia’s policy easing will boost domestic demand, but fuel inflation. Current account deficit will widen, and the rupiah will weaken. Stay short the rupiah and go underweight Indonesian stocks, domestic bonds, and sovereign credit in their respective EM portfolios.
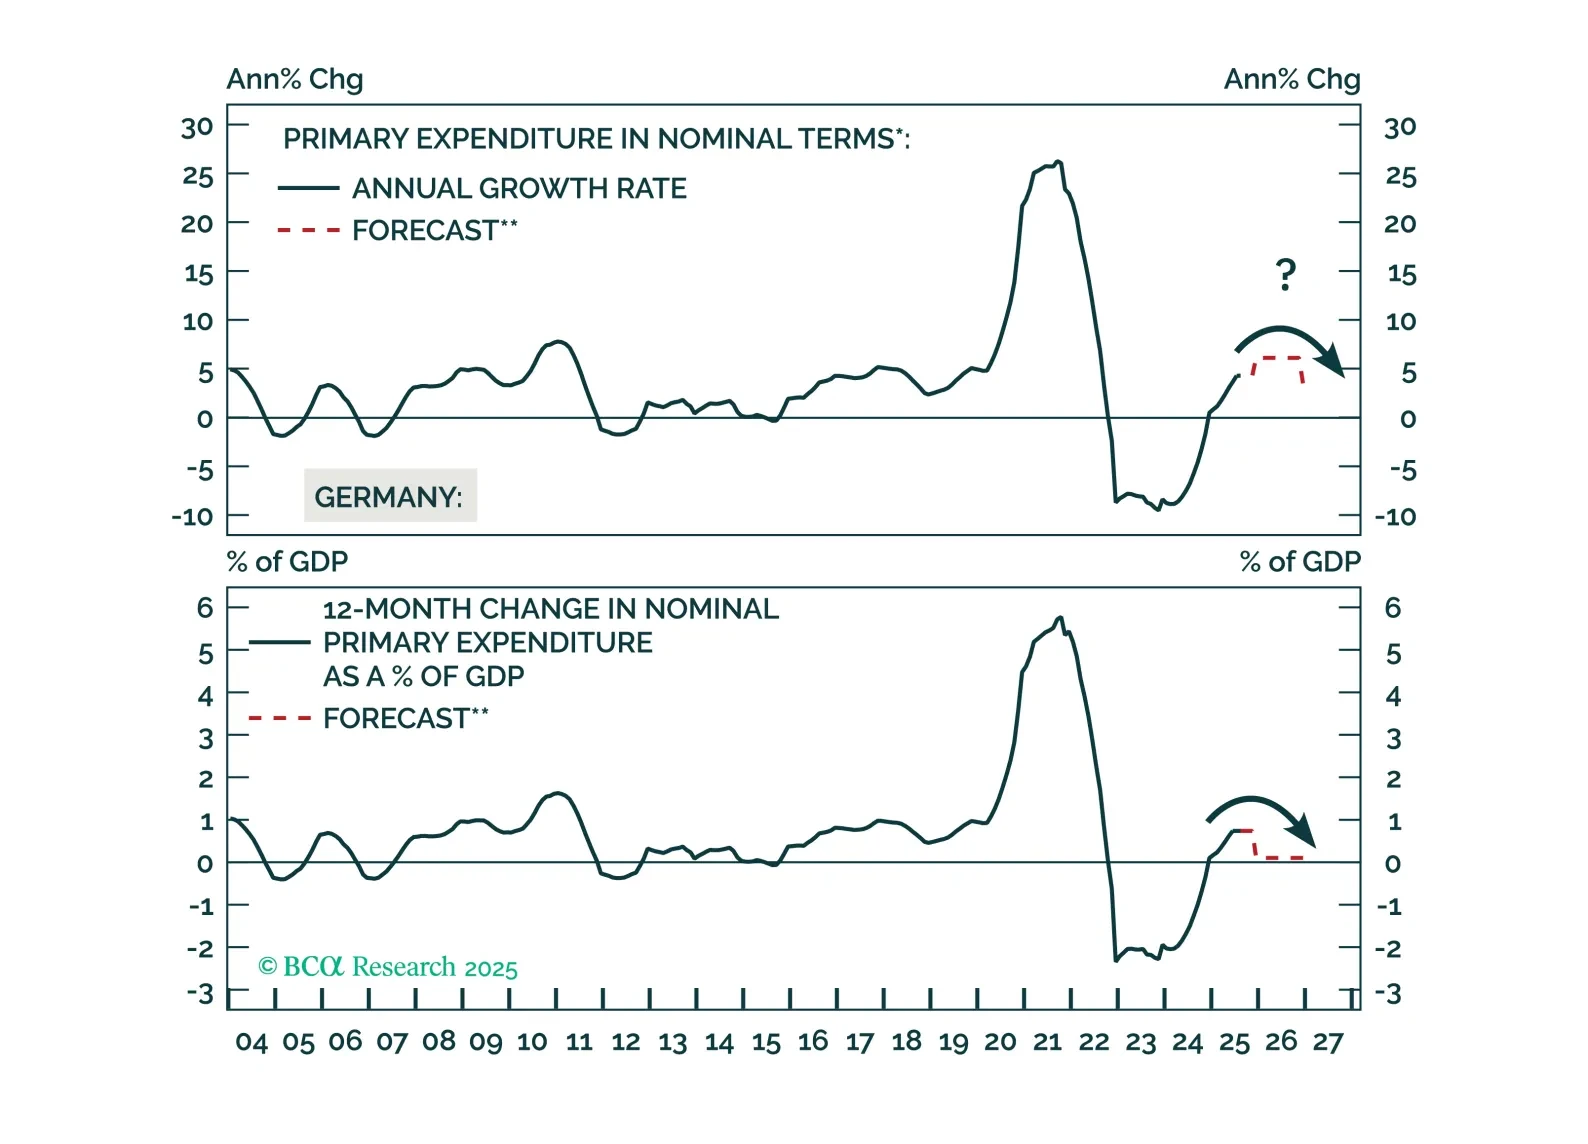
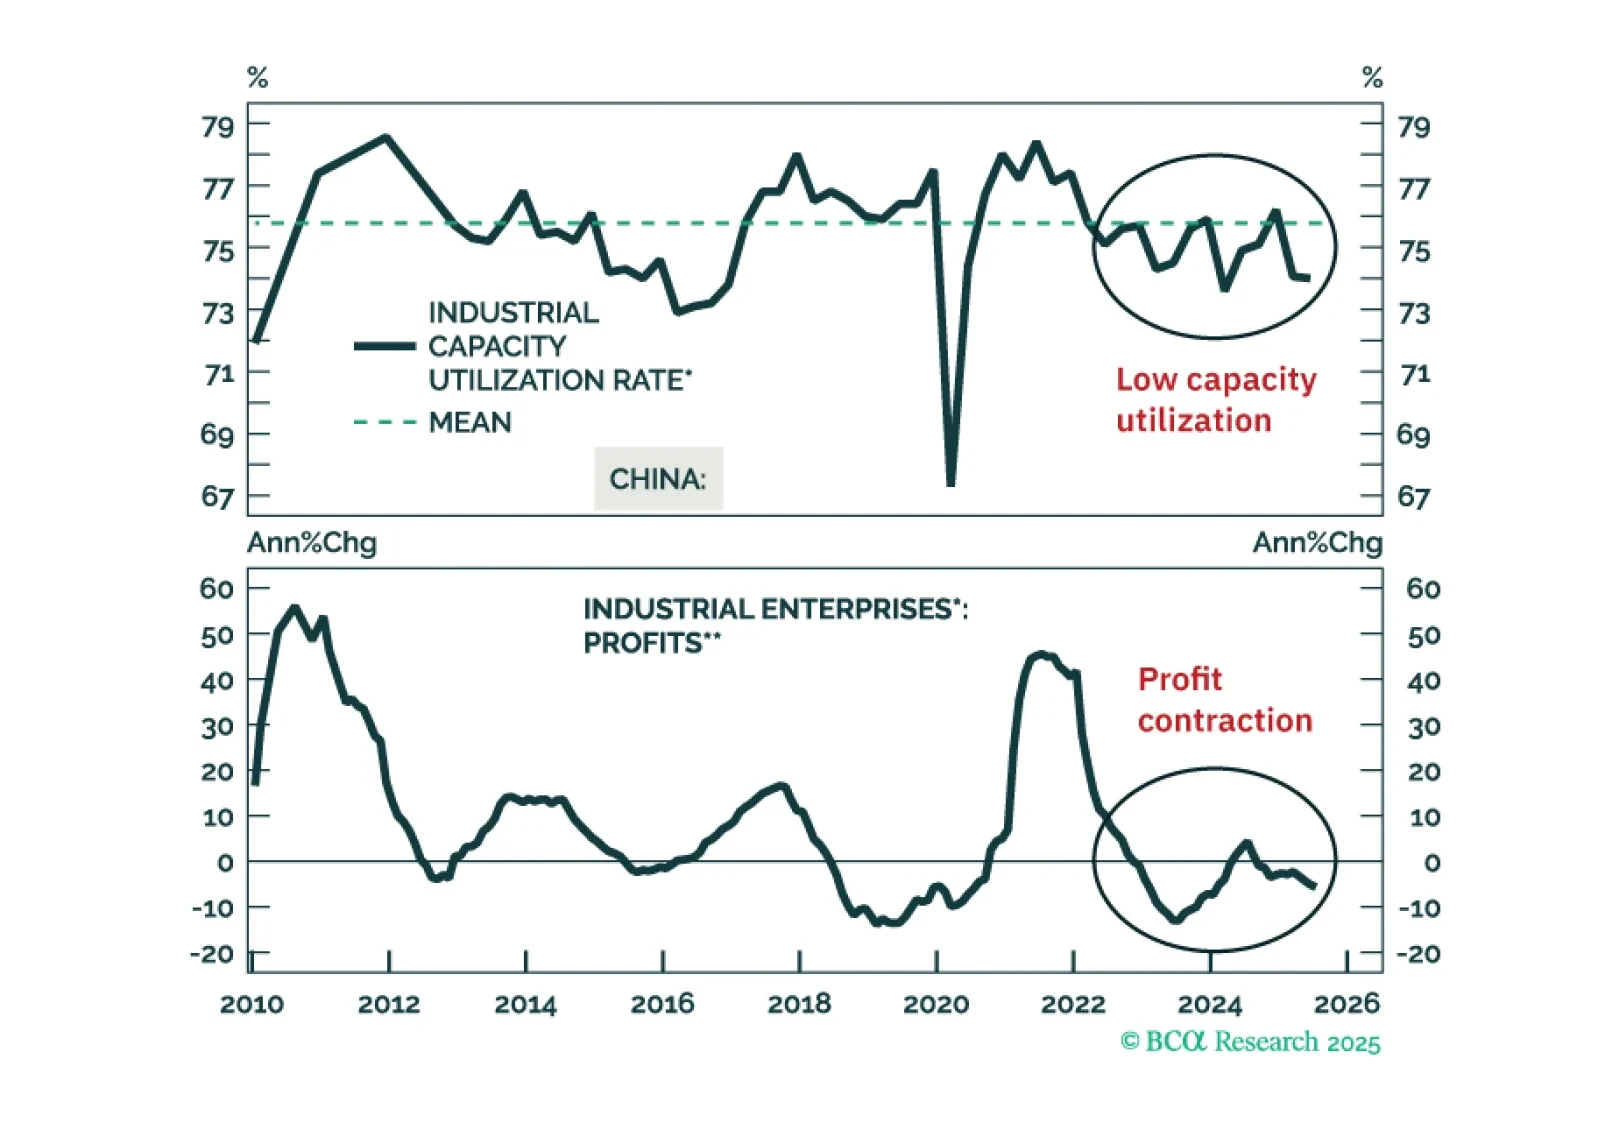
Core Europe’s industrial sector will relapse in the coming months due to US tariffs and a strong euro. Investors can play the imminent deflationary shock by being long Central European bonds. They should, however, hedge the currency risk vis-à-vis the euro.