Earnings
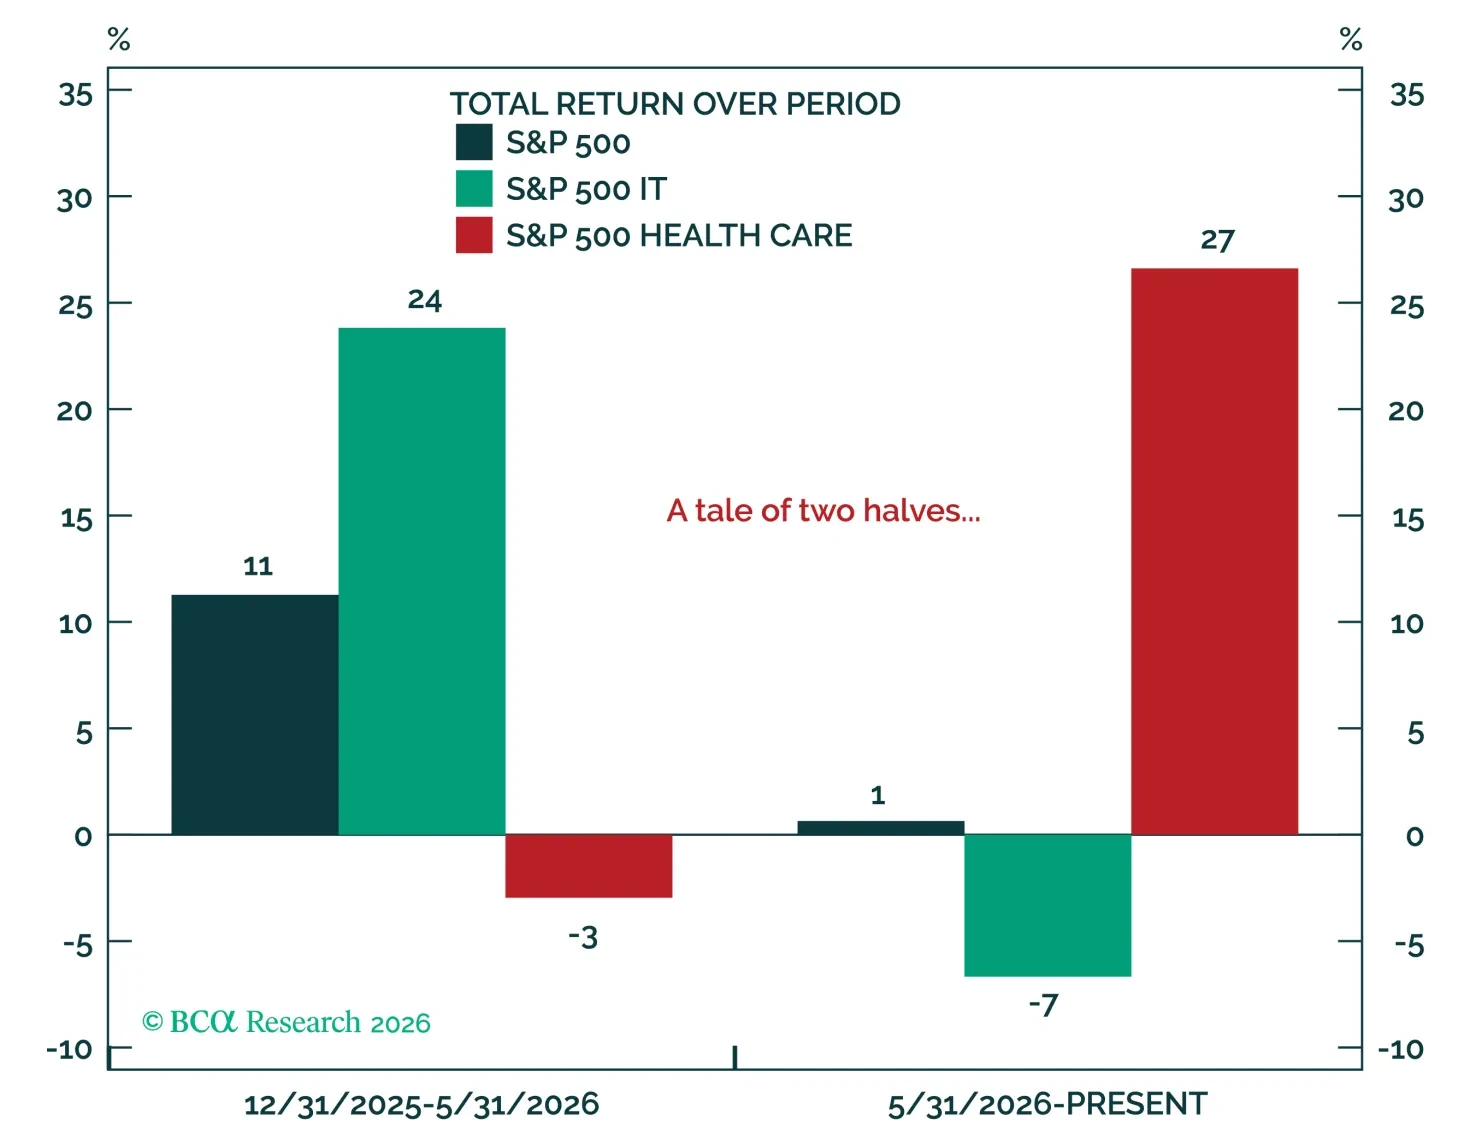
Health Care’s second-half 2026 rally has largely been a defensive rotation, not the start of a new bull market. Health Care leadership is more typical when the economy is slowing/contracting and is hard to sustain in a rising market. With the cycle still firm and our expectation that the market rallies into year end, we are neutral on the sector, though we recognize its hedging value. Within Health Care, we are underweight Providers & Services, overweight Equipment & Supplies, and market weight Pharmaceuticals, Biotech & Life Sciences (“Pharma”).
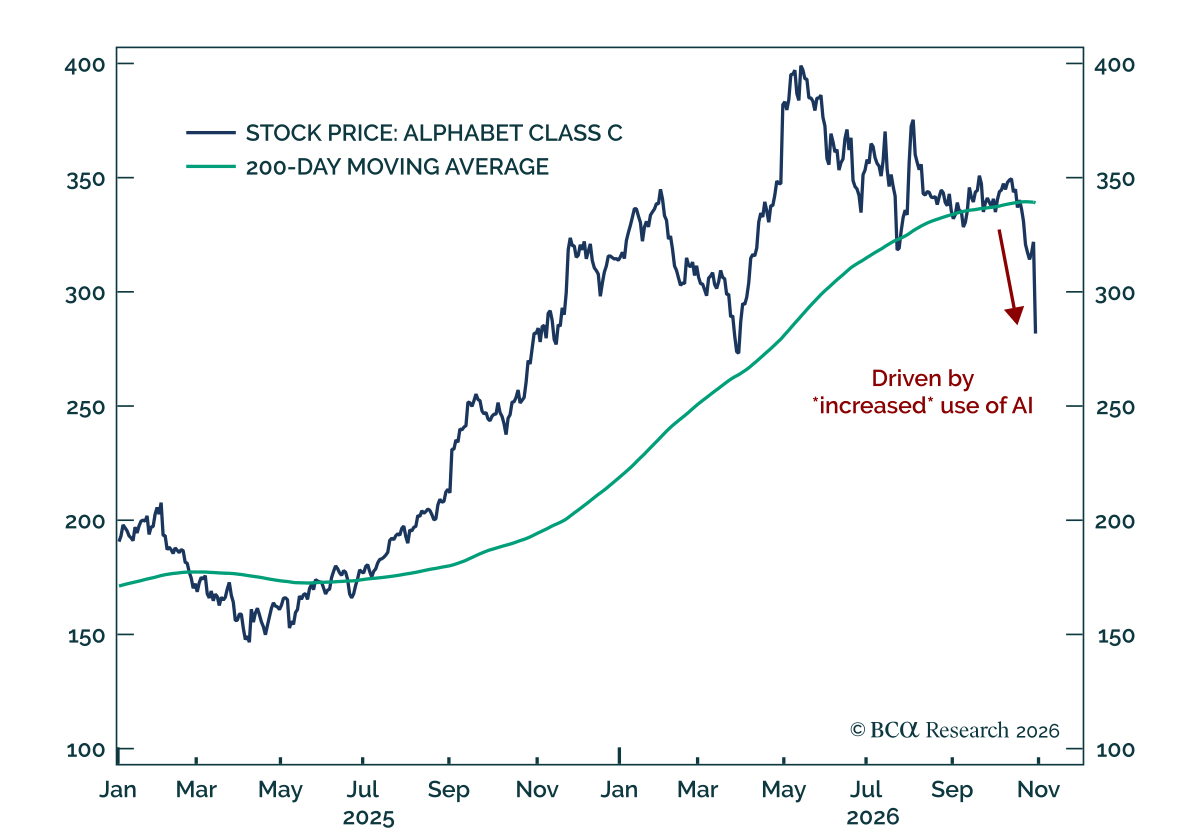
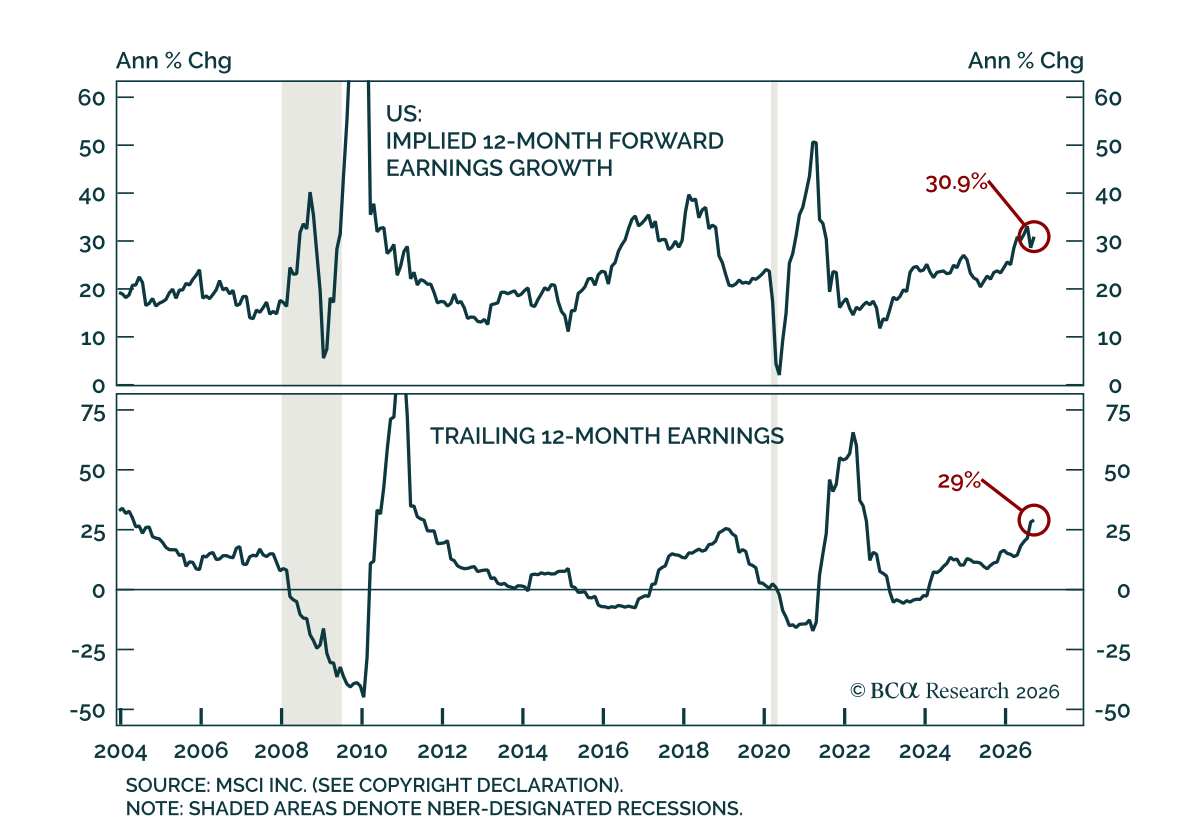
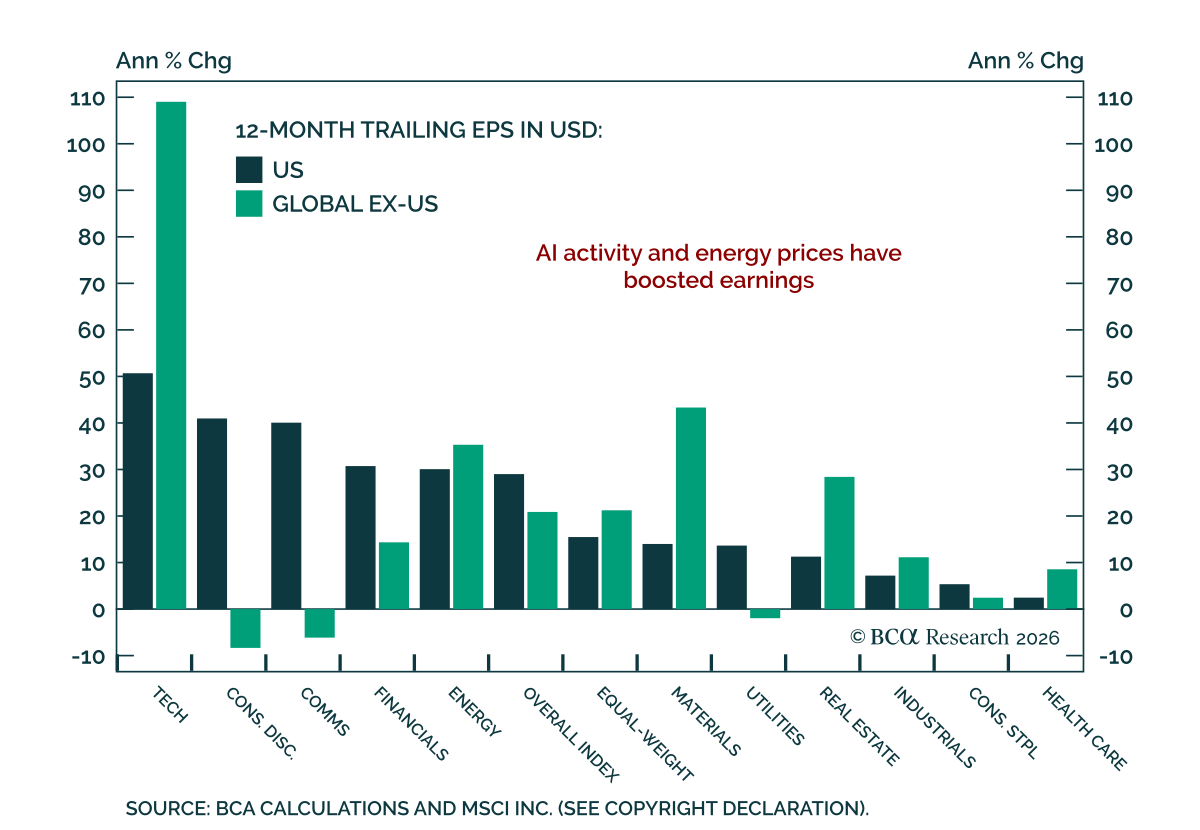
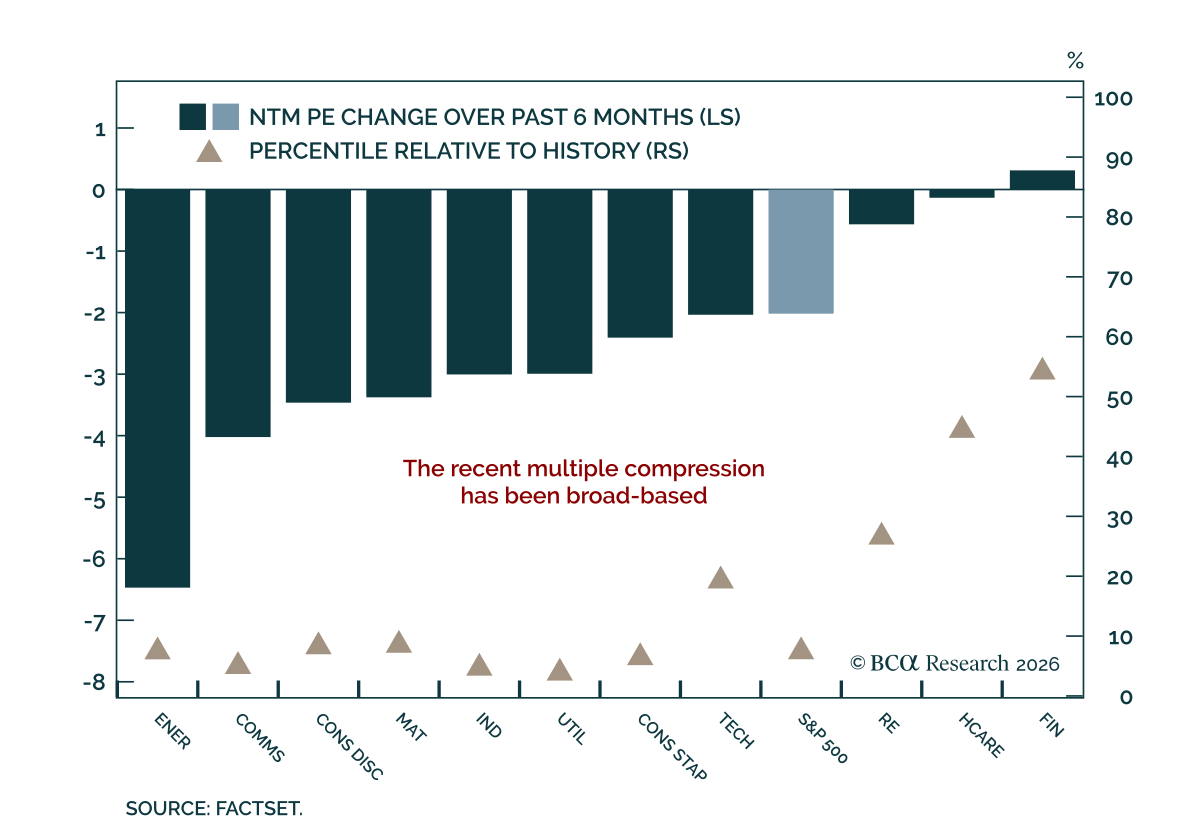
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
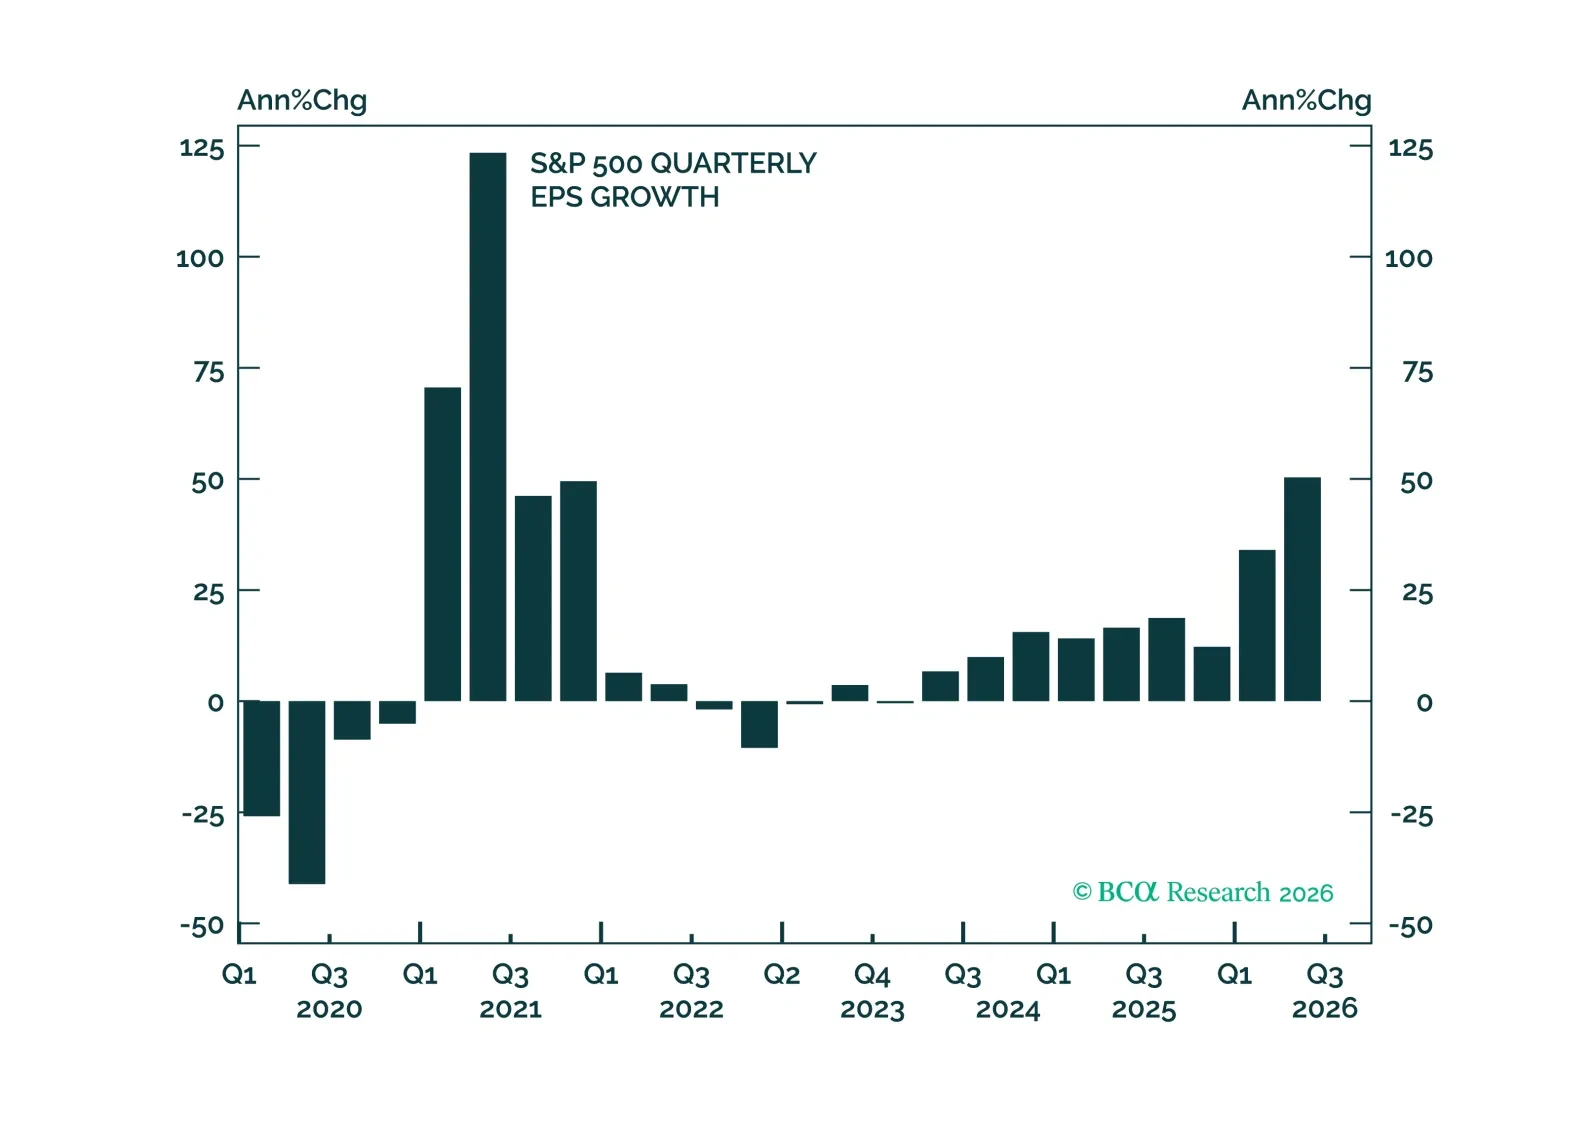
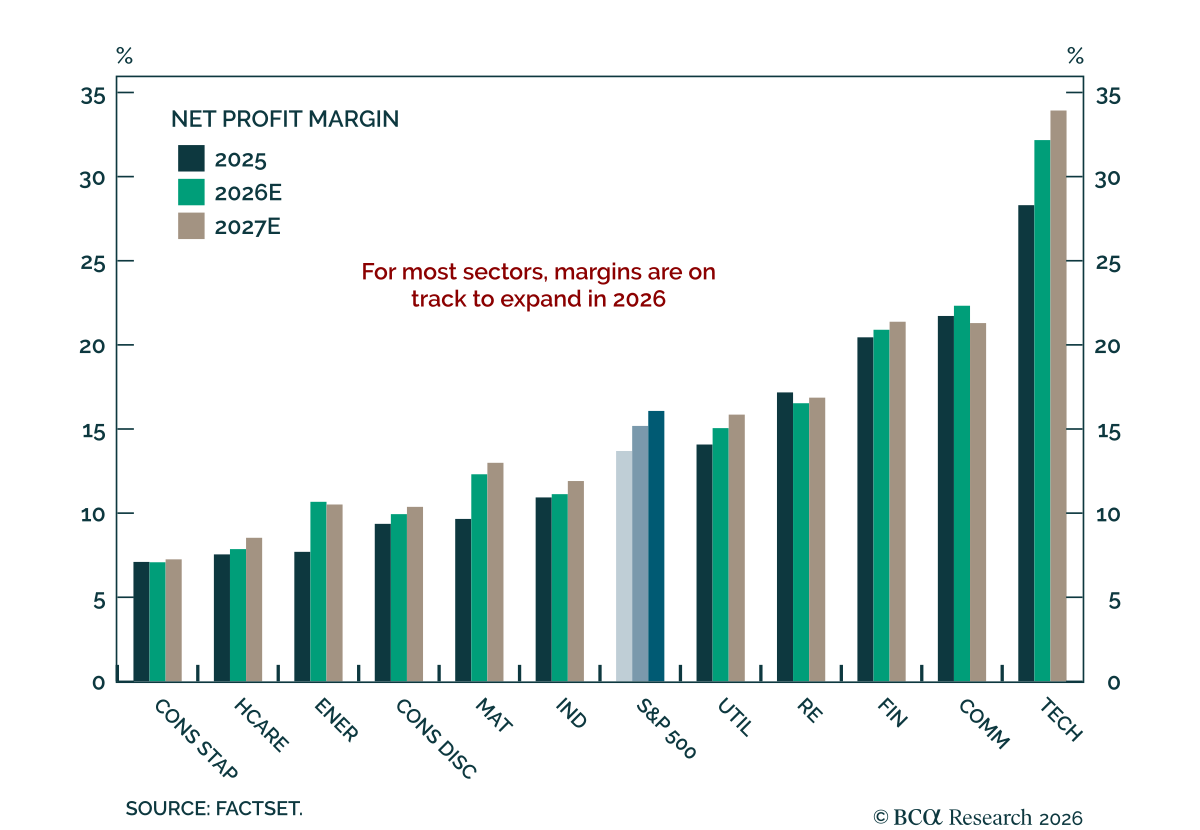
Q2 earnings confirm broad-based strength, but the bond market remains the key risk to equity multiples given today's positive stock/bond correlation regime. We close our tactical GDX long for a 16% gain, though we continue to view goldminers as a valuable structural hedge.
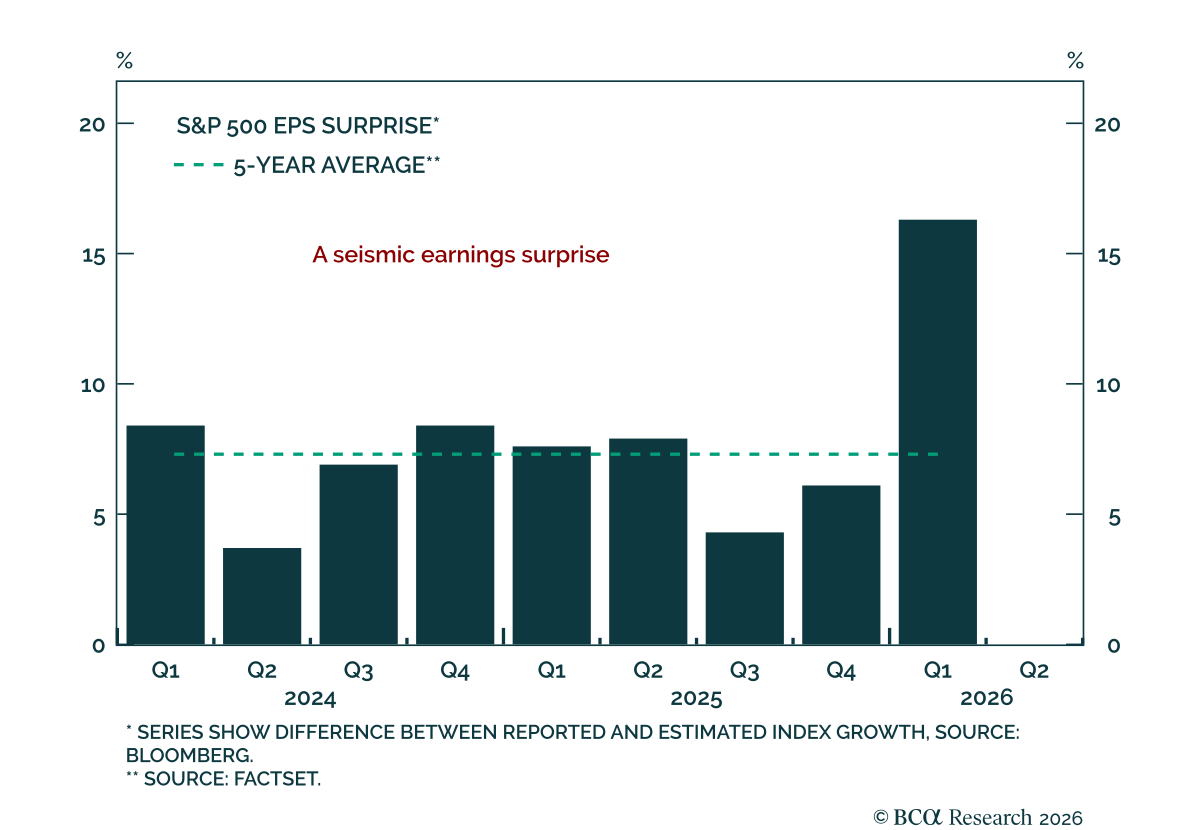
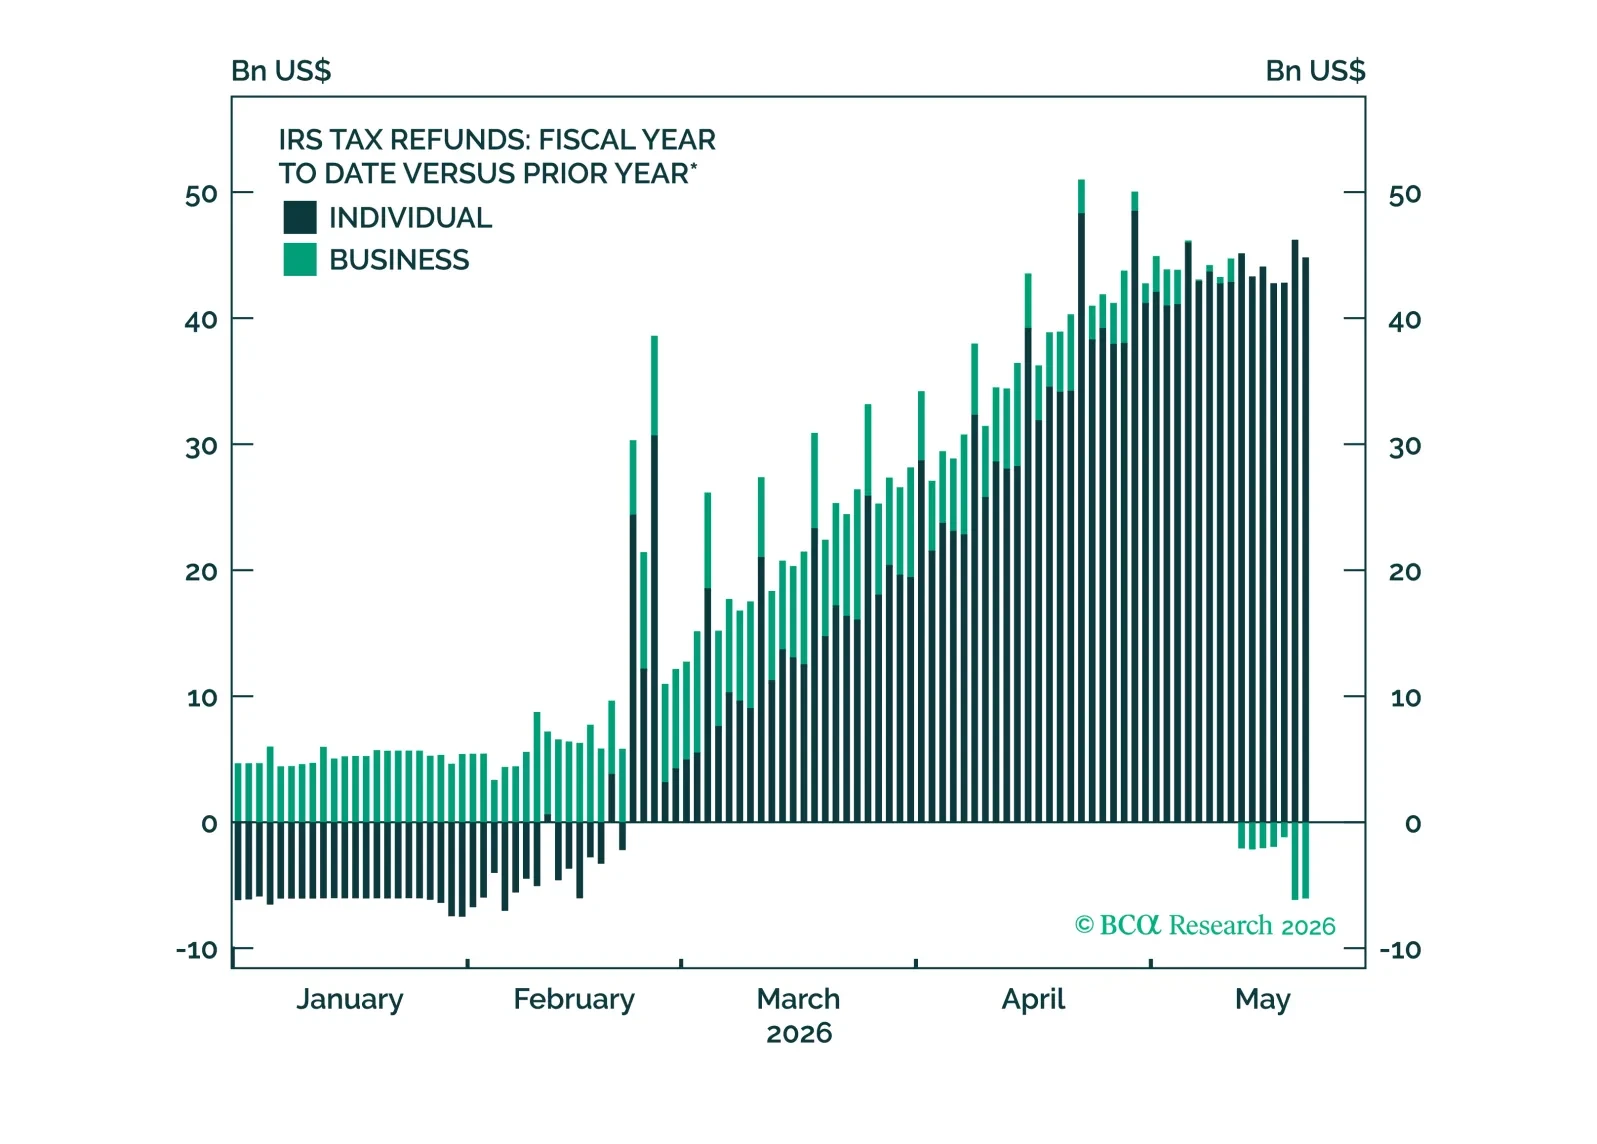
Against the earnings-versus-everything-else market backdrop, stellar earnings are easily outweighing elevated oil prices, rising yields and the increased probability that the Fed may hike rates before the year is out. US allocators should remain invested in equities.