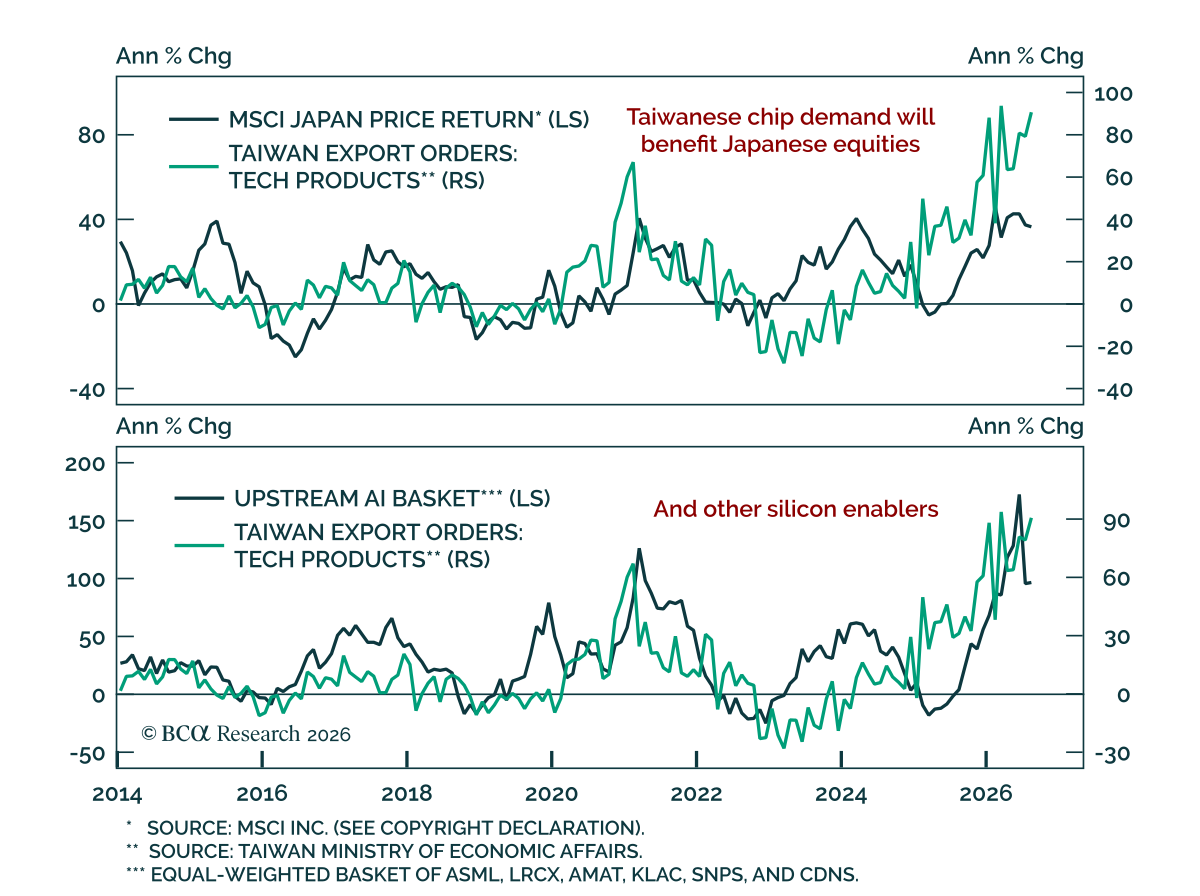
AI
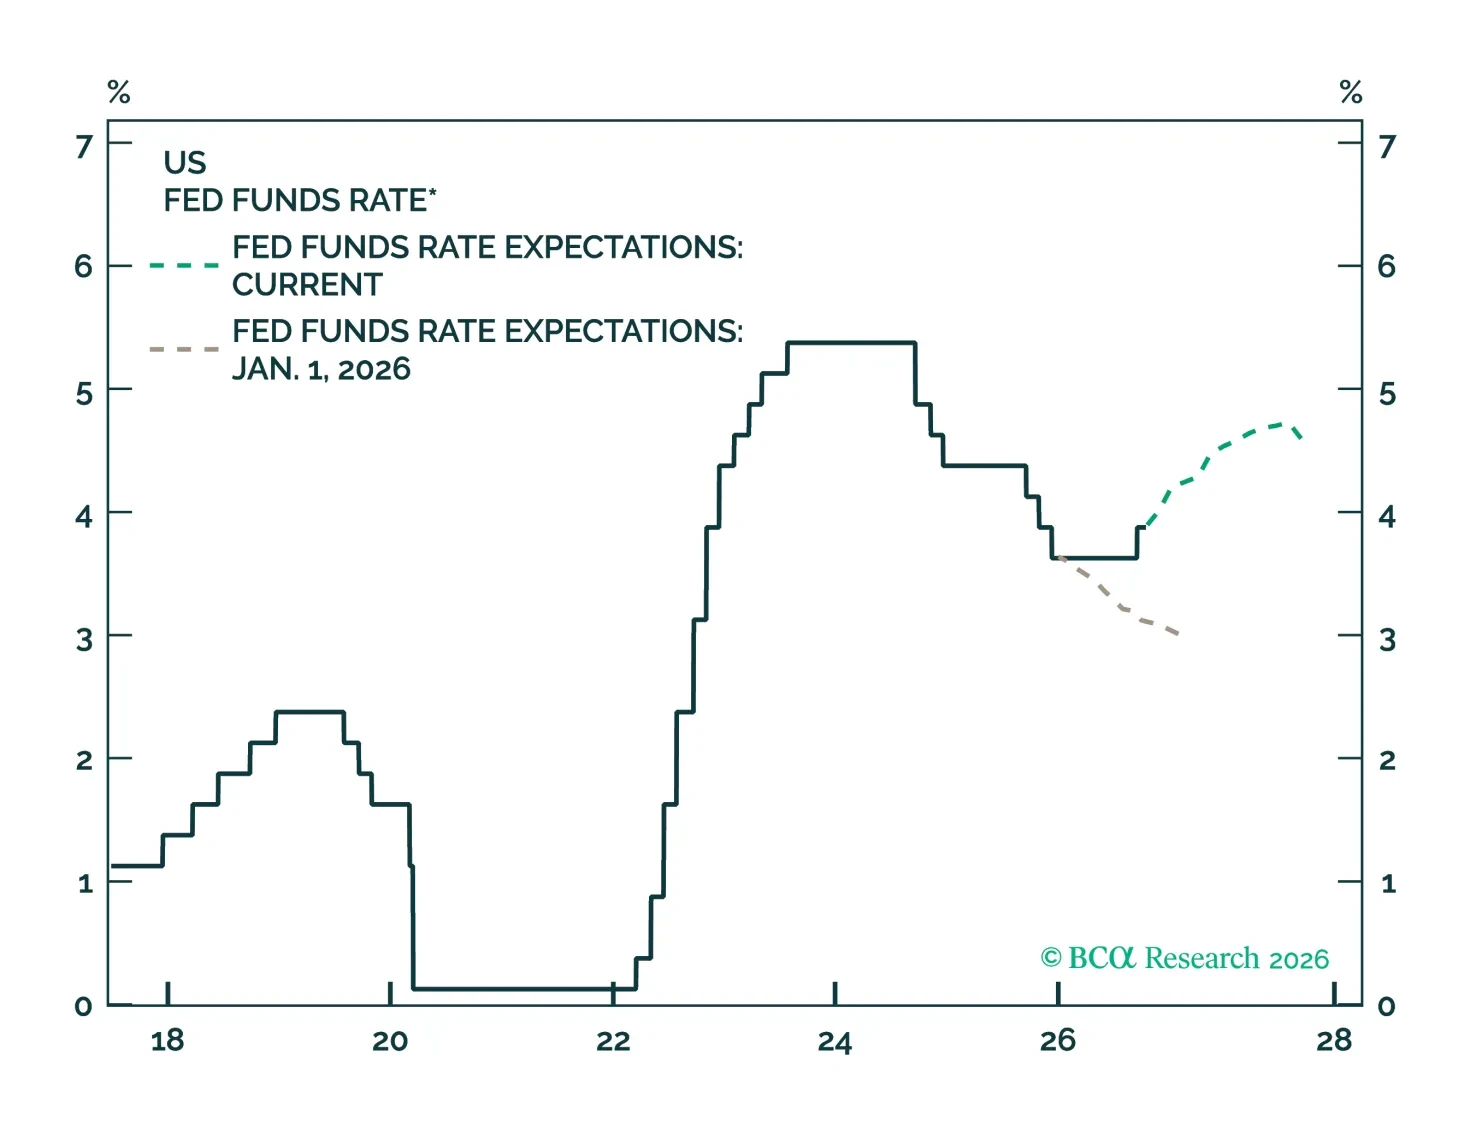
AI capex is supporting the global economy but also generating collateral damage for rate-sensitive sectors such as housing, as well as highly indebted governments. Maintain a benchmark allocation to equities for now and look to get more defensive next year.
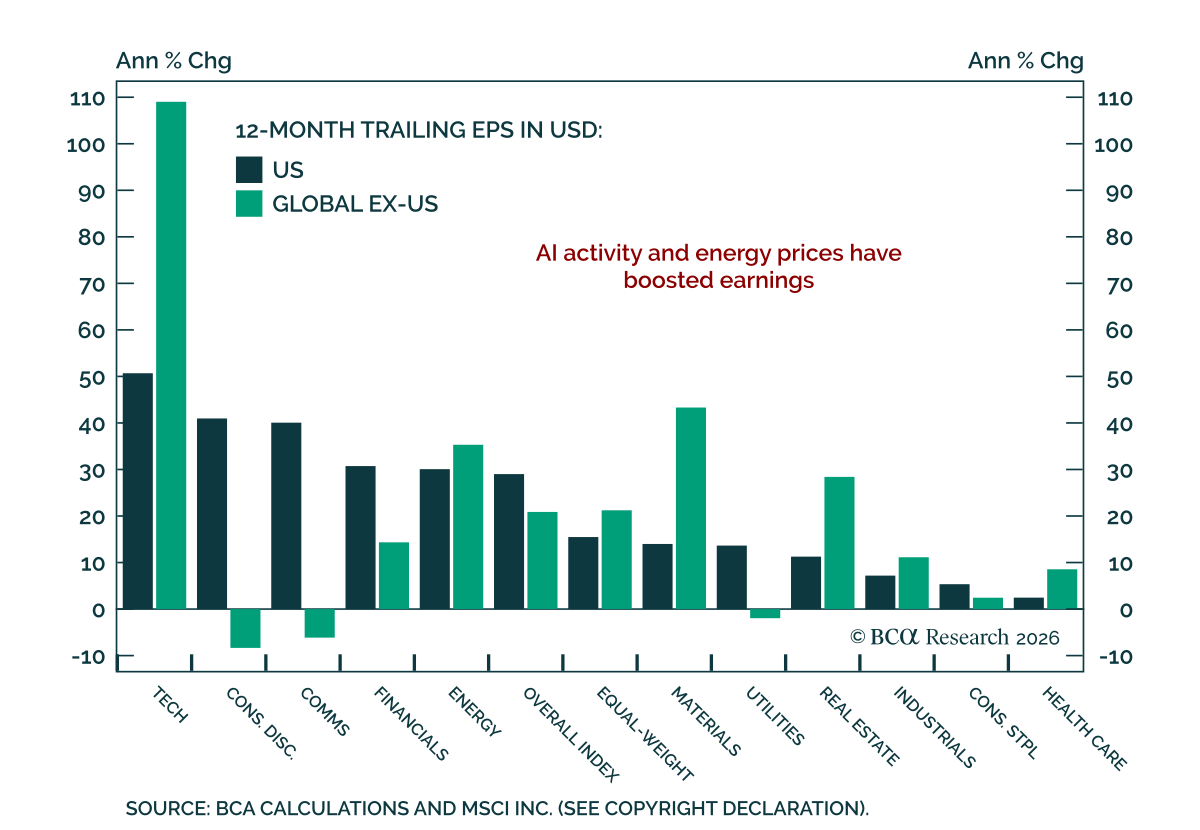
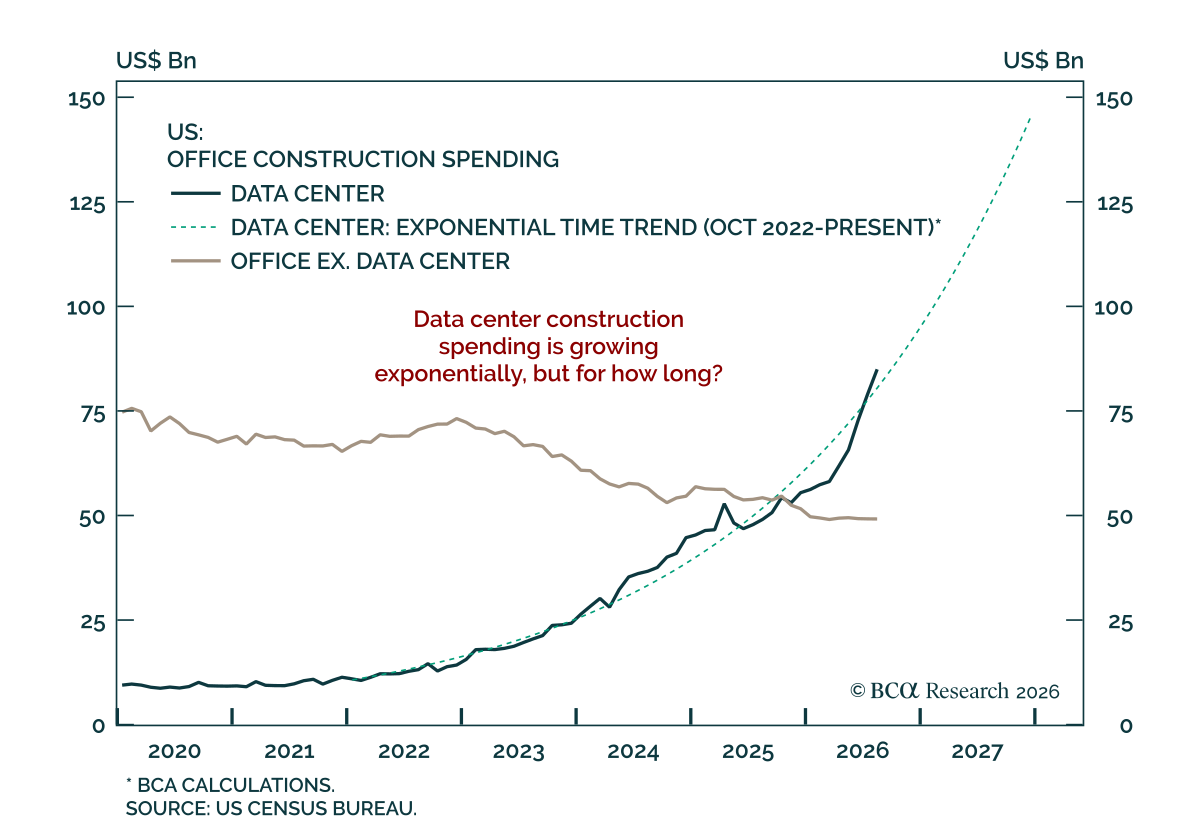
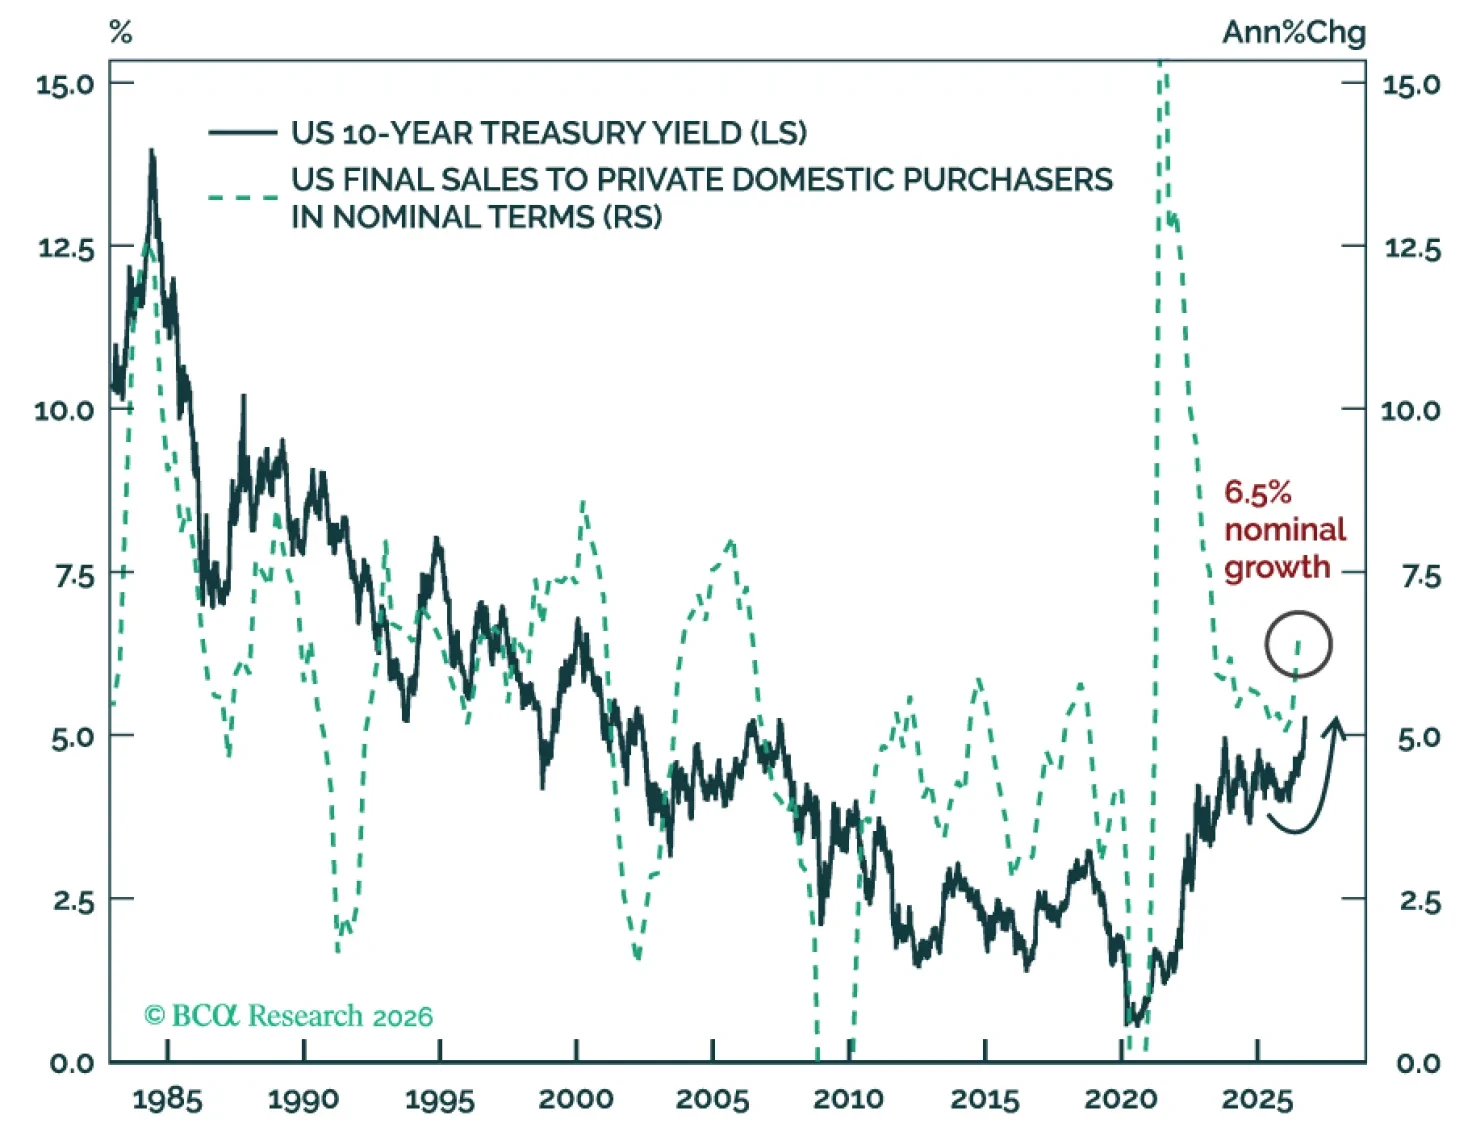
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
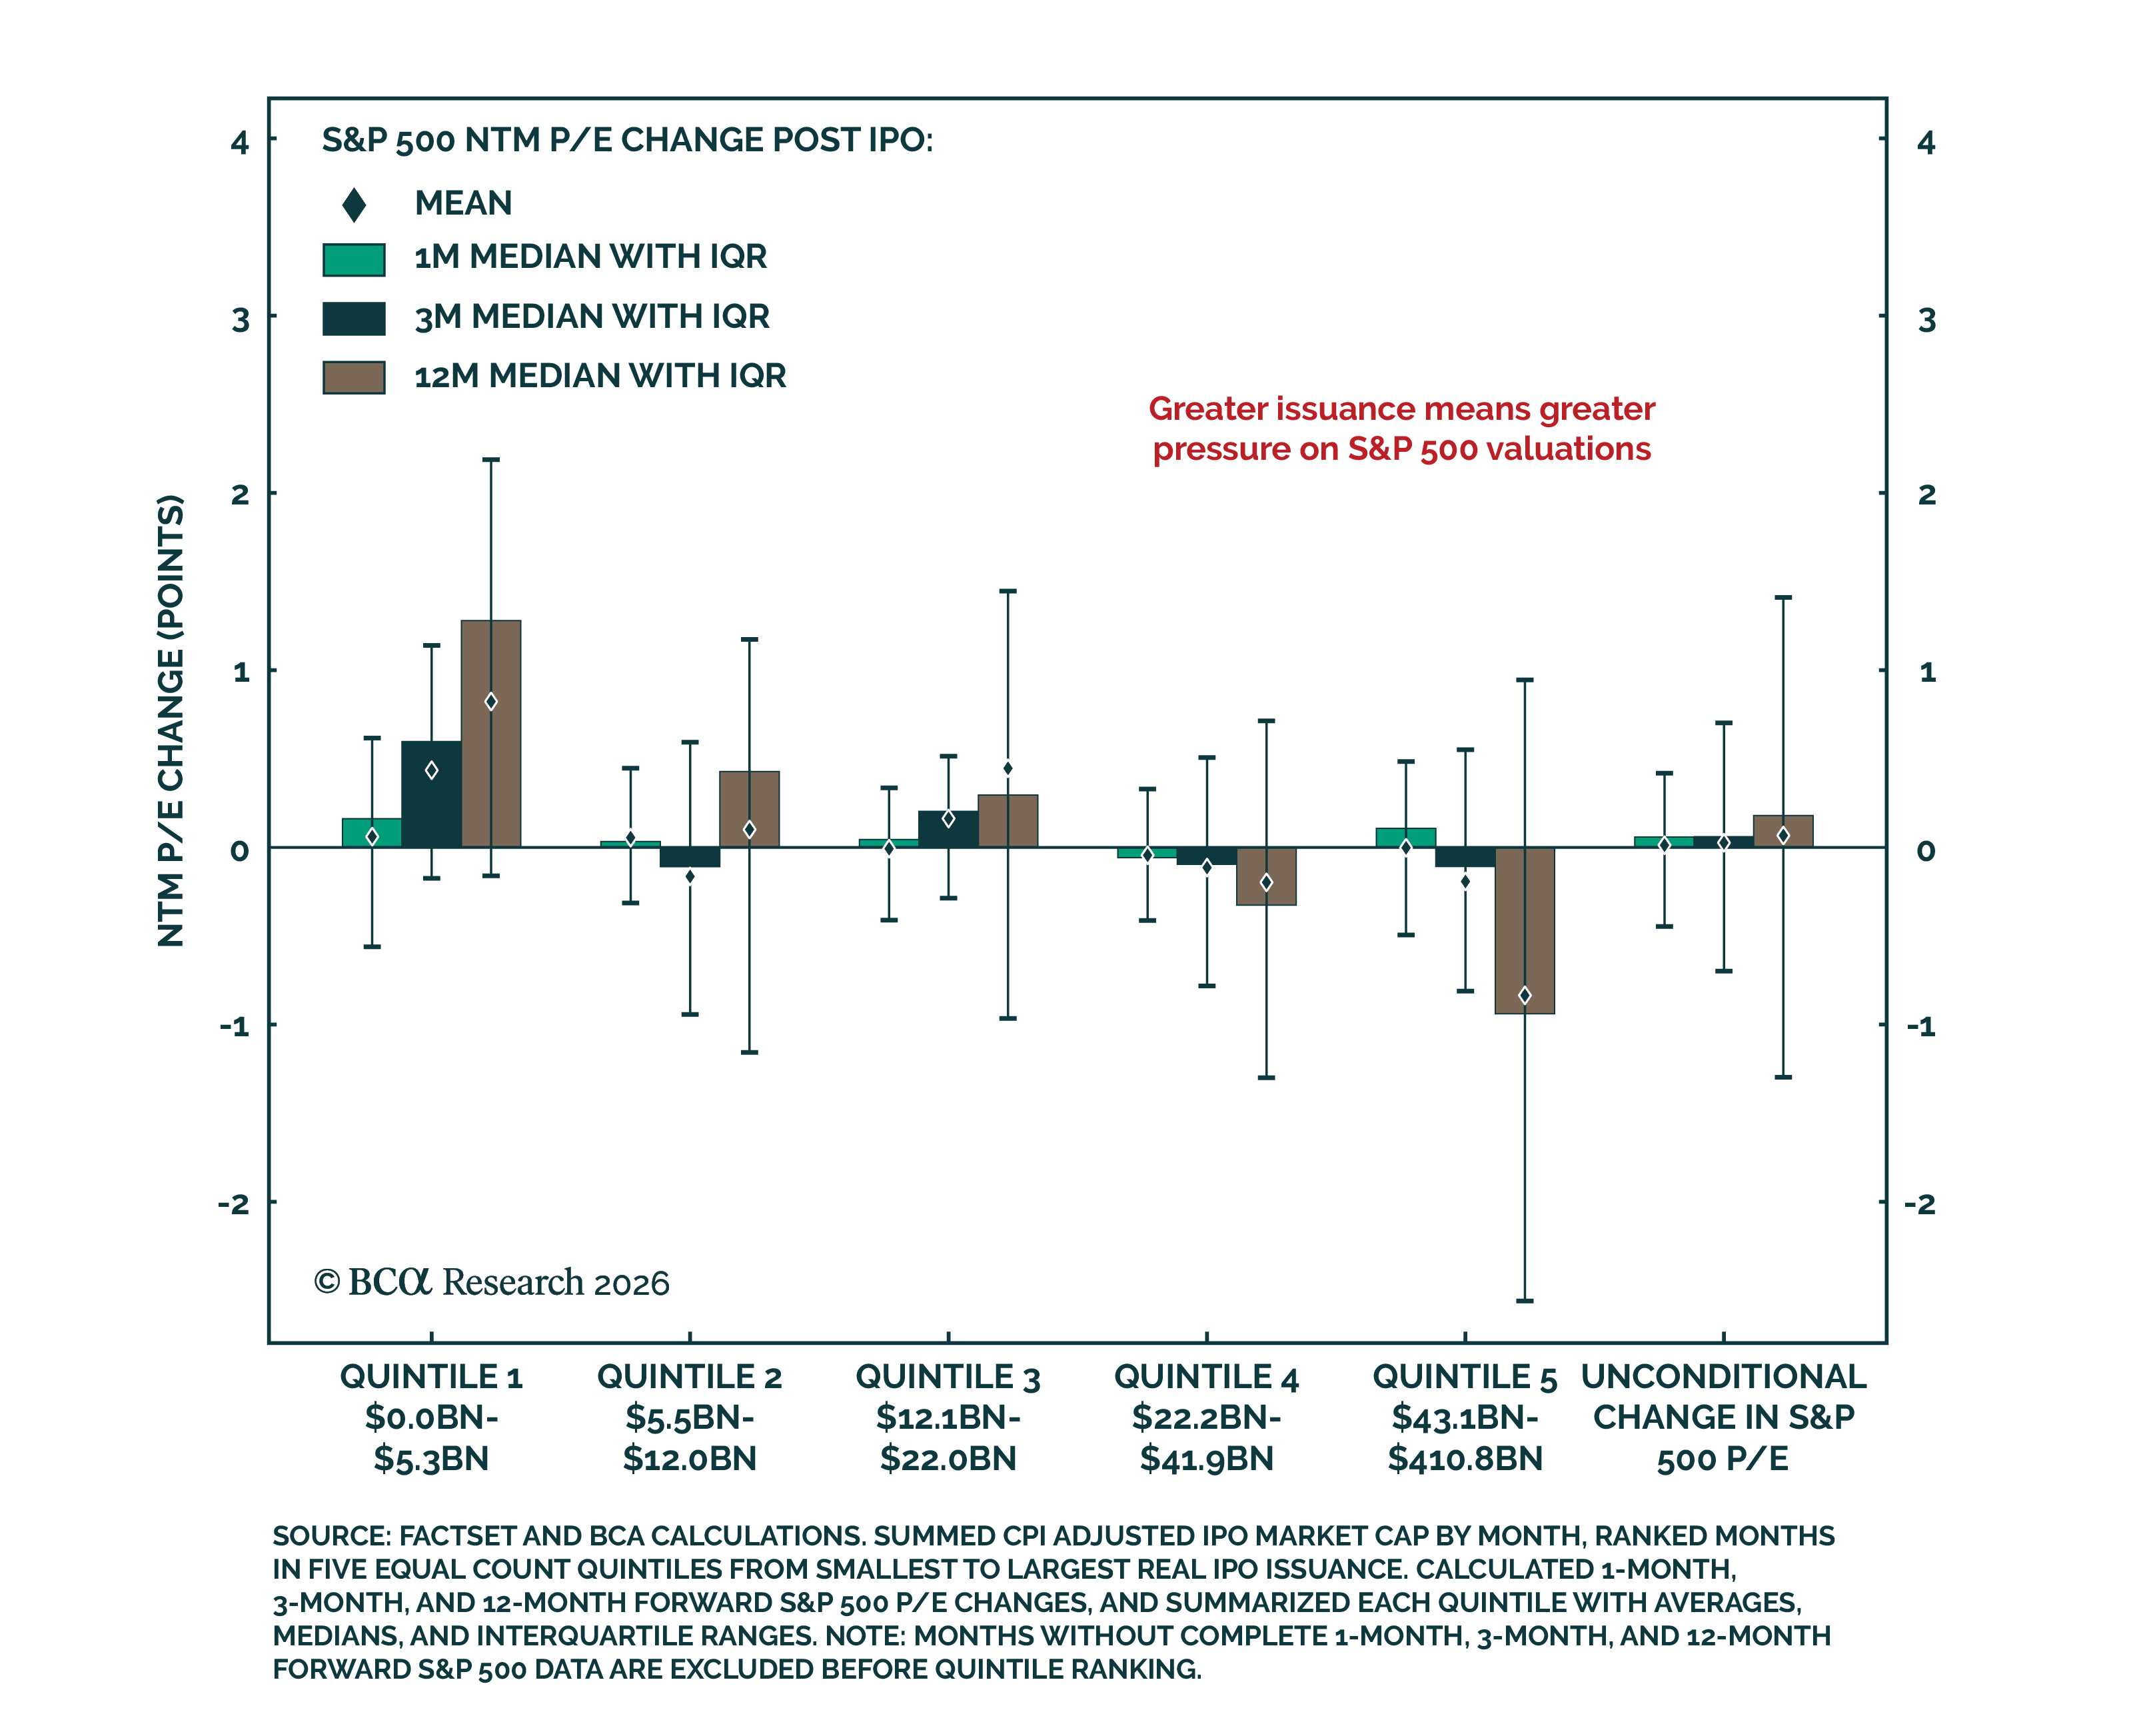
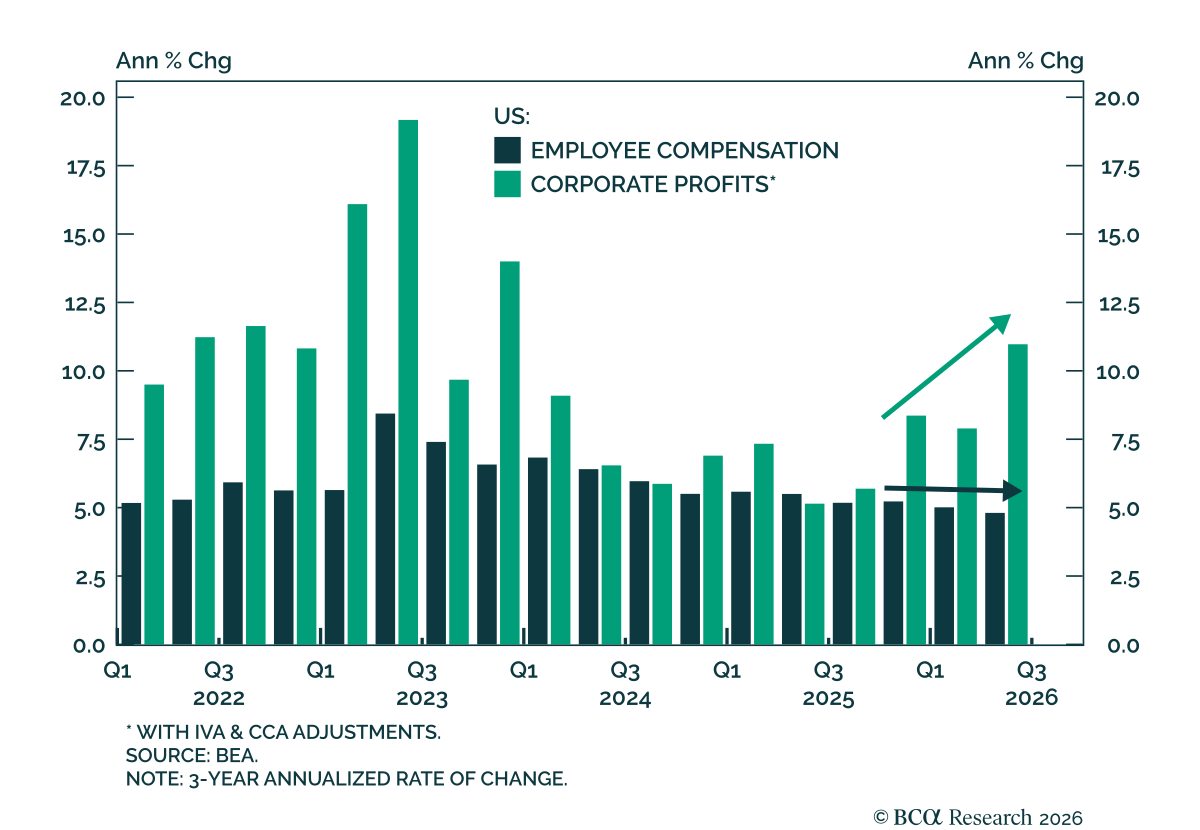
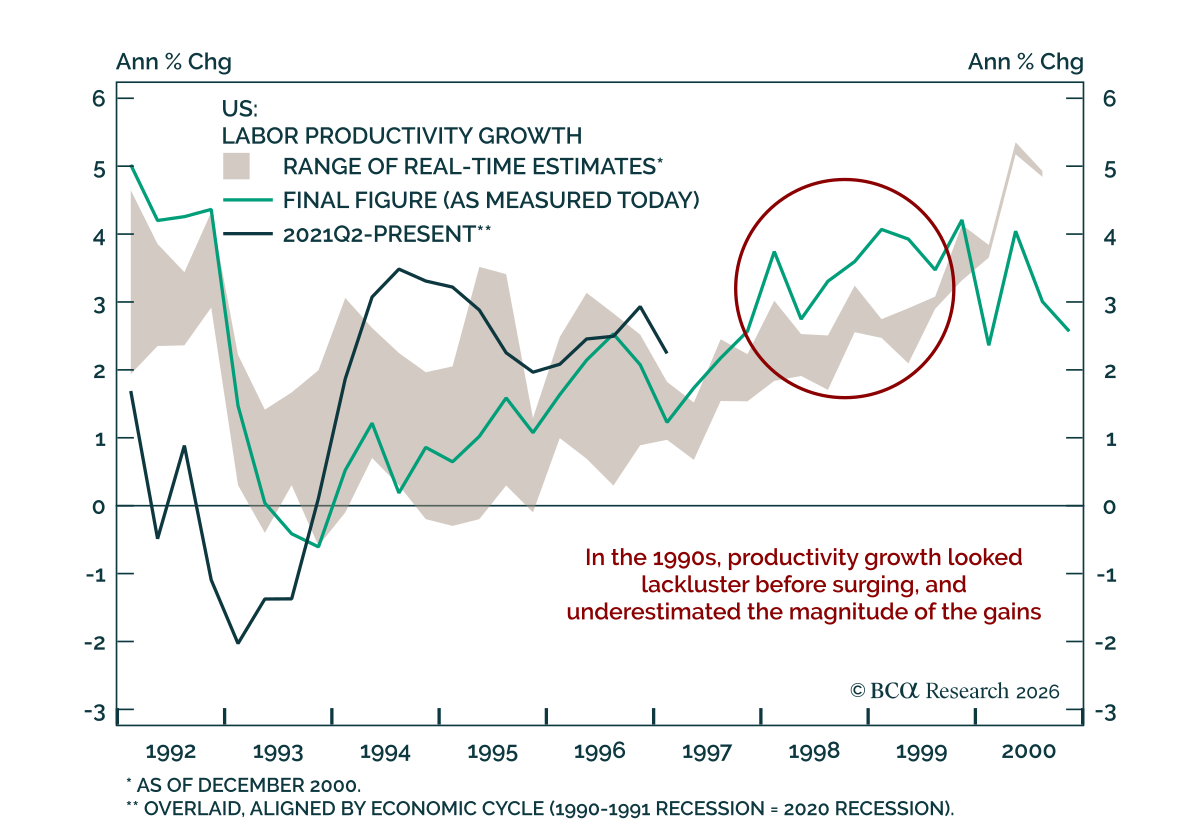
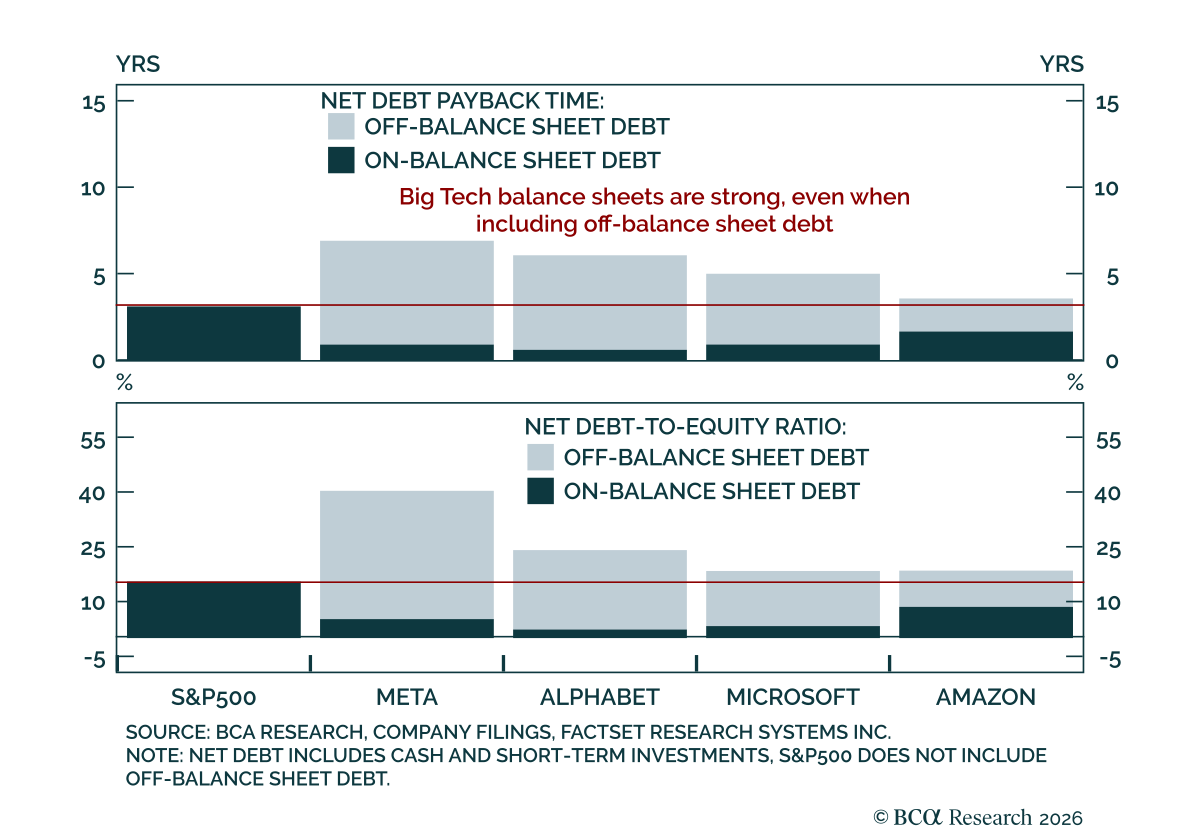
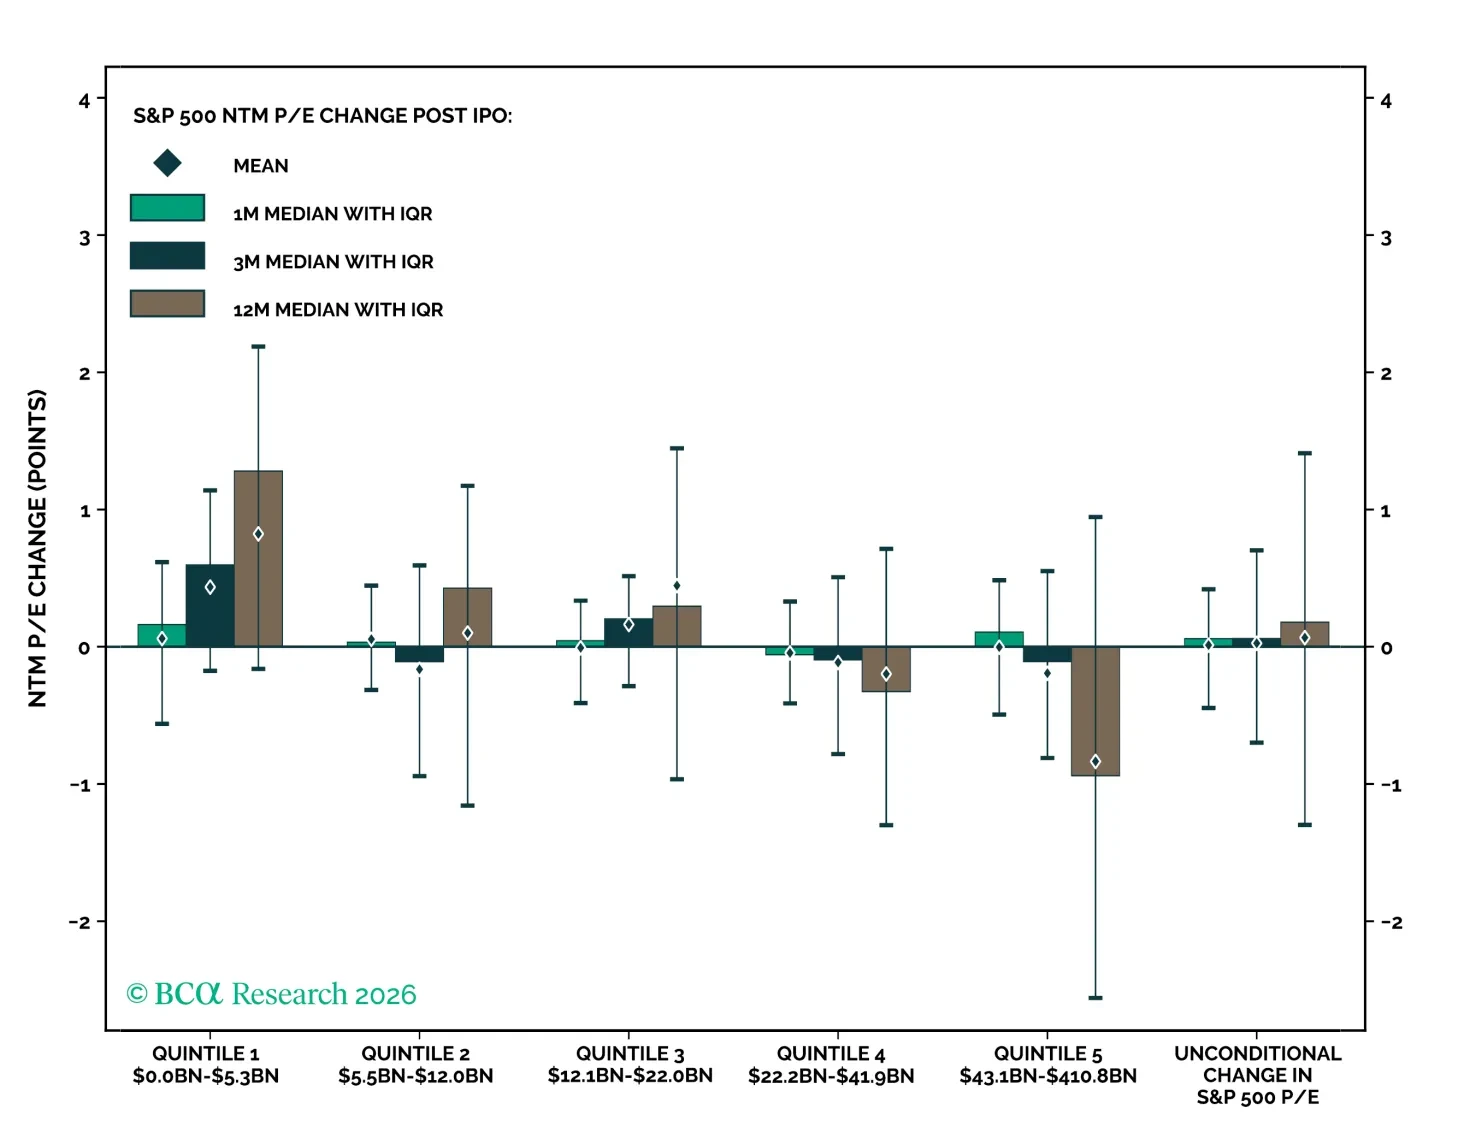
The IPO wave has arrived, dominated by SpaceX’s massive listing. Aftermarket performance has been weak, and elevated issuance is weighing on S&P 500 multiples, although some pressure is already priced. SpaceX remains only partly digested, while Anthropic and OpenAI will bring further supply and greater business model scrutiny.