Latest from BCA Research
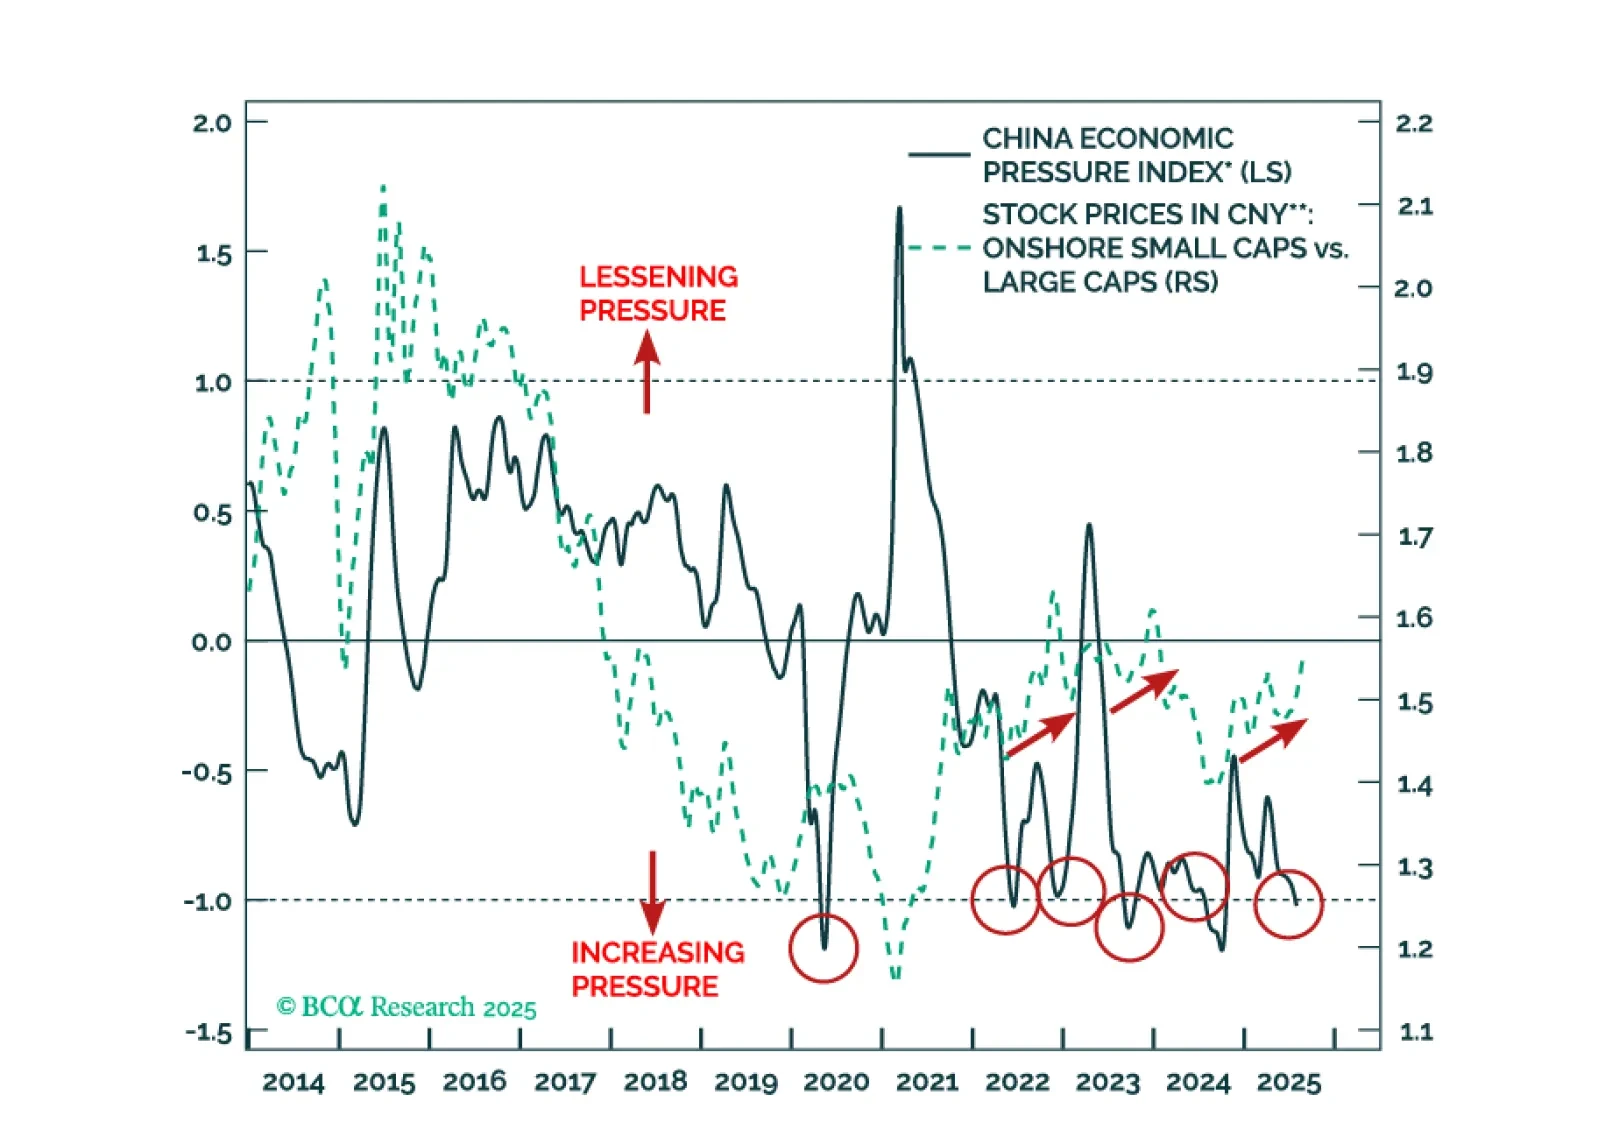
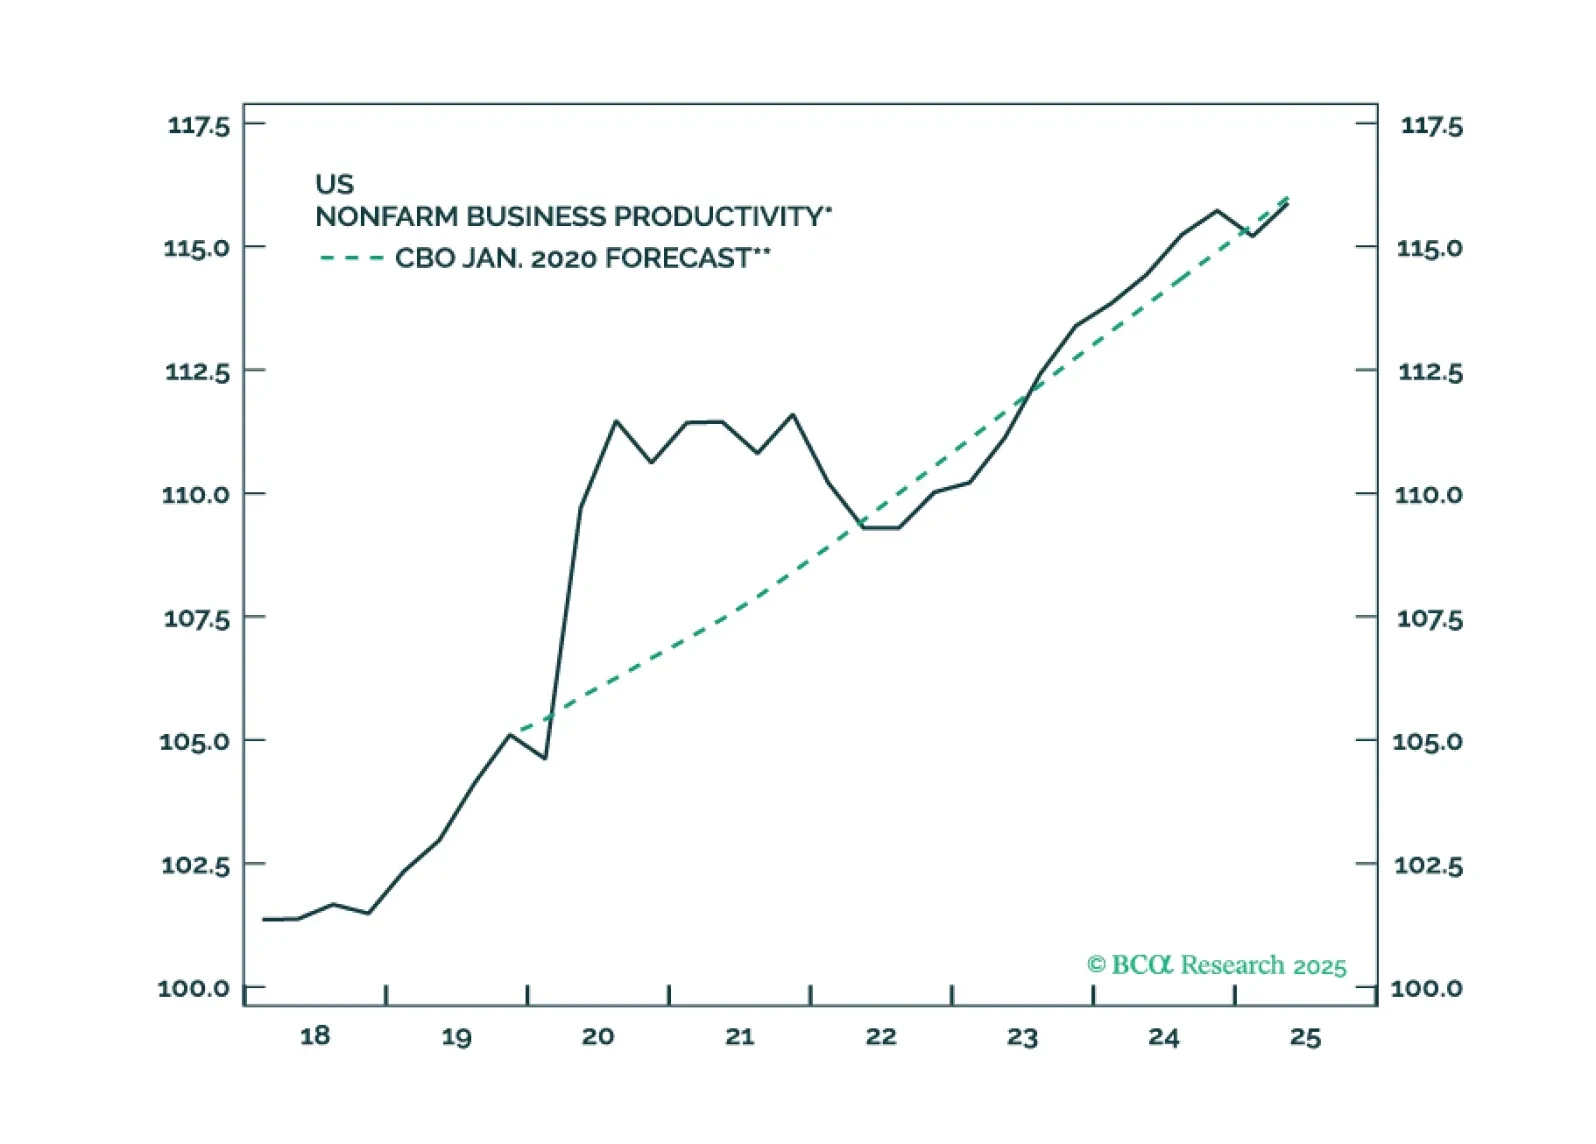
The AI boom has had less of an impact on the economy than widely believed. This may eventually change, but the risk is that investors grow impatient before it does.
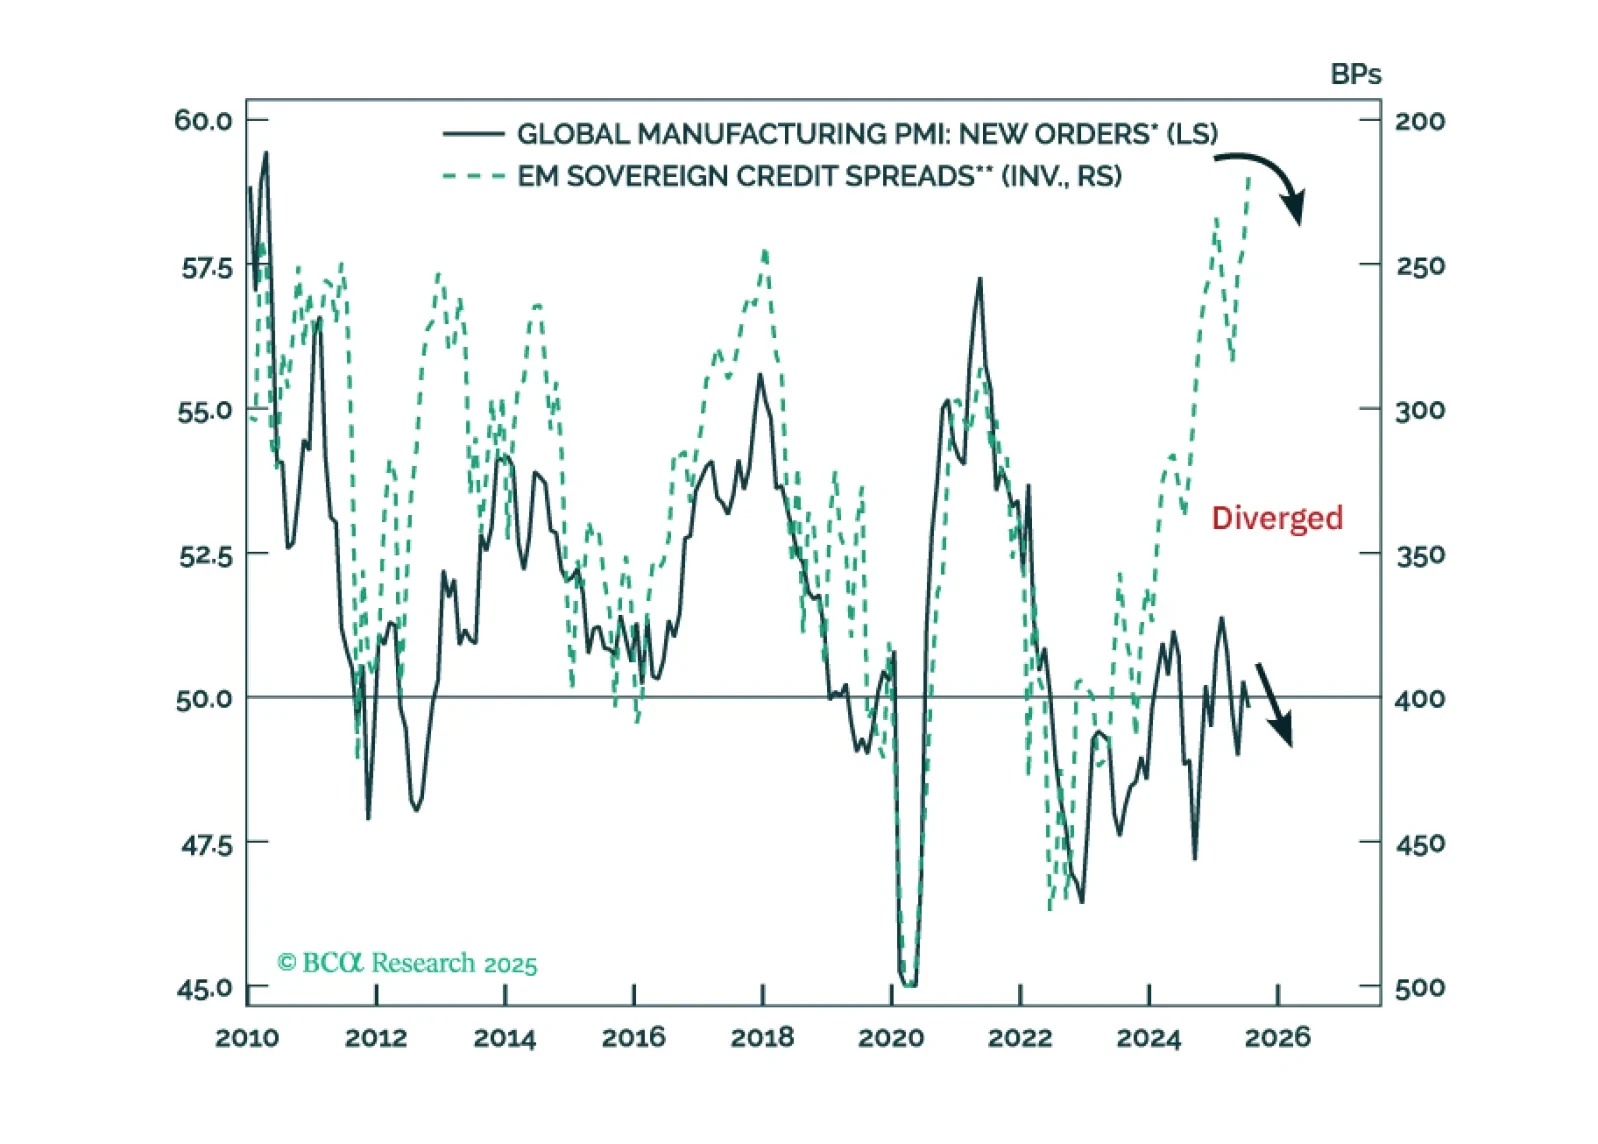
EM sovereign and corporate credit spreads are set to widen. Within a global credit portfolio, maintain a neutral allocation to EM credit markets versus US corporate credit. Favor EM local currency bonds over EM USD bonds.
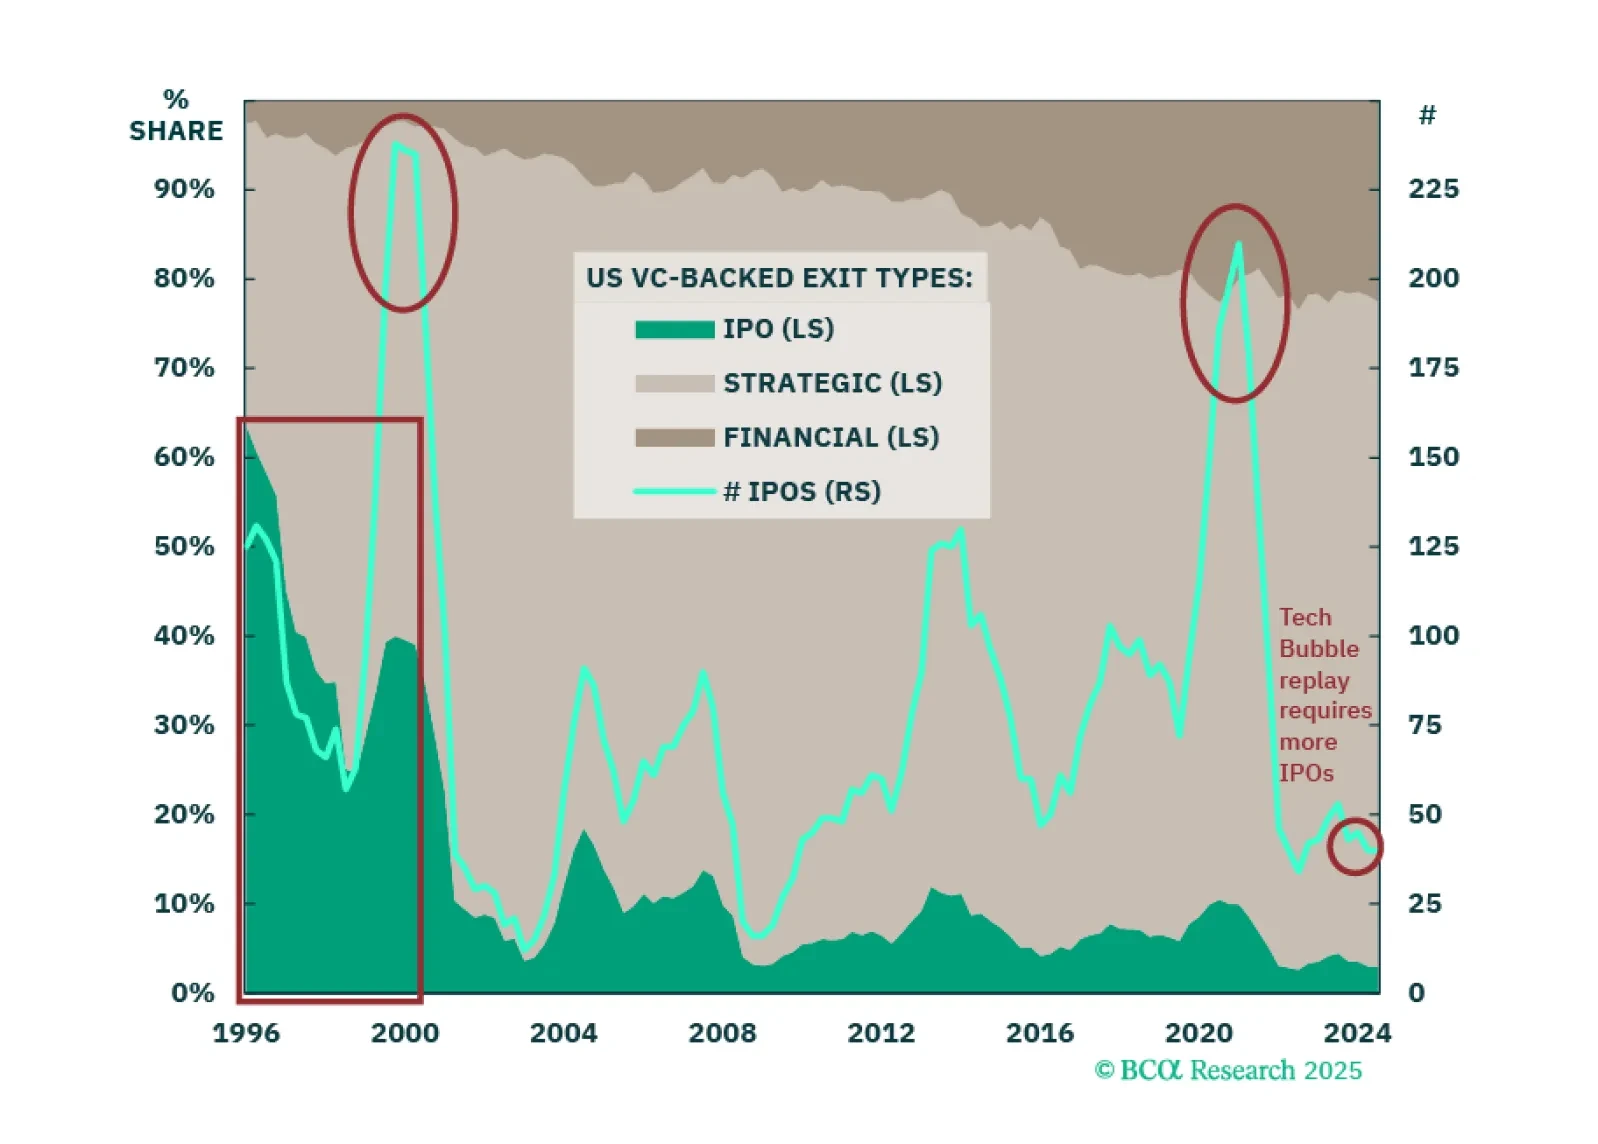
In 7 charts and under 1,000 words, we reveal the real story behind AI Venture Capital. Valuations are not at extremes and IPOs do not signal a replay of the 2000 Tech Bubble—yet.
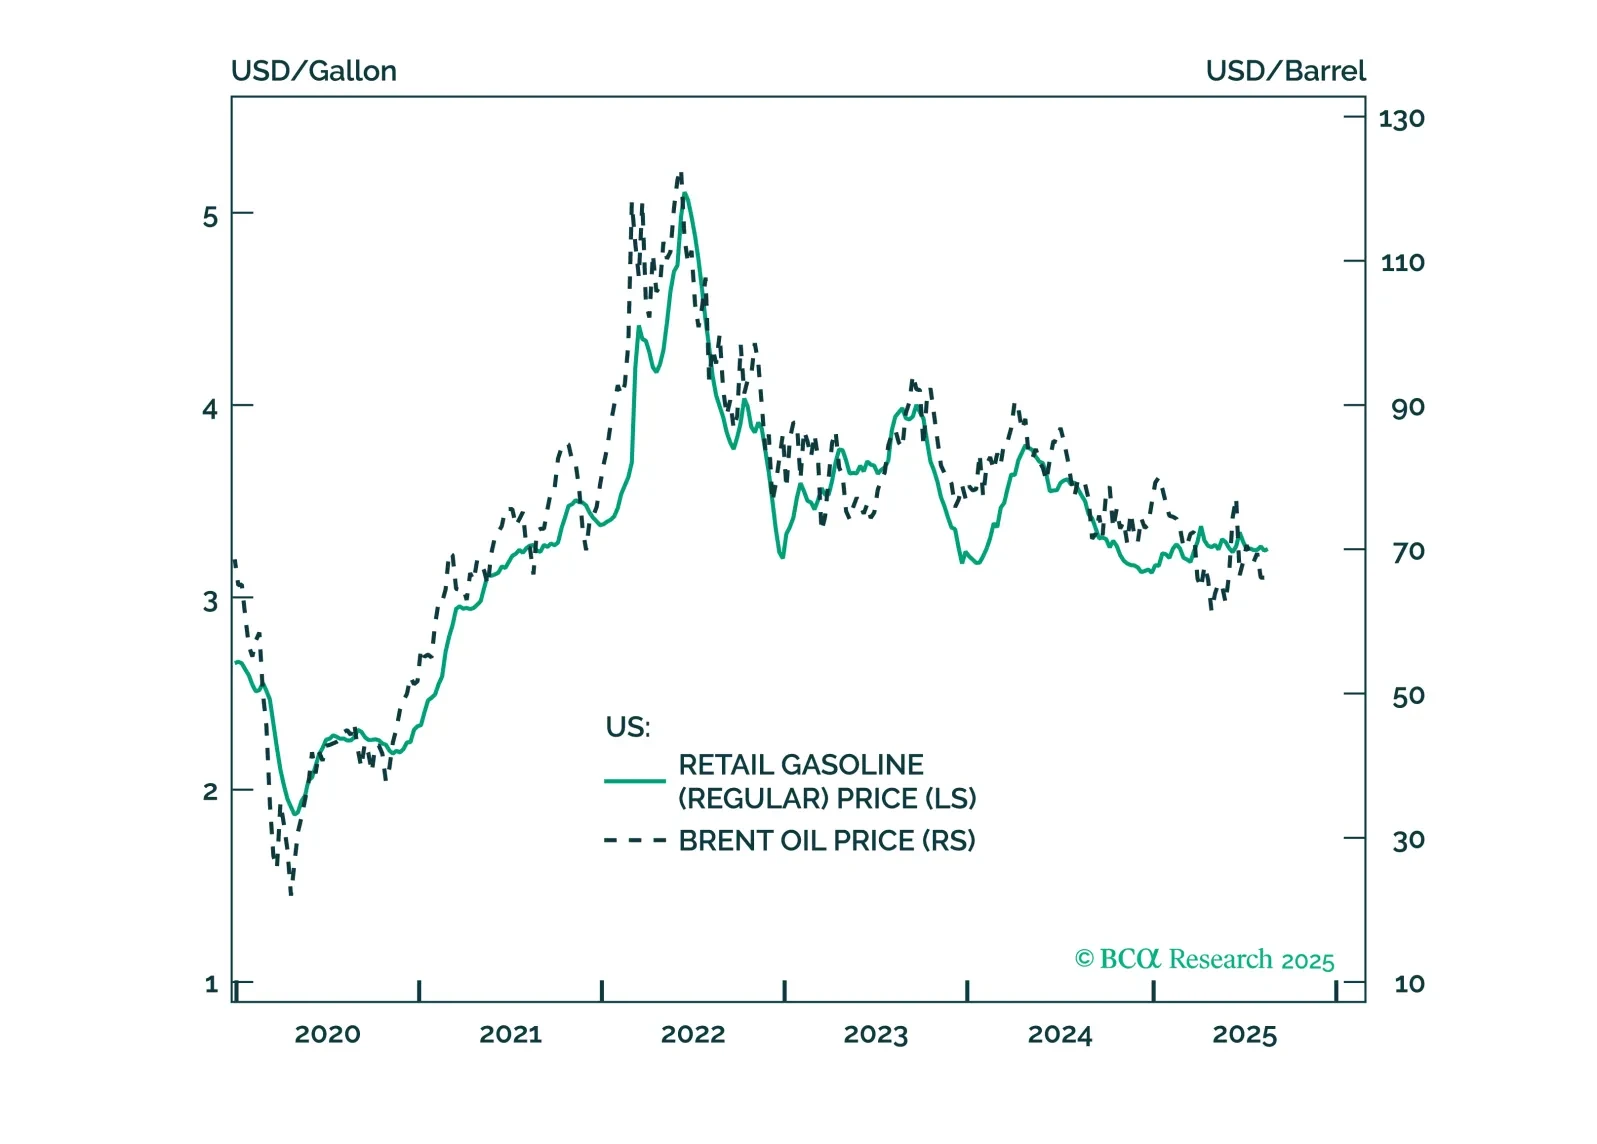
The media is missing the big picture: the war is already contained. The falling oil price confirms that. We fully expect cold feet and volatility incidents in the very near term but there is only a 5% chance of Russia triggering a larger war with NATO – and that is what really matters.
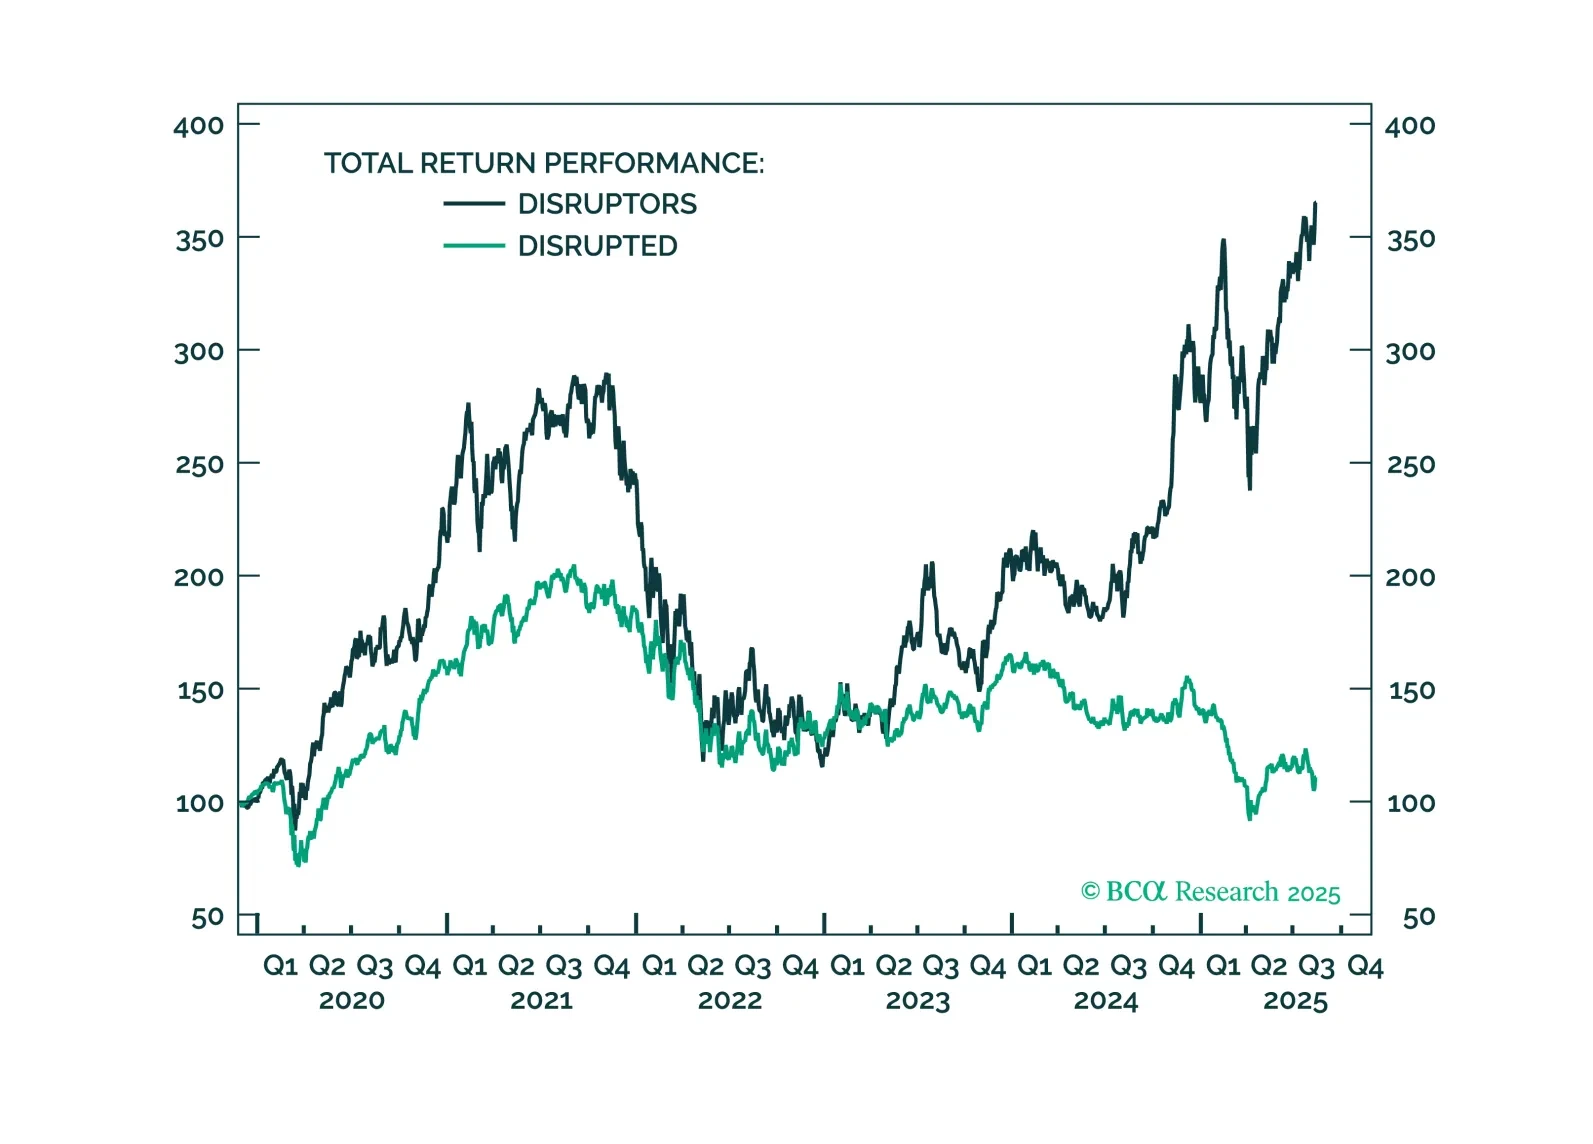
GenAI momentum is building. Many companies are already reaping benefits from the technology. GenAI is disrupting entire industries, such as education, image generation, and staffing. Investors should prefer our “disruptors” basket over the “disrupted” basket.
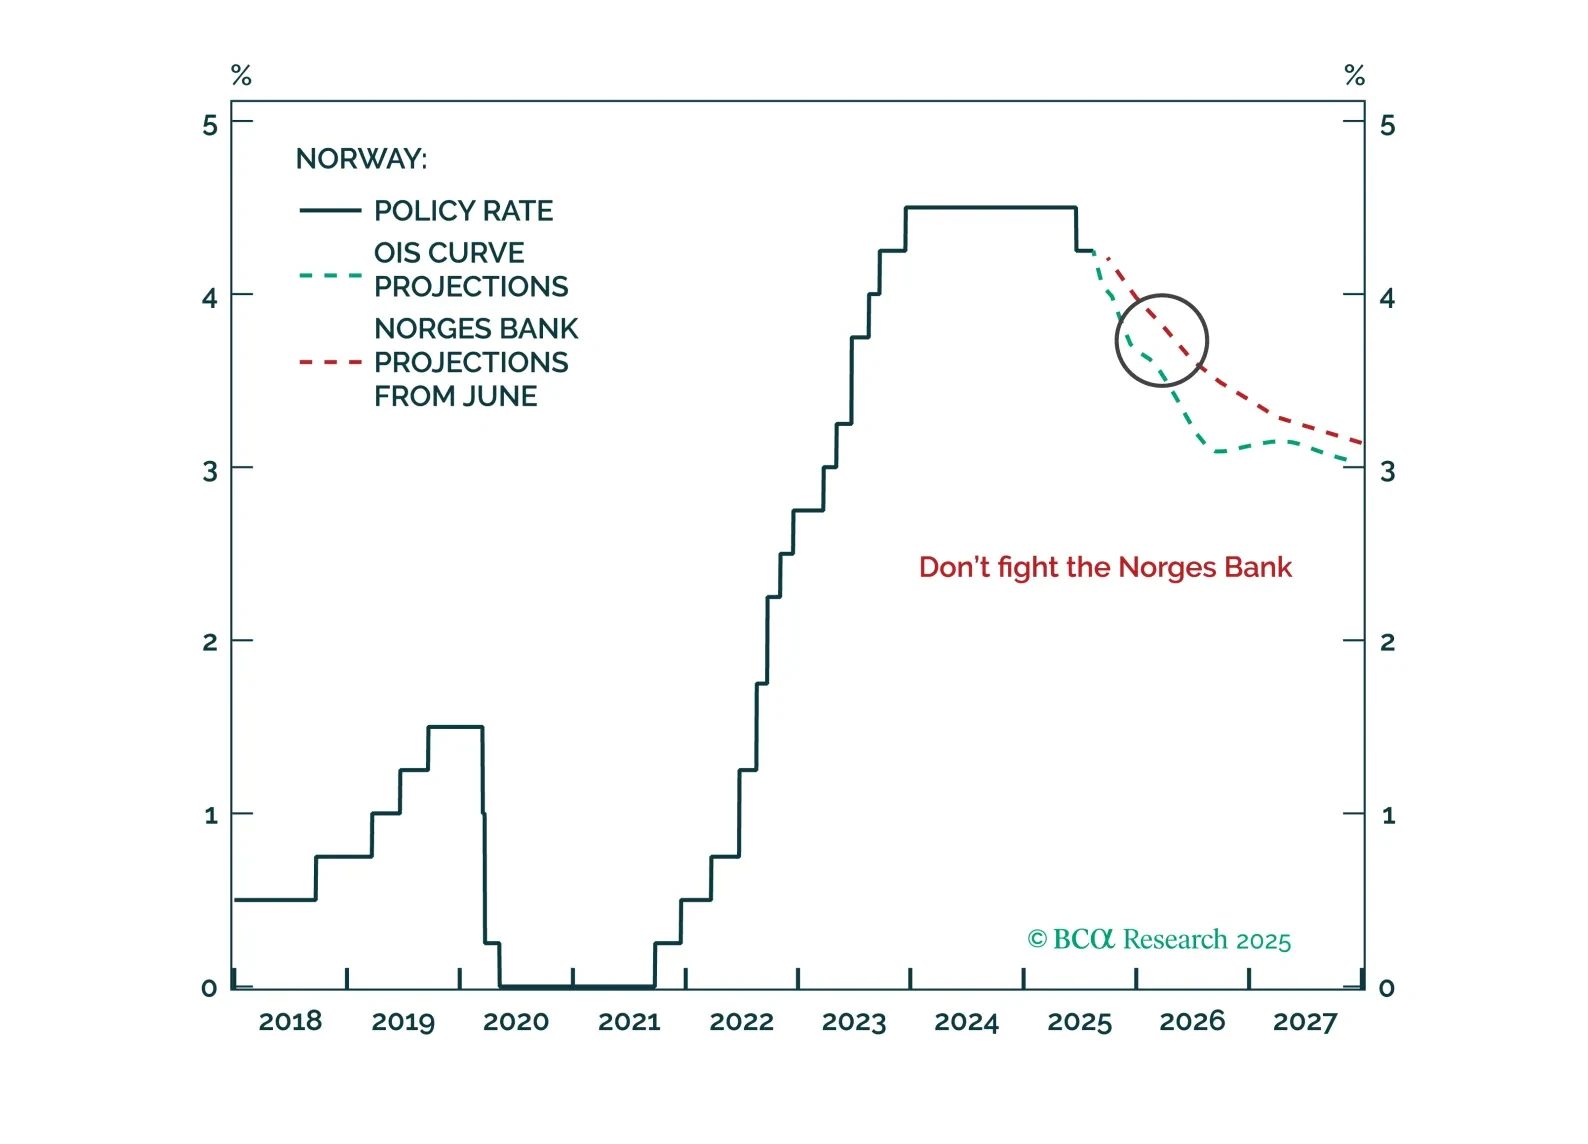
The Norges Bank will cut rates only once until year-end as the NOK weakens and inflation hovers around 3%. Expect aggressive easing next year as the economic recovery is delayed by weakness in the energy sector and the labor market deteriorates.
President Donald Trump and his counterpart President Vladimir Putin have met at an air force base in Alaska. The backdrop? America’s shiny F-22 Raptors ominously gleaming on the tarmac, a clear show of force by the US. A reminder that President Trump may be quite friendly with Putin, but that he will not hesitate to impose pain on Moscow if the Kremlin keeps dragging out the conflict in Ukraine.
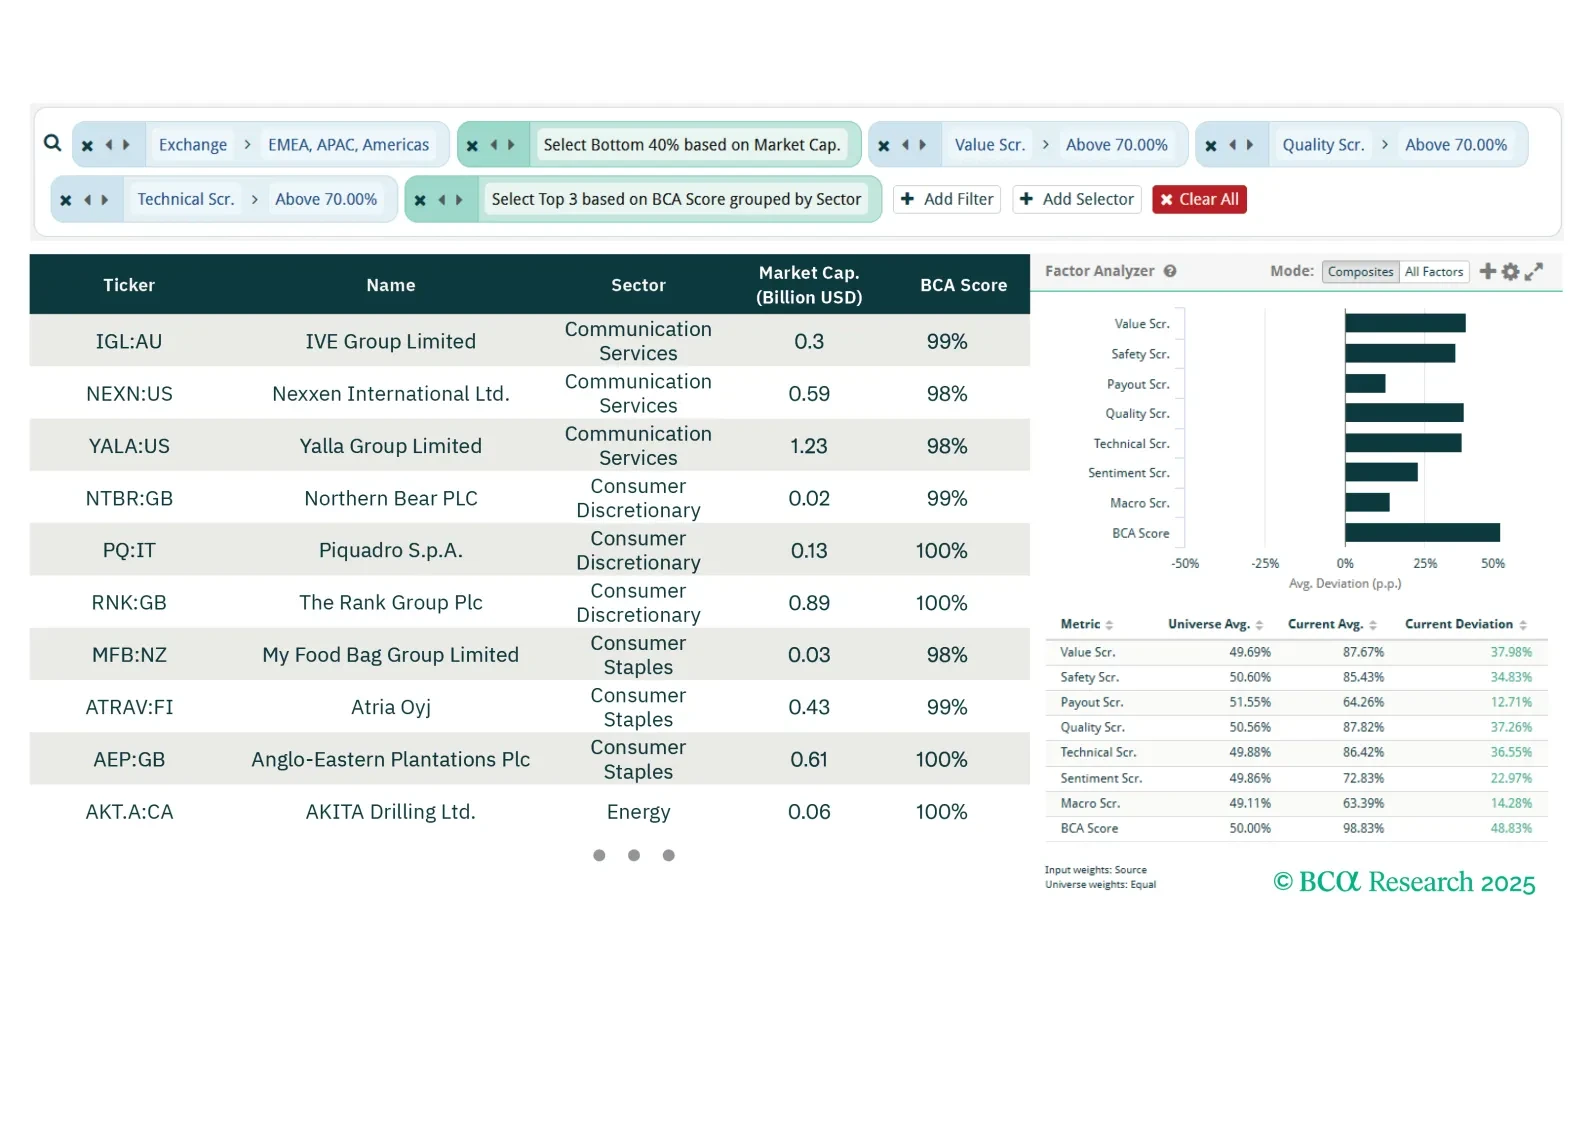
This week our three screeners highlight plays in global small-cap value stocks, gold miners, and stocks exposed to an exciting structural investment theme: Space.
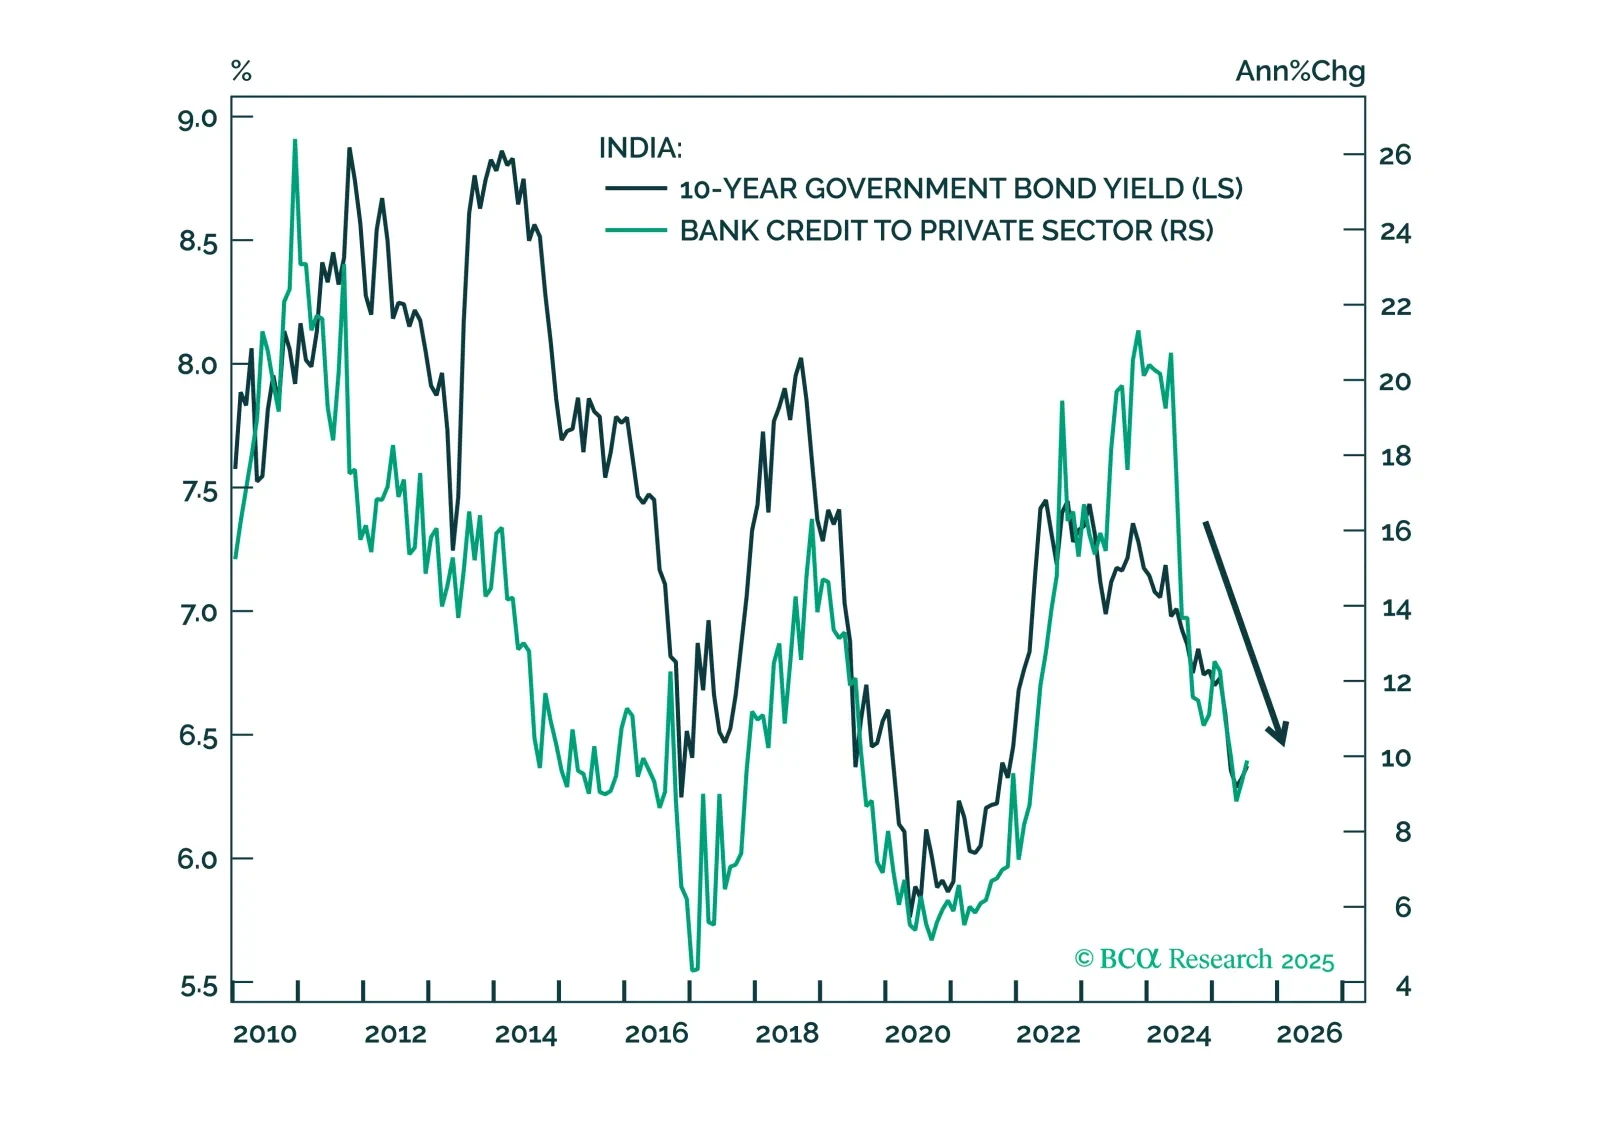
The Indian rupee remains vulnerable to further depreciation amid slowing growth, tight domestic policy, and fragile capital flows. Trade risks and a weakening external balance will likely keep INR underperforming EM Asia peers.