Latest from BCA Research

The cost of tariffs is falling on the US consumer, not foreign exporters or US firms.
Trump’s political capital is near its peak. But near-term optimism will give way to a new round of volatility. Contrary to expectations, the USD may benefit.
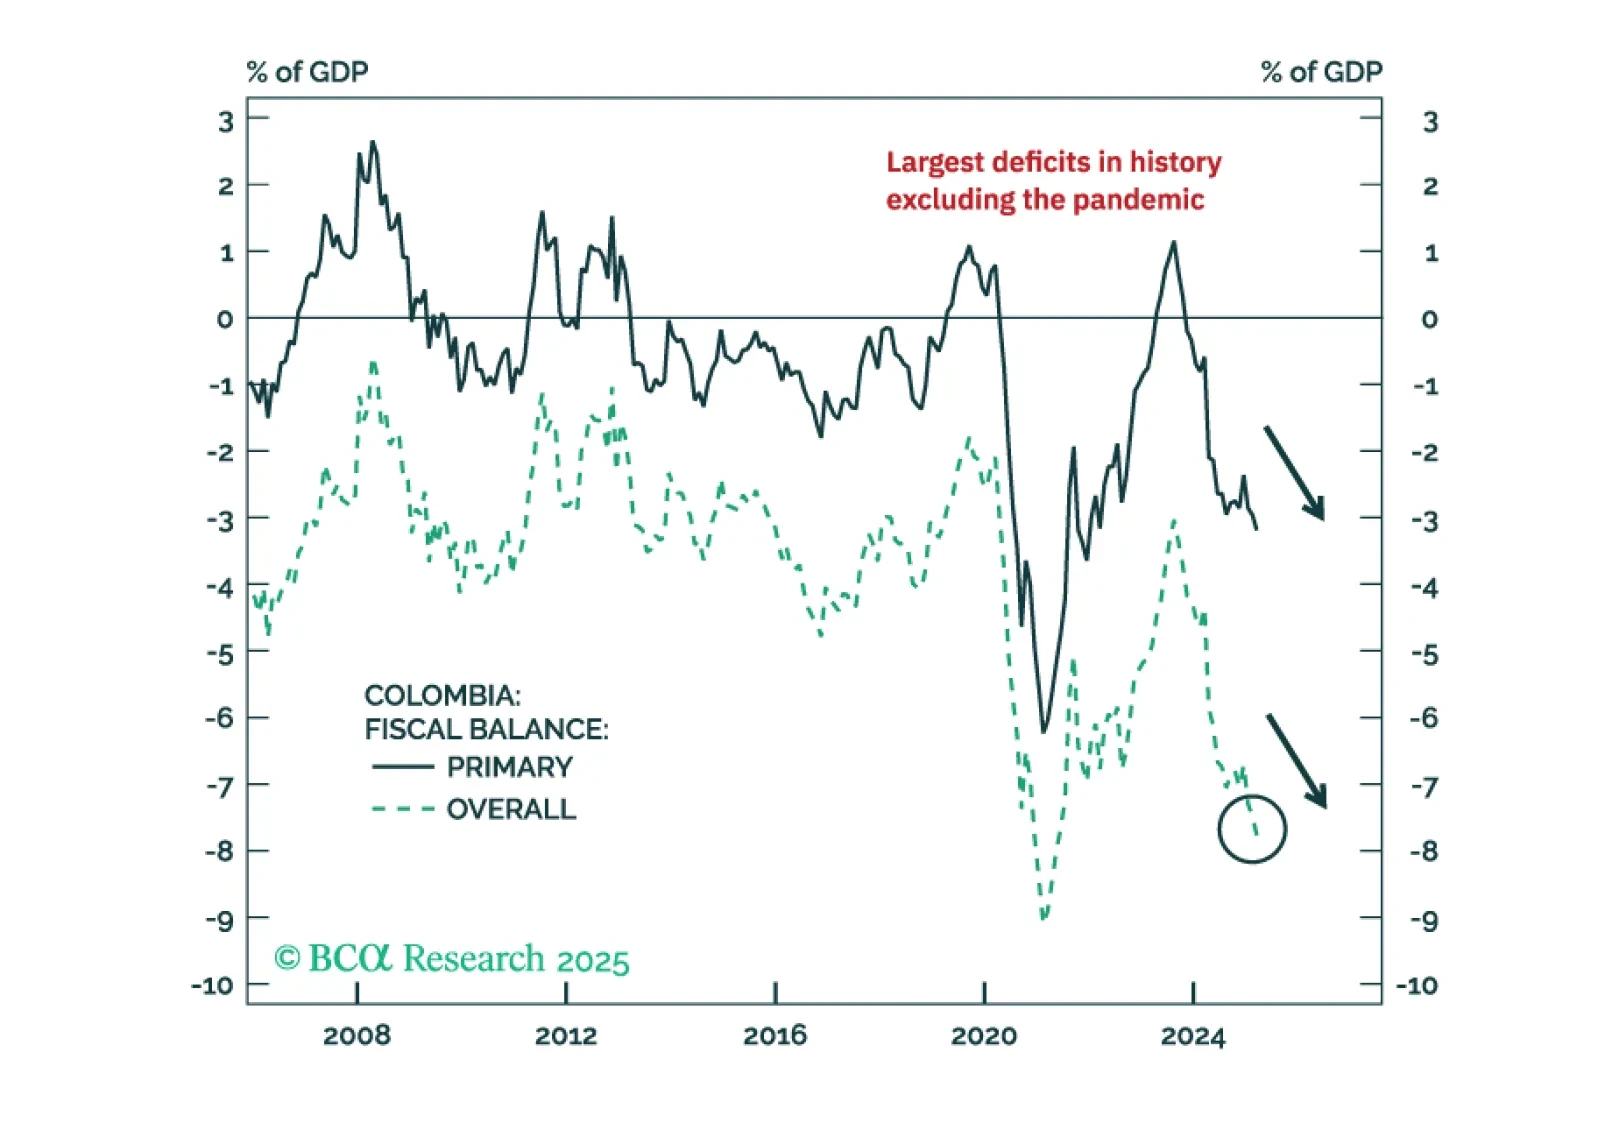
Colombian markets will be torn between expectations of future orthodox policies and the reality of a worsening macro backdrop in the next 12 months. To balance risks, we are upgrading Colombian equities, local bonds, and sovereign credit from underweight to neutral versus their respective EM benchmarks.

In a widely anticipated move, the RBA resumed cutting rates. However, with housing, consumption, and PMIs improving, we see little scope for the RBA to ease beyond market expectations.
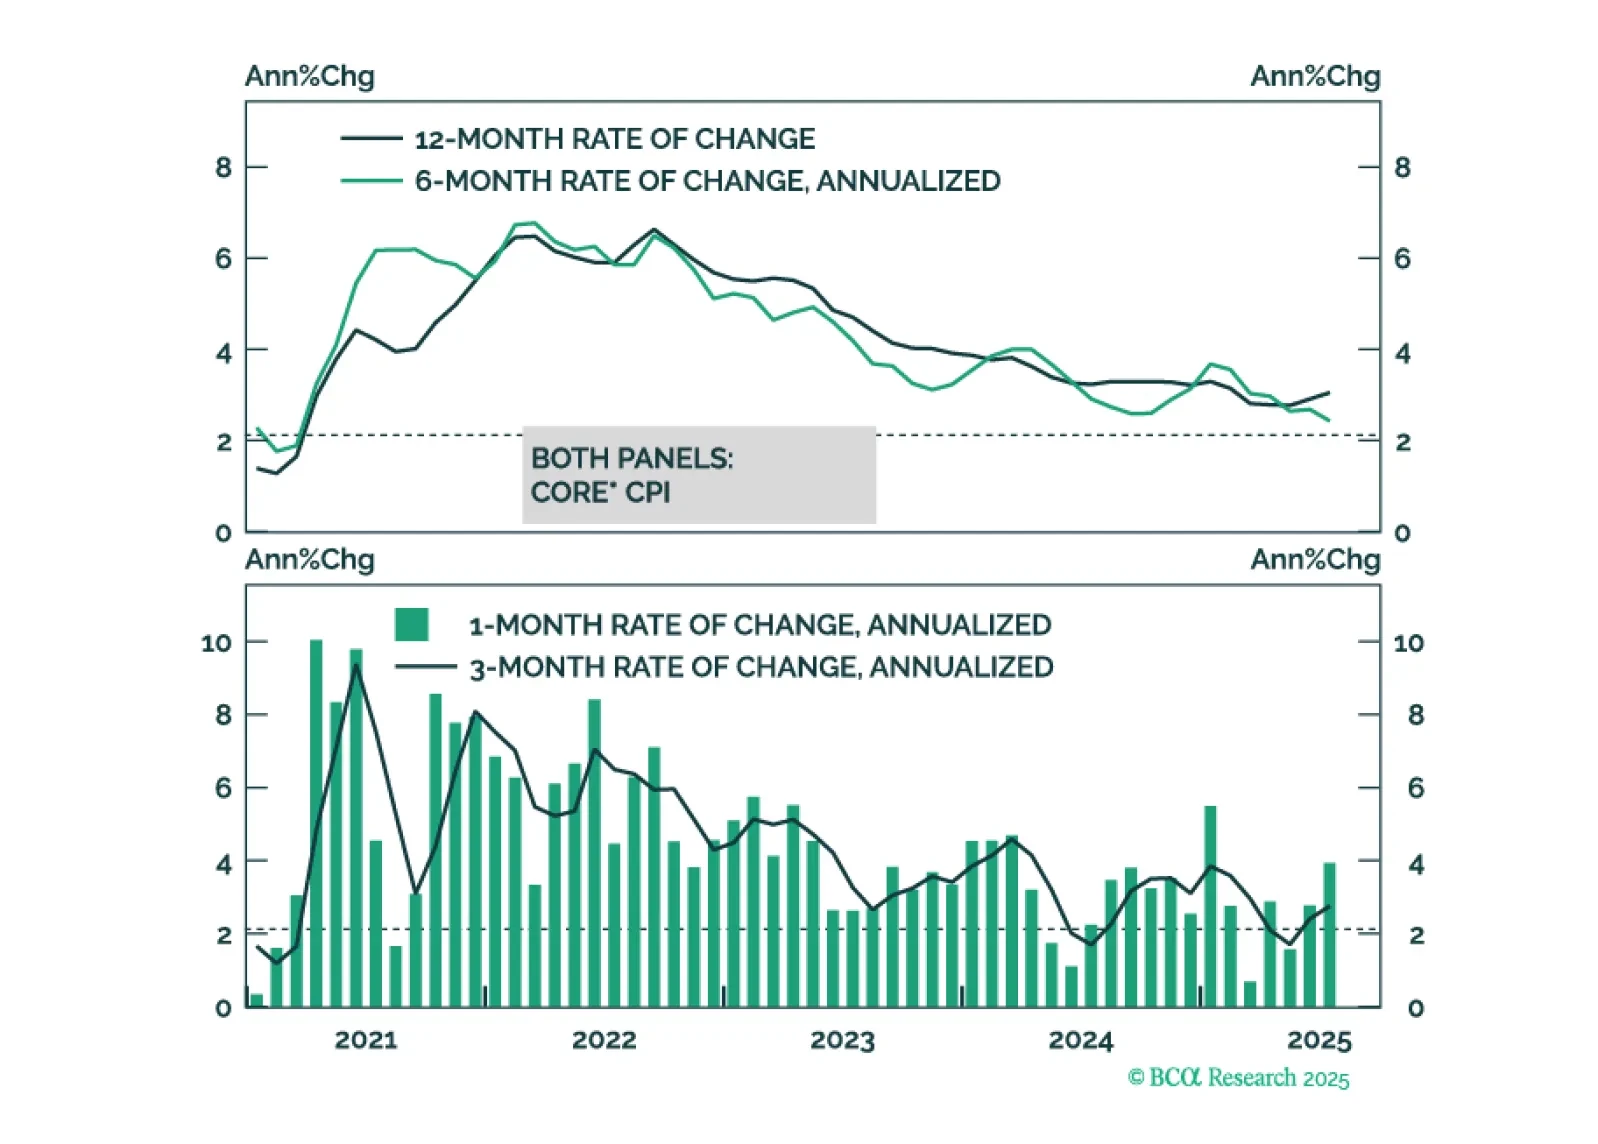
This morning’s CPI report marginally tips the scales in favor of a September rate cut.
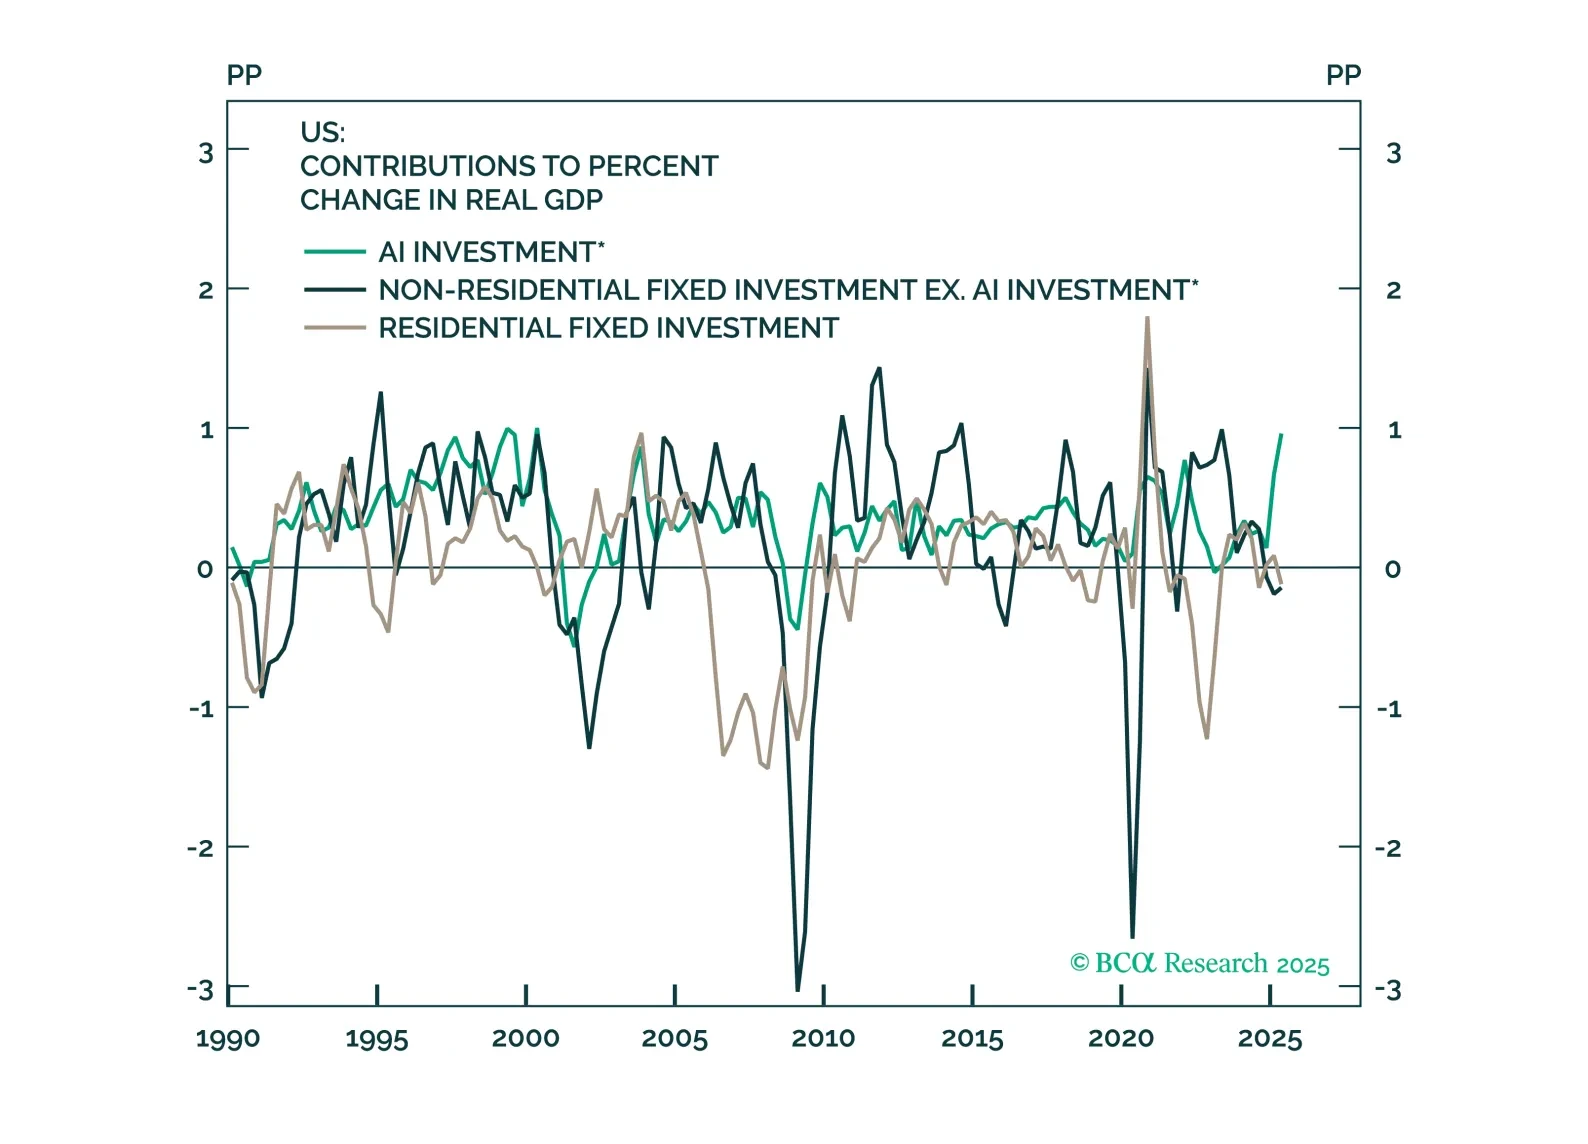
This is the first time that our chartpack does not include any charts on the trade war. Did we just curse our equity overweight? Right as the inflation print comes out and causes agita to the market? Sure, maybe. The tactical ins and outs are not that interesting to us. Far more interesting is the fact that the Fed is going to have to cut regardless of what "widget inflation" does. With no more fiscal backstop fueling the economy via wanton transfer payments to households, the inflation-fiscal gravy train is over. As such, the Fed will cut more than the market thinks, particularly given the political pressure from the Trump White House.
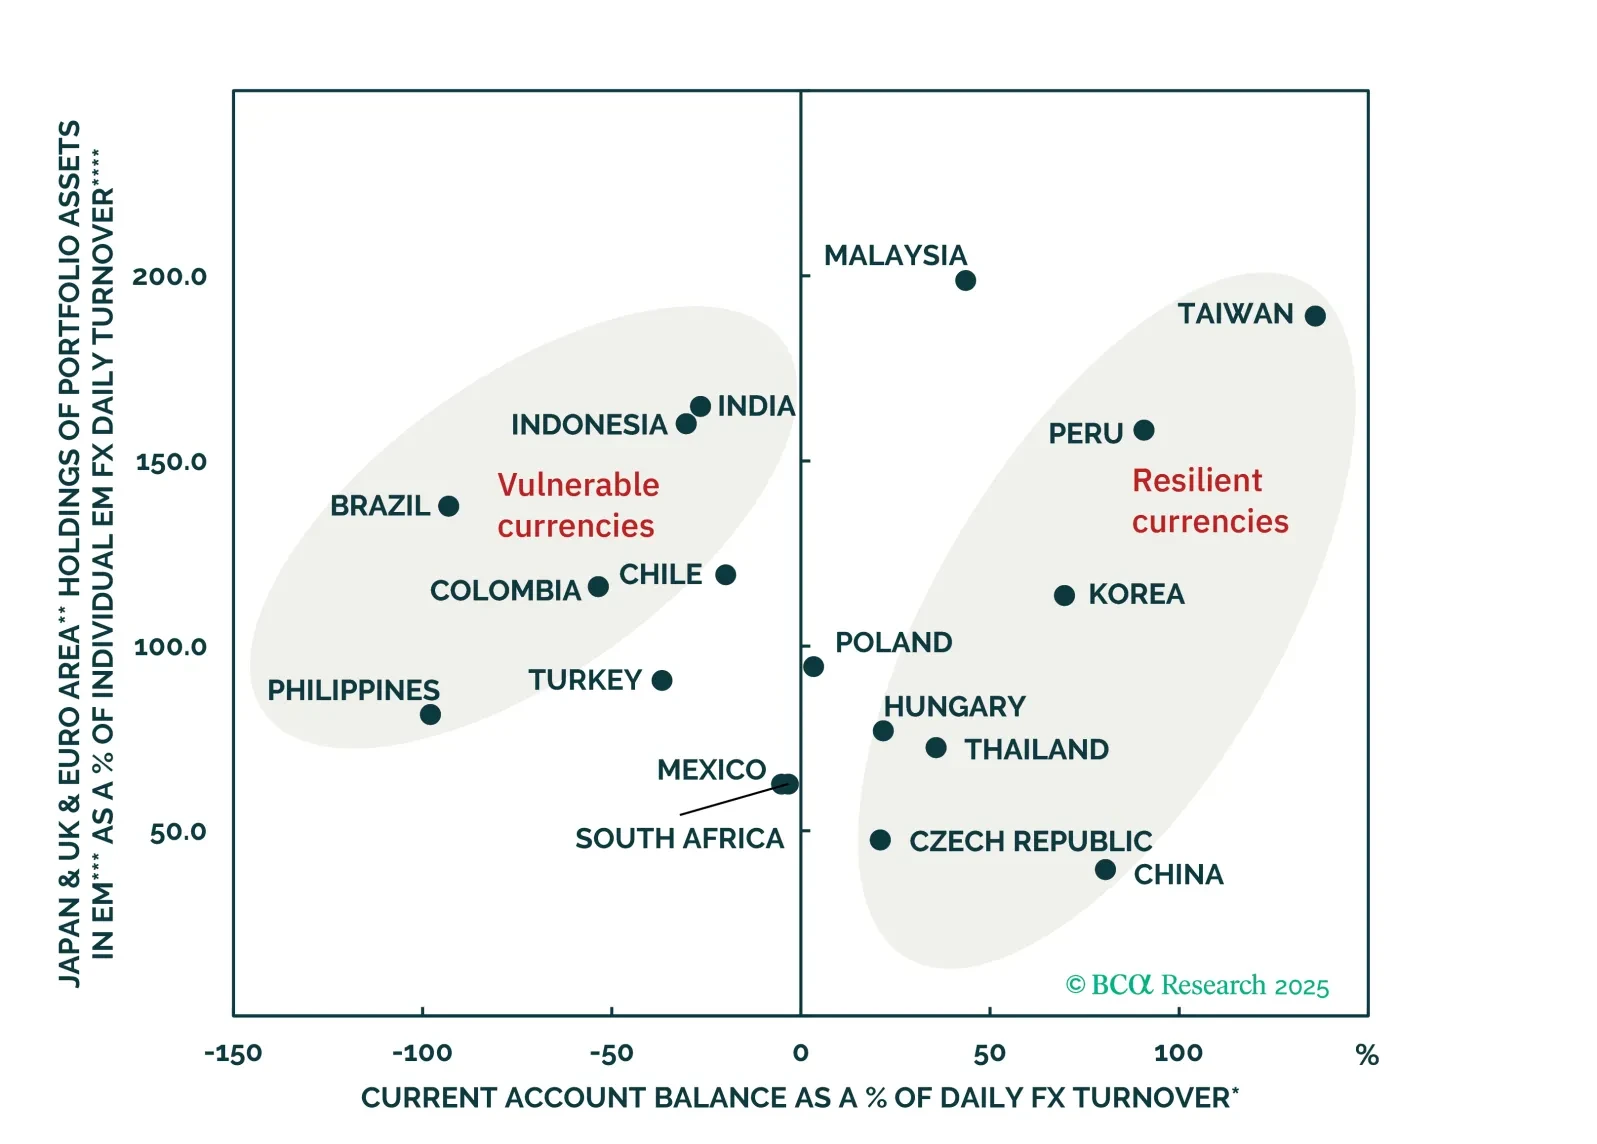
Despite widespread investor optimism Brazil’s currency outlook is challenged by a toxic mix of poor external, fiscal, and macro fundamentals. Expect BRL to underperform most EM peers.