Latest from BCA Research
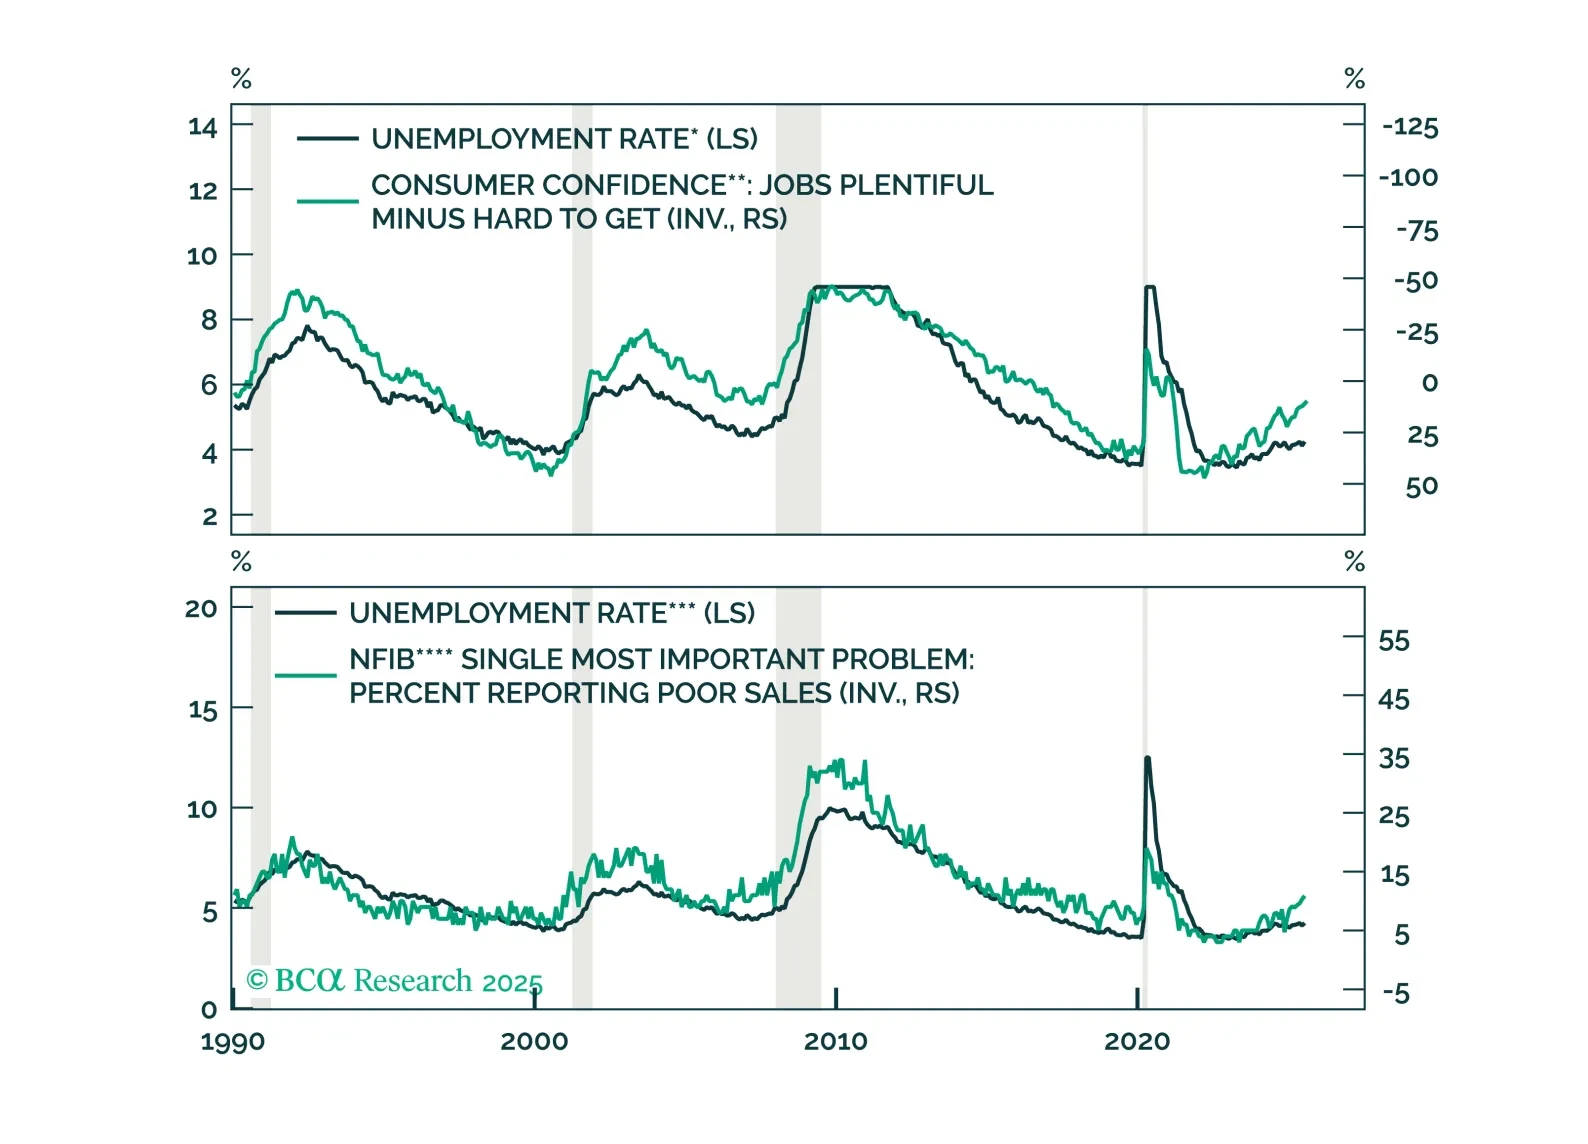
I am pleased to announce the launch of PowerTrades, an exclusive new service for Global Investment Strategy subscribers that delivers our top trading insights directly to your inbox.
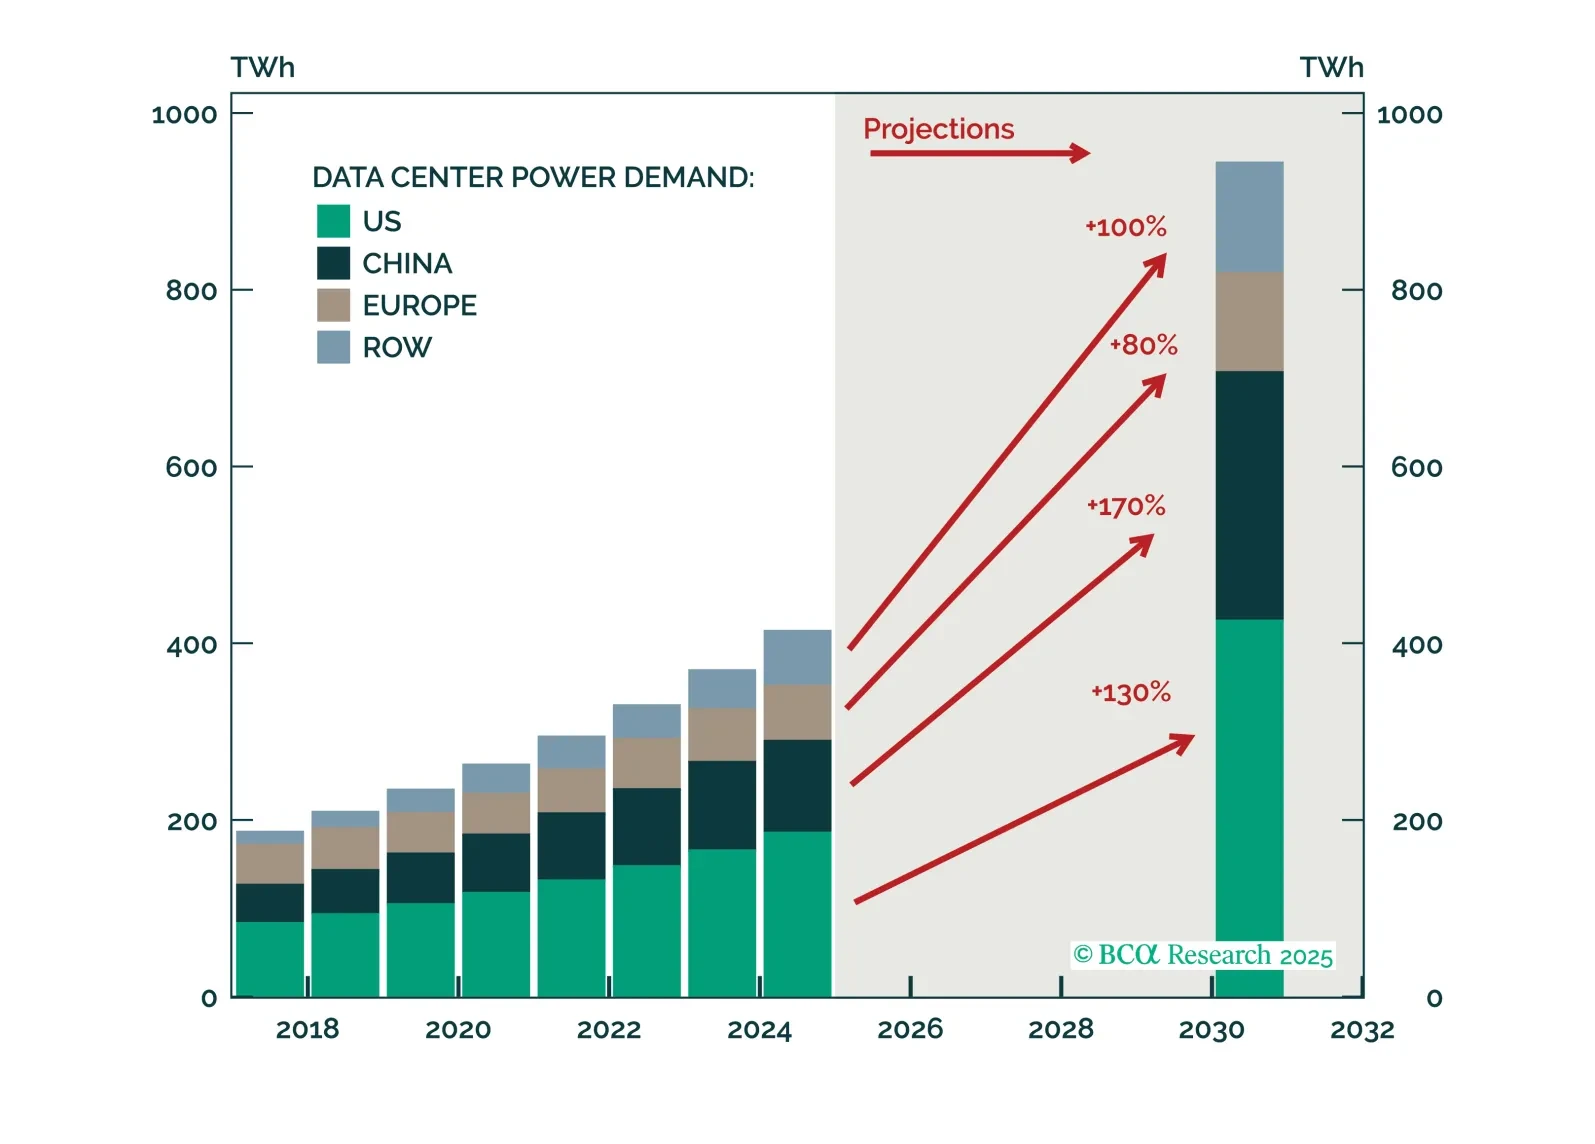
Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.
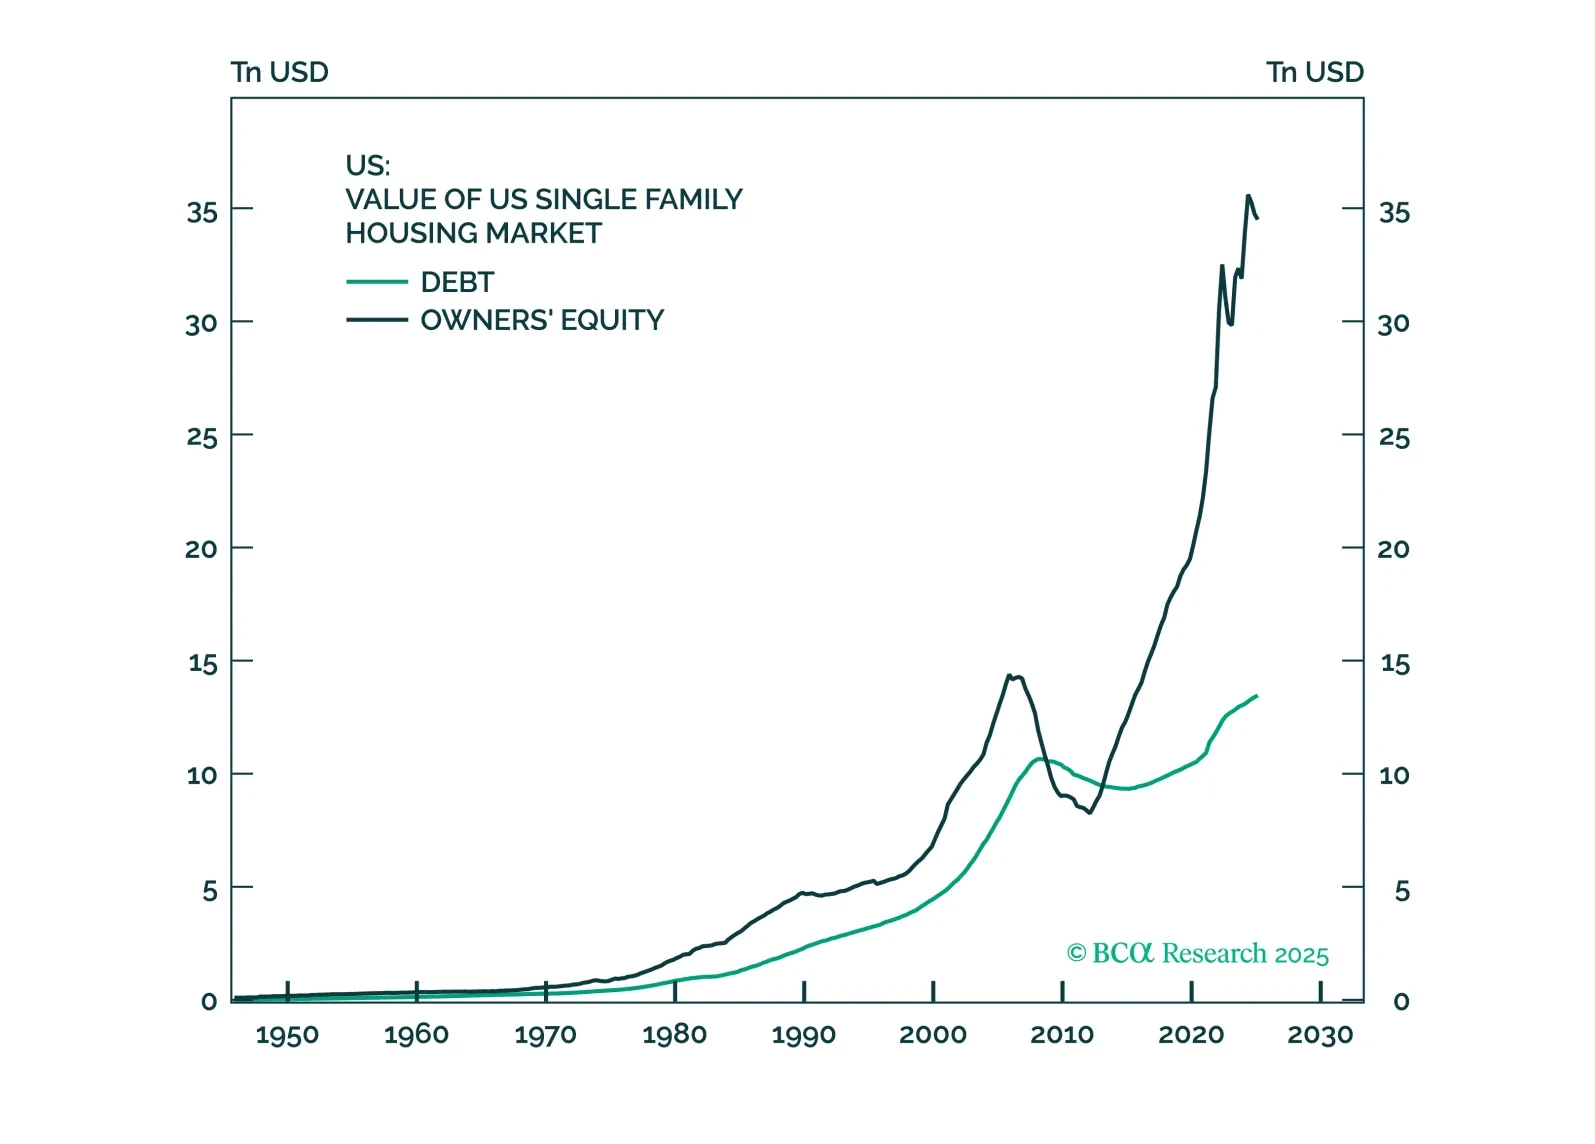
In the Alpha report, we maintain our bullishness on the equity market. We are optimistic that the cash-fueled cycle will evolve into a leverage-driven one, with the AI capex cycle acting as the "bridge" between the two. Our view is easily falsifiable. If the 10-year yield starts moving against us, we will pull the plug on the cycle. One reason to fret is that tariff revenue has now become critical to the equity bull market. Without it, bonds could riot.
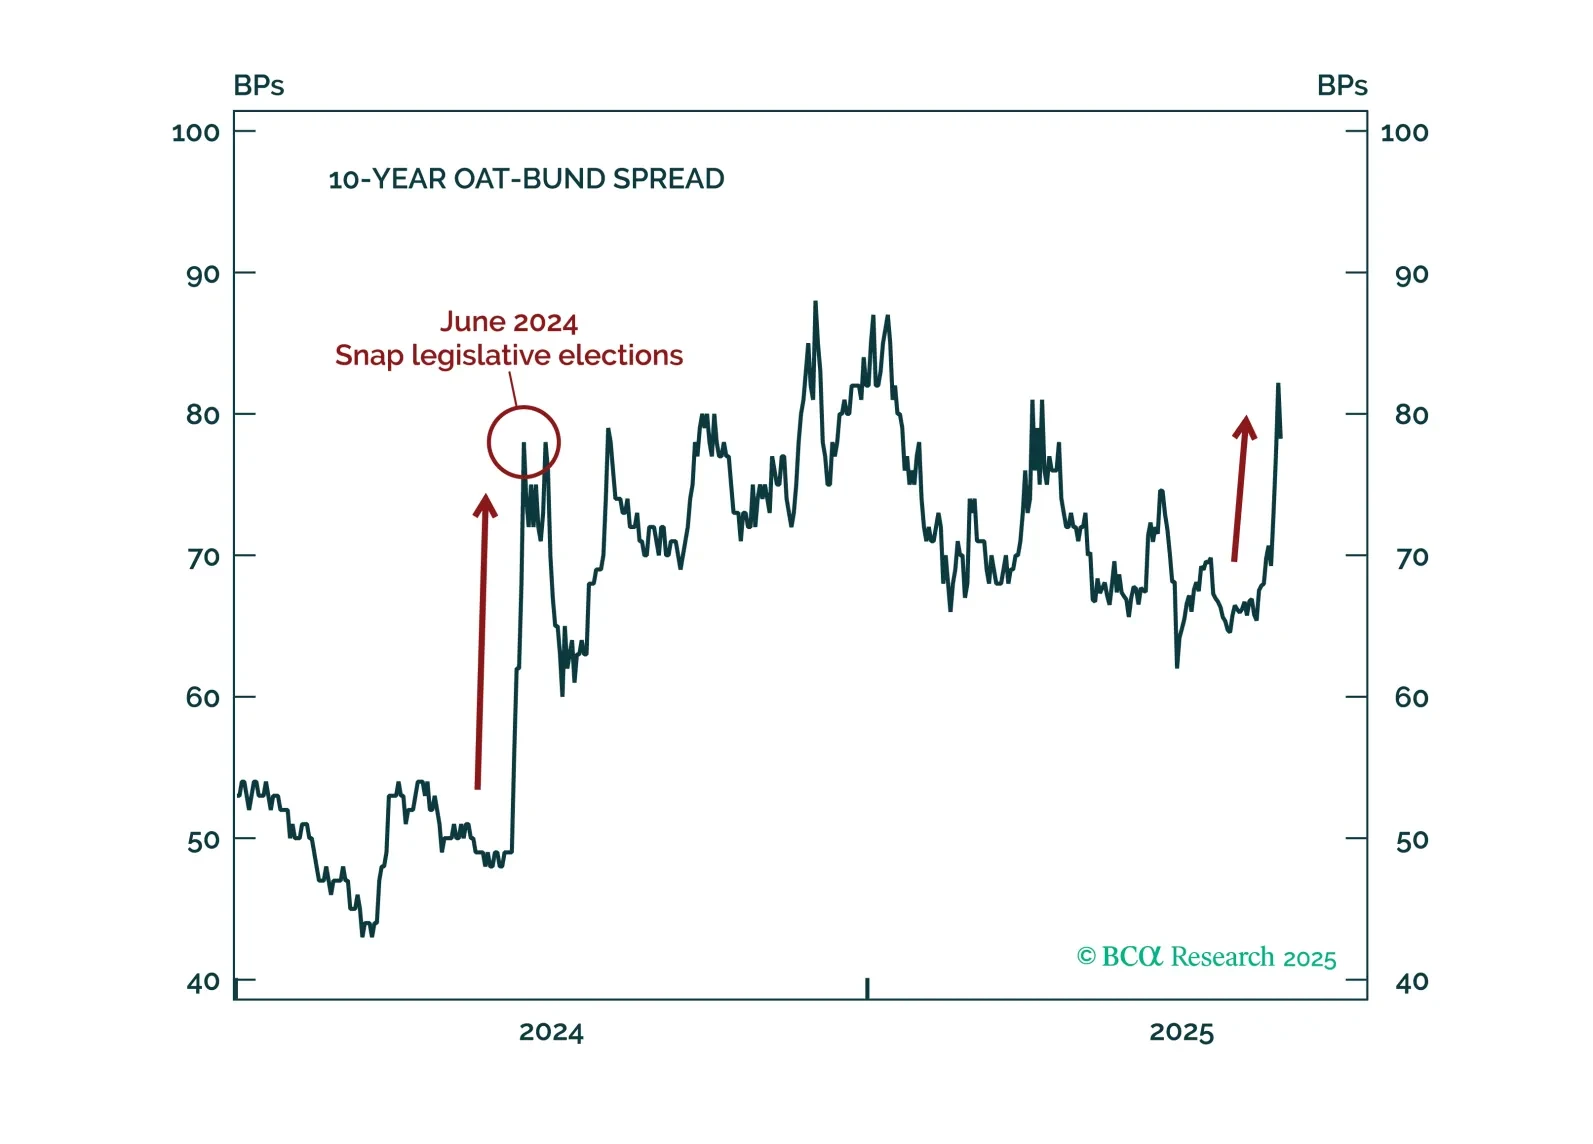
Political instability will persist in France as PM François Bayrou loses the confidence vote. The nomination of a new PM will not end the country’s political paralysis and will further fuel fiscal fears. Investors should remain underweight French OAT. French equities, especially French banks, should be bought on dips.
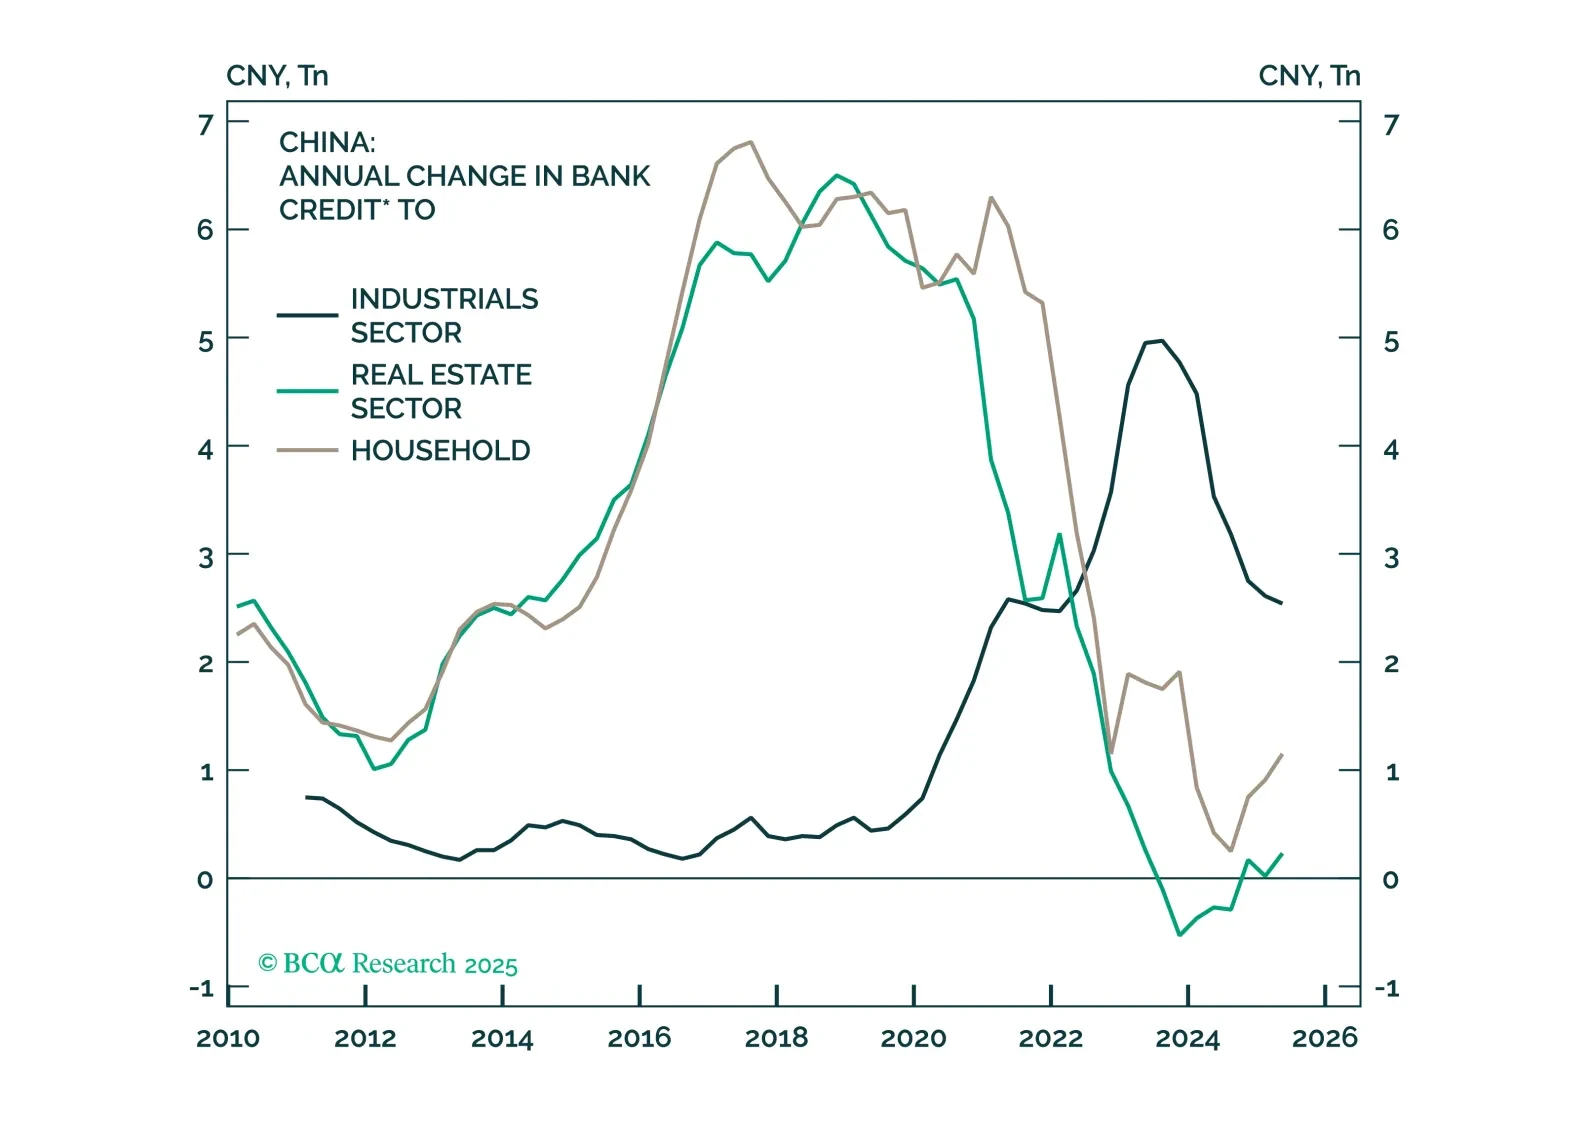
The US overconsumes and underproduces. China overproduces and underconsumes. There are early signs that this decades-old imbalance has peaked and is beginning to reverse. Upgrade the CNY to overweight.
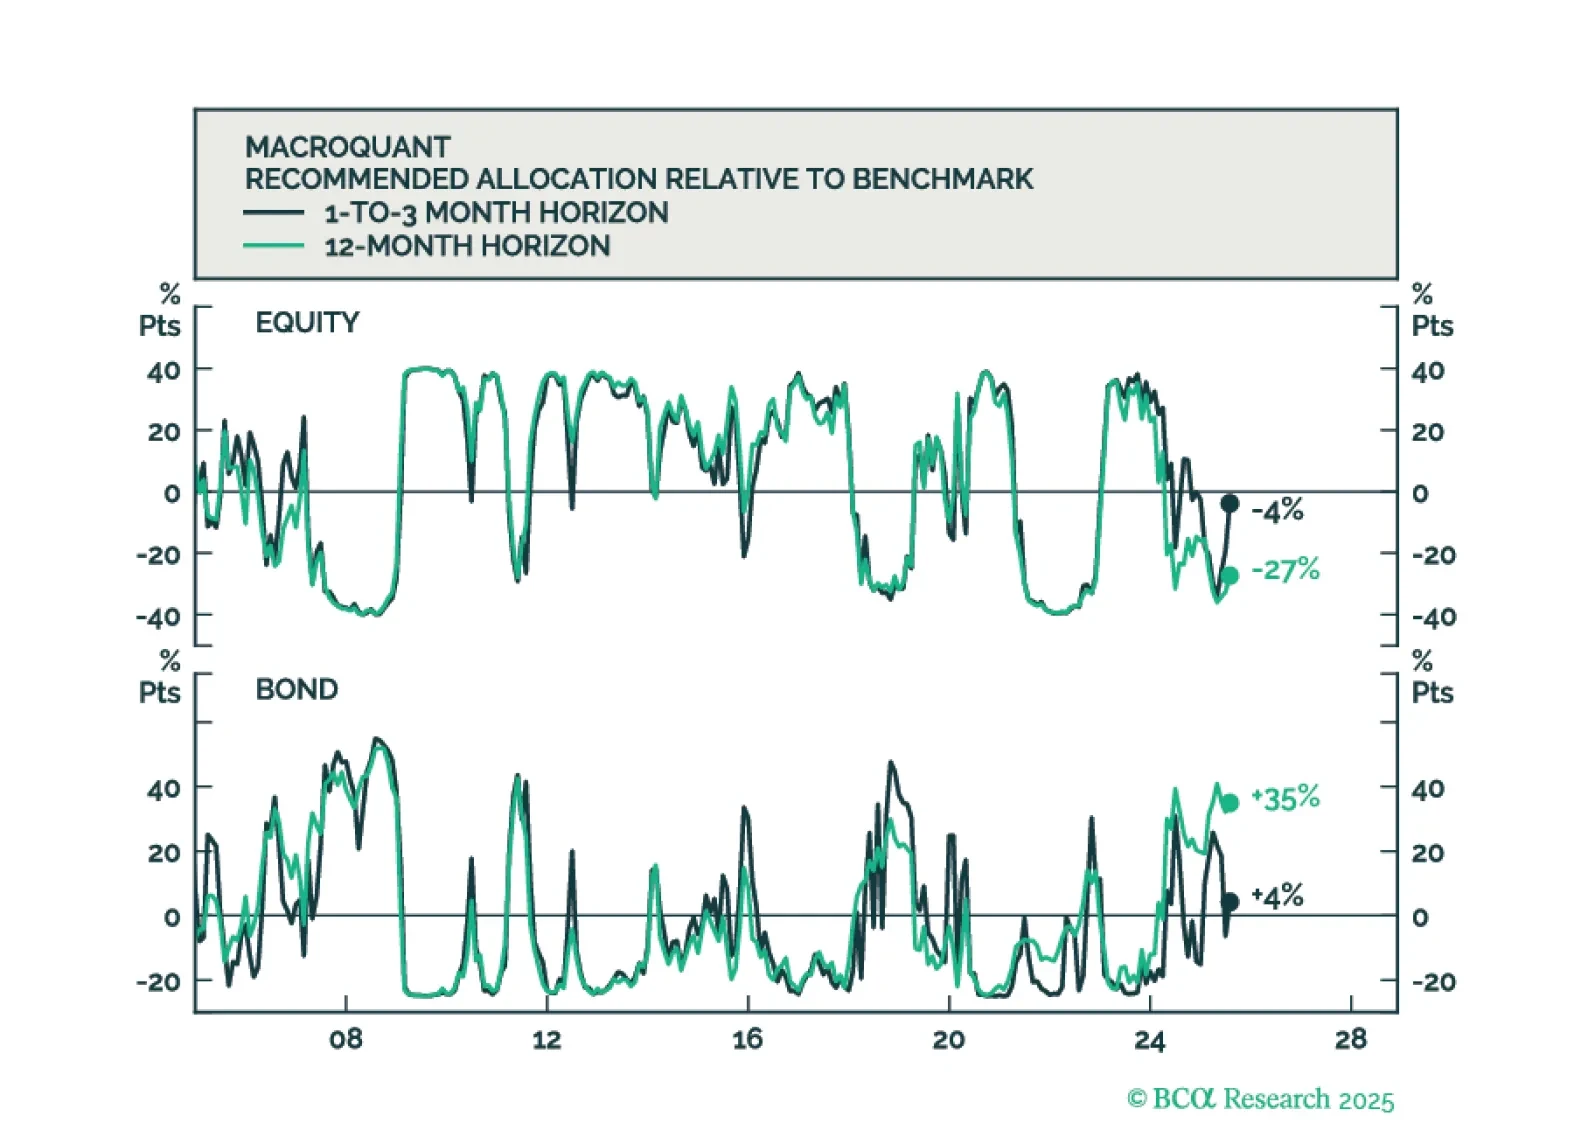
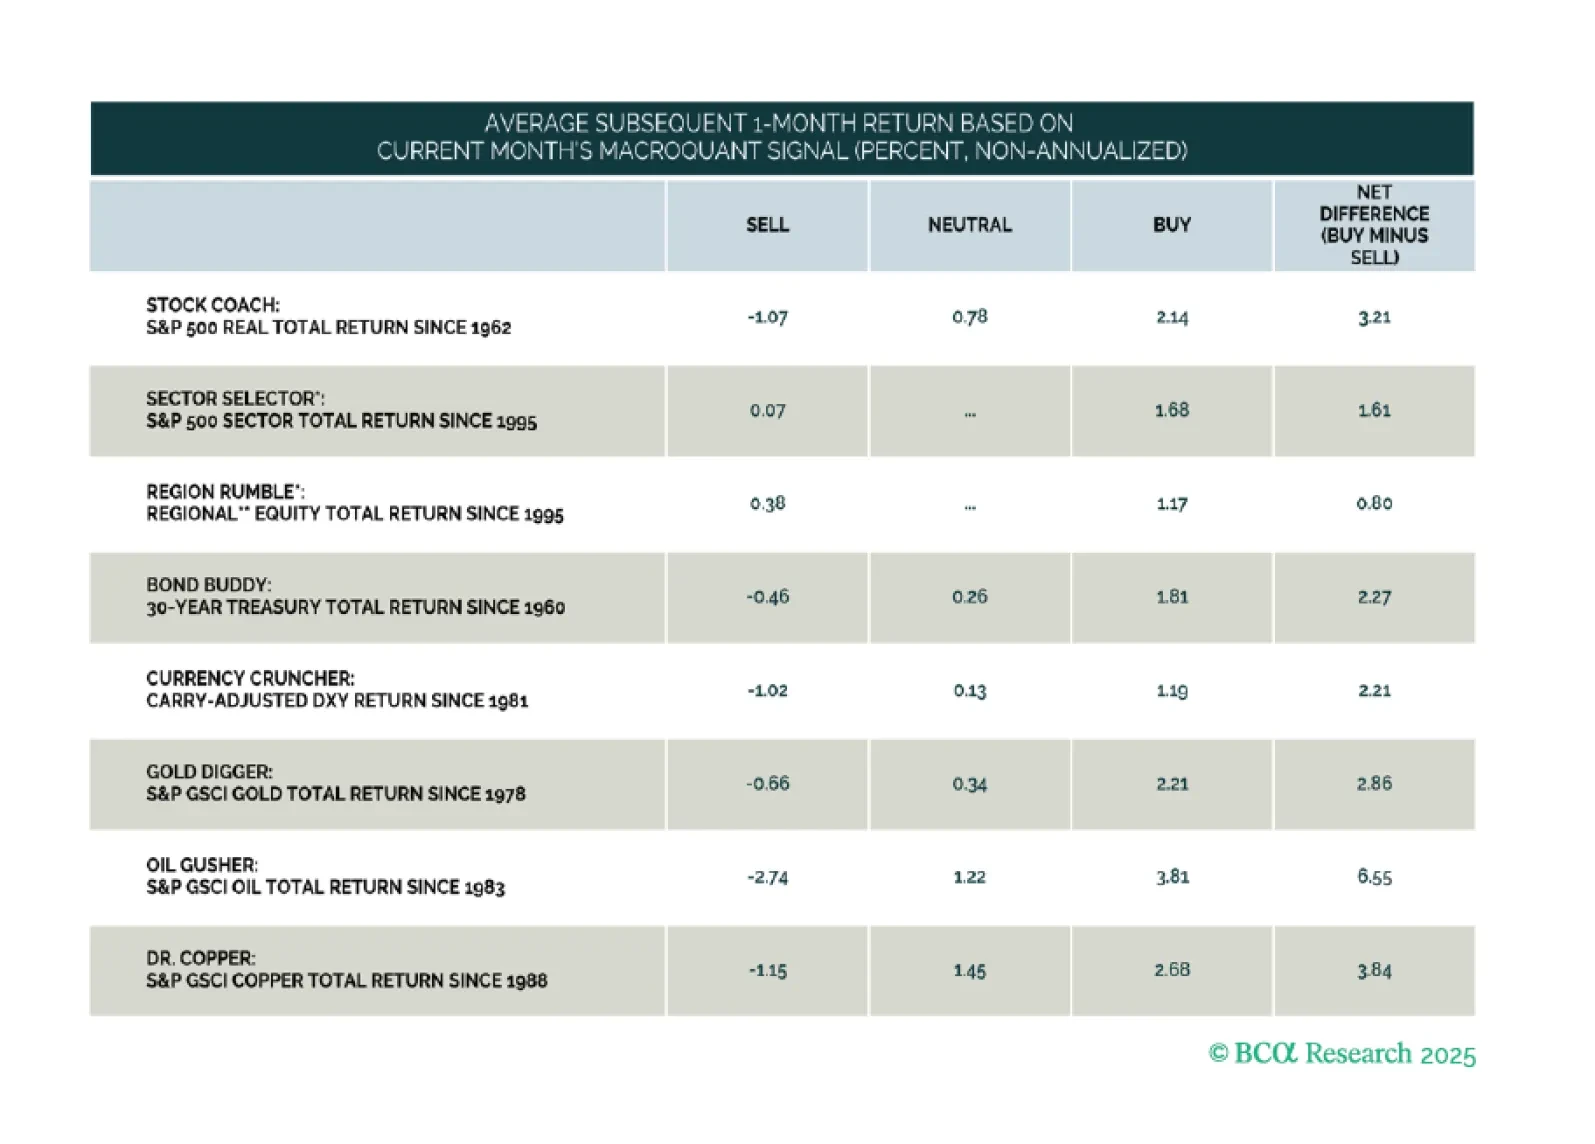
MacroQuant sees downside risks to stocks over a long-term horizon but is not yet saying that we are at imminent risk of an equity bear market.
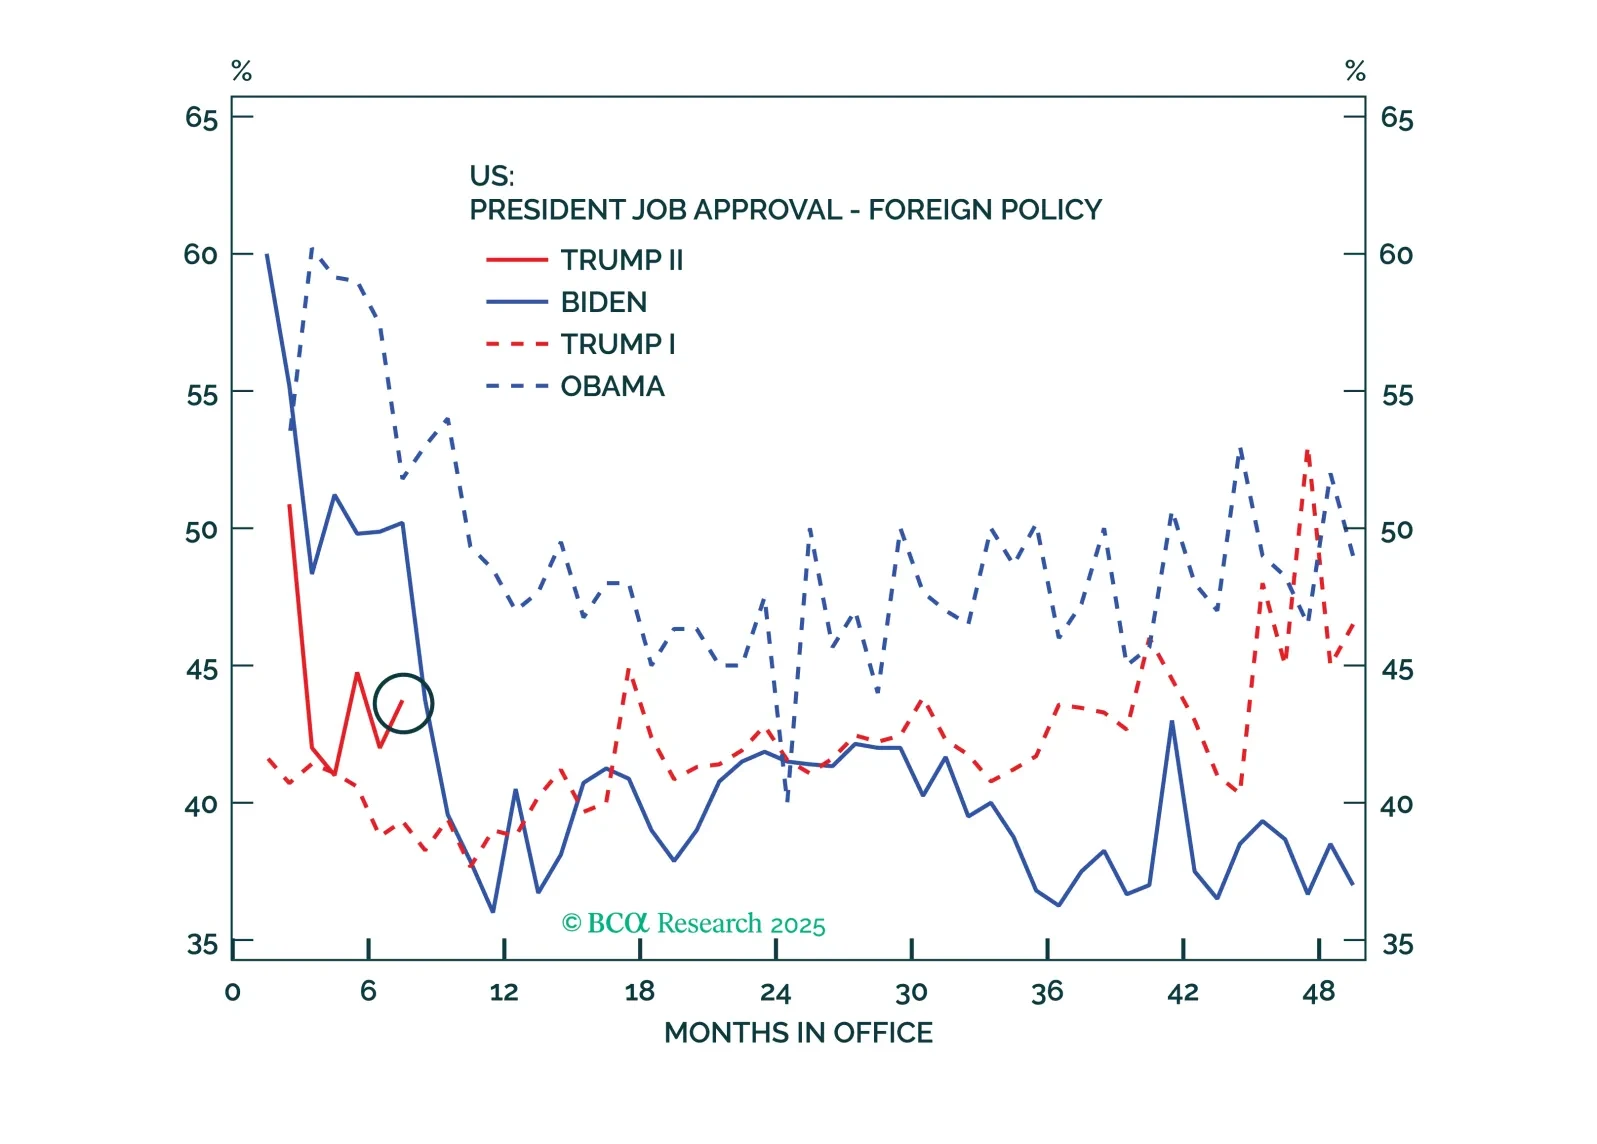
Trump, the Fed, the Russo-China bloc, Venezuela, and France are all seeing developments that imply some contrarian tactical views: Long USD, overweight US versus Europe, overweight Europe versus China, and short oil.
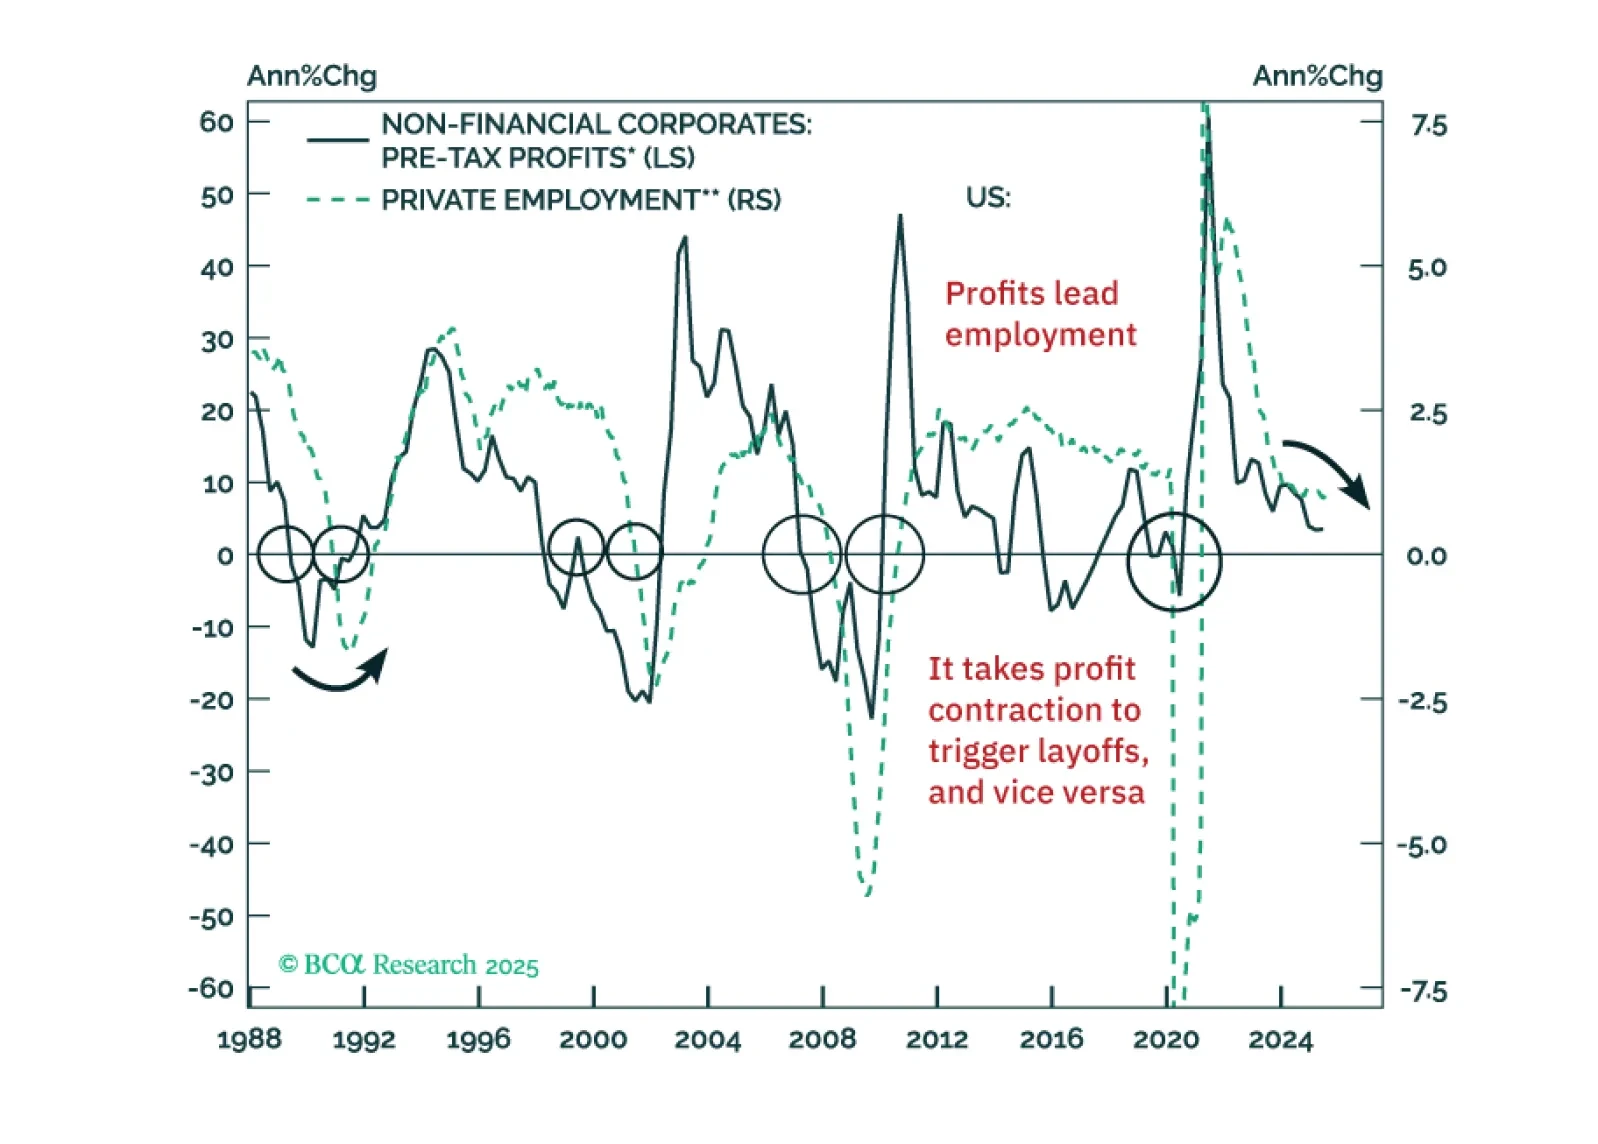
We see two risks that could spoil the rally in US risk assets: (1) a tariff-driven stagflation, and (2) a US Treasury tantrum. Our negative view on EM risk assets is primarily driven by the outlook for global trade, which is set to shrink in Q4 this year.