Latest from BCA Research
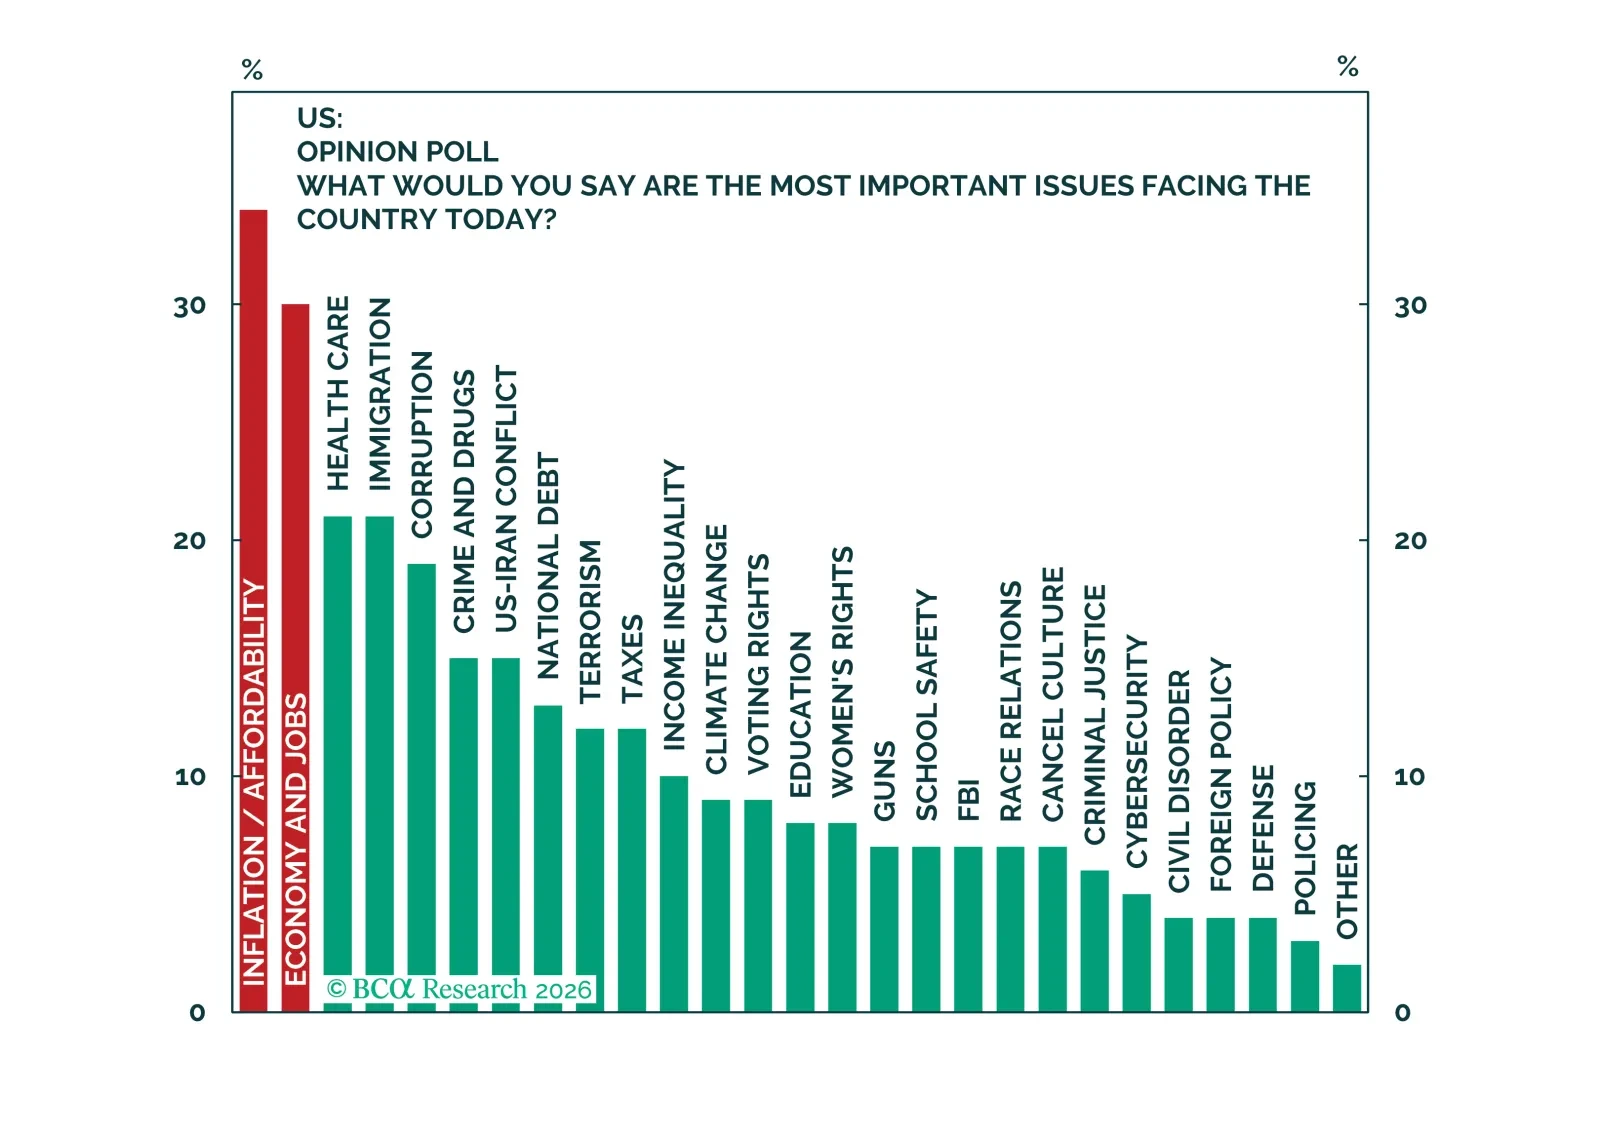
In our last update on the Iran-US conflict, we noted that both sides in the conflict (all three, if we include Israel) were “coloring inside the lines.” By that we meant that they were abiding by the “red lines” of kinetic activity established in the heat of the first iteration of the Iran conflict. Specifically, we noted that investors should watch carefully for any sign that attacks were spreading beyond military facilities.
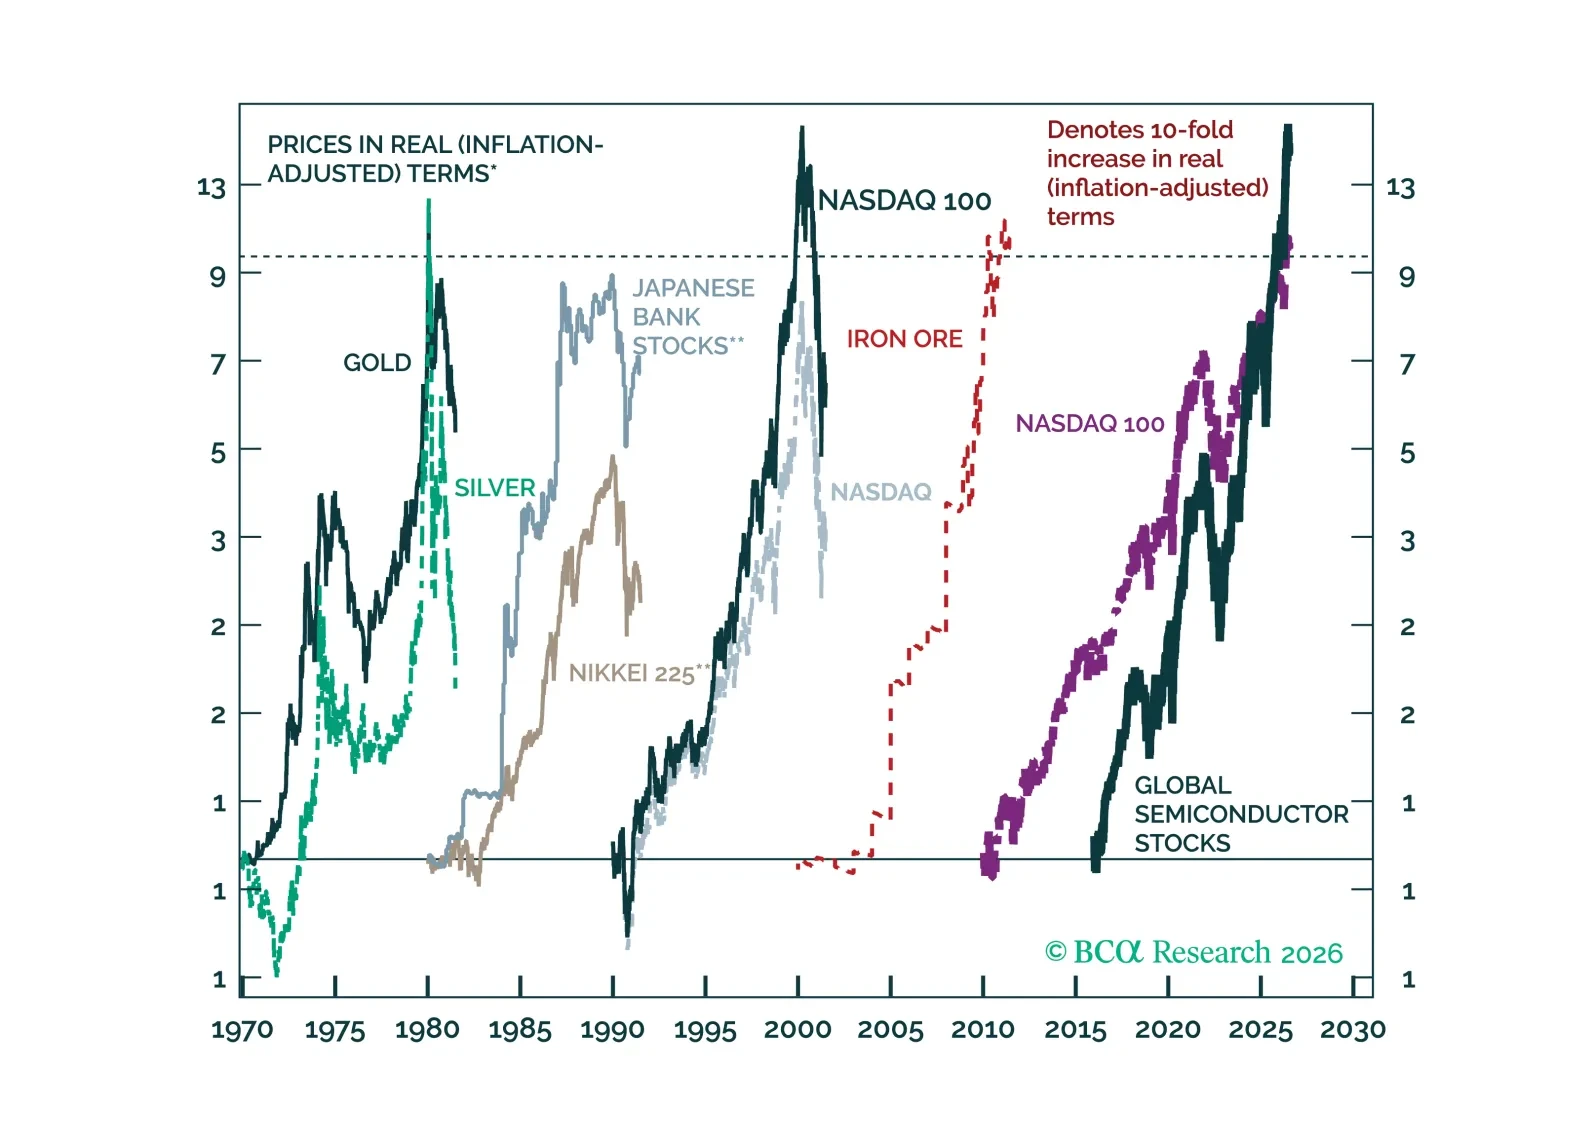
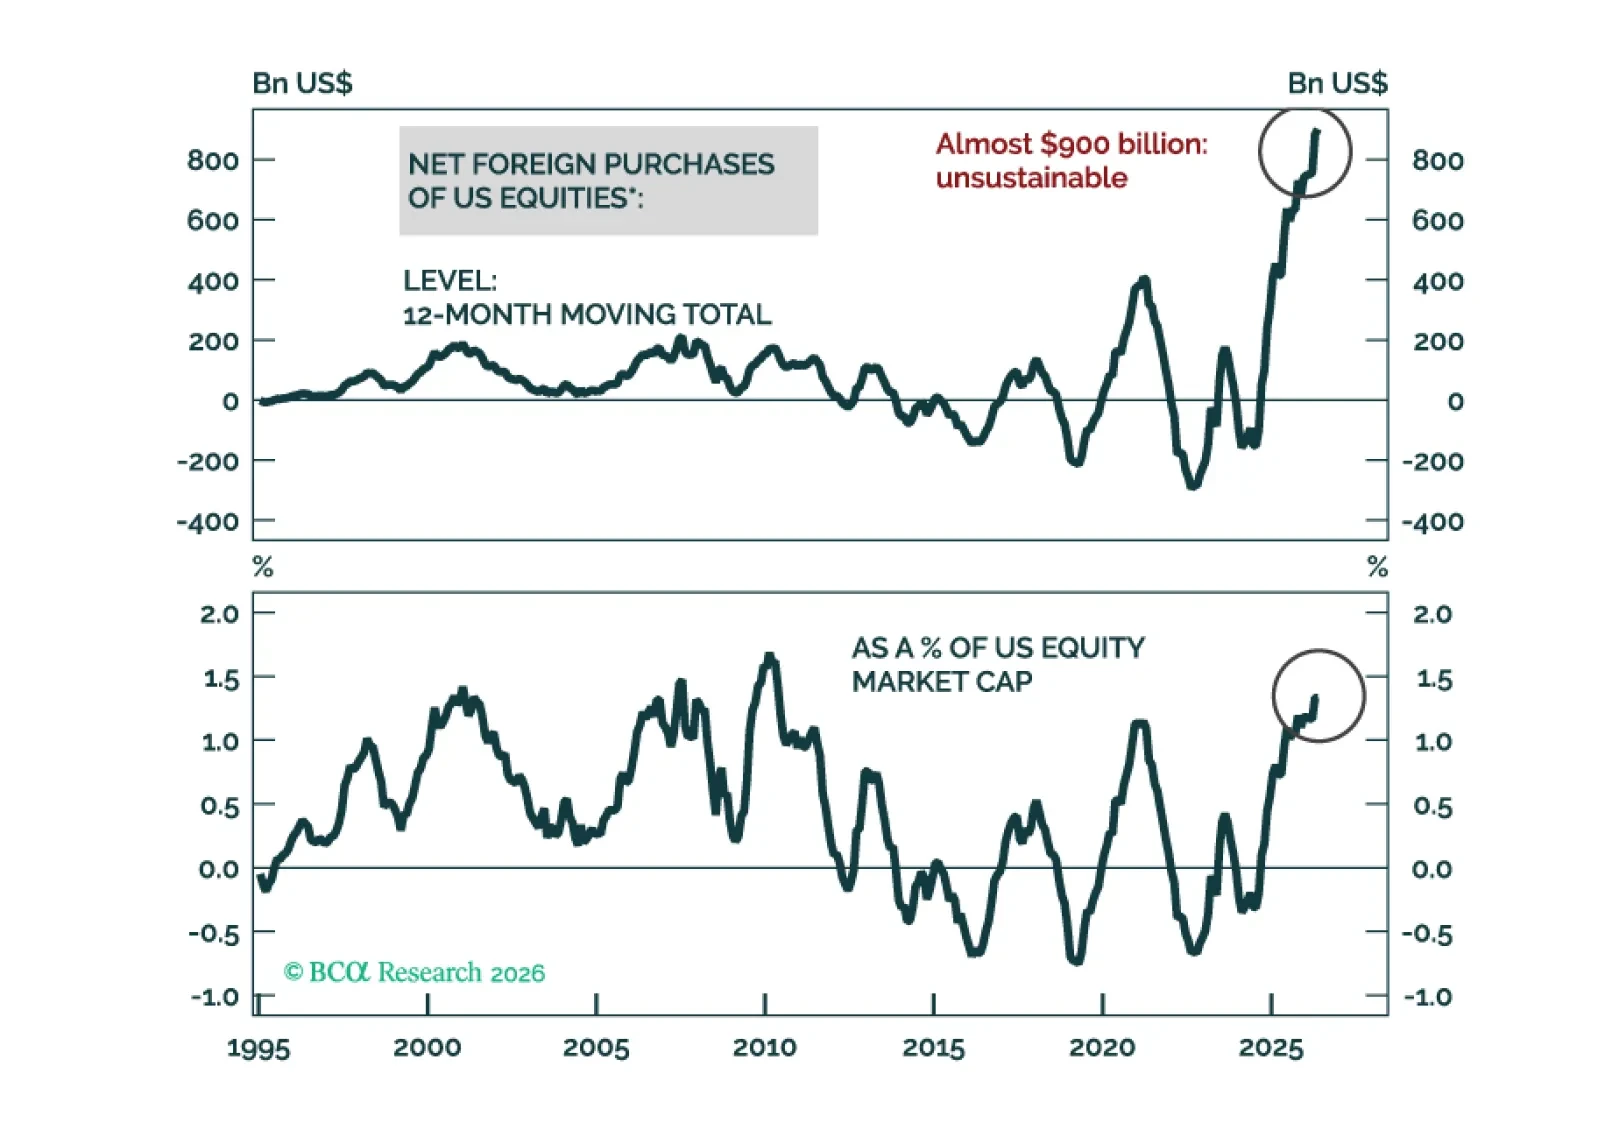
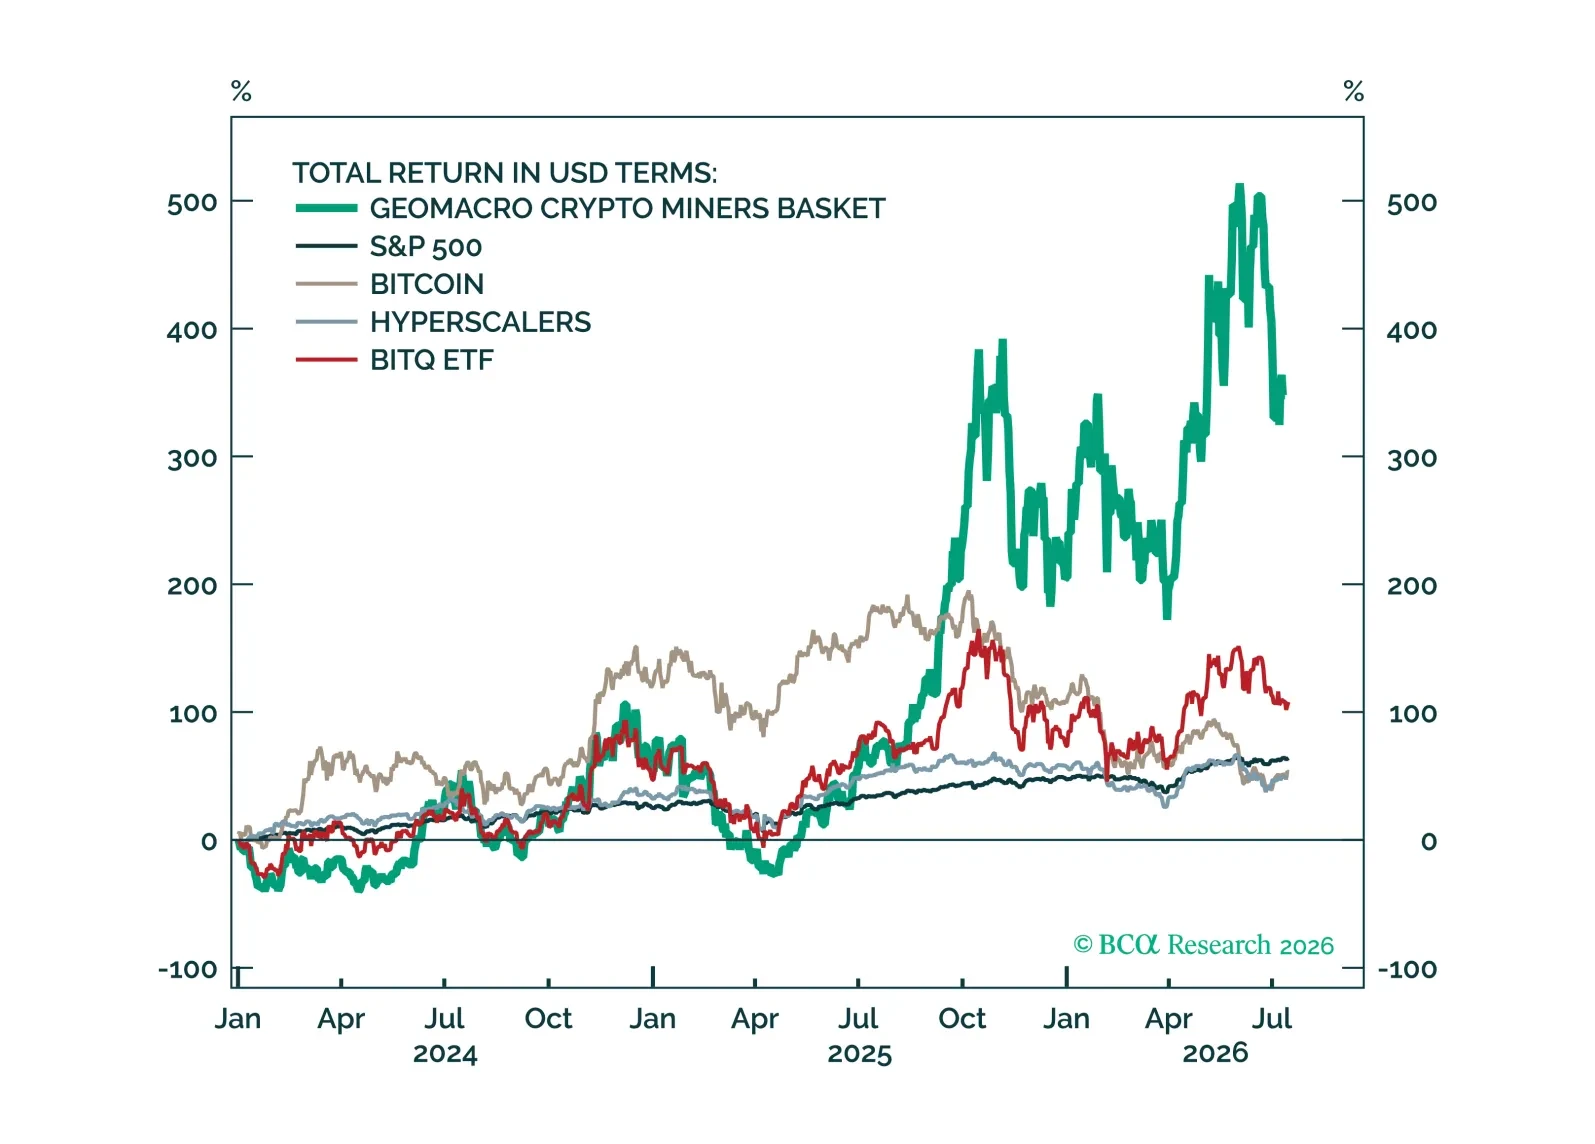
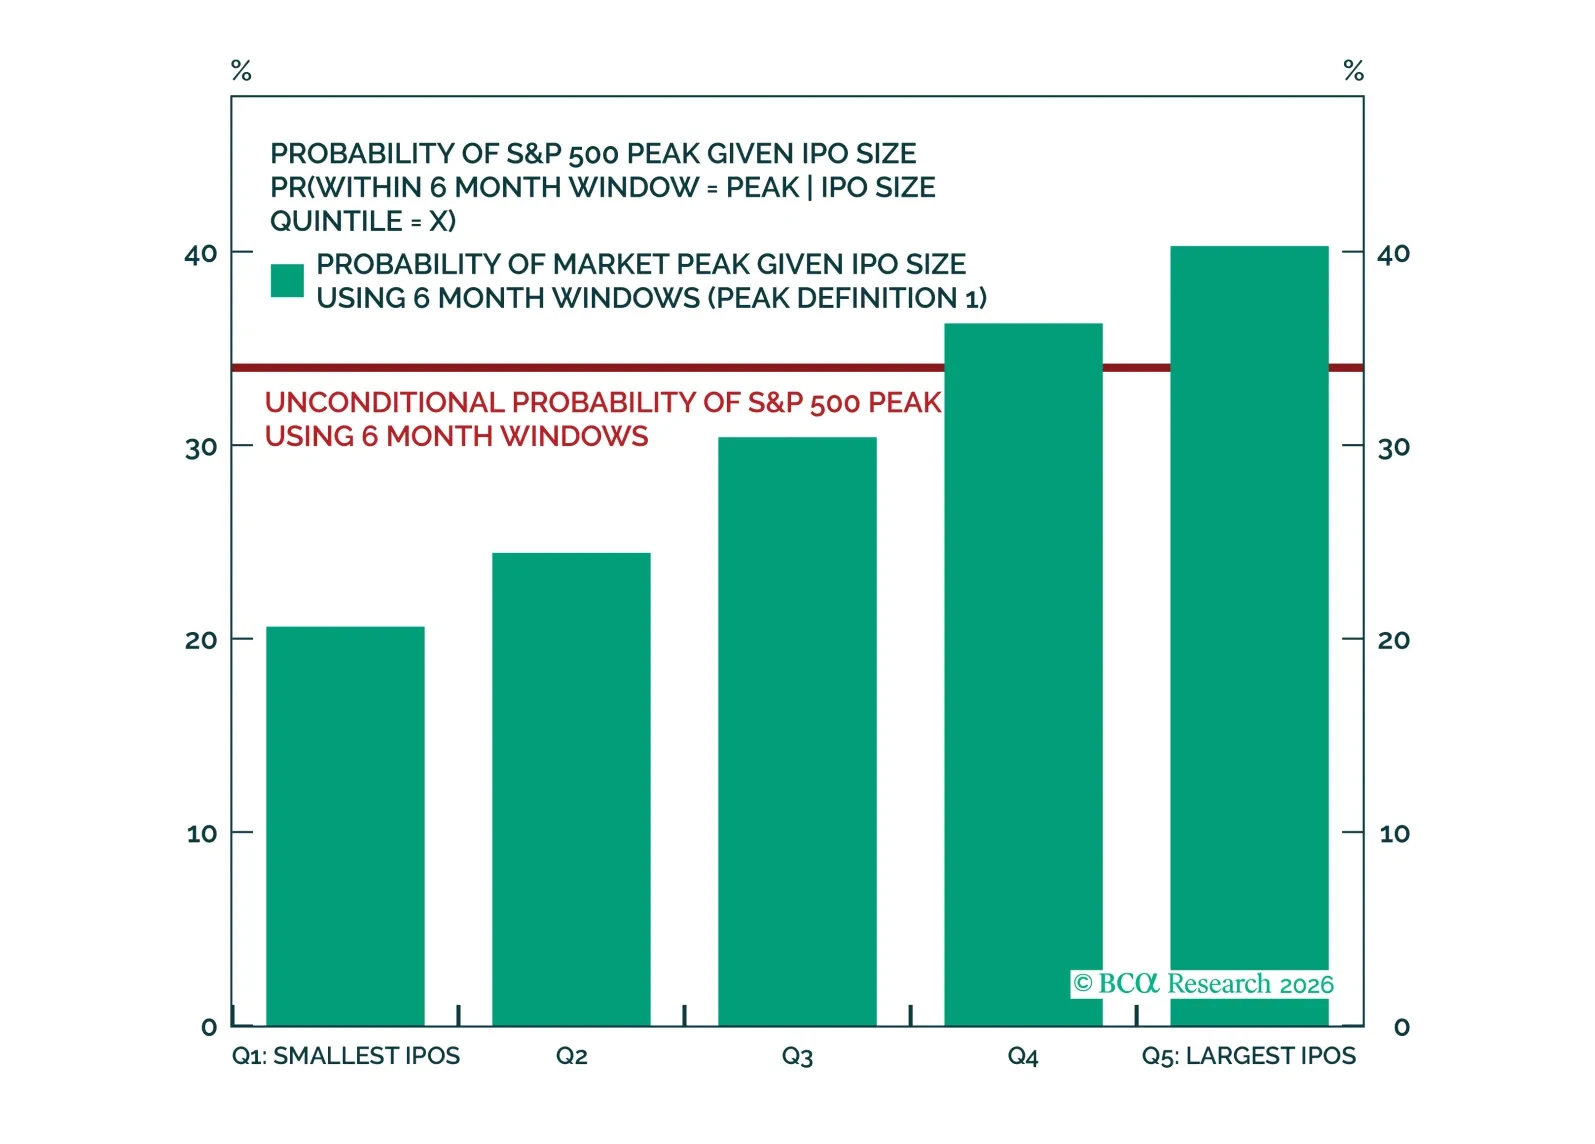
We stick to the view that geopolitical risk has peaked. The US and Iran tensions will increase oil prices, but below a level that will matter for the market. With global liquidity ample, private sector leverage low, and inflation peaking, bears are holding onto an epic collapse of the AI capex to short stocks. Eventually, the capex cycle will end in tears. That much history teaches us. But not yet.
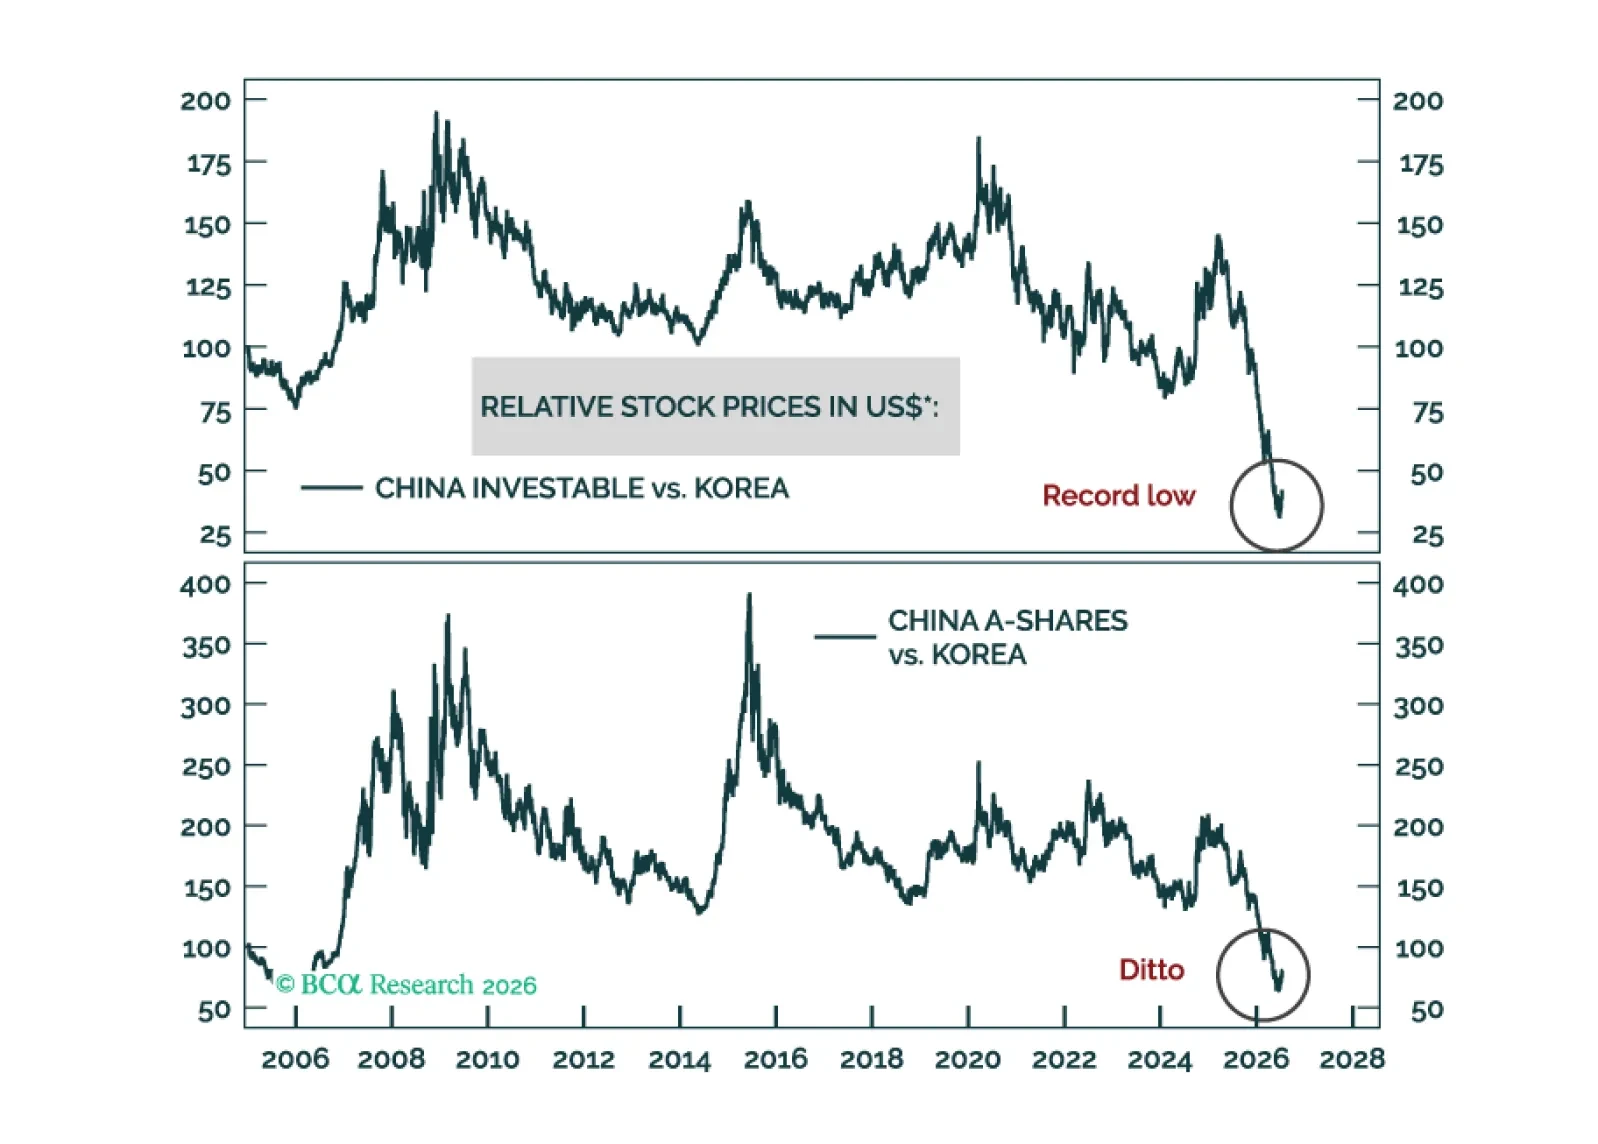
As a short-term (0-3 months) trade, go long an equal-weighted basket of Chinese Investable and A-shares / short the KOSPI. This is a bet on mean reversion. We do not recommend that medium- and long-term investors implement this strategy.
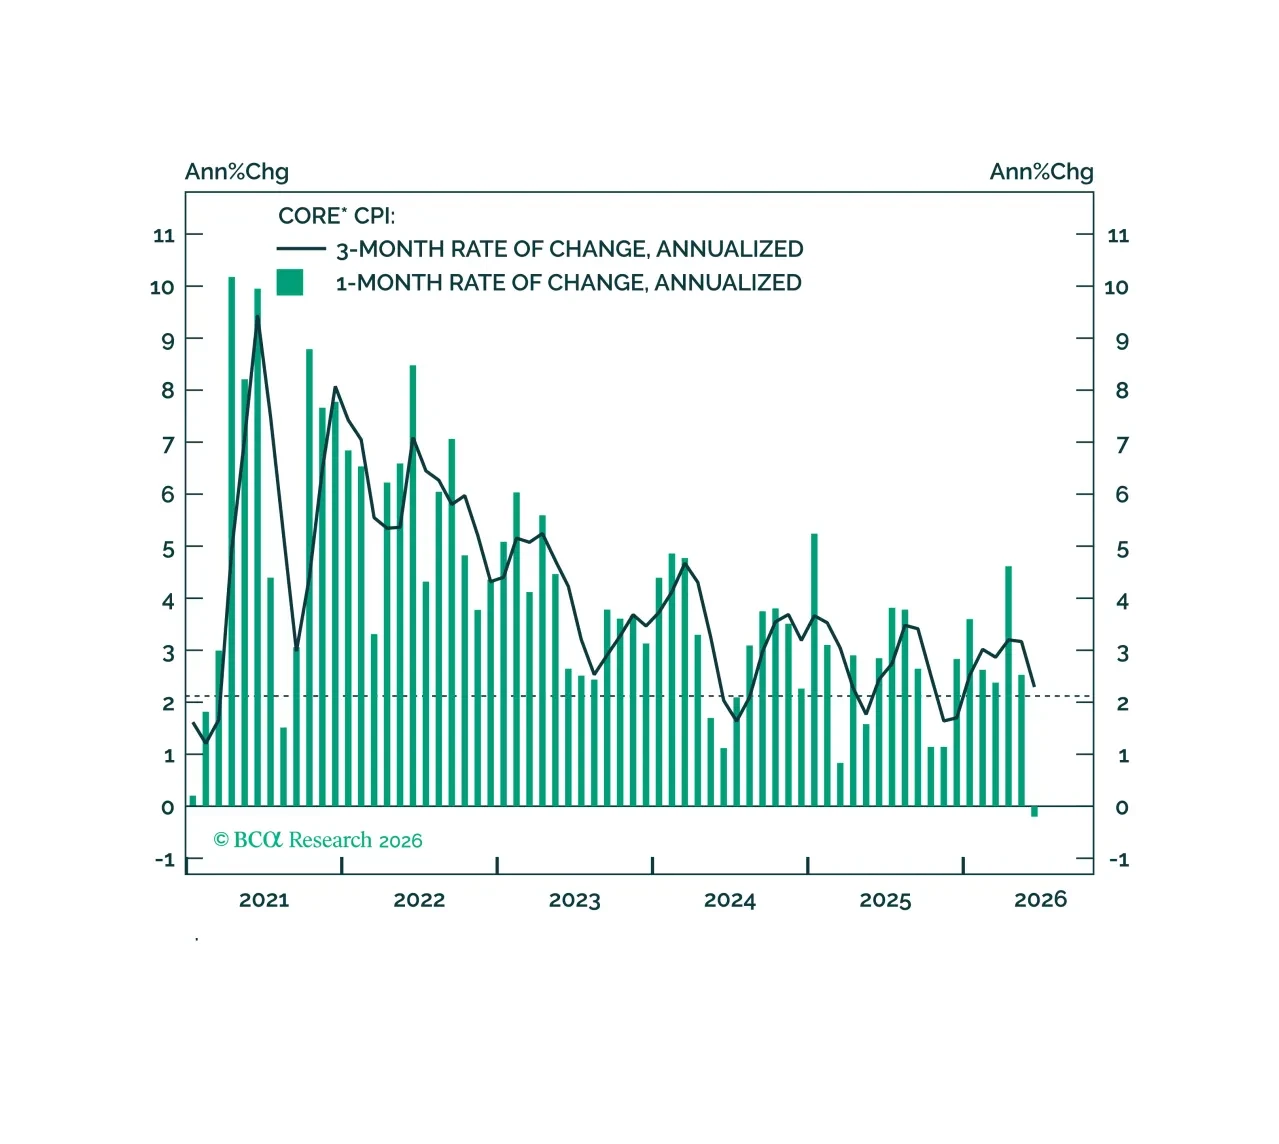
June’s low CPI reading rules out a July rate hike, but September is still on the table.
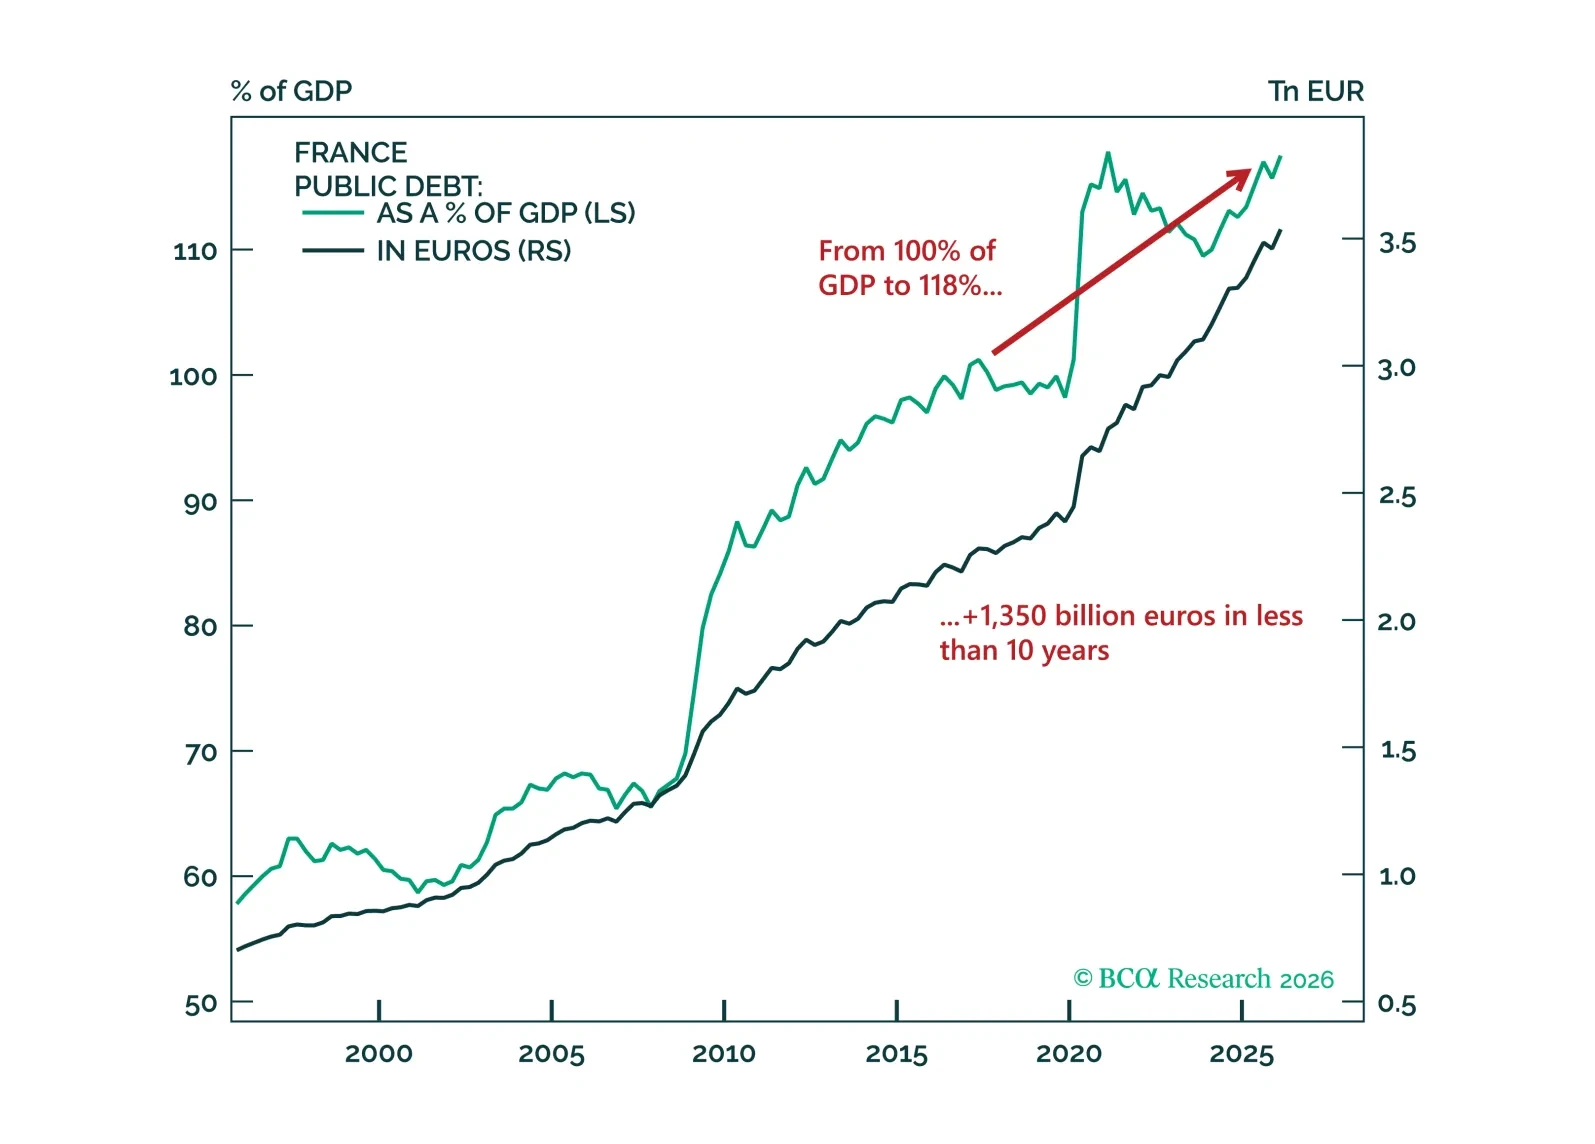
We wish all our French clients Bonne Fête Nationale! The rest of the world knows the holiday by its other name, Bastille Day. It is fitting, therefore, that we publish today GeoMacro Beta report on the coming political earthquake in France.
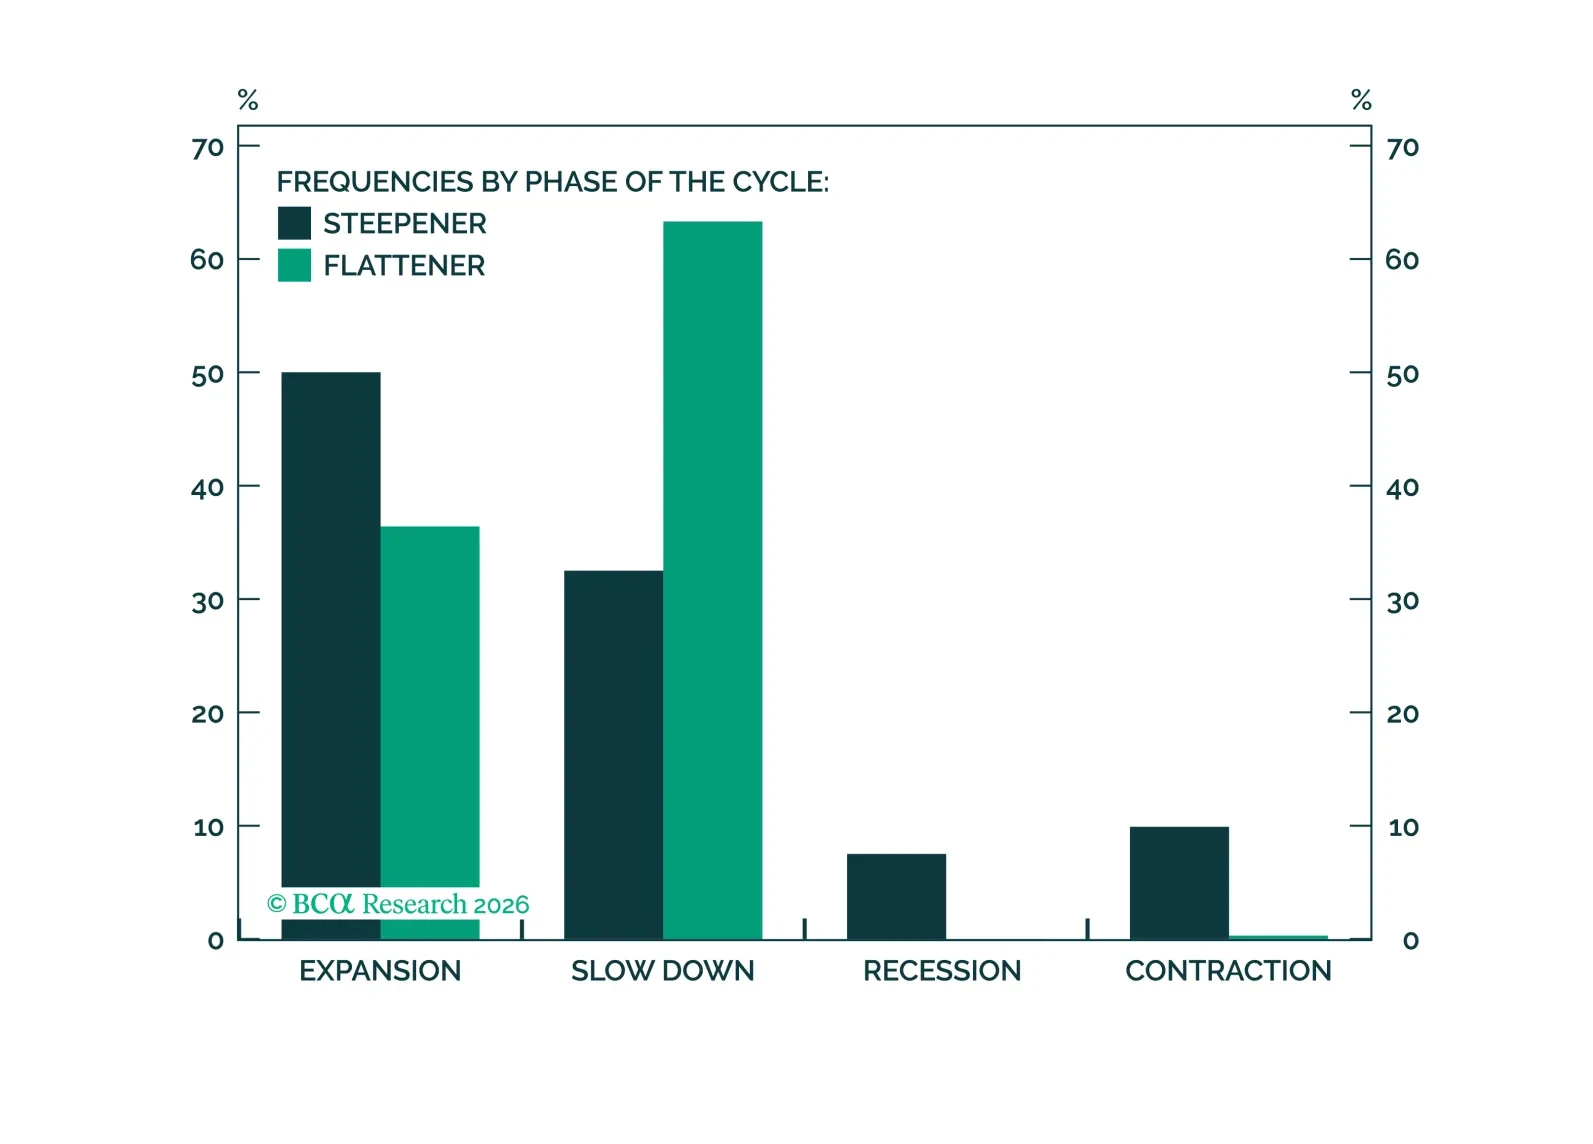
History suggests that the equity impact of rate moves depends heavily on the stock/bond correlation regime, and today’s positive correlation regime leaves the bond market as the main risk to equity multiples.