 GeoMacro
Find out more
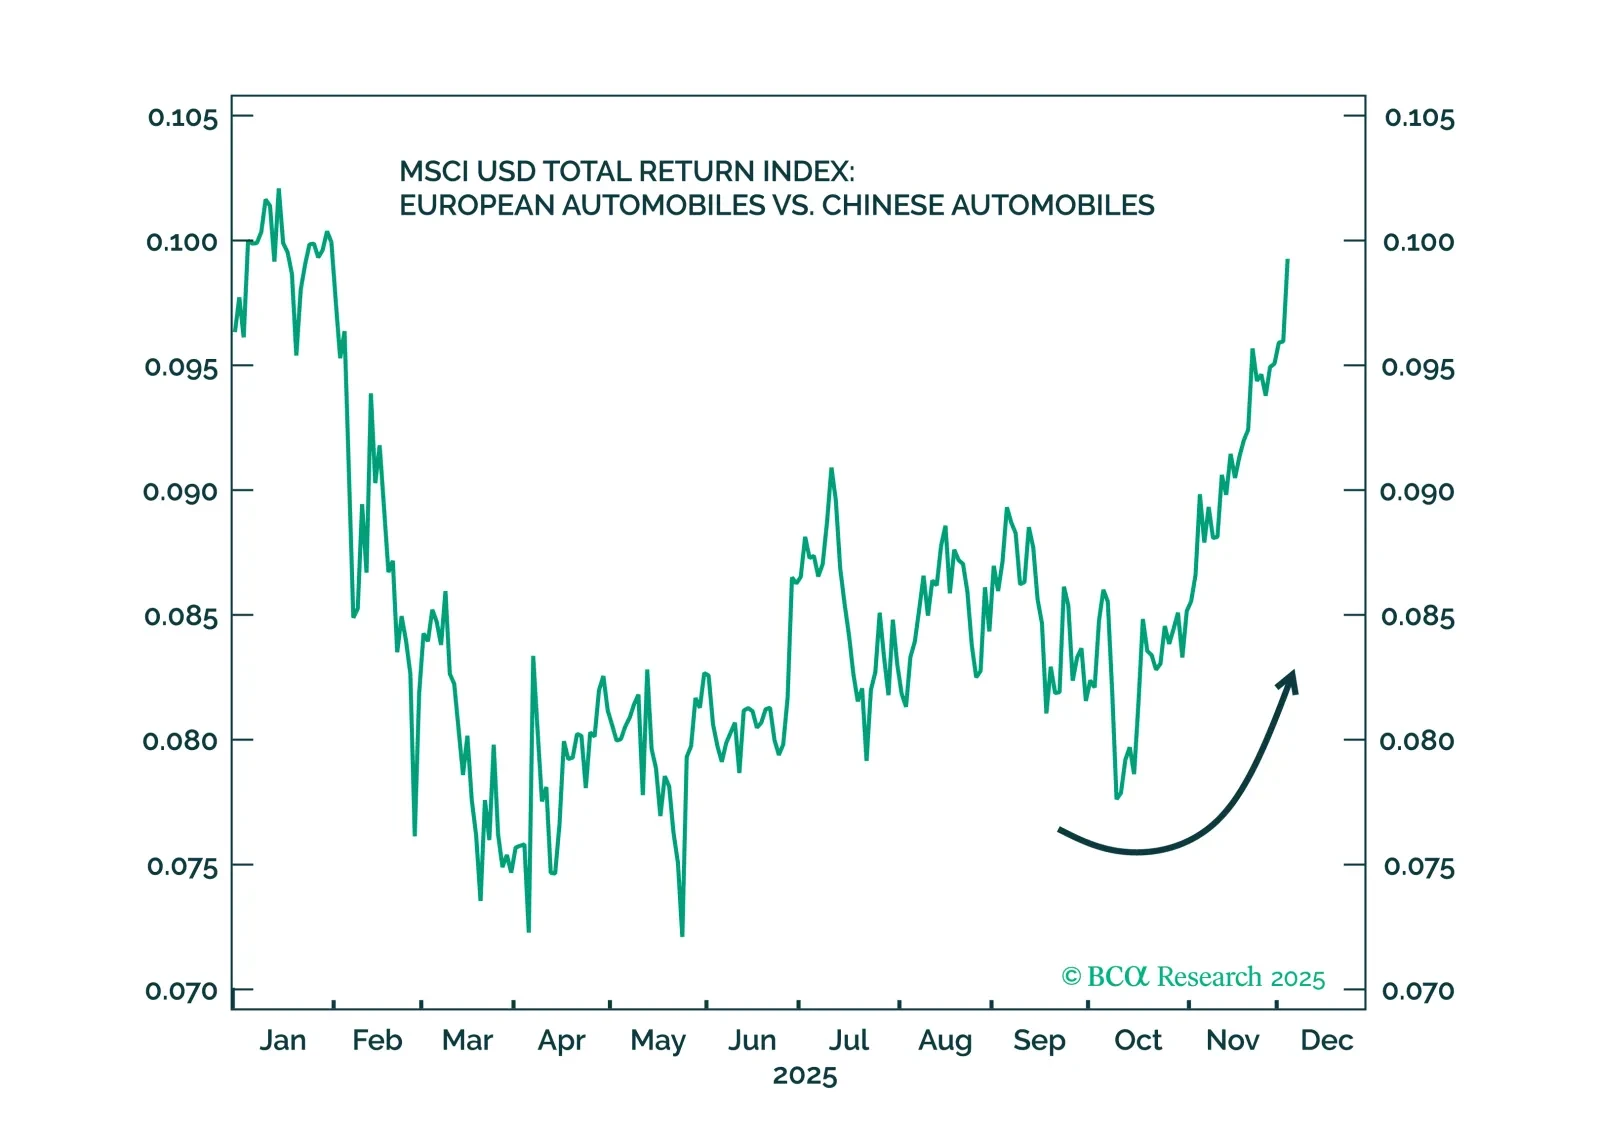
We got Trump's tariff shock and backtracking correct and predicted Israel's attack on Iran. But we missed the China rally — and there is still no Ukraine ceasefire.
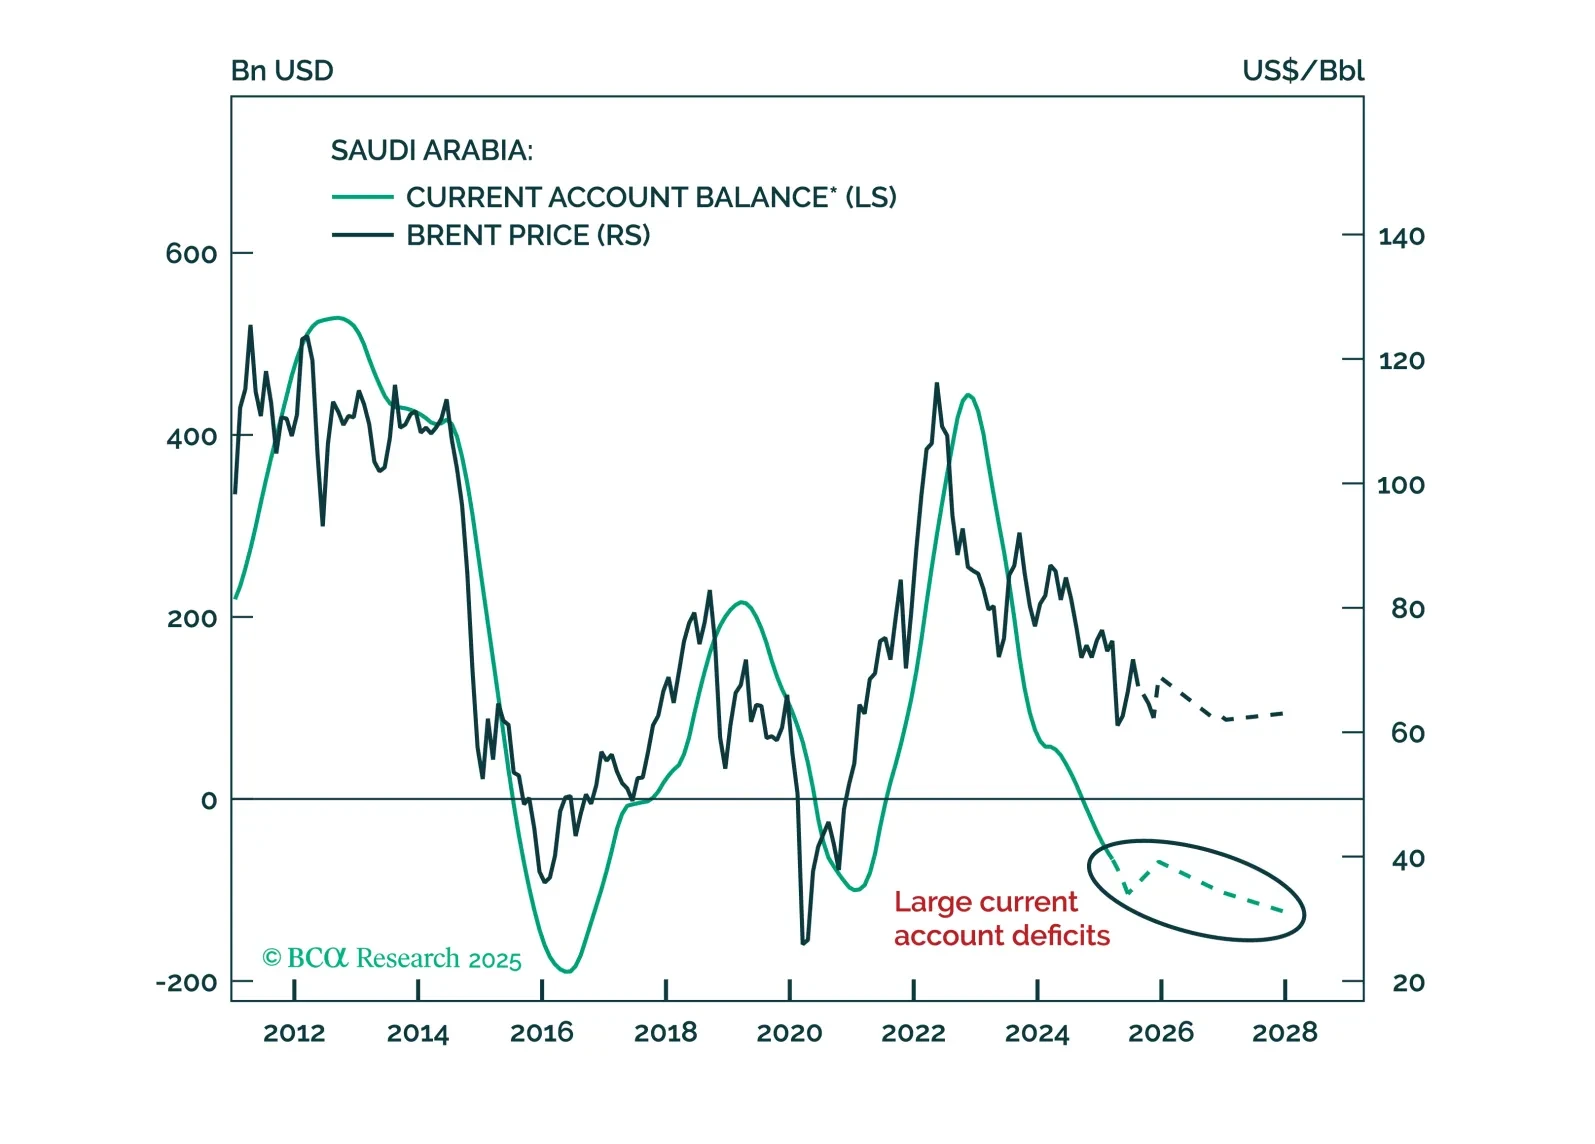
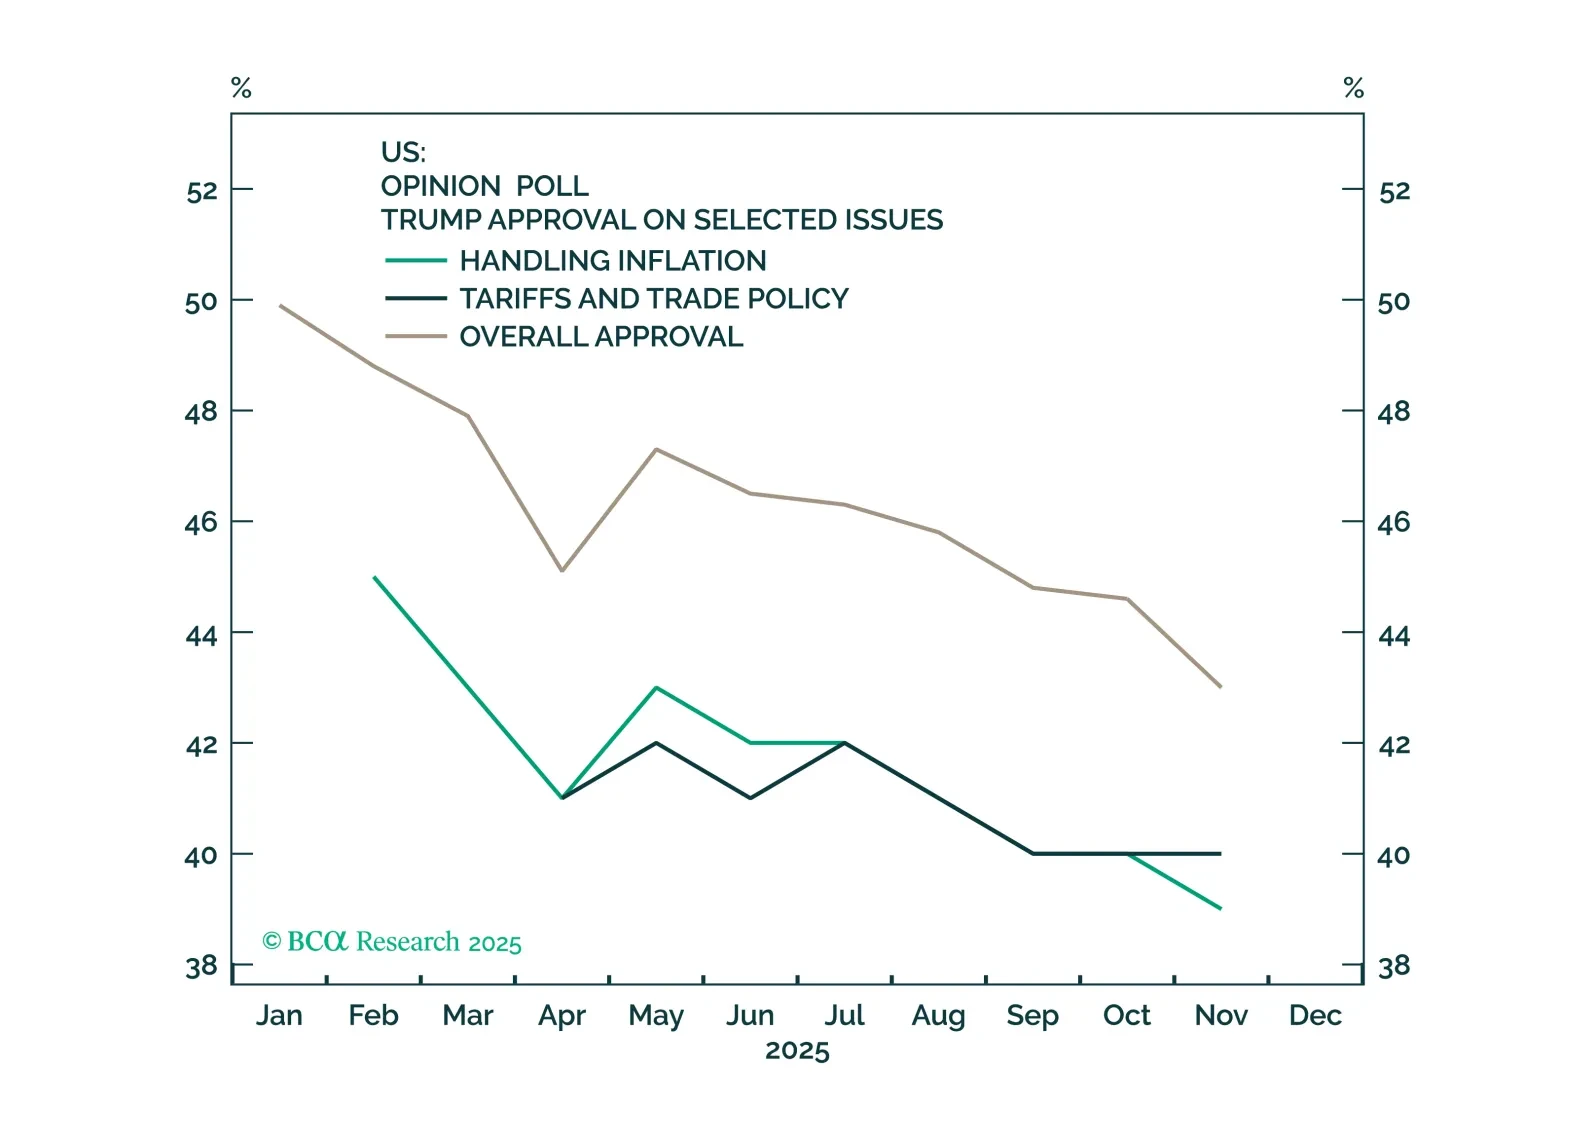
On purely macroeconomic terms, the US economy appears to be heading towards a recession. But the whole point of our framework – GeoMacro – is to forecast the interplay between politics, geopolitics, and macro. The White House is taking control of the Fed in 2026 and, together, they will look to re-lever the US consumer.
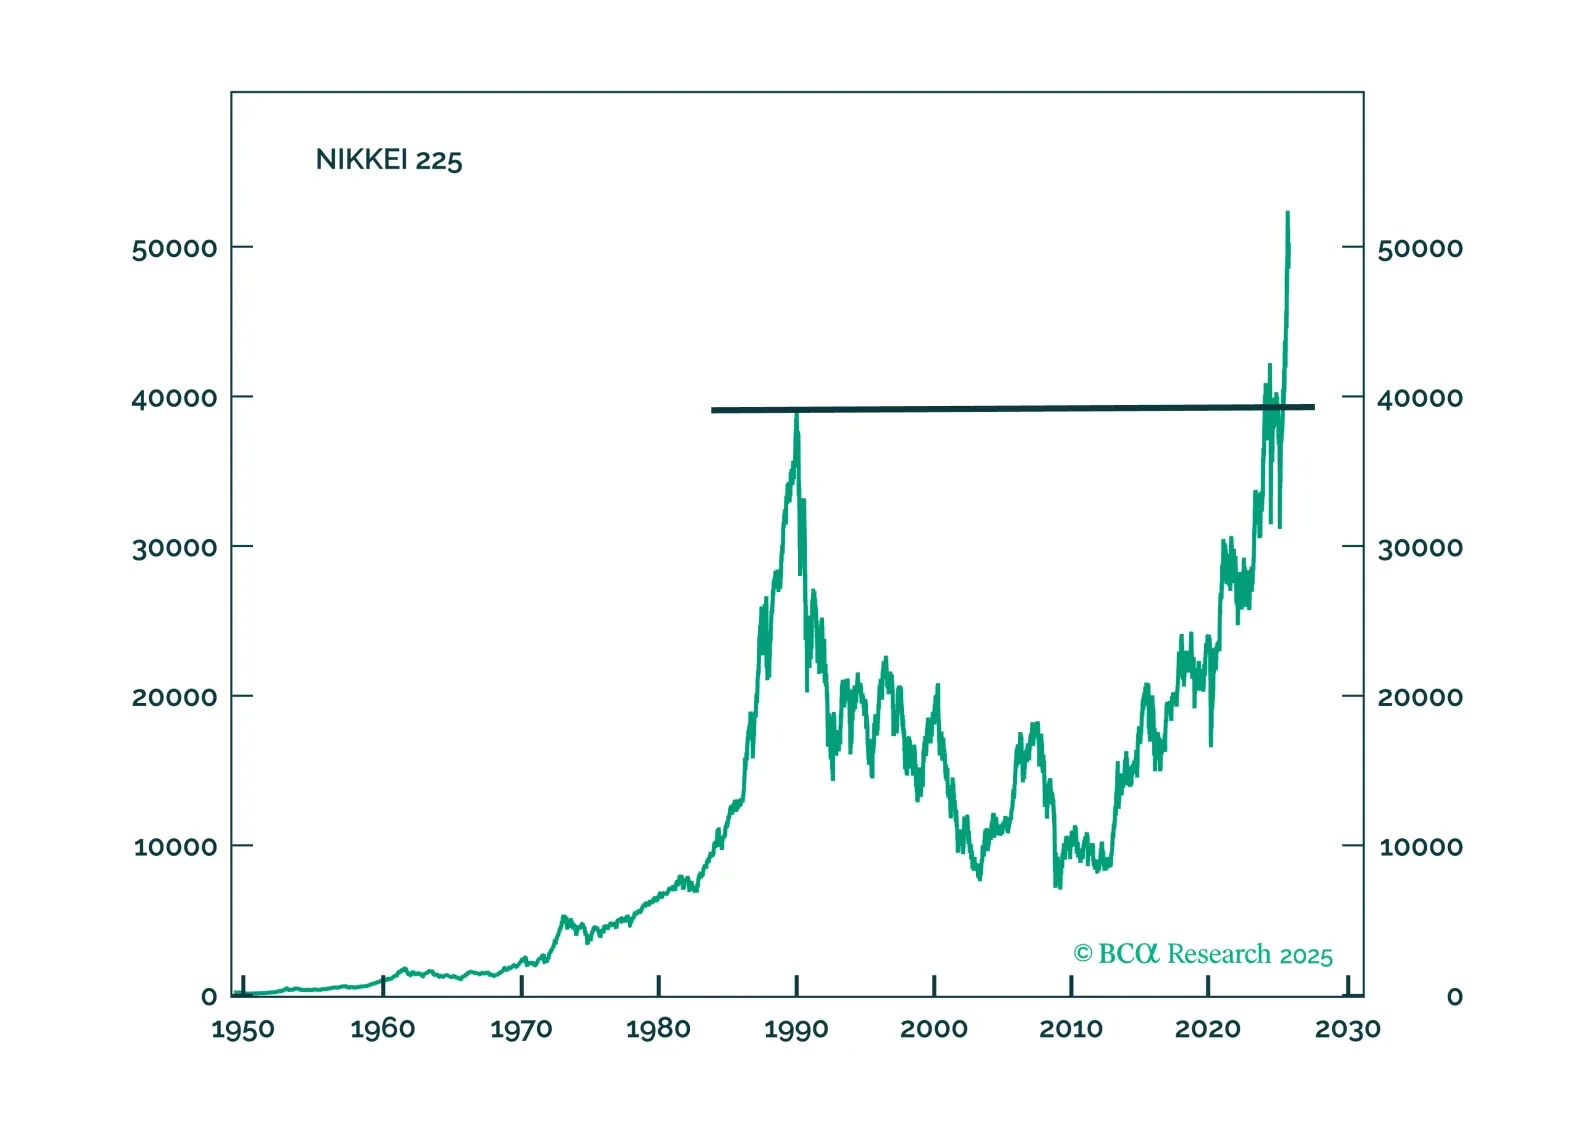
Japanese financial assets will finally have unfettered access to outsized returns. This performance will come in fits and starts, but we are comfortable laying our cards down on buying the yen, and Japanese industrial stocks.
The real reason behind the overt support by the US of Argentina’s experiment is far less exotic and yet also far more lucrative for global investors.
Our conclusions from 2019 were on point. We correctly predicted the fiscal and monetary deluge in 2020 and the subsequent rise in fiscal deficits. Now that we are where we are, someone is going to have to pay for it all. Especially as America's income inequality outcomes are just as bad as ever.
What should investors take from this flurry of diplomatic activity ahead of the US Thanksgiving holiday?
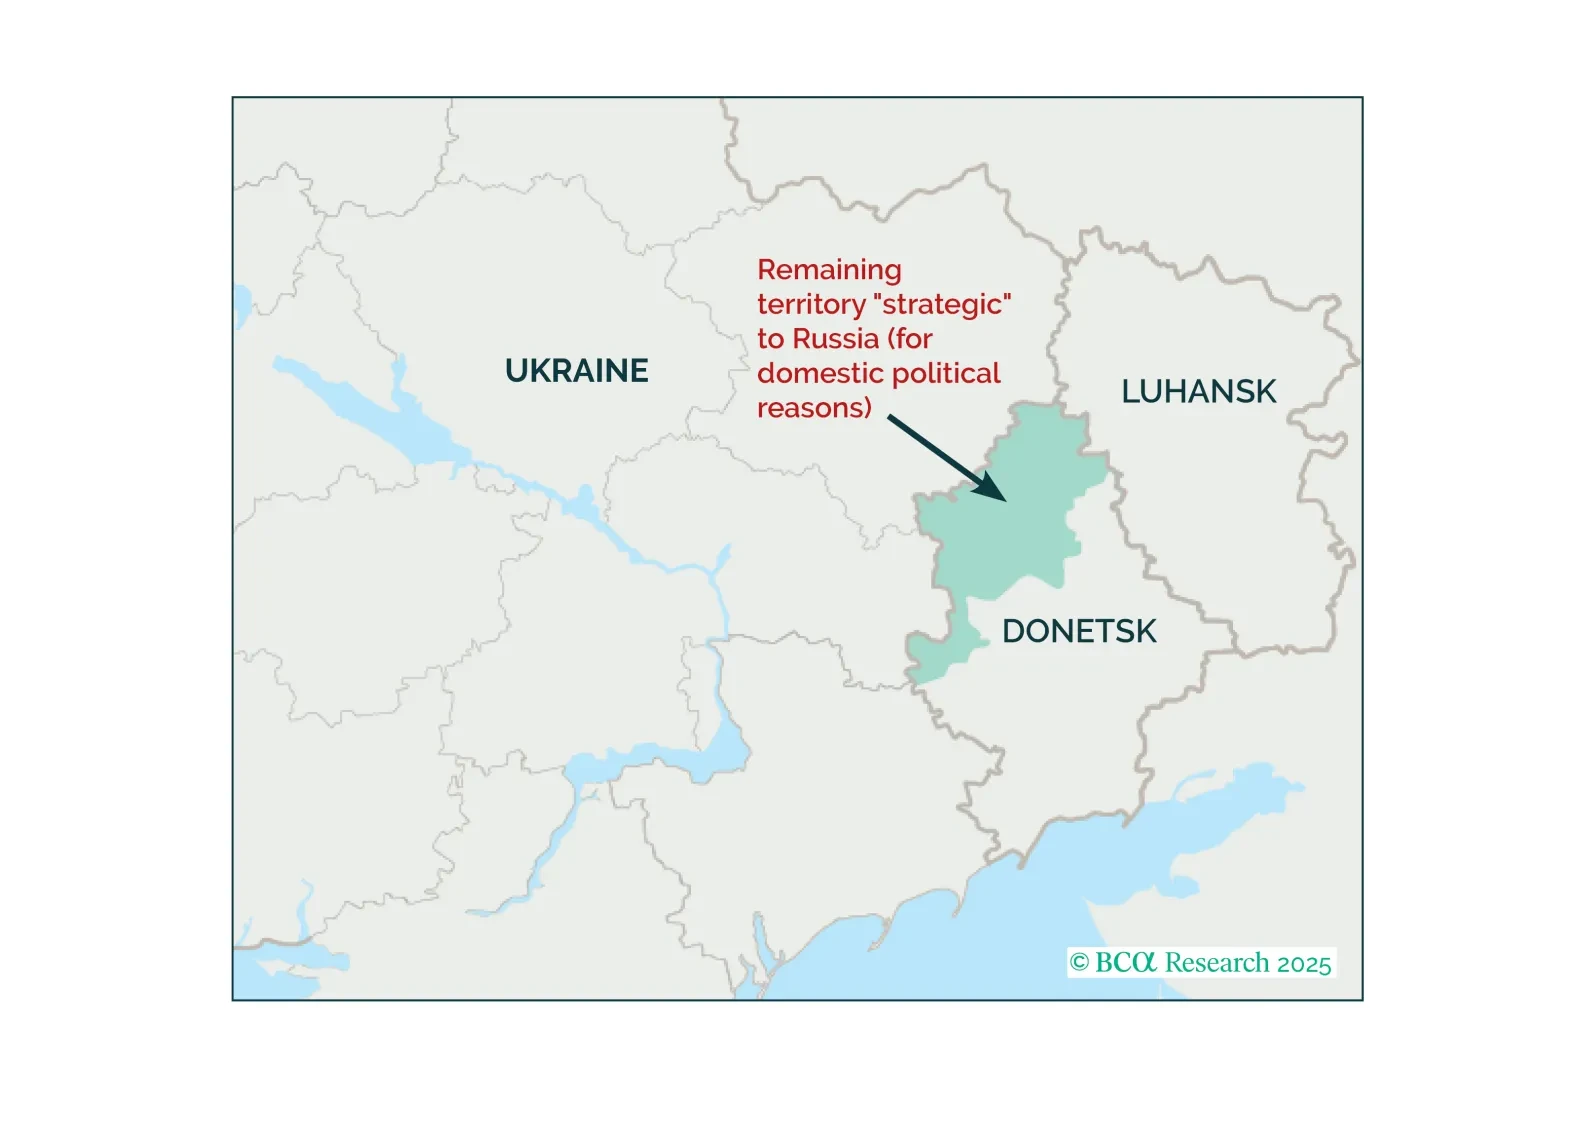
Investors are starting to price an end to the conflict in Ukraine as President Trump’s team puts on a full court press with the intention of replicating the successful peace negotiations in the Middle East.
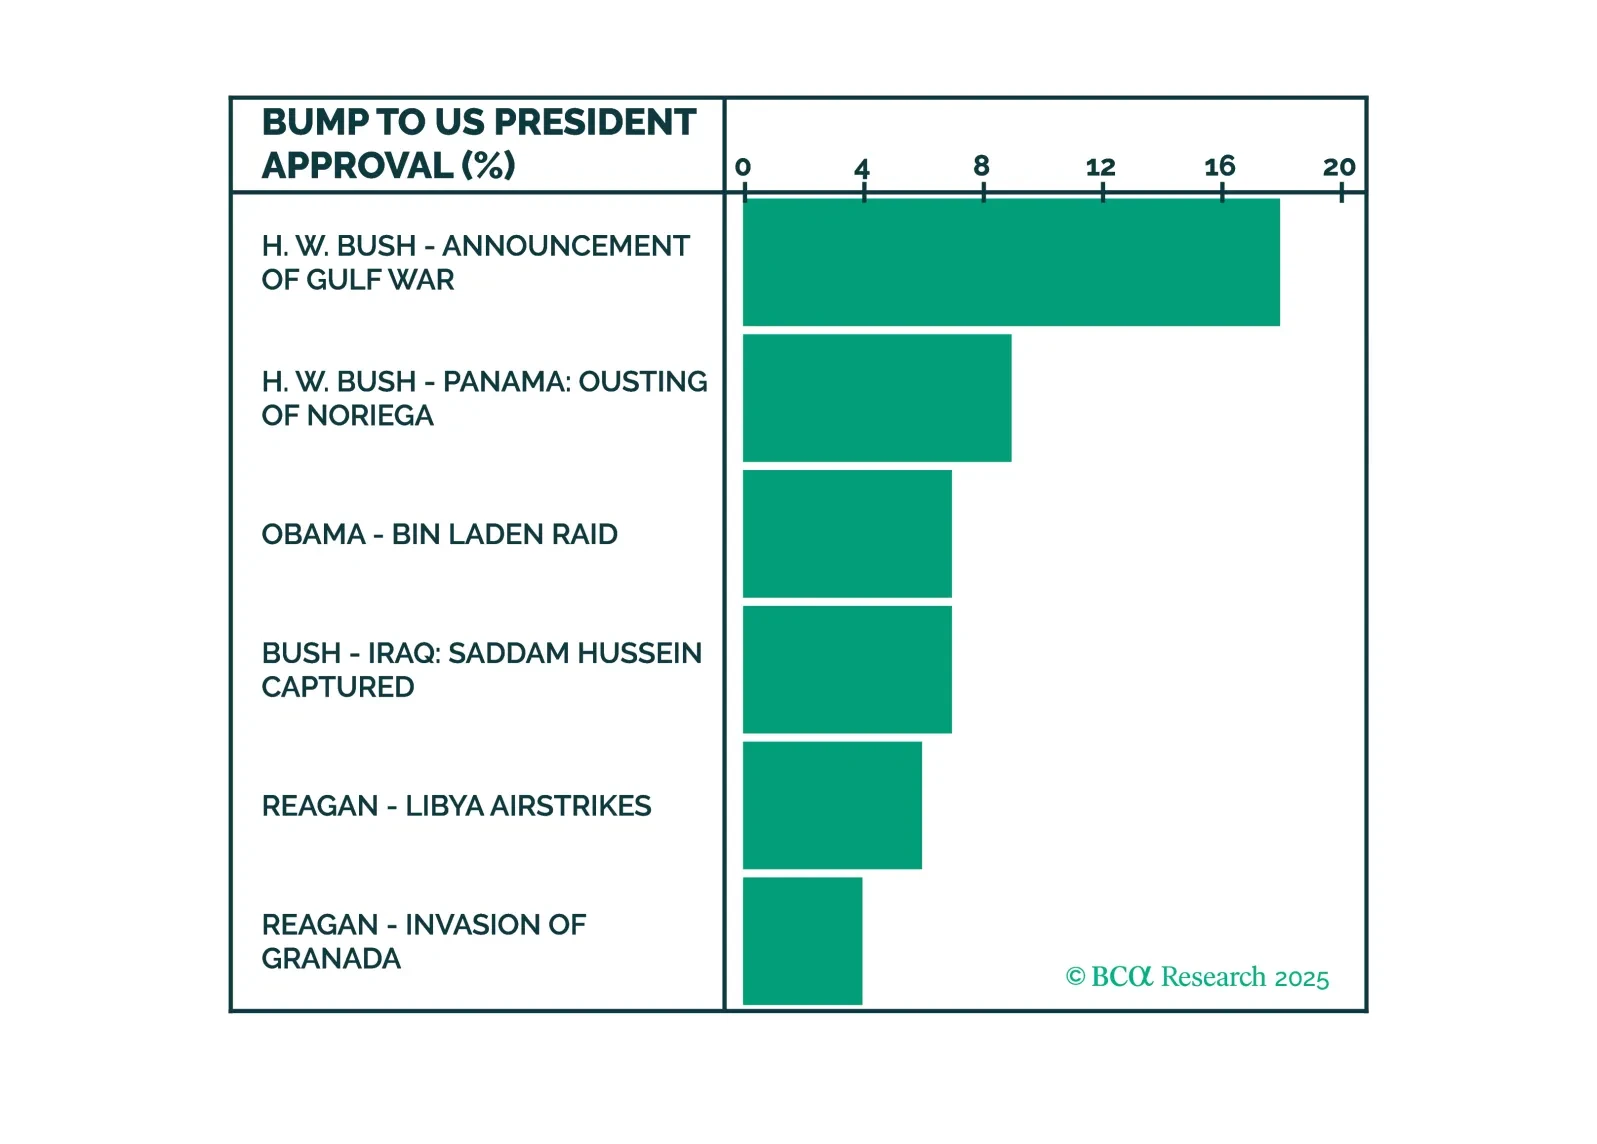
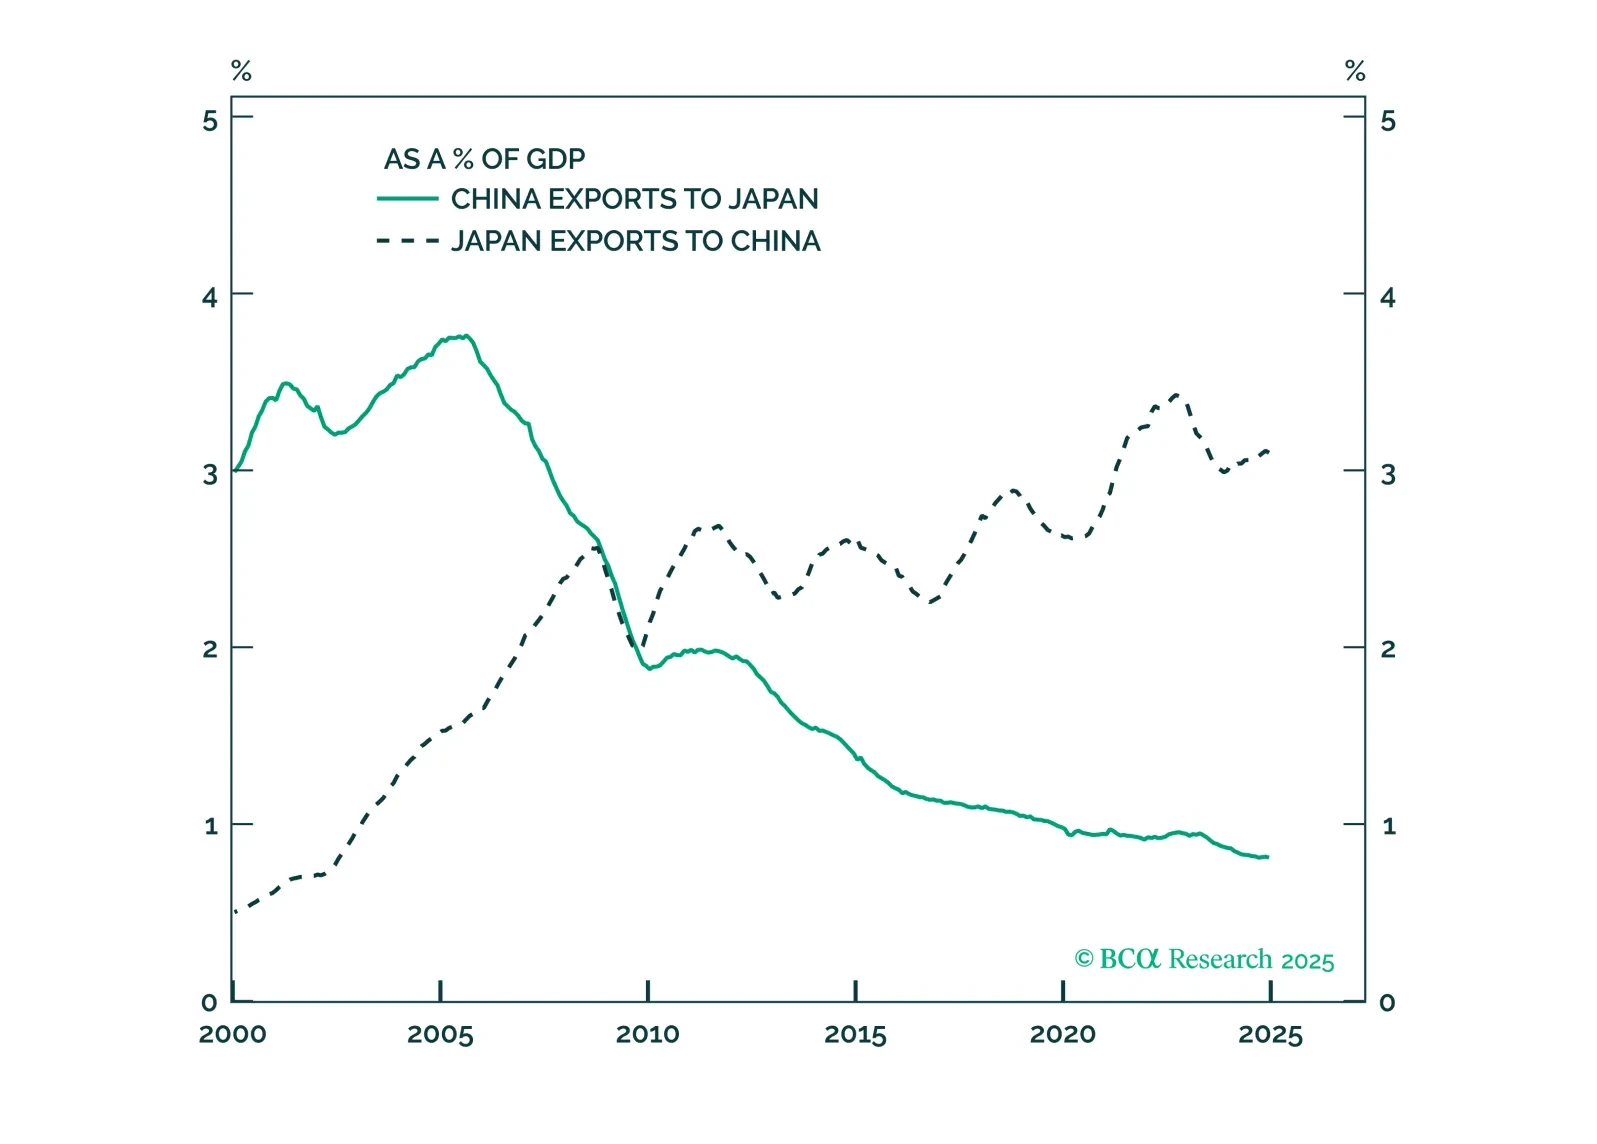
US talks with Russia and China coincide with rising EU-Russia and Japan-China tensions. Stay overweight US assets and long Japanese yen.