 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
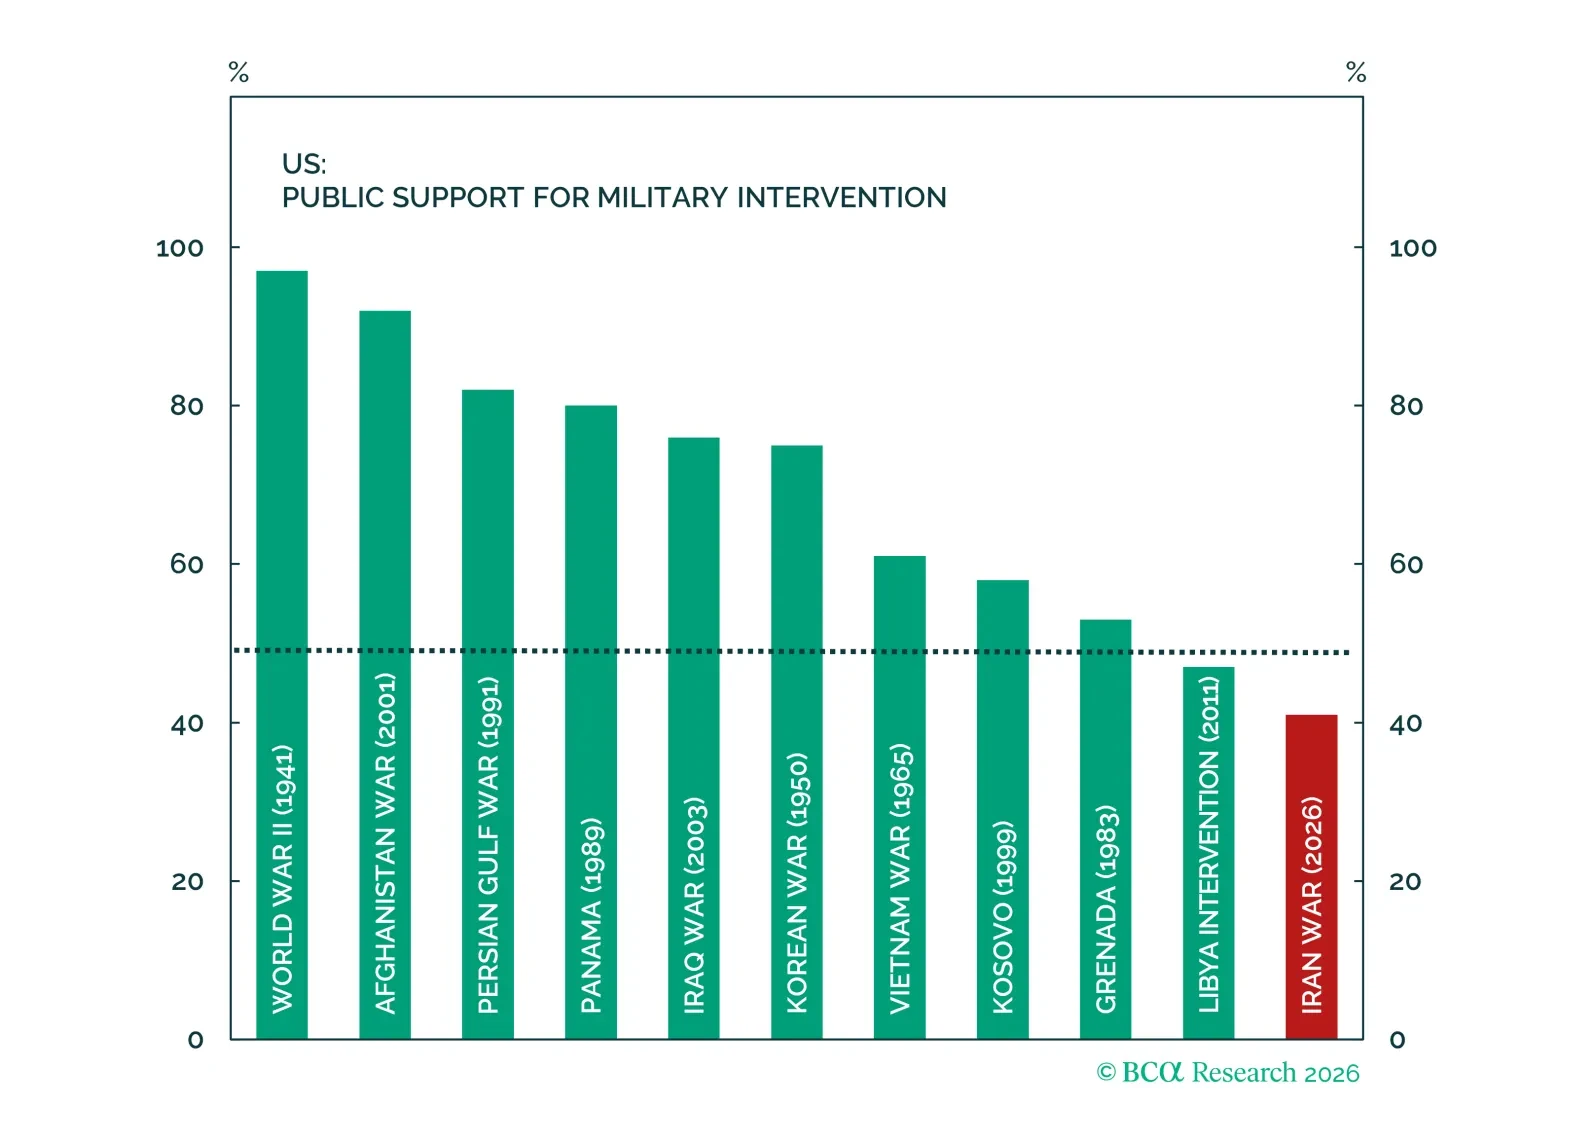
I spent the last week in London, speaking to a wide array of BCA Research clients. Throughout the early part of the week, well connected friends and sources in the Middle East warned me that a renewed US attack on Iran was imminent (by Friday, May 22, after the market close, bien sûr). Several clients with hefty AUM’s – and thus an impressive geopolitical consulting budget – in London confirmed that the US attack was all but assured.
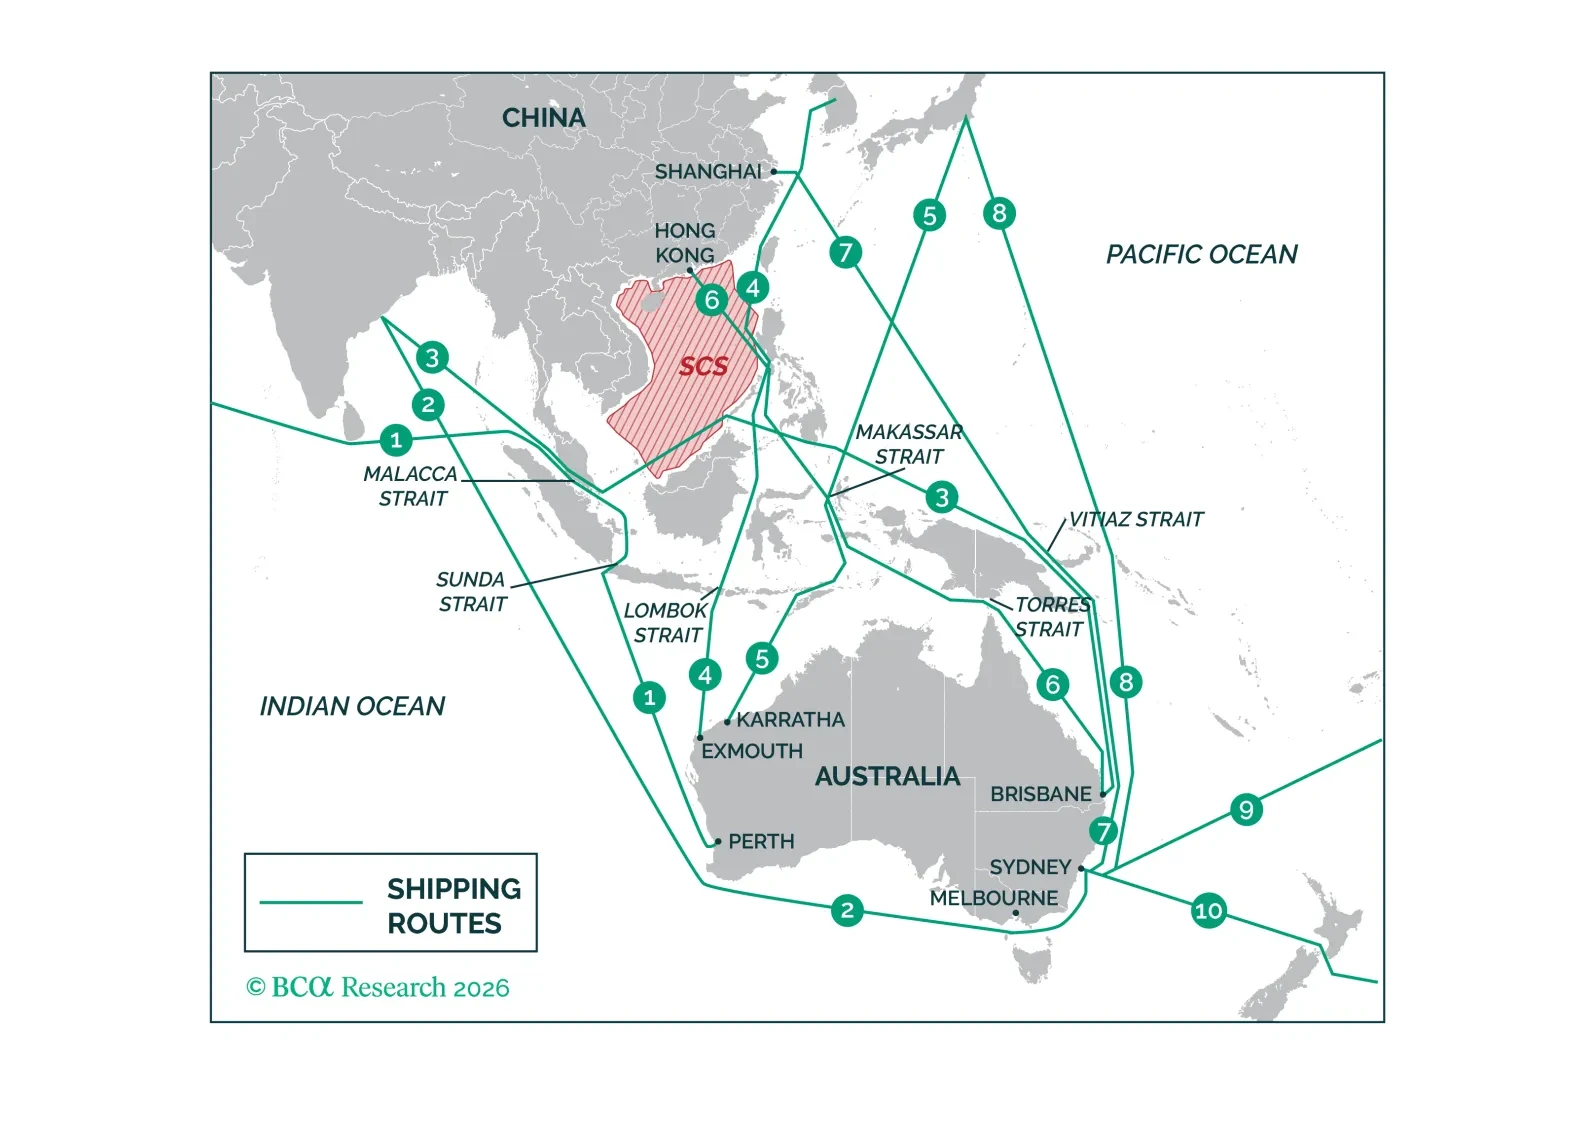
In this month’s Beta Report, we assess what that structural tension means for investors under two distinct scenarios. In our base case – a multipolar world order – Australia's position turns out to be more advantageous than it appears. The great power capital expenditure race generates demand for precisely what Australia produces. In the tail risk – a hard bipolar rupture – the calculus inverts, and the same commodity dependencies that long appeared as structural strengths begin to look like structural liabilities.
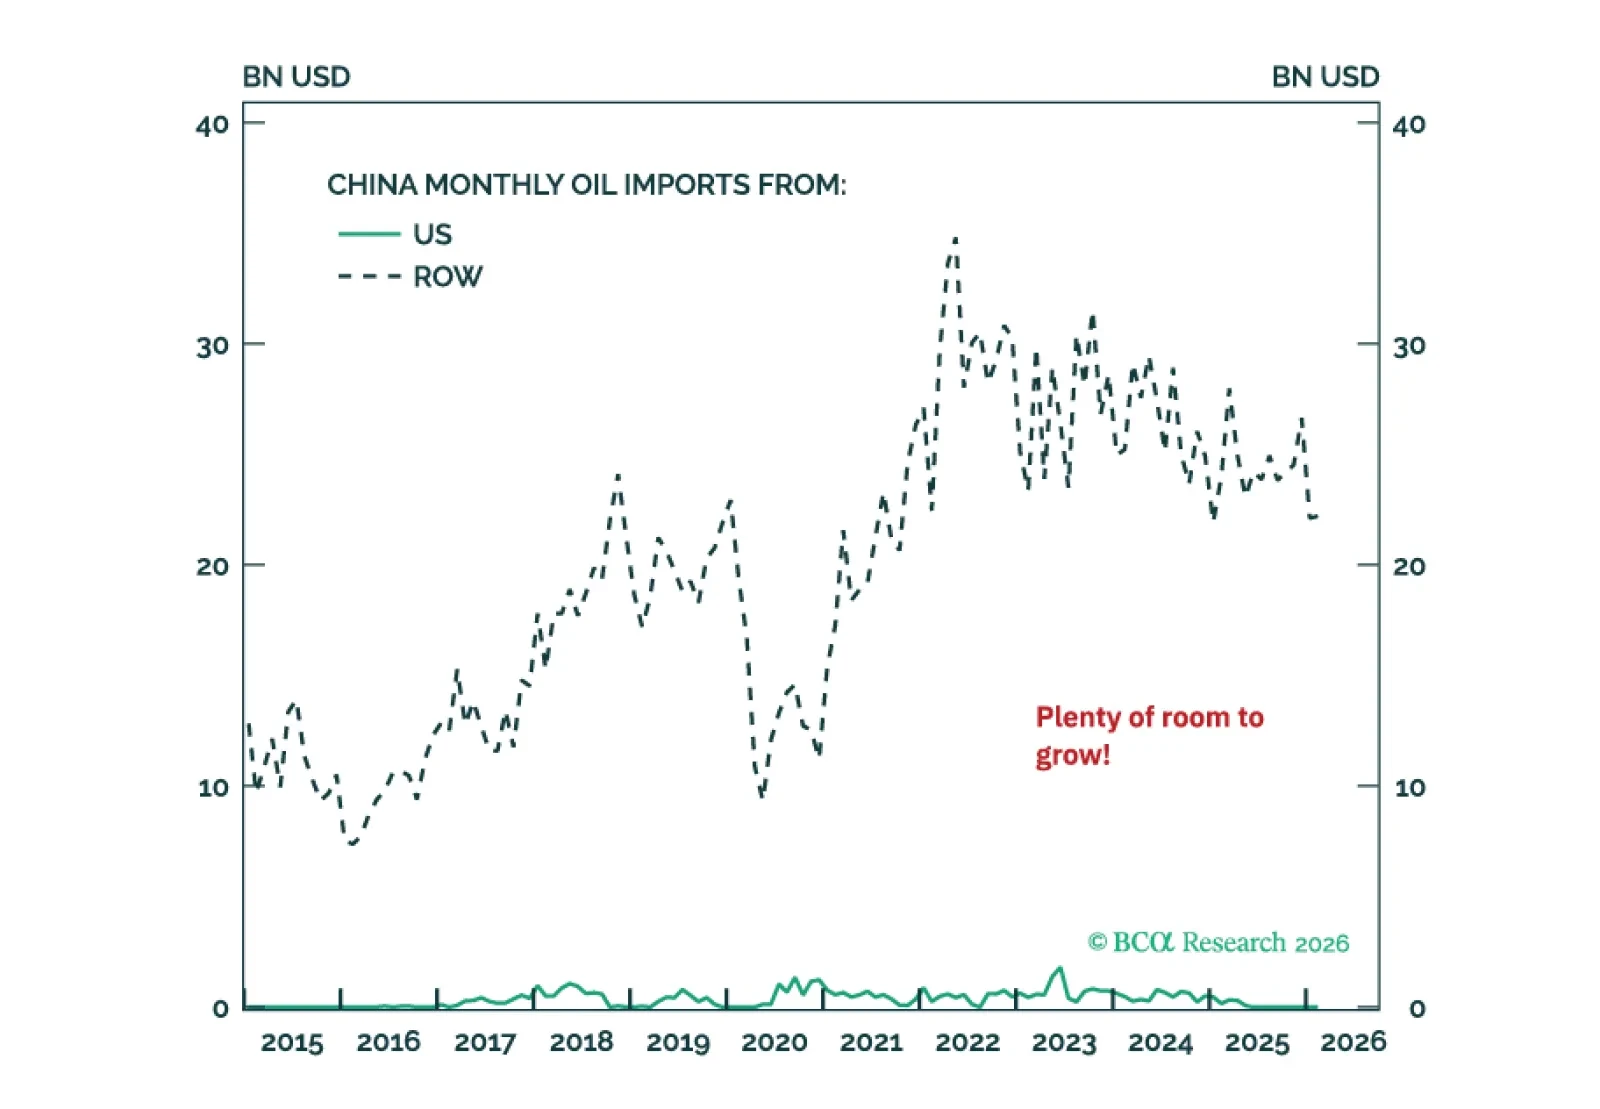
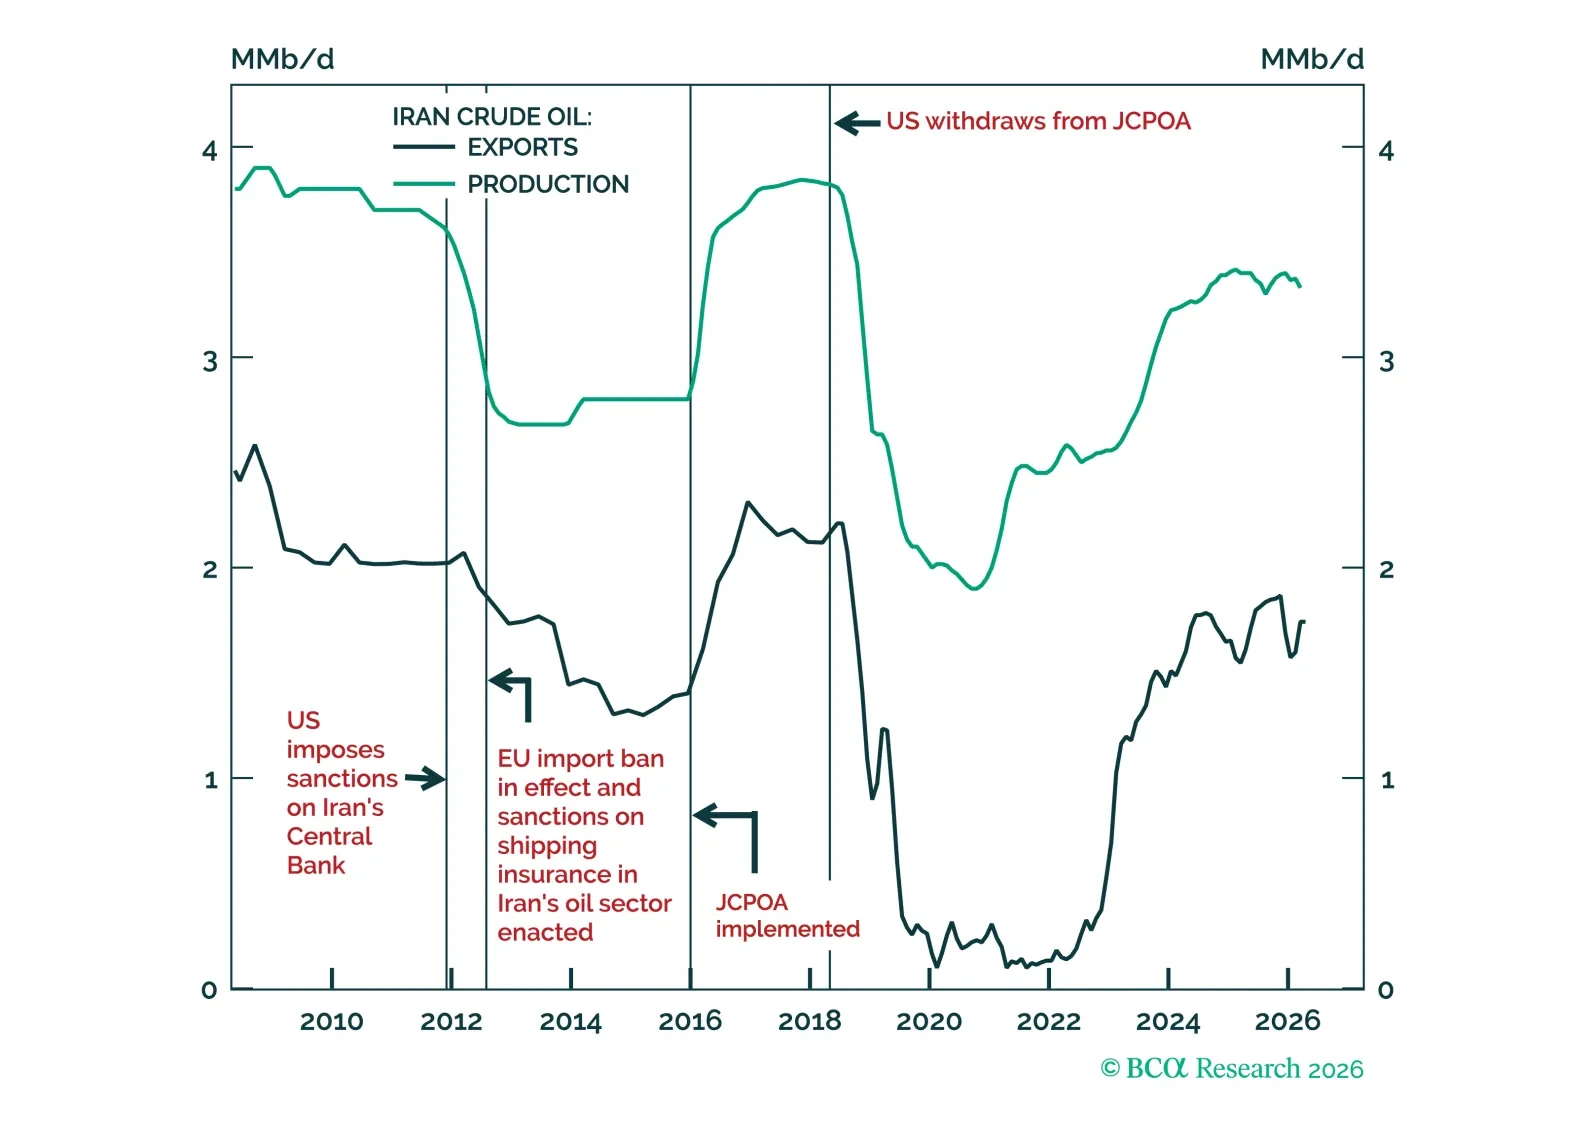
Hopes for an imminent Middle East de-escalation have capped oil prices in recent weeks, but that restraint may soon fade.
Equities have thrown caution to the wind for much of April and early May. We do not disagree with the sanguine mood, but caution that the Hormuz saga is far from over. Still, the AI capex mania continues and the labor market is firming in the US, suggesting that there is more upside to equities.

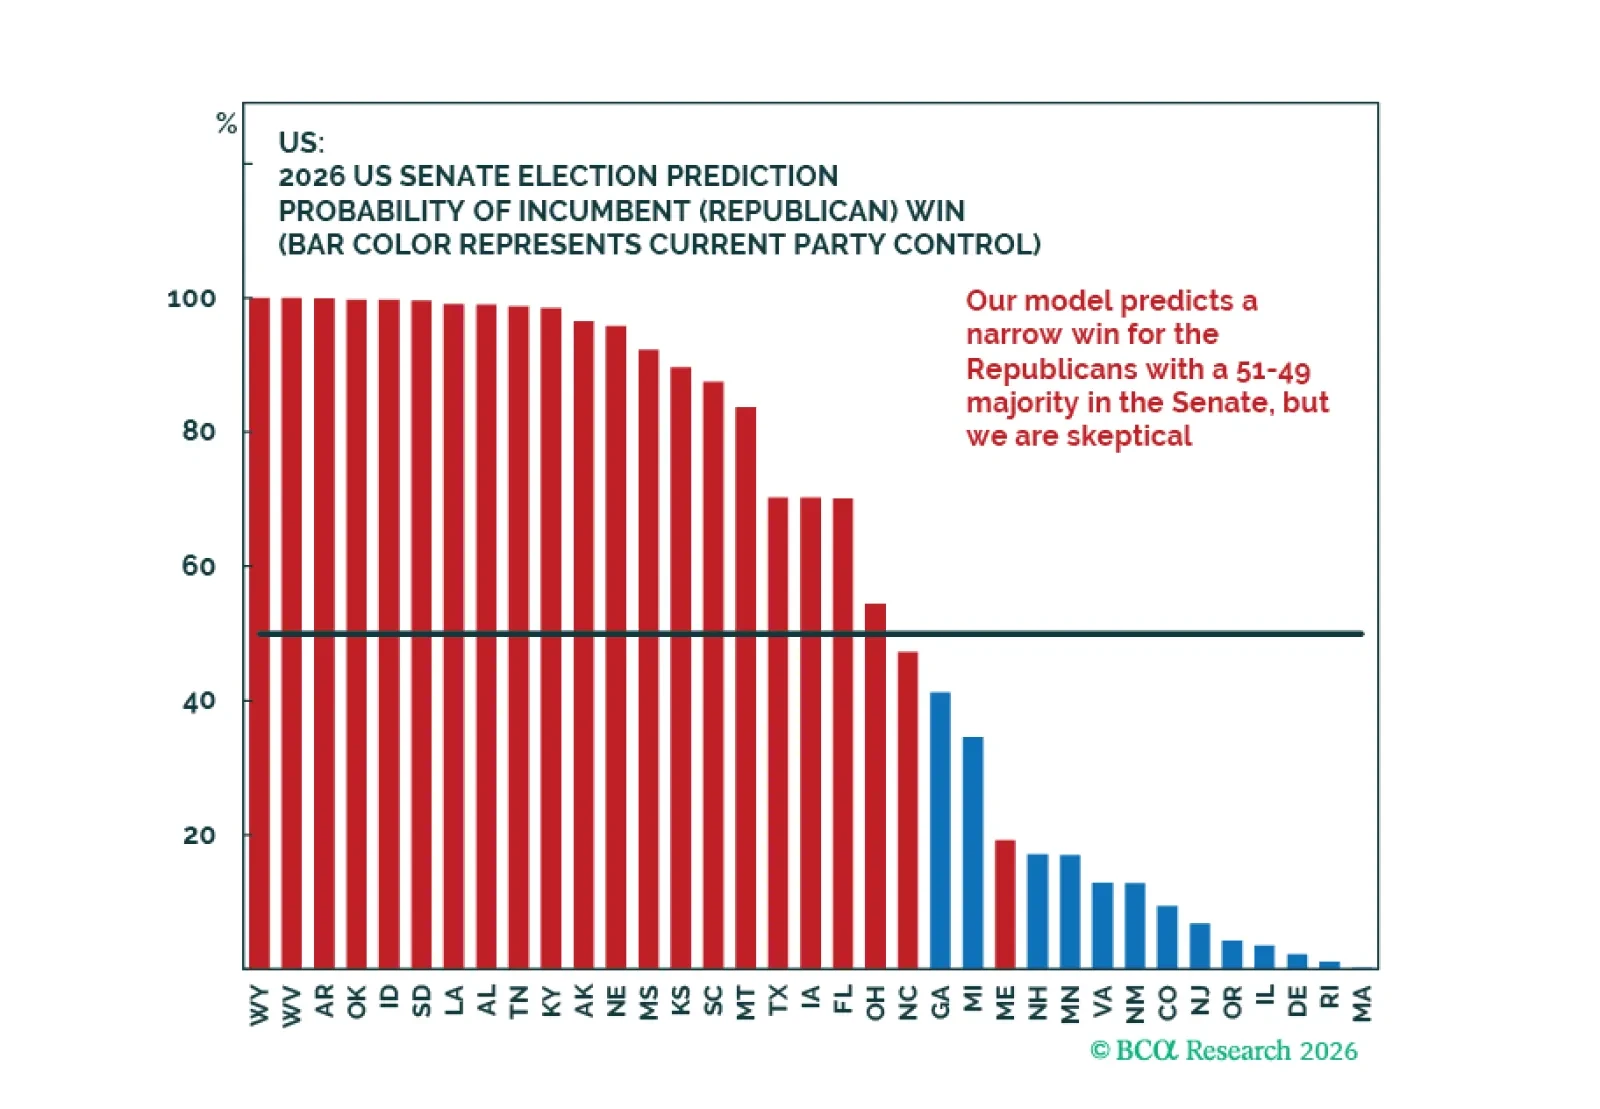
Aggregate Senate betting market pricing appears too pessimistic on Democrats relative to state-level odds and early polling, suggesting a potential mispricing and a relatively sanguine attitude towards the still-unresolved conflict in Iran and its aftermath.
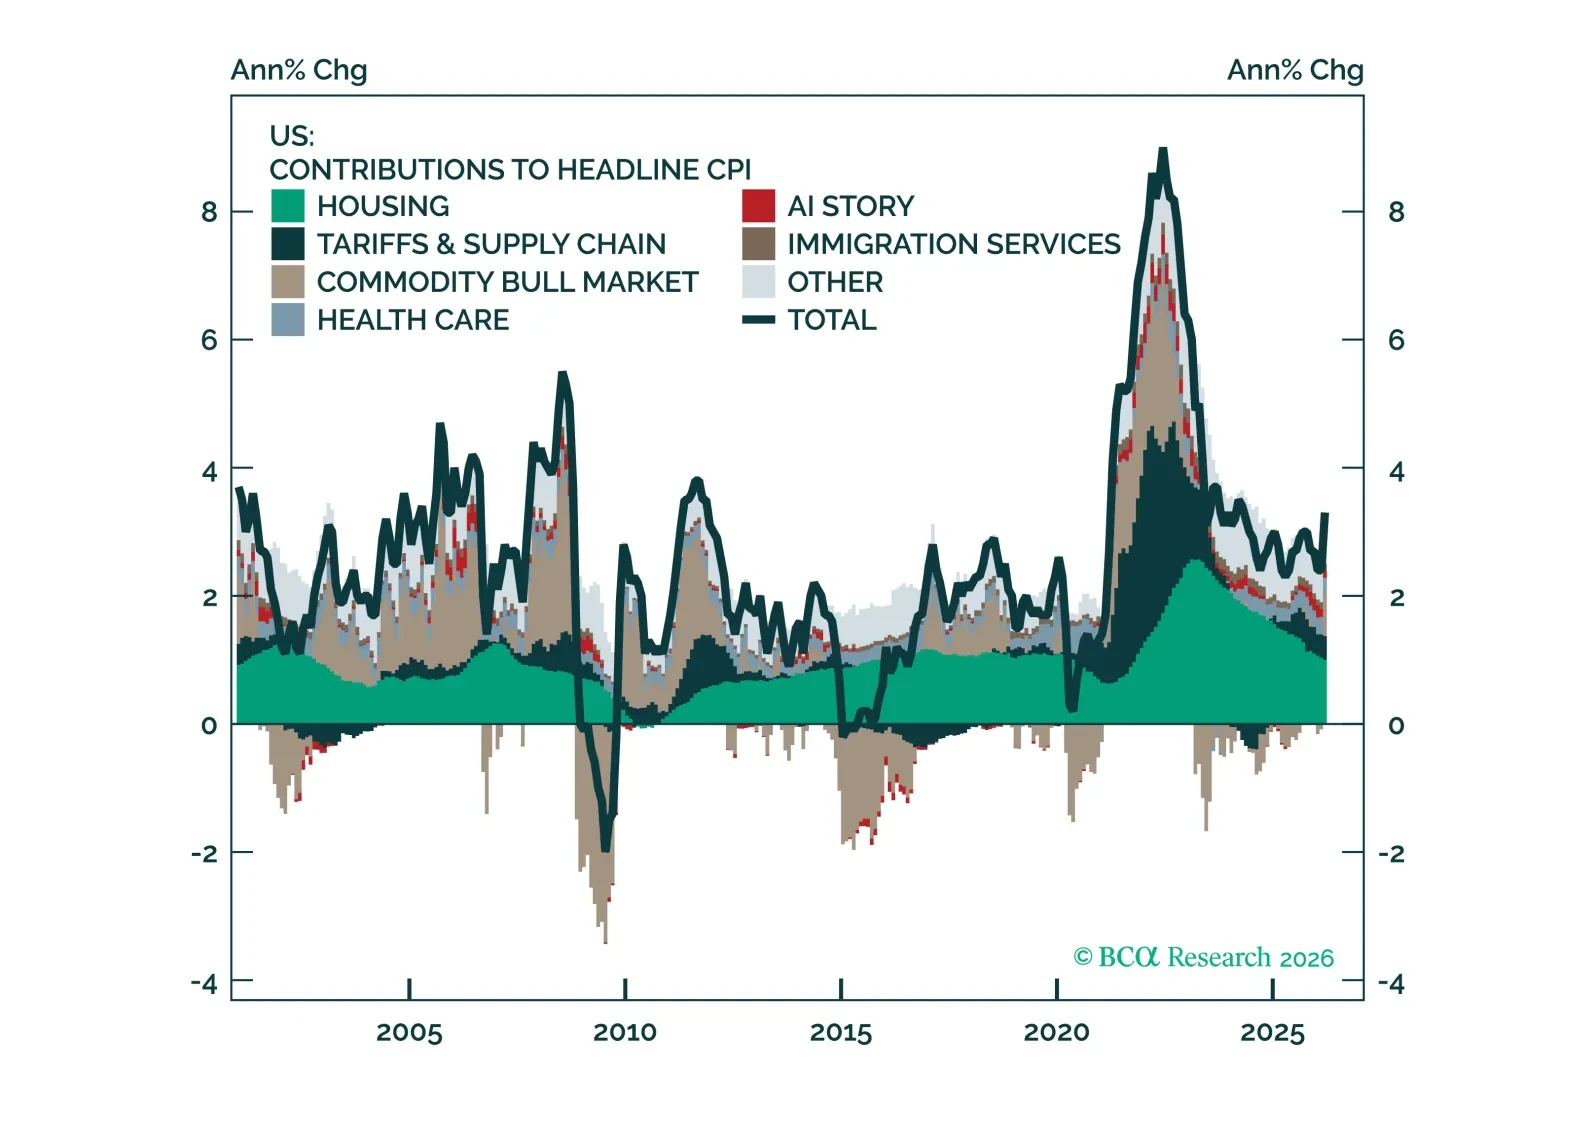
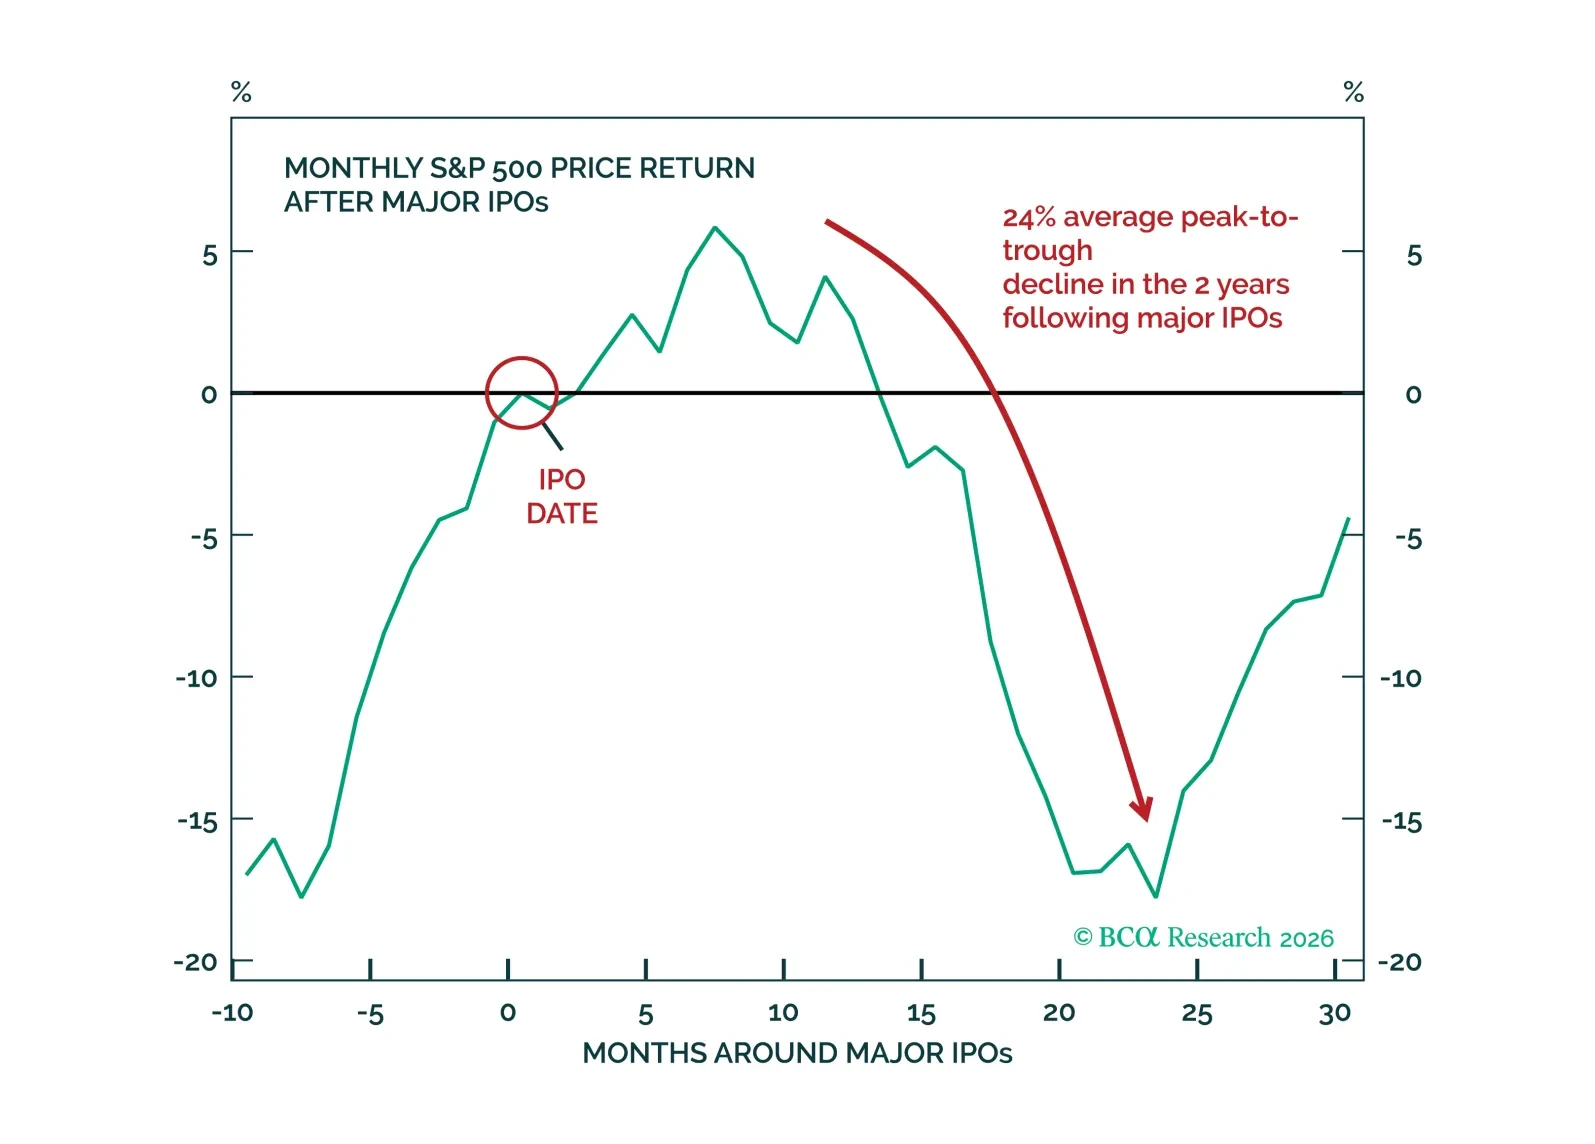
The tenuous ceasefire holds, with the "new geopolitical equilibrium scenario" remaining in place. Enough crude trickles through Hormuz to avert a global recession, but not to alleviate building inflationary pressures, a product of a complicated geomacro context that is not transitory. The Fed will look to ignore these in the short term, fueling the equity rally in the US. Chinese equities may pop thanks to the upcoming détente. When does it all end? Beware of major IPOs!
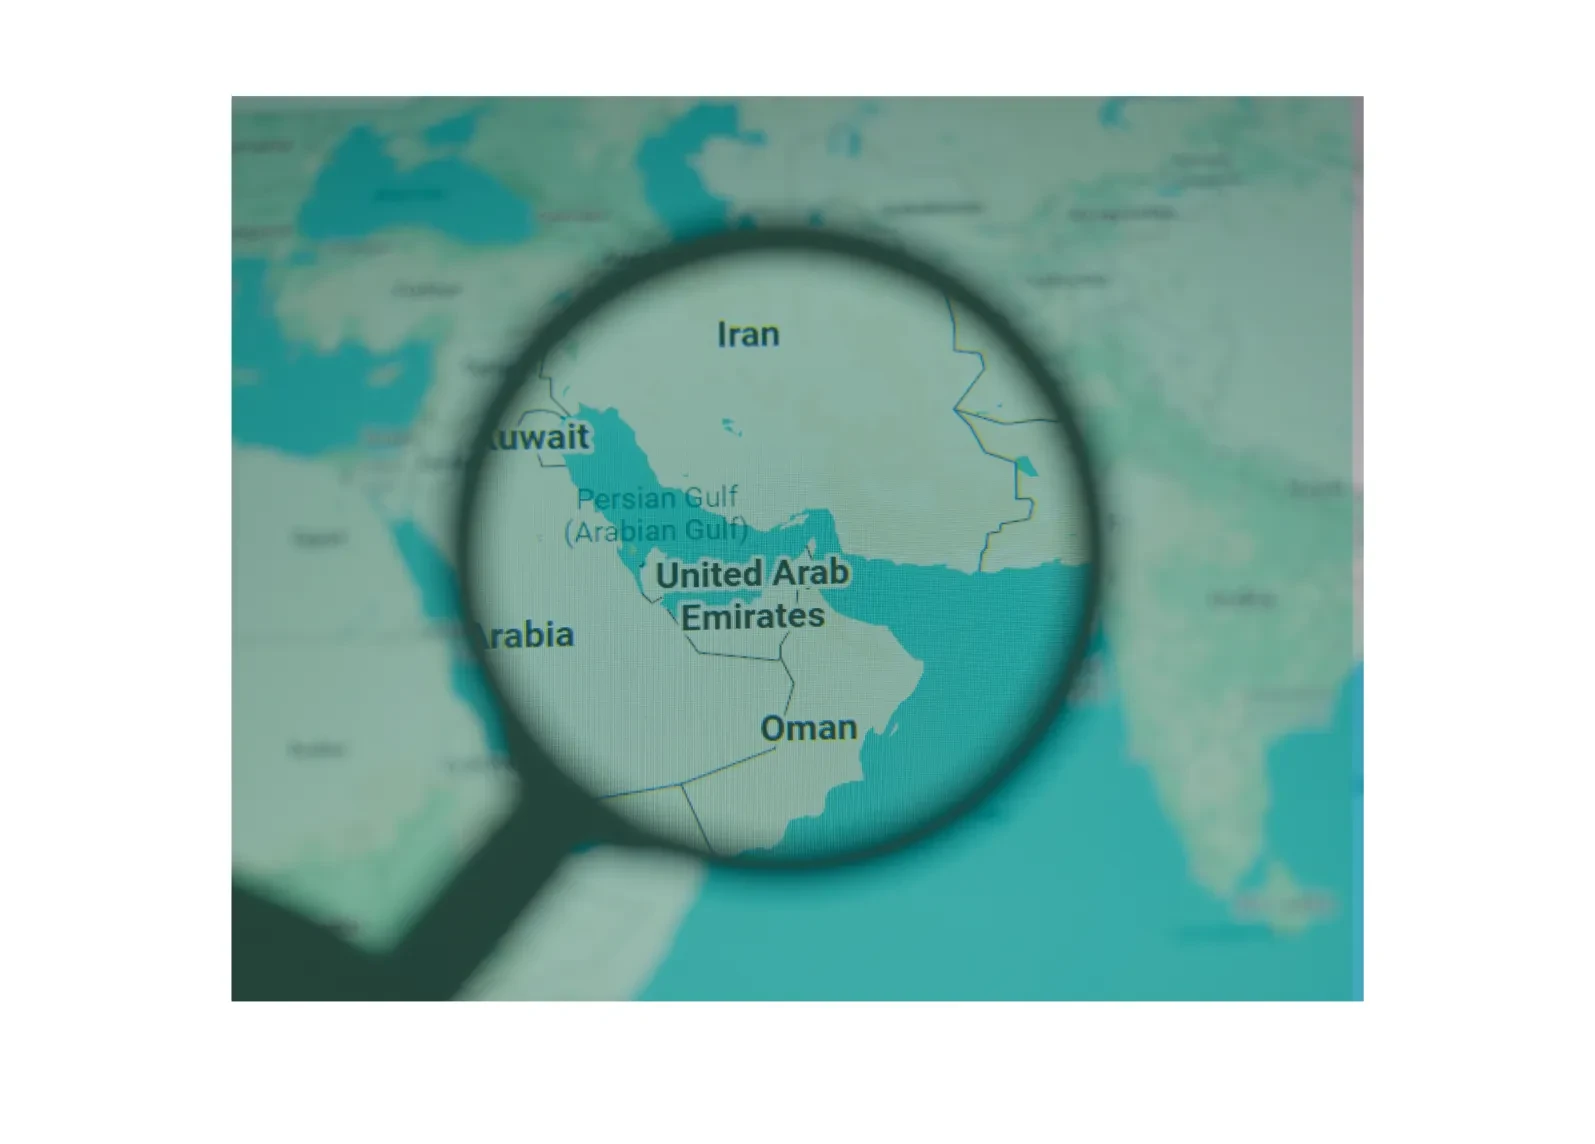
The surprisingly solid ceasefire between Iran, the US, Israel, and GCC countries broke on May 4 with a ballistic missile and drone attack against the UAE. According to reports, UAE defense forces intercepted 12 ballistic missiles, three cruise missiles, and four drones, launched by Iran.
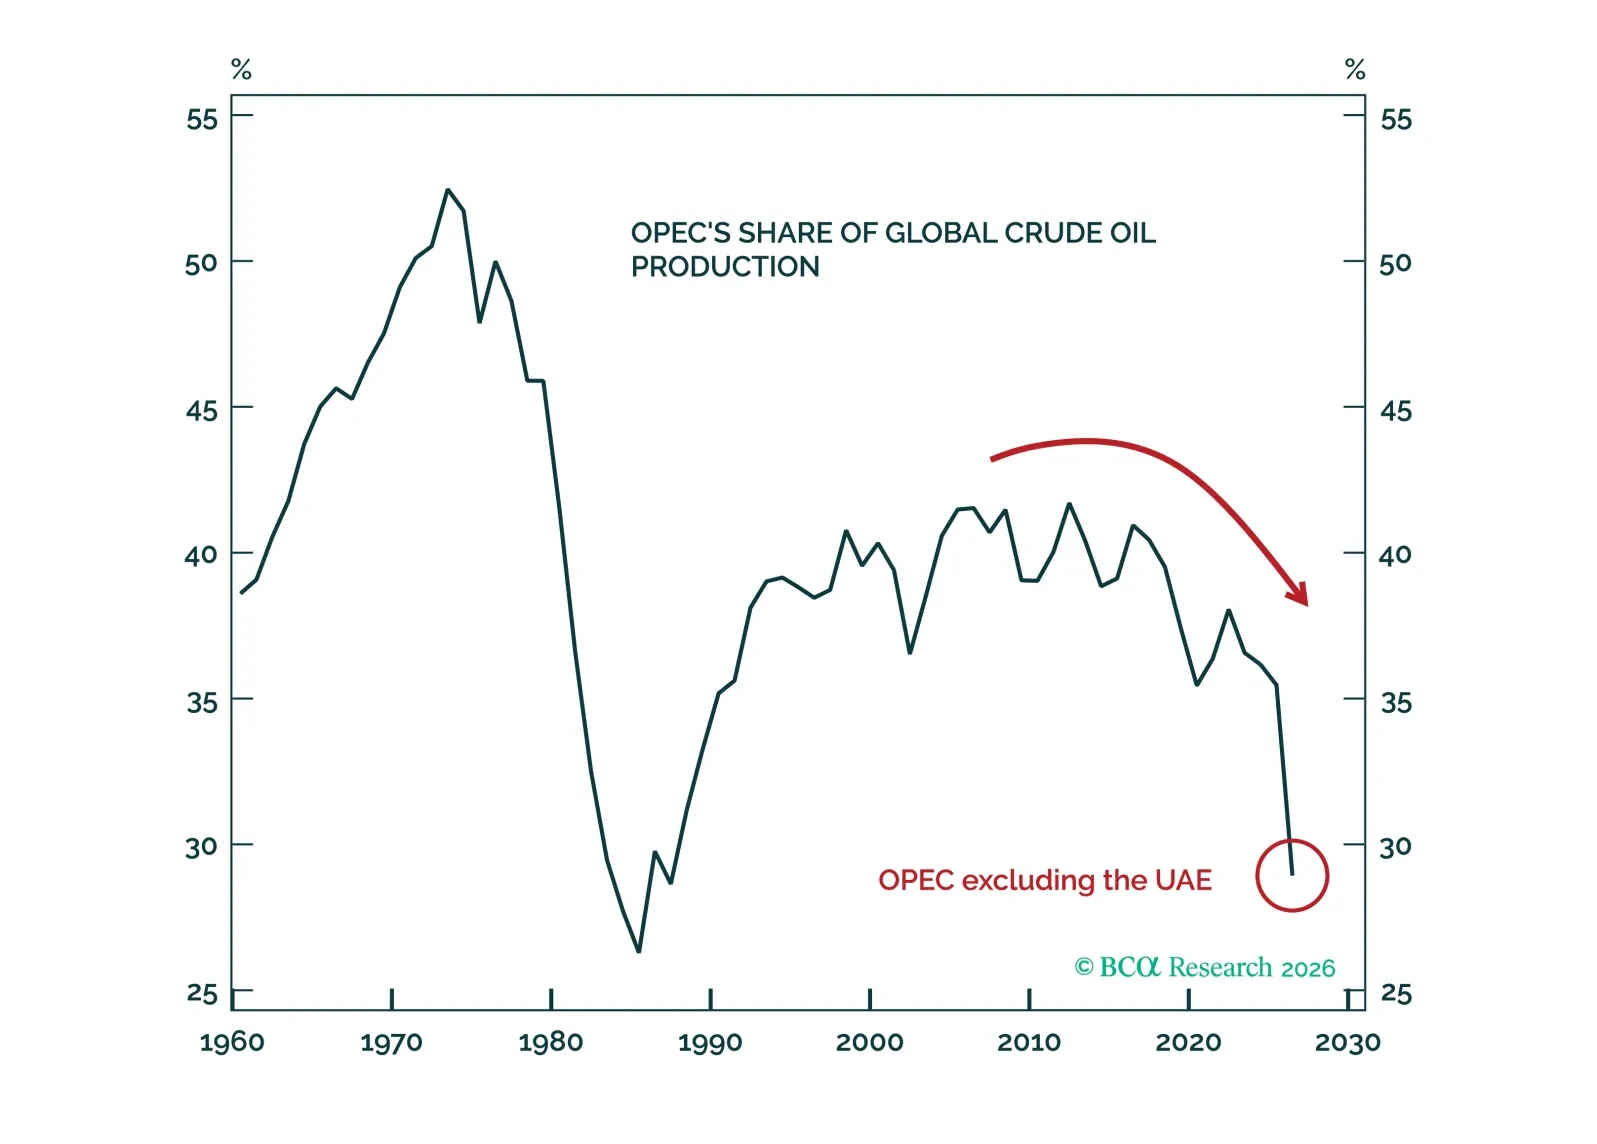
The UAE’s exit from OPEC is unlikely to impact oil markets in 2026. Over the longer term, however, the emergence of an “anti-OPEC club” of producers favoring unconstrained oil output growth would create a headwind to crude prices and weaken the price floor that OPEC seeks to defend.