 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
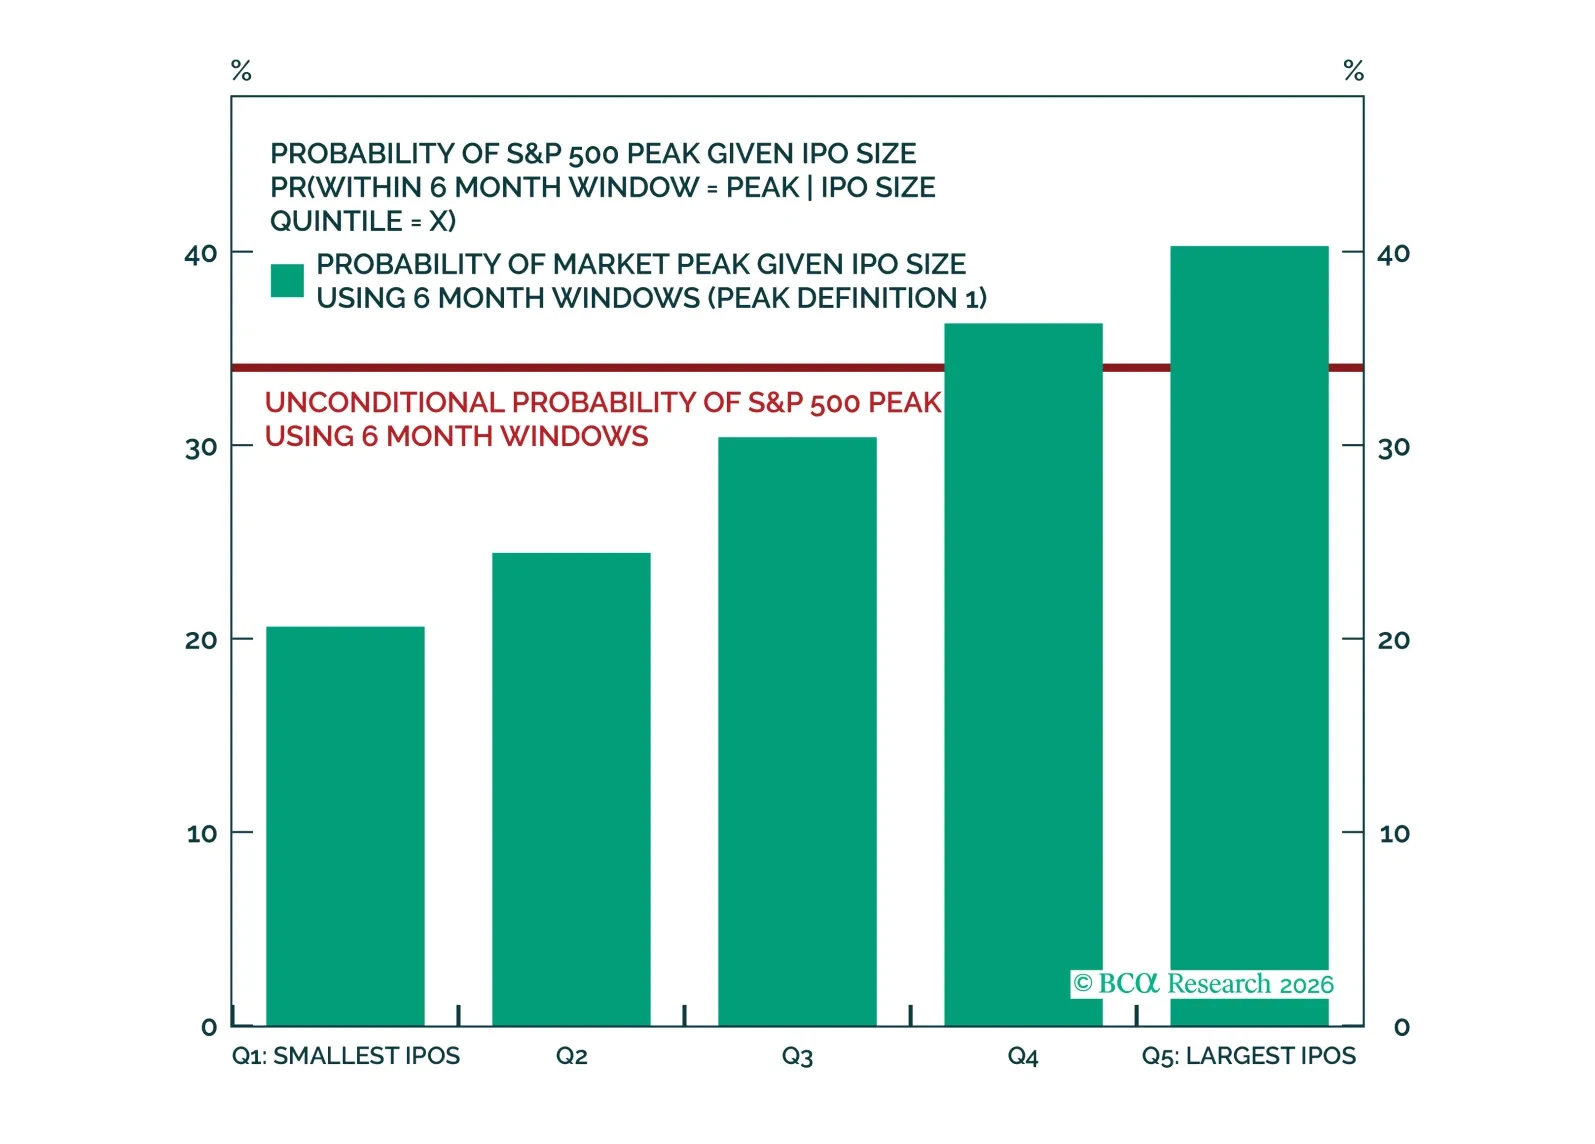
We stick to the view that geopolitical risk has peaked. The US and Iran tensions will increase oil prices, but below a level that will matter for the market. With global liquidity ample, private sector leverage low, and inflation peaking, bears are holding onto an epic collapse of the AI capex to short stocks. Eventually, the capex cycle will end in tears. That much history teaches us. But not yet.
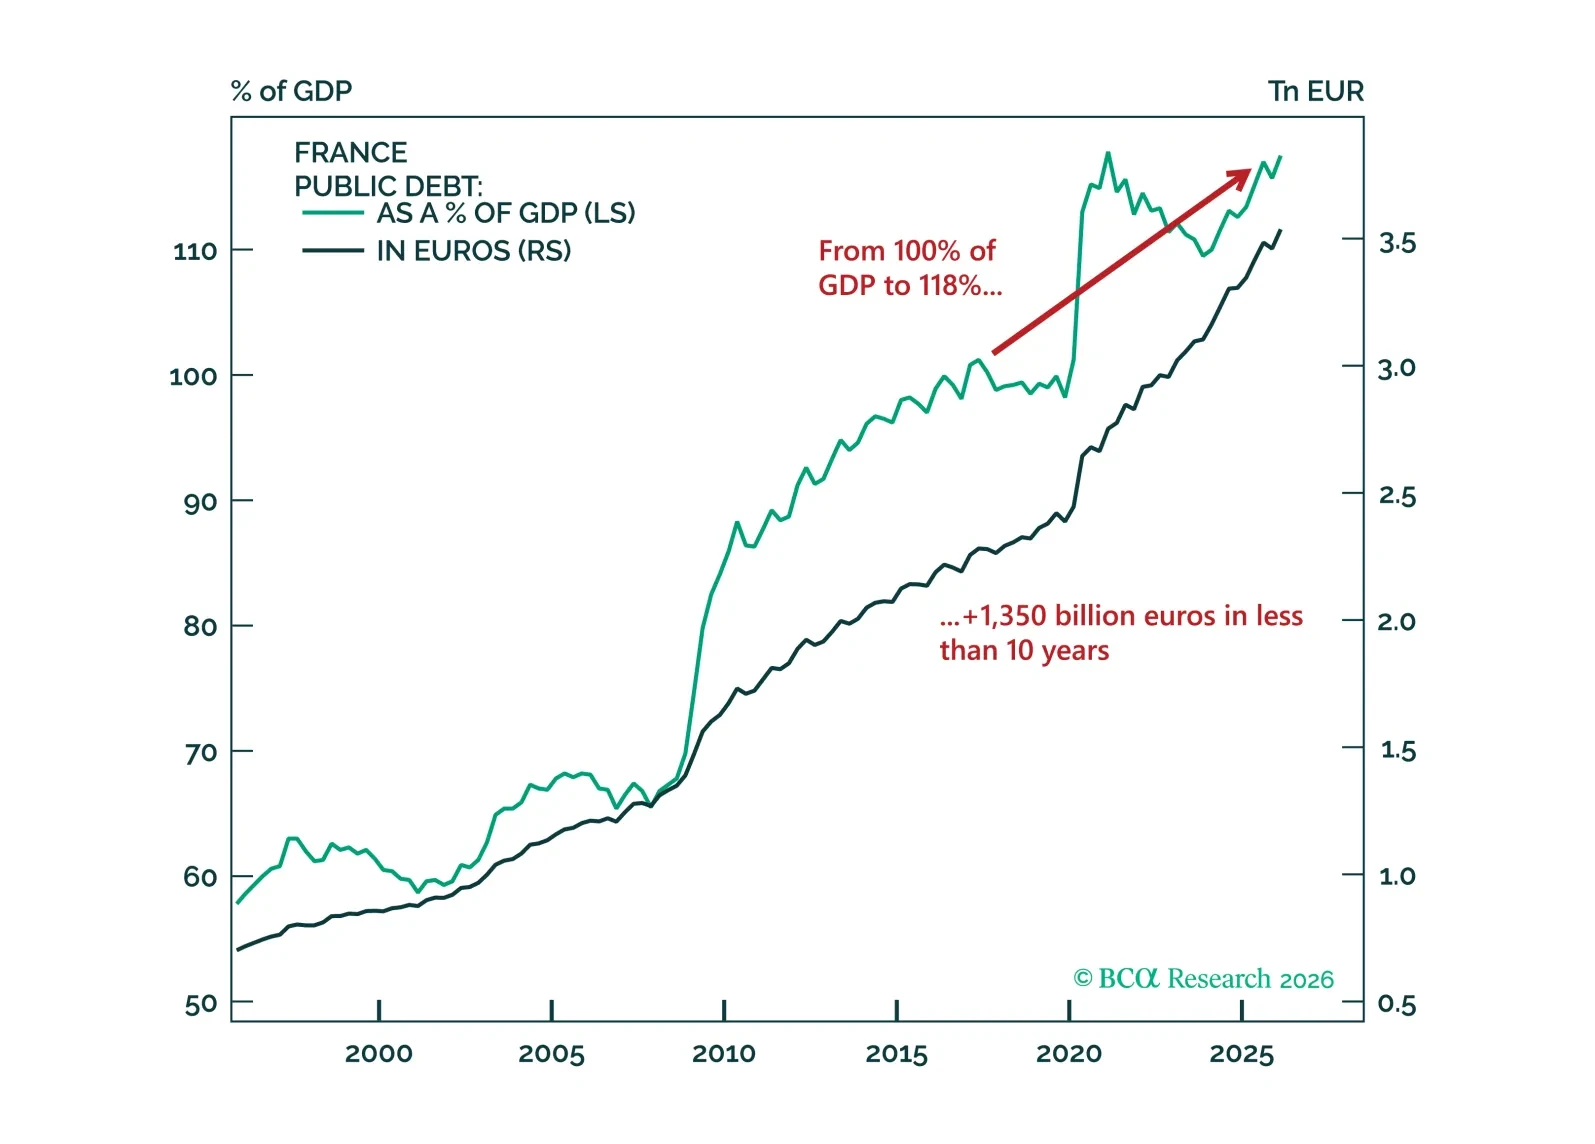
We wish all our French clients Bonne Fête Nationale! The rest of the world knows the holiday by its other name, Bastille Day. It is fitting, therefore, that we publish today GeoMacro Beta report on the coming political earthquake in France.
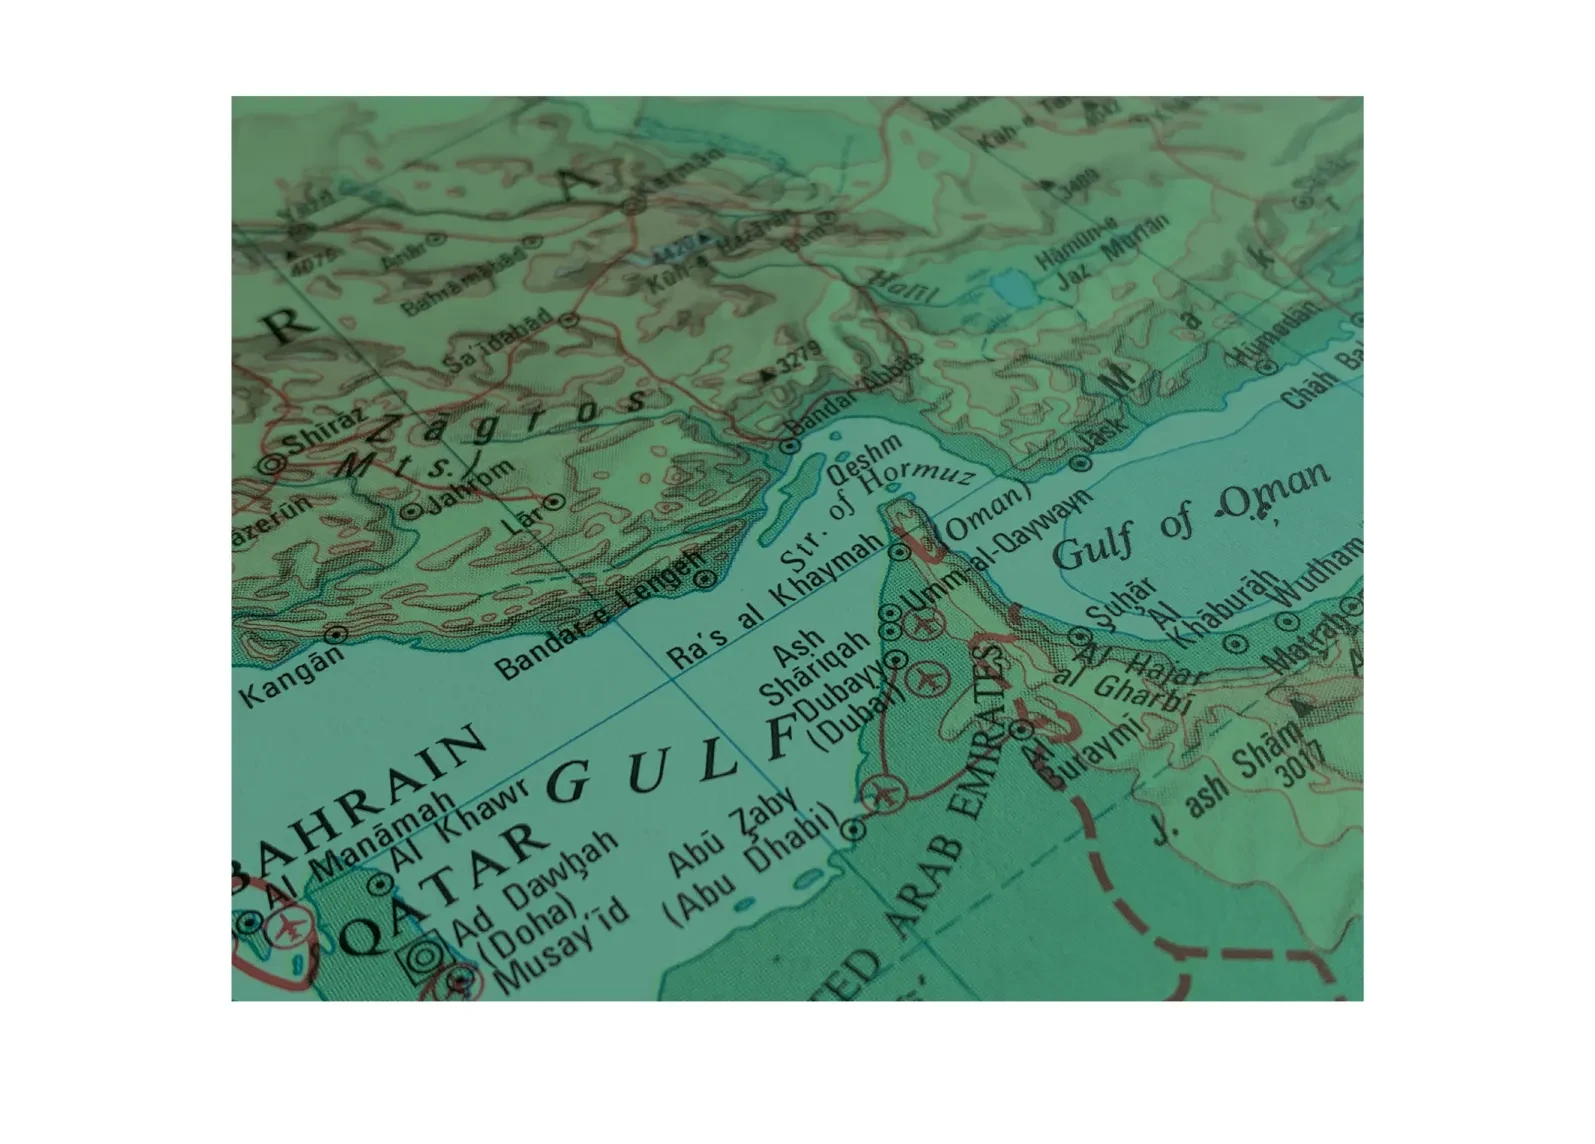
The US and Iran have engaged in a dramatic increase in kinetic activity over the past several days. It all appears to have started on July 6-7, when Iran allegedly attacked several ships in the Strait of Hormuz, vessels that were using the US-recommended route closer to Oman. Following US strikes against Iran in retaliation for that incident – with the US military claiming to have struck 140 sites – Iran has retaliated against US military facilities across the Gulf region. According to media reporting and Iranian government sources themselves, Iran attacked Bahrain, Kuwait, Jordan, Qatar and Oman on July 11-12.
As part of our new and improved GeoMacro service, please find attached our Global Risk Outlook, a quarterly digest of scenario probabilities and estimated market impacts for all the major geopolitical topics in the world today.
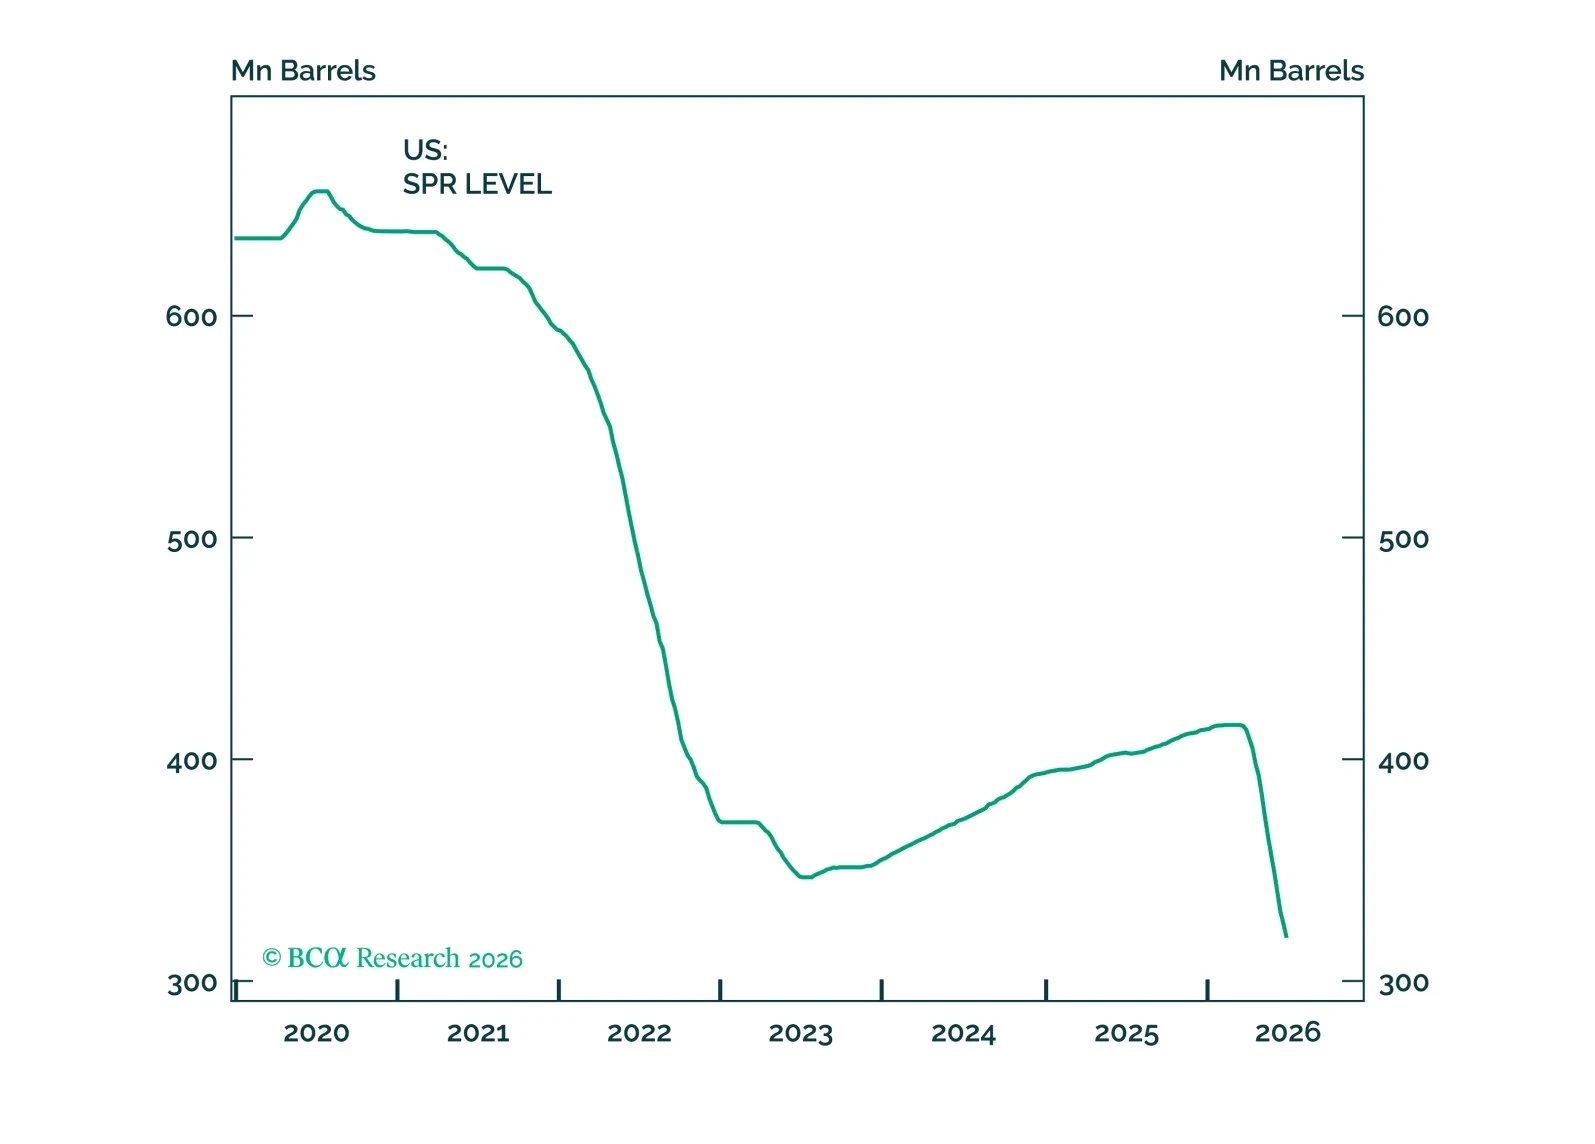
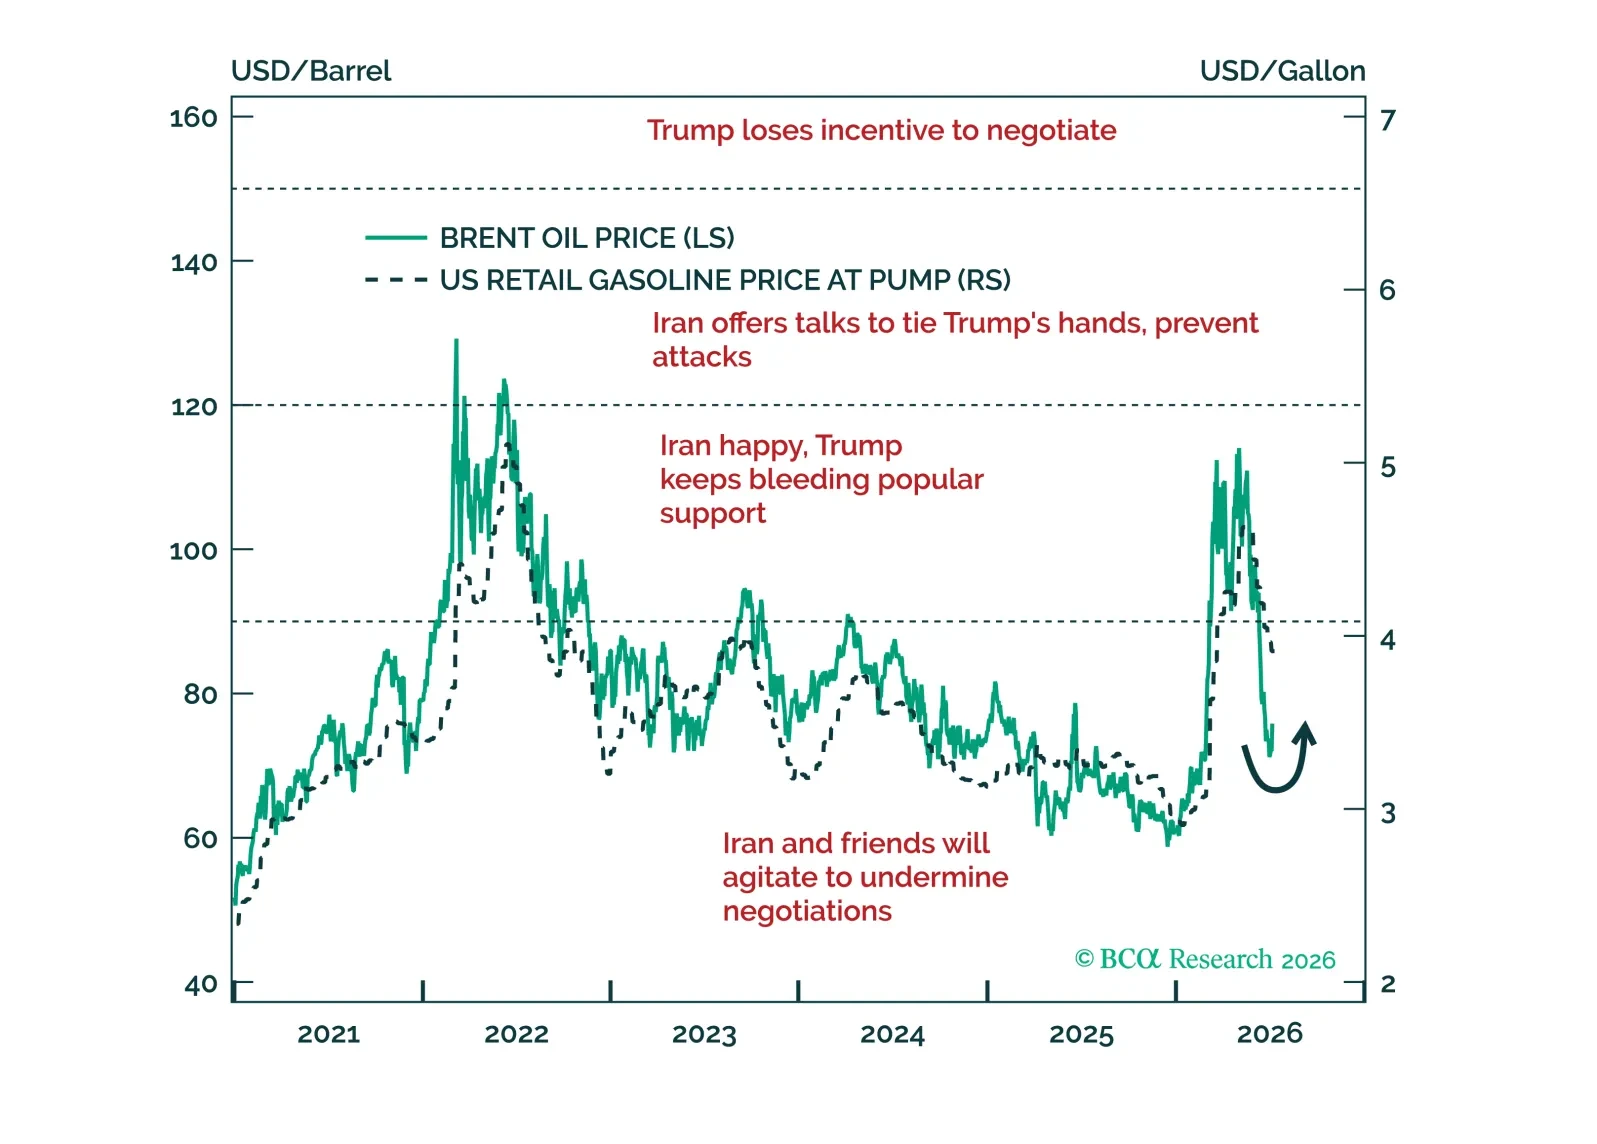
Just as we declared that geopolitical risk has peaked for the year – in yesterday’s Alpha report – President Trump has declared the ceasefire with Iran over after repeated violations via strikes against three tankers in the Strait of Hormuz. That is the life of an investment strategist. But the underlying dynamics continue to play out as we’ve described.
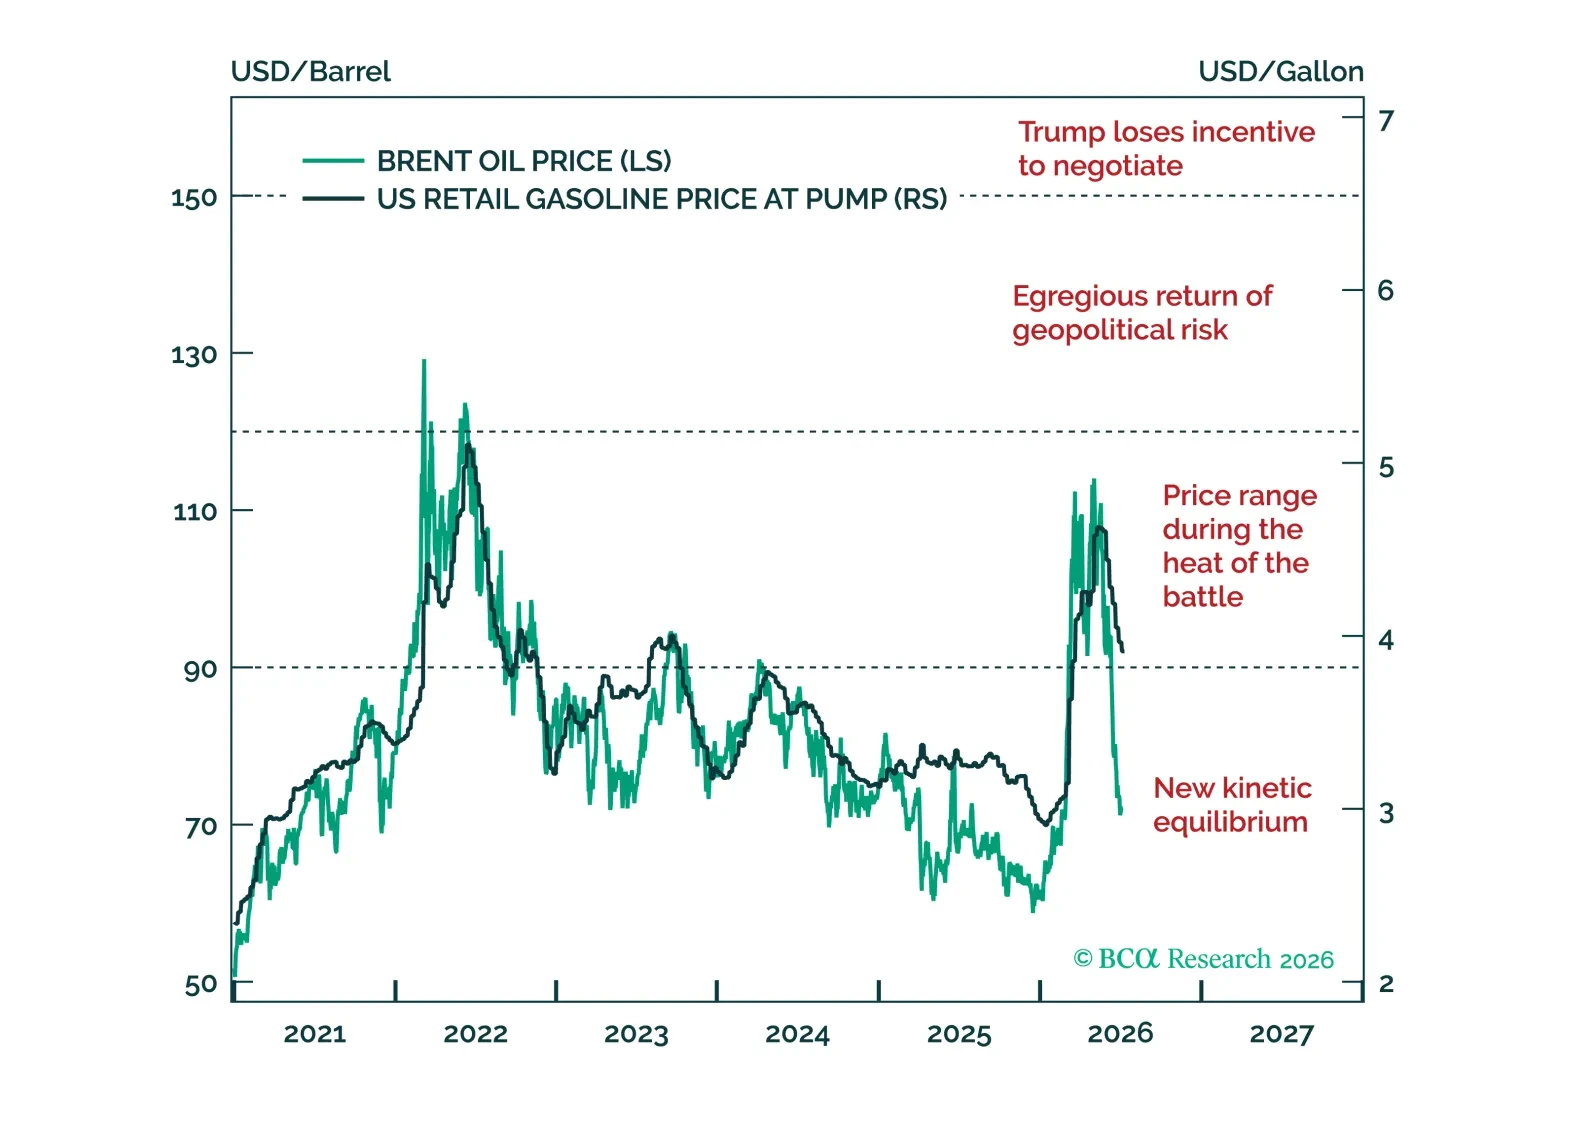
We remain bullish on risk assets given that the Hormuz war has resolved itself and oil prices have declined by even more than we expected. In addition, the macro fundamentals are not flashing any red signs. That said, we remain skeptical that the AI revolution will continue without any hiccups. In fact, a price war may ensue once all the players realize they’re in the commodity – not tech – space.
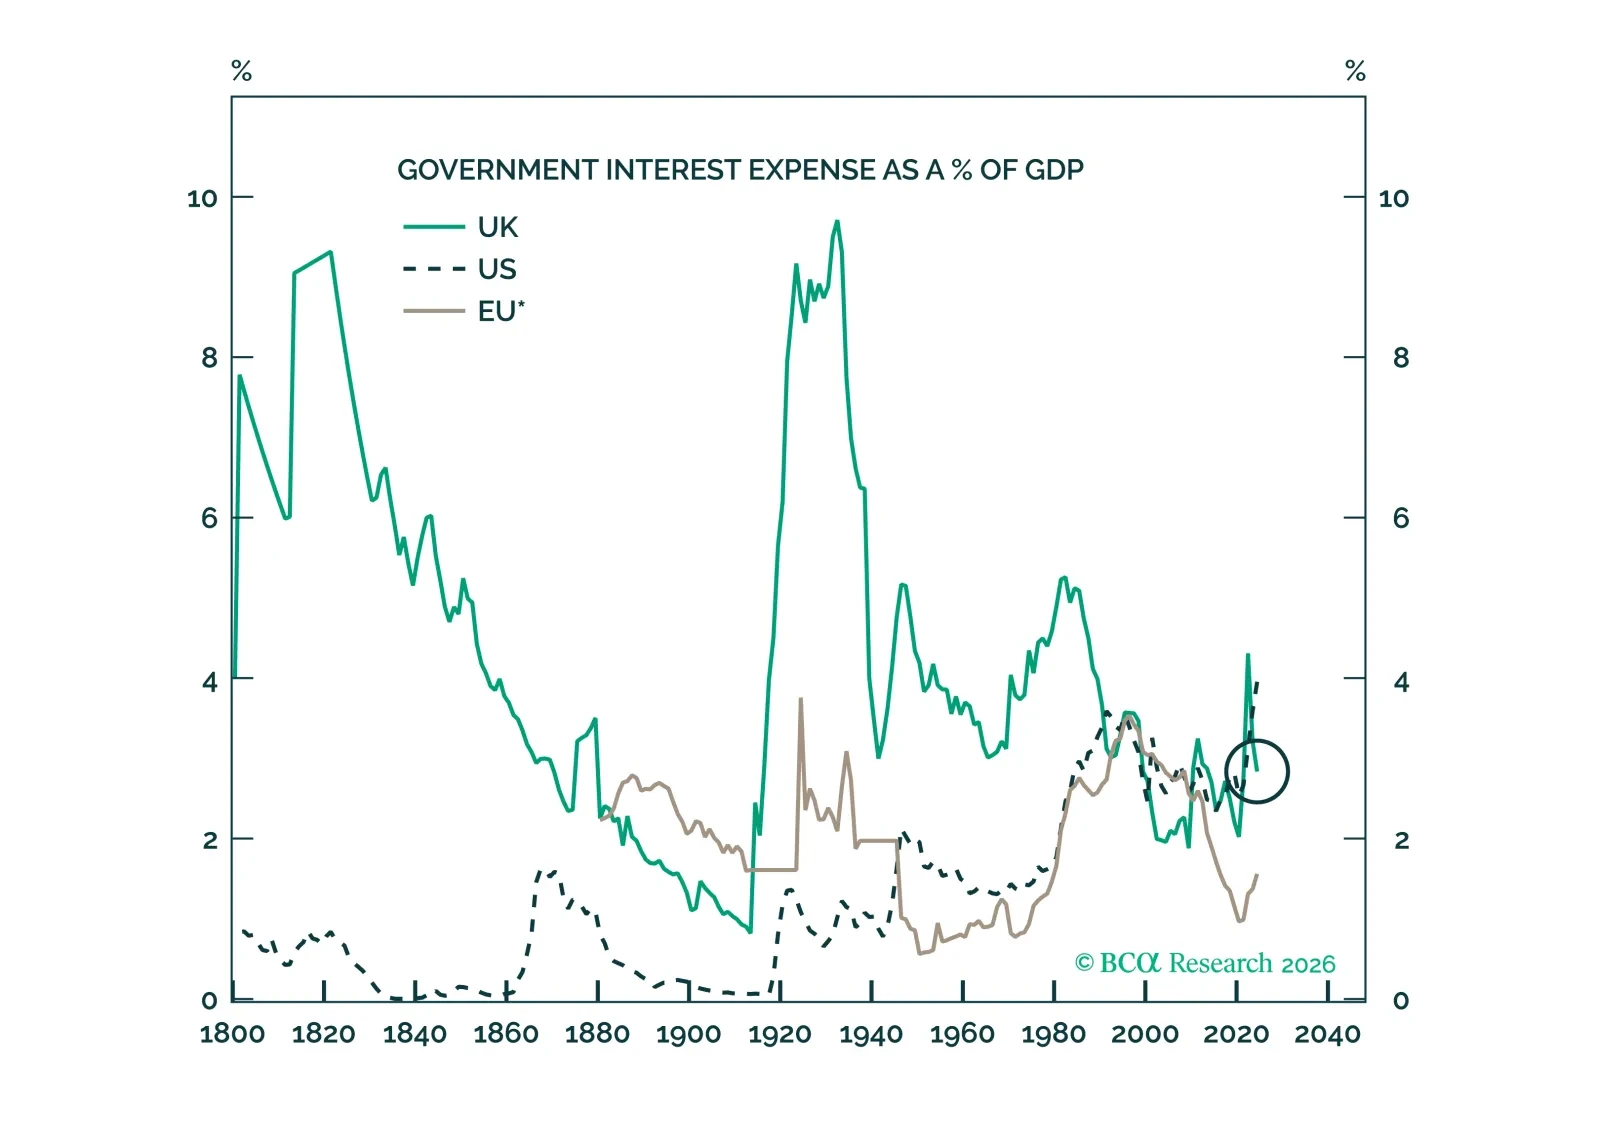
Stay overweight gilts despite renewed political turmoil in the UK.
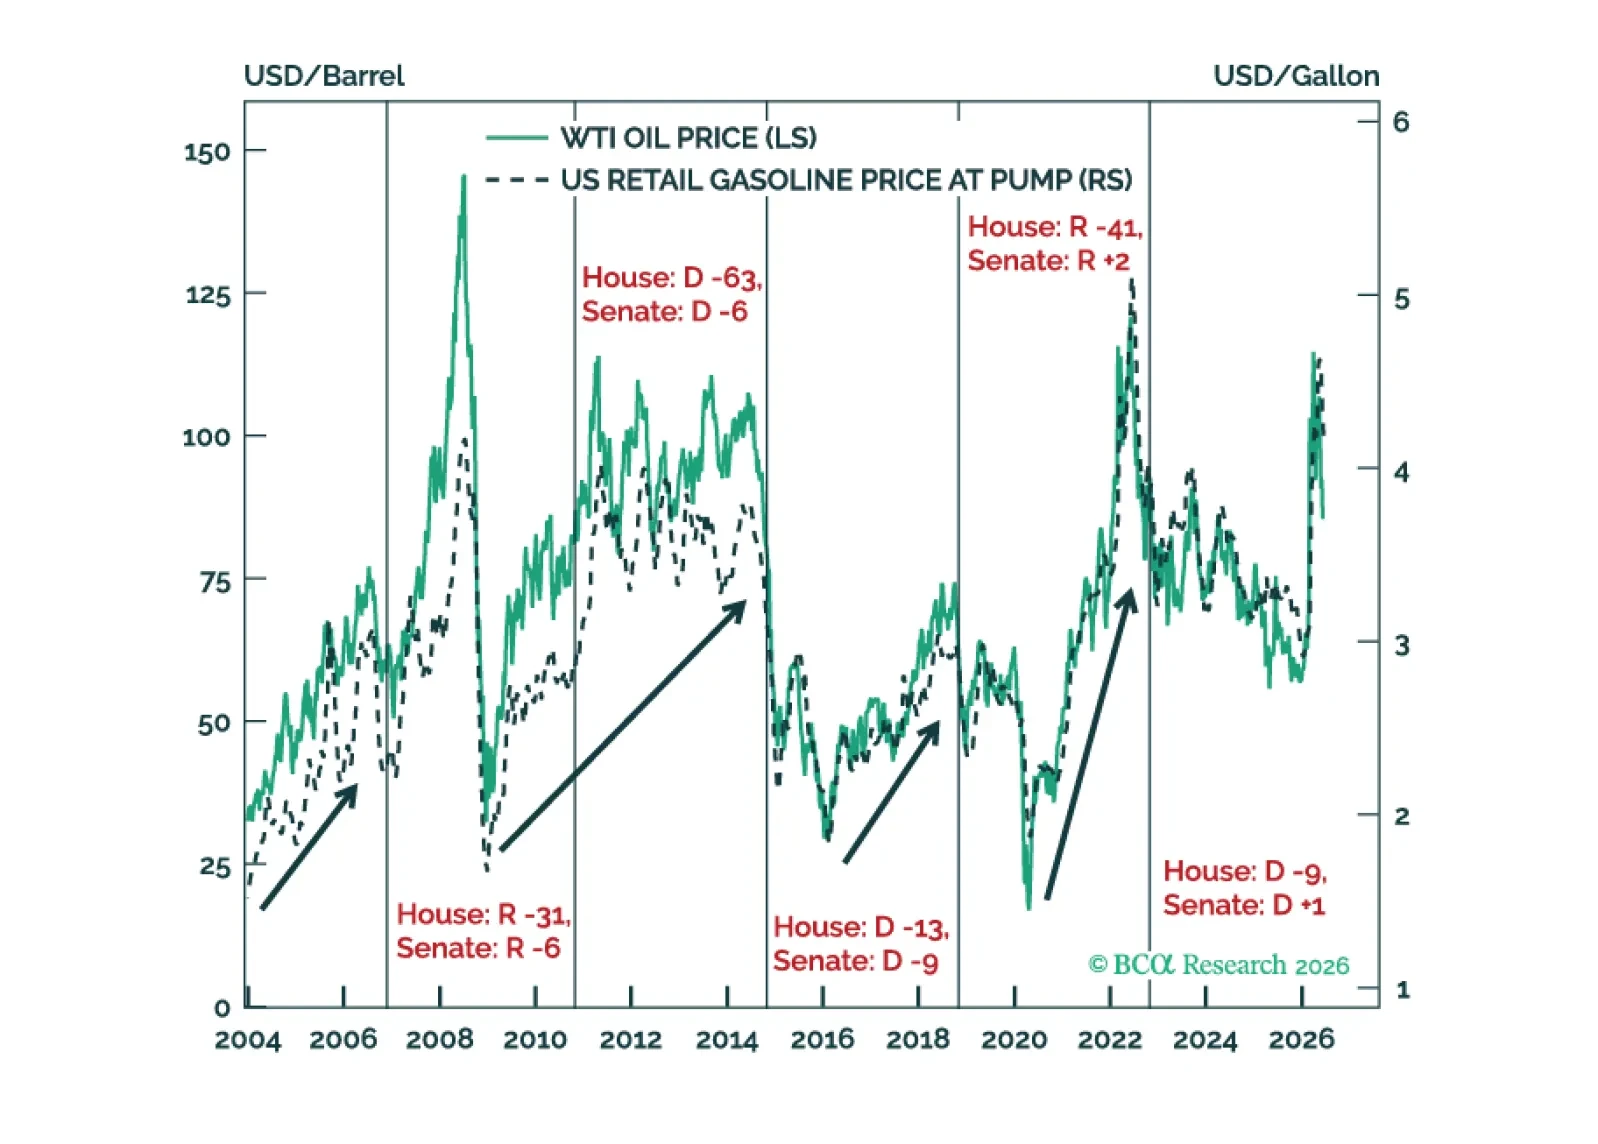
The US-Iran deal offers temporary relief from oil supply risk, but both Hormuz and trade tensions could revive in 2027.