 Explore FICC
FICC | Commodities
Global macro commodity and energy coverage, combining top-down and bottom-up fundamental research. Typically published twice a month.
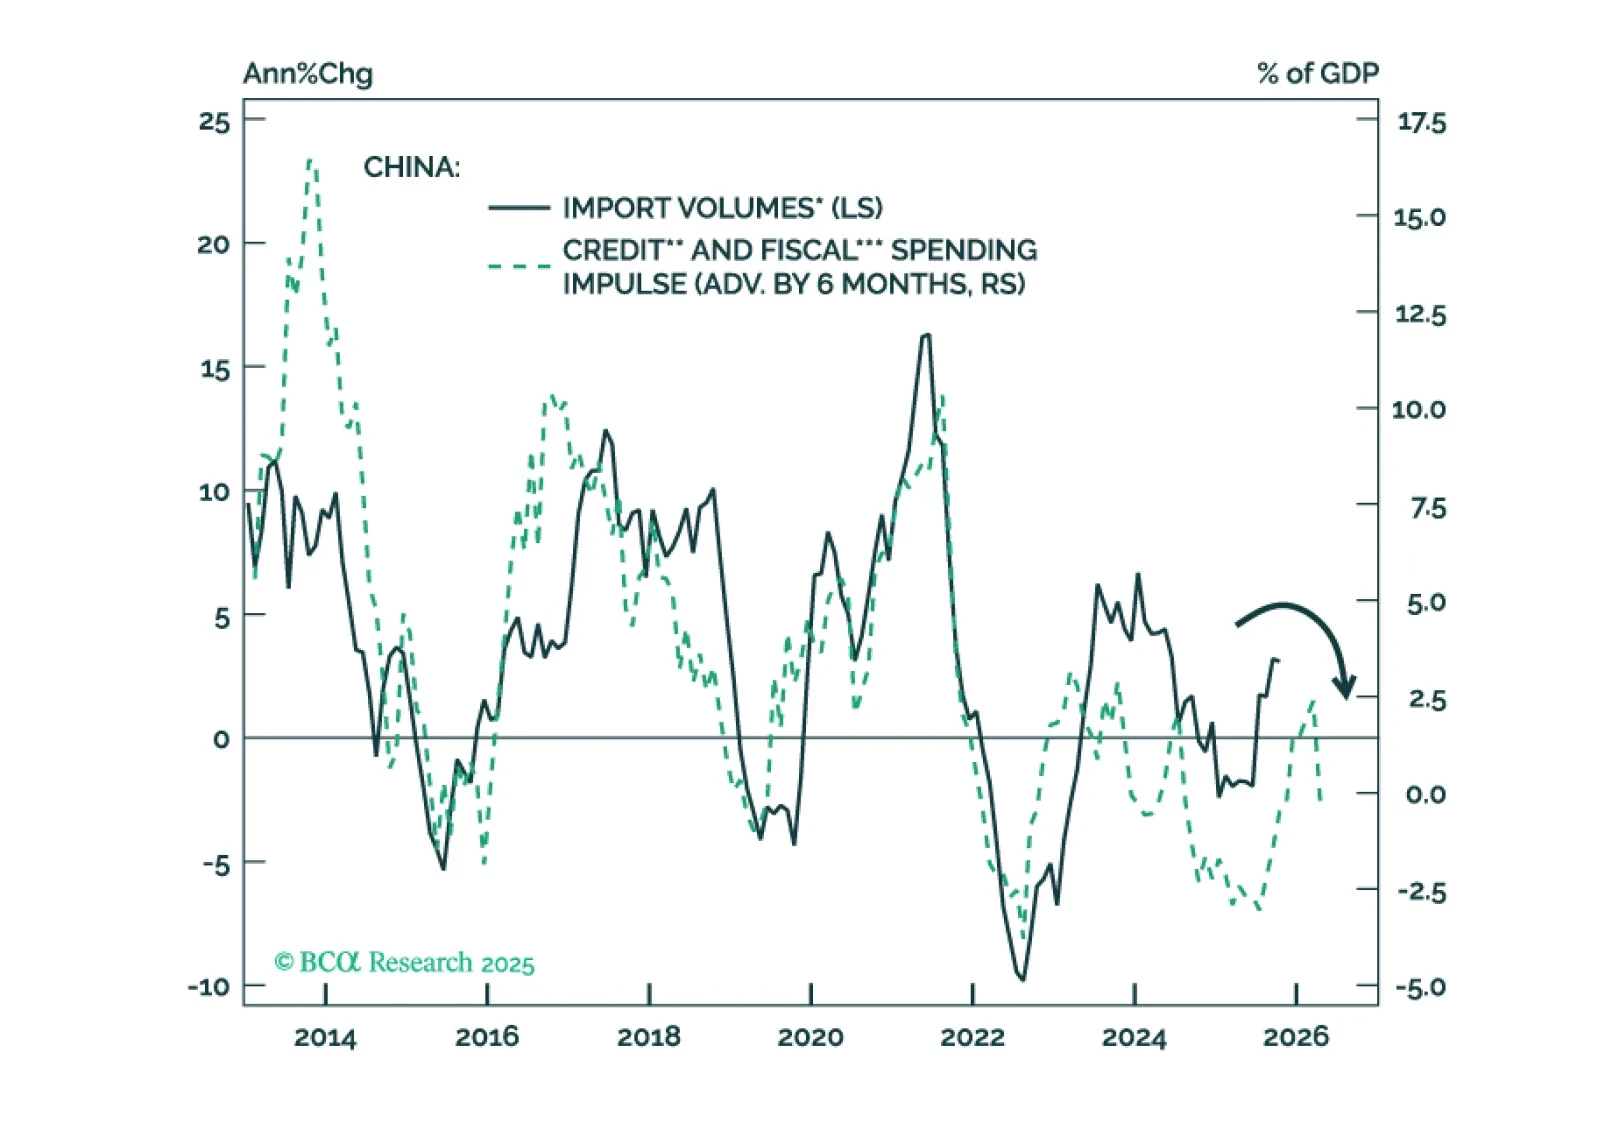
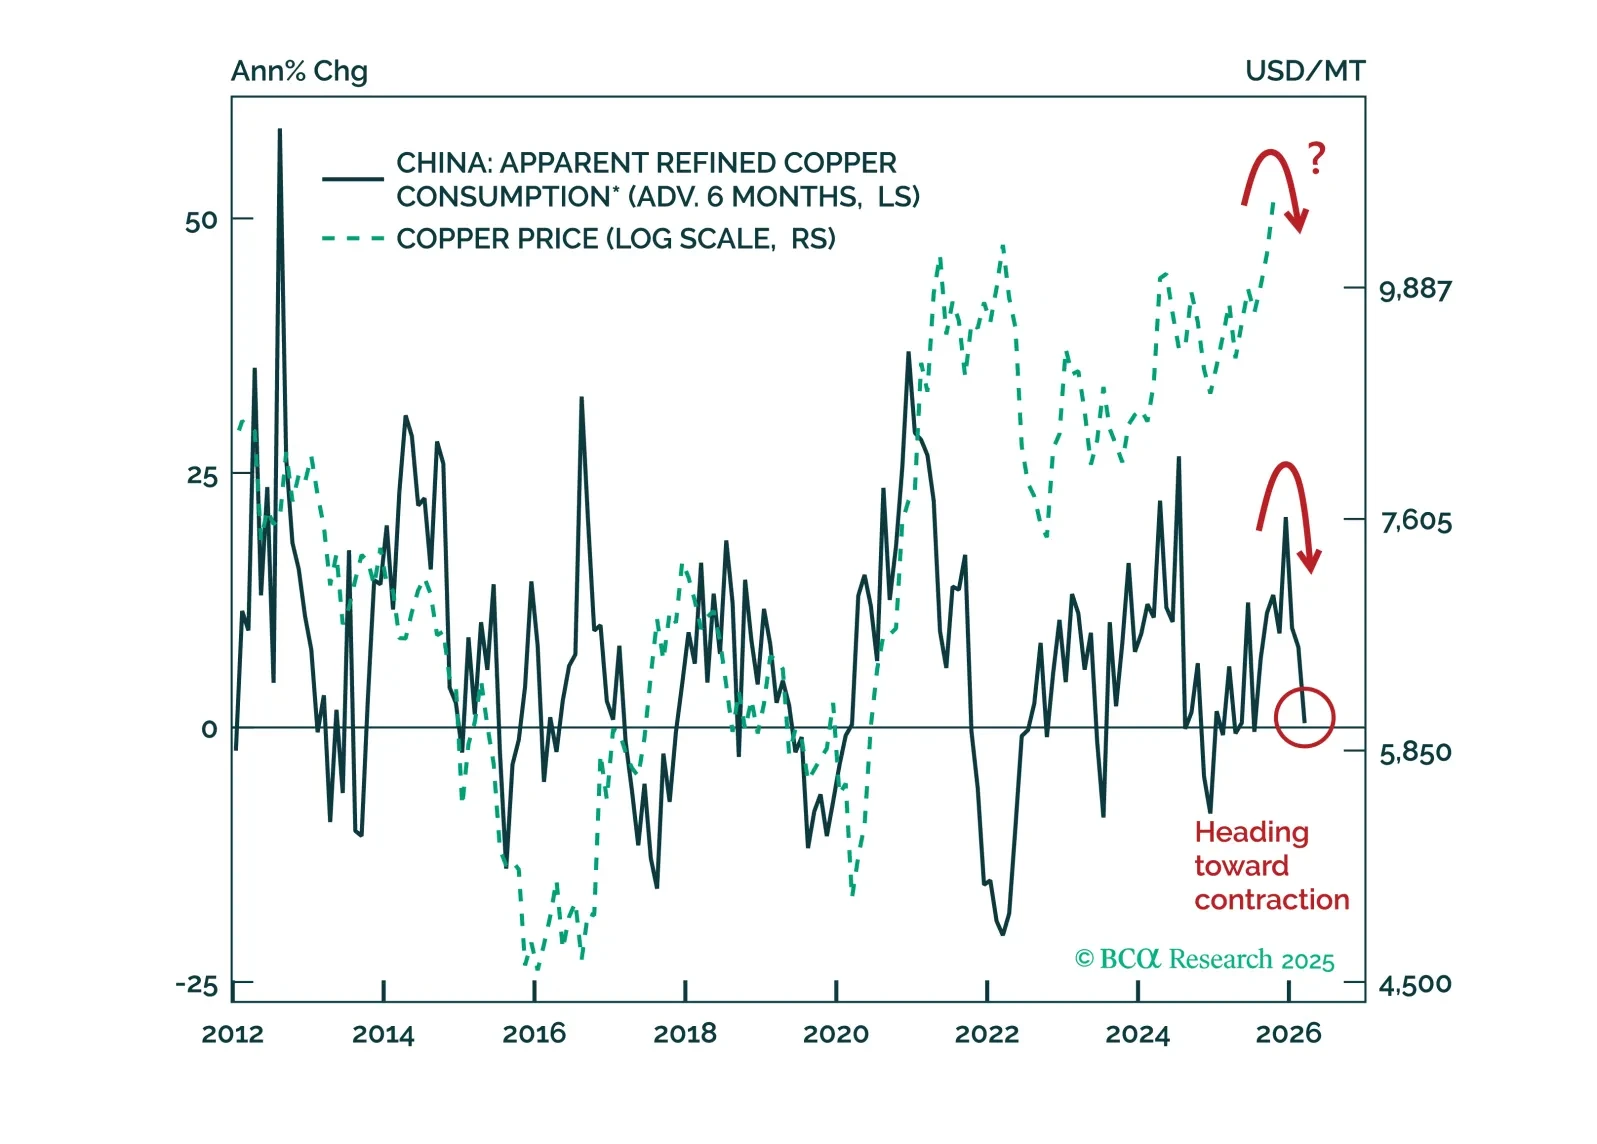
Should investors chase the copper rally or use the latest bout of strength as an opportunity to sell? We warn that weakening Chinese demand and shrinking global manufacturing will weigh on the metal’s price over a cyclical timeframe.
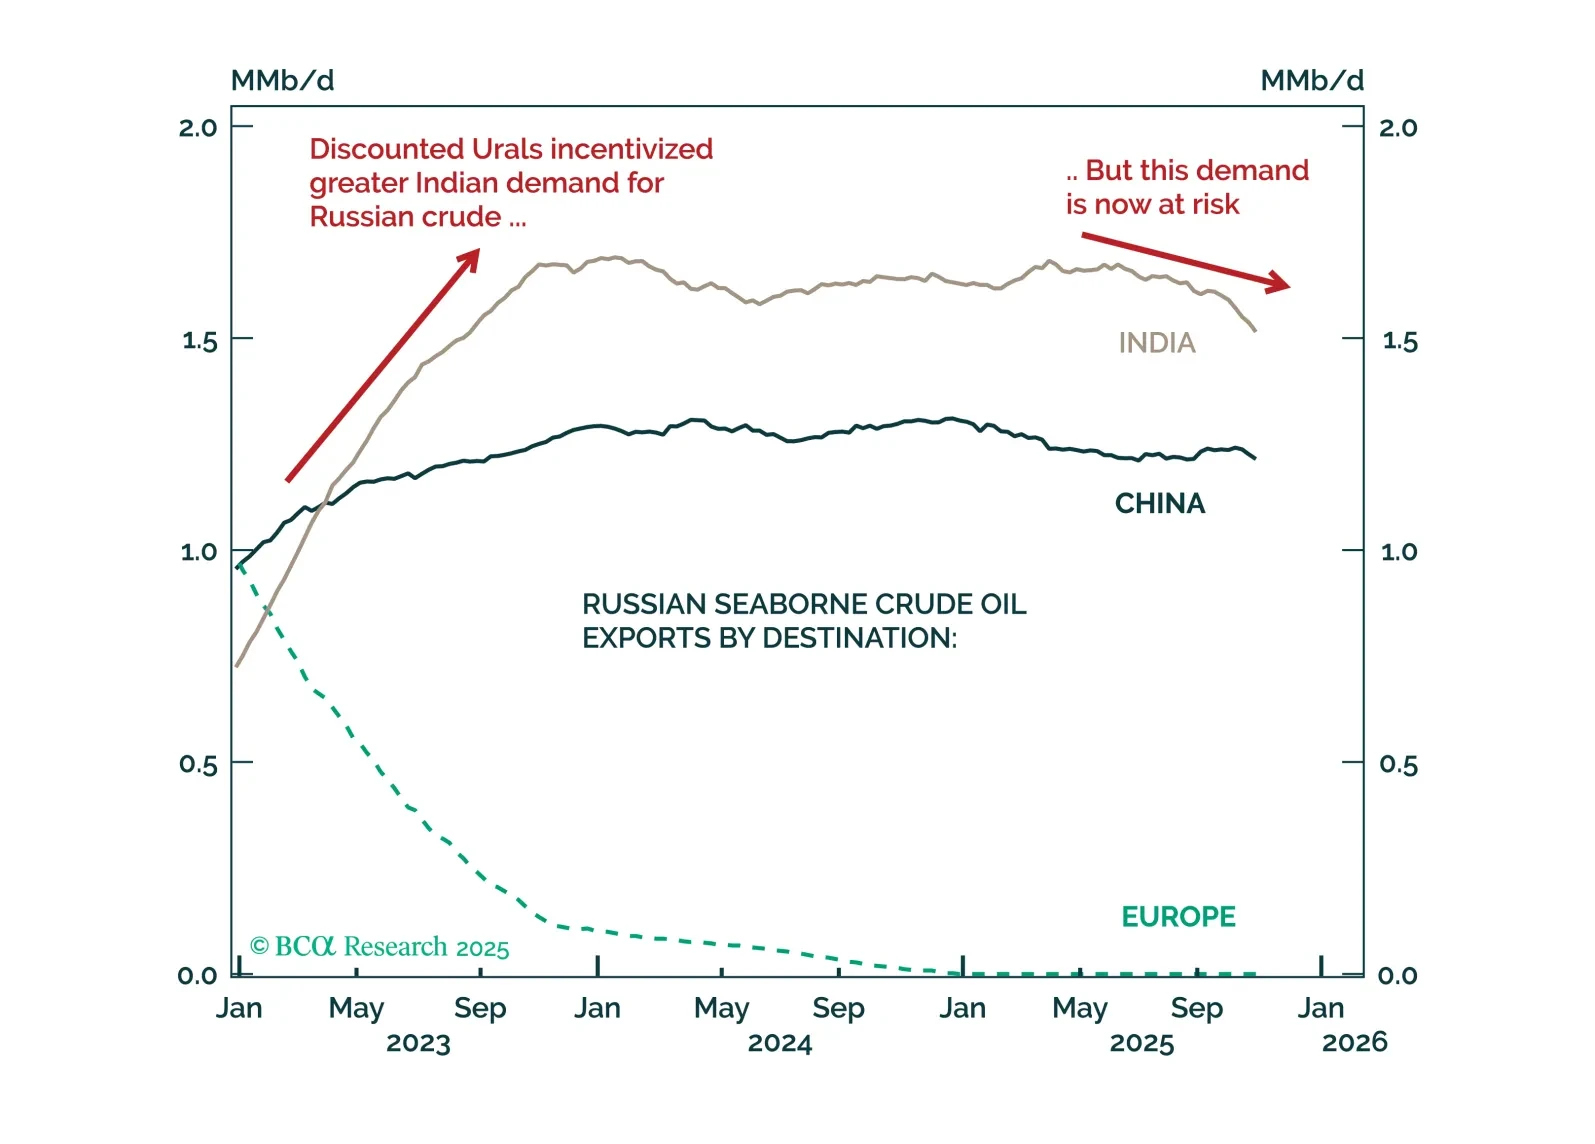
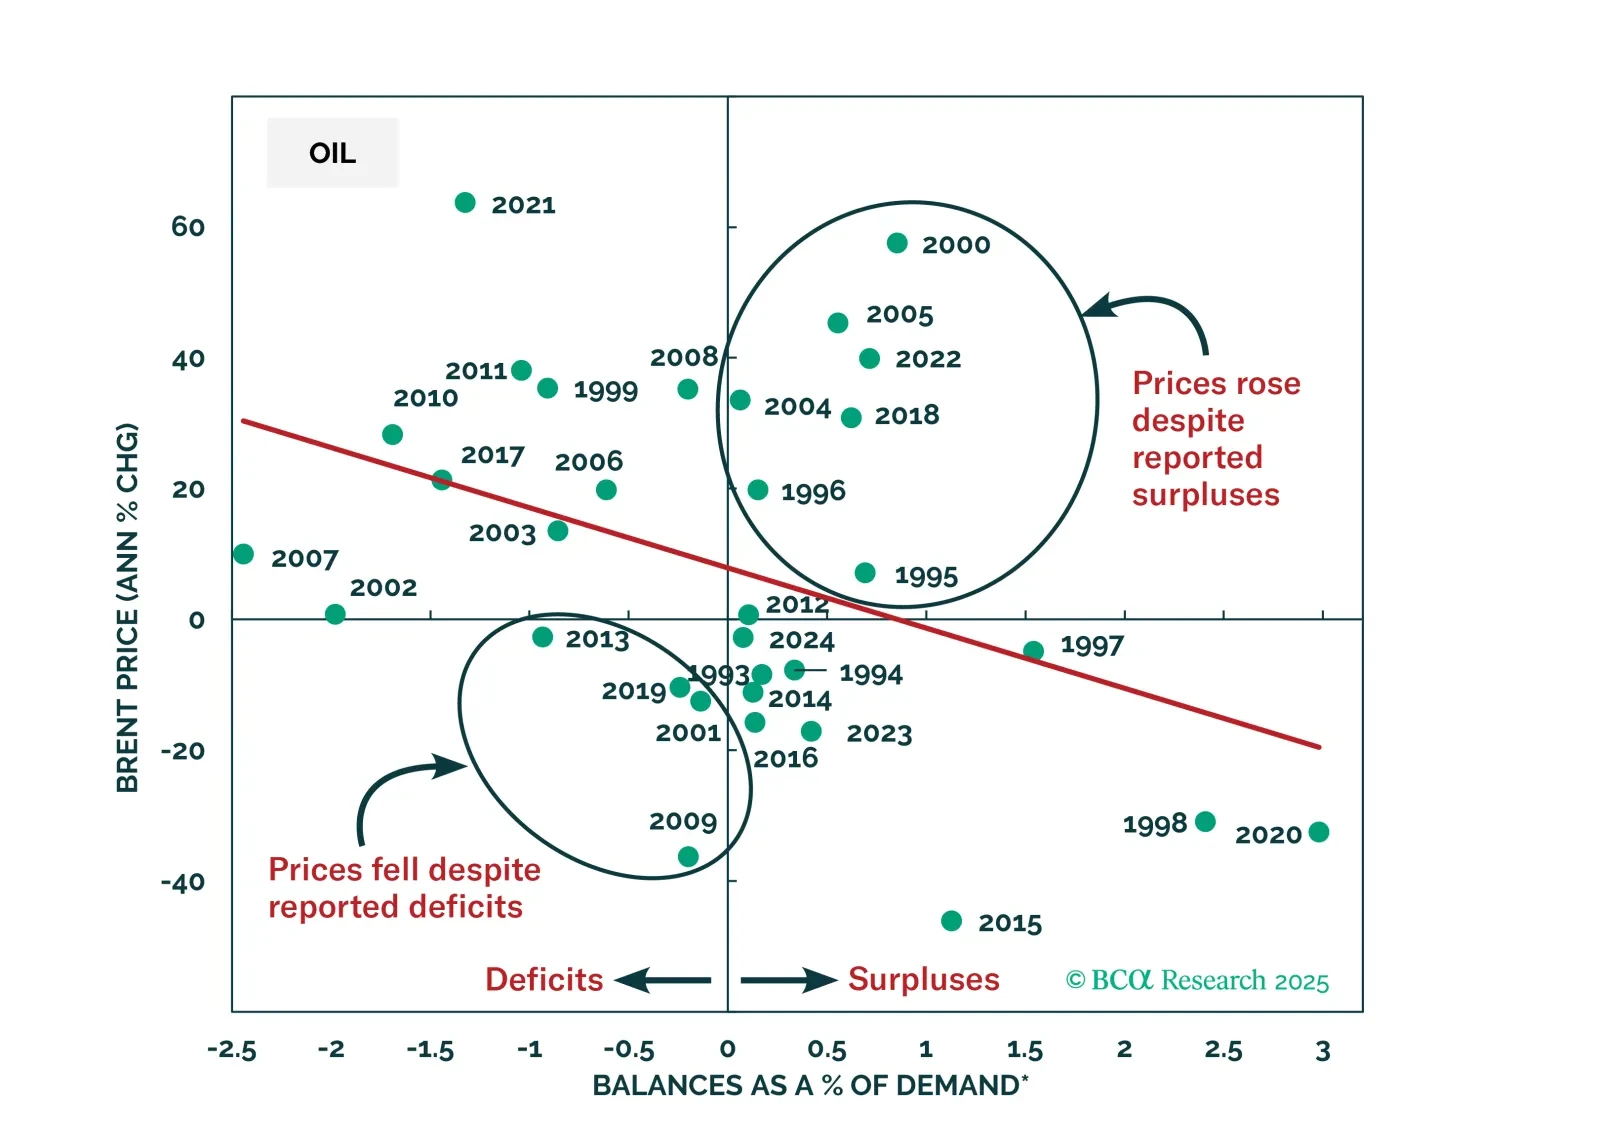
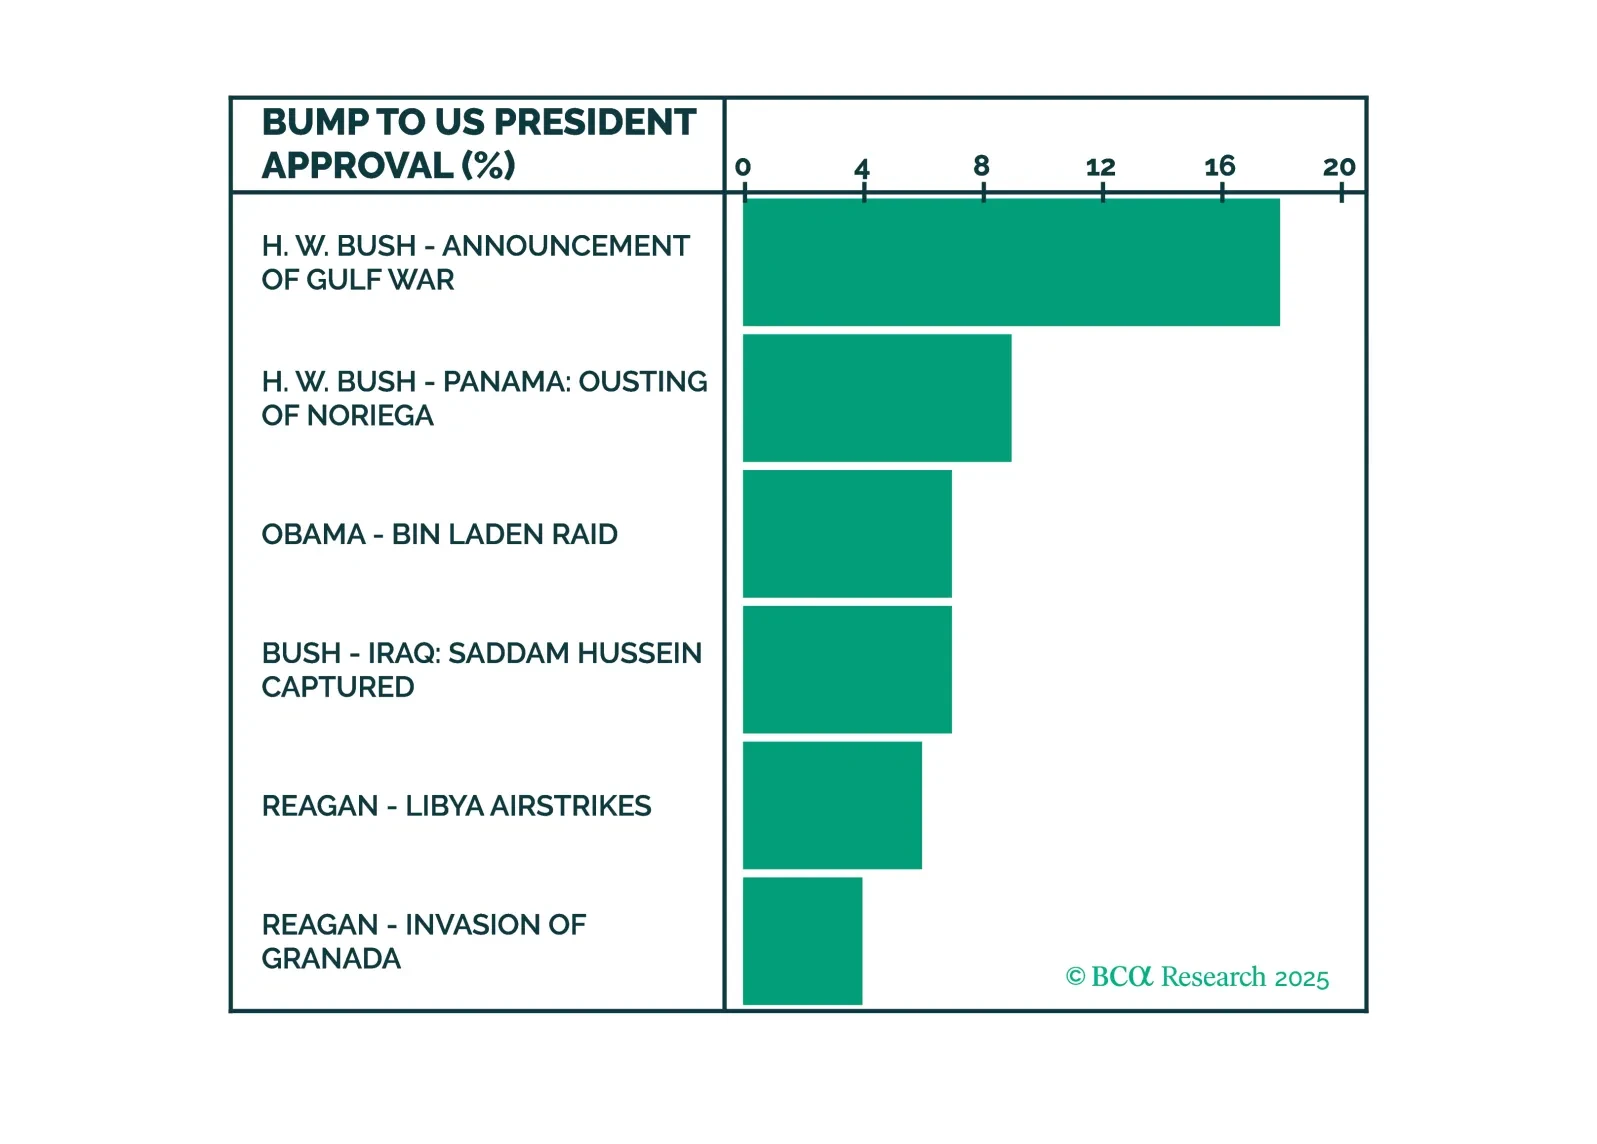
US restrictions on Russian crude exports could disrupt global oil supplies and trade flows over the near term. However, they are unlikely to have a meaningful impact on crude prices over a cyclical timeframe. Stay short Brent.
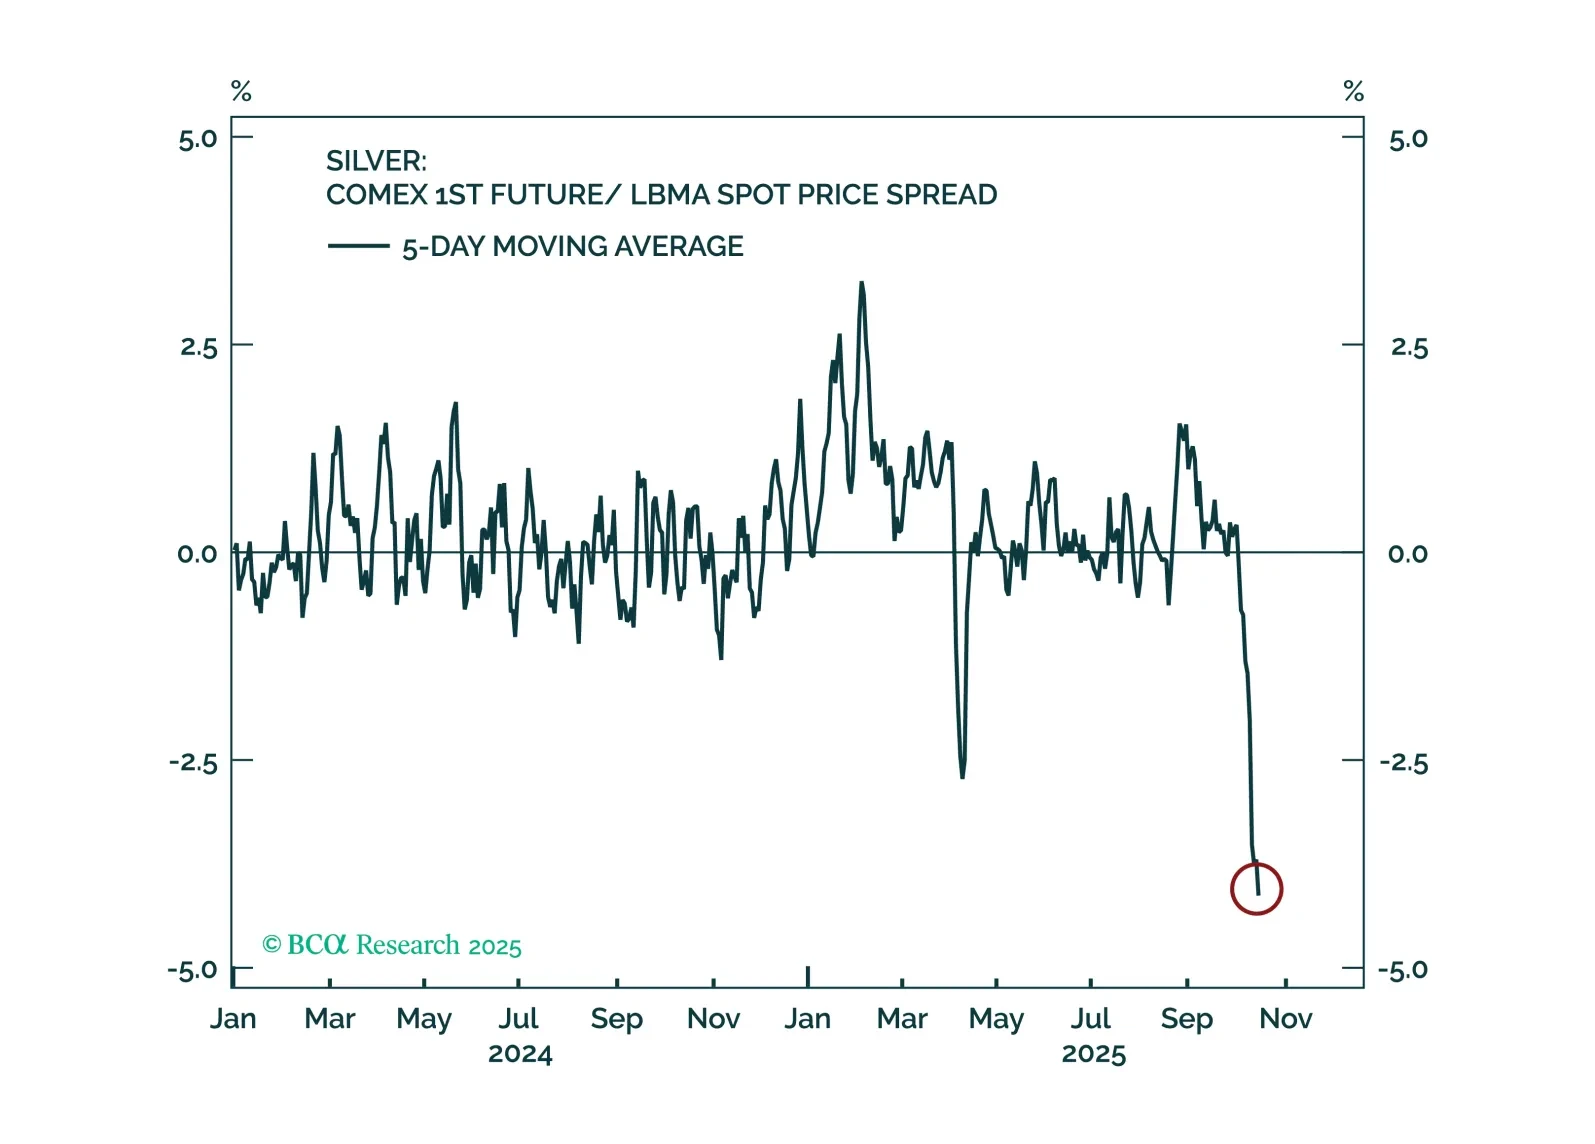
Silver’s short squeeze and stretched technicals warn of a potential tactical pullback.
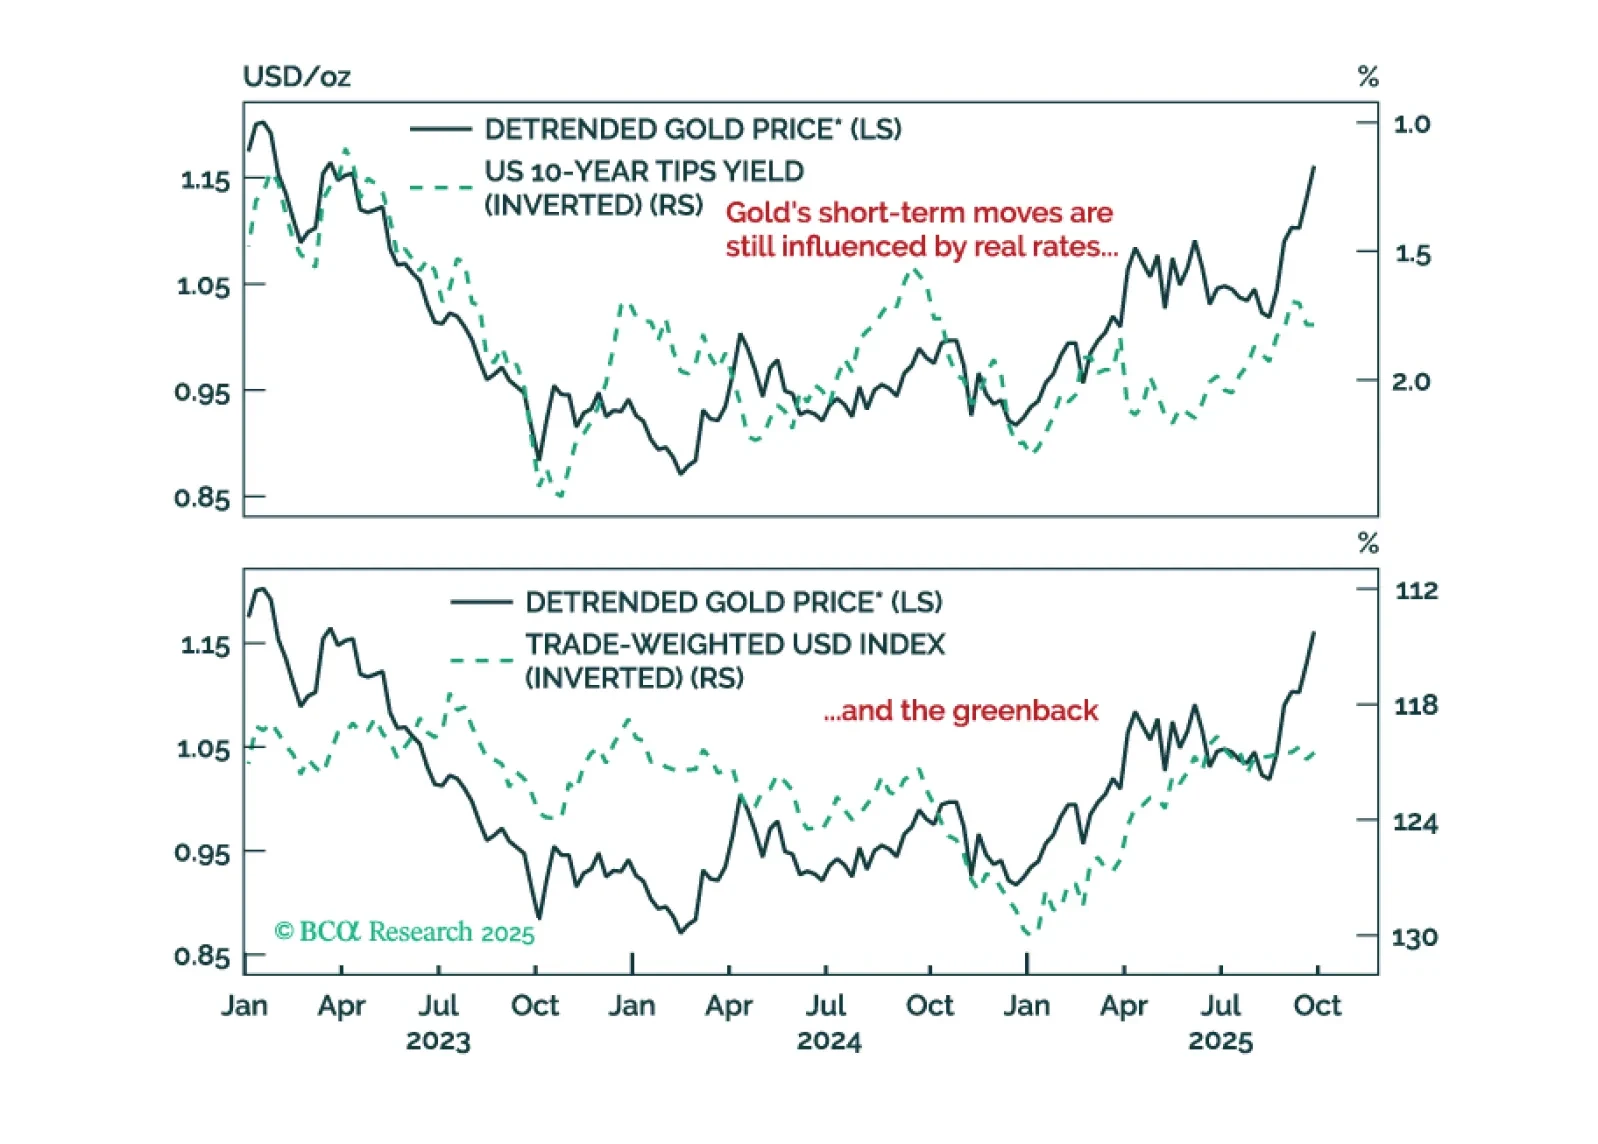
Commodity market breadth would need to improve for it to signal bullish conditions for the aggregate commodity complex. We maintain a defensive tilt within commodities, favoring precious metals over the more cyclically sensitive energy and industrial metals.
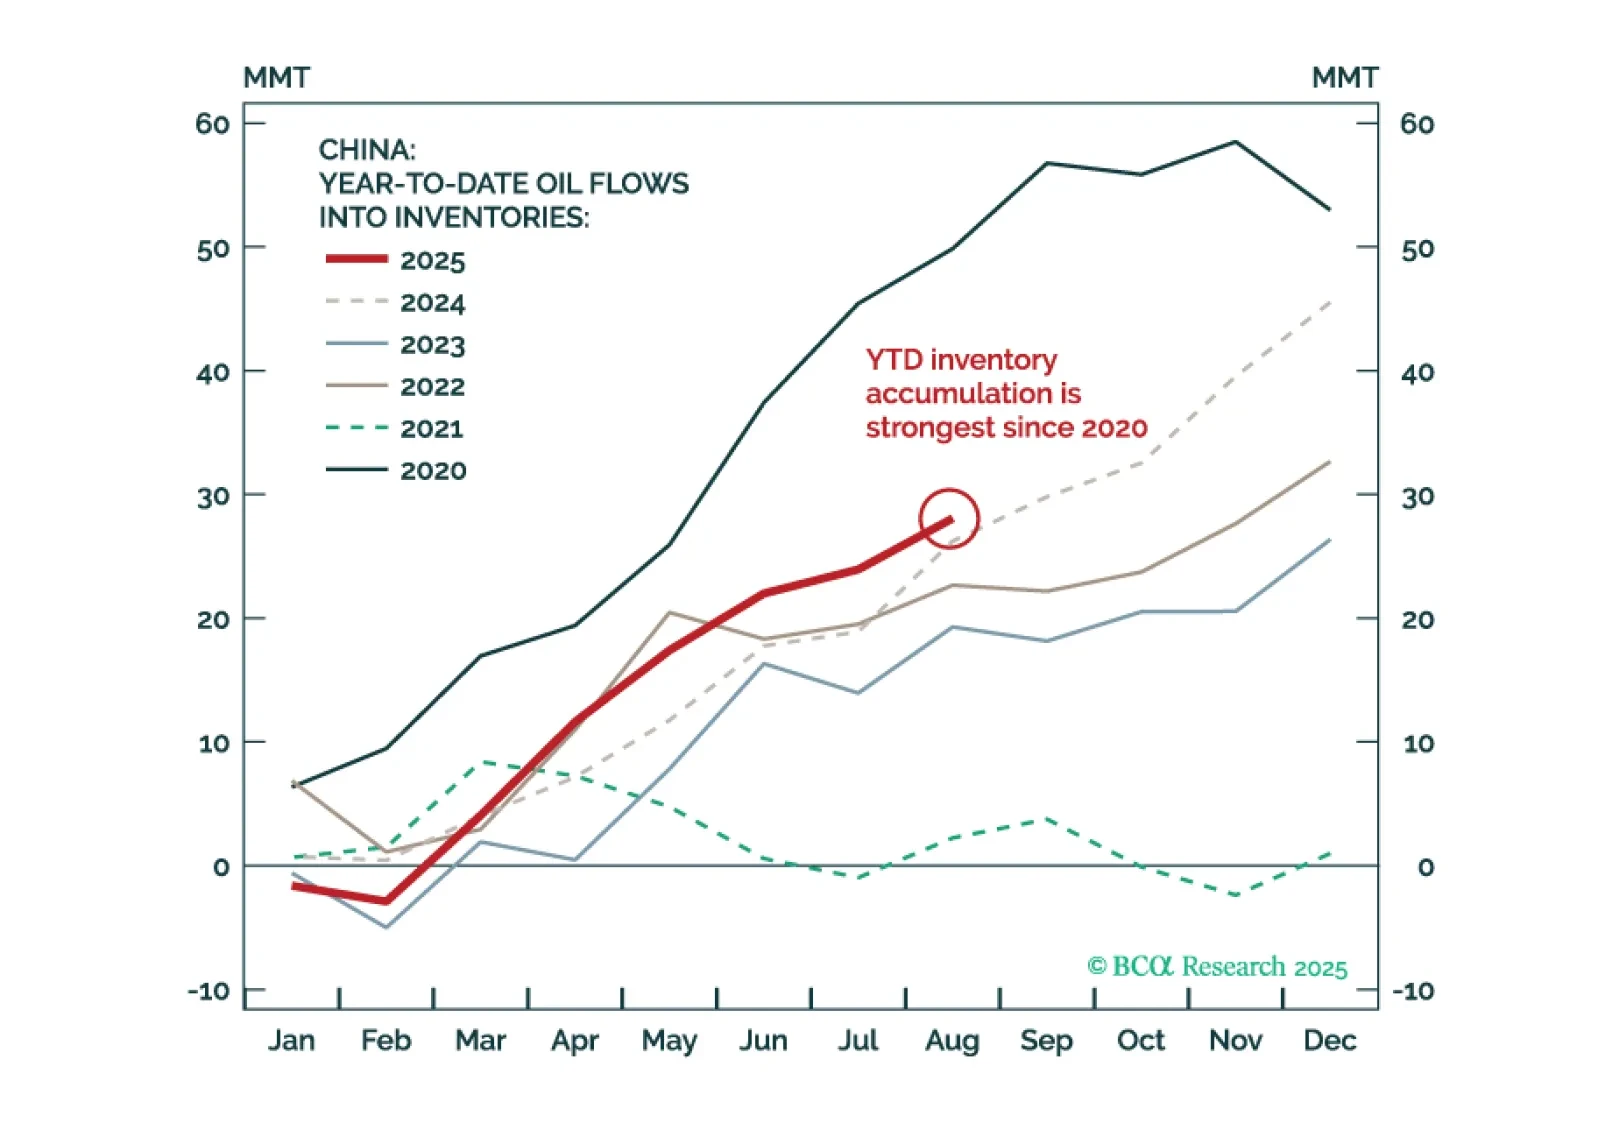
We remain cyclically short Brent but are tightening the stop loss to $73/bbl to guard against a geopolitics-driven upside break.
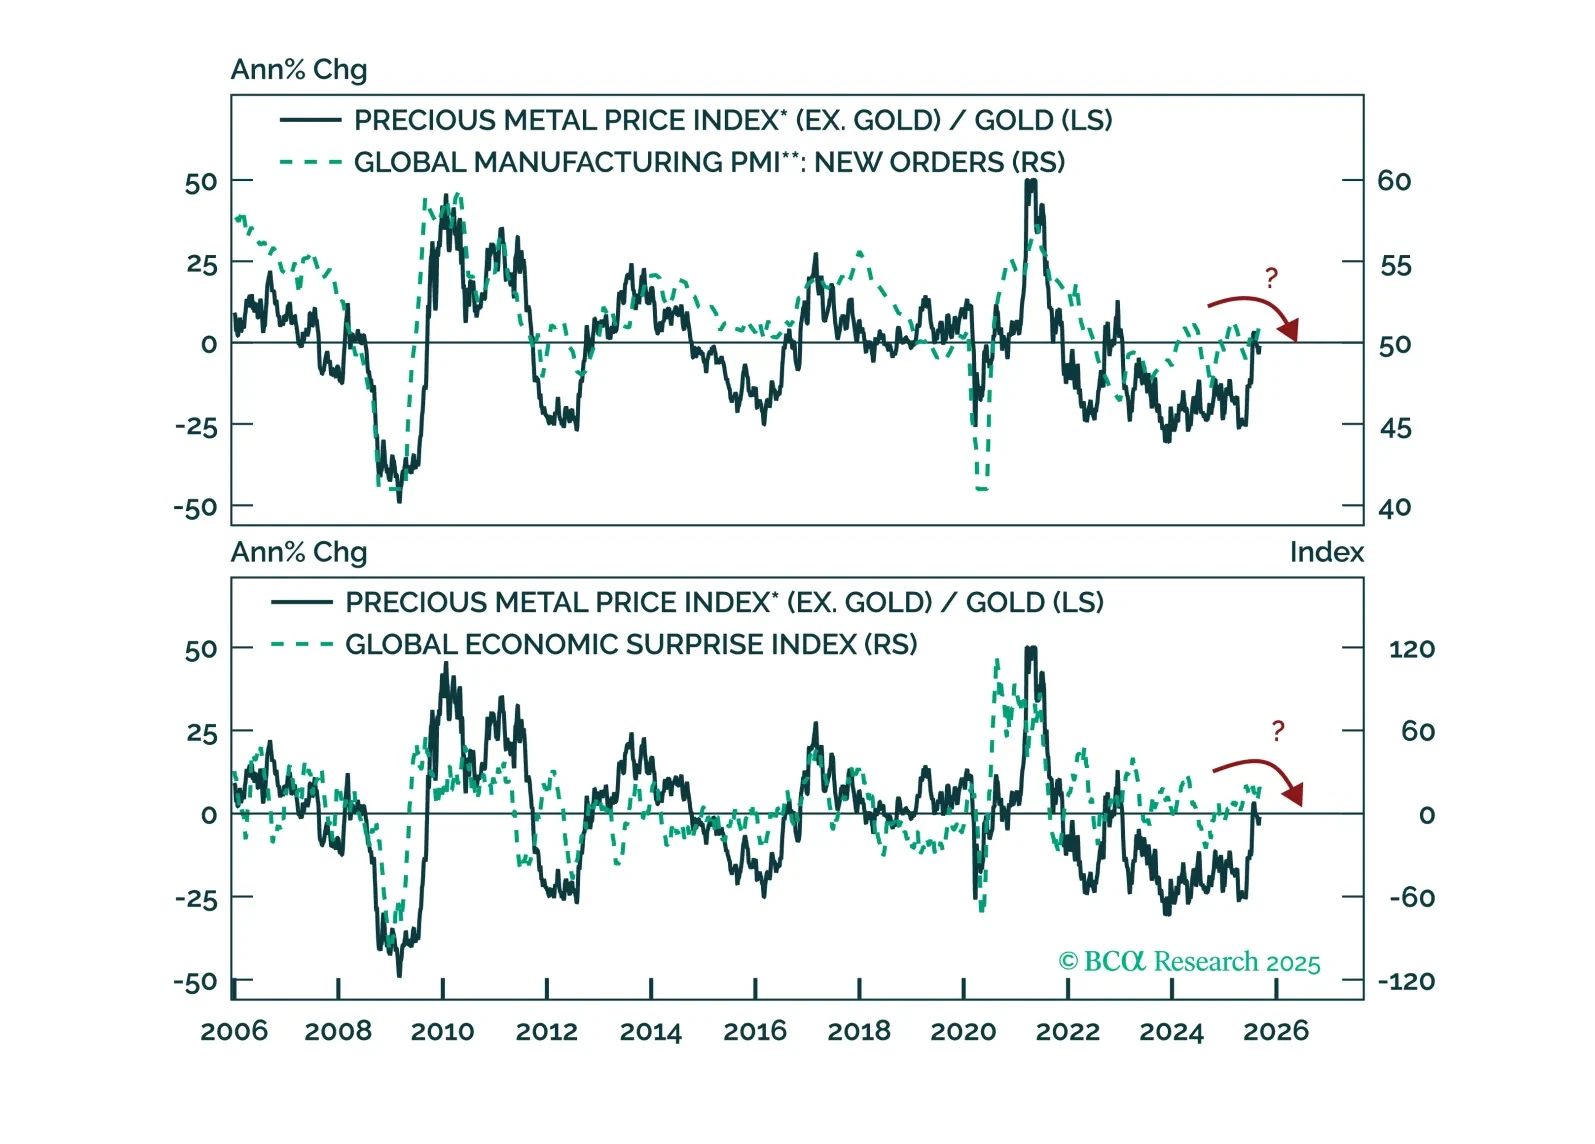
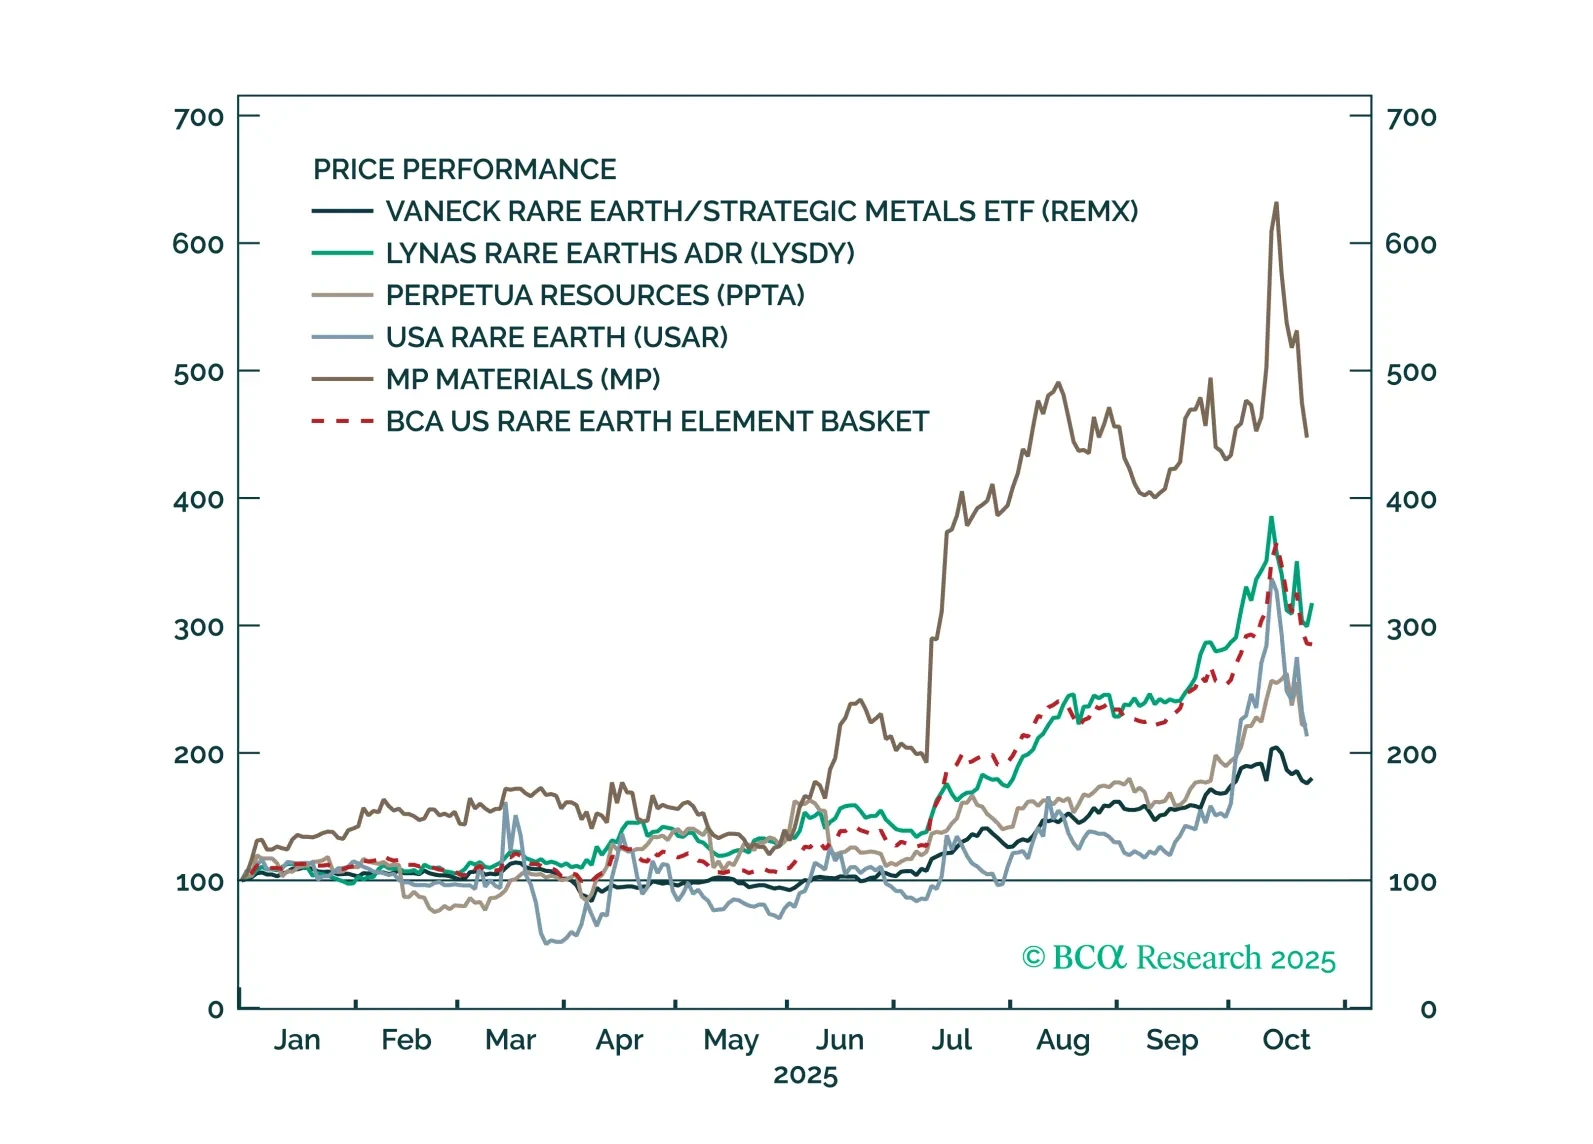
Silver, platinum, and palladium may ride the same cyclical tailwinds as gold in the coming months. However, four key risks threaten their relative performance versus the yellow metal.