 Explore FICC
FICC | Commodities
Global macro commodity and energy coverage, combining top-down and bottom-up fundamental research. Typically published twice a month.
Drone and ballistic missile attacks were slowing, as of March 11. Air traffic in the region was also slowly recovering, as the pace of attacks declined. Warning, however: Reports from US CENTCOM and the IDF claim that Iran still has around 40% to 50% of its stockpile of missiles and launchers. Attacks are continuing, even though at a reduced tempo.
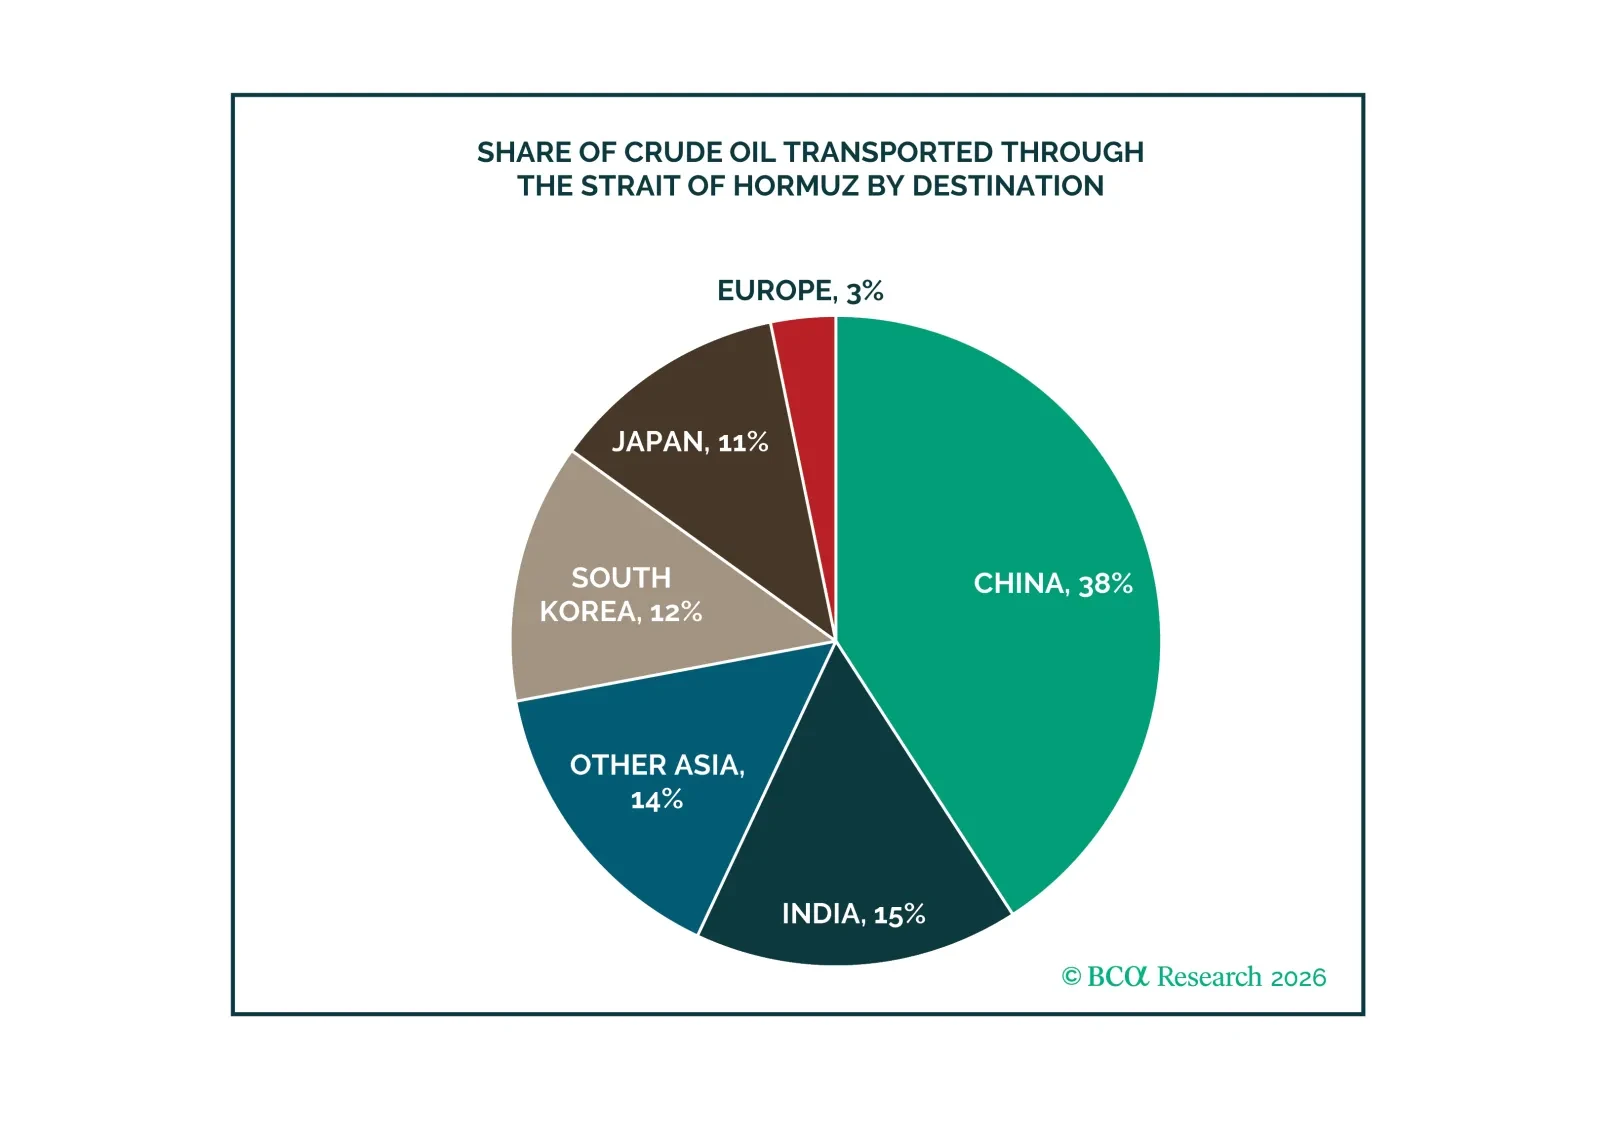
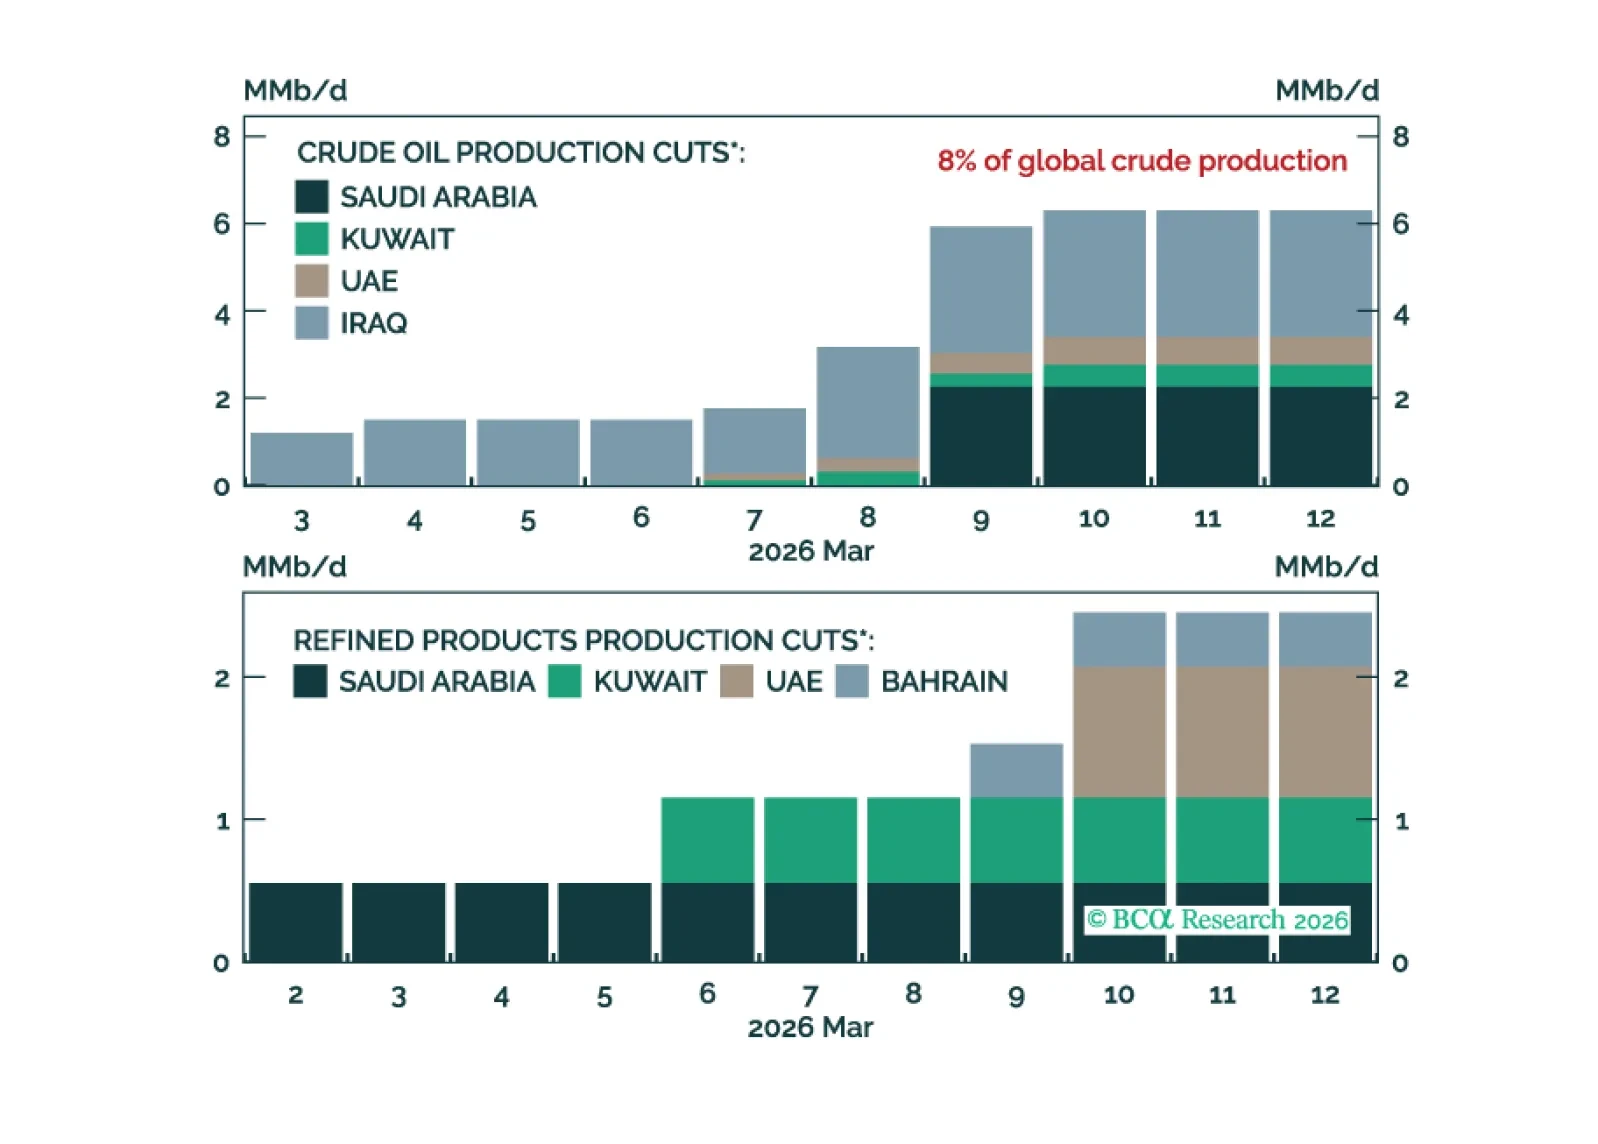
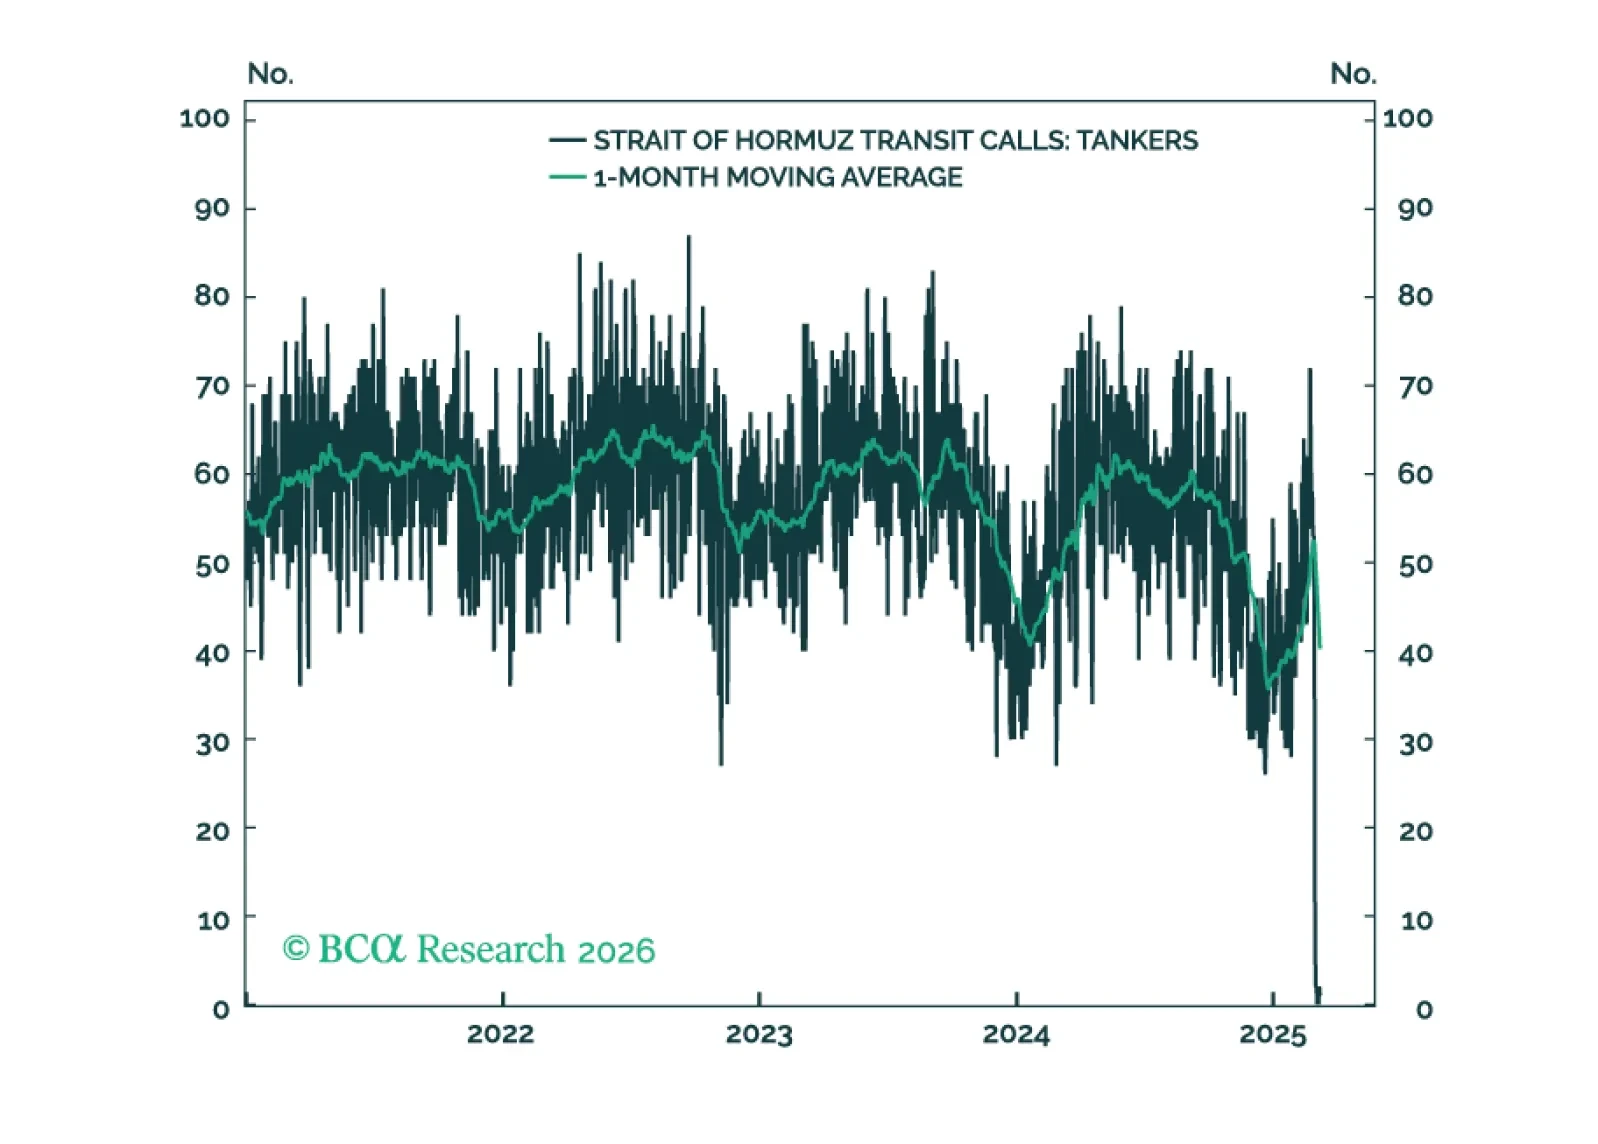
The war in Iran is disrupting global oil and LNG flows and remains a threat to regional energy infrastructure. Energy price risks remain skewed to the upside over the near term.
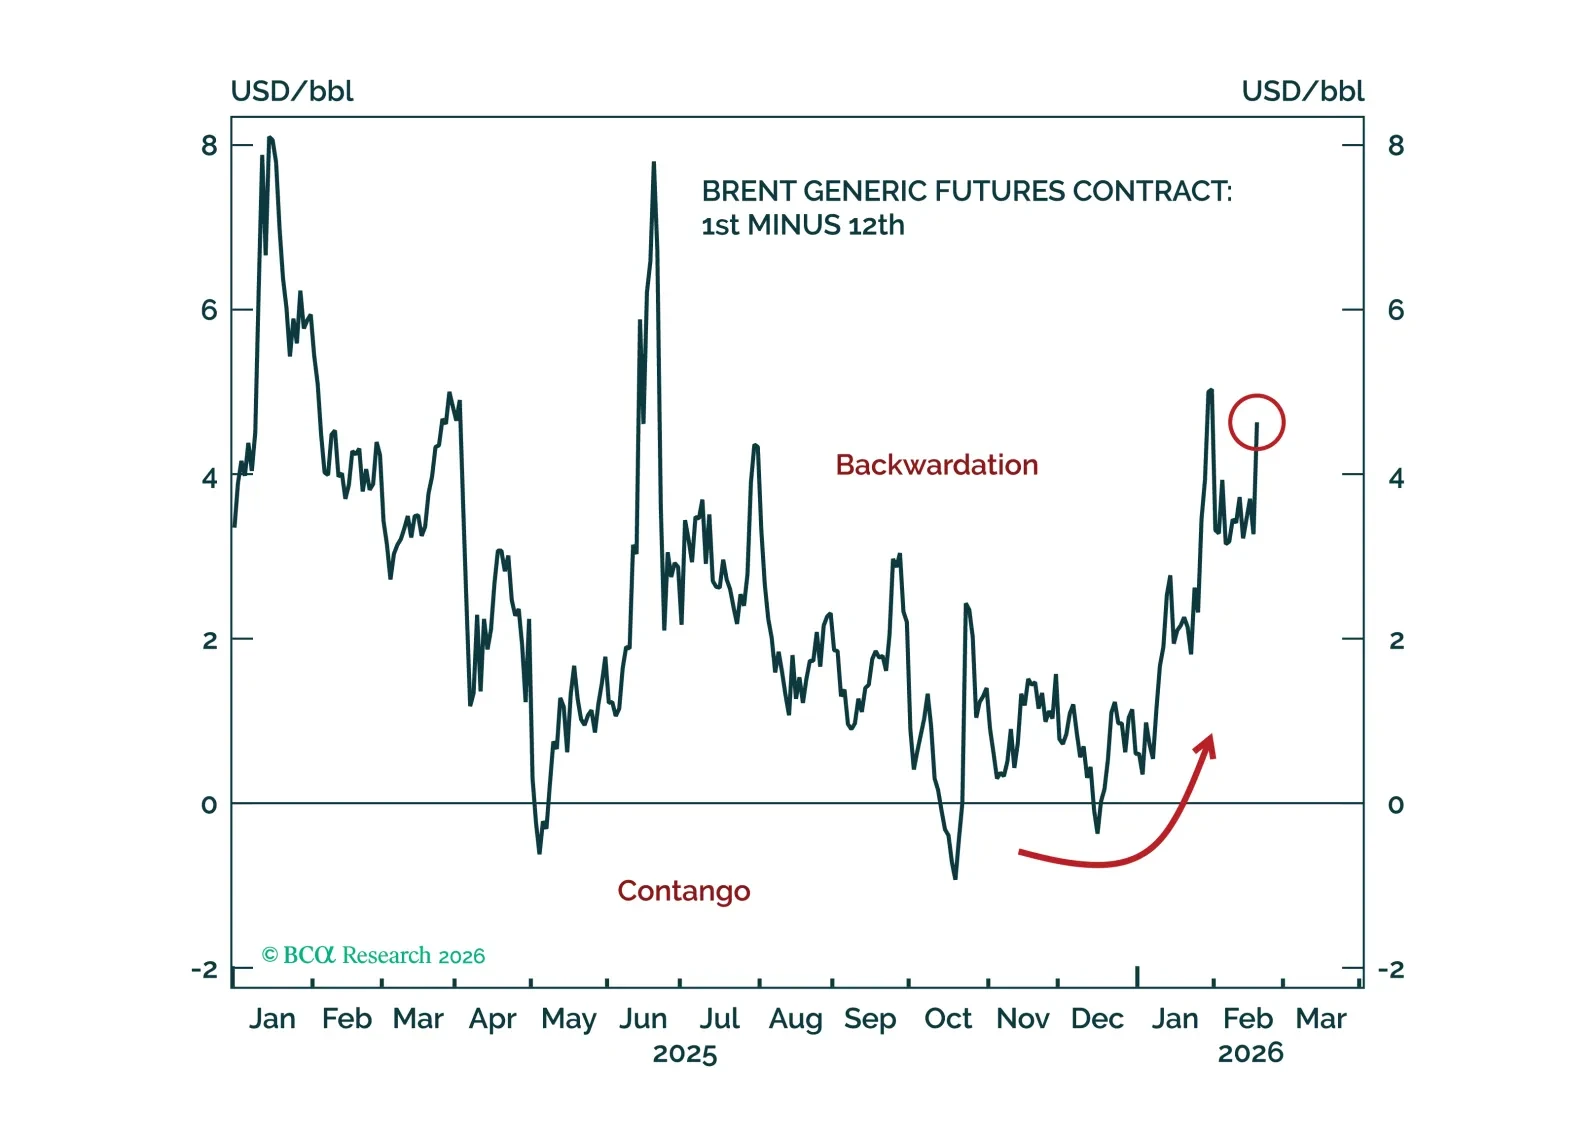
Oil price risks remain skewed to the upside over the near term as geopolitical risks continue to dominate. Nevertheless, we ultimately expect bearish fundamentals to reassert themselves over a six-to-12-month timeframe and drive oil prices lower.
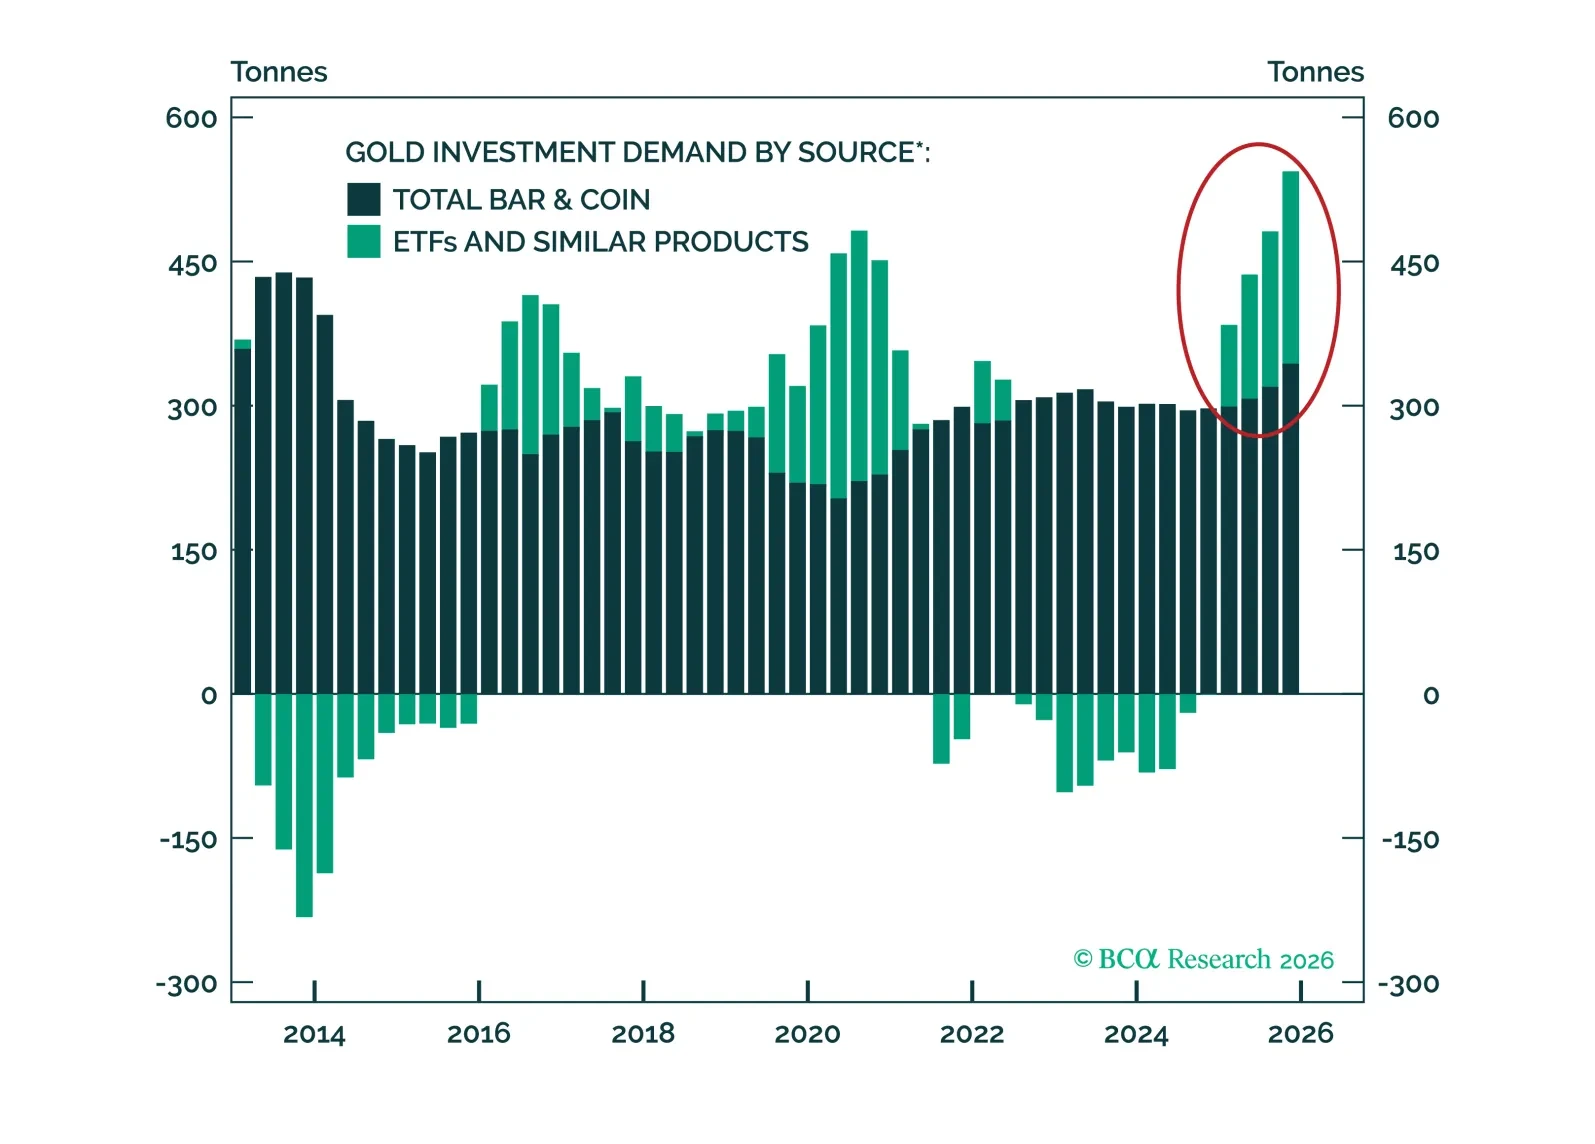
This report flags near-term risks for gold. Yet we remain optimistic about the prospects for its long-term bull market.
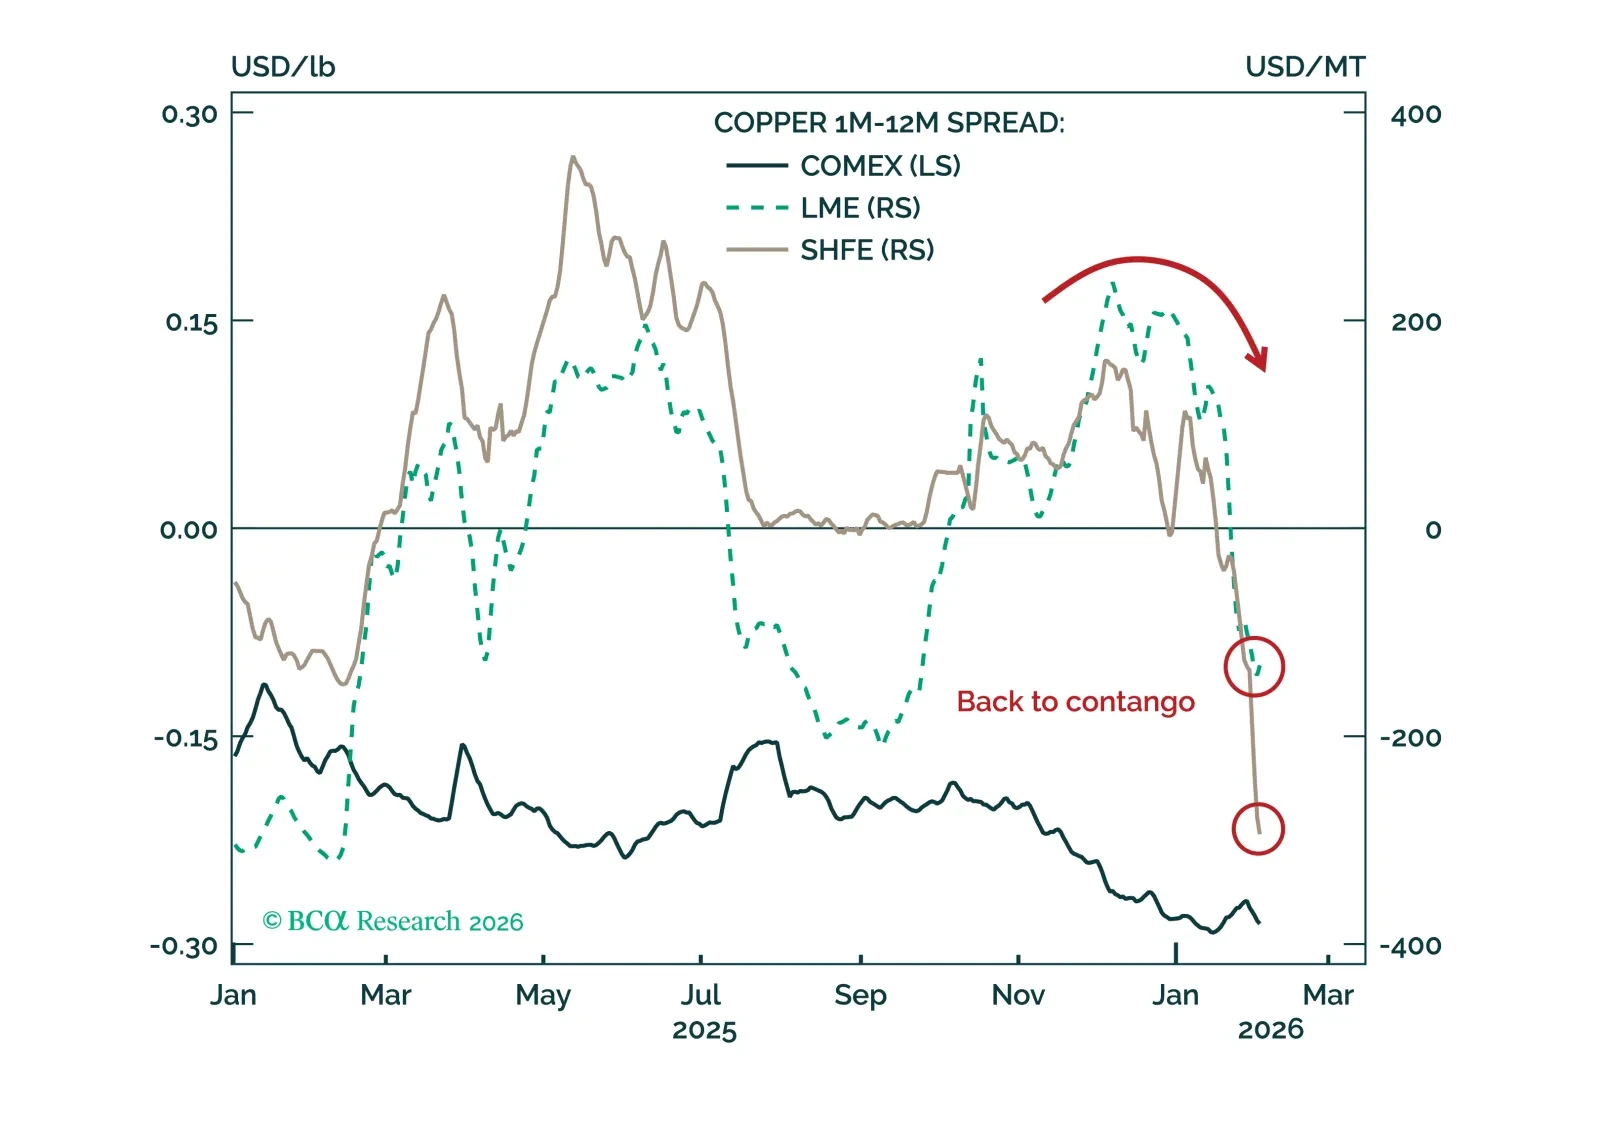
The metals mania is fueling extreme volatility. In particular, the price of copper has become detached from fundamentals and is vulnerable to the downside.
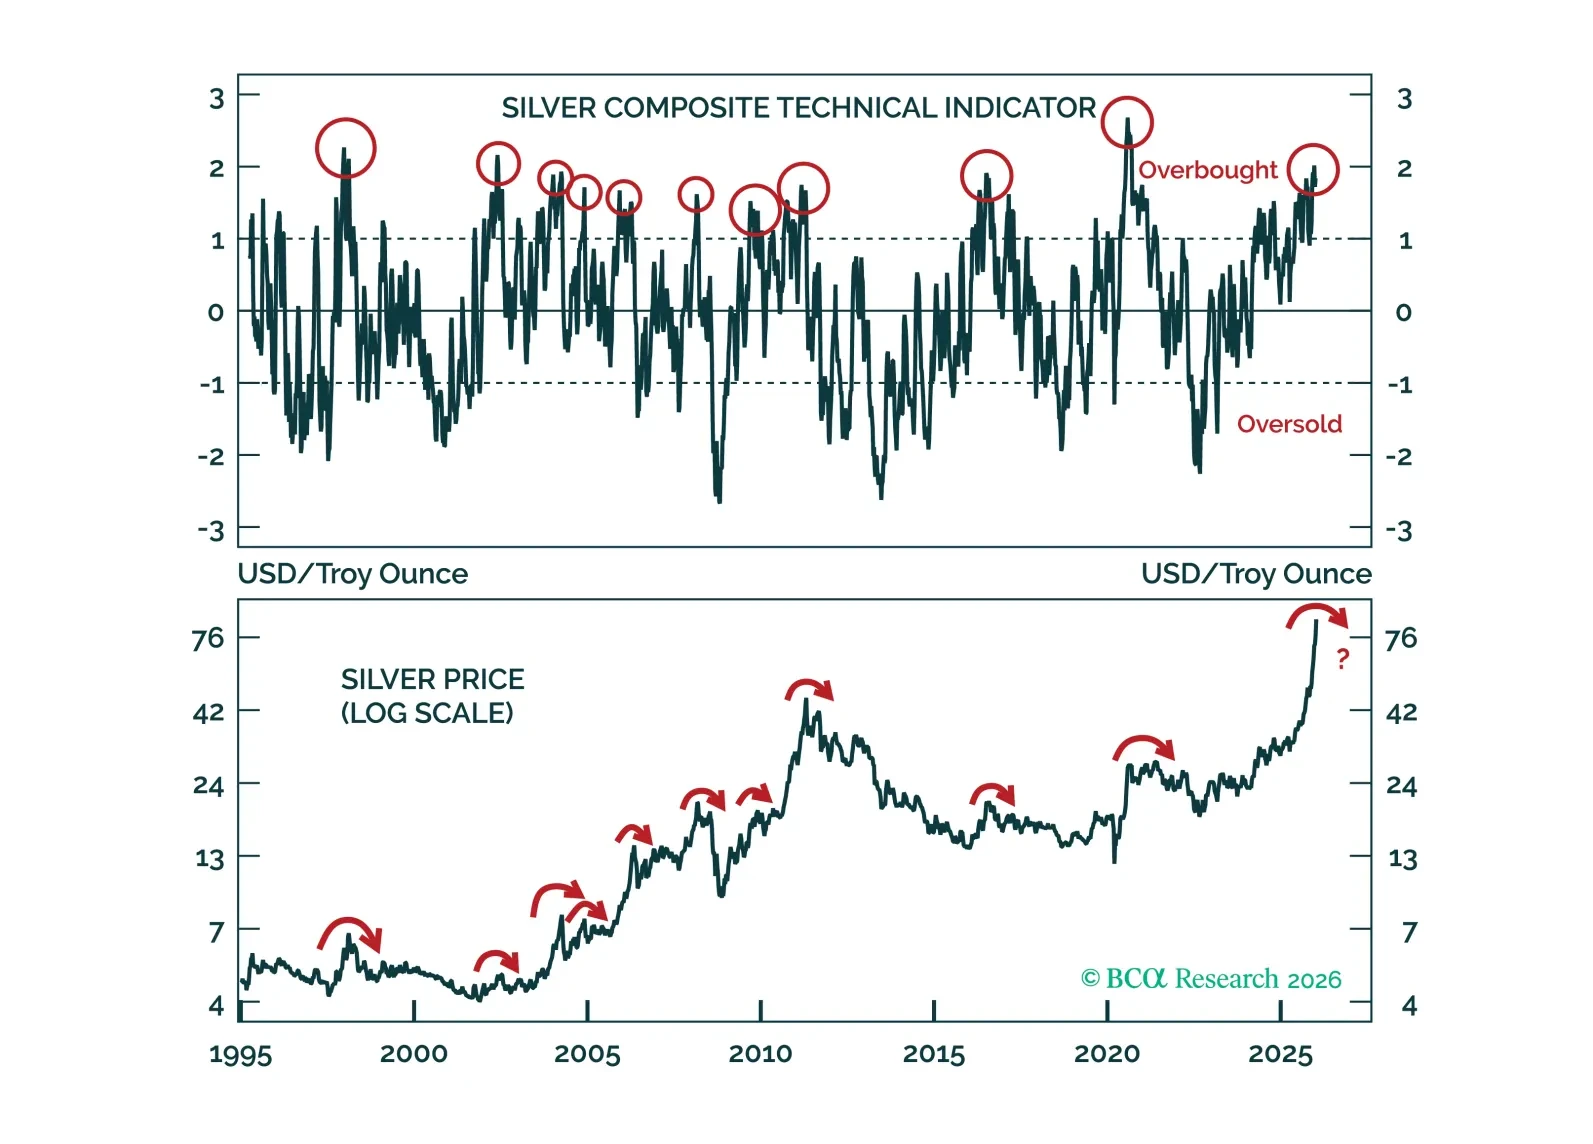
After silver's parabolic surge, we assess the rally's vulnerability by examining its weakest links. We conclude that silver is ripe for a pullback.
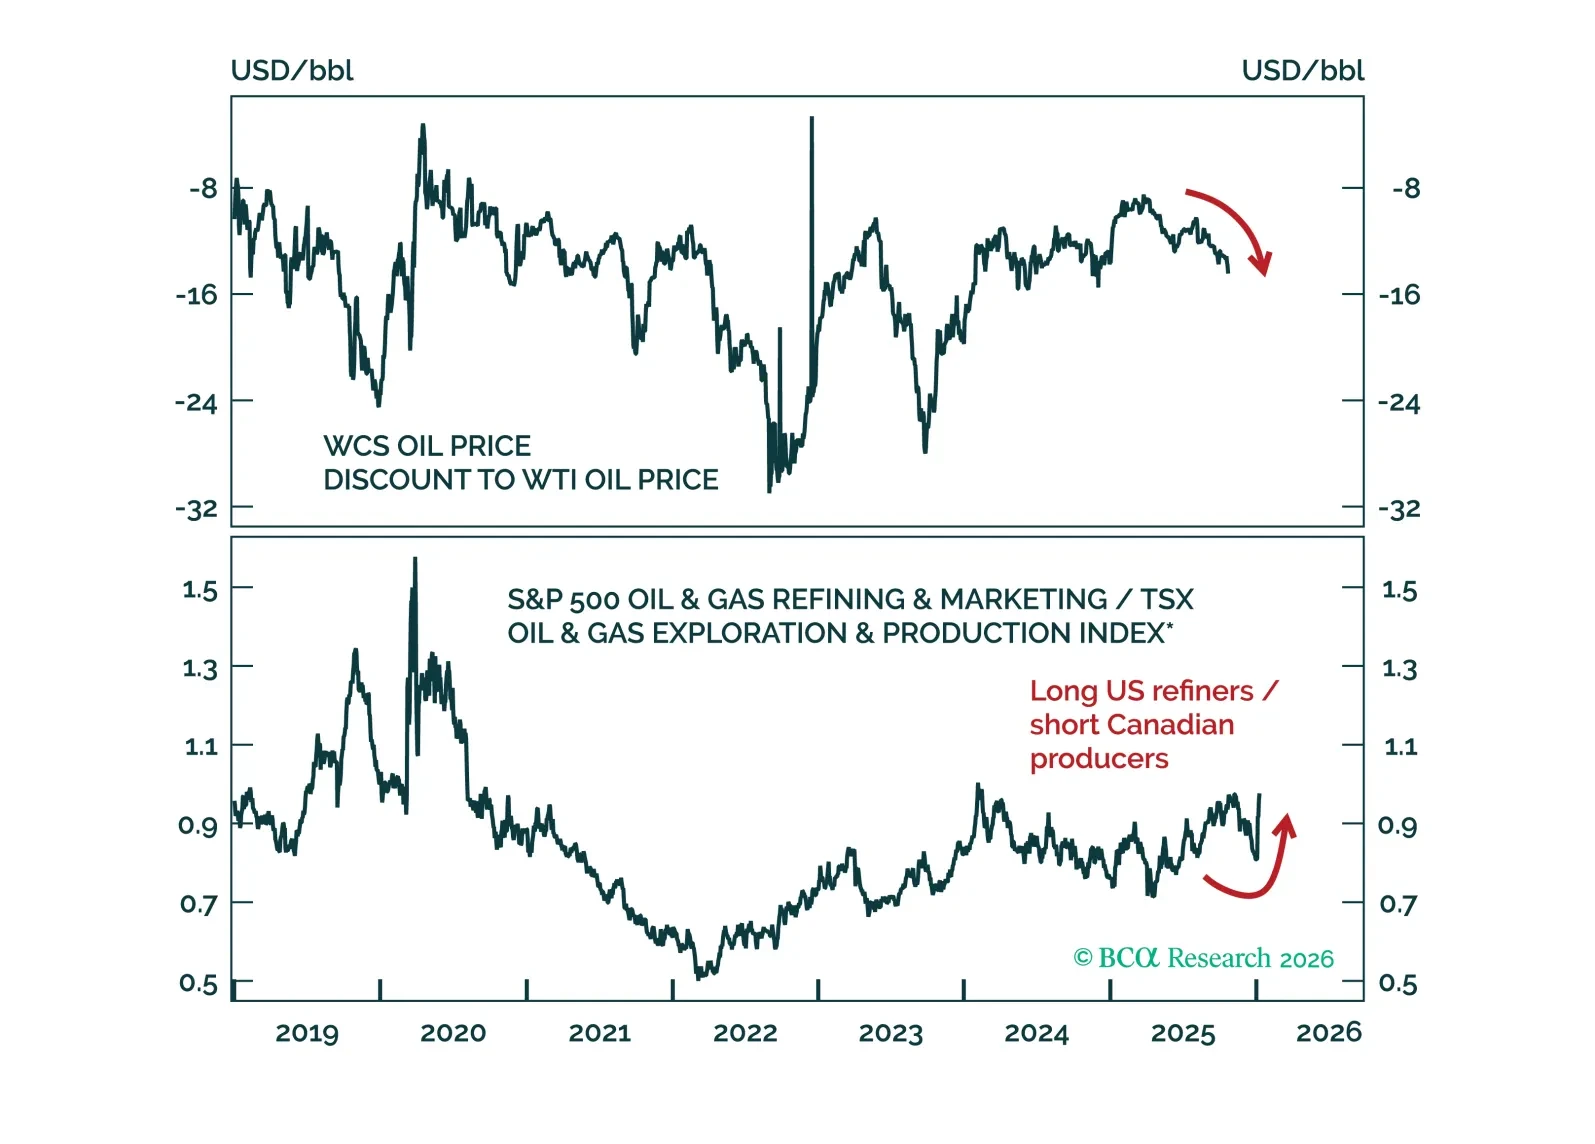
Venezuelan crude output is unlikely to alter the global oil market outlook for this year. However, US control of Venezuelan crude is a risk to Canadian oil sands producers and Canadian oil prices. Go long US oil refiners/short Canadian oil producers.
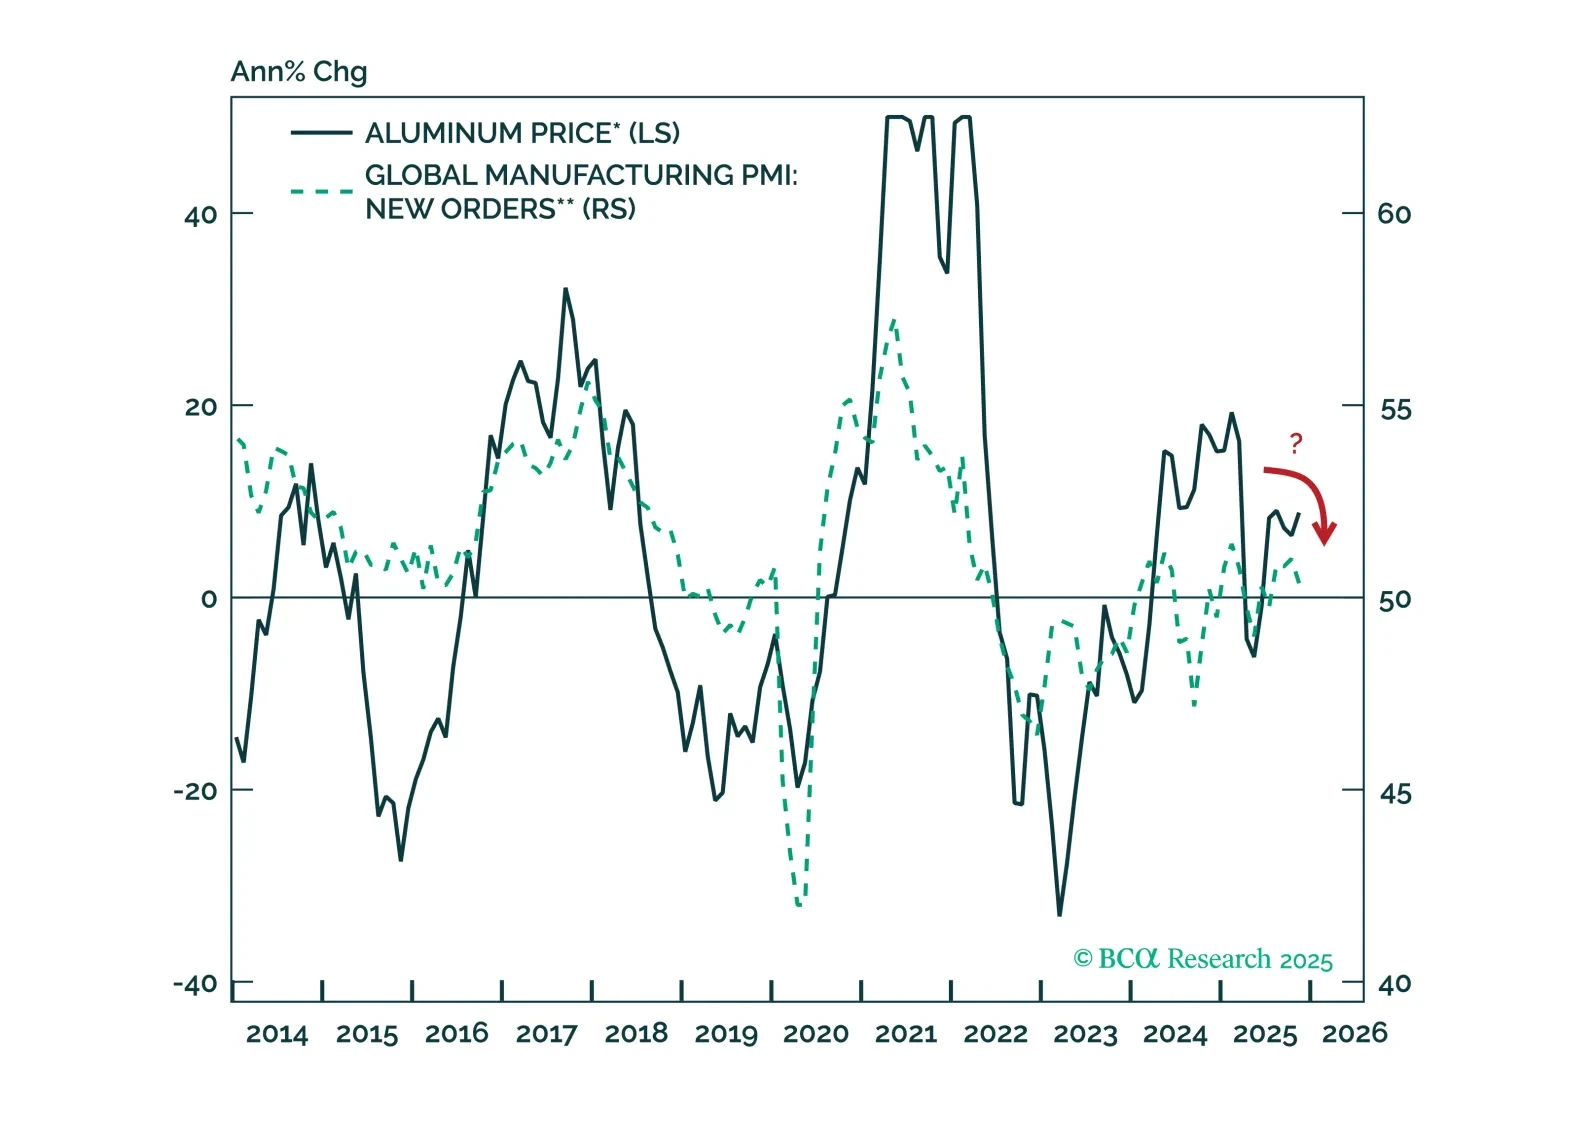
The forces that have recently propelled aluminum prices will remain supportive over the near term. However, beyond the coming months, aluminum prices will retreat as bearish cyclical pressures overwhelm over the course of 2026.