 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
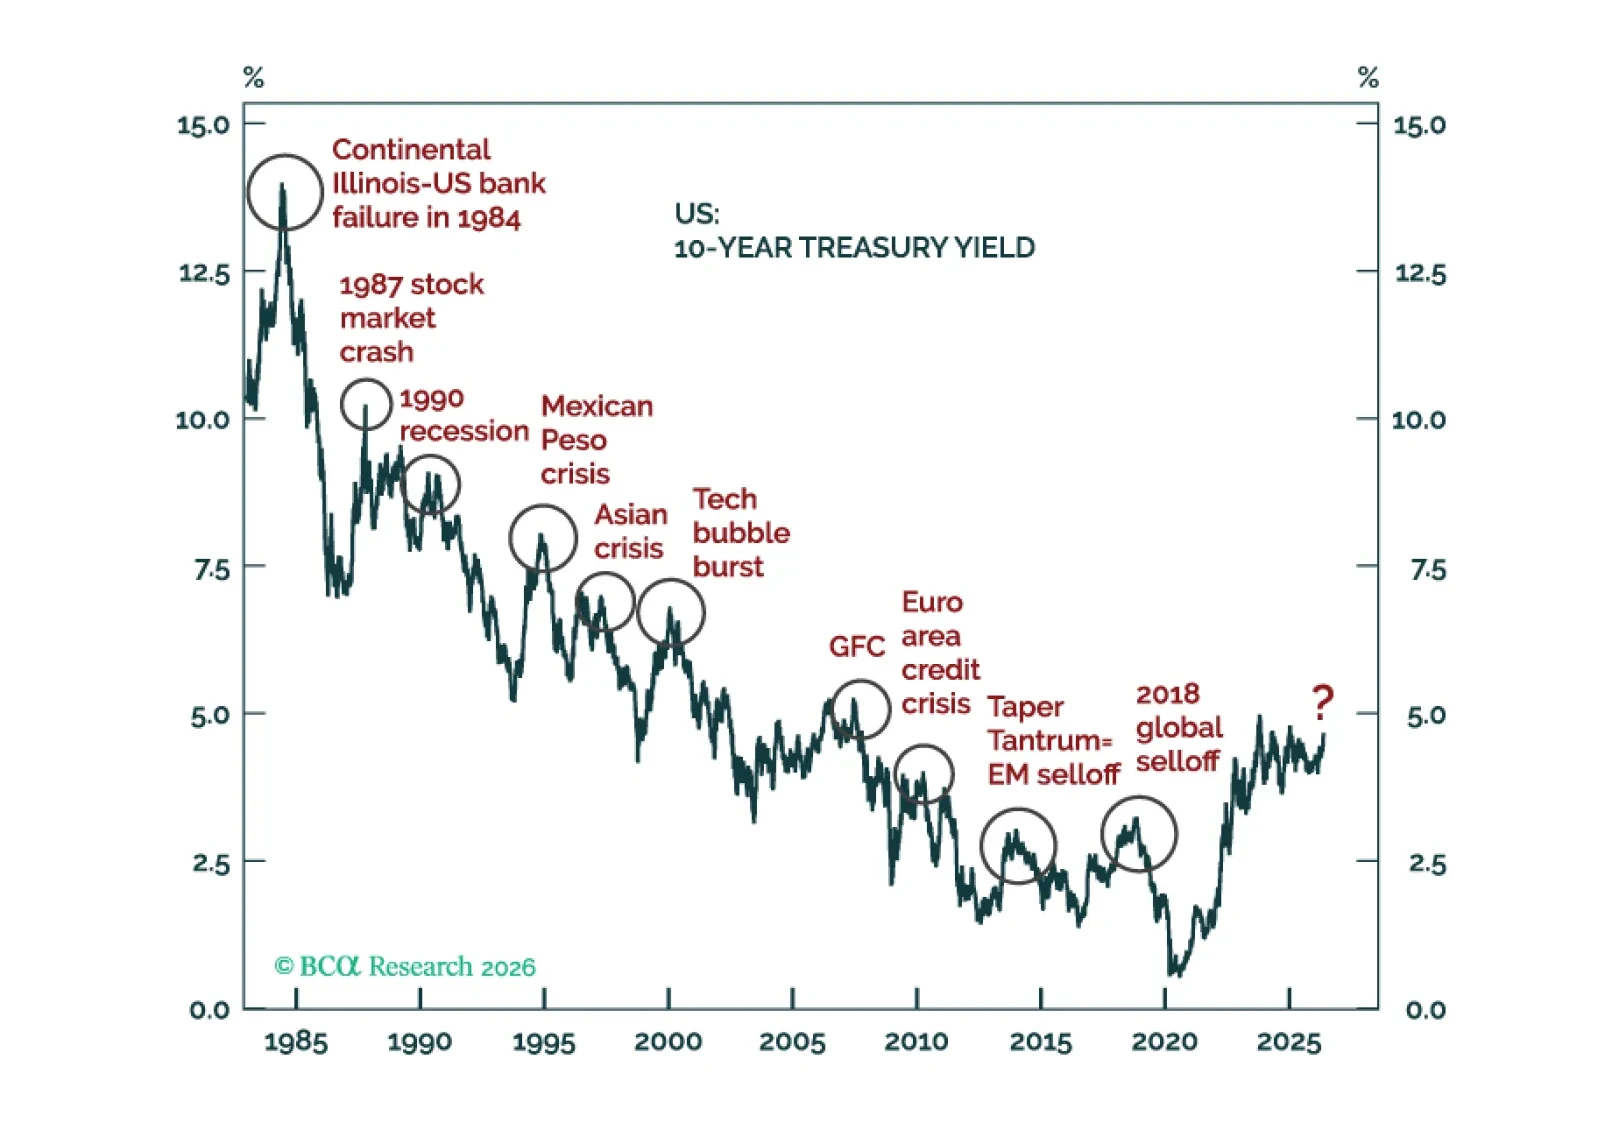
US stocks and bonds are on a collision course. Only a meaningful equity selloff is likely to pull bond yields considerably lower. Global equity risk-reward looks poor. The dollar will stay firm near term, but its medium- and long-term outlook remains bearish.
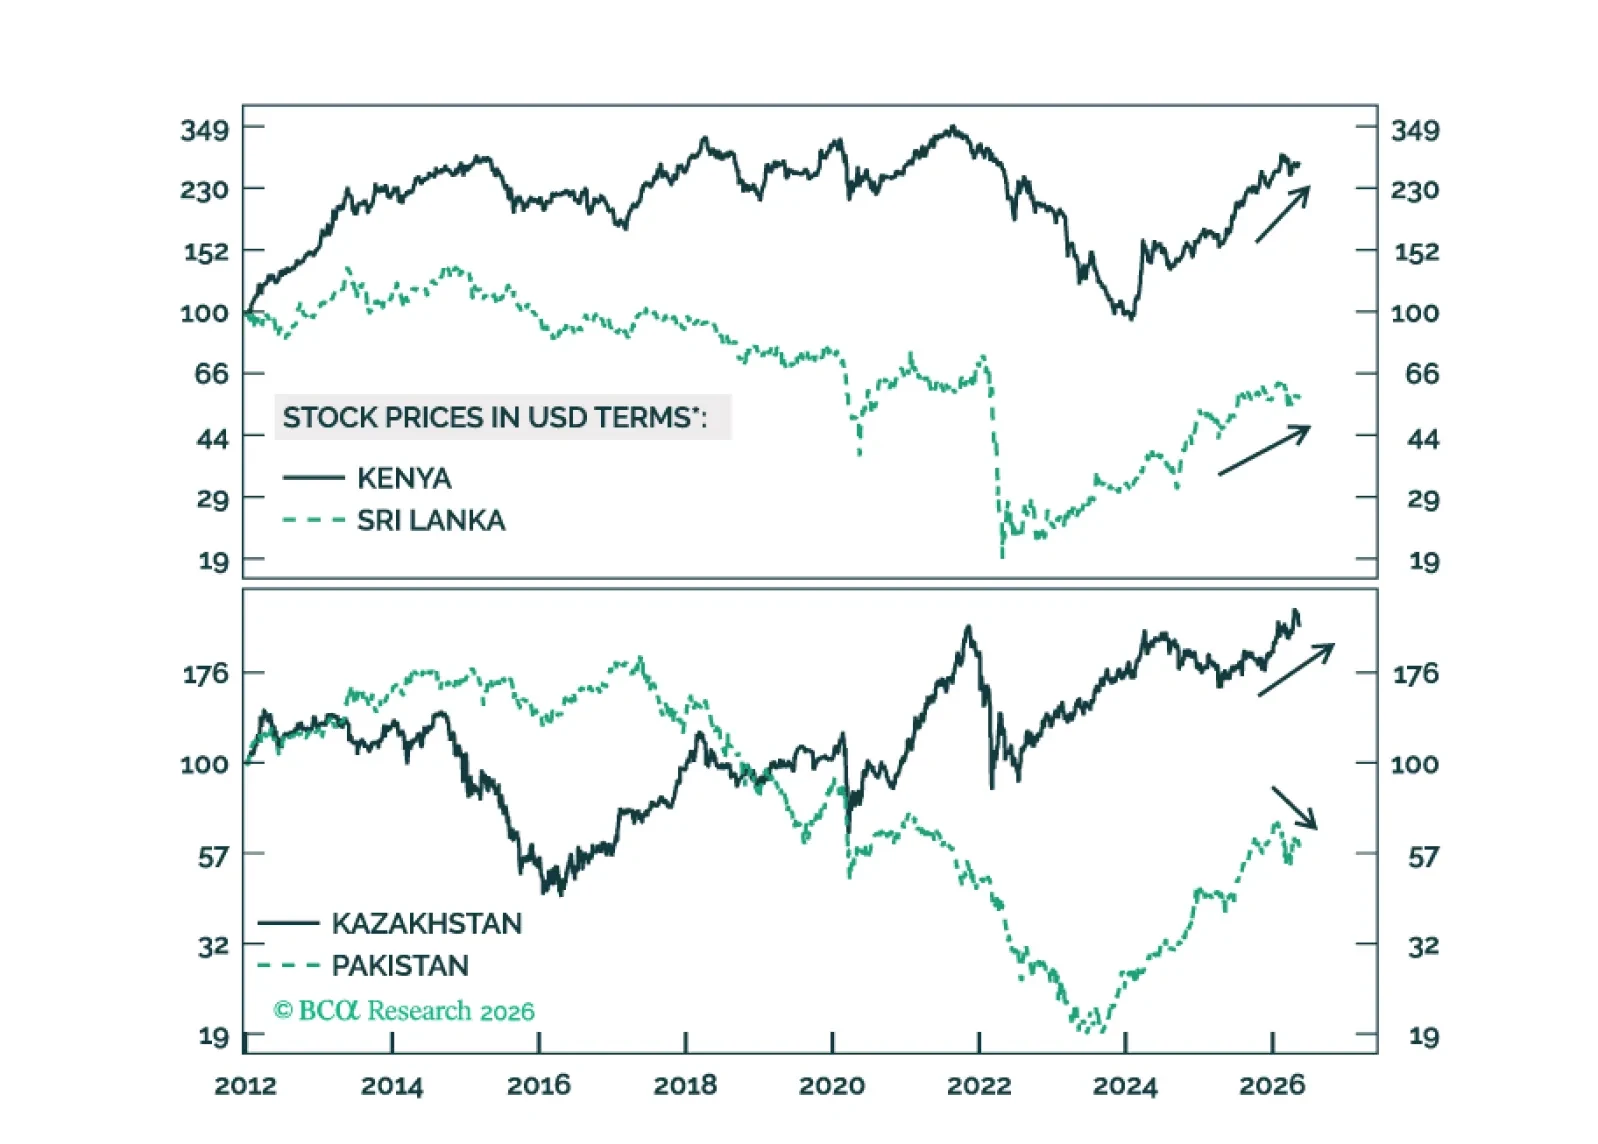
The divergence across frontier markets is likely to widen. Kenya, Kazakhstan, and Sri Lanka are well placed to outperform, while Pakistan is vulnerable. We offer several trade ideas to capture this divergence.
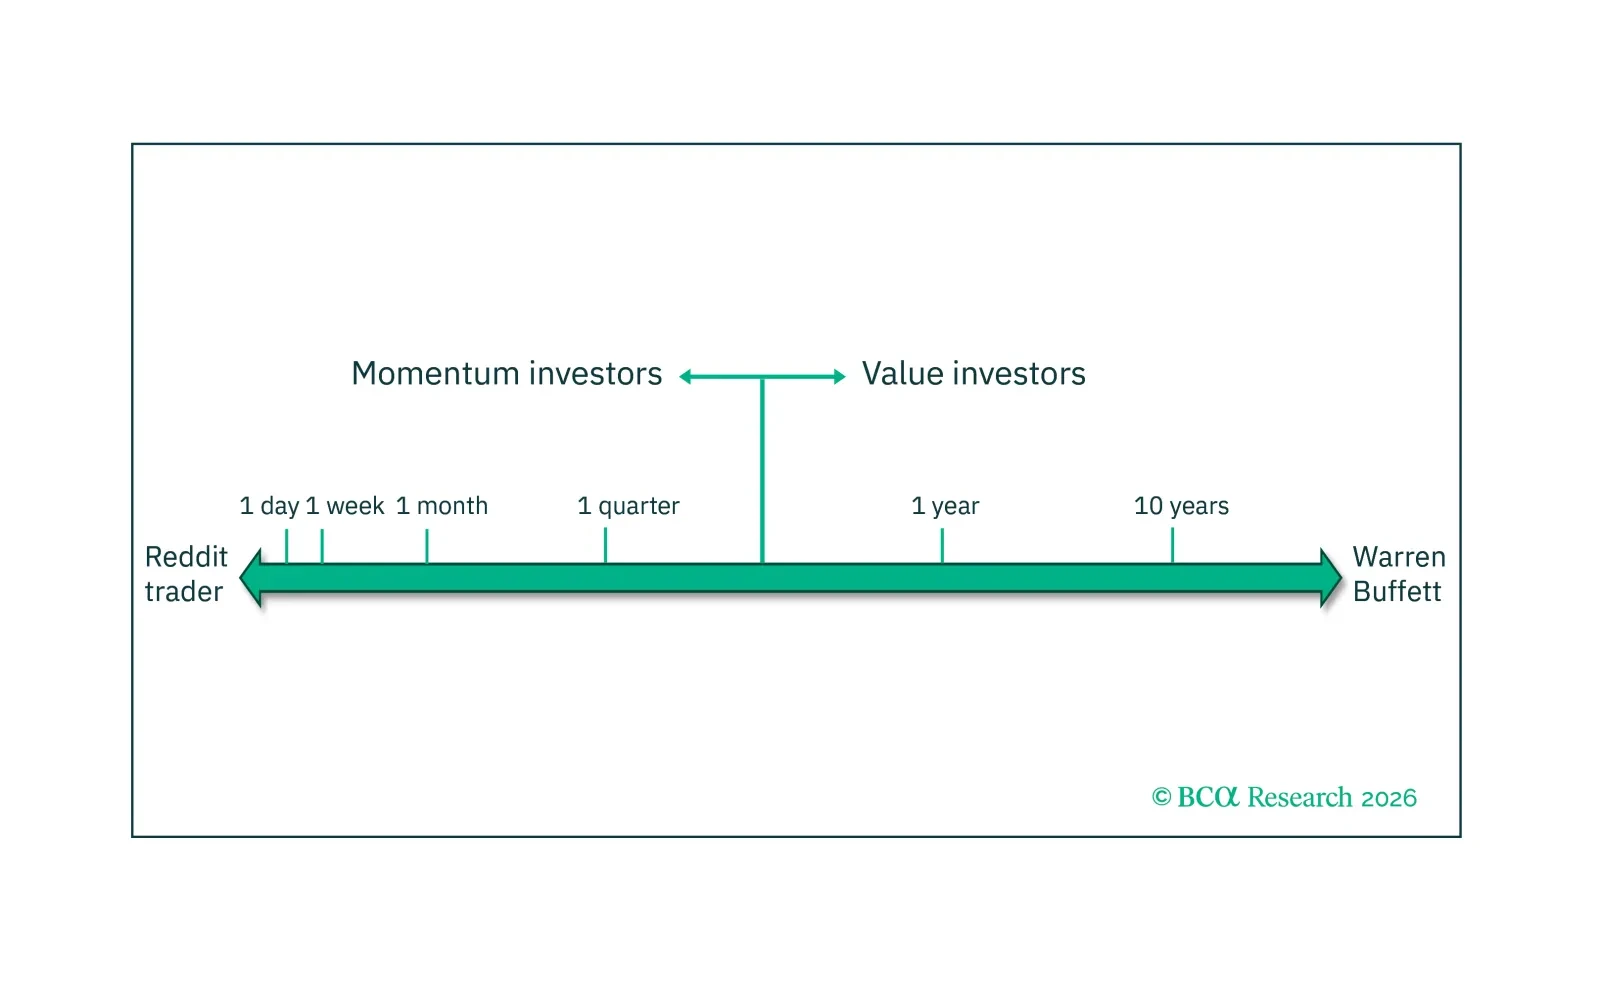

We take stock of earnings, AI capex and the labor market and explain why we think the repeated new highs in the S&P 500 are justified.
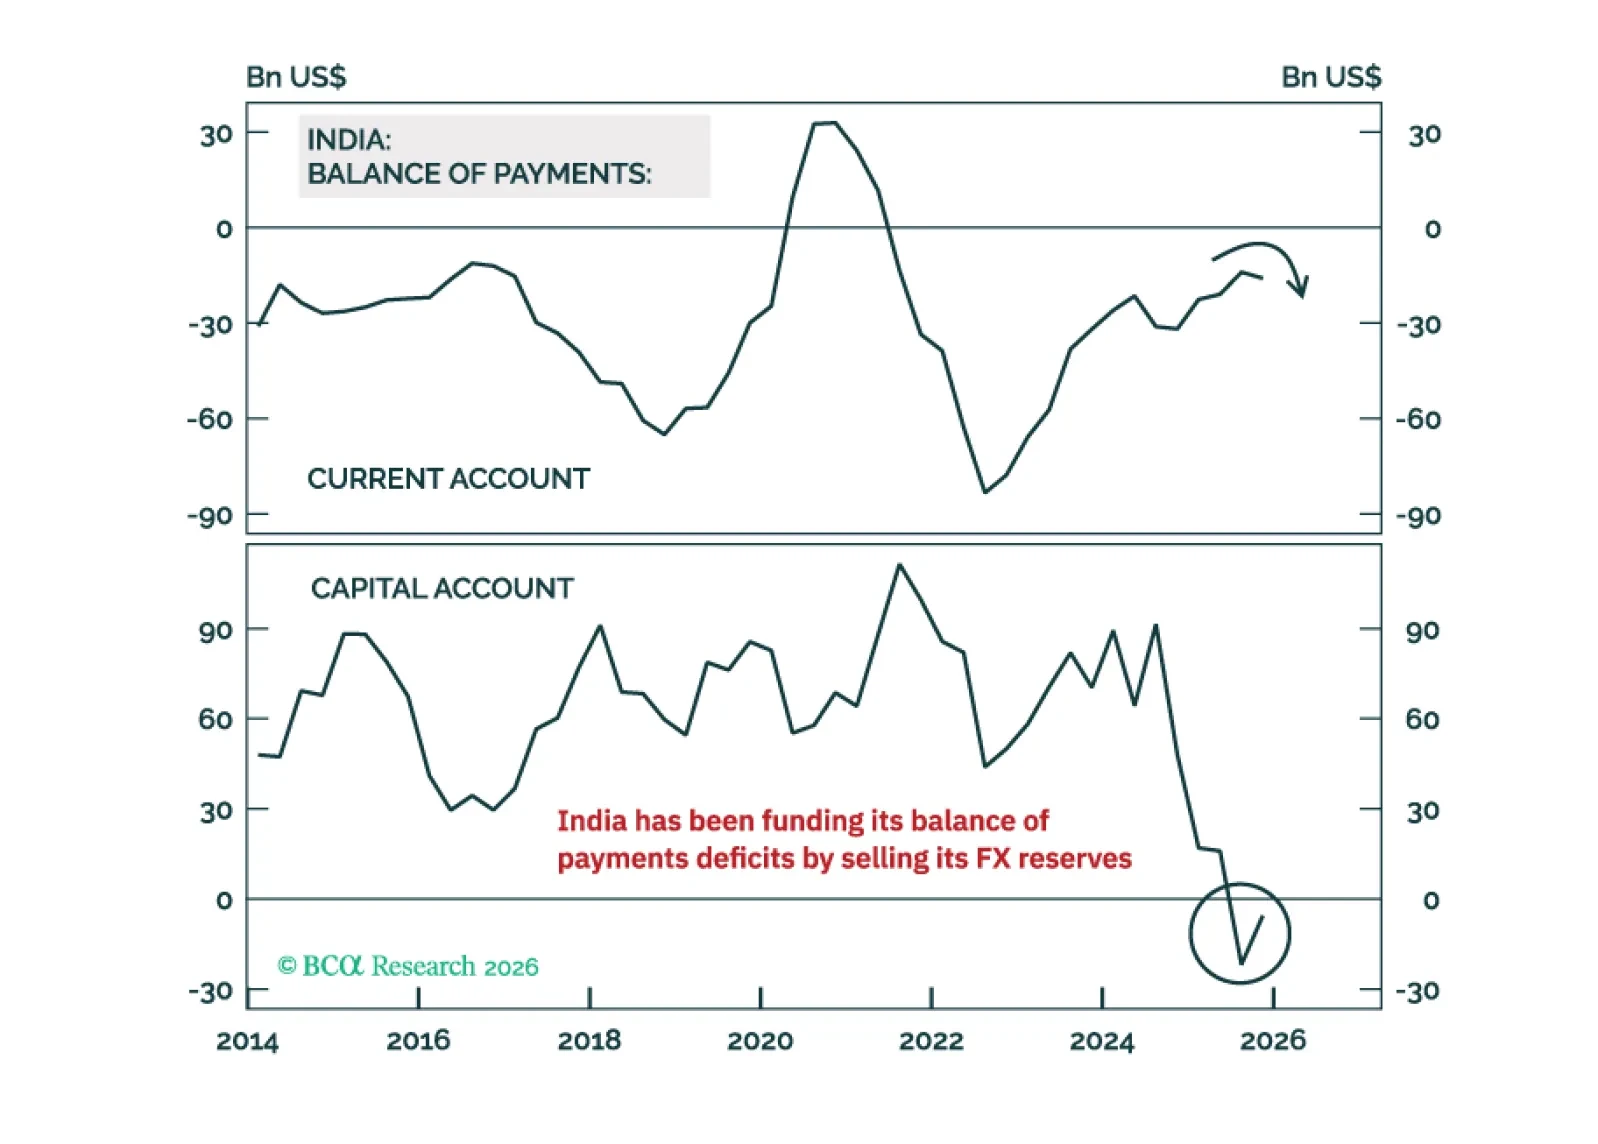
India is probably the most vulnerable among the G-20 economies should the Strait of Hormuz not reopen fully by the end of this month. Growth will slow, while inflation will rise materially. Investors should brace for further weakness in the currency and stock prices.

New Fed Chair, Kevin Warsh, is betting that an AI-driven productivity acceleration will get the Fed out of jail for persistently missing its 2 percent inflation target. But history informs us that while new technology adoption is exponential, total productivity growth is not. So, if Warsh’s bet goes wrong, as is likely, the US inflation overshoot will persist. We discuss the investment implications. Plus, a new trade is short cotton.
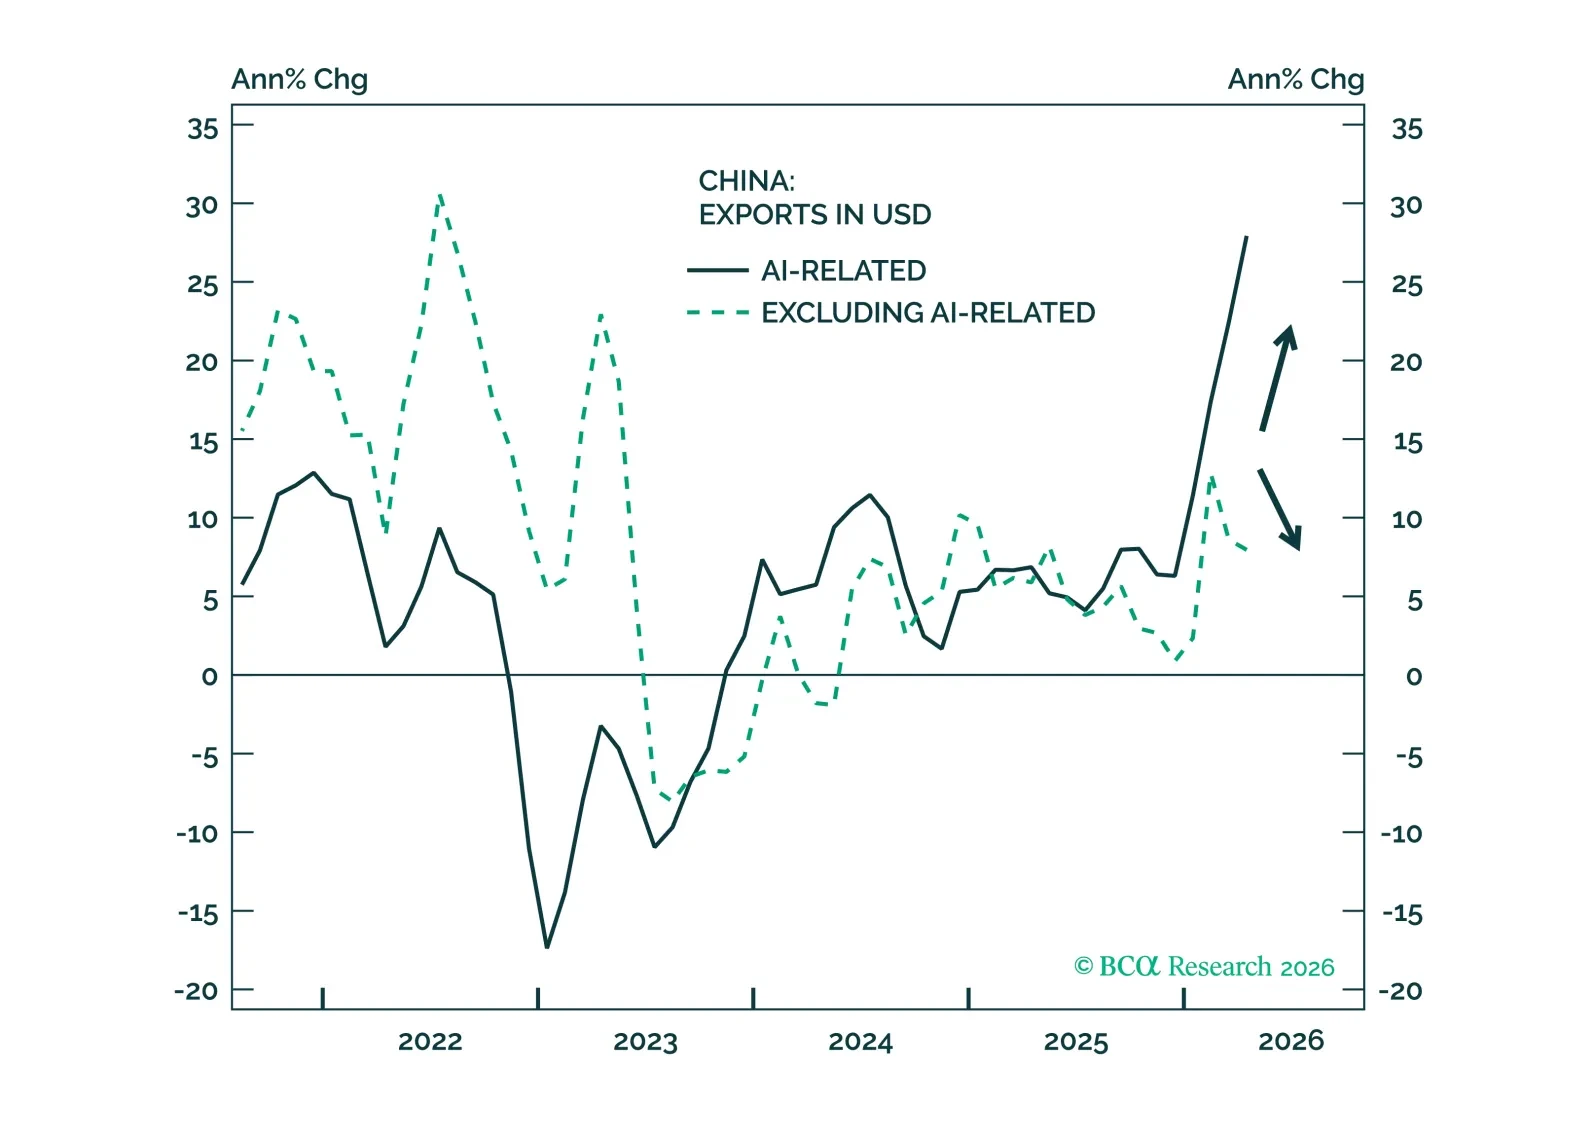
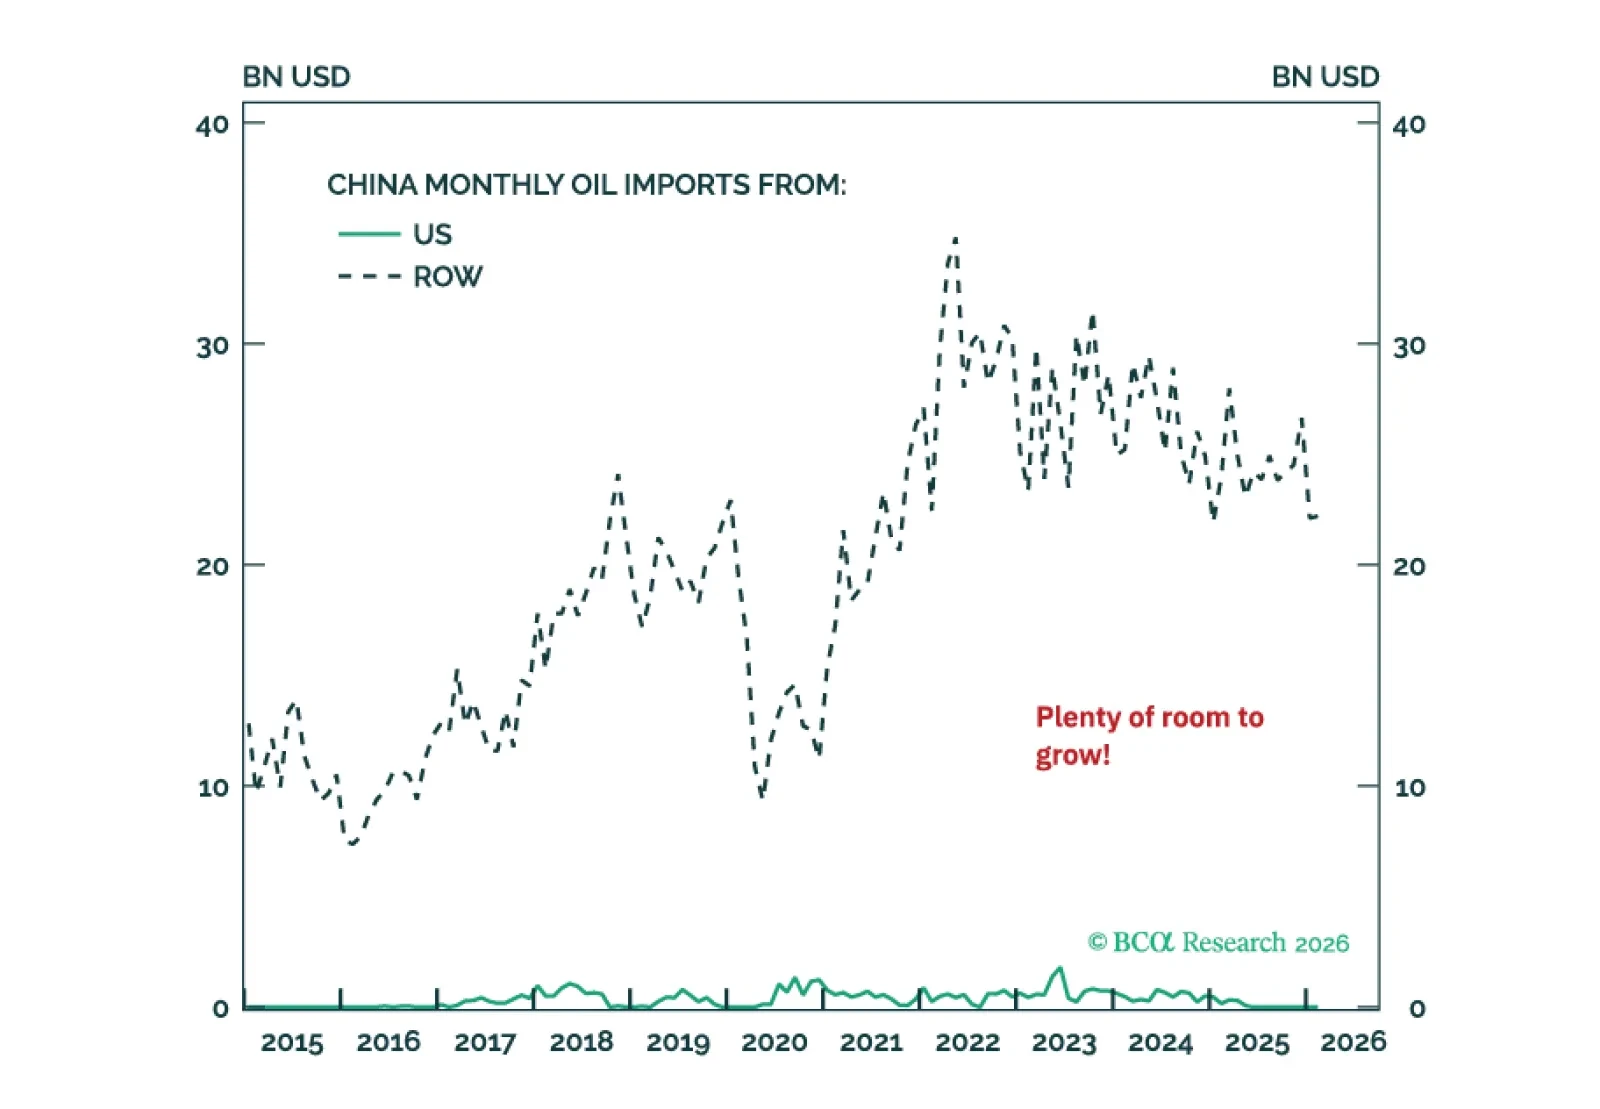
China’s K-shaped economy is widening, with resilient exports and subdued domestic consumption. Over the next 6–12 months, we see a higher probability that global capex momentum persists than China delivers meaningful consumer-focused stimulus.
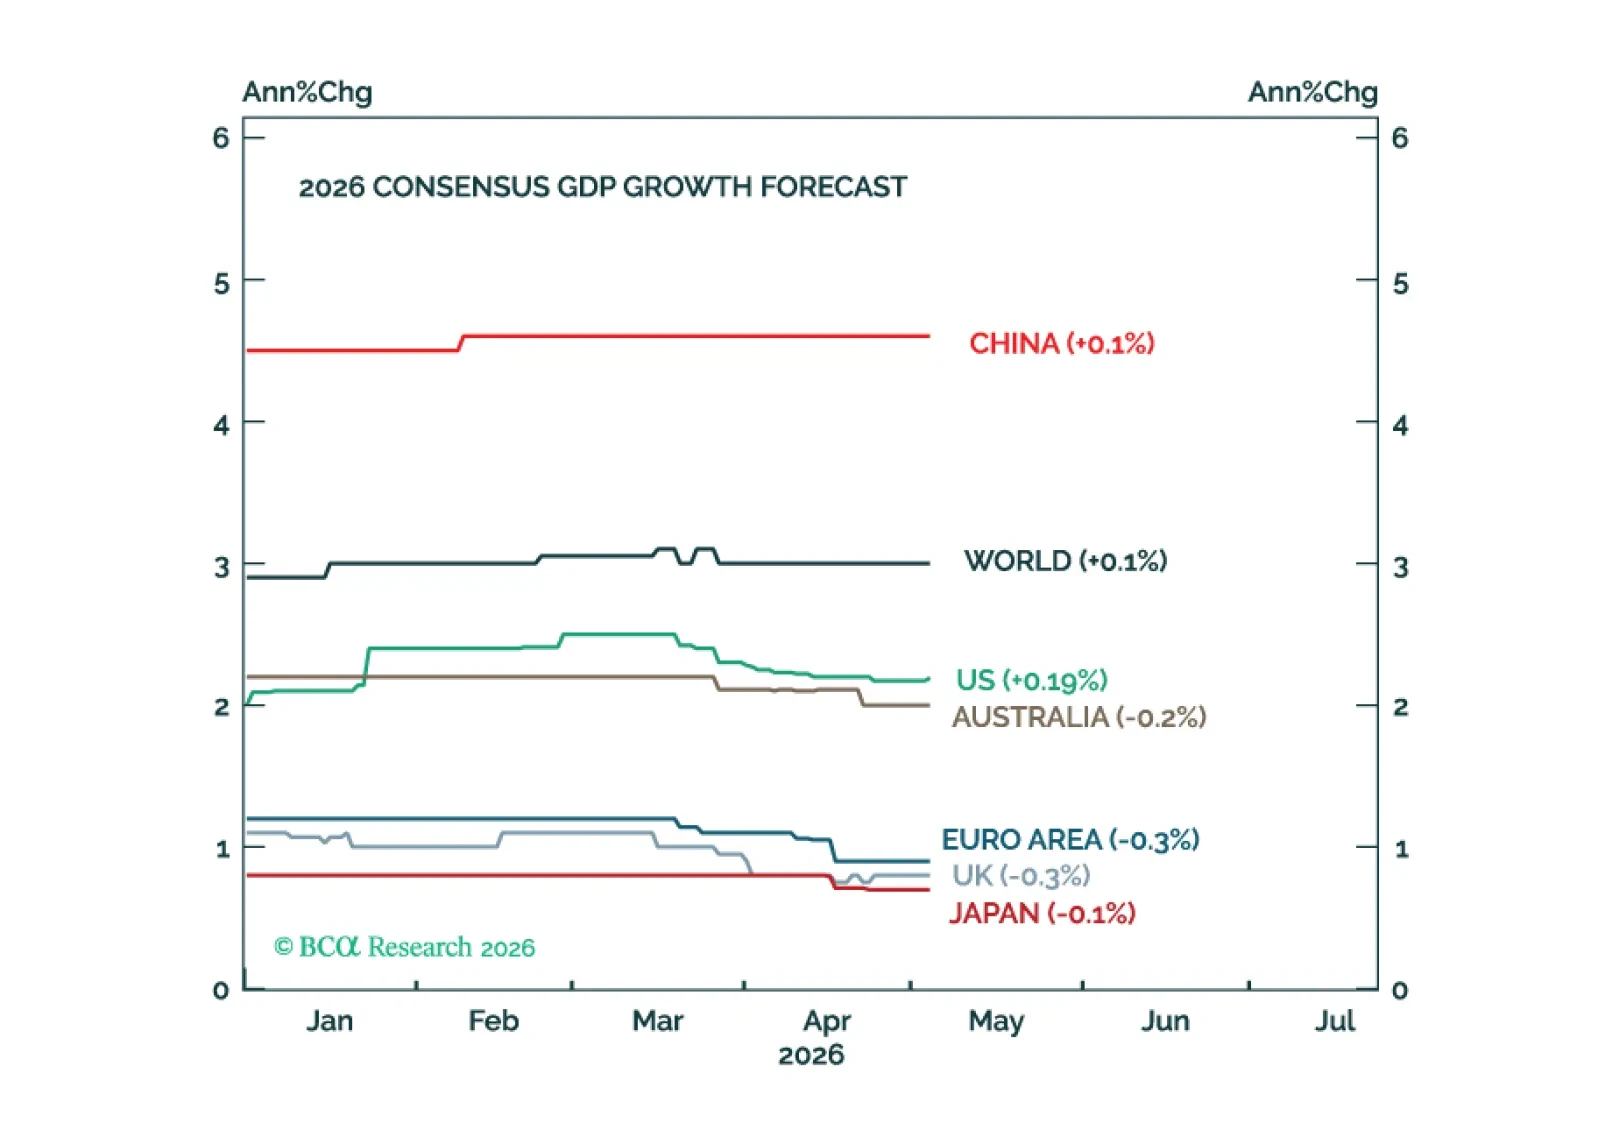
The global economy has weathered the oil shock reasonably well so far. However, the risk of a recession will increase meaningfully if the Strait of Hormuz remains closed into June.