 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
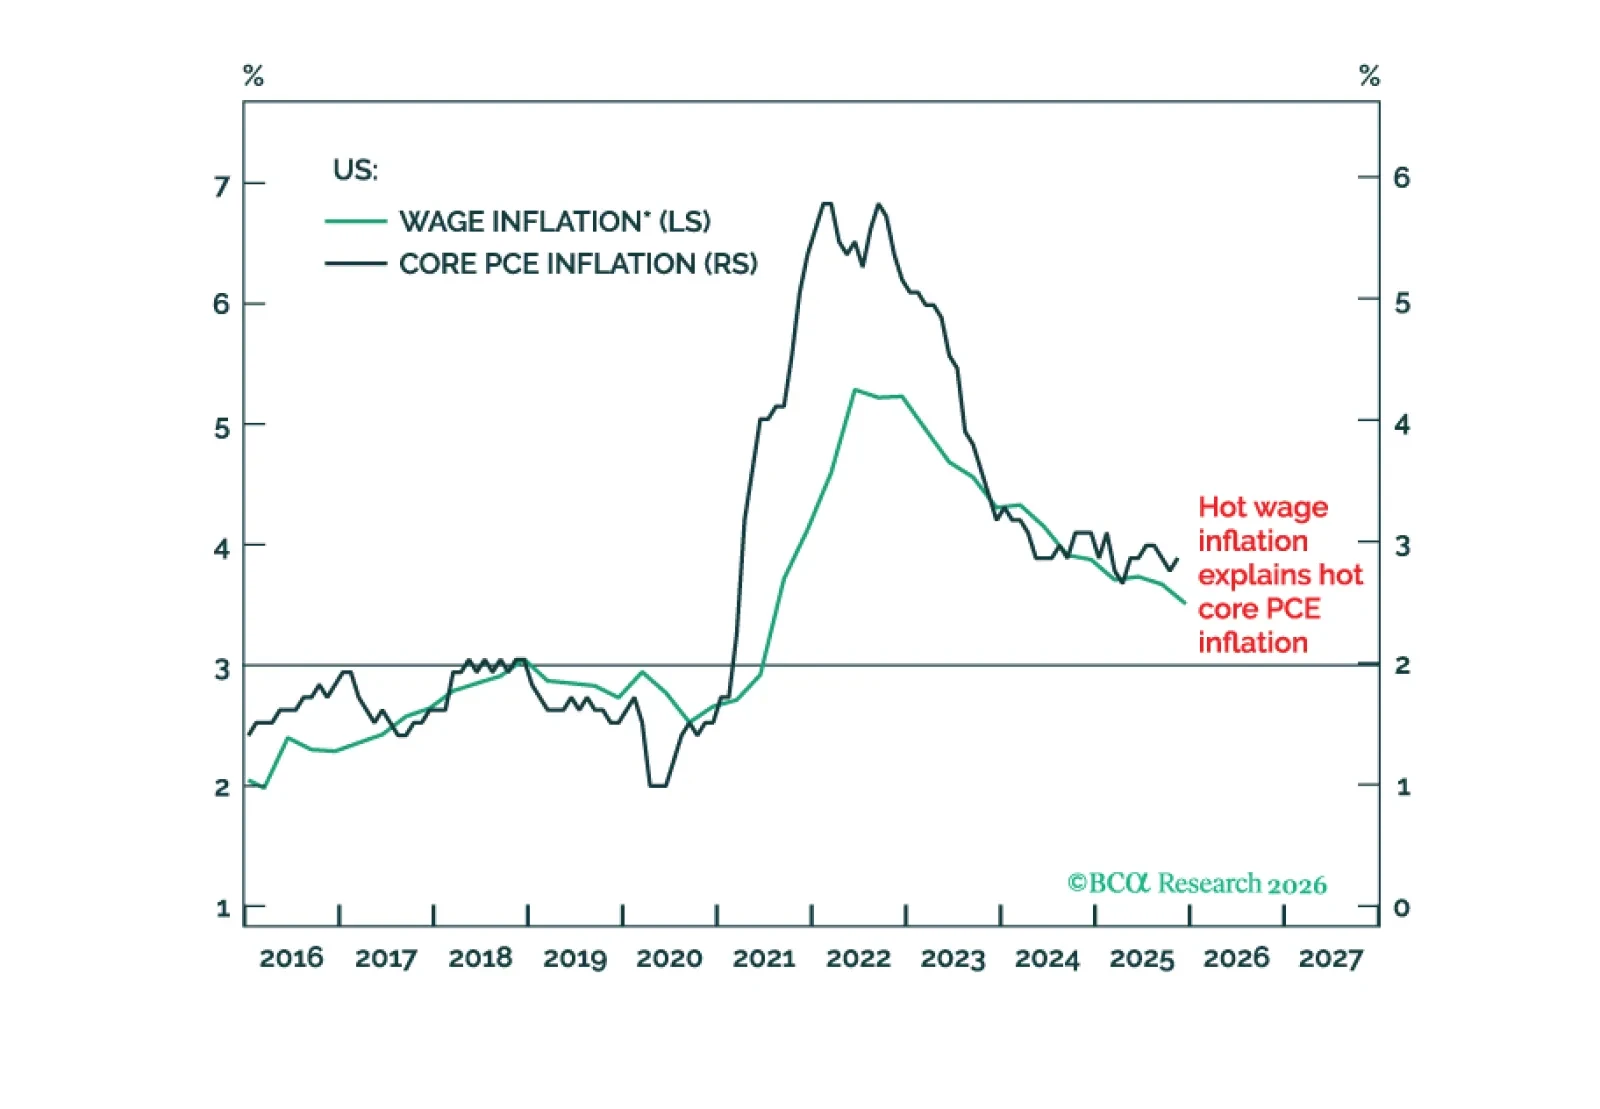
The Warsh Fed will run the US economy hot. This is bad for T-bonds and the dollar, but good for stocks. Plus, a new tactical trade is overweight Consumer Discretionary (RXI) versus Industrials (EXI).
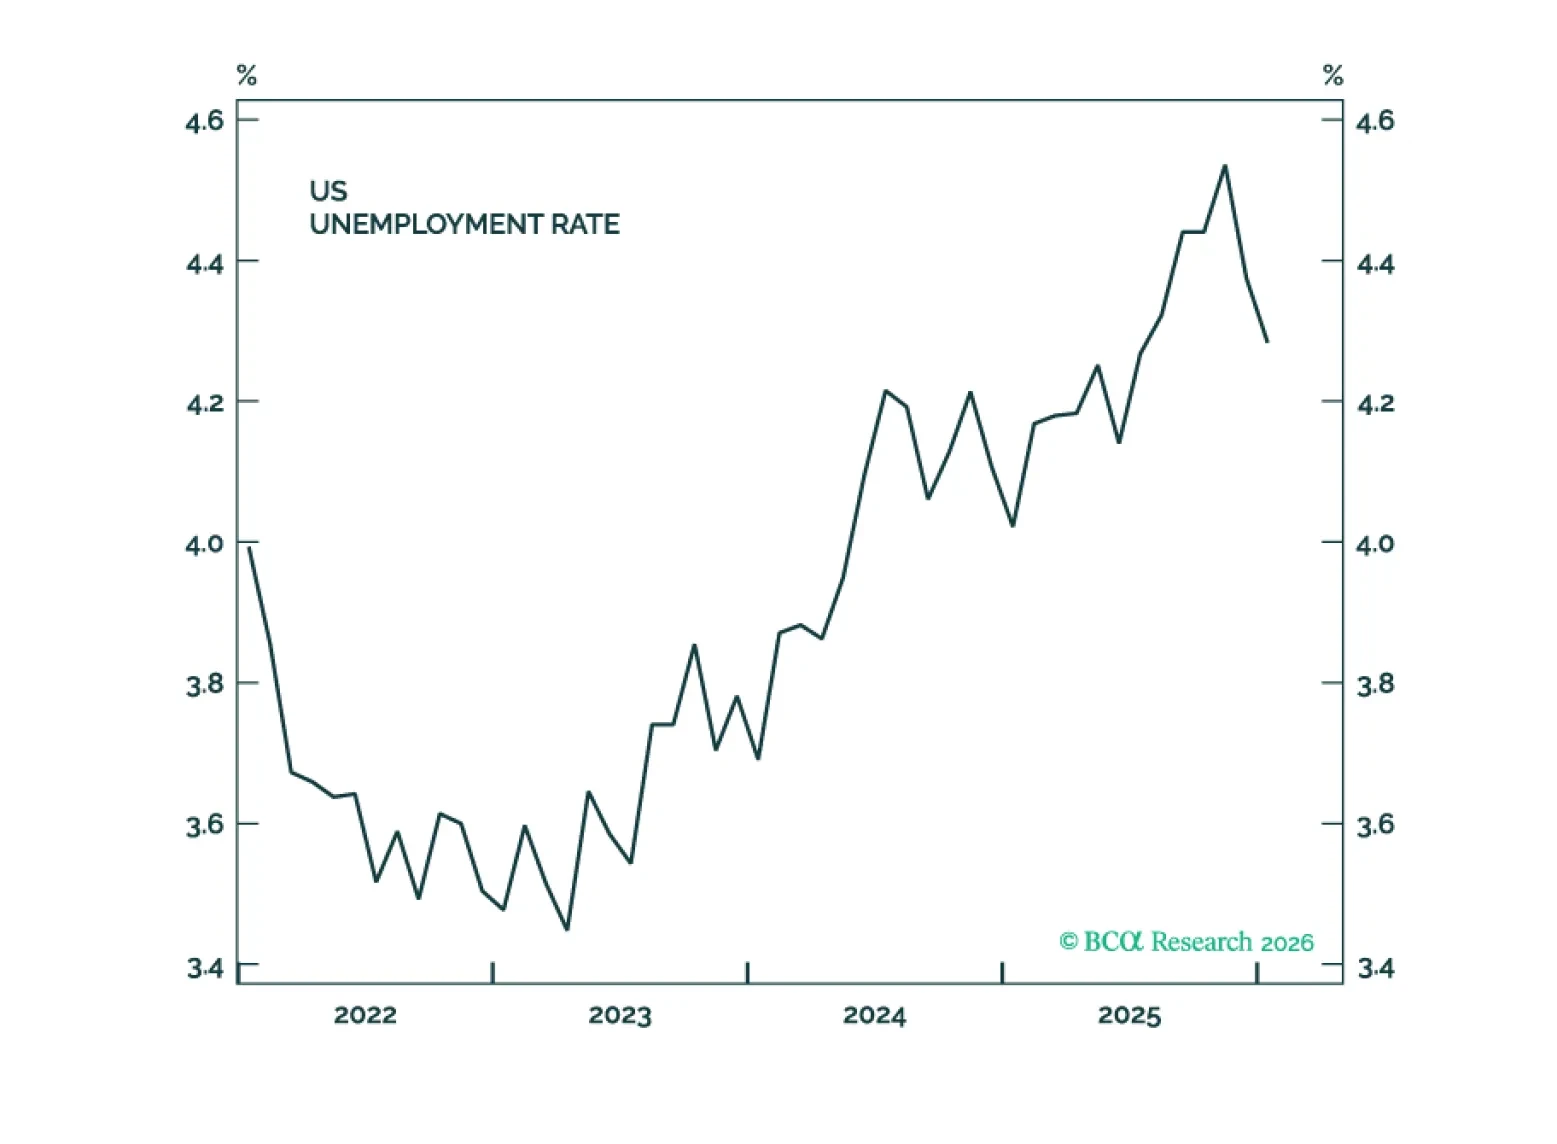
The January jobs report was unambiguously strong. Although the 172K gain in private payrolls will almost certainly be revised down, the message from the "ratios" was reassuring: The unemployment rate fell for a second straight month, the labor force participation rate increased, the share of workers who are involuntarily part-time declined, and the prime-age employment-to-population ratio rose back to its all-time high. Unlike the payroll survey, the household survey from which ratios are calculated is subject to minimal revisions.
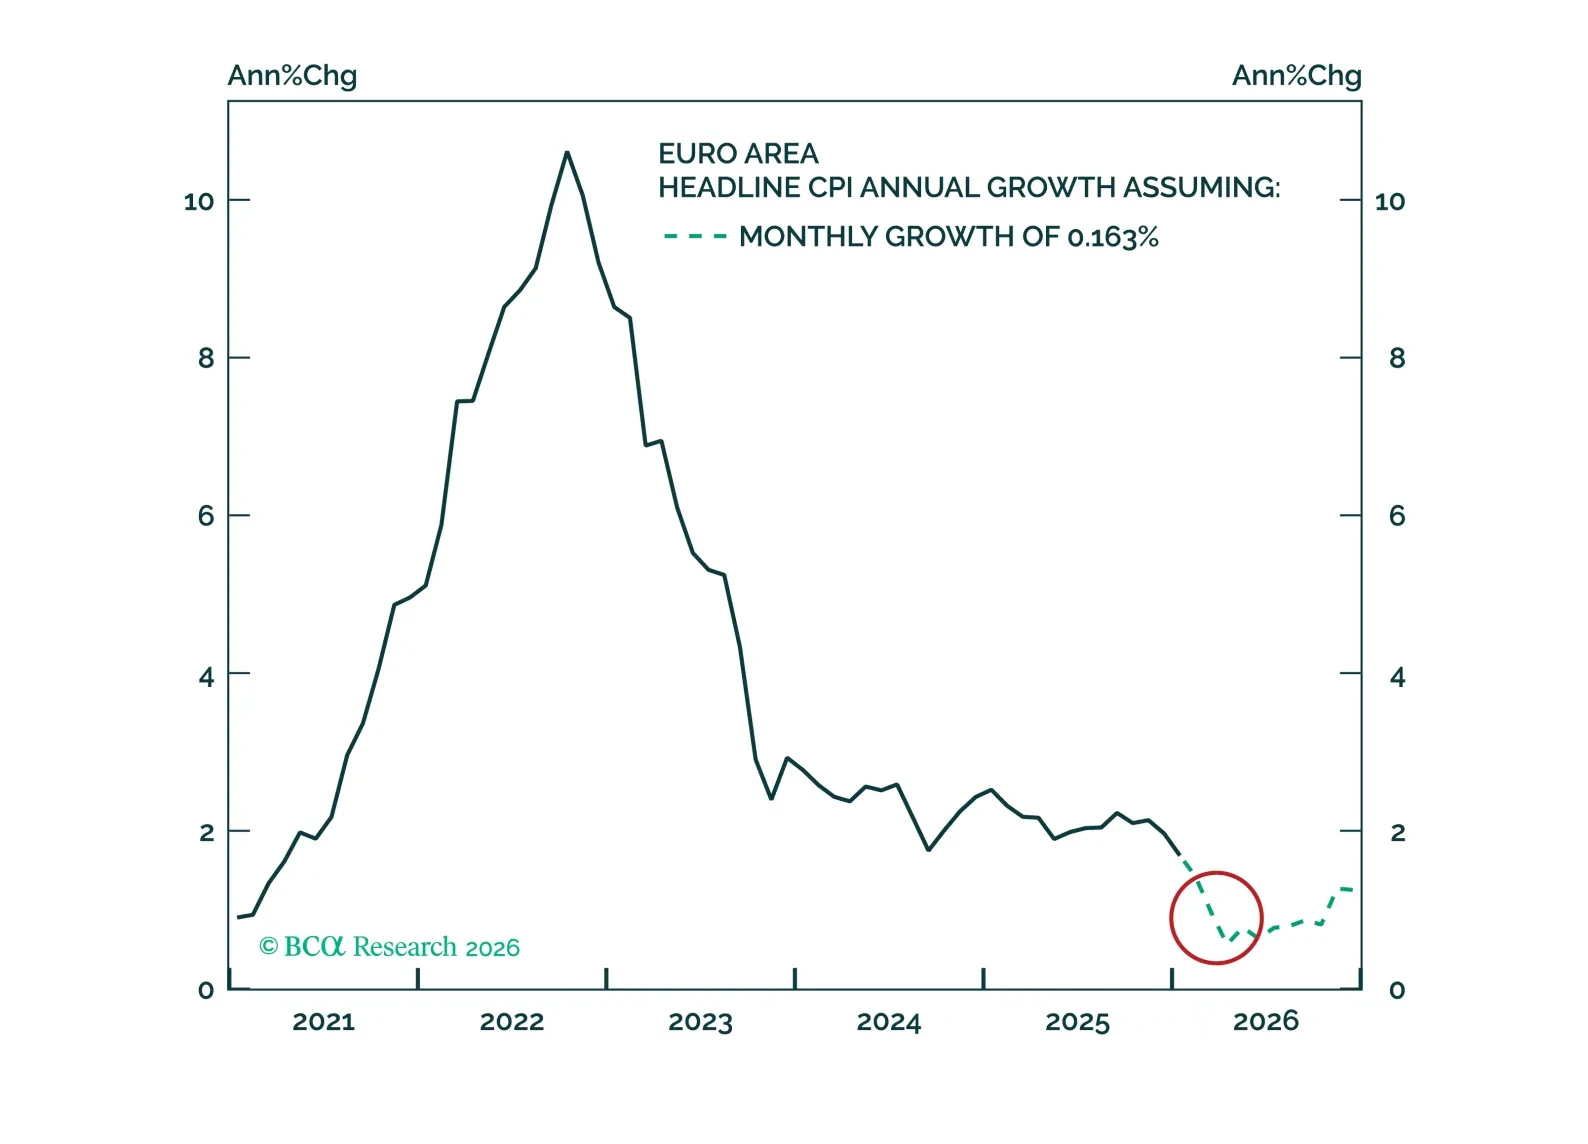
The ECB is about to make its first policy mistake in the current cycle by being complacent about the downside risks to inflation. The confluence of base effects, a stronger euro, food and energy deflation, and rapid services disinflation will push headline inflation closer to 1% in the first half of the year. This significant undershoot will force the ECB to deliver reflationary cuts. Go long the September 2026 3-month Euribor futures and tactically reduce exposure to inflation-linked bonds in the Eurozone.
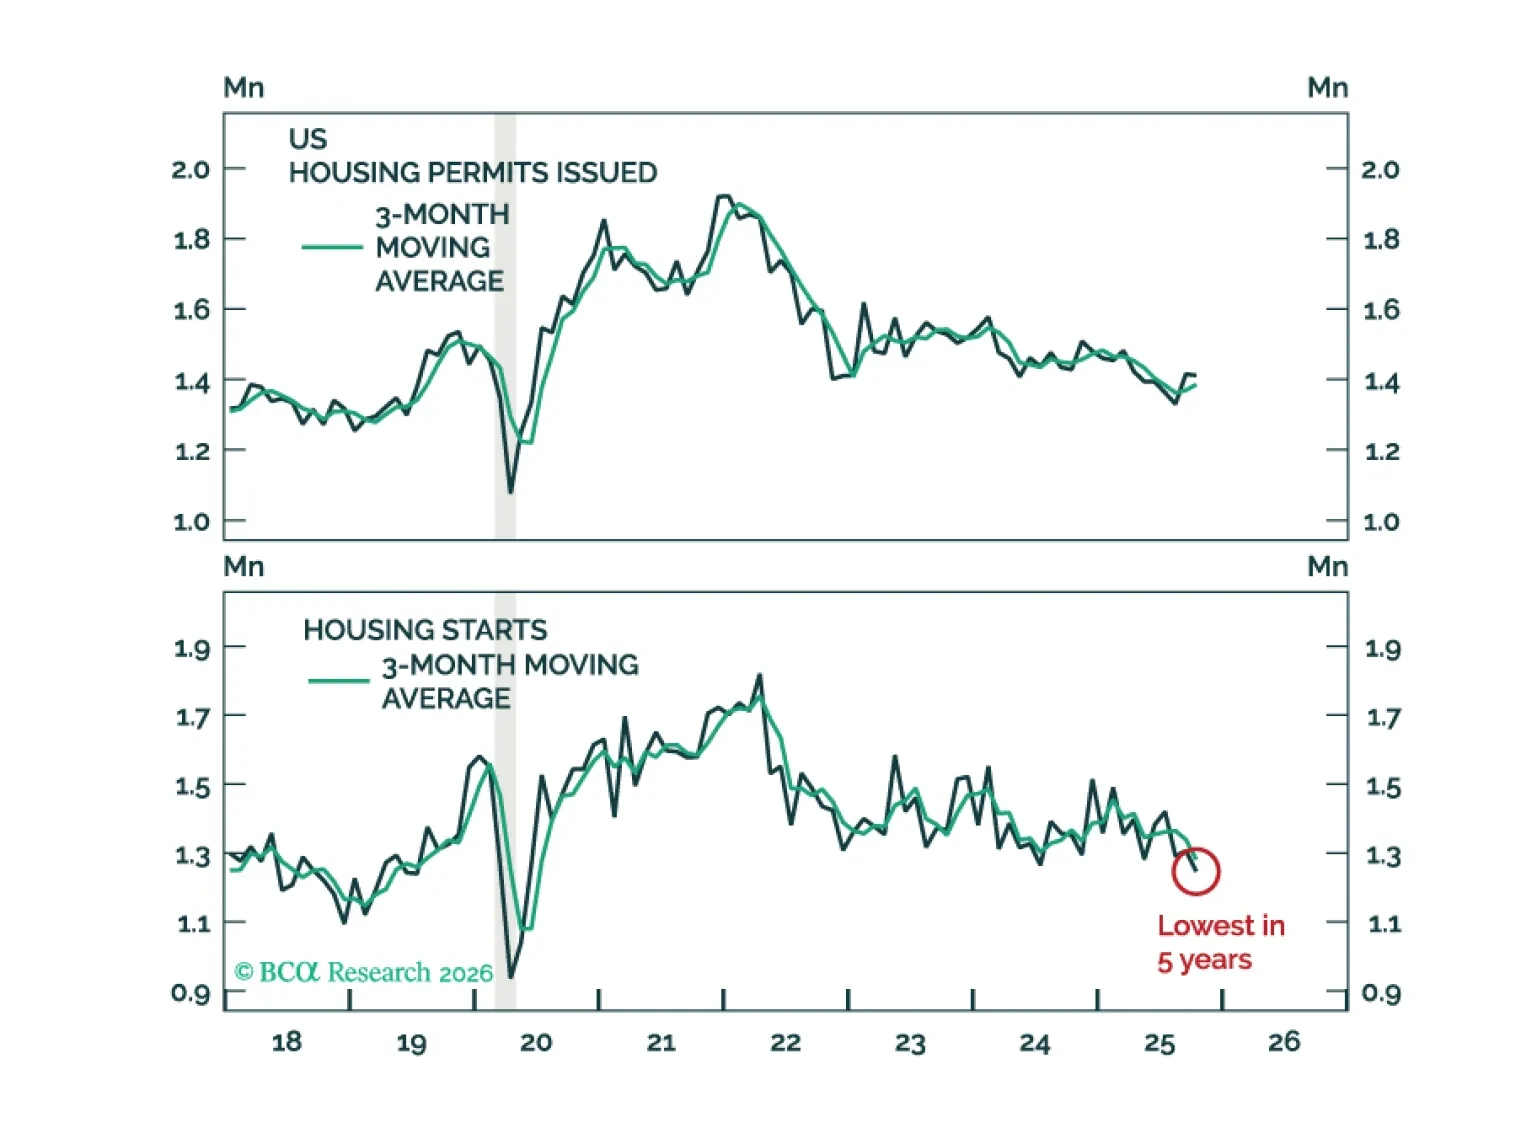
The US residential real estate market remains soft. While the decline in mortgage rates is a positive, it is too early to bet on housing becoming the engine of growth for the US economy this year.
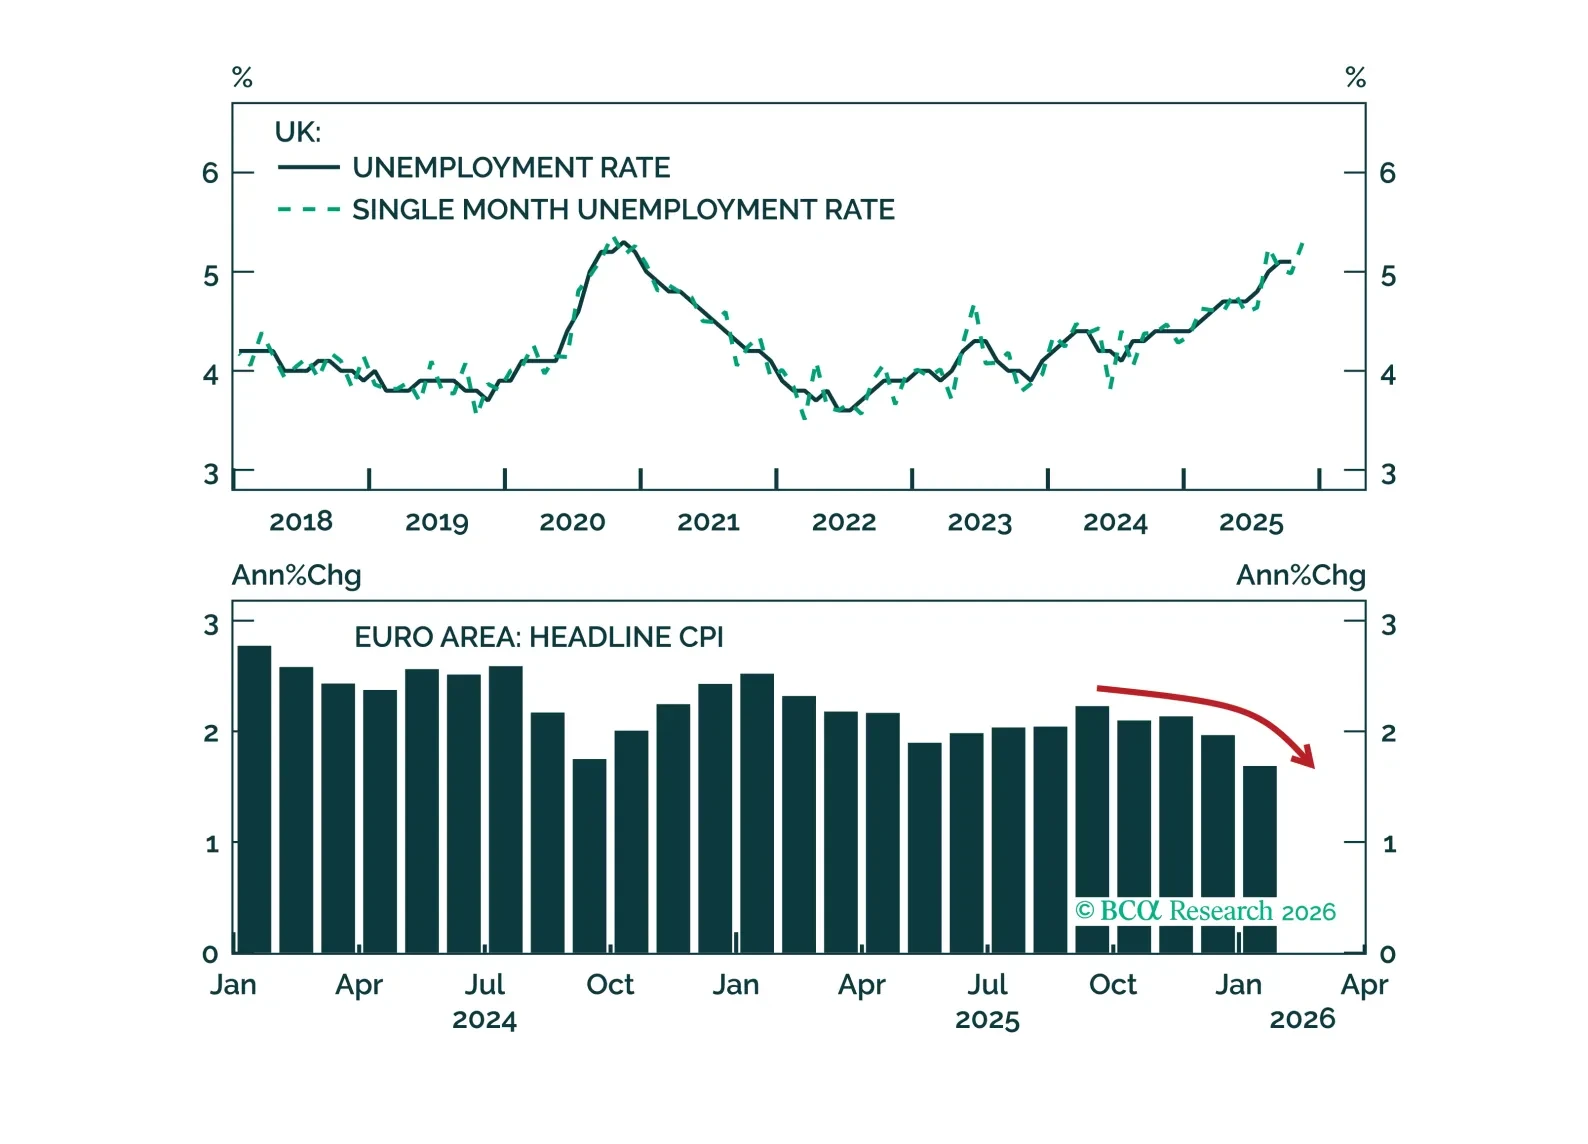
This week’s central bank meetings are a good reminder that monetary policy can still surprise. The Bank of England sounded more dovish, and the European Central Bank sounded complacent about the inflation undershoot. Meanwhile, the Reserve Bank of Australia hiked rates earlier this week. Investors should remain overweight UK Gilts, position for more ECB easing by going long the September 2026 3-month Euribor futures, and fade further rate hikes priced in Australia.
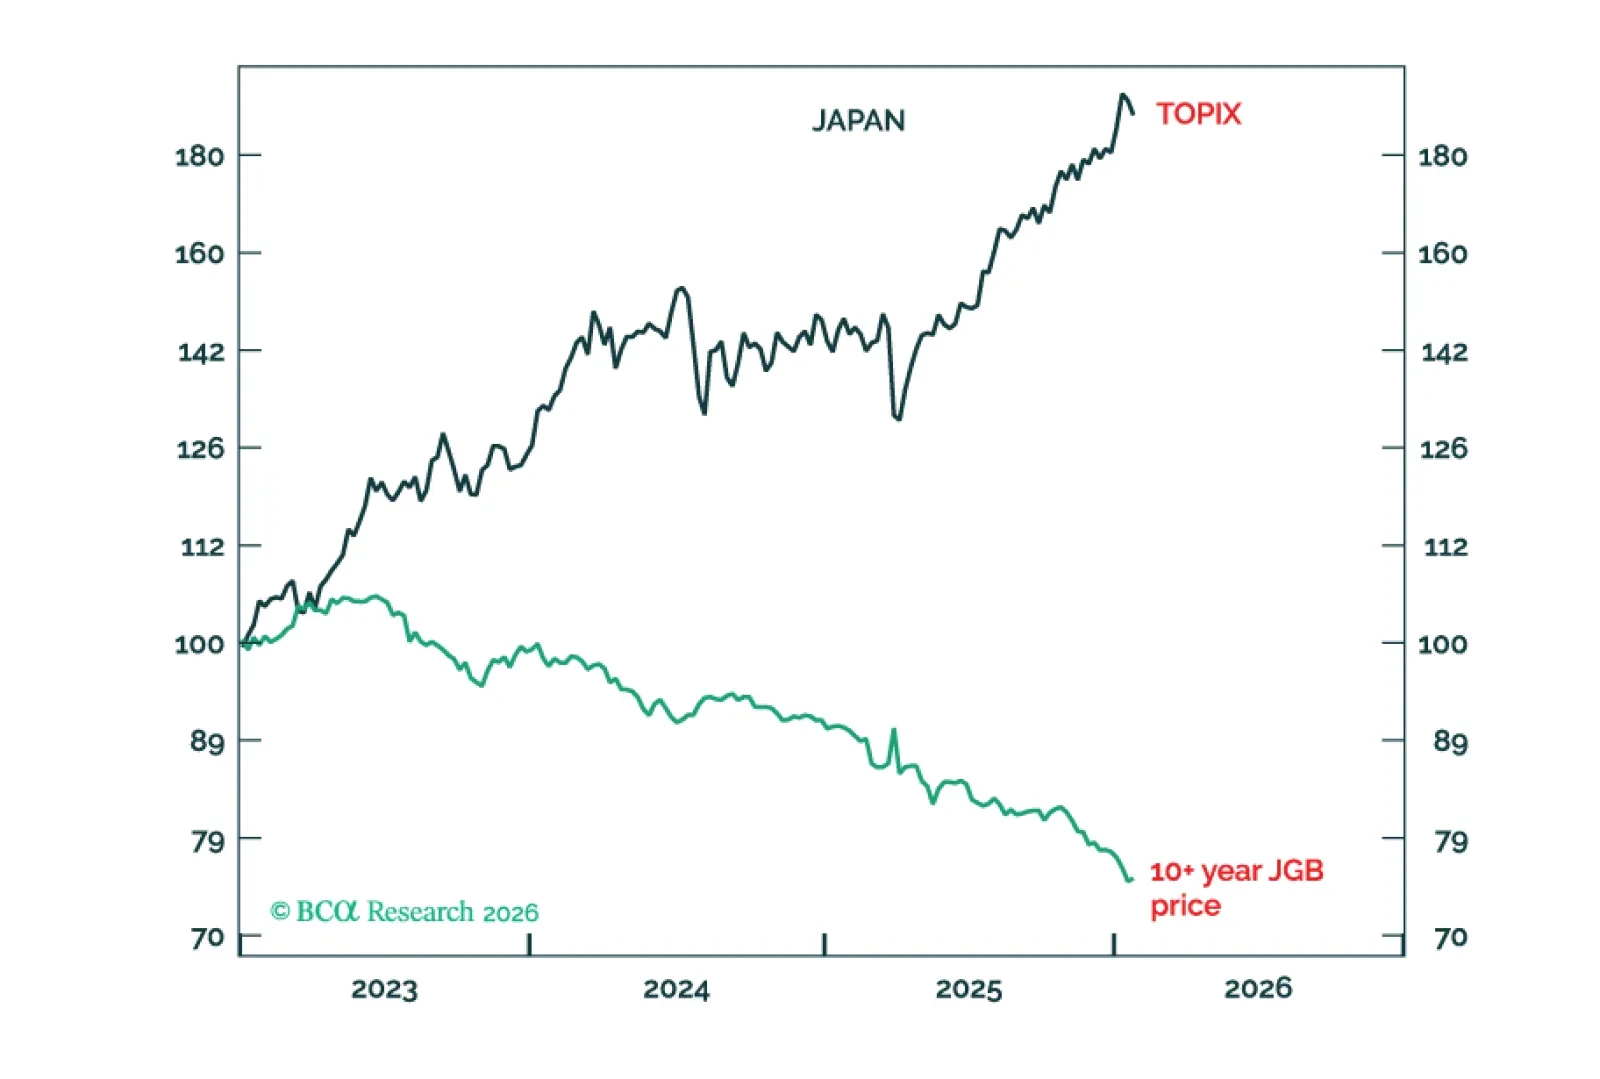
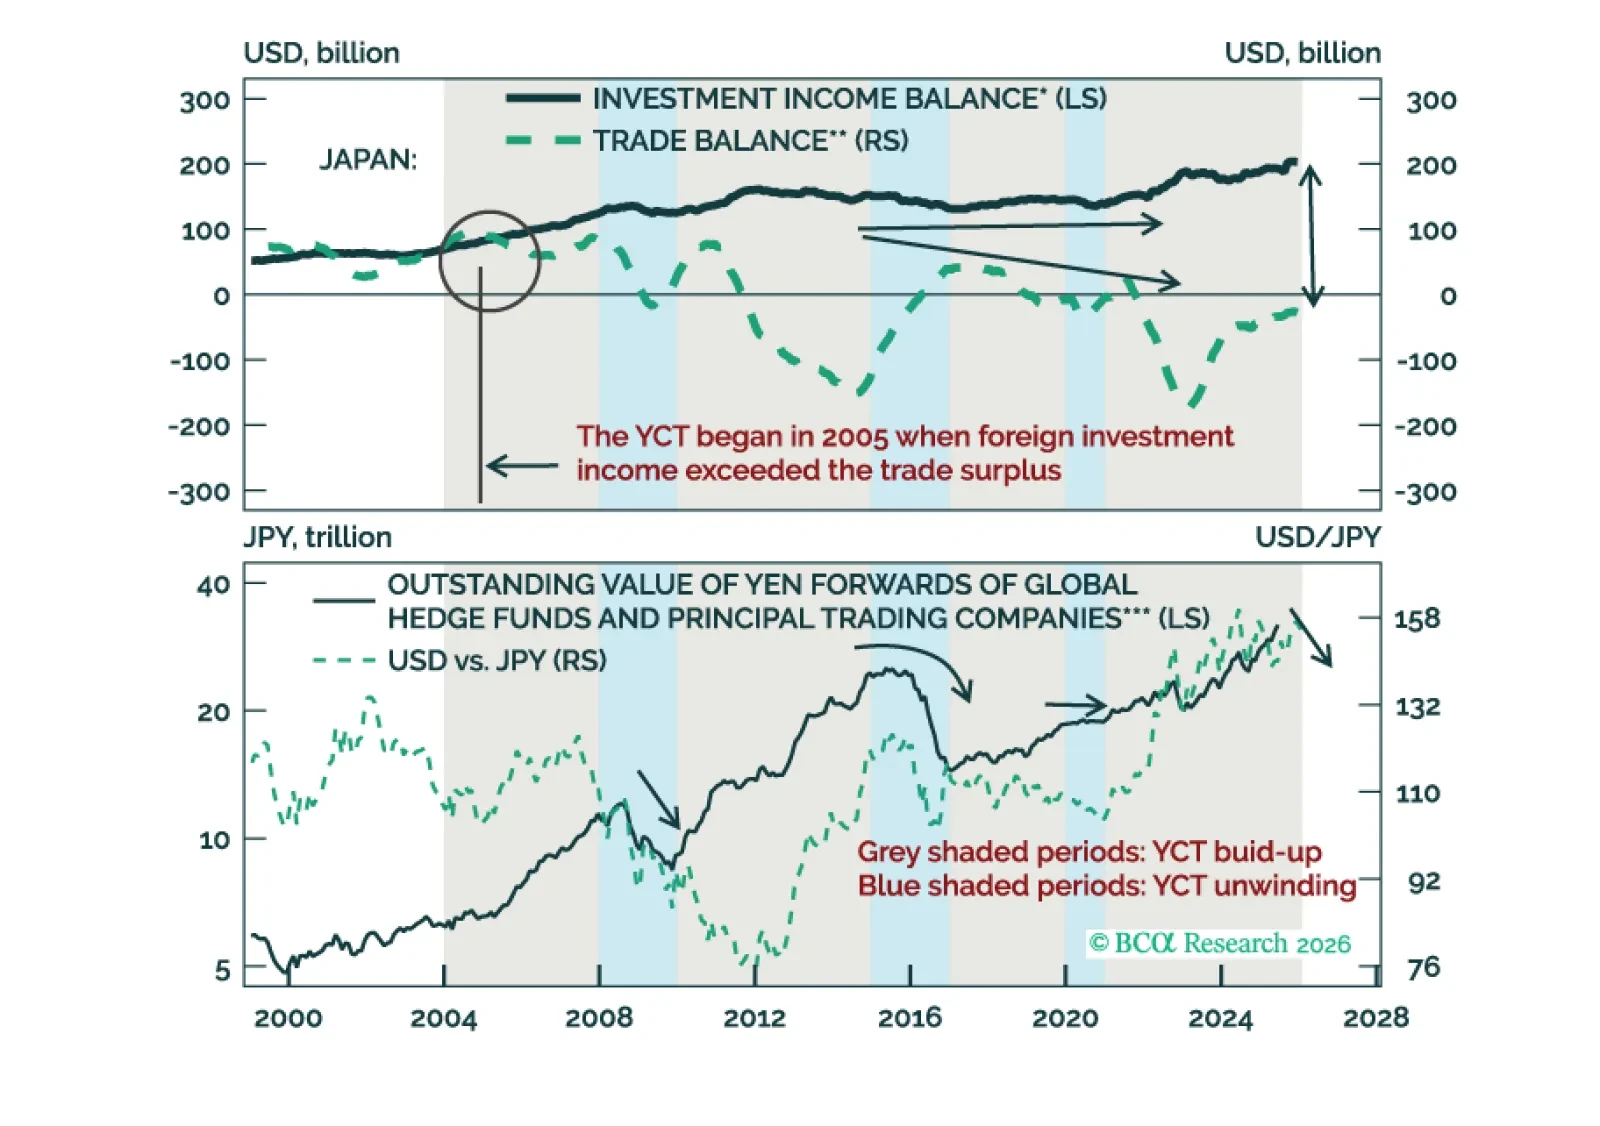
The US and Japan are in the same predicament: save the bond market or save the stock market? How this predicament will be resolved is the biggest global macro call of 2026-27. Plus: a new tactical trade is to go short AUD/JPY.
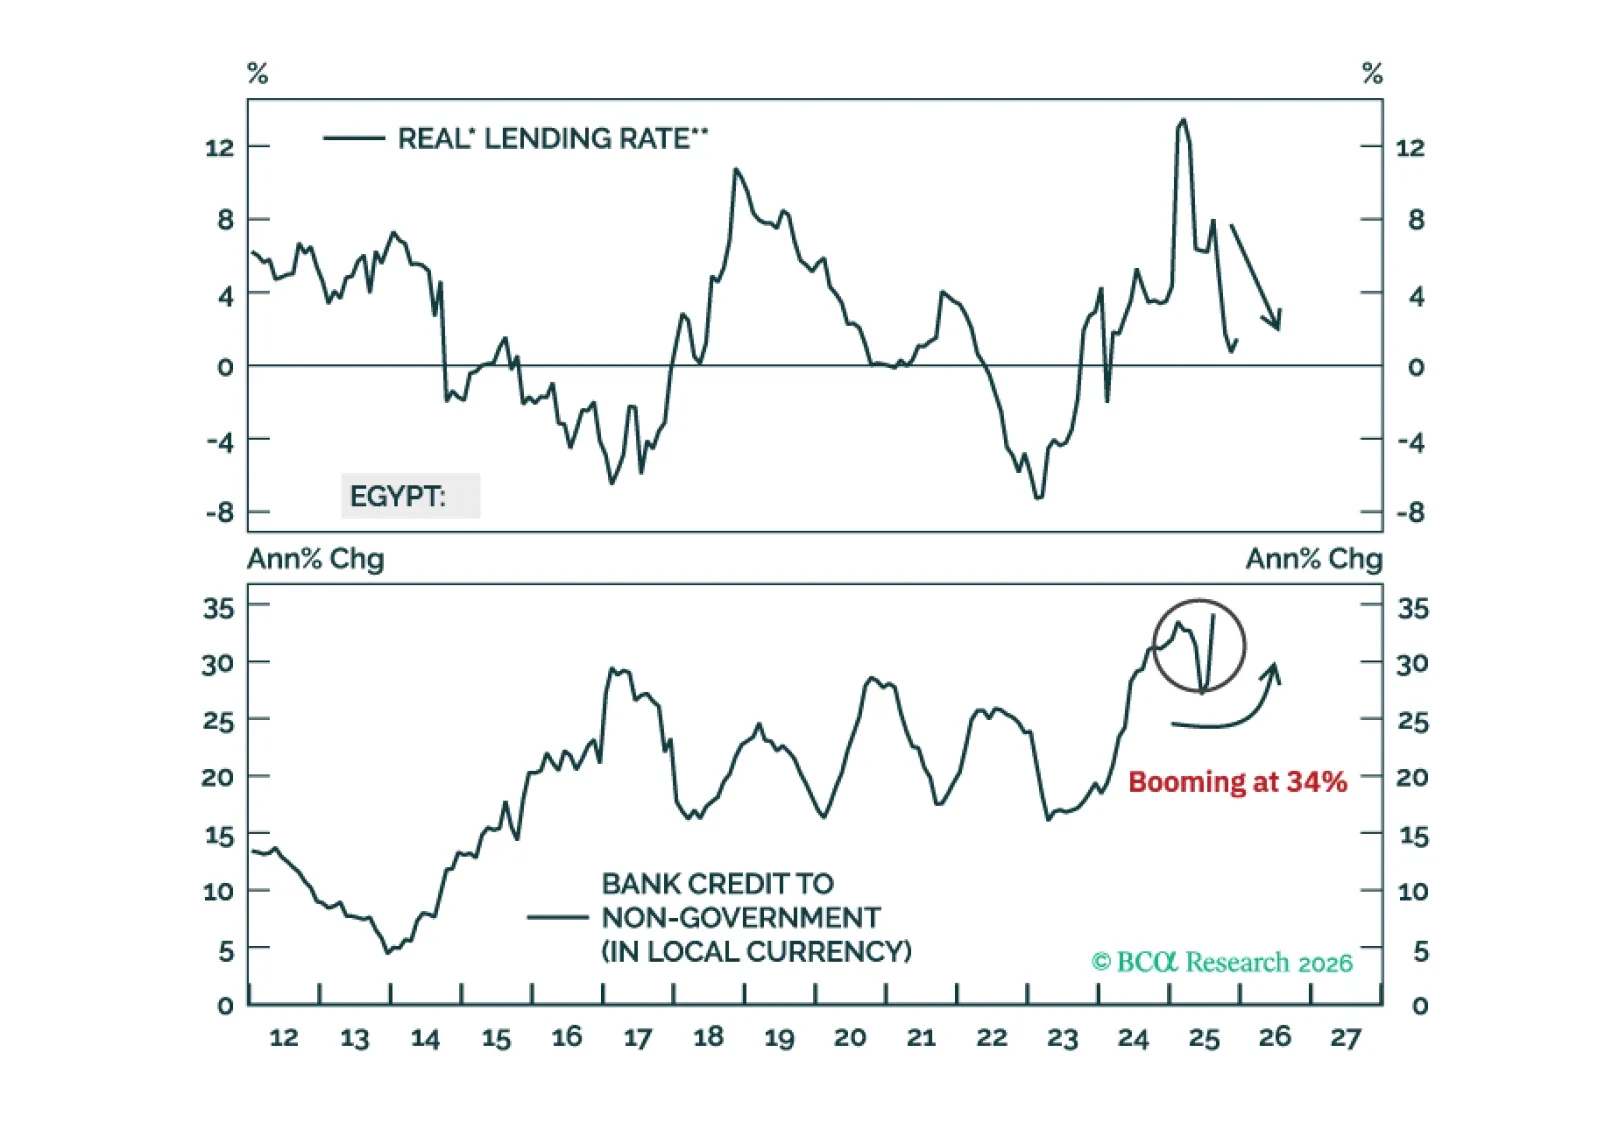
Egypt’s underlying inflation pressures are much higher than the headline CPI numbers imply. Real interest rates have plunged. As such, domestic bond yields have stayed high for a reason. Steer clear.
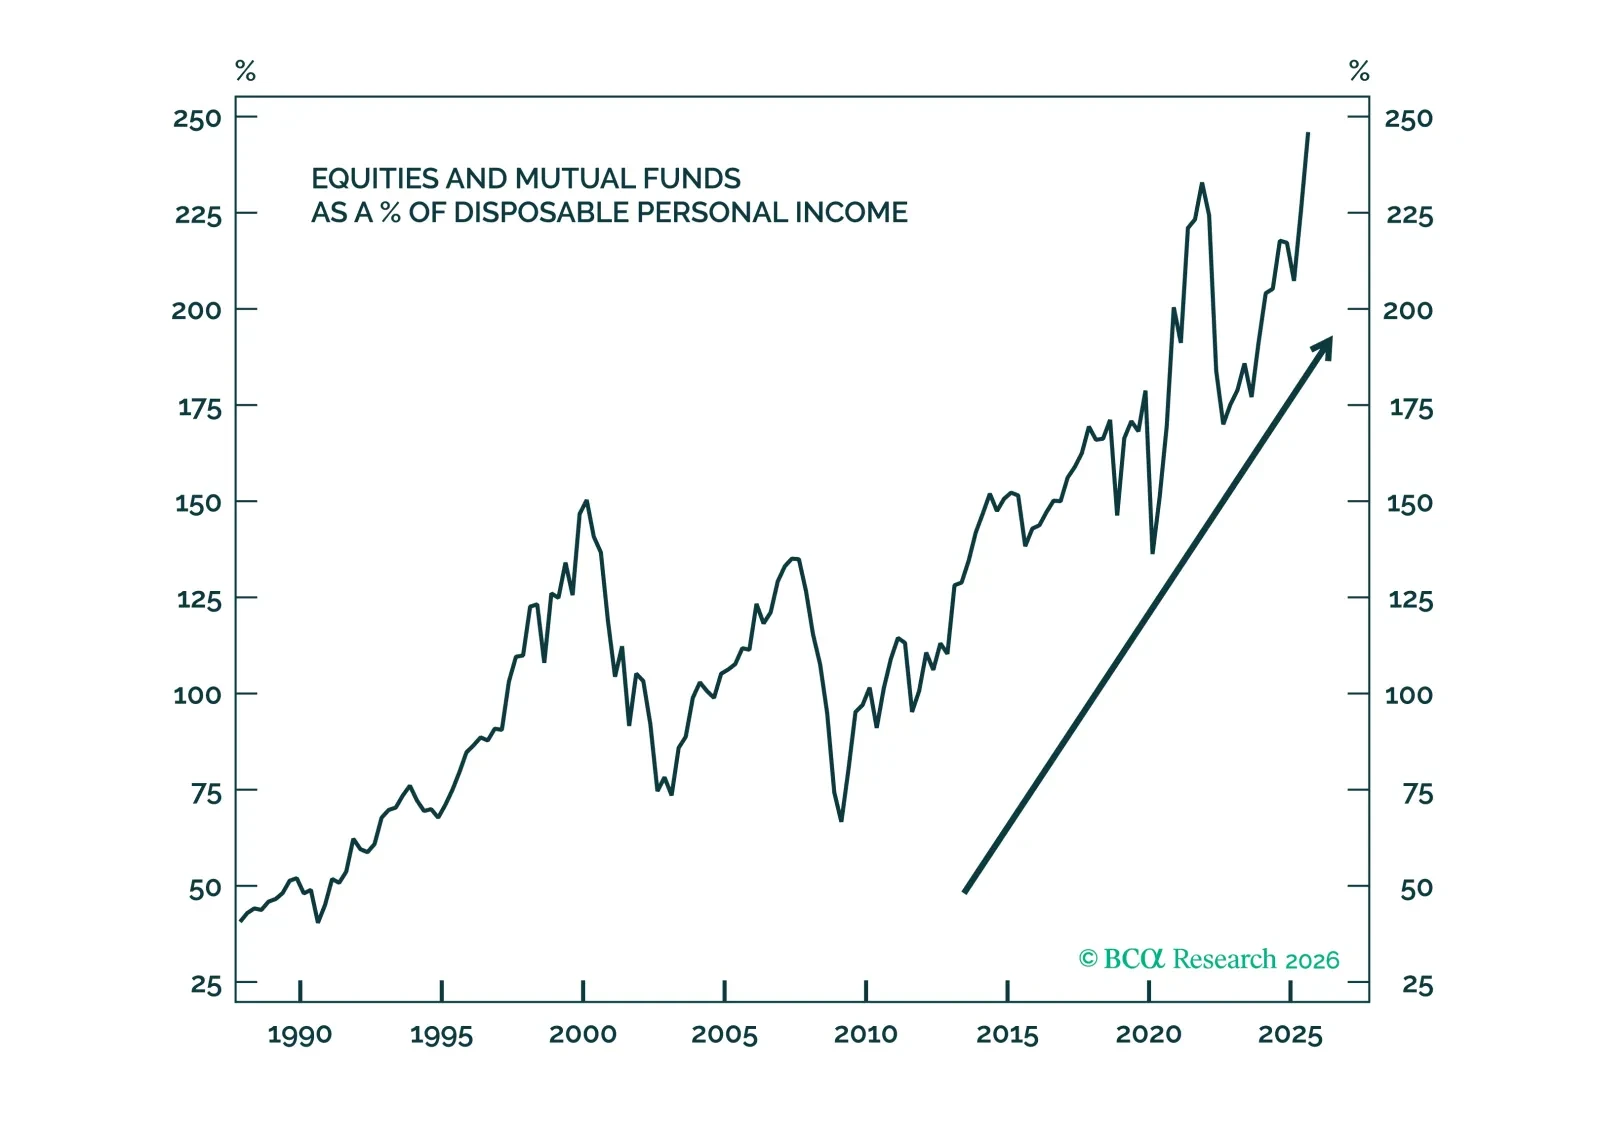
It appears that households have been able to spend more than they’ve earned since May by dipping into their swollen brokerage accounts. Bulked-up equity holdings could herald a future where consumption is more sensitive to stock market ups and downs. That’s great in bull markets but could be an unexpected drag on activity when the next bear arrives.
Almost all bull markets are built on a foundation of truth. With enough time, however, FOMO takes over, causing prices to overshoot fundamentals. This is what has happened to gold and silver, and increasingly to other metals as well.