 CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
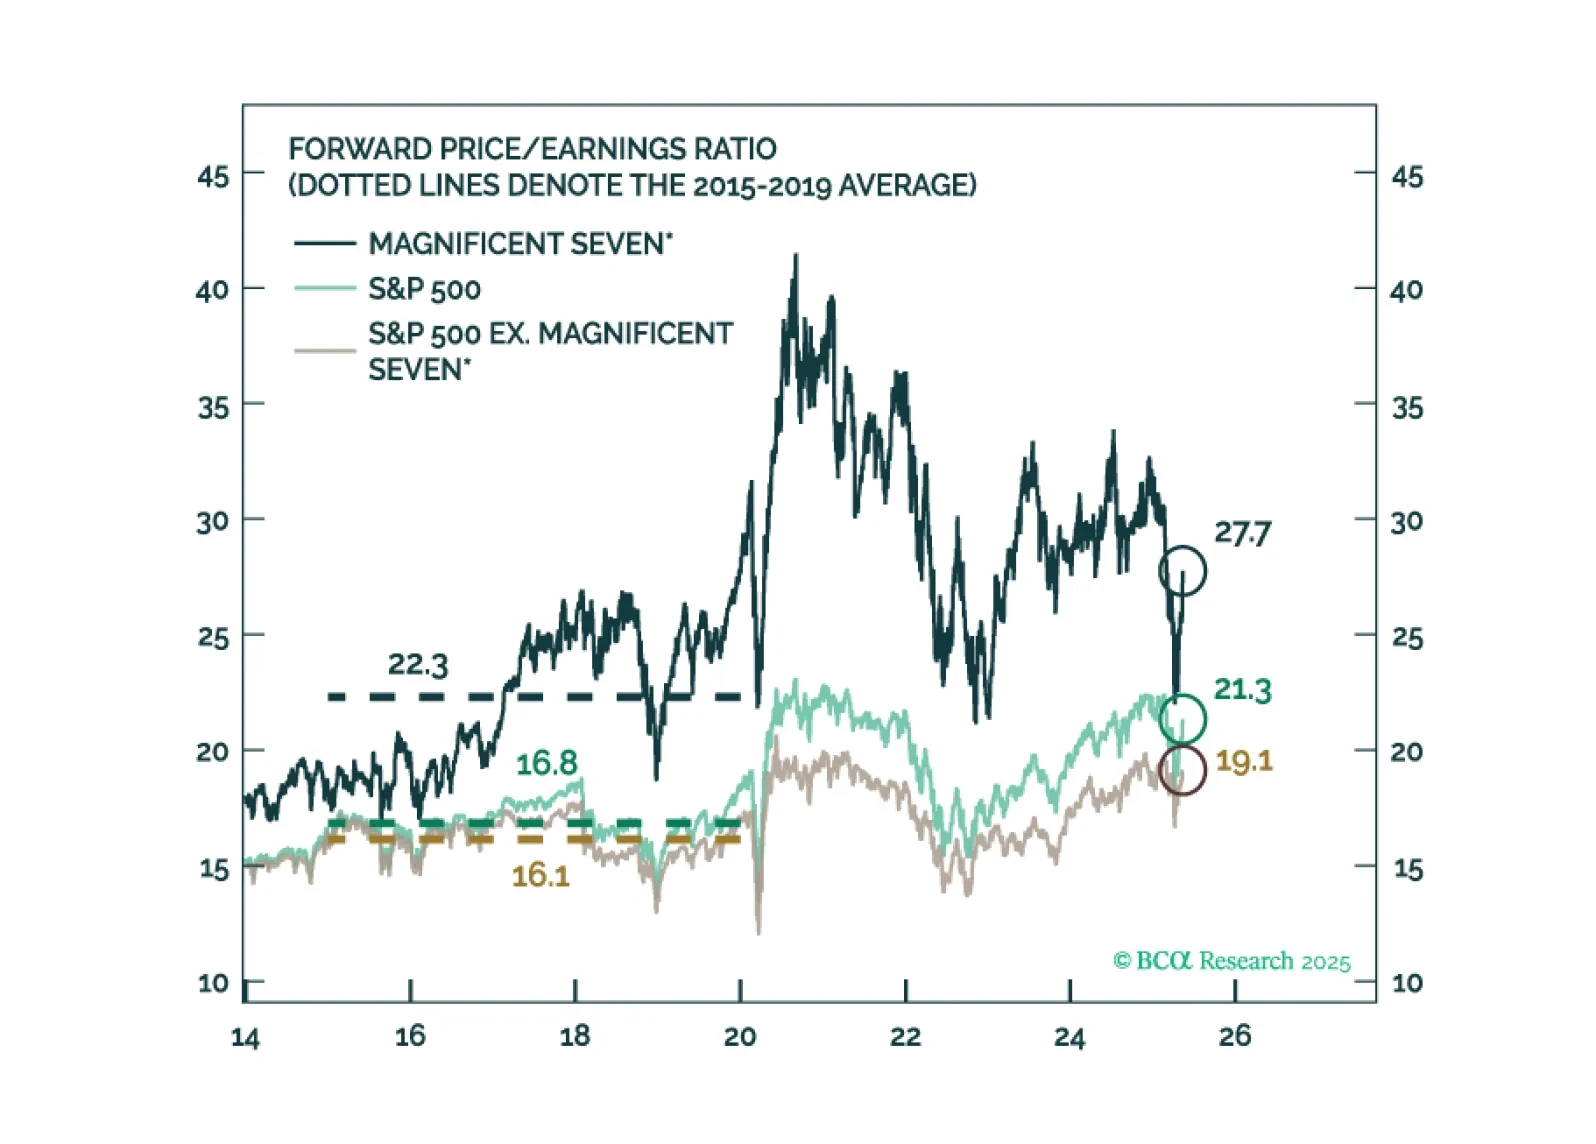
Although tariffs have receded, they are still high enough to weigh on growth, especially given that underlying economic momentum in the US was weakening going into 2025. The possibility of a fiscal crisis only adds to the risks.
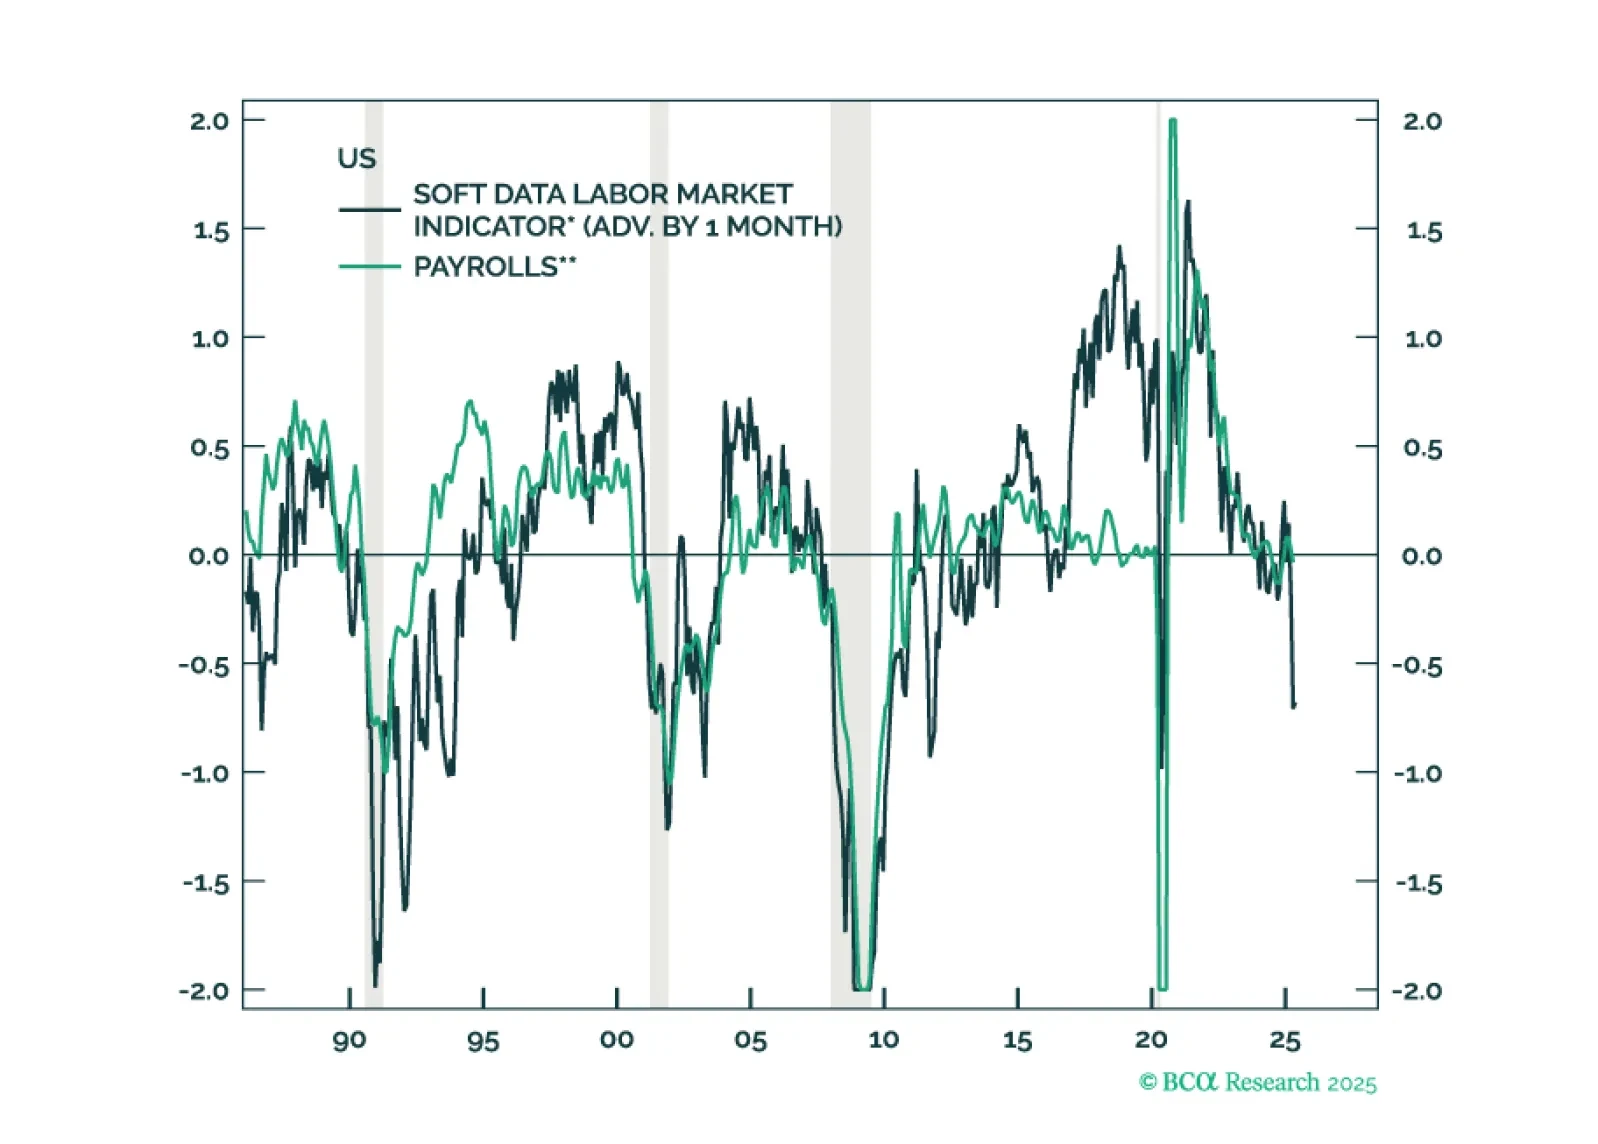
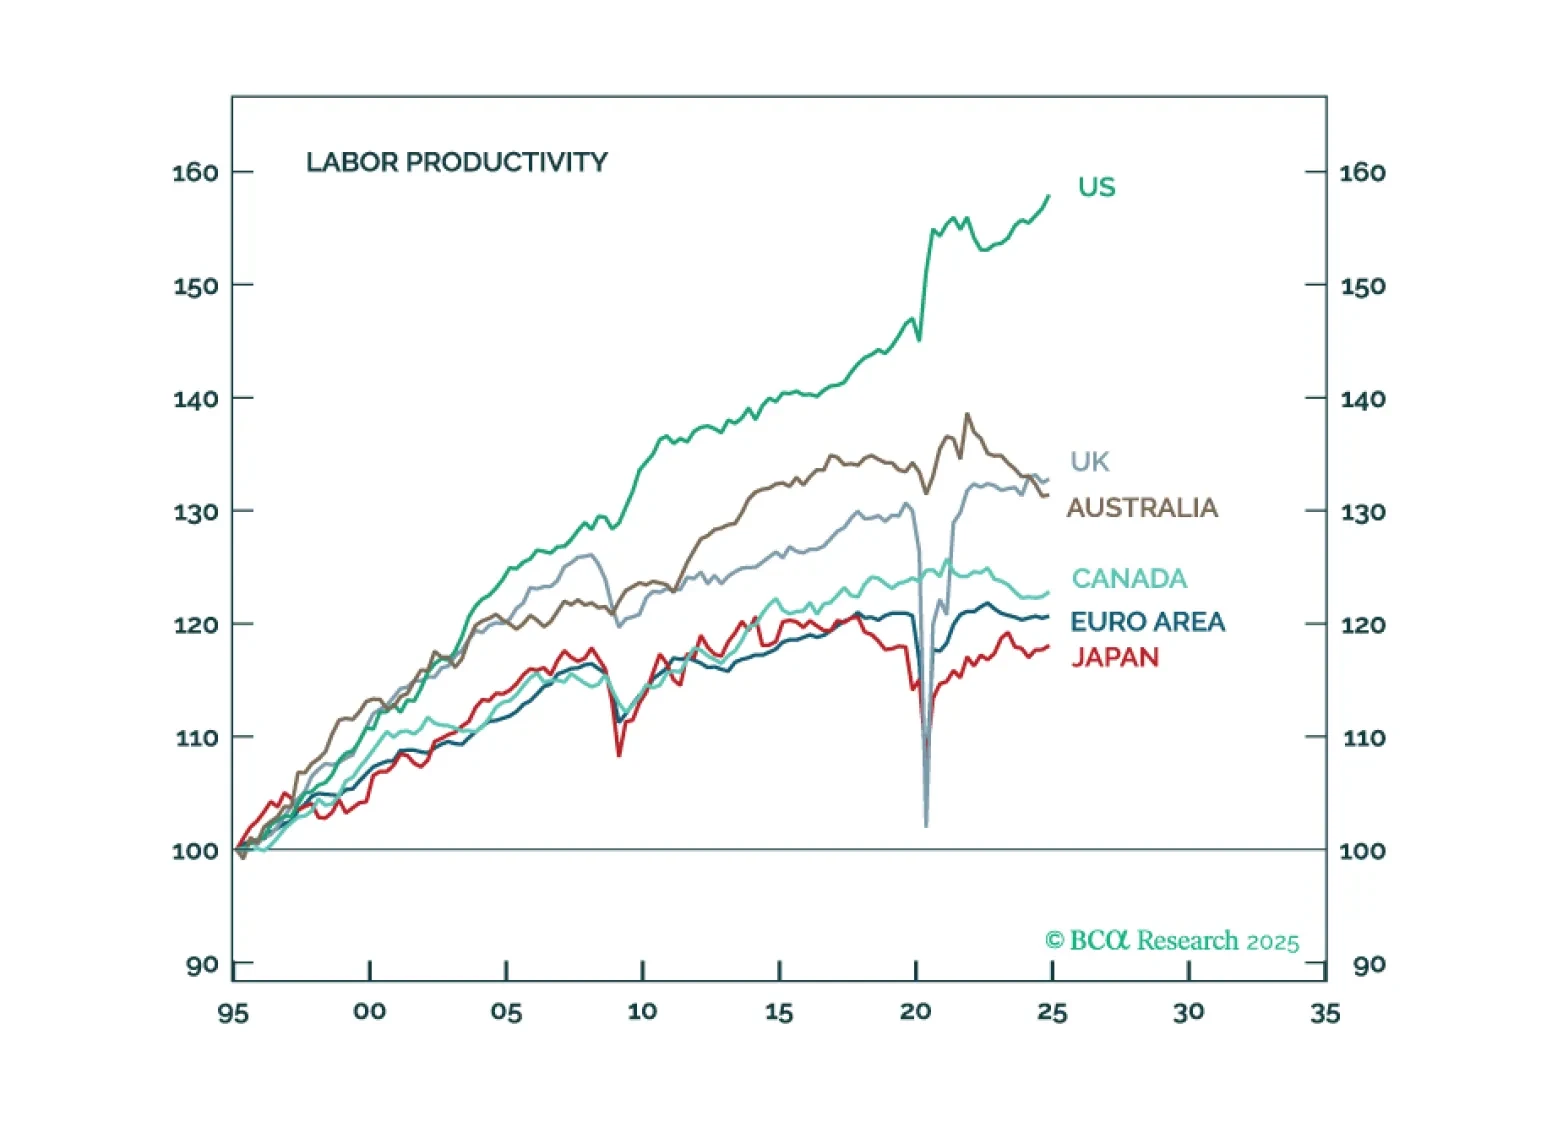
Although the sell-off in the US dollar and relative outperformance of non-US stocks will pause over the coming months as a global recession begins, the fading of US exceptionalism will still cause the dollar to weaken and US stocks to underperform over a multi-year horizon.
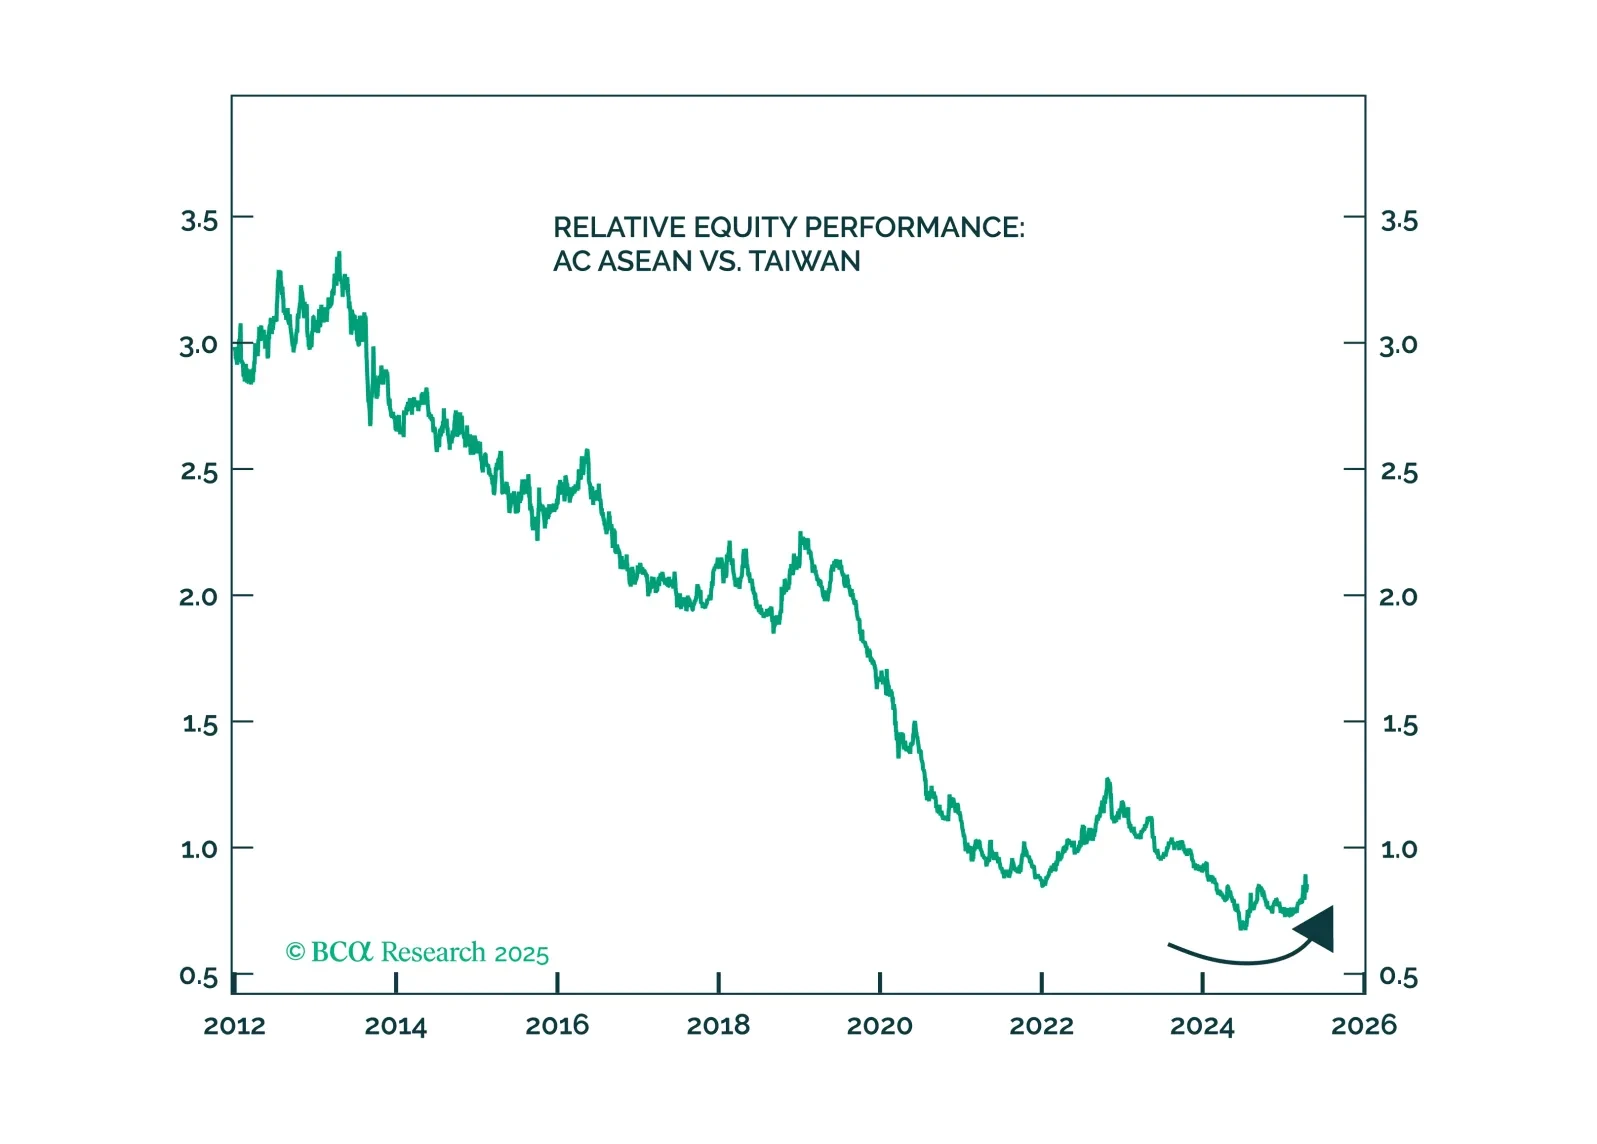
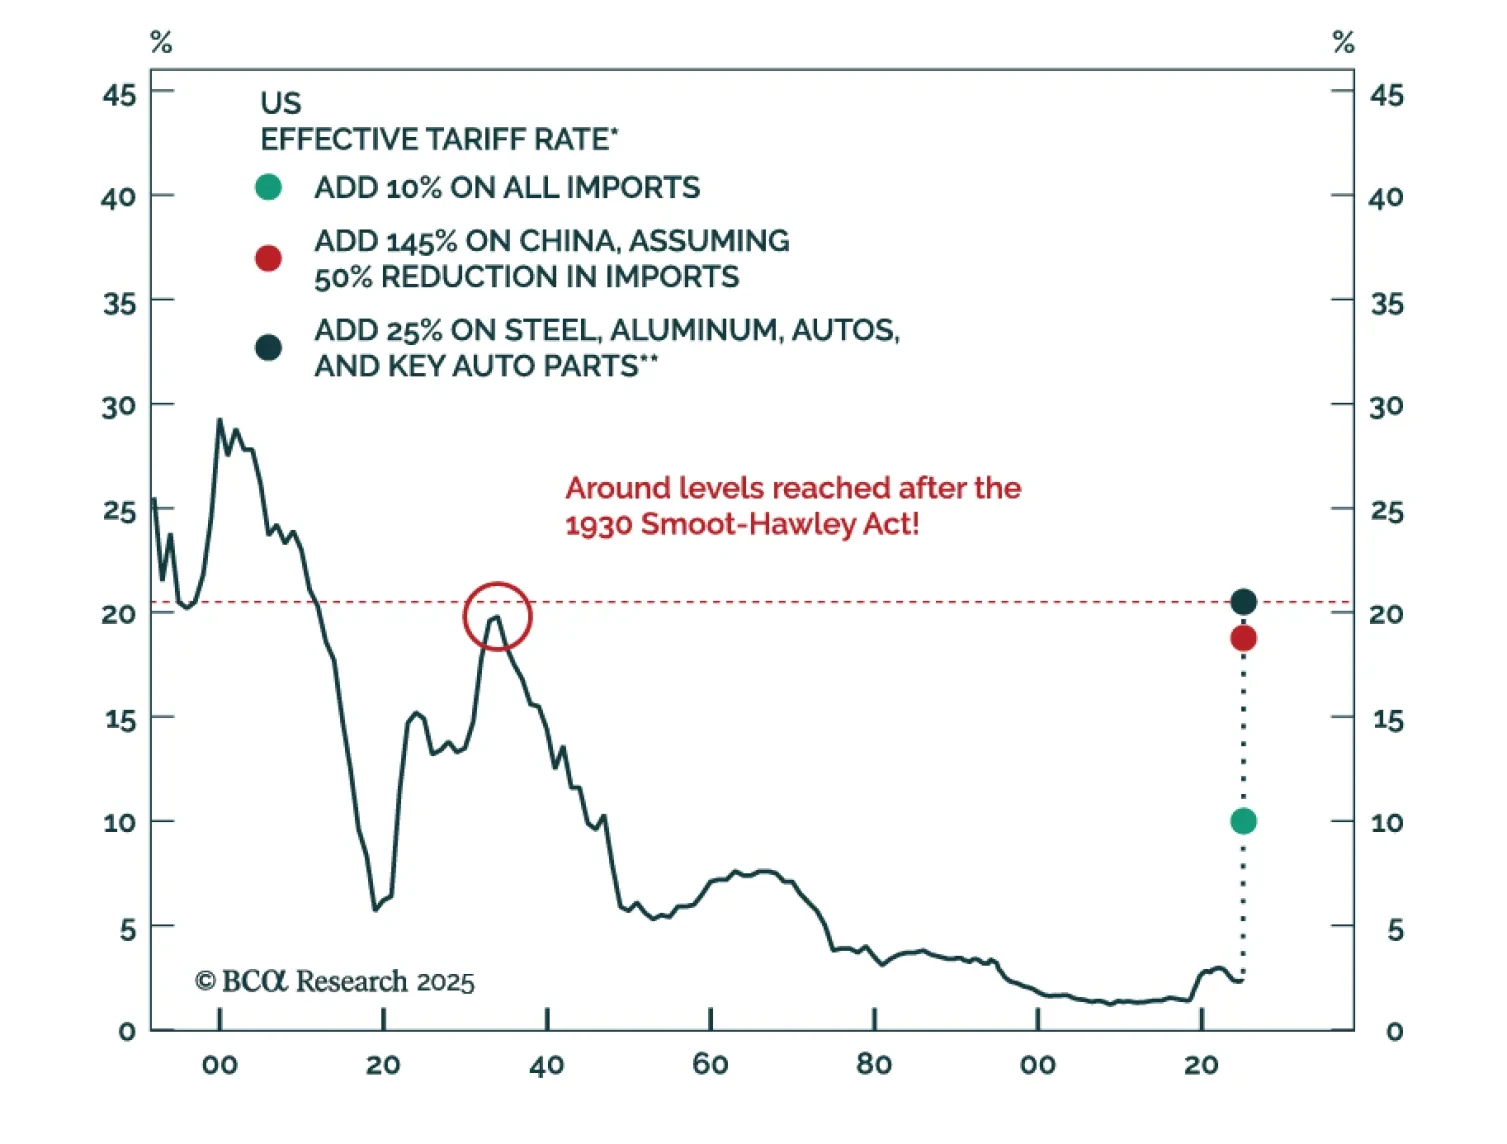
Barring a dramatic further de-escalation of the trade war, the US and much of the rest of the world will enter a recession over the next few months. Investors should remain defensively positioned for now.
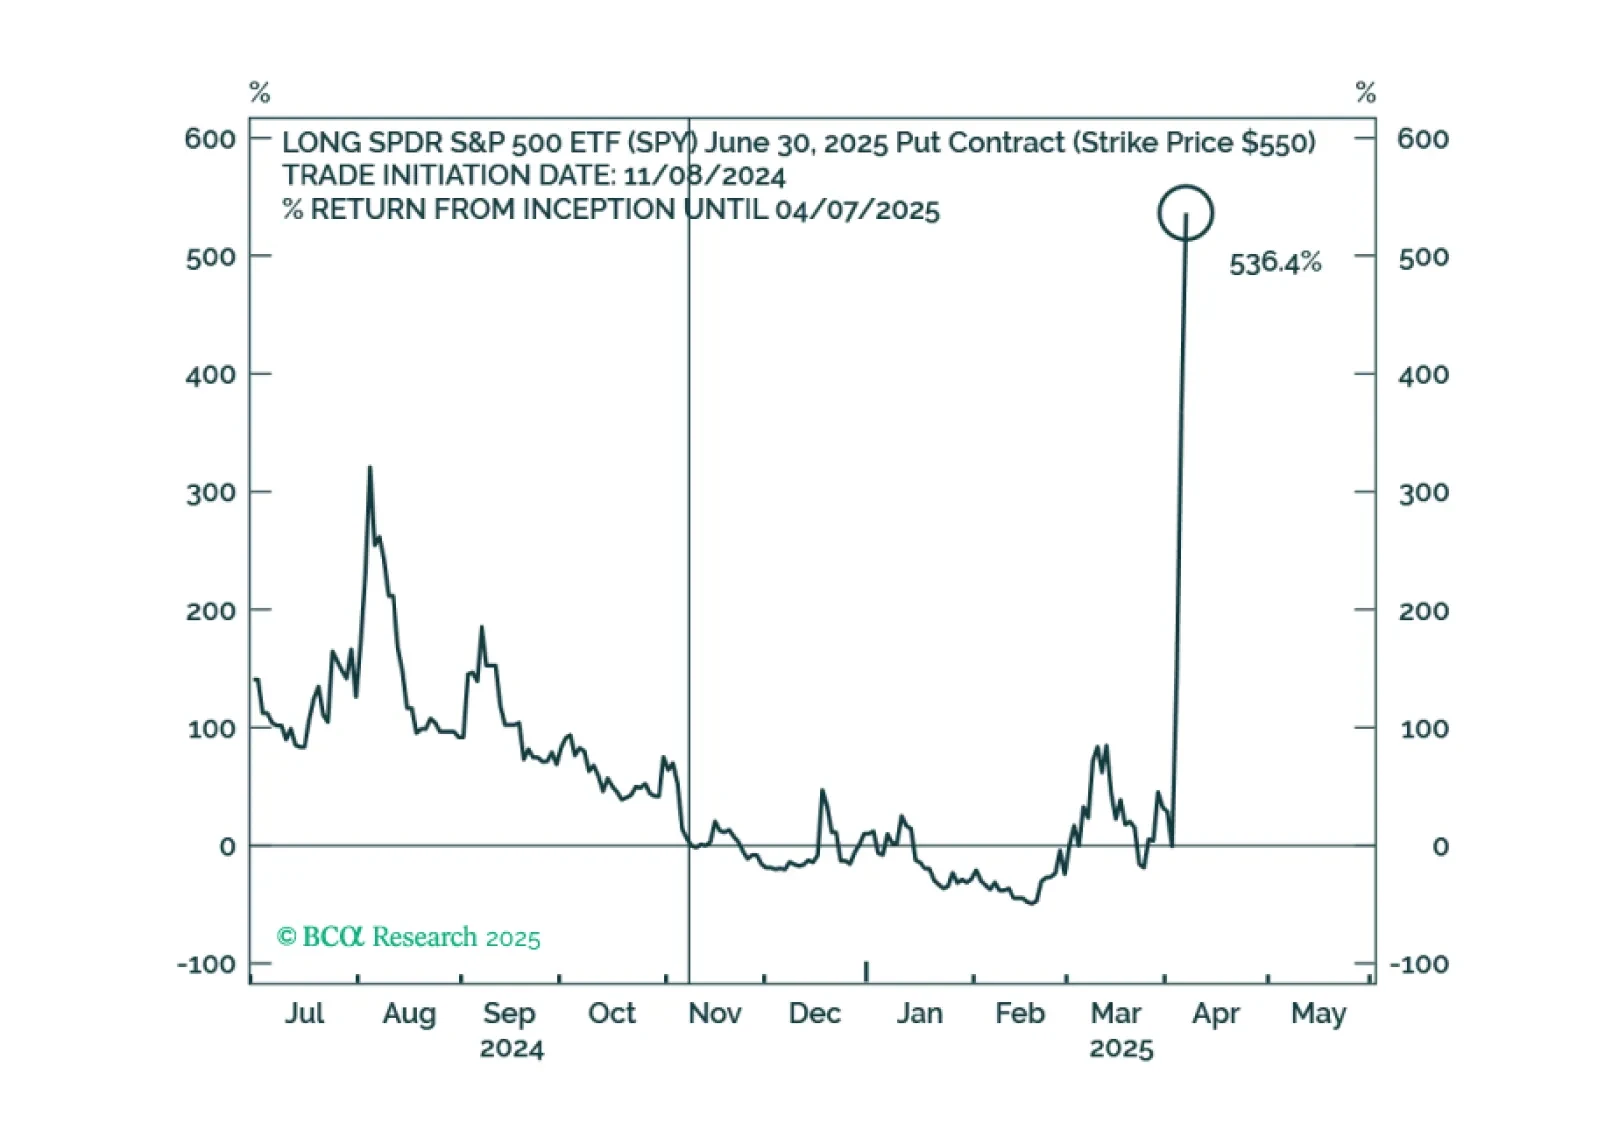
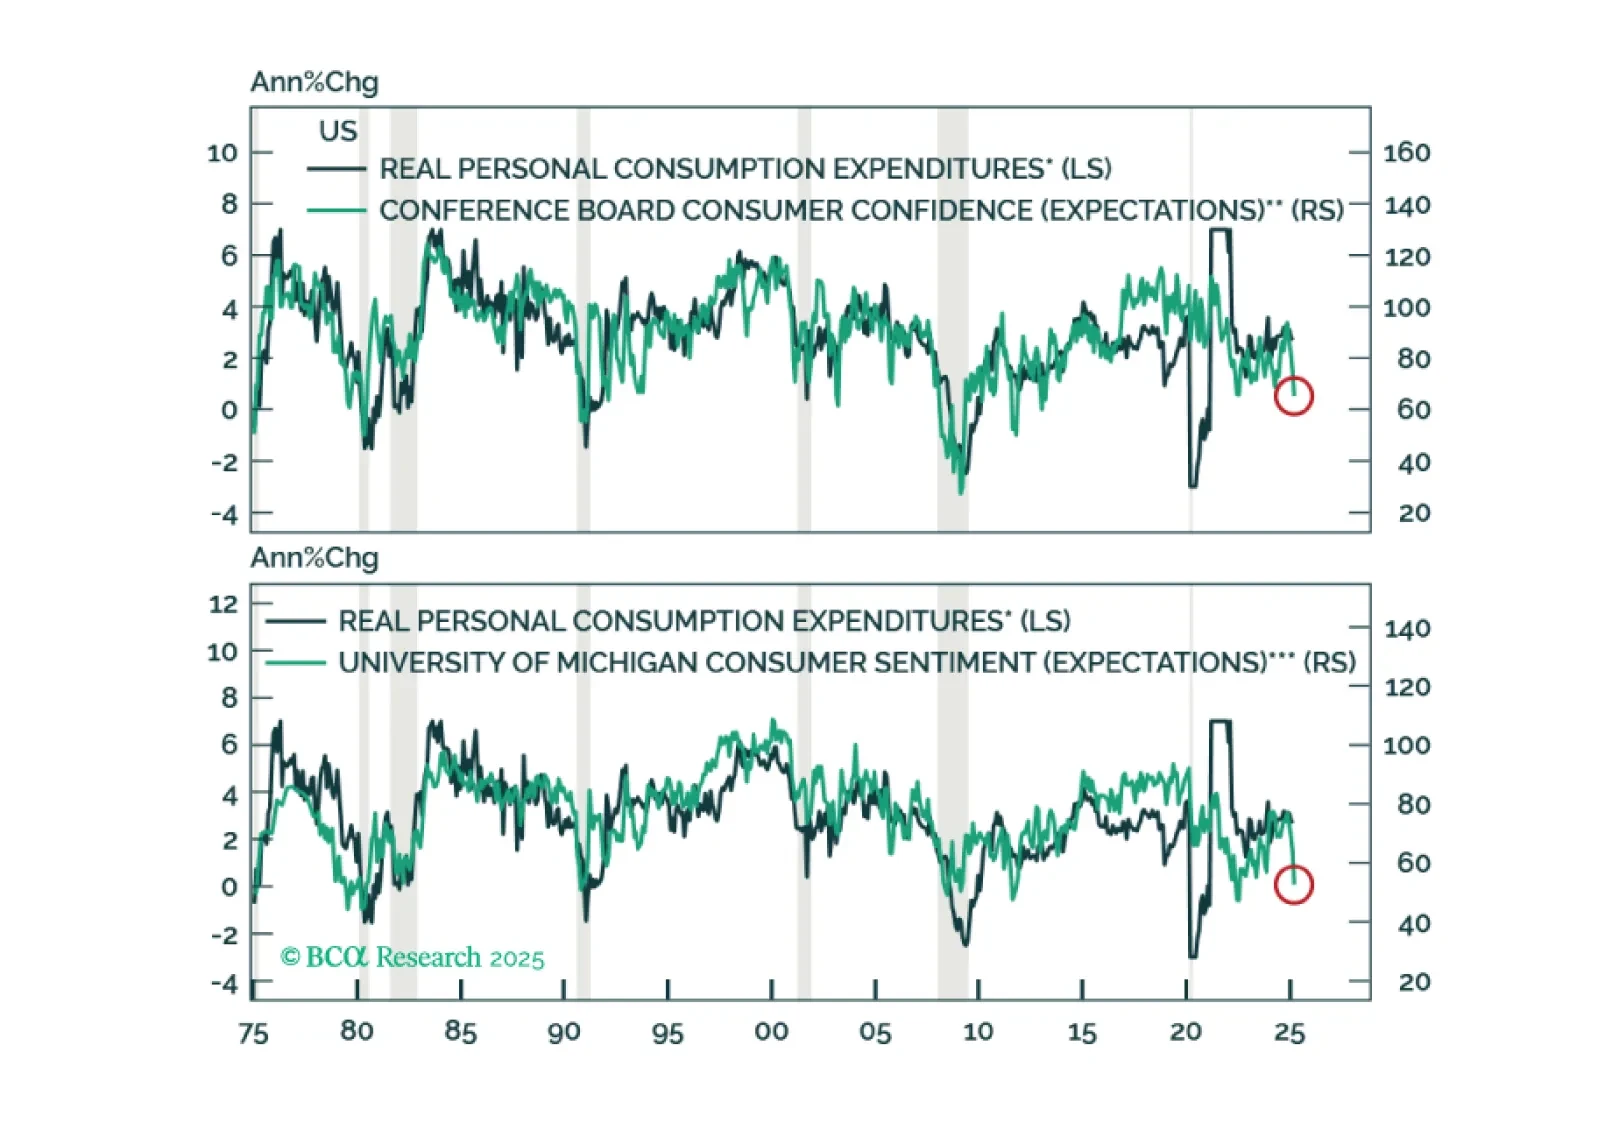
Going into this year, I was by far the most bearish strategist in the Bloomberg survey. A number of clients have reached out to me asking if I plan to change my end-year price of 4450 for the S&P 500 in light of recent events. The answer is “no,” since recent events have unfolded broadly in line with my expectations.
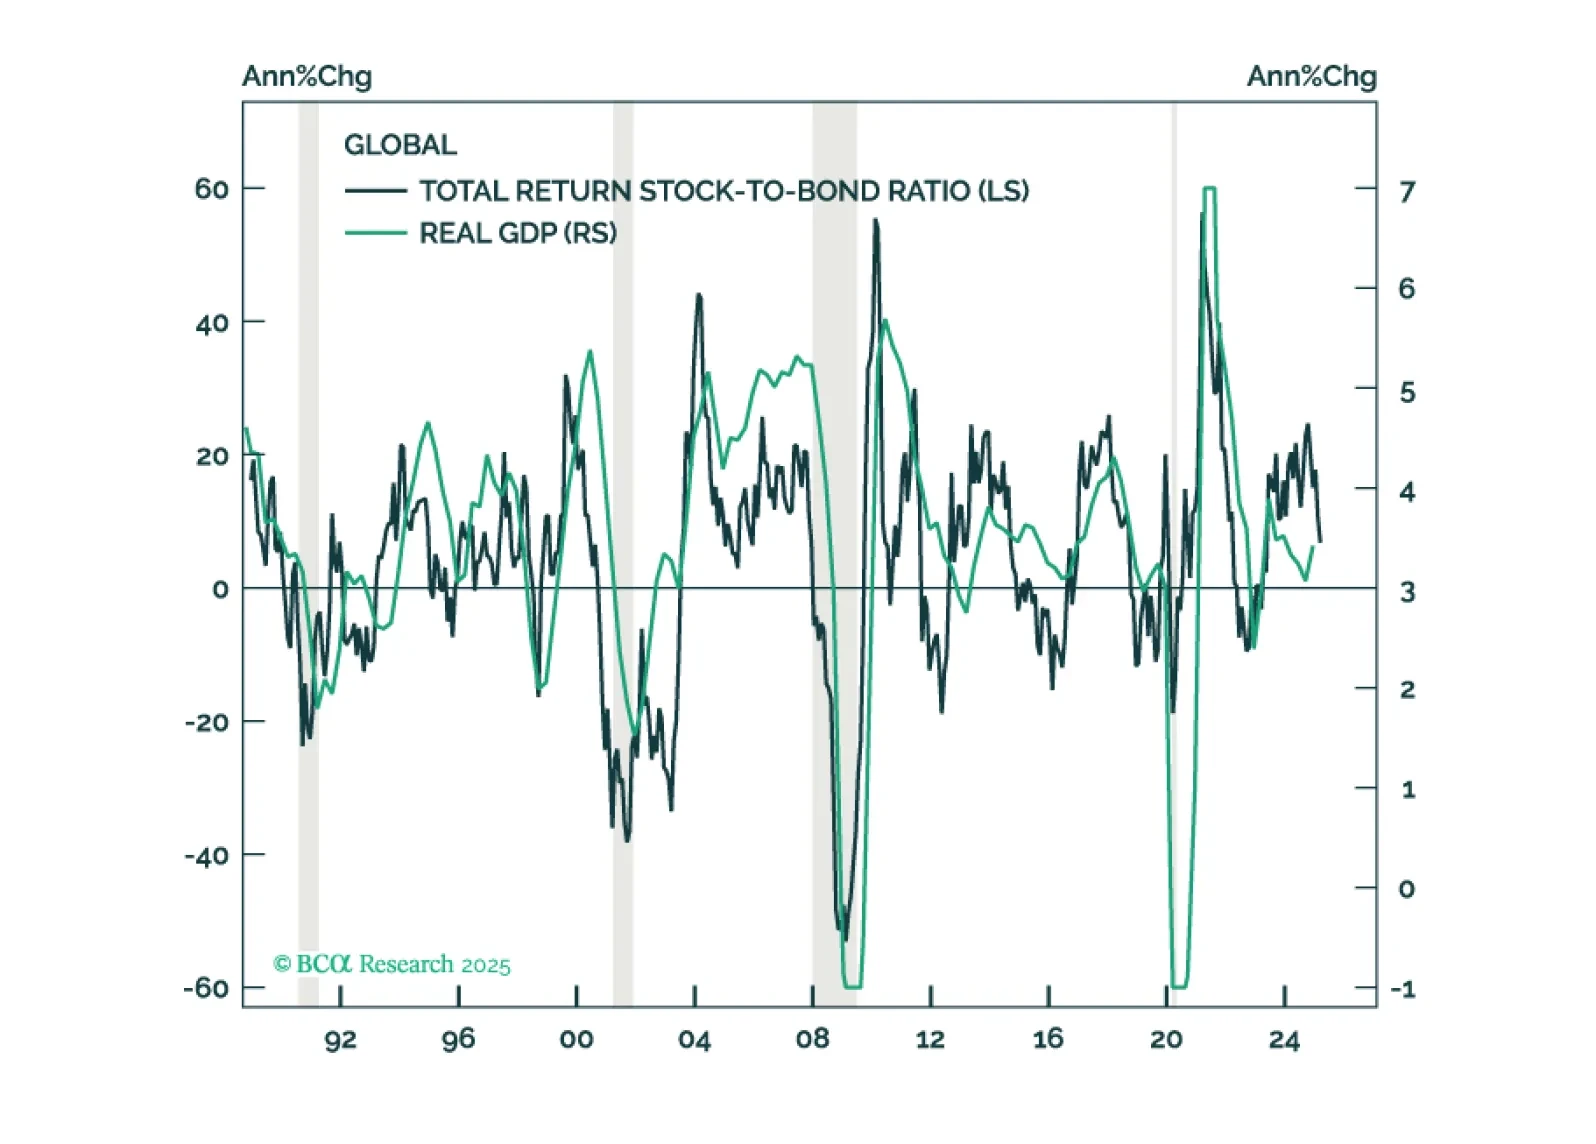
In this Second Quarter Strategy Outlook, we explore the major trends that are set to drive financial markets for the rest of 2025 and beyond.
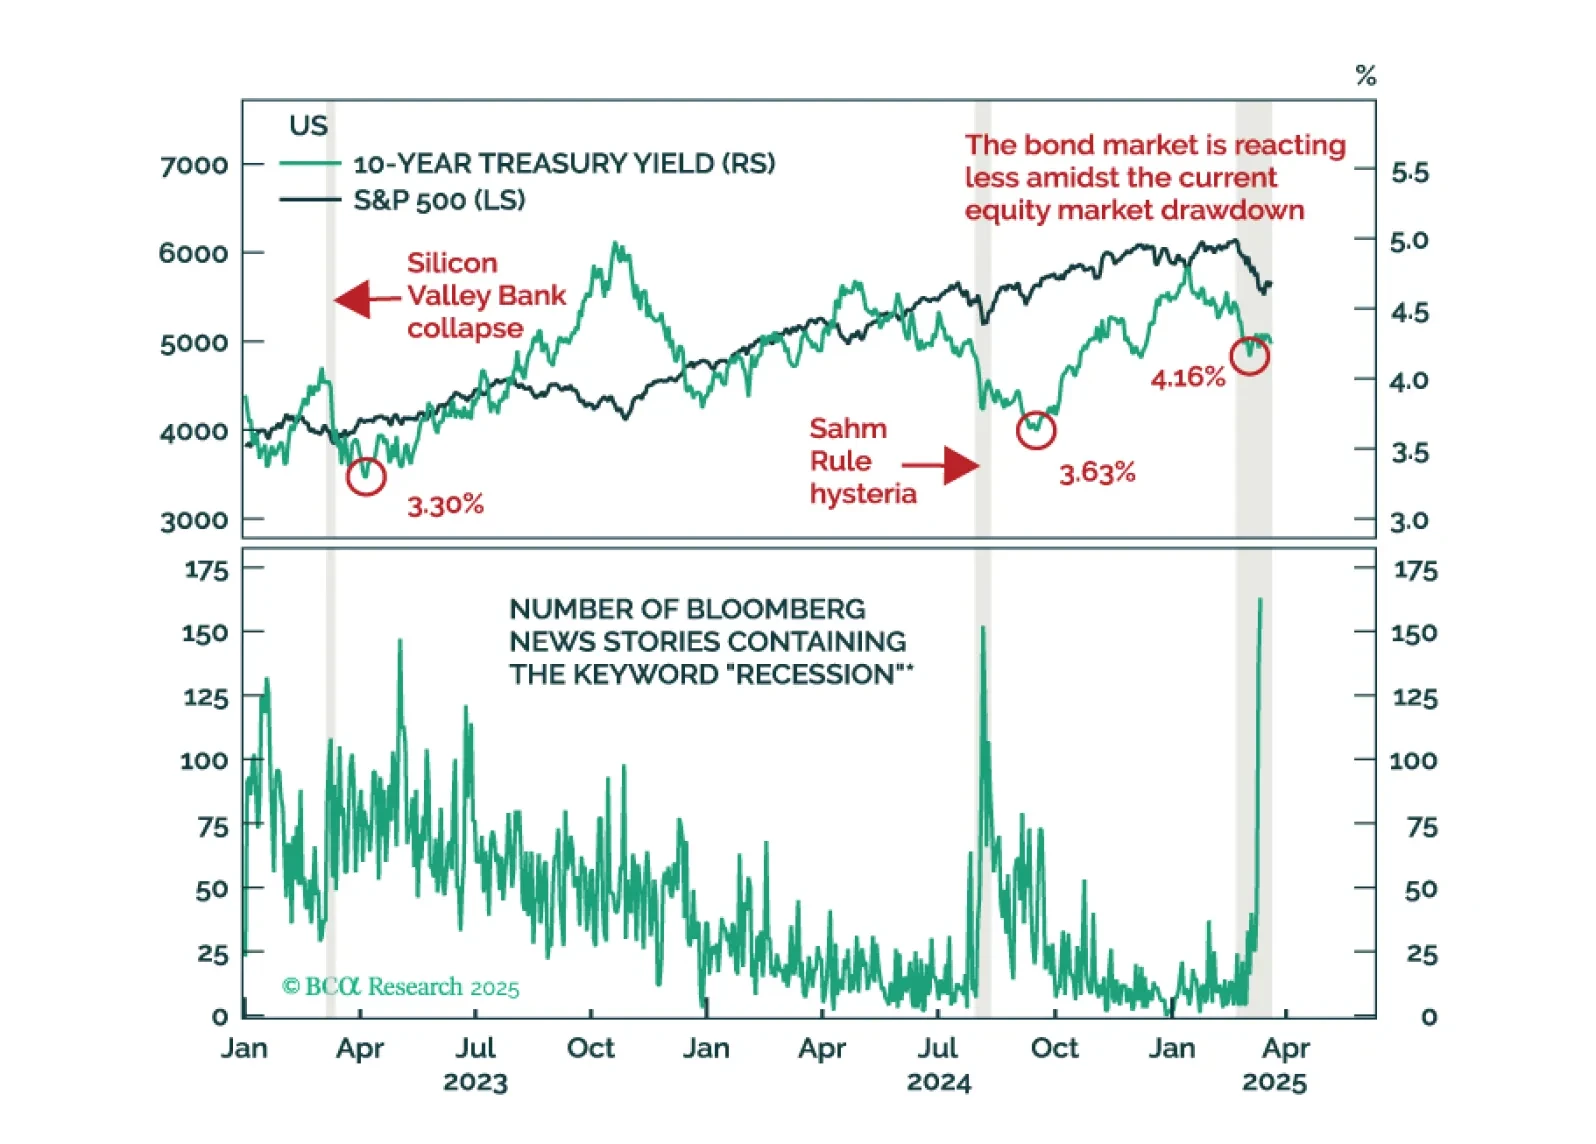
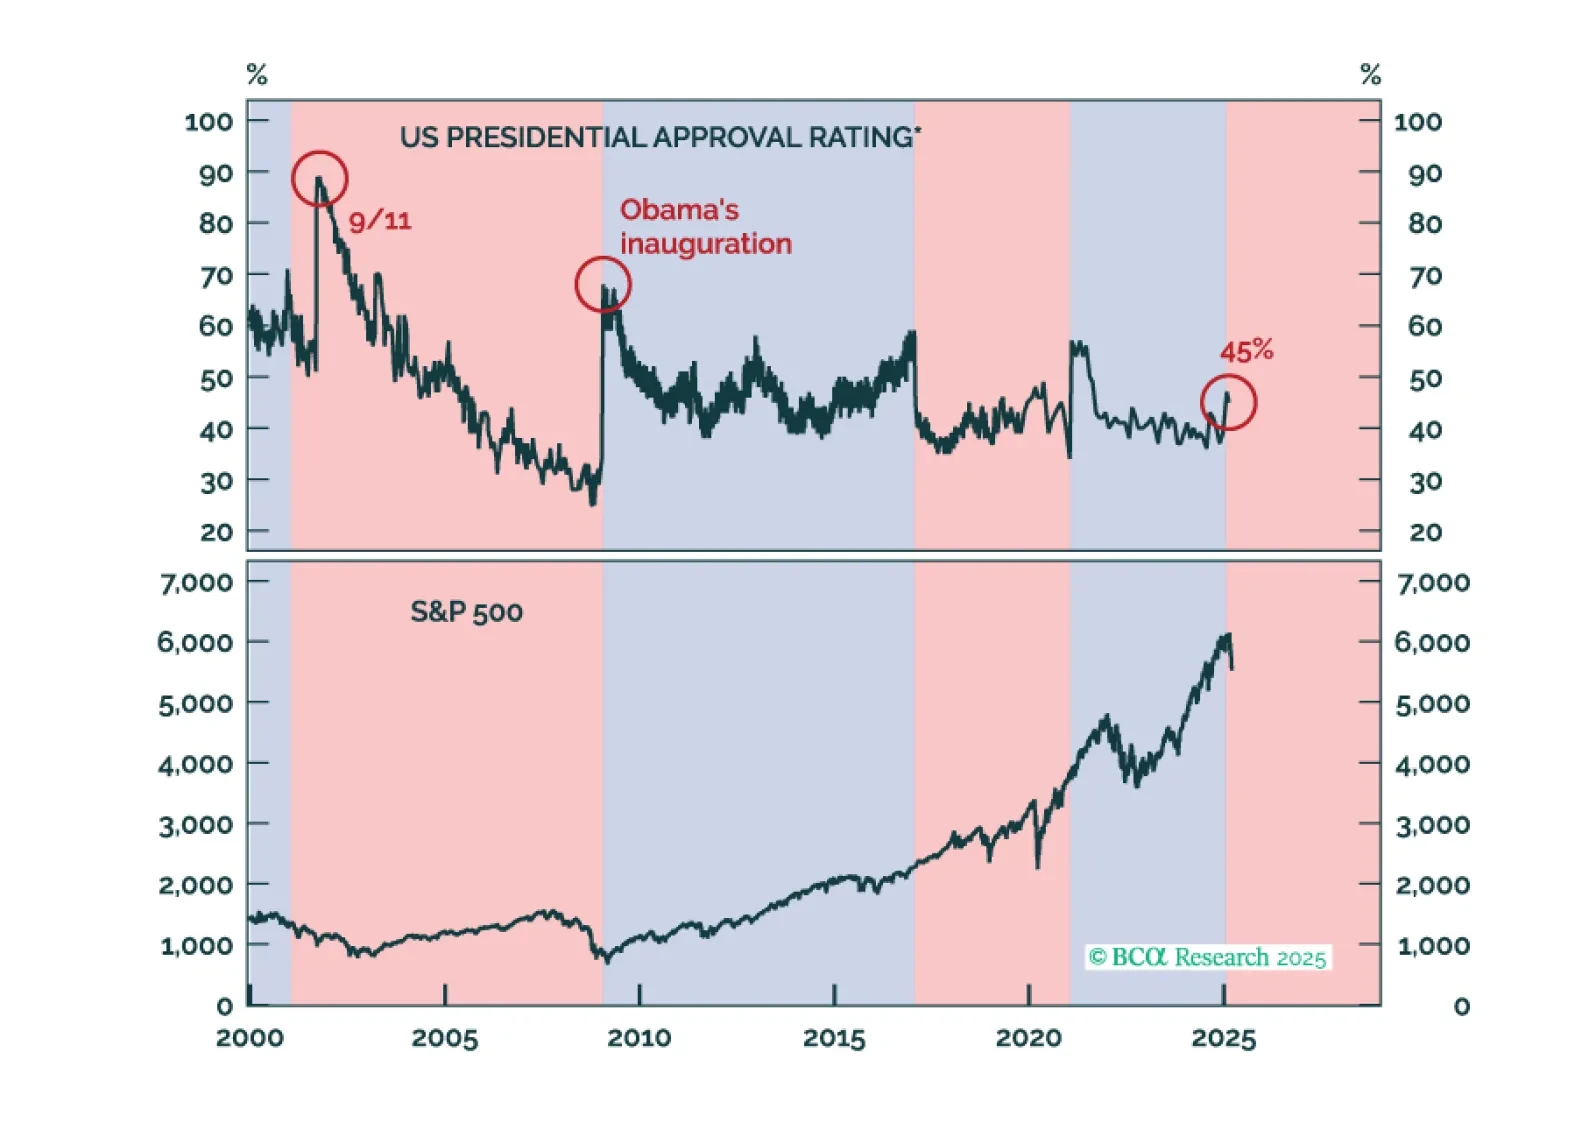
Despite our bearish predisposition towards stocks, we are open-minded to anything that could challenge our thesis. As such, in this report, we review five upside scenarios for equities.