Economy
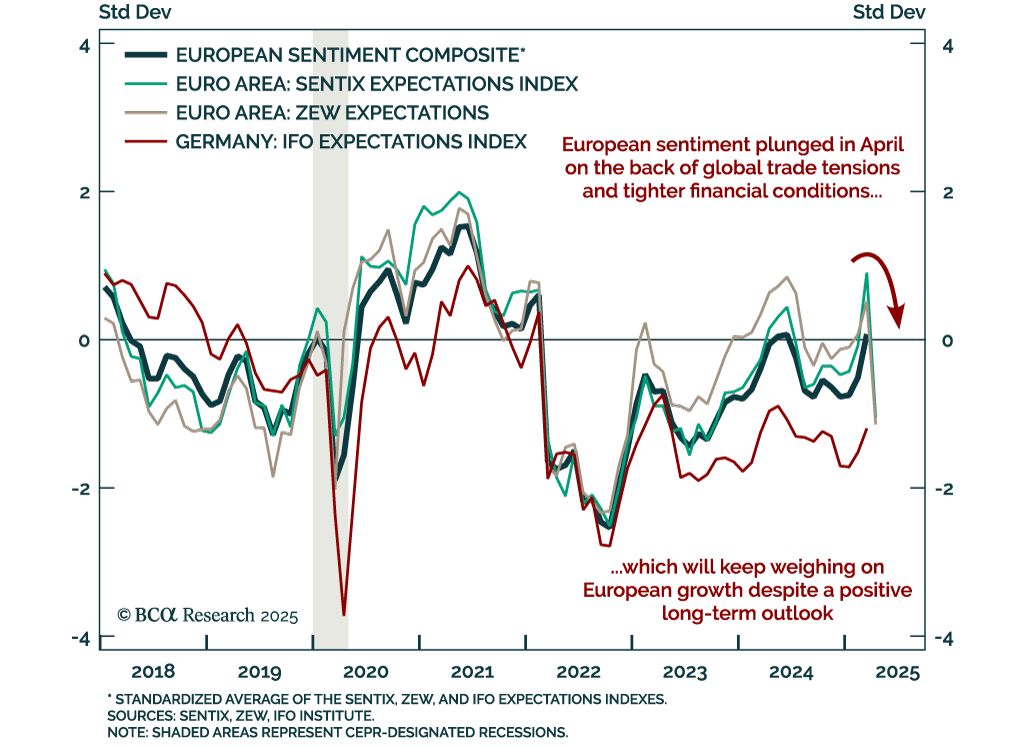
Eurozone sentiment has sharply deteriorated, reinforcing a cautious stance on European assets over the next 6 to 12 months. The April ZEW expectations index for the eurozone collapsed to -18.5 from 39.8, while Germany’s gauge also plunged and missed…
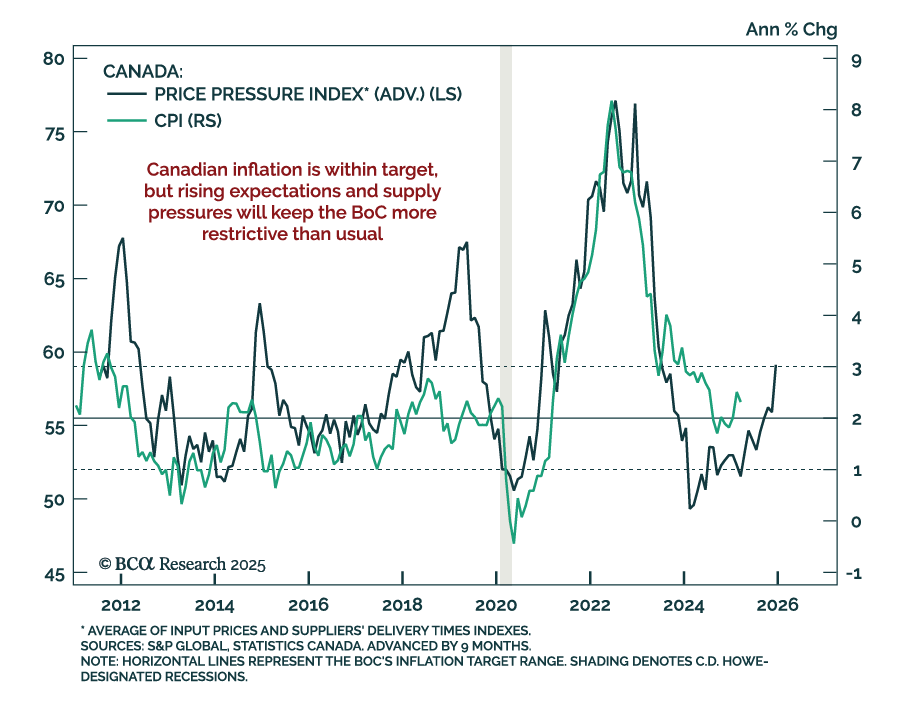
Cooler inflation will not shift the BoC’s stance, as stagflation limits potential easing, keeping us neutral on Canadian bonds. In March, headline CPI slowed more than expected to 2.3% y/y from 2.6%. However, lower energy prices drove much of the downside…
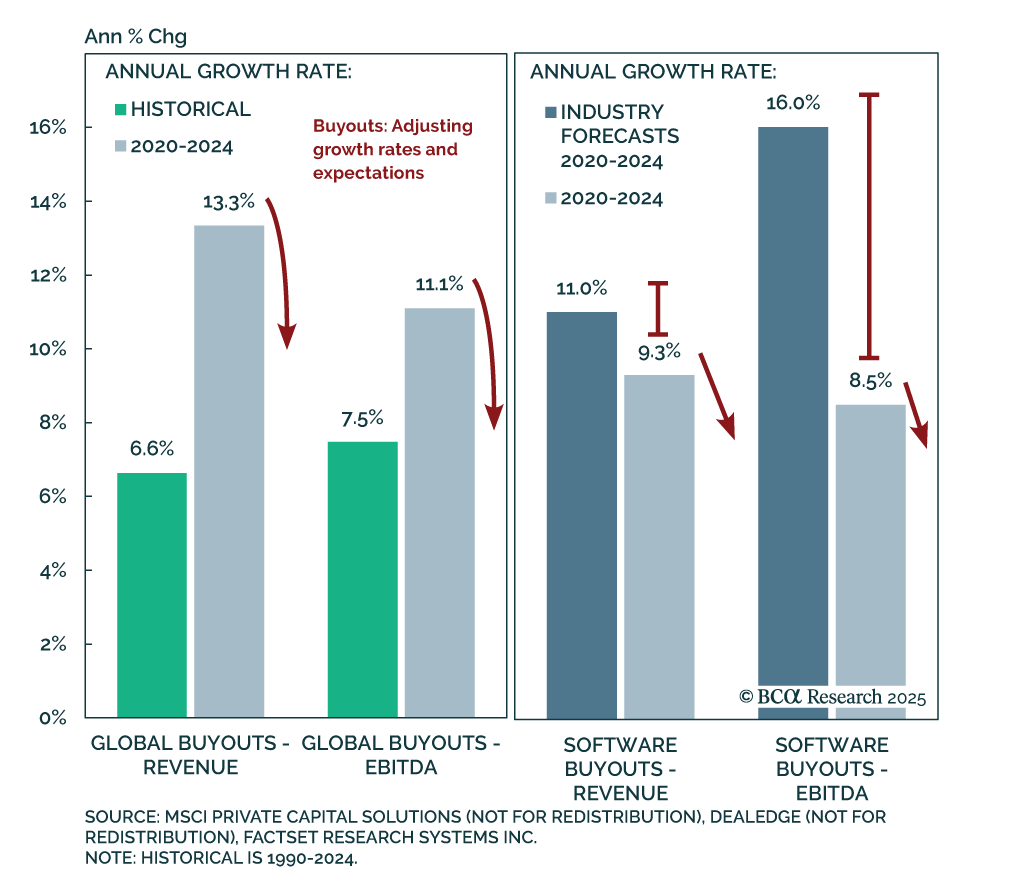
Our Private Markets & Alternatives strategists remain positioned for a downturn. Private Equity is most threatened as tariffs intensify existing recession risks. Buyout strategies face stress from record-low distributions and rising LP-GP friction. Venture…
We are pleased to share the replay of US Equity Market Intelligence Session, hosted by Chief US Equity Strategist Irene Tunkel.
Please join BCA Research's Chief US Equity Strategist, Irene Tunkel, for a US Equity Intelligence session on Wednesday, April 16 at 9:00 AM HKT, 11:00 AM AEST.
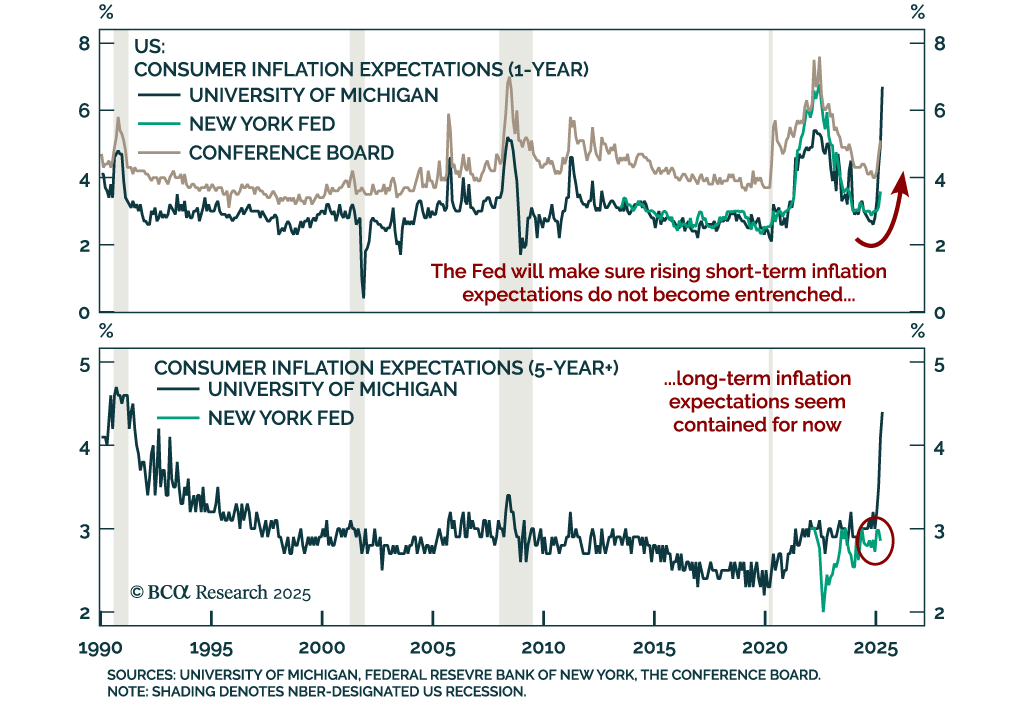
The latest NY Fed Survey of Consumer Expectations reinforces our defensive stance, with growth concerns deepening even as long-term inflation expectations remain anchored. The survey is a useful cross-check against broader sentiment and inflation indicators,…
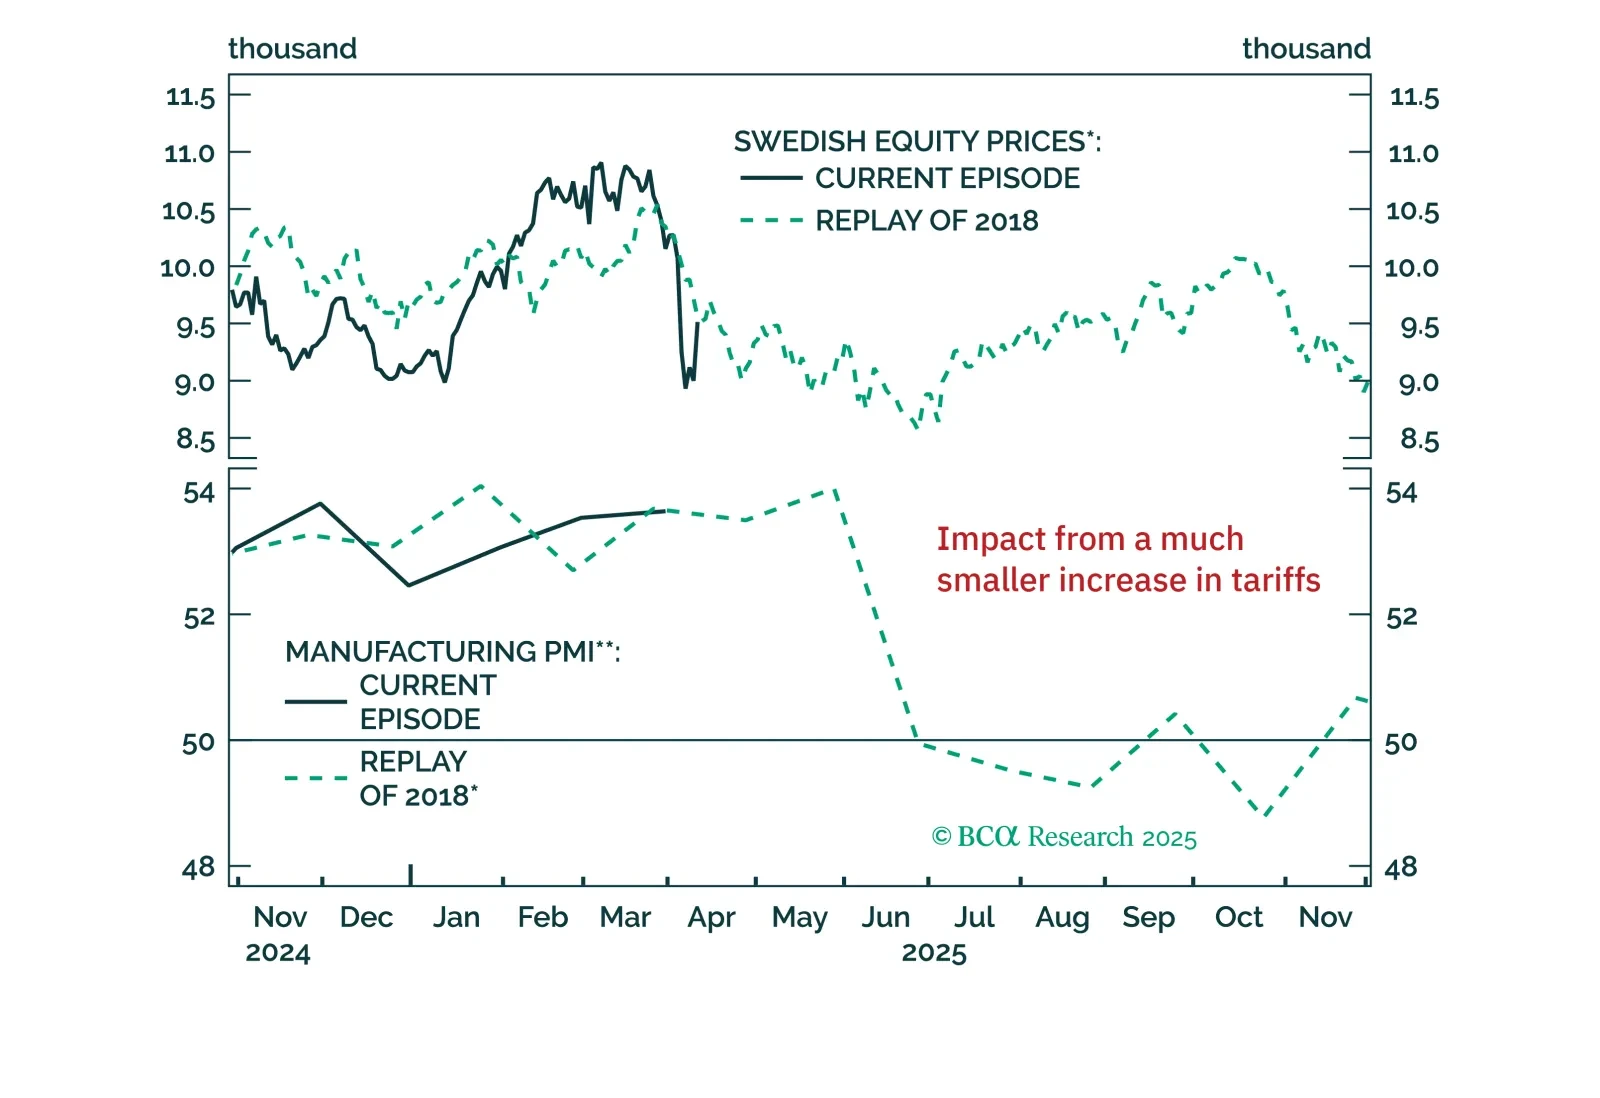
Europe’s near-term outlook remains clouded by uncertainty, even after the tariff reprieve. Our latest update breaks down why the risks to growth, profits, and financial conditions are still skewed to the downside — with Sweden standing out as a key bellwether.
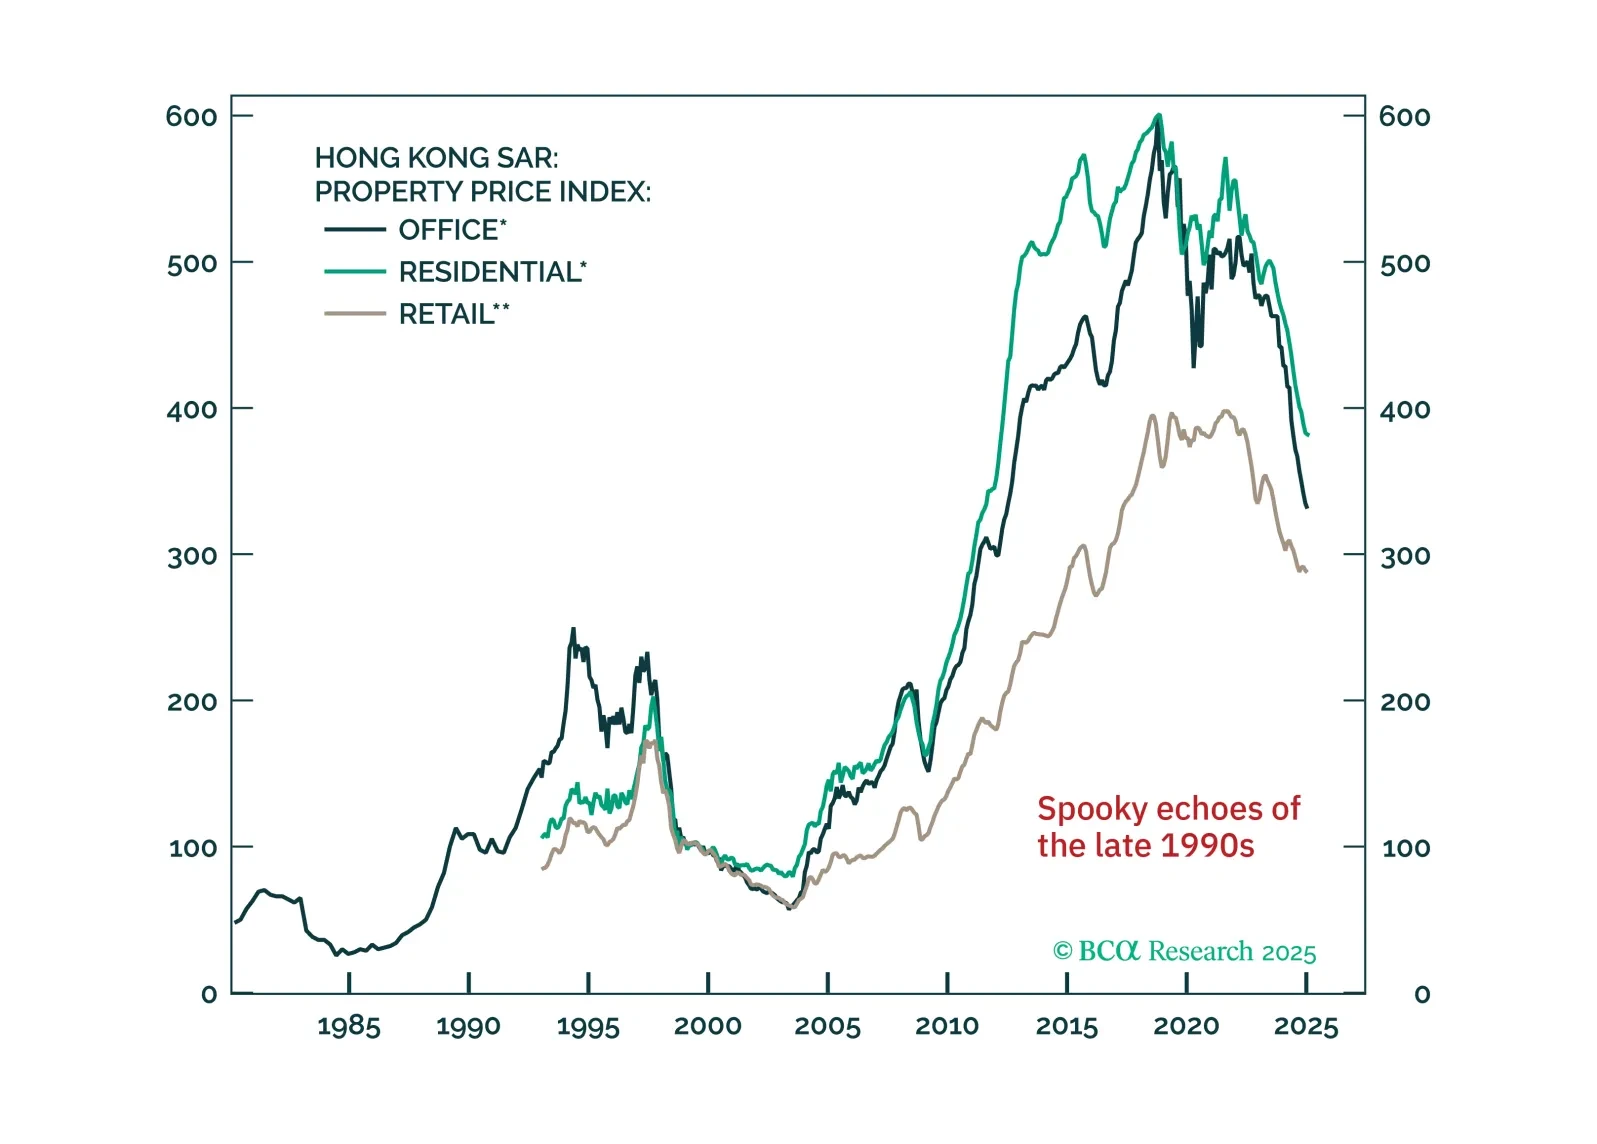
This week, we look at the sustainability of the HKD peg as the next whale to move markets, given what is happening to tariffs. After careful analysis, our bias is that it is here to stay. With the DXY dipping below 100, we are likely to see a rebound, which is actually bad news for the Hong Kong region of China, since it will tighten financial conditions. We have no new short-term trades, but if the peg broke, you want to be short HKD/JPY.

The sharp drop in consumer sentiment and rise in inflation expectations reinforce our defensive positioning and preference for long-duration bonds. The preliminary April University of Michigan Consumer Sentiment Index fell to 50.8 from 57.0 in March, missing…
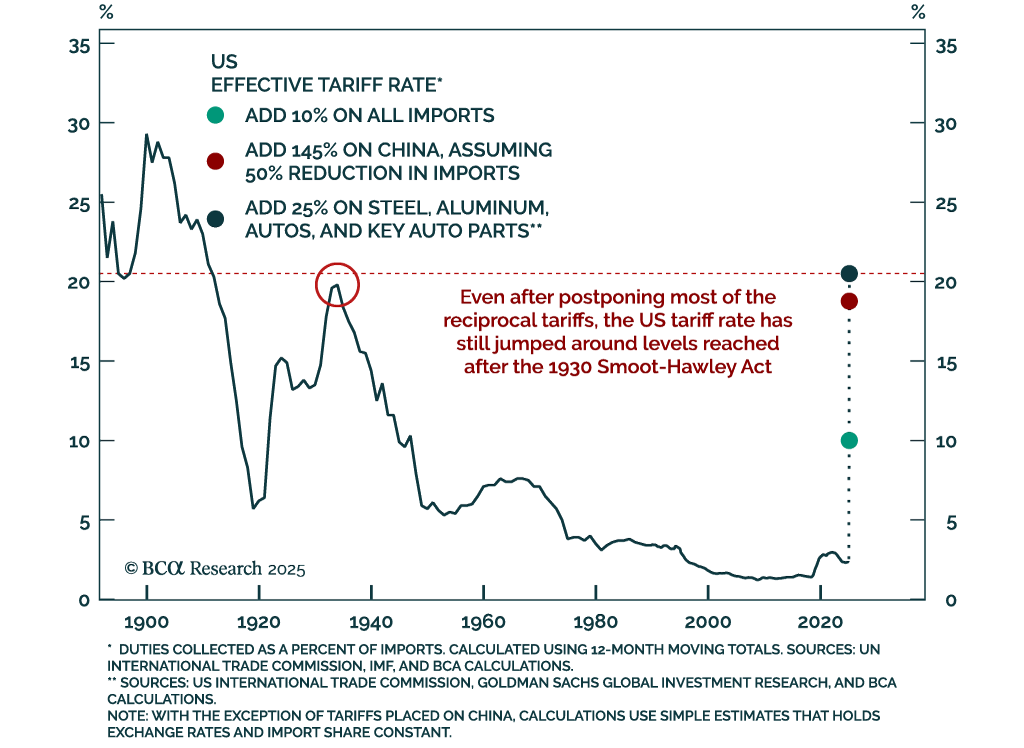
Our Global Investment Strategists remain defensive, expecting a global recession in the coming months unless the trade war de-escalates meaningfully. They maintain a year-end S&P 500 target of 4450, with downside risk to 4200.While reciprocal tariffs were…