Latest from BCA Research
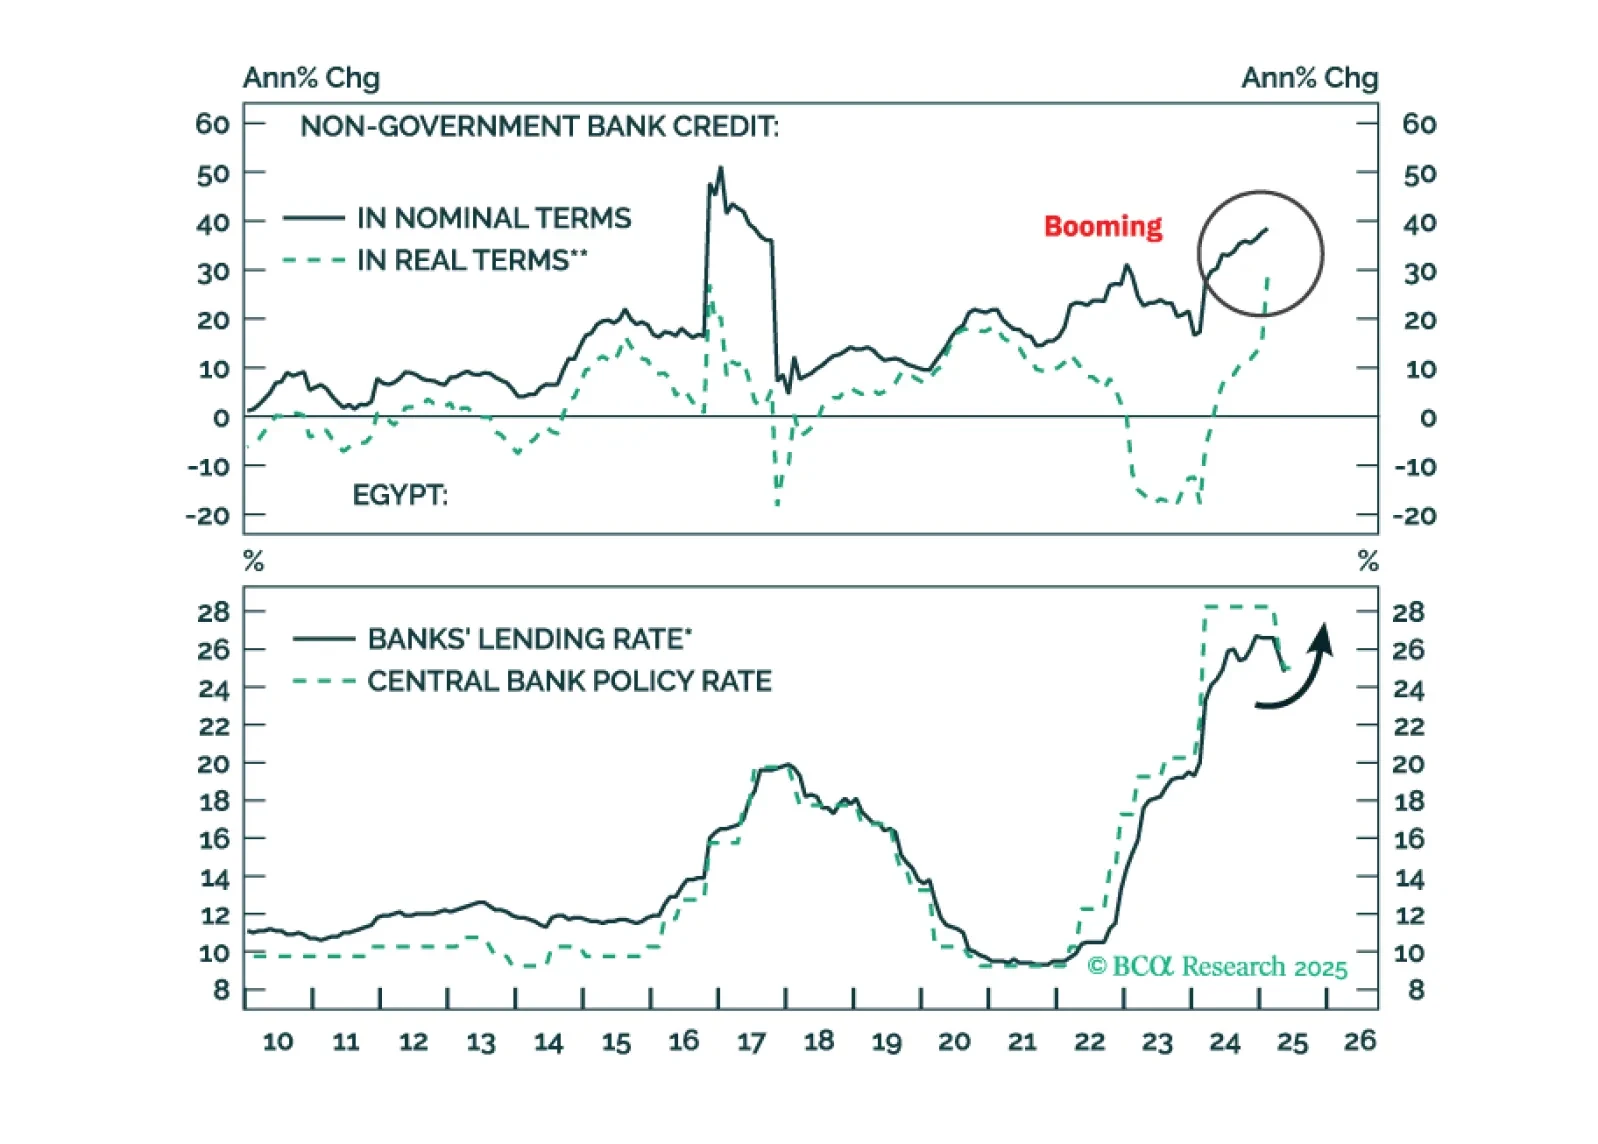
Downward pressure on the pound will rise in the coming months. Inflation will go up, so will bond yields. It’s time to book profits on Egyptian domestic bonds.
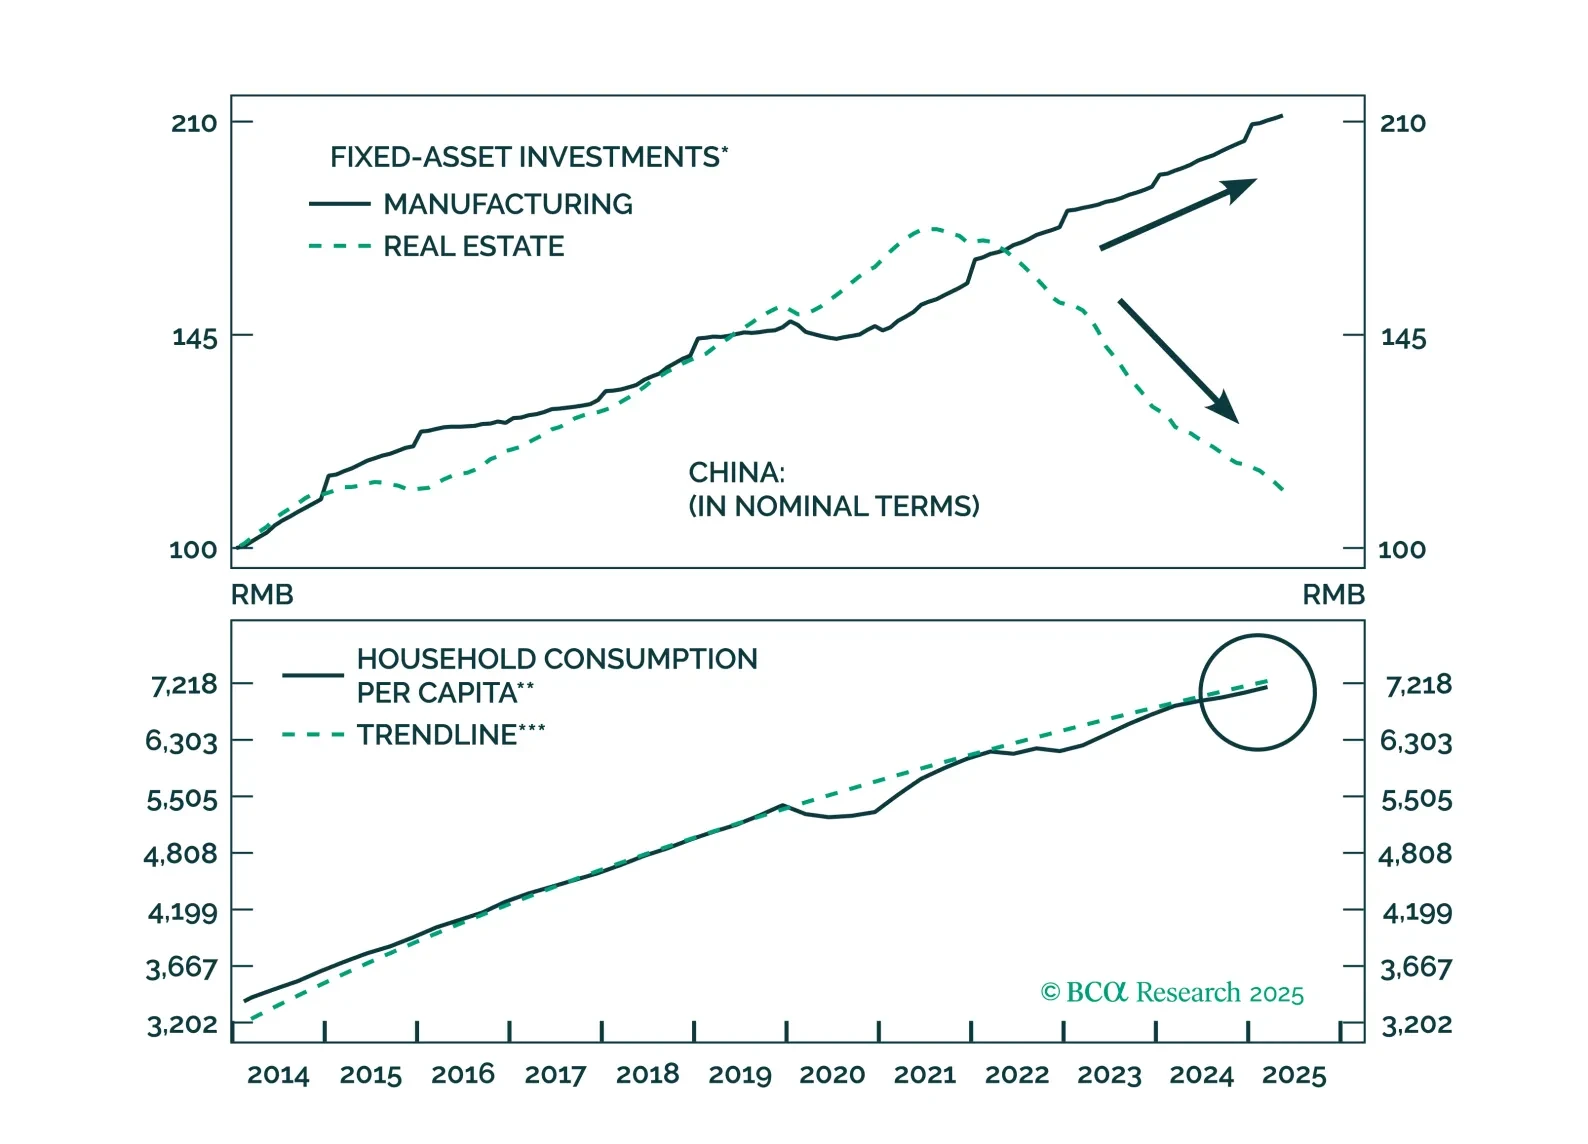
This report analyzes China’s persistent deflation, which is rooted in supply-side forces. Consumption support will be slow and incremental, keeping deflationary pressures elevated for the next 6–12 months.
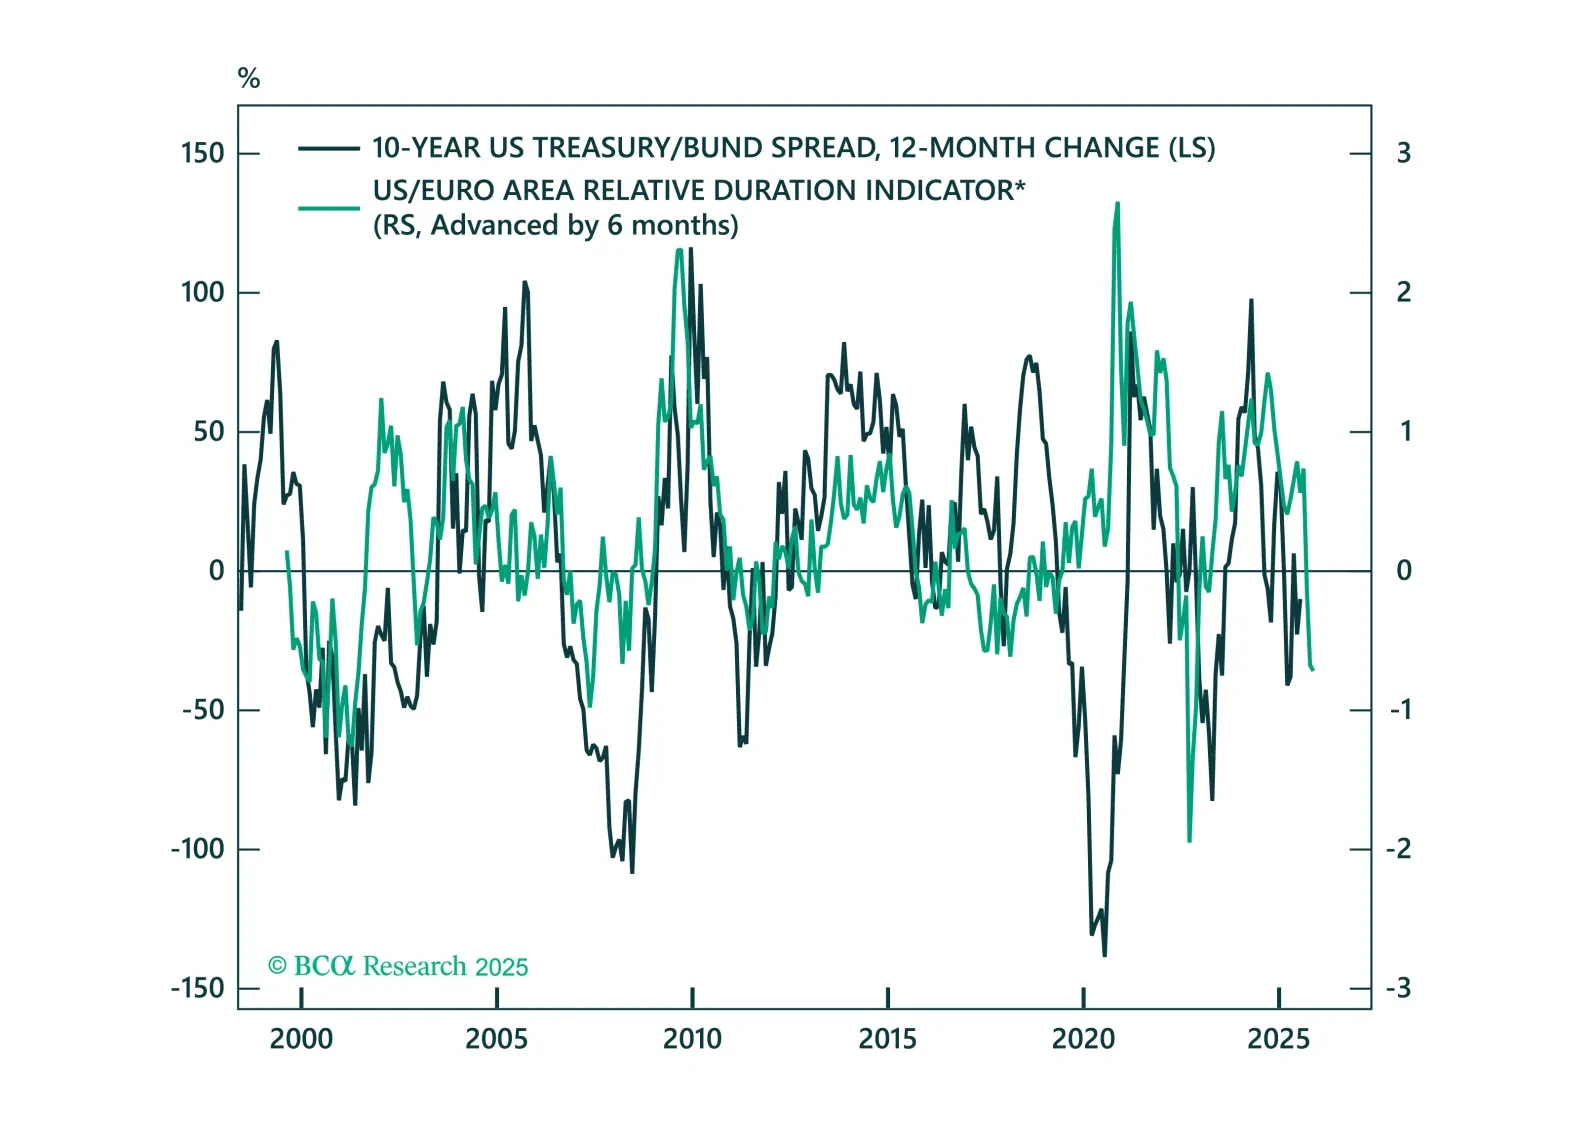
Volatility is back in UST/Bund spreads. We unpack what’s driving the moves and explain what we are watching for tactical opportunities in the UST/Bund spread.
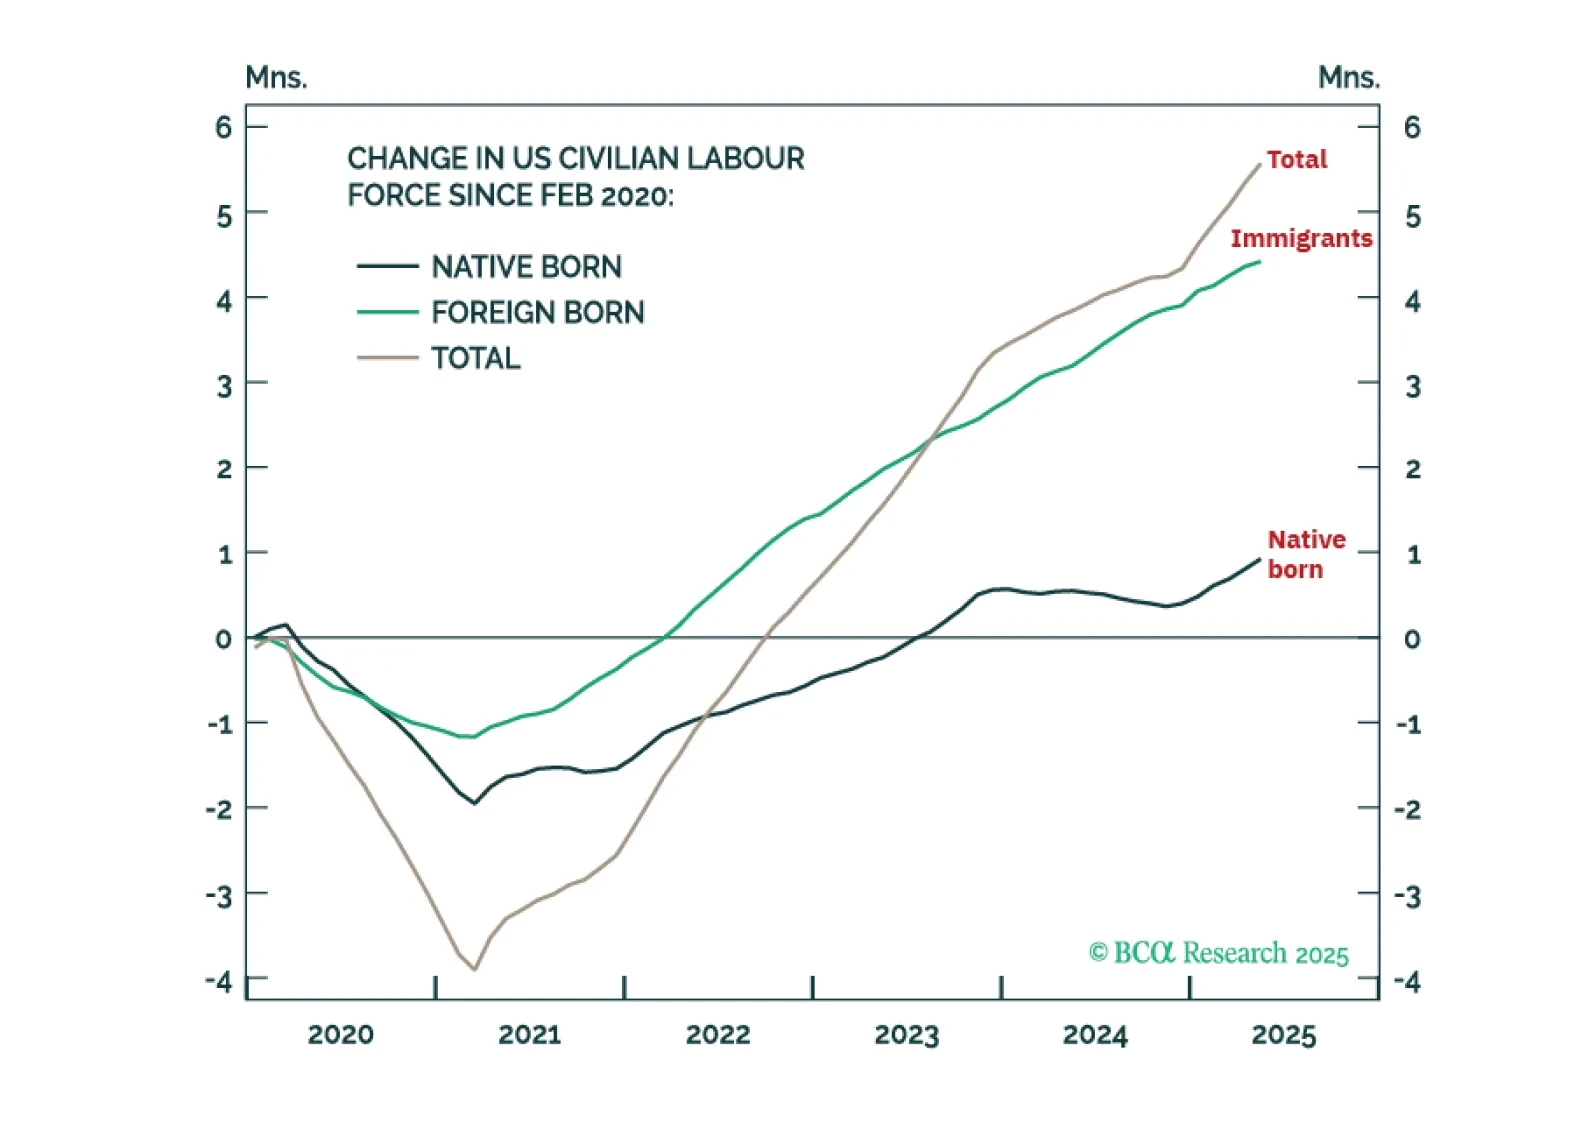
Trump’s immigration policies are protecting the US economy from a sharp rise in unemployment but steering it into a ‘mini stagflation’. Plus: a new tactical trade is to underweight global technology (IXN).
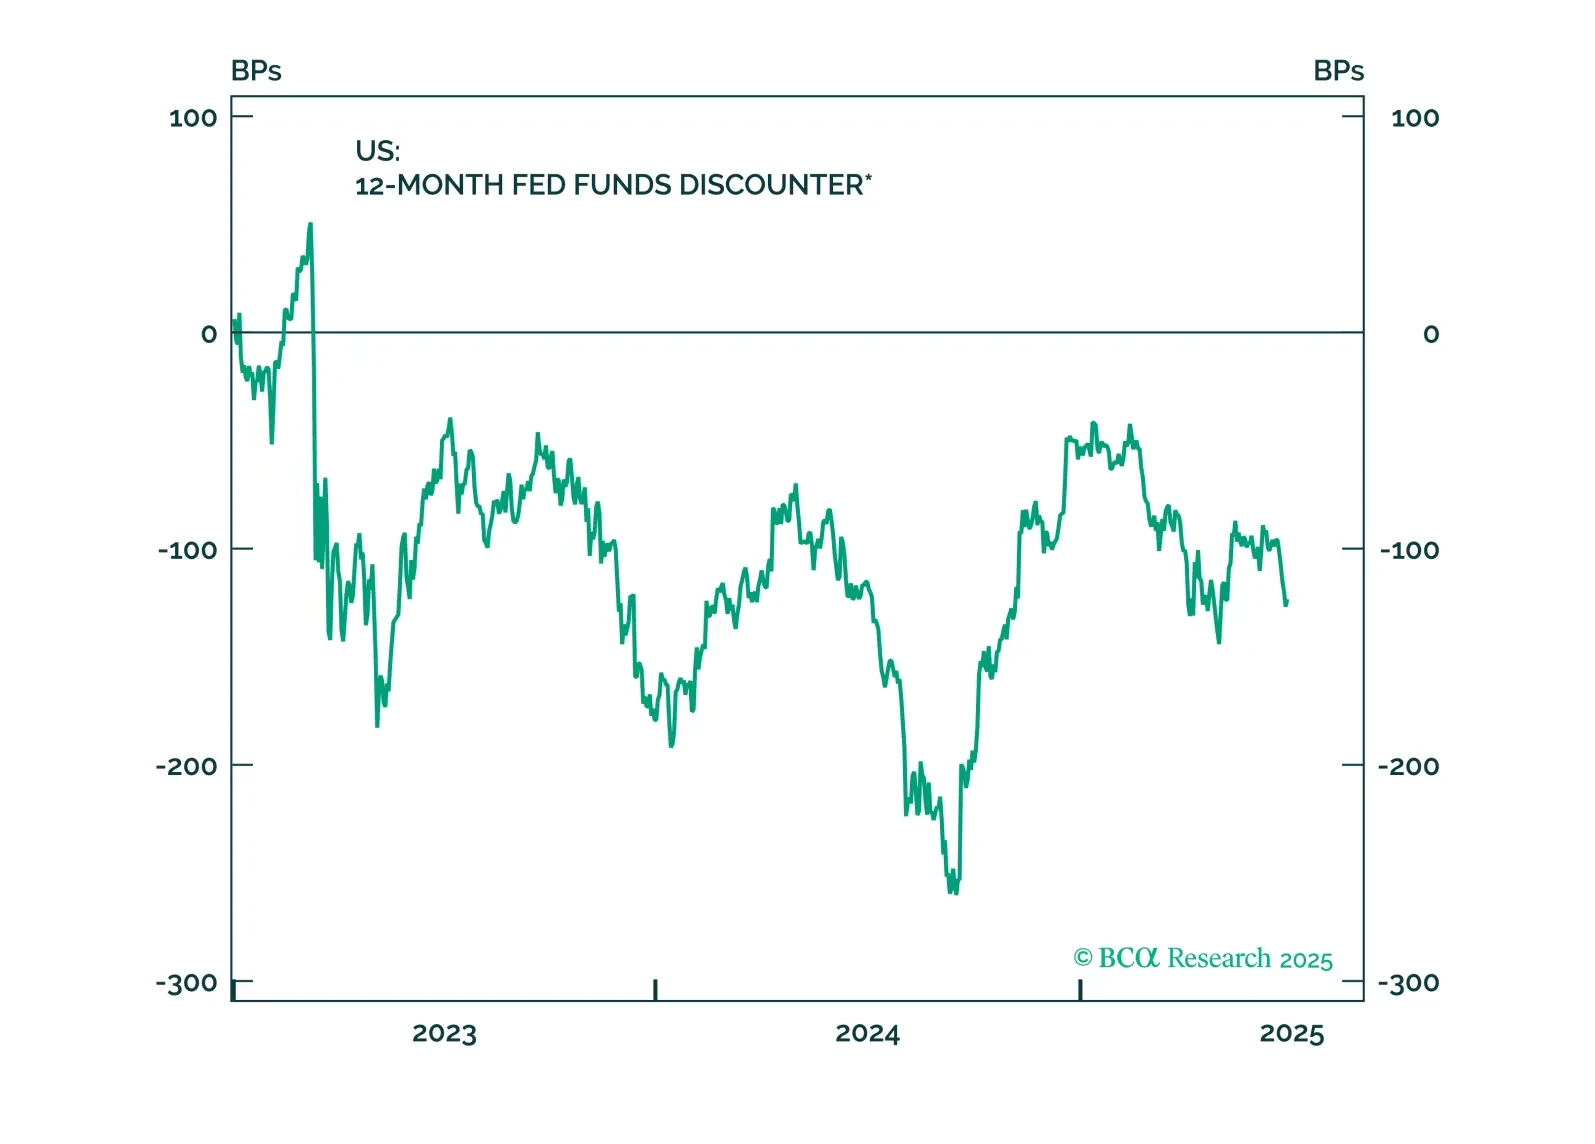
Monetary policy is about to become a powerful tailwind to the already bullish brew that includes Trump’s repeated step-downs from a global trade war, irrelevant geopolitical risks in the Middle East, and a fiscal policy that is no longer as alarming to the bond markets as the raft of campaign promises appears to be. Investors should hesitate to get overly bearish either bonds or stocks. However, we remain uber USD bears.
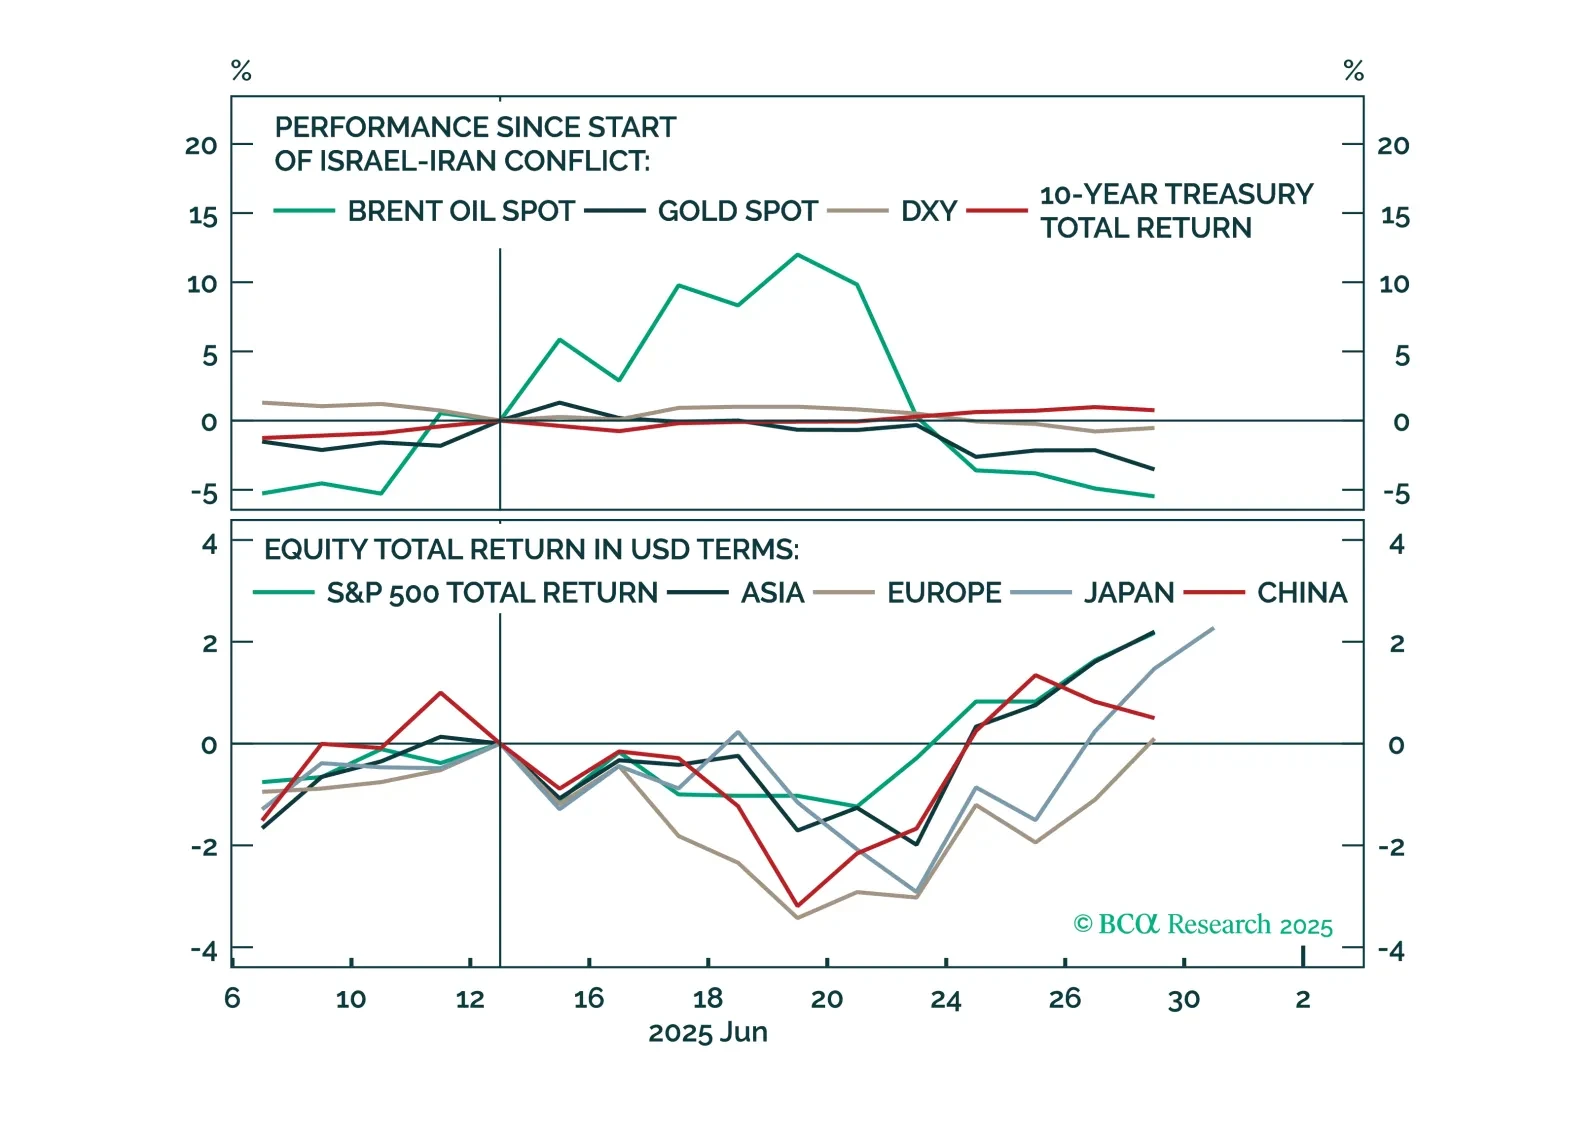
There is a thin line between geopolitical risk and Enlightenment, just ask Europe in the seventeenth century. The Middle East is exhibiting both. Investors are over-indexing on the negative – which has not impacted the investible universe – and ignoring the positives.
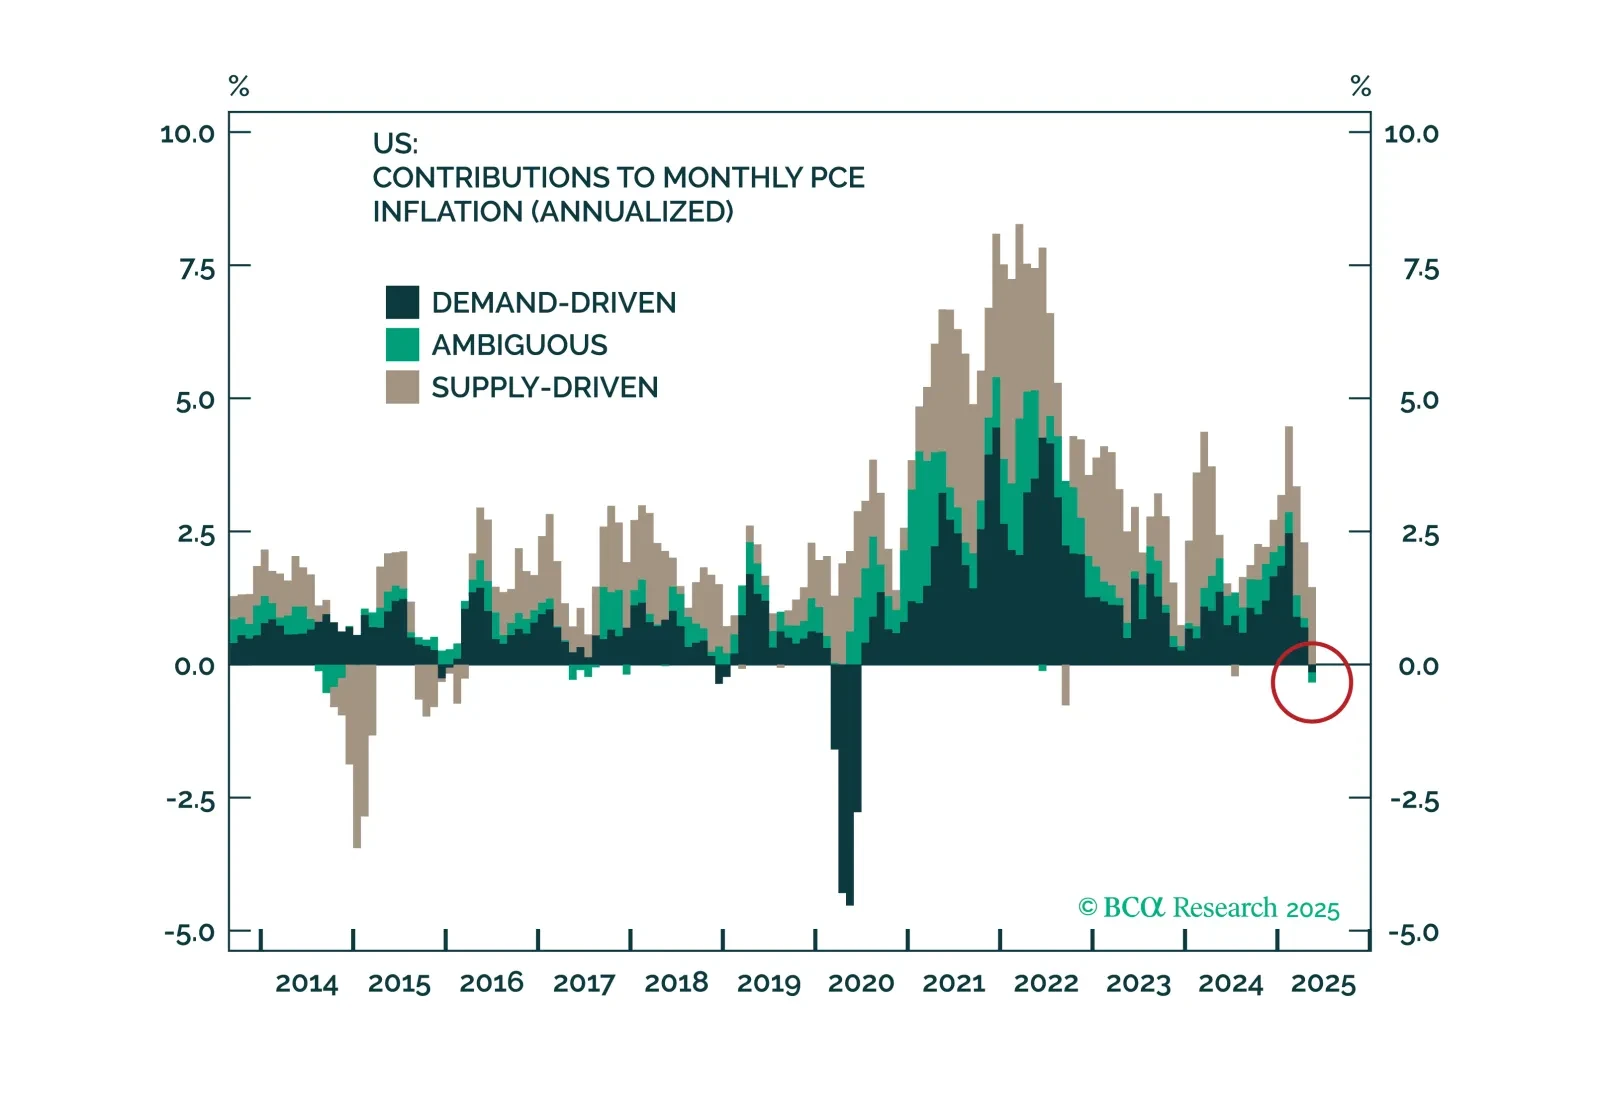
The US economy is not in recession, but is suffering from a post-pandemic stimulus hangover. The cure: lower interest rates. We expect the Fed to start lowering rates, which will benefit both equities and bonds. We upgrade stocks to neutral and downgrade cash to underweight. We also upgrade duration to overweight. The US dollar will continue to weaken, so favour Europe and China within equities.
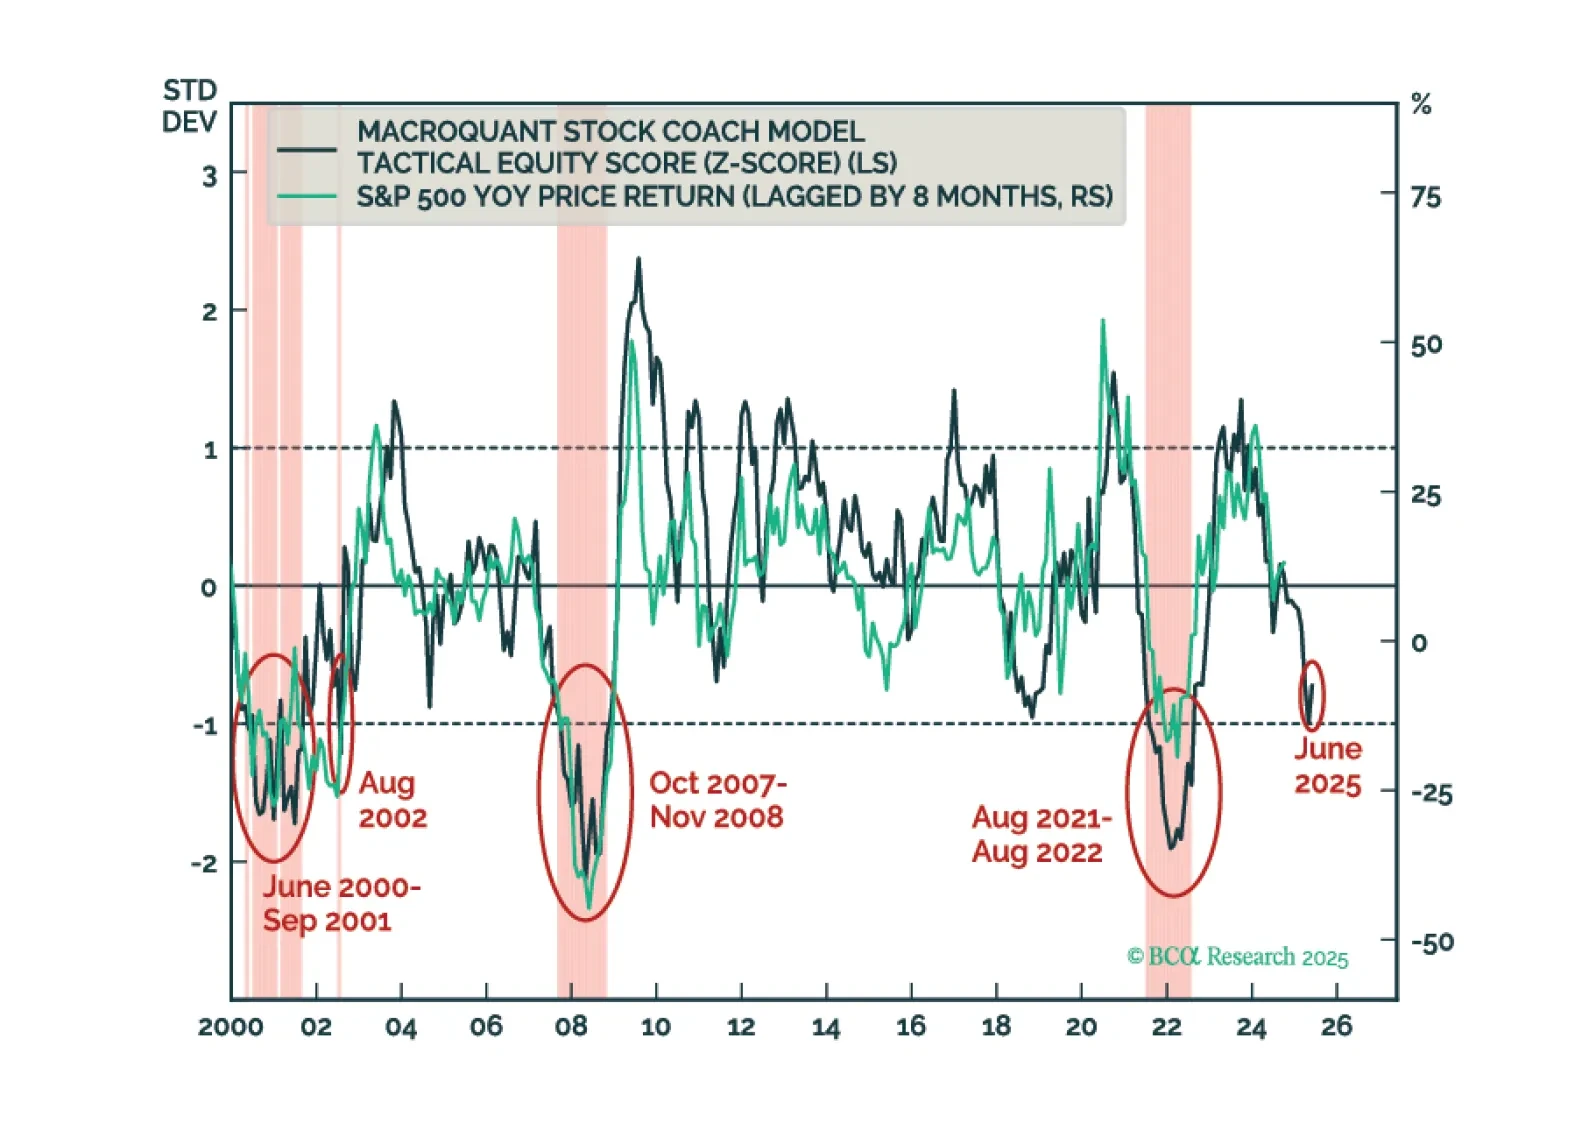
MacroQuant’s US equity z-score is dangerously close to the -1 threshold. Moves below that threshold have reliably coincided with equity bear markets in the past. As such, MacroQuant recommends an underweight on stocks, offset by an overweight on bonds and cash.
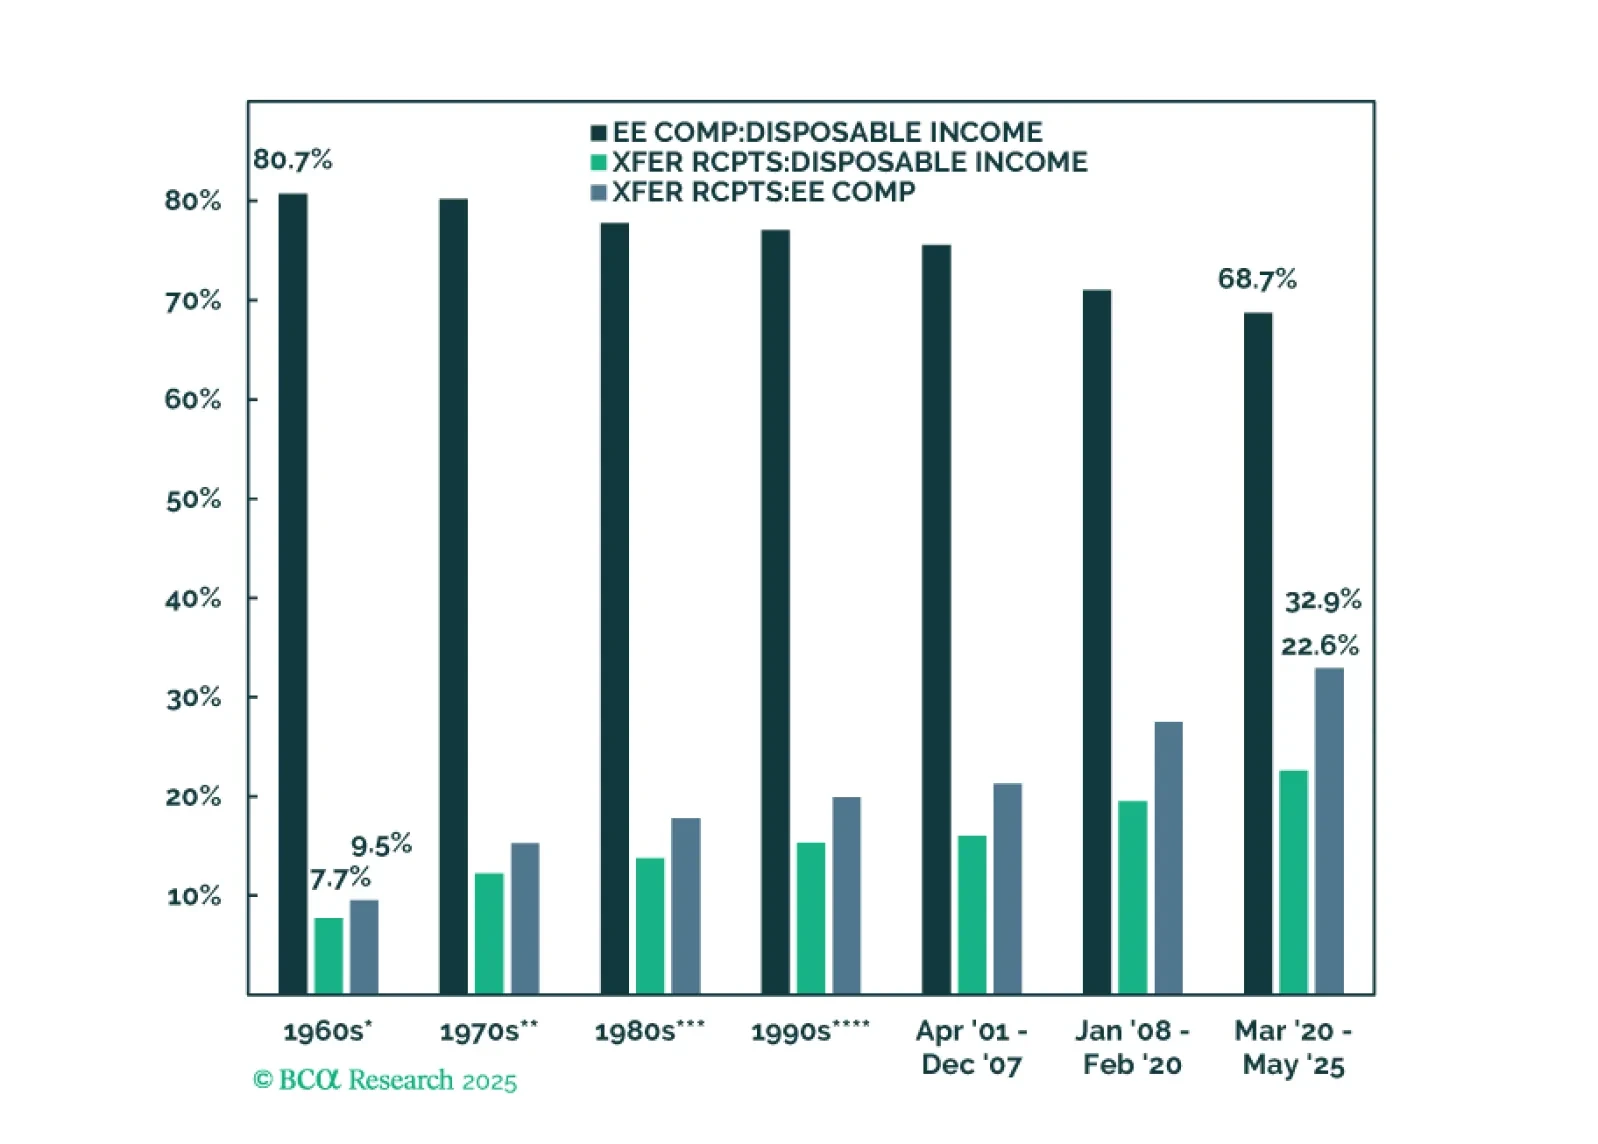
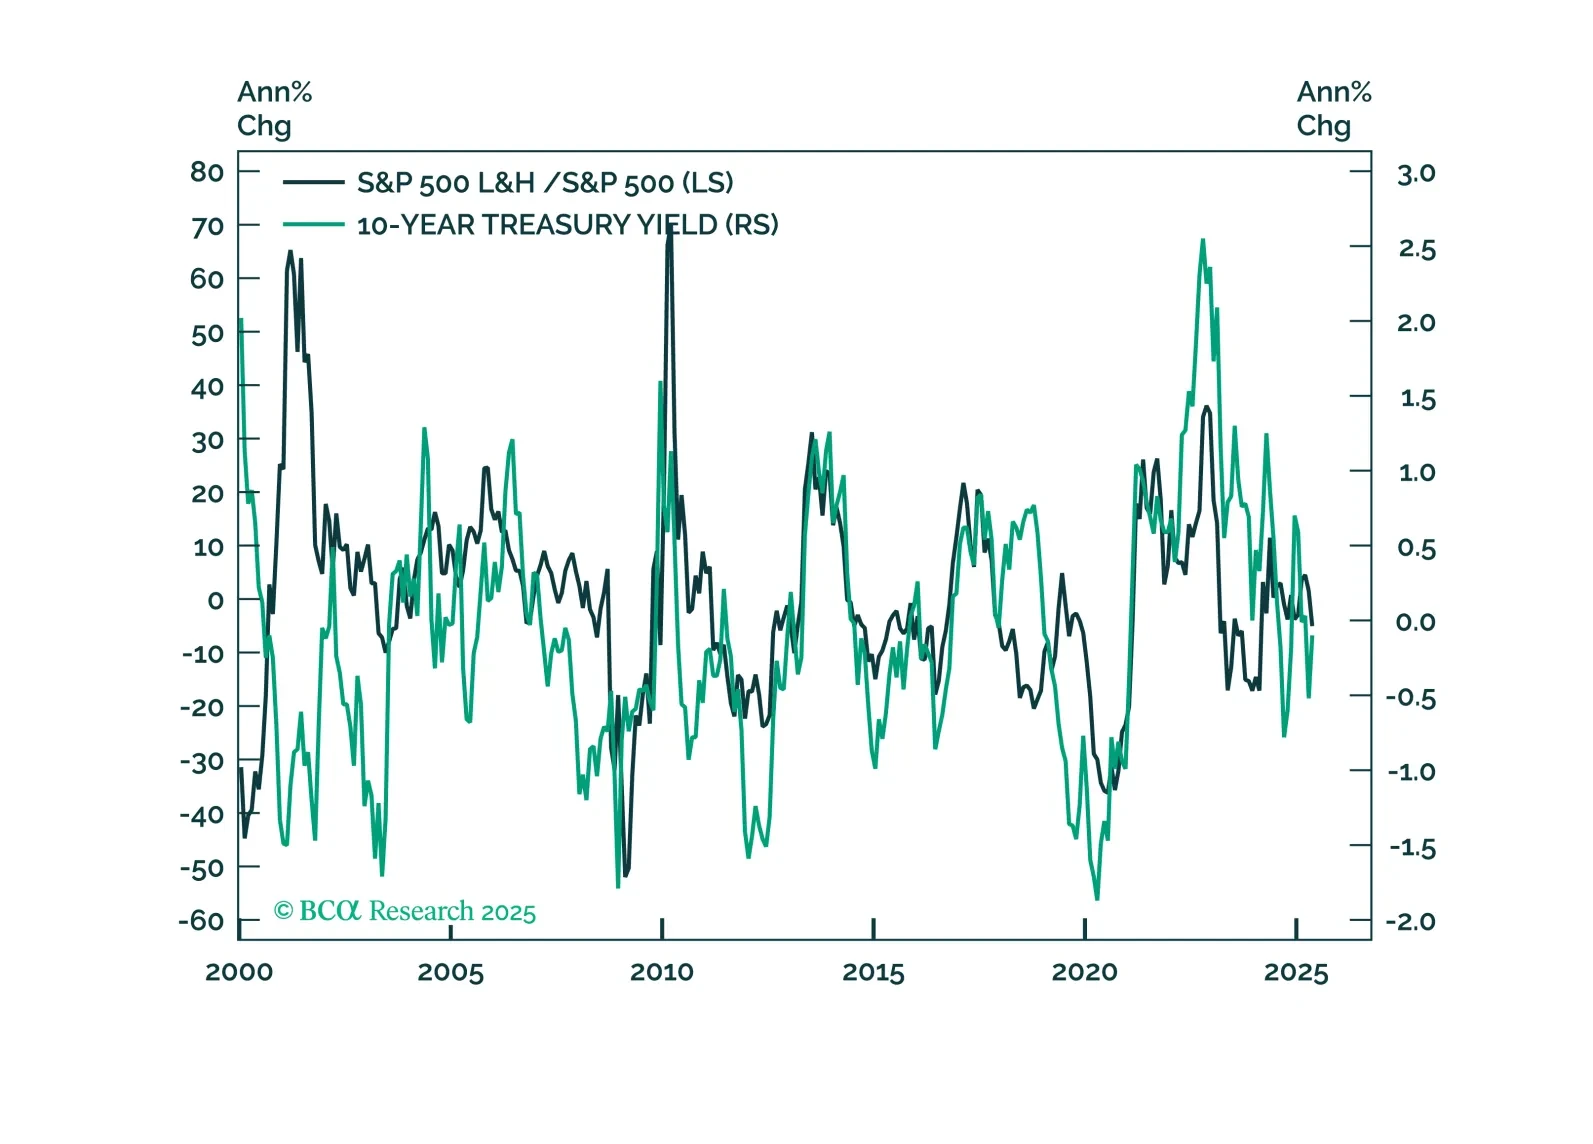
The Life and Health Insurance industry offers downside protection and portfolio diversification in the event of a market correction, surging inflation, or stubbornly high interest rates.