Latest from BCA Research
President Trump keeps walking back his tariffs, aligning with our Seven Steps of Maximum Pressure. Investors should expect a lot of back and forth over the next few weeks, including the dreaded Step 5 (“Leave the Bride at the Altar”). Already, Commerce Secretary Howard Lutnick has suggested that the tariff exemptions for electronics – which surged global risk assets today – would not last long. We hesitate to just declare the “all clear” and go outright long but are shifting our posture on global risk assets to neutral.
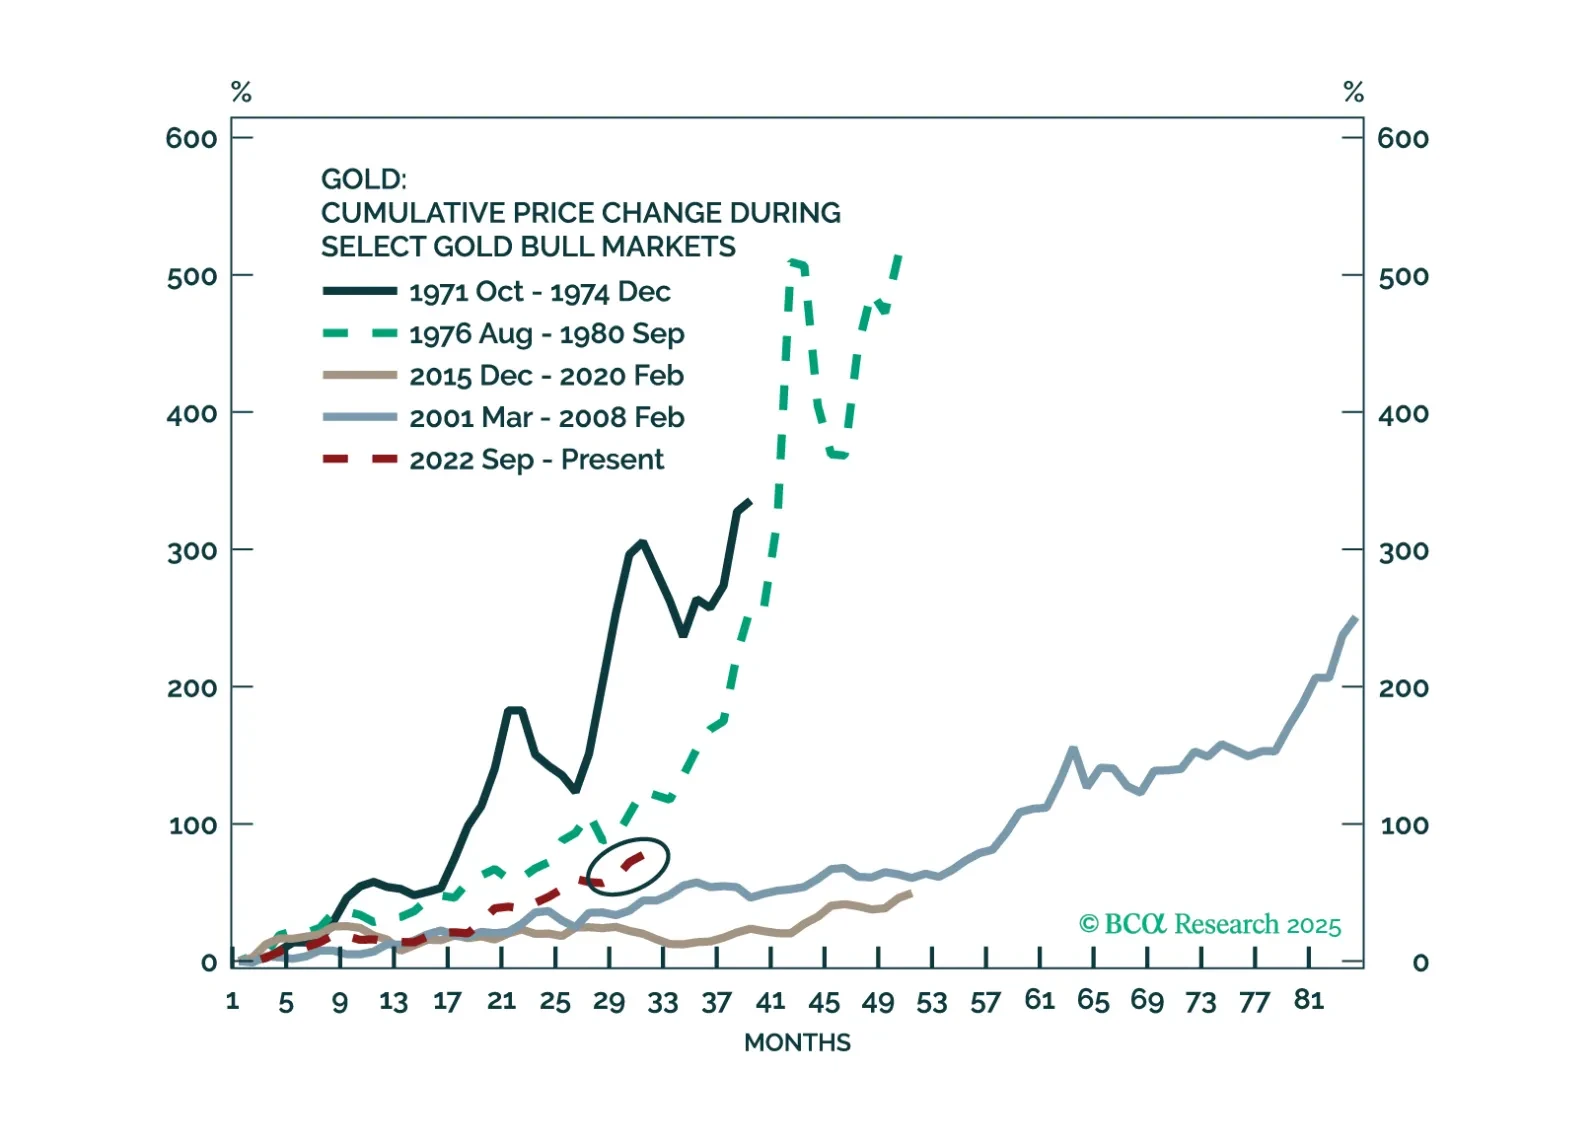
Commodities have not been spared the wrath of the post-"Liberation Day" selloff. However, in the sea of red, gold continues to shine bright, climbing to a fresh record high. How much further does the recent price action have left to run? We explore technical indicators to gauge the likely price outlook for gold, oil, and copper over the coming months.
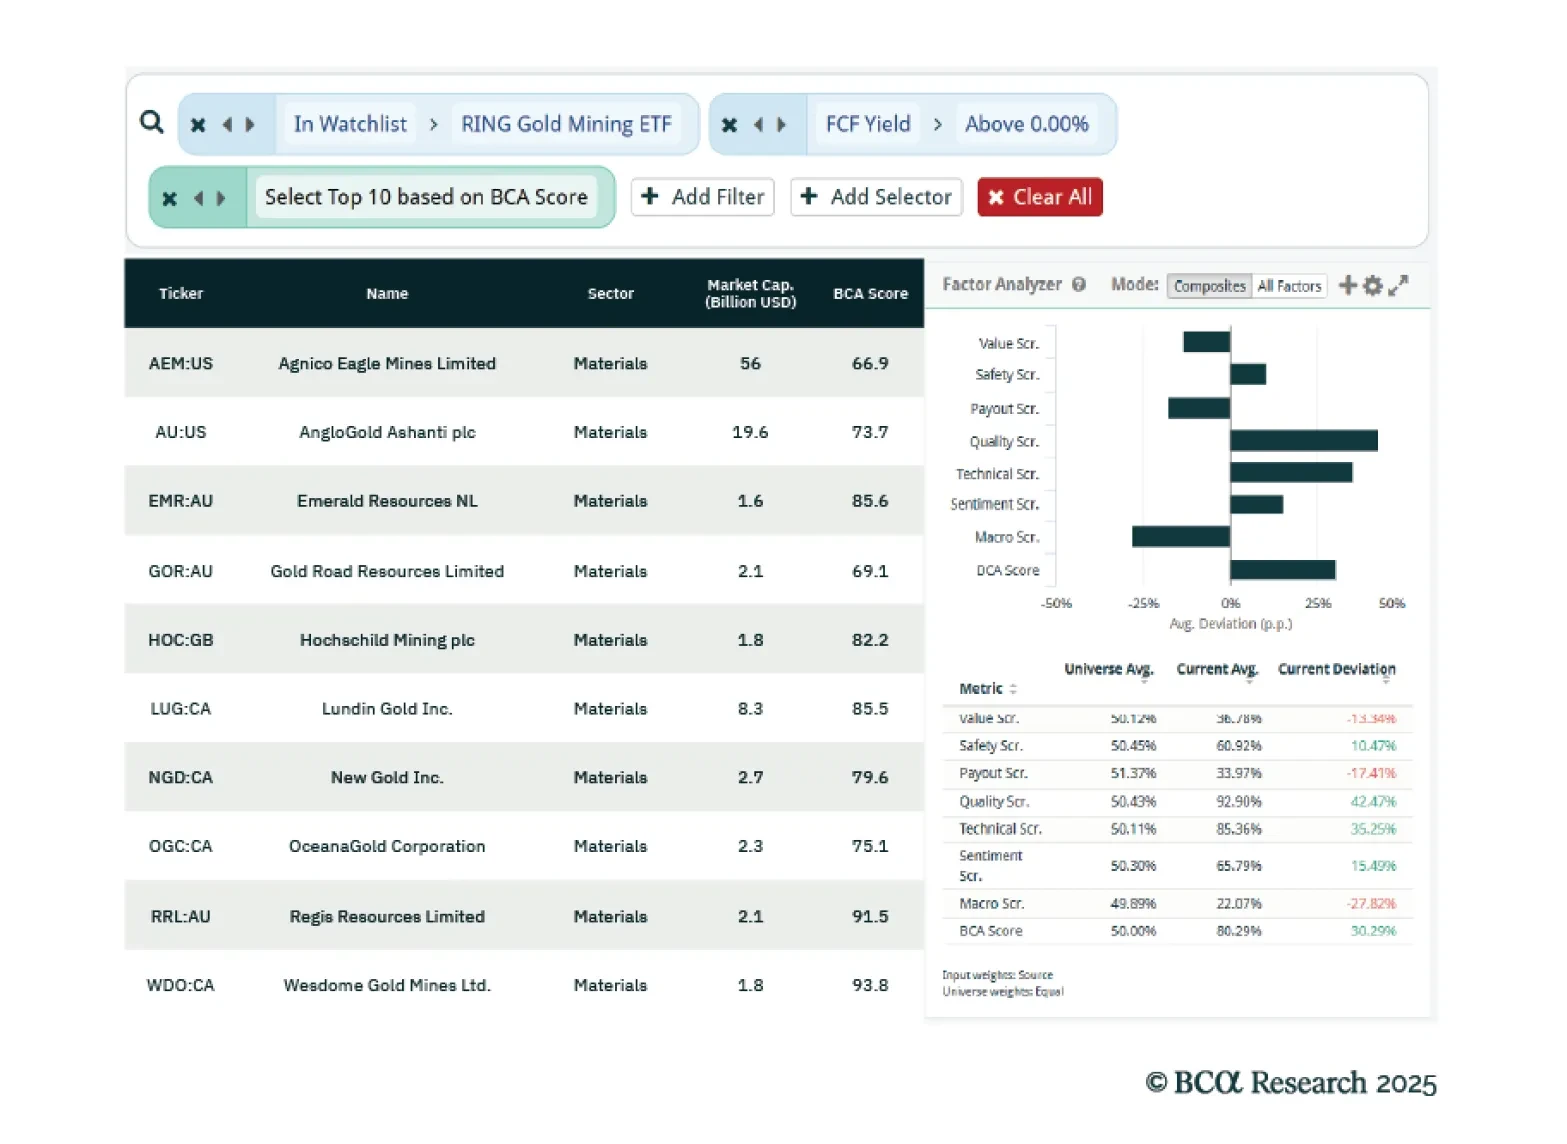
This week, our three screeners cover equity plays in: Gold mining stocks, Japanese Staples, and Implicit Dividend Yield.
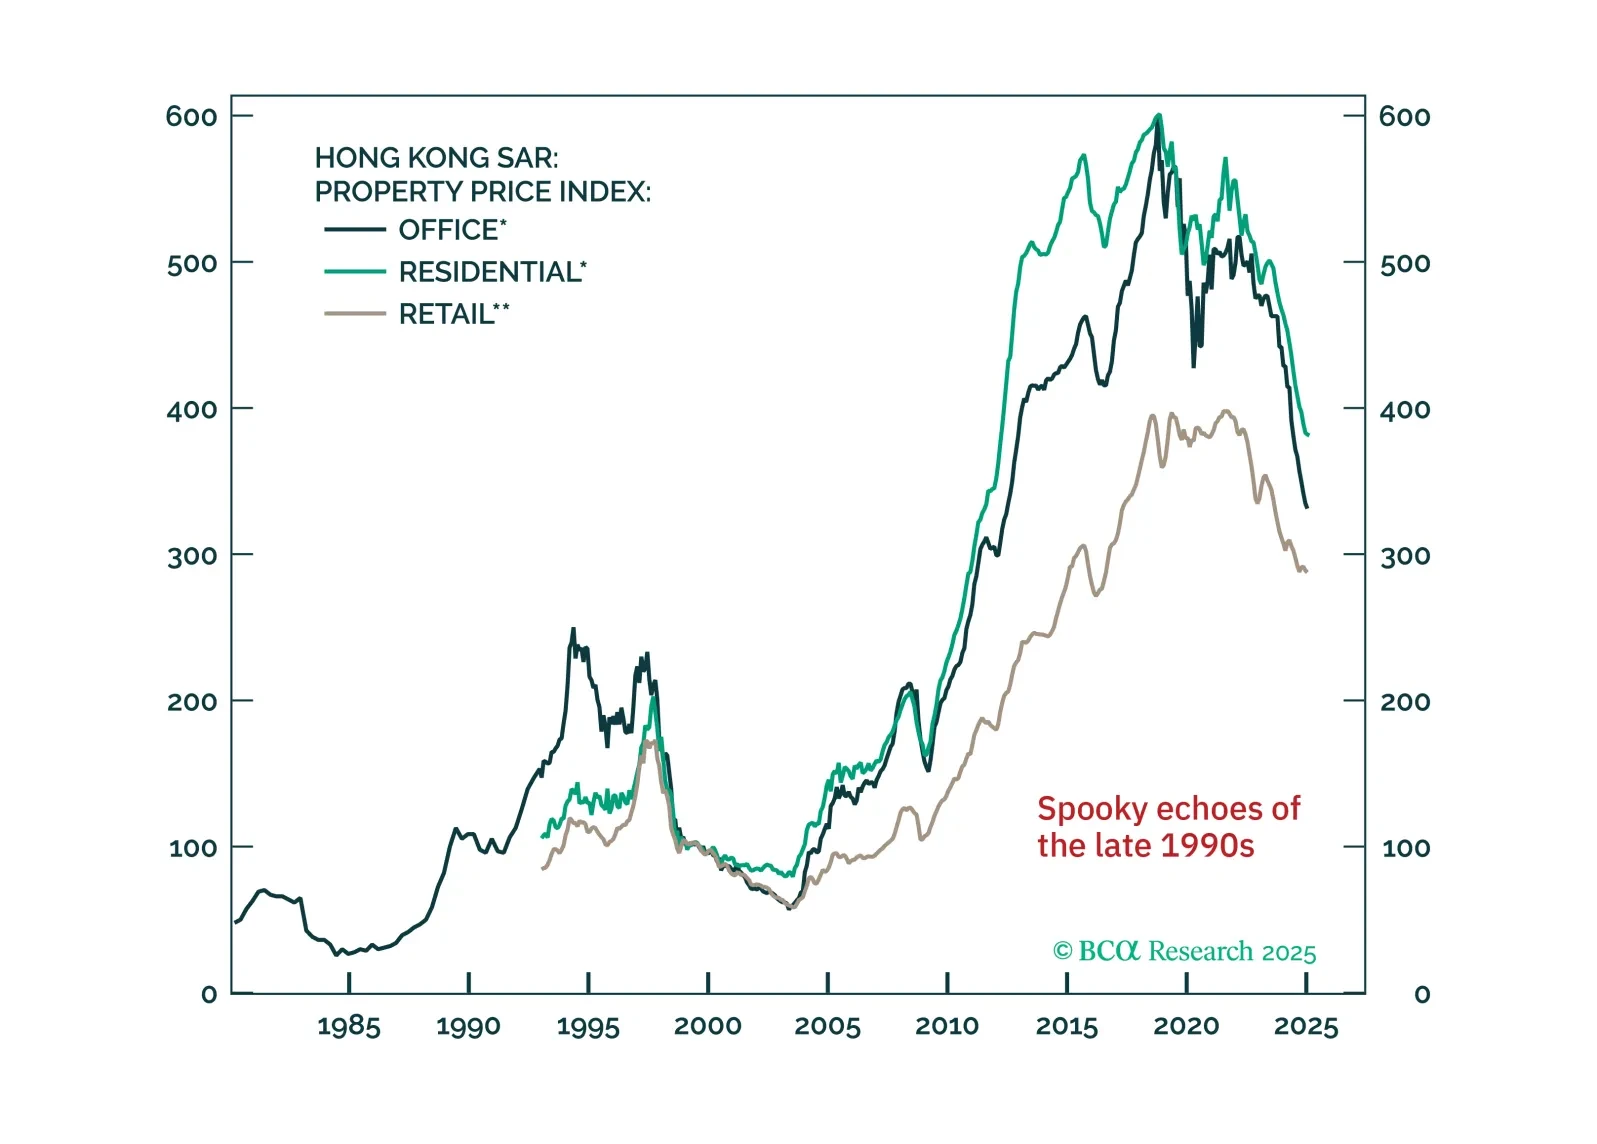
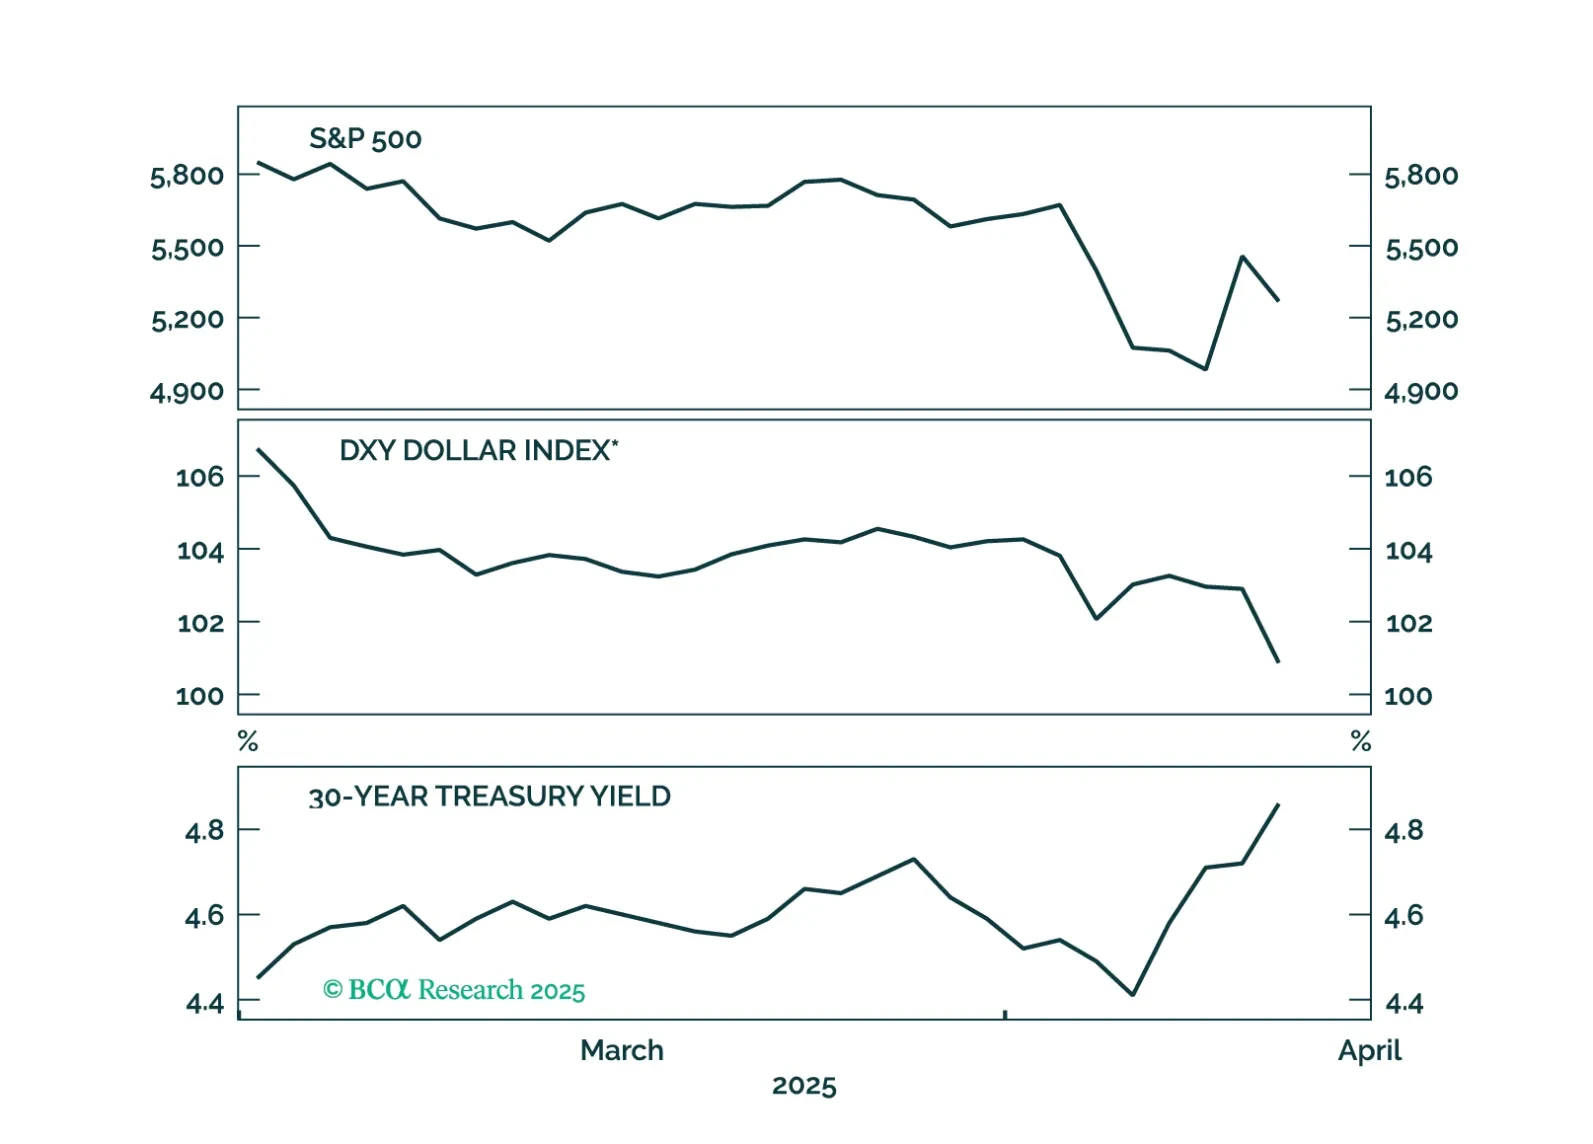
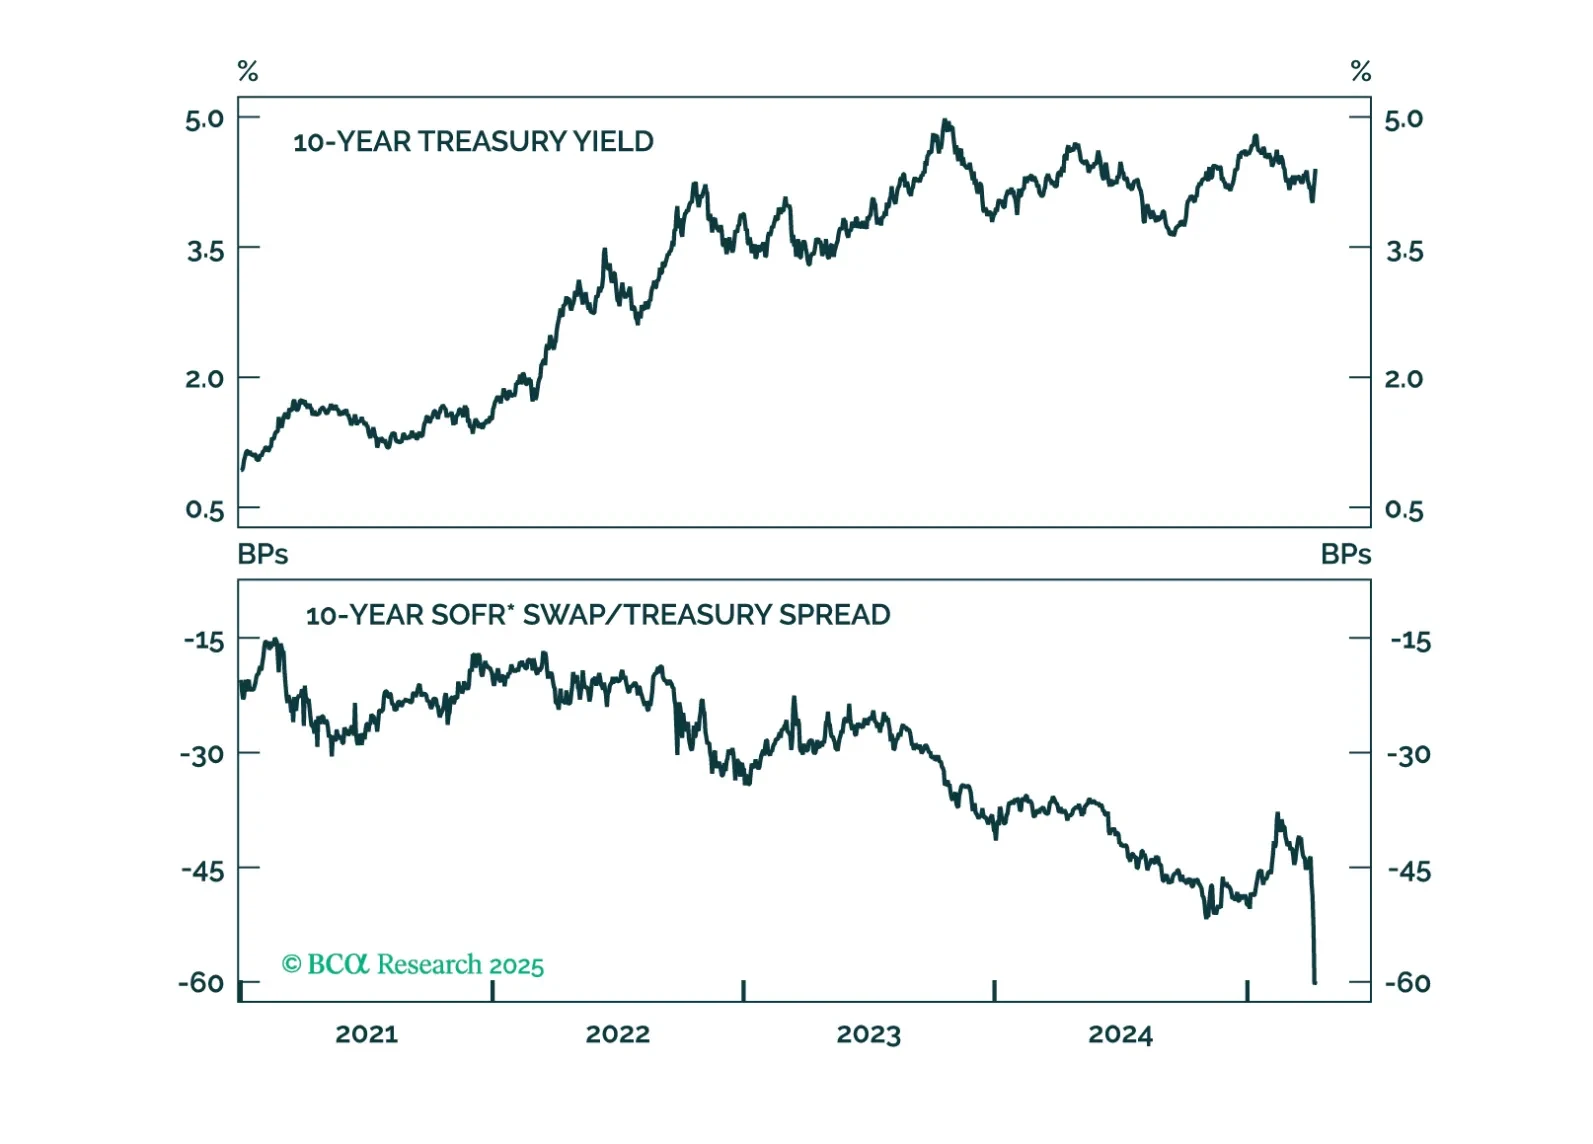
The combination of dollar weakness and rising US yields suggests global investors are questioning the safe-haven status of US Treasuries.
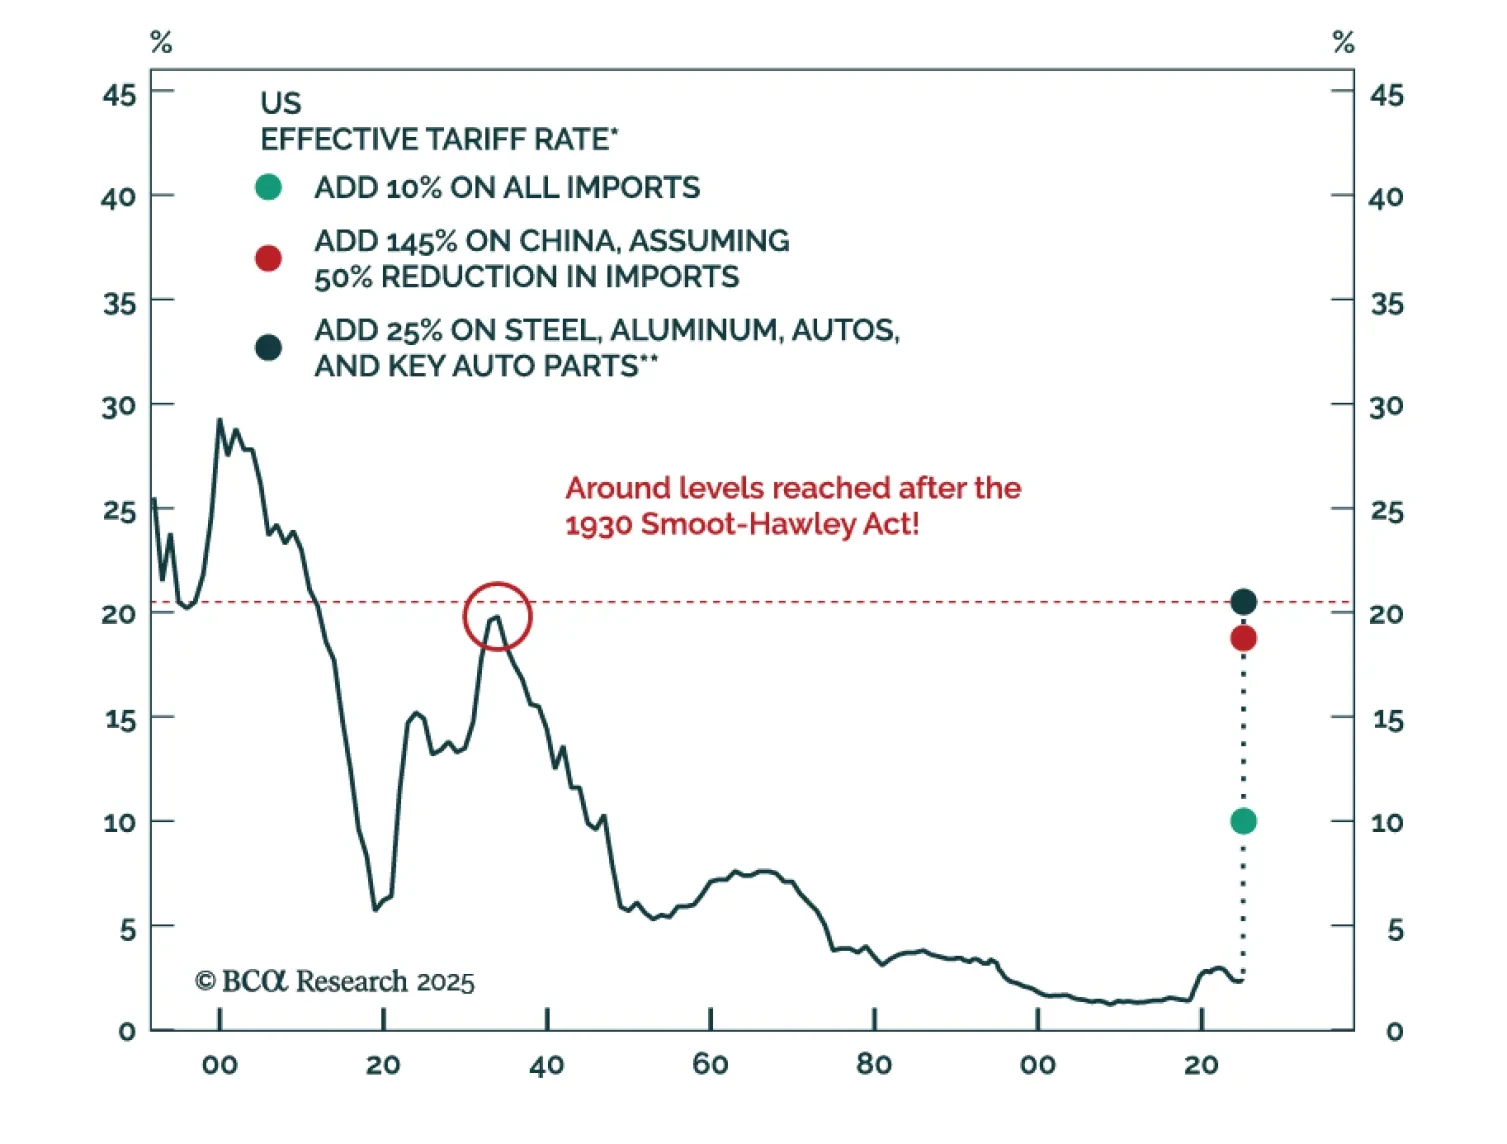
Barring a dramatic further de-escalation of the trade war, the US and much of the rest of the world will enter a recession over the next few months. Investors should remain defensively positioned for now.
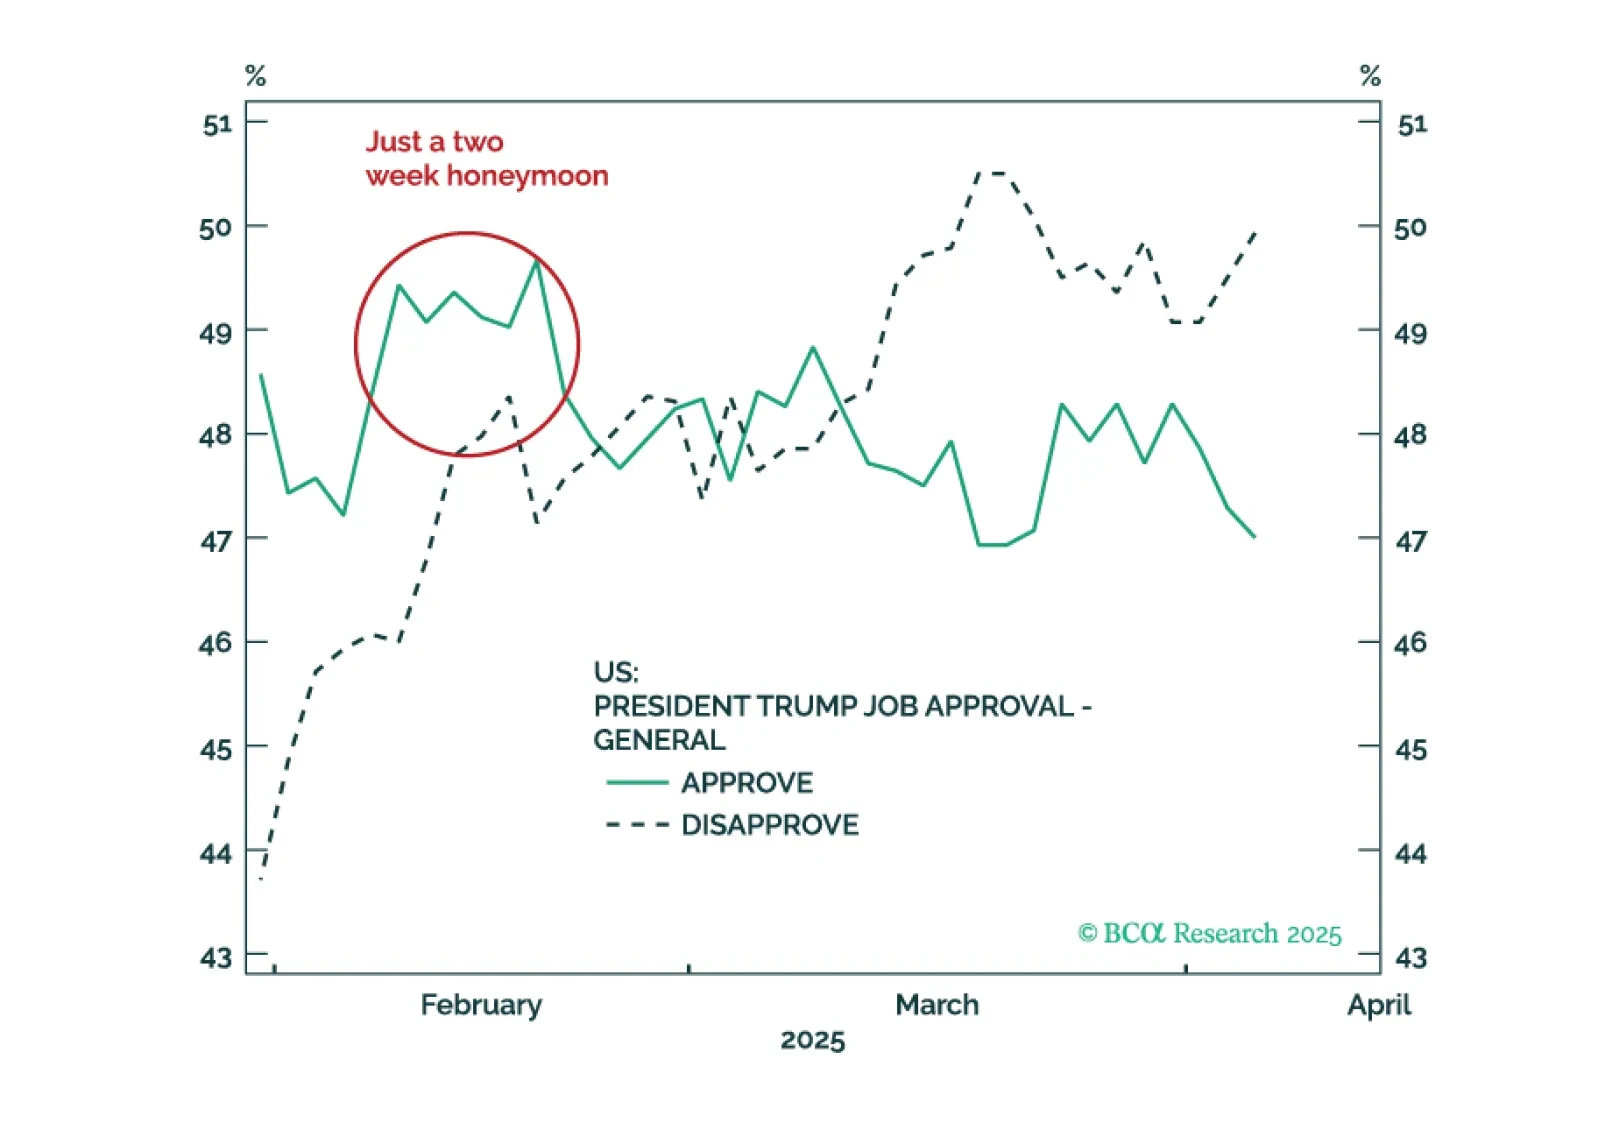
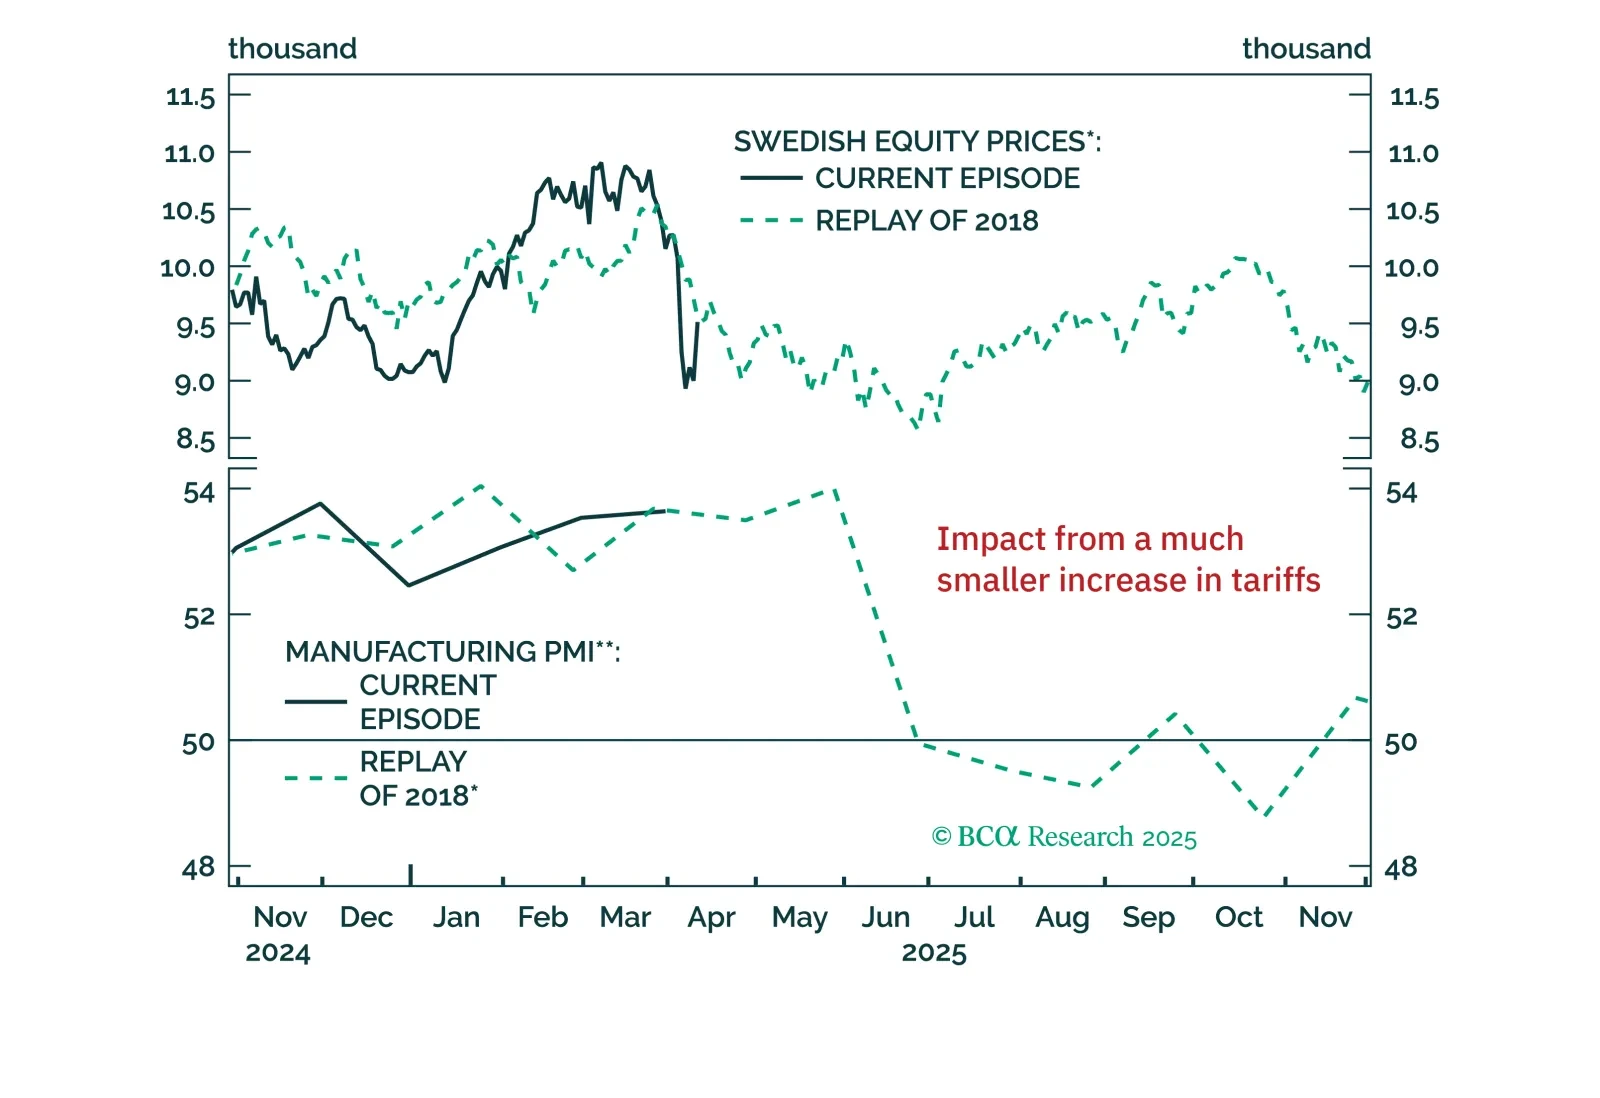
While the market welcomed the pause in Liberation Day tariffs, we believe investors are overly optimistic about the relief from this Trump-driven uncertainty. Even with the pause, current tariff levels remain higher than they were in January. Elevated tariff levels are likely to be inflationary, which could explain the recent spikes in US Treasury yields. Currently, Congress does not have a veto-proof majority to rein in President Trump’s tariff policies, meaning the trade war with China will persist.

We believe Beijing views these US trade actions as nothing short of a declaration of economic war, not just a trade dispute. The US-China confrontation is set to escalate from here. Chinese authorities will allow the yuan to depreciate materially. Go short CNH against the US dollar. For EM and Asian equity portfolios, we are downgrading Chinese investable/offshore stocks from neutral to underweight.