Latest from BCA Research
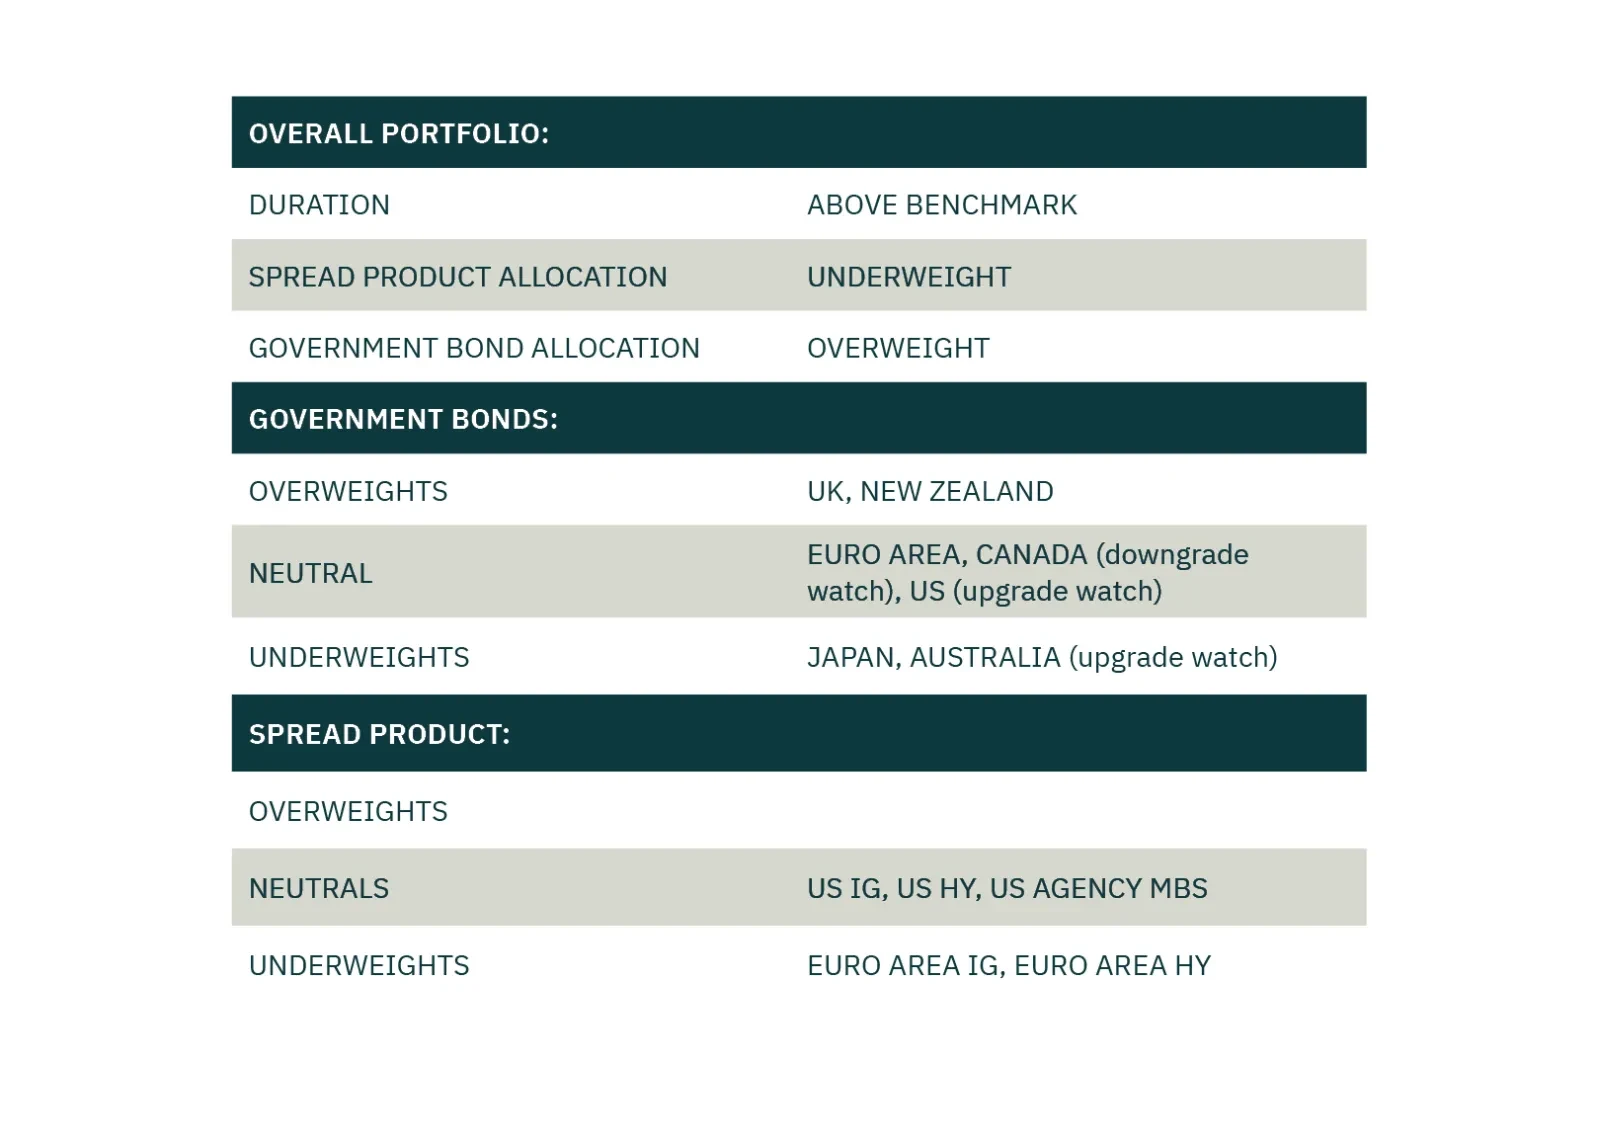
Today, we publish our Quarterly Model Bond Portfolio report. We discuss how the trade war has further increased the global recession risk, but US Treasuries could underperform their global peers in the near term. We cover the fixed income investment implications in the short run and which bond markets are poised to outperform in a severe economic downturn.
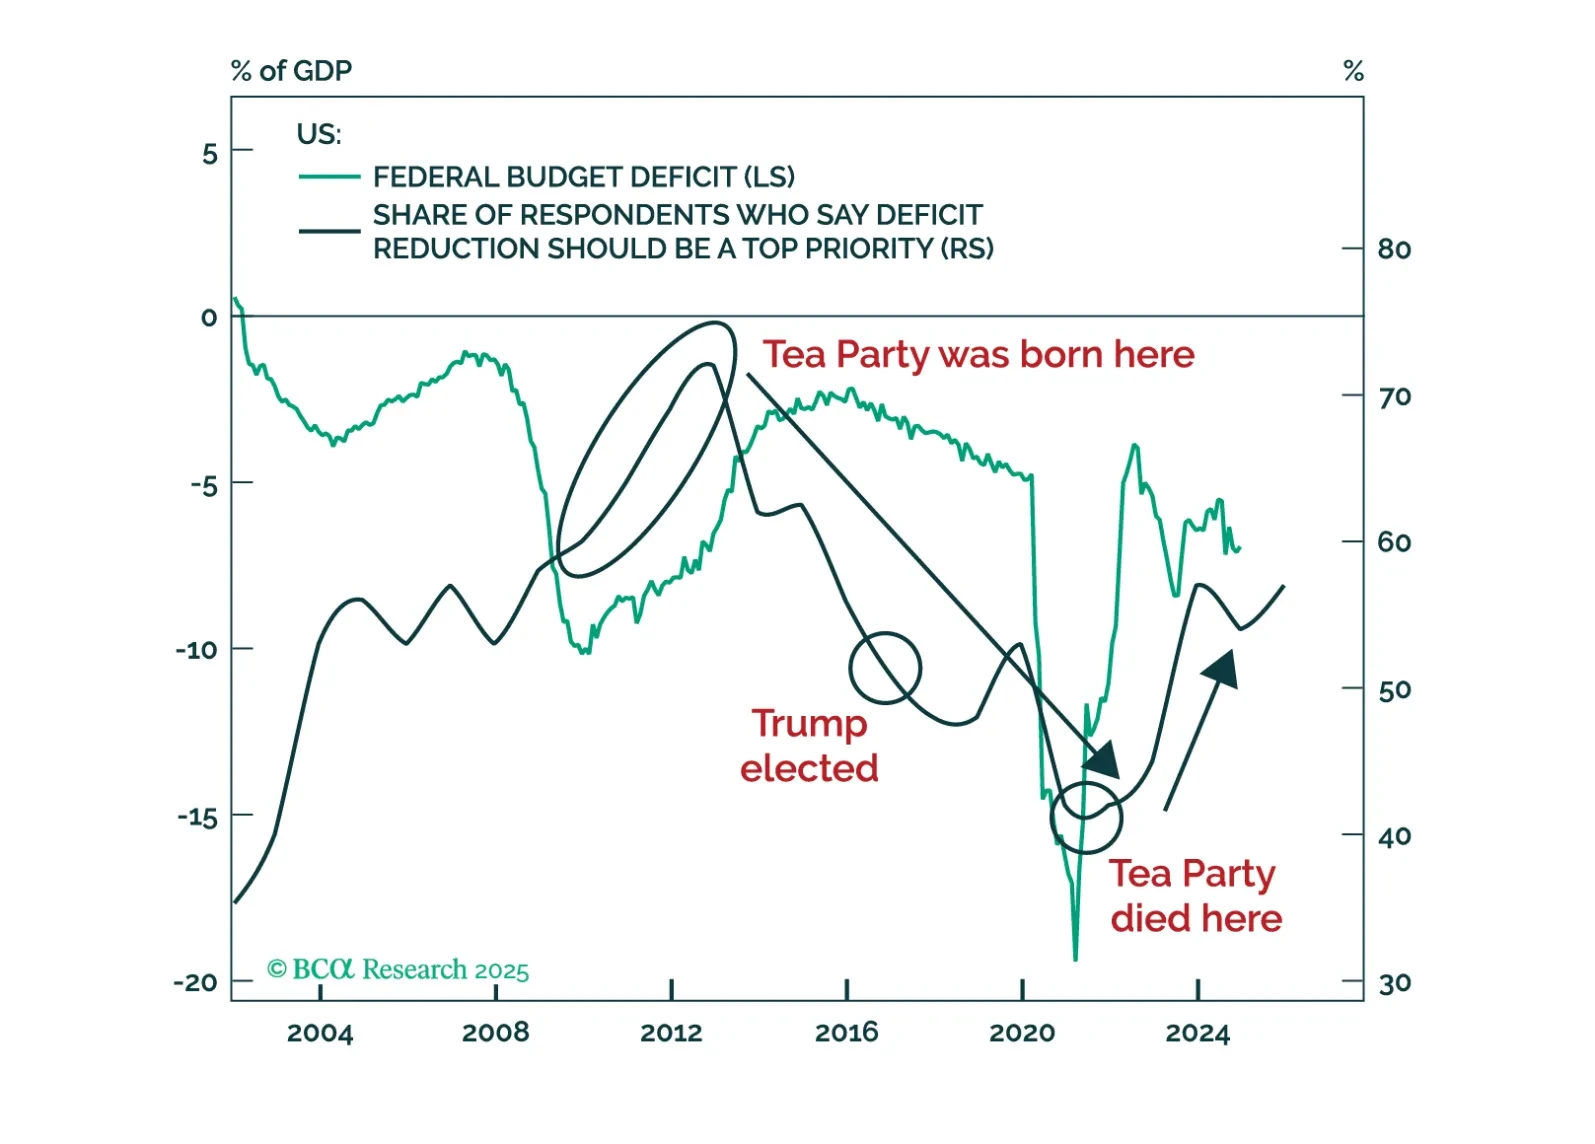
The world is focused entirely on the trade war between the US and… well everyone. This is fair given that there has been no greater market catalyst than Liberation Day since the pandemic. However, we continue to stress that the BIG PICTURE for macro investors is the rotation out of the US. A rotation that started well before April 2, despite the understanding of the investment community that some tariff action would be afoot.
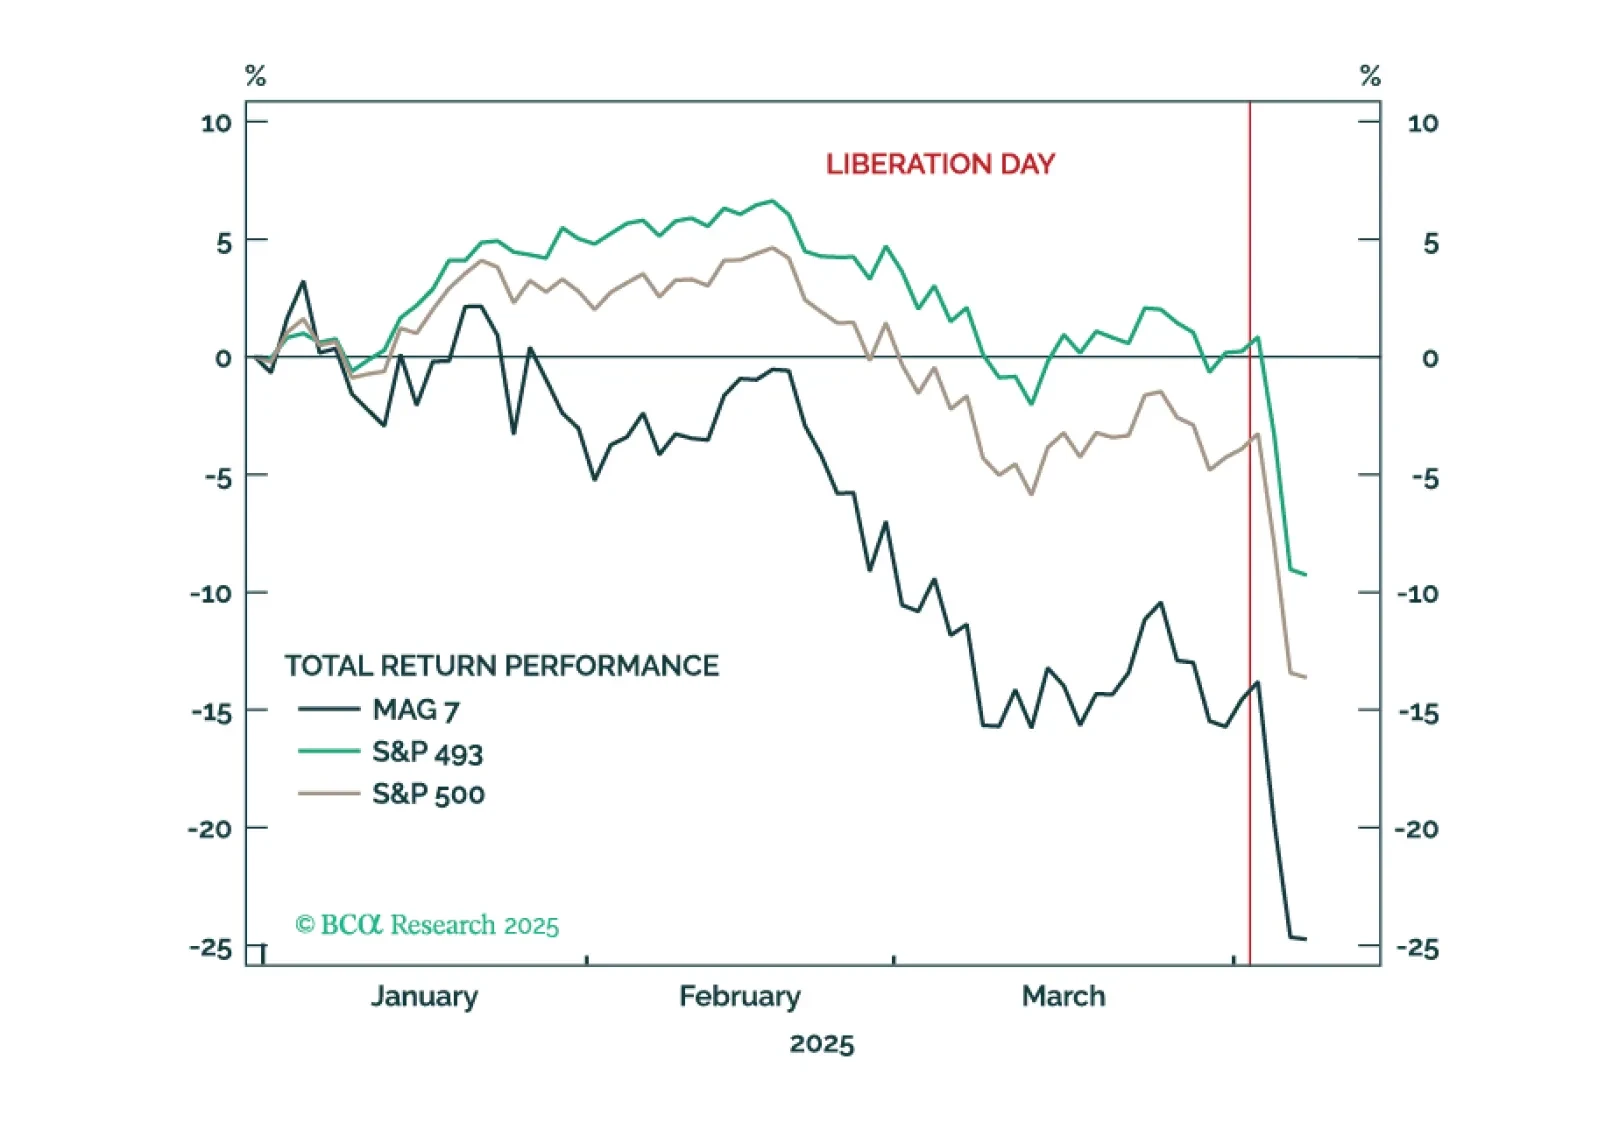
In the front section of the chart pack, we review March’s performance. We will also recommend the portfolio positioning for downward protection.
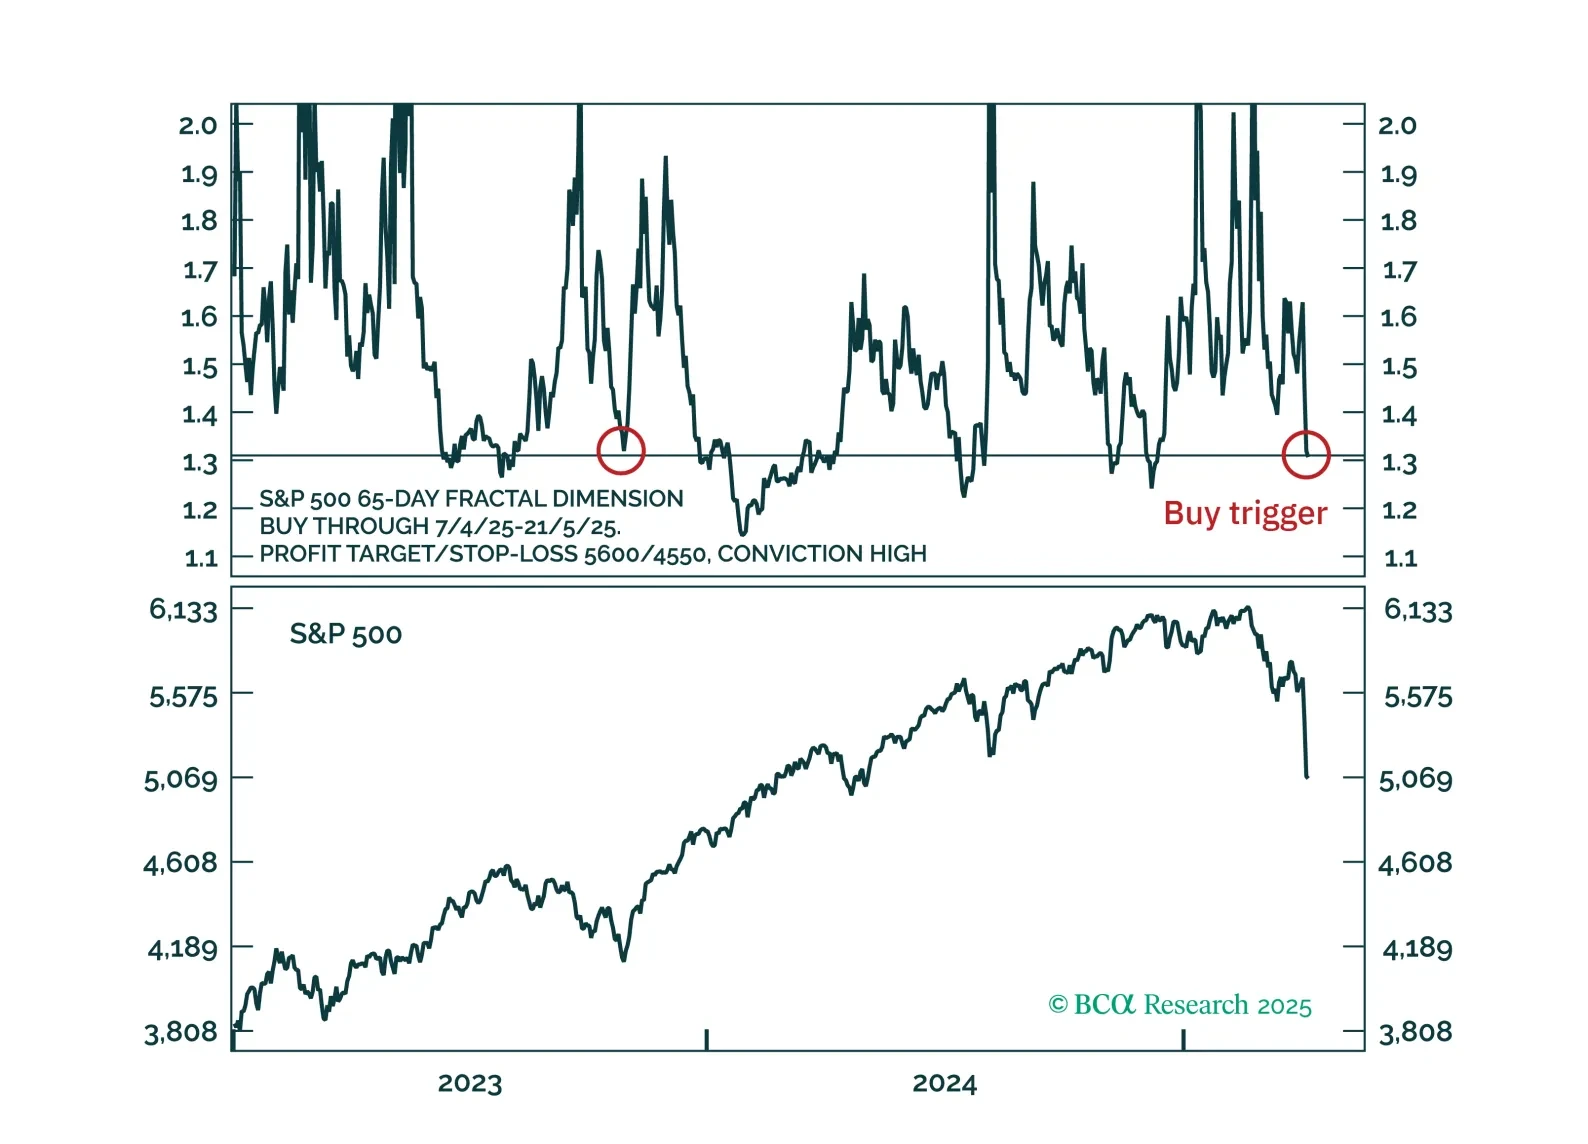
Countertrend buy triggers have been activated for the S&P 500, Nasdaq and Nasdaq versus 30-year T-bond.
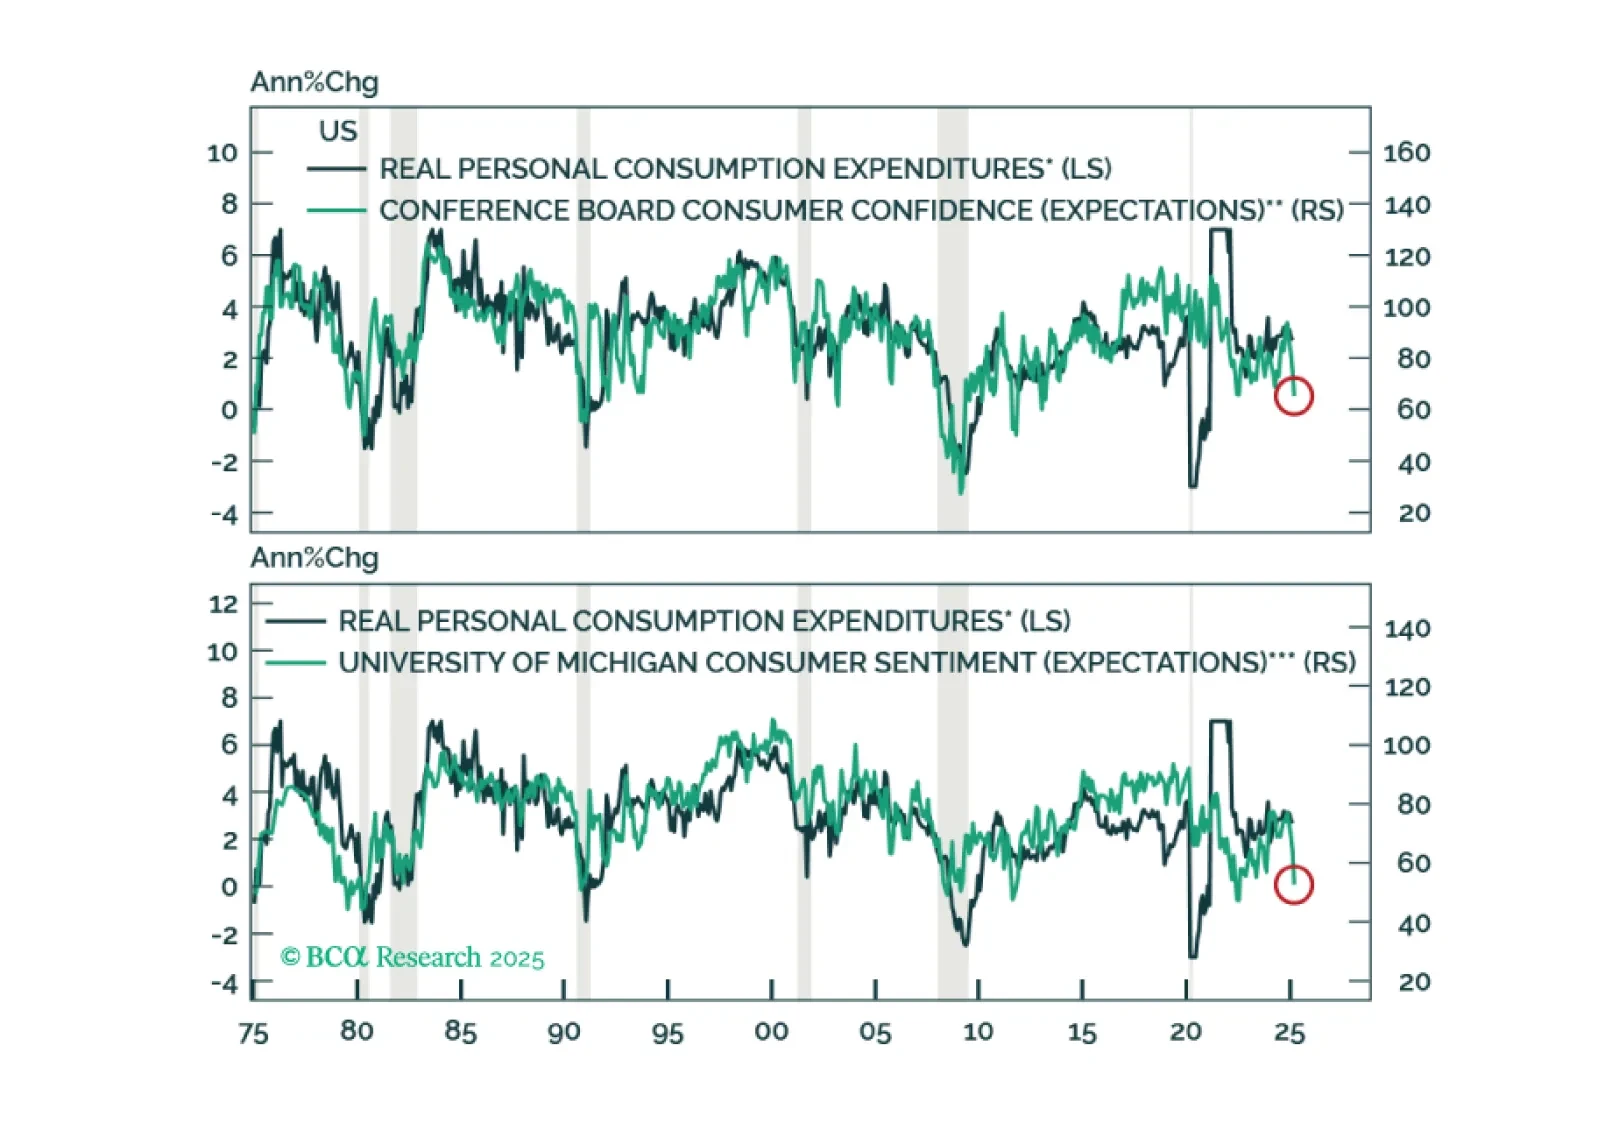
President Trump imposed tariffs on the world in his first 100 days, as we expected. Tariffs may have catalyzed a recession in the US, given the weakness in consumer sentiment and demand. Trump will soon backpedal and grant exemptions to countries that are negotiating, which he will showcase as proofs of his successful trade policy. While he may backpedal on his tariffs on other countries, China is not likely to receive the same treatment due to the US-China strategic competition.
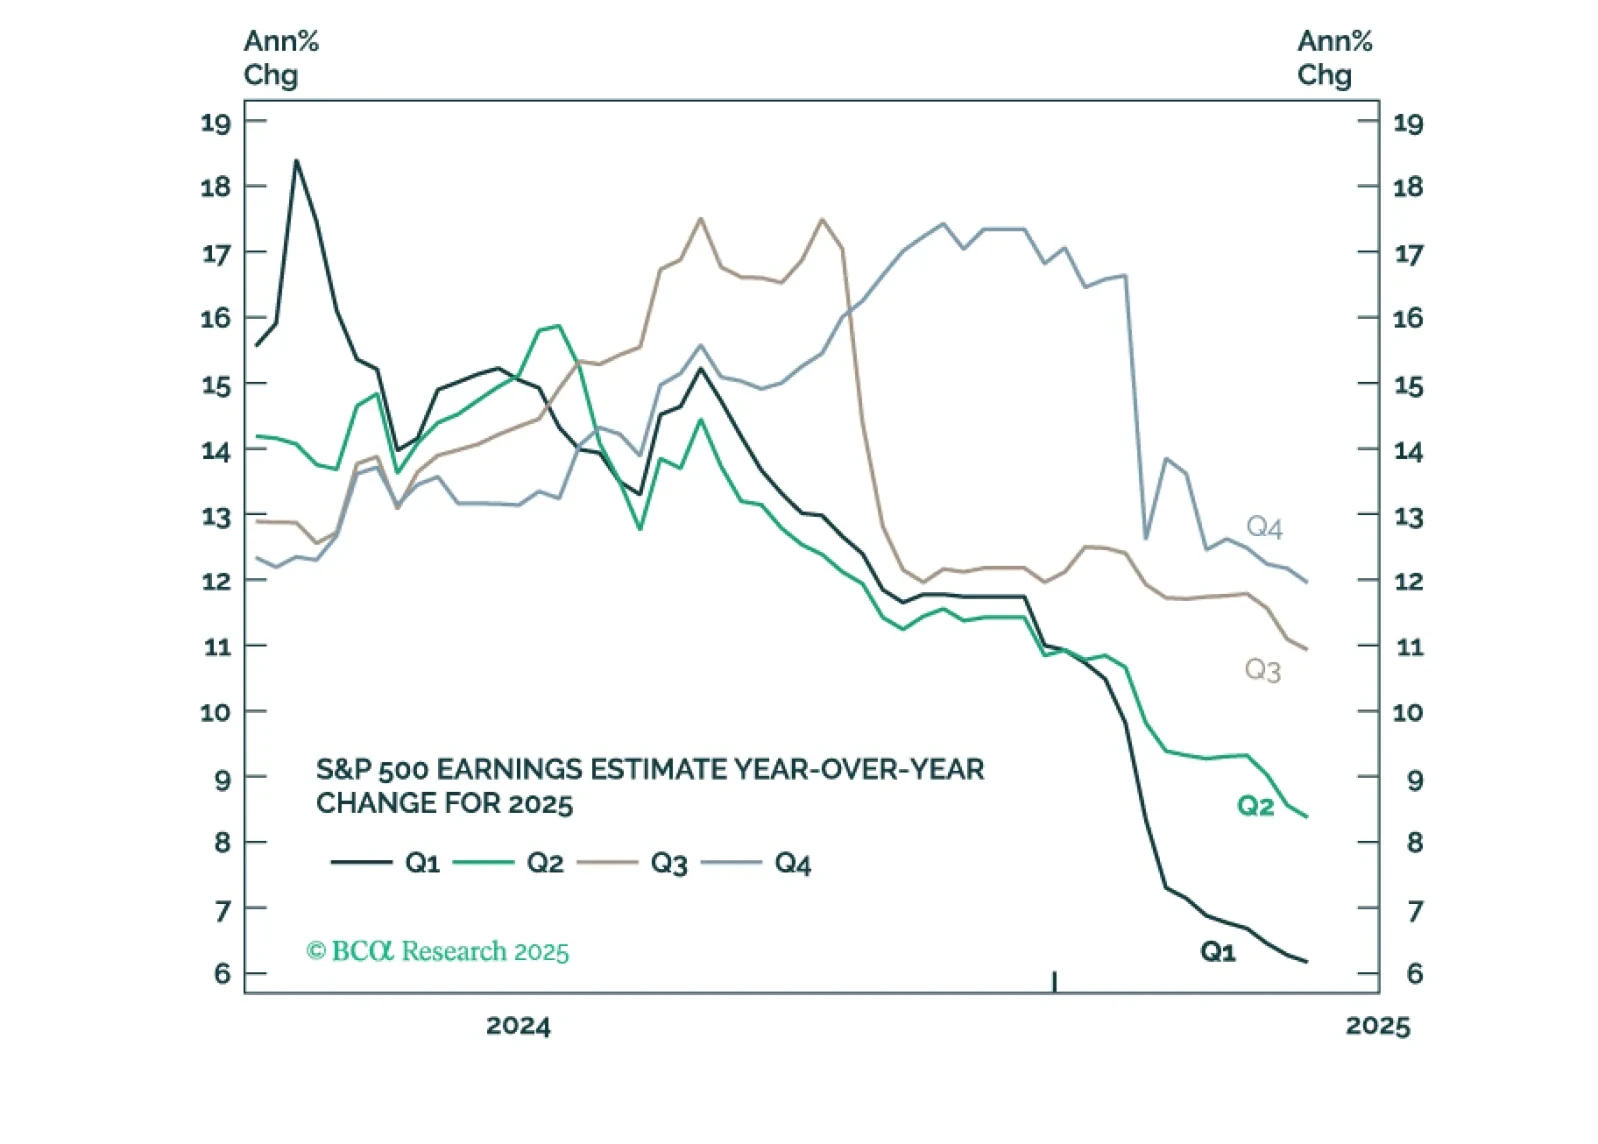
Equities will find a bottom when the full effects of tariffs on earnings and economic growth are priced in. The bottom of the market appears a long way away, and the S&P 500 may end up as low as 4,300, barring any reversals in trade policy that could undo the damage.
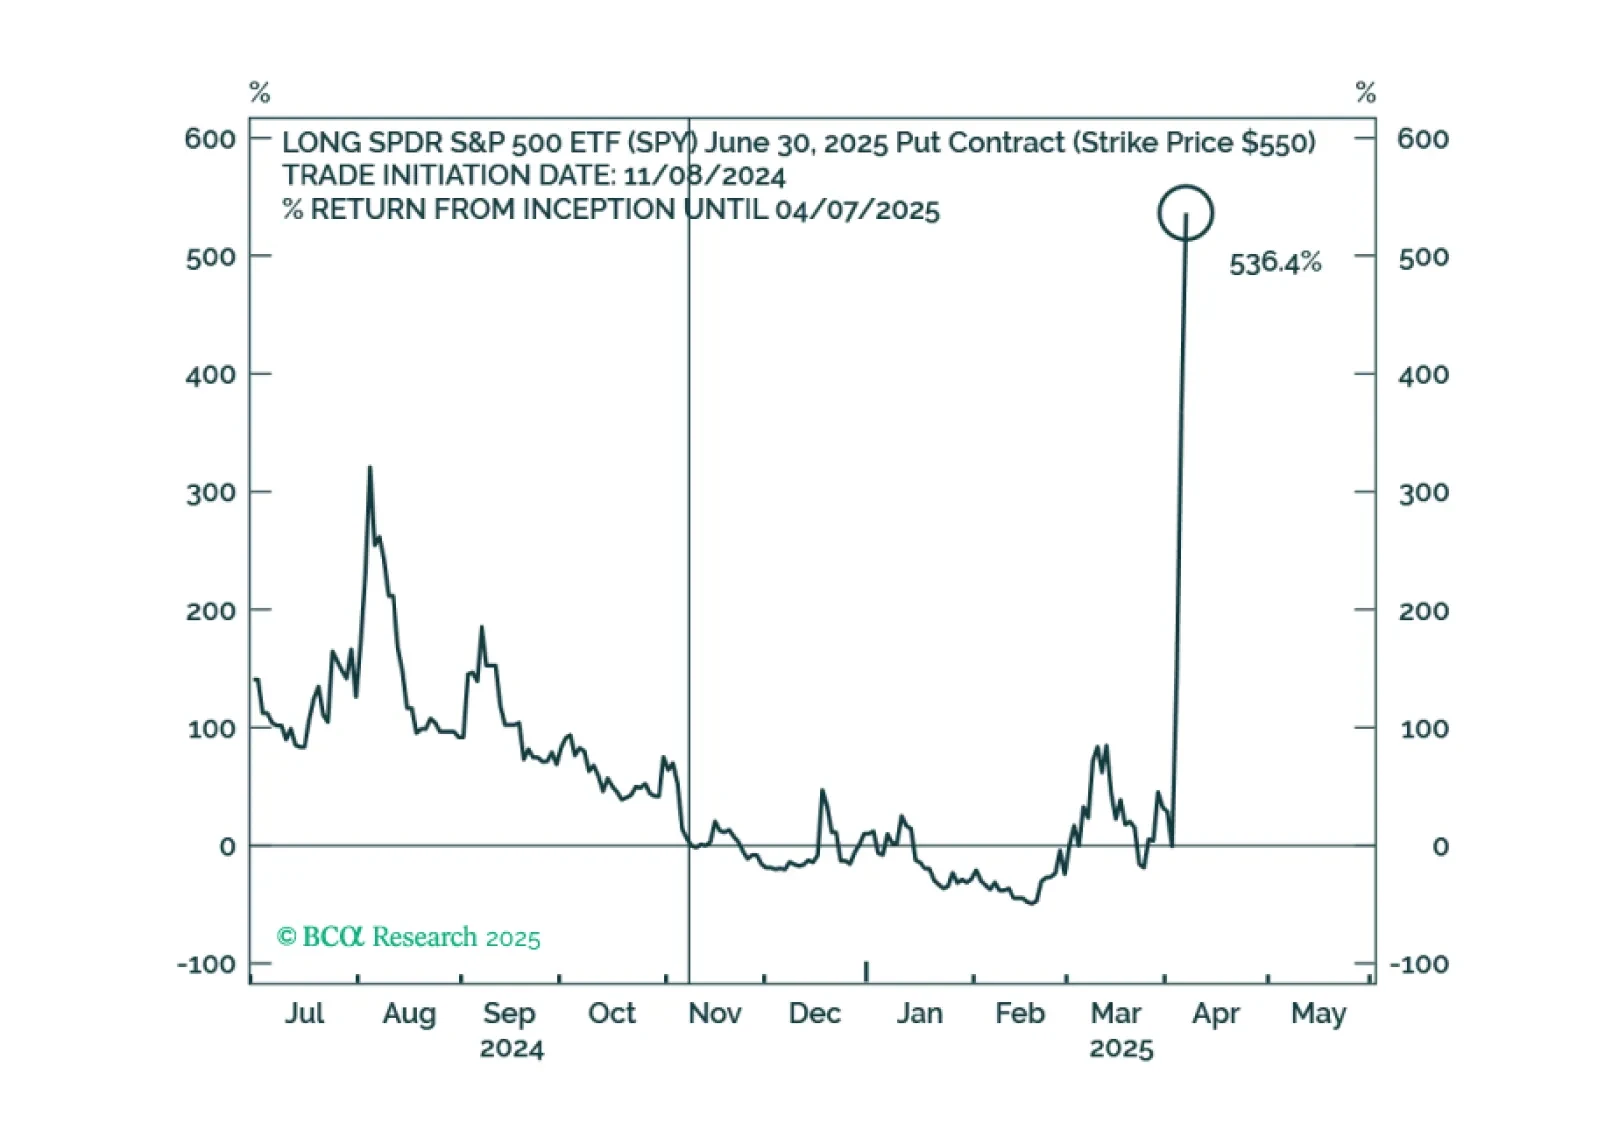
Going into this year, I was by far the most bearish strategist in the Bloomberg survey. A number of clients have reached out to me asking if I plan to change my end-year price of 4450 for the S&P 500 in light of recent events. The answer is “no,” since recent events have unfolded broadly in line with my expectations.
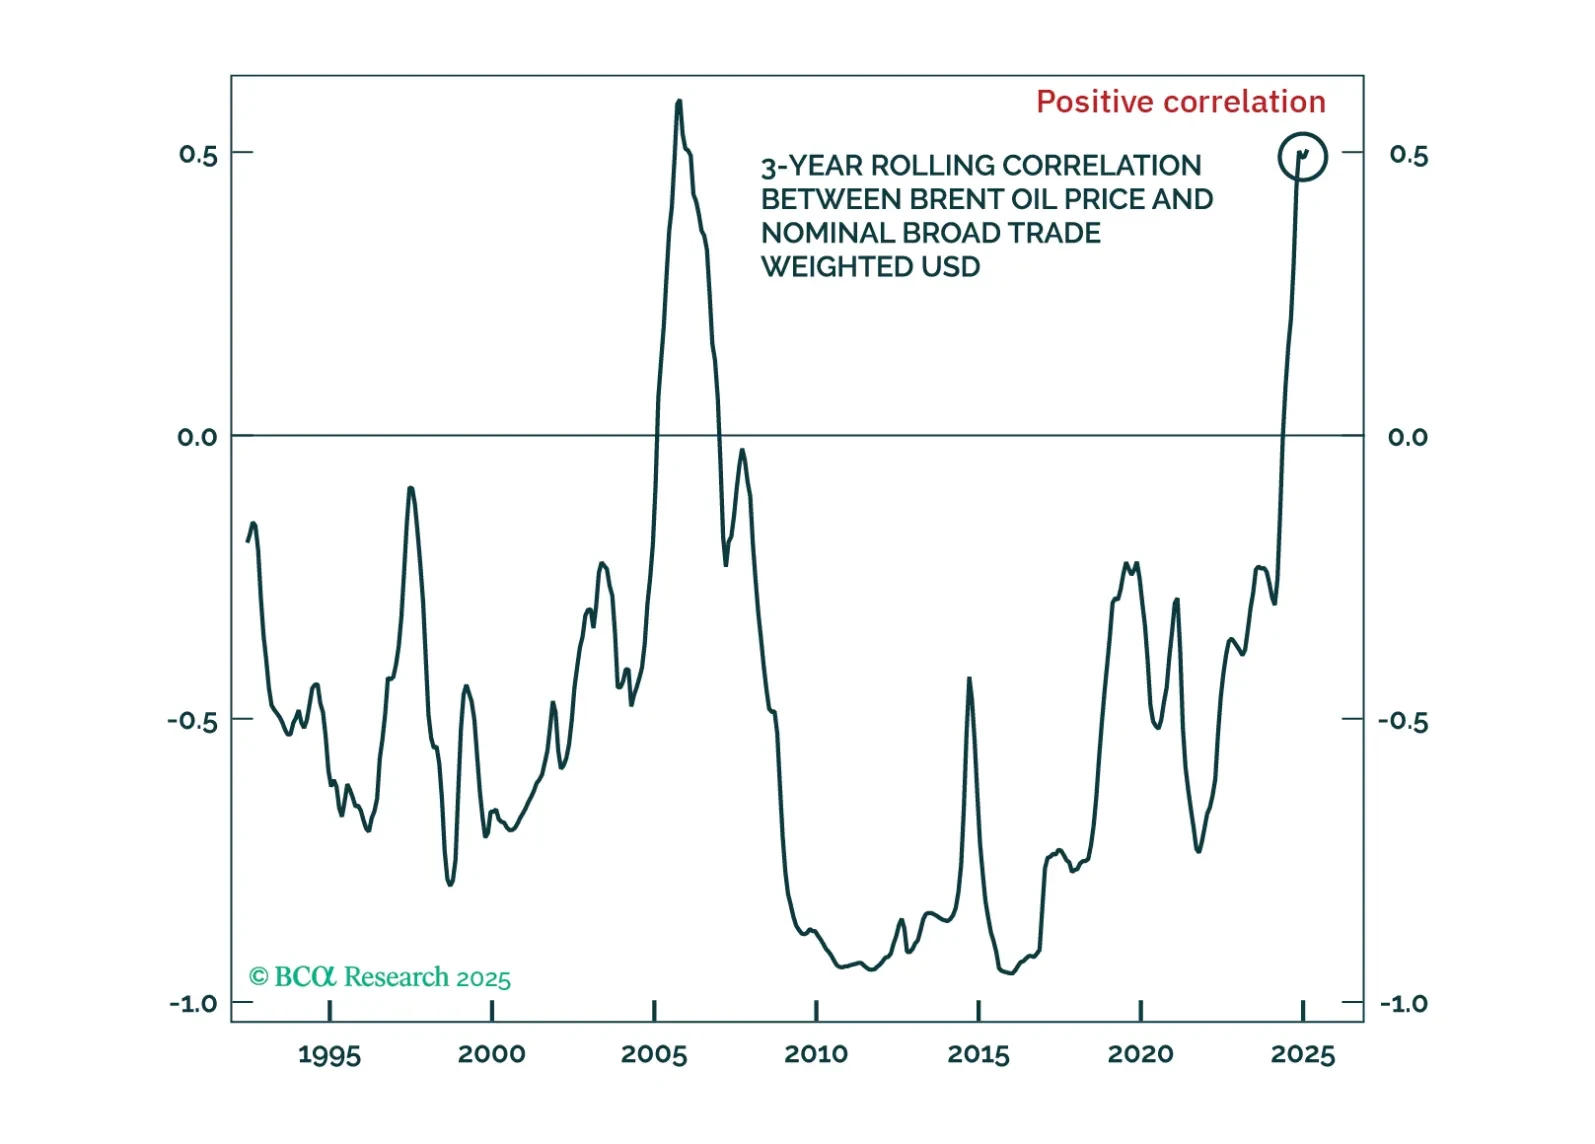
Commodity prices are succumbing to the risk-off environment triggered by President Trump’s reciprocal tariff announcement. The latest events and market moves raise several important questions about the outlook for commodity markets. In this Strategy Report we address some of the most pressing questions raised during our recent discussions.
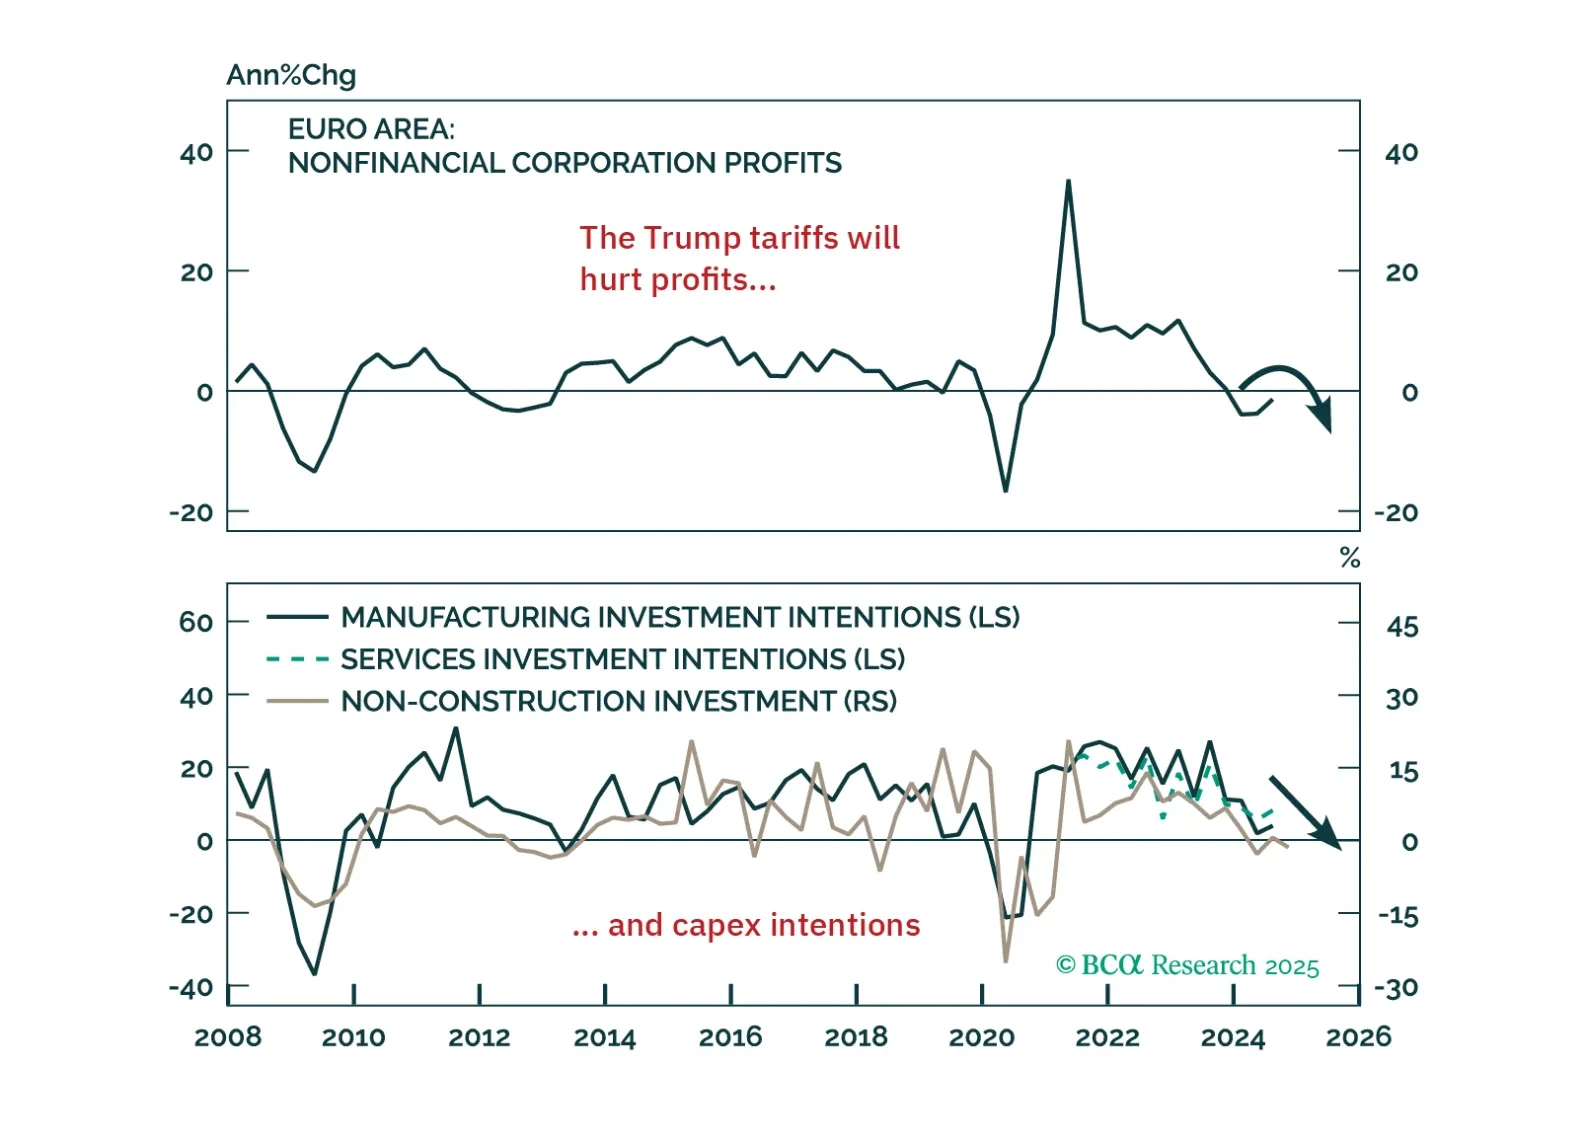
Trump’s tariff shock will push Europe into recession — but it’s also triggering a powerful integration response. In this report, we lay out the tactical case for staying defensive and the structural case for going long European assets when the dust settles.