Latest from BCA Research
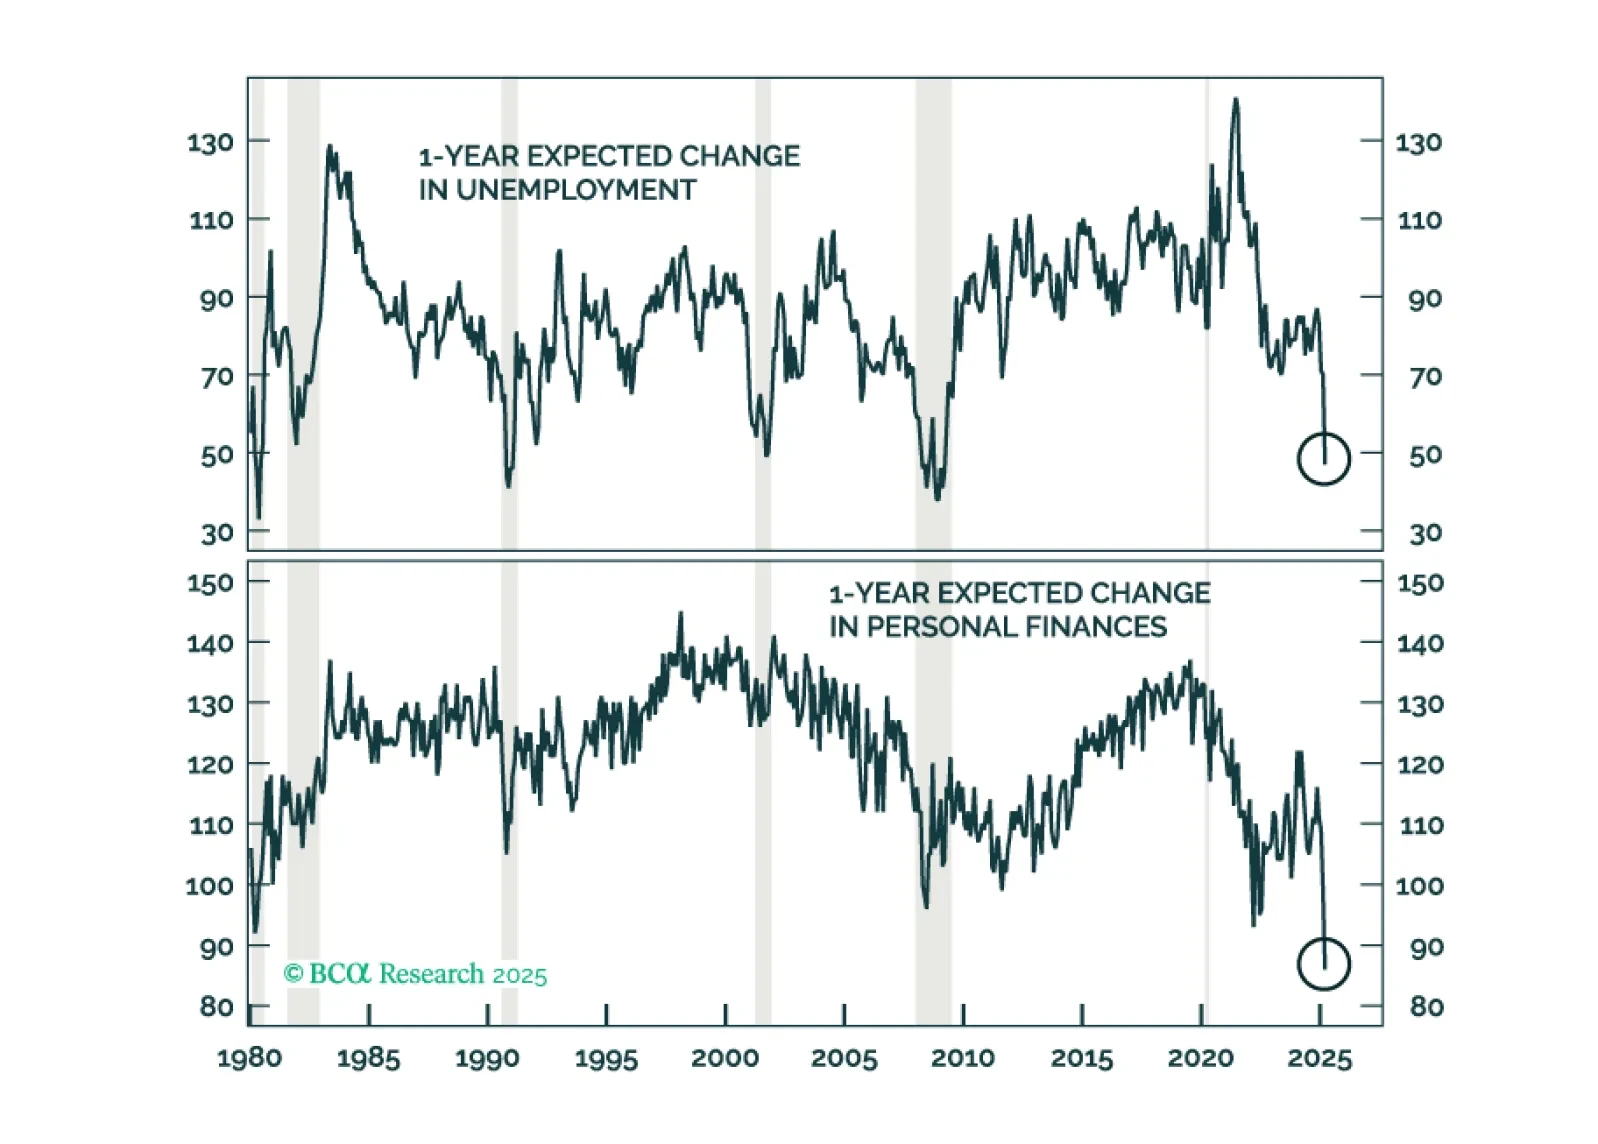
The stimulus measures driving the post-COVID expansion were beginning to wane after five years and pointing the economy in the direction of an organically occurring recession. Now that DOGE and the multi-front trade war have sped up the timetable, we reiterate our risk-off recommendations.
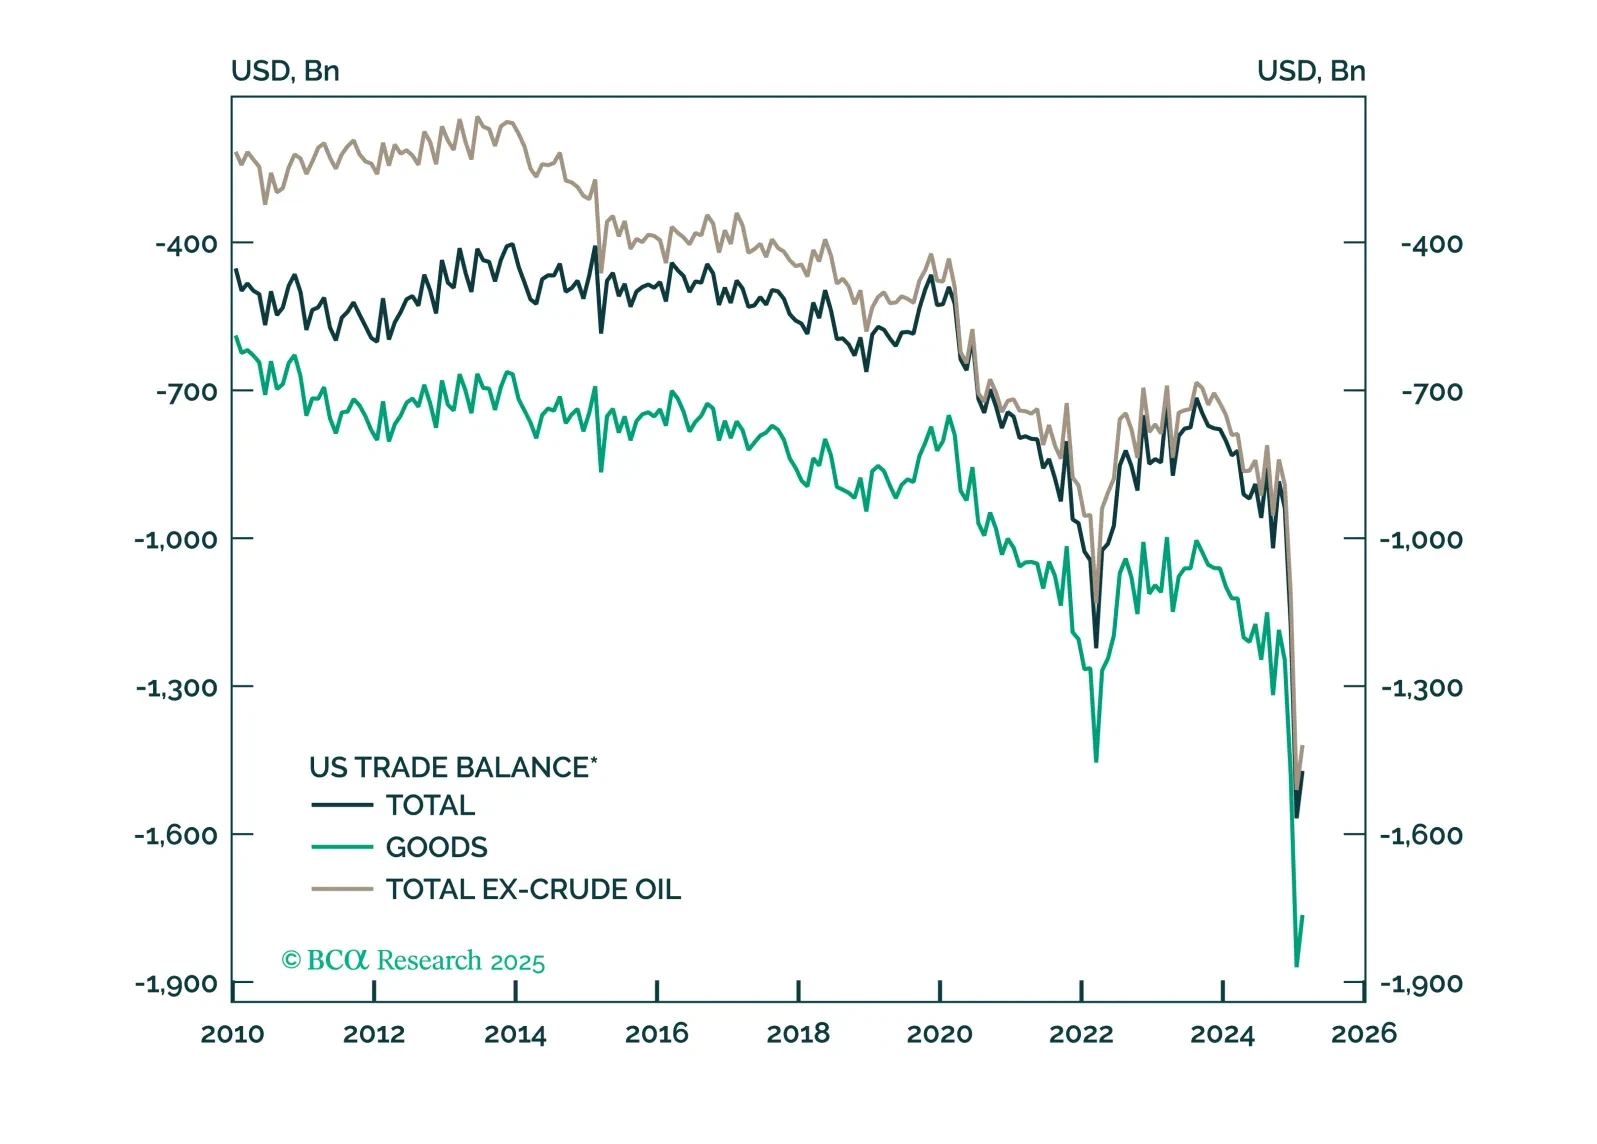
This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.
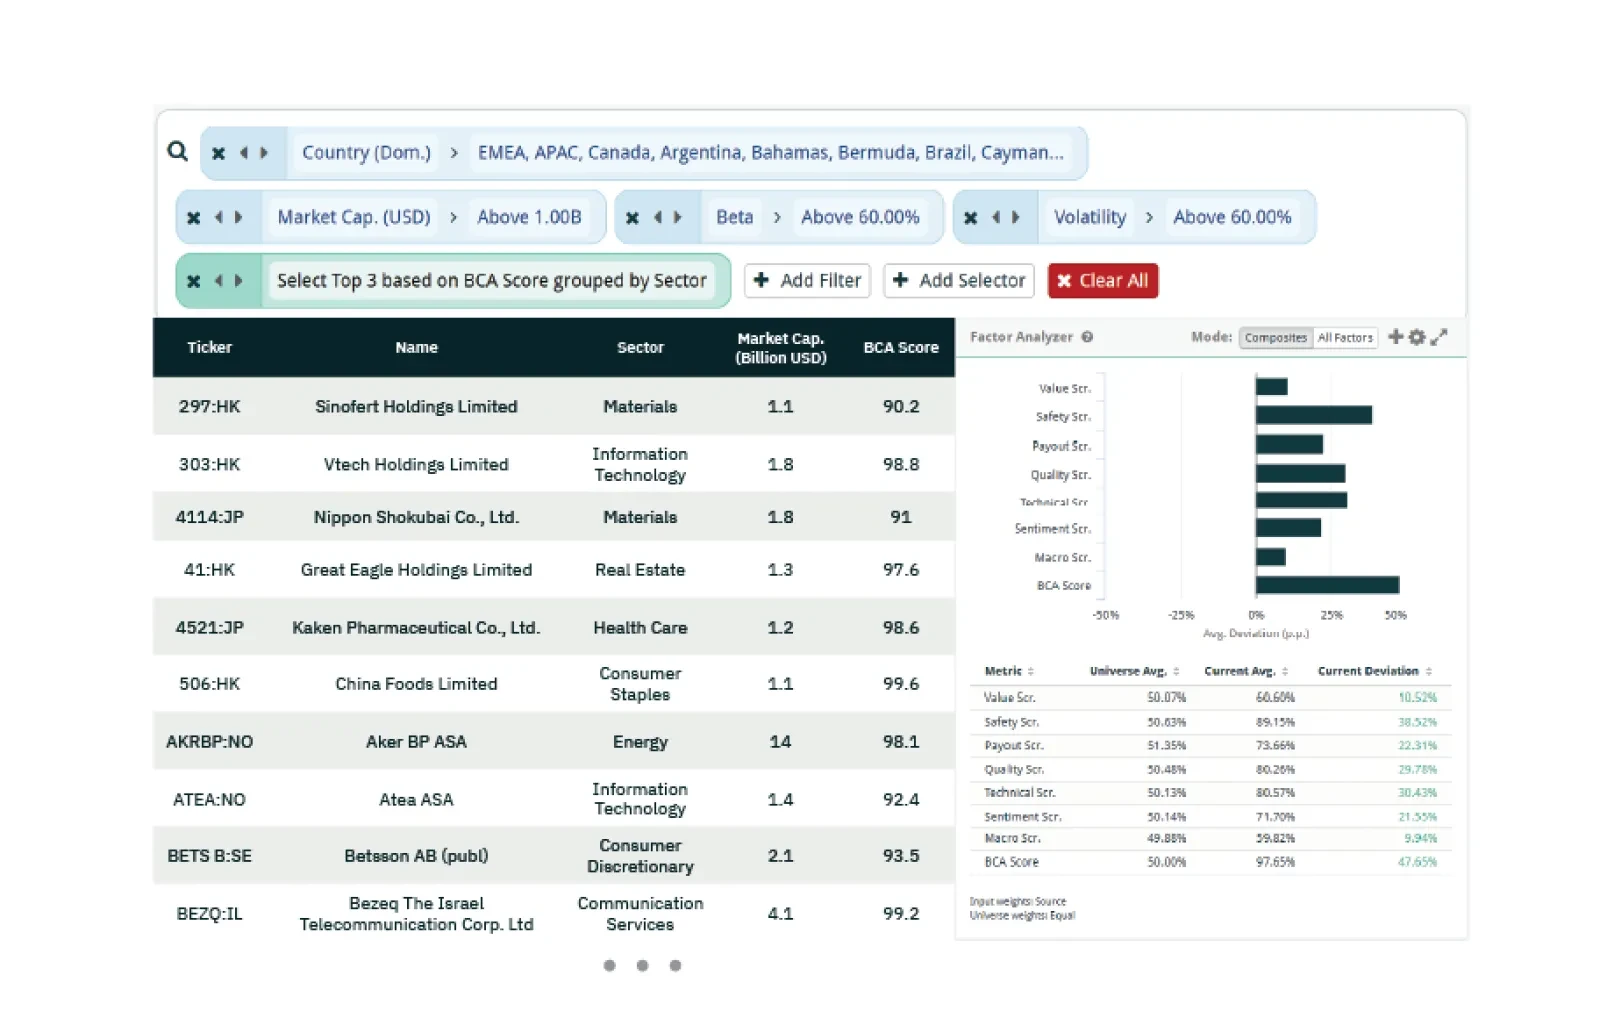
This week, our three screeners cover: Equity plays in Low Vol & Low Beta outside the US; Chinese stocks; and stocks that are buys according to the PEG ratio.
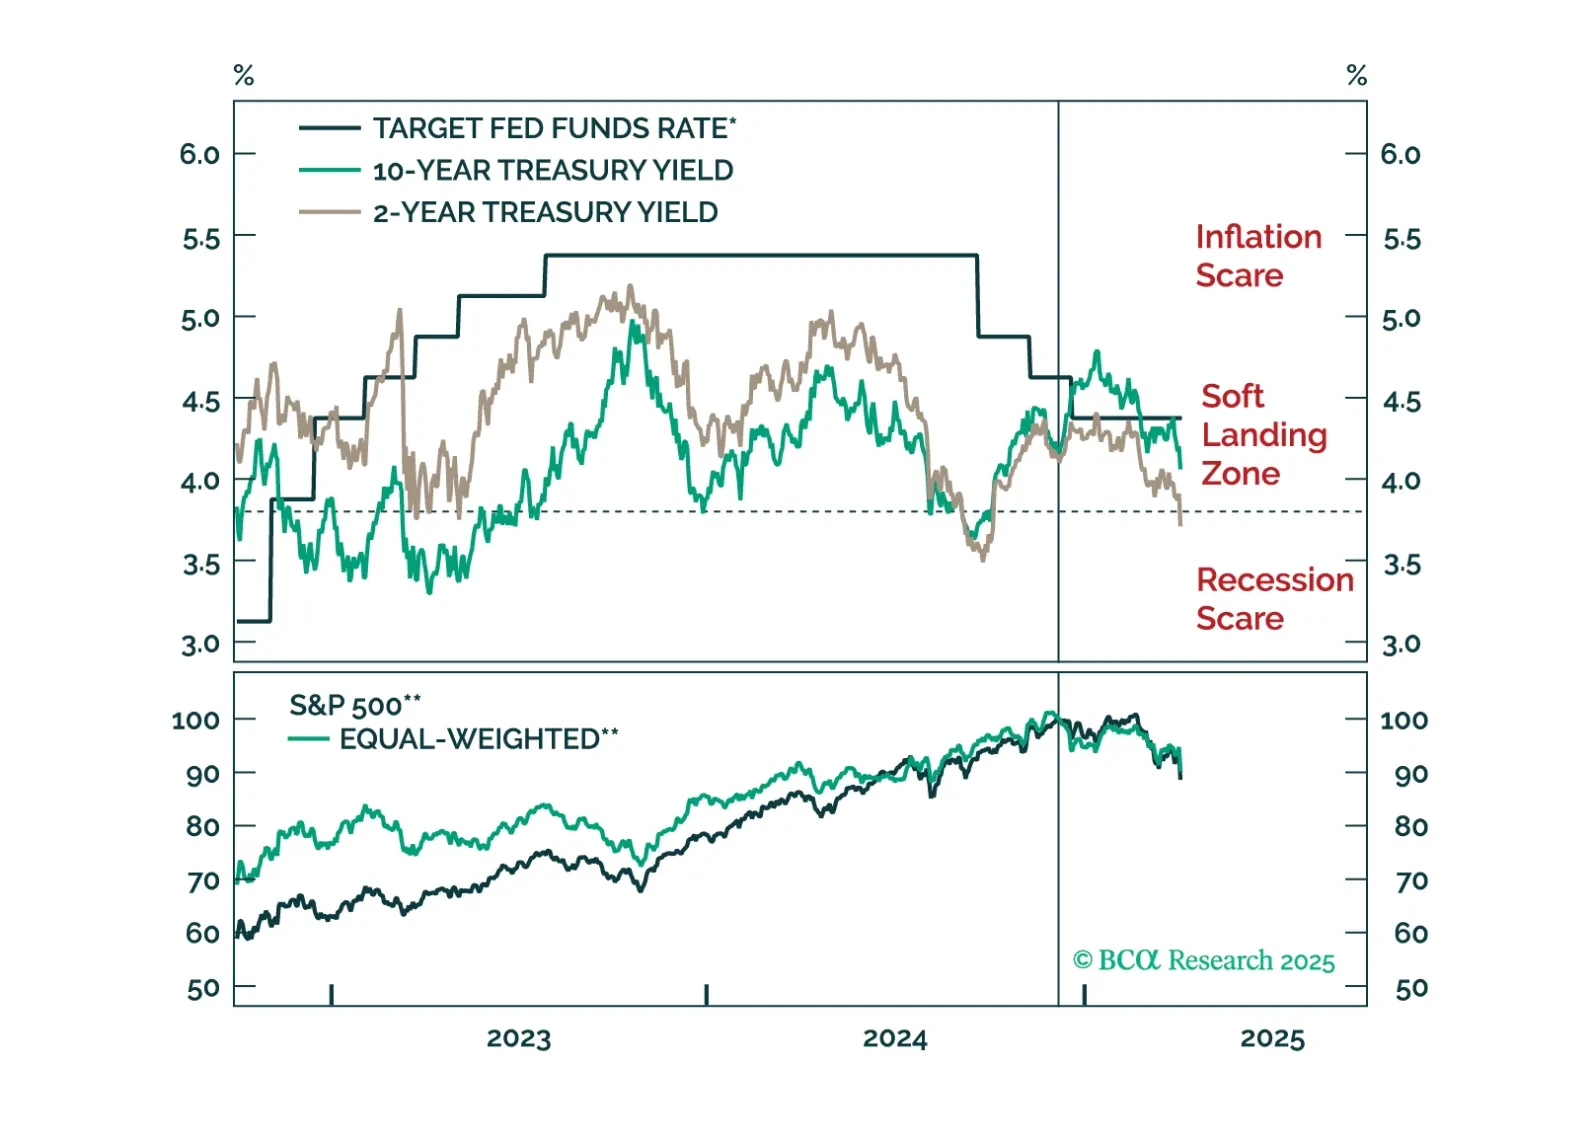
The March employment report showed strong job growth, but the labor market remains in a fragile state and the demand shock from tariffs could be the catalyst that tips it over the edge into recession.
Did you know that the high-quality Japanese zippers you use every day are macro relevant? That is because YKK dared to sue – and win – against President Richard Nixon 10% across-the-board tariffs.
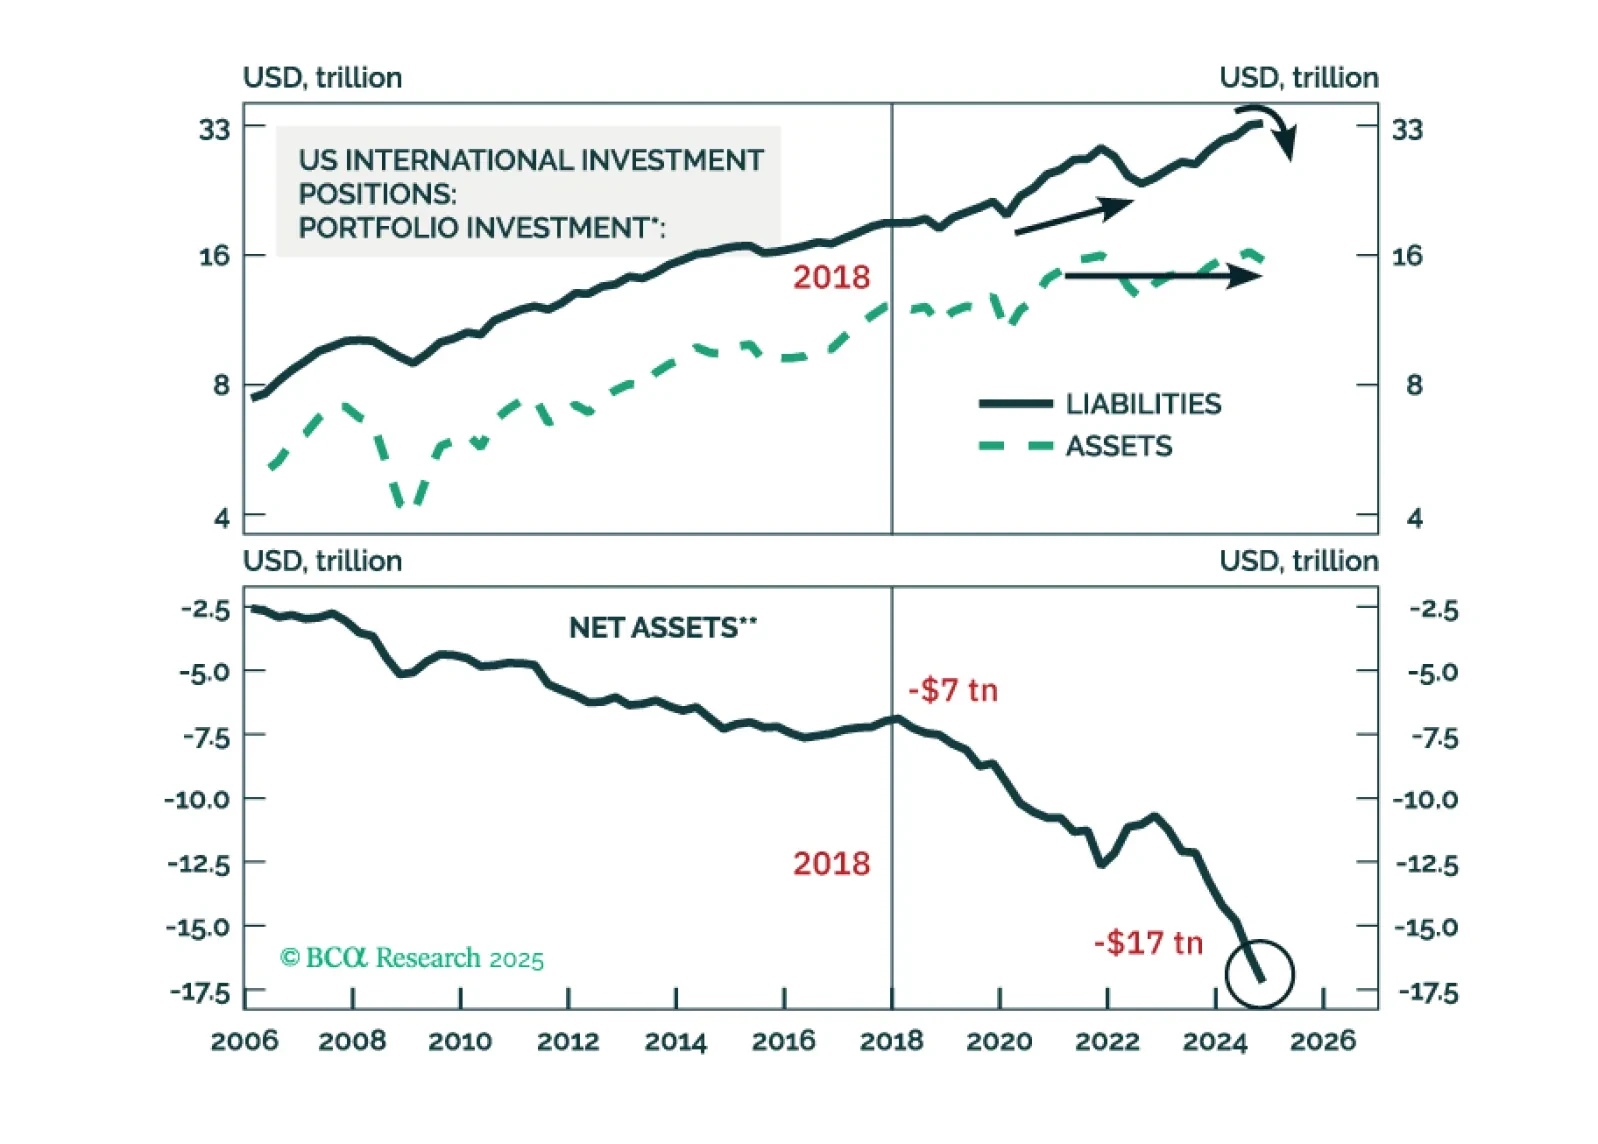
On the one hand, US tariffs are much more deflationary for the rest of the world than for the US, so interest rate differentials might move in favor of the US dollar in the near term. On the other hand, portfolio outflows from the US will weigh on the greenback over a cyclical horizon. We recommend buying Mexican and Central European domestic bonds.
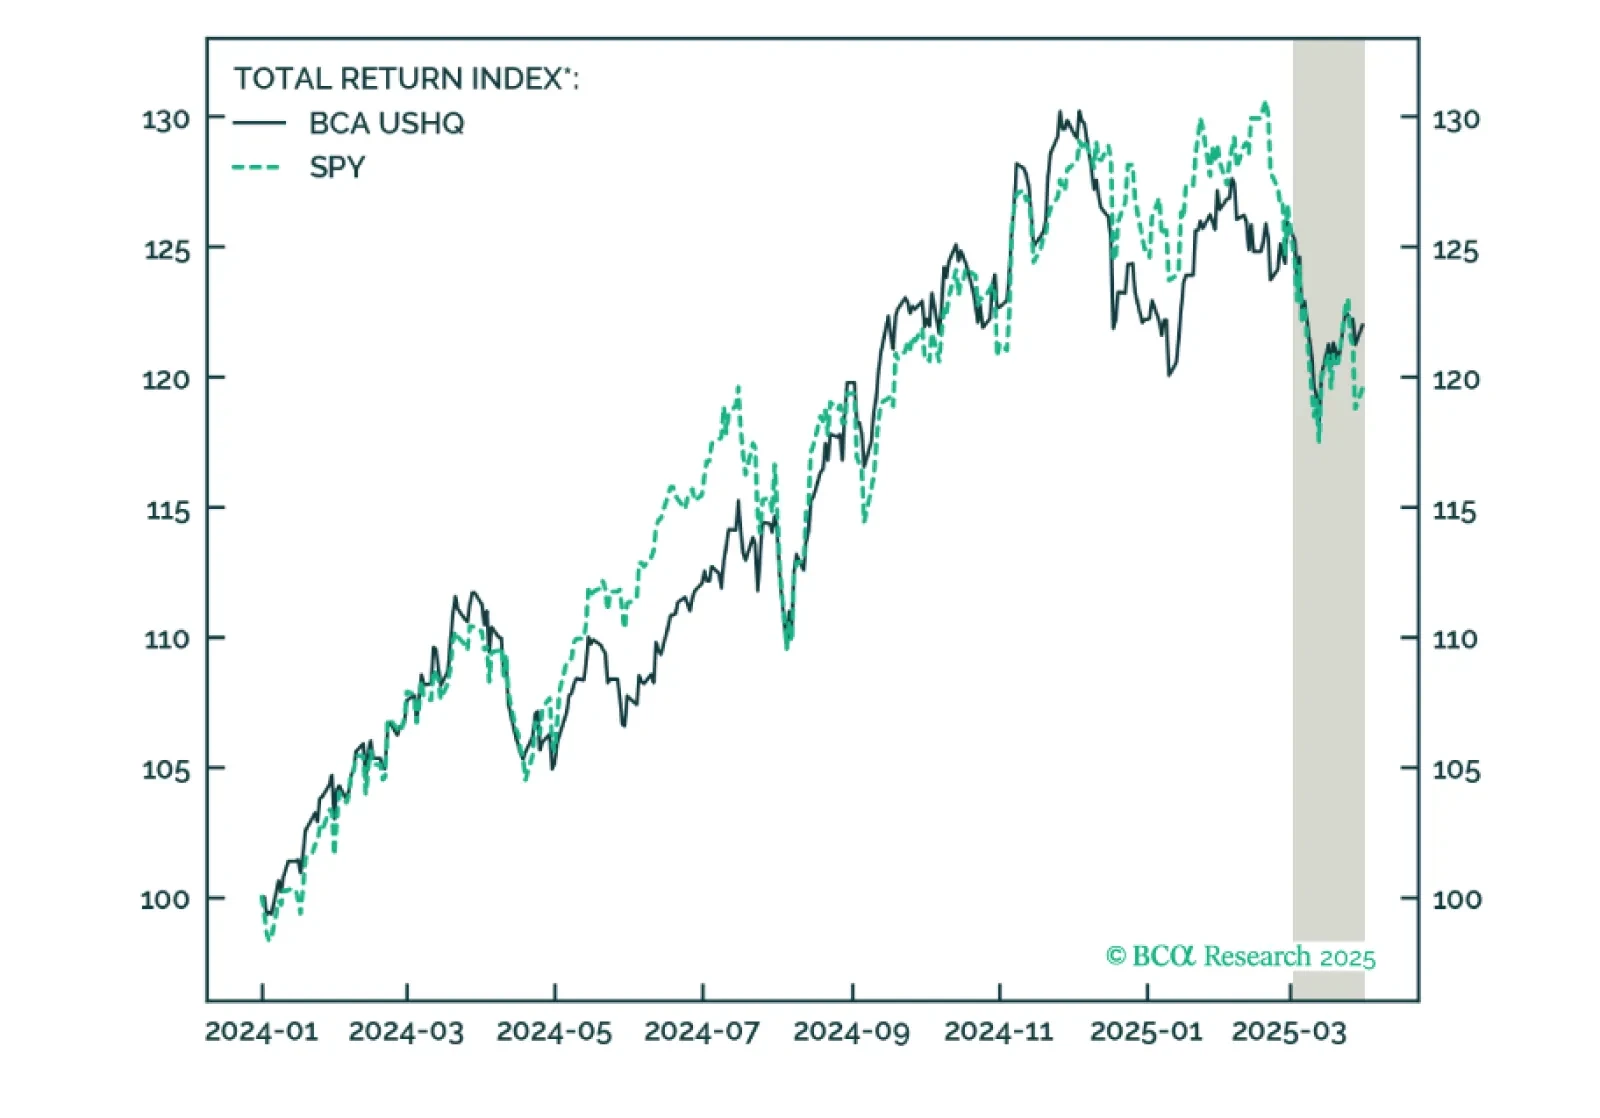
The US High Quality (USHQ) portfolio outperformed its benchmark in March, despite realizing a negative return. USHQ returned -2.6%, whilst its SPY benchmark returned -3.9%. Over a trailing-quarter basis, USHQ posted meaningful outperformance vs. benchmark, generating +230bps of excess return, while also exhibiting lower volatility and a smaller drawdown.
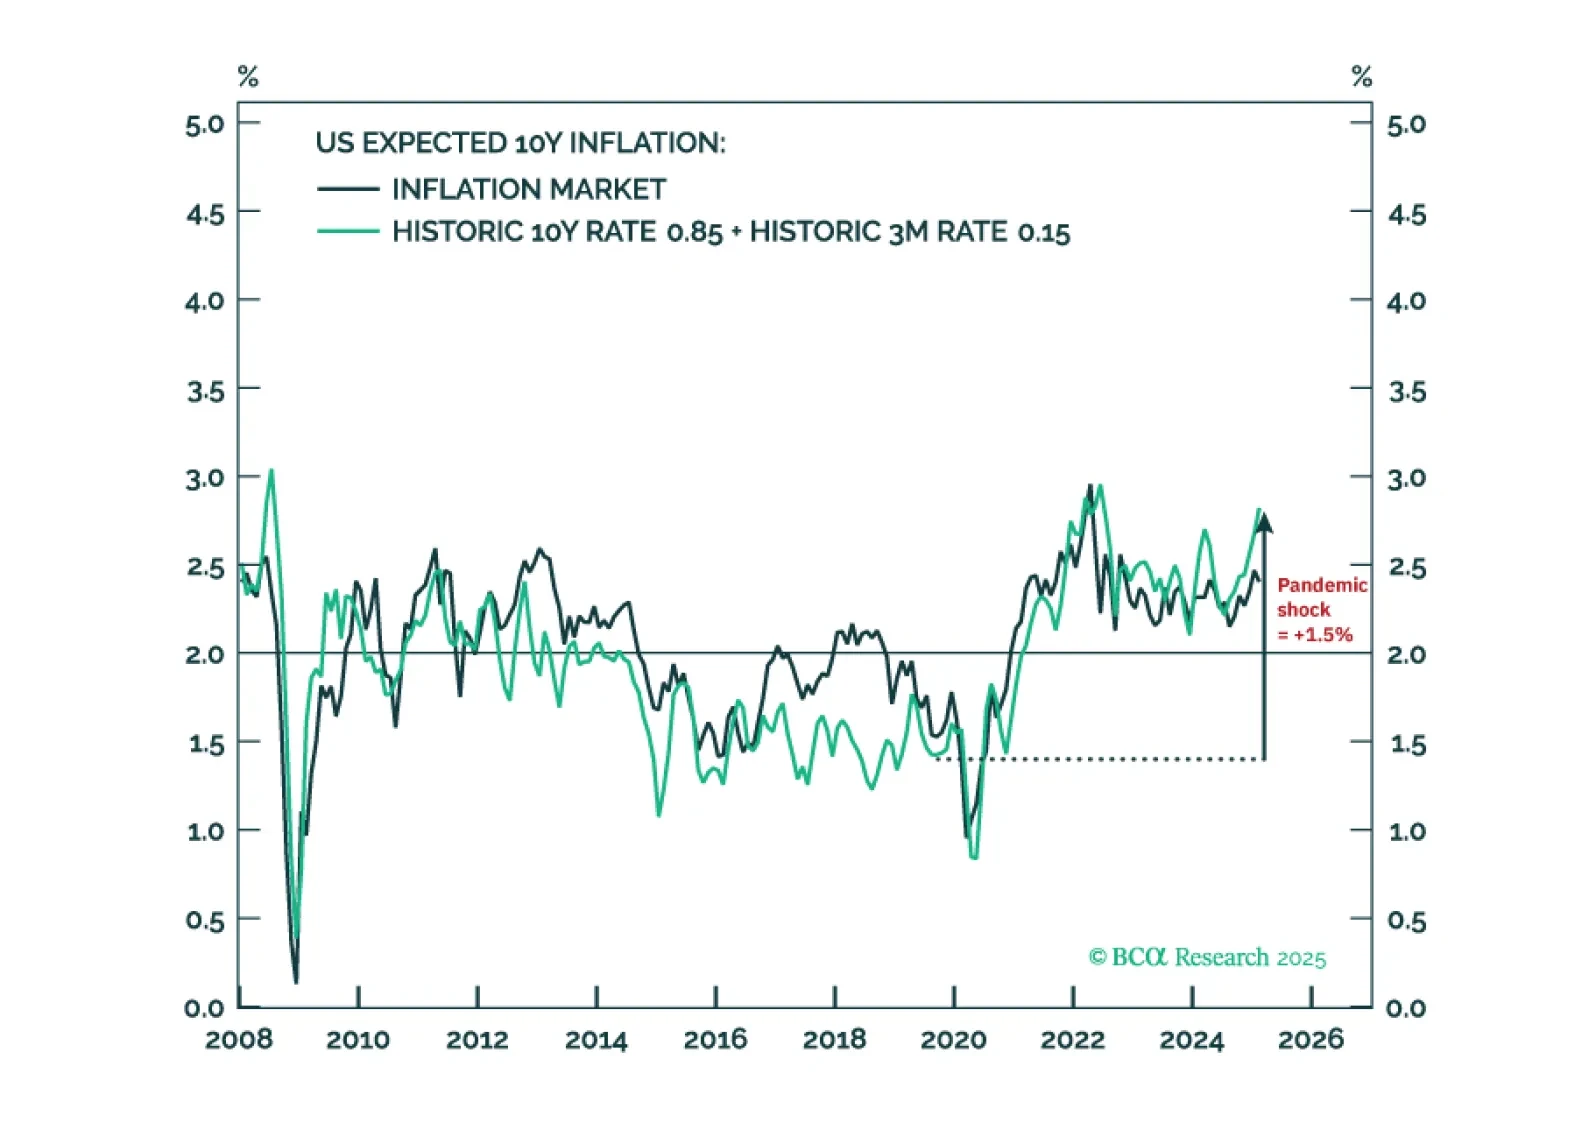
Tariffs will make a difficult job almost impossible. Hitting and sustaining a precise 2 percent inflation target is more about luck than judgement. It requires both the starting point for inflation expectations and any inflation/deflation shock to combine perfectly to 2 percent. While structural inflation expectations in the euro area and Japan could be close to 2 percent, those in the US and the UK will be stuck uncomfortably above 2 percent. We discuss the investment implications for rates and FX. Plus: gold is vulnerable to a tactical reversal.
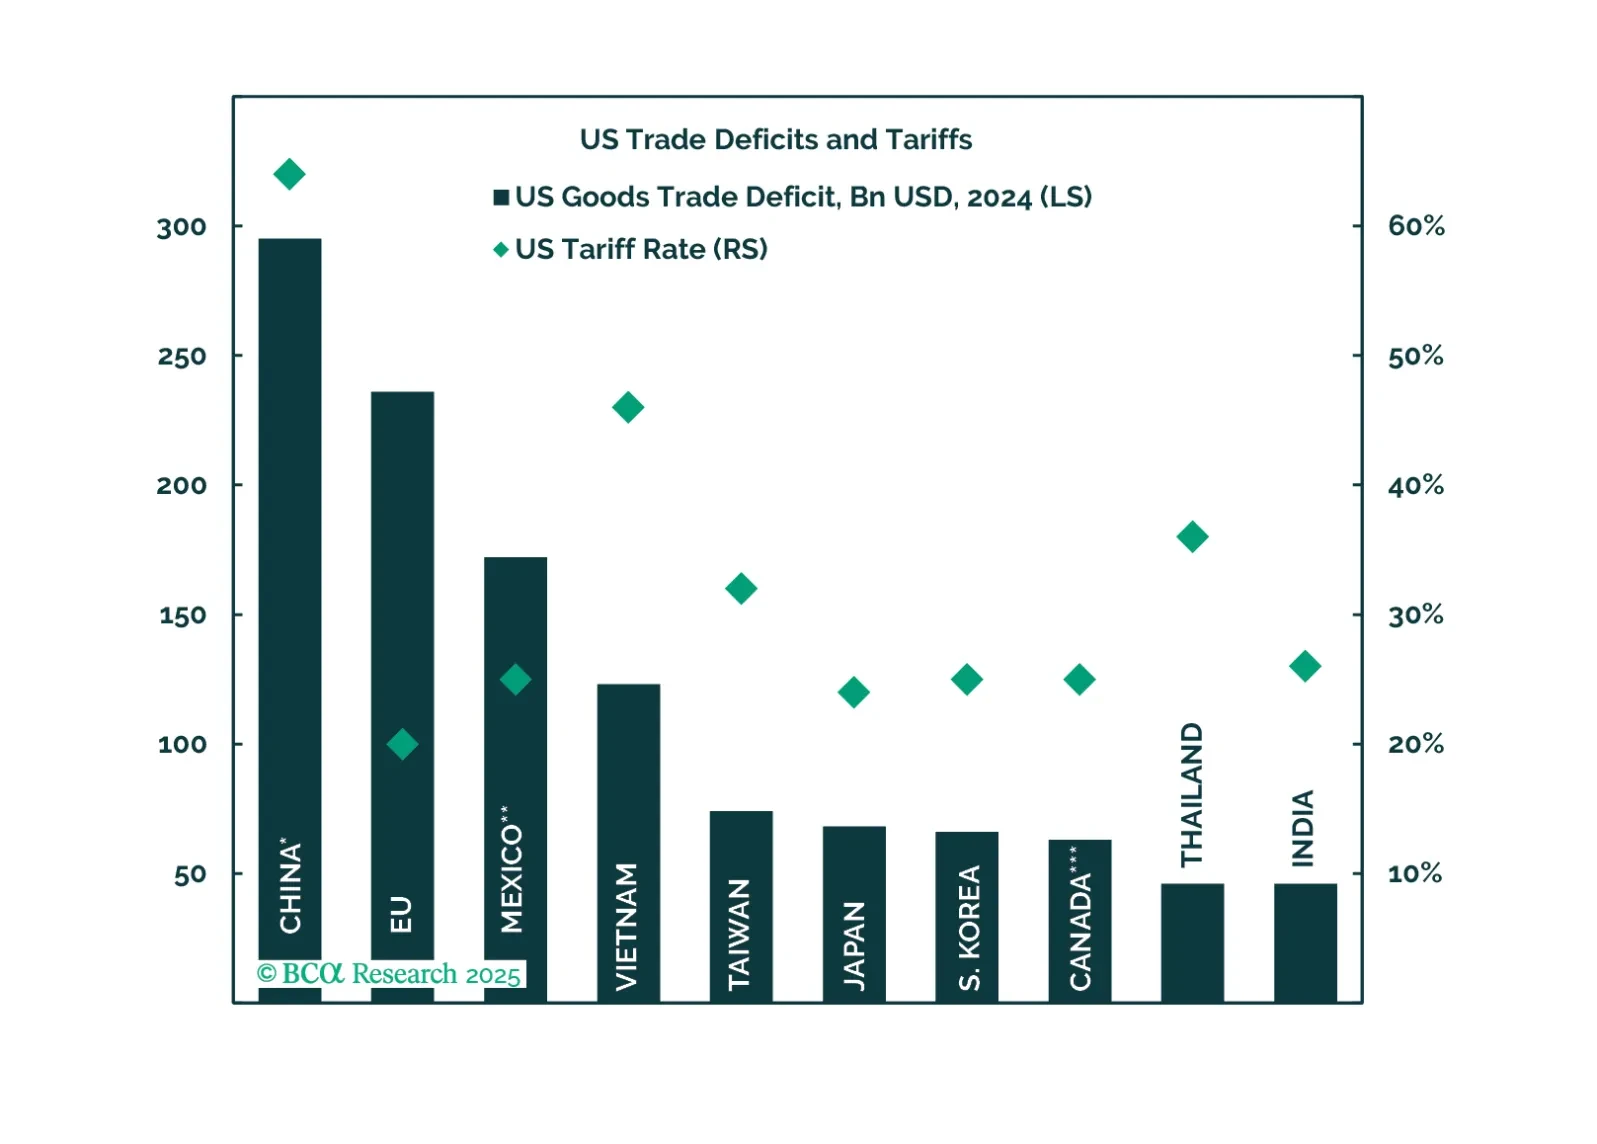
Trump's Tariff D-Day brings a negative surprise to financial markets already anxious over a declining US cyclical economy. Investors should sell risky assets, increase safe havens, and overweight US assets in the near term.
The White House has revealed the plans for Liberation Day. They broadly include: Reciprocal tariffs, on a case-by-case basis. A message from President Trump to other countries to lower their own tariffs and buy US goods. Our take is that April 2 will be remembered – 6-12 months from now – as the peak in “de-globalization” thesis. Markets react to the delta of bad news, not bad news in the absolute.