Latest from BCA Research
Liberation Day is coming to America! In honor of the new holiday, GeoMacro will be increasing prices using an algorithm that will determine how much each client owes us for the sweet taste of their liberty (… from the clutches of normative geopolitical analysis)!
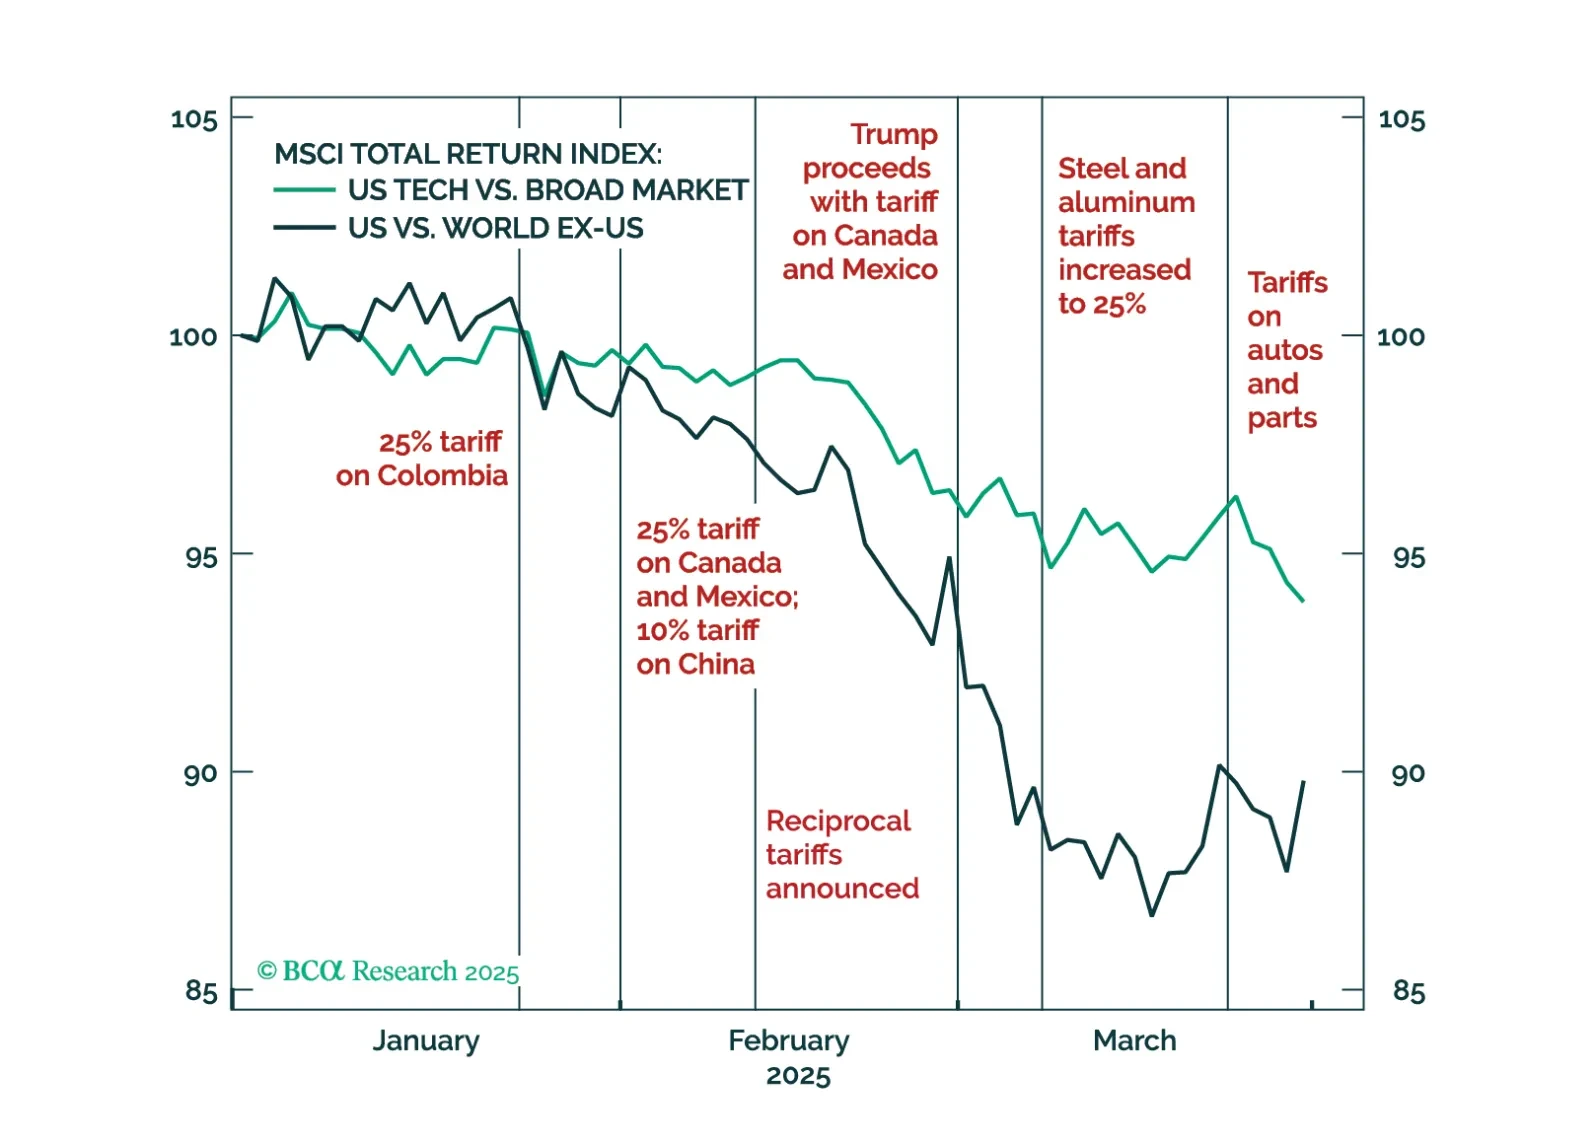
The trade war is on everyone’s mind with America’s “Liberation Day” upon us! However, the reality under the surface is that the main macro narrative has been a rotation – nay… exodus – out of US assets into RoW. This was not supposed to happen with de-globalization and a MAGA trade policy. US assets – form equities to the USD – were supposed to be the safe haven from “America First” policies by Donald Trump. Meanwhile, the noose of material constraints is tightening around Trump, suggesting that a pivot away from brinkmanship may not be long away from “Liberation Day.”

In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.

Corporate bond spreads are tight around the globe and do not adequately compensate for the risk of a deterioration in credit quality. We examine the global corporate credit landscape to identify which markets are best equipped to perform in the current environment.
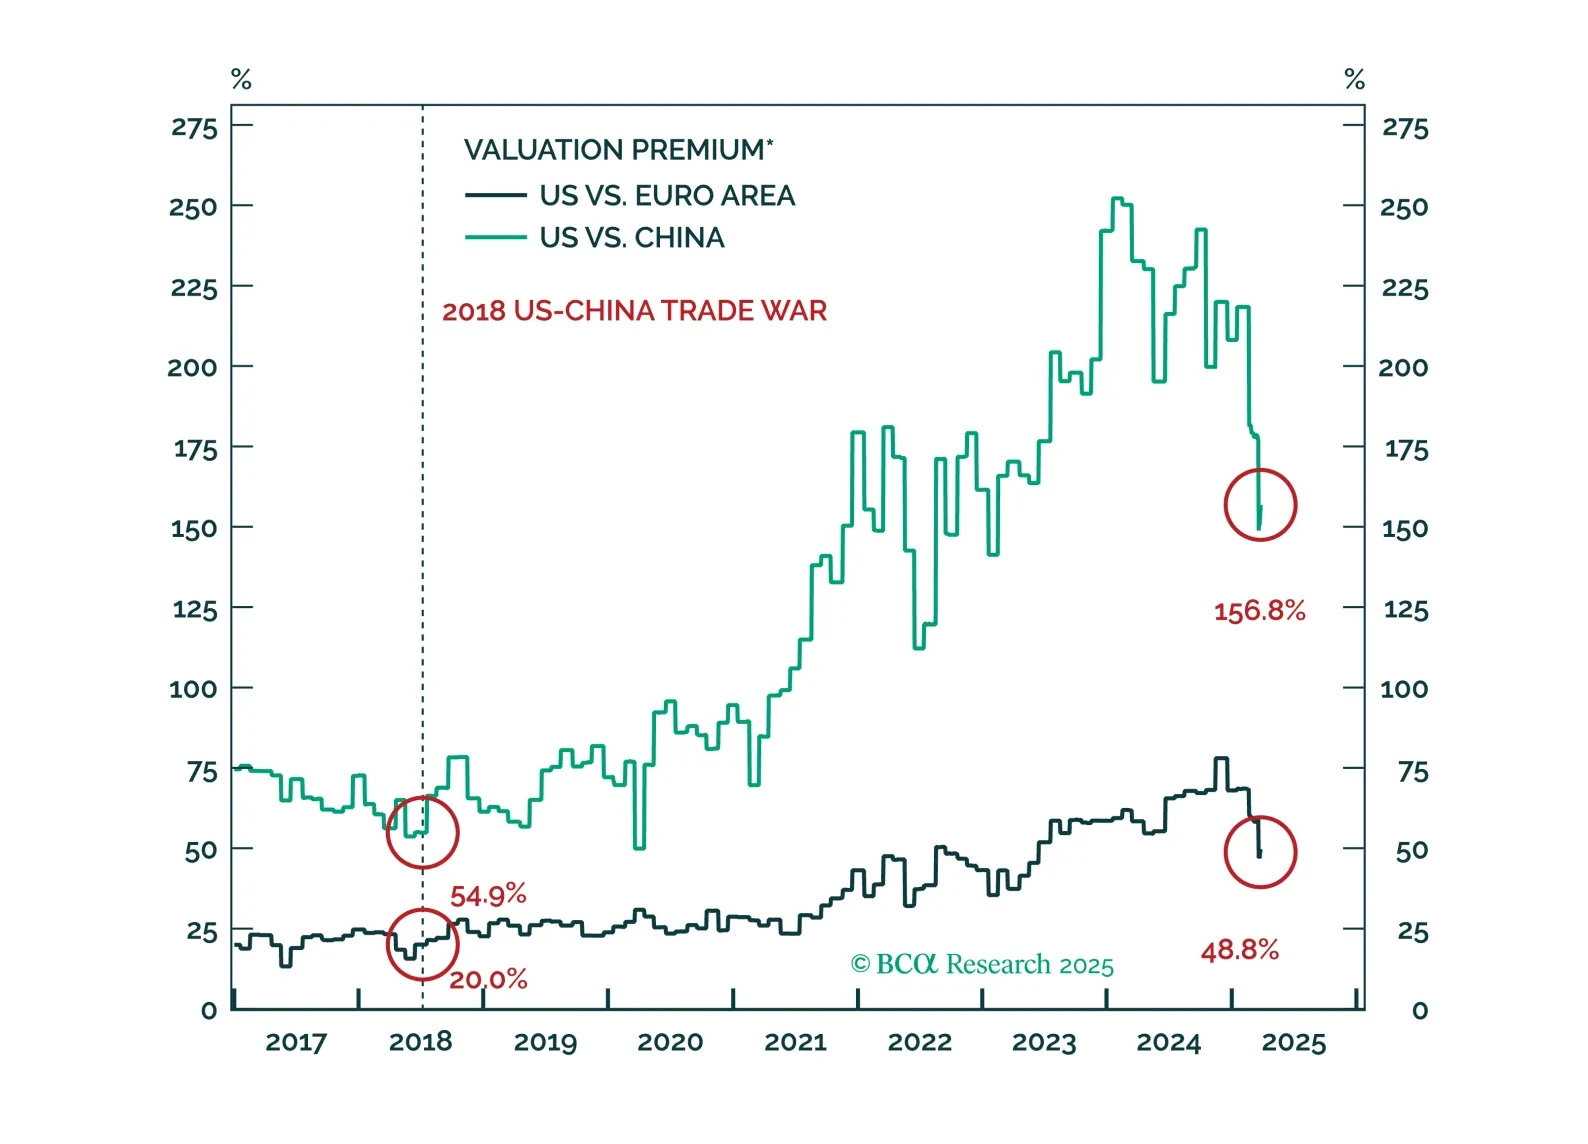
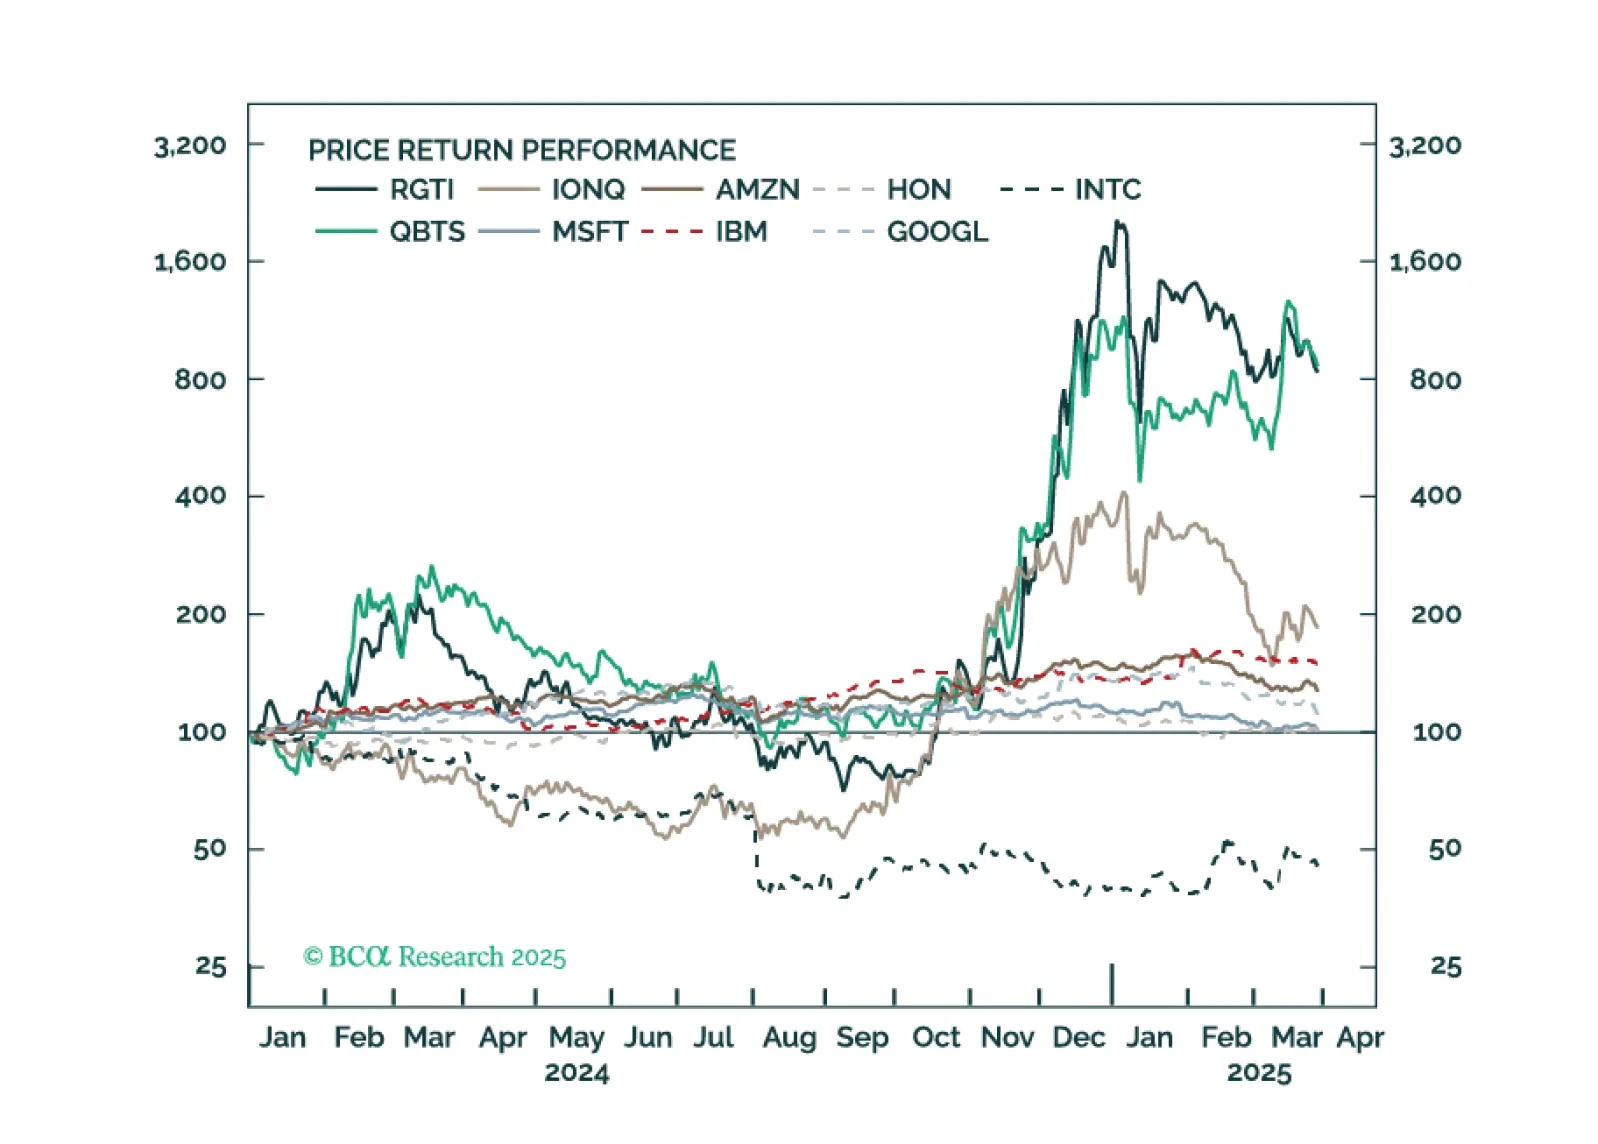
Trump’s foreign policy has been the focus for investors over the past few months. But is it really the underlying cause of the selloff? Market dynamics suggests that tariffs have only been a catalyst. In our view, investors should not focus on the man – Trump and his policy preferences – but should instead focus on the macro. Specifically, we outline three trends that will matter over the cyclical horizon: valuation and policy differences between the US and the rest of the world, the collapse of US animal spirits, and how the AI narrative has begun to crack. While markets could whipsaw around “Liberation Day,” this will only be the opening salvo of the negotiations. We believe that investors will be better served by focusing on these three forces – none of which are positive to risk assets. Remain defensively positioned.

Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.
Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.
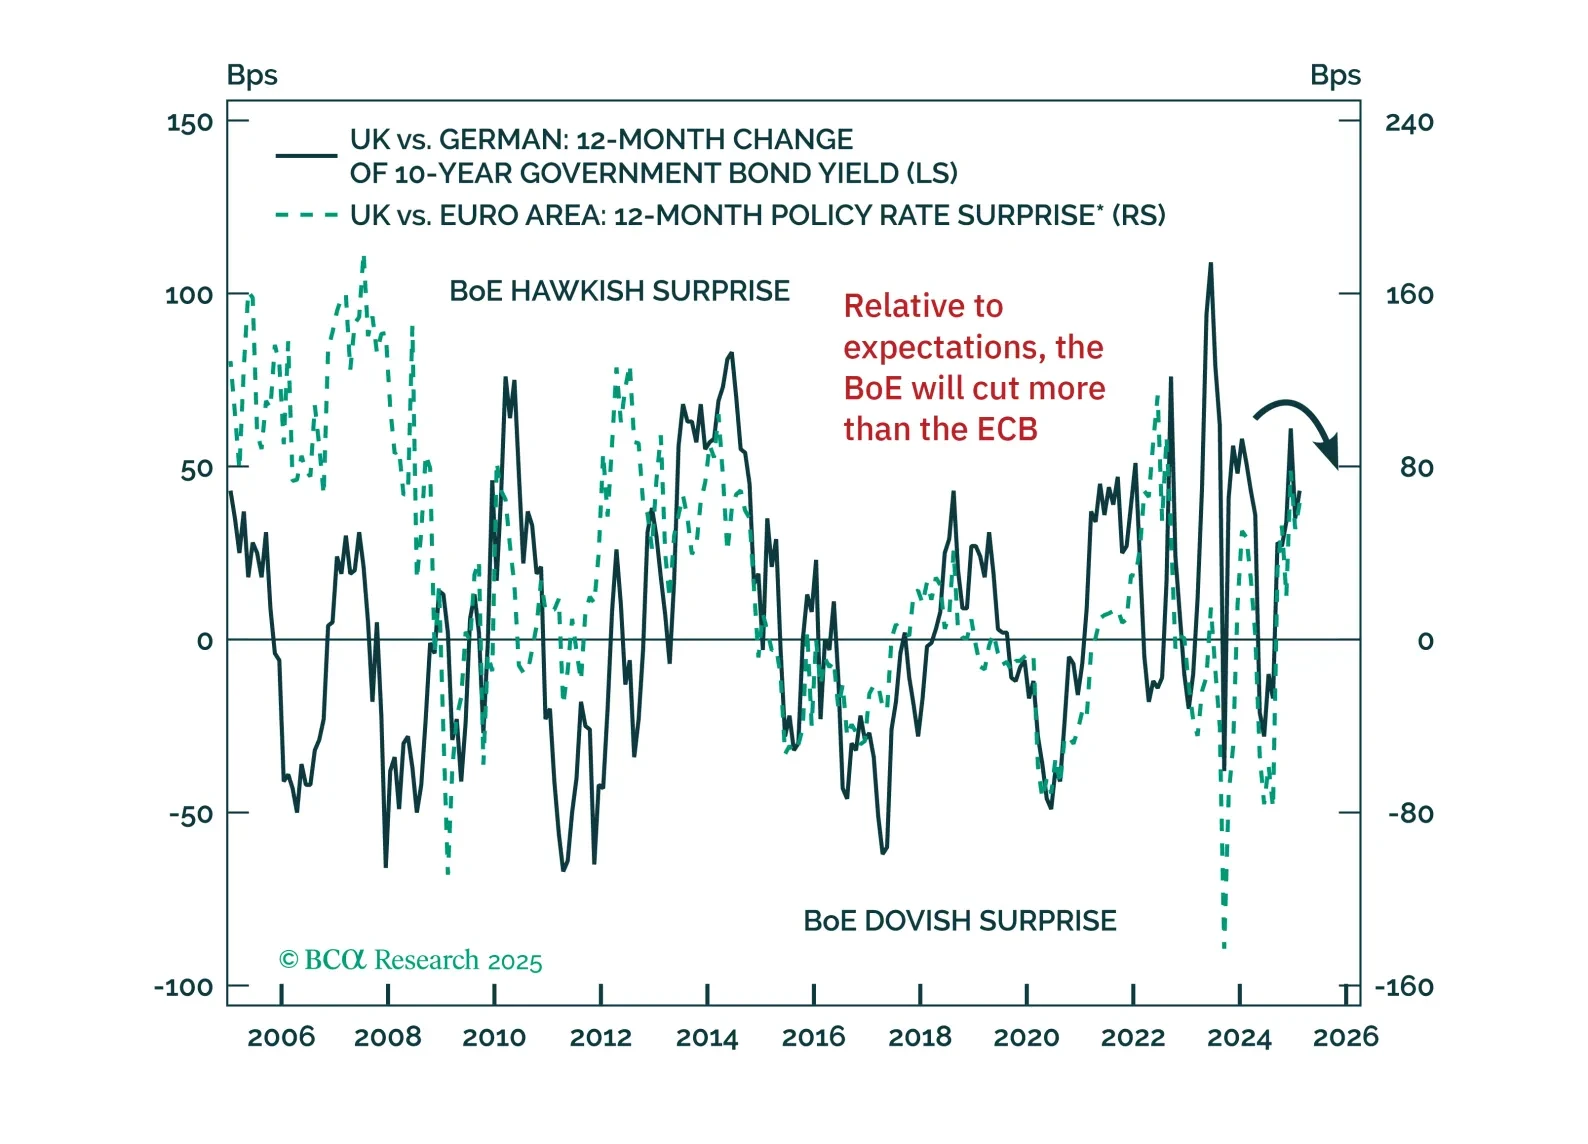
With economic headwinds building and fiscal dynamics shifting, bond markets are at a turning point. Our latest note outlines why German bund yields are set to decline and why UK gilts are poised to outperform — and how to position accordingly.
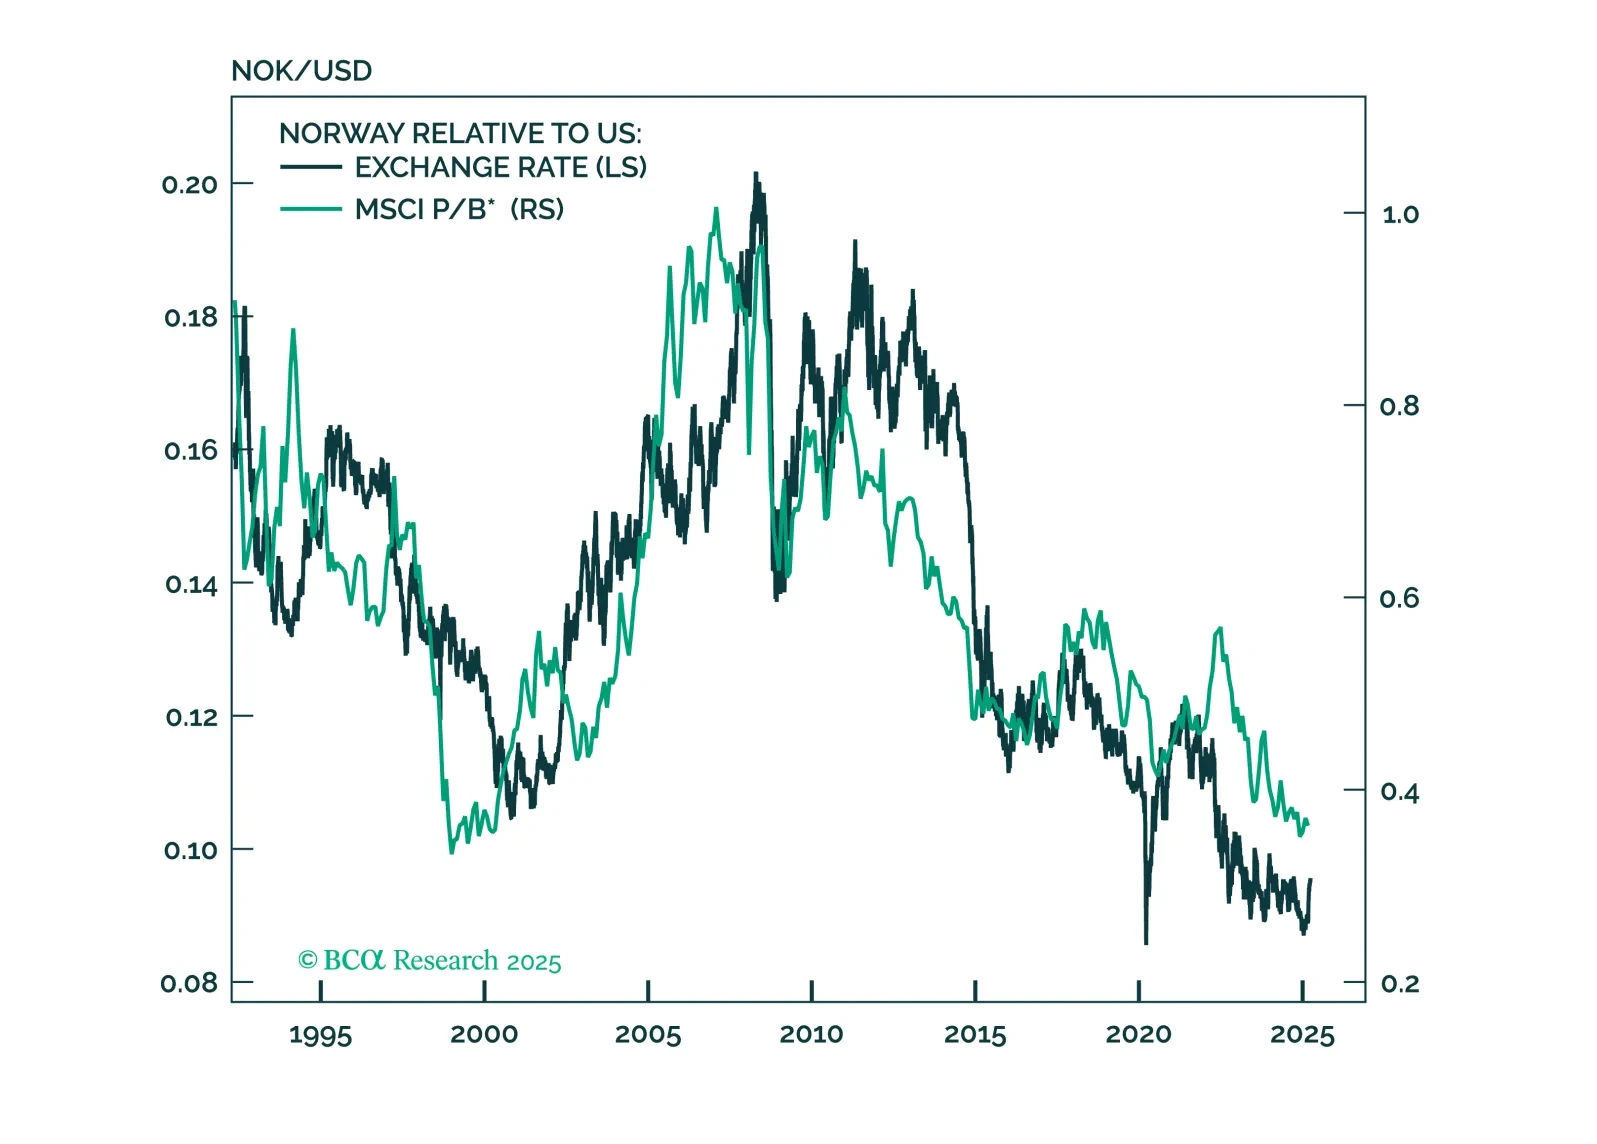
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.