Latest from BCA Research

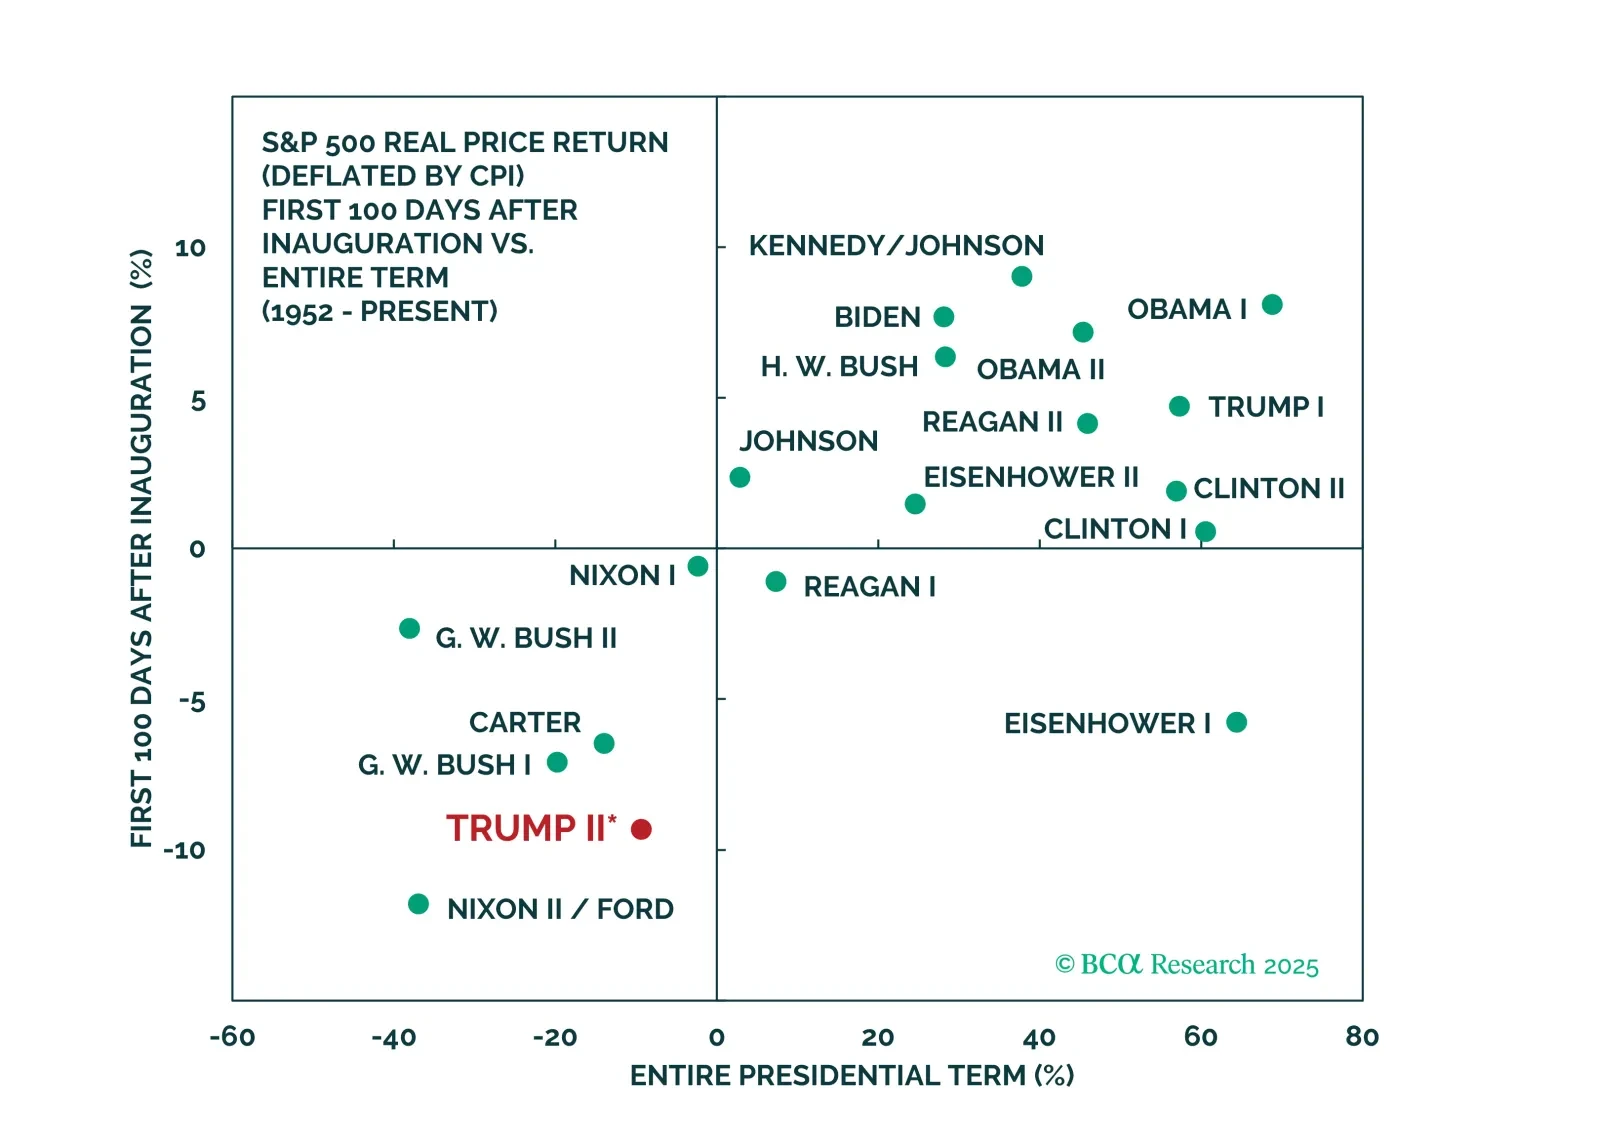
US Treasuries typically outperform both equities and global government bonds during downturns. Recent political shifts could lessen that outperformance this cycle, but we doubt it will disappear completely.
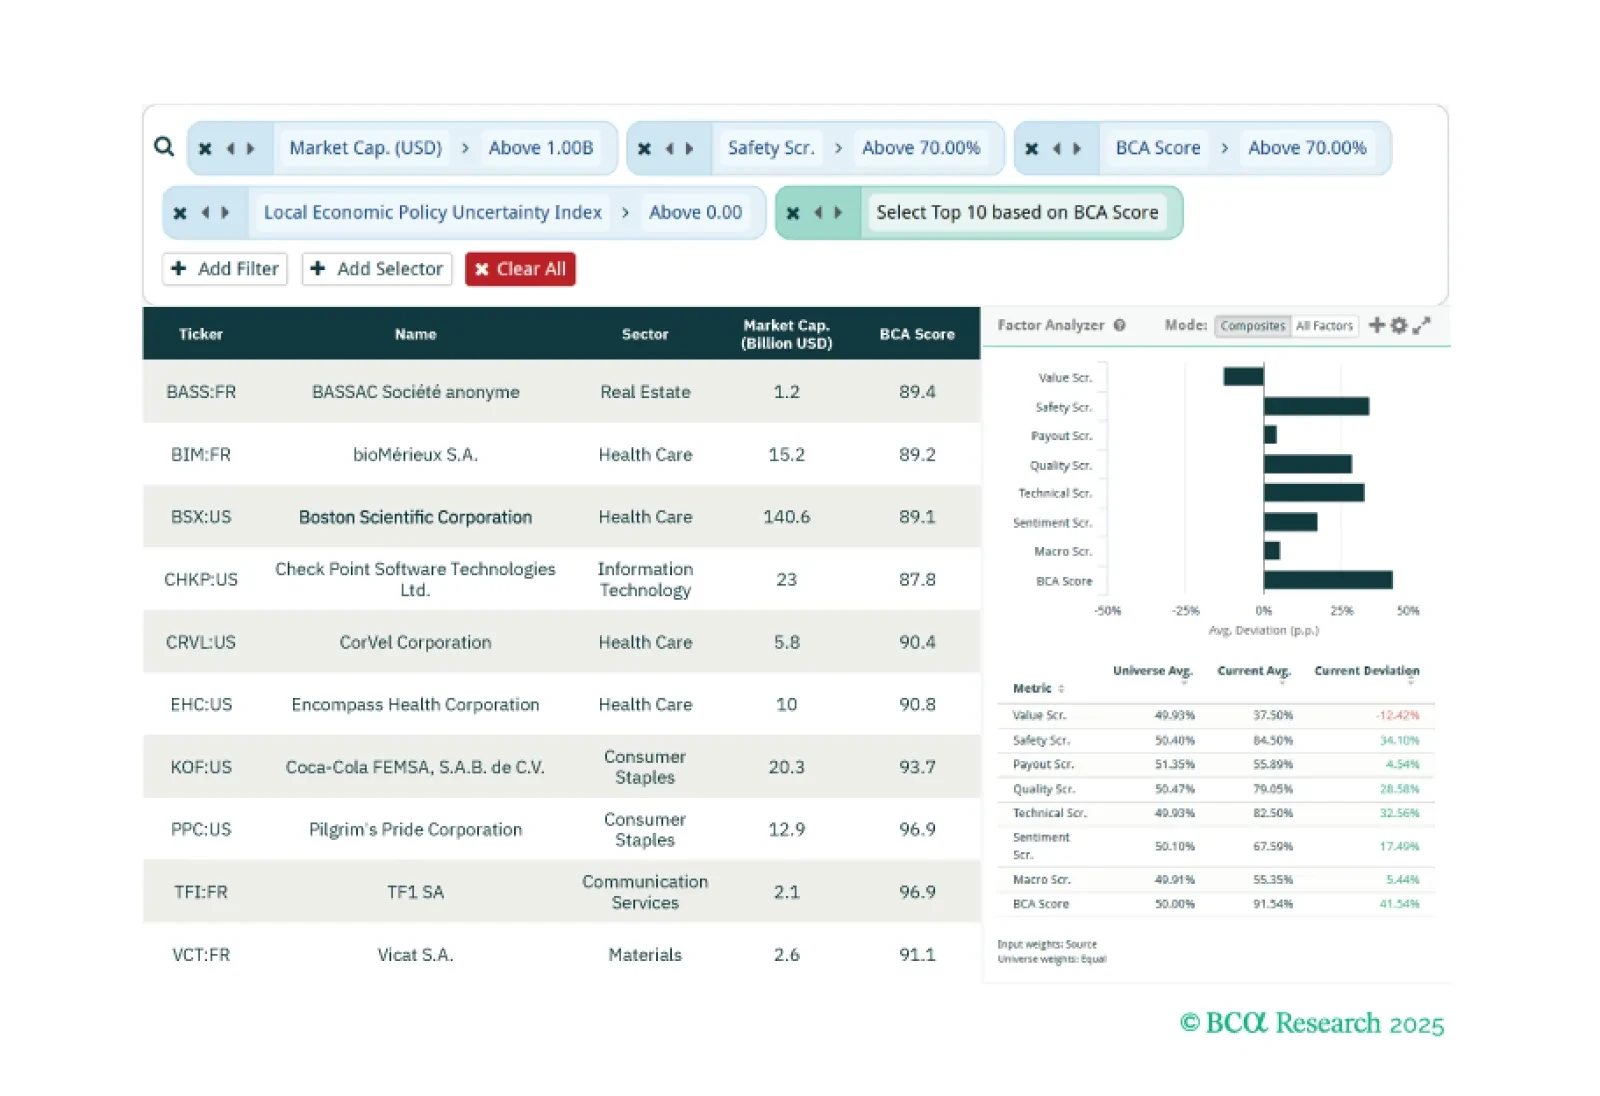
This week, our three screeners all cover equity plays centered around safe stock selection within Equity Analyzer.
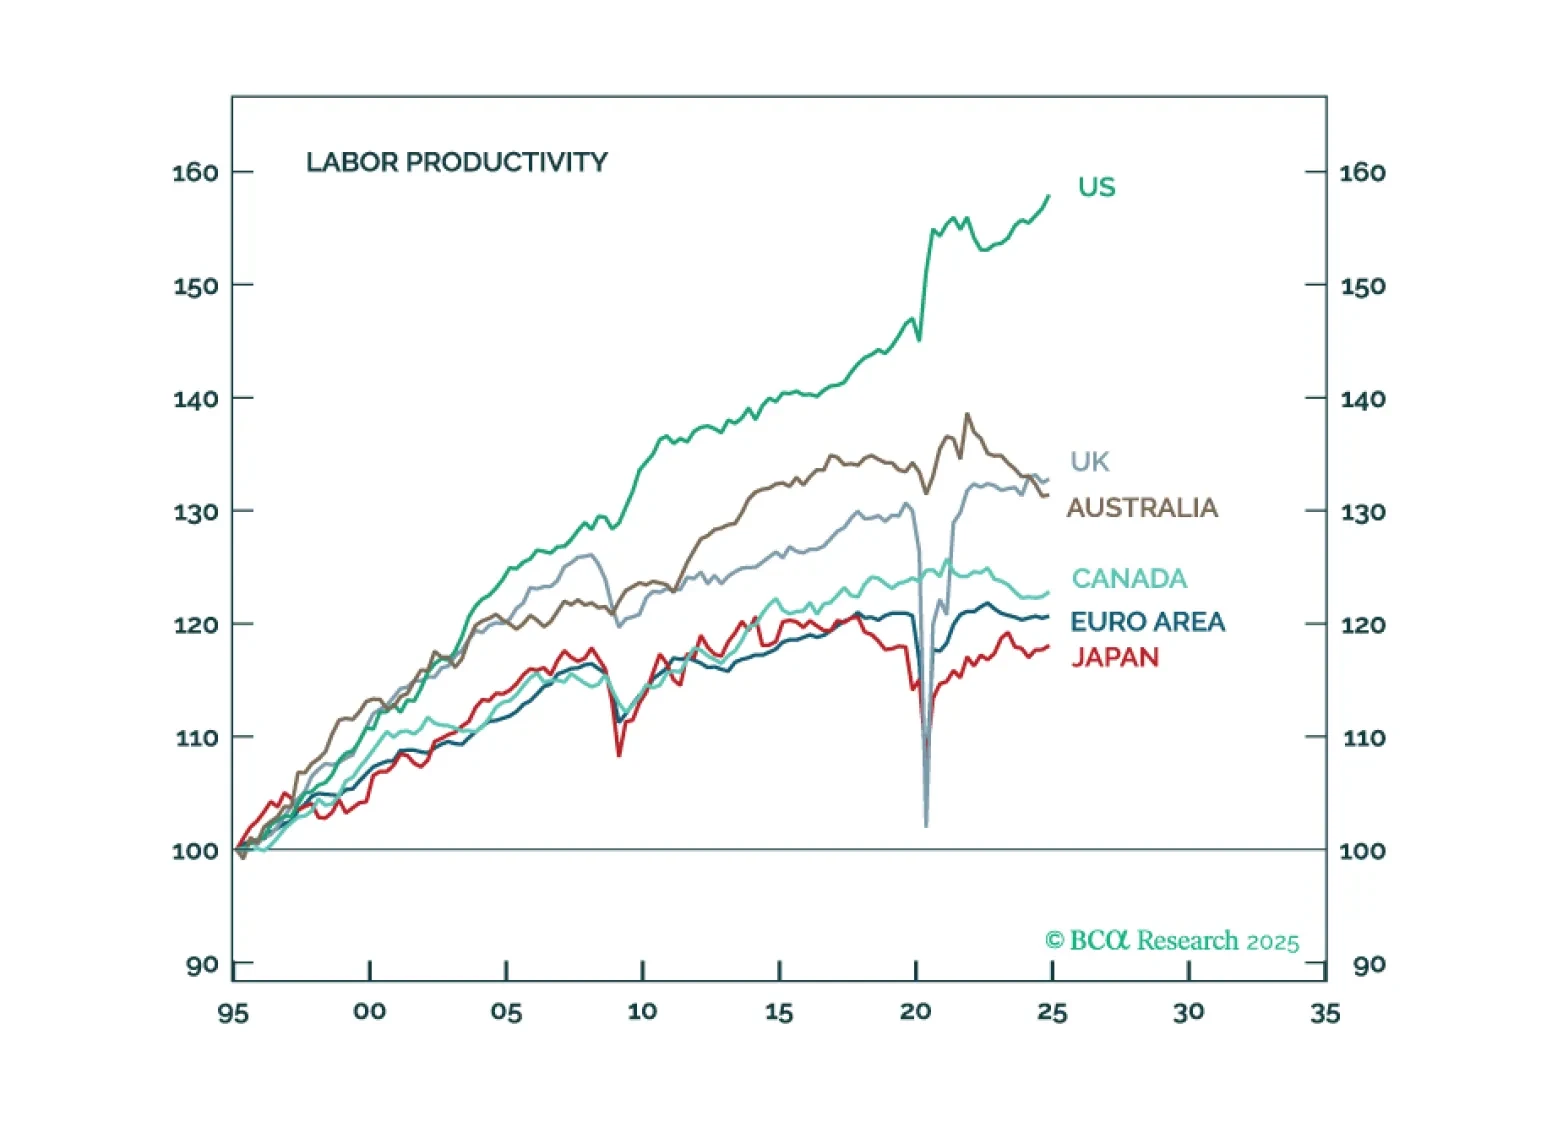
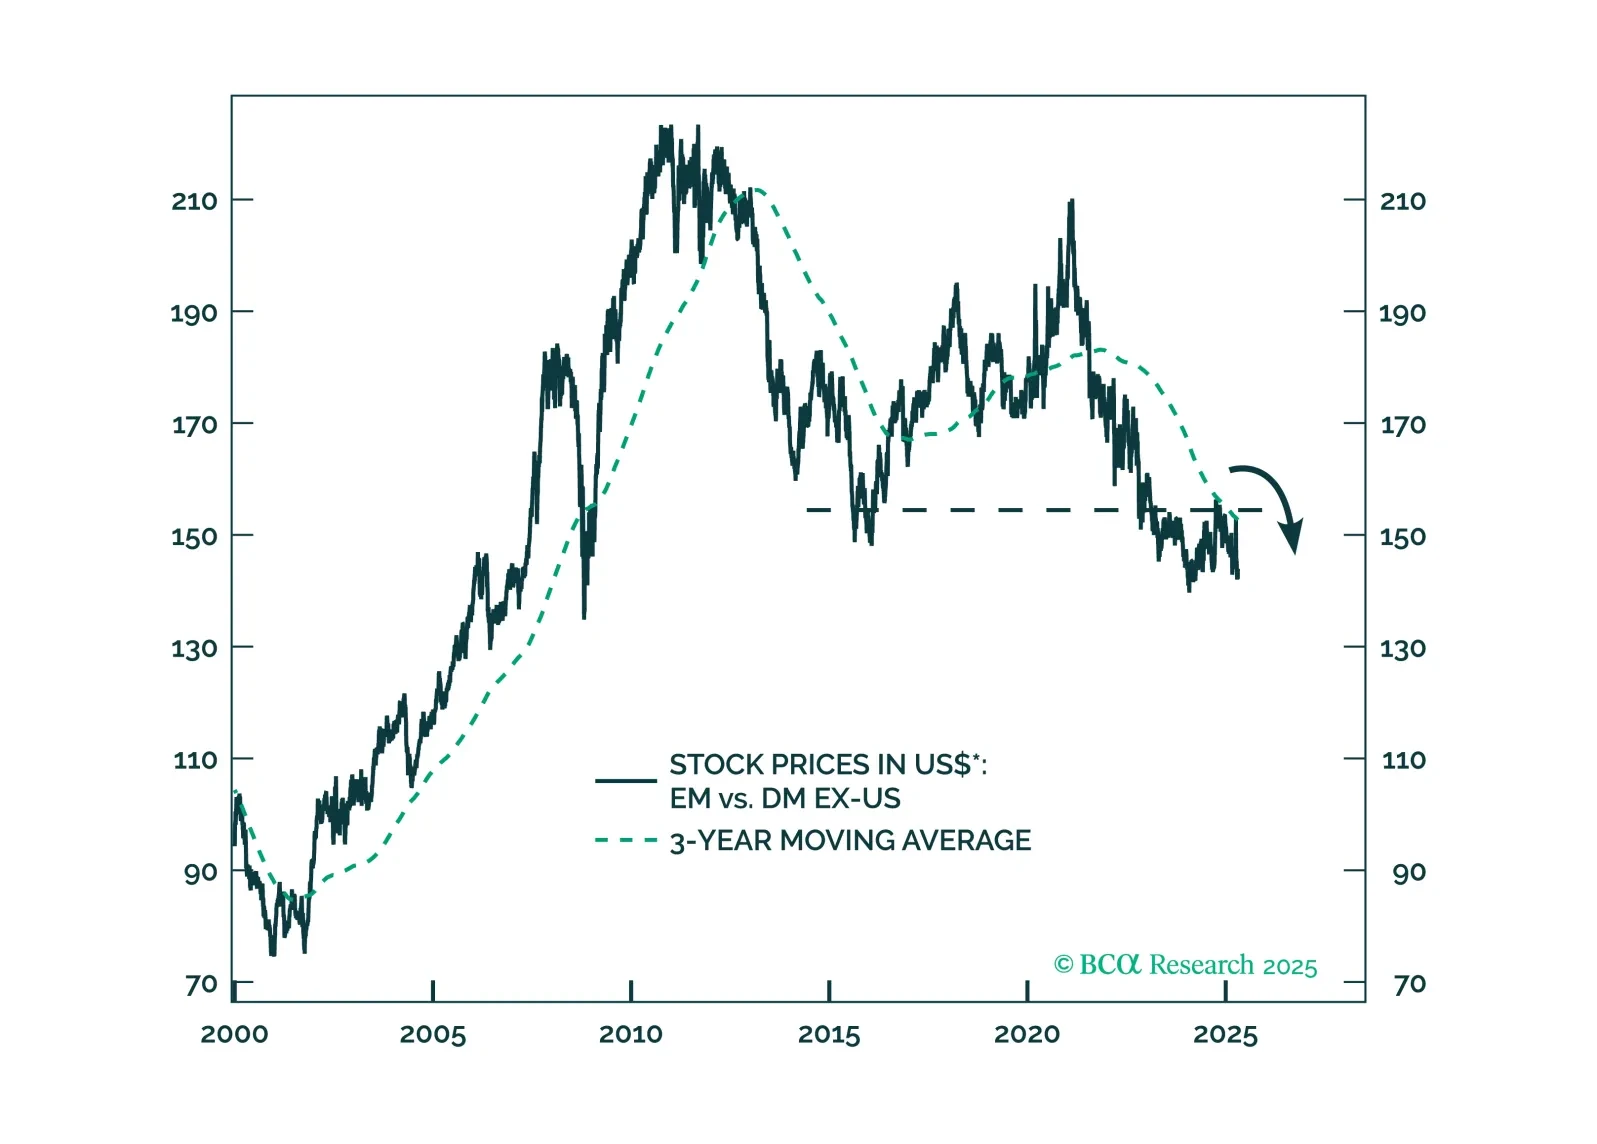
Although the sell-off in the US dollar and relative outperformance of non-US stocks will pause over the coming months as a global recession begins, the fading of US exceptionalism will still cause the dollar to weaken and US stocks to underperform over a multi-year horizon.
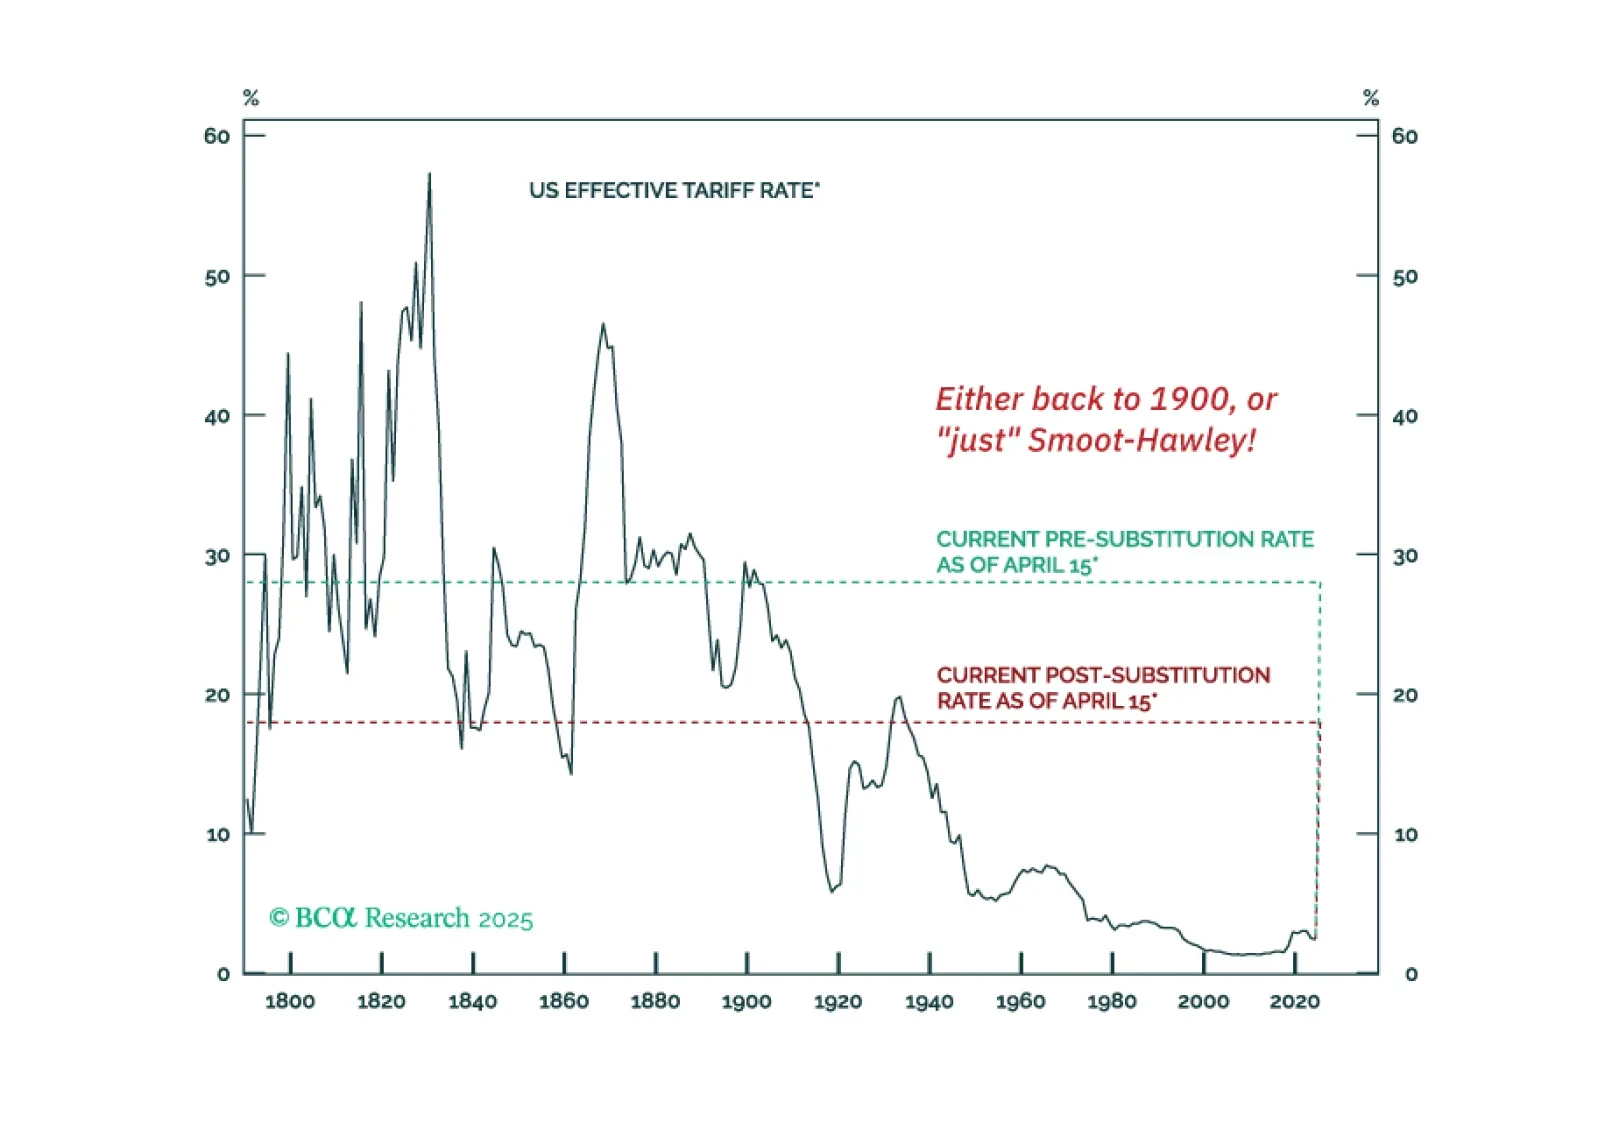
Bessenomics has failed so far. The key pillars of Bessent’s policy mix – achieving lower interest rates and robust economic growth – have been severely jeopardized. The US dollar has depreciated for different reasons than Bessent had envisioned and has pushed up long-term US bond yields. A trade deal between the US and China will likely come too late to preclude a major downshift in global growth.

Amid the storm of global financial uncertainty, Argentina stands out as a free-market safe haven. The lifting of currency controls was the last step taken by this country to embrace market mechanisms. We recommend that investors buy Argentine equities, sovereign credit, and domestic bonds, and overweight Argentina within EM equity and fixed-income portfolios.

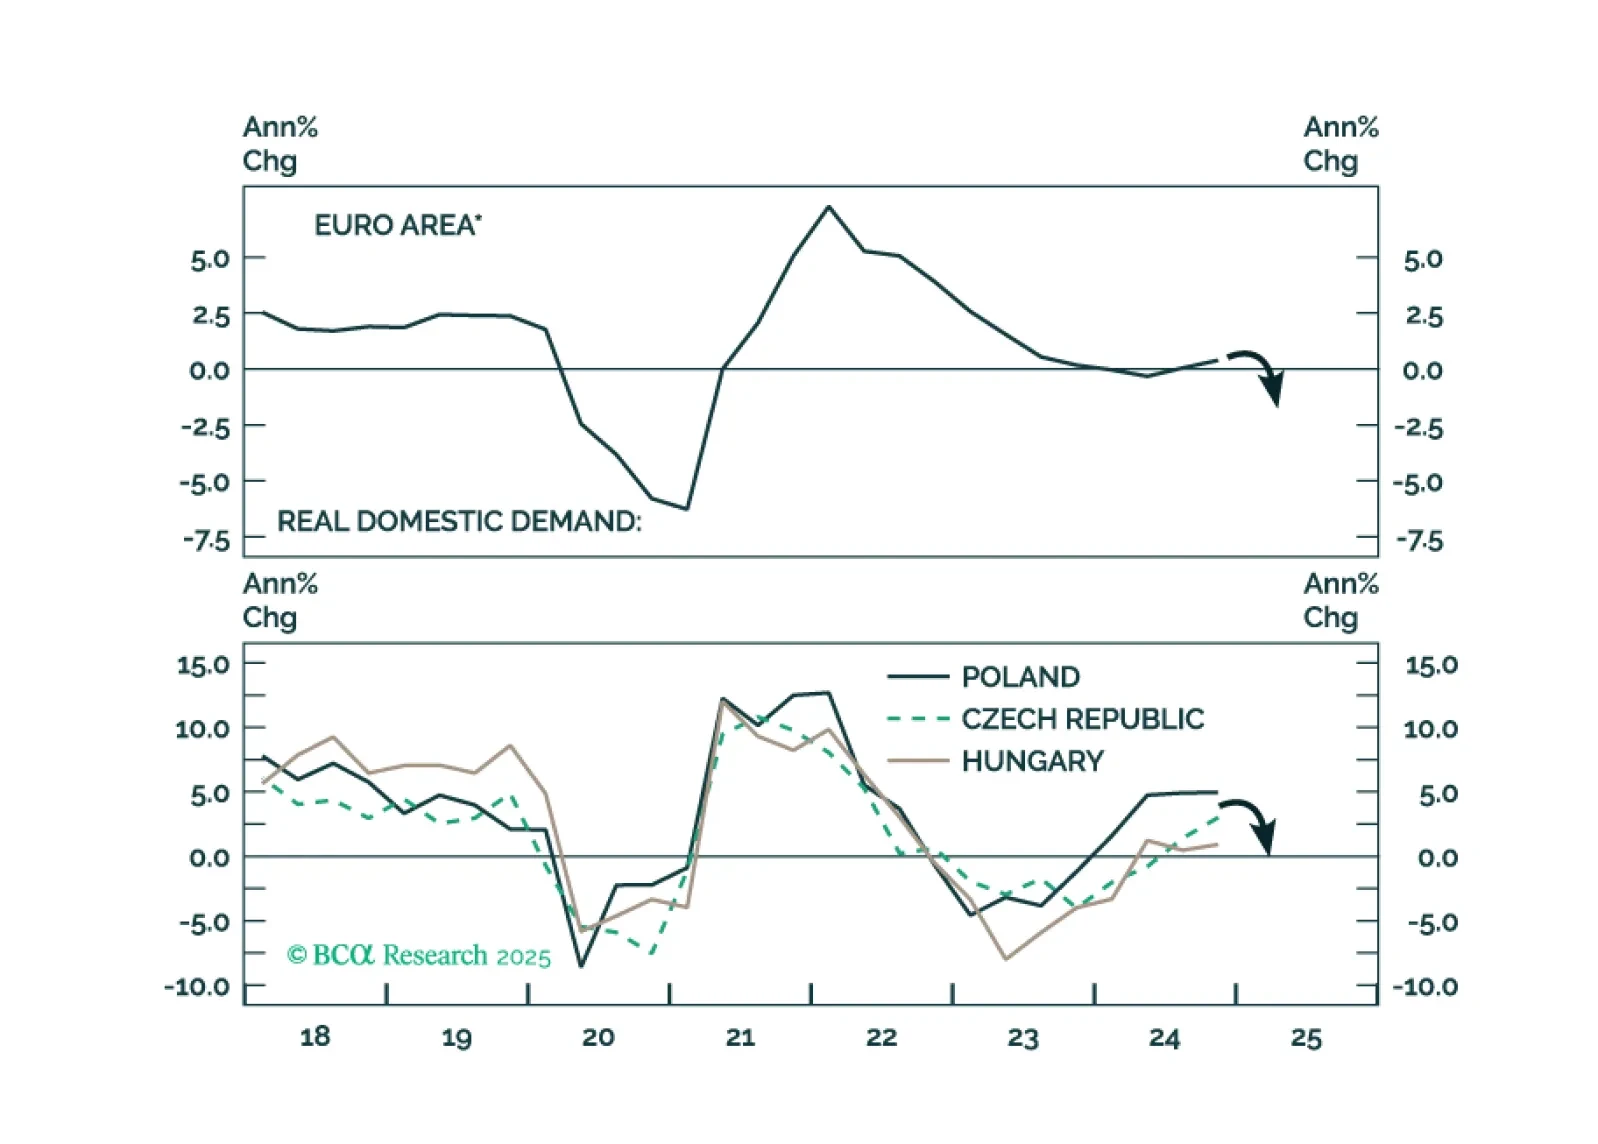
The European economies are facing a major deflationary shock. We recommend that investors stay long a basket of Central European (CE3) domestic bonds. They should also upgrade CE3 bonds and stocks in their respective EM portfolios.