 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
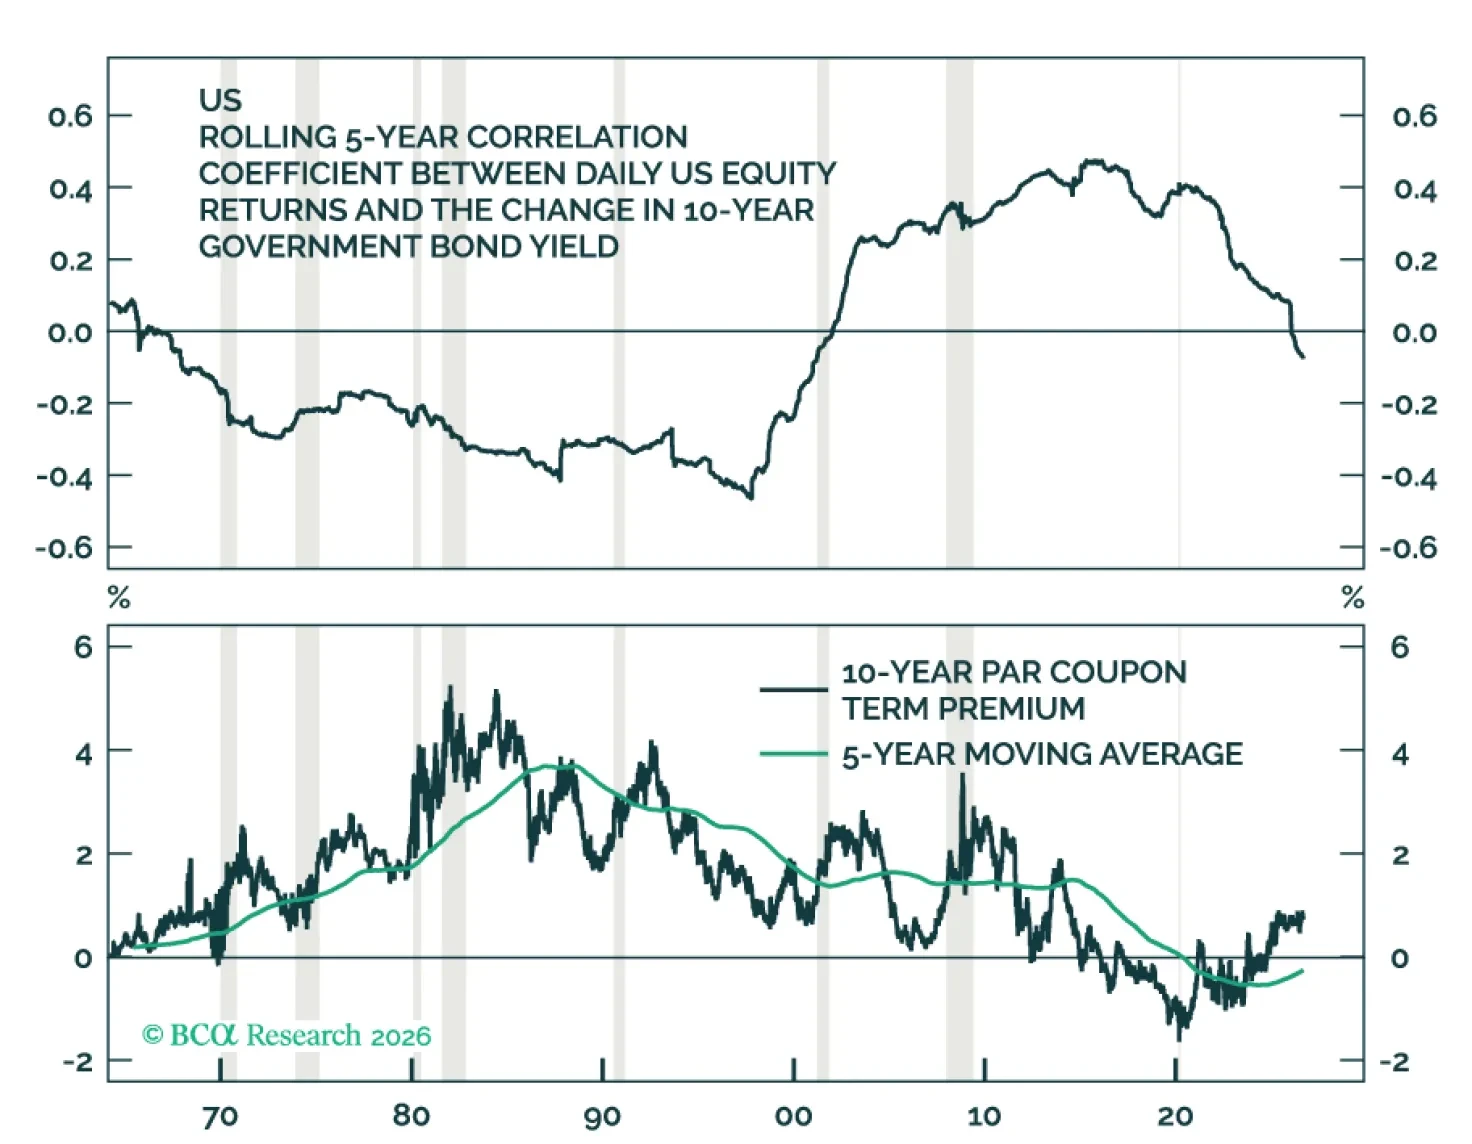
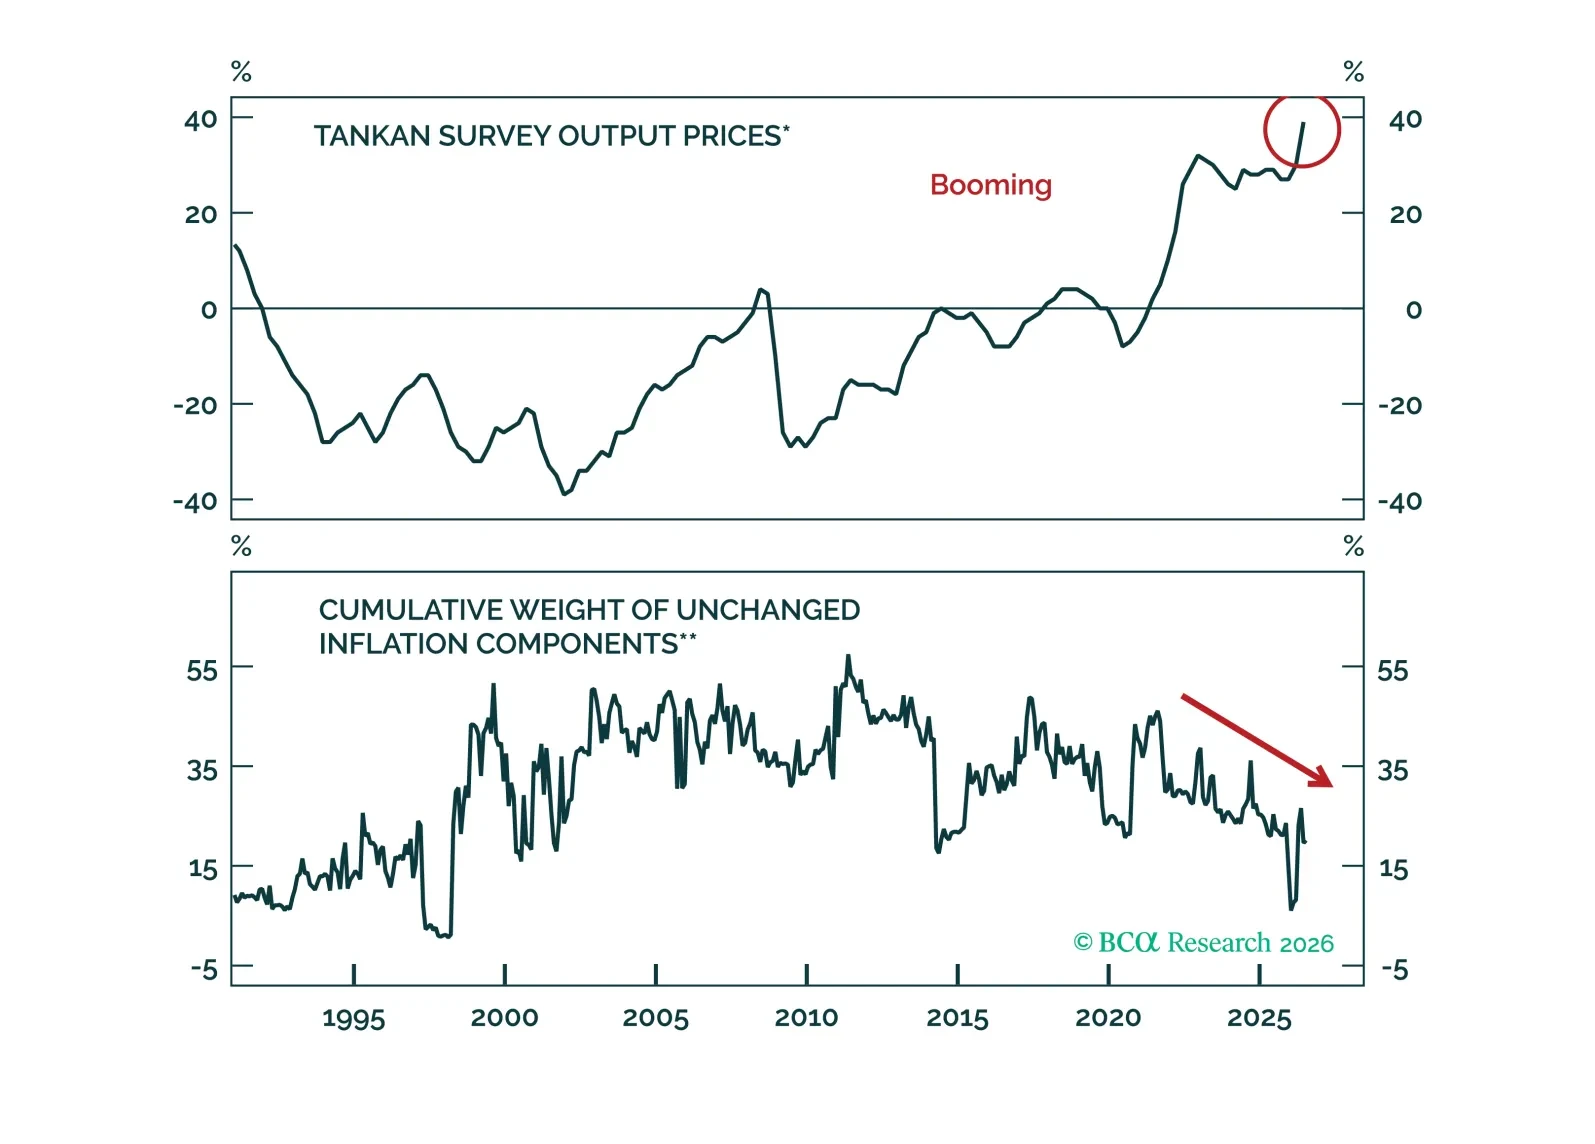
The yen's next leg isn't a fiscal story, it's an inflation one, and the BoJ is about to admit it. We lay out why a September pivot sends USD/JPY toward 99, and why global risk assets won't pay the price.
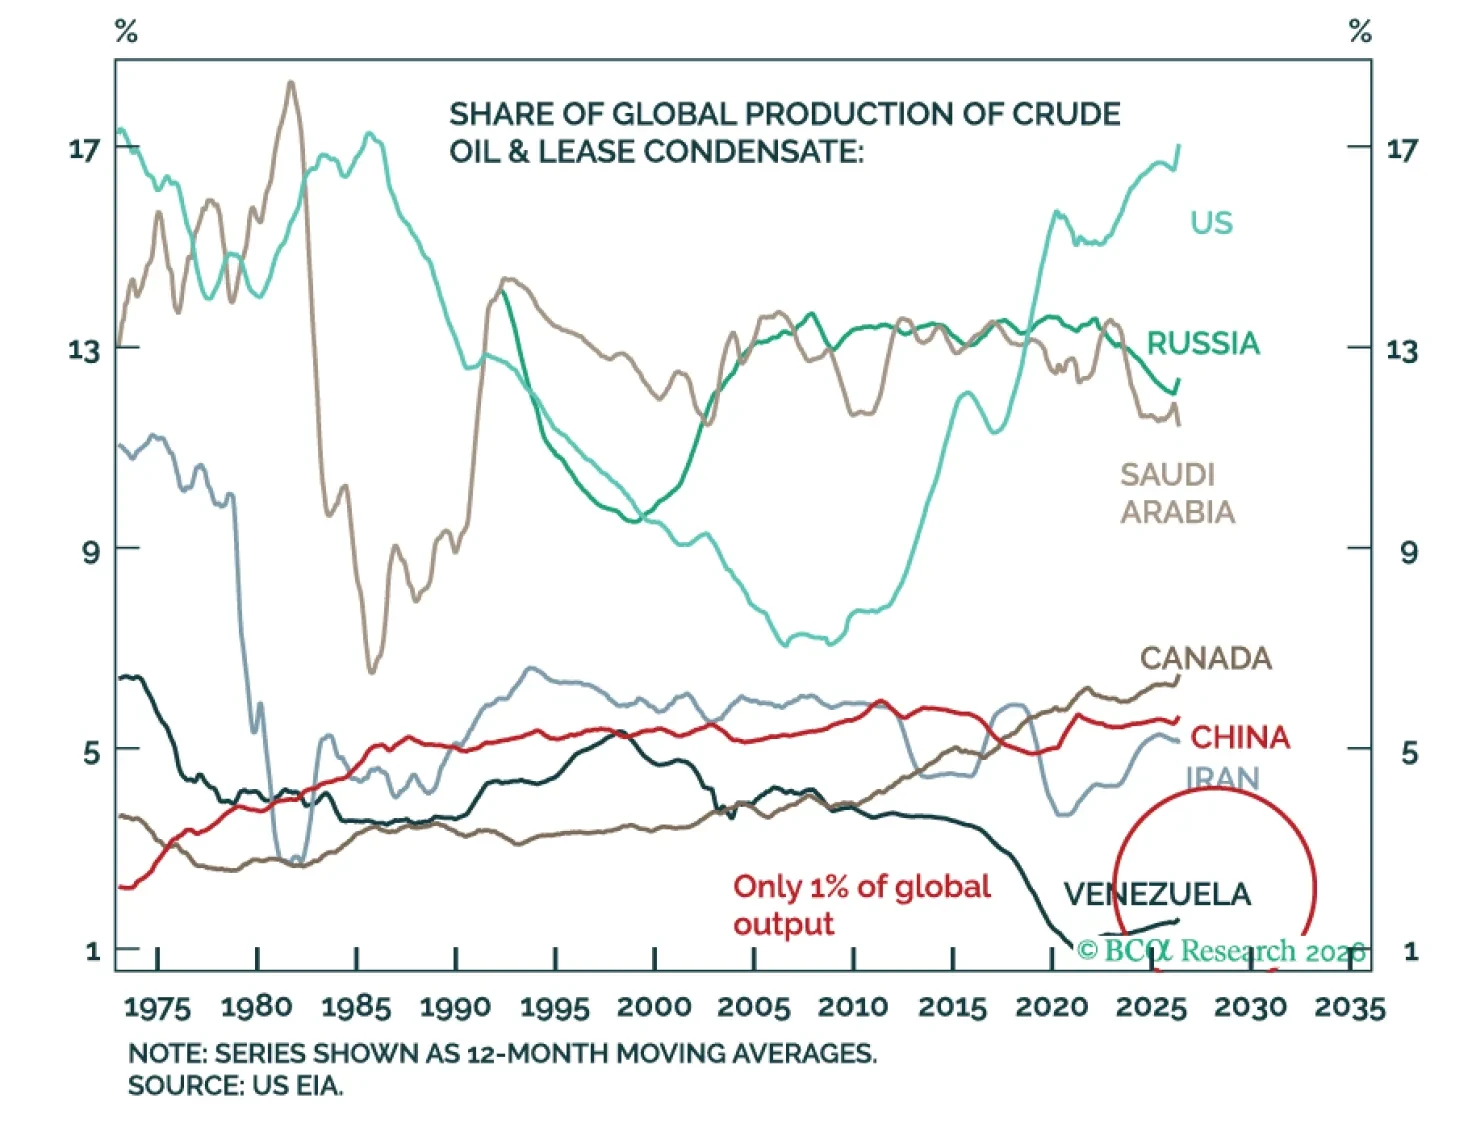
President Trump referred to the US-Venezuela agreement as the “biggest oil deal in world history.” However, oil production growth constraints limit its near-term impact on global crude markets. Instead, Middle East developments will continue to dominate oil’s trajectory over the coming months.
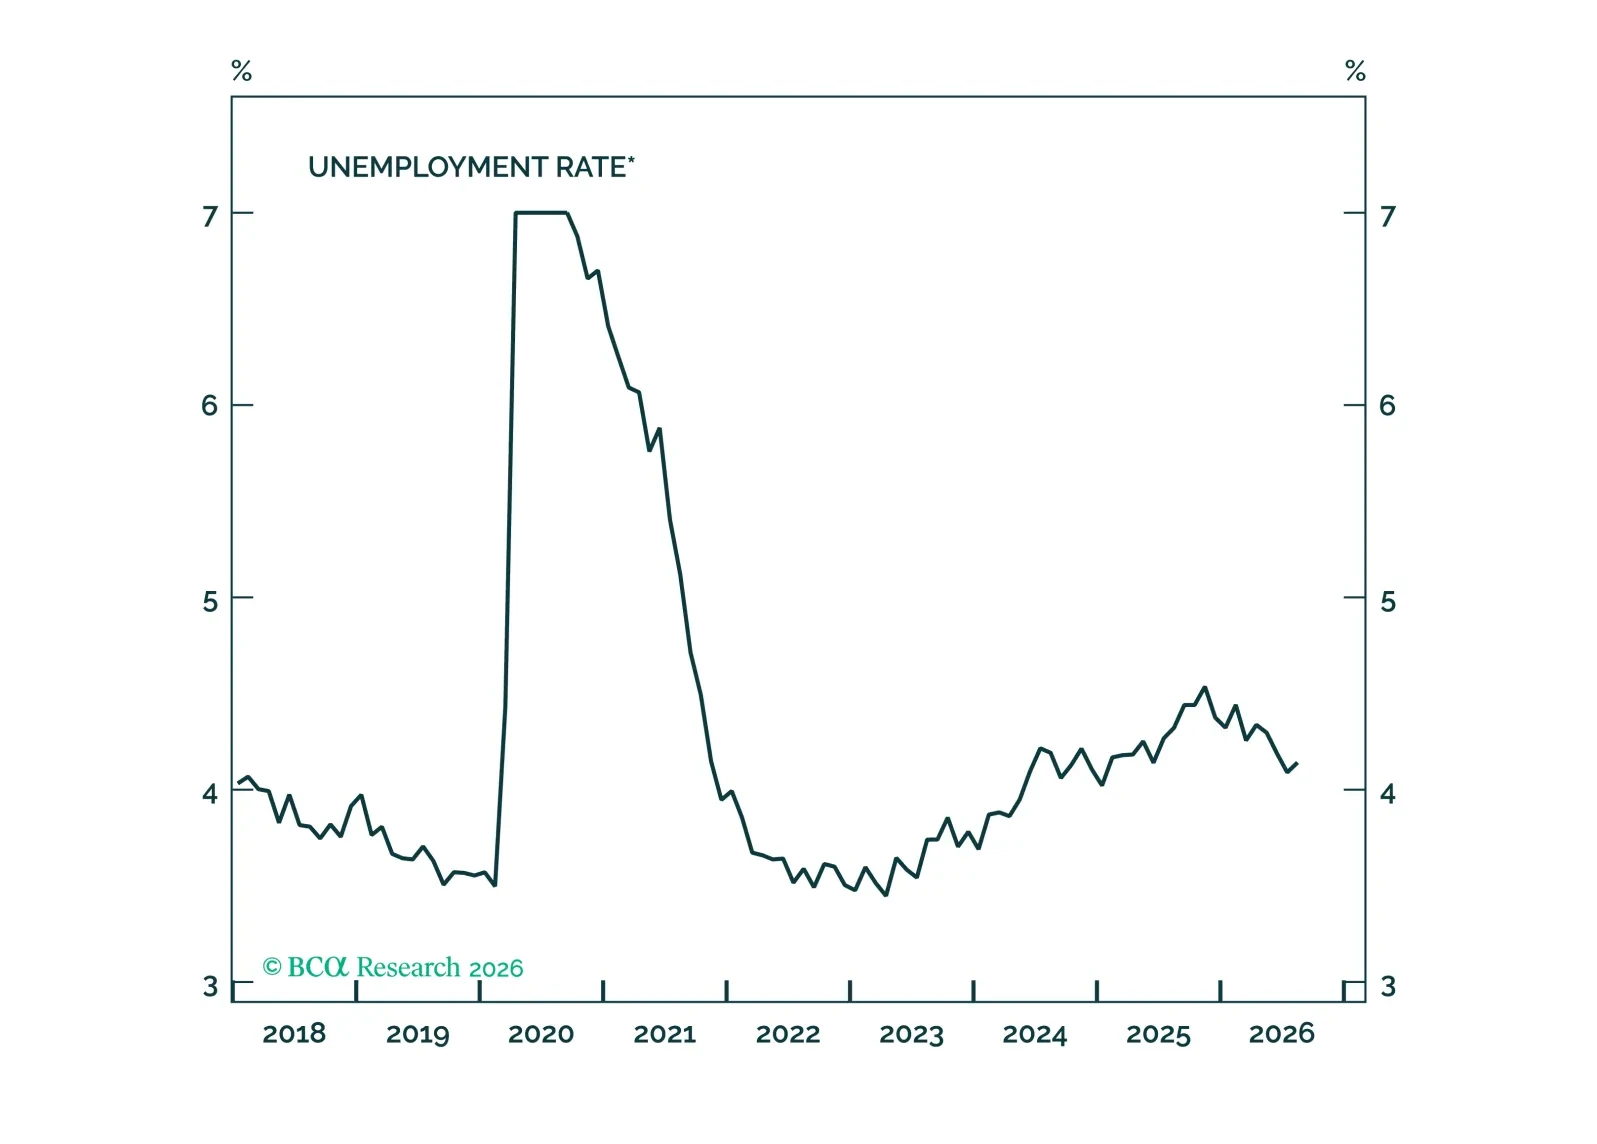
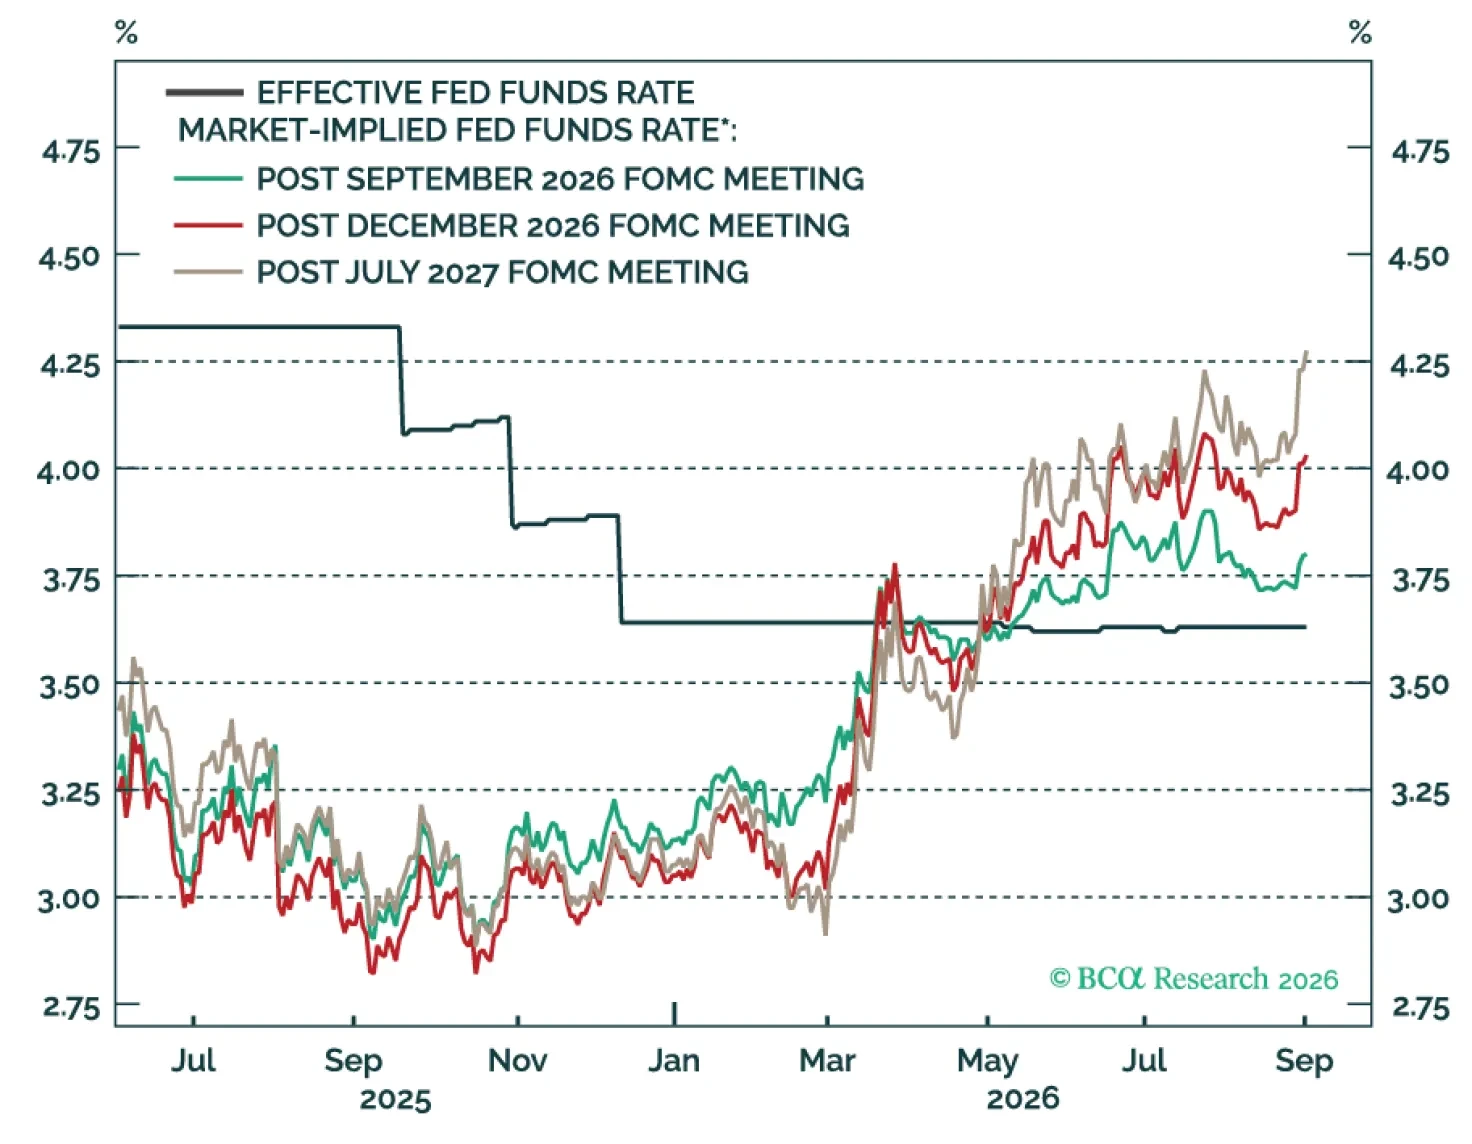
Next week’s CPI and PPI reports will be much more important determinants of the near-term Fed policy path than this morning’s employment report. However, if the trend of labor market tightening continues through year-end, it could lead to a re-acceleration of wage growth in 2027.
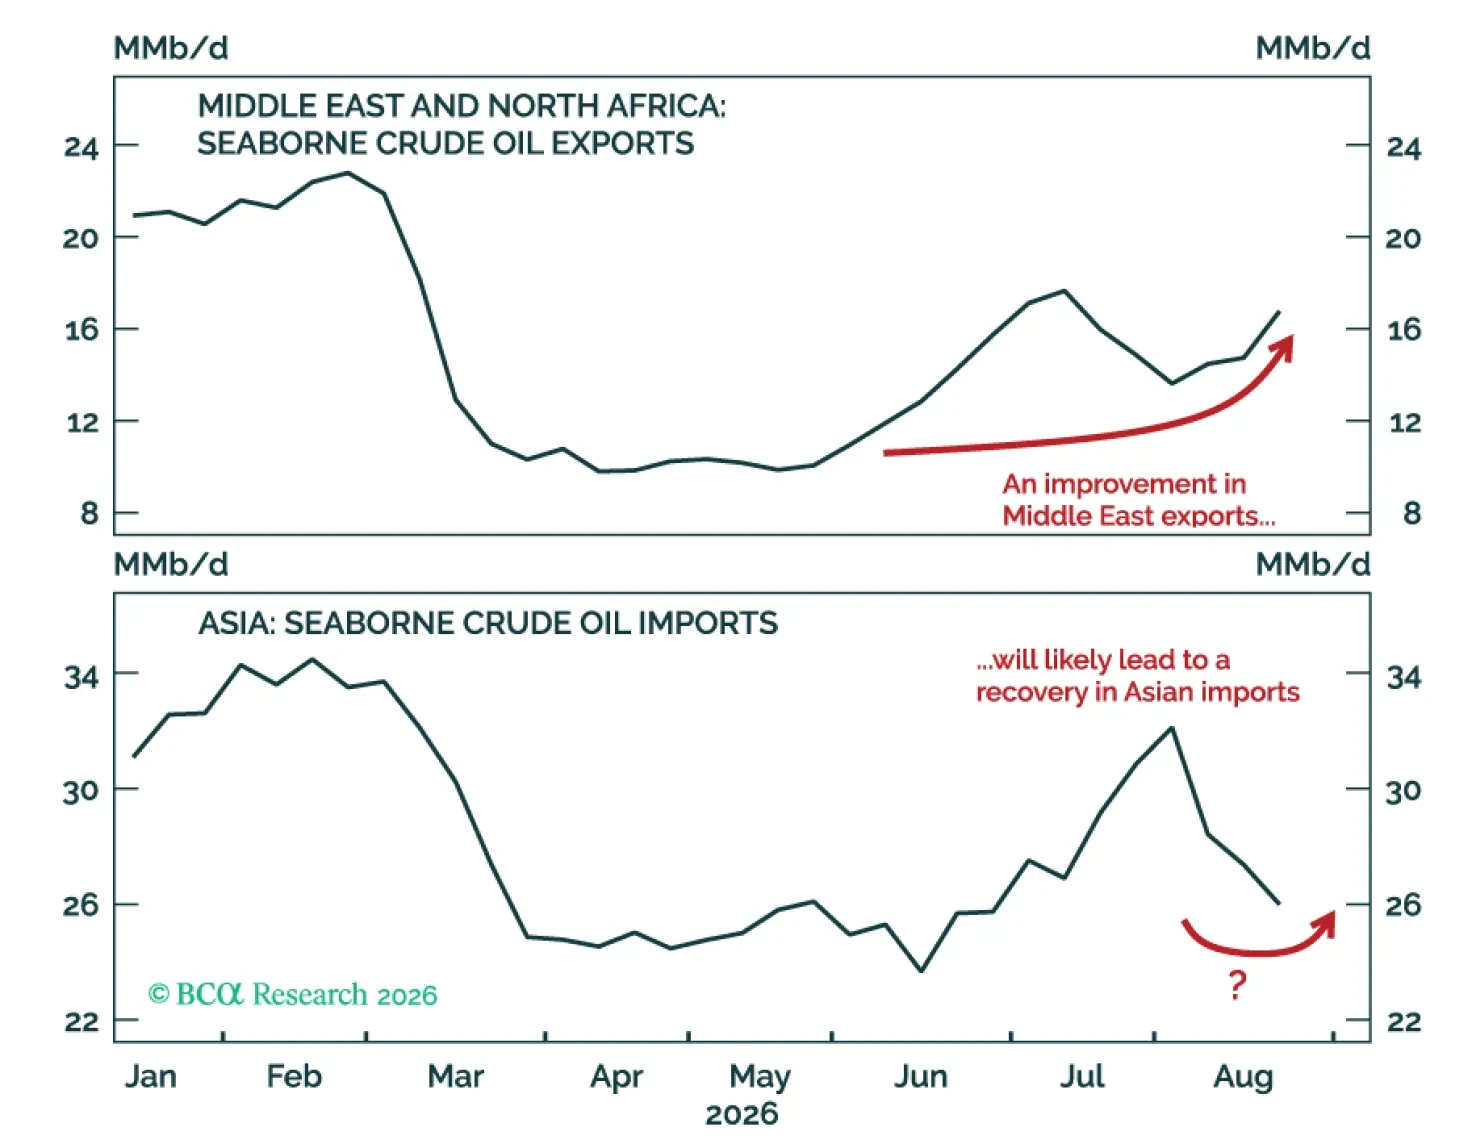
The wide crack spread reflects a bifurcated oil market. The severity of the crude oil disruption has recently softened, while the US-Iran and Ukraine-Russia conflicts have created a perfect storm for refined product markets. Going forward, even though conditions are not yet in place for the crack spread to return to its pre-conflict level, it is likely to narrow over the coming months.
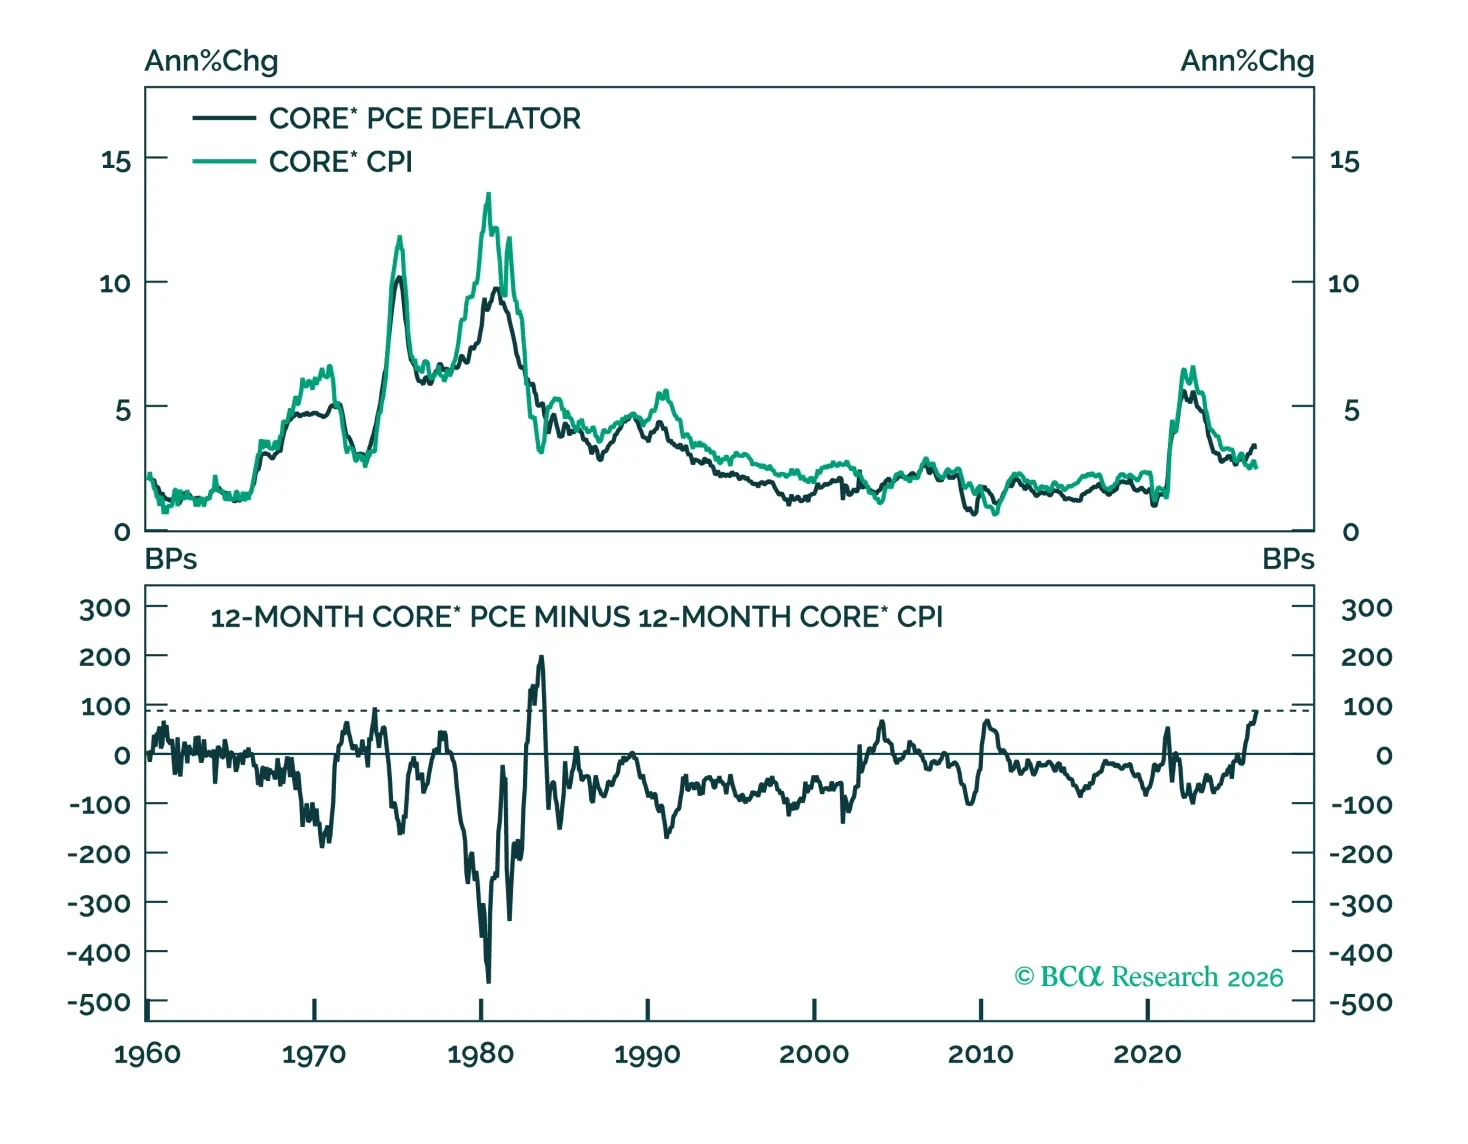
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months.
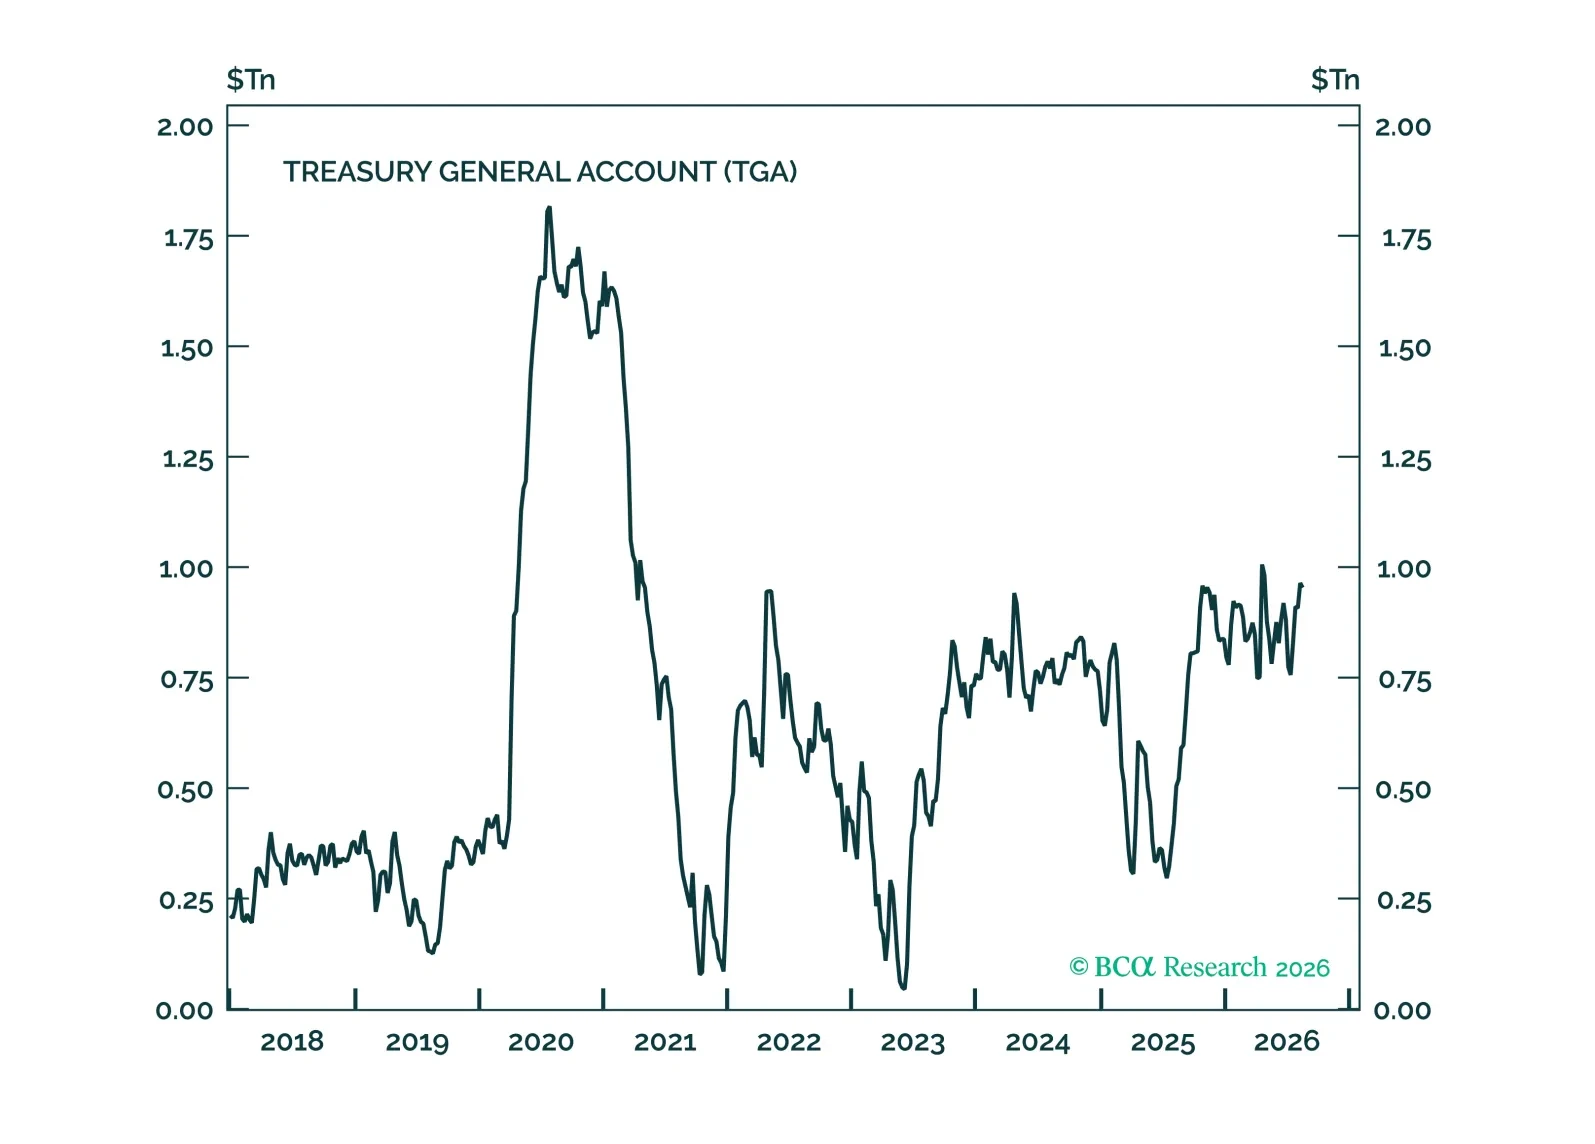
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.
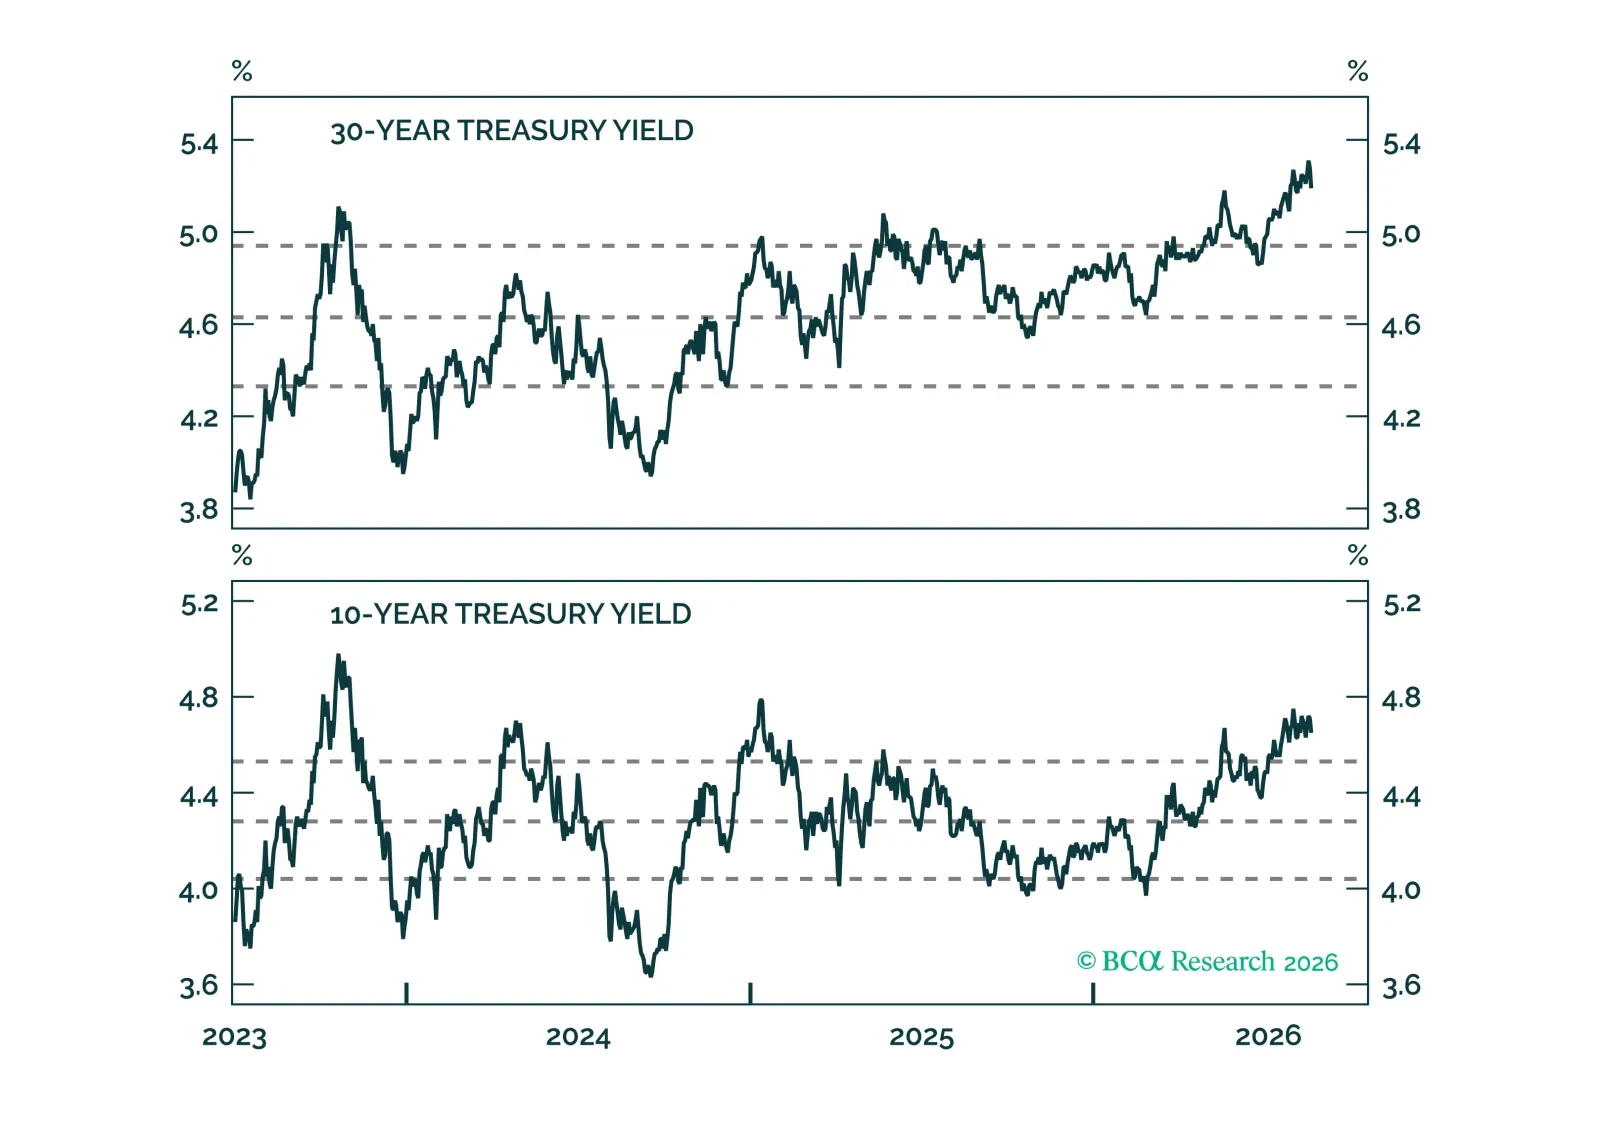
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
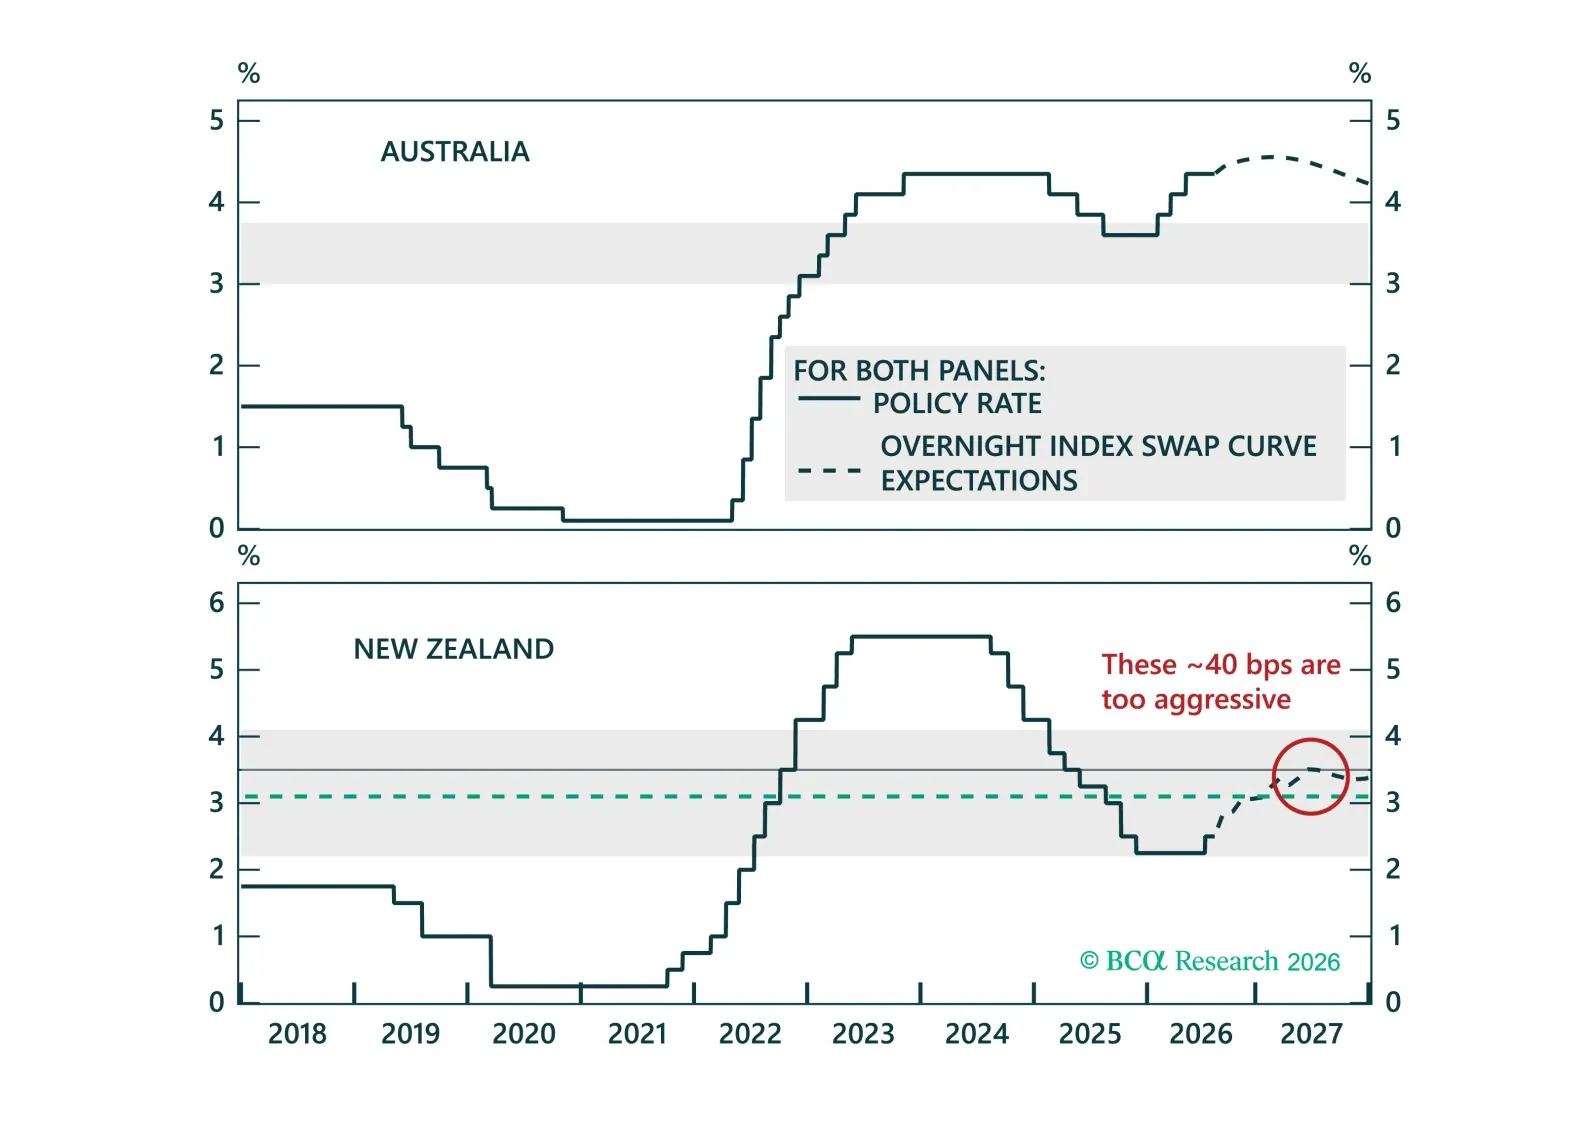
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view.