 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
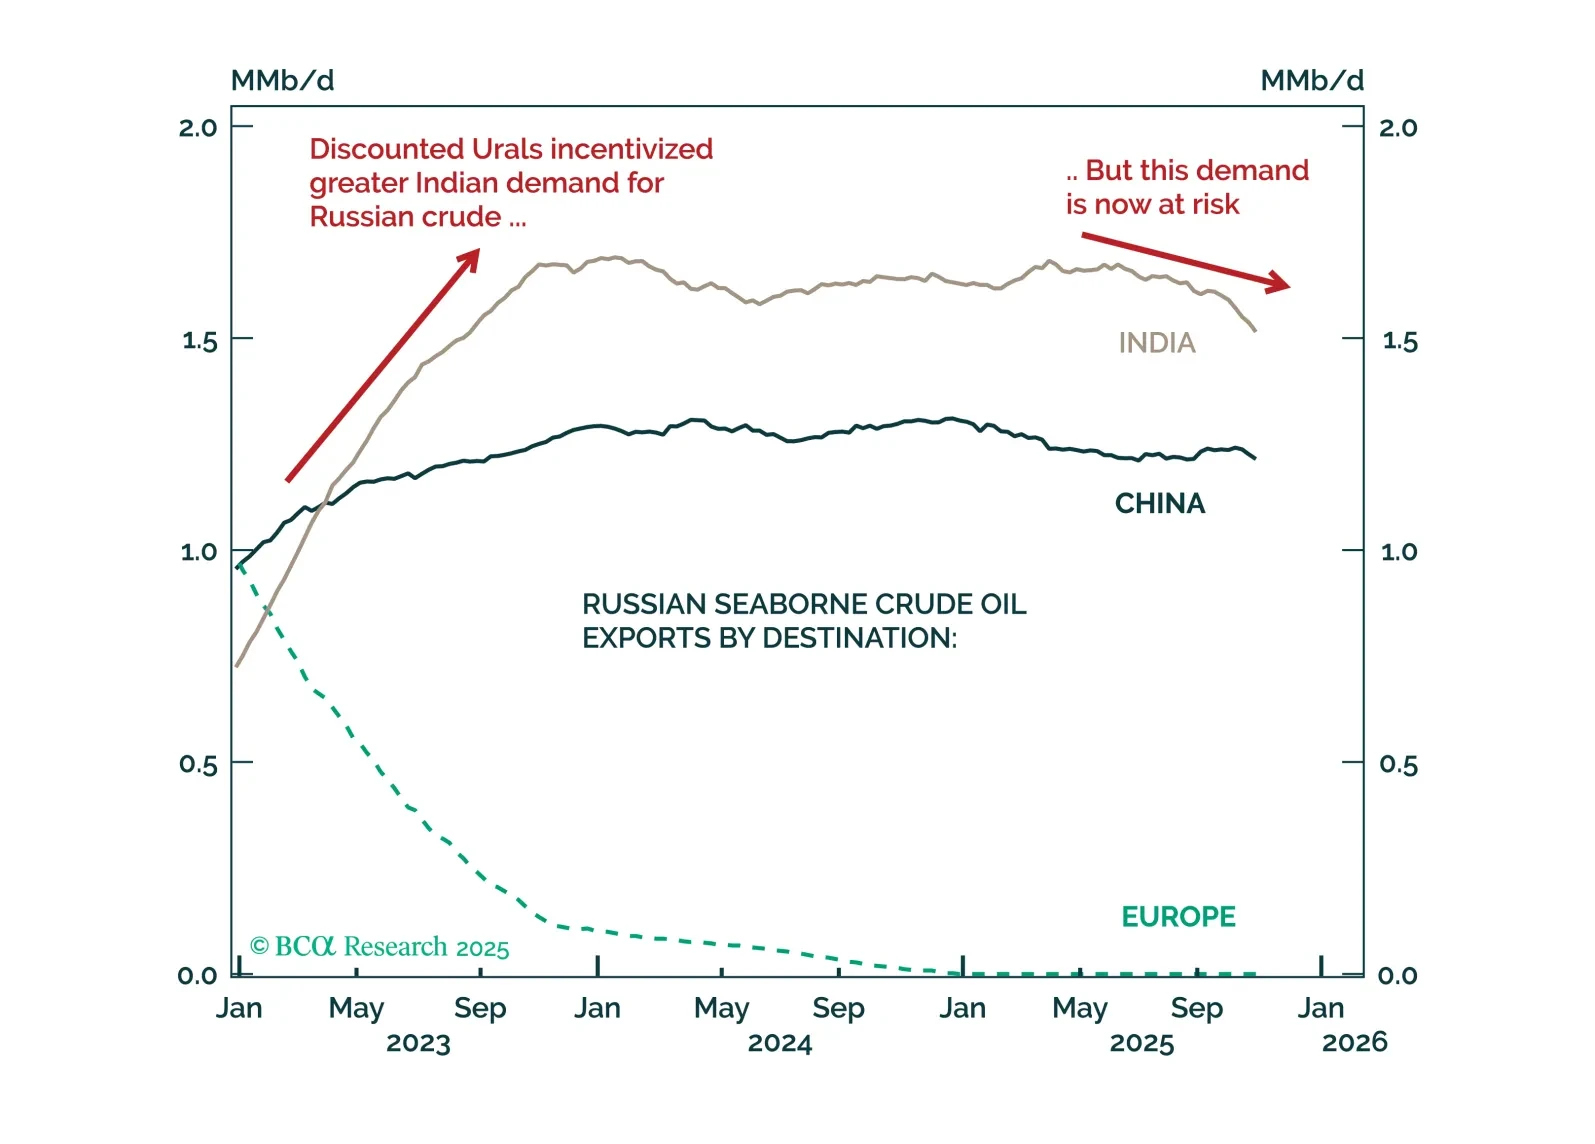
US restrictions on Russian crude exports could disrupt global oil supplies and trade flows over the near term. However, they are unlikely to have a meaningful impact on crude prices over a cyclical timeframe. Stay short Brent.
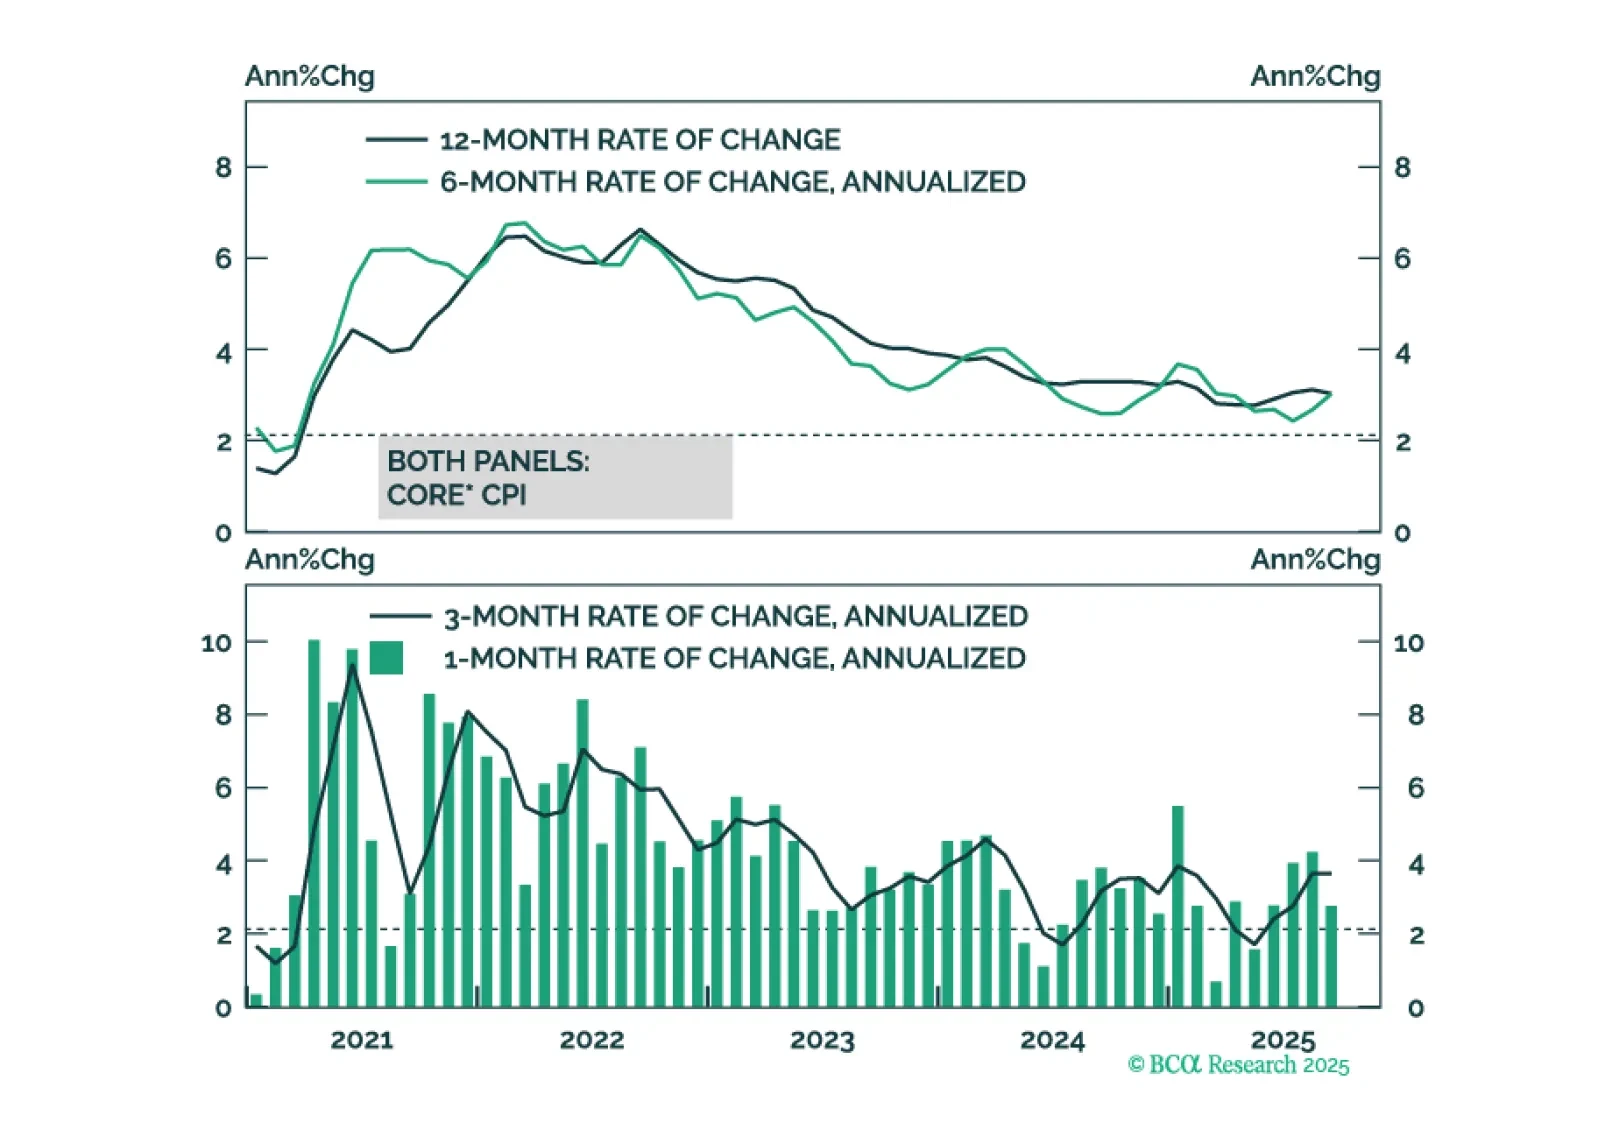
US inflation data continue to show no signs of price pressures beyond a near-term tariff effect.
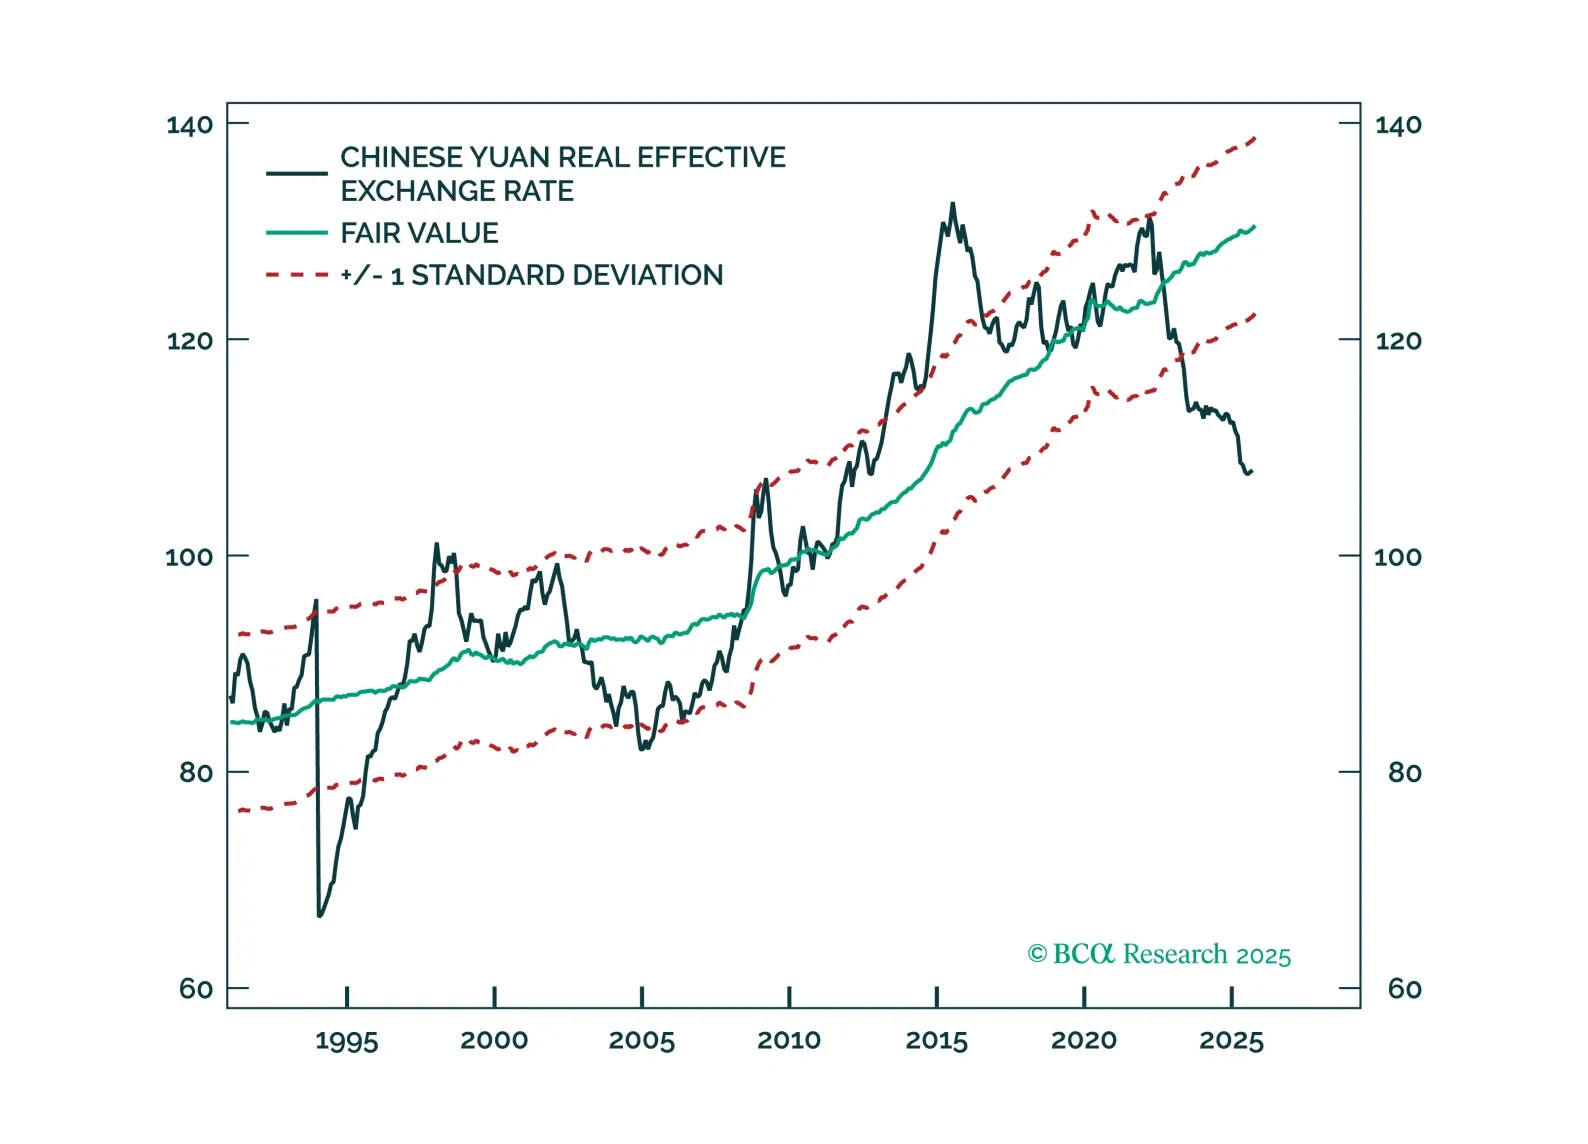
Beijing’s quiet pivot toward RMB strength and a deep valuation discount set the stage for a multi-year appreciation. Our latest FX Insight explores why we see the CNY rising to 6.5–6.8 versus the USD over the next year.
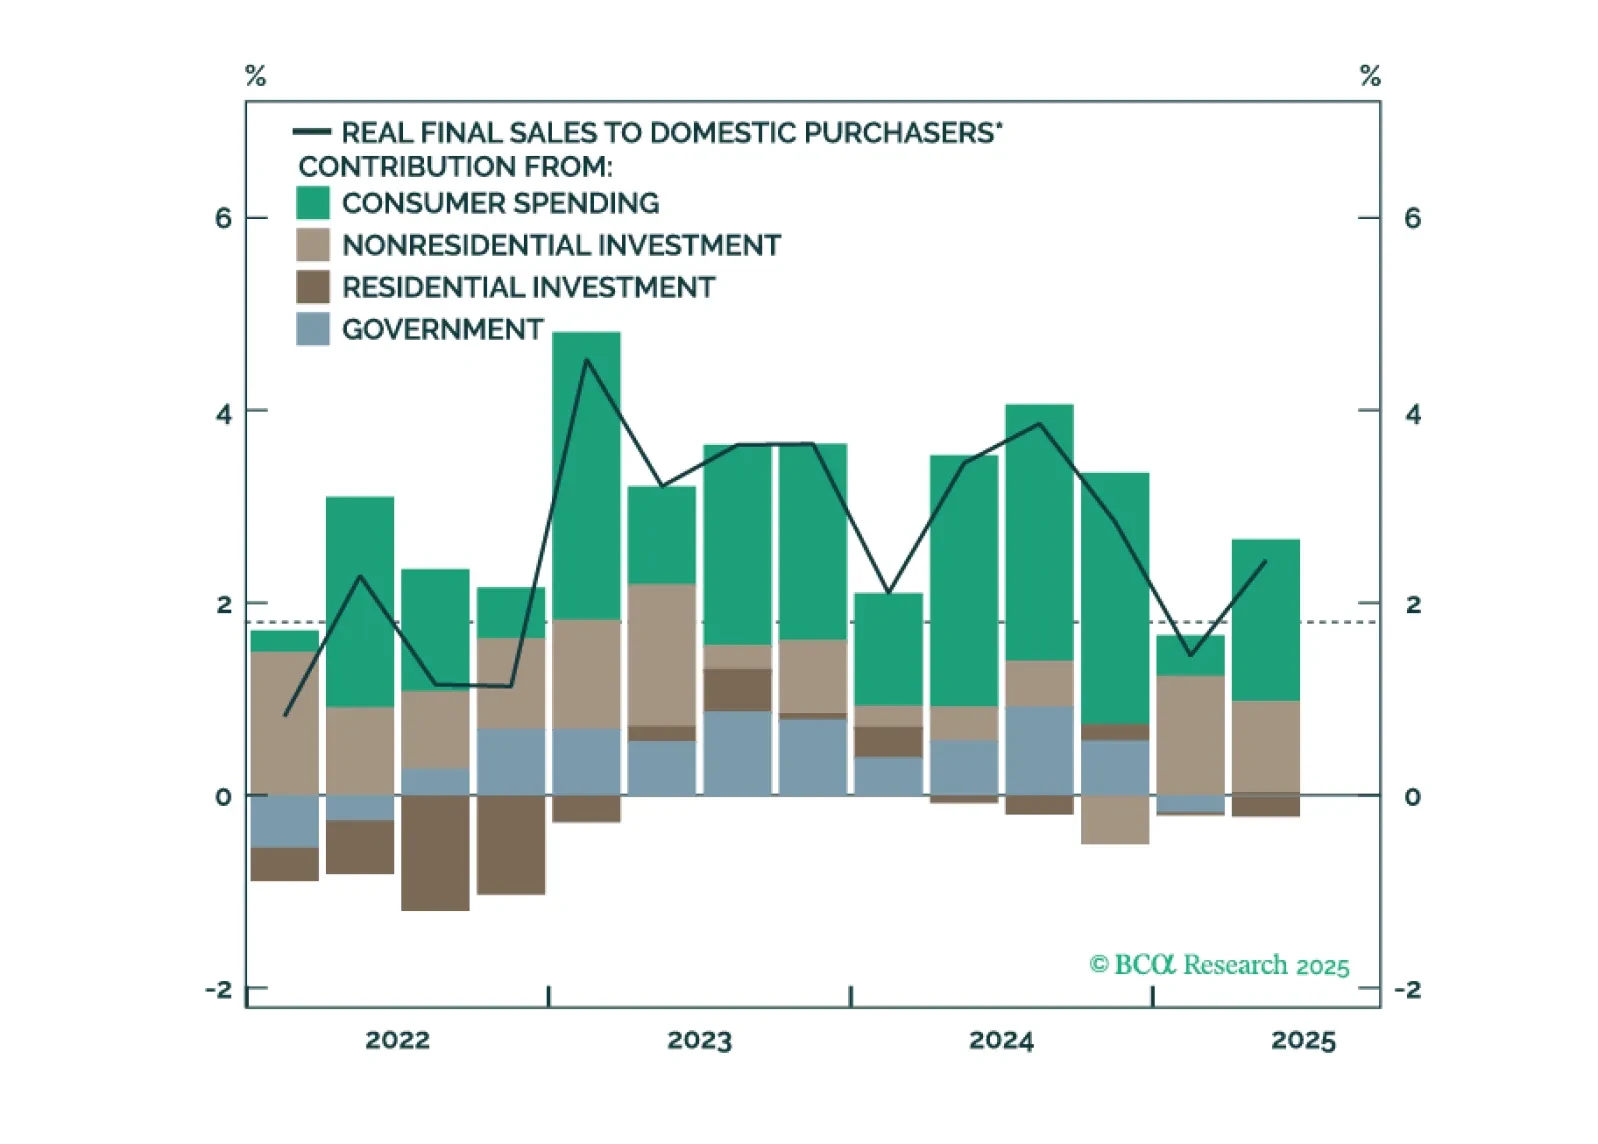
The Fed is poised to deliver a 25-basis-point rate cut this month, but a follow-up rate cut in December will depend on how the divergence between strong consumer spending and weak employment growth is resolved.

Same policy rate, very different expectations. We break down why policy convergence between the Fed and BoE is THE fixed income trade for year-end.
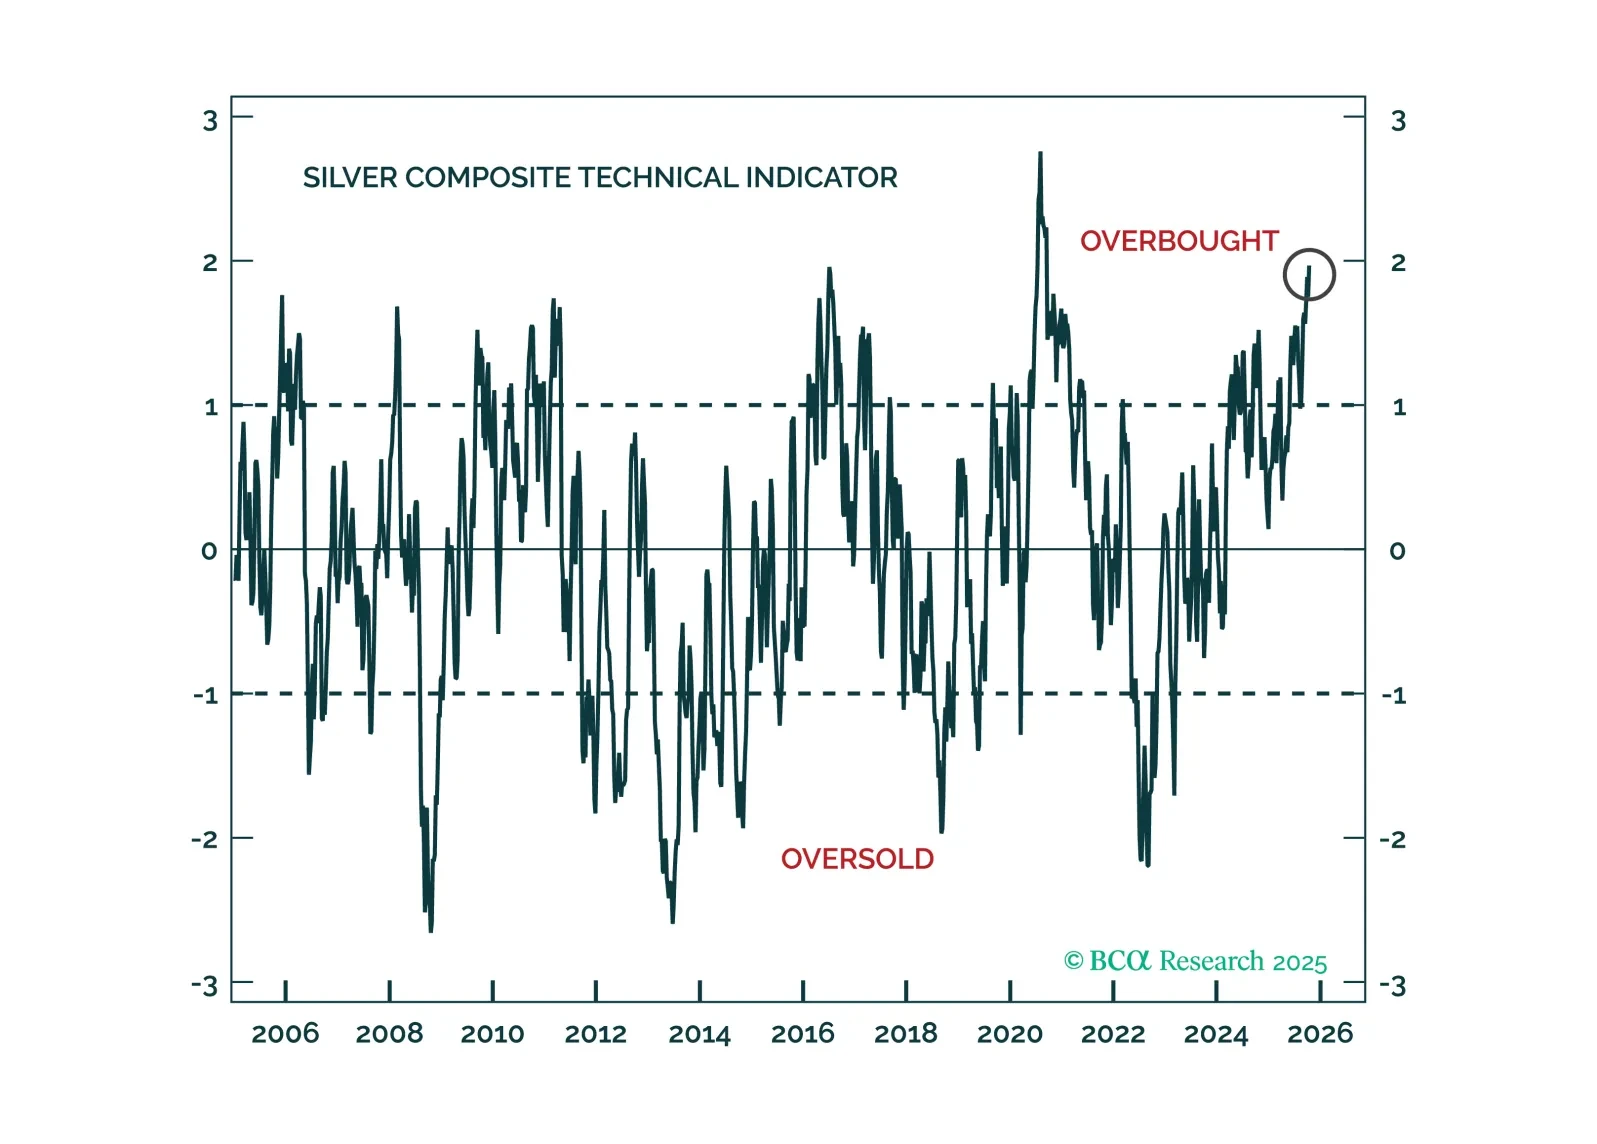
Speculative froth has built up across all precious metals, yet gold’s structural tailwinds will allow it to weather corrections better than its peers.
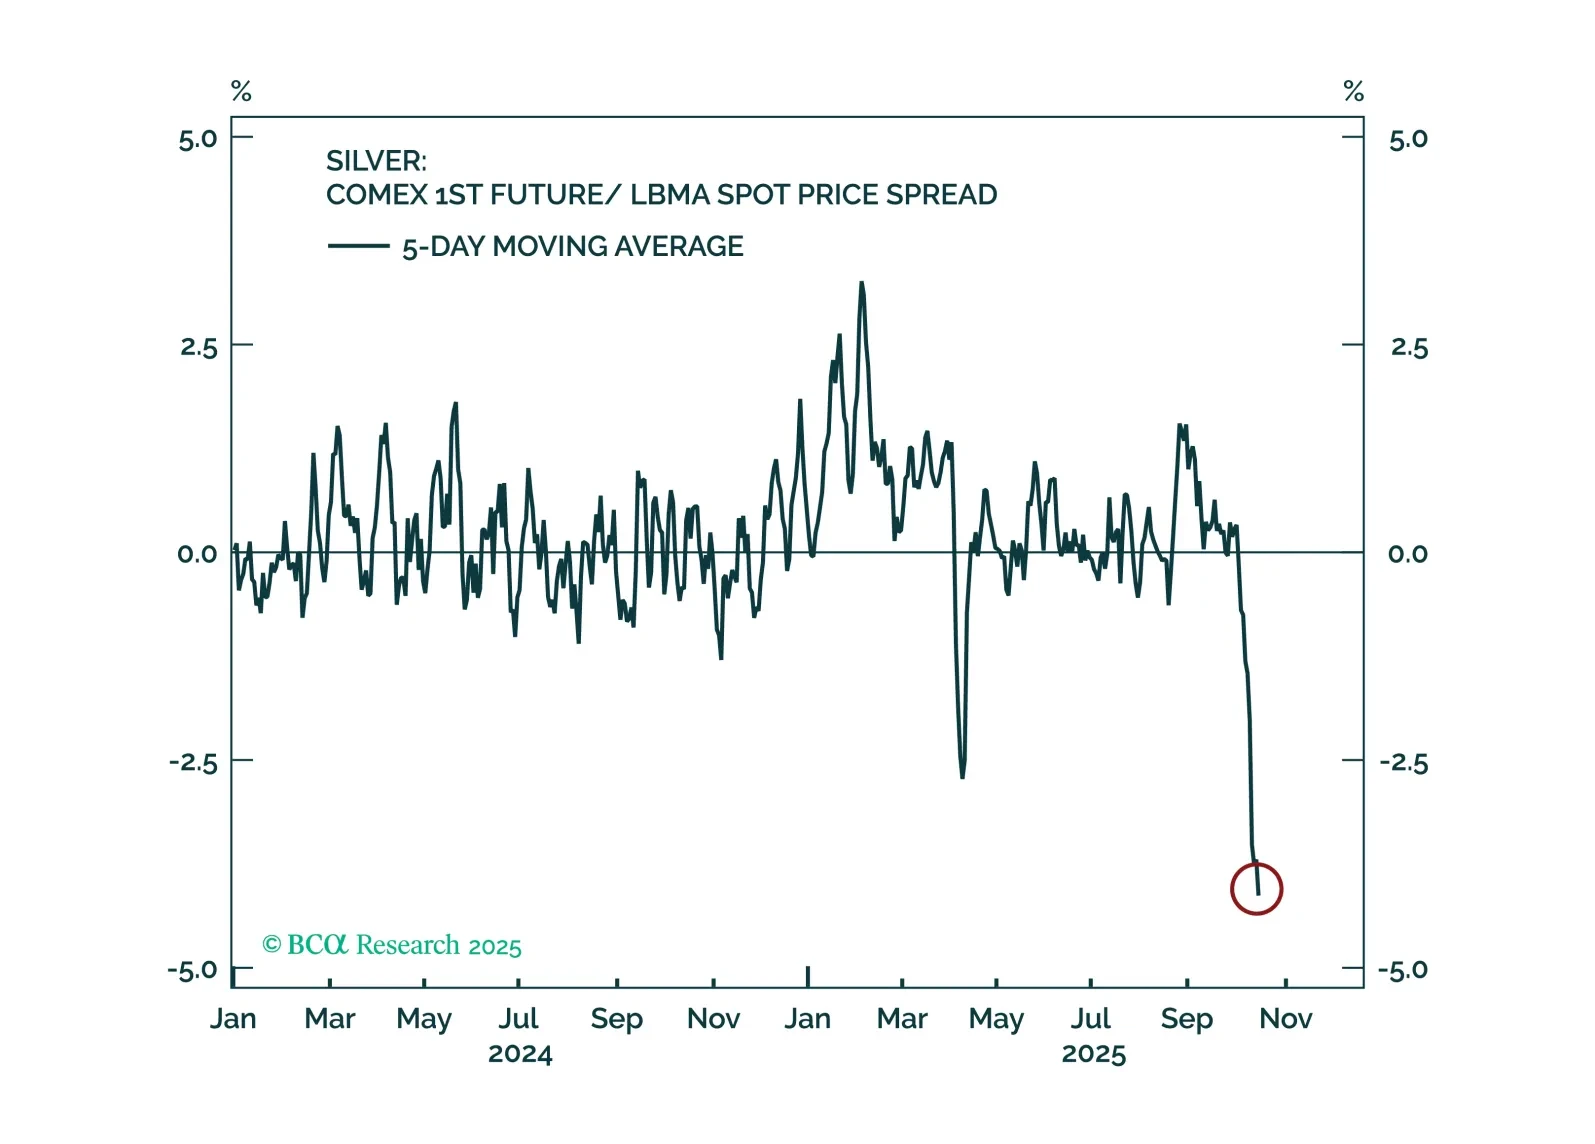
Silver’s short squeeze and stretched technicals warn of a potential tactical pullback.
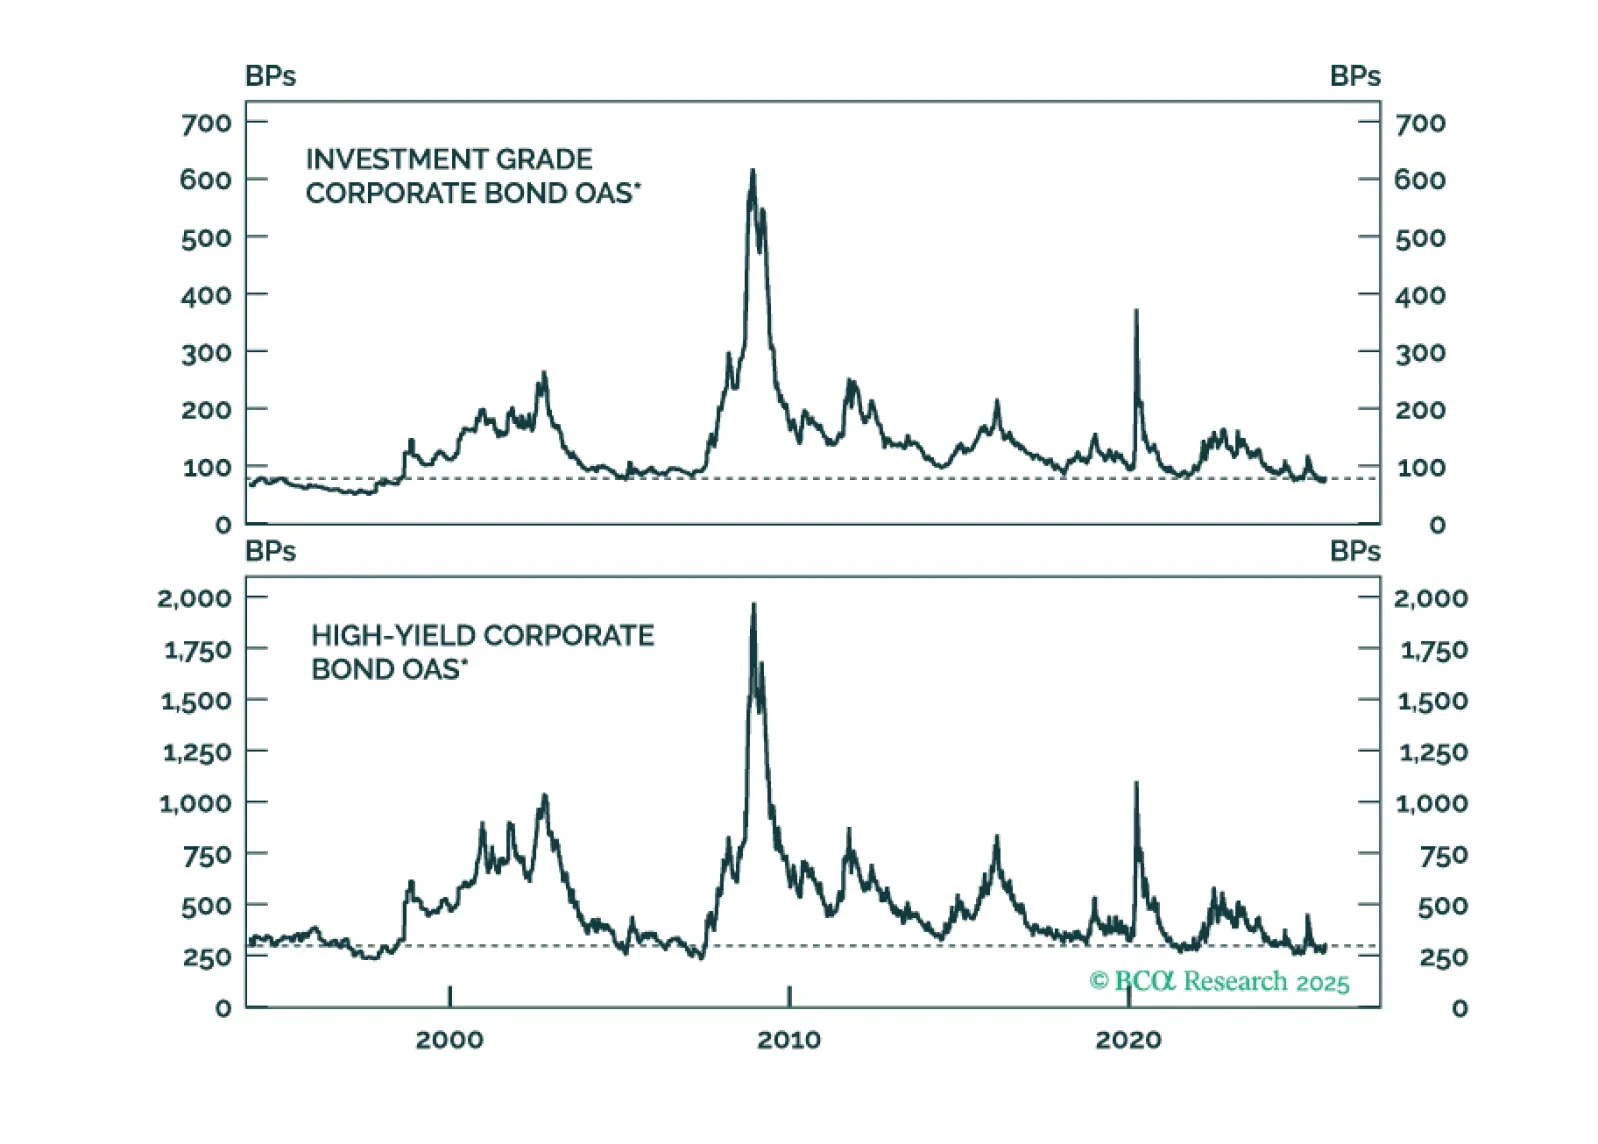
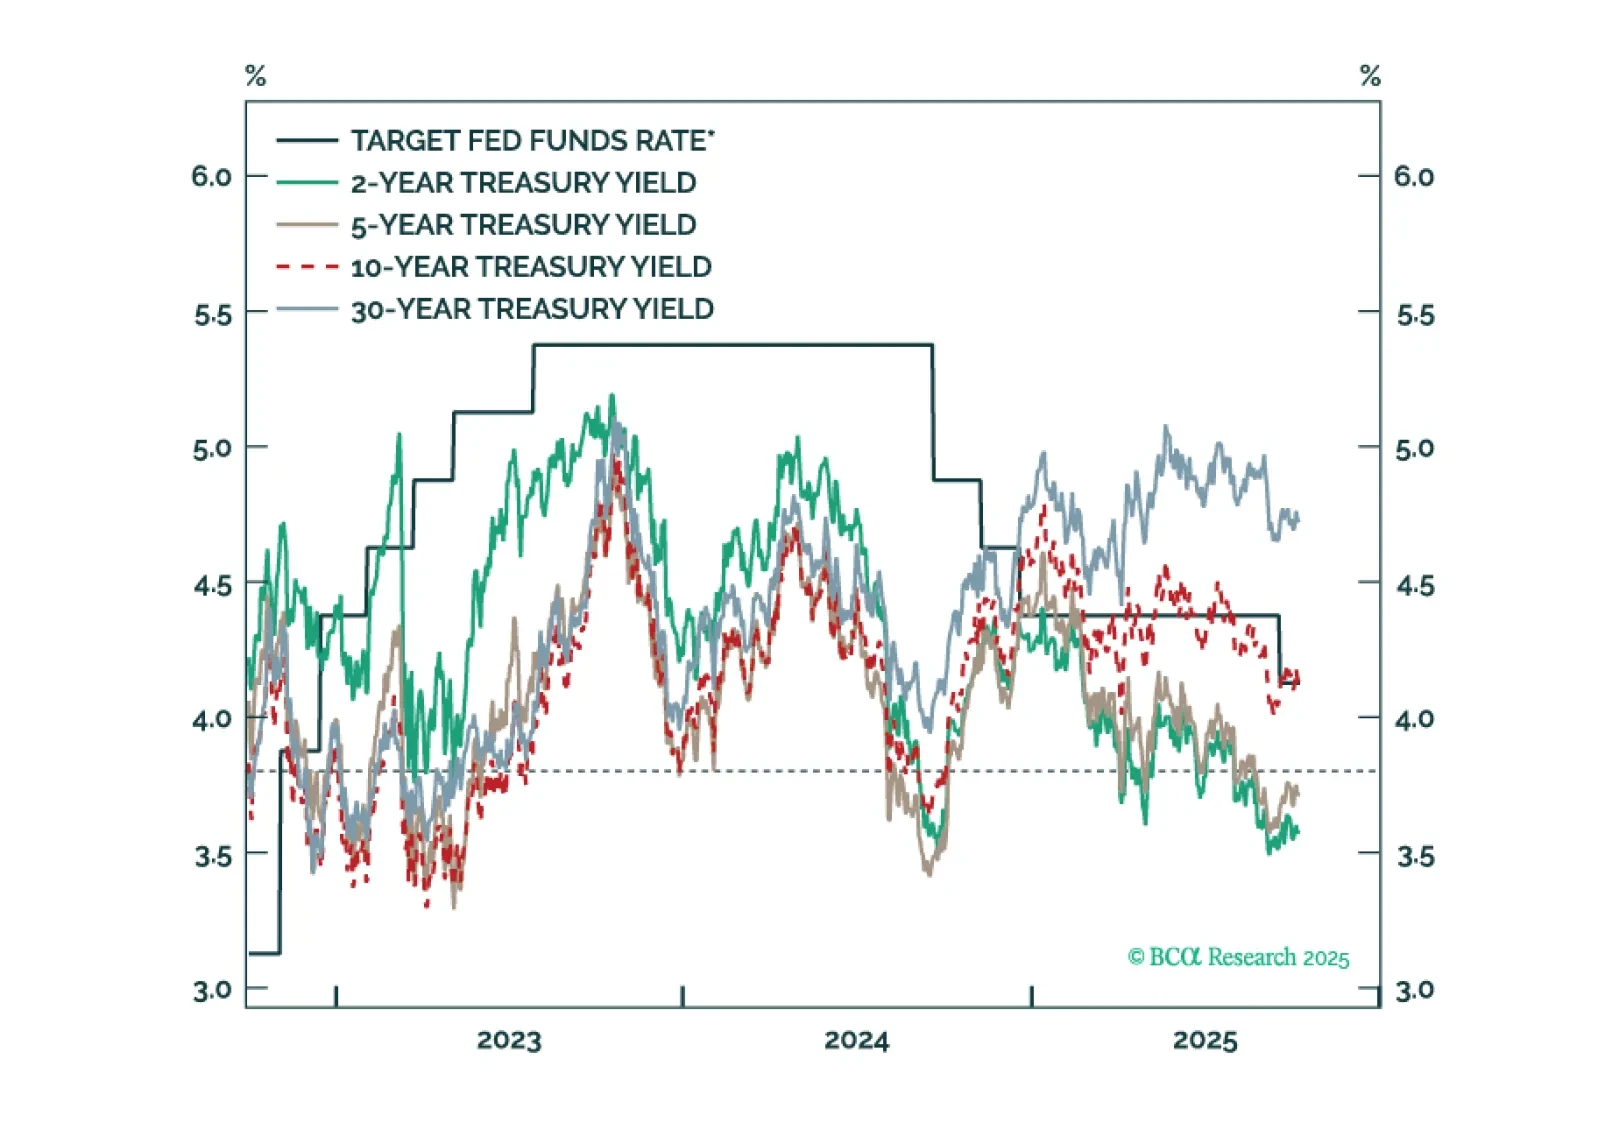
Treasury yields are generally following the pattern of past interest rate cycles, but with a larger term premium keeping the curve steeper than usual.