Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
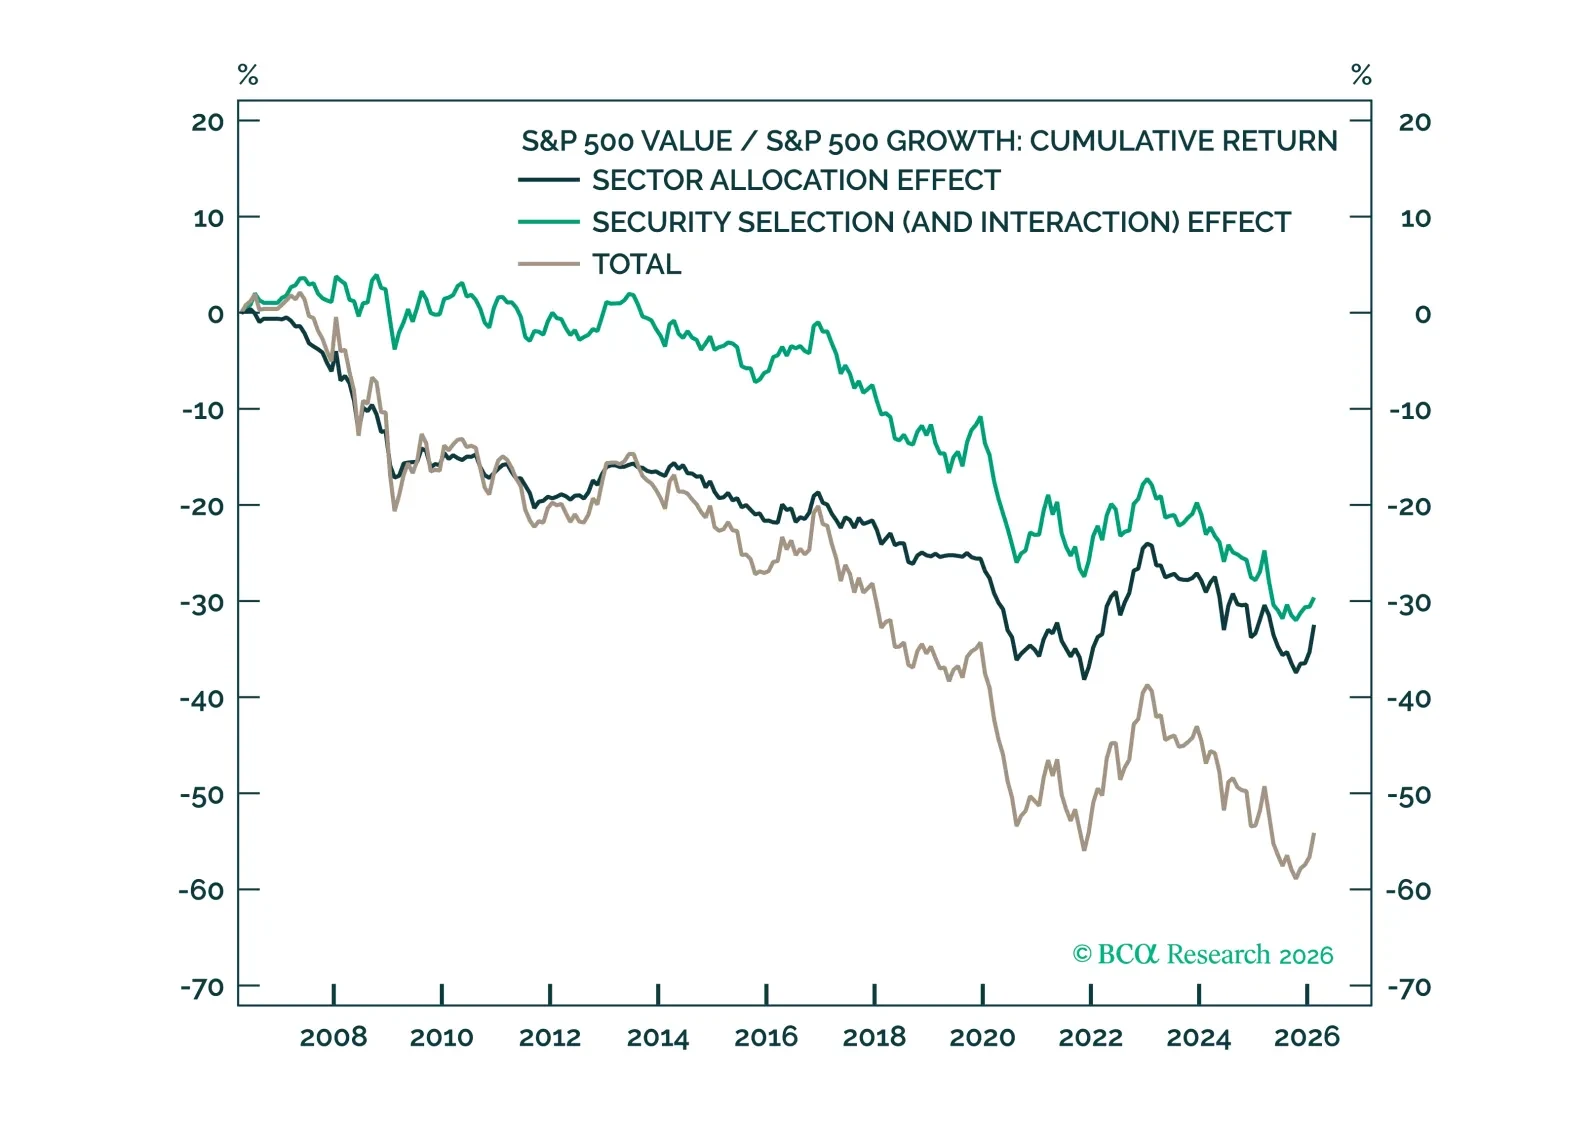
Although Value has had a meaningful run, the longer-run Growth trend likely remains intact. However, benchmark Growth indices are increasingly concentrated. Sector-neutral and within-sector implementations may allow investors to retain much of the same Growth/Value exposure while reducing dependence on technology and limiting concentration risk.
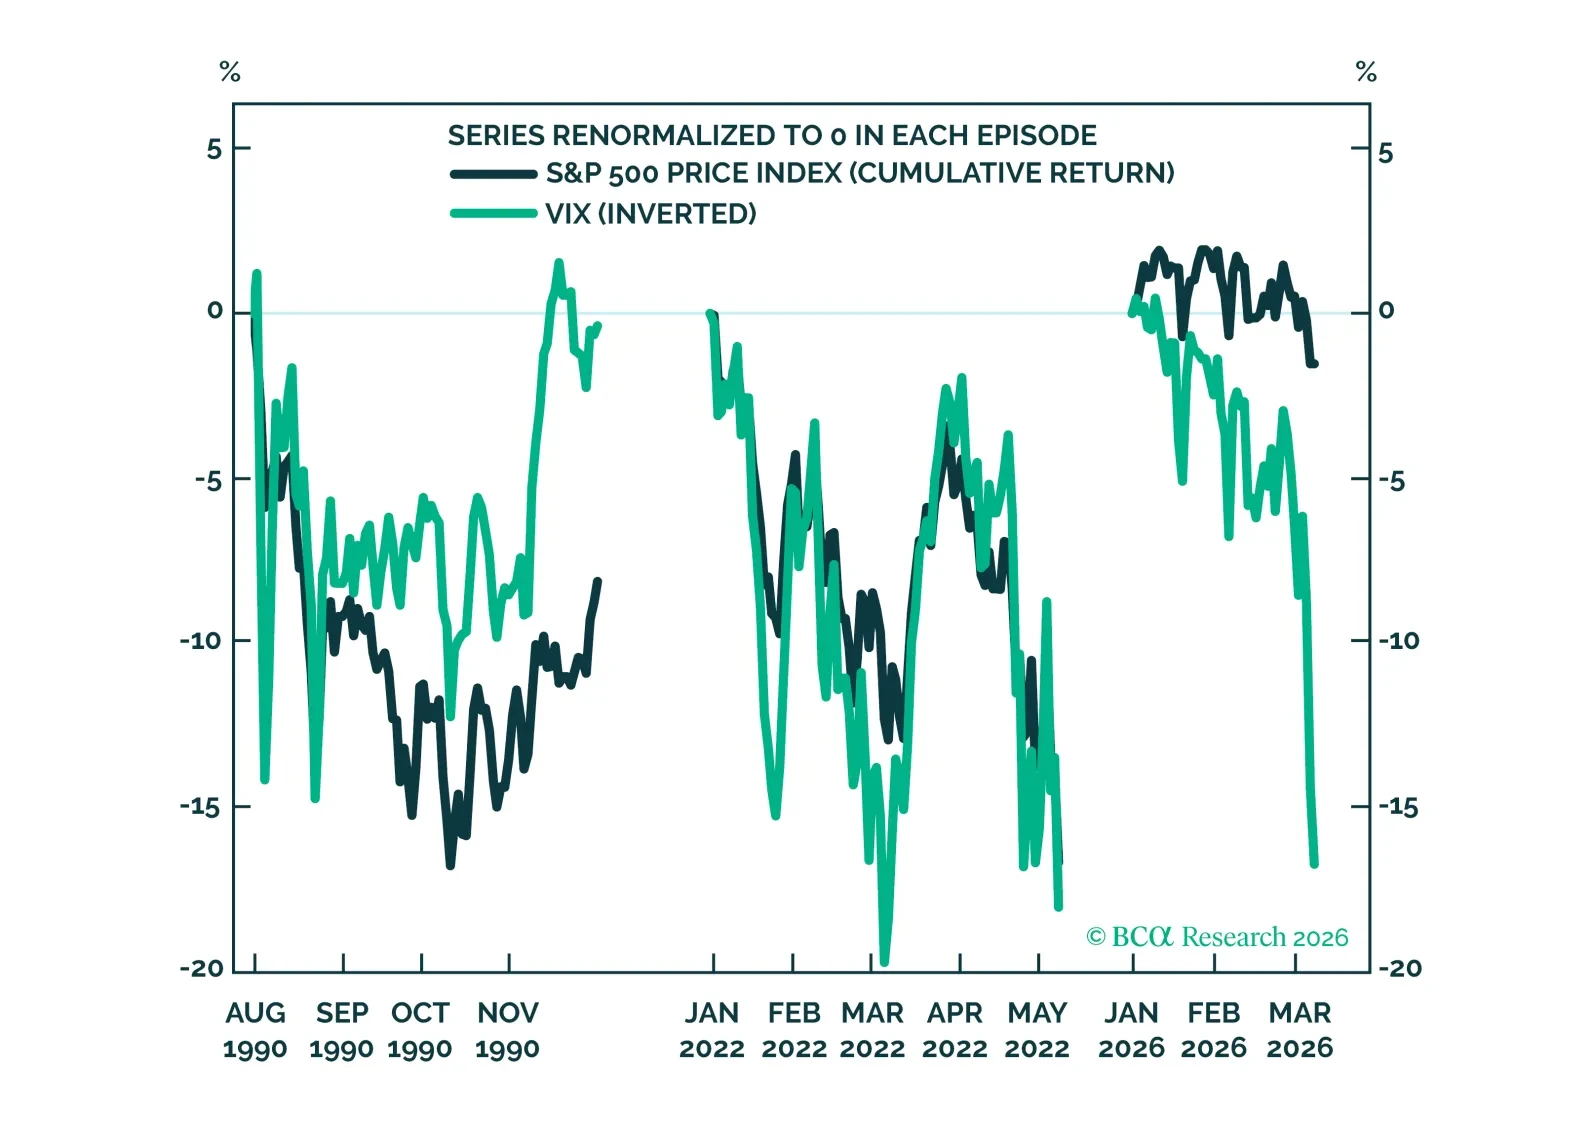
Middle East tensions sparked a surge in volatility, yet the S&P 500 decline has been comparatively modest. Across asset classes, moves seem related to risk preferences and near-term inflation concerns. Within equities, some cyclicals are under pressure, but the equity market’s growth view has been resilient, while the inflation view has climbed.
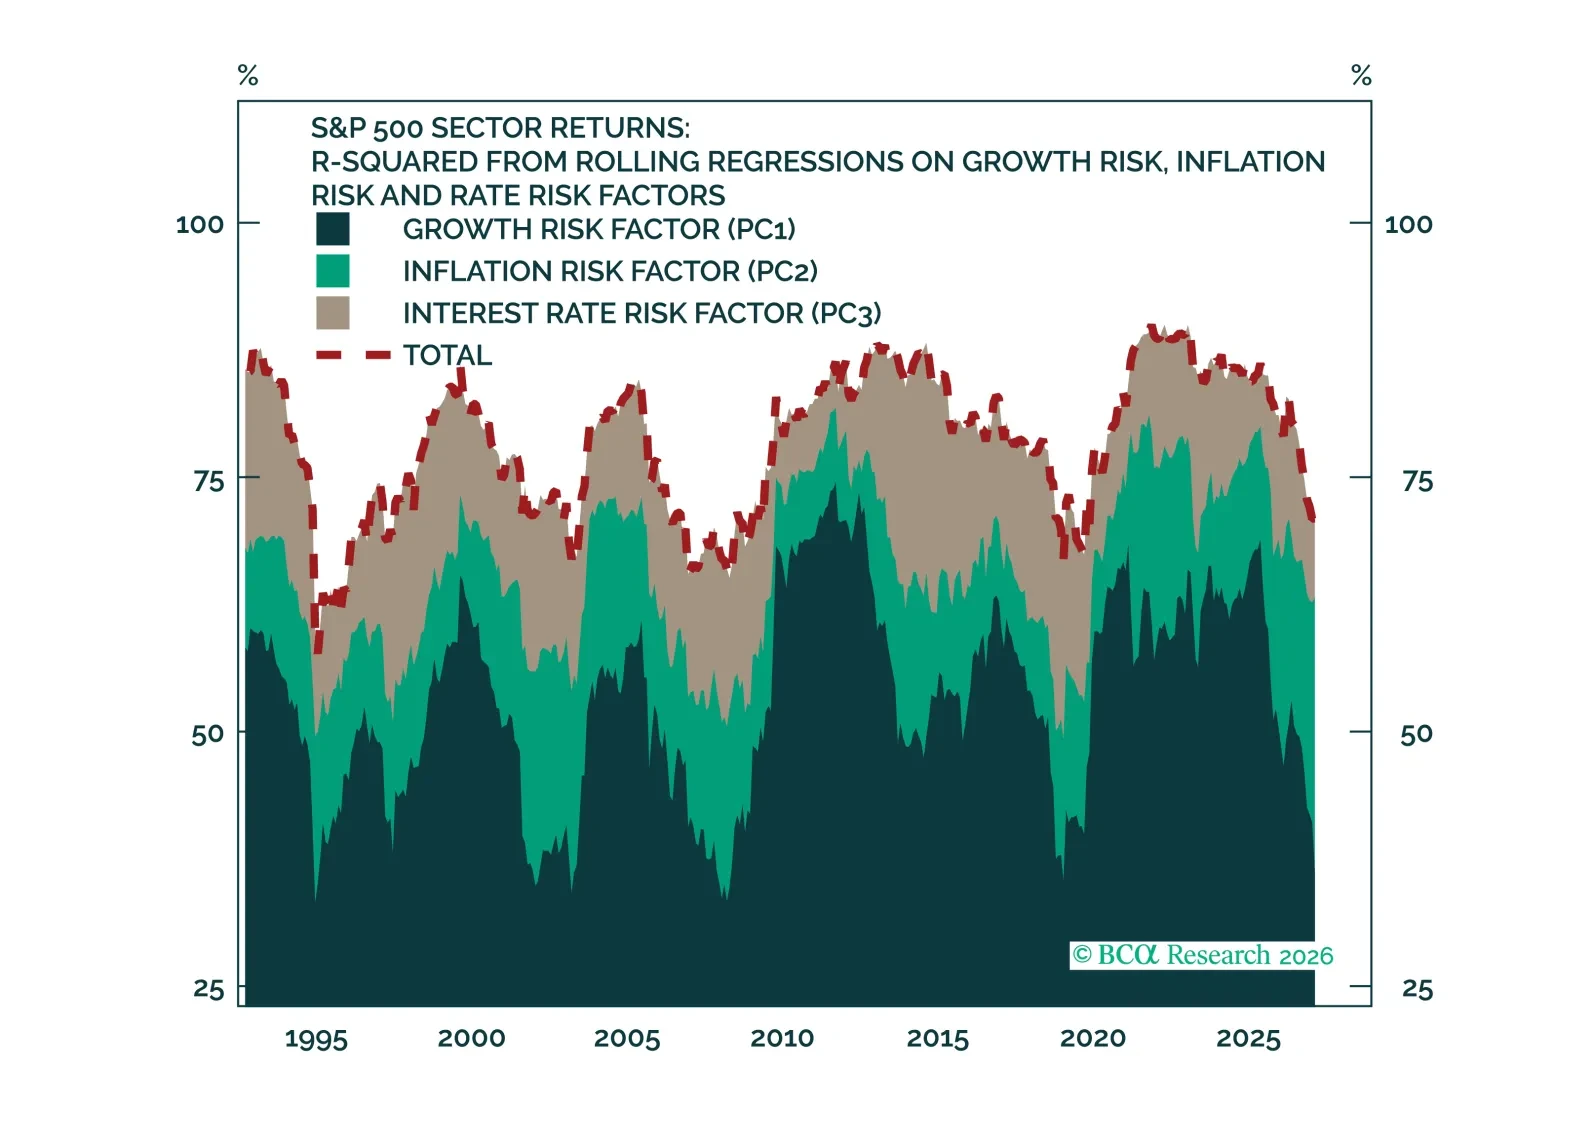
Growth, inflation, and rate risk drive sector returns and fundamentals, but macro’s explanatory power is at multi-decade lows. Long/short industry-group baskets show the equity market has turned pessimistic about growth, a potential opportunity as the macro data firm. The market’s inflation view has climbed, a move that may be harder to fade given rising oil prices.
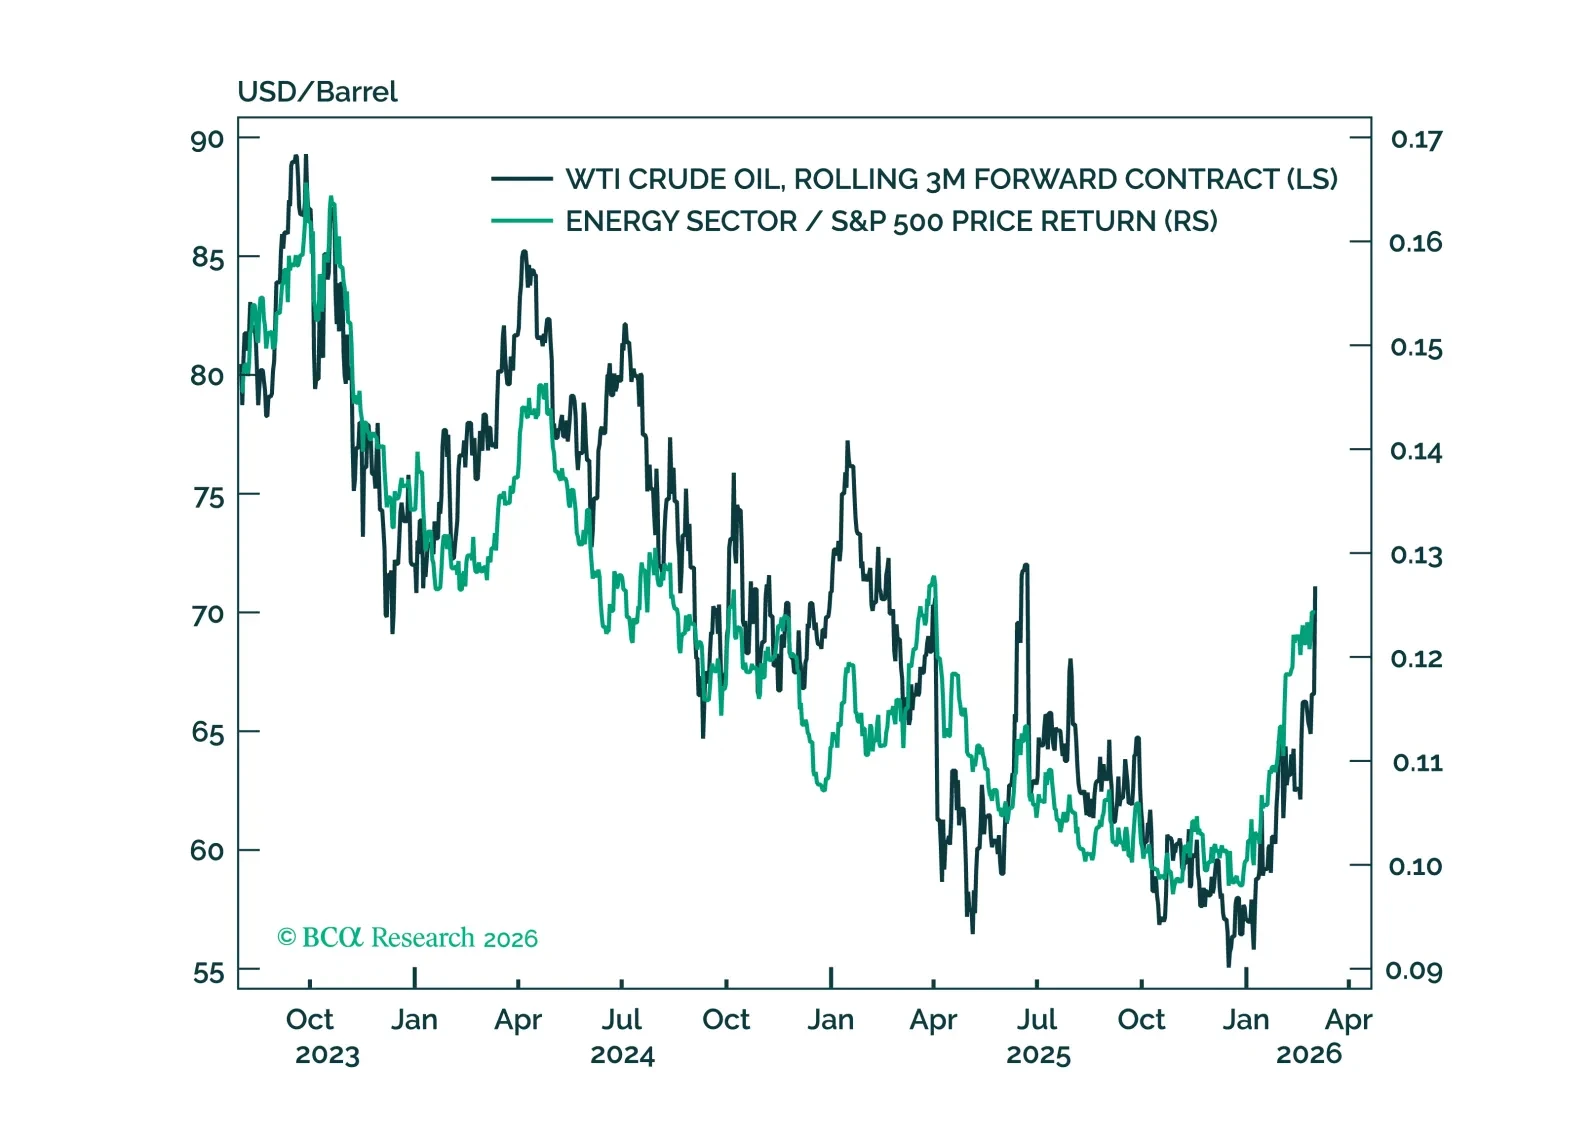
Middle East hostilities have triggered risk-off moves and pushed oil prices higher. Previous geopolitically driven oil price disruptions suggest that speed, persistence and equity market vulnerability relate to the degree of the market sell off. At the other end of the spectrum, energy stocks should benefit, but have already rallied significantly.
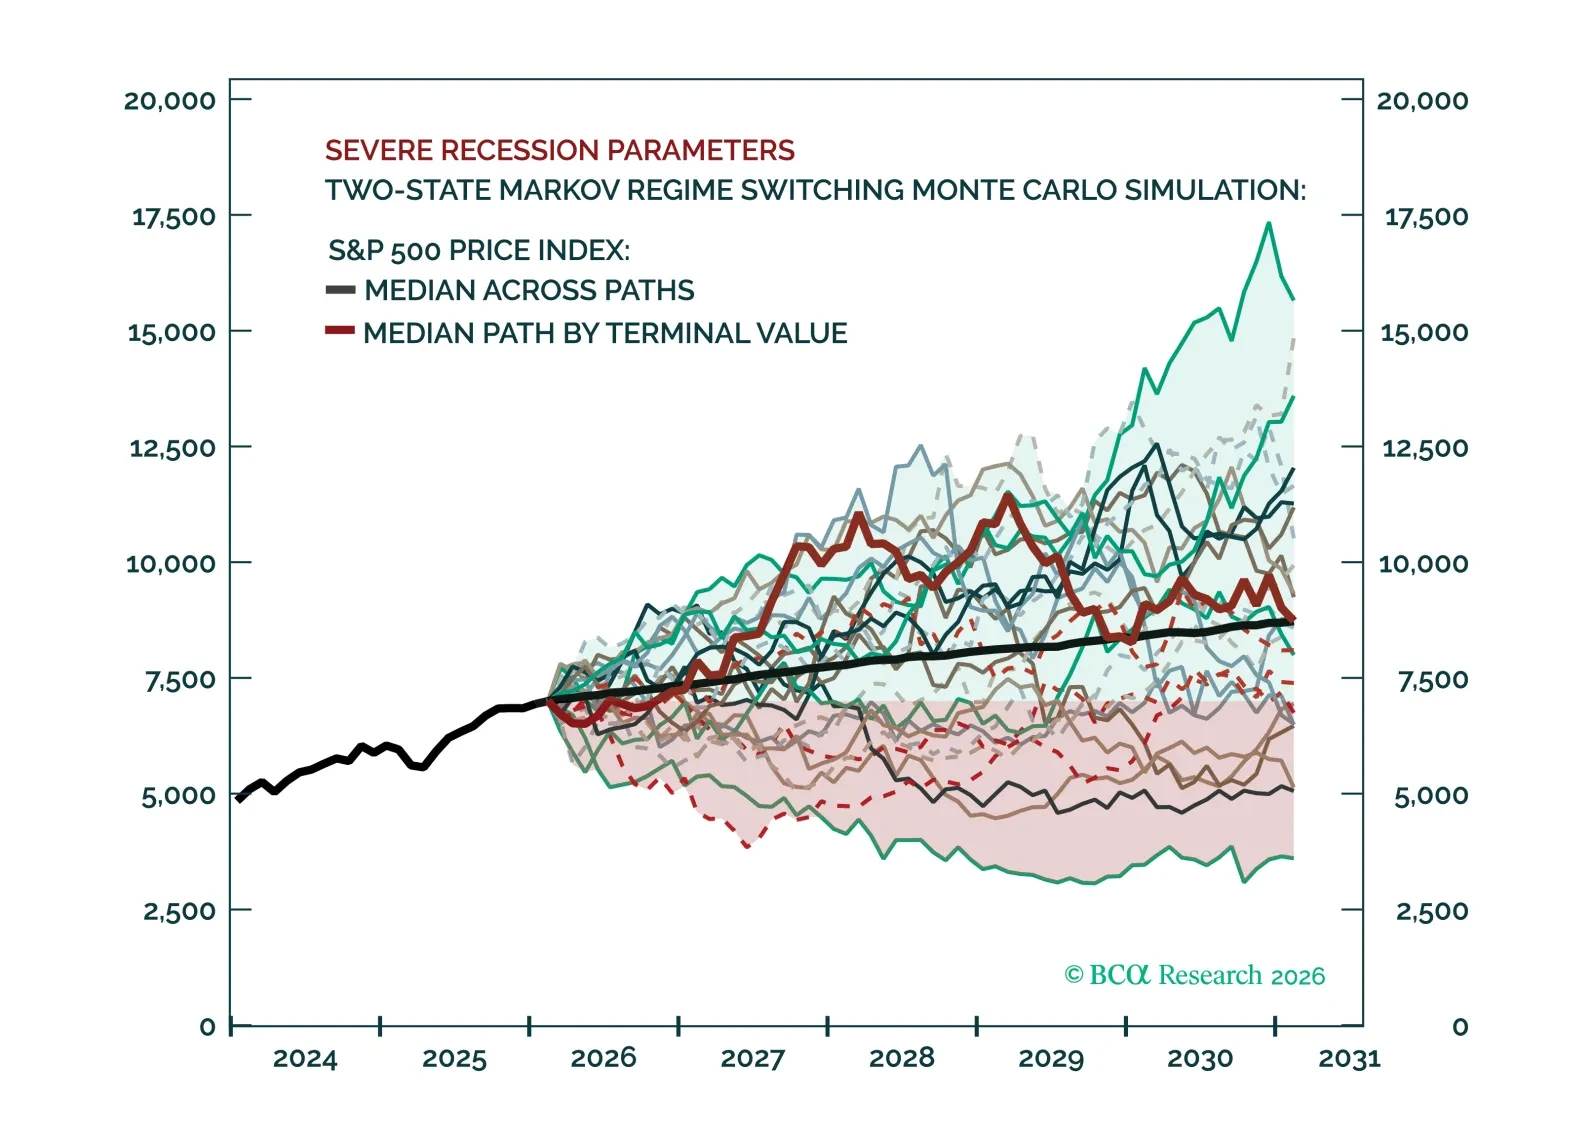
Recessions are inevitable but unpredictable. While earnings drive long‑term equity performance through the cycle, around turning points fundamentals follow a predictable sequence: multiples contract first, then prices, then earnings. Recessions can shift sector leadership, but simulations show that medium‑term index‑level upside remains intact unless future downturns are materially more severe than in history.
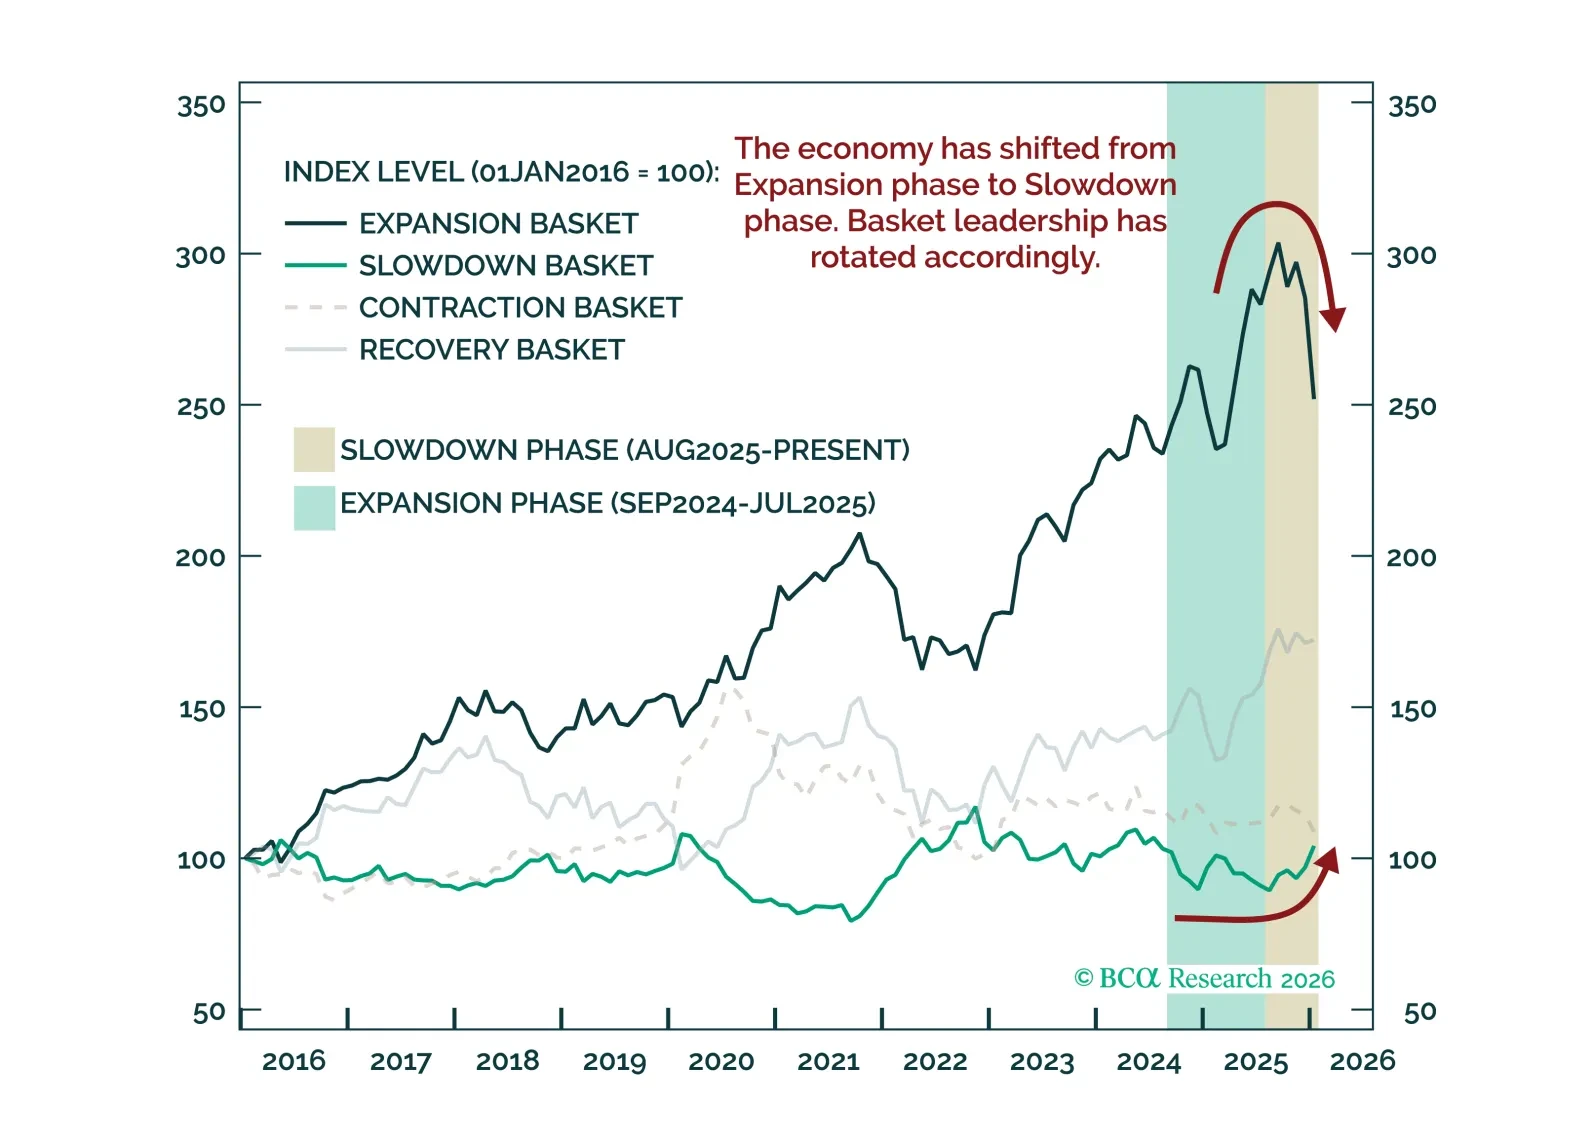
The US economy is in the Slowdown phase of the business cycle, according to our measure of aggregate US economic activity; growth remains positive but acceleration is negative. Historically, this phase more often resolves in reacceleration than recession. Recent market price action, from the index, to sectors, to relative industry performance, broadly reflects typical Slowdown phase dynamics.
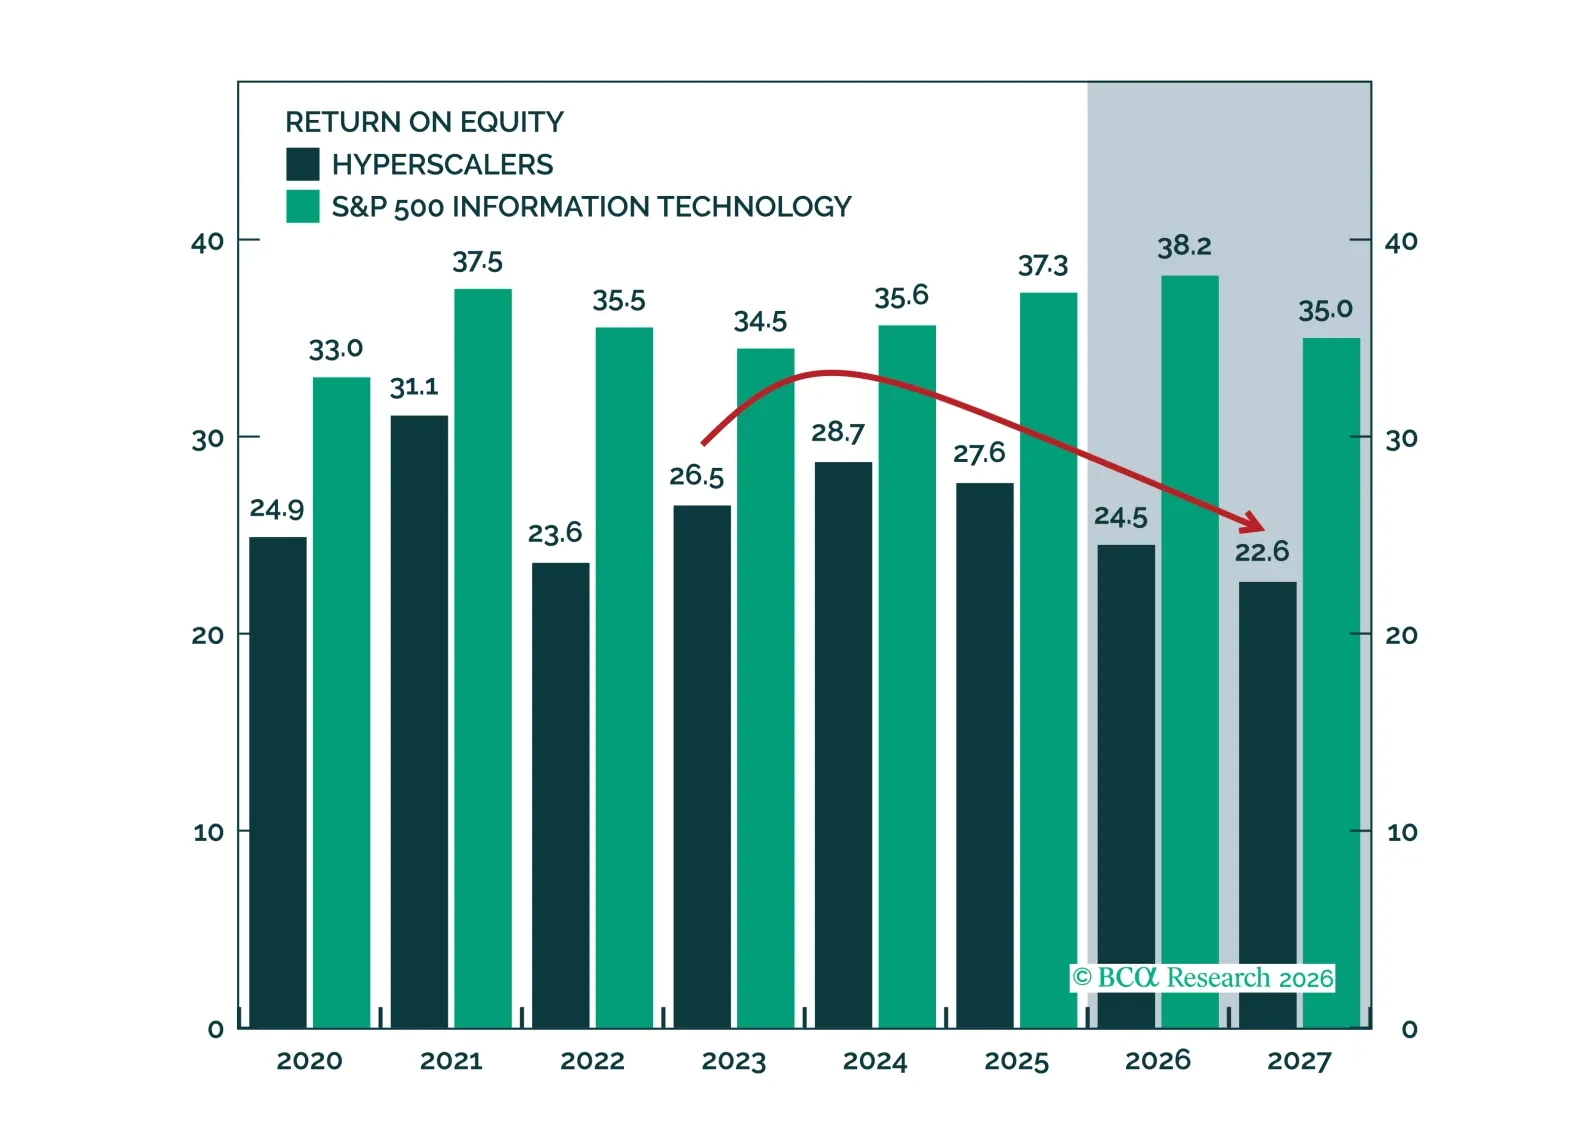
The capex debate is better framed not as boom versus bubble, but as around capacity, leverage, and cash conversion. ROEs have compressed, but revenue growth and margin expansion offer a credible path back. Spenders likely have time to make good on their investments, though the market’s leash may be shorter than anticipated.
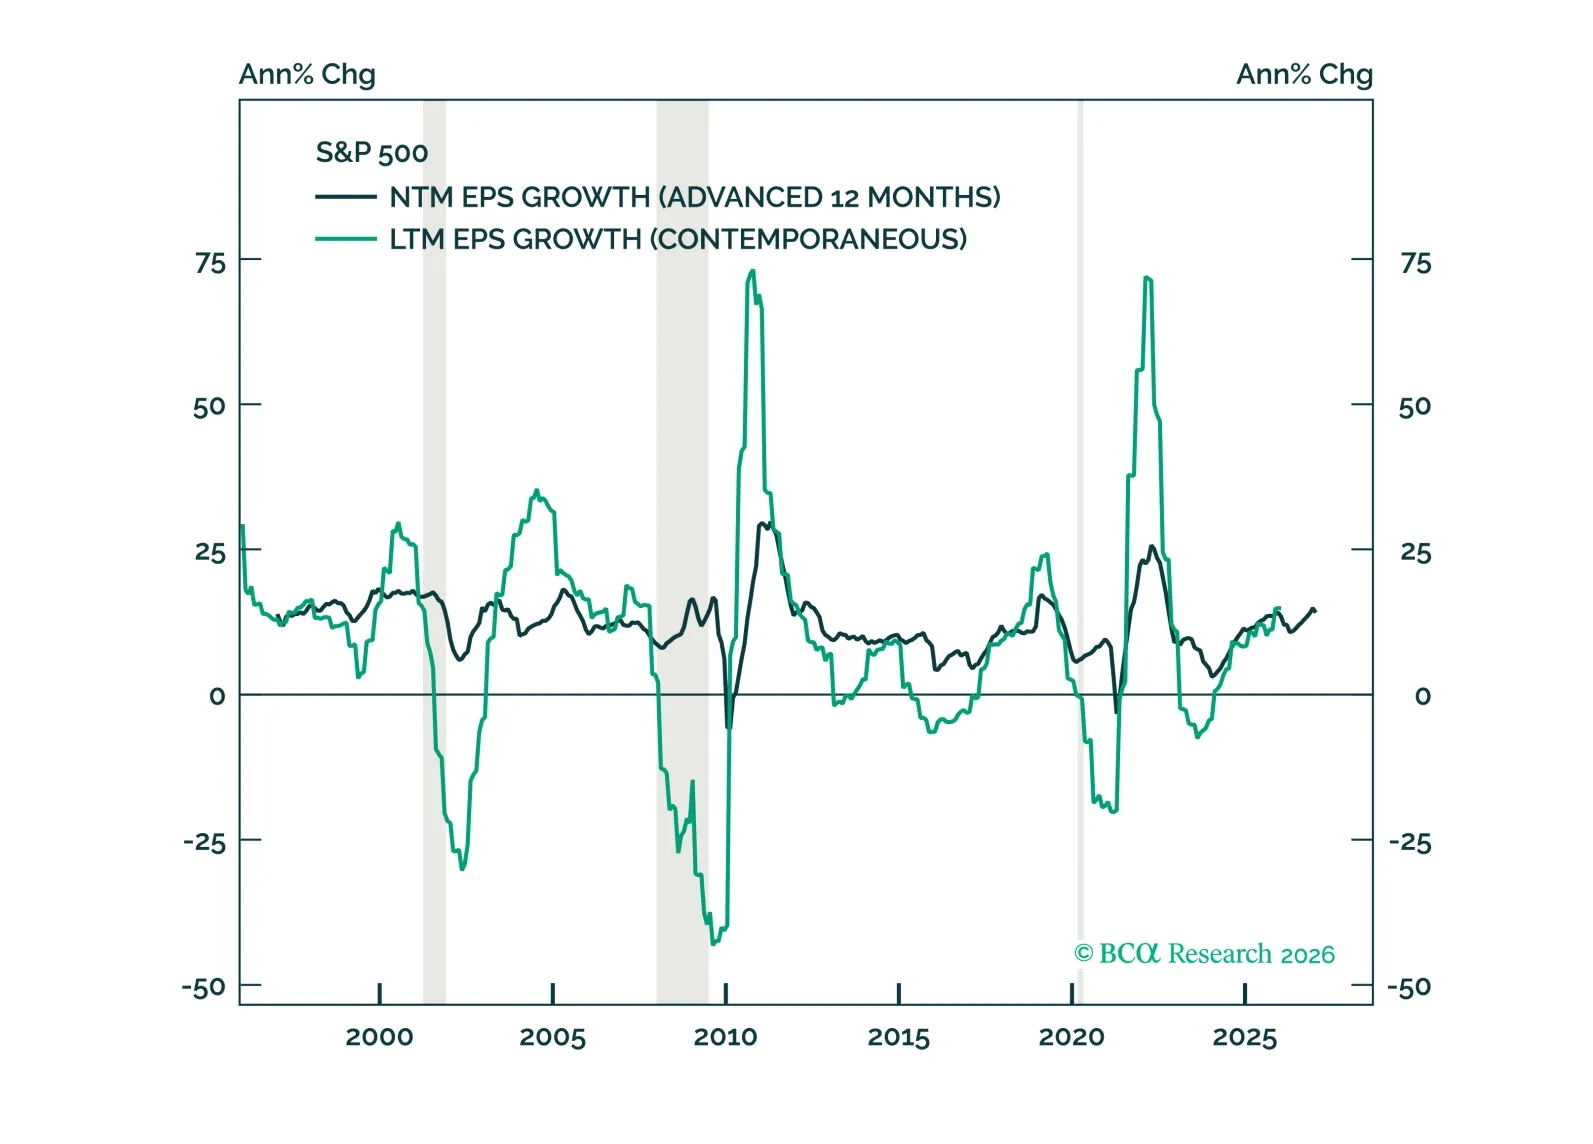
Earnings strength, durability, and breadth are all improving. As the market transitions from multiple-driven to earnings-driven returns, this backdrop supports continued gains in 2026—but with less concentration and greater scope for laggards to catch up rather than leaders to roll over.

2026 should see another year of gains for the S&P 500, but, as the bull market matures and growth slows, returns will be capped by revenue growth rather than being boosted by expanding margins and multiples. We think Tech can outperform, but leadership will broaden and performance gaps will narrow.