Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.

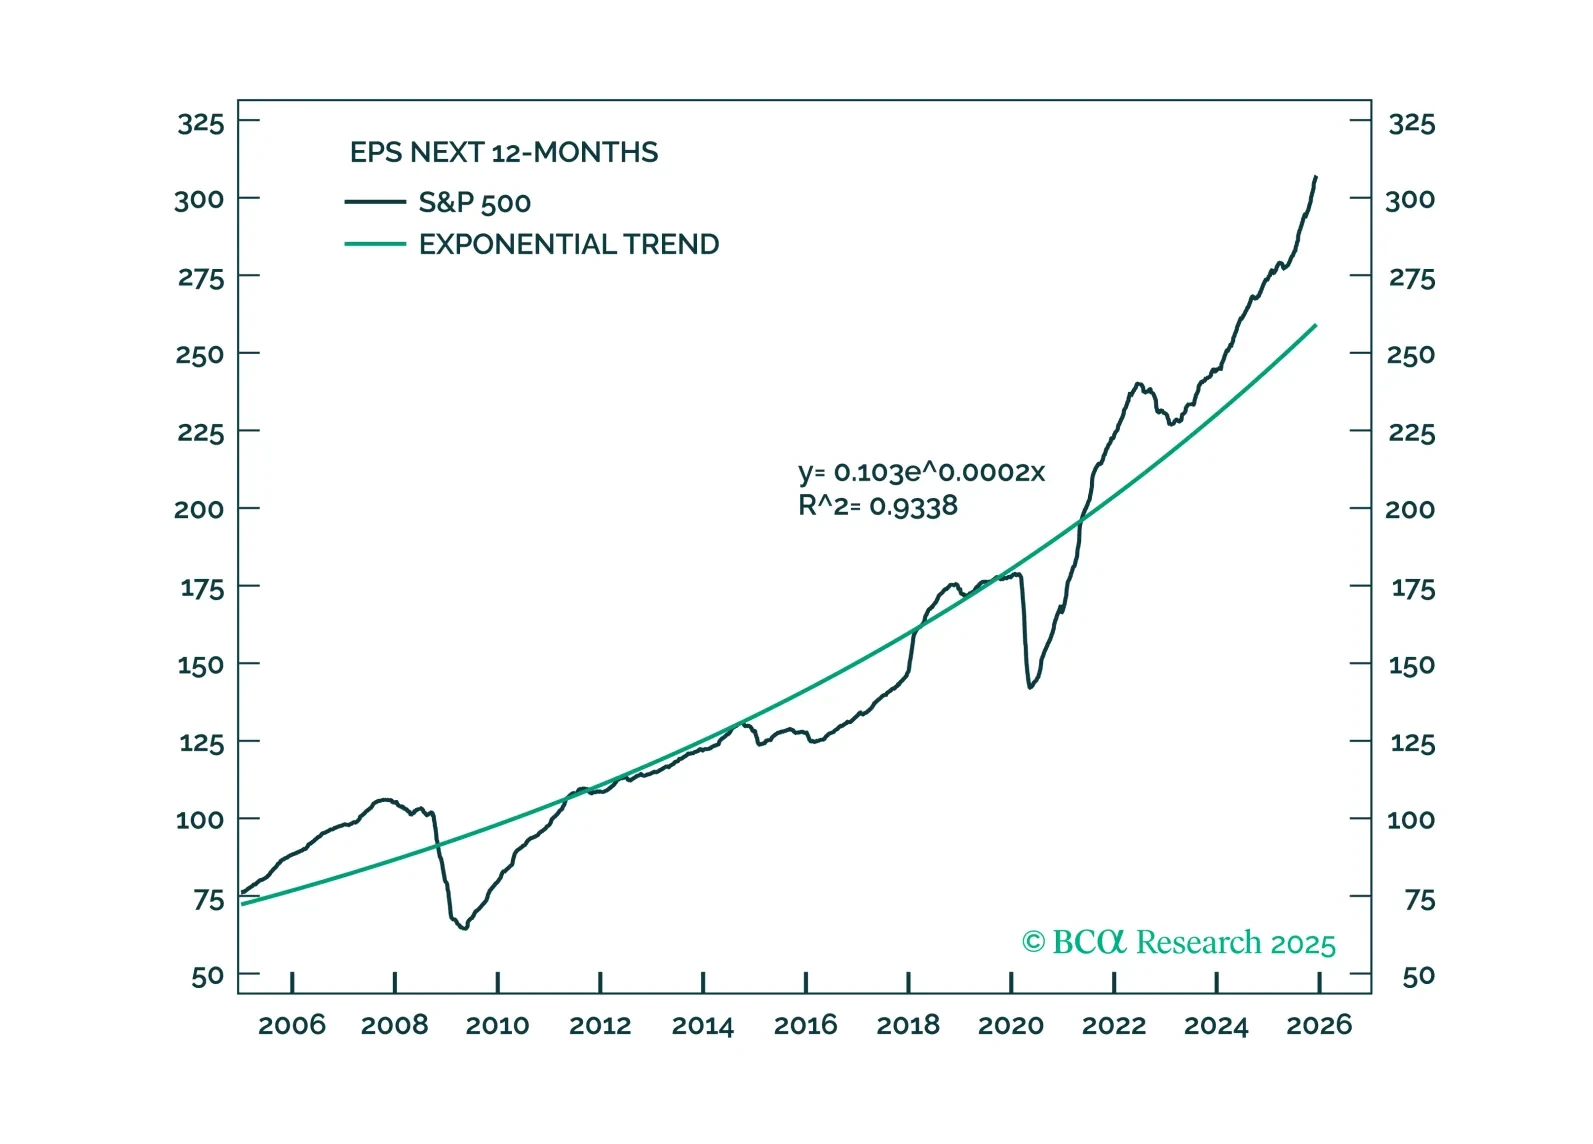
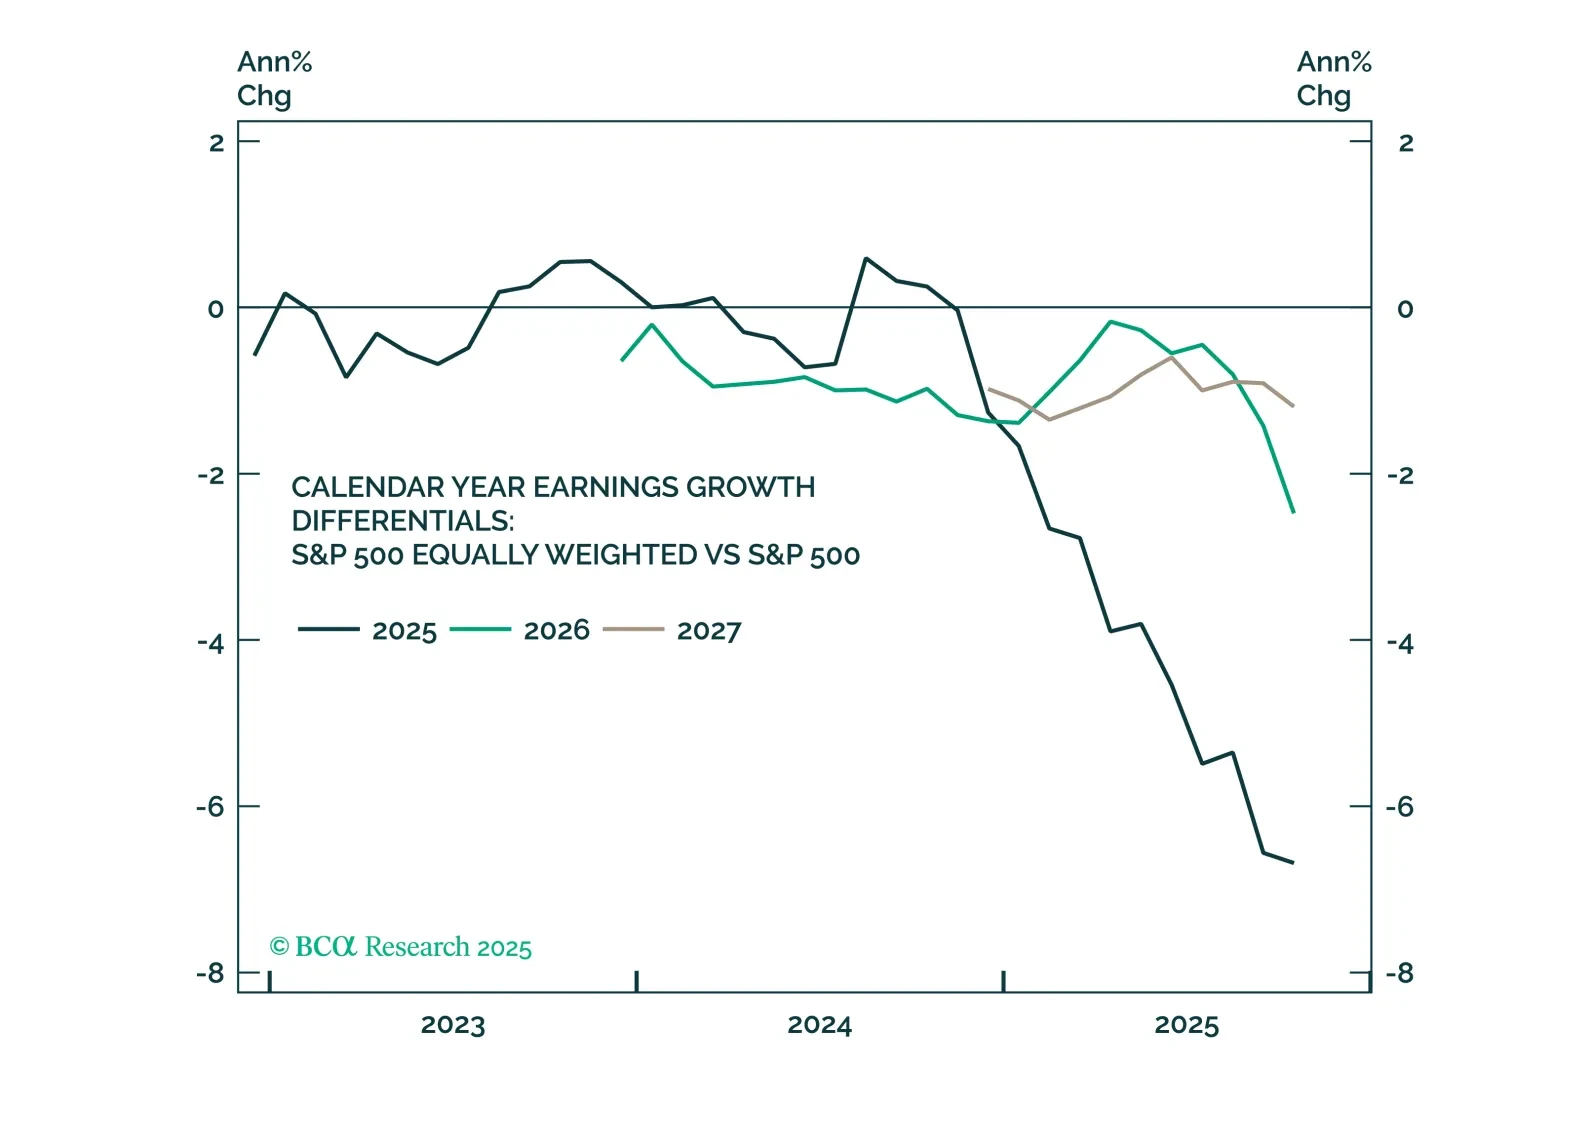
The outperformance of the S&P 500 relative to the S&P 500 EW index is likely to continue over the next year, supported by stronger earnings growth. However, extreme levels of market concentration will ultimately halt the outperformance of the mega-caps.
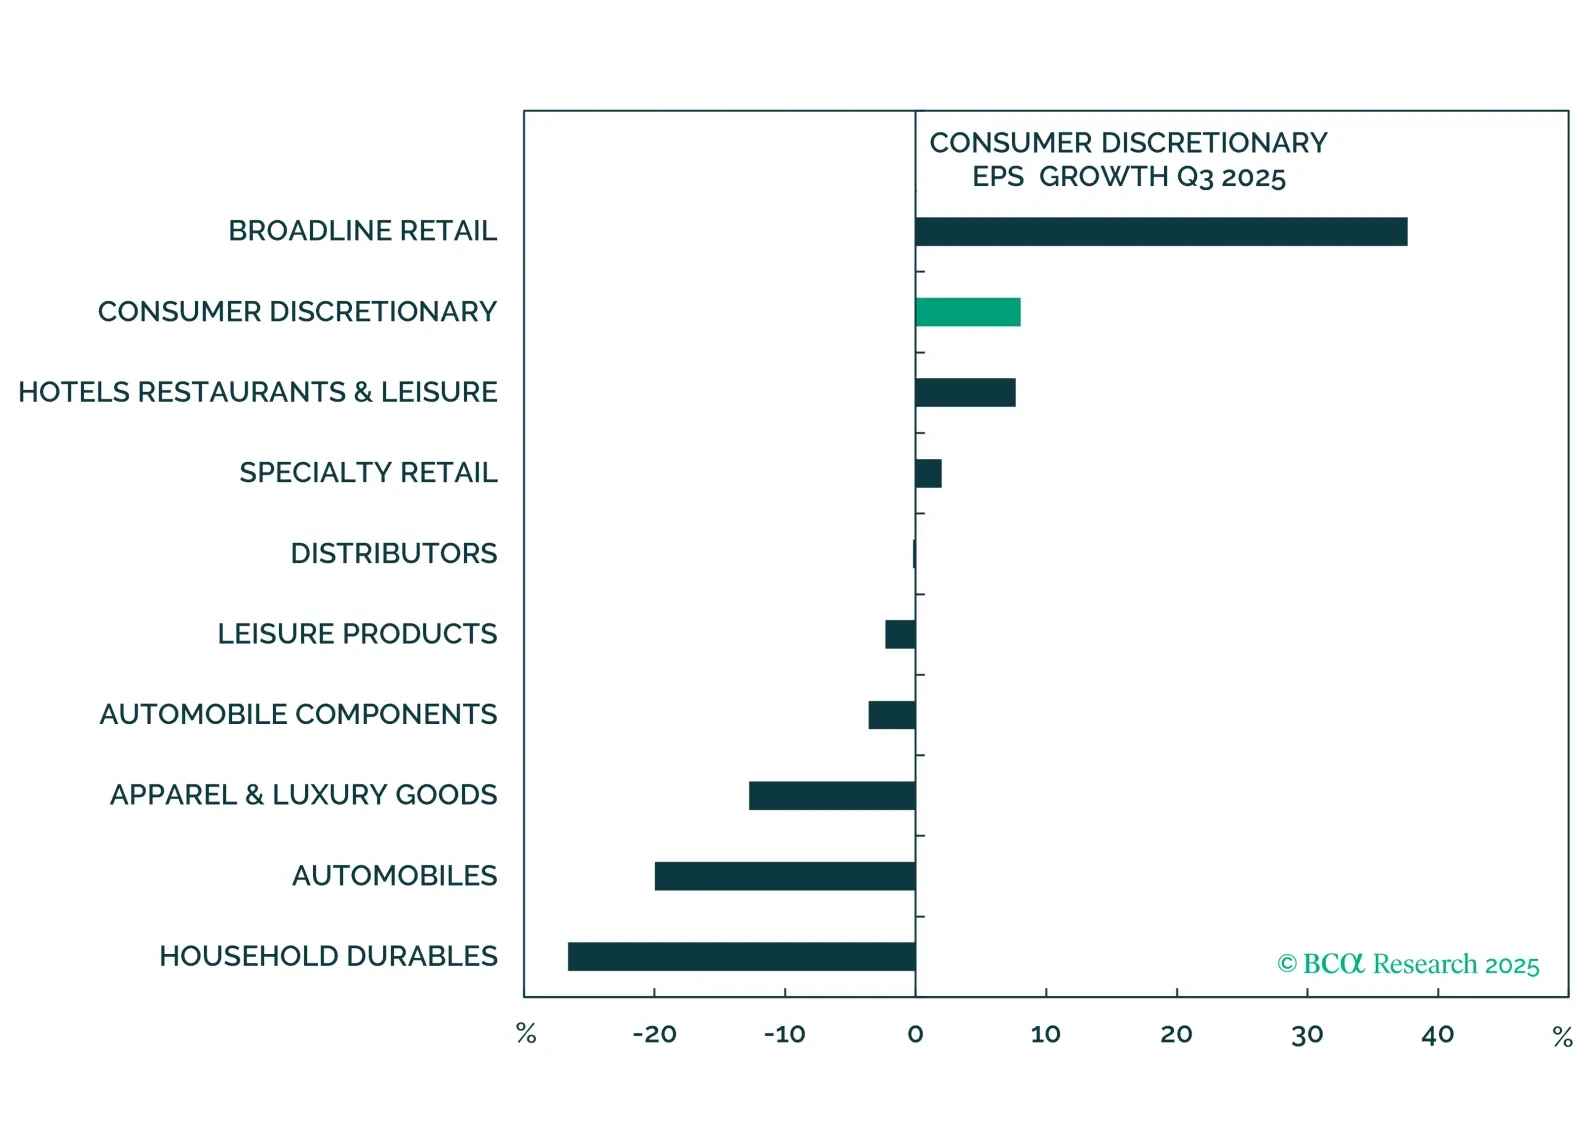
Q3 results were strong but failed to impress investors, and Q4 will likely prove more challenging. Beneath the surface, earnings diverged sharply: Firms catering to affluent consumers maintained solid momentum, while those reliant on the mass market lagged. We remain equal weight Consumer Services and underweight Consumer Staples.
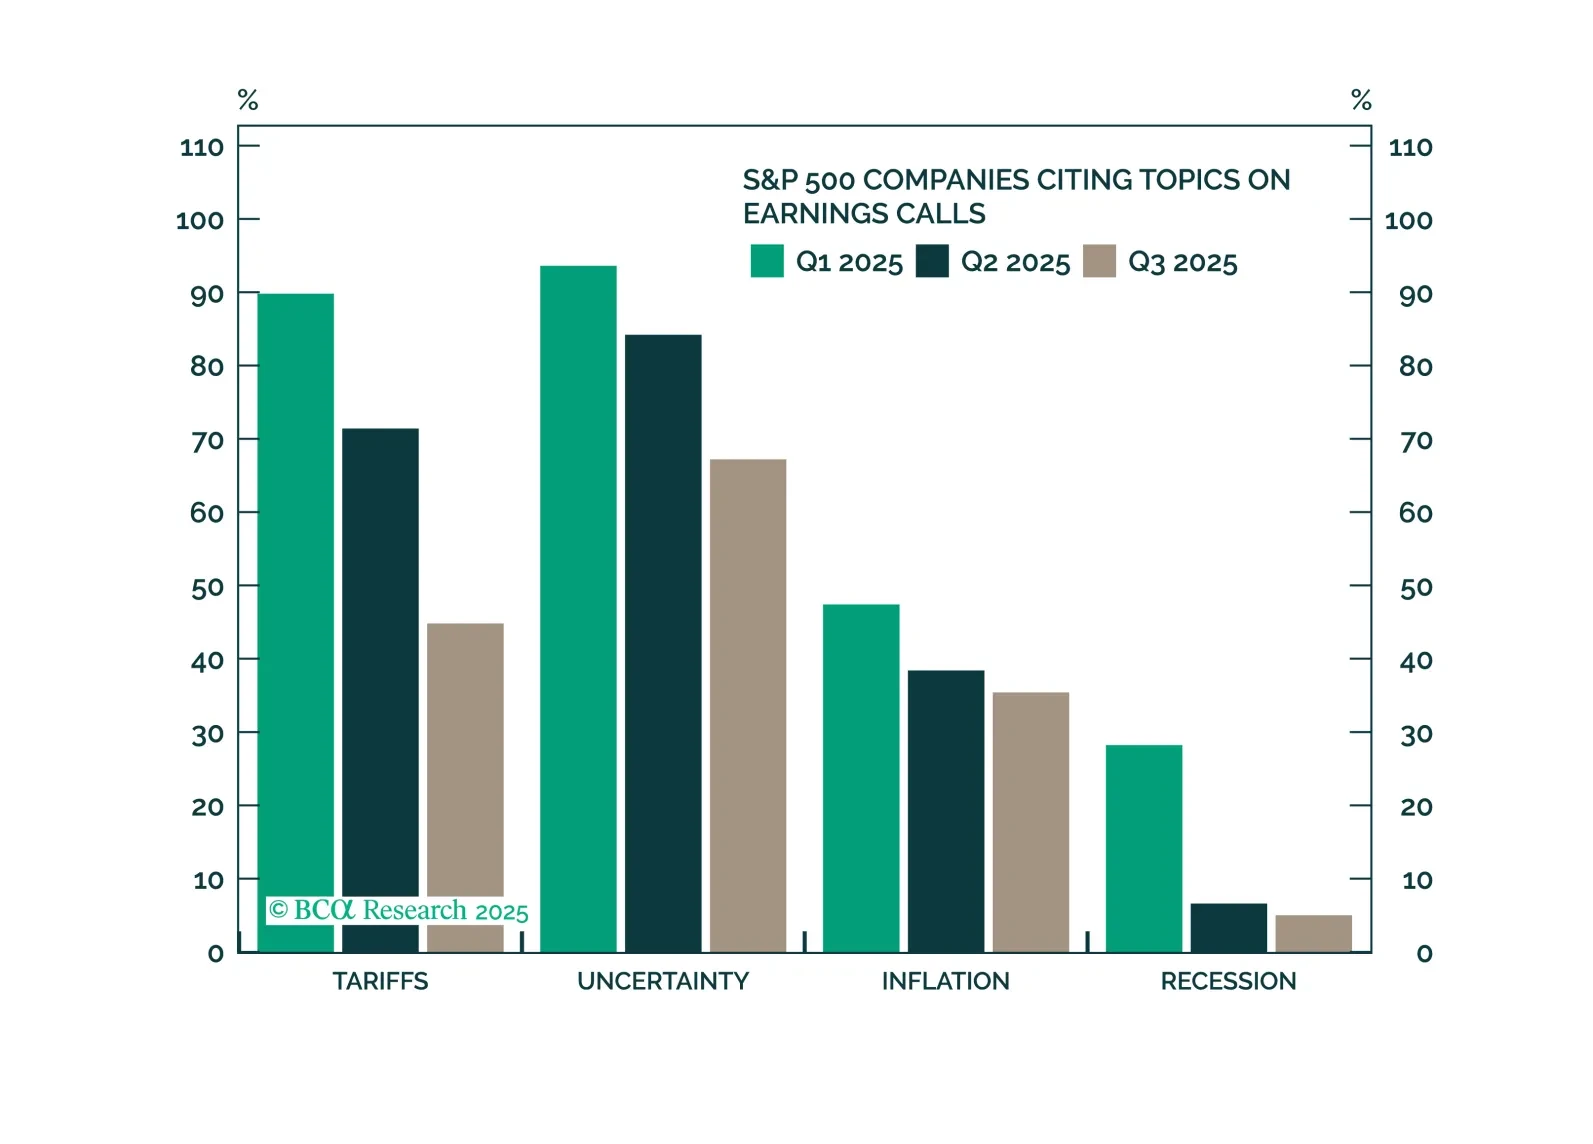
Tariffs are fading in importance as companies successfully mitigate cost pressures and preserve profitability. The recent wave of high-profile layoffs is more concerning, but there does not appear to be a systemic reason behind the announcements. However, emerging labor market softness could pose a major risk for equities. We remain vigilant.
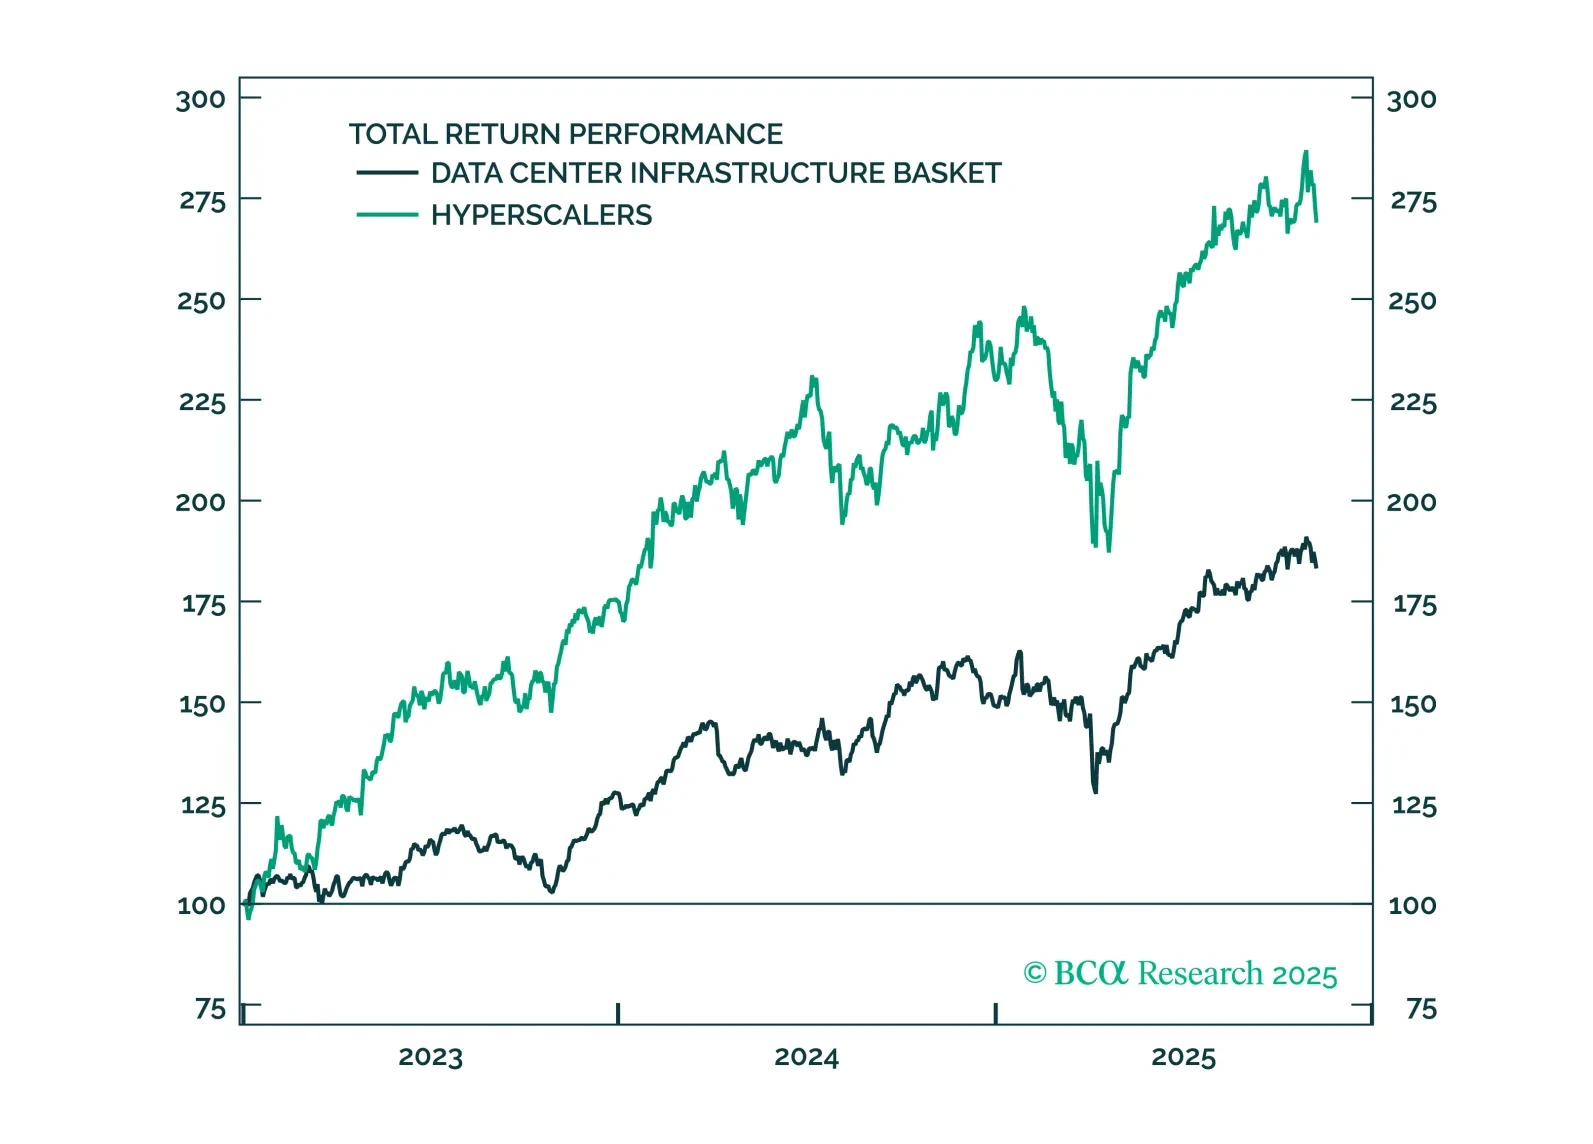
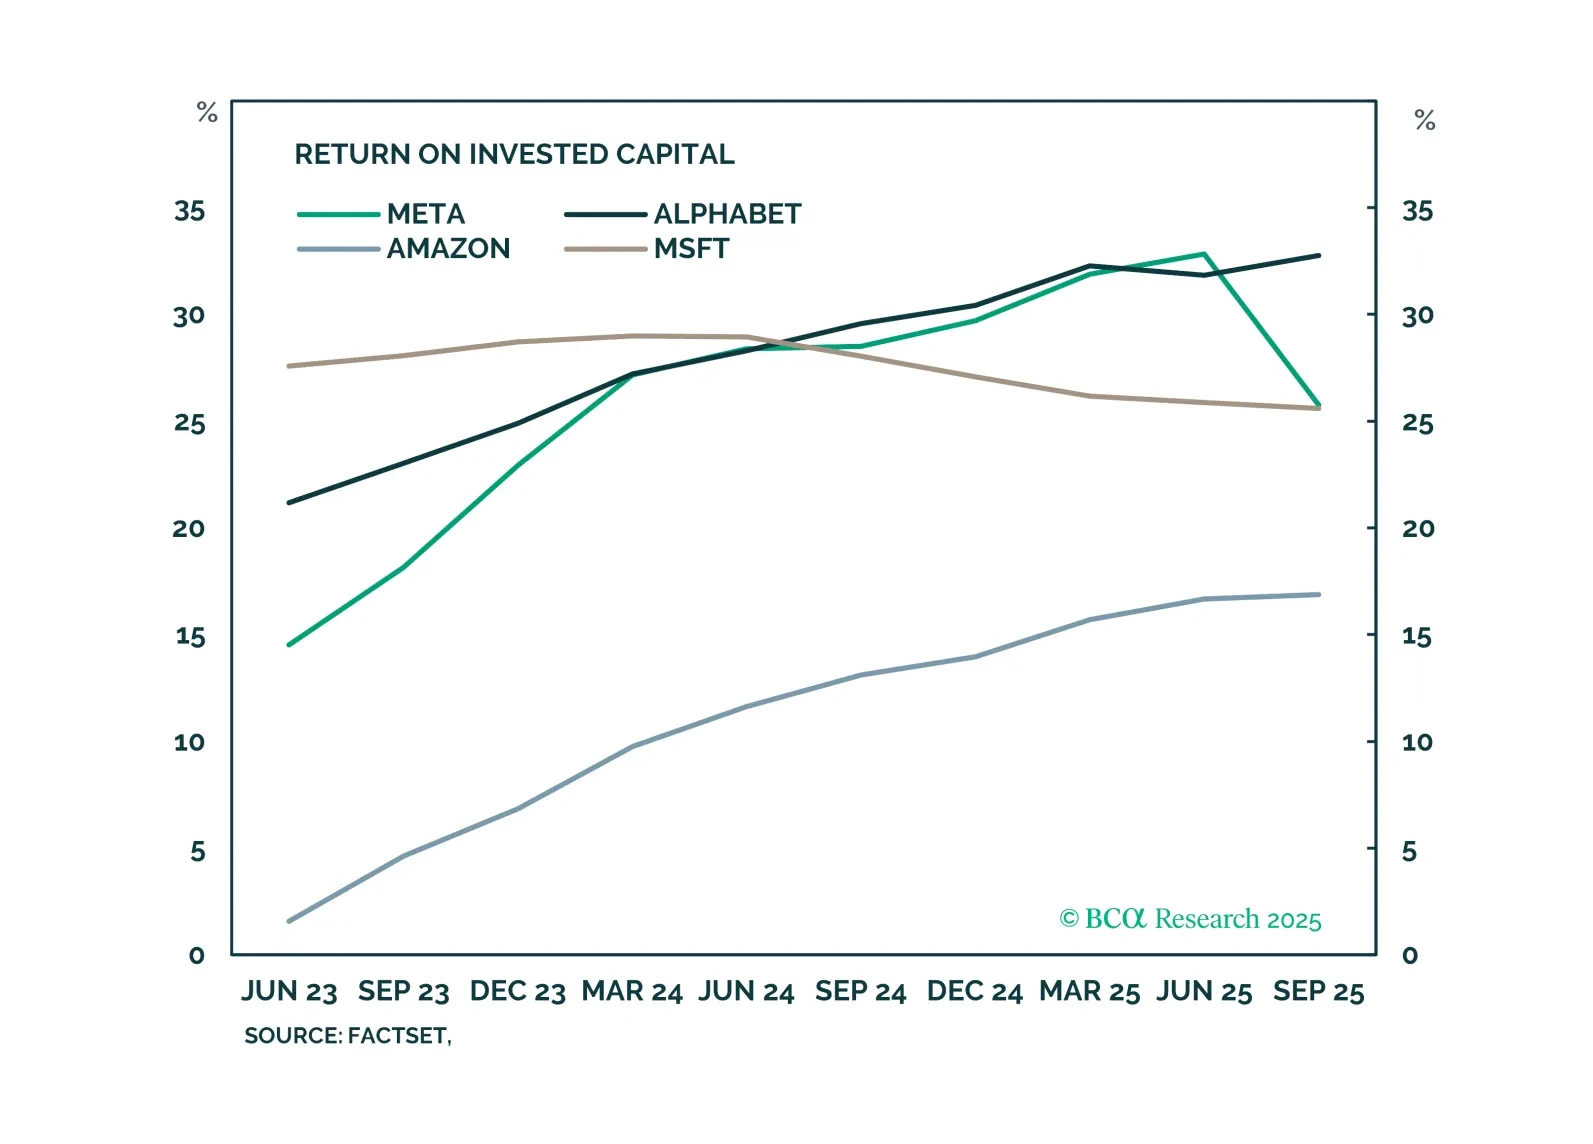
Investor reaction to Meta’s GenAI is an admonition against overspending, rather than a sign of a fraying GenAI rally. Other hyperscalers’ investments are driven by buoyant demand and remain profitable. With valuations stretched and many of the positives priced in, market consolidation is likely. We are decreasing portfolio beta.