 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
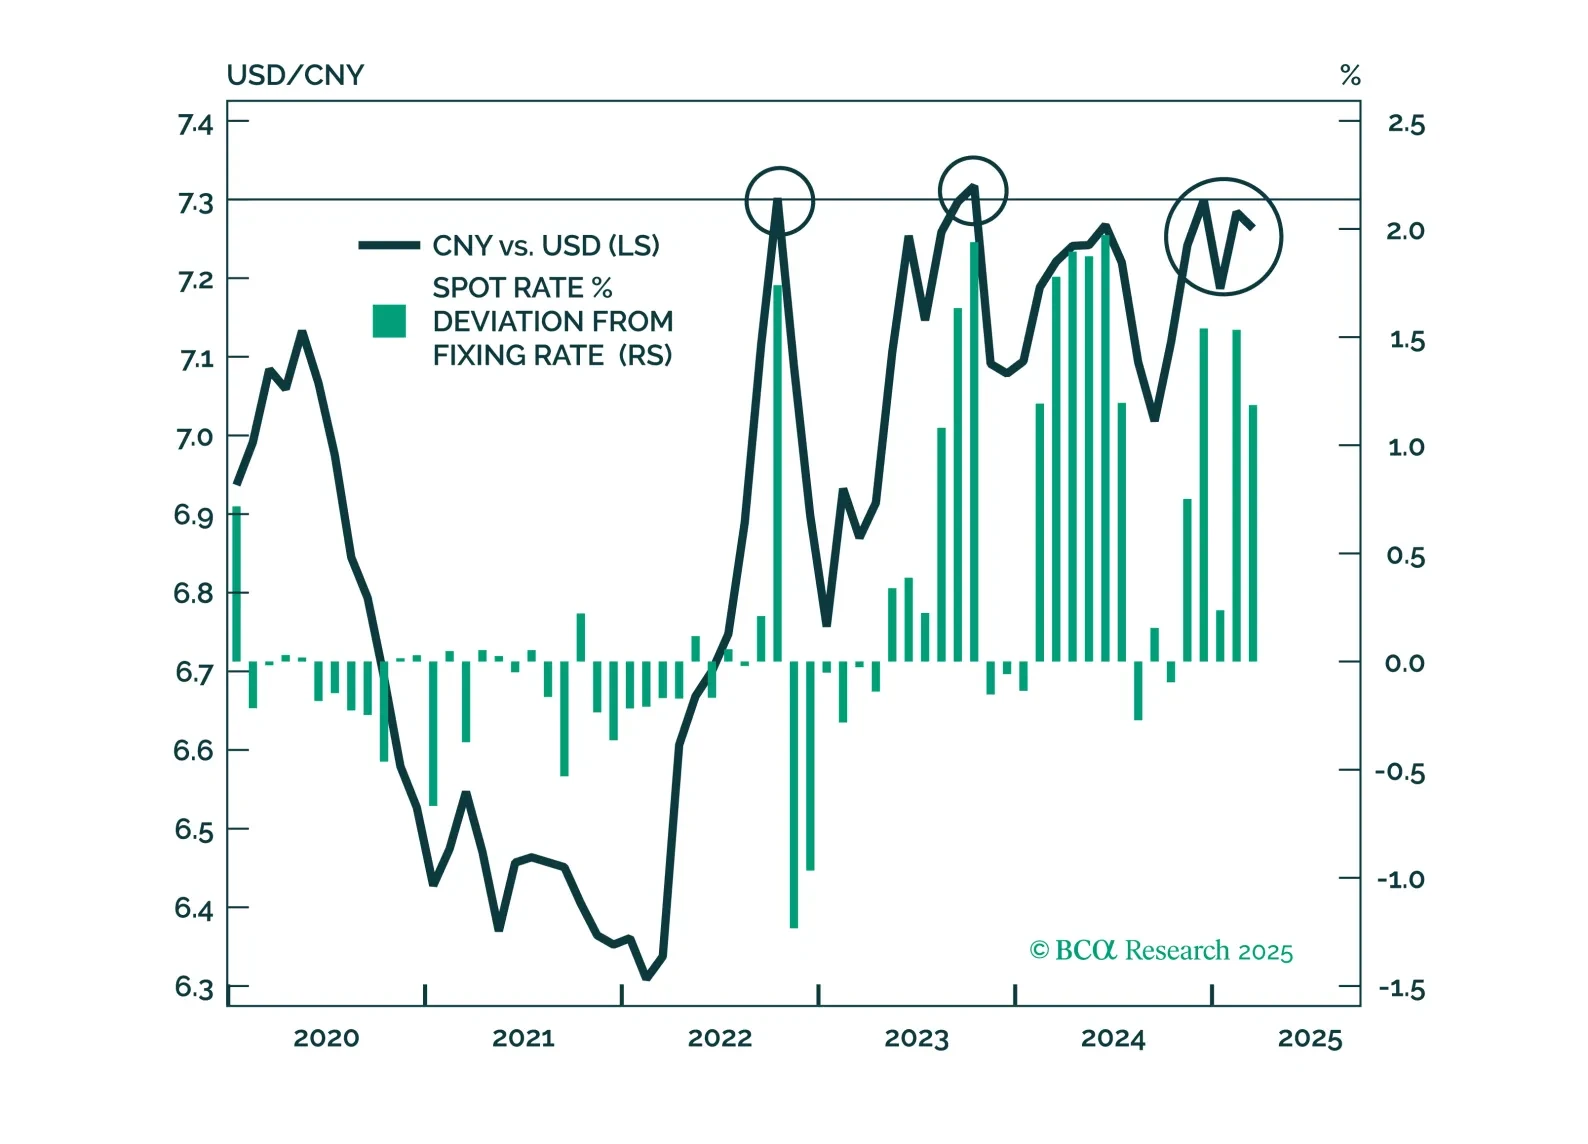
While the United States and China may aim for full decoupling, all they can afford now is some form of trade skirmishes. Increasing economic pressure will eventually force both Washington and Beijing to pursue more proactive negotiations. Until then, internal economic and financial strains are likely necessary to break the stalemate and resume dialogue between the two nations.
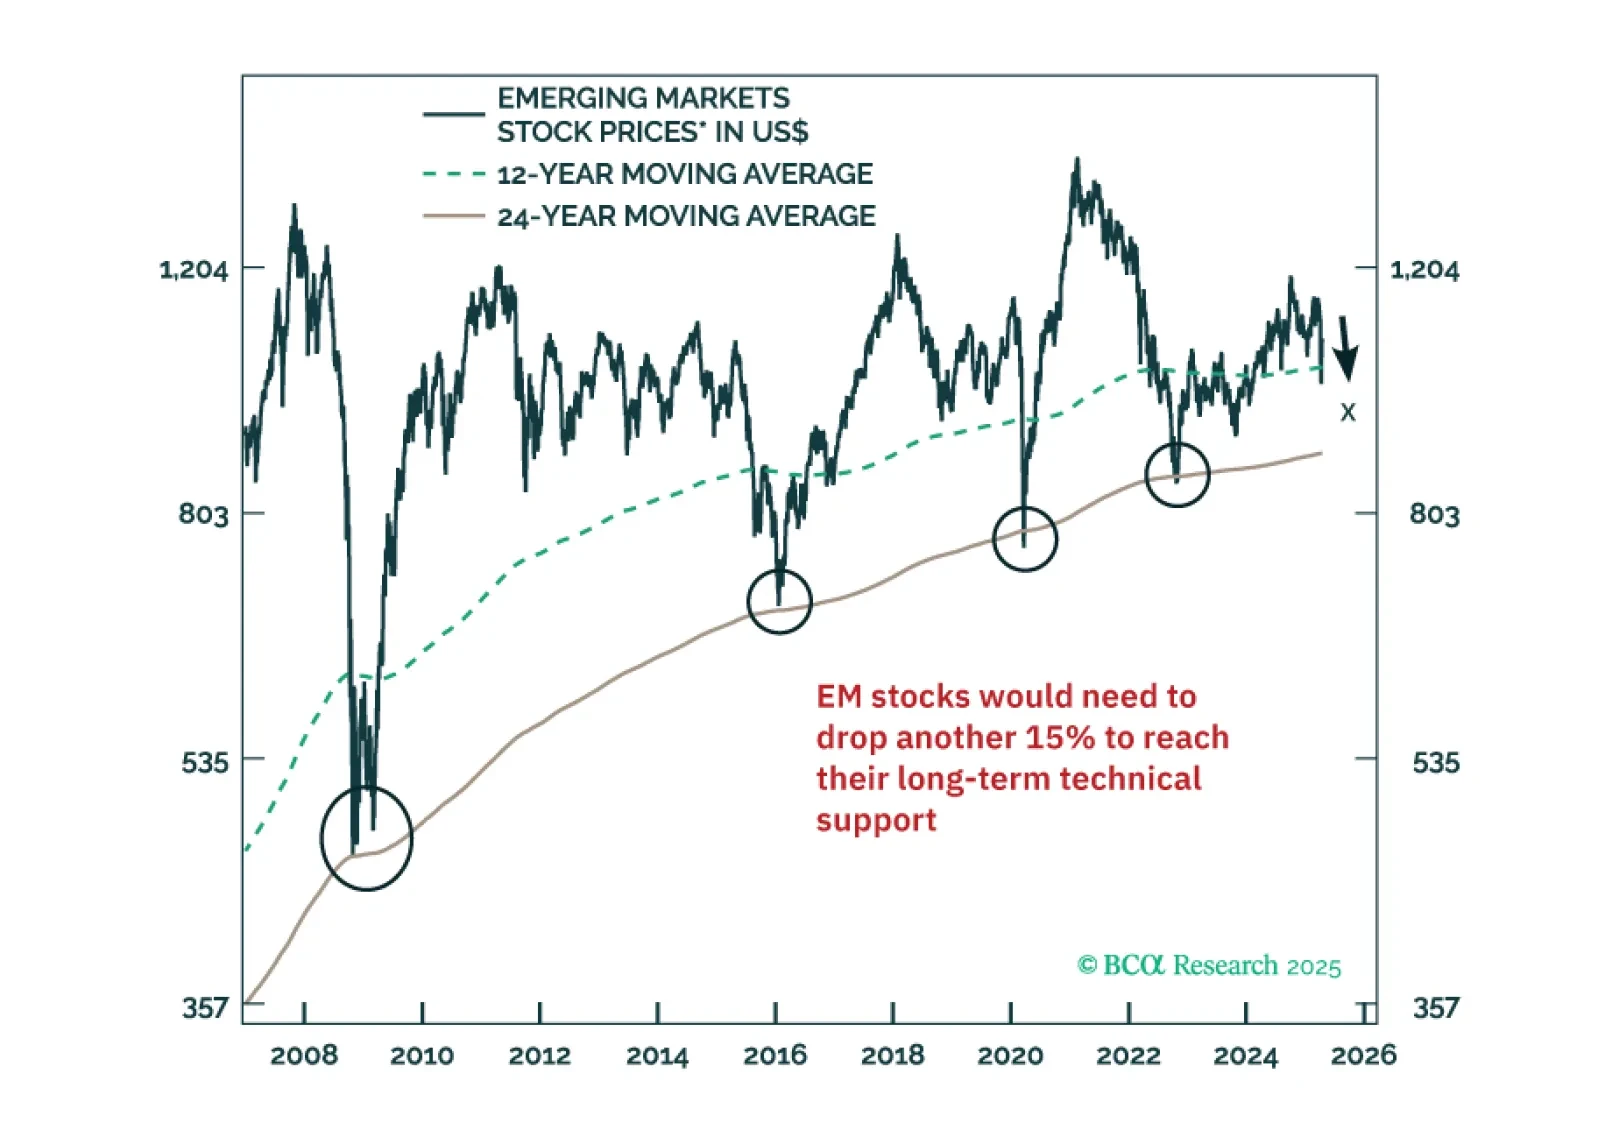
Even after policymakers retract their prejudicial actions, financial markets might continue selling off. We compare the current tariff shock with two past episodes when policy reversals did not produce market turnarounds: (1) the RMB devaluation in August 2015, and (2) the US Congress's initial rejection of the TARP bank bailout program in 2008. In addition, we show numerous technical indicators illustrating at which levels the potential bottom in various equity markets could be.
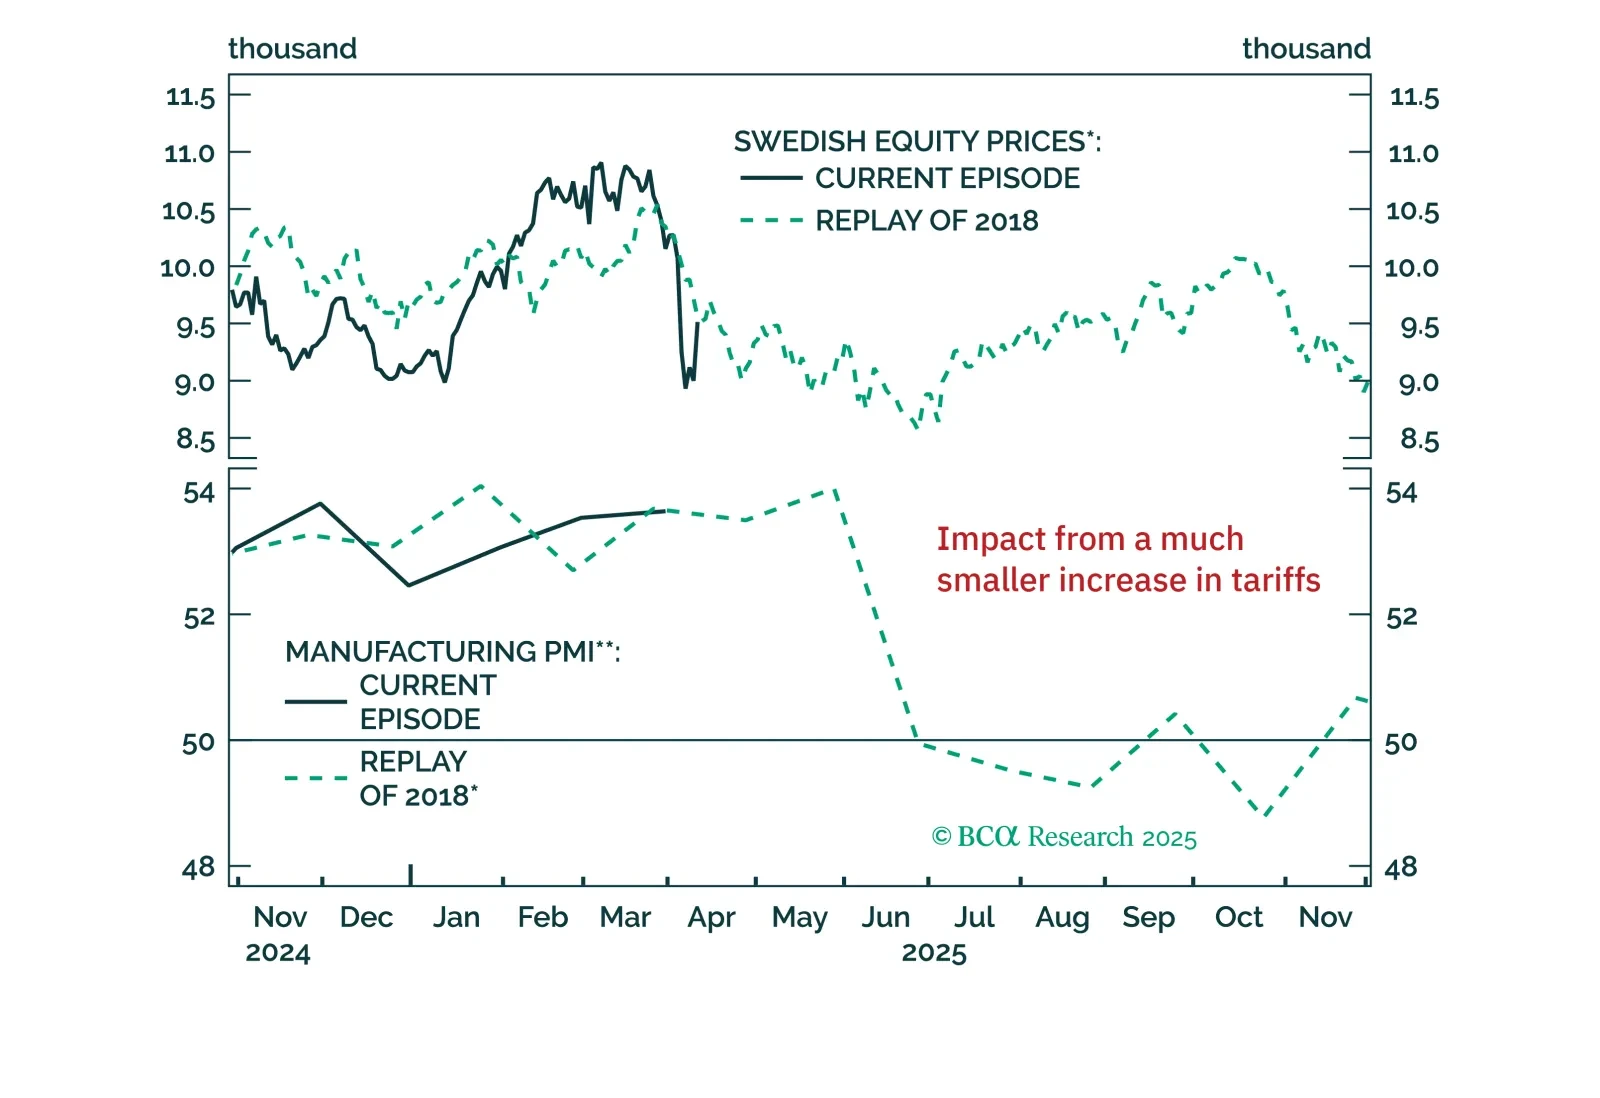
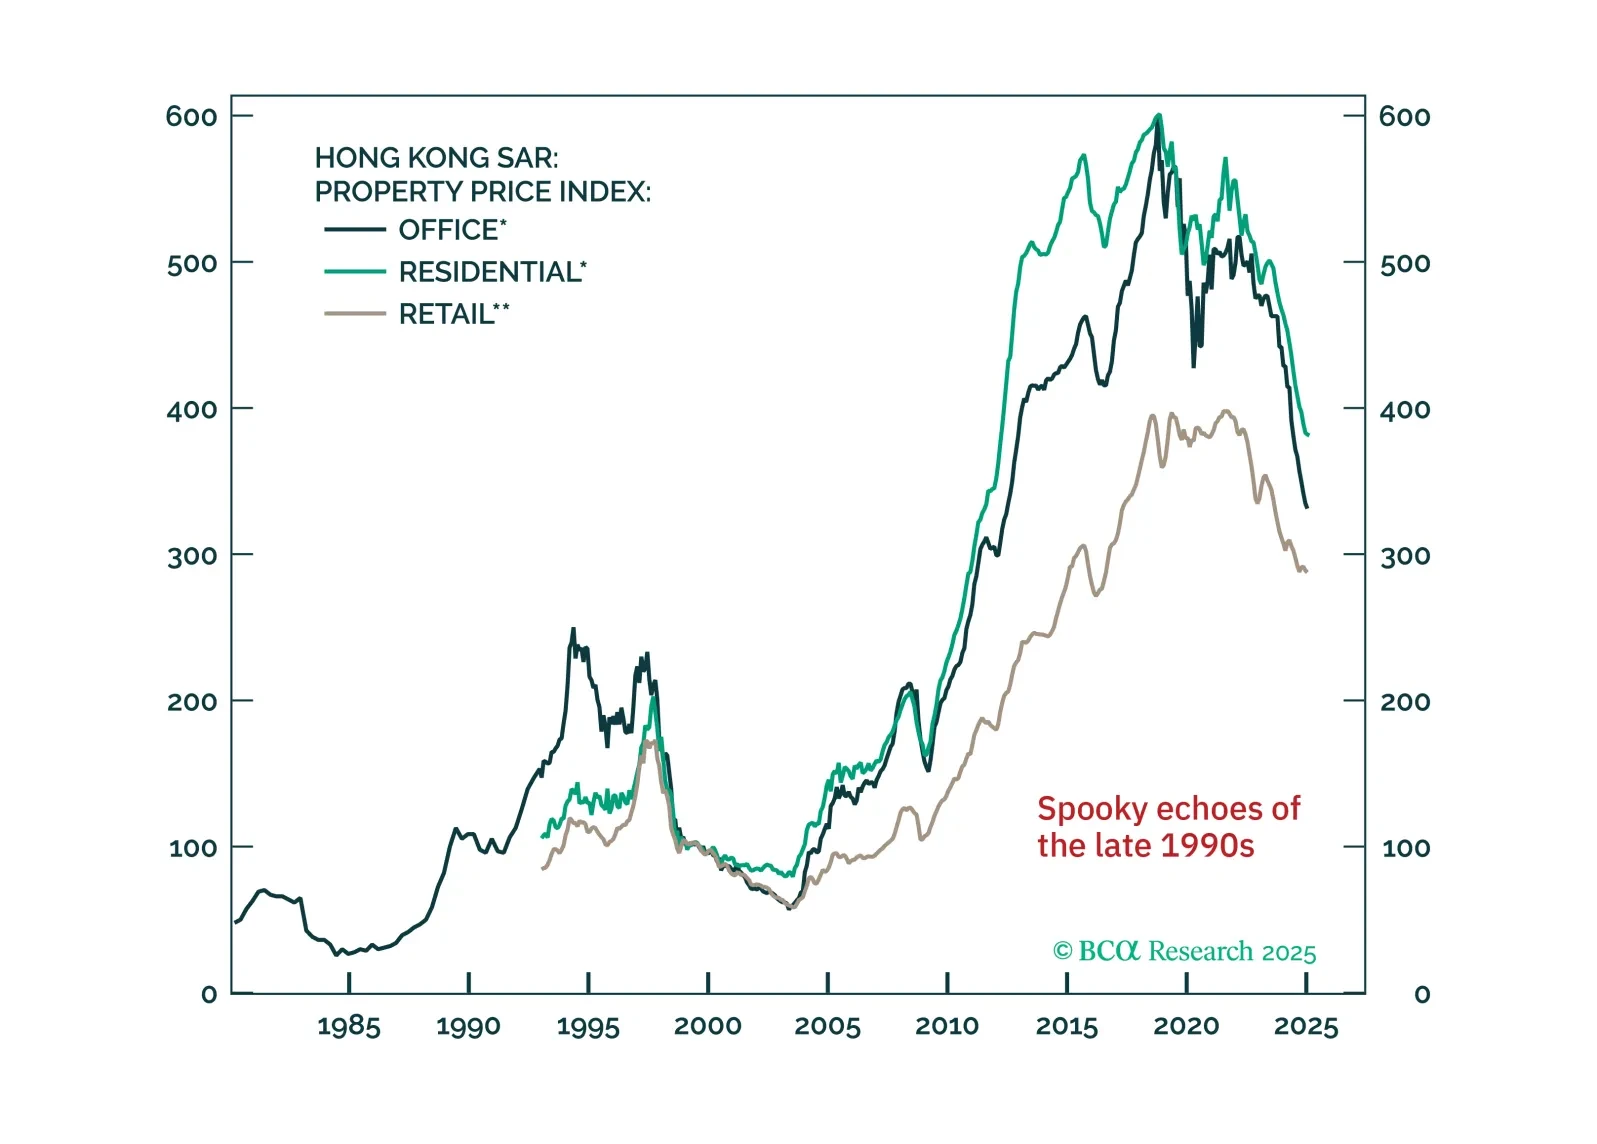
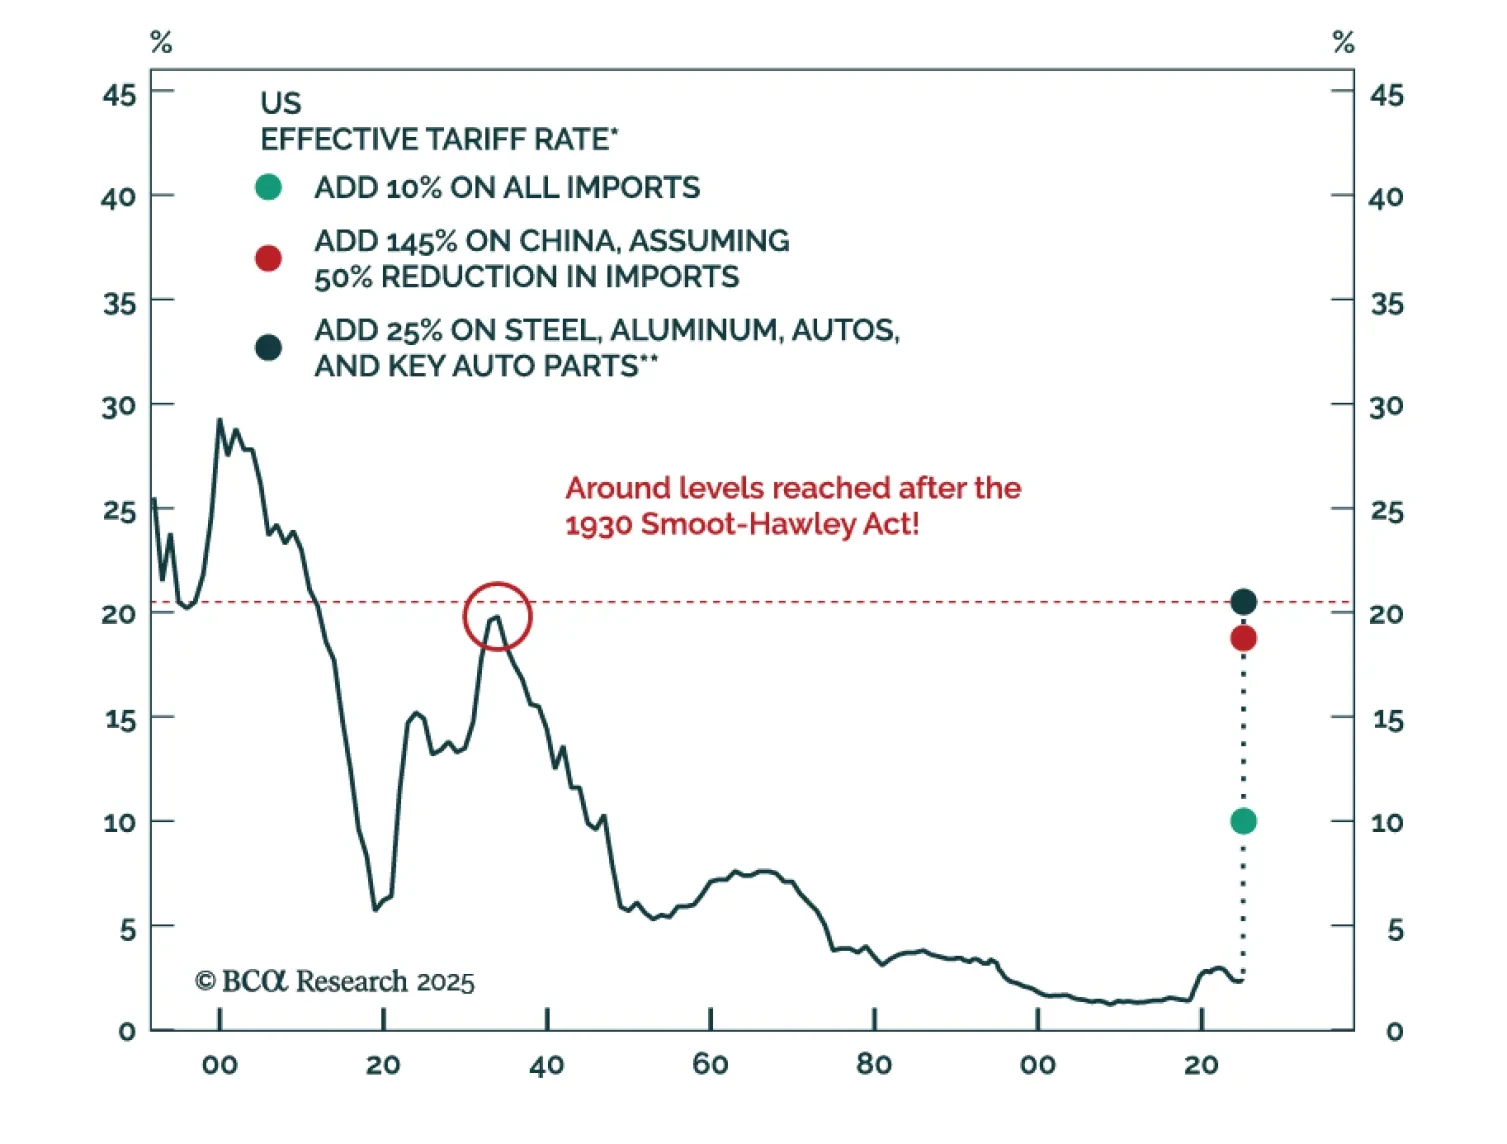
Barring a dramatic further de-escalation of the trade war, the US and much of the rest of the world will enter a recession over the next few months. Investors should remain defensively positioned for now.

We believe Beijing views these US trade actions as nothing short of a declaration of economic war, not just a trade dispute. The US-China confrontation is set to escalate from here. Chinese authorities will allow the yuan to depreciate materially. Go short CNH against the US dollar. For EM and Asian equity portfolios, we are downgrading Chinese investable/offshore stocks from neutral to underweight.
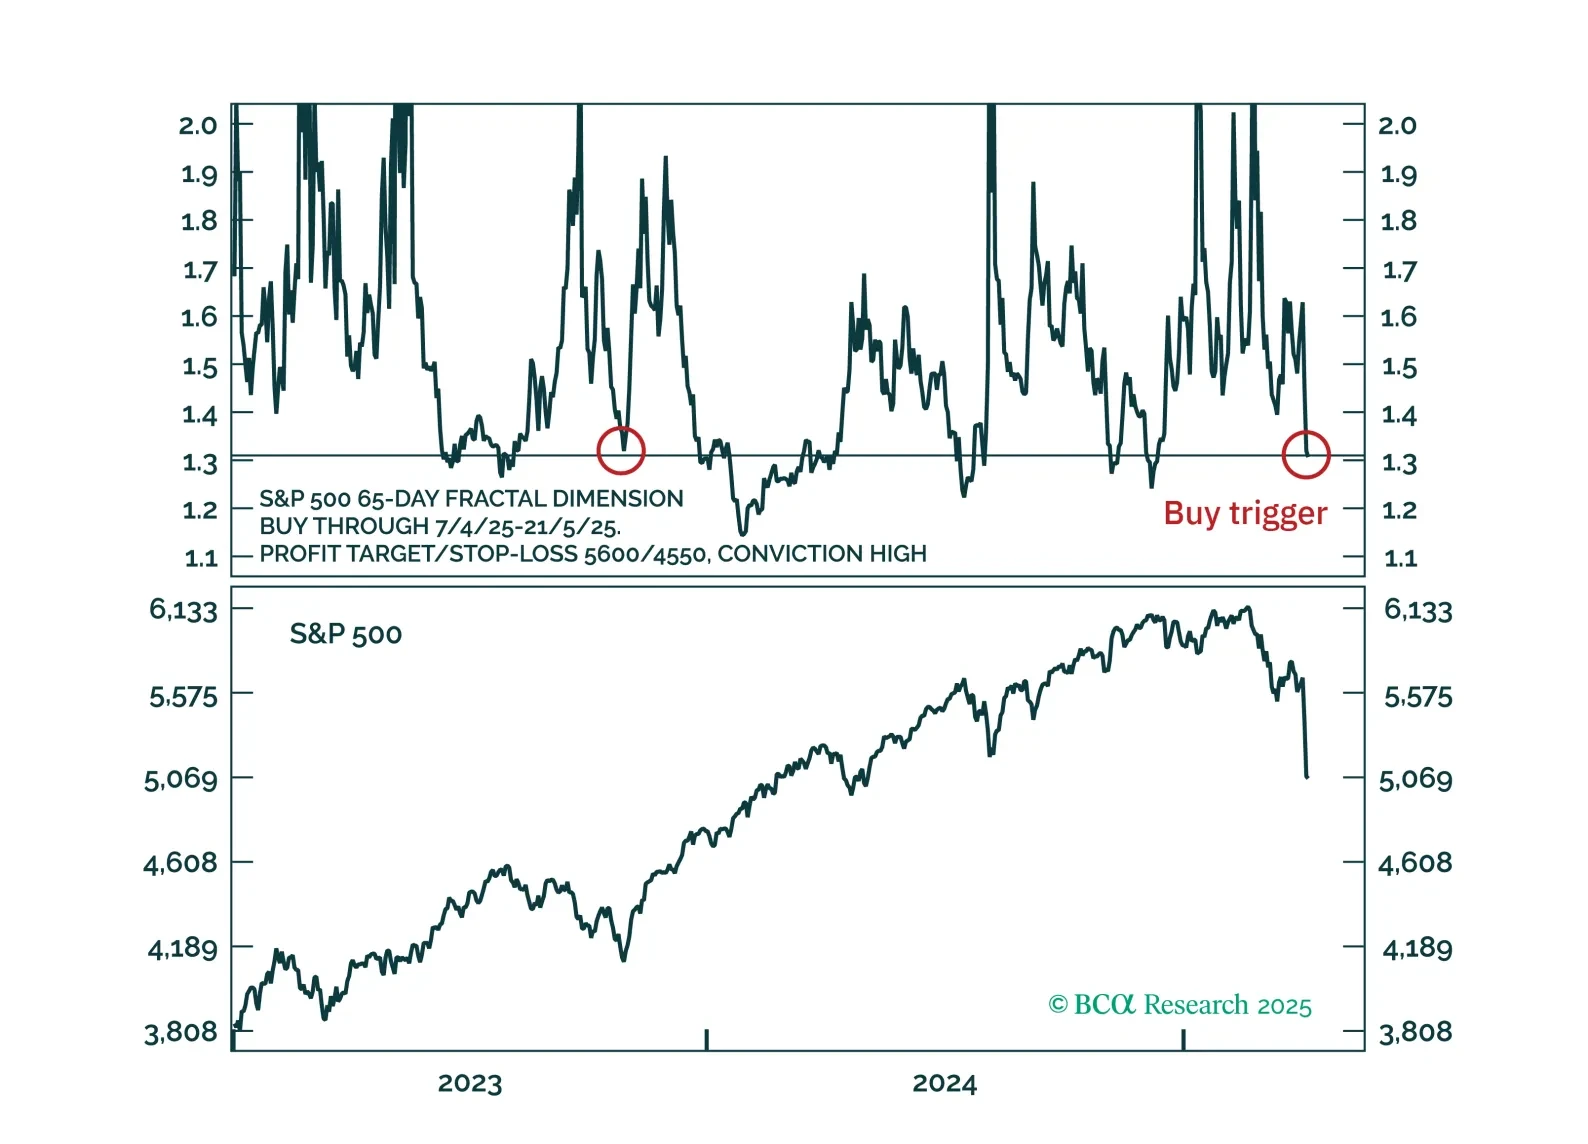
Countertrend buy triggers have been activated for the S&P 500, Nasdaq and Nasdaq versus 30-year T-bond.
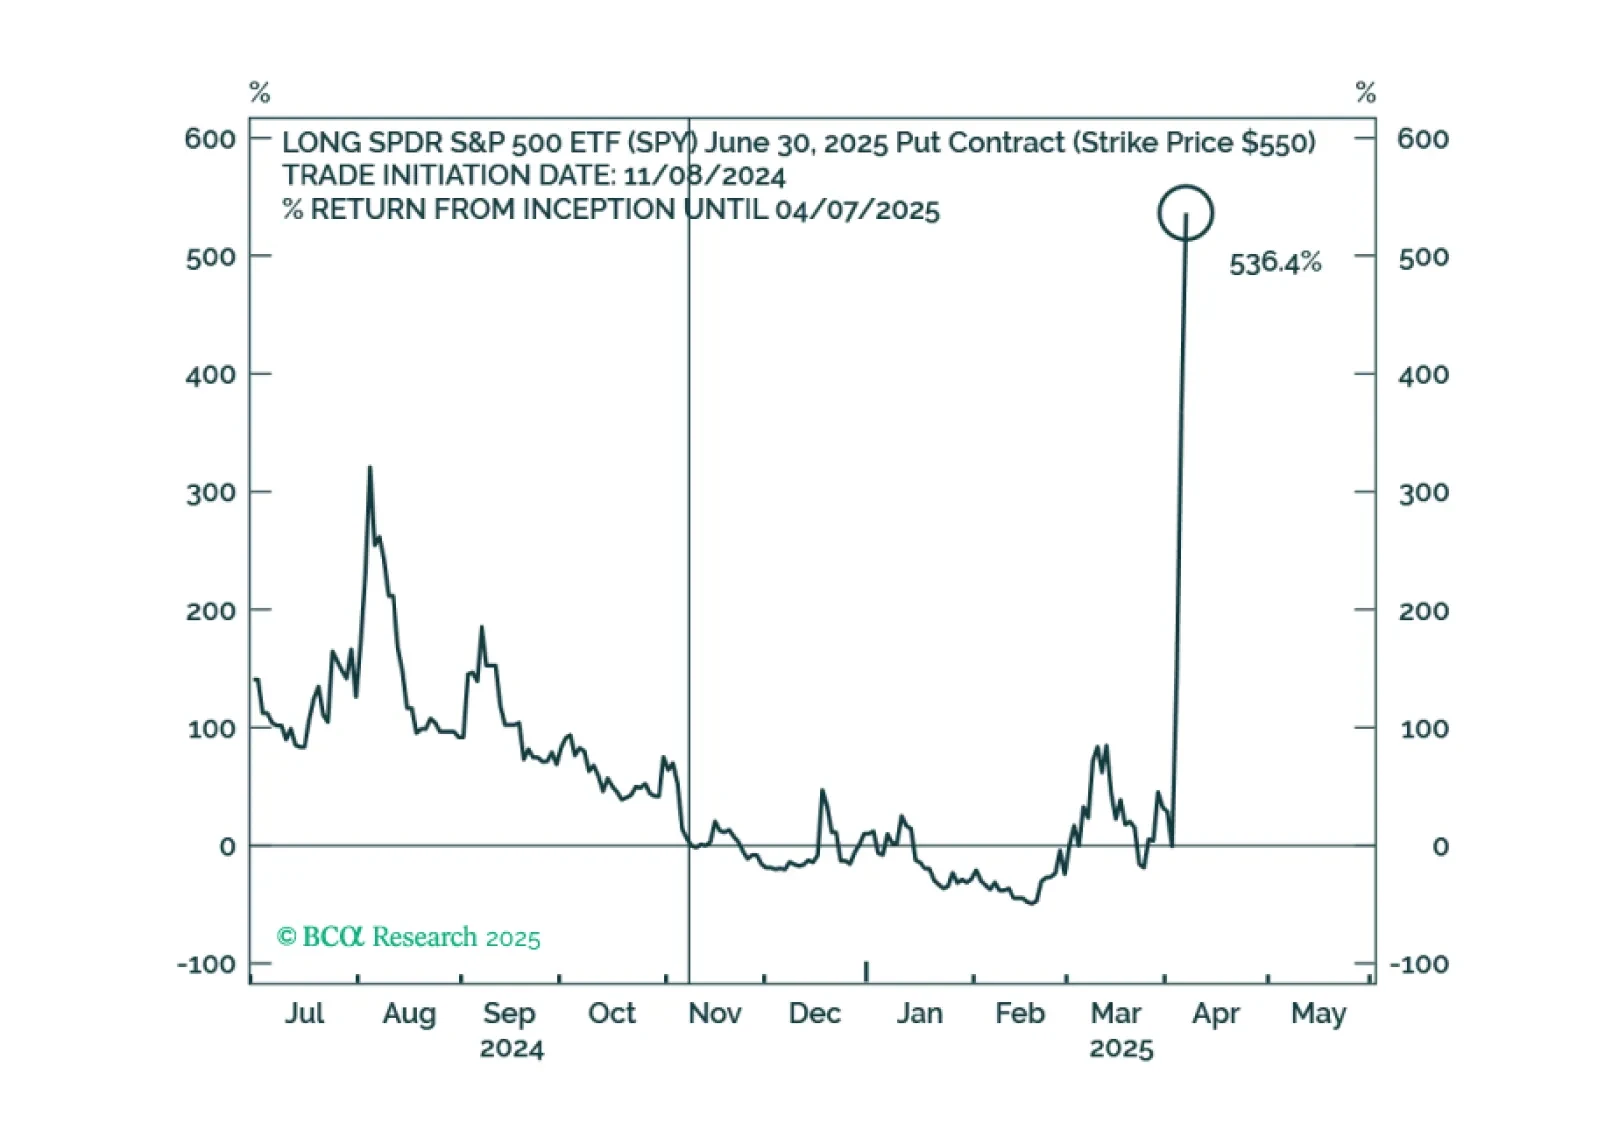
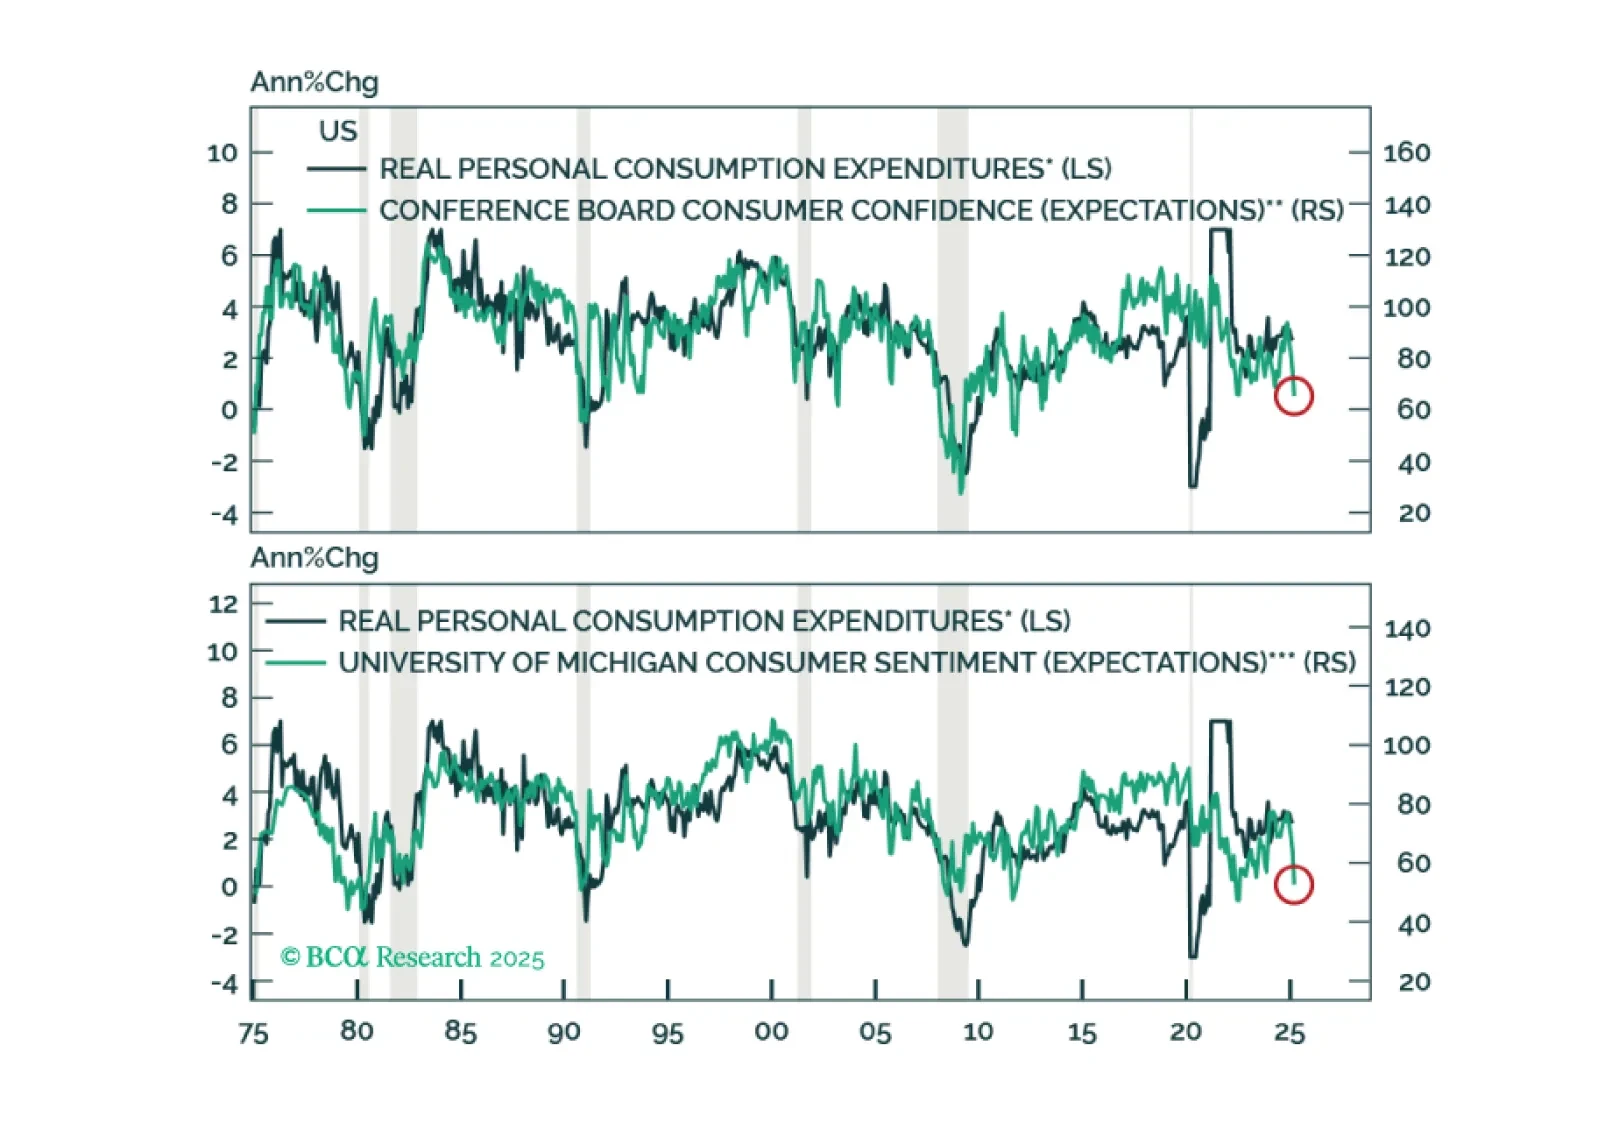
Going into this year, I was by far the most bearish strategist in the Bloomberg survey. A number of clients have reached out to me asking if I plan to change my end-year price of 4450 for the S&P 500 in light of recent events. The answer is “no,” since recent events have unfolded broadly in line with my expectations.
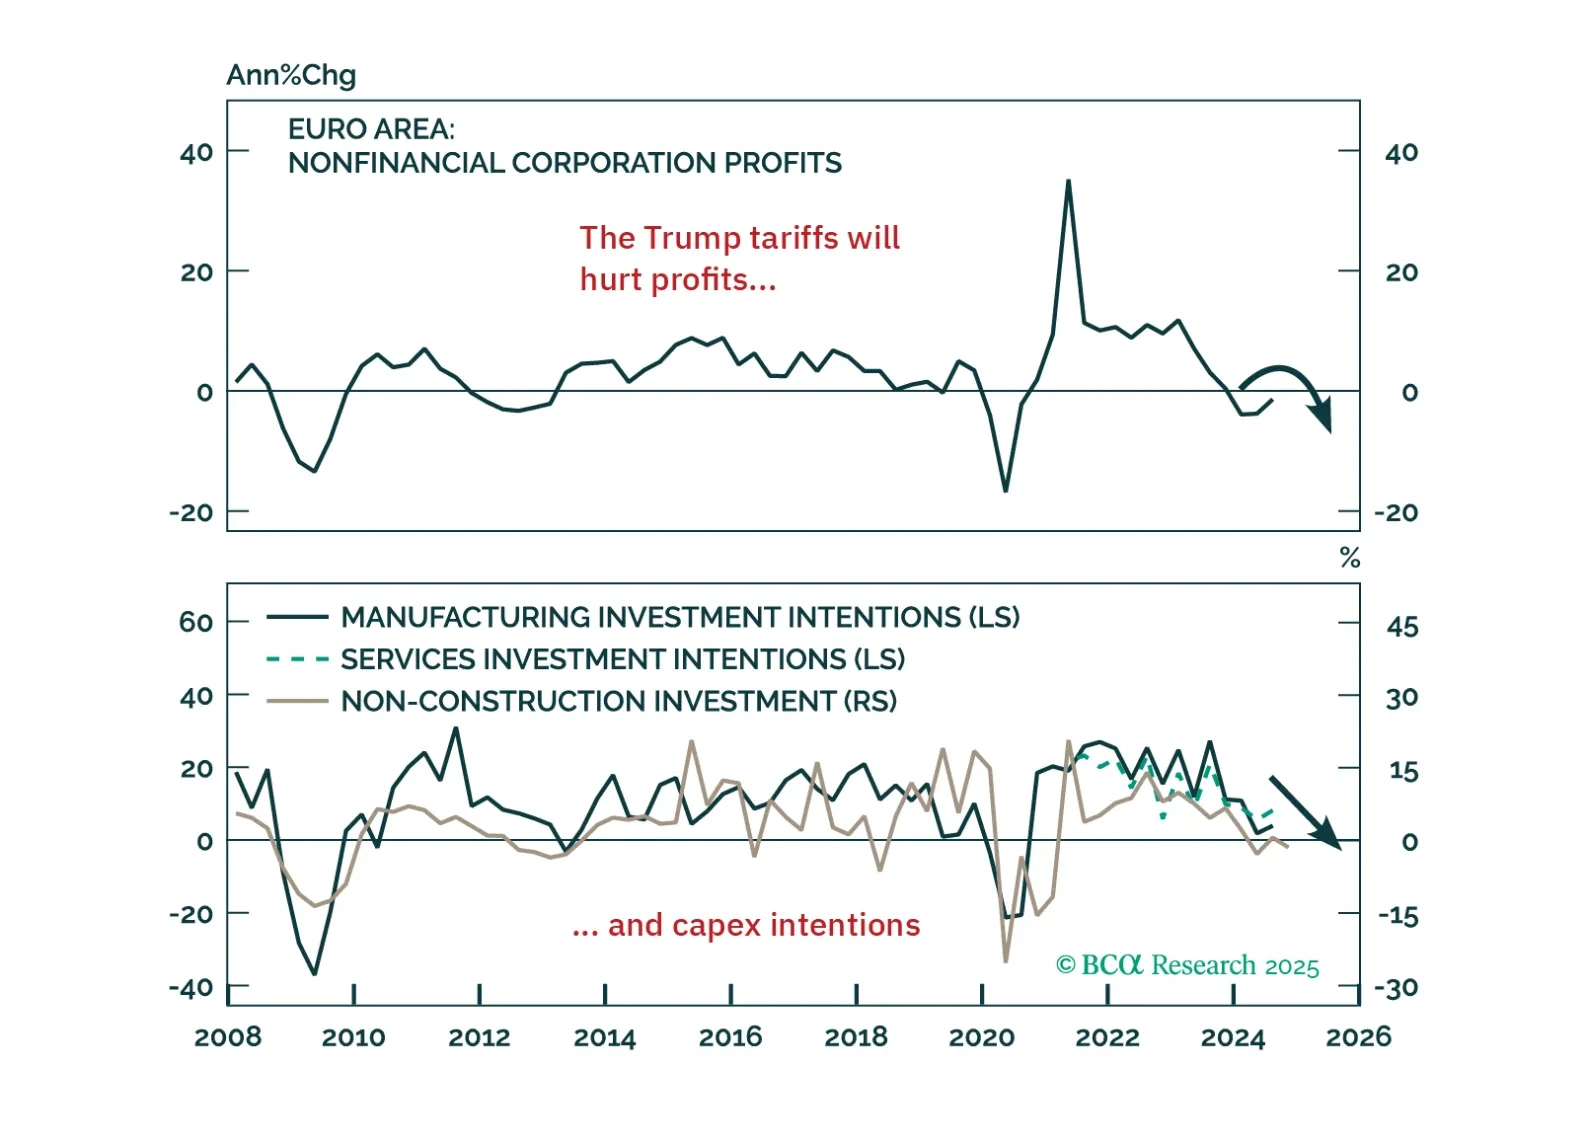
Trump’s tariff shock will push Europe into recession — but it’s also triggering a powerful integration response. In this report, we lay out the tactical case for staying defensive and the structural case for going long European assets when the dust settles.