Regiones Geopolíticas
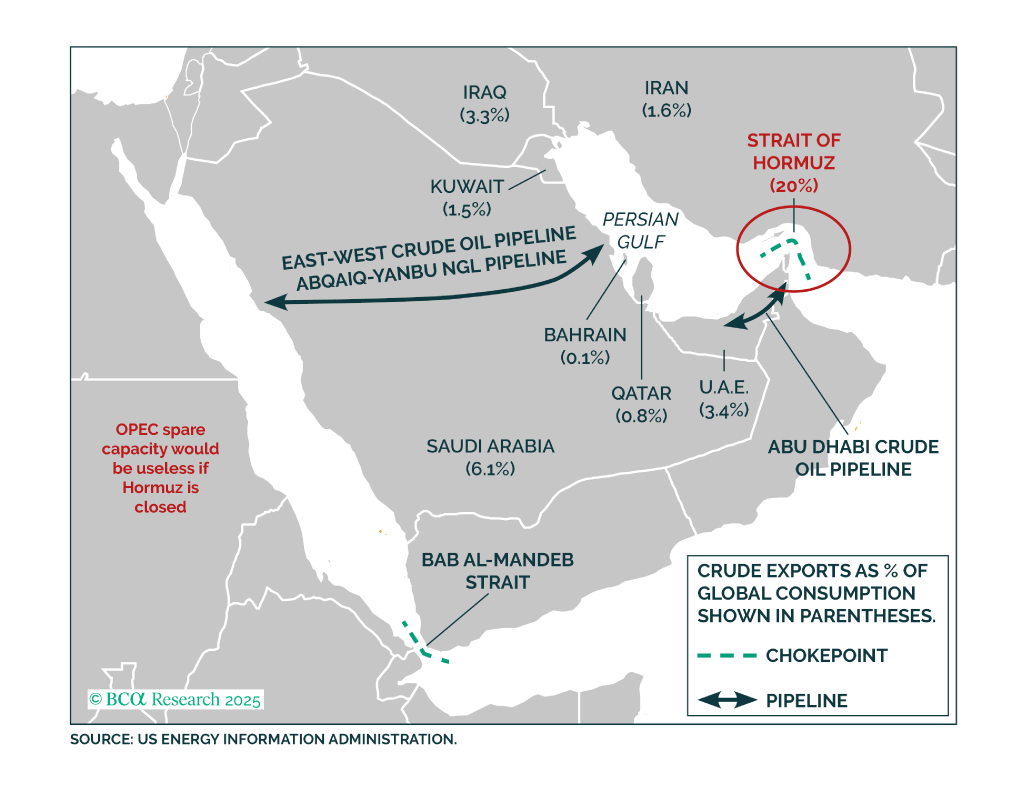
Disrupciones de Petróleo: No Seas Complaciente Disrupciones de Petróleo: No Seas Complaciente Nuestros estrategas de materias primas ven los crecientes riesgos geopolíticos como un catalizador para el desempeño superior del oro y advierten que los mercados de…
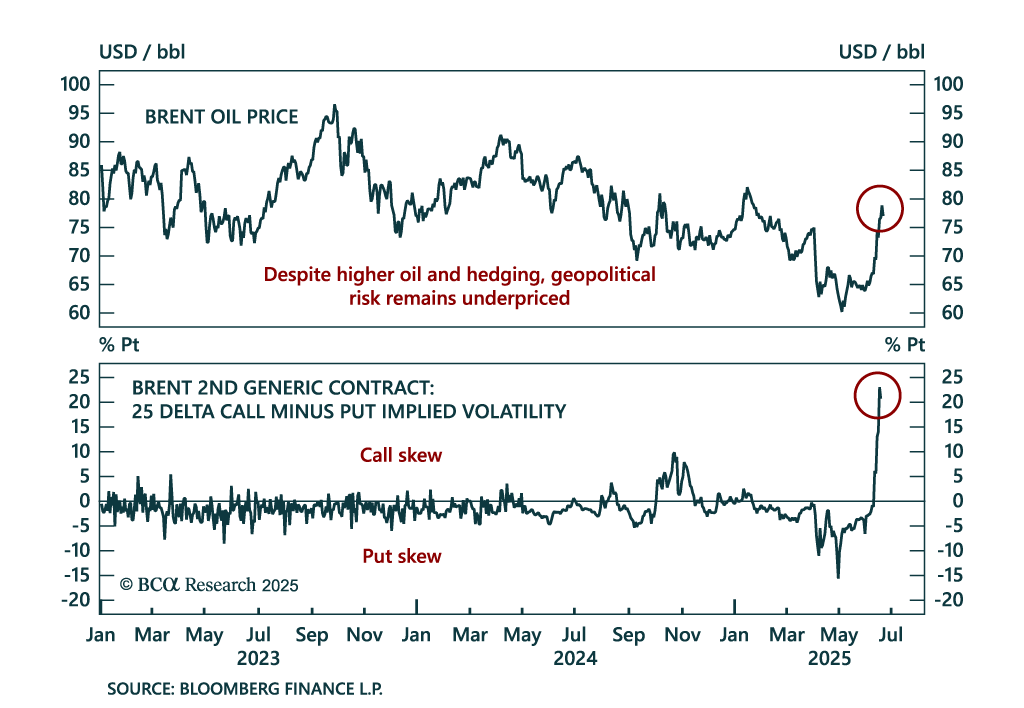
Tensiones en Medio Oriente: Actualización del 23 de junio Tensiones en Medio Oriente: Actualización del 23 de junio La complacencia elevada del mercado contrasta con el alto riesgo geopolítico mientras la interrupción del petróleo sigue siendo una amenaza…
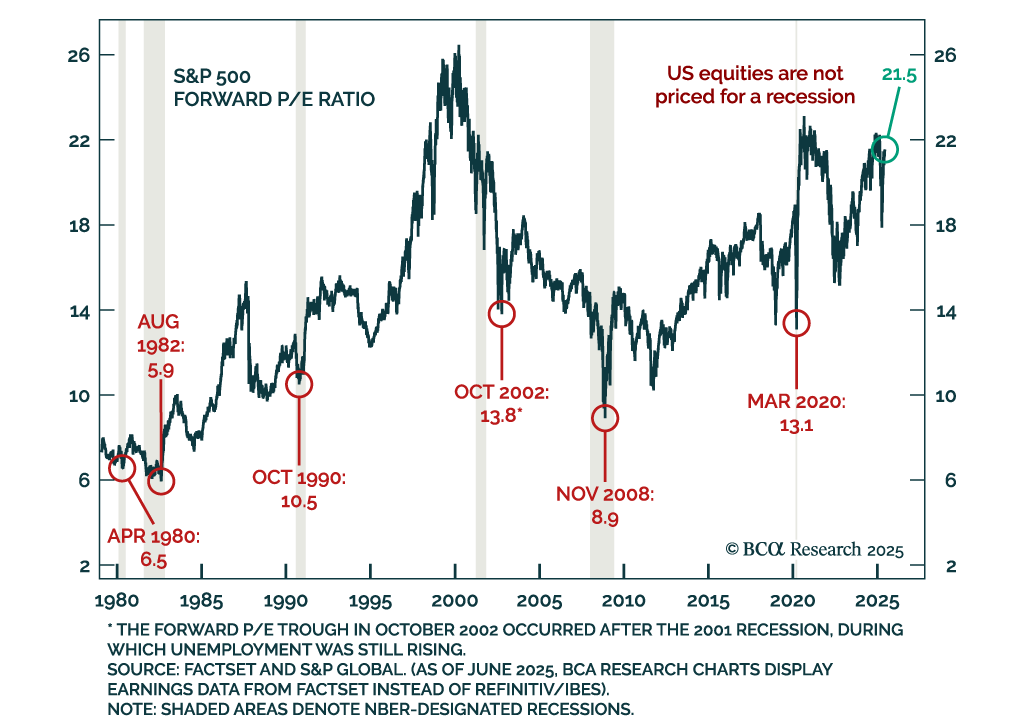
Los Riesgos de Irán y la Fragilidad de las EPS Subrayan la Necesidad de Precaución Los Riesgos de Irán y la Fragilidad de las EPS Subrayan la Necesidad de Precaución Los riesgos geopolíticos y los márgenes frágiles refuerzan una postura defensiva en la…
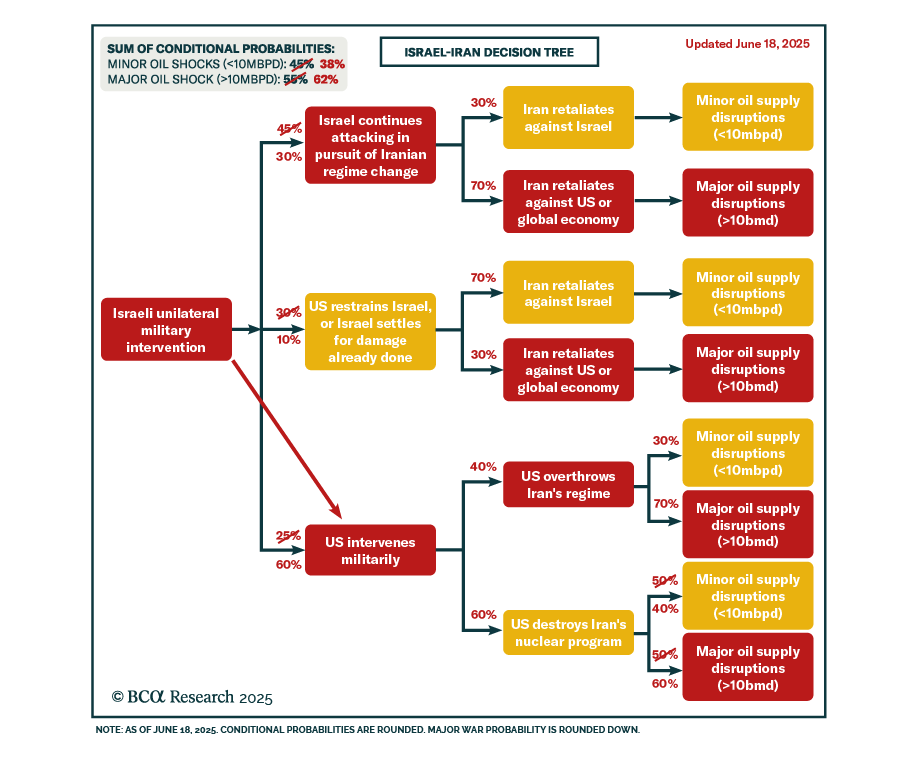
Tensiones entre Israel e Irán: Actualización del 18 de junio Tensiones entre Israel e Irán: Actualización del 18 de junio Nuestros estrategas geopolíticos esperan la participación de EE. UU. en la campaña militar de Israel contra Irán, lo que incrementa los…
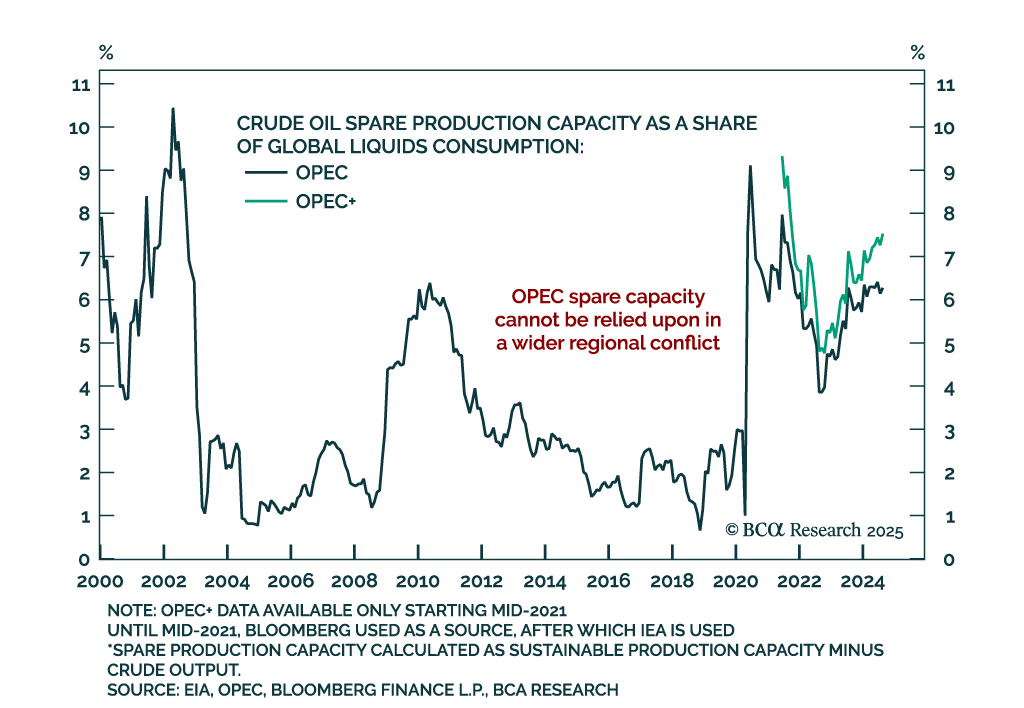
The Israel-Iran conflict is escalating, raising the odds of a major oil supply shock and reinforcing the case for cash, US equity overweight, and tactical energy exposure. Our Chart Of The Week comes from Matt Gertken, Chief Geopolitical and US Political…
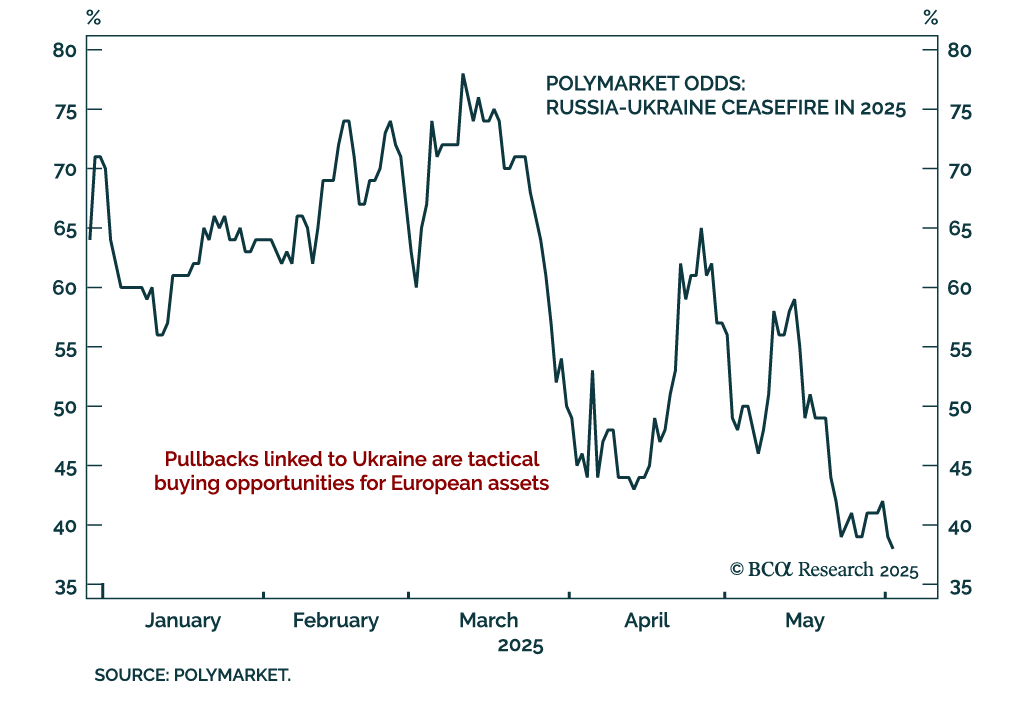
Ongoing military tensions between Ukraine and Rusia and renewed US-EU trade friction reinforce tactical opportunities to add European exposure on dips. Ukraine’s drone strike on Russian air assets and the limited outcome of the latest Istanbul talks point to…
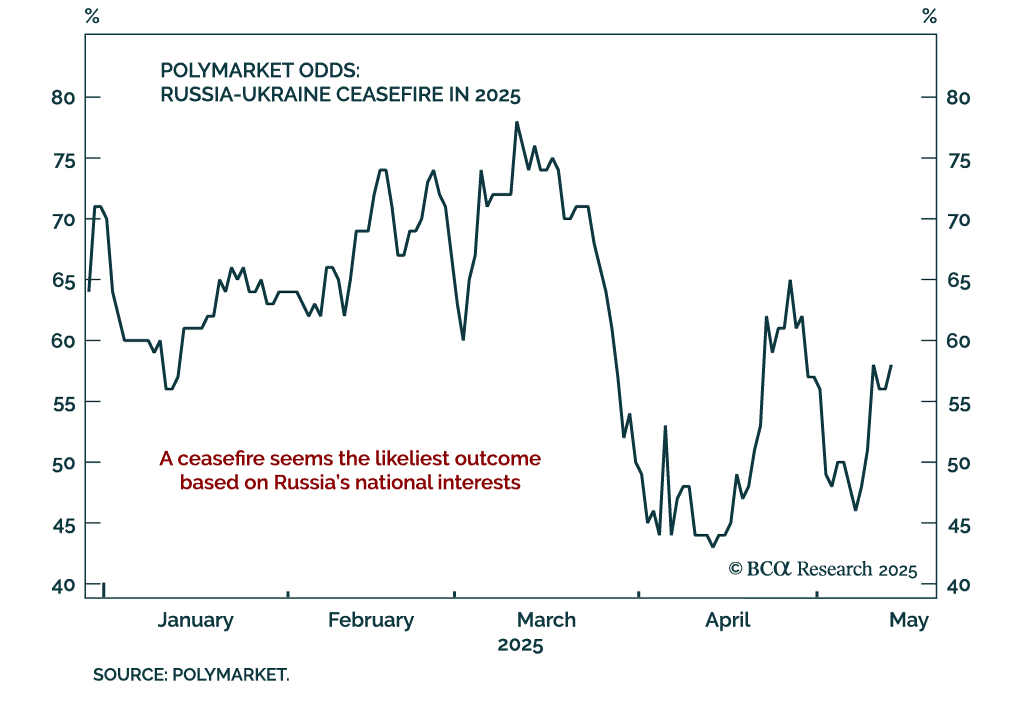
Our Geopolitical strategists expect a Ukraine ceasefire as Russia’s economic weakness compels Putin to shift focus from war to domestic stability. The likely outcome is not peace, but a frozen conflict that enables Russia to consolidate territorial gains…
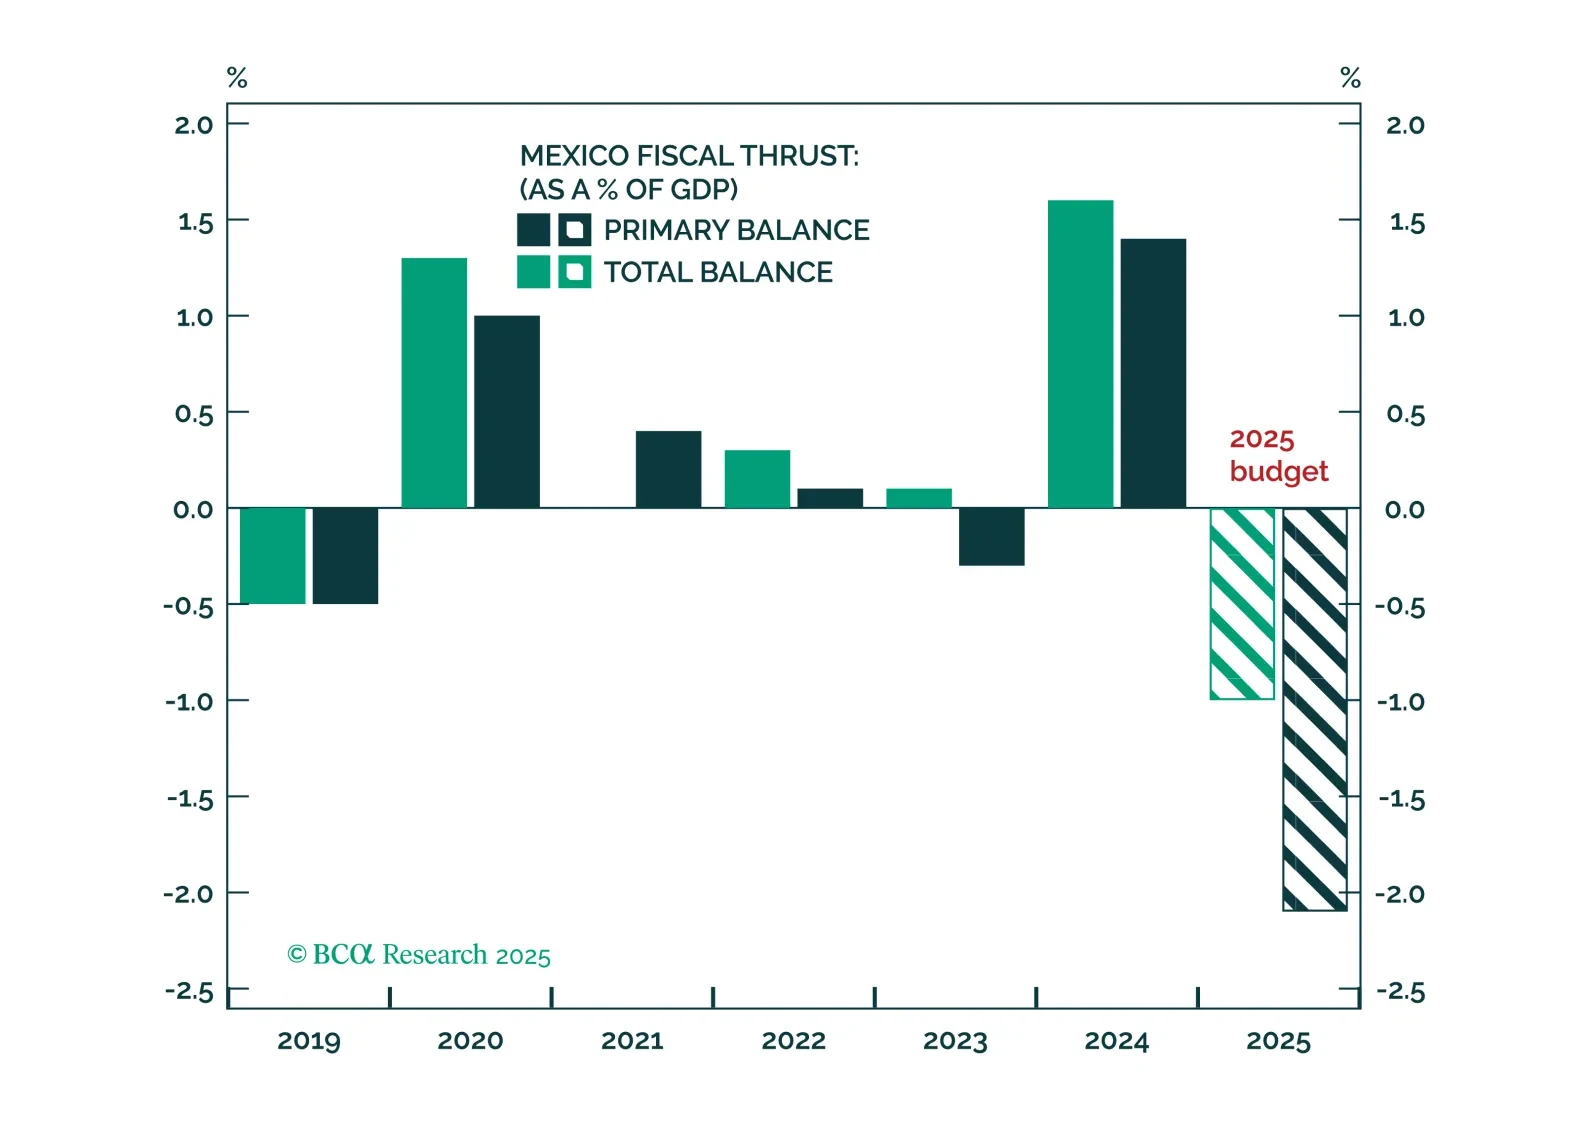
Short-term pain from Trump-related concessions, fiscal tightening amid a US and Mexican slowdown, and rising labor slack will weigh further on Mexican assets. But long-run, policy direction will capitalize on the nearshoring trend and resume the trend of Mexican asset outperformance relative to other emerging markets.

Our Private Markets & Alternatives strategists recommend shifting exposure within Port Infrastructure to India as re-globalization reshapes trade flows. The US will remain a trade leader, but tensions with China and the reorganization of supply chains will…
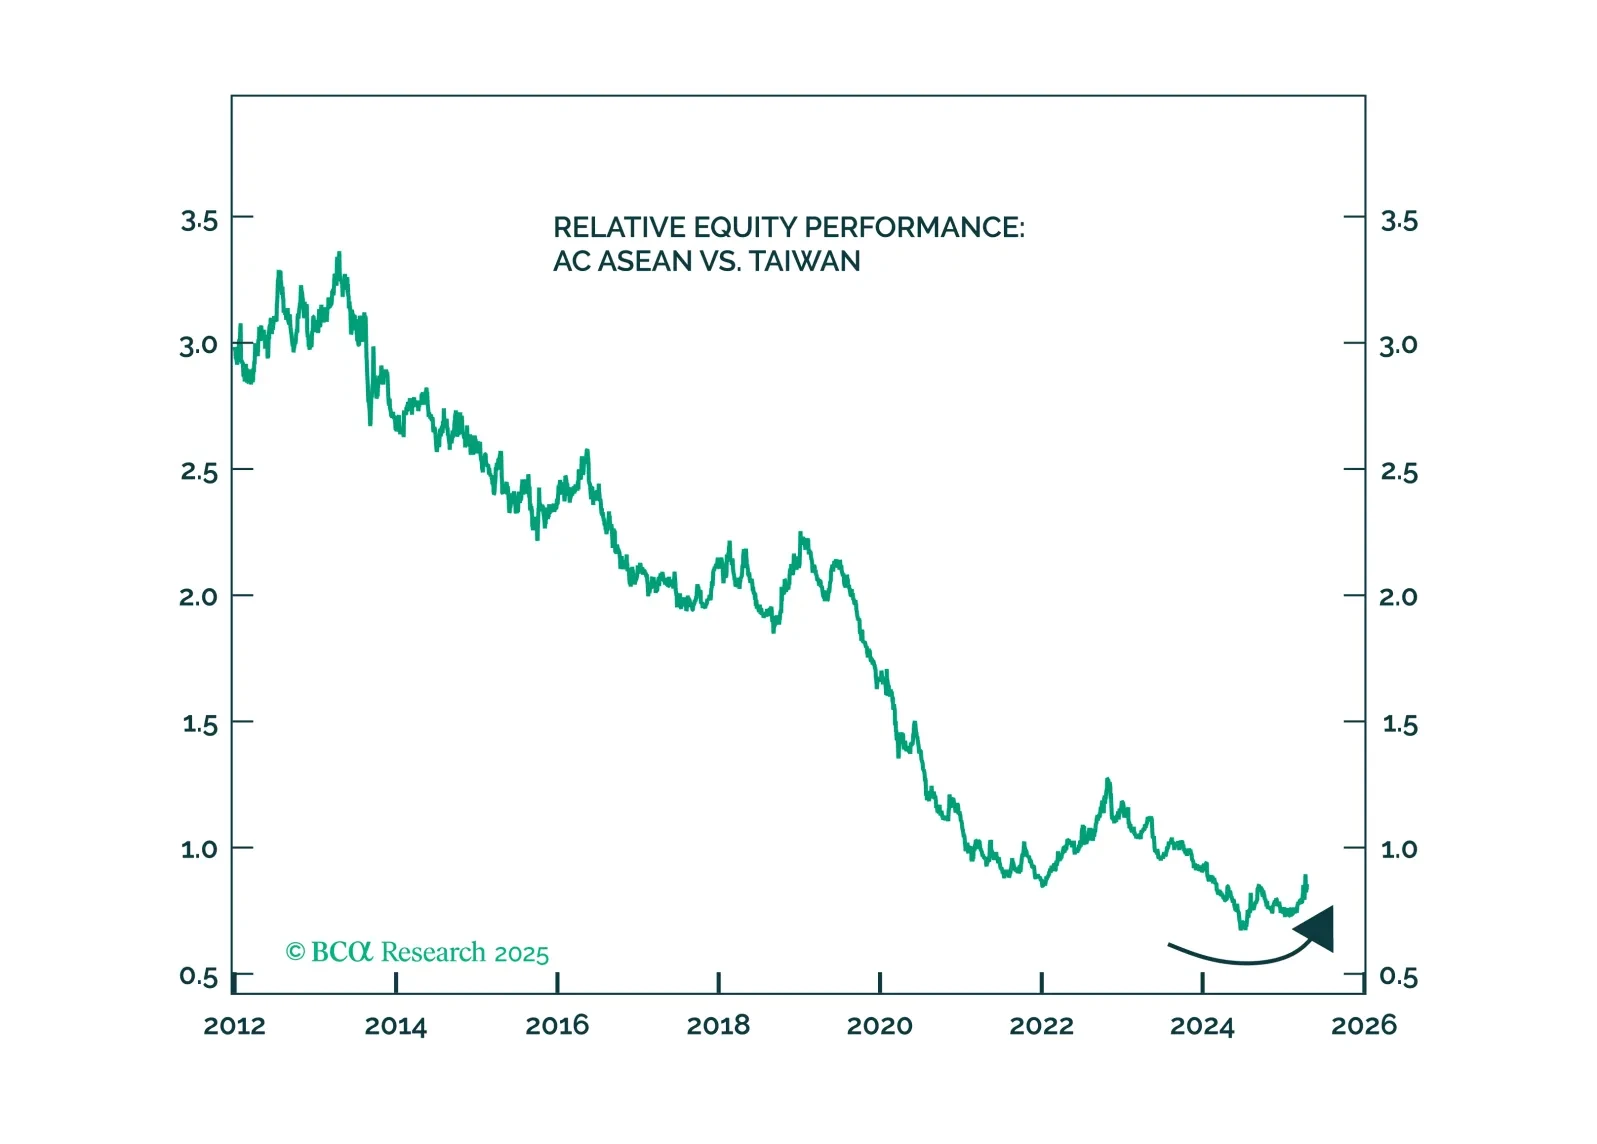
Upgrade the odds of a full-scale war in the Taiwan Strait from 5% to 10%. Rapid escalation of US-China economic war raises the probability of tensions spilling into the military-strategic domain. Investors should buy insurance against this tail risk while it is cheap. Meanwhile, use this year’s trade shock and equity volatility to increase allocation to EM manufacturing states.