Latest from BCA Research
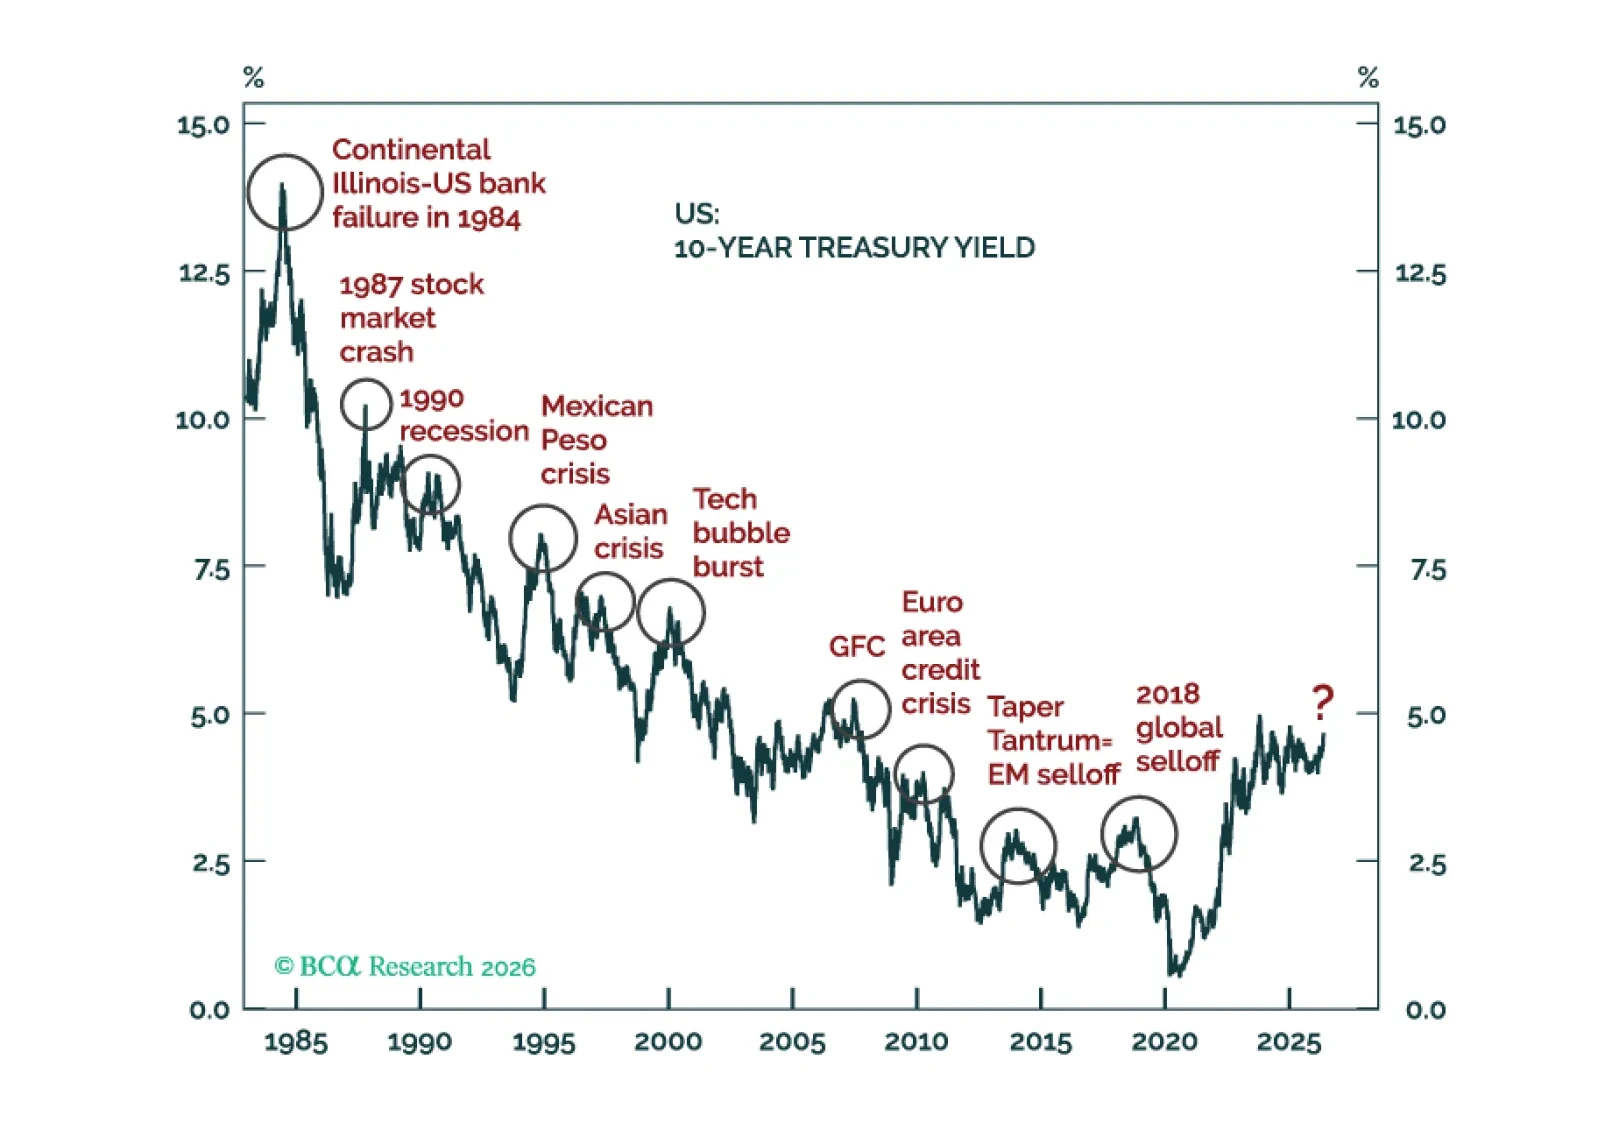
US stocks and bonds are on a collision course. Only a meaningful equity selloff is likely to pull bond yields considerably lower. Global equity risk-reward looks poor. The dollar will stay firm near term, but its medium- and long-term outlook remains bearish.
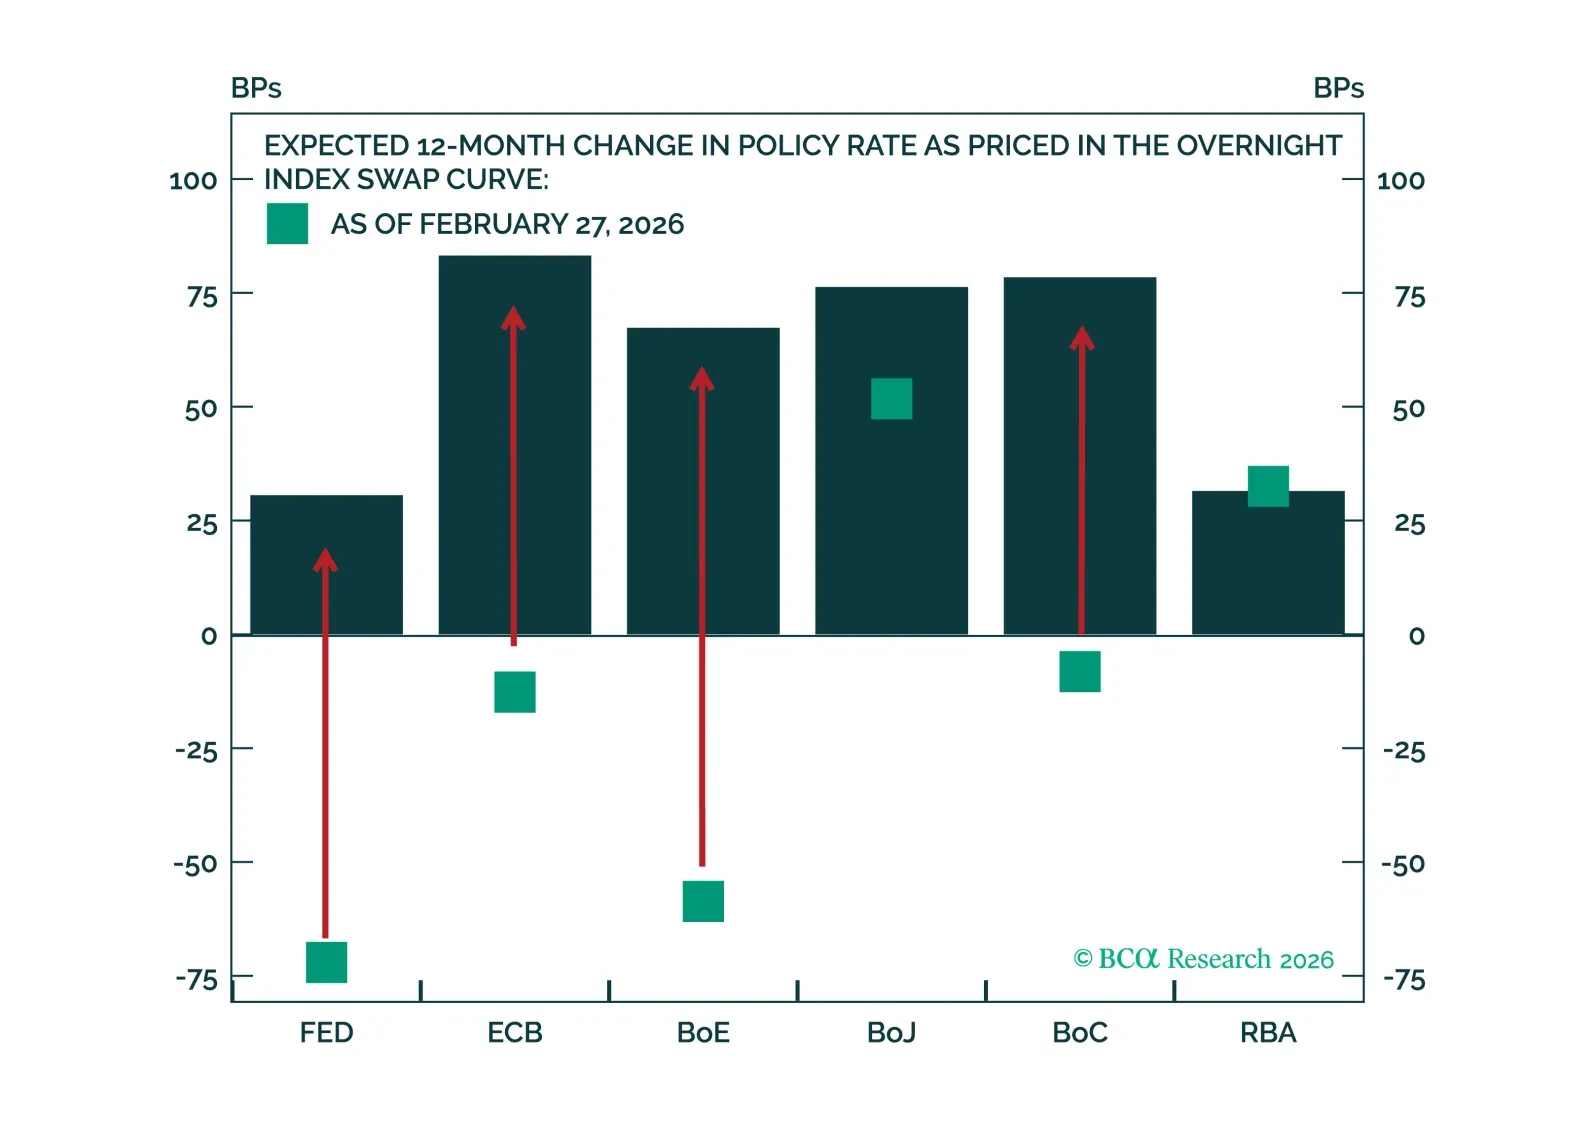
Downgrade global and US portfolio duration from “above benchmark” to “at benchmark” as the risk of hawkish monetary policy surprises is rising.
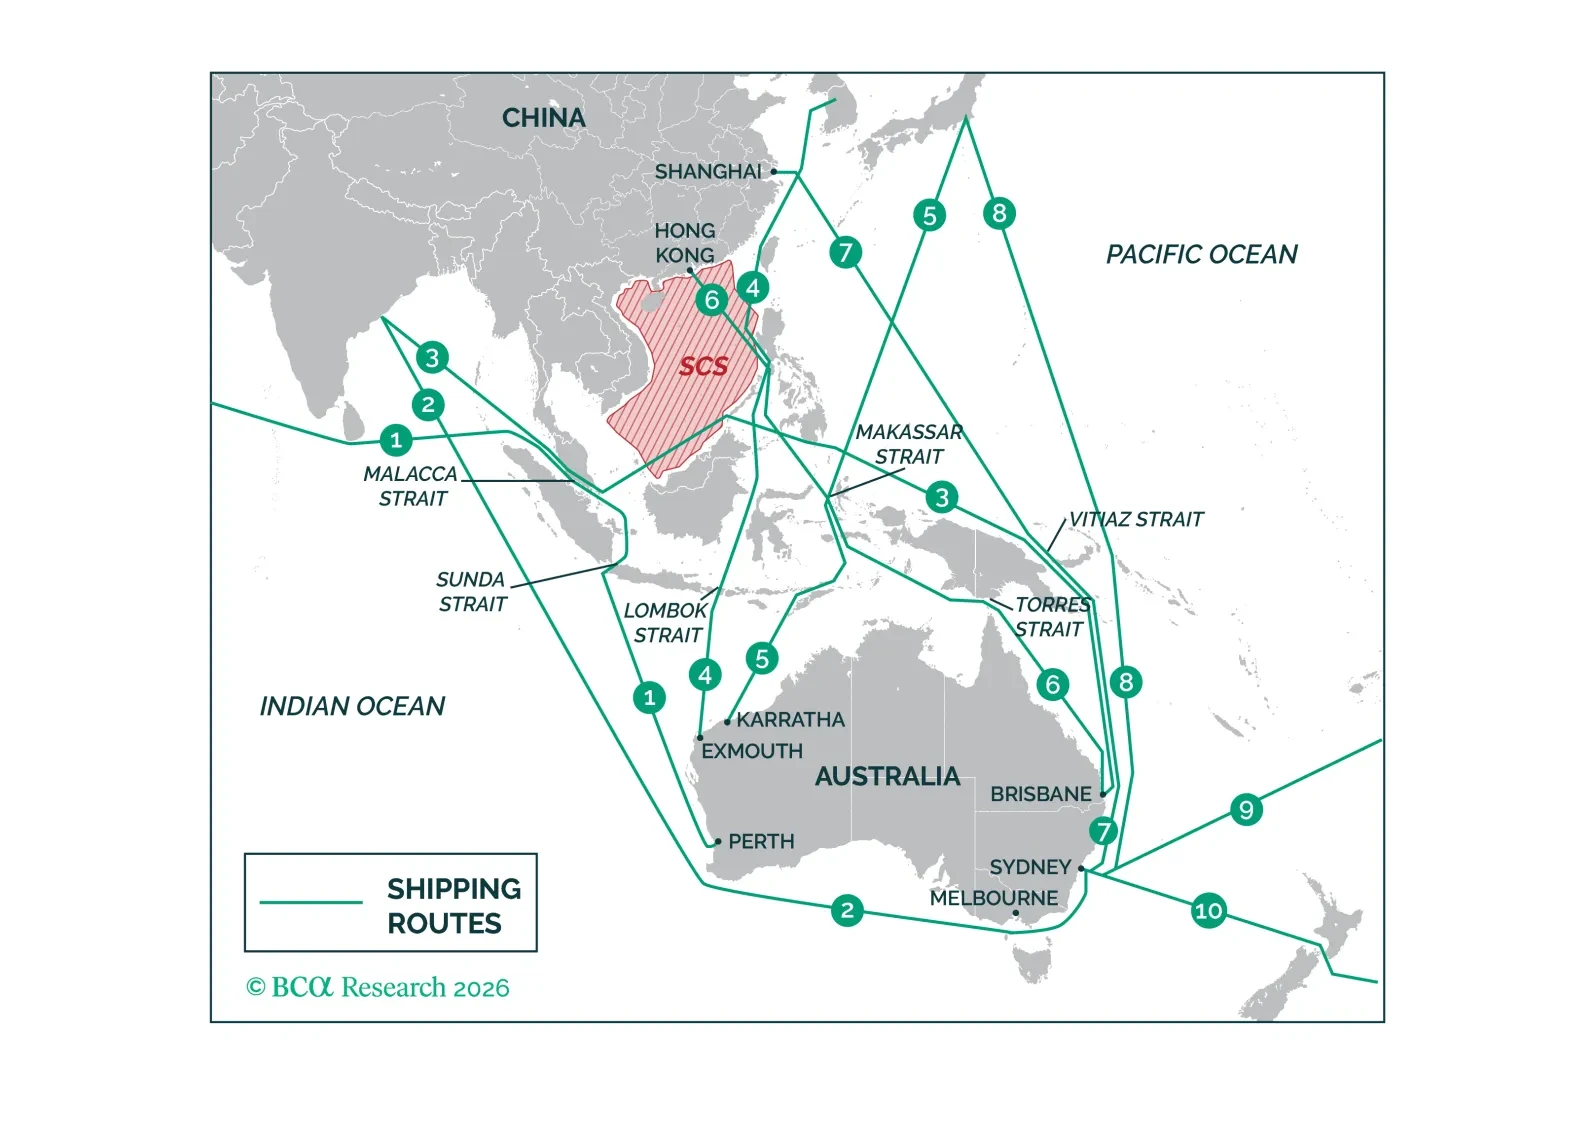
In this month’s Beta Report, we assess what that structural tension means for investors under two distinct scenarios. In our base case – a multipolar world order – Australia's position turns out to be more advantageous than it appears. The great power capital expenditure race generates demand for precisely what Australia produces. In the tail risk – a hard bipolar rupture – the calculus inverts, and the same commodity dependencies that long appeared as structural strengths begin to look like structural liabilities.
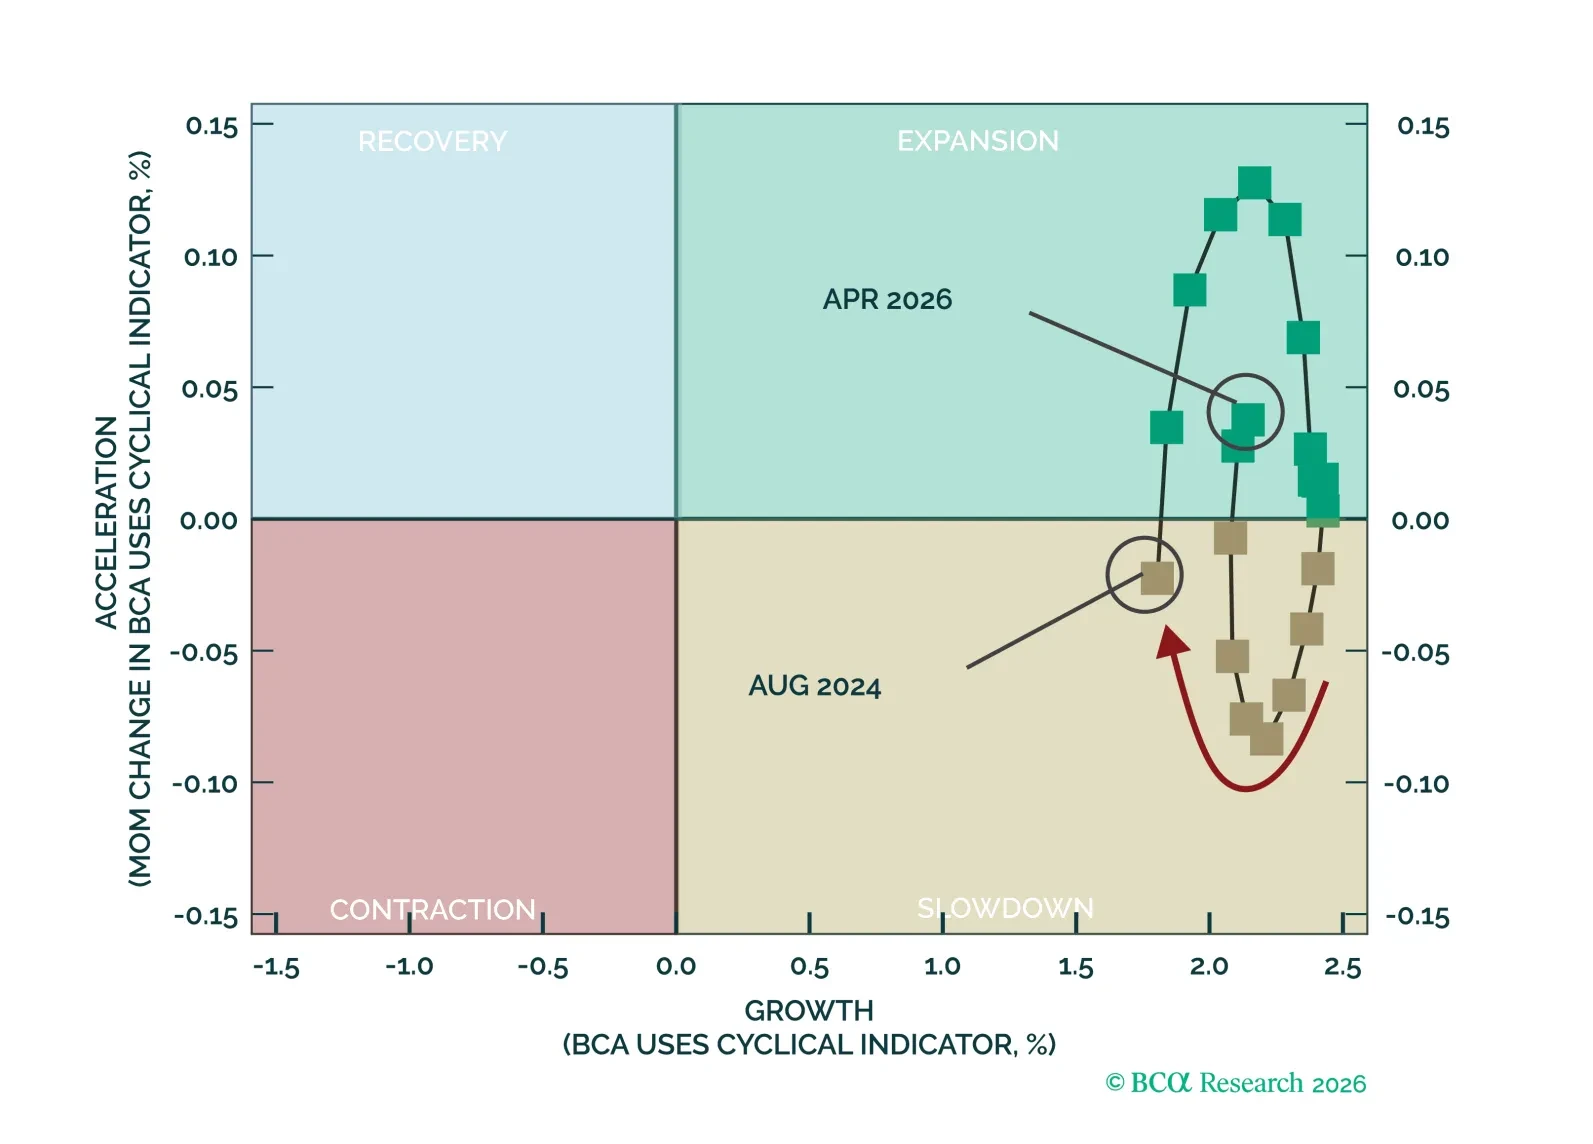
US growth remains positive and is now improving, with the economy seemingly exiting Slowdown and proceeding into Expansion. Markets are reflecting the shift, rewarding revenue growth and capex growth, while earnings expectations continue to advance. The backdrop remains supportive, but expectations are rising and risks from financial conditions linger.
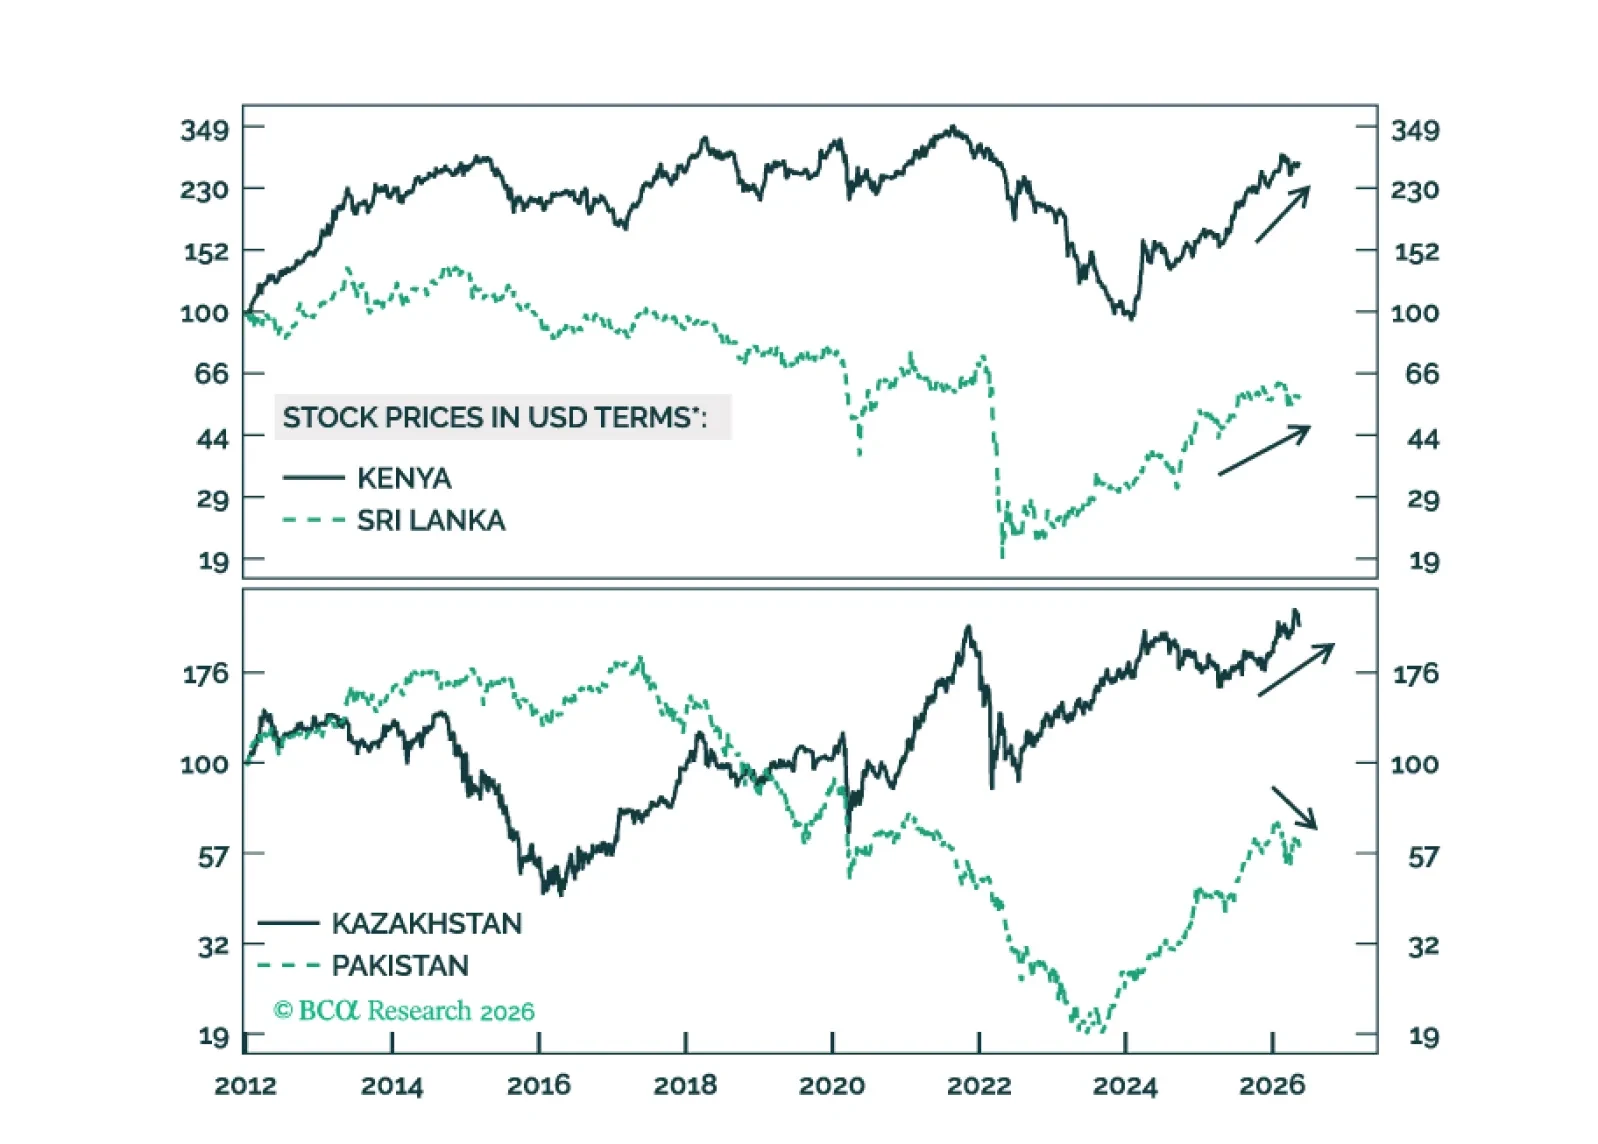
The divergence across frontier markets is likely to widen. Kenya, Kazakhstan, and Sri Lanka are well placed to outperform, while Pakistan is vulnerable. We offer several trade ideas to capture this divergence.
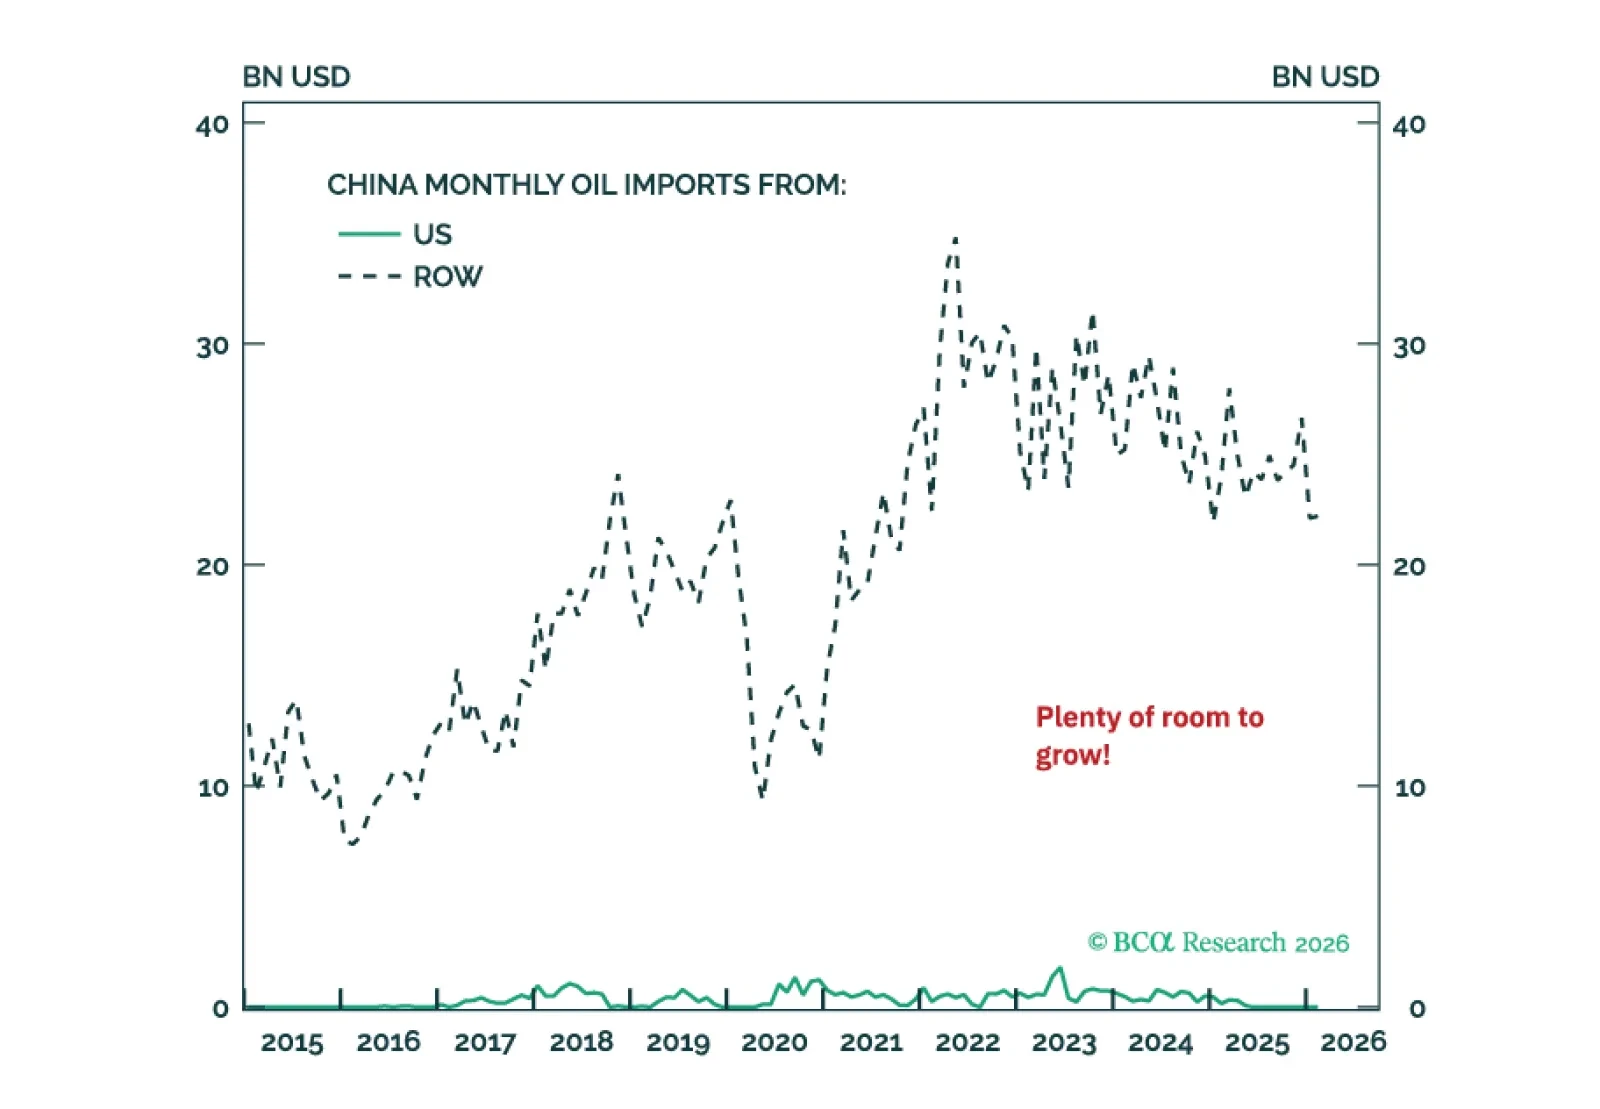
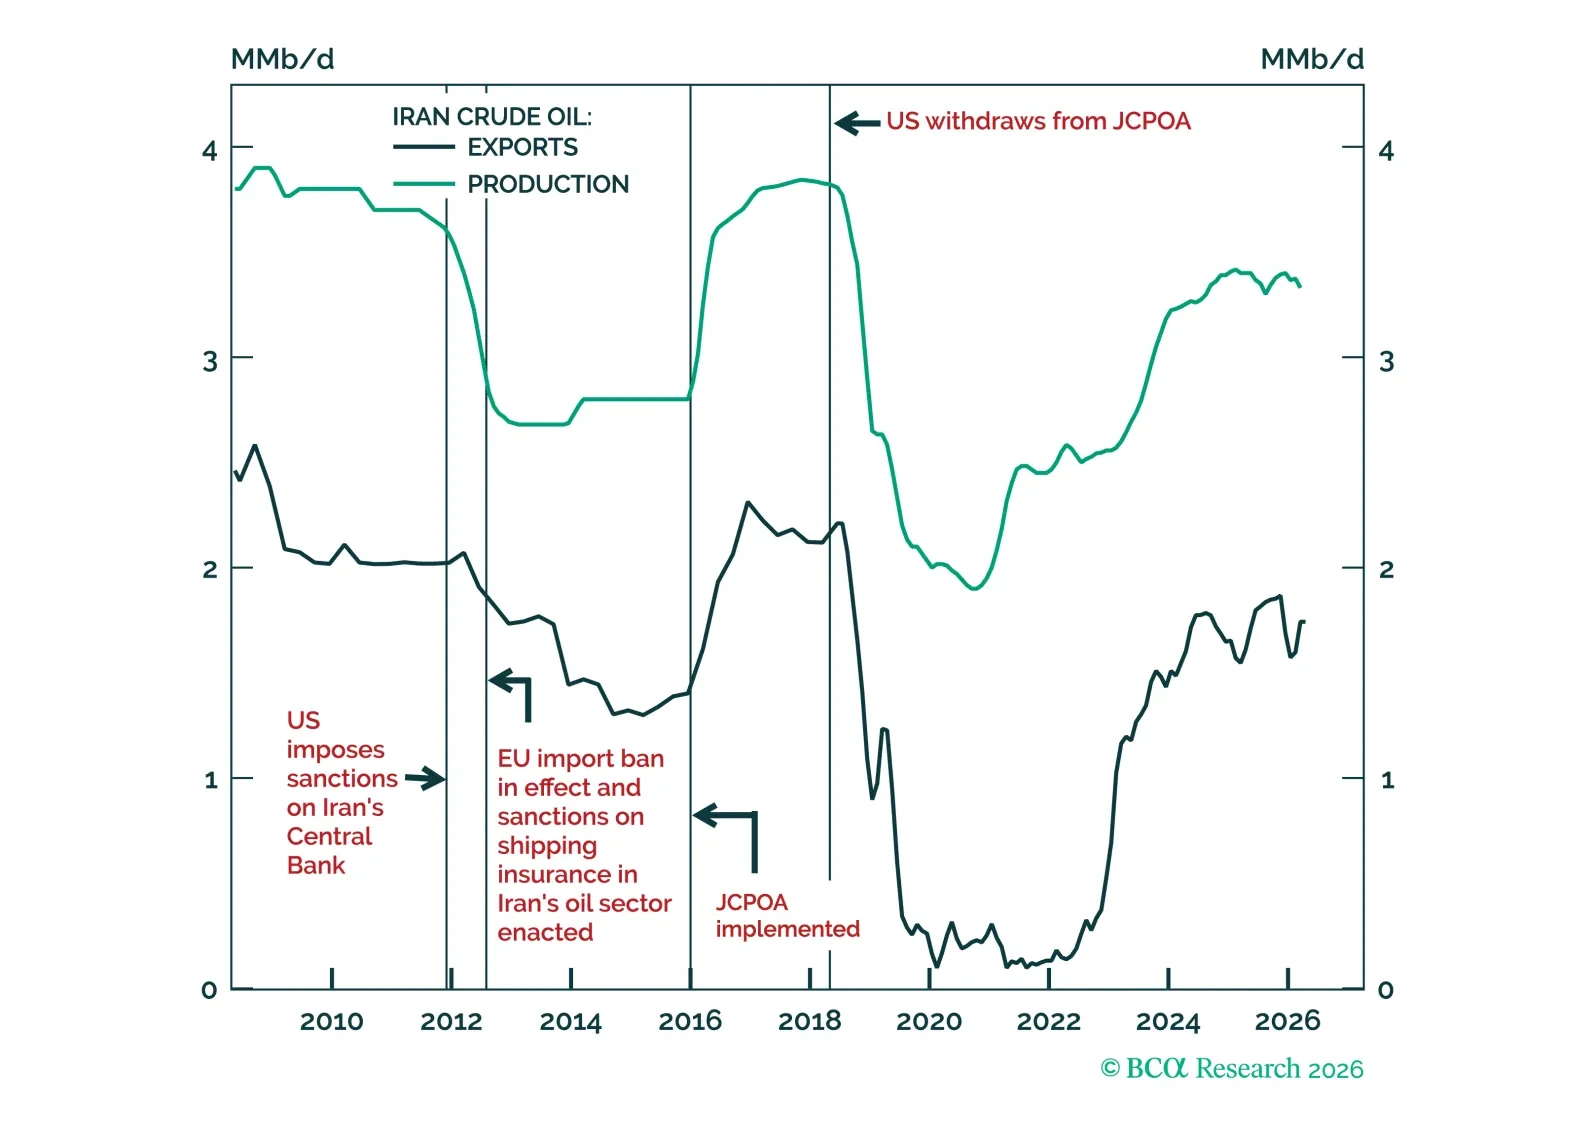
Hopes for an imminent Middle East de-escalation have capped oil prices in recent weeks, but that restraint may soon fade.