GeoMacro
Find out more
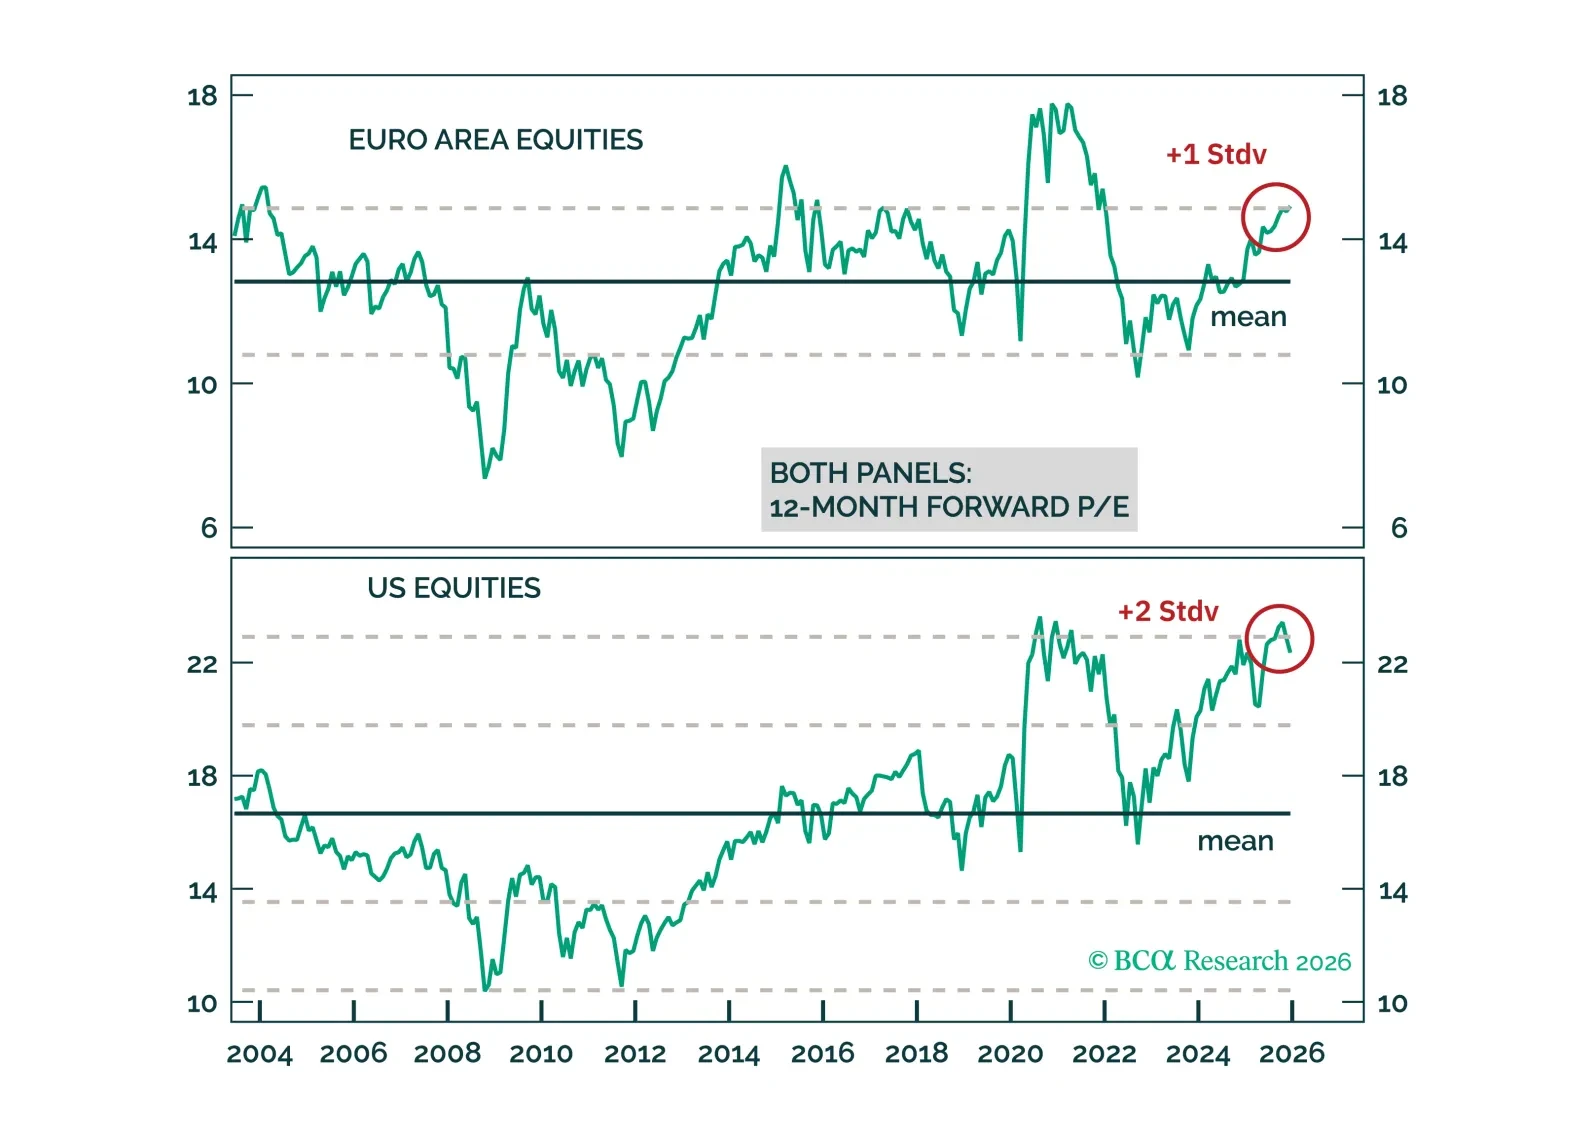
Europe is in a geopolitical sweet spot. Exaggerated fears of Russian military aggression and abandonment by the United States, as well as increased competition from China, create a geopolitical imperative to stimulate, reflate, and reform. Taken together with fading cyclical headwinds, it suggests that European risk assets can continue to outperform US ones on a cyclical investment time horizon. Remain long European stocks, in particular industrials, and EUR/USD.
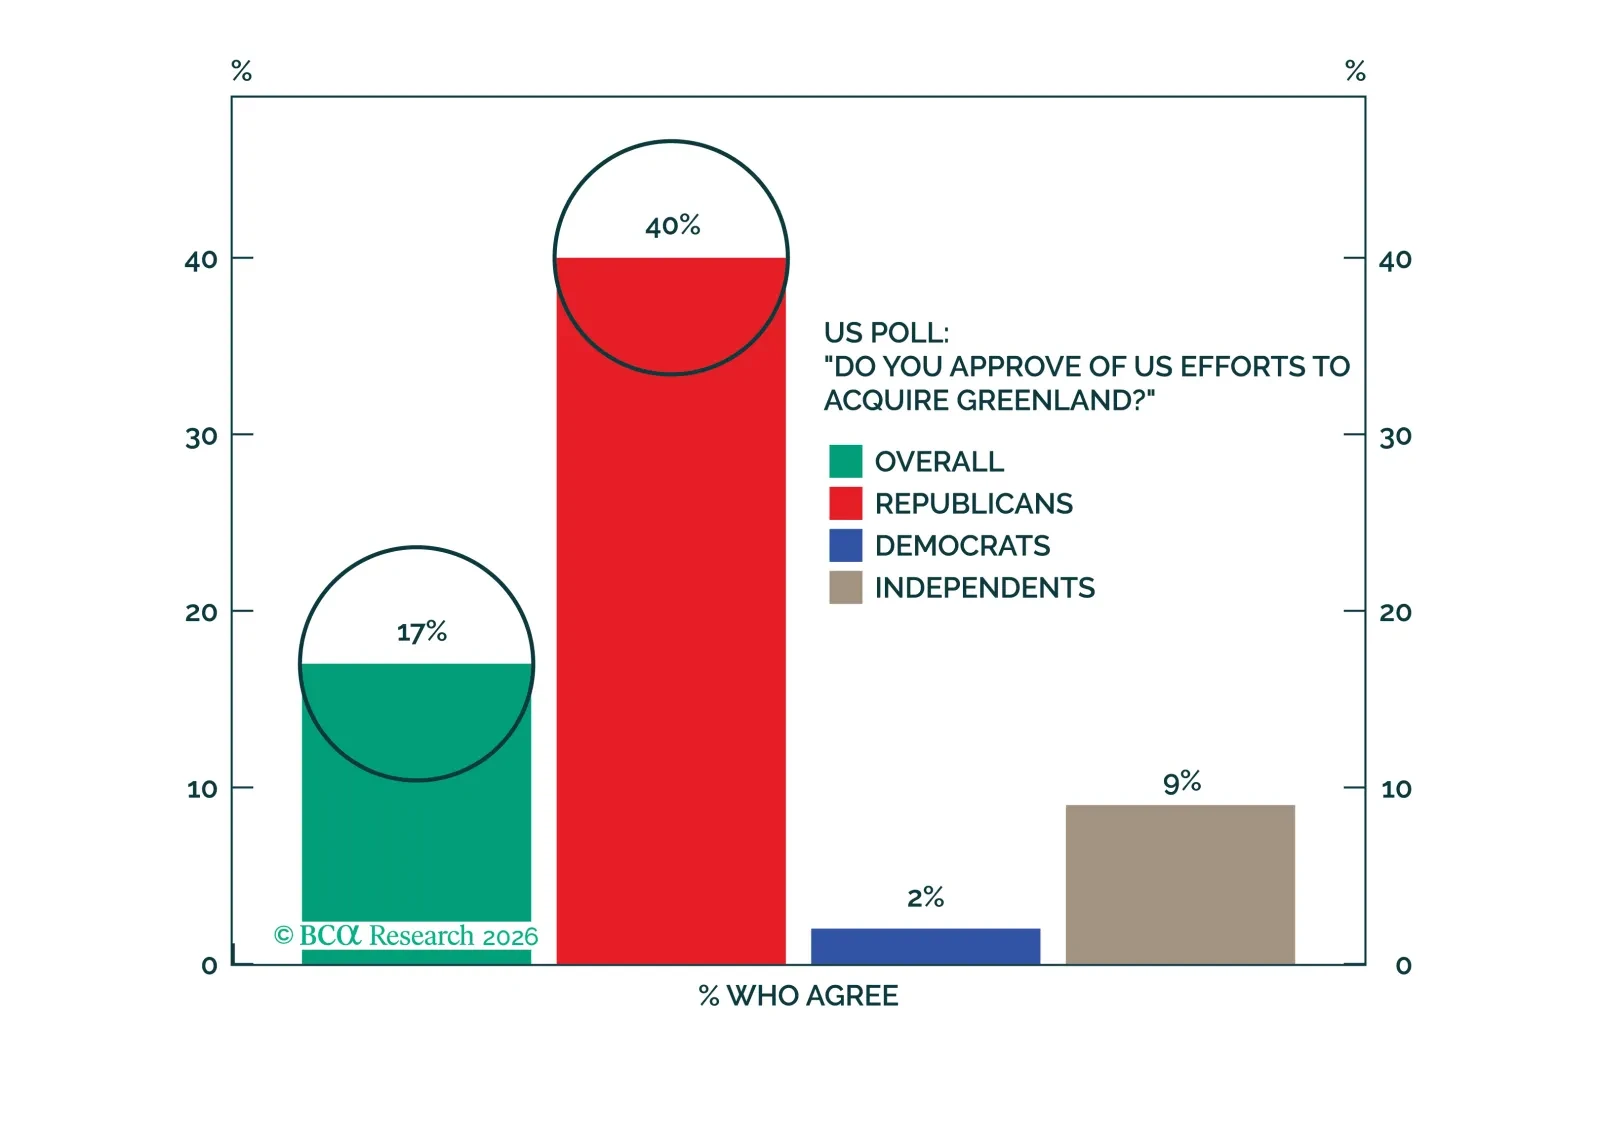
Investors should bet against the US seizing Greenland by force and collapsing NATO. But stay tactically defensive anyway.
On Monday – January 19 – BCA Research will hold its View Meeting (open to all clients to view online or as a recording!). This is the gathering of all Chief Strategists to talk about the economy, views, and markets. A veritable Macro Entmoot! Every weekend before a View Meeting, I try to step back and think big picture. In particular, I like to think what will be the defining geomacro issue of the year. And how will it impact the markets.
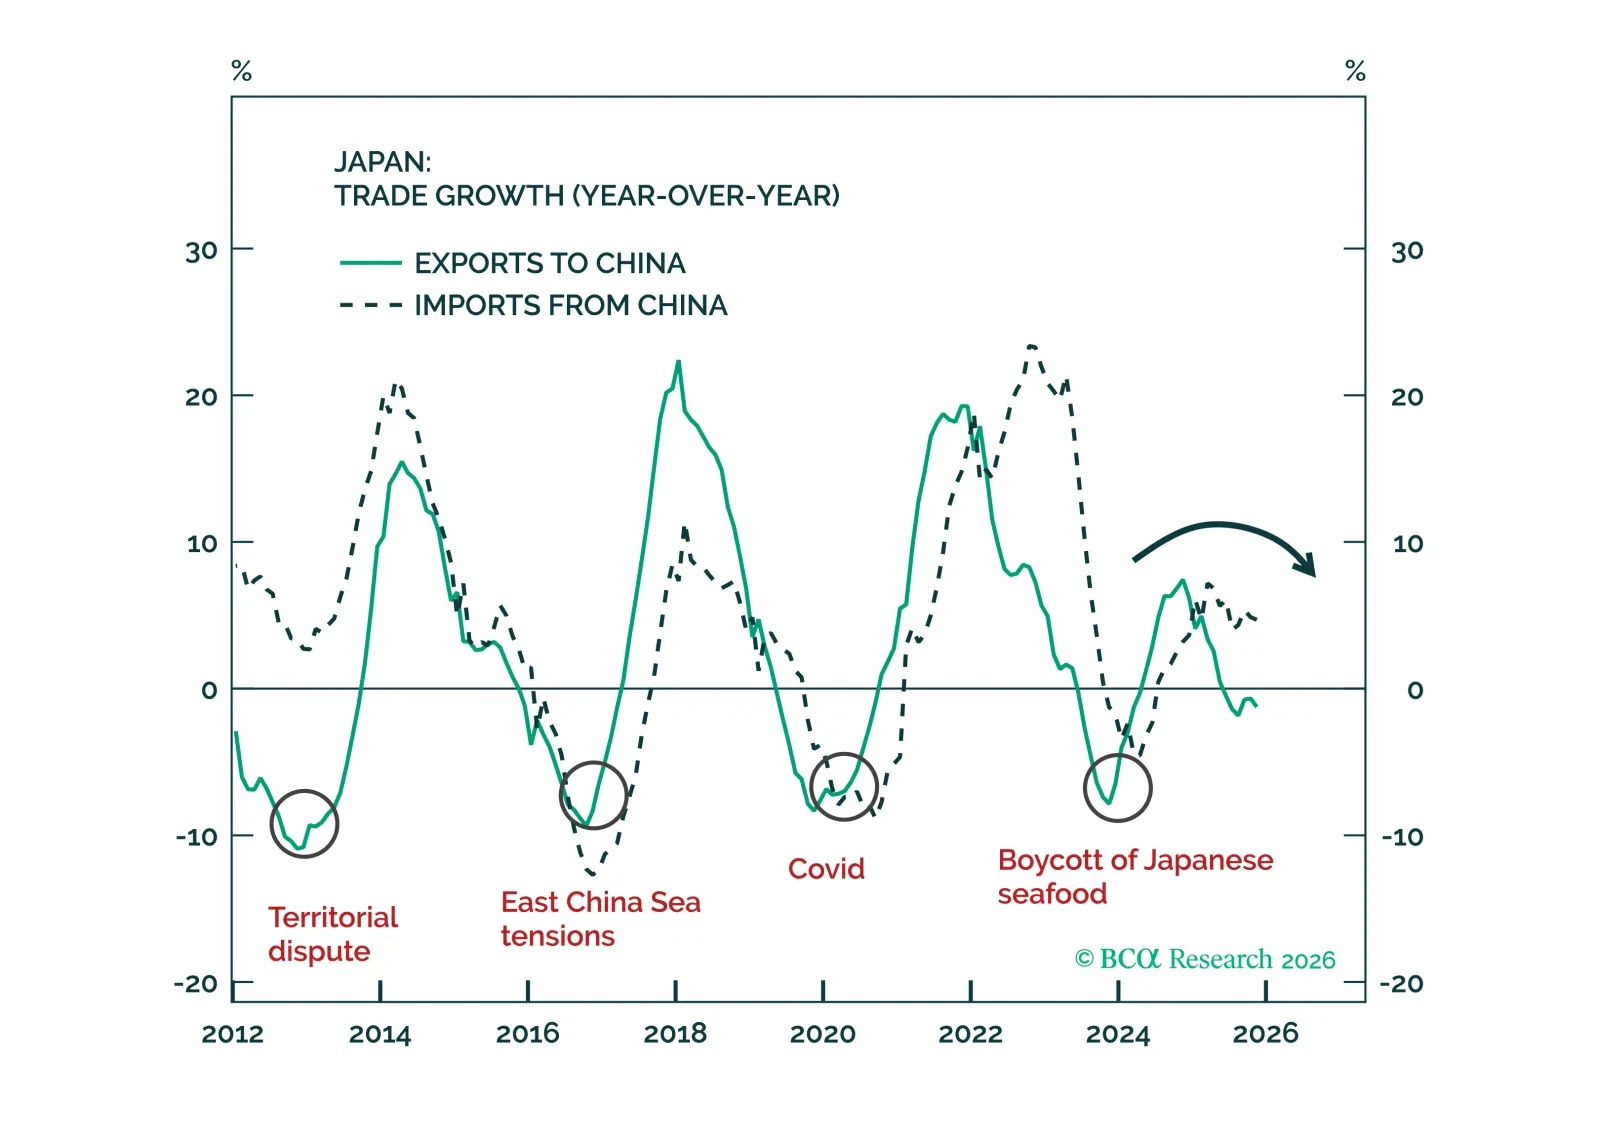
Japan's new government will continue, but politics and foreign policy have become more competitive.
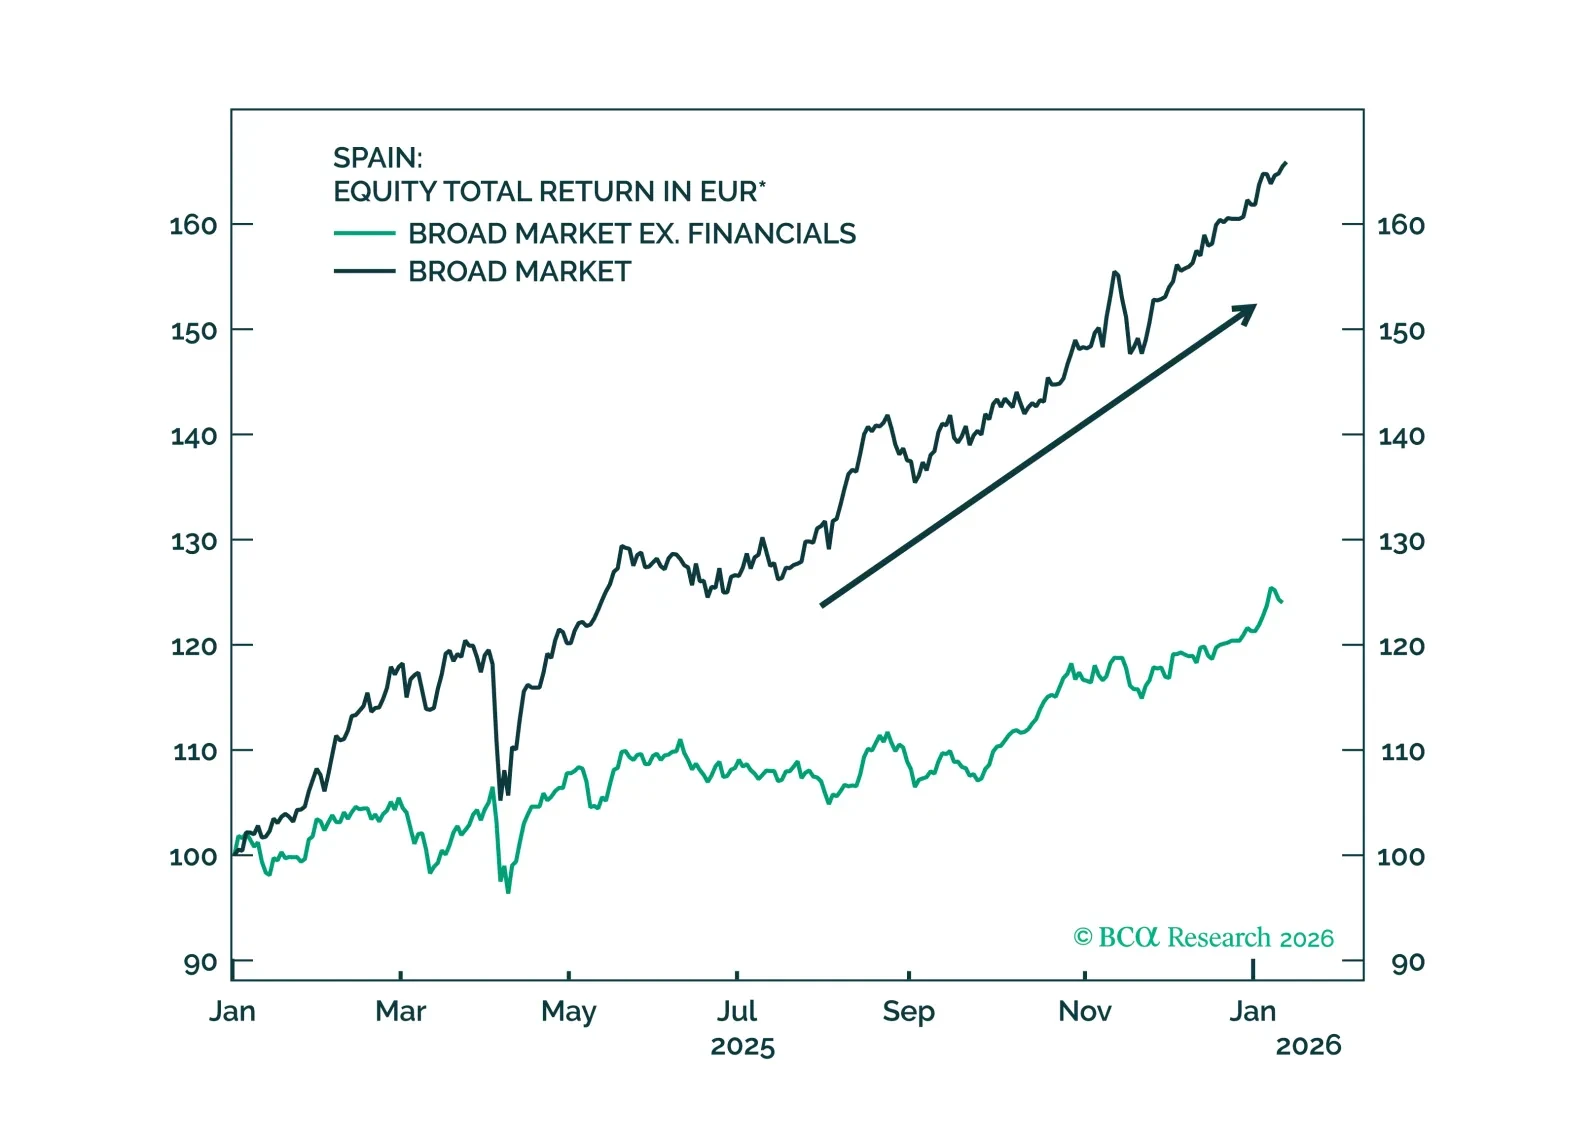
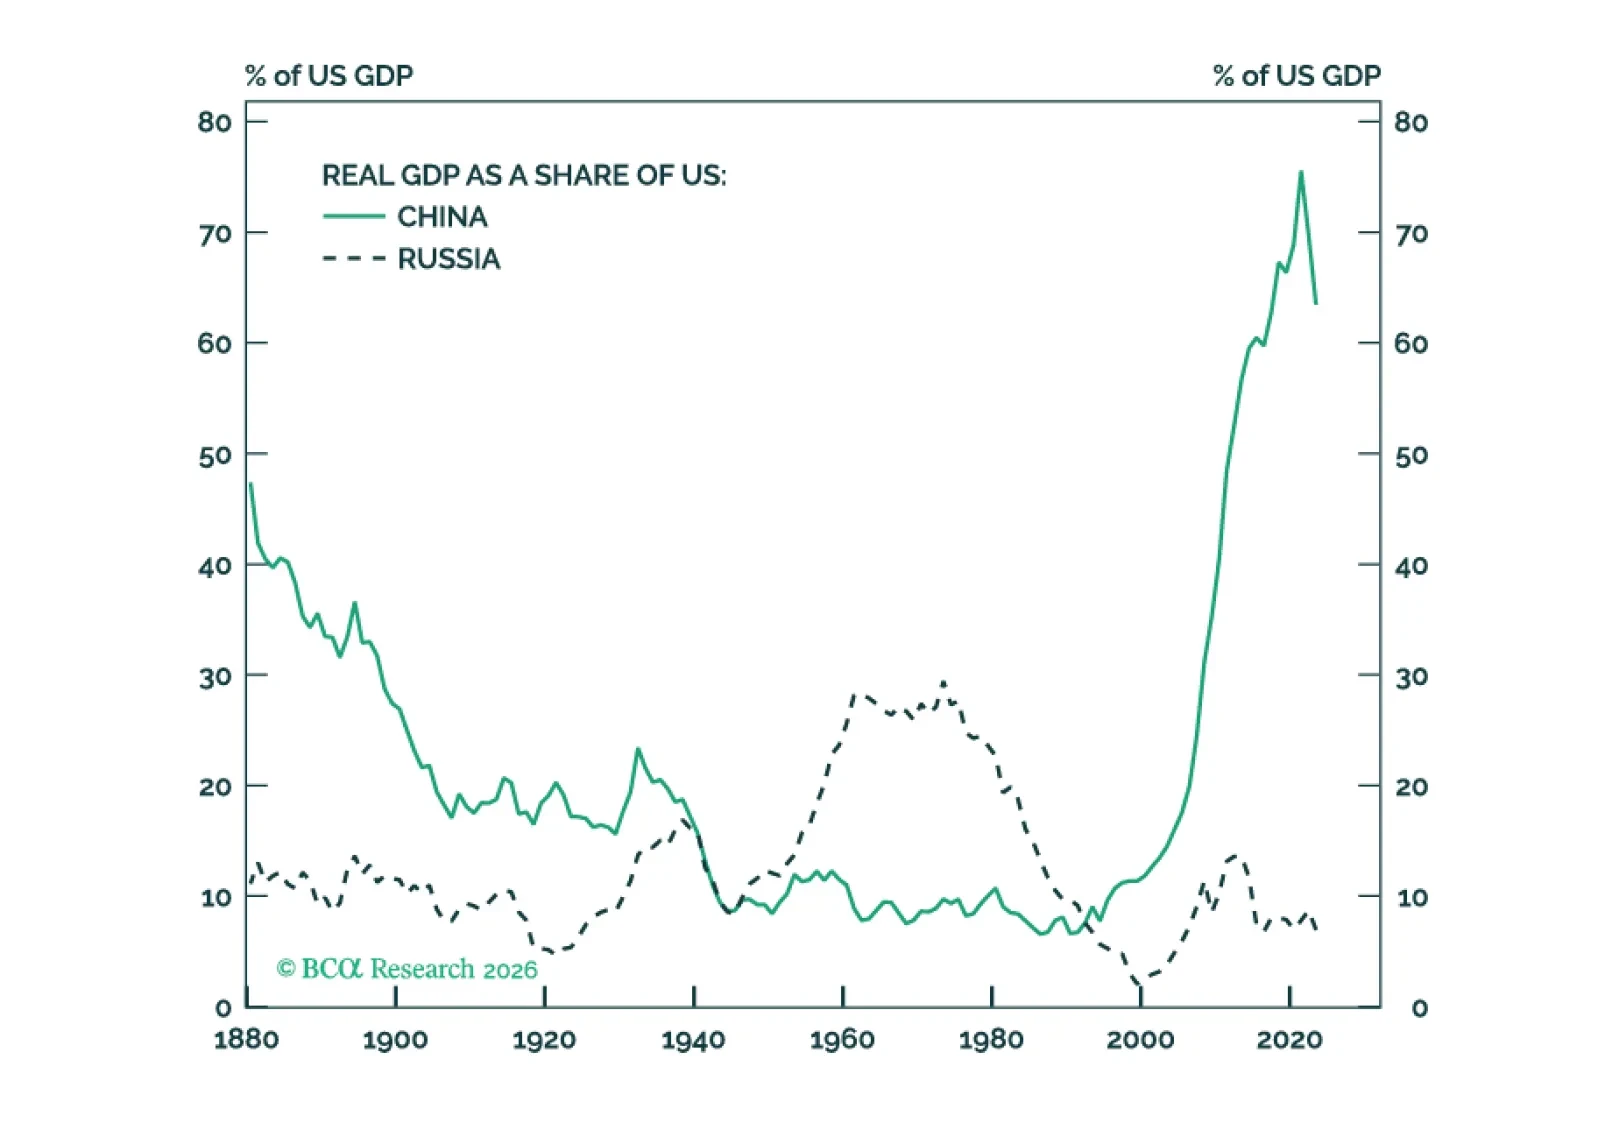
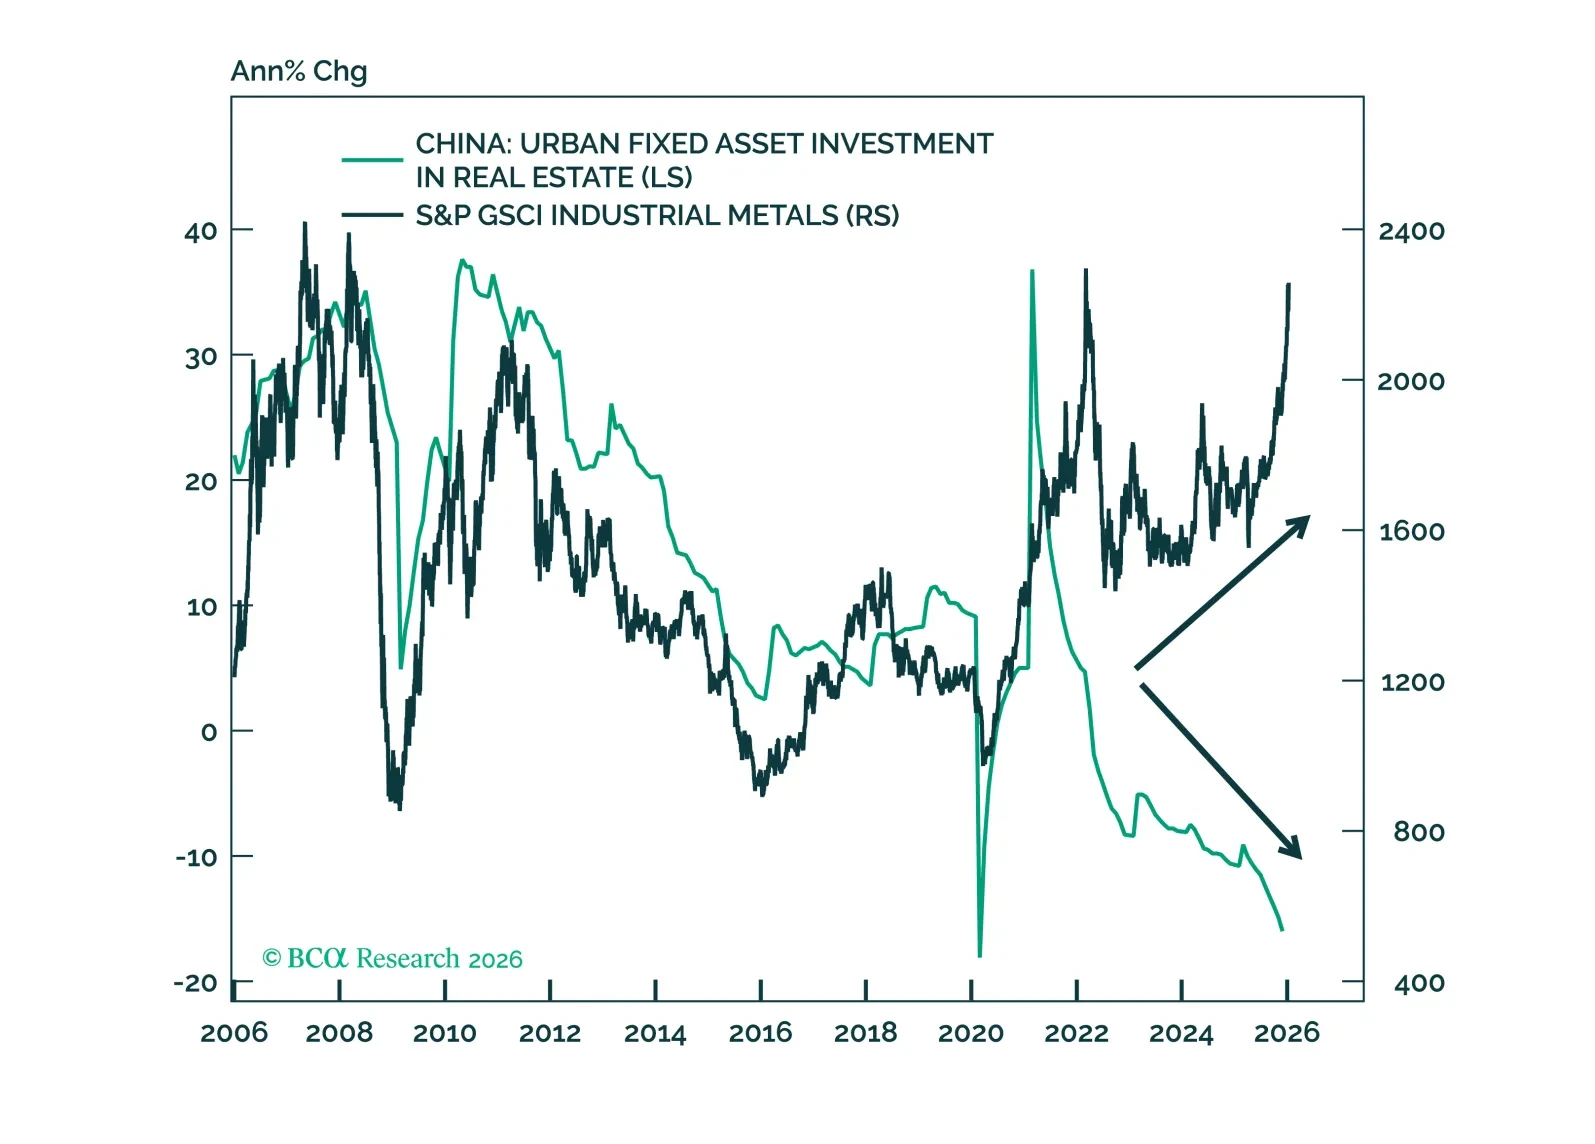
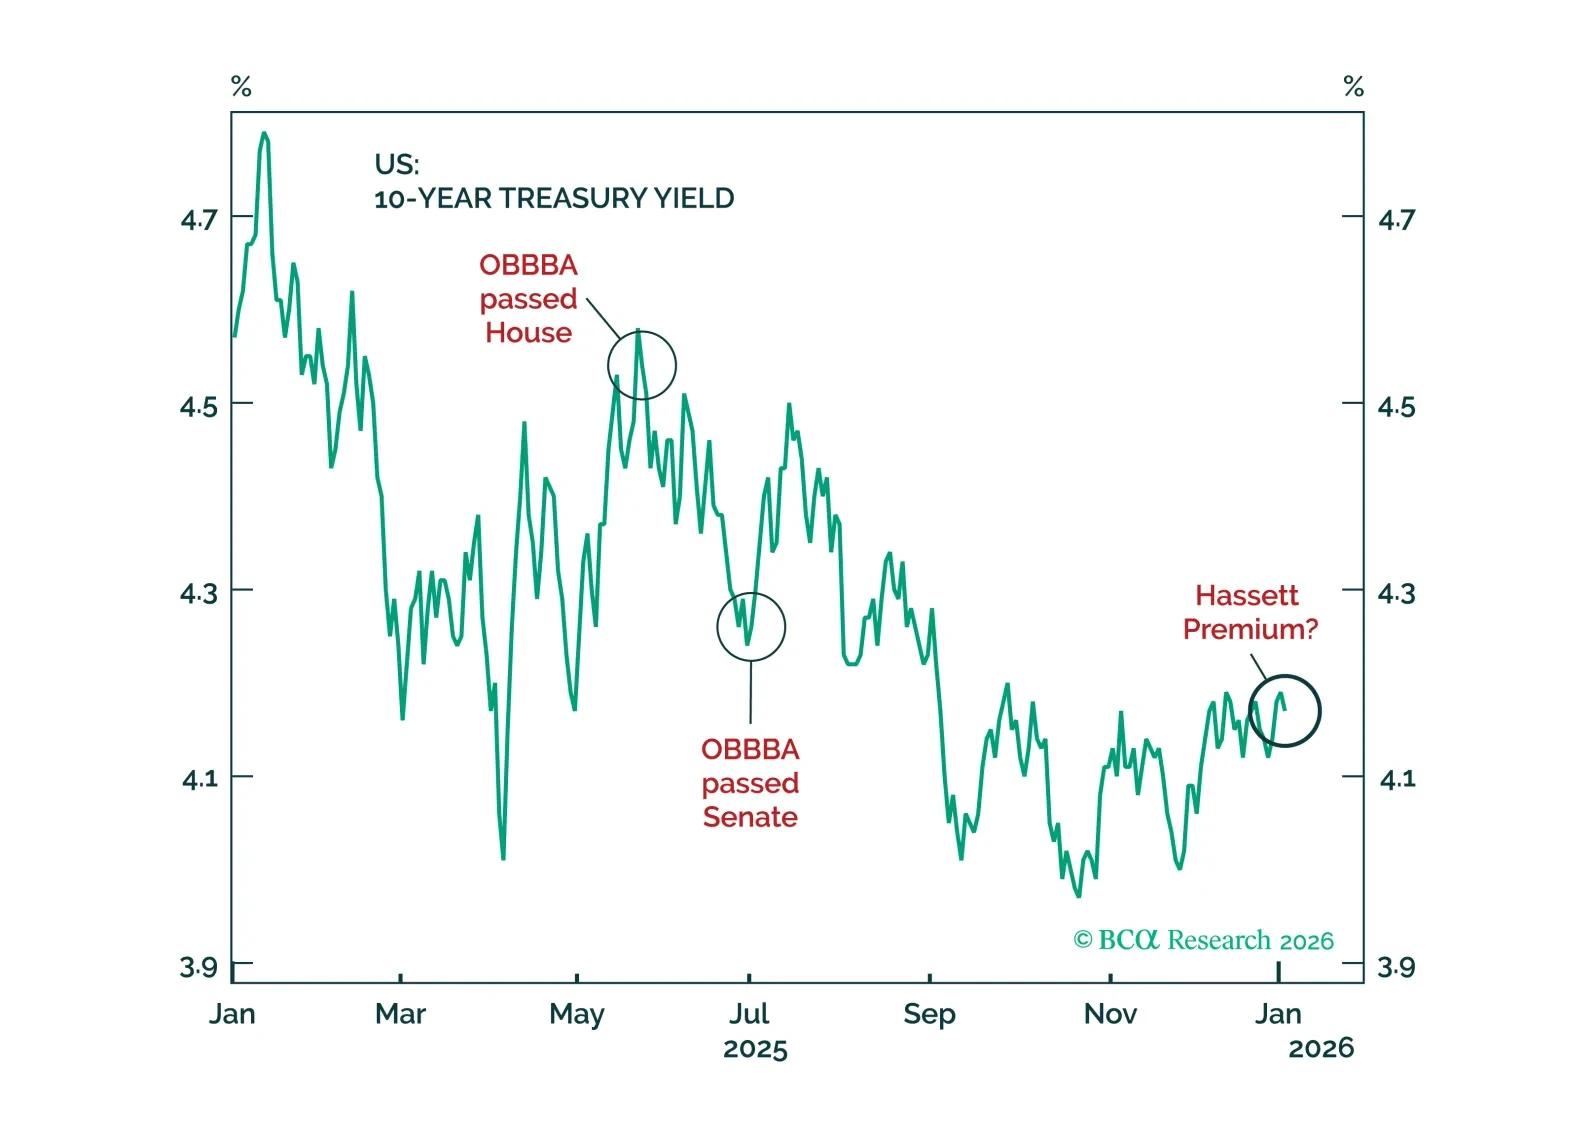
The year 2026 has started off well, with not even the threat to central bank independence denting the market's enthusiasm. Perhaps our tactical caution is misplaced.
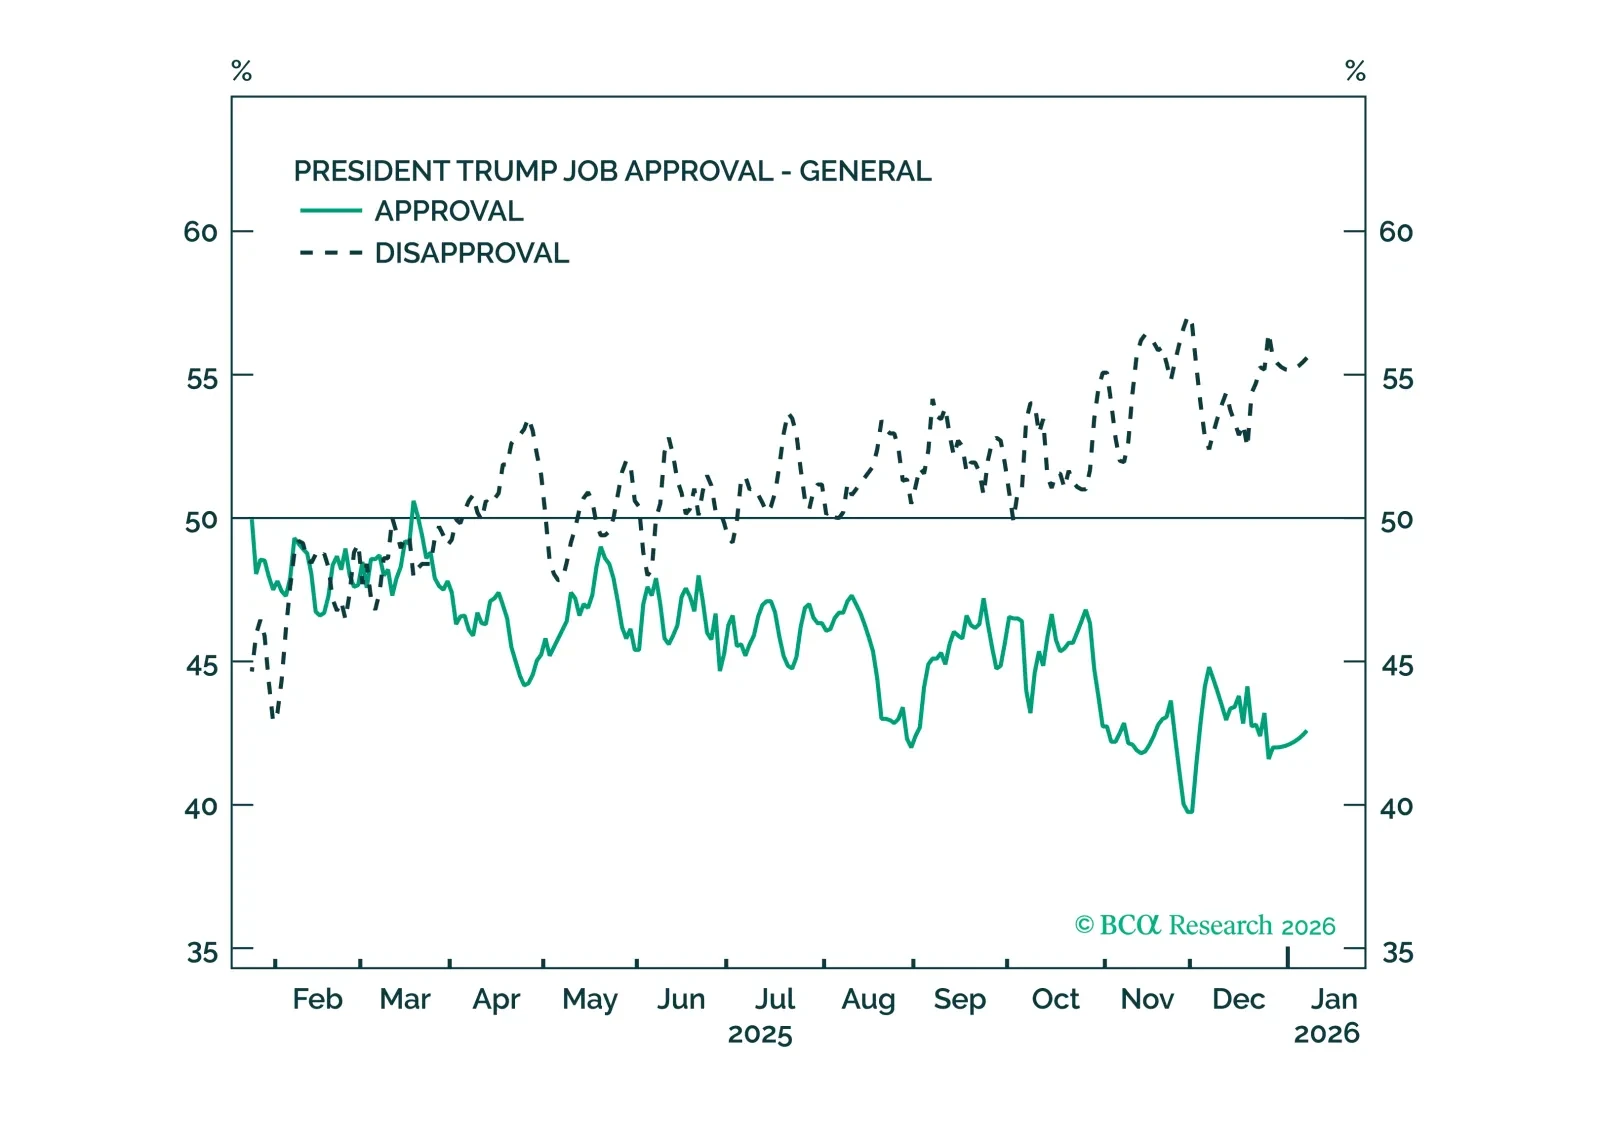
Congress will ultimately limit Trump from acting on his worst impulses, but his efforts to bypass those limits will cause market volatility.
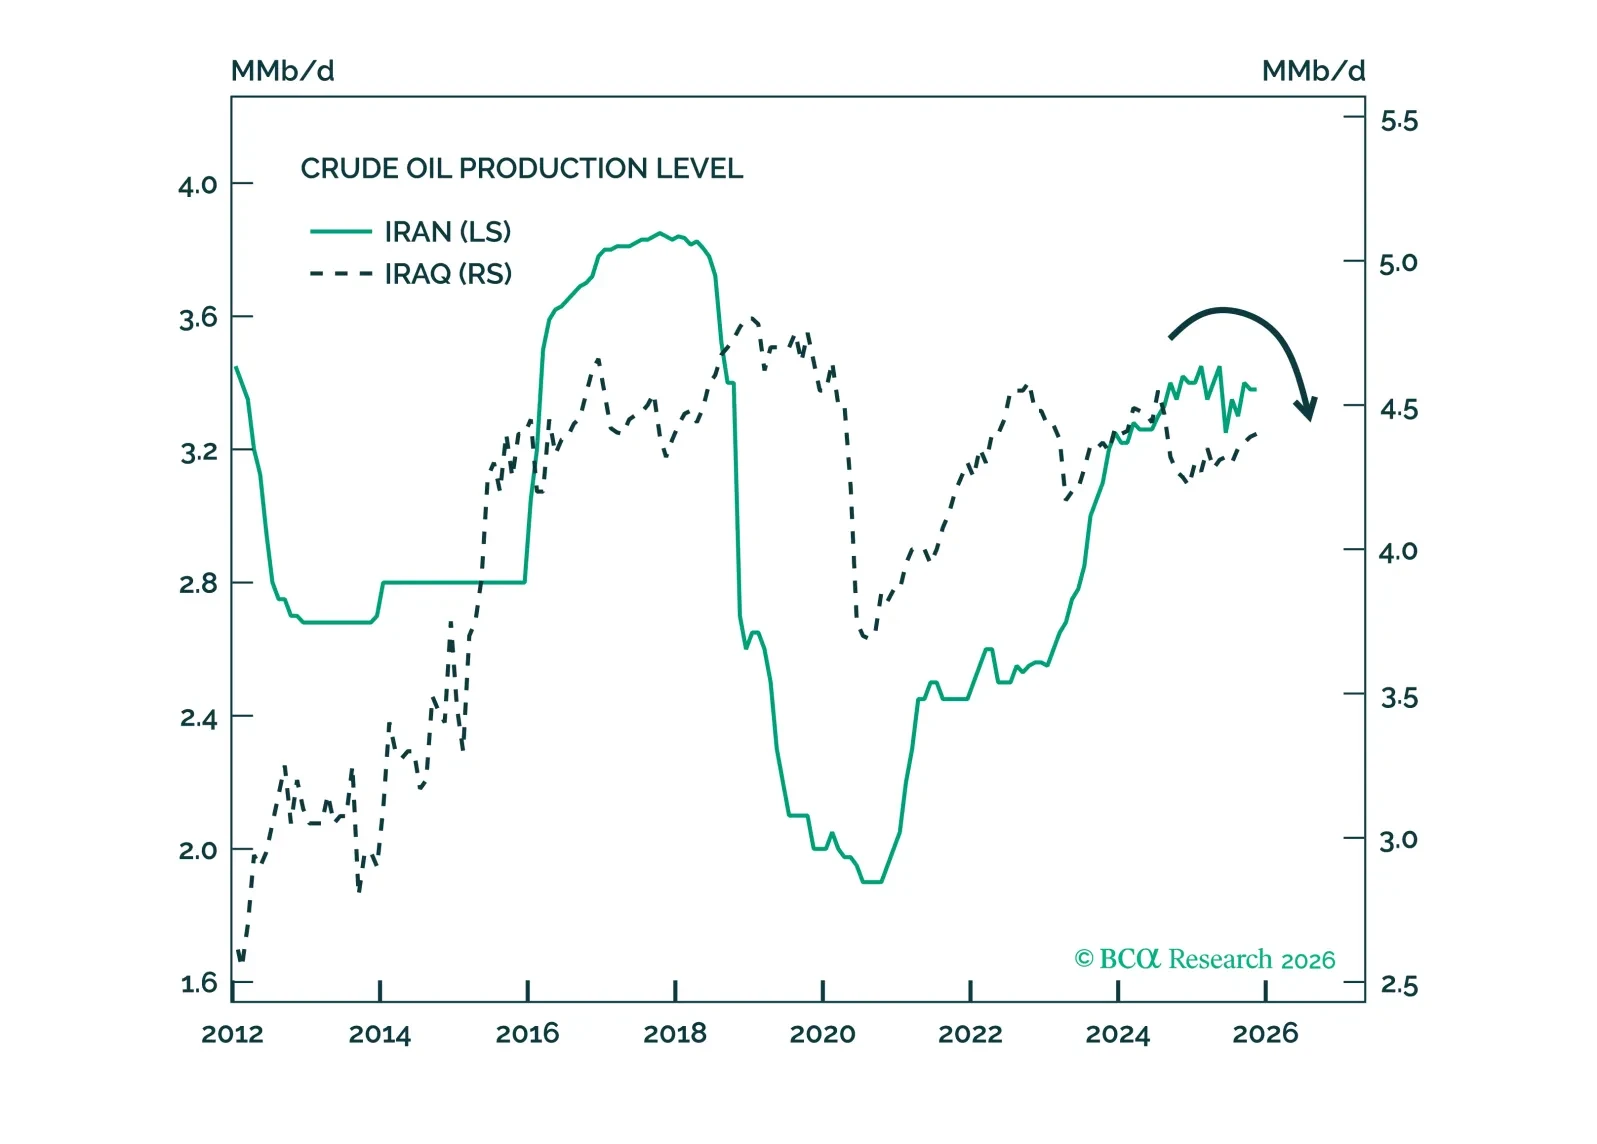
The risk to Iran's regime survival raises the probability of a massive global oil supply shock back to around 40%, where we put it last year.